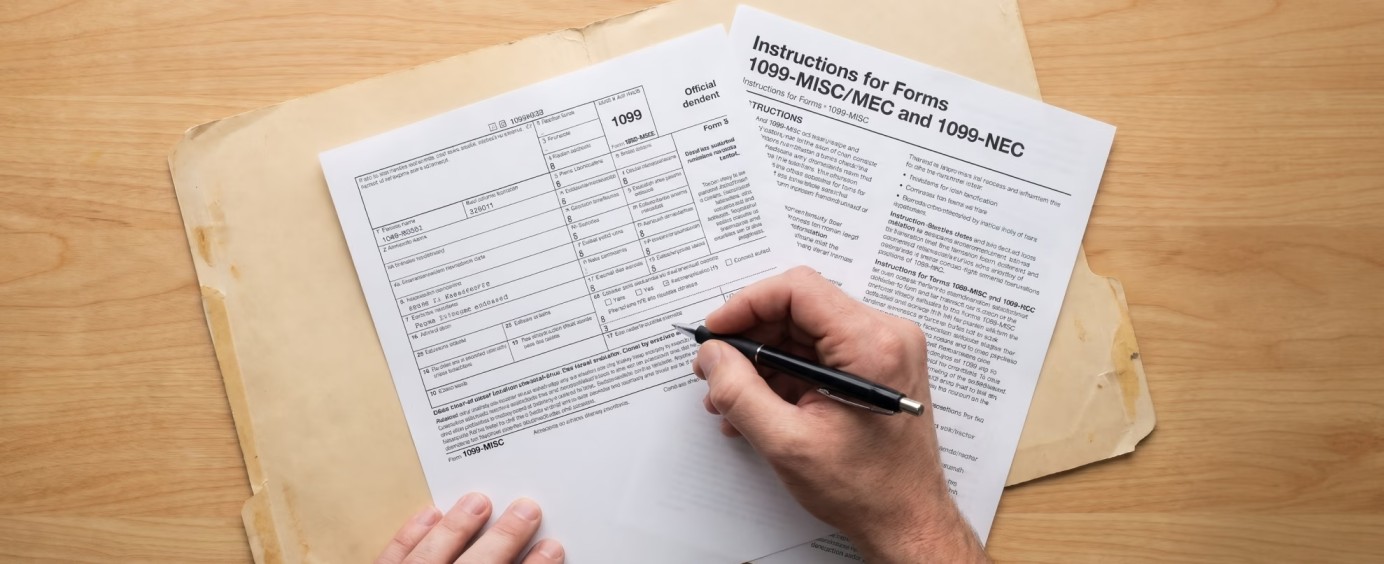
It’s 3 am, and the phone is lighting up the ceiling. What if my main client does not renew next month? What if that transfer went to the wrong account number and it has already left? What if the card declines in a city where I know nobody? What if someone at home calls tonight and needs money by morning?
We rarely say these out loud, yet most of us carry some version of them. At that hour, they feel shapeless. In daylight, most turn out to be a few specific risks and a few specific steps.
Five money fears tend to keep people awake: losing income, a payment that never arrives, a transfer sent to the wrong person, running out of money abroad, and an emergency at home. Each is partly rational and partly reducible.
This is how we can get ahead of these worries and how to make each situation easier to handle.
What if I lose my income?
Of the five, this is the one with the most reason behind it. Clients leave, contracts end, companies restructure, and a salary that felt permanent can stop with a month’s notice. We are not being dramatic when we worry about it.
What we can usually reduce is how fast the fear turns into a crisis. Two numbers do most of the work. The first is the cost of one month: rent, food, transport, data, and any fixed obligations such as school fees or loan repayments. The second is how much of your income comes from one source. If a single client or employer pays most of it, losing them hurts differently from losing one of five.
Always have a buffer of one month’s costs, kept somewhere separate from the account you spend from, like in a Pouch. One month is not a deep cushion but it’s enough to turn a sudden stop into a few weeks of choices instead of a few days of panic. From there, three months is a common target if you can reach it.
This is not to forsee stalled income but to be prepared if it does.
What if the payment never comes through?
Late payment is perhaps the least troubling of the five, because it does not feel like a disaster. It feels like waiting, refreshing the account, and drafting a polite email for the third time. Invoices do get paid late, and some clients, rather annoyingly, treat the due date, as a suggestion.
Part of the fear can be shrunk before you send an invoice. Here's what you can do:
- State the due date and the payment method in writing, and agree what happens if the date passes, such as a late fee or a pause on work. Ask for a deposit on larger jobs so you are never fully exposed.
- Check that the name on your invoice matches the name on the account that will receive the money. Many banks and payment providers hold a payment for review when the sender's details and the receiving account name do not match, and you may be asked for documents before it is released. A payment can be on its way and still not be spendable.
- A follow-up routine helps too: a reminder two days before the due date, one on the day, and one a week later. A scheduled message is easier to send than an anxious one.
What if I send money to the wrong person?
This is the fear with the sharpest edge, because many transfers cannot simply be taken back. Once a bank transfer has left, getting it returned usually depends on the receiving bank, and on the person who received it, more than on how quickly we notice.
What we can reduce is the chance of it happening, and how fast we act if it does:
Check the account number, the bank, and the name twice, and read the digits out loud instead of skimming them.
For a large amount or a new recipient, send a small test first and confirm it arrived before sending the rest.
Save a recipient only after a transfer has landed with them, so the saved details are the ones that worked.
If something goes wrong, contact your bank or provider straight away, with the date, amount, reference, and recipient details ready.
Be honest about the odds. Recalls depend on the receiving bank, can carry a fee, and do not always succeed. Speed improves the chances. It does not guarantee a return.
We cannot remove this fear completely, and we should not pretend to. We can make the mistake less likely and the response faster, which is most of what is in our control.
What if I run out of money abroad?
Being abroad changes the shape of this worry. At home, a failed card is an annoyance at best. Somewhere else, it can mean a missed ride, a stalled hotel check-in, or a long call to a bank that is closed. Some of the fear is justified: cards do get declined abroad, banks do flag unfamiliar transactions, and the exchange rate at a till can be worse than the one on your phone.
These steps can help:
Carry a second way to pay that does not depend on your main card, ideally from a different provider, and keep it apart from your main card.
Keep a small amount of cash in the local currency for the first day.
Keep a buffer in the currency you will be spending, not only in naira, so a swing in the exchange rate does not shrink your trip while you are on it.
Check what each card charges for payments abroad before you leave, because the fee can differ a lot from one card to another.
The part of this fear that is not rational is the idea that one failed payment means everything has failed. Usually, it means we need the second option, and the point of having one is that the first failure becomes a small event.
This is the fear that does not stay in our own heads, because it arrives as a phone call and a familiar voice. Money for a hospital deposit or a parent's rent is needed quickly, and to a specific place. An emergency usually comes with a deadline, and the person usually asking cannot wait for an exchange rate to improve.
In these instances, what you can decide in advance is the route and the amount. Know how money reaches that person: which bank, which account name, which details, and whether it can arrive at all on a weekend or a public holiday. You can confirm the details and when you are a little calmer, in a calm moment, send what you can without without putting your housing or tuition and other commitments at risk.
Transfer times vary by route and by day, so learn how long your usual route takes before you need it, not on the day. Treat any delivery estimate as an estimate, and leave room around bank cut-off times.
We carry this fear because we care about the people on the other end of it. That is not something to fix. What we can do is make the next call a little less frightening by doing the dull preparation before it comes.
Frequently asked questions
Can you reverse a bank transfer sent to the wrong person?
Sometimes, but not always. It depends on the receiving bank, the type of transfer, and whether the money has already been spent. Contact your bank or provider immediately, because speed improves the chances, and expect that a fee may apply.
What should I do first if I sent money to the wrong account?
Contact your bank or provider straight away. Have the date, amount, transaction reference, and the recipient's details ready, and say what went wrong in plain terms. Do not wait to see whether the recipient notices.
How big should my emergency fund be if my income is irregular?
Start with one month of essential costs, then build towards three to six months. People with irregular income often aim for the higher end, because a gap can last longer. These are general guidelines, not financial advice.
Why is my payment pending or on hold?
Providers often hold a payment for verification when the sender's details and the receiving account name do not match, or when more information is needed about the source of the funds. You may be asked for documents before the money is released.
How do I avoid running out of money when I travel?
Carry two ways to pay from different providers, keep a little cash in the local currency, keep a buffer in the currency you will spend, and check each card's fees for payments abroad before you leave.
Is it normal to be anxious about money?
Yes. Money worries are common, and some of them are rational. A useful way to handle them is to separate the part that is a real risk from the part that is not, and then act on the part you can change.
Fees and rates: deposits by ACH, SEPA, or Faster Payments cost 0.8%, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. Currency conversion costs 1%, capped at $6. Withdrawals to a Nigerian bank account cost ₦35. A virtual card costs $5 to create, once, with no monthly fee, and payments on non-US websites can carry a cross-border fee of 2% plus $0.50. A recall of a USD, EUR, or GBP payment carries a fixed fee of $50, €25, or £25, even if it fails. Exchange rates vary with a margin over the mid-market rate.
In the early days of running a business, many people just use their personal accounts. However, as you expand your client base and start to cover business expenses, your personal account won’t cut it. Your business needs to have a business account.
It makes it easier to receive and spend money in a separate account; it’s also easier to track monthly expenses without reading multiple bank statements.
What do you need to open a business bank account? The list is short, but it varies slightly depending on your business type, your tax ID, and where you, the owner, live. Here’s what you will need to open a US business account, how the requirements differ by structure, and what founders and business owners living outside the United States should expect.
To open a US business bank account, you typically need your EIN, business formation documents, ownership and control details, and a personal photo ID for each owner. Sole proprietors may use a Social Security number instead of an EIN. Some banks also ask for a business licence and an opening deposit.
The full checklist
Most business bank accounts require the same set of documents:
Your EIN: The employer identification number is the IRS tax ID for your business. Some sole proprietors can use their Social Security number instead.
Business formation documents: For an LLC, this is usually the Articles of Organisation or Certificate of Formation. For a corporation, it is the Articles or Certificate of Incorporation. Sole proprietors who trade under a name other than their own may need a DBA (doing business as) or assumed name certificate.
Ownership agreement, if you have one: Banks commonly ask for an operating agreement (for an LLC) or a partnership agreement that shows who owns the business.
Ownership and control details: For legal entities, US banks must collect the name, date of birth, address, and ID number of each person who owns 25% or more of the business, plus one person with significant control, such as a CEO or managing member. Foreign owners can provide a passport number. The FinCEN guidance on the customer due diligence rule explains the rule.
A personal photo ID for each owner: A driver’s licence or passport is typical, and some banks also ask for a second form of ID.
A physical business address: Some large banks do not accept a registered agent address, virtual address, or PO box as your business address.
Proof the business is registered, or a business licence: Banks may ask for a document showing your business is registered with a government agency, and for any state or local licences you hold.
An opening deposit: Initial deposits and minimum balances vary by bank and account type, and some banks waive them.
Requirements vary by bank, so check your chosen bank’s own list before you go. This is general information, not legal advice.
Requirements by business type
This list is the same for every business, but what you have to provide changes depending on your structure. A sole proprietor has the fewest requirements, and a corporation or partnership has the most paperwork.
Sole proprietor
LLC
Corporation
Partnership
Tax ID
Social Security number, or an EIN
EIN
EIN
EIN
Registration documents
A DBA or assumed name certificate, if you use a business name
Articles of Organization or Certificate of Formation
Articles or Certificate of Incorporation
Partnership agreement or business registration
Ownership agreement
Not applicable
Operating agreement, usually for multi-member LLCs
Ask your bank what it needs, such as bylaws or a board resolution
Partnership agreement, or a signed statement if none exists
Photo ID
The owner
Each owner with 25% or more, plus one person with control
Each owner with 25% or more, plus one person with control
Each owner with 25% or more, plus one person with control
having to readPlease note:
Sole proprietors are not covered by the beneficial ownership rule because a sole proprietorship is not a separate legal entity. You are the owner, so your own ID is usually enough.
LLCs are the most common structure for freelancers and small online businesses. Multi-member LLCs are more likely to be asked for an operating agreement. Our guide to the best business bank accounts for an LLC compares the options.
Corporations and partnerships are asked to provide the founding documents showing who owns the business and who can sign on its behalf.
Not always, but banks prefer you have one. Some sole proprietors can open an account using their Social Security number, while LLCs, corporations, and partnerships are usually required to provide an EIN. Having one also keeps your personal number off your business records.
An EIN, or employer identification number, is a nine-digit tax ID assigned by the IRS to a business. It is free. The IRS says you never have to pay a fee for an EIN, so be wary of sites that charge.
Here is how to get one:
Apply online if you qualify: The IRS online tool is for businesses formed in the US or its territories that have a principal place of business there. You need the responsible party’s Social Security number or individual taxpayer identification number (ITIN).
Use the IRS hours: The online application runs at set times in Eastern Time, so check the IRS page before you start.
Apply once per day. You can apply for only one EIN per responsible party per day.
Keep the confirmation. Banks may ask for the IRS letter confirming your EIN, not just the number.
The IRS page on getting an EIN has the full details. If you do not qualify to apply online, for example, because your business is outside the US, you can apply by phone, fax, or mail instead. We cover that in the non-resident section below.
Requirements for non-residents
Non-residents can open a US business bank account, but it’s usually more difficult, and it depends on the bank. No federal rule bars it, yet each bank sets its own requirements for identity, address, and tax ID, and some do not accept foreign owners at all.
Here is what overseas founders usually need:
A US business entity and an EIN: Most founders form a US company, such as an LLC, and then get an EIN.
A valid passport: It usually replaces the Social Security number as your ID. US banks may record a passport number for foreign beneficial owners.
Formation documents and an ownership agreement: The same documents as in the checklist above.
Address evidence: A home address abroad, and a physical business address that the bank accepts.
Proof of what the business does: Some banks ask for contracts, invoices, a website, or evidence of the source of funds.
You can still get an EIN without a Social Security number or ITIN. The IRS instructions for Form SS-4 say you enter “foreign” on line 7b if the responsible party has neither. The online tool is not available to you if you have no residence or principal place of business in the US, so you apply by phone, fax, or mail. Fax usually returns the EIN within about four business days. By mail, allow about four to five weeks.
The common hurdles are:
Social Security number rules: Some banks require an SSN from each owner, and an EIN does not replace it.
Address rules: A registered agent address, virtual address, or PO box is often rejected as your business address.
In-person visits: Some traditional banks expect you to visit a branch.
Country and industry limits: Providers may exclude some countries or business types.
Extra checks: A bank may ask follow-up questions before approving the account, and incomplete answers can slow the process.
Opening the account is one step, and getting paid across borders is another. A US business account is designed for domestic payments, so if you invoice clients abroad or pay suppliers in other countries, you may want a second layer to handle foreign currencies.
Grey offers multi-currency accounts, with no account opening fees, no maintenance charges, and no minimum deposit, so adding it does not require an additional opening deposit. You can also create a proper USD business account in your business name.
Grey also helps you send and receive money from the US. You can fund a transfer from a US bank account via ACH or wire, choose the destination, and check the exchange rate and fees before confirming. If you work with people or suppliers in Nigeria, you can send money from the US to Nigeria without the recipient needing a Grey account.
Transfer times and fees depend on the destination, the funding method, and the recipient’s bank, so check the details on Grey before you send.
Frequently asked questions
What documents do I need?
You typically need your EIN, formation documents, ownership and control details, and a personal photo ID for each owner. Some banks also ask for a business licence, proof of address, and an opening deposit.
Do I need an EIN?
Not always. Some sole proprietors can use their Social Security number, but LLCs, corporations, and partnerships are usually required to provide an EIN, and many banks prefer one for each business. An EIN is free from the IRS.
Can a sole proprietor open one?
Yes. A sole proprietor can open a business account using a personal ID and a Social Security number or an EIN. If you trade under a name other than your own, you may also need a DBA or assumed name certificate.
Can a non-resident open one?
Sometimes. It depends on the bank. Non-residents usually need a US business entity, an EIN, and a passport; some banks also require a Social Security number or an in-person visit. Ask the bank what it accepts before you apply.
Do I need a deposit?
It depends on the bank and the account. Initial deposits and minimum balances vary, and some banks waive them. Check the account terms before you apply.
Can I open one online?
Often yes. Many banks let you apply online and upload your documents, though some ask you to visit a branch. Have your documents ready as digital copies either way.
I was scrolling through Temu a couple days ago and saw a really nice jacket that was fairly priced. As strong as I would like to think my will is, unfortunately I couldn’t resist, so it went in the cart, along with a new pair of gym shoes and a new phone case.
I got my first orders wrong because I just wasn't looking in the right place, and after getting burnt a few times, I’ve mastered the art of finding the perfect Temu order.
To get the best products on Temu, look at how many units a listing has sold rather than its star rating, read the specifications as well as the title, check buyer photos instead of studio images, and compare sizing charts against your own measurements. Stick to simple goods and avoid categories where quality varies most.
In the following paragraphs, I’ll be explaining in detail all you should know about getting exactly what you need on Temu.
Before you buy: set expectations
Temu is a marketplace, which means the items in your cart come from many different sellers, not from one shop with a single standard. Quality therefore varies from listing to listing, and the same-looking product can be a pleasant surprise from one seller and a dud from another.
That has two practical effects.
Quality is uneven: Low prices often indicate basic materials and light packaging. That is fine for a silicone spatula and risky for anything you need to last, fit perfectly, or plug into a wall.
Delivery depends on the warehouse: Items shipped from overseas take longer than items shipped from a warehouse or seller near you, so the delivery estimate matters as much as the price.
Where Temu genuinely delivers value is on simple, low-risk goods: organisers, kitchen gadgets, phone accessories, craft supplies, and basic home items. If you want to know how its prices stack up against another big marketplace, read our comparison on is Temu cheaper than AliExpress.
The rest of this guide assumes that your goal is good-enough items at a fair price, with no nasty surprises.
15 tips for buying well on Temu
Each of these Temu shopping tips is something you can check on the listing page in under a minute. Together, they cover most of the ways a cheap order goes wrong.
1. Read the specification, not the title
Titles are written to match searches, so sometimes, they are stuffed with keywords. The specification section is where the real details live: material, dimensions, weight, capacity, and compatibility. If a listing has no specification at all, treat that as a warning.
2. Check how many units have sold
Many listings show a units-sold figure. A product that thousands of people have bought and kept has been tested far more than one with ten glowing reviews. Look at volume first, then at the rating.
3. Look at buyer photos, not studio images
Studio shots show the best-case scenario under perfect lighting. Buyer photos show the item on a real table, on a real body, in daylight. Scroll to the review photos before you look at anything else.
4. Run a reverse image search on the main photo
Press and hold the main image, or save it, then search it with a reverse image tool. If the same polished photo appears on many unrelated listings, it is probably a generic stock image, and buyer photos matter even more.
5. Compare the size chart with your own measurements
Sizing labels vary by seller, so “M” tells you very little. Measure a similar item that fits you well, then compare it with the centimetres or inches in the size chart, not the label.
6. Read the three-star and one-star reviews first
Five-star reviews tell you what the seller wants you to believe. Low and middling reviews usually name the actual problems: sizing, smell, a flimsy zip, a cable that stops charging. If the same complaint appears repeatedly, it’s most likely a problem.
7. Check dimensions properly
Be sure you’re getting the proper size, as it can sometimes be difficult to picture how big or smal things are. Take the stated length, width, or height and compare it with an object at home using a tape measure. A “30 cm” organiser is smaller than most people picture.
8. Look for specific materials
“Premium” and “high quality” mean nothing. “100% cotton”, “stainless steel”, or “BPA-free silicone” are claims you can check against the spec and the reviews. Vague wording often means the seller has nothing specific to claim.
9. Check the delivery estimate and where the item ships from
Some items ship from nearby, and others come from overseas. Look at the estimated delivery date and any local-warehouse label before you pay, especially for gifts or anything with a deadline.
10. Ignore the crossed-out price
Temu’s own terms of use tell shoppers not to rely on the strike-through price when deciding what to buy. Compare the price you would actually pay with similar listings instead.
11. Compare two or three similar listings
Search for the same item and open several results. Put the specifications, units sold, and buyer photos side by side. The cheapest listing is rarely the best, and the gap between it and the second-cheapest is often small.
12. Check whether the item can be returned
Temu’s returns page states that most items can be returned within 90 days of purchase, and that the first return on each order is free. Some items, such as underwear, groceries, and customised products, cannot be returned, so check the listing before you order.
13. Count the total, not the headline price
Temu’s terms state that listed prices exclude customs duties, sales taxes, and shipping, which are charged separately where applicable. Check the checkout total before you confirm, and do not pad your cart with filler just to reach a free-shipping threshold.
14. Start with one item
Before a big haul, order a single low-cost item from a seller. See how it arrives, how it feels, and how long delivery takes. Then decide whether to order more.
15. Photograph the item as soon as it arrives
Take photos of the item, the packaging, and any damage straight away. If you need a refund, clear evidence taken on delivery day makes your case much easier, and return windows start from the purchase date.
Reading reviews and photos properly: how to spot fake reviews on Temu
Reviews help, but they are not proof, so treat them as clues and look for patterns.
Buyer photos beat studio shots A real customer photo shows the colour, the finish, and the true size. If a listing has hundreds of reviews and almost no customer photos, be cautious.
Volume beats a perfect rating A 4.4 from thousands of buyers tells you more than a 5.0 from a dozen. Small numbers are easy to skew.
One-review accounts: The same guidance says a reviewer who created an account to write a single review for one product may be fake.
Copy-and-paste praise: Lines like “great product, fast delivery” repeated across reviews, with no detail, say little.
Four-star fakes: Some fake positive reviews avoid the top score to look believable, so do not dismiss every moderate rating, and do not trust every high one.
Look for detail The most useful reviews mention specific details, such as how a seam held up after washing, how long a battery lasted, and how the item compared with its photo. Mixed reviews that mention both pros and cons are usually more informative than pure praise.
Temu’s terms of use say reviews must be truthful and based on first-hand experience, and that sponsored reviews must be clearly marked, but they also allow Temu to remove reviews at its discretion. Use that as a reminder that you are the final check.
What to buy on Temu and what to avoid
Categories that tend to work
Organisers and storage: Boxes, hooks, and drawer dividers are simple objects with few ways to fail.
Kitchen gadgets: Silicone tools, measuring spoons, and basic utensils, as long as the listing names the material.
Phone cases and stands: Cheap to replace, and buyer photos show the fit.
Craft and stationery supplies: Beads, stickers, notebooks, and pens are easy to judge from reviews.
Home and party decor: Fairy lights are a common pick, though anything with a plug deserves extra care.
Categories that often disappoint
Anything that charges or plugs in: Chargers, power banks, and cheap batteries are where poor quality costs the most, so consider established brands.
Items where fit matters: Shoes, fitted clothing, and bras depend on sizing that varies by seller.
Skincare, supplements, and anything you swallow or apply: Ingredient claims are hard to verify from a listing.
Children’s products: Toys and baby items should meet safety standards you can check.
Brand lookalikes: If a listing resembles a famous brand at a fraction of the price, expect it to be a copy.
None of this means every item in these groups is bad. It means mistakes cost more, and the savings are rarely worth the risk.
Paying safely and without FX surprises
A good deal can still get expensive at the payment step. Prices on Temu are listed in dollars for US shoppers, and if your card is not a dollar card, your bank converts the amount and may add a foreign transaction fee or a weaker exchange rate. On a $9 order, the difference is small. Across a big haul, it adds up.
A few habits help:
Pay in the listed currency: When checkout offers to convert the price for you, the rate is often worse than your card’s. Pay in the listed currency where you can.
Keep your main card number off shopping apps: Use a separate card for marketplace orders so your saved number isn’t your everyday card. If you are choosing between formats, see our guide to virtual vs physical card.
With Gey, you can pay with a virtual card that charges your USD balance, so an order priced in dollars does not require currency conversion on Grey's side. You can also fund your card from a USD balance and keep your shopping money apart from everything else. Card creation and some payments carry fees, and availability depends on where you live, so check Grey's pricing page for current details.
Grey is a financial technology company, not a bank. Exchange rates, fees, limits, and transfer times vary by destination and are subject to change.
Frequently asked questions
How do I find good products on Temu?
Start with simple, low-risk items, then check the specifications, units sold, buyer photos, and the lower-rated reviews. Compare two or three similar listings, and order a single item first before a bigger purchase.
Are the reviews real?
Some will be, and some may not be. The FTC says it can often be nearly impossible to tell for sure, so look for patterns such as bursts of reviews in a short window, one-review accounts, and copy-and-paste praise. Detailed reviews with buyer photos are the most useful.
Will I pay customs?
Possibly. Temu’s terms state that listed prices exclude customs duties, sales taxes, and shipping, which are charged separately where applicable. The US duty-free treatment for low-value parcels was suspended for all countries from 29 August 2025, so check your checkout total. This is general guidance, not professional tax advice. Consult a certified tax professional for your specific situation.
How do returns work?
Temu’s returns page says most items can be returned within 90 days of purchase, with the first return on each order free. Some items, including underwear, groceries, and customised products, cannot be returned. Refunds go to your original payment method or to a Temu credit balance, and bank refunds can take several business days. Check the listing for its exact terms.
Is it safe to pay by card?
Card payments carry some risk anywhere online. Shop only in the official app or on the official site, check your statements, and consider using a virtual card funded with just the amount you need.
International money transfers have made it easier to send funds across borders, but knowing where your money is after hitting the send button remains a common frustration. A payment can leave your bank account without immediately appearing in the recipient's, leaving you wondering whether it's processing, sitting with an intermediary bank, or facing an unexpected delay.
This lack of visibility has long been a challenge in cross-border banking. Unlike local transfers, international payments may pass through several financial institutions, making it difficult for customers to follow their progress or know when to expect delivery.
That's where SWIFT GPI (Global Payments Innovation) makes a difference. Introduced to improve international payment services, it gives participating banks a way to track cross-border transfers from the sending bank to the receiving institution. Each payment receives a unique reference called a UETR (Unique End-to-End Transaction Reference), which works much like a parcel tracking number.
With SWIFT GPI, customers can get better visibility into their payments, identify delays, and know when funds have reached their destination. Most GPI payments are credited within minutes to hours, although processing times vary.
What is SWIFT GPI?
SWIFT GPI (Global Payments Innovation) is an upgraded international payment framework introduced by SWIFT to make cross-border bank transfers faster, more transparent, and easier to track.
Traditional international wire transfers can take several business days to reach their destination, especially when multiple intermediary banks are involved. SWIFT GPI was developed to address these delays by improving how banks process and monitor international payments.
One of its biggest advantages is speed. Most GPI-enabled payments are credited within 30 minutes, although actual processing times depend on the banks, countries, and compliance checks involved.
It also introduces end-to-end payment tracking through a unique reference number called a UETR (Unique End-to-End Transaction Reference). This allows participating banks to follow a payment throughout its journey and provide updates on its status.
Another important feature is transparency. Customers can get better visibility into intermediary bank charges, foreign exchange costs, and the amount received by the beneficiary. Payment information is also preserved throughout the transfer process, reducing the risk of missing or altered remittance details.
The three key features of SWIFT GPI
GPI stands for Global Payments Innovation. It improves the traditional SWIFT network by addressing three major concerns associated with international transfers: delays, hidden charges, and the difficulty of tracking payments. Here are the three features that make it different:
Speed: International transfers no longer have to mean waiting several business days. Nearly 60% of payments settle within 30 minutes, while almost all are completed within 24 hours. However, actual processing times depend on the banks, countries, and compliance checks involved.
Transparency: Knowing how much money will arrive is just as important as knowing when it will get there. The system provides better visibility into foreign exchange rates and fees deducted by intermediary banks. This helps senders understand the cost of transferring money and gives recipients a clearer picture of what to expect.
Tracking: Every payment receives a unique 36-character reference called a UETR (Unique End-to-End Transaction Reference). Participating banks use this number to monitor the transfer from the sending institution to the receiving bank, providing updates on its progress and final credit.
Together, these features make cross-border payments faster, easier to monitor, and more transparent for everyone involved.
How to track a SWIFT GPI transfer
Once an international transfer has been sent, the next thing you probably want to know is whether the money is still moving between banks or has reached the recipient. Fortunately, you don't have to rely entirely on waiting for a confirmation message. You can request a payment trace using your UETR.
Here's how to do it:
Find your UETR: Check your payment confirmation receipt or contact the sending bank to request the 36-character Unique End-to-End Transaction Reference.
Contact your bank: Ask the bank that initiated the transfer to check its SWIFT GPI Tracker using your UETR. Some banks also provide tracking through their online banking portals. You can visit the official SWIFT website to learn more about how the international payment network works.
Review the payment status: Your bank can help you understand where the funds are and whether the transfer has been completed, delayed, or rejected.
What do the different tracking statuses mean?
As you check the payment, you may come across a few common status updates:
In Progress: The payment is still moving through the banking network or awaiting confirmation.
Completed: The receiving bank has confirmed that the beneficiary's account has been credited.
On Hold: The transfer has been paused, possibly because of compliance checks or missing information.
Rejected: A bank has declined the payment, and you may need to contact the sender's bank for an explanation.
One important detail: don't confuse your UETR with a SWIFT code. A UETR tracks an individual payment, while a SWIFT/BIC identifies a bank. If you're unsure about the difference, Grey's guide to SWIFT codes, BICs and IBANs breaks down what each one does and when you need it.
How long does a GPI transfer take?
Speed is one of the biggest advantages of SWIFT GPI. Nearly 60% of payments are credited to recipients within 30 minutes, while almost 100% are completed within 24 hours. However, these timelines aren't guaranteed, and certain issues can keep your money in transit longer.
Here are three common reasons for delays:
Compliance checks: Banks may pause a transfer for anti-money laundering (AML), sanctions screening, or additional identity verification. Manual reviews can add hours or days.
Cut-off times and holidays: Payments sent after banking hours, during weekends, or on public holidays may not be processed until the next working day.
Incomplete details: Incorrect account numbers, beneficiary names, or missing intermediary bank information can trigger additional checks.
Currency conversion can also affect how much the recipient receives. Understanding foreign transaction fees helps you prepare for these extra costs.
For UK payments, CHAPS provides another option for time-sensitive, high-value transfers, with same-day settlement when payments are submitted before the bank's cut-off time. You can also read our guide to how CHAPS payments work to understand the process, key requirements, and when to use this payment method
Sending and tracking transfers with Grey
International transfers involve more than moving money from one bank account to another. Exchange rates, transfer fees, delivery times, and payment visibility all matter, particularly when you're sending money across borders regularly.
Grey simplifies this process by bringing international transfers and multicurrency banking together. Users in the US can send money internationally, including to India through the US-to-India transfer service. Before confirming a transaction, users can review the applicable exchange rate and transfer charges, making it easier to know how much the recipient will receive.
Beyond sending money, Grey's foreign currency accounts provide a place to receive and hold international payments without immediately converting the balances. This is particularly useful for freelancers, remote workers, and businesses dealing with overseas clients.
By bringing these services together, Grey makes it easier to manage international income, handle cross-border payments, and keep money accessible for future transactions.
Frequently asked questions about SWIFT GPI
1. What is SWIFT GPI?
SWIFT GPI is an upgraded international payment framework that makes cross-border bank transfers faster, more transparent, and easier to track. It allows participating banks to monitor payments as they move through the banking network, giving senders and recipients better visibility into transfer progress, processing times, and intermediary bank charges.
2. What does GPI stand for?
GPI stands for Global Payments Innovation. It is a modern payment standard introduced by SWIFT to improve traditional international bank transfers. Its main purpose is to address common problems associated with cross-border payments, including slow processing, limited tracking information, and unclear intermediary bank fees.
3. How do I track a SWIFT payment?
To track an international SWIFT payment, request the 36-character UETR (Unique End-to-End Transaction Reference) from your sending bank. You can then ask the bank to check the payment through its SWIFT GPI tracking system. Some banks also provide tracking through their online banking portals, allowing you to check the transfer's progress.
4. What is a UETR?
A UETR, or Unique End-to-End Transaction Reference, is a 36-character code assigned to an individual international payment. It works much like a parcel tracking number, helping participating banks identify and follow a transaction throughout its journey. Your bank can use this reference to investigate any delays and confirm the progress of your payment.
5. How long does a GPI transfer take?
SWIFT GPI payments are generally faster than traditional international wire transfers. Roughly 60% settle within 30 minutes, while nearly 100% reach their destination within 24 hours. However, these figures aren't guarantees. Compliance reviews, banking holidays, incorrect beneficiary details, and processing by intermediary banks can still cause delays.
6. Can I track my transfer with Grey?
Yes. Grey provides transfer status updates within its platform, helping users follow their transactions. However, if you're tracking an external SWIFT bank transfer, you'll need to obtain the UETR from the sending bank. Grey's transfer tracking and SWIFT's bank-to-bank tracking are separate processes.
Send and track transfers with Grey
International payments don't have to be complicated. With Grey, you can send money across borders, monitor transfers, and manage multiple currencies, all from one platform.
An old classmate of mine started freelancing in the US a couple of years ago. At first, it was a few small projects, and he got paid in his personal account, with nothing formal in place. He’s always had a great work ethic, so it wasn’t surprising to see his business take on getting steady clients, bigger contracts, and subsequently, a large, sustainable income that had grown massively.
During one of our catch-up calls, I got to understand that, as a sole proprietor, his business and personal finances are legally one and the same, so a dispute or debt on the business side could generally reach his personal savings. He’d been thinking about whether he needed an LLC. We researched together and found that the answer depended on his risk, income, and his clients, not on a legal rule.
This guide details our findings and covers what an LLC does, what it costs, and when it’s worth forming.
Typically, you don’t need an LLC to freelance in the US. Most freelancers start as sole proprietors and can work legally without one. You should consider an LLC once you want liability protection, have more to lose, or want a more professional setup. It generally separates your personal and business assets.
Do freelancers need an LLC?
No. You do not need an LLC to freelance in the US. If you do freelance work without registering any other business structure, you are automatically treated as a sole proprietor.
That is the default for most freelancers, and it is simple. There is no formation filing, no separate business entity, and no annual state fee to maintain one. Your business income is reported on your personal tax return, and you pay self-employment tax on your profits.
The trade-off is that a sole proprietorship is not separate from you. The SBA says sole proprietors can be held personally liable for the business’s debts and obligations. If a client sues you or a business debt goes unpaid, your personal savings and property may be exposed.
Being a sole proprietor does not mean you can ignore the paperwork. Depending on your city, state, and line of work, you may still need a business licence or permit, and you may need to register a trade name if you work under a name other than your own. Check with your state and local offices.
The main benefit of an LLC for a freelancer is liability protection: it creates a separate legal entity, so your personal assets are generally shielded from the business’s debts and lawsuits. That is not the only advantage. Here are the benefits worth weighing:
Liability protection The SBA says LLCs protect you from personal liability in most instances, so your personal assets are generally not at risk if the LLC is sued or cannot pay its debts. The protection has limits. It does not usually cover debts you personally guaranteed, fraud, or your own wrongful acts. Professional insurance is a separate layer of protection, and many freelancers use it with or without an LLC.
Separate business and personal money An LLC gives you a reason to run a dedicated business bank account, which makes your records cleaner at tax time. Keeping the two apart is also generally expected if you want the liability protection to hold up.
Credibility “Jane Doe Design LLC” immediately looks more established to some clients than an individual name, and some larger clients prefer to contract with a registered business.
Simple pass-through taxation by default The SBA says LLC profits and losses can pass through to your personal income without facing corporate taxes. For income tax purposes, the IRS treats a single-member LLC as a disregarded entity separate from its owner unless it elects otherwise.
Tax options later An LLC can file Form 8832 to elect to be taxed as a corporation, and a qualifying LLC can elect S corporation status. These elections change how the business is taxed and add filing requirements, so they are worth discussing with a tax professional before you commit. See the IRS guidance on LLCs filing as a corporation or partnership.
One thing an LLC does not do by default is cut your tax bill. The SBA notes that LLC members are considered self-employed and pay self-employment tax contributions toward Social Security and Medicare, just as sole proprietors do.
Downsides and costs
The main downsides of an LLC are the costs and the admin: you pay a state filing fee to form it, and most states charge fees or taxes to keep it active. Weigh these against the benefits above:
Filing fees: Every state charges a fee to form an LLC, and the amount varies widely.
Ongoing costs: Many states require an annual or biennial report, and some charge a yearly fee or tax on top.
More paperwork: You need a registered agent, a filing with your state, and, in many cases, an operating agreement. You also need to keep business and personal money apart.
No automatic tax savings: A single-member LLC is taxed like a sole proprietorship by default, and self-employment tax still applies.
Protection is not absolute: Personal guarantees, fraud, and your own wrongful acts can still put your personal assets at risk.
Costs depend heavily on where you form the LLC. These examples come from state agencies, and you should check the current figures before you file:
Wyoming: a $100 filing fee for Articles of Organisation, and an annual report fee that starts at $60.
Florida: $125 to file, made up of a $100 filing fee and a $25 registered agent designation fee, plus a $138.75 annual report.
Texas: a $300 filing fee for the certificate of formation.
California: an $800 annual tax for every LLC doing business or organised in the state, and an extra fee once California income passes $250,000. The California Franchise Tax Board sets out the details.
The gap between states can be large. A freelancer in a low-fee state pays far less to keep an LLC than one in a state with a high annual tax, and an LLC formed in one state may need to register in another if you work from there. For a state-by-state breakdown, see our guide to how much it costs to start an LLC.
When should a freelancer form an LLC?
A freelancer should form an LLC when the risk of losing personal assets or of a client’s requirements outweighs the yearly cost of maintaining one. If you are asking at what income level you need an LLC, there is no income threshold that makes one mandatory. It is a judgment about risk, not a legal threshold.
These signs suggest it may be time:
You have more to protect: A home, savings, or other assets are all exposed if you are sued or owe a business debt as a sole proprietor.
Your work carries real risk: If a mistake could cost a client a lot of money or cause injury or damage, the stakes rise.
Your clients are getting bigger: Larger clients may prefer or require a registered business, and their contracts often carry more liability.
You are hiring or subcontracting: Working with other people adds risk and paperwork.
You are taking on debt or signing leases:. Contracts like these are where limited liability matters most.
Your income is steady: If the business is no longer a side project, the annual cost is easier to justify.
There are also good reasons to wait. If you are just starting out, earn little, do low-risk work, or live in a state with a high annual tax, staying a sole proprietor and using clear written contracts may be enough. Many freelancers start that way and convert later.
The SBA’s guide to choosing a business structure is a useful starting point. It notes that ownership rules, liability, taxes, and filing requirements vary by state, and that LLCs can have a limited life in many states, so check the rules where you live.
This is general guidance, not professional tax advice. Consult a certified tax professional for your specific situation. It is also not legal advice, so speak to a qualified lawyer about your liability.
Getting paid as a freelancer
Whatever structure you choose, you get paid by sending clear invoices and giving clients an easy way to pay. Both matter more when your clients are overseas.
Start with the paperwork. A written agreement that sets out the scope, rate, due date, and payment method prevents most disputes. Our guide to writing a freelance contract covers the key clauses. On each invoice, state the currency, the due date, and exactly how the client should pay.
Payment is where freelancers often lose time. Overseas clients may pay by international wire, which can come with intermediary fees and unclear exchange rates. If you form an LLC, you will also want your client payments to land in a separate business account, not your personal one.
Grey can help with the money side. You can open a USD account with Grey, a multi-currency account that lists no account opening fees, no maintenance charges, and no minimum deposit. That gives you a place to receive and hold your freelance income. Grey also lets you get paid from the US and move the money onward: fund a transfer from a US bank account by ACH or wire, then check the exchange rate and fee before you confirm. If you support family or a team in Nigeria, for example, you can send money from the US to Nigeria, and the recipient does not need a Grey account.
Transfer times and fees depend on the destination, the funding method, and the recipient’s bank, so check the details on Grey before you send.
Frequently asked questions
Do I need an LLC to freelance?
No. You can legally freelance in the US as a sole proprietor without forming a business entity. An LLC is optional and mainly adds liability protection.
When should I form one?
Form an LLC when the risk of losing personal assets or a client's requirements outweighs the annual cost of maintaining one. Common triggers are bigger clients, higher-risk work, hiring help, signing leases or taking on debt, and having more assets to protect.
How much does an LLC cost?
It depends on the state. For example, Wyoming charges $100 to form an LLC and at least $60 for its annual report, while Florida charges $125 to form one and $138.75 for the annual report. California charges every LLC an $800 annual tax. Check your state's Secretary of State for current fees.
Can I freelance as a sole proprietor?
Yes. If you do freelance work without registering another structure, you are a sole proprietor by default. You may still need a local business licence or permit, and you are personally liable for business debts.
Does an LLC save tax?
Not by itself. A single-member LLC is taxed like a sole proprietorship by default, and self-employment tax still applies. An LLC can elect corporate or S corporation treatment, which may change your tax, so speak to a tax professional first.
How do I get paid by overseas clients?
Agree on the currency and payment method in your contract, then state them on every invoice. Clients can pay by bank transfer, and a multi-currency account such as Grey's can provide a place to receive and hold the funds. Check the rate and fee before you move it.
The short answer is in the next paragraph, but the rest of this guide covers the details, from the forms you need to the limits on how much control you can have.
A 1099 worker is an independent contractor, not an employee, so most employment rules do not apply. You do not withhold payroll tax, but you should collect a Form W-9, file a 1099-NEC if you pay a US contractor $2,000 or more in a year, and avoid controlling how they work. Misclassifying workers carries penalties.
Are 1099 workers really employees?
No. A 1099 worker is an independent contractor, not an employee. “1099 employee” is a popular shortcut, but it blends two different legal relationships, and the difference decides almost every rule in this guide.
The name comes from the form. Businesses report what they pay contractors on Form 1099-NEC, while employees receive a W-2. That one difference reflects a bigger one. An employee works for your business under your direction, and you withhold income and payroll taxes from their pay. A contractor runs their own business, decides how the work gets done, and pays their own taxes, including self-employment tax.
Employee
1099 contractor
Year-end form
W-2
1099-NEC, if payments pass the threshold
Tax withholding
You withhold income tax and payroll taxes
You do not withhold (backup withholding aside)
Benefits
Eligible for employer benefits
Not eligible as a contractor
Control
You direct how, when, and where the work is done
They decide how the work is done
Taxes on their earnings
Employer and employee share payroll taxes
Contractor pays self-employment tax and estimated tax
The label in your contract does not settle the question. The IRS looks at the real working relationship, not just the title on the page, so a person you treat like staff can still be an employee even if you call them a contractor. If you want the full definition, read our guide to what a 1099 employee is. A “1099 job” is simply work performed under this type of contractor arrangement.
The rules below apply to US tax law. If you hire people in other countries, local employment rules may also apply.
The rules for engaging a 1099 contractor
Engaging a 1099 contractor comes down to six rules: confirm the work is genuinely independent, put the terms in writing, collect tax details before you pay, pay against invoices, keep records, and report the payments after the year ends. Use this checklist before the first payment goes out.
Confirm the work is genuinely independent: The contractor should control how the work is done, use their own tools, and be free to work for other clients. If you would need to train, schedule, and supervise them like staff, you are probably hiring an employee.
Put the terms in writing: A contract should cover scope, deliverables, deadlines, fees, payment terms, ownership of the finished work, confidentiality, and how either party can terminate the arrangement. State that the contractor is responsible for their own taxes, insurance, and equipment. A contract shows intent, but it does not decide classification on its own.
Collect a Form W-9 before the first payment: It provides the contractor’s legal name, address, and taxpayer identification number (TIN). Keep it on file. The IRS advises keeping it for four years.
Pay against invoices: The contractor invoices you for the work, and you pay the agreed amount in full on the agreed date, with no payroll deductions.
Keep clear records: Note the date, amount, and invoice number of every payment during the calendar year, because you will need the total when it is time to report.
Report what you paid: If you pay a contractor above the reporting threshold, file Form 1099-NEC and send the contractor a copy by 31 January of the following year.
Contractors based outside the US work differently. A foreign contractor cannot complete a W-9, which is for US persons. They provide a Form W-8BEN (for individuals) or W-8BEN-E (for entities) instead, and the IRS says that a valid W-8 generally exempts the payee from backup withholding and from Form 1099 reporting. Whether any other US tax rules apply can depend on where the work is performed, so check with a tax professional before you pay someone abroad.
Forms and thresholds
Two forms matter for most small businesses: Form W-9, which the contractor completes, and Form 1099-NEC, which you file.
Form W-9 The contractor fills in their name, business name (if applicable), tax classification, address, and TIN (a Social Security number or an employer identification number), then signs it. You keep the form in your records. You do not send it to the IRS. Ask for it before the first payment, because if a US contractor does not provide a TIN, you generally have to apply a 24% backup withholding to what you pay them.
o pay themThe IRS instructions for requesters of Form W-9 confirm that rate and say it applies straight away to nonemployee compensation. If you do backup withholding, you report it on Form 945.
Form 1099-NEC NEC stands for nonemployee compensation, which is what you pay a contractor for services. You report the total you paid each contractor during the calendar year, not each individual payment. The reporting threshold has changed recently:
Payments made in 2025: $600 or more.
Payments made after 31 December 2025: $2,000 or more, which may be adjusted for inflation from 2027.
That means payments you make during 2026 are reported in January 2027, and the $2,000 threshold applies. The IRS instructions for Forms 1099-MISC and 1099-NEC set out the current figures and are worth checking each year.
The deadline is 31 January. You send one copy to the IRS and one to the contractor, and if that date falls on a weekend or legal holiday, it moves to the next business day. 31 January 2027 is a Sunday, so the deadline will move to Monday, 1 February. If you file 10 or more information returns in a year, you must file them electronically.
A few more points are worth knowing:
Payments to corporations generally do not need a 1099-NEC, though attorneys’ fees are an exception.
Late or missing filings can lead to penalties, and the amount increases the longer you wait.
For a plain-English overview of the wider 1099 family, see what a 1099 form is.
This is general guidance, not professional tax advice. Consult a certified tax professional for your specific situation.
What you cannot do
You cannot control how a 1099 contractor does the work, treat them like a member of staff, or offer them employee benefits as if they were one. Doing so puts the arrangement at risk of being reclassified as employment, regardless of what your contract says.
The IRS sorts the evidence into three groups, and no single factor decides the outcome:
Behavioural control. Do you control, or have the right to control, what the worker does and how they do it? Setting their daily hours, dictating their methods, requiring training, or supervising their day-to-day work all point towards employment.
Financial control. Do you control the business side of the job? Reimbursing expenses, supplying tools, and deciding how they are paid all matter. A contractor typically invoices, uses their own equipment, and can make a profit or a loss.
Type of relationship. Is there a written contract, or are there employee-type benefits such as insurance, a pension plan, or paid leave? Is the relationship ongoing, and is the work a key part of your business?
What you can do is agree on the result. You can set deadlines, deliverables, quality standards, and confidentiality terms. You can also end the contract if the work is not delivered. The line is between controlling the outcome, which is fine, and controlling the method, which is not.
Misclassification is the main risk. It means treating a worker as a contractor when the facts say they are an employee. If the IRS reclassifies them, you may owe employment taxes, plus penalties and interest, and state agencies may take their own action. If you are unsure, the IRS offers Form SS-8, which either you or the worker can file for an official determination, though it can take at least six months.
There is also the Voluntary Classification Settlement Program, which allows eligible businesses to reclassify workers as employees going forward and receive partial relief from federal employment taxes.
Paying 1099 contractors
Always pay a 1099 contractor on time, against an approved invoice, and in a way that leaves a clear record. Late or messy payments strain the relationship, and they make your year-end reporting harder.
This is where many businesses hit friction, especially when the contractor lives abroad. International wires can carry fees, exchange rates can be unclear, and the timing can be hard to predict. A contractor who has to chase a payment is also more likely to look for other work.
With Grey, you can pay contractors in the US by funding your account from a US bank account via ACH or wire, selecting the destination, entering the contractor's bank details, and checking the exchange rate and fees before confirming. Grey also lets you hold and send multiple currencies, so you can keep a balance in the currencies you pay in. If your contractor is in India, you can send money from the US to India by bank transfer or UPI, and the recipient does not need a Grey account.
A simple routine keeps things clean:
Collect the right form first: a W-9 for a US contractor, or a W-8BEN for an individual abroad.
Approve the invoice and agree on the currency.
Send the payment and keep the confirmation with the invoice.
Add the amount to your running total for the year.
Transfer times and fees depend on the destination, the funding method, and the recipient's bank, so check the details on Grey before you send.
Grey is a financial technology company, not a bank. Exchange rates, fees, limits, and transfer times vary by destination and are subject to change.
Frequently asked questions about the rules for 1099 employees
Is a 1099 worker an employee?
No. A 1099 worker is an independent contractor who runs their own business, pays their own taxes, and decides how the work gets done. Employees receive a W-2 and have taxes withheld from their pay.
What forms do I need?
For a US contractor, you need a Form W-9 from them before you pay, and you file Form 1099-NEC if you pay them above the threshold. If you apply backup withholding, you also file Form 945. For an individual contractor based abroad, you generally collect a Form W-8BEN instead of a W-9.
What is the 1099 threshold?
For payments made after 31 December 2025, the threshold for Form 1099-NEC is $2,000 in a calendar year. It was $600 for payments made in 2025, and it may be adjusted for inflation from 2027.
Can I set their hours?
Generally, no. Setting a contractor’s daily hours is a sign of control and points to an employment relationship. You can agree on deadlines and delivery dates, but the contractor should decide when and how they work to meet them.
What is misclassification?
Misclassification is treating someone as an independent contractor when the facts show they are an employee. It can lead to back employment taxes, penalties, and interest, so check the IRS tests before you engage anyone.
How do I pay an overseas contractor?
Collect their tax form, agree on the currency, approve the invoice, and send the payment. With Grey, you can fund your account from a US bank account, enter the contractor’s bank details, and review the exchange rate and fees before confirming.
If a form marked "1099-MISC” has landed in your inbox, or you need to send one, then you’ve found the perfect article that explains all you need to know. I explain what the 1099-MISC form reports, who gets one, how it differs from the 1099-NEC, and what to do with it.
The 1099-MISC is one of the IRS 1099 forms, and it has changed significantly in recent years. It reports miscellaneous income such as rent, prizes, awards, and certain legal settlements. Since 2020, contractor and freelance pay has been reported on the separate 1099-NEC form, so the 1099-MISC now covers other income categories. The payer sends it to the recipient and the IRS.
What is a 1099-MISC form?
A 1099-MISC form is an IRS information return that reports certain payments that are not wages and, since 2020, are not contractor pay. The IRS describes it as the form used to report rents, royalties, prizes and awards, and other fixed or determinable income.
It works like this. A business or other payer that paid you money during the year files the form with the IRS, so the IRS knows what you received. The payer also sends you a copy, so you can report the income on your own tax return. The form is not a bill, and it doesn’t say you owe tax. It’s a record of what was paid.
The 1099-MISC used to be the all-purpose 1099. Before 2020, freelancer and contractor pay was reported in one of its boxes. From 2020, that pay moved to a separate form, the 1099-NEC, which stands for nonemployee compensation. That change left the 1099-MISC for everything else, which is why people who still call every contractor form a “1099-MISC” are using an older name.
The 1099-MISC is one of several 1099 forms. For a wider look at the family, see our guide to what a 1099 form is.
What the 1099-MISC reports
The 1099-MISC reports rents, royalties, prizes and awards, and a handful of other payment types. Each category has its own box on the form, as shown in the table below. The box numbers follow the current IRS instructions for 2026 forms.
Box
What it reports
Typical examples
1
Rents
Rent a business pays for office space, equipment, or other property
2
Royalties
Payments for the use of intellectual property or natural resources
3
Other income
Prizes, awards, damages, and other taxable payments that fit no other box
4
Federal income tax withheld
Backup withholding, when a payee has not provided a taxpayer ID
6
Medical and health care payments
Payments to doctors and other health care providers for services
8
Substitute payments in lieu of dividends or interest
Payments a broker makes in place of dividends or tax-exempt interest
9
Crop insurance proceeds
Payments from crop insurance
10
Gross proceeds paid to an attorney
Payments to a lawyer in connection with legal services, such as a settlement paid through them
There are also a few less common items, such as direct sales of consumer products for resale and certain deferred compensation payments. The IRS instructions for Forms 1099-MISC and 1099-NEC list every box.
Two things you should note:
Settlements: A legal settlement is reported in different boxes depending on what it covers. Damages can fall under other income, while money paid to a lawyer is reported as gross proceeds paid to an attorney.
Backup withholding: If a payer withholds federal tax because you didn’t provide a taxpayer ID, it is reported in box 4, whatever the amount.
Who gets a 1099-MISC?
You get a 1099-MISC if a payer paid you at least the reporting threshold in one of the covered categories during the year. The threshold depends on the type of payment, and many of them have changed recently.
People who commonly receive one include:
Landlords: A business that pays you $2,000 or more in rent in the year, such as a company renting your office space, reports it on a 1099-MISC.
Prize and award winners: Prizes, awards, and other income of $2,000 or more are reported in box 3.
Royalty earners: Royalties of $10 or more are reported in box 2.
Health care providers: Medical and health care payments of $2,000 or more are reported in box 6.
Lawyers: Gross proceeds paid to an attorney of $600 or more are reported in box 10.
The $2,000 threshold is relatively new. For payments made after 31 December 2025, the minimum for most of these categories rose from $600 to $2,000, and it may be adjusted for inflation from 2027. The $10 minimum for royalties and substitute payments, and the $600 minimum for attorney proceeds, did not change. These figures come from the IRS instructions for 2026 forms, which payers use in early 2027. Backup withholding is reported regardless of the amount.
Payers send their copy to recipients by 31 January. They file with the IRS by 28 February if filing on paper, or 31 March if filing electronically. If a date falls on a weekend or legal holiday, it moves to the next business day. For 2026 payments, since 31 January 2027 falls on a Sunday, the recipient deadline moves to Monday 1 February.
Some payments are reported only if the payer is paying as part of a trade or business, so the rules differ for individuals who pay rent on a home they live in. If you are a payer, check the instructions or ask a tax professional before you file.
This is general guidance, not professional tax advice. Consult a certified tax professional for your specific situation.
1099-MISC vs 1099-NEC
The difference is simple: the 1099-NEC reports pay for services from someone who is not your employee, and the 1099-MISC reports other payments such as rent, royalties, and prizes. If a business paid you for work you did as a freelancer or contractor, you should get a 1099-NEC, not a 1099-MISC.
1099-NEC
1099-MISC
What it reports
Non-employee compensation, which is pay for services
Rents, royalties, prizes and awards, medical payments, and other income
Who usually gets one
Freelancers, contractors, and self-employed workers
Landlords, prize winners, royalty earners, and some service providers
Reporting threshold
$2,000 for payments made after December 31, 2025
$2,000 for most categories, $10 for royalties, $600 for attorney proceeds
Recipient copy due
January 31
January 31
IRS filing due
January 31
February 28 (paper) or March 31 (electronic)
People confuse the two because, before 2020, contractor pay was reported on the 1099-MISC. Many contractors still say they are paid on a "1099-MISC" when they mean the 1099-NEC. If you receive the wrong form, ask the payer to check it, as it affects how the income is reported.
To see how 1099 pay compares with employee pay, read our guide explaining the differences between 1099 and W-2.
Receiving 1099-MISC income from the US
If you earn 1099-MISC income from the US, the practical question is how to get that money to you in USD without losing a huge part of it on the way. This matters most if you live outside the US or if you collect rent, royalties, or prize money from US payers.
A standard international wire transfer can incur fees, and the exchange rate you get may not be clear until the money lands. If your payer sends US dollars to a local bank account in another currency, the conversion happens before you see it.
Grey gives you another way to receive it. You can open a USD account with Grey, a multi-currency account that lists no account opening fees, no maintenance charges, and no minimum deposit. That gives you a place to receive and hold dollars, and you can choose when to convert.
Grey helps you get paid from the US and move your money onward. You can fund a transfer from a US bank account via ACH or wire, choose the destination, and check the exchange rate and fees before confirming.
Whichever way you receive the money, keep a record of every payment and its date. It will help you check that each 1099-MISC you receive matches what you were paid. If you live outside the US, which form you receive depends on your tax status, so check with the payer or a tax professional.
Transfer times and fees depend on the destination, the funding method, and the recipient’s bank, so check the details on Grey before you send.
Grey is a financial technology company, not a bank. Exchange rates, fees, limits, and transfer times vary by destination and are subject to change.
Frequently asked questions about the 1099-MISC form
What is a 1099-MISC used for?
A 1099-MISC is used to report miscellaneous income that is not wages or contractor pay, such as rent, royalties, prizes and awards, and certain other payments. The payer files it with the IRS and sends a copy to the recipient.
What is the difference between 1099-MISC and 1099-NEC?
The 1099-NEC reports pay for services from someone who is not your employee, while the 1099-MISC reports other income such as rent, royalties, and prizes. Contractor pay moved from the 1099-MISC to the 1099-NEC in 2020.
Is rent reported on a 1099-MISC?
Yes, when a business pays rent of $2,000 or more in a year, it is generally reported in box 1 of the 1099-MISC. The $2,000 threshold applies to payments made after December 31, 2025. It was $600 before that.
Who files the 1099-MISC?
The payer files it, not the recipient. The payer sends a copy to the recipient by January 31 and files it with the IRS on paper by February 28 or electronically by March 31.
What if I do not receive my 1099-MISC?
Contact the payer first and ask for the form. You must still report the income on your tax return even if you do not receive one. The IRS guidance on missing 1099-MISC forms confirms this for prizes and awards.
Imagine finishing a successful project for a client, only to find yourself negotiating another contract a few weeks later. You're back to discussing rates, agreeing on deadlines, and figuring out when the next payment will arrive. Now, imagine having that same client pay you consistently every month for ongoing work. That's where a retainer agreement comes in.
A retainer agreement is a contract where a client pays a freelancer a fixed fee on a recurring basis in exchange for ongoing services or availability. It outlines the scope of work, fees, payment terms, agreed hours or deliverables, and how either party can end the arrangement.
For example, a freelance graphic designer might receive a monthly fee to create social media graphics, design promotional materials, and handle regular brand updates. The agreement establishes the expected deliverables, deadlines, and additional charges for requests outside the original scope.
It should also address revisions, unused hours, late payments, and termination notice. These details protect your time, manage client expectations, and ensure both parties understand their responsibilities. With clear terms in place, you can spend less time chasing new projects and more time building stable, long-term client relationships.
What is a retainer agreement?
A retainer agreement is a contract where a client pays a freelancer a fixed fee on a recurring basis for ongoing services or availability. It outlines the scope of work, payment terms, deliverables, timelines and responsibilities of both parties. For example, a freelance writer might receive $800 monthly to produce eight articles and provide editorial support.
Retainer agreements are particularly useful when clients need your services regularly rather than for one-off projects. However, before settling on this arrangement, consider how you operate as a freelancer. Understanding whether you need an LLC as a freelancer and the differences between a contractor vs. employee can help you clarify your business structure, responsibilities, and working relationship with clients. These considerations also make it easier to establish retainer terms that suit your business and the services you provide.
Here are four benefits of a retainer agreement:
Predictable income: Being certain that a client will pay you $1200 every month makes it easier to budget, save and manage business expenses.
Stronger client relationships: Working continuously with a client helps you understand their business, audience and expectations.
Better workload planning: Agreed deliverables and hours help you manage capacity and avoid overcommitting.
Less time finding clients: Recurring engagements reduce the pressure to constantly pitch for new projects to maintain your income.
Types of retainer agreements
Retainers generally fall into two categories: pay-for-work and pay-for-access, depending on what clients are paying you to provide.
If you're comparing retainers with other ways of charging clients, Grey's freelance pricing models explains how hourly, project-based and retainer arrangements differ.
1. Pay-for-work retainer
With a pay-for-work retainer, a client pays you a recurring fee for an agreed amount of work or specific deliverables. You know what you are expected to produce, and the client knows what they are paying for. For example, a freelance social media manager might charge $1,000 monthly to manage three platforms, create 20 posts and provide monthly performance reports. Any work outside the agreed scope attracts an additional fee.
2. Pay-for-access retainer
A pay-for-access retainer means a client pays to secure your availability and expertise when needed, rather than for a fixed number of deliverables. Lawyers commonly use this arrangement, charging clients a recurring fee to retain their services and access legal advice when issues arise. Similarly, a freelance consultant might charge $500 monthly to be available for strategy calls, urgent consultations and professional advice, even when the client does not need support every week.
What to include in your freelance retainer agreement
Before signing, make sure your retainer agreement covers these seven areas. Each one helps establish clear expectations, protect your time and prevent disagreements as the working relationship develops.
1. Scope of work
Define the services you will provide and the deliverables expected within each billing cycle. A freelance graphic designer may agree to create 12 social media graphics and two promotional banners each month. You can use a statement of work (SOW) to document these deliverables, timelines, and responsibilities, including what falls outside the agreed scope and attracts additional fees.
2. Retainer fee
State the agreed fee, currency and billing frequency. Whether you charge $500 or $2,000 monthly, ensure the amount reflects your workload, expertise and the value you provide. Also clarify whether the fee is fixed or subject to review after an agreed period.
3. Payment terms
Specify when invoices are issued, payment deadlines and accepted payment methods. For example, you might require clients to pay on the first of every month before work begins. Include provisions for late payments, missed payments and any applicable penalties.
4. Hours and availability
Clarify the working hours covered by the retainer, your availability and expected response times. If your agreement includes 15 hours per month, explain how additional hours will be billed and whether unused hours roll over to the next billing cycle.
5. Revisions
Establish how many revision rounds are included and what qualifies as additional work. For instance, you might offer two rounds of revisions per article. Requests that require a complete rewrite or change the original brief should attract additional fees.
6. Intellectual property
Explain who owns the completed work and when ownership transfers. You might agree that clients receive full ownership of approved deliverables upon payment, while you retain the right to showcase selected projects in your portfolio, subject to confidentiality agreements.
7. Termination
State how either party can end the agreement, including notice periods and outstanding payment obligations. For example, you could require 30 days' written notice before termination. Also clarify how unfinished assignments, final invoices and access to completed work will be handled.
Free freelance retainer agreement template
Use this simplified template to outline your working arrangement with a client. Fill in the relevant details, agree on the terms and have both parties sign before work begins.
Effective date:
Client: Client Name
Freelancer: Your Name / Business Name
1. Scope of services
The Freelancer agrees to provide the following services:
[List agreed services and deliverables]
[Specify monthly hours or availability]
Any work outside this scope will require separate approval and additional fees.
2. Retainer fee and payment
Fee:
Payment date:
Payment deadline:
Additional work:
3. Duration and termination
This agreement begins on [Start Date] and continues on a [monthly / fixed-term] basis.
Either party may end the agreement by providing [30 days] written notice. Immediate termination may apply if either party breaches the agreement and fails to resolve the issue within [7 days] of written notice.
4. Independent contractor status
The Freelancer operates as an independent contractor, not an employee of the Client, and is responsible for their own taxes, insurance and business obligations.
5. Confidentiality and ownership
Both parties agree to protect confidential business information. Ownership of final deliverables transfers to the Client once all outstanding payments have been made, unless otherwise agreed in writing.
6. Liability and disputes
Each party is responsible for claims arising from its own negligence or misconduct. The Freelancer's total liability will not exceed [agreed amount or fees paid in the preceding three months], subject to applicable law.
Any disagreement will first be addressed through good-faith discussions, followed by mediation or arbitration if necessary.
7. Governing law
This agreement is governed by the laws of [State / Country].
8. Signatures
By signing below, both parties confirm that they understand and accept these terms.
Getting paid on a retainer
Set up recurring invoicing so you receive payments consistently. You can invoice at the beginning of each billing cycle, with a clear payment deadline. This makes it easier to track income, plan expenses and follow up on overdue payments.
If you work with international clients, receiving payments in foreign currencies can introduce additional costs and conversion challenges. With Grey, you can open a multi-currency account to receive and hold USD, GBP and EUR payments from clients abroad.
When you need access to your earnings in Nigeria, you can convert your balance and withdraw to your local bank account. You can also send money from the US to Nigeria directly to a Nigerian bank account, making it easier to manage your freelance income across borders.
Frequently asked questions about freelance retainer agreements
1. What is a retainer agreement?
A retainer agreement is a contract between a freelancer and a client for ongoing services or availability in exchange for a recurring fee. It outlines the work involved, payment arrangements, timelines and responsibilities, giving both parties clarity and helping freelancers secure more predictable income.
2. How does a freelance retainer work?
A freelance retainer works by establishing a recurring payment for agreed services. You and your client decide on the fee, deliverables, working hours and billing cycle. You then provide the agreed services throughout that period, invoice according to your arrangement and receive payment at the agreed time.
3. What should a retainer agreement include?
A retainer agreement should include the scope of work, recurring fee, payment deadlines, working hours, deliverables, revision limits, intellectual property rights and termination conditions. You should also clarify how additional work, unused hours, confidentiality and expenses will be handled to prevent misunderstandings during the engagement.
4. Are retainers paid upfront?
Yes, many retainers are paid upfront at the beginning of each billing cycle, usually monthly. This allows freelancers to secure payment before committing their time and availability. However, payment arrangements depend on what both parties agree to, so specify invoice dates and deadlines in your contract.
5. Can I end a retainer agreement?
Yes. Most retainer agreements include termination clauses that allow either party to end the arrangement with written notice, typically 14 or 30 days. Check your contract for notice requirements, outstanding payments and unfinished deliverables before ending the engagement to avoid disputes with your client.
6. How do I get paid on a retainer from overseas?
You can receive overseas retainer payments through international bank transfers or multi-currency payment platforms. With Grey, you can open a USD, GBP or EUR account to receive client payments, hold foreign currency and transfer your earnings to your local Nigerian bank account when needed.
Somewhere out there, there is someone trying to pay for a family brunch in Wuse 2 or send euros to a friend in Lagos as a birthday gift. You'd think sending €500 from Paris to Nigeria would be pretty simple. Pick an app, enter the amount, and send.
If you are living in Germany, France, Ireland, the Netherlands, or elsewhere in Europe, try comparing a few services before deciding. Depending on the exchange rates and fees each provider offers, your recipient will receive different amounts in naira when sending euros.
We’ve compared seven of the best apps to send money from Europe to Nigeria. You'll find a breakdown of their fees, transfer times and payout options. We will also show you how much naira €500 can get you, so you can compare before sending.
How to choose an app to send money from Europe to Nigeria
Before downloading another money transfer app, there are a few things worth checking.
Exchange rate: How many naira will your recipient get for each euro?
Fees: Are there transfer fees, conversion charges, or hidden exchange rate markups?
Speed: How long does it take for the money to arrive?
Payout options: Can you send directly to a Nigerian bank account, or does the recipient need to collect cash?
Availability: Does the app support transfers from your country in Europe?
Here’s something people often overlook: zero transfer fees don’t always mean a cheaper transfer. An app might charge nothing upfront but give you fewer naira per euro.
The easiest way to compare services is to enter the same amount in different apps and check how much your recipient will actually receive.
The 7 best apps to send money from Europe to Nigeria
There are plenty of ways to send money from Europe to Nigeria, but not every app works the same way.
Here’s a quick comparison before we get into the details.
App
Fees
Delivery time
Best for
Grey
1% (capped at $6) EUR to NGN conversion + flat payout fee
Typically minutes after funding
Receiving, holding and sending money across currencies
LemFi
Zero transfer fees on supported routes
Usually minutes
Regular family transfers
Wise
Variable upfront fee, mid-market exchange rate
Minutes to working days
Transparent exchange rates
Remitly
Variable fees; promotional rates available
Minutes to several days
Flexible payout options
WorldRemit
Variable; some zero-fee transfers
Minutes to working days
International remittances
Western Union
Variable fees and exchange rate margin
Minutes to several days
Cash pickup
MoneyGram
Variable fees and exchange rate margin
Minutes to working days
Bank transfers and cash services
International payment cards
+1.5% on base rate
+1.5% on base rate
+1.5% on base rate
Cash or cheque
Free ($0)
Free ($0)
Free ($0)
Fees and delivery times depend on your country, payment method and transfer amount. Check the final quote before sending.
1. Grey: Best for receiving, holding and sending money across currencies
Getting paid in euros is great. But when you’re living and working in a European city and still handling financial responsibilities in Nigeria, things can get a little complicated.
Grey is built for exactly this kind of situation. Instead of moving money between different apps, you can receive payments in EUR, GBP, or USD, hold your balance in those currencies, and convert to naira whenever you need to send money to Nigeria.
If you receive €1,500 from a client in France, for instance. You don't have to convert everything into naira right away. You can leave €1,000 in your EUR balance for expenses or savings and convert the remaining €500 to send home. Your recipient gets the money directly into their Nigerian bank account, without needing a Grey account.
What are Grey's fees for sending money to Nigeria?
For EUR-to-NGN transfers, Grey charges a 1% conversion fee plus a flat NGN withdrawal fee. If you convert €500, that’s €5 in conversion fees, with the withdrawal fee charged separately.
Receiving money through SEPA also comes with a 0.8% fee, with a €2 minimum and €10 maximum. So, receiving €500 would cost €4.
Before you send, Grey shows you the exchange rate, applicable fees and the final amount your recipient will receive. Once the funds are available in your balance, transfers to Nigerian bank accounts typically arrive within minutes.
Best for: Nigerians in Europe who get paid internationally and want to manage multiple currencies and send money home without constantly switching between platforms.
2. LemFi: Best for regular transfers to family in Nigeria
If you send money to Nigeria every month, you probably have a familiar routine. Maybe it's money for your parents, school fees for a sibling or a contribution towards household expenses. Whatever the reason, you want an app that makes repeat transfers easy.
LemFi focuses on international money transfers and is particularly popular among Africans living abroad. It supports transfers from several European countries to Nigeria, with recipients receiving naira directly in their bank accounts.
Say you live in the UK and send money to your family in Lagos every month. With LemFi, you can save your recipient's bank details, check the exchange rate and send another transfer without entering everything again.
What are LemFi's fees for sending money to Nigeria?
LemFi offers zero transfer fees on many supported routes, including Nigeria. However, that doesn't automatically mean you’ll receive the best exchange rate.
The amount your recipient gets depends on LemFi's quoted rate at the time of the transaction. For example, if you're sending €500, the app will show how much that converts to in naira before you confirm.
Transfers can arrive within minutes, although processing times depend on the payment method, bank and any additional checks. Availability also varies by European country.
Best for: People in Europe who regularly send money to family or friends in Nigeria and want international transfers.
3. Wise: Best for transparent exchange rates and fees
Ever sent money abroad and wondered why the amount that arrived was lower than you expected? Sometimes the transfer fee looks small, but the exchange rate tells a different story.
Wise makes comparing costs easier by showing its fees separately and using the mid-market exchange rate, the rate you typically see when searching for a currency pair online.
It's particularly useful if you're sending money from Europe and want to understand exactly how much you're paying for the conversion.
For example, if you're sending €500 from Germany to a Nigerian bank account, Wise shows the transfer fee, exchange rate and estimated amount in naira before you pay.
What are Wise’s fees for sending money to Nigeria?
Wise doesn’t charge one fixed fee for every international transfer. Its fees depend on the currencies, amount and payment method.
Bank transfers are often cheaper than using a debit or credit card. The app calculates the total cost before confirmation, so you can compare payment options.
Best for: People who prioritise exchange-rate transparency and want to compare the full cost of international transfers before sending.
4. Remitly: Best for flexible delivery options
Sometimes sending money home isn’t just about finding a good exchange rate. You also want to know when the money will arrive.
Remitly offers different payment and delivery options depending on where you're sending from. It also lets you track the transfer. When sending euros to Nigeria, payouts can be made to local bank accounts and other supported payout methods.
Imagine you're living in France and need to send €300 to your mum in Nigeria. You can enter the amount, choose an available delivery method and see the estimated arrival time before paying. Remitly also lets you track the transfer.
What are Remitly's fees for sending money to Nigeria?
Remitly's fees depend on your sending country, payment method and transfer amount. New customers may qualify for a promotional exchange rate or a fee-free first transfer, but these offers have limits and don't necessarily apply to future payments.
For example, a €500 transfer from France may have a different fee and exchange rate from the same transfer sent from Germany. Paying by card can also affect the total cost.
Before confirming, check the fee, exchange rate and final NGN amount. Some transfers can arrive within minutes, while others take longer depending on the payment and delivery methods.
Best for: Nigerians in Europe who want flexible ways to pay for transfers, track their money and choose from available delivery options.
5. WorldRemit: Best for sending money and mobile airtime
Sometimes your family needs money for groceries or bills. Other times, they just need their phone topped up so they can stay connected. WorldRemit is useful because it offers both international money transfers and mobile airtime top-ups.
You can send money to supported Nigerian bank accounts from several European countries, using the website or mobile app. Depending on the route, you can pay by bank transfer or card.
Say you're living in the Netherlands and want to send €200 to your brother in Nigeria. You can choose a bank deposit, enter his details and check how much he'll receive in naira. If he only needs mobile credit, you can purchase an airtime top-up instead.
What are WorldRemit's fees for sending money to Nigeria?
WorldRemit currently advertises fee-free transfers when sending naira to Nigeria, although the offer and available payout methods should be checked for your particular route.
The exchange rate still matters. Even without a separate transfer fee, the rate offered determines how much naira your recipient receives.
For example, if you're sending €500, compare the NGN amount shown by WorldRemit with the amount offered by other apps for the same €500 payment.
WorldRemit says bank transfers to Nigeria can arrive within an hour, although verification, payment processing and local banking conditions may affect delivery.
Best for: Nigerians in Europe who want to send money to bank accounts and occasionally top up a family member's mobile phone.
6. Western Union: Best for sending money online or in person
Not everyone wants to manage international transfers entirely through an app. Maybe you prefer paying in cash, or you're helping a relative who is more comfortable collecting money in person.
Western Union has been around for generations, and its biggest advantage is flexibility. You can send money to Nigeria online, through its app or at participating agent locations across Europe.
For example, if you're living in Italy and want to send €300 to a relative in Nigeria, you can compare the available payment and delivery methods before choosing one. Depending on the route, you may be able to fund the transfer using a bank account, card or cash.
What are Western Union's fees for sending money to Nigeria?
Western Union doesn't have one standard fee for transfers from Europe to Nigeria. Costs depend on the sending country, amount, payment method and how your recipient receives the money.
For example, sending €500 online from Germany may cost something different from paying €500 in cash at an agent in Italy.
Western Union also earns money through currency conversion, so it's important to check both the transfer fee and the exchange rate. The app shows the estimated amount your recipient will receive before you confirm.
Delivery can take minutes for eligible transfers, but bank deposits and other payment methods may take longer.
Best for: Nigerians in Europe who want the option to send money online or in person, particularly when cash payments or collection options are important.
7. MoneyGram: Best for cash transfers and a large international network
Like Western Union, MoneyGram combines a large international network of physical locations with digital transfers through its website and app.
You can send money from supported European countries to Nigeria, with delivery options that may include bank deposits, cash pickup and mobile wallets, depending on the route.
You can check the available delivery options between both currencies, enter the recipient's details and compare the cost of sending online with the options available at a local MoneyGram location.
What are MoneyGram's fees for sending money to Nigeria?
MoneyGram's fees vary depending on where you're sending from, how much you're transferring, how you pay and how the recipient collects the money.
There's no single fixed fee that applies to every Europe-to-Nigeria transfer.
For example, a €500 bank deposit funded by debit card may have a different total cost from a cash-funded transfer at an agent location. MoneyGram also earns money through currency exchange, so the quoted rate matters.
Before paying, you'll see the transfer fee, exchange rate, estimated delivery time and final amount your recipient should receive.
Some transfers can be available within minutes, while others take longer depending on the delivery method and processing requirements.
Best for: Nigerians in Europe who prefer cash-based transfers or want access to both physical agent locations and digital money transfer services.
Which money transfer app should you choose?
One way to decide is how frequently you would have to send money. If this is a one-time payment, comparing the final payout might be enough. But if you’re regularly receiving euros, holding different currencies, and sending money to Nigeria, other features matter as well.
These options vary as exchange rates fluctuate and are priced by location.
If you want to
Consider
Receive euros, hold foreign currency and send NGN
Grey
Send money home regularly
Grey or LemFi
Compare fees against the mid-market rate
Wise
Use a first-transfer promotional rate
Remitly
Send money for cash pickup
Western Union or MoneyGram
How to send money from Europe to Nigeria with Grey
Sending money from Europe to Nigeria usually takes just a few steps. Here's how to do it with Grey.
Create your Grey account. Sign up and verify your identity.
Set up your EUR account. Users can open a euro account to receive and manage euros.
Add money. Fund your account using a supported method, such as a SEPA transfer.
Choose your recipient. Select an existing beneficiary or add someone new.
Enter the amount. Choose NGN and enter how much you want to send.
Review and confirm. Check the exchange rate, fees and the final amount your recipient will receive.
Once you've confirmed the transfer, you can follow its progress in the app.
Nobody wants to send €500 only to discover they could have got a better deal elsewhere.
Check rates before sending
Exchange rates change, sometimes several times a day. If your transfer isn't urgent, compare a few apps before confirming.
You don't necessarily need to wait for the perfect rate. Just make sure you're comfortable with the amount your recipient will receive.
You can also check official exchange rate information from the Central Bank of Nigeria, although the rate offered by your transfer app may differ.
Watch out for promotional rates
Some apps offer special rates or reduced fees for your first transfer.
That's useful, but if you send money every month, also compare their regular prices. A good first-transfer deal doesn't always mean the best long-term option.
Pay attention to how you fund your transfer
Bank transfers and card payments can have different fees. If you're not in a hurry, check which funding method gives you the best overall price.
And if you send money regularly, even small differences add up. A 1% difference on €500 every month works out to €60 over a year.
Other ways to send money from Europe to Nigeria
Apps are convenient, but they're not your only option.
International bank transfers: You can send money through a European bank using SWIFT, provided the receiving Nigerian account supports the transfer. This can be useful for larger payments or sending foreign currency to a domiciliary account. However, intermediary fees and longer processing times may apply.
Cash pickup: Services such as Western Union and MoneyGram let recipients collect money at eligible locations. This can help when someone doesn't have a suitable bank account, although you'll need to check the available payout currency and identification requirements.
Transfers from the UK: If you're sending from the UK, you'll usually be converting GBP rather than EUR. Fees and rates may be different, so compare the specific corridor. Here's how to send money from the UK to Nigeria.
Send money from Europe to Nigeria with Grey
If you're regularly sending money home, having an app that lets you manage foreign currencies and make transfers can make life easier.
With Grey, you can hold supported foreign currencies, convert funds and send NGN directly to Nigerian bank accounts. You'll see the applicable rate and fees before confirming, so you know what your recipient is expected to receive.
Frequently asked questions about sending money from Europe to Nigeria
What is the best app to send money from Europe to Nigeria?
Grey is a good choice if you want to manage foreign currencies and send money to Nigerian bank accounts. LemFi, Wise and Remitly are also worth considering. Compare the final NGN amount, fees and transfer speed to find the best option for you.
How long does a transfer from Europe to Nigeria take?
Some transfers arrive within minutes, while others take several working days. The exact time depends on the provider, payment method, verification requirements and receiving bank.
Which app gives the best euro to naira rate?
No single app always offers the best rate. Compare the amount your recipient will receive after fees using the same euro amount across different providers.
Can I send euros to a Nigerian domiciliary account?
Yes, some Nigerian domiciliary accounts accept EUR transfers through supported international banking channels. Check the receiving bank's requirements, SWIFT details and fees before sending.
How much can I send from Europe to Nigeria?
Limits depend on the app, sending country and verification level. Some providers support large transfers, but additional documentation may be required. Check your available limit before sending.
Do I need a European bank account to send money?
Not always. Some apps accept card payments, while services such as Western Union and MoneyGram may support cash-funded transfers at eligible locations. Grey users can fund their accounts through supported payment methods.
It’s a packed Saturday afternoon at your coffee shop. The line stretches out the door, orders are flying, and customers are tapping their cards and phones at the register every thirty seconds. By closing time, you’ve had your best sales day of the month. Then Monday morning rolls around, you check your bank payout, and the deposit is noticeably smaller than the total on your sales screen.
If you’ve ever had that moment of confusion, you’re looking at payment processing fees in action. For many small businesses, those payments are handled by Square, an all-in-one financial and point-of-sale (POS) platform that lets merchants accept card and mobile payments in person or online.
While Square makes getting paid easy, figuring out how much it takes from each sale can be a bit complicated. Between different rates for card taps and online invoices, the advertised numbers don't always tell the full story.
This guide breaks down how Square’s pricing actually works across every payment method, and the extra costs to take note of.
What is Square?
Square is a financial service and merchant platform that provides point-of-sale (POS) hardware, software, and payment processing solutions. It makes buying and selling easier by making digital card payments accessible to business owners.
How does Square pricing work?
Square uses a transaction-based pricing model, which means businesses pay a fee whenever they process a payment. Most card payments come with two charges: a percentage of the transaction amount and a fixed fee. For example, if Square charges 2.6% + $0.15, it takes 2.6% of the payment amount and an additional 15 cents. If a customer paid $100 using a card, the the business would receive $97.25.
The amount you pay depends on how a customer makes a payment. When someone pays in person using a card, Square charges a lower processing rate. However, online payments and manually entered card details usually cost more because they carry a higher risk of fraud. This is because the customer and their physical card are not necessarily present when the payment is made.
Square also offers three main subscription plans: Square Free, Square Plus and Square Premium. The Free plan has no monthly subscription fee, while the paid plans offer additional business tools and lower processing rates for some payment types.
The plan you end up choosing will affect how much you spend on transaction fees and software each month. Understanding these costs can help you choose a plan that suits your business and avoid paying for features you do not need.
Square fees by transaction type
Your exact Square processing fee depends on how a customer pays. For example, processing a payment in person generally costs less than accepting a card payment through your website.
The table below shows Square's published US processing fees for 2026.
Payment type
Square Free ($0/month)
Square Plus ($49/month)
Square Premium ($149/month)
In-person (tap, dip or swipe)
2.6% + $0.15
2.5% + $0.15
2.4% + $0.15
Online store and Square invoices (card)
3.3% + $0.30
2.9% + $0.30
2.9% + $0.30
Online API (custom, website/app)
2.9% + $0.30
2.9% + $0.30
2.9% + $0.30
Manually keyed-in card payments
3.5% + $0.15
3.5% + $0.15
3.5% + $0.15
ACH bank transfer (via invoice)
1% ($1 min, no cap)
1% ($1 min, $10 cap)
1% ($1 min, $10 cap)
ACH bank transfer (via API or payment link)
1% ($1 min, $5 cap)
1% ($1 min, $5 cap)
1% ($1 min, $5 cap)
Afterpay (buy now, pay later)
6% + $0.30
6% + $0.30
6% + $0.30
International payment cards
+1.5% on base rate
+1.5% on base rate
+1.5% on base rate
Cash or cheque
Free ($0)
Free ($0)
Free ($0)
Note: Grey is not affiliated with Square. These rates apply to eligible US-based Square accounts and may change. Always check Square's official pricing page for the latest information.
A few other payment methods have different fees:
International cards: An additional 1.5% applies to cards issued outside the US.
Afterpay: 6% + $0.30 per transaction.
EBT payments: 1.8% + $0.05 per transaction.
Cash and cheques: No processing fee.
Gift card loading: 2.5% on Free and Plus plans; no loading fee on Premium.
Others costs to budget for
Transaction fees are not the only expenses to consider when using Square. Businesses may also need to pay for payment equipment, monthly subscriptions and certain banking services.
Monthly software plans: Square offers three main plans: Free ($0 per month), Plus ($49 per month, per location) and Premium ($149 per month, per location). Paid plans come with additional business management features and lower processing rates for some payment types.
Hardware: Businesses may need to purchase equipment to accept in-person payments. Square's contactless and chip reader costs $59, while Square Stand costs $149. More advanced options include Square Terminal at $299 and Square Register at $899. These are one-time hardware purchases, separate from subscription fees.
Chargebacks: Square does not charge an additional fee for handling payment disputes. However, it may temporarily withhold the disputed amount from your balance or linked bank account while investigating the claim.
Instant payouts: Standard next-business-day transfers are free, but businesses that need faster access to their money can use instant or same-day transfers for a 1.95% fee.
Refunds: Square does not charge an extra fee to issue a refund, and your customer receives their full purchase price back. However, Square keeps the original payment processing fee you paid when the sale first went through.
What Square actually costs a small business
Looking at Square's advertised processing rates alone does not always show how much a business will spend. The actual cost depends on how many transactions it processes, how much customers spend and which payment methods they use.
To understand how this works, consider a small retail business that makes $15,000 in monthly sales. Assume $10,000 comes from in-person card payments, with an average purchase of $50, while the remaining $5,000 comes from online orders, with an average purchase of $100.
The business processes 200 in-person transactions and 50 online transactions each month.
Using Square Free
On the Free plan, the business pays 2.6% + $0.15 for in-person payments and 3.3% + $0.30 for online payments.
In-person payments ($10,000 across 200 transactions): The percentage fee is $260 (2.6% of $10,000). The fixed fee is $30 (200 × $0.15). This brings the total in-person processing cost to $290.
Online payments ($5,000 across 50 transactions): The percentage fee is $165 (3.3% of $5,000). The fixed fee is $15 (50 × $0.30). The total online processing cost is $180.
Total monthly processing fees: $290 + $180 = $470.
The business pays $470 to process $15,000 in monthly sales. This is an effective processing rate of approximately 3.13%.
Using Square Plus
Suppose the same business upgrades to Square Plus for $49 per month. Its in-person processing rate drops to 2.5% + $0.15, while its online rate drops to 2.9% + $0.30.
In-person payments ($10,000 across 200 transactions): The percentage fee is $250 (2.5% of $10,000). The fixed fee is $30 (200 × $0.15). Total: $280.
Online payments ($5,000 across 50 transactions): The percentage fee is $145 (2.9% of $5,000). The fixed fee is $15 (50 × $0.30). Total: $160.
Total processing fees: $280 + $160 = $440.
Monthly subscription: $49.
Total monthly cost: $440 + $49 = $489.
In this example, the business spends $489 per month on Square Plus, compared with $470 on Square Free.
Although Square Plus reduces the business's processing fees by $30, the $49 subscription costs an additional $19. This makes the Free plan the cheaper option for this business.
The example shows why business owners should consider their monthly sales, transaction volumes and payment methods before choosing a Square subscription. A paid plan is not automatically cheaper, even if it offers lower transaction rates. However, a business that processes more payments or needs the additional software features may find that upgrading is worthwhile.
Getting paid across borders using Grey
For all its benefits and features, Square is built for local payments. To use it, your business must be registered in a supported country and linked to a local bank account in that same currency. If you run a US business, Square sends your payouts in US dollars. Once your money lands, moving it across borders gets expensive. Sending funds to overseas suppliers, remote workers, or your bank account back home often means high wire fees and inconsistent and often expensive bank exchange rates.
If you run a business that spans continents, you will need a cost-effective way to move money. Grey gives you flexibility and control over what happens to your funds after you get paid. Grey does not replace Square at checkout. While Square handles payment collections, Grey helps you manage and move your money once you get paid. With Grey foreign accounts, you get US, UK, and European account details to receive USD, GBP, and EUR payouts. You can then swap currencies with Grey currency exchange at transparent rates or send money internationally to over 80 countries.
Frequently Asked Questions
How much does Square take per transaction?
Square charges 2.6% plus $0.15 for in-person tap, dip, or swipe payments on its free plan. Online payments and invoices cost 3.3% plus $0.30, while manually keyed entries cost 3.5% plus $0.15. Paid plans have a lower percentage rate in exchange for a recurring monthly subscription fee.
Does Square have monthly fees?
The Square Free plan has no monthly subscription fee; you only pay when you successfully process a transaction. However, Square offers paid tiers such as Square Plus at $49 per month and Square Premium at $149 per month, which unlock reduced processing rates and advanced administrative tools.
Why was I charged more than the standard rate?
You might get higher charges if you manually key in customer card numbers instead of using a physical reader, process international cards which has an additional surcharge, or use add-on services like Afterpay or instant payout transfers.
How fast are payouts?
Standard bank transfers from Square are included at no extra charge and typically arrive as soon as the next business day. If you want immediate access to your funds, instant payouts are available for a 1.95% fee.
Does Square charge for refunds?
Square does not charge extra processing fees when you issue a refund. When you refund a payment in full, Square returns the original processing fee to your account. Partial refunds receive a proportional fee return.
Selling across borders? Receive and move your money with Grey.
We've all heard about the Colosseum, the Leaning Tower of Pisa and the Trevi Fountain, but what I loved most about Italy was everything in between.
I spent three months there, and even the simplest moments felt like scenes from a historical film. I could spend hours wandering through old streets, admiring the architecture or sitting in a piazza with a coffee, just watching life go by. It's the perfect place to embrace il dolce far niente, the Italian art of doing nothing and enjoying every minute of it. And, of course, eating more pasta and gelato than I'd like to admit.
One thing I learnt during those months is that you don't need a huge budget to enjoy Italy. But you do need to plan a little, especially if you're hoping to visit several cities.
Trips to Italy can be surprisingly affordable or quite expensive, depending on where you're coming from, when you visit and how you travel. A week in Rome, Florence and Venice, for example, will cost more than staying in one smaller town.
A one-week trip to Italy costs roughly $1,500 to $3,500 per person. Budget travellers spend around $1,500 to $2,200, mid-range $2,500 to $3,500, and luxury $6,000 or more. Flights vary most by origin, while trains between cities and summer hotel rates shape the daily budget.
So, how much should you actually save for your Italy trip? Let's break down the costs, from flights and accommodation to food, trains and those extra gelatos you'll inevitably want.
How much does a trip to Italy cost? Budget range overview
The cost of a trip to Italy depends on a few things: where you're flying from, how long you're staying, the time of year and your travel style.
For a seven-day holiday, here's what you can expect to spend per person, including an estimated return flight from the US.
Travel style
Estimated cost for 7 days
Budget
$1,500–$2,200
Mid-range
$2,500–$3,500
Luxury
$6,000+
These are planning estimates, not fixed prices. Summer is generally the most expensive time to visit, particularly in popular destinations such as Rome, Florence, Venice and the Amalfi Coast.
Your itinerary also makes a difference. Visiting three cities in one week means more train tickets and potentially higher accommodation costs. Staying longer in one place can help you save.
If you're travelling from the US, flights will probably be one of your biggest expenses.
Return economy tickets to Rome or Milan typically cost around $600 to $1,200, although prices depend on your departure city, season and booking dates.
Flying from New York or Boston can be cheaper than departing from the West Coast, especially when direct flights are available.
Here's an estimated budget for seven days:
Expense
Estimated cost
Return flight
$600–$1,200
Accommodation
$350–$1,050
Food and drinks
$210–$420
Transport
$100–$250
Attractions
$80–$200
Total
$1,340–$3,120
For a comfortable trip, budgeting around $2,500 to $3,000 per person is a reasonable starting point.
If you're planning to visit Rome, Florence and Venice, consider arriving in Rome and flying home from Venice, or vice versa. This can save you the time and cost of travelling back to your arrival city.
How much does a trip to Italy cost from North America?
For travellers coming from Canada or Mexico, flights are also likely to take up a significant part of the budget.
From major Canadian cities, return flights to Italy can cost approximately $700 to $1,300 USD. Toronto and Montreal often have more direct connections, while flights from western Canada may involve longer journeys.
From Mexico, prices vary considerably depending on your departure city and available connections.
Here's a general seven-day budget in USD:
Expense
Estimated cost
Return flight
$700–$1,300
Accommodation
$350–$1,050
Food and drinks
$210–$420
Transport and attractions
$180–$450
Total
$1,440–$3,220
If you have flexible travel dates, compare flights to both Rome and Milan. Sometimes, arriving in a different city can make a noticeable difference to the overall cost.
How much does a trip to Italy cost from Europe?
Travelling to Italy from another European country is usually much more affordable, particularly if you're flexible with your dates.
Low-cost airlines connect Italy with cities such as London, Paris, Barcelona, Madrid and Berlin. Depending on your route, return flights can cost around €80 to €300.
Just remember that the cheapest fares often don't include checked luggage.
For seven days in Italy, you could spend:
Expense
Estimated cost
Return flight
€80–€300
Accommodation
€280–€840
Food and drinks
€175–€350
Transport and attractions
€130–€350
Total
€665–€1,840
If you're travelling from a neighbouring country, trains and buses are also worth considering.
And if you only have a few days, I'd recommend choosing one region rather than trying to squeeze in every major city. Spending four days in Florence and exploring Tuscany, for example, can be a lovely way to experience Italy without constantly packing your bags.
How much does a trip to Italy cost from Africa?
The cost of travelling to Italy from Africa varies quite a bit depending on where you're departing from.
Travellers from North African countries such as Morocco, Tunisia and Egypt may find shorter and more affordable flights. From countries such as Nigeria, Kenya or South Africa, journeys are generally longer and may require connections.
Return flights can cost approximately $400 to $900 on selected routes, although some departures can be considerably more expensive.
Here's an estimated seven-day budget in USD:
Expense
Estimated cost
Return flight
$400–$900
Accommodation
$350–$1,050
Food and drinks
$210–$420
Transport and attractions
$180–$450
Total
$1,140–$2,820
Depending on your nationality and residence status, you may also need a Schengen visa. Remember to include the application fee, travel insurance and any additional processing charges in your budget.
How much does a trip to Italy cost from South America?
If you're travelling from South America, getting to Italy will probably be the most expensive part of your holiday.
Return economy flights from major cities such as São Paulo, Rio de Janeiro, Buenos Aires and Bogotá can cost around $1,000 to $1,800, depending on the route and season.
Some cities have direct flights to Italy, while others require a connection.
Here's what a seven-day trip might cost:
Expense
Estimated cost
Return flight
$1,000–$1,800
Accommodation
$350–$1,050
Food and drinks
$210–$420
Transport and attractions
$180–$450
Total
$1,740–$3,720
Since flights are relatively expensive, I'd consider staying for at least 10 to 14 days if your schedule and budget allow.
You'll spend more overall, but you'll have more time to explore and won't feel as though you've crossed the Atlantic just to rush through three cities.
Trip to Italy cost breakdown: Flights, hotels, trains and food
Now that we've covered the cost of getting to Italy, let's look at what you'll actually spend once you're there.
The nice thing about Italy is that you have plenty of choices. You can stay in a luxury hotel, eat at expensive restaurants and book private tours, but you can also have an incredible trip with simple accommodation, local food and public transport.
Here's a breakdown of typical expenses:
Expense
Budget option
Mid-range option
Accommodation per night
€40–€80
€100–€180
Breakfast
€3–€7
€8–€15
Lunch
€10–€18
€20–€35
Dinner
€15–€25
€30–€55
Local transport per day
€3–€8
€8–€15
Museum or attraction
€10–€20
€20–€35
Rome to Florence train
€20–€45
€45–€75
Florence to Venice train
€20–€45
€45–€70
These are approximate planning ranges. Accommodation prices depend on the type of room or bed, and train fares vary by departure time and booking date.
Accommodation: Location matters more than you think
Rome, Florence and Venice are among the more expensive places to stay, especially during the summer.
But you don't necessarily need to stay right next to the main attractions. Choosing accommodation a little further from the historic centre, but close to public transport, can save you quite a bit.
In Venice, for example, staying in Mestre on the mainland is often cheaper than booking a hotel on the islands. Just remember to account for the time and cost of travelling into Venice.
Smaller cities such as Bologna, Padua and Perugia are also worth considering if you'd like to experience a different side of Italy.
Food: Good meals don't have to be expensive
If there's one thing I wouldn't worry too much about in Italy, it's finding good food.
You can have a delicious plate of pasta, pizza or a panino without spending a fortune. And honestly, some of the simplest meals are the ones I remember most.
A quick breakfast at a local café might cost €3 to €7, while a casual lunch can be around €10 to €18.
For dinner, expect to spend approximately €15 to €25 at an affordable restaurant.
One thing to keep in mind is the coperto, a cover charge some restaurants add to your bill. It's usually a few euros per person and should be listed on the menu.
And a small tip from my time there: having your coffee standing at the counter is often cheaper than sitting at a table, especially in tourist areas.
Trains: The best way to travel between Italian cities
If you're visiting several cities, trains are probably going to be your best friend.
Italy has an extensive railway network, including high-speed services connecting major destinations such as Rome, Florence, Milan, Naples and Venice.
For example, the high-speed train from Rome to Florence can take around 90 minutes, making it much easier than dealing with airports.
There are two main high-speed operators: Trenitalia and Italo. You can compare fares on their websites and often find better prices by booking early.
Regional trains are usually cheaper and work well for shorter journeys, particularly if you're exploring smaller towns.
Of course, places such as the Colosseum, Vatican Museums and Uffizi Gallery are worth considering, but some of the best experiences are completely free.
Walking through Rome, admiring Florence's architecture or wandering around Venice can easily fill an afternoon.
For paid attractions, budget approximately €10 to €35 per visit, although guided tours and special experiences can cost more.
I'd recommend choosing a few attractions you really want to see and leaving some free time to explore without a strict itinerary.
How to budget and pay for your trip to Italy
Once you've worked out how much your holiday will cost, the next step is deciding how to manage your money.
Italy uses the euro, so if you're travelling from a country with another currency, you'll need to think about exchange rates, card fees and how much cash to carry.
A little planning here can help you avoid unnecessary expenses.
Set aside part of your budget in euros
If you're planning your trip a few months in advance, you can start putting money aside for accommodation, transport and everyday spending.
With Grey, eligible users can hold euros alongside other supported currencies, such as USD and GBP.
This can be particularly useful if you receive income in different currencies or prefer to keep your travel budget separate from your everyday money.
Just remember that exchange rates fluctuate, so converting money early doesn't guarantee a better deal.
Use a virtual card for travel expenses
You'll probably make several payments before and during your trip, from booking hotels and train tickets to paying at restaurants and shops.
Grey's virtual Visa card can be linked to your supported currency balances and used for eligible online purchases and contactless payments through Apple Pay or Google Pay, where available.
You won't need to manually top up a separate card balance, although applicable transaction and conversion fees depend on your payment.
It's worth checking the card's availability and fees before travelling.
Stay connected with a travel eSIM
Having mobile data in Italy is useful for everything from checking train schedules to navigating unfamiliar streets.
Instead of relying on public Wi-Fi or paying expensive roaming charges, you can explore options to buy a travel eSIM for Italy through Grey Lifestyle.
Before purchasing, check that your phone supports eSIM technology and compare the plan's data allowance, validity period and coverage.
Check the available payment methods, exchange rates, transfer fees and estimated delivery times before sending.
Ready to explore Italy?
A little financial preparation can make your holiday much more enjoyable. With Grey, you can manage supported currencies, make eligible payments with a virtual card and explore travel eSIM options.
Frequently asked questions about the cost of a trip to Italy
How much does a trip to Italy cost for one week?
A one-week trip to Italy generally costs around $1,500 to $3,500 per person, including flights, accommodation, food, transport and activities.
Budget travellers may spend less by staying in hostels, eating at casual restaurants and travelling outside peak season. Luxury holidays can easily exceed $6,000 per person.
Is Italy expensive for tourists?
Italy can be expensive in popular destinations such as Venice, Rome, Florence and the Amalfi Coast, particularly during summer.
However, it's possible to travel affordably by visiting smaller cities, using public transport and choosing local restaurants.
Your accommodation and travel dates will usually have the biggest impact on your budget.
How much does a 10-day trip to Italy cost?
A 10-day trip to Italy can cost approximately $2,000 to $4,500 per person, including an estimated return flight from the US.
Budget travellers might spend around $2,000 to $2,800, while mid-range travellers could spend $3,000 to $4,500.
The total depends on your itinerary, travel season and accommodation choices.
What is the cheapest month to visit Italy?
January, February and November are often among the cheapest months to visit major Italian cities, excluding holidays and special events.
Hotels can be more affordable, and popular attractions are generally less crowded.
If you'd prefer warmer weather, April, May, late September and October can offer a good balance, although prices may be higher.
How much spending money do I need for seven days in Italy?
Excluding flights and accommodation, budget around €40 to €70 per day for an affordable trip or €80 to €150 for a more comfortable experience.
That's approximately €280 to €490 for a budget week or €560 to €1,050 for a mid-range trip.
You don't need to carry everything in cash, as cards are widely accepted across Italy.
Is it cheaper to visit Rome, Florence or Venice?
Rome and Florence generally offer more accommodation options across different budgets, while staying in central Venice can be particularly expensive.
However, prices depend on the season and neighbourhood.
If you're trying to save, consider staying outside the historic centre or visiting nearby towns.
How can I save money on a trip to Italy?
Travelling outside the summer season, booking trains and accommodation early, and spending more time in fewer cities can help reduce costs.
Eating at local restaurants, using public transport and combining paid attractions with free activities also makes a difference.
And if you're paying in a currency other than euros, remember to compare exchange rates and card fees before travelling.
Make the most of your Italy trip
Three months in Italy taught me that some of the best travel experiences don't require much money. Sometimes, all you need is a beautiful town to explore, a good meal and enough time to enjoy where you are.
Planning your budget means you can spend less time worrying about expenses and more time enjoying everything Italy has to offer.
With Grey, you can hold euros in supported accounts, pay with an eligible virtual Visa card and explore travel eSIM options.
Say you’re dealing with a factory whose quote is in dollars, and they want a deposit before production starts, and the account details arrive by email under a company name that isn’t quite the one on the invoice. For a first-time importer in Lagos or Nairobi, nothing about that moment is unusual, and each part of it is a place where a small mistake costs real money.
Many African businesses usually pay Chinese suppliers by international bank transfer, in US dollars or yuan. A common pattern is a deposit before production and the balance before shipment, though terms are negotiable. Importers in Nigeria must also register a Form M with their bank. Platform escrow, where offered, adds protection for first orders.
However, with cross-border and global payments making it easier for businesses to settle renminbi (RMB) transactions, trading with China has become easier, and more options are available to people and businesses to send yuan directly to local bank accounts in China.
In this article, I cover how to find and check a supplier, what an order should cost, how to manage the relationship, and how to pay.
Why China, and why now?
If you are looking to start or scale a business, China is hard not to consider. China is a major source of manufactured goods for African businesses, and the volumes show it. Trade between China and Africa reached a record US$348.05 billion in 2025, up 17.7% on the year, according to a report from the NTU-SBF Centre for African Studies. Chinese exports to Africa accounted for US$225.03 billion, up 25.8%, while imports from Africa were US$123.02 billion, up 5.4%. The same report puts Africa’s deficit with China at US$102.01 billion, meaning African buyers are importing far more than they export.
Behind those totals are the businesses this guide is for: shop owners, online sellers, and small manufacturers who buy fabric, electronics, machine parts, packaging, and finished goods. A growing number go a step further and develop private-label products, in which a factory makes a product to the importer's specifications and under the importer’s brand. That raises the stakes on everything that follows: choosing the factory, agreeing the order size, checking quality, and moving the money.
What has changed in China-Africa trade in the last five years
China opened its market to African exports Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.
China opened its market to African exports Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.
Nigeria’s foreign exchange policy has been updated The CBN issued a new foreign exchange manual in May 2026. Coverage states that importers must submit exchange control documents within 90 days of negotiating shipping documents, and that importers who fail to do so may be restricted from the foreign exchange market. We’ll talk about this a bit more in the section on paying suppliers.
There are more ways to pay in yuan Some payment providers, like Grey, now deliver yuan directly to Chinese bank accounts, giving importers an alternative to paying only in dollars.
How to find a reliable Chinese supplier
For businesses looking to source from China, finding a supplier often starts with an online marketplace, especially for first-time importers.
Alibaba.com is built for export buyers and lists suppliers that work with overseas customers. 1688 is China’s domestic wholesale platform. It is written in Chinese, prices are often lower, and most foreign buyers use a sourcing agent or a translator to work with it. Trade fairs such as the Canton Fair in Guangzhou let you meet suppliers and handle samples in person, and referrals from other importers in your market often lead to suppliers that already ship to Africa.
Factory or trading company? When you make contact, you have to ask directly: “Do you own the factory?” A trading company is not a bad choice, since it can combine products from several factories and handle export paperwork, but it adds its own margin and puts you one step further from the people making your product. A factory can usually show its production line on a video call and explain who works on your order.
Check that the company exists Ask for the business licence, which carries an 18-character Unified Social Credit Code. China’s National Enterprise Credit Information Publicity System at gsxt.gov.cn lets you search for that code to see whether the company is registered, who its legal representative is, and whether it has abnormal operation records. The site is in Chinese with no official English version and can be slow from outside China, so browser translation helps. Two limits matter. A matching code proves that a company exists, not that the person you are talking to works for it. And the English name on a supplier’s profile often differs from its registered Chinese name, so make sure the name on the licence, contract, invoice, and bank account all match.
Order samples before you commit Pay for samples, test them yourself, and then compare the first production units with the approved sample. Making one good sample is easy. What you want to know is whether the supplier can repeat it.
Document exactly what you want A supplier can only build what is written down. Send specifications with photos, dimensions, materials, colours, packaging, and tolerances, and confirm every decision in writing, even if you also talk on WeChat or WhatsApp. Ask the supplier to repeat back what they will make.
Warning signs A price far below every other quote, a refusal to join a video call, pressure to pay quickly, a request to pay a personal account for a company order, or a request to move the payment outside the platform you are using.
The real cost of sourcing from China: MOQs, shipping and duties
The price in the quote is the starting point, not the end. What matters is the landed cost: everything you have paid by the time the goods are in your warehouse.
MOQs A minimum order quantity (MOQ) is the smallest order a supplier will produce. It varies by product and factory, and custom or private-label work tends to carry higher minimums than catalogue items because the factory has to set up materials and tooling for you. MOQs are often negotiable, especially if you accept a higher unit price, a later delivery date, or a promise of repeat orders. A smaller first order costs more per unit, but it limits your potential losses while you test the supplier and the market.
Shipping Sea freight costs less per unit and takes longer. Air freight is faster but more expensive, making it suitable for samples and urgent restocks. For sea freight, a full container (FCL) gives you the entire container, while a less-than-container load (LCL) lets smaller orders share space at a higher per-unit cost. Ask every quote to state its Incoterm, which says who pays for what and where responsibility passes to you. Under FOB, the supplier delivers the goods to the port in China, and you pay the freight from that point onward. Under CIF, the supplier also pays freight and insurance to your destination port.
Duties and clearing Import duty depends on how the product is classified under the Harmonised System (HS) code, and rates differ by product. Check the HS code and the current rate with a licensed clearing agent before you place the order, because a wrong classification can change the bill after the goods arrive. In Nigeria, the goods also need a registered Form M, covered in the section on paying suppliers.
Payment costs Bank fees and exchange rate margins sit on top. For a thin-margin product, a percentage point or two can decide whether an order is worth repeating.
The numbers below are made up and rounded to show how a quote grows. They are not real prices or rates.
Cost
Example amount
Goods: 1,000 units at US$4.00
US$4,000
Sea freight and insurance
US$650
Duties, taxes, and clearing
US$1,200
Quality inspection
US$300
Payment fees and exchange margin (2% of goods)
US$80
Landed cost
US$6,230
On these made-up figures, a unit quoted at US$4.00 costs US$6.23 once it lands, about 56% more. Work out your own version before you agree a price, and repeat it for each product.
Managing suppliers across time zones and currencies
Time zones China runs on UTC+8. Lagos is seven hours behind it, and Nairobi is five hours behind it. A supplier’s working day, roughly 9 am to 6 pm in China, runs from about 2 am to 11 am in Lagos, so the useful overlap is the morning. Agree on a fixed weekly call time, and use written updates for everything else, so nothing depends on both of you being online at once.
Milestones, not trust Split the order into stages and tie each stage to evidence: a confirmed specification and a signed sample; production started, with photos or a video; finished goods before packing; and a pre-shipment inspection. An independent inspection company can check quantity, workmanship, and packaging before you pay the balance. Include these stages in the contract, along with what happens if the goods do not match the sample.
Holidays Chinese New Year and the National Day holiday in early October can close factories for days or weeks, and orders placed just before them can slip. Build the dates into your plan and place orders early.
One record Keep one shared order sheet with the product, specification, quantity, price, currency, deposit paid, balance due, and expected dates. When a supplier changes a price or a date, ask for it in writing and update the sheet.
Currencies Decide the invoice currency at the start. A quote is a snapshot, so ask how long the price is valid. If your local currency weakens between the quote and payment, the same dollar or yuan amount costs more to buy. Where you can, hold or earn the currency you pay in, so a swing in the exchange rate does not change the size of the bill. Splitting a large order into a deposit and a balance paid weeks apart also spreads the exchange rate risk, though it can work in either direction.
How to pay Chinese suppliers from Nigeria and the rest of Africa
There is no single best way to pay a supplier. The right route depends on the size of the order, how well you know the supplier, and what your bank and customs require.
The main ways to pay
Method
How it works
Best for
Watch for
Bank wire (telegraphic transfer)
Your bank sends US dollars, or another currency, to the supplier's bank account, usually through the SWIFT network
Established suppliers and larger orders
Intermediary and receiving bank fees, your bank's exchange rate, and no protection if the supplier does not deliver
Platform payment with escrow
You pay through the marketplace, which protects the payment under its own terms, for example bank wire with escrow protection on Alibaba.com
First orders with a new supplier
Protection applies only if you keep the payment on the platform, and only as far as its terms cover
Letter of credit
Your bank promises to pay the supplier once agreed documents are presented
Large orders where trust is low
Higher bank charges and strict paperwork
Yuan payout through a payment provider
The provider delivers yuan to the supplier's Chinese bank account
Regular small to mid-sized payments
Per-transfer limits, the provider's rate and fee, and whether your bank accepts the route for import documentation
Informal channels and payment agents
A third party pays the supplier for you
Not recommended
You may lack the paperwork your bank and customs expect, and the money is hard to trace if something goes wrong
What Nigerian importers need to know
In Nigeria, an importer must complete Form M for goods entering the country. GTBank’s guide to Form M calls it a mandatory statutory document for all importers who are registered with an authorised dealer (a bank) when the order is placed, whether or not the transaction requires foreign exchange. It is submitted electronically on the CBN’s Trade Portal, which works with the Nigeria Customs Service. It is valid for 180 days for general merchandise and 365 days for plant and machinery, and the bank can extend it.
The CBN’s foreign exchange manual, issued in May 2026, adds a second deadline. Coverage of it says importers must submit exchange control documents within 90 days of negotiating shipping documents with overseas correspondent banks, and that importers who do not can be barred from foreign exchange transactions, including Form M processing, for periods that lengthen with repeat offences. Keep every invoice, contract, and shipping document organised so you can produce them when needed.
Before you pay, ask your bank how it wants the Form M and supporting documents handled for your route, and whether payments made through a payment provider fit its documentation requirements. Rules change, so confirm the current position with your bank or the CBN, not from a blog.
Protect the payment itself
Pay only to an account in the supplier’s registered company name, as shown on the contract and invoice.
Confirm bank details by a second channel, such as a video call, before the first payment and whenever they change. A change of account details sent by email is a common fraud.
Size the deposit to what you can afford to lose on a first order, and tie the balance to the inspection result.
Get the invoice in writing, with the currency, amount, and bank details.
Comparing what you pay
Quotes are hard to compare because the cost is split between a fee and an exchange rate. To compare them, divide the total naira you pay by the amount the supplier receives, then compare the resulting rate with the mid-market rate for the same day. The gap, plus any fee, is the real cost of the transfer. Do the same for each route, and ask the supplier whether the price changes depending on whether you pay in dollars or yuan.
Paying with Grey
Grey recently launched payouts to China, giving Nigerian importers another option.
The supplier receives yuan in their own Chinese bank account with ICBC, Bank of China, China Construction Bank, or Agricultural Bank of China and does not need a Grey account.
Before you confirm, Grey shows the rate and the fee as two separate numbers, and the yuan amount your recipient receives does not change after you confirm.
The account name you enter must match the account name on the supplier’s invoice, so copy it from there.
Grey charges a flat fee of $2.80 per bank transfer, with a limit of 50 to 21,000 yuan per transfer. Transfers are typically completed within 24 hours on banking days, with a 10:00 GMT cut-off; transfers made after this time may take longer. A limit of 21,000 yuan per transfer means a large factory deposit may need to be split into several transfers or paid another way, so check the limit shown in the app for your route before relying on it.
To hold US dollars and convert them when you need to pay, see Grey's foreign accounts. For small-order samples on platforms that accept cards, a virtual card is another option, though payments on non-US websites may incur a cross-border fee. If you pay several suppliers, Grey also offers a business account for cross-border trade with bulk payouts and payment status tracking. Check whether it is available in your country first.
Grey is a financial technology company, not a bank, and works with CBN-licensed banking partners in Nigeria. Its US services are regulated by FinCEN and its Canadian services by FINTRAC.
Frequently asked questions
How do African businesses pay Chinese suppliers?
Most pay through international bank transfer in US dollars or yuan, often with a deposit before production and the balance before shipment. Other routes include platform payments with escrow, letters of credit, and yuan payouts through payment providers. The right choice depends on the order size, the supplier, and your bank’s requirements.
Do they need a Form M to import from China into Nigeria?
Yes. GTBank’s guide describes Form M as a mandatory statutory document for all importers, which must be registered with a bank when the order is placed, whether or not the transaction requires foreign exchange. Confirm the current process with your bank.
Is it better to pay a Chinese supplier in dollars or yuan?
Neither is better by default. Ask the supplier for the price in both currencies, then compare the total you pay in your local currency, including fees and the exchange rate, against the mid-market rate on the day.
How can I check that a Chinese supplier is real?
Ask for the business licence and search its Unified Social Credit Code on China’s National Enterprise Credit Information Publicity System. Make sure the name on the licence, contract, invoice, and bank account match; order samples first; and join a video call before you pay a deposit.
Can I pay a supplier in China with Grey from Nigeria?
Grey offers payouts to Chinese bank accounts, delivered in yuan, from a naira top-up or a USD balance. The recipient does not need a Grey account. Check the fee, rate, and limit shown in the app before you confirm, as per-transfer limits apply.
Does China’s zero-tariff policy make imports from China cheaper?
No. The policy, in force from 1 May 2026, covers goods entering China from 53 African countries. It helps African exporters without changing what importers pay for Chinese goods.
How much deposit should I pay a new supplier?
Terms are negotiable, and a deposit before production, with the balance due before shipment, is a common pattern. For a first order, pay only what you can afford to lose, use platform protection where available, and tie the balance to an inspection result. This is general guidance, not financial advice.
Fees and rates: Grey's CNY payout post lists a flat fee of $2.80 per bank transfer and a limit of 21,000 yuan per transfer. Currency conversion is listed at 1% (capped at $6) on USD, GBP, and EUR transfers, so check the fee shown in the app for your route. A virtual card costs $5 to create once, with no monthly fee, and payments on non-US websites may incur a cross-border fee of 2% plus $0.50. Exchange rates vary with a margin over the mid-market rate, and delivery times depend on the bank, the route, and cut-off times.
AI tools, streaming services, cloud storage, creator platforms and digital subscriptions have quietly changed what a normal financial life costs. What happened to all these new monthly expenses?
My latest obsession is a garden I’ve not yet tended to. My new home will finally have the backyard I've always wanted, and I'm already dreaming about plants, outdoor furniture and slow mornings drinking coffee outside. All the things that come with this new, very offline version of my life.
Which also means I need to make room for them in my budget. So I went through my bank statements looking for a little extra money for my new garden, and what I found was my expensive subscription collection.
Spotify, Netflix, Apple, Amazon, Canva, AI… It’s a long list.
I don't particularly want to give up most of these things. I love having music wherever I go. I use AI almost every day for work. And I'm definitely not giving up my series.
So somewhere between budgeting for my new garden and wondering which subscription I could live without, I started thinking: when did having a normal digital life become something we had to budget for?
The $10 problem
Digital subscriptions have become so normal that they blend into all the other payments you make every day. Until you get an email saying prices are going up, or, like me, you're trying to free up some money to set aside for a dream.
There's something psychologically harmless about $9.99. I would probably think twice before spending $120 on something I wasn't sure I'd use. But $9.99 a month? That barely registers.
The thing is, they're practically the same amount over a year. And these days, $10 doesn't even cover some of our most common subscriptions.
Take Netflix and ChatGPT, for example. Here's what they cost in the US and Nigeria, based on 2026 pricing:
Subscription
US monthly price
Nigeria monthly price
Annual cost (US)
Netflix Standard (no ads)
$19.99
₦6,500
$239.88
ChatGPT Plus
$20
₦31,500*
$240
Total
$39.99
₦38,000
$479.88
ChatGPT Plus price based on the Nigerian iOS App Store. Prices may vary by billing platform.
That's almost $480 a year for just two subscriptions. And we haven't even added Spotify, cloud storage, design software or all those little subscriptions we tend to forget about.
What's worse is that prices keep increasing. In July 2026, Google One reportedly raised its 200GB storage plan in Nigeria from ₦2,900 to ₦4,400 a month, an increase of more than 50%.
And cloud storage is particularly difficult to give up. If you've spent years saving photos, videos and documents in Google Photos, cancelling isn't as simple as deciding you no longer need a service. You might have to move files, delete memories or find another way to pay for storage. Exceeding your free storage allowance can also affect how Gmail, Drive and Photos work.
That's what makes these subscriptions complicated. Some entertain us, others help us work, and a few have become part of how we preserve our lives.
Does that mean I should cancel everything? Not necessarily.
I use many of these services regularly, and they're probably worth every dollar (and Brazilian reais in my case). But $480 could also buy a few pieces of furniture for my backyard. And that's enough to make me look at my subscriptions a little differently.
Work has its own subscription economy now
Freelancers and remote workers might not have office rent, but we certainly have software bills. You could pay for software once and use external storage units to support your work, but these days much of what we use for work and everyday life is available online.
AI tools like ChatGPT, cloud storage, design platforms like Adobe Creative Cloud, and project management software. Suddenly, your one-person business has its own software department, and you’re the software department.
I actually think most of these subscriptions are worth it. They help me do my job, and some save me hours every week.
There's also the fact that I get paid in dollars but live in Brazil. Some of my expenses are in Brazilian reais, others are in USD, especially my work subscriptions. So I've come to appreciate the flexibility to manage both without converting all my income at once.
It's why I use Grey, where I can manage multiple currency balances, shop worldwide with a virtual card, all while saving money thanks to low fees.
It's a small detail, but one that's worth considering when your work and expenses cross borders.
How streaming got expensive again
Remember when Netflix felt like the answer to expensive cable TV? One subscription, endless entertainment. Then everybody decided they needed their own streaming platform.
Now your favourite series is on Netflix, another is on Disney+ (mine happens to be on Apple TV). Then a friend recommends another brilliant show, and, of course, it's somewhere else. We've basically rebuilt the expensive entertainment bundle we wanted to escape, one subscription at a time.
And now the industry is coming together again. With Paramount's proposed takeover of Warner Bros. Discovery, streaming giants are looking to combine their platforms and content libraries. That could mean fewer subscriptions to manage, but analysts are already warning that less competition could bring higher prices. So we might end up paying more for the convenience of having everything in one place.
In theory, we can always cancel and rotate between services. In practice, many of us are paying for a small United Nations of streaming platforms.
We don't really own our digital lives anymore
Just look at how much of your life now exists somewhere you pay to access or maintain. Your photos might be in iCloud or Google Photos. Your files might be in Google Drive, Dropbox or OneDrive. Your playlists live on Spotify. Your favourite films live across streaming services.
Your website exists because you keep paying the hosting bill. Your creative work might depend on software that requires an active subscription.
None of this means subscriptions are inherently bad. In many cases, cloud services are safer and far more convenient than the systems they replaced. But our relationship with ownership has changed.
You can spend hundreds of dollars on a service over several years and still walk away with nothing tangible when you cancel it. Imagine paying for cloud storage for ten years because it contains thousands of family photos. At some point, is that still optional? Technically, yes.
Emotionally, good luck cancelling it.
That’s what makes digital spending different from much traditional discretionary spending. These services gradually weave themselves into our routines until cancelling them means changing the way we work, relax, communicate or remember things.
So, how much does being online actually cost?
This is where I think everyone should do a slightly uncomfortable experiment.
Imagine a relatively casual digital user paying for a video streaming service, music and cloud storage. Individually, those bills probably don't attract much attention. A remote professional might have all three, plus an AI subscription and one or two productivity tools.
A freelancer or creator could add design software, larger cloud storage, website hosting, a domain, editing software and specialised work platforms.
It isn’t difficult for a digital life to reach $100 a month. That’s $1,200 a year. At $200 a month, you’re spending $2,400 a year.
And because these costs are scattered across entertainment, work, storage and apps, we rarely think of them as one expense. We make allowances for housing, transport costs, even our emergency funds. Digital life deserves its own category now.
Look through your bank statement and do a subscription audit. Music and film streaming, Cloud storage, AI, online newsletters. Gaming subscriptions. Creator memberships. Productivity tools. Website costs. Premium features you pay for through the App Store or Google Play, then multiply the monthly total by 12. It is easier to decide whether or not a service is worth keeping when you see how much it costs for a year of use.
Check whether you are paying for similar services, check what storage plans could work for you, and if you are enjoying a free trial, check what pricing looks like when the trial period ends.
I don't think the solution is to become anti-subscription. I use some of them constantly. Cancelling them to make my bank statement prettier wouldn’t necessarily improve my finances or my life.
The more useful exercise is asking what each subscription is actually doing for you. Are you using it for work or daily life? Then there’s my favourite category: subscriptions you forgot existed.
These aren’t saving you time, entertaining you, or storing anything important. They’re simply feeding quietly. A subscription audit doesn’t need to end with cancelling half your digital life. Finding two or three services you no longer use might be enough.
If you work internationally, it’s good to know which of these expenses are being paid for in dollars, pounds or euros.
The new financial skill is deciding what deserves to stay
In the end, I didn't cancel everything after looking at my bank statement. I cancelled two things.
The rest, annoyingly, I actually use.
And maybe that’s the point. Our digital lives aren’t getting any cheaper, especially with new AI tools and subscriptions popping up all the time. So instead of giving everything up, maybe we just need to pay a little more attention to what we're spending and what's actually worth it.
Because the internet doesn’t really feel free anymore. Somewhere between rent, electricity and our phone bills, we’ve built an entirely new category of expenses, $9.99 at a time.
So, after my little deep dive into the cost of being online, I'll leave you with one suggestion: give Grey a try. If you’re earning internationally and juggling different currencies, subscriptions and online payments, having a multi-currency account and a virtual international card can make things a little easier.
And honestly, we could all use a little less to think about.