<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/llc-vs-sole-proprietorship#article","headline":"LLC vs sole proprietorship: Which is right for you?","description":"LLC vs sole proprietorship: compare liability, taxes, cost and paperwork to choose the right US business structure for you. Compare them now.","inLanguage":"en","url":"https://grey.co/blog/llc-vs-sole-proprietorship","mainEntityOfPage":{"@id":"https://grey.co/blog/llc-vs-sole-proprietorship#webpage"},"datePublished":"2026-08-23T22:07:17.204Z","dateModified":"2026-09-29T02:21:27.233Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/llc-vs-sole-proprietorship#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a8b6f0044c353b42487227f_LLC%20vs%20Sole%20Proprietorship%20Which%20Is%20Right%20for%20You-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a8b6f0044c353b42487227f_LLC%20vs%20Sole%20Proprietorship%20Which%20Is%20Right%20for%20You-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/llc-vs-sole-proprietorship#webpage","url":"https://grey.co/blog/llc-vs-sole-proprietorship","name":"LLC vs Sole Proprietorship: Which Is Right? | Grey","description":"LLC vs sole proprietorship: compare liability, taxes, cost and paperwork to choose the right US business structure for you. Compare them now.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/llc-vs-sole-proprietorship#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/llc-vs-sole-proprietorship#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/llc-vs-sole-proprietorship#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"LLC vs sole proprietorship: Which is right for you?","item":"https://grey.co/blog/llc-vs-sole-proprietorship"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/llc-vs-sole-proprietorship#faq","mainEntity":[{"@type":"Question","name":"Is an LLC better than a sole proprietorship?","acceptedAnswer":{"@type":"Answer","text":"Not necessarily. A sole proprietorship is usually simpler and cheaper, while an LLC generally offers personal liability protection and a more formal business structure. The better option depends on your business risk, income, plans for growth and willingness to handle additional state filings, fees and administrative requirements as your business develops."}},{"@type":"Question","name":"Do I need an LLC to start?","acceptedAnswer":{"@type":"Answer","text":"No. You can start many small businesses as a sole proprietor without forming an LLC. For example, a freelancer testing an idea with a few clients may prefer the simpler route. You may still need local licences, permits or a registered business name depending on your location and activities."}},{"@type":"Question","name":"Can I switch from sole proprietor to LLC?","acceptedAnswer":{"@type":"Answer","text":"Yes. Many business owners start as sole proprietors and later form an LLC as their income, clients or business risks increase. You generally create the LLC through your state, obtain any required tax identification numbers and update contracts, accounts, licences and registrations so the business operates under its new structure."}},{"@type":"Question","name":"How are they taxed differently?","acceptedAnswer":{"@type":"Answer","text":"A sole proprietor generally reports business income on their personal federal tax return and pays self-employment tax on net earnings. A single-member LLC is usually taxed the same way by default. However, an LLC may be eligible to elect different tax treatment, potentially changing how some income is taxed."}},{"@type":"Question","name":"Which is cheaper?","acceptedAnswer":{"@type":"Answer","text":"A sole proprietorship is generally cheaper because you typically do not pay a state formation fee simply to create the structure. An LLC usually requires an initial filing fee and may have recurring state fees, reports or taxes. The exact cost varies significantly by state, so check local requirements before deciding."}},{"@type":"Question","name":"Does an LLC protect my personal assets?","acceptedAnswer":{"@type":"Answer","text":"Generally, yes. An LLC creates a legal separation between the business and its owners, which can protect personal assets from many business debts and claims. However, protection is not absolute. Personal guarantees, fraud, certain taxes and wrongful acts can still create personal liability, so an LLC is not complete immunity."}}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/llc-vs-sole-proprietorship#terms","name":"LLC vs sole proprietorship: Which is right for you? glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"sole proprietorship","description":"A sole proprietorship is the simplest business structure in the US. It is essentially you and your business under the same legal identity. If you start freelancing, sell products, offer consulting services or run a small business without registering another business entity, you may already be operating as a sole proprietor.","inDefinedTermSet":{"@id":"https://grey.co/blog/llc-vs-sole-proprietorship#terms"}}]}] </script>

LLC vs sole proprietorship: Which is right for you?

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Choosing a business structure can feel like a small decision until taxes, personal liability and registration requirements start affecting how you run your company. For international entrepreneurs setting up a business in the US, the choice between a sole proprietorship and an LLC can have important financial and legal implications.

A sole proprietorship may offer a simpler way to start, while an LLC provides a separate legal structure that can offer greater protection for your personal assets. The right option depends on your business activities, risk, tax situation and plans for growth.

Before registering your US business, it is worth understanding how each structure works and what it means for you as a business owner.

Also read: How to Register as Self-Employed: UK and US Guide

LLC vs sole proprietorship: the key differences at a glance

If you are deciding between keeping things simple or creating a separate legal business entity, these are the differences that matter most.

What matters Sole proprietorship LLC
Personal liability You are generally personally responsible for business debts and obligations. Generally provides personal liability protection, subject to exceptions.
Tax Business income is typically reported on your personal tax return. Usually pass-through taxation by default, with other tax elections available.
Cost Usually cheaper to start and maintain, with fewer formal requirements. Registration and ongoing state fees can make it more expensive.
Paperwork Minimal setup and fewer ongoing formalities. More formation paperwork and state compliance requirements.
Credibility Simple and perfectly suitable for many small businesses, but may appear less formal. A separate business entity can give the business a more established structure.
Best suited to Freelancers, solo operators and low-risk businesses testing an idea. Owners seeking liability protection, a formal structure or room to grow.

What is a sole proprietorship?

A sole proprietorship is the simplest business structure in the US. It is essentially you and your business under the same legal identity. If you start freelancing, sell products, offer consulting services or run a small business without registering another business entity, you may already be operating as a sole proprietor.

How does it starts?

Unlike an LLC, you generally do not create a sole proprietorship by filing formation documents with the state. It can arise automatically when you carry on a business by yourself without choosing a different legal structure. You may still need to register a trade name, obtain licences or permits and deal with local requirements depending on where you operate.

Why do people choose it?

The appeal is straightforward: less administration and lower setup costs.

  • Easy to start
  • Fewer ongoing formalities
  • Simple tax reporting
  • Complete control over business decisions

For someone testing a business idea or working independently, that simplicity can be valuable.

The biggest drawback is personal liability. Because the business and owner are not legally separate, business debts and certain claims can put your personal assets at risk. If the business grows or takes on greater financial or legal risk, an LLC may provide a more suitable structure.

What is an LLC and how is it different from a sole proprietorship?

If you are comparing an LLC vs sole proprietorship, the biggest difference is what happens when the business and the owner are treated as separate. A limited liability company (LLC) is a business entity created under state law. Unlike a sole proprietorship, the LLC generally creates a legal separation between you and the business.

How an LLC is formed

Setting one up usually involves a few practical steps:

  • Choose an available business name that meets your state’s rules.
  • Appoint a registered agent.
  • File Articles of Organisation with the state.
  • Pay the required formation fee.
  • Create an operating agreement where appropriate.
  • Apply for an Employer Identification Number (EIN) if needed.

For example, imagine you run a small web design business. As a sole proprietor, a business debt is generally your personal responsibility. With an LLC, the company generally stands separately, meaning your personal assets may receive protection from business debts and certain claims. That protection is not absolute, however, and personal guarantees, fraud and some other circumstances can still create personal liability.

How taxes work

For federal income tax purposes, a single-member LLC is generally treated as a disregarded entity by default, meaning its business income typically passes through to the owner's personal tax return. An LLC can also elect different tax treatment if eligible.

So, when weighing an LLC vs sole proprietorship, think beyond the registration fee: liability, administration, taxation and the level of risk your business carries all matter.

Also read: Freelancer vs Employee Tax: What You Owe Compared

What are the key differences between an LLC and a Sole Proprietorship?

Choosing between an LLC vs sole proprietorship often comes down to three practical questions: what happens if the business owes money, how will the income be taxed, and how much will the structure cost to maintain?

Personal liability

A sole proprietor and the business are legally the same. If the business cannot pay a supplier or faces a qualifying lawsuit, the owner’s personal assets can potentially be exposed.

An LLC generally creates a legal separation. For example, if your design business owes $20,000 in business debts, the LLC structure can generally protect your personal savings and property from those business obligations. That protection has limits, particularly where you personally guarantee a debt or engage in wrongful conduct.

Taxes

A sole proprietor normally reports business income on their personal tax return and generally pays self-employment tax on net earnings.

A single-member LLC is usually taxed similarly by default for federal income tax purposes, so forming an LLC does not automatically eliminate self-employment tax. However, an eligible LLC can choose a different tax classification, such as S corporation treatment, which may change how some income is taxed.

Cost

A sole proprietorship is usually the cheaper option because there is generally no state formation filing simply to create the structure.

An LLC normally involves a state filing fee and may have recurring annual or biennial fees, reports or taxes depending on the state. So while an LLC can provide valuable protection, it also comes with additional administrative costs and responsibilities.

Which is right for you: an LLC or sole proprietorship?

There is no universal winner in the LLC vs sole proprietorship decision. The better choice depends on what you are building, how much risk you are taking on and where you expect the business to go. A freelancer testing an idea with a few clients has different needs from someone signing large contracts or employing staff.

Start simple when the risk is low

A sole proprietorship can make sense when you are working alone, keeping costs down and testing whether your idea can make money. For example, a freelance writer earning modest income from a handful of clients may prefer the simpler setup while getting established.

Consider an LLC as things grow

An LLC may become more attractive when the business starts taking on greater financial or legal risk. You might consider one if you are:

  • Signing larger contracts
  • Hiring employees or contractors
  • Taking on business debt
  • Holding significant business assets
  • Working in an industry where liability is a bigger concern

You do not necessarily have to start with an LLC. Some people begin as sole proprietors, prove that the business works, then form an LLC when their income, clients or exposure increases. The important thing is to review the decision as the business changes rather than choosing a structure and forgetting about it.

How to get paid as a US Based business

Once your business starts bringing in money, getting paid is only half the job; you also need a sensible place to receive, hold and move that money. A US business bank account can handle everyday expenses, payroll, subscriptions and payments from domestic customers while keeping business finances separate from personal spending.

International clients can make things slightly more complicated. A client in the UK, for example, may need to pay you in USD, while another client in Europe may prefer a different payment route. That is where having access to suitable foreign-currency payment options can make receiving international income easier.

[Grey](https://app.grey.co/auth/register?) can complement your business banking setup when you work with clients across borders. You can receive and manage supported currencies, including USD, through your Grey account, then convert or move funds when needed. This can be useful for freelancers, agencies and online businesses earning from international clients. Download the Grey app to create an account and check the currencies and services currently available to your business.

Frequently asked questions on LLC and sole proprietorship

Is an LLC better than a sole proprietorship?

Not necessarily. A sole proprietorship is usually simpler and cheaper, while an LLC generally offers personal liability protection and a more formal business structure. The better option depends on your business risk, income, plans for growth and willingness to handle additional state filings, fees and administrative requirements as your business develops.

Do I need an LLC to start?

No. You can start many small businesses as a sole proprietor without forming an LLC. For example, a freelancer testing an idea with a few clients may prefer the simpler route. You may still need local licences, permits or a registered business name depending on your location and activities.

Can I switch from sole proprietor to LLC?

Yes. Many business owners start as sole proprietors and later form an LLC as their income, clients or business risks increase. You generally create the LLC through your state, obtain any required tax identification numbers and update contracts, accounts, licences and registrations so the business operates under its new structure.

How are they taxed differently?

A sole proprietor generally reports business income on their personal federal tax return and pays self-employment tax on net earnings. A single-member LLC is usually taxed the same way by default. However, an LLC may be eligible to elect different tax treatment, potentially changing how some income is taxed.

Which is cheaper?

A sole proprietorship is generally cheaper because you typically do not pay a state formation fee simply to create the structure. An LLC usually requires an initial filing fee and may have recurring state fees, reports or taxes. The exact cost varies significantly by state, so check local requirements before deciding.

Does an LLC protect my personal assets?

Generally, yes. An LLC creates a legal separation between the business and its owners, which can protect personal assets from many business debts and claims. However, protection is not absolute. Personal guarantees, fraud, certain taxes and wrongful acts can still create personal liability, so an LLC is not complete immunity.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How much does Square charge per transaction?

•

•

2 min read

It’s a packed Saturday afternoon at your coffee shop. The line stretches out the door, orders are flying, and customers are tapping their cards and phones at the register every thirty seconds. By closing time, you’ve had your best sales day of the month. Then Monday morning rolls around, you check your bank payout, and the deposit is noticeably smaller than the total on your sales screen.

If you’ve ever had that moment of confusion, you’re looking at payment processing fees in action. For many small businesses, those payments are handled by Square, an all-in-one financial and point-of-sale (POS) platform that lets merchants accept card and mobile payments in person or online.

While Square makes getting paid easy, figuring out how much it takes from each sale can be a bit complicated. Between different rates for card taps and online invoices, the advertised numbers don't always tell the full story.

This guide breaks down how Square’s pricing actually works across every payment method, and the extra costs to take note of.

What is Square?

Square is a financial service and merchant platform that provides point-of-sale (POS) hardware, software, and payment processing solutions. It makes buying and selling easier by making digital card payments accessible to business owners.

How does Square pricing work?

Square uses a transaction-based pricing model, which means businesses pay a fee whenever they process a payment. Most card payments come with two charges: a percentage of the transaction amount and a fixed fee. For example, if Square charges 2.6% + $0.15, it takes 2.6% of the payment amount and an additional 15 cents. If a customer paid $100 using a card, the the business would receive $97.25.

The amount you pay depends on how a customer makes a payment. When someone pays in person using a card, Square charges a lower processing rate. However, online payments and manually entered card details usually cost more because they carry a higher risk of fraud. This is because the customer and their physical card are not necessarily present when the payment is made.

Square also offers three main subscription plans: Square Free, Square Plus and Square Premium. The Free plan has no monthly subscription fee, while the paid plans offer additional business tools and lower processing rates for some payment types.

The plan you end up choosing will affect how much you spend on transaction fees and software each month. Understanding these costs can help you choose a plan that suits your business and avoid paying for features you do not need.

Square fees by transaction type

Your exact Square processing fee depends on how a customer pays. For example, processing a payment in person generally costs less than accepting a card payment through your website.

The table below shows Square's published US processing fees for 2026.

Payment type Square Free ($0/month) Square Plus ($49/month) Square Premium ($149/month)
In-person (tap, dip or swipe) 2.6% + $0.15 2.5% + $0.15 2.4% + $0.15
Online store and Square invoices (card) 3.3% + $0.30 2.9% + $0.30 2.9% + $0.30
Online API (custom, website/app) 2.9% + $0.30 2.9% + $0.30 2.9% + $0.30
Manually keyed-in card payments 3.5% + $0.15 3.5% + $0.15 3.5% + $0.15
ACH bank transfer (via invoice) 1% ($1 min, no cap) 1% ($1 min, $10 cap) 1% ($1 min, $10 cap)
ACH bank transfer (via API or payment link) 1% ($1 min, $5 cap) 1% ($1 min, $5 cap) 1% ($1 min, $5 cap)
Afterpay (buy now, pay later) 6% + $0.30 6% + $0.30 6% + $0.30
International payment cards +1.5% on base rate +1.5% on base rate +1.5% on base rate
Cash or cheque Free ($0) Free ($0) Free ($0)

‍Note: Grey is not affiliated with Square. These rates apply to eligible US-based Square accounts and may change. Always check Square's official pricing page for the latest information.

A few other payment methods have different fees:

  • International cards: An additional 1.5% applies to cards issued outside the US.
  • Afterpay: 6% + $0.30 per transaction.
  • EBT payments: 1.8% + $0.05 per transaction.
  • Cash and cheques: No processing fee.
  • Gift card loading: 2.5% on Free and Plus plans; no loading fee on Premium.

Others costs to budget for

Transaction fees are not the only expenses to consider when using Square. Businesses may also need to pay for payment equipment, monthly subscriptions and certain banking services.

Monthly software plans: Square offers three main plans: Free ($0 per month), Plus ($49 per month, per location) and Premium ($149 per month, per location). Paid plans come with additional business management features and lower processing rates for some payment types.

Hardware: Businesses may need to purchase equipment to accept in-person payments. Square's contactless and chip reader costs $59, while Square Stand costs $149. More advanced options include Square Terminal at $299 and Square Register at $899. These are one-time hardware purchases, separate from subscription fees.

Chargebacks: Square does not charge an additional fee for handling payment disputes. However, it may temporarily withhold the disputed amount from your balance or linked bank account while investigating the claim.

Instant payouts: Standard next-business-day transfers are free, but businesses that need faster access to their money can use instant or same-day transfers for a 1.95% fee.‍

Refunds: Square does not charge an extra fee to issue a refund, and your customer receives their full purchase price back. However, Square keeps the original payment processing fee you paid when the sale first went through.

‍
What Square actually costs a small business

Looking at Square's advertised processing rates alone does not always show how much a business will spend. The actual cost depends on how many transactions it processes, how much customers spend and which payment methods they use.

To understand how this works, consider a small retail business that makes $15,000 in monthly sales. Assume $10,000 comes from in-person card payments, with an average purchase of $50, while the remaining $5,000 comes from online orders, with an average purchase of $100.

The business processes 200 in-person transactions and 50 online transactions each month.

Using Square Free

On the Free plan, the business pays 2.6% + $0.15 for in-person payments and 3.3% + $0.30 for online payments.

  • In-person payments ($10,000 across 200 transactions): The percentage fee is $260 (2.6% of $10,000). The fixed fee is $30 (200 × $0.15). This brings the total in-person processing cost to $290.
  • Online payments ($5,000 across 50 transactions): The percentage fee is $165 (3.3% of $5,000). The fixed fee is $15 (50 × $0.30). The total online processing cost is $180.
  • Total monthly processing fees: $290 + $180 = $470.

The business pays $470 to process $15,000 in monthly sales. This is an effective processing rate of approximately 3.13%.

Using Square Plus

Suppose the same business upgrades to Square Plus for $49 per month. Its in-person processing rate drops to 2.5% + $0.15, while its online rate drops to 2.9% + $0.30.

  • In-person payments ($10,000 across 200 transactions): The percentage fee is $250 (2.5% of $10,000). The fixed fee is $30 (200 × $0.15). Total: $280.
  • Online payments ($5,000 across 50 transactions): The percentage fee is $145 (2.9% of $5,000). The fixed fee is $15 (50 × $0.30). Total: $160.
  • Total processing fees: $280 + $160 = $440.
  • Monthly subscription: $49.
  • Total monthly cost: $440 + $49 = $489.

In this example, the business spends $489 per month on Square Plus, compared with $470 on Square Free.

Although Square Plus reduces the business's processing fees by $30, the $49 subscription costs an additional $19. This makes the Free plan the cheaper option for this business.

The example shows why business owners should consider their monthly sales, transaction volumes and payment methods before choosing a Square subscription. A paid plan is not automatically cheaper, even if it offers lower transaction rates.
However, a business that processes more payments or needs the additional software features may find that upgrading is worthwhile.

Getting paid across borders using Grey

For all its benefits and features, Square is built for local payments. To use it, your business must be registered in a supported country and linked to a local bank account in that same currency. If you run a US business, Square sends your payouts in US dollars. Once your money lands, moving it across borders gets expensive. Sending funds to overseas suppliers, remote workers, or your bank account back home often means high wire fees and inconsistent and often expensive bank exchange rates.

If you run a business that spans continents, you will need a cost-effective way to move money. Grey gives you flexibility and control over what happens to your funds after you get paid. Grey does not replace Square at checkout. While Square handles payment collections, Grey helps you manage and move your money once you get paid. With Grey foreign accounts, you get US, UK, and European account details to receive USD, GBP, and EUR payouts. You can then swap currencies with Grey currency exchange at transparent rates or send money internationally to over 80 countries.

‍

Frequently Asked Questions

How much does Square take per transaction?

Square charges 2.6% plus $0.15 for in-person tap, dip, or swipe payments on its free plan. Online payments and invoices cost 3.3% plus $0.30, while manually keyed entries cost 3.5% plus $0.15. Paid plans have a lower percentage rate in exchange for a recurring monthly subscription fee.

Does Square have monthly fees?

The Square Free plan has no monthly subscription fee; you only pay when you successfully process a transaction. However, Square offers paid tiers such as Square Plus at $49 per month and Square Premium at $149 per month, which unlock reduced processing rates and advanced administrative tools.

Why was I charged more than the standard rate?

You might get higher charges if you manually key in customer card numbers instead of using a physical reader, process international cards which has an additional surcharge, or use add-on services like Afterpay or instant payout transfers.

How fast are payouts?

Standard bank transfers from Square are included at no extra charge and typically arrive as soon as the next business day. If you want immediate access to your funds, instant payouts are available for a 1.95% fee.

Does Square charge for refunds?

Square does not charge extra processing fees when you issue a refund. When you refund a payment in full, Square returns the original processing fee to your account. Partial refunds receive a proportional fee return.

Selling across borders? Receive and move your money with Grey.
9 best platforms to earn US dollars in India

•

•

2 min read

You do not need to relocate to earn in dollars. Thousands of Indians are already doing it, working remotely for US companies, freelancing on global platforms, selling digital products, and teaching online. The platforms exist. The demand for Indian talent exists. The only question is how you set yourself up to earn, receive, and keep more of that income.

This guide covers the best platforms to earn US dollars in India, the types of work that pay in USD, and how to withdraw your earnings to your Indian bank account without incurring steep conversion fees or slow bank transfers.

Why earning in USD makes sense for Indians

The Indian rupee has depreciated consistently over the past decade, and inflation continues to pressure salaries and savings. At the same time, global demand for digital services in development, design, writing, marketing, and education continues to grow. Earning in a stable currency like USD gives you a structural advantage.

Beyond currency stability, dollar income gives you stronger purchasing power for international tools, courses, and subscriptions. It gives you better returns when saving or investing. And it gives you more control over when and how you convert, so you can time your conversions around exchange rate movements instead of being forced into bad rates by your bank.

What kind of work pays in USD from India?

Indians are earning dollars in more ways than most people realise. Some of the most common paths include:

  • Freelancing: Writing, web development, video editing, translation, graphic design, and digital marketing on platforms that connect you with international clients.
  • Remote contract jobs: Especially with US-based startups that hire globally for engineering, product, operations, and customer support roles.
  • Online tutoring and teaching: Conversational English, test prep (SAT, GRE, GMAT), and academic subjects through platforms that pay per session or per minute in USD.
  • Content creation: YouTube ad revenue via AdSense, Instagram Reels bonuses, podcast sponsorships, and newsletter monetisation.
  • Selling digital products: Online courses, design templates, printables, stock photography, and music through global marketplaces.
  • Affiliate marketing and dropshipping: Promoting international products and earning commissions in USD.
  • User testing and surveys: Getting paid to review websites, apps, and prototypes for US companies.

Whatever your skill set, there is likely a global market for it, and platforms to help you access it. If you are freelancing for international clients, Grey also lets you invoice clients abroad directly from the app.

Top platforms to earn US dollars in India

Here are 9 platforms Indians use to get paid in USD, with practical details on how each works.

1. Upwork

Upwork is one of the largest freelance marketplaces globally, and Indian professionals regularly secure contracts with US and European clients across fields such as software development, writing, design, data analysis, and virtual assistance. Upwork pays in USD and lets you withdraw via direct bank transfer, PayPal, Payoneer, or wire transfer.

The platform takes a sliding service fee: 20% on the first $500 with each client, dropping to 10% after that, and 5% after $10,000. Long-term contracts are where the real value is. Once you build a relationship with a client and move past the initial fee bracket, Upwork becomes significantly more cost-effective than other platforms.

Best for: Developers, writers, designers, VAs, and marketers with at least some portfolio work to show.

2. Fiverr

Fiverr works differently from Upwork. Instead of bidding on projects, you list fixed-price services ("gigs") and buyers come to you. This suits creatives and service providers who prefer packaging their skills into clear deliverables, such as logo design, video editing, voiceover work, social media management, or website builds.

Fiverr takes a flat 20% commission on every order. Earnings are in USD and can be withdrawn via PayPal, bank transfer, or Fiverr Revenue Card. The key to earning well on Fiverr is niche positioning and strong reviews. Generic gigs get buried.

Best for: Designers, video editors, voiceover artists, and anyone who can package a service into a clear deliverable.

3. Toptal

Toptal is a premium platform that accepts only the top 3% of applicants in software engineering, design, and finance. The vetting process is rigorous (multiple interviews and a test project), but the payoff is access to high-quality, well-paying contracts with major companies. Rates are significantly higher than general freelance platforms, often $60-$150+/hour depending on the role.

Best for: Experienced developers, designers, and finance professionals who can pass the vetting process and want premium rates.

4. Amazon KDP (Kindle Direct Publishing)

If you can write, Amazon KDP lets you self-publish eBooks, paperbacks, and low-content books (journals, planners, workbooks) and earn royalties in USD. Royalties range from 35% to 70%, depending on pricing and distribution. The income is passive once a book is published, and some Indian authors have built meaningful monthly income streams with a catalog of 10-20 books in specific niches.

Best for: Writers, educators, and anyone willing to learn self-publishing. Works well as a side income that compounds over time.

5. YouTube Partner Program

Once your channel hits 1,000 subscribers and 4,000 watch hours (or 10 million Shorts views), you can monetise through Google AdSense. Ad revenue is paid in USD. Indian creators in English-language niches (tech reviews, personal finance, education, productivity) tend to earn higher CPMs than Hindi-language content because advertisers pay more for English-speaking audiences.

Best for: Creators with a niche, consistency, and willingness to build an audience over 6-12 months before meaningful income kicks in.

6. Cambly

Cambly pays you to teach conversational English to learners worldwide. There is no lesson prep required; you simply have conversations. Pay is $0.17/minute ($10.20/hour), paid weekly via PayPal. The sessions are casual and unstructured, which makes it one of the lowest-effort ways to earn USD if you are a fluent English speaker.

Best for: Fluent English speakers looking for flexible, low-commitment side income. Particularly popular with students and professionals with flexible schedules.

7. Teachable and Gumroad

If you have expertise in any subject, you can package it as an online course (Teachable) or as a digital product, such as templates, guides, or design assets (Gumroad). Both platforms serve a global audience and pay in USD. Earning potential scales with your audience and your marketing. Some Indian creators earn $1,000-$5,000+/month from a single well-positioned course.

Best for: Subject matter experts, designers, and educators who can build or already have an audience to sell to.

8. UserTesting and TryMyUI

These platforms pay you to test websites and apps and share your feedback via screen recording. Each test takes 15-20 minutes and pays $4-$10 (UserTesting pays $10 for most tests). Availability depends on your demographic profile matching what companies need, so it works best as supplemental income rather than a primary source of income.

Best for: Anyone with clear English communication skills and a computer with a microphone. Good for side income between other work.

9. Etsy

Even without shipping physical products, you can sell digital downloads on Etsy: printable planners, resume templates, wedding invitations, digital art, and social media templates. Etsy charges a $0.20 listing fee plus a 6.5% transaction fee. Earnings are in USD. The platform has a built-in audience of buyers searching for these products, so you do not need to drive your own traffic.

Best for: Designers and creatives who can produce templates or digital art. Works well as passive income once listings are live.

Also read: Best way to receive euros in India

How to actually receive your USD earnings in India

Landing a client or getting approved on a platform is only half the problem. Withdrawing your earnings to India is where most people lose money.

Traditional Indian banks typically charge 1.5-3% on foreign currency conversion, add wire transfer fees of $15-$30 per transaction, offer exchange rates 2-4% worse than the mid-market rate, take 3-5 business days to process, and require paperwork that slows everything down. PayPal is faster but takes a 3-4% cut when converting USD to INR, in addition to withdrawal fees.

How Grey works for USD earnings in India

Grey gives you a free USD account with US bank details (routing number and account number). You can share these details with clients, connect them to freelance platforms, or use them to receive payments from any US-based source.

Here is how the flow works:

  1. Receive USD: Share your Grey US bank details with your client or platform. Payments arrive as standard ACH transfers.
  2. Hold or convert: Your USD sits in your Grey wallet. No forced conversion. You decide when to move it to INR based on the exchange rate.
  3. Withdraw to India: When you are ready, send to any Indian bank account using the recipient's IFSC code and account number. Grey charges a 1% conversion fee on USD to INR.
  4. Spend in USD: Need to pay for tools, subscriptions, or courses in dollars? Use your Grey virtual USD card to pay directly without converting first.

For a detailed walkthrough with screenshots, see the step-by-step guide to sending money to India. For a full breakdown of costs, check Grey's fees and charges.

Grey vs other ways to receive USD in India

Method Conversion Cost Speed Hold USD?
Grey 1% conversion fee Same day to 1 business day Yes, convert when you choose
Indian bank wire 1.5–3% + wire fee ($15–30) 3–5 business days Requires separate forex account
PayPal 3–4% total (conversion + withdrawal) 1–3 business days Limited, auto-converts
Payoneer Up to 2% + withdrawal fee 2–5 business days Yes, but fees on holding

You can check the current USD-to-INR rate and see the exact amount you would receive using Grey's fee calculator.

Also read: How to receive British pounds in India

Tips to maximise your USD earnings from India

Work directly with clients when possible

Platforms like Upwork and Fiverr take 10-20% in service fees. Once you have built a relationship with a client, consider moving to direct contracts with invoicing. You save the platform fee and get paid faster.

Time your conversions

The USD/INR rate fluctuates daily. If you can hold your dollars in your Grey account and convert when the rate is favourable, you keep more of your earnings. Watch exchange rate trends and convert in batches rather than converting every payment immediately.

Diversify your income sources

Relying on a single platform or client is risky. Combine freelancing with passive income (KDP, digital products) or side income (tutoring, user testing) to stabilise your cash flow.

Track everything

Use a simple Google Sheet or Notion database to track invoices, payment dates, conversion rates, and net INR received. This helps you understand your effective hourly rate across platforms and makes tax filing easier.

Understand the tax implications

Income earned in USD is taxable in India. Freelance income falls under "Income from Business and Profession" and is subject to your applicable income tax slab. You can deduct legitimate business expenses (software, equipment, and internet). If your gross receipts exceed Rs 50 lakh, you may need a tax audit. Consult a CA who understands freelance and foreign income if you regularly earn in USD.

This article is intended for general guidance and does not replace professional tax advice. Readers should consult a chartered accountant for personalised recommendations.

Start earning and receiving USD today. Open a free Grey account and get US bank details you can share with clients and platforms immediately.

Frequently asked questions

How can I earn US dollars from India?

You can earn USD from India through freelancing platforms (Upwork, Fiverr, Toptal), teaching English online (Cambly), selling digital products (Amazon KDP, Gumroad, Etsy), content creation (YouTube), and user testing (UserTesting). Most of these platforms pay in USD and allow you to withdraw to an Indian bank account or a USD account like Grey.

How do I receive USD payments in India?

You can receive USD payments through a Grey USD account, which gives you US bank details (routing number and account number) to share with clients or platforms. When you are ready to withdraw, you can send the funds to any Indian bank account using the recipient's IFSC code and account number. Grey charges a 1% conversion fee.

Is it legal to earn in USD from India?

Yes. Earning foreign currency for services rendered from India is legal under FEMA (Foreign Exchange Management Act) guidelines. You are required to declare the income for tax purposes, and it is taxable under the Indian income tax law based on your slab rate.

Which platform pays the most for freelancers in India?

Toptal pays the highest rates (often $60-$150+/hour) but only accepts the top 3% of applicants. For most freelancers, Upwork offers the best balance of volume and rate, especially once you move past the initial 20% fee bracket with repeat clients.

How do I avoid losing money on USD to INR conversion?

Avoid using traditional bank wires (1.5-3% markup) or PayPal (3-4% total cost). Use a platform like Grey that charges a transparent 1% conversion fee and lets you hold USD until the exchange rate is favourable. Check the exact amount you would receive using the fee calculator before converting.

Can NRIs use Grey to receive USD?

Grey provides USD accounts that NRIs can use to receive payments from US clients or employers. You can hold dollars in the account and send INR to any Indian bank account when you need to transfer money home.

More from Grey:

How African businesses source from and pay suppliers in China

•

•

2 min read

Say you’re dealing with a factory whose quote is in dollars, and they want a deposit before production starts, and the account details arrive by email under a company name that isn’t quite the one on the invoice. For a first-time importer in Lagos or Nairobi, nothing about that moment is unusual, and each part of it is a place where a small mistake costs real money.

Many African businesses usually pay Chinese suppliers by international bank transfer, in US dollars or yuan. A common pattern is a deposit before production and the balance before shipment, though terms are negotiable. Importers in Nigeria must also register a Form M with their bank. Platform escrow, where offered, adds protection for first orders.

However, with cross-border and global payments making it easier for businesses to settle renminbi (RMB) transactions, trading with China has become easier, and more options are available to people and businesses to send yuan directly to local bank accounts in China.

In this article, I cover how to find and check a supplier, what an order should cost, how to manage the relationship, and how to pay.

Why China, and why now?

If you are looking to start or scale a business, China is hard not to consider. China is a major source of manufactured goods for African businesses, and the volumes show it. Trade between China and Africa reached a record US$348.05 billion in 2025, up 17.7% on the year, according to a report from the NTU-SBF Centre for African Studies. Chinese exports to Africa accounted for US$225.03 billion, up 25.8%, while imports from Africa were US$123.02 billion, up 5.4%. The same report puts Africa’s deficit with China at US$102.01 billion, meaning African buyers are importing far more than they export.

Behind those totals are the businesses this guide is for: shop owners, online sellers, and small manufacturers who buy fabric, electronics, machine parts, packaging, and finished goods. A growing number go a step further and develop private-label products, in which a factory makes a product to the importer's specifications and under the importer’s brand. That raises the stakes on everything that follows: choosing the factory, agreeing the order size, checking quality, and moving the money.

What has changed in China-Africa trade in the last five years

China opened its market to African exports
Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.

China opened its market to African exports
Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.

Nigeria’s foreign exchange policy has been updated
The CBN issued a new foreign exchange manual in May 2026. Coverage states that importers must submit exchange control documents within 90 days of negotiating shipping documents, and that importers who fail to do so may be restricted from the foreign exchange market. We’ll talk about this a bit more in the section on paying suppliers.

There are more ways to pay in yuan
Some payment providers, like Grey, now deliver yuan directly to Chinese bank accounts, giving importers an alternative to paying only in dollars.

How to find a reliable Chinese supplier

For businesses looking to source from China, finding a supplier often starts with an online marketplace, especially for first-time importers.

Alibaba.com is built for export buyers and lists suppliers that work with overseas customers. 1688 is China’s domestic wholesale platform. It is written in Chinese, prices are often lower, and most foreign buyers use a sourcing agent or a translator to work with it. Trade fairs such as the Canton Fair in Guangzhou let you meet suppliers and handle samples in person, and referrals from other importers in your market often lead to suppliers that already ship to Africa.

Factory or trading company?
When you make contact, you have to ask directly: “Do you own the factory?” A trading company is not a bad choice, since it can combine products from several factories and handle export paperwork, but it adds its own margin and puts you one step further from the people making your product. A factory can usually show its production line on a video call and explain who works on your order.

Check that the company exists
Ask for the business licence, which carries an 18-character Unified Social Credit Code. China’s National Enterprise Credit Information Publicity System at gsxt.gov.cn lets you search for that code to see whether the company is registered, who its legal representative is, and whether it has abnormal operation records. The site is in Chinese with no official English version and can be slow from outside China, so browser translation helps. Two limits matter. A matching code proves that a company exists, not that the person you are talking to works for it. And the English name on a supplier’s profile often differs from its registered Chinese name, so make sure the name on the licence, contract, invoice, and bank account all match.

Order samples before you commit
Pay for samples, test them yourself, and then compare the first production units with the approved sample. Making one good sample is easy. What you want to know is whether the supplier can repeat it.

Document exactly what you want
A supplier can only build what is written down. Send specifications with photos, dimensions, materials, colours, packaging, and tolerances, and confirm every decision in writing, even if you also talk on WeChat or WhatsApp. Ask the supplier to repeat back what they will make.

Warning signs
A price far below every other quote, a refusal to join a video call, pressure to pay quickly, a request to pay a personal account for a company order, or a request to move the payment outside the platform you are using.

The real cost of sourcing from China: MOQs, shipping and duties

The price in the quote is the starting point, not the end. What matters is the landed cost: everything you have paid by the time the goods are in your warehouse.

MOQs
A minimum order quantity (MOQ) is the smallest order a supplier will produce. It varies by product and factory, and custom or private-label work tends to carry higher minimums than catalogue items because the factory has to set up materials and tooling for you. MOQs are often negotiable, especially if you accept a higher unit price, a later delivery date, or a promise of repeat orders. A smaller first order costs more per unit, but it limits your potential losses while you test the supplier and the market.

Shipping
Sea freight costs less per unit and takes longer. Air freight is faster but more expensive, making it suitable for samples and urgent restocks. For sea freight, a full container (FCL) gives you the entire container, while a less-than-container load (LCL) lets smaller orders share space at a higher per-unit cost. Ask every quote to state its Incoterm, which says who pays for what and where responsibility passes to you. Under FOB, the supplier delivers the goods to the port in China, and you pay the freight from that point onward. Under CIF, the supplier also pays freight and insurance to your destination port.

Duties and clearing
Import duty depends on how the product is classified under the Harmonised System (HS) code, and rates differ by product. Check the HS code and the current rate with a licensed clearing agent before you place the order, because a wrong classification can change the bill after the goods arrive. In Nigeria, the goods also need a registered Form M, covered in the section on paying suppliers.

Payment costs
Bank fees and exchange rate margins sit on top. For a thin-margin product, a percentage point or two can decide whether an order is worth repeating.

The numbers below are made up and rounded to show how a quote grows. They are not real prices or rates.

Cost Example amount
Goods: 1,000 units at US$4.00 US$4,000
Sea freight and insurance US$650
Duties, taxes, and clearing US$1,200
Quality inspection US$300
Payment fees and exchange margin (2% of goods) US$80
Landed cost US$6,230

‍

On these made-up figures, a unit quoted at US$4.00 costs US$6.23 once it lands, about 56% more. Work out your own version before you agree a price, and repeat it for each product.

Managing suppliers across time zones and currencies

Time zones
China runs on UTC+8. Lagos is seven hours behind it, and Nairobi is five hours behind it. A supplier’s working day, roughly 9 am to 6 pm in China, runs from about 2 am to 11 am in Lagos, so the useful overlap is the morning. Agree on a fixed weekly call time, and use written updates for everything else, so nothing depends on both of you being online at once.

Milestones, not trust
Split the order into stages and tie each stage to evidence: a confirmed specification and a signed sample; production started, with photos or a video; finished goods before packing; and a pre-shipment inspection. An independent inspection company can check quantity, workmanship, and packaging before you pay the balance. Include these stages in the contract, along with what happens if the goods do not match the sample.

Holidays
Chinese New Year and the National Day holiday in early October can close factories for days or weeks, and orders placed just before them can slip. Build the dates into your plan and place orders early.

One record
Keep one shared order sheet with the product, specification, quantity, price, currency, deposit paid, balance due, and expected dates. When a supplier changes a price or a date, ask for it in writing and update the sheet.

Currencies
Decide the invoice currency at the start. A quote is a snapshot, so ask how long the price is valid. If your local currency weakens between the quote and payment, the same dollar or yuan amount costs more to buy. Where you can, hold or earn the currency you pay in, so a swing in the exchange rate does not change the size of the bill. Splitting a large order into a deposit and a balance paid weeks apart also spreads the exchange rate risk, though it can work in either direction.

How to pay Chinese suppliers from Nigeria and the rest of Africa

There is no single best way to pay a supplier. The right route depends on the size of the order, how well you know the supplier, and what your bank and customs require.

The main ways to pay

Method How it works Best for Watch for
Bank wire (telegraphic transfer) Your bank sends US dollars, or another currency, to the supplier's bank account, usually through the SWIFT network Established suppliers and larger orders Intermediary and receiving bank fees, your bank's exchange rate, and no protection if the supplier does not deliver
Platform payment with escrow You pay through the marketplace, which protects the payment under its own terms, for example bank wire with escrow protection on Alibaba.com First orders with a new supplier Protection applies only if you keep the payment on the platform, and only as far as its terms cover
Letter of credit

Your bank promises to pay the supplier once agreed documents are presented Large orders where trust is low Higher bank charges and strict paperwork
Yuan payout through a payment provider The provider delivers yuan to the supplier's Chinese bank account Regular small to mid-sized payments Per-transfer limits, the provider's rate and fee, and whether your bank accepts the route for import documentation
Informal channels and payment agents A third party pays the supplier for you Not recommended You may lack the paperwork your bank and customs expect, and the money is hard to trace if something goes wrong

‍

What Nigerian importers need to know

In Nigeria, an importer must complete Form M for goods entering the country. GTBank’s guide to Form M calls it a mandatory statutory document for all importers who are registered with an authorised dealer (a bank) when the order is placed, whether or not the transaction requires foreign exchange. It is submitted electronically on the CBN’s Trade Portal, which works with the Nigeria Customs Service. It is valid for 180 days for general merchandise and 365 days for plant and machinery, and the bank can extend it.

The CBN’s foreign exchange manual, issued in May 2026, adds a second deadline. Coverage of it says importers must submit exchange control documents within 90 days of negotiating shipping documents with overseas correspondent banks, and that importers who do not can be barred from foreign exchange transactions, including Form M processing, for periods that lengthen with repeat offences. Keep every invoice, contract, and shipping document organised so you can produce them when needed.

Before you pay, ask your bank how it wants the Form M and supporting documents handled for your route, and whether payments made through a payment provider fit its documentation requirements. Rules change, so confirm the current position with your bank or the CBN, not from a blog.

Protect the payment itself

  • Pay only to an account in the supplier’s registered company name, as shown on the contract and invoice.
  • Confirm bank details by a second channel, such as a video call, before the first payment and whenever they change. A change of account details sent by email is a common fraud.
  • Size the deposit to what you can afford to lose on a first order, and tie the balance to the inspection result.
  • Get the invoice in writing, with the currency, amount, and bank details.

Comparing what you pay

Quotes are hard to compare because the cost is split between a fee and an exchange rate. To compare them, divide the total naira you pay by the amount the supplier receives, then compare the resulting rate with the mid-market rate for the same day. The gap, plus any fee, is the real cost of the transfer. Do the same for each route, and ask the supplier whether the price changes depending on whether you pay in dollars or yuan.

Paying with Grey

Grey recently launched payouts to China, giving Nigerian importers another option.

  • The supplier receives yuan in their own Chinese bank account with ICBC, Bank of China, China Construction Bank, or Agricultural Bank of China and does not need a Grey account.
  • Before you confirm, Grey shows the rate and the fee as two separate numbers, and the yuan amount your recipient receives does not change after you confirm.
  • The account name you enter must match the account name on the supplier’s invoice, so copy it from there.

Grey charges a flat fee of $2.80 per bank transfer, with a limit of 50 to 21,000 yuan per transfer. Transfers are typically completed within 24 hours on banking days, with a 10:00 GMT cut-off; transfers made after this time may take longer. A limit of 21,000 yuan per transfer means a large factory deposit may need to be split into several transfers or paid another way, so check the limit shown in the app for your route before relying on it.

To hold US dollars and convert them when you need to pay, see Grey's foreign accounts. For small-order samples on platforms that accept cards, a virtual card is another option, though payments on non-US websites may incur a cross-border fee. If you pay several suppliers, Grey also offers a business account for cross-border trade with bulk payouts and payment status tracking. Check whether it is available in your country first.

Grey is a financial technology company, not a bank, and works with CBN-licensed banking partners in Nigeria. Its US services are regulated by FinCEN and its Canadian services by FINTRAC.

Frequently asked questions

How do African businesses pay Chinese suppliers?

Most pay through international bank transfer in US dollars or yuan, often with a deposit before production and the balance before shipment. Other routes include platform payments with escrow, letters of credit, and yuan payouts through payment providers. The right choice depends on the order size, the supplier, and your bank’s requirements.

Do they need a Form M to import from China into Nigeria?

Yes. GTBank’s guide describes Form M as a mandatory statutory document for all importers, which must be registered with a bank when the order is placed, whether or not the transaction requires foreign exchange. Confirm the current process with your bank.

Is it better to pay a Chinese supplier in dollars or yuan?

Neither is better by default. Ask the supplier for the price in both currencies, then compare the total you pay in your local currency, including fees and the exchange rate, against the mid-market rate on the day.

How can I check that a Chinese supplier is real?

Ask for the business licence and search its Unified Social Credit Code on China’s National Enterprise Credit Information Publicity System. Make sure the name on the licence, contract, invoice, and bank account match; order samples first; and join a video call before you pay a deposit.

Can I pay a supplier in China with Grey from Nigeria?

Grey offers payouts to Chinese bank accounts, delivered in yuan, from a naira top-up or a USD balance. The recipient does not need a Grey account. Check the fee, rate, and limit shown in the app before you confirm, as per-transfer limits apply.

Does China’s zero-tariff policy make imports from China cheaper?

No. The policy, in force from 1 May 2026, covers goods entering China from 53 African countries. It helps African exporters without changing what importers pay for Chinese goods.

How much deposit should I pay a new supplier?

Terms are negotiable, and a deposit before production, with the balance due before shipment, is a common pattern. For a first order, pay only what you can afford to lose, use platform protection where available, and tie the balance to an inspection result. This is general guidance, not financial advice.

Paying a supplier in China? See the rate and fee before you send.

Fees and rates: Grey's CNY payout post lists a flat fee of $2.80 per bank transfer and a limit of 21,000 yuan per transfer. Currency conversion is listed at 1% (capped at $6) on USD, GBP, and EUR transfers, so check the fee shown in the app for your route. A virtual card costs $5 to create once, with no monthly fee, and payments on non-US websites may incur a cross-border fee of 2% plus $0.50. Exchange rates vary with a margin over the mid-market rate, and delivery times depend on the bank, the route, and cut-off times.

How to verify a company EIN number: Free lookup methods

•

•

2 min read

An Employer Identification Number (EIN) is a nine-digit number the IRS assigns to businesses for tax reporting and identification. If you work with a new supplier, verify a company’s tax details, or prepare business documents, you may need to confirm that its EIN is valid.

However, finding a company’s EIN is not always straightforward. The IRS does not provide a public database where anyone can search for any business’s EIN. Your options depend on the type of company and your reason for checking its details.

Fortunately, there are several free methods you can use. You can request a signed Form W-9 directly from the business, search SEC EDGAR filings for publicly traded companies, or use the IRS Tax Exempt Organization Search to find eligible nonprofits. If you file information returns, the IRS TIN Matching service may also help you verify taxpayer identification details.

This guide explains how to complete an employer identification number lookup using these methods, what information you can access, and when each option is appropriate.

Can you look up any company's EIN?

No, you can't look up every company's Employer Identification Number (EIN) through a single public database. The IRS does not provide a public search tool that reveals the EIN of every registered business. This restriction helps protect business tax information from unauthorised access and misuse.

However, some EINs are publicly available. For example, you can find tax identification details in certain public company filings on SEC EDGAR or search for eligible nonprofits through the IRS Tax Exempt Organization Search.

Who can verify a company's EIN depends on the situation. Business owners can confirm their EIN through IRS notices and tax records. Banks, employers, and other authorised organisations may verify taxpayer identification details when permitted and necessary for their responsibilities. Businesses can also request a completed Form W-9 from vendors or contractors to confirm the information provided for tax reporting.

If you need to verify an EIN, start by asking the company directly or checking the relevant public records. The appropriate method depends on the company's status and your reason for verification.

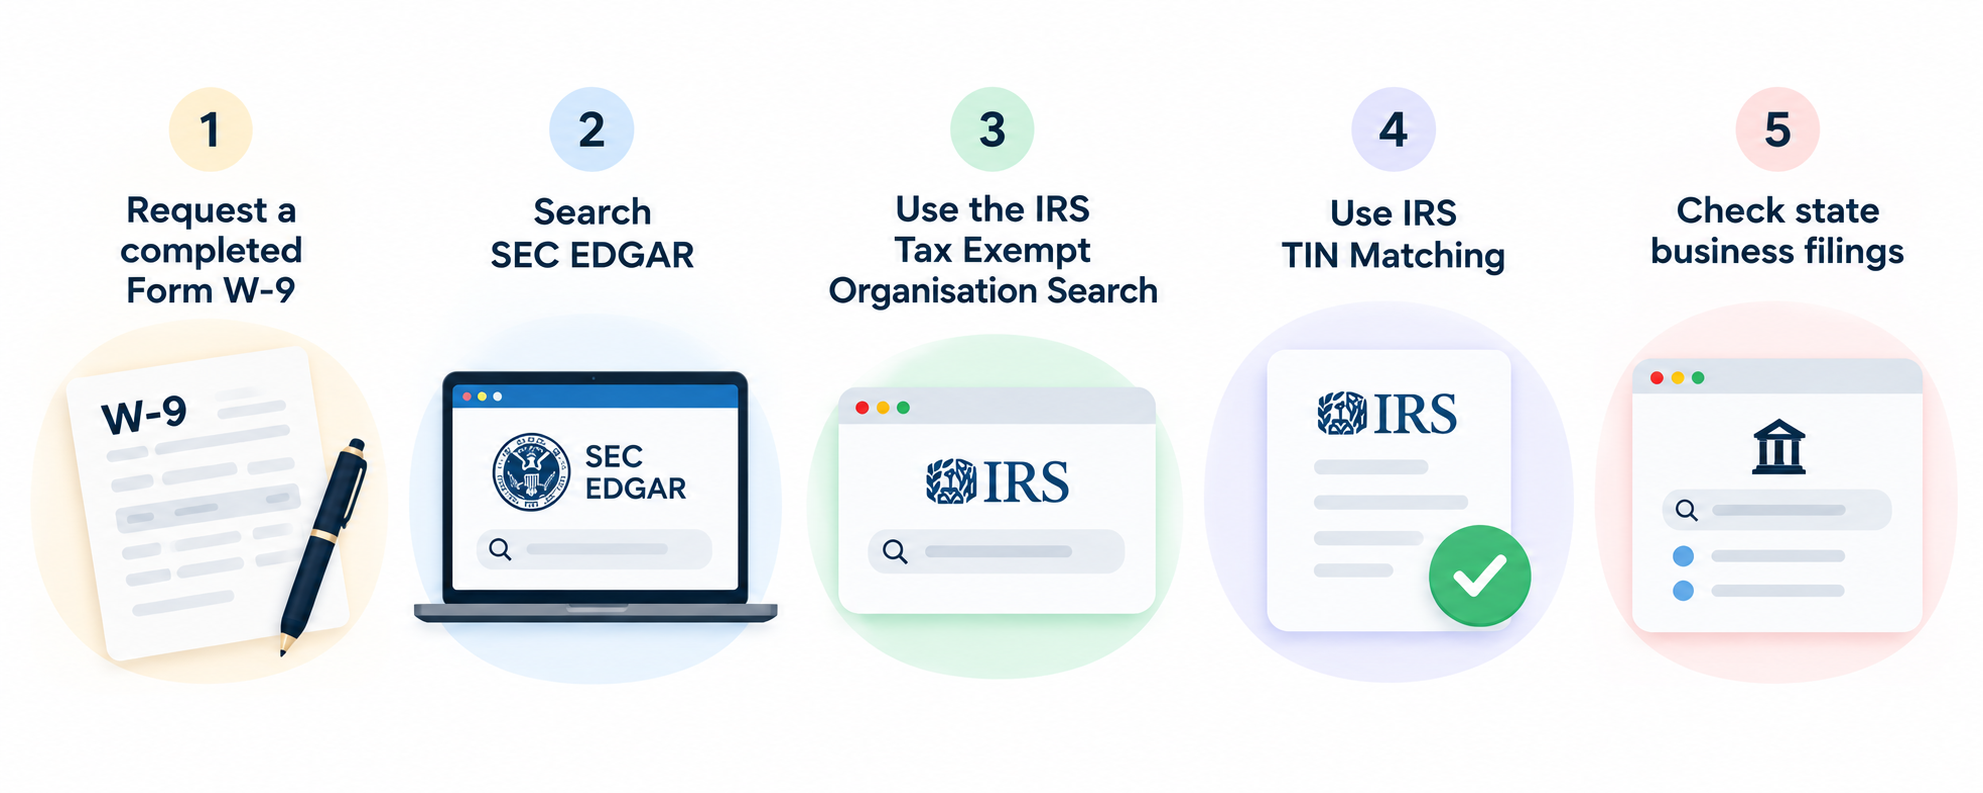
Five free ways to verify a company EIN

Five free ways to verify a company EIN.

1. Request a completed Form W-9

Ask the company to provide a signed Form W-9 containing its legal business name and taxpayer identification number. This is one of the simplest ways to obtain an EIN for vendor payments and tax reporting. Compare the details with your business records before proceeding.

2. Search SEC EDGAR

Publicly traded companies may disclose their EINs in regulatory filings. Visit SEC EDGAR and search for the company's name. Review relevant filings, such as annual reports, for available tax identification details. Not every filing includes an EIN.

3. Use the IRS Tax Exempt Organisation Search

If the company is a nonprofit, use the IRS Tax Exempt Organisation Search to find eligible organisations and review their publicly available tax records. This tool is not designed to look up every for-profit business.

4. Use IRS TIN Matching

Businesses authorised to use IRS TIN Matching can check taxpayer identification information against IRS records for eligible payees when filing information returns. This service is restricted to qualifying payers and cannot be used for unrestricted public searches.

5. Check state business filings

Visit the relevant state's official business registry to search for the company's registration details. Some filings may include federal tax identification information, but many do not. Start with the state's official government website, as access and available records vary by state.

Also read: How to complete a W-8BEN form as a non-US resident

How to find your own EIN

If you have misplaced your Employer Identification Number (EIN), you do not need to apply for a new one immediately. There are several ways to recover your existing number, depending on the records you have and whether you have previously used it for business activities.

1. Check your CP 575 confirmation letter. When the IRS assigns your EIN, it sends a confirmation notice called CP 575. Check your business files, emails, or saved documents for this letter, which contains your EIN.

2. Review previous tax returns. Look at your federal business tax returns and other tax documents. Your EIN is typically listed near the top of the relevant forms.

3. Contact your bank. If you used your EIN when opening a business account, your bank may have it on file. Contact your bank and ask how to retrieve your business tax identification details. If you are still setting up your finances, learn how to open a business bank account to understand the documents you may need.

4. Call the IRS. Contact the IRS Business and Specialty Tax Line at 800-829-4933, Monday through Friday, 7 a.m. to 7 p.m. local time. After verifying your identity and authorisation, an IRS representative can help you recover your EIN.

Paying verified vendors and contractors abroad

Paying an overseas contractor involves more than sending money. You also need the right tax documents and a reliable way to deliver their payment. For foreign individuals working outside the US, request Form W-8BEN when applicable to document their foreign status for US tax purposes. Foreign entities may need Form W-8BEN-E instead.

Once you have verified the contractor's details and confirmed the appropriate tax documentation, you can arrange payment. For example, if your LLC hires a developer in the Philippines, you can use Grey to send money from the US to the Philippines and pay them through a supported transfer method.

If you also hire US-based independent contractors, understanding what a 1099 employee is can help you distinguish contractors from employees and understand your reporting responsibilities. The term “1099 employee” is informal; independent contractors are generally not classified as employees for tax reporting.

For businesses managing multiple international payments, you can open a Grey Business account to pay vendors and contractors across borders.

Frequently asked questions about a company EIN number

1. Is there a free EIN lookup?

Yes, you can find some company EINs for free through public records. Try SEC EDGAR for publicly traded companies or the IRS Tax Exempt Organisation Search for eligible nonprofits. However, there is no single public IRS database that lists every company's EIN.

2. How do I verify an EIN with the IRS?

If you are an eligible payer filing information returns, you can use the IRS TIN Matching service to check taxpayer identification details. Business owners who have lost their EIN can contact the IRS Business and Specialty Tax Line for assistance after verifying their identity.

3. Can I find a company's EIN online?

Sometimes. Public company filings, nonprofit tax records, and certain business documents may disclose an EIN. Search official sources such as SEC EDGAR or the IRS Tax Exempt Organisation Search. If the number is not publicly available, ask the company directly for a completed Form W-9.

4. How do I find my own EIN?

Check your IRS CP 575 confirmation letter, previous business tax returns, or bank records. If you cannot locate your number, contact the IRS Business and Specialty Tax Line at 800-829-4933. After verifying your identity and authorisation, an IRS representative can help you recover it.

5. Is an EIN public information?

An EIN is not universally public information. Some businesses disclose it in public filings, while other companies' EINs may not be readily available. Although you can access certain tax identification details through official records, the IRS does not provide unrestricted public access to every business's EIN.

6. Is an FEIN the same as an EIN?

Yes, an FEIN (Federal Employer Identification Number) generally refers to the same nine-digit federal tax identification number as an EIN. Businesses use this number for tax reporting, banking, hiring employees, and other official purposes. The term FEIN simply emphasises that the identification number is federal rather than state-issued.

11 best business bank accounts to have in the US

•

•

2 min read

Choosing the right business account in the US can make a real difference in how you manage your company’s money, from receiving customer payments to paying suppliers and tracking everyday expenses. However, with so many banks and financial platforms offering different account types, fees and features, knowing which one fits your business can be difficult.

The best business bank accounts pair low or waivable monthly fees with strong online banking, cards and integrations. The right one depends on your size, transaction volume and whether you handle international payments. Compare fees, minimums and features side by side before opening one.

For example, a freelancer receiving occasional payments may prioritise low fees and simple digital banking, while a growing company may need higher transaction limits, cash deposit options and tools for managing payroll. If you work with international clients or suppliers, access to cross-border payments and multiple currencies may also influence your decision.

This guide compares 11 business bank accounts available in the US, highlighting their fees, minimum balance requirements, key features and suitability to help you choose an account that works for your business.

Also read: Best business bank accounts for an LLC

How to choose a business bank account

Choosing a business bank account starts with understanding how your business earns, spends and manages money. The right account should support your daily operations without adding unnecessary costs or making payments difficult to track.

Fees and charges: Compare monthly maintenance fees, transaction limits, cash deposit charges, wire transfer costs and ATM fees. An account advertised as free may still charge for certain services.

Minimum balance requirements: Check the opening deposit and ongoing balance requirements. If your cash flow fluctuates, choose an account with no minimum balance or an achievable fee waiver.

Banking tools: Look for reliable online banking, mobile cheque deposits, debit cards, accounting software integrations and payment processing. Growing businesses may also benefit from payroll support and cash management tools.

Access and eligibility: Confirm that your business structure qualifies, whether you can apply online and which documents you need. Some providers require a US address, while others have additional residency restrictions.

If you receive international payments, compare foreign exchange rates, supported currencies and transfer fees before deciding. Your account should fit your current needs while leaving room for your business to grow.

11 best business bank accounts in the US

The following comparison ranks 11 business banking options by monthly fees, key features, limitations and suitability, helping you identify the right fit for your company's size, cash flow and banking needs.

Rank Bank / Platform Monthly Fees and waivers Core pros Core cons Best for
1 Chase Business Complete Banking $15; waivable with qualifying balances or activity Card processing, extensive branch network, credit card options Wire fees, cash deposit limits, no interest Storefronts needing branch access
2 Mercury $0 standard tier; paid plans available Digital tools, wire transfers, API integrations No physical cash handling, premium features cost extra Tech startups and online businesses
3 Bluevine $0 Standard plan; paid tiers available Interest potential, sub-accounts, accounting integrations Conditions for earning interest, wire fees Online businesses prioritising interest
4 U.S. Bank Business Essentials $0 monthly fee Branch access, no ongoing maintenance fee Transaction limits, credit approval requirements Small retailers
5 Bank of America Business Advantage $16; waivable with qualifying balance Rewards programme, national network, credit integration Balance requirements, potential extra fees Established businesses
6 American Express Business Checking $0 monthly fee Interest potential, Membership Rewards, support No cash deposits, limited branch access Existing Amex customers
7 Relay $0 basic plan; Pro costs extra Multiple sub-accounts, team access, bill management Some tools require paid plan, ATM fees Growing teams and agencies
8 Novo $0 monthly fee Invoicing tools, ATM fee refunds, online dashboard No built-in interest, limited user controls Freelancers and sole proprietors
9 Wells Fargo Navigate Business Checking Tiered fees; waivers may apply Branch network, cash handling, lending services Fees and service costs vary Cash-heavy businesses
10 Found $0 base tier; paid Plus plan Tax tracking, receipt capture, invoicing Limited international features, fewer team tools Sole proprietors and independent contractors
11 Rho $0 platform fee; service eligibility applies Corporate cards, expense controls, accounts payable US business eligibility restrictions, credit criteria Established companies managing expenses

‍

Traditional banks vs. online providers for your LLC

When choosing a business bank account for your LLC, consider how you receive payments, manage expenses, and access your money. Traditional banks and online providers offer different benefits, so the right choice depends on how your business operates.

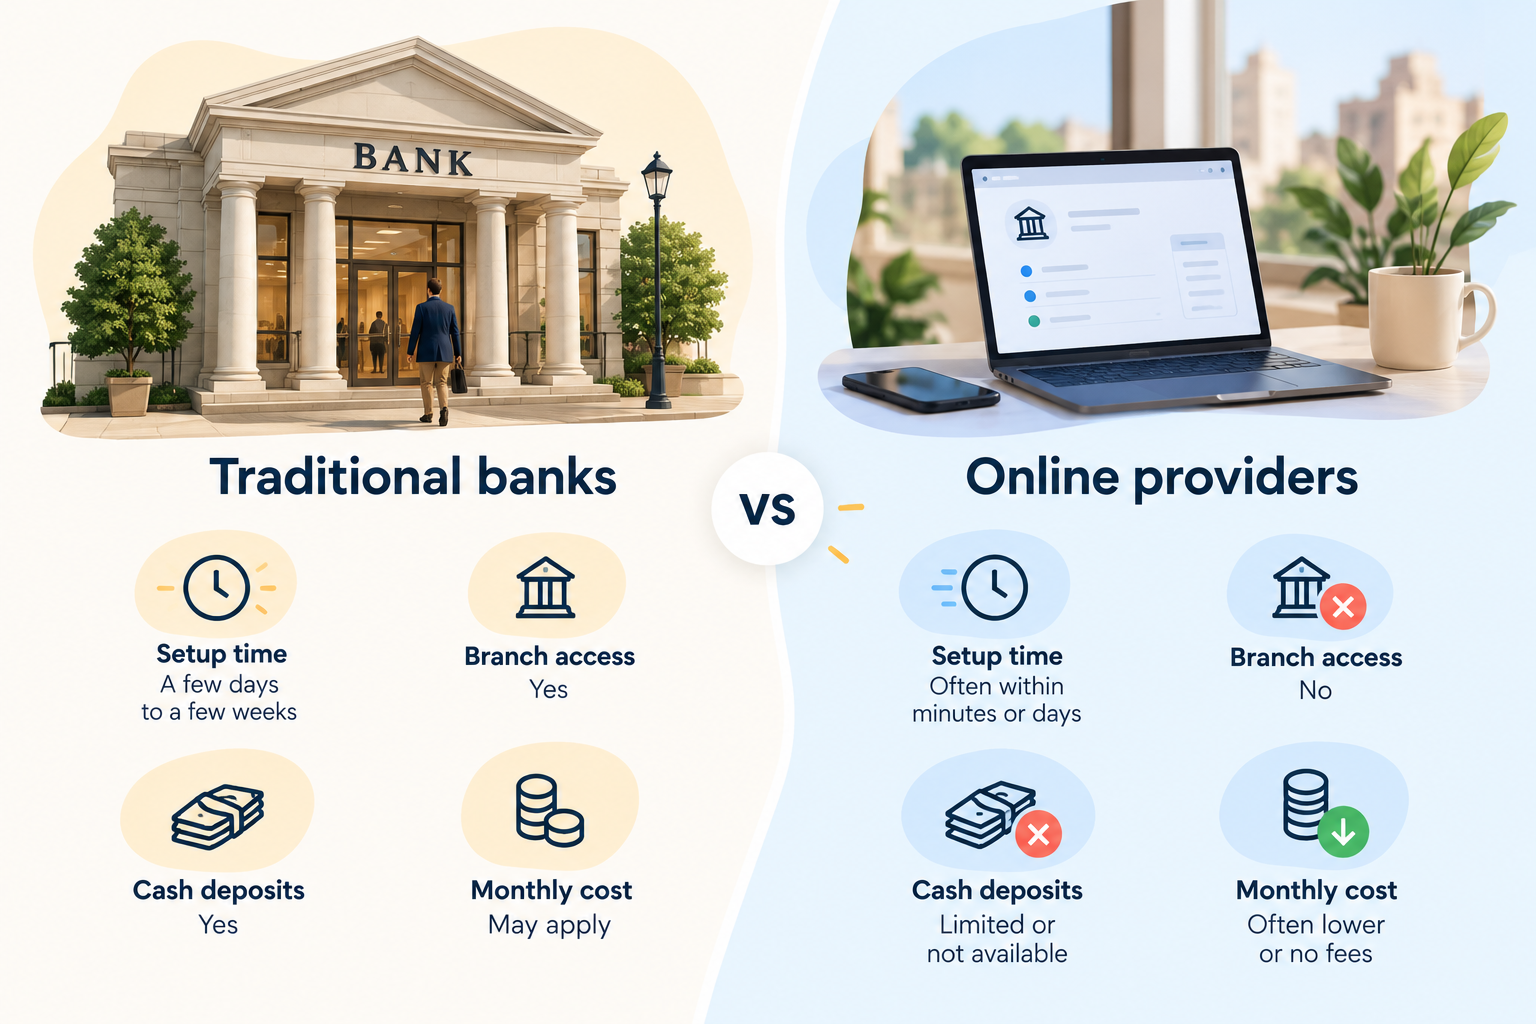
Traditional US banks compared with online business account providers on setup time, branch access and fees.

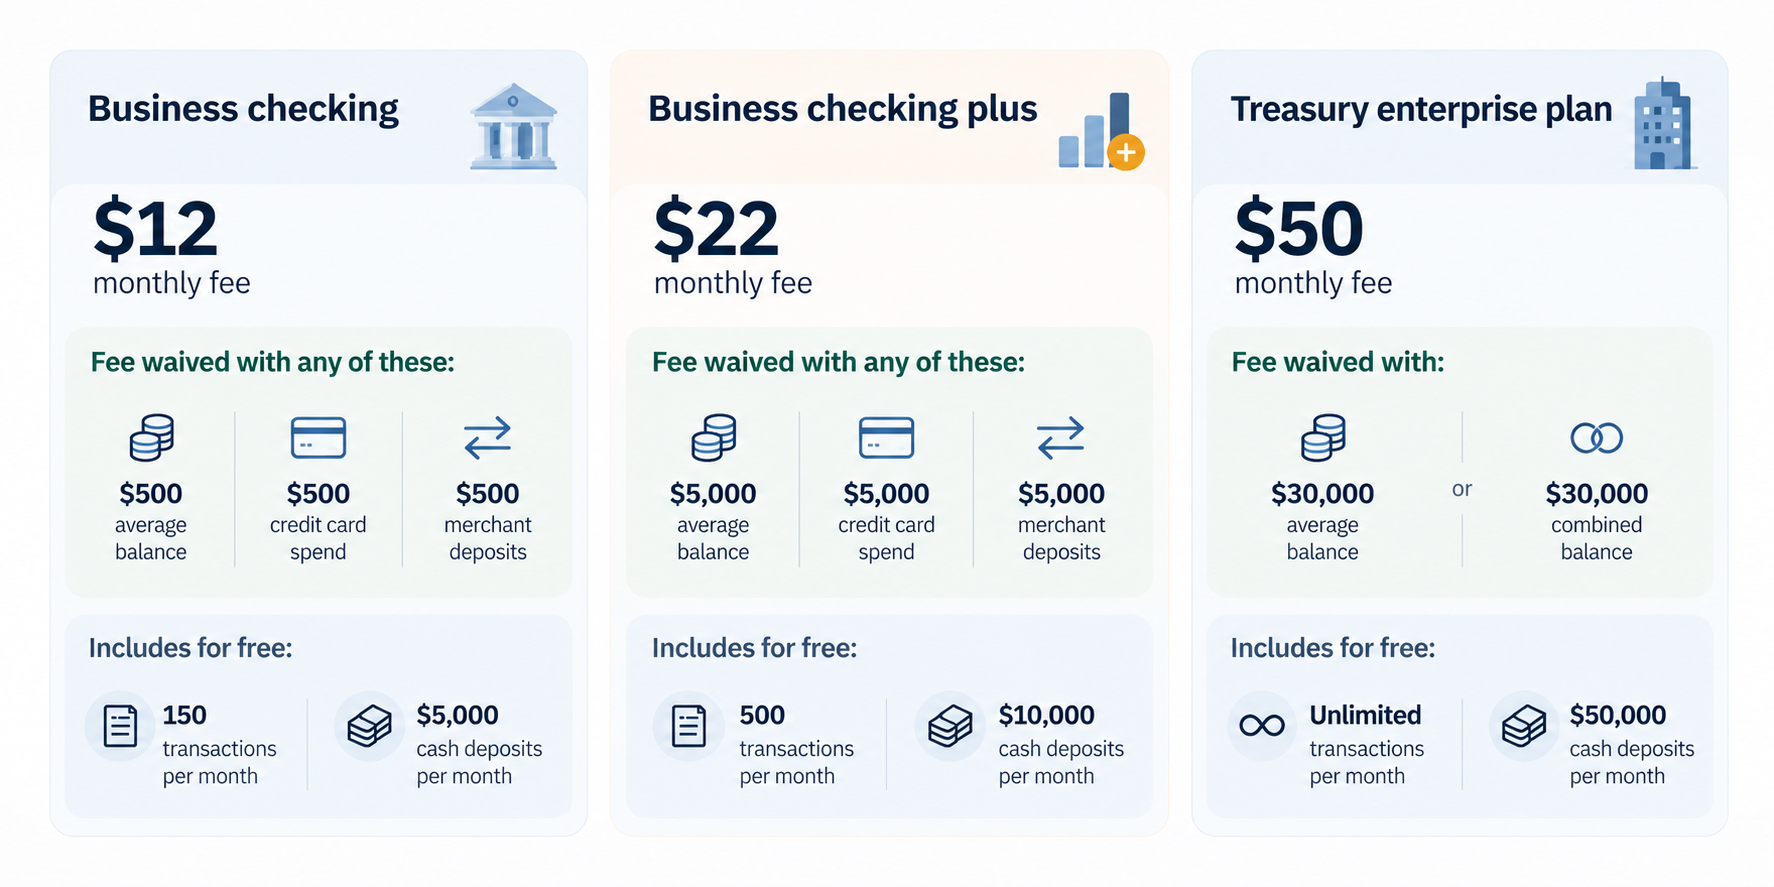
Traditional banks such as Chase, Bank of America, and U.S. Bank give you access to physical branches. You can deposit cash, speak with bank staff, and look into business loans or other financial services. However, some accounts charge monthly maintenance fees unless you meet specific requirements. For one example, see the PNC business account fees and features.

Online providers such as Bluevine, Mercury, Relay, and Grey let you manage your finances digitally. While Bluevine, Mercury, and Relay offer business banking tools, Grey supports cross-border payments, making it useful for businesses that send or receive money internationally. Online providers may offer lower fees, faster account setup, and convenient payment management. However, cash deposits and in-person support may be limited.

Before you decide, compare monthly fees, transaction limits, deposit options, and eligibility requirements. If you need branch access, a traditional bank may suit you better. If you value convenience and digital payments, an online provider may be the better fit.

Also read: Can non-residents open a US bank account online in 2026?

Adding international payments

Opening an LLC in the US can help you establish your business, but what happens when your customers, suppliers, or team are in different countries? You need a simple way to move money across borders without disrupting your day-to-day operations.

That is where Grey comes in. With Grey, you can send and receive money from the US to support international business transactions, whether you are collecting payments from clients or paying partners overseas. Instead of relying on your traditional business bank account for every cross-border transaction, you can add a dedicated payment solution to your setup.

To get started, open a Grey Business account and see which options suit your business.

Frequently asked questions about the best business bank accounts to have in the US

What is the best business bank account for an LLC?

The best business bank account depends on your LLC’s needs. Chase and Bank of America offer branch access, while Bluevine, Mercury, and Relay provide digital banking tools. Compare fees, transaction limits, payment options, and eligibility requirements to find an account that suits your business.

Which business bank account has the lowest fees?

Online providers such as Bluevine, Mercury, and Relay offer business accounts with no monthly maintenance fees on certain plans. However, other charges may apply for specific transactions or services. Compare each provider’s fee schedule and account requirements before making your decision.

Can I open a business bank account online?

Yes, many banks and online providers let you apply for a business bank account online. You will typically need your LLC formation documents, identification, and business details. Approval times and requirements vary by provider, so check the application process before applying.

Do I need an EIN to open a business bank account?

Many banks require an Employer Identification Number (EIN) to open an LLC business account. Some single-member LLCs may qualify to use other tax identification details, depending on the bank’s policies. Check the provider’s requirements and obtain an EIN from the IRS if needed.

What about international payments for my LLC?

If your LLC works with overseas clients or suppliers, look for accounts that support international transfers and multiple currencies. Grey can complement your business banking setup by helping you send and receive money from the US. Compare transfer fees, exchange rates, supported currencies, and eligibility before choosing a provider.

Are online business accounts safe?

Online business accounts can offer strong security features, including encryption, multi-factor authentication, and transaction monitoring. However, protections vary by provider. Check whether deposits are held at an FDIC-insured bank, understand applicable coverage limits, and review the provider’s security policies before opening an account.

PNC business account: Fees, features and how to open

•

•

2 min read

Choosing the right business bank account can make it easier to manage daily expenses, receive customer payments and keep your business finances organised. However, monthly maintenance fees, transaction limits and minimum balance requirements can affect how much you pay for banking services. If you are considering a PNC Bank business account, understanding these costs and features can help you decide whether it suits your business needs.

PNC offers several business checking accounts designed for businesses with different transaction volumes and banking needs. Each account comes with its own fee structure, transaction allowances and requirements for waiving monthly maintenance fees. Depending on the account you choose, maintaining a qualifying balance may help you avoid these charges.

Opening an account is also relatively straightforward, with options to apply online or visit a branch. You will generally need your employer identification number (EIN), business formation documents and valid identification. This guide covers PNC business account fees, key features, eligibility requirements and how to open an account, helping you understand what to expect before applying.

Also read: Best business bank accounts for an LLC

PNC Business account options: which checking tier fits your business?

PNC offers several business checking options designed for different transaction volumes, cash handling needs and business sizes. Choosing the right tier depends on your monthly activity, available balance and financial management needs.

Business Checking: Best for freelancers, sole proprietors and micro-businesses with fewer transactions. Its $500 balance waiver threshold can help eligible account holders avoid the monthly maintenance fee.

Business Checking Plus: Suits local retailers, storefronts and growing businesses that handle more payments. It accommodates up to 500 monthly items and $10,000 in cash deposits before additional charges may apply.

Treasury Enterprise: Designed for businesses managing multiple entities or accounts. It allows up to four linked accounts to qualify toward a combined $30,000 balance requirement.

Analysis: Best suited to large enterprises with substantial cash flows. Earnings Credits can help offset eligible account service charges, making it worth considering for businesses with complex treasury management needs.

PNC business checking line-up (2026)

Account tier Monthly fee /
waiver minimum
Free transactions Free cash deposits Ideal for
Business Checking $12 / $500 balance 150/month $5,000/month Freelancers, side hustles and startups
Business Checking Plus $22 / $5,000 balance 500/month $10,000/month Growing businesses and local retailers
Treasury Enterprise Plan $50 / $30,000 combined balance Unlimited across linked accounts $50,000/month Established mid-sized businesses
Analysis Business Checking Variable / Earnings Credit Custom Custom Large enterprises with complex cash flows

‍

PNC business account fees and how to avoid them

 Graphic showing how a monthly business checking fee can be waived by meeting a balance requirement.

1. Business checking: $12 monthly fee

How to avoid the fee:

  • Maintain a $500 average monthly balance.
  • Spend $500 on a linked PNC Business Credit Card.
  • Process $500 in deposits through a linked PNC merchant account.

How to avoid extra charges:

  • Keep monthly transactions within the 150 free-item limit.
  • Keep monthly cash deposits within the $5,000 free allowance.

2. Business checking plus: $22 monthly fee

How to avoid the fee:

  • Maintain a $5,000 average monthly balance.
  • Maintain a combined $20,000 balance across eligible linked checking and money market accounts.
  • Spend $5,000 on a linked PNC Business Credit Card.
  • Process $5,000 in deposits through a linked PNC merchant account.

How to avoid extra charges:

  • Keep monthly transactions within the 500 free-item limit.
  • Keep monthly cash deposits within the $10,000 free allowance.

3. Treasury enterprise plan: $50 monthly fee

How to avoid the fee:

  • Maintain a $30,000 average monthly balance.
  • Alternatively, maintain a combined $30,000 balance across eligible linked corporate accounts.

How to avoid extra charges:

  • Enjoy unlimited transactions across linked accounts.
  • Keep monthly cash deposits within the $50,000 free allowance.

PNC Business account features and tools

PNC provides digital banking, business debit cards, payment processing and cash management tools to help businesses handle everyday transactions, monitor cash flow and manage finances more efficiently.

Digital tools: PNC Business Online Banking and mobile deposit capabilities help business owners check balances, review transactions, deposit eligible checks and manage accounts without visiting a branch.

Cards: Eligible account holders can access PNC Bank Visa Business Debit cards for convenient business purchases. The Purchase Payback® programme may offer cash-back rewards on qualifying purchases from participating merchants, subject to applicable terms.

Integrations: Businesses with more complex financial needs can use PINACLE®, PNC's treasury management platform, to access cash management services and tools that support cash-flow forecasting, payment management and account visibility.

Payment processing: PNC Merchant Services helps businesses accept customer payments and manage transactions. When used alongside available cash-flow tracking tools, these services can make it easier to monitor incoming payments, reconcile transactions and manage accounts receivable.

Together, these features give businesses tools to manage routine banking, track incoming funds and oversee payments. Fees and thresholds in this guide come from PNC's business deposit fee schedule effective 25 October 2026. They can change, so review PNC's current terms before enrolling.

Also read: How to open a business bank account

Handling international payments

While a PNC business account can help you manage everyday banking in the US, businesses working with international clients, suppliers or remote teams may need additional options for cross-border payments. This is where Grey can complement your banking setup.

With a Grey Business account, eligible businesses can send and receive money from the US, making it easier to manage international payments when working with American clients, paying overseas suppliers or serving customers across borders.

Grey adds a multi-currency layer to your financial operations, helping you handle international transactions alongside your regular business banking. Before choosing a service, review supported currencies, transfer fees, exchange rates and account eligibility to understand the costs involved.

Frequently asked questions

1. What business accounts does PNC offer?

PNC offers several business checking options, including Business Checking, Business Checking Plus, Treasury Enterprise Plan and Analysis Business Checking. Each serves different needs, from freelancers and small businesses to larger companies managing substantial cash flows. The right account depends on your transaction volume, cash deposits and treasury management requirements.

2. What are the fees?

Monthly maintenance fees vary by account tier. Business Checking costs $12, Business Checking Plus costs $22, and Treasury Enterprise Plan costs $50, based on the fee schedule outlined above. Analysis Business Checking has variable fees. Eligible accounts may qualify for waivers by meeting balance or other requirements. Transaction and cash deposit limits may also trigger additional charges.

3. Can I open one online?

Yes, PNC allows eligible customers to apply for certain business checking accounts online. You can also visit a branch to complete the application. Availability may depend on your business structure, location and eligibility. Before applying, review the account requirements and prepare the necessary identification and business documents to help avoid delays.

4. What documents do I need?

PNC generally requires your business Tax Identification Number (TIN), or Social Security number for eligible sole proprietors, business registration documents and proof of authority to operate the business. You will also need identification. Online applicants need a valid email address. Requirements vary by business structure.

5. Is there a minimum balance?

PNC Business Checking has a $100 minimum opening deposit. This differs from the $500 average monthly balance that can waive its $12 maintenance fee. Other account tiers have different waiver requirements. You may avoid monthly fees through qualifying linked credit card purchases or merchant deposits, depending on the account.

6. How do I handle overseas payments?

You can use PNC international wire transfers to send money overseas or receive payments from abroad, although transfer fees and currency conversion costs may apply. For additional cross-border flexibility, eligible businesses can use a Grey Business account to send and receive money from the US. Compare fees and supported currencies before choosing a service.

Arrow (up)

Back to top