<script type="application/ld+json" data-schema-version="grey-blog-v4">
[{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#article","headline":"How to Pay for ChatGPT Plus in Nigeria","description":"ChatGPT Plus costs $20/month and needs a dollar card. Nigerian naira cards are not accepted. Here is how to subscribe using a Grey virtual dollar card.","inLanguage":"en","url":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria","mainEntityOfPage":{"@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#webpage"},"datePublished":"2026-06-29T06:59:57.539Z","dateModified":"2026-06-30T09:05:00+01:00","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a4217063e8ea6dcc92e1a4a_image%20(5)%20(1)%20(1).png","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a4217063e8ea6dcc92e1a4a_image%20(5)%20(1)%20(1).png","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#webpage","url":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria","name":"How to Pay for ChatGPT Plus in Nigeria 2026 | Grey","description":"ChatGPT Plus costs $20/month and needs a dollar card. Nigerian naira cards are not accepted. Here is how to subscribe using a Grey virtual dollar card.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to Pay for ChatGPT Plus in Nigeria","item":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#faq","mainEntity":[{"@type":"Question","name":"Does ChatGPT Plus renew automatically?","acceptedAnswer":{"@type":"Answer","text":"Yes. OpenAI charges your card $20 on the same date each month. Make sure your Grey USD balance has at least $20 before each renewal date to avoid the payment failing and your account reverting to free."}},{"@type":"Question","name":"Is there a transaction fee when ChatGPT charges my Grey card?","acceptedAnswer":{"@type":"Answer","text":"No fee on the card transaction itself. ChatGPT charges in USD, and your Grey card operates in USD, so no currency conversion happens at the point of payment."}},{"@type":"Question","name":"What if my card balance is too low at renewal?","acceptedAnswer":{"@type":"Answer","text":"OpenAI will attempt the charge. If it fails, your account is downgraded to the free plan. Top up your Grey USD balance and re-subscribe. OpenAI does not automatically retry failed payments, so you need to go back into the subscription flow to reactivate."}},{"@type":"Question","name":"Can I use one Grey card for multiple subscriptions?","acceptedAnswer":{"@type":"Answer","text":"Yes. Your Grey virtual card is a standard Visa card. Use it for ChatGPT Plus, Adobe, Notion, Canva, AWS, Shopify, and any other USD-billed service simultaneously. There is no limit on the number of services you can subscribe to from one card."}},{"@type":"Question","name":"Does the 2% cross-border card fee apply to ChatGPT?","acceptedAnswer":{"@type":"Answer","text":"No. The 2% plus $0.50 cross-border card fee applies only when a merchant processes a transaction in a currency other than USD. ChatGPT Plus is billed in USD, so you pay no cross-border fee on this subscription. The same applies to any other service that charges in USD."}},{"@type":"Question","name":"Can I get a refund if I cancel ChatGPT Plus?","acceptedAnswer":{"@type":"Answer","text":"OpenAI does not automatically refund unused time if you cancel mid-cycle. If you believe you were incorrectly charged, you can submit a refund request through OpenAI’s support pages. Refunds typically take five to ten business days to process after approval.’"}},{"@type":"Question","name":"Is there a ChatGPT Go plan below Plus?","acceptedAnswer":{"@type":"Answer","text":"Yes. OpenAI introduced ChatGPT Go at $7 per month (GBP equivalent on the UK pricing page). Go gives you more access than Free, including more messages and uploads, longer memory, and the ability to create and share custom GPTs. It does not include GPT-5.5 Thinking, deep research tools, or tasks. Go is a middle-ground option if $20 per month is too much. You can pay for it with your Grey card using the same process described in this guide."}},{"@type":"Question","name":"Is ChatGPT data private on Plus?","acceptedAnswer":{"@type":"Answer","text":"OpenAI may use conversations to improve model performance and safety on all individual plans including Plus. You can opt out of having your data used for training at any time through Settings in your ChatGPT account. Business and Enterprise plans do not use data for training by default."}}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#terms","name":"How to Pay for ChatGPT Plus in Nigeria glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"ChatGPT Plus","description":"ChatGPT is the AI assistant developed by OpenAI and launched in November 2022. The free version gives you access to a limited version of OpenAI’s models with lower message caps and slower responses during busy periods.","inDefinedTermSet":{"@id":"https://grey.co/blog/how-to-pay-for-chatgpt-plus-in-nigeria#terms"}}]}]
</script>
Grey Guides
•
June 29, 2026
•
8 min read
How to Pay for ChatGPT Plus in Nigeria
Olayoyin Olorunmota
TABLE OF CONTENT
SHARE THIS POST
ChatGPT Plus costs $20 a month. The first problem for most Nigerians is that OpenAI does not accept naira-denominated debit cards, which means your standard Nigerian bank card will be declined at checkout every time.
The solution is a virtual dollar card. With a Grey account, you can create one in minutes and complete the ChatGPT Plus subscription on the same day. This guide covers the full process: what you are paying for, how much it costs in naira, how to set up your Grey card, and exactly how to complete the subscription on desktop and mobile.
What is ChatGPT Plus?
ChatGPT is the AI assistant developed by OpenAI and launched in November 2022. The free version gives you access to a limited version of OpenAI’s models with lower message caps and slower responses during busy periods.
ChatGPT Plus is OpenAI’s paid subscription tier at $20 per month. It gives you significantly more capability across every dimension of the product.
ChatGPT Plus vs Free: what you actually get
Feature
Free
Plus
GPT-5.5 Instant (standard model)
Limited access
Expanded access
GPT-5.5 Thinking (reasoning model)
Not available
Expanded access
Message limits
Limited
Expanded
Response speed
Limited by demand
Fast
Voice conversations
Yes (basic)
Expanded
Voice with video
No
Yes
Image generation
Limited
Yes (including with Thinking)
File uploads and data analysis
Limited
Yes
Deep research and agent mode
Limited
Expanded
Custom GPT creation
No
Yes
Tasks and scheduled actions
No
Yes
Apps connecting to internal tools
No
Yes
Early access to new features
No
Yes
Context window (Instant model)
27K tokens (about 12 pages)
54K tokens (about 40 pages)
Price
Free
$20 per month
Is there a higher-tier plan?
Yes. Above Plus, OpenAI offers ChatGPT Pro at $100 per month (billed in GBP on the UK pricing page; USD equivalent applies for Nigerian users). Pro gives you five to twenty times more usage than Plus, access to GPT-5.5 Pro (the most powerful version), unlimited image generation, maximum deep research and agent mode, and a research preview of new features before they reach Plus.
For most Nigerian users, Plus at $20 per month covers everything. Pro is designed for power users who hit Plus usage limits regularly.
OpenAI does not currently offer annual billing for ChatGPT Plus or Pro. All plans are billed monthly.
How much does ChatGPT Plus cost in naira?
OpenAI charges $20 per month, billed in USD. The naira equivalent shifts with the exchange rate. At typical market rates, $20 works out to roughly N25,000 to N30,000 per month. Verify the current rate in the Grey app before subscribing, since this changes daily.
Because the charge is in USD and your Grey card operates in USD, there is no currency conversion on the ChatGPT transaction itself. You only pay the Grey FX swap fee once, when you convert naira to USD to fund your account.
Why do Nigerian naira cards not work for ChatGPT subscription?
OpenAI processes all payments in USD through Stripe, its payments processor. Stripe requires a card with a valid USD billing relationship. Nigerian naira debit cards issued by local banks are naira-denominated and do not meet this requirement, so they are declined at the payment step regardless of your card balance.
This is not a Grey-specific issue. Any naira card, whether issued by GTBank, Access, Zenith, UBA, First Bank, or any other Nigerian bank, will be declined. The only cards that work are dollar-denominated Visa or Mastercard cards, either physical (from a domiciliary account) or virtual (such as Grey’s virtual dollar card).
OpenAI also does not accept PayPal on the web checkout, gift cards, or prepaid cards without a matching billing address. Apple Pay and Google Pay work on mobile apps only, and only if your Apple or Google account is linked to a valid dollar payment method.
What you need before you subscribe
A Grey account (download the Grey app from the App Store or Google Play and complete signup)
A Grey virtual dollar card
A ChatGPT account, which is free to create at chatgpt.com
Step 1: Create a Grey account
If you already have a Grey account, skip to Step 2.
Download the Grey app from the App Store (iOS) or Google Play (Android).
Open the app and tap Sign Up.
Enter your email address and create a password.
Complete identity verification. Grey requires a valid government-issued ID to comply with financial regulations.
Your account is active once verification is approved.
Step 2: Get a Grey virtual dollar card
If you already have a Grey virtual card, skip to Step 3.
Open the Grey app and tap the Cards section on the dashboard.
Select Create Virtual Card.
Review the card creation fee. A $5 one-time creation fee will be charged. You need a minimum of $5 USD in your account before creating the card.
Confirm, and your card is created immediately. Your card number, expiry date, and CVV appear in the Cards section of the app.
Your Grey virtual dollar card is a Visa card which pulls directly from your USD balance. It’s accepted anywhere Visa is supported internationally, including on ChatGPT and on every major USD-billed subscription platform.
Step 3: Fund your Grey USD balance
You need at least $20 in your USD balance to pay for ChatGPT Plus. The recommended method is to swap naira to USD inside the Grey app.
Open the Grey app and tap “Convert”.
Select NGN to USD and enter the amount. A 1% currency conversion fee (capped at $6) will apply.
Review the rate and confirm. Your USD balance updates immediately.
You can also fund your USD balance via ACH transfer from a US bank account if you have one. The ACH receiving fee is 0.5% (minimum $2, maximum $10). For most Nigerian users, the in-app naira-to-USD swap is the most straightforward route.
Click your profile icon in the bottom-left corner.
Select Upgrade Plan.
Choose the Plus plan at $20 per month.
On the payment screen, enter your Grey virtual card number, expiry date, and CVV. Use the name on your Grey account and any valid billing address.
Click Subscribe. Your subscription activates immediately, and $20 is charged to your Grey card balance.
On Android
Open the ChatGPT app and go to Settings.
Select Upgrade to Plus.
Payment is processed through Google Play. Add your Grey virtual card as a payment method on Google Play before proceeding if you have not already done so.
On iOS
Open the ChatGPT app and tap the menu at the top.
Select Get Plus.
Payment goes through Apple’s in-app purchase system. Add your Grey card to your Apple ID payment methods first. You can do this in iPhone Settings under your Apple ID, then Payment and Shipping.
Payment methods: what works and what does not
Method
Works?
Notes
Grey virtual dollar card (Visa)
Yes
Recommended. Works on web, Android, and iOS.
Physical dollar card (domiciliary)
Yes
Works, but requires sourcing USD separately through your bank.
Nigerian naira debit card
No
OpenAI does not accept naira-denominated cards on any platform.
PayPal
Not on web
Works on iOS or Android only if PayPal is linked to your Apple or Google account.
Gift cards
No
OpenAI does not accept gift cards for ChatGPT subscriptions.
Annual billing
No
OpenAI currently offers monthly billing only for Plus and Pro.
How to manage your ChatGPT subscription
To view your subscription details, invoices, or cancel your plan, log into chatgpt.com, click your profile icon, select Settings, then Account.
To cancel, go to Manage My Subscription and select Cancel Plan. Cancelling stops the next renewal charge. Your Plus access continues until the end of the billing period you have already paid for.
If you subscribed through the iOS app, manage and cancel through iPhone Settings, then your Apple ID, then Subscriptions. The same applies to Android subscriptions managed through Google Play.
What happens at renewal?
ChatGPT Plus renews automatically every month on the same date you first subscribed. OpenAI charges your Grey card for $20 on that date.
If your Grey USD balance is below $20 at renewal time, the charge will fail, and your account will be downgraded to the free plan. You will need to top up your balance and resubscribe. To avoid this, set a reminder to check your Grey balance a few days before each renewal date, or keep a small buffer in your USD balance above the $20 threshold.
OpenAI sends a receipt by email for each billing cycle. If you see an unexpected charge, you can request a refund through OpenAI’s support. Refunds are typically processed within five to ten business days after approval.
Troubleshooting common issues
Payment declined at checkout
Check that your Grey USD balance has at least $20 available.
Confirm that the card number, expiry date, and CVV are entered correctly from the Grey app.
Make sure the billing name matches the name on your Grey account.
If using a billing address, use a consistent format. Grey’s registered address works.
If the issue persists, contact Grey support through the app.
Subscribed but account still shows “free plan”
Log out of ChatGPT on all devices and log back in using the exact email address you used to subscribe.
If you subscribed through Apple and used Hide My Email, find the private relay address in your Apple ID settings and use that to sign in.
On iOS or Android, go to Settings and tap Restore Purchases to sync your subscription.
If none of these work, contact OpenAI support with your receipt or the last four digits of the card charged.
Grey card not accepted on Google Play or Apple
On Google Play: go to pay.google.com, add your Grey card as a new payment method, then return to the ChatGPT app to subscribe.
On Apple: go to iPhone Settings, tap your name, then Payment and Shipping, and add your Grey card. Once added, it will be available for in-app purchases.
Other USD subscriptions you can pay with your Grey card
Once your Grey virtual dollar card is set up, it works across every major USD-billed subscription platform. You do not need to create a new card for each service.
Service
What you can pay for
Adobe Creative Cloud
Photoshop, Illustrator, Premiere Pro, Acrobat, the full Creative Cloud suite
Notion AI
Notion Plus and AI add-on plans
Canva Pro
Canva Pro monthly and annual plans
Spotify Premium
Spotify individual and family plans billed in USD
Netflix
Netflix plans billed in USD
AWS
Amazon Web Services usage and reserved instance billing
Shopify
Shopify Basic, Grow, and Advanced plans
Figma
Figma Starter and Professional plans
GitHub Copilot
GitHub Copilot Individual and Business plans
Midjourney
Midjourney AI image generation plans
The smart way to manage dollar subscriptions from Nigeria
A Grey multi-currency account lets you hold a USD balance and spend it directly with a virtual dollar card across all of the above. One account, one card, no currency conversion at the point of payment on any USD-billed service. You convert naira to USD once, at Grey’s 1% rate, and spend from that balance across every subscription you run.
If you also send money internationally, Grey pays out to bank accounts and mobile money in Nigeria, India, Ghana, Kenya, the Philippines, and over 50 other destinations. You can manage everything from one app.
Open a Grey account, create your virtual dollar card, and have ChatGPT Plus running today at grey.co.
Frequently asked questions
Does ChatGPT Plus renew automatically?
Yes. OpenAI charges your card $20 on the same date each month. Make sure your Grey USD balance has at least $20 before each renewal date to avoid the payment failing and your account reverting to free.
Is there a transaction fee when ChatGPT charges my Grey card?
No fee on the card transaction itself. ChatGPT charges in USD, and your Grey card operates in USD, so no currency conversion happens at the point of payment.
What if my card balance is too low at renewal?
OpenAI will attempt the charge. If it fails, your account is downgraded to the free plan. Top up your Grey USD balance and re-subscribe. OpenAI does not automatically retry failed payments, so you need to go back into the subscription flow to reactivate.
Can I use one Grey card for multiple subscriptions?
Yes. Your Grey virtual card is a standard Visa card. Use it for ChatGPT Plus, Adobe, Notion, Canva, AWS, Shopify, and any other USD-billed service simultaneously. There is no limit on the number of services you can subscribe to from one card.
Does the 2% cross-border card fee apply to ChatGPT?
No. The 2% plus $0.50 cross-border card fee applies only when a merchant processes a transaction in a currency other than USD. ChatGPT Plus is billed in USD, so you pay no cross-border fee on this subscription. The same applies to any other service that charges in USD.
Can I get a refund if I cancel ChatGPT Plus?
OpenAI does not automatically refund unused time if you cancel mid-cycle. If you believe you were incorrectly charged, you can submit a refund request through OpenAI’s support pages. Refunds typically take five to ten business days to process after approval.’
Is there a ChatGPT Go plan below Plus?
Yes. OpenAI introduced ChatGPT Go at $7 per month (GBP equivalent on the UK pricing page). Go gives you more access than Free, including more messages and uploads, longer memory, and the ability to create and share custom GPTs. It does not include GPT-5.5 Thinking, deep research tools, or tasks. Go is a middle-ground option if $20 per month is too much. You can pay for it with your Grey card using the same process described in this guide.
Is ChatGPT data private on Plus?
OpenAI may use conversations to improve model performance and safety on all individual plans including Plus. You can opt out of having your data used for training at any time through Settings in your ChatGPT account. Business and Enterprise plans do not use data for training by default.
This article is for general information purposes only. Subscription pricing, plan features, and accepted payment methods are set by OpenAI and may change at any time. Always verify current pricing and terms at chatgpt.com before subscribing. Grey’s fees are accurate as of June 2026; verify current rates in the Grey app before transacting.
There’s a specific kind of fatigue that comes from living globally. Not from flights or visas, but from the tiny negotiations of daily life. Figuring out which card will work. Wondering if the terminal will accept it. Keeping mental notes of what to try next.
When you add your Grey virtual card to Apple Pay, you remove one layer of uncertainty. All you need to do is tap, and the payment goes through.
Why your Grey virtual card pairs so well with Apple Pay
If you’ve ever struggled with cards that randomly fail abroad or get blocked on international platforms, you’ll feel the difference immediately. We built the Grey virtual card built for global use, and Apple Pay simply amplifies that experience.
Let's discuss why the Grey card + Apple Pay combination works so seamlessly.
One card that adapts to your life
Your Grey virtual card is directly linked to your balance. There’s no need to top up before paying or shuffle funds between wallets. You choose what you want to buy, Apple Pay handles the tap, and the payment goes through.
Designed for international spending
Fewer card declines. Better compatibility with global merchants. Clearer transactions. Whether you’re paying locally or online, Apple Pay with Grey is consistent and predictable, at home and abroad
Contactless, effortless, and global
Apple Pay is accepted in millions of locations worldwide. From supermarkets and cafés to trains, taxis, and co-working spaces, your phone becomes your payment tool. Combined with Grey’s global card functionality, spending across countries becomes second nature.
Built-in security that travels with you
Apple Pay never shares your full card details with merchants, and the Grey virtual card supports 3D Secure for online transactions. Together, they offer a safer way to shop, subscribe, and spend internationally without constant worry.
Who benefits most from using Apple Pay with the Grey Visa card?
This Grey Card + Apple Pay setup is designed for people who spend often across borders.
Travellers and frequent movers
When your Grey Visa card is added to Apple Pay, you can move through airports, metros, shops, and cafés with just your phone. No fumbling, no cash exchanges, no stress at the counter.
Freelancers and remote professionals
If you earn from international clients or pay for tools hosted abroad, Apple Pay gives you a fast, reliable way to manage everyday spending. Subscriptions, software, ads, and services all become easier to handle.
Business owners and creators
From running ads to paying for platforms like Canva, Google Workspace, or Notion, Apple Pay with Grey keeps your operations smooth and interruption-free.
How to add your Grey Visa card to Apple Pay
Setting up Apple Pay with your Grey virtual card takes just a minute:
Once added, you can use Apple Pay for in-store contactless payments, online checkouts, in-app purchases, and public transport wherever Apple Pay is accepted.
Where you can use Apple Pay with your Grey virtual card
With Apple Pay accepted in dozens of countries, your Grey virtual card becomes a global companion. You can use it to:
Pay in cafés, shops, and supermarkets worldwide
Book flights, hotels, and short stays
Subscribe to services like Spotify, Apple Music, Netflix, Canva, and YouTube
Pay for transport, food delivery, and everyday essentials
Handle online payments securely across international platforms
Your Grey balance does the heavy lifting, while Apple Pay keeps everything fast and contactless.
Why is it important to use a virtual card with Apple Pay?
Too many people are still dealing with cards that weren’t built for global lives. Unexpected declines. Confusing restrictions. Payments that work one day and fail the next.
The Grey virtual card changes that. Paired with Apple Pay, it creates a payment experience that feels modern, reliable, and genuinely global.
Different virtual cards work differently depending on how you spend, where you shop, and which currencies you use. Some excel at simple travel spending, others at multi-currency holding. Some support crypto, others don’t. Understanding the real differences helps you pick which one works for you.
Today, I’m comparing the Grey card with six other well-known virtual card options, just so you know which one works best for you.
1. Wise multi-currency card
If you’ve ever needed a card that is like a multi-currency wallet first and a spending card, Wise probably fits that bill. Wise is widely used as a borderless account with a card that lets you tap into more than 50 currencies and spend internationally at transparent exchange rates.
For many global workers and travellers, such simplicity is appealing. You get the real exchange rate plus a small, clear fee. There are generally no hidden surprises, and you can hold currencies like USD, EUR, or GBP in one place.
Wise also doesn’t support crypto balances, so if you’re someone who keeps part of your funds in digital assets and wants to spend crypto, your Wise card won’t help.
People who want to hold and spend multiple currencies with clear exchange pricing, especially for everyday purchases and travel, will love the Wise card.
Revolut is one of the most talked-about fintech platforms in the world, and its card ecosystem reflects that breadth. You can have both virtual and physical cards, generate disposable virtual cards for added security, and even manage budgeting, investments, and crypto trading all in one app.
It ticks many boxes: multi-currency support, budgeting tools, and virtual card creation. However, the complexity of features can become a hurdle, especially when key perks are tucked behind paid tiers.
Revolut is strong as part of a broader lifestyle finance app, especially for travellers and users who want added perks like travel insurance, purchase protection, and trip disruption coverage, which are included in higher-tier plans such as Premium, Metal, or Ultra. However, these benefits depend on subscription level and eligibility requirements, and coverage is provided through third-party insurers rather than built directly into the card experience.
Its virtual cards can still face issues on international platforms, and the way it converts currencies, including weekend markups, adds a layer of unpredictability for some users.
3. Payoneer card
Payoneer is a name many freelancers, online sellers, and international businesses know quite well. Its card, especially the virtual prepaid card, is excellent for receiving payments from global marketplaces, handling international transfers, and covering business expenses in multiple currencies.
However, many users report sudden card blocks, limited personal support, and slow resolution times, which can be frustrating when you’re trying to pay for everyday subscriptions or online purchases.
In many regions, Payoneer is ideal for business payouts and marketplace earnings; however, it may not be the best option if you require a card for personal multi-currency spending or flexible international use.
Freelancers and businesses requiring comprehensive currency support with global payouts, especially via marketplaces, will appreciate the Payoneer card.
N26 operates as a digital bank primarily across the EU and EEA. Its cards, both physical and virtual, are built around simplicity, with no foreign transaction fees for many currencies and straightforward Mastercard exchange rates.
It works well for everyday spending both within and outside the Eurozone, and virtual cards can be issued quickly as part of the account opening process.
The big limitation, a practical one, is its availability. N26’s services were pulled back from the U.S. and some other markets in recent years, and it remains focused on European customers.
So if you travel frequently within Europe or spend in EUR, N26 cards can be a solid choice. But outside that context, it’s less flexible, especially for global needs.
LDMAG1
5. Crypto-linked cards
Crypto cards deserve their own mention. Cards like the Coinbase Card and Crypto.com Visa Card allow you to spend cryptocurrency by instantly converting it to fiat at the point of sale. These are especially interesting for people who live or earn in digital assets and want to use them without extra conversion steps.
For example, Binance’s card (in regions where it is still supported) offers significant cashback rewards in BNB, and Coinbase lets you spend multiple crypto assets directly, with rewards in crypto.
The downside is that these cards often tie you into a specific exchange ecosystem, may carry higher fees for some transactions, and their rewards are typically token-based — valuable if you’re bullish on crypto, less so if you’re not.
I’ll recommend these cards for crypto holders who want to spend digital assets with conversion at checkout and enjoy token rewards.
6. Traditional bank virtual cards
There’s a whole category of virtual cards issued by traditional or app-based banks, like Monzo (UK), Starling (UK), or wallet-front cards like Curve.
These are solid for everyday use, especially in their home markets, and often integrate well with Apple Pay/Google Pay. However, international currency support varies widely; some have foreign transaction fees, others rely on slower underlying banking rails, and they’re sometimes limited in where they’ll work for recurring payments or certain ad platforms.
For many users, these cards are excellent backups or complementary payment methods. But if your life or work relies on consistent, global spending, their limitations become noticeable.
7. Grey card offers a more flexible virtual global spending experience
By now, it should be clear: not all virtual cards are the same. Some are designed for holding money, others for daily banking, and others still for specific ecosystems.
Grey’s approach sits in a different space from the others above. Your card works across fiat (USD, EUR, GBP, local currency) and stablecoins (USDC), eliminating the need to get an extra crypto card. Your Grey card automatically pulls funds from your available balances in the following order: USD, USDC, and then the next highest available balance.
You can also create multiple cards for different purposes, such as travel, subscriptions, personal, and business. Still, each card will work seamlessly without requiring you to select which balance to spend from. We built the Grey virtual card for people who:
Spend in multiple currencies regularly
Want predictable outcomes at checkout
Value clear messaging and control
Need support for both fiat and crypto balances
Instead of requiring top-ups or rigid currency conversion steps, your Grey card automatically draws from your available balances, making spending across fiat and stablecoin currencies effortless.
Many of the other options we’ve discussed above are great in their contexts. However, each has trade-offs that make it difficult to be everything to everyone.
There’s no single answer, but here’s a quick way to think about it:
If you want clear, no-nonsense multi-currency holding and spending, Wise or N26 are strong choices.
If you’re looking for a financial super app with perks, Revolut is a great fit.
If you earn or spend in crypto and enjoy token rewards, crypto cards like Coinbase or Crypto.com are worth exploring.
If you want a card that automatically draws from different balances, supports multiple cards, and makes international or multi-currency spending predictable globally, we built Grey for your lifestyle.
Different cards shine in various life scenarios. The key is knowing which trade-offs matter to you, and how your day-to-day spending looks.
Choose with clarity, and let your card work for you, not the other way around. Create your Grey visa card and enjoy a smoother, more inclusive, and more predictable global spending experience.
Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.
Then remote work happened.
Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you also need structure because, without proper structure, even the most careful spender can lose track of where their money is going.
Your Grey card is a practical budgeting tool for people who live, work, earn, and spend across borders. I’ll explain.
Why budgeting in multiple currencies breaks down so easily
Many people who overspend don't do so because they’re irresponsible. But because their money isn’t organised in a way that reflects how they live.
It’s pretty common to be juggling subscriptions in USD, running ads in EUR, buying coffee in GBP, and somehow all on the same card. Eventually, everything blurs together. You can no longer track your Netflix renewal, that Facebook ad campaign, the flight you booked last week, or the coworking space membership. Then one day you check your balance and think, “Where did all that money go?” You know you spent it. You just can’t figure out where, or why, it felt like so much more than you expected.
It’s not that you’re careless. It’s that your money isn’t organised in a way that matches how you actually live and work. And once things start blurring, it’s nearly impossible to untangle without spending an hour combing through statements, converting currencies in your head, and still not feeling certain you’ve caught everything.
What should budgeting look like when you earn and spend globally?
Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:
See exactly what each type of spending is costing you.
Stop or pause spending instantly when needed.
Protect one part of your budget from another.
Make changes without disrupting everything else.
The Grey card is designed around solving these exact needs.
How does the Grey card help with budgeting?
Use multiple cards to separate your spending
One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes. Your Grey virtual card helps you structure your spending as such.
For example, you can create:
One card for subscriptions and recurring tools
One card for ads and growth experiments
One card for travel or everyday spending
One card per client or project
Each card acts like its own budget lane, pulling from the same balance. You don’t need to guess where the money went because you already know.
This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.
Freeze cards instantly when spending goes off-track
Budgets fail when you can’t act fast enough.
With the Grey card, you can instantly freeze or unfreeze any card in the app. If a digital ad campaign starts burning through too cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.
Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.
Set limits that protect your budget
Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.
You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.
For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.
Track spending clearly in one place
When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.
When budgeting time comes around, you’re not sitting there trying to remember what that mysterious €47 charge was three weeks ago or why your USD balance dropped. Everything’s already categorised. The structure did the work for you.
Spend confidently across borders
Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.
A quick note on protection when spending abroad
An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.
When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.
It’s one less thing to worry about while managing money across borders.
What budgeting in foreign currencies is like with the Grey card
When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency your spend is coming from and more importantly, when something changes.
Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.
If you’re ready to make your budget work wherever you are, create or update your Grey card today and start spending and budgeting in the ways that matter to you.
A few months ago, I was eyeing a pair of sneakers on a US website for weeks. Then the store started running sales and I decided to buy them (hashtag #YOLO), but my bank card declined the payment.
Not once, not twice… but four times!.
The same card that worked perfectly in Nigeria where I live, and the same details I’d used for years. I tried to get another card, but by then, sales had ended, and the sneakers were out of stock. It was annoying, but I just had to accept my L.
If you’ve ever tried to shop internationally, on sites like ASOS UK, Amazon US, Zara EU, or even the Apple Store, you may already be familiar with this pain. Sometimes the website rejects your card. Sometimes your bank blocks the transaction. Sometimes the currency conversion takes too long, and the payment times out.
It shouldn’t be this difficult to buy something online in big 2026… yet for many people, it still is.
But if you use a Grey card, you'll eliminate the uncertainty of thoughts like, “Will this payment go through?”, and transform your international shopping into a simple and predictable process.
Why shopping abroad is often frustrating
Shopping from US or European stores usually comes with these hurdles:
1. Many foreign merchants decline local cards
Some US/UK online stores automatically reject certain African-issued cards, even if you have more than enough balance.
2. Stores bill strictly in USD, GBP, or EUR
If your card requires manual currency conversion, it can cause payment delays that may result in declines.
3. Banks block “suspicious” international transactions
This usually happens when the merchant is unfamiliar.
4. Conversion errors and hidden fees
Some cards convert long after the purchase, leading to surprises on your statement.
These problems are common, but they’re also exactly what Grey card is built to avoid.
How your Grey card makes shopping internationally easy
Smart spending across multiple currencies and USDC
Your Grey card doesn’t require you to pick or switch wallets before paying. Instead, it automatically spends from your balances. Your USD account is debited first; if that’s empty, your USDC, and then the highest of your remaining balances.
This means your payment goes through as long as you have funds available in your account, without requiring you to consider currencies at checkout.
Works across major US and European stores
Your Grey card is an international spend card, so you can pay at 150 million merchants worldwide.
Use Apple Pay and Google Pay
For stores that support mobile wallets, you can simply add your Grey Visa card to Apple Pay or Google Pay. This is more secure and makes for much faster checkouts.
Create multiple cards for better organisation
If you shop frequently or mix personal and business purchases, you can:
Use one card for personal shopping
another for business imports
another for gift purchases
It keeps your spending clean and easy to track.
Freeze and unfreeze anytime
You can always freeze your cards to control your spending.
Better protection for online transactions
You receive real-time notifications, card controls, and instant limits - everything you need for peace of mind when buying from foreign sites.
LDMAG1
How to shop in the US or Europe with your Grey card
1. Request your Grey visa card
Create a Grey account and go to the cards section of your Grey app to request a Grey card for $5.
2. Add your card to the store’s checkout
Enter your card details or simply pay through Apple Pay/Google Pay.
3. Make your purchase normally
Shipping, duties, and taxes will be displayed as they are for every other international shopper.
4. Track everything in your Grey app
Every charge, refund, or verification appears instantly, so there are no surprises later.
Tips for smarter international shopping
Use a separate card for business or bulk purchases so you can easily track expenses.
Keep a bit extra in your wallet for shipping fees and taxes.
Use Apple Pay/Google Pay when available. It’s the most seamless way to tap and pay, and also supports contactless payments.
Shopping abroad doesn’t have to be stressful
Your Grey card helps you shop with confidence. There are no random declines or conversion drama. Ahead of your next international purchase, you can create your Grey card and enjoy a smoother, more predictable shopping experience.
The default way Indian banks handle inbound USD is: receive the wire, convert to INR immediately at their own rate, credit your account in rupees, and deduct fees at every step. You never see the dollars. You never choose the conversion rate. You never decide when to convert. The bank decides all three, and the bank's rate is never the mid-market rate. That automatic conversion is where freelancers, consultants, and remote workers lose the most money on international payments.
The cost of this setup is not small. A 2% to 3% FX spread on every transfer, intermediary deductions on SWIFT wires, and receiving bank charges add up to lakhs lost annually for anyone earning regular USD income. This guide covers the four main ways to receive US dollar payments in India, what each one actually costs on a real invoice, the compliance requirements (purpose codes, FIRC, FEMA) that most payment guides skip entirely, and how to set up an infrastructure that gives you control over when and at what rate your dollars become rupees.
The four main ways to receive USD in India
1. US ACH or Fedwire transfers
ACH (Automated Clearing House) and Fedwire are US domestic transfer systems. When a US client pays you via ACH or Fedwire, the money moves within the US banking system to a US-based account. This is important because US companies strongly prefer paying vendors through their domestic payment rails. Their finance teams process ACH payments the same way they pay local contractors, which means less friction on the client side and faster approval on yours.
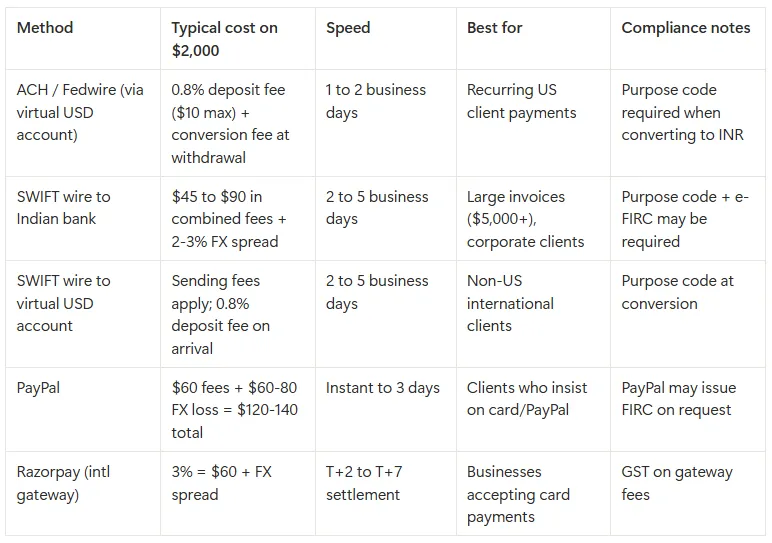
ACH transfers typically cost the sender nothing or a small flat fee (usually under $1). Fedwire transfers may cost the sender $15 to $30, depending on their bank. On your end, the cost depends on where the funds land. If you are receiving into a virtual USD account from a fintech provider, the provider charges a deposit fee (Grey charges 0.8%, minimum $2, maximum $10). There is no intermediary bank deduction because the payment never leaves the US banking system.
ACH is best for recurring payments from US-based clients, such as monthly retainers, project milestones, or regular consulting fees. If most of your clients are American, setting up a virtual USD account that supports ACH and Fedwire deposits is typically the lowest-cost option for regular income.
2. International wire transfers (SWIFT)
SWIFT is the global messaging network that banks use to route cross-border payments. When a client outside the US (or a US client whose bank does not support ACH to your provider) sends you a wire transfer, it travels through the SWIFT network. This is the most universally accepted method, but it is also the most expensive.
The costs stack up at multiple points. The sending bank charges a wire fee, typically $20 to $50, depending on the country and bank. If the payment routes through an intermediary (correspondent) bank, that bank deducts another $10 to $25 from the transfer amount. Your receiving bank may charge an additional inward remittance fee of $5 to $15. On a $2,000 invoice, total fees can range from $45 to $90, which is 2.25% to 4.5% before any currency conversion. Settlement takes 2 to 5 business days.
SWIFT makes sense for large, infrequent payments where the fixed fees represent a smaller percentage of the total: invoices above $5,000, corporate contracts, or one-off project payments. For smaller recurring payments, the per-transfer cost makes SWIFT significantly more expensive than ACH.
Payment aggregators collect funds from your client (usually via card or local bank transfer) and remit the proceeds to your Indian bank account. The most common ones Indian freelancers encounter are PayPal, Razorpay (for businesses accepting international payments), and Stripe (with limited availability for payouts in India).
PayPal charges 2.99% on incoming goods and services payments, plus a currency conversion spread of 3% to 4% above mid-market when you withdraw to INR. On a $2,000 payment, that is roughly $60 in transaction fees plus $60 to $80 in conversion loss, totalling $120 to $140. Razorpay's international payment gateway charges 3% per transaction for international cards. These platforms are convenient for clients who prefer paying by card or who are not set up for bank transfers, but the cumulative cost is the highest of all four methods.
Aggregators are best for small, one-off projects where the client insists on paying by card, or for marketplace payouts (Upwork, Fiverr) where the platform dictates the payment method.
4. Cross-border transaction caps
India's cross-border payment framework includes transaction-level limits in certain categories. Some payment setups cap individual cross-border transactions at ₹25 lakh per unit of goods or services. If your invoice size approaches that range, bank-led rails such as SWIFT are usually more suitable than aggregator platforms. Having access to a USD receiving account through a provider like Grey gives you more flexibility when handling higher-value international payments, because the funds arrive in USD first and you control the conversion timing and method.
How the four methods compare
The compliance layer most freelancers overlook
Receiving USD payments in India is regulated under the Foreign Exchange Management Act (FEMA) and RBI reporting guidelines. Getting the compliance right upfront prevents delays, frozen transfers, and problems during audits.
Purpose codes
Indian banks require a purpose code on every inward remittance to classify the transaction under FEMA. Common codes for freelancers include those for software development, consulting, and marketing services. These codes are defined under the RBI purpose code list for inward remittances. Providing the correct code on your invoice and communicating it to your client's bank reduces the risk of your payment being held for manual review. Vague or missing purpose codes are one of the most common reasons for delayed credits.
If you export services (which includes freelancing for foreign clients), you may need a Foreign Inward Remittance Certificate (FIRC or e-FIRC) for GST export documentation, audits, and platform compliance. Only authorised dealer banks issue e-FIRC documentation. Confirm your bank's process for issuing these certificates in advance, because requesting them after the fact can take weeks. If you receive payments through a virtual USD account and then transfer to your Indian bank, the e-FIRC is issued by the Indian bank that receives the final INR credit.
Export realisation timelines
India requires that export proceeds be realised (received in India) within a prescribed period. Long-pending invoices can create compliance issues. Keep your documentation organised and follow up on overdue payments early. For a complete explanation of FIRC requirements, tax implications, and RBI compliance rules, see Grey's guide on FIRC, taxes, and compliance for Indians earning foreign currency.
Which setup is right for your situation
The right payment method depends on three factors: where your clients are located, your average invoice size, and whether you want to hold USD or convert to INR immediately.
For mostclientsintheUS, a virtual USD account that supports ACH and Fedwire is typically the lowest-cost option. Your US client pays you the same way they pay a local vendor. You receive the funds in USD, hold them until you are ready to convert, and withdraw to your Indian bank at a rate and time you choose. SWIFT works as a backup for clients whose banks do not support ACH to their provider.
Global clients across multiple countries: Ensure your account can receive international SWIFT wires without intermediary deductions eating into your payment. A multi-currency account lets you hold USD, GBP, or EUR and convert only when the rate is favourable, rather than accepting your bank's automatic conversion on arrival.
Large invoices ($5,000+): Direct bank rails (SWIFT or Fedwire) are preferable to aggregator platforms. The fixed fees are lower as a percentage of the total than the percentage-based fees aggregators charge. A $10,000 invoice through PayPal costs roughly $600-$700 in combined fees and FX losses. The same invoice received via SWIFT to a virtual USD account costs $10 in deposit fees plus the conversion cost when you move to INR.
Priority is maximising take-home INR. Compare the total cost at every step: incoming transfer fees, deposit fees, FX margin versus the mid-market rate, and withdrawal fees. Small differences in FX margins compound significantly over a year of regular payments. A 1% difference on $3,000 per month is $360 annually.
Relying on a single payment method leaves you exposed if that channel has downtime, compliance issues, or fee changes. The safest setup is ACH or Fedwire as your primary rail with SWIFT as a fallback. Ignoring FX spreads is the most expensive mistake: the difference between mid-market and a 3% markup on $2,000 is $60 per transfer. Waiting until a compliance request arrives to organise your documentation can delay your funds for days or weeks. Sending invoices without detailed service descriptions triggers manual review at Indian banks because the purpose of the remittance is unclear. Include the service type, project reference, and your client's details on every invoice.
How Grey works for Indian freelancers receiving USD
Grey provides Indian freelancers, consultants, and remote professionals with USD, GBP, and EUR foreign currency accounts that can receive payments via ACH, Fedwire, or international SWIFT wire transfers. The setup is fully digital: sign up at grey.co or download the Grey app, complete KYC verification with your PAN card, Aadhaar, and proof of address, and your account details are available within 24 hours.
When a payment arrives via ACH or Fedwire, Grey charges a 0.8% deposit fee (minimum $2, maximum $10). The funds sit in your USD wallet. You can hold them in dollars for as long as you need, which is useful if you want to wait for a more favourable exchange rate or if you have USD expenses (software subscriptions, SaaS tools, advertising spend) that you can pay directly using a Grey virtual card. The virtual card costs $5 to create with no monthly maintenance fee. Transactions on USD-priced sites incur no additional fee; purchases on non-USD websites carry a 2% + $0.50 cross-border fee.
When you are ready to convert to INR, Grey charges a 1% conversion fee capped at $6 per transaction. The conversion rate is displayed before you confirm, so you see exactly how much INR you will receive. Transfers to your Indian bank account require your IFSC code and typically arrive the same day. You can check Grey's fee calculator to see the exact cost for any transaction amount before you commit.
Instead of relying on automatic bank conversions that happen at arrival, or juggling multiple platforms for different currencies, you receive USD through one account, manage your balance in dollars, and convert to INR when the timing and rate suit you.
Grey charges a 0.8% fee on deposits (minimum $2, maximum $10), a 1% conversion fee (capped at $6), and a withdrawal fee that varies by currency. Exchange rates on Grey are variable and include a margin over the mid-market rate. Cross-border card transactions on non-USD websites incur a 2% + $0.50 fee. Always review fees and the conversion rate before confirming a transaction.
I remember my first international payout like it was yesterday. I’d spent months building an audience, finally hit the YouTube monetisation threshold, and eagerly waited for the payment from Google AdSense. When the notification came through saying the money had been sent, I felt brilliant. Proper creator now, getting paid for my work. “Tell Mr Beast to come outside!” I said.
When I checked my account, the platform had sent the money, yes, but somewhere between California and my bank account, a part of it just vanished.
That moment taught me that understanding how you get paid is just as crucial as understanding how to create content people want to watch. Over the years, I’ve learned the hard way how international payouts actually work, where money gets lost, and how to structure things so you keep more of what you earn. This is what I wish someone had told me before that first disappointing payout.
Platforms don’t just send money directly to your bank account like a friend transferring you a tenner. They use intermediaries called payout processors because they’re dealing with millions of creators across dozens of countries, all expecting payment, some even in their local currency.
YouTube pays through Google AdSense. TikTok uses various regional processors. Patreon, Twitch, and Substack all rely on third-party systems to handle the actual movement of money across borders. This makes sense from their perspective. They can’t open bank accounts in every country or navigate every local banking regulation themselves.
LDMAG1
The most common payout methods
I’ve used nearly every payout method available to creators, and each has taught me something different.
Direct bank transfers
Direct bank transfers via wire seemed more professional when I started getting larger payments. But international wire transfers involve multiple banks, each charging fees. I once received a $2,000 payment that cost me nearly $90 in combined bank charges and poor exchange rates. The sender paid $25, an intermediary bank took $20, my bank charged a receiving fee, and then converted USD at a rate significantly worse than the mid-market rate. It added up fast.
Platform-specific systems
Platform-specific systems like Payoneer work better for creators on freelance marketplaces. Payoneer integrates smoothly with platforms like Upwork and Fiverr, and it’s cheaper than PayPal. I still lost 1-2% on currency conversion, though, and withdrawal fees applied depending on how I accessed the money.
Multi-currency fintech accounts
The breakthrough for me came when I discovered multi-currency fintech accounts. Services like Wise, Revolut, and Grey offer virtual bank accounts in multiple currencies, such as USD, EUR, and GBP, so you can receive payments easily. This changed everything for me.
After years of losing money unnecessarily, I finally sorted out a proper system, and it made an immediate difference.
First, I opened a multi-currency account that let me receive USD, EUR, and GBP without forced conversion. I went with Grey because it gave me proper banking details with an account number, sort code, and routing number so that platforms and clients could pay into it directly.
Next, I updated my payout details across every platform. YouTube, Patreon, freelance platforms, and direct clients, I gave them all my new account details. Some platforms required verification periods, others had specific payout cycles. But once everything was switched over, the difference was clear.
Finally, I started converting currency strategically instead of immediately. If I’m not spending the money right away, I hold it in USD until the exchange rate improves. Sometimes this saves me 2-3%, which compounds significantly over months.
I’m not here to give you a sales pitch, but I do want to explain why Grey made such a difference for me specifically.
Grey gives you virtual bank accounts in USD, EUR, and GBP with proper banking details. When a platform or client pays you, the funds are deposited directly into the relevant currency account. There’s no forced conversion, no intermediary banks taking unexpected fees, and no waiting two weeks for international wires to clear.
The exchange rates are transparent. Whenever I convert, I know exactly what I’m paying, as there are no hidden fees buried in exchange-rate spreads.
For creators earning from multiple countries and platforms, having one system that handles everything is genuinely valuable. I used to juggle different platforms, but now everything flows into Grey, and I manage it all in one place.
The clarity this provides also makes tax filing significantly easier. I have clean records of what I earned, in which currency, and when.
Treating your payout infrastructure as part of your overall creator strategy isn’t boring back-office admin. It’s keeping more of the money you’ve worked hard to earn. It’s having control over your finances instead of just accepting whatever arrives in your account. It’s being professional about your business.
The platforms will keep paying you, but they won’t optimise how you receive that money. That’s your job. Understand the fees, use the right tools, and structure your systems intelligently. Your future self will thank you.