


STAY UP TO DATE
The Grey Blog


FEATURED ARTICLES

The things we’re secretly scared of when it comes to money
Losing a job, sending to the wrong account, running out abroad: the money fears we rarely admit, and the tools that shrink them with Grey. Open.
Olayoyin Olorunmota
•
6 min read
It’s 3 am, and the phone is lighting up the ceiling. What if my main client does not renew next month? What if that transfer went to the wrong account number and it has already left? What if the card declines in a city where I know nobody? What if someone at home calls tonight and needs money by morning?
We rarely say these out loud, yet most of us carry some version of them. At that hour, they feel shapeless. In daylight, most turn out to be a few specific risks and a few specific steps.
Five money fears tend to keep people awake: losing income, a payment that never arrives, a transfer sent to the wrong person, running out of money abroad, and an emergency at home. Each is partly rational and partly reducible.
This is how we can get ahead of these worries and how to make each situation easier to handle.
What if I lose my income?
Of the five, this is the one with the most reason behind it. Clients leave, contracts end, companies restructure, and a salary that felt permanent can stop with a month’s notice. We are not being dramatic when we worry about it.
What we can usually reduce is how fast the fear turns into a crisis. Two numbers do most of the work. The first is the cost of one month: rent, food, transport, data, and any fixed obligations such as school fees or loan repayments. The second is how much of your income comes from one source. If a single client or employer pays most of it, losing them hurts differently from losing one of five.
Always have a buffer of one month’s costs, kept somewhere separate from the account you spend from, like in a Pouch. One month is not a deep cushion but it’s enough to turn a sudden stop into a few weeks of choices instead of a few days of panic. From there, three months is a common target if you can reach it.
This is not to forsee stalled income but to be prepared if it does.
What if the payment never comes through?
Late payment is perhaps the least troubling of the five, because it does not feel like a disaster. It feels like waiting, refreshing the account, and drafting a polite email for the third time. Invoices do get paid late, and some clients, rather annoyingly, treat the due date, as a suggestion.
Part of the fear can be shrunk before you send an invoice. Here's what you can do:
- State the due date and the payment method in writing, and agree what happens if the date passes, such as a late fee or a pause on work. Ask for a deposit on larger jobs so you are never fully exposed.
- Check that the name on your invoice matches the name on the account that will receive the money. Many banks and payment providers hold a payment for review when the sender's details and the receiving account name do not match, and you may be asked for documents before it is released. A payment can be on its way and still not be spendable.
- A follow-up routine helps too: a reminder two days before the due date, one on the day, and one a week later. A scheduled message is easier to send than an anxious one.
What if I send money to the wrong person?
This is the fear with the sharpest edge, because many transfers cannot simply be taken back. Once a bank transfer has left, getting it returned usually depends on the receiving bank, and on the person who received it, more than on how quickly we notice.
What we can reduce is the chance of it happening, and how fast we act if it does:
- Check the account number, the bank, and the name twice, and read the digits out loud instead of skimming them.
- For a large amount or a new recipient, send a small test first and confirm it arrived before sending the rest.
- Save a recipient only after a transfer has landed with them, so the saved details are the ones that worked.
- If something goes wrong, contact your bank or provider straight away, with the date, amount, reference, and recipient details ready.
Be honest about the odds. Recalls depend on the receiving bank, can carry a fee, and do not always succeed. Speed improves the chances. It does not guarantee a return.
We cannot remove this fear completely, and we should not pretend to. We can make the mistake less likely and the response faster, which is most of what is in our control.
What if I run out of money abroad?
Being abroad changes the shape of this worry. At home, a failed card is an annoyance at best. Somewhere else, it can mean a missed ride, a stalled hotel check-in, or a long call to a bank that is closed. Some of the fear is justified: cards do get declined abroad, banks do flag unfamiliar transactions, and the exchange rate at a till can be worse than the one on your phone.
These steps can help:
- Carry a second way to pay that does not depend on your main card, ideally from a different provider, and keep it apart from your main card.
- Keep a small amount of cash in the local currency for the first day.
- Keep a buffer in the currency you will be spending, not only in naira, so a swing in the exchange rate does not shrink your trip while you are on it.
- Check what each card charges for payments abroad before you leave, because the fee can differ a lot from one card to another.
The part of this fear that is not rational is the idea that one failed payment means everything has failed. Usually, it means we need the second option, and the point of having one is that the first failure becomes a small event.
Holding USD, GBP or EUR while abroad keeps travel spending flexible and Grey's virtual cards give you a second option.
What if there's an emergency back home?
This is the fear that does not stay in our own heads, because it arrives as a phone call and a familiar voice. Money for a hospital deposit or a parent's rent is needed quickly, and to a specific place. An emergency usually comes with a deadline, and the person usually asking cannot wait for an exchange rate to improve.
In these instances, what you can decide in advance is the route and the amount. Know how money reaches that person: which bank, which account name, which details, and whether it can arrive at all on a weekend or a public holiday. You can confirm the details and when you are a little calmer, in a calm moment, send what you can without without putting your housing or tuition and other commitments at risk.
Transfer times vary by route and by day, so learn how long your usual route takes before you need it, not on the day. Treat any delivery estimate as an estimate, and leave room around bank cut-off times.
We carry this fear because we care about the people on the other end of it. That is not something to fix. What we can do is make the next call a little less frightening by doing the dull preparation before it comes.
Frequently asked questions
Can you reverse a bank transfer sent to the wrong person?
Sometimes, but not always. It depends on the receiving bank, the type of transfer, and whether the money has already been spent. Contact your bank or provider immediately, because speed improves the chances, and expect that a fee may apply.
What should I do first if I sent money to the wrong account?
Contact your bank or provider straight away. Have the date, amount, transaction reference, and the recipient's details ready, and say what went wrong in plain terms. Do not wait to see whether the recipient notices.
How big should my emergency fund be if my income is irregular?
Start with one month of essential costs, then build towards three to six months. People with irregular income often aim for the higher end, because a gap can last longer. These are general guidelines, not financial advice.
Why is my payment pending or on hold?
Providers often hold a payment for verification when the sender's details and the receiving account name do not match, or when more information is needed about the source of the funds. You may be asked for documents before the money is released.
How do I avoid running out of money when I travel?
Carry two ways to pay from different providers, keep a little cash in the local currency, keep a buffer in the currency you will spend, and check each card's fees for payments abroad before you leave.
Is it normal to be anxious about money?
Yes. Money worries are common, and some of them are rational. A useful way to handle them is to separate the part that is a real risk from the part that is not, and then act on the part you can change.
Open a Grey account to receive, hold, and send money in one place.
Fees and rates: deposits by ACH, SEPA, or Faster Payments cost 0.8%, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. Currency conversion costs 1%, capped at $6. Withdrawals to a Nigerian bank account cost ₦35. A virtual card costs $5 to create, once, with no monthly fee, and payments on non-US websites can carry a cross-border fee of 2% plus $0.50. A recall of a USD, EUR, or GBP payment carries a fixed fee of $50, €25, or £25, even if it fails. Exchange rates vary with a margin over the mid-market rate.
ALL ARTICLES
How much does Square charge per transaction?
See what Square really costs per transaction, by payment type, plus monthly fees, chargebacks and payout timing explained. Check the numbers.
Odunmorayo Oke
•
November 17, 2026
•
6 min read
It’s a packed Saturday afternoon at your coffee shop. The line stretches out the door, orders are flying, and customers are tapping their cards and phones at the register every thirty seconds. By closing time, you’ve had your best sales day of the month. Then Monday morning rolls around, you check your bank payout, and the deposit is noticeably smaller than the total on your sales screen.
If you’ve ever had that moment of confusion, you’re looking at payment processing fees in action. For many small businesses, those payments are handled by Square, an all-in-one financial and point-of-sale (POS) platform that lets merchants accept card and mobile payments in person or online.
While Square makes getting paid easy, figuring out how much it takes from each sale can be a bit complicated. Between different rates for card taps and online invoices, the advertised numbers don't always tell the full story.
This guide breaks down how Square’s pricing actually works across every payment method, and the extra costs to take note of.
What is Square?
Square is a financial service and merchant platform that provides point-of-sale (POS) hardware, software, and payment processing solutions. It makes buying and selling easier by making digital card payments accessible to business owners.
How does Square pricing work?
Square uses a transaction-based pricing model, which means businesses pay a fee whenever they process a payment. Most card payments come with two charges: a percentage of the transaction amount and a fixed fee. For example, if Square charges 2.6% + $0.15, it takes 2.6% of the payment amount and an additional 15 cents. If a customer paid $100 using a card, the the business would receive $97.25.
The amount you pay depends on how a customer makes a payment. When someone pays in person using a card, Square charges a lower processing rate. However, online payments and manually entered card details usually cost more because they carry a higher risk of fraud. This is because the customer and their physical card are not necessarily present when the payment is made.
Square also offers three main subscription plans: Square Free, Square Plus and Square Premium. The Free plan has no monthly subscription fee, while the paid plans offer additional business tools and lower processing rates for some payment types.
The plan you end up choosing will affect how much you spend on transaction fees and software each month. Understanding these costs can help you choose a plan that suits your business and avoid paying for features you do not need.
Square fees by transaction type
Your exact Square processing fee depends on how a customer pays. For example, processing a payment in person generally costs less than accepting a card payment through your website.
The table below shows Square's published US processing fees for 2026.
Note: Grey is not affiliated with Square. These rates apply to eligible US-based Square accounts and may change. Always check Square's official pricing page for the latest information.
A few other payment methods have different fees:
- International cards: An additional 1.5% applies to cards issued outside the US.
- Afterpay: 6% + $0.30 per transaction.
- EBT payments: 1.8% + $0.05 per transaction.
- Cash and cheques: No processing fee.
- Gift card loading: 2.5% on Free and Plus plans; no loading fee on Premium.
Others costs to budget for
Transaction fees are not the only expenses to consider when using Square. Businesses may also need to pay for payment equipment, monthly subscriptions and certain banking services.
Monthly software plans: Square offers three main plans: Free ($0 per month), Plus ($49 per month, per location) and Premium ($149 per month, per location). Paid plans come with additional business management features and lower processing rates for some payment types.
Hardware: Businesses may need to purchase equipment to accept in-person payments. Square's contactless and chip reader costs $59, while Square Stand costs $149. More advanced options include Square Terminal at $299 and Square Register at $899. These are one-time hardware purchases, separate from subscription fees.
Chargebacks: Square does not charge an additional fee for handling payment disputes. However, it may temporarily withhold the disputed amount from your balance or linked bank account while investigating the claim.
Instant payouts: Standard next-business-day transfers are free, but businesses that need faster access to their money can use instant or same-day transfers for a 1.95% fee.
Refunds: Square does not charge an extra fee to issue a refund, and your customer receives their full purchase price back. However, Square keeps the original payment processing fee you paid when the sale first went through.
What Square actually costs a small business
Looking at Square's advertised processing rates alone does not always show how much a business will spend. The actual cost depends on how many transactions it processes, how much customers spend and which payment methods they use.
To understand how this works, consider a small retail business that makes $15,000 in monthly sales. Assume $10,000 comes from in-person card payments, with an average purchase of $50, while the remaining $5,000 comes from online orders, with an average purchase of $100.
The business processes 200 in-person transactions and 50 online transactions each month.
Using Square Free
On the Free plan, the business pays 2.6% + $0.15 for in-person payments and 3.3% + $0.30 for online payments.
- In-person payments ($10,000 across 200 transactions): The percentage fee is $260 (2.6% of $10,000). The fixed fee is $30 (200 × $0.15). This brings the total in-person processing cost to $290.
- Online payments ($5,000 across 50 transactions): The percentage fee is $165 (3.3% of $5,000). The fixed fee is $15 (50 × $0.30). The total online processing cost is $180.
- Total monthly processing fees: $290 + $180 = $470.
The business pays $470 to process $15,000 in monthly sales. This is an effective processing rate of approximately 3.13%.
Using Square Plus
Suppose the same business upgrades to Square Plus for $49 per month. Its in-person processing rate drops to 2.5% + $0.15, while its online rate drops to 2.9% + $0.30.
- In-person payments ($10,000 across 200 transactions): The percentage fee is $250 (2.5% of $10,000). The fixed fee is $30 (200 × $0.15). Total: $280.
- Online payments ($5,000 across 50 transactions): The percentage fee is $145 (2.9% of $5,000). The fixed fee is $15 (50 × $0.30). Total: $160.
- Total processing fees: $280 + $160 = $440.
- Monthly subscription: $49.
- Total monthly cost: $440 + $49 = $489.
In this example, the business spends $489 per month on Square Plus, compared with $470 on Square Free.
Although Square Plus reduces the business's processing fees by $30, the $49 subscription costs an additional $19. This makes the Free plan the cheaper option for this business.
The example shows why business owners should consider their monthly sales, transaction volumes and payment methods before choosing a Square subscription. A paid plan is not automatically cheaper, even if it offers lower transaction rates.
However, a business that processes more payments or needs the additional software features may find that upgrading is worthwhile.
Getting paid across borders using Grey
For all its benefits and features, Square is built for local payments. To use it, your business must be registered in a supported country and linked to a local bank account in that same currency. If you run a US business, Square sends your payouts in US dollars. Once your money lands, moving it across borders gets expensive. Sending funds to overseas suppliers, remote workers, or your bank account back home often means high wire fees and inconsistent and often expensive bank exchange rates.
If you run a business that spans continents, you will need a cost-effective way to move money. Grey gives you flexibility and control over what happens to your funds after you get paid. Grey does not replace Square at checkout. While Square handles payment collections, Grey helps you manage and move your money once you get paid. With Grey foreign accounts, you get US, UK, and European account details to receive USD, GBP, and EUR payouts. You can then swap currencies with Grey currency exchange at transparent rates or send money internationally to over 80 countries.
Frequently Asked Questions
How much does Square take per transaction?
Square charges 2.6% plus $0.15 for in-person tap, dip, or swipe payments on its free plan. Online payments and invoices cost 3.3% plus $0.30, while manually keyed entries cost 3.5% plus $0.15. Paid plans have a lower percentage rate in exchange for a recurring monthly subscription fee.
Does Square have monthly fees?
The Square Free plan has no monthly subscription fee; you only pay when you successfully process a transaction. However, Square offers paid tiers such as Square Plus at $49 per month and Square Premium at $149 per month, which unlock reduced processing rates and advanced administrative tools.
Why was I charged more than the standard rate?
You might get higher charges if you manually key in customer card numbers instead of using a physical reader, process international cards which has an additional surcharge, or use add-on services like Afterpay or instant payout transfers.
How fast are payouts?
Standard bank transfers from Square are included at no extra charge and typically arrive as soon as the next business day. If you want immediate access to your funds, instant payouts are available for a 1.95% fee.
Does Square charge for refunds?
Square does not charge extra processing fees when you issue a refund. When you refund a payment in full, Square returns the original processing fee to your account. Partial refunds receive a proportional fee return.
Selling across borders? Receive and move your money with Grey.
How African businesses source from and pay suppliers in China
A practical guide to sourcing from China: finding factories, checking quality, and paying suppliers from Nigeria without losing margin to fees. Start.
Olayoyin Olorunmota
•
November 11, 2026
•
6 min read
Say you’re dealing with a factory whose quote is in dollars, and they want a deposit before production starts, and the account details arrive by email under a company name that isn’t quite the one on the invoice. For a first-time importer in Lagos or Nairobi, nothing about that moment is unusual, and each part of it is a place where a small mistake costs real money.
Many African businesses usually pay Chinese suppliers by international bank transfer, in US dollars or yuan. A common pattern is a deposit before production and the balance before shipment, though terms are negotiable. Importers in Nigeria must also register a Form M with their bank. Platform escrow, where offered, adds protection for first orders.
However, with cross-border and global payments making it easier for businesses to settle renminbi (RMB) transactions, trading with China has become easier, and more options are available to people and businesses to send yuan directly to local bank accounts in China.
In this article, I cover how to find and check a supplier, what an order should cost, how to manage the relationship, and how to pay.
Why China, and why now?
If you are looking to start or scale a business, China is hard not to consider. China is a major source of manufactured goods for African businesses, and the volumes show it. Trade between China and Africa reached a record US$348.05 billion in 2025, up 17.7% on the year, according to a report from the NTU-SBF Centre for African Studies. Chinese exports to Africa accounted for US$225.03 billion, up 25.8%, while imports from Africa were US$123.02 billion, up 5.4%. The same report puts Africa’s deficit with China at US$102.01 billion, meaning African buyers are importing far more than they export.
Behind those totals are the businesses this guide is for: shop owners, online sellers, and small manufacturers who buy fabric, electronics, machine parts, packaging, and finished goods. A growing number go a step further and develop private-label products, in which a factory makes a product to the importer's specifications and under the importer’s brand. That raises the stakes on everything that follows: choosing the factory, agreeing the order size, checking quality, and moving the money.
What has changed in China-Africa trade in the last five years
China opened its market to African exports
Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.
China opened its market to African exports
Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.
Nigeria’s foreign exchange policy has been updated
The CBN issued a new foreign exchange manual in May 2026. Coverage states that importers must submit exchange control documents within 90 days of negotiating shipping documents, and that importers who fail to do so may be restricted from the foreign exchange market. We’ll talk about this a bit more in the section on paying suppliers.
There are more ways to pay in yuan
Some payment providers, like Grey, now deliver yuan directly to Chinese bank accounts, giving importers an alternative to paying only in dollars.
How to find a reliable Chinese supplier
For businesses looking to source from China, finding a supplier often starts with an online marketplace, especially for first-time importers.
Alibaba.com is built for export buyers and lists suppliers that work with overseas customers. 1688 is China’s domestic wholesale platform. It is written in Chinese, prices are often lower, and most foreign buyers use a sourcing agent or a translator to work with it. Trade fairs such as the Canton Fair in Guangzhou let you meet suppliers and handle samples in person, and referrals from other importers in your market often lead to suppliers that already ship to Africa.
Factory or trading company?
When you make contact, you have to ask directly: “Do you own the factory?” A trading company is not a bad choice, since it can combine products from several factories and handle export paperwork, but it adds its own margin and puts you one step further from the people making your product. A factory can usually show its production line on a video call and explain who works on your order.
Check that the company exists
Ask for the business licence, which carries an 18-character Unified Social Credit Code. China’s National Enterprise Credit Information Publicity System at gsxt.gov.cn lets you search for that code to see whether the company is registered, who its legal representative is, and whether it has abnormal operation records. The site is in Chinese with no official English version and can be slow from outside China, so browser translation helps. Two limits matter. A matching code proves that a company exists, not that the person you are talking to works for it. And the English name on a supplier’s profile often differs from its registered Chinese name, so make sure the name on the licence, contract, invoice, and bank account all match.
Order samples before you commit
Pay for samples, test them yourself, and then compare the first production units with the approved sample. Making one good sample is easy. What you want to know is whether the supplier can repeat it.
Document exactly what you want
A supplier can only build what is written down. Send specifications with photos, dimensions, materials, colours, packaging, and tolerances, and confirm every decision in writing, even if you also talk on WeChat or WhatsApp. Ask the supplier to repeat back what they will make.
Warning signs
A price far below every other quote, a refusal to join a video call, pressure to pay quickly, a request to pay a personal account for a company order, or a request to move the payment outside the platform you are using.
The real cost of sourcing from China: MOQs, shipping and duties
The price in the quote is the starting point, not the end. What matters is the landed cost: everything you have paid by the time the goods are in your warehouse.
MOQs
A minimum order quantity (MOQ) is the smallest order a supplier will produce. It varies by product and factory, and custom or private-label work tends to carry higher minimums than catalogue items because the factory has to set up materials and tooling for you. MOQs are often negotiable, especially if you accept a higher unit price, a later delivery date, or a promise of repeat orders. A smaller first order costs more per unit, but it limits your potential losses while you test the supplier and the market.
Shipping
Sea freight costs less per unit and takes longer. Air freight is faster but more expensive, making it suitable for samples and urgent restocks. For sea freight, a full container (FCL) gives you the entire container, while a less-than-container load (LCL) lets smaller orders share space at a higher per-unit cost. Ask every quote to state its Incoterm, which says who pays for what and where responsibility passes to you. Under FOB, the supplier delivers the goods to the port in China, and you pay the freight from that point onward. Under CIF, the supplier also pays freight and insurance to your destination port.
Duties and clearing
Import duty depends on how the product is classified under the Harmonised System (HS) code, and rates differ by product. Check the HS code and the current rate with a licensed clearing agent before you place the order, because a wrong classification can change the bill after the goods arrive. In Nigeria, the goods also need a registered Form M, covered in the section on paying suppliers.
Payment costs
Bank fees and exchange rate margins sit on top. For a thin-margin product, a percentage point or two can decide whether an order is worth repeating.
The numbers below are made up and rounded to show how a quote grows. They are not real prices or rates.
On these made-up figures, a unit quoted at US$4.00 costs US$6.23 once it lands, about 56% more. Work out your own version before you agree a price, and repeat it for each product.
Managing suppliers across time zones and currencies
Time zones
China runs on UTC+8. Lagos is seven hours behind it, and Nairobi is five hours behind it. A supplier’s working day, roughly 9 am to 6 pm in China, runs from about 2 am to 11 am in Lagos, so the useful overlap is the morning. Agree on a fixed weekly call time, and use written updates for everything else, so nothing depends on both of you being online at once.
Milestones, not trust
Split the order into stages and tie each stage to evidence: a confirmed specification and a signed sample; production started, with photos or a video; finished goods before packing; and a pre-shipment inspection. An independent inspection company can check quantity, workmanship, and packaging before you pay the balance. Include these stages in the contract, along with what happens if the goods do not match the sample.
Holidays
Chinese New Year and the National Day holiday in early October can close factories for days or weeks, and orders placed just before them can slip. Build the dates into your plan and place orders early.
One record
Keep one shared order sheet with the product, specification, quantity, price, currency, deposit paid, balance due, and expected dates. When a supplier changes a price or a date, ask for it in writing and update the sheet.
Currencies
Decide the invoice currency at the start. A quote is a snapshot, so ask how long the price is valid. If your local currency weakens between the quote and payment, the same dollar or yuan amount costs more to buy. Where you can, hold or earn the currency you pay in, so a swing in the exchange rate does not change the size of the bill. Splitting a large order into a deposit and a balance paid weeks apart also spreads the exchange rate risk, though it can work in either direction.
How to pay Chinese suppliers from Nigeria and the rest of Africa
There is no single best way to pay a supplier. The right route depends on the size of the order, how well you know the supplier, and what your bank and customs require.
The main ways to pay
What Nigerian importers need to know
In Nigeria, an importer must complete Form M for goods entering the country. GTBank’s guide to Form M calls it a mandatory statutory document for all importers who are registered with an authorised dealer (a bank) when the order is placed, whether or not the transaction requires foreign exchange. It is submitted electronically on the CBN’s Trade Portal, which works with the Nigeria Customs Service. It is valid for 180 days for general merchandise and 365 days for plant and machinery, and the bank can extend it.
The CBN’s foreign exchange manual, issued in May 2026, adds a second deadline. Coverage of it says importers must submit exchange control documents within 90 days of negotiating shipping documents with overseas correspondent banks, and that importers who do not can be barred from foreign exchange transactions, including Form M processing, for periods that lengthen with repeat offences. Keep every invoice, contract, and shipping document organised so you can produce them when needed.
Before you pay, ask your bank how it wants the Form M and supporting documents handled for your route, and whether payments made through a payment provider fit its documentation requirements. Rules change, so confirm the current position with your bank or the CBN, not from a blog.
Protect the payment itself
- Pay only to an account in the supplier’s registered company name, as shown on the contract and invoice.
- Confirm bank details by a second channel, such as a video call, before the first payment and whenever they change. A change of account details sent by email is a common fraud.
- Size the deposit to what you can afford to lose on a first order, and tie the balance to the inspection result.
- Get the invoice in writing, with the currency, amount, and bank details.
Comparing what you pay
Quotes are hard to compare because the cost is split between a fee and an exchange rate. To compare them, divide the total naira you pay by the amount the supplier receives, then compare the resulting rate with the mid-market rate for the same day. The gap, plus any fee, is the real cost of the transfer. Do the same for each route, and ask the supplier whether the price changes depending on whether you pay in dollars or yuan.
Paying with Grey
Grey recently launched payouts to China, giving Nigerian importers another option.
- The supplier receives yuan in their own Chinese bank account with ICBC, Bank of China, China Construction Bank, or Agricultural Bank of China and does not need a Grey account.
- Before you confirm, Grey shows the rate and the fee as two separate numbers, and the yuan amount your recipient receives does not change after you confirm.
- The account name you enter must match the account name on the supplier’s invoice, so copy it from there.
Grey charges a flat fee of $2.80 per bank transfer, with a limit of 50 to 21,000 yuan per transfer. Transfers are typically completed within 24 hours on banking days, with a 10:00 GMT cut-off; transfers made after this time may take longer. A limit of 21,000 yuan per transfer means a large factory deposit may need to be split into several transfers or paid another way, so check the limit shown in the app for your route before relying on it.
To hold US dollars and convert them when you need to pay, see Grey's foreign accounts. For small-order samples on platforms that accept cards, a virtual card is another option, though payments on non-US websites may incur a cross-border fee. If you pay several suppliers, Grey also offers a business account for cross-border trade with bulk payouts and payment status tracking. Check whether it is available in your country first.
Grey is a financial technology company, not a bank, and works with CBN-licensed banking partners in Nigeria. Its US services are regulated by FinCEN and its Canadian services by FINTRAC.
Frequently asked questions
How do African businesses pay Chinese suppliers?
Most pay through international bank transfer in US dollars or yuan, often with a deposit before production and the balance before shipment. Other routes include platform payments with escrow, letters of credit, and yuan payouts through payment providers. The right choice depends on the order size, the supplier, and your bank’s requirements.
Do they need a Form M to import from China into Nigeria?
Yes. GTBank’s guide describes Form M as a mandatory statutory document for all importers, which must be registered with a bank when the order is placed, whether or not the transaction requires foreign exchange. Confirm the current process with your bank.
Is it better to pay a Chinese supplier in dollars or yuan?
Neither is better by default. Ask the supplier for the price in both currencies, then compare the total you pay in your local currency, including fees and the exchange rate, against the mid-market rate on the day.
How can I check that a Chinese supplier is real?
Ask for the business licence and search its Unified Social Credit Code on China’s National Enterprise Credit Information Publicity System. Make sure the name on the licence, contract, invoice, and bank account match; order samples first; and join a video call before you pay a deposit.
Can I pay a supplier in China with Grey from Nigeria?
Grey offers payouts to Chinese bank accounts, delivered in yuan, from a naira top-up or a USD balance. The recipient does not need a Grey account. Check the fee, rate, and limit shown in the app before you confirm, as per-transfer limits apply.
Does China’s zero-tariff policy make imports from China cheaper?
No. The policy, in force from 1 May 2026, covers goods entering China from 53 African countries. It helps African exporters without changing what importers pay for Chinese goods.
How much deposit should I pay a new supplier?
Terms are negotiable, and a deposit before production, with the balance due before shipment, is a common pattern. For a first order, pay only what you can afford to lose, use platform protection where available, and tie the balance to an inspection result. This is general guidance, not financial advice.
Paying a supplier in China? See the rate and fee before you send.
Fees and rates: Grey's CNY payout post lists a flat fee of $2.80 per bank transfer and a limit of 21,000 yuan per transfer. Currency conversion is listed at 1% (capped at $6) on USD, GBP, and EUR transfers, so check the fee shown in the app for your route. A virtual card costs $5 to create once, with no monthly fee, and payments on non-US websites may incur a cross-border fee of 2% plus $0.50. Exchange rates vary with a margin over the mid-market rate, and delivery times depend on the bank, the route, and cut-off times.
Single-member LLC: How it works and how to set one up
A single member LLC gives one owner liability protection with pass-through tax. Learn how it works and the five steps to form one. Get started today.
Olayoyin Olorunmota
•
November 1, 2026
•
6 min read
A client’s accounts team emails you: before they can pay the next invoice, they need your business name and an EIN. Until now, you’ve invoiced under your own name, and a friend has told you a single-member LLC (sometimes called a single-member LLC) will sort it all out. It gives you a separate legal entity, but it won’t change how you pay tax unless you ask it to. This guide explains what the structure does, how it’s taxed, and the five steps to set one up.
A single-member LLC is a limited liability company with one owner. It limits your personal liability for business debts and, by default, is taxed as a disregarded entity, so profits pass through to your personal tax return. You set one up by filing formation documents with your state and getting an EIN.
What is a single-member LLC?
A single-member LLC is a limited liability company with exactly one owner, called the member, who owns the business and keeps its profits. You create it by filing with a US state, and the state treats the LLC as a legal entity that is separate from you. The member can be an individual or another company.
People also search for this structure as a single-member LLC. It’s the same thing: the name only describes how many owners the company has. Freelancers, consultants, online sellers, and solo founders use it because it adds a legal layer between the owner and the business without the paperwork required for a corporation.
That legal layer is the main reason to form one. An LLC generally limits your personal liability for the business’s debts, so a creditor of the company can normally go after what the company owns, not your home or savings. The protection has limits:
- It can be undone if you mix personal and business money, so keep a separate business bank account.
- It doesn’t cover debts you’ve personally guaranteed, such as a loan or a lease you signed in your own name.
- It doesn’t shield you from liability for your own wrongdoing.
A sole proprietor has no such separation, because the owner and the business are legally the same person. If you’re weighing the two, LLC vs sole proprietorship compares them side by side.
Owners don’t need to live in the US. A non-resident can own a US LLC, which is why many freelancers abroad form one to invoice American clients. The tax and reporting rules for them differ, and the FAQ below covers the basics.
How a single-member LLC is taxed
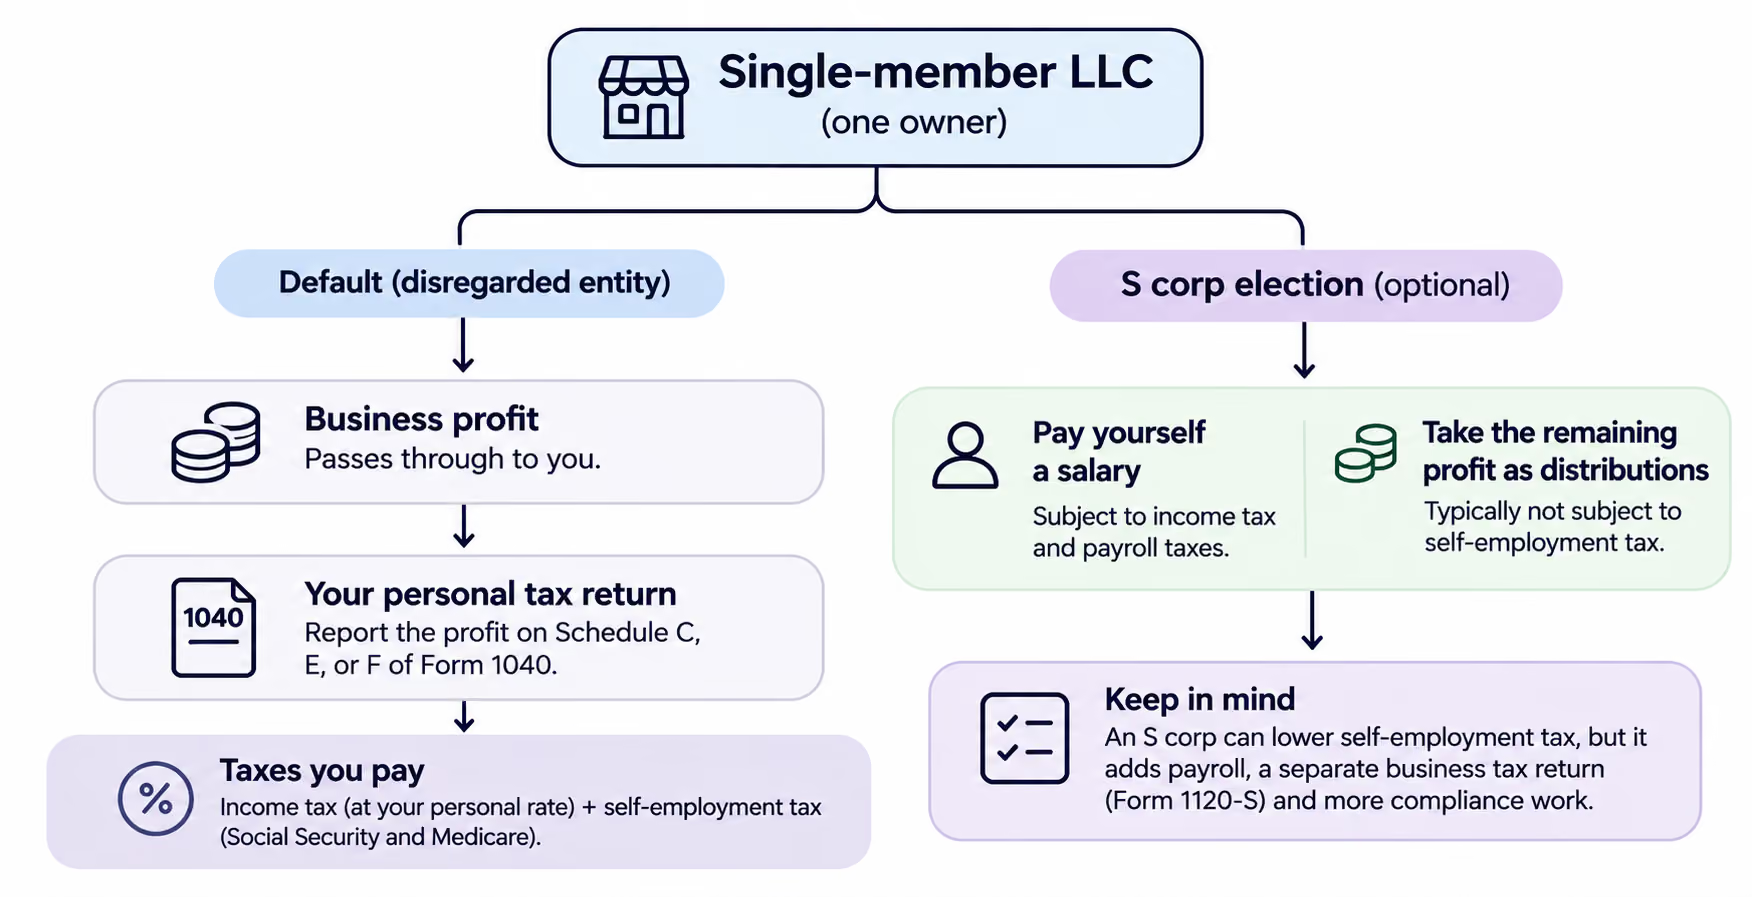
By default, the IRS treats a single-member LLC as a disregarded entity: it ignores the LLC for income tax and taxes the profit as your own. The LLC doesn’t file a federal income tax return of its own. Per IRS guidance on single-member LLCs, an individual owner reports the business on Schedule C, E, or F of Form 1040, depending on the type of income.
This is what “pass-through” means: the profit passes through the LLC to your personal return and is taxed there, at your personal rate, with no separate tax at the company level.
Self-employment tax
An individual owner also pays self-employment tax on the LLC’s net earnings, the same as a sole proprietor. This is the tax that funds Social Security and Medicare for people who don’t have an employer paying into them, and it’s charged on top of income tax. It’s the part of the bill that the options below can change.
Forms your clients may send
If you’re paid for services by US clients, they may send you a Form 1099-NEC at the end of the year. The 1099 form for contractors records what a client paid you, and it’s a reporting document, not a bill. You report all your business income whether or not a client sends you one, so keep your own invoices and bank records.
Taxed as a corporation or an S corp
A single-member LLC isn’t locked into the default. You can file Form 8832 to elect to be taxed as a corporation, and you can also elect S corporation status. An S corp election can lower self-employment tax because you pay yourself a salary and take the remaining profit as distributions, but it adds payroll, a separate business tax return and more compliance work. S corp vs LLC covers when the switch is worth considering.
One exception applies even to a disregarded LLC. For employment and excise taxes, the IRS treats the LLC as a separate entity, so an LLC with employees reports payroll under its own name and EIN.
This is general guidance, not professional tax advice. Consult a certified tax professional for your specific situation.
How to set up a single-member LLC step by step
You set up a single-member LLC in five steps: choose a name, appoint a registered agent, file formation documents with your state, get an EIN, and open a business bank account. The SBA’s guide to registering a business sets out the same sequence. The details vary by state, so check your state’s Secretary of State or business agency website before you file.
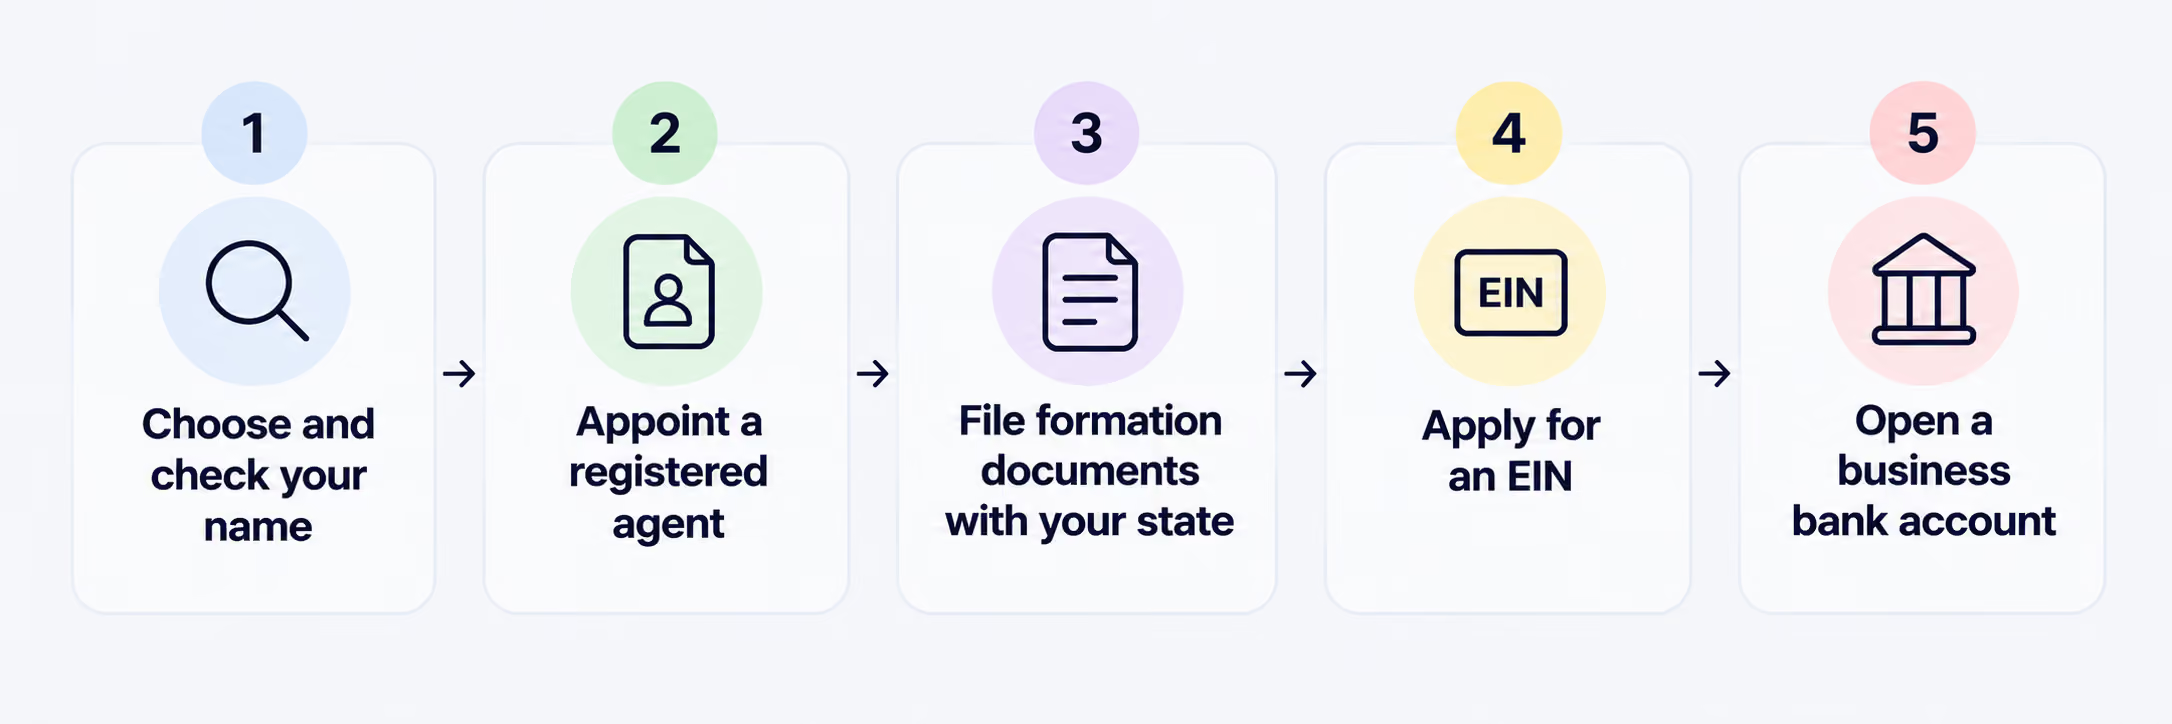
- Choose and check your name: State registration protects your entity name at the state level, and most states won’t let you register a name another business already holds. Search your state’s business register before you commit to one, and check that the matching domain is free.
- Appoint a registered agent: This is the person or service that receives official papers and legal notices for the LLC, and the agent must have an address in the state where the LLC is registered. Many owners pay a registered agent service rather than use their own address.
- File your formation documents: For an LLC, these are usually called the articles of organisation. Most states take them through the Secretary of State or a business agency, some online and some by post. The SBA usually puts the total cost under $300, though fees vary by state. An operating agreement is widely recommended even where your state doesn’t require one: it records how the LLC is run, and for a single owner, it also helps show the LLC is genuinely separate from you.
- Apply for an EIN: An EIN is the IRS’s nine-digit number for your business. Applying is free through the IRS, so avoid any site that charges for it. The IRS says most new single-member LLCs need one, and you’ll need one for employees, for excise taxes, or to open a bank account.
- Open a business bank account: Keep the LLC’s money separate from yours from day one. Banks usually ask for your formation documents and EIN, and a separate account is the simplest way to protect the liability separation described earlier.
After you register, check whether your state wants anything further. Some states require an initial report within 30 to 90 days of registering, and some require a state tax ID depending on their income and employment tax rules. If you operate in more than one state, you may need to register as a foreign LLC in each of them, even if you’re a US resident. That’s a state-law term, not a reference to where you live.
Pros and cons of a single-member LLC
A single-member LLC is worth it when the liability protection and client credibility matter more to you than the added cost and admin, and it’s not worth it if you earn little and have no business debts to protect against. This table weighs each factor from both sides.
The pattern is that the protection and the credibility come with a fixed cost and a regular admin routine. If you’re a freelancer with few assets and a single client, a sole proprietorship may be enough until your income or your risk grows. If you sign contracts, hold stock, employ people or work with larger clients, the case for an LLC gets stronger.
Getting paid as a single-member LLC
Once the LLC and its bank account exist, the next question is how clients pay it. US clients usually pay by bank transfer into a US account, while overseas clients may need to pay in euros or pounds. If your clients are spread across currencies, or you run the LLC from outside the US, a business account that holds several currencies can save you from collecting each payment through a separate route.
You can open a Grey Business account for your LLC to hold USD, EUR and GBP in one place. Grey is a financial technology company, not a bank: banking services are provided by licensed banking partners. Its invoicing tool is free, lets you send an invoice by email or download it as a PDF, and automatically fills in your Grey account details, so a client can pay in the currency they’re sending.
If your clients are in the US, get paid from the US covers how to receive money from the US. If your LLC pays contractors or relatives in India, you can also send money from the US to India. Whichever route you use, keep the business’s income in the business account and pay yourself from it, so your records stay clear for tax time.
Before you move money, check three costs: the fee charged when money arrives, the fee for converting between currencies, and the exchange-rate margin. The margin is built into the rate rather than shown as a line item, so Grey states it up front in the app before you confirm a transaction.
Frequently asked questions
What is a single-member LLC?
A single-member LLC is a limited liability company with one owner. It's a legal entity separate from you that limits your personal liability for business debts, and by default, the IRS ignores it for income tax and taxes the profit on your personal return.
How is a single-member LLC taxed?
By default, it’s taxed as a disregarded entity, so you report the profit on your own return, usually on Schedule C, and pay self-employment tax on net earnings. You can instead elect corporate or S corporation treatment, which changes how profits and salaries are taxed and adds payroll and filing requirements.
Do I need an EIN for a single-member LLC?
Usually, yes. The IRS says most new single-member LLCs need an EIN, and you need one if you have employees or excise tax liability. You’ll also use it to open a business bank account.
How do I set up a single-member LLC?
Choose a name, appoint a registered agent, file your formation documents with your state, apply for an EIN, and open a business bank account. State fees vary, and the SBA usually puts the total cost under $300.
Does a single-member LLC protect my personal assets?
Generally, yes: it limits your personal liability for the LLC’s debts, so creditors of the business normally can’t reach your own property. It doesn’t protect debts you’ve personally guaranteed, and the protection can be lost if you mix personal and business money.
Can a non-resident own a single-member LLC?
Yes, a non-resident can own a US LLC. If you have no US address, the IRS’s online EIN application isn’t available to you, so you apply by phone, fax or post using Form SS-4, and the IRS instructions for Form SS-4 explain how to complete it without an SSN or ITIN. A foreign-owned single-member LLC may also have to file Form 5472 each year, so take advice from a certified tax professional before you form one.
How to verify a company EIN number: Free lookup methods
Need an employer identification number lookup? Here are five free ways to verify a company EIN, plus how to find your own if it is lost. Check it now.
Tunde Aladeloba
•
October 25, 2026
•
6 min read
An Employer Identification Number (EIN) is a nine-digit number the IRS assigns to businesses for tax reporting and identification. If you work with a new supplier, verify a company’s tax details, or prepare business documents, you may need to confirm that its EIN is valid.
However, finding a company’s EIN is not always straightforward. The IRS does not provide a public database where anyone can search for any business’s EIN. Your options depend on the type of company and your reason for checking its details.
Fortunately, there are several free methods you can use. You can request a signed Form W-9 directly from the business, search SEC EDGAR filings for publicly traded companies, or use the IRS Tax Exempt Organization Search to find eligible nonprofits. If you file information returns, the IRS TIN Matching service may also help you verify taxpayer identification details.
This guide explains how to complete an employer identification number lookup using these methods, what information you can access, and when each option is appropriate.
Can you look up any company's EIN?
No, you can't look up every company's Employer Identification Number (EIN) through a single public database. The IRS does not provide a public search tool that reveals the EIN of every registered business. This restriction helps protect business tax information from unauthorised access and misuse.
However, some EINs are publicly available. For example, you can find tax identification details in certain public company filings on SEC EDGAR or search for eligible nonprofits through the IRS Tax Exempt Organization Search.
Who can verify a company's EIN depends on the situation. Business owners can confirm their EIN through IRS notices and tax records. Banks, employers, and other authorised organisations may verify taxpayer identification details when permitted and necessary for their responsibilities. Businesses can also request a completed Form W-9 from vendors or contractors to confirm the information provided for tax reporting.
If you need to verify an EIN, start by asking the company directly or checking the relevant public records. The appropriate method depends on the company's status and your reason for verification.
Five free ways to verify a company EIN
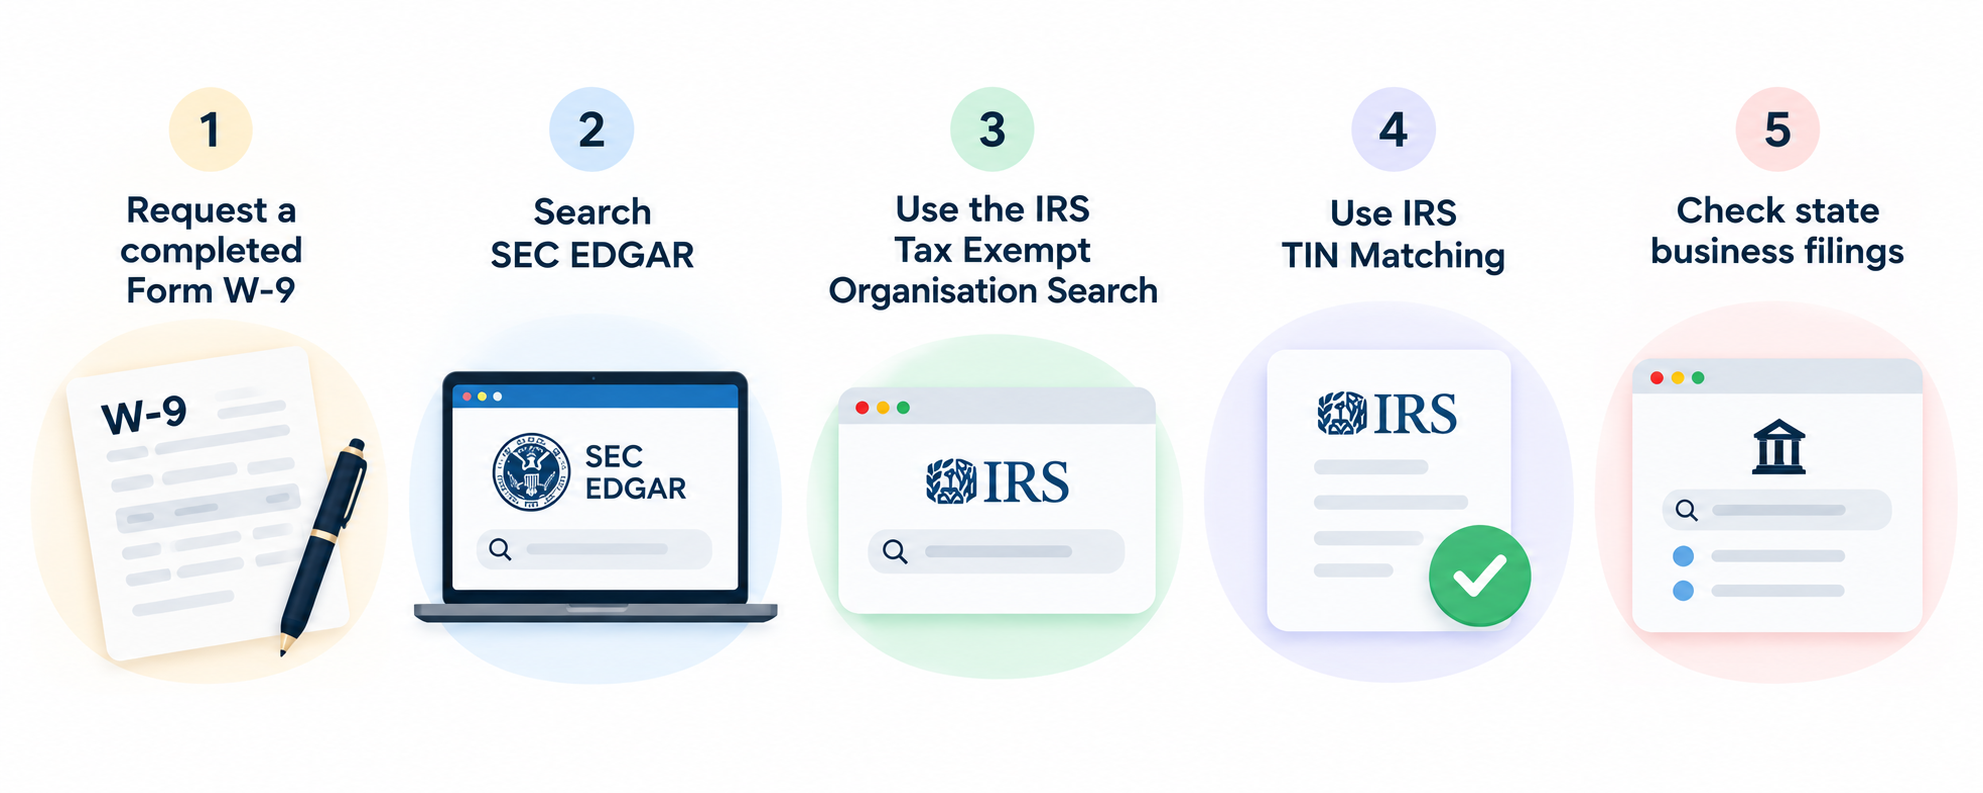
1. Request a completed Form W-9
Ask the company to provide a signed Form W-9 containing its legal business name and taxpayer identification number. This is one of the simplest ways to obtain an EIN for vendor payments and tax reporting. Compare the details with your business records before proceeding.
2. Search SEC EDGAR
Publicly traded companies may disclose their EINs in regulatory filings. Visit SEC EDGAR and search for the company's name. Review relevant filings, such as annual reports, for available tax identification details. Not every filing includes an EIN.
3. Use the IRS Tax Exempt Organisation Search
If the company is a nonprofit, use the IRS Tax Exempt Organisation Search to find eligible organisations and review their publicly available tax records. This tool is not designed to look up every for-profit business.
4. Use IRS TIN Matching
Businesses authorised to use IRS TIN Matching can check taxpayer identification information against IRS records for eligible payees when filing information returns. This service is restricted to qualifying payers and cannot be used for unrestricted public searches.
5. Check state business filings
Visit the relevant state's official business registry to search for the company's registration details. Some filings may include federal tax identification information, but many do not. Start with the state's official government website, as access and available records vary by state.
Also read: How to complete a W-8BEN form as a non-US resident
How to find your own EIN
If you have misplaced your Employer Identification Number (EIN), you do not need to apply for a new one immediately. There are several ways to recover your existing number, depending on the records you have and whether you have previously used it for business activities.
1. Check your CP 575 confirmation letter. When the IRS assigns your EIN, it sends a confirmation notice called CP 575. Check your business files, emails, or saved documents for this letter, which contains your EIN.
2. Review previous tax returns. Look at your federal business tax returns and other tax documents. Your EIN is typically listed near the top of the relevant forms.
3. Contact your bank. If you used your EIN when opening a business account, your bank may have it on file. Contact your bank and ask how to retrieve your business tax identification details. If you are still setting up your finances, learn how to open a business bank account to understand the documents you may need.
4. Call the IRS. Contact the IRS Business and Specialty Tax Line at 800-829-4933, Monday through Friday, 7 a.m. to 7 p.m. local time. After verifying your identity and authorisation, an IRS representative can help you recover your EIN.
Paying verified vendors and contractors abroad
Paying an overseas contractor involves more than sending money. You also need the right tax documents and a reliable way to deliver their payment. For foreign individuals working outside the US, request Form W-8BEN when applicable to document their foreign status for US tax purposes. Foreign entities may need Form W-8BEN-E instead.
Once you have verified the contractor's details and confirmed the appropriate tax documentation, you can arrange payment. For example, if your LLC hires a developer in the Philippines, you can use Grey to send money from the US to the Philippines and pay them through a supported transfer method.
If you also hire US-based independent contractors, understanding what a 1099 employee is can help you distinguish contractors from employees and understand your reporting responsibilities. The term “1099 employee” is informal; independent contractors are generally not classified as employees for tax reporting.
For businesses managing multiple international payments, you can open a Grey Business account to pay vendors and contractors across borders.
Frequently asked questions about a company EIN number
1. Is there a free EIN lookup?
Yes, you can find some company EINs for free through public records. Try SEC EDGAR for publicly traded companies or the IRS Tax Exempt Organisation Search for eligible nonprofits. However, there is no single public IRS database that lists every company's EIN.
2. How do I verify an EIN with the IRS?
If you are an eligible payer filing information returns, you can use the IRS TIN Matching service to check taxpayer identification details. Business owners who have lost their EIN can contact the IRS Business and Specialty Tax Line for assistance after verifying their identity.
3. Can I find a company's EIN online?
Sometimes. Public company filings, nonprofit tax records, and certain business documents may disclose an EIN. Search official sources such as SEC EDGAR or the IRS Tax Exempt Organisation Search. If the number is not publicly available, ask the company directly for a completed Form W-9.
4. How do I find my own EIN?
Check your IRS CP 575 confirmation letter, previous business tax returns, or bank records. If you cannot locate your number, contact the IRS Business and Specialty Tax Line at 800-829-4933. After verifying your identity and authorisation, an IRS representative can help you recover it.
5. Is an EIN public information?
An EIN is not universally public information. Some businesses disclose it in public filings, while other companies' EINs may not be readily available. Although you can access certain tax identification details through official records, the IRS does not provide unrestricted public access to every business's EIN.
6. Is an FEIN the same as an EIN?
Yes, an FEIN (Federal Employer Identification Number) generally refers to the same nine-digit federal tax identification number as an EIN. Businesses use this number for tax reporting, banking, hiring employees, and other official purposes. The term FEIN simply emphasises that the identification number is federal rather than state-issued.
11 best business bank accounts to have in the US
Compare the best business bank accounts in the US on fees, minimums and tools. All 11 ranked with the trade-offs named. Open the right one today.
Tunde Aladeloba
•
October 23, 2026
•
6 min read
Choosing the right business account in the US can make a real difference in how you manage your company’s money, from receiving customer payments to paying suppliers and tracking everyday expenses. However, with so many banks and financial platforms offering different account types, fees and features, knowing which one fits your business can be difficult.
The best business bank accounts pair low or waivable monthly fees with strong online banking, cards and integrations. The right one depends on your size, transaction volume and whether you handle international payments. Compare fees, minimums and features side by side before opening one.
For example, a freelancer receiving occasional payments may prioritise low fees and simple digital banking, while a growing company may need higher transaction limits, cash deposit options and tools for managing payroll. If you work with international clients or suppliers, access to cross-border payments and multiple currencies may also influence your decision.
This guide compares 11 business bank accounts available in the US, highlighting their fees, minimum balance requirements, key features and suitability to help you choose an account that works for your business.
Also read: Best business bank accounts for an LLC
How to choose a business bank account
Choosing a business bank account starts with understanding how your business earns, spends and manages money. The right account should support your daily operations without adding unnecessary costs or making payments difficult to track.
Fees and charges: Compare monthly maintenance fees, transaction limits, cash deposit charges, wire transfer costs and ATM fees. An account advertised as free may still charge for certain services.
Minimum balance requirements: Check the opening deposit and ongoing balance requirements. If your cash flow fluctuates, choose an account with no minimum balance or an achievable fee waiver.
Banking tools: Look for reliable online banking, mobile cheque deposits, debit cards, accounting software integrations and payment processing. Growing businesses may also benefit from payroll support and cash management tools.
Access and eligibility: Confirm that your business structure qualifies, whether you can apply online and which documents you need. Some providers require a US address, while others have additional residency restrictions.
If you receive international payments, compare foreign exchange rates, supported currencies and transfer fees before deciding. Your account should fit your current needs while leaving room for your business to grow.
11 best business bank accounts in the US
The following comparison ranks 11 business banking options by monthly fees, key features, limitations and suitability, helping you identify the right fit for your company's size, cash flow and banking needs.
| Rank | Bank / Platform | Monthly Fees and waivers | Core pros | Core cons | Best for |
|---|---|---|---|---|---|
| 1 | Chase Business Complete Banking | $15; waivable with qualifying balances or activity | Card processing, extensive branch network, credit card options | Wire fees, cash deposit limits, no interest | Storefronts needing branch access |
| 2 | Mercury | $0 standard tier; paid plans available | Digital tools, wire transfers, API integrations | No physical cash handling, premium features cost extra | Tech startups and online businesses |
| 3 | Bluevine | $0 Standard plan; paid tiers available | Interest potential, sub-accounts, accounting integrations | Conditions for earning interest, wire fees | Online businesses prioritising interest |
| 4 | U.S. Bank Business Essentials | $0 monthly fee | Branch access, no ongoing maintenance fee | Transaction limits, credit approval requirements | Small retailers |
| 5 | Bank of America Business Advantage | $16; waivable with qualifying balance | Rewards programme, national network, credit integration | Balance requirements, potential extra fees | Established businesses |
| 6 | American Express Business Checking | $0 monthly fee | Interest potential, Membership Rewards, support | No cash deposits, limited branch access | Existing Amex customers |
| 7 | Relay | $0 basic plan; Pro costs extra | Multiple sub-accounts, team access, bill management | Some tools require paid plan, ATM fees | Growing teams and agencies |
| 8 | Novo | $0 monthly fee | Invoicing tools, ATM fee refunds, online dashboard | No built-in interest, limited user controls | Freelancers and sole proprietors |
| 9 | Wells Fargo Navigate Business Checking | Tiered fees; waivers may apply | Branch network, cash handling, lending services | Fees and service costs vary | Cash-heavy businesses |
| 10 | Found | $0 base tier; paid Plus plan | Tax tracking, receipt capture, invoicing | Limited international features, fewer team tools | Sole proprietors and independent contractors |
| 11 | Rho | $0 platform fee; service eligibility applies | Corporate cards, expense controls, accounts payable | US business eligibility restrictions, credit criteria | Established companies managing expenses |
Traditional banks vs. online providers for your LLC
When choosing a business bank account for your LLC, consider how you receive payments, manage expenses, and access your money. Traditional banks and online providers offer different benefits, so the right choice depends on how your business operates.
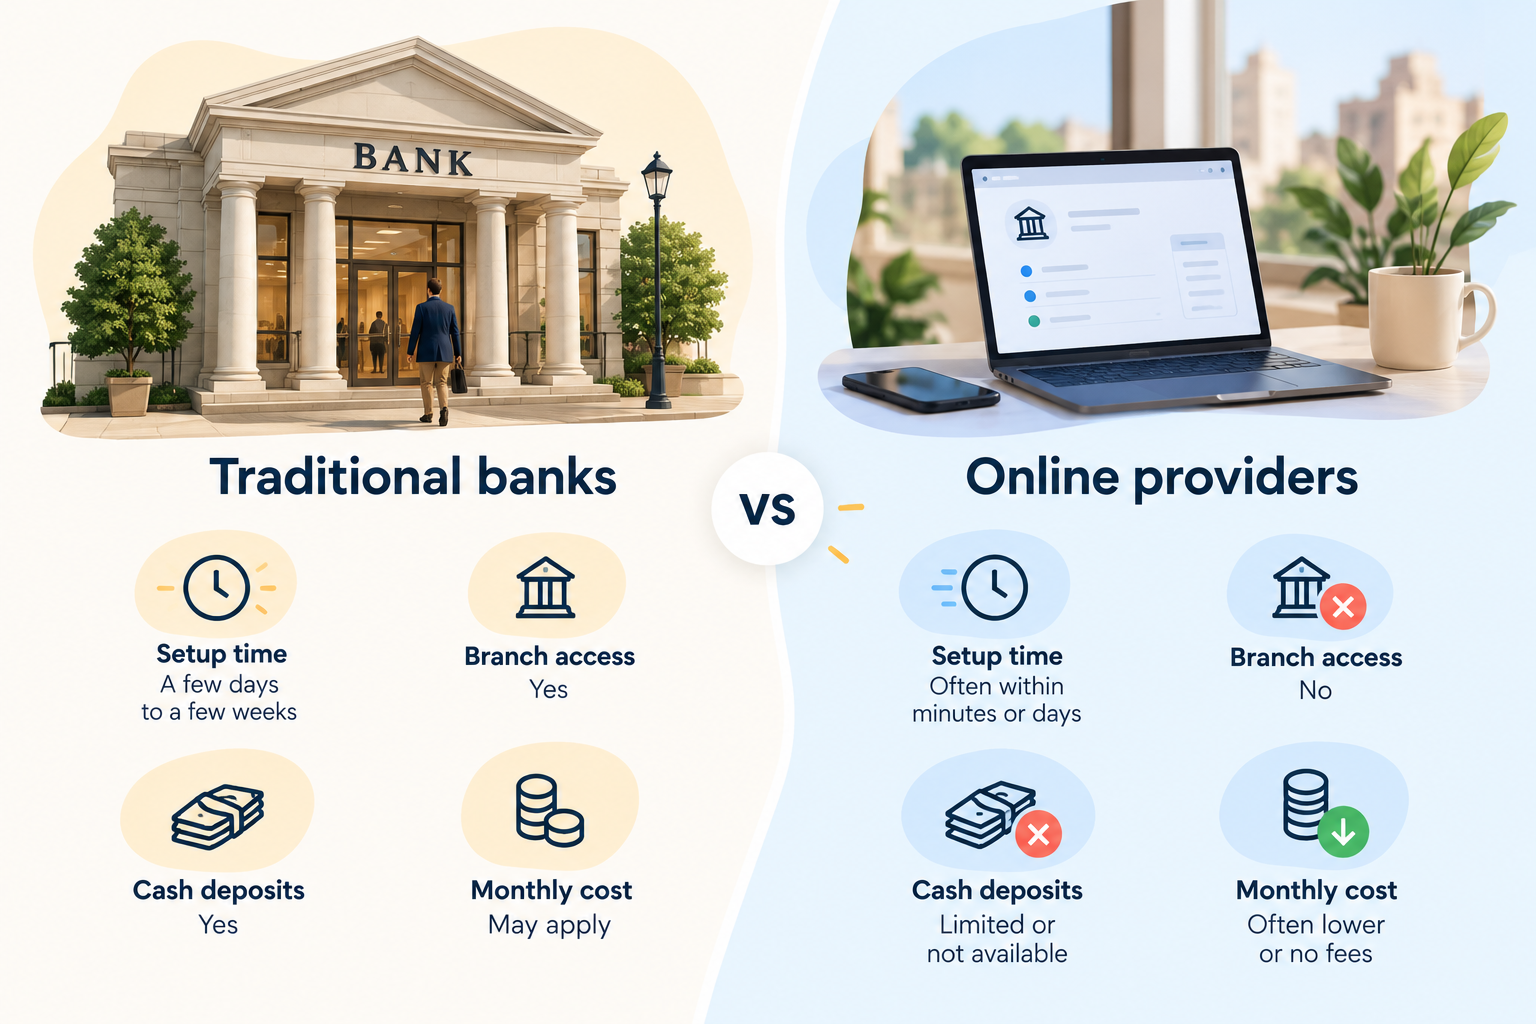
Traditional banks such as Chase, Bank of America, and U.S. Bank give you access to physical branches. You can deposit cash, speak with bank staff, and look into business loans or other financial services. However, some accounts charge monthly maintenance fees unless you meet specific requirements. For one example, see the PNC business account fees and features.
Online providers such as Bluevine, Mercury, Relay, and Grey let you manage your finances digitally. While Bluevine, Mercury, and Relay offer business banking tools, Grey supports cross-border payments, making it useful for businesses that send or receive money internationally. Online providers may offer lower fees, faster account setup, and convenient payment management. However, cash deposits and in-person support may be limited.
Before you decide, compare monthly fees, transaction limits, deposit options, and eligibility requirements. If you need branch access, a traditional bank may suit you better. If you value convenience and digital payments, an online provider may be the better fit.
Also read: Can non-residents open a US bank account online in 2026?
Adding international payments
Opening an LLC in the US can help you establish your business, but what happens when your customers, suppliers, or team are in different countries? You need a simple way to move money across borders without disrupting your day-to-day operations.
That is where Grey comes in. With Grey, you can send and receive money from the US to support international business transactions, whether you are collecting payments from clients or paying partners overseas. Instead of relying on your traditional business bank account for every cross-border transaction, you can add a dedicated payment solution to your setup.
To get started, open a Grey Business account and see which options suit your business.
Frequently asked questions about the best business bank accounts to have in the US
What is the best business bank account for an LLC?
The best business bank account depends on your LLC’s needs. Chase and Bank of America offer branch access, while Bluevine, Mercury, and Relay provide digital banking tools. Compare fees, transaction limits, payment options, and eligibility requirements to find an account that suits your business.
Which business bank account has the lowest fees?
Online providers such as Bluevine, Mercury, and Relay offer business accounts with no monthly maintenance fees on certain plans. However, other charges may apply for specific transactions or services. Compare each provider’s fee schedule and account requirements before making your decision.
Can I open a business bank account online?
Yes, many banks and online providers let you apply for a business bank account online. You will typically need your LLC formation documents, identification, and business details. Approval times and requirements vary by provider, so check the application process before applying.
Do I need an EIN to open a business bank account?
Many banks require an Employer Identification Number (EIN) to open an LLC business account. Some single-member LLCs may qualify to use other tax identification details, depending on the bank’s policies. Check the provider’s requirements and obtain an EIN from the IRS if needed.
What about international payments for my LLC?
If your LLC works with overseas clients or suppliers, look for accounts that support international transfers and multiple currencies. Grey can complement your business banking setup by helping you send and receive money from the US. Compare transfer fees, exchange rates, supported currencies, and eligibility before choosing a provider.
Are online business accounts safe?
Online business accounts can offer strong security features, including encryption, multi-factor authentication, and transaction monitoring. However, protections vary by provider. Check whether deposits are held at an FDIC-insured bank, understand applicable coverage limits, and review the provider’s security policies before opening an account.
PNC business account: Fees, features and how to open
The PNC Bank business account explained: checking tiers, monthly fees and how to open one. Grey adds the cross-border layer on top. Compare your options.
Tunde Aladeloba
•
October 23, 2026
•
6 min read
Choosing the right business bank account can make it easier to manage daily expenses, receive customer payments and keep your business finances organised. However, monthly maintenance fees, transaction limits and minimum balance requirements can affect how much you pay for banking services. If you are considering a PNC Bank business account, understanding these costs and features can help you decide whether it suits your business needs.
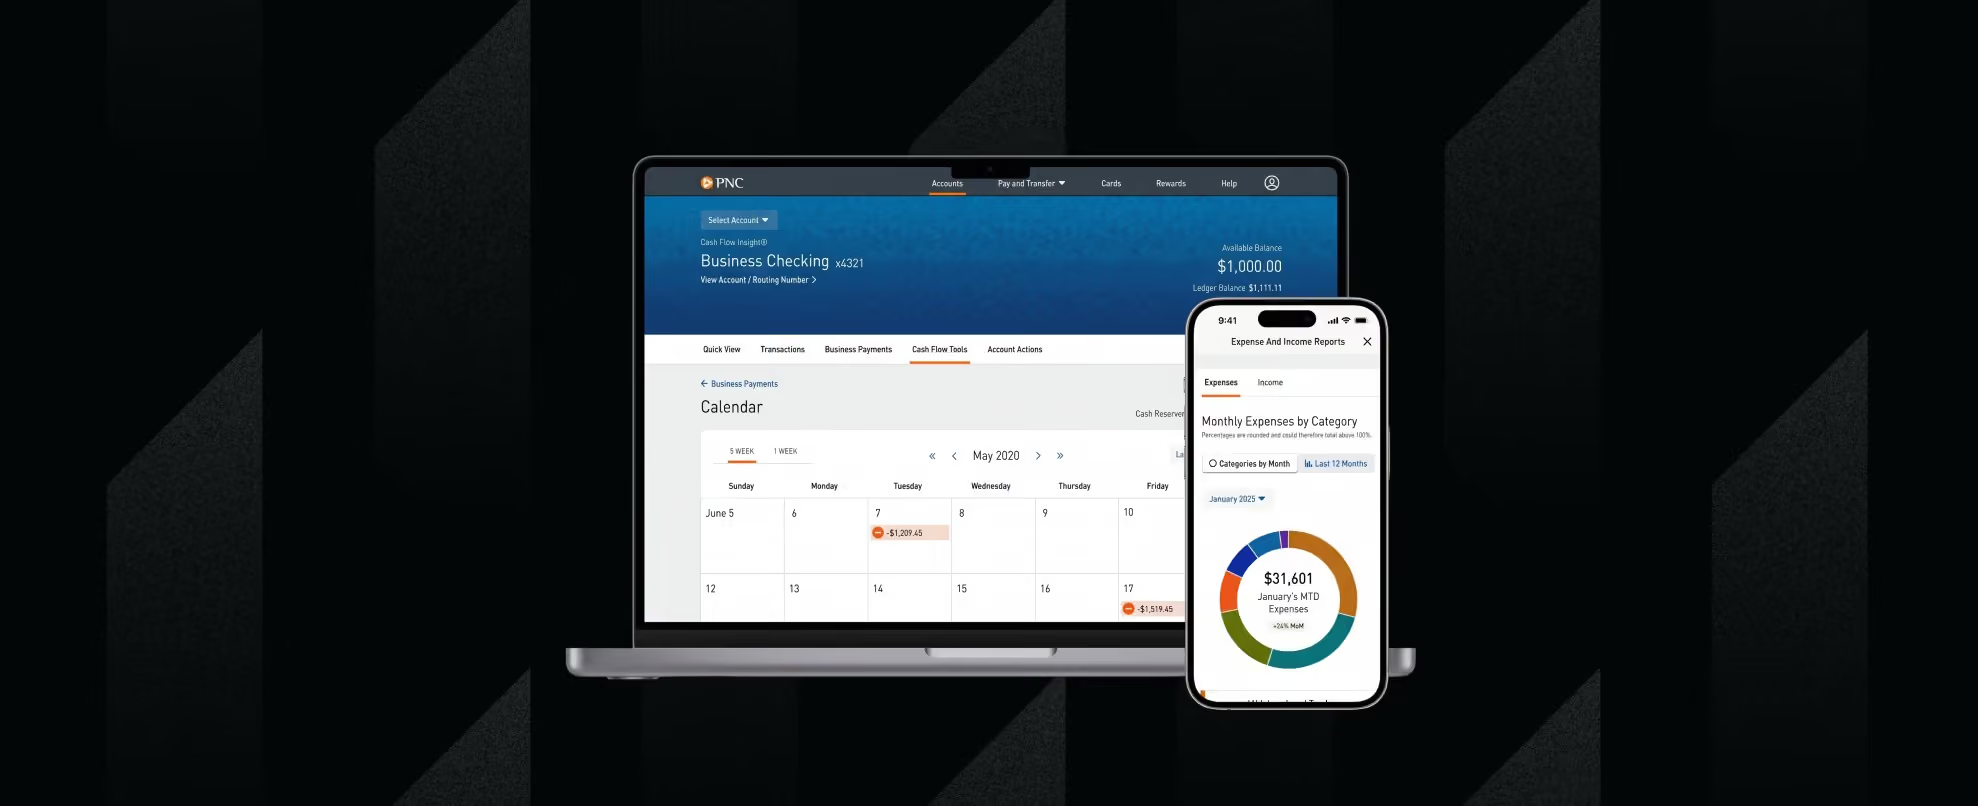
PNC offers several business checking accounts designed for businesses with different transaction volumes and banking needs. Each account comes with its own fee structure, transaction allowances and requirements for waiving monthly maintenance fees. Depending on the account you choose, maintaining a qualifying balance may help you avoid these charges.
Opening an account is also relatively straightforward, with options to apply online or visit a branch. You will generally need your employer identification number (EIN), business formation documents and valid identification. This guide covers PNC business account fees, key features, eligibility requirements and how to open an account, helping you understand what to expect before applying.
Also read: Best business bank accounts for an LLC
PNC Business account options: which checking tier fits your business?
PNC offers several business checking options designed for different transaction volumes, cash handling needs and business sizes. Choosing the right tier depends on your monthly activity, available balance and financial management needs.
Business Checking: Best for freelancers, sole proprietors and micro-businesses with fewer transactions. Its $500 balance waiver threshold can help eligible account holders avoid the monthly maintenance fee.
Business Checking Plus: Suits local retailers, storefronts and growing businesses that handle more payments. It accommodates up to 500 monthly items and $10,000 in cash deposits before additional charges may apply.
Treasury Enterprise: Designed for businesses managing multiple entities or accounts. It allows up to four linked accounts to qualify toward a combined $30,000 balance requirement.
Analysis: Best suited to large enterprises with substantial cash flows. Earnings Credits can help offset eligible account service charges, making it worth considering for businesses with complex treasury management needs.
PNC business checking line-up (2026)
| Account tier | Monthly fee / waiver minimum |
Free transactions | Free cash deposits | Ideal for |
|---|---|---|---|---|
| Business Checking | $12 / $500 balance | 150/month | $5,000/month | Freelancers, side hustles and startups |
| Business Checking Plus | $22 / $5,000 balance | 500/month | $10,000/month | Growing businesses and local retailers |
| Treasury Enterprise Plan | $50 / $30,000 combined balance | Unlimited across linked accounts | $50,000/month | Established mid-sized businesses |
| Analysis Business Checking | Variable / Earnings Credit | Custom | Custom | Large enterprises with complex cash flows |
PNC business account fees and how to avoid them
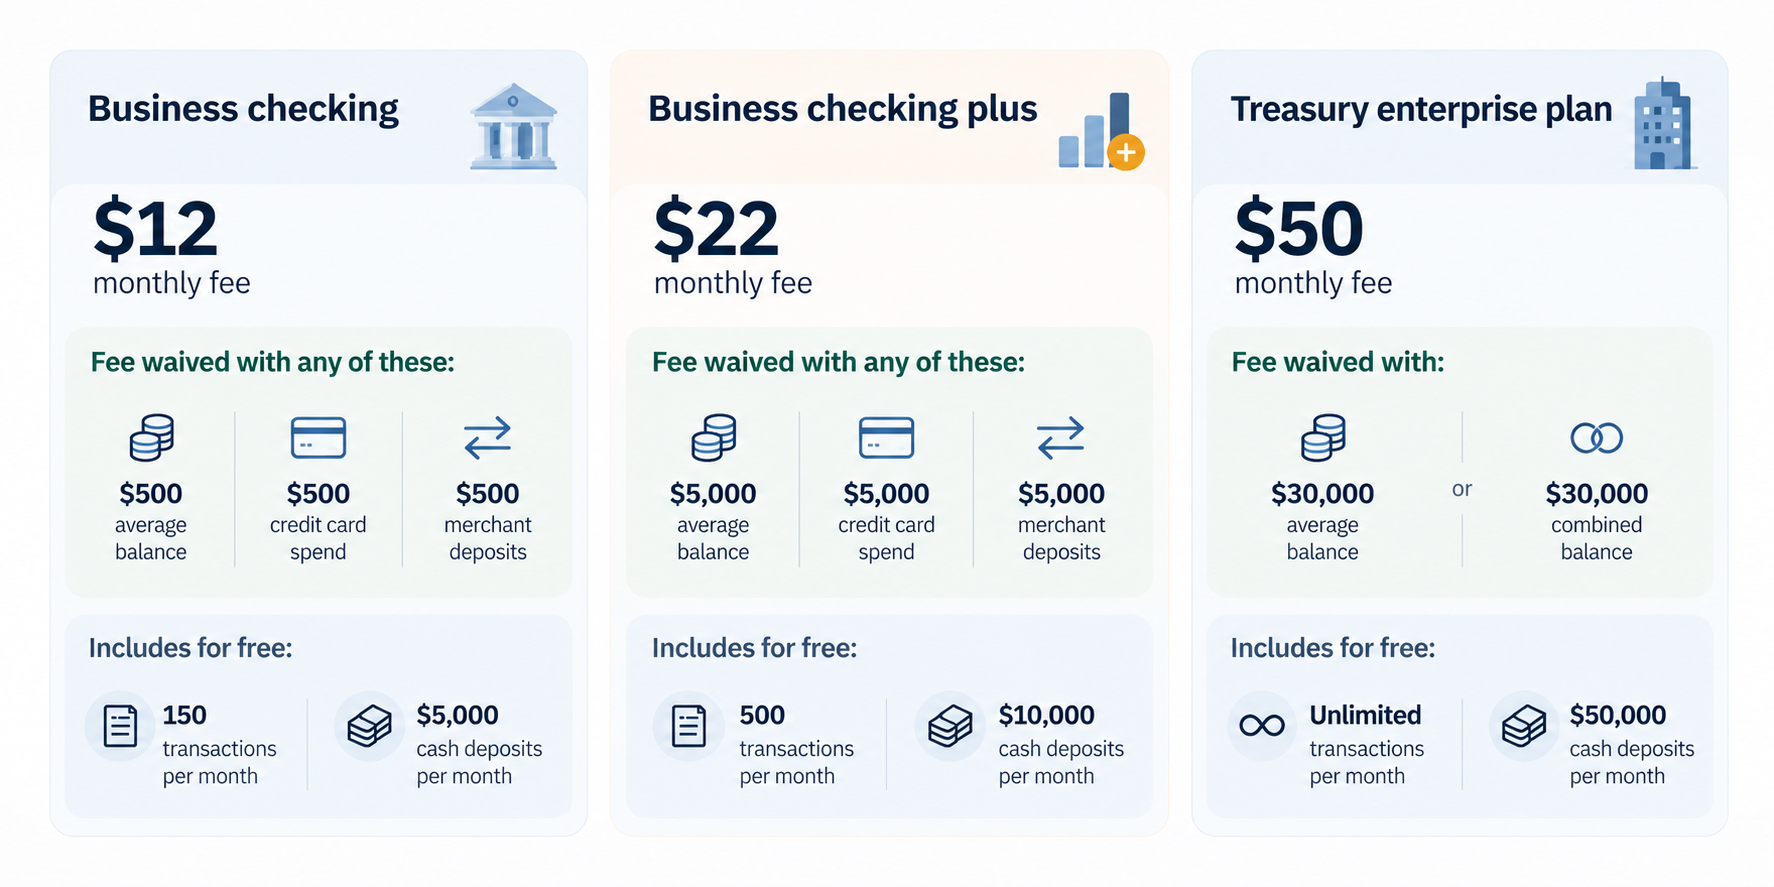
1. Business checking: $12 monthly fee
How to avoid the fee:
- Maintain a $500 average monthly balance.
- Spend $500 on a linked PNC Business Credit Card.
- Process $500 in deposits through a linked PNC merchant account.
How to avoid extra charges:
- Keep monthly transactions within the 150 free-item limit.
- Keep monthly cash deposits within the $5,000 free allowance.
2. Business checking plus: $22 monthly fee
How to avoid the fee:
- Maintain a $5,000 average monthly balance.
- Maintain a combined $20,000 balance across eligible linked checking and money market accounts.
- Spend $5,000 on a linked PNC Business Credit Card.
- Process $5,000 in deposits through a linked PNC merchant account.
How to avoid extra charges:
- Keep monthly transactions within the 500 free-item limit.
- Keep monthly cash deposits within the $10,000 free allowance.
3. Treasury enterprise plan: $50 monthly fee
How to avoid the fee:
- Maintain a $30,000 average monthly balance.
- Alternatively, maintain a combined $30,000 balance across eligible linked corporate accounts.
How to avoid extra charges:
- Enjoy unlimited transactions across linked accounts.
- Keep monthly cash deposits within the $50,000 free allowance.
PNC Business account features and tools
PNC provides digital banking, business debit cards, payment processing and cash management tools to help businesses handle everyday transactions, monitor cash flow and manage finances more efficiently.
Digital tools: PNC Business Online Banking and mobile deposit capabilities help business owners check balances, review transactions, deposit eligible checks and manage accounts without visiting a branch.
Cards: Eligible account holders can access PNC Bank Visa Business Debit cards for convenient business purchases. The Purchase Payback® programme may offer cash-back rewards on qualifying purchases from participating merchants, subject to applicable terms.
Integrations: Businesses with more complex financial needs can use PINACLE®, PNC's treasury management platform, to access cash management services and tools that support cash-flow forecasting, payment management and account visibility.
Payment processing: PNC Merchant Services helps businesses accept customer payments and manage transactions. When used alongside available cash-flow tracking tools, these services can make it easier to monitor incoming payments, reconcile transactions and manage accounts receivable.
Together, these features give businesses tools to manage routine banking, track incoming funds and oversee payments. Fees and thresholds in this guide come from PNC's business deposit fee schedule effective 25 October 2026. They can change, so review PNC's current terms before enrolling.
Also read: How to open a business bank account
Handling international payments
While a PNC business account can help you manage everyday banking in the US, businesses working with international clients, suppliers or remote teams may need additional options for cross-border payments. This is where Grey can complement your banking setup.
With a Grey Business account, eligible businesses can send and receive money from the US, making it easier to manage international payments when working with American clients, paying overseas suppliers or serving customers across borders.
Grey adds a multi-currency layer to your financial operations, helping you handle international transactions alongside your regular business banking. Before choosing a service, review supported currencies, transfer fees, exchange rates and account eligibility to understand the costs involved.
Frequently asked questions
1. What business accounts does PNC offer?
PNC offers several business checking options, including Business Checking, Business Checking Plus, Treasury Enterprise Plan and Analysis Business Checking. Each serves different needs, from freelancers and small businesses to larger companies managing substantial cash flows. The right account depends on your transaction volume, cash deposits and treasury management requirements.
2. What are the fees?
Monthly maintenance fees vary by account tier. Business Checking costs $12, Business Checking Plus costs $22, and Treasury Enterprise Plan costs $50, based on the fee schedule outlined above. Analysis Business Checking has variable fees. Eligible accounts may qualify for waivers by meeting balance or other requirements. Transaction and cash deposit limits may also trigger additional charges.
3. Can I open one online?
Yes, PNC allows eligible customers to apply for certain business checking accounts online. You can also visit a branch to complete the application. Availability may depend on your business structure, location and eligibility. Before applying, review the account requirements and prepare the necessary identification and business documents to help avoid delays.
4. What documents do I need?
PNC generally requires your business Tax Identification Number (TIN), or Social Security number for eligible sole proprietors, business registration documents and proof of authority to operate the business. You will also need identification. Online applicants need a valid email address. Requirements vary by business structure.
5. Is there a minimum balance?
PNC Business Checking has a $100 minimum opening deposit. This differs from the $500 average monthly balance that can waive its $12 maintenance fee. Other account tiers have different waiver requirements. You may avoid monthly fees through qualifying linked credit card purchases or merchant deposits, depending on the account.
6. How do I handle overseas payments?
You can use PNC international wire transfers to send money overseas or receive payments from abroad, although transfer fees and currency conversion costs may apply. For additional cross-border flexibility, eligible businesses can use a Grey Business account to send and receive money from the US. Compare fees and supported currencies before choosing a service.
Independent contractor vs employee: How to tell the difference
Know where contractor vs employee status really differs. Compare control, tax, benefits and the IRS classification tests in one place. Get the breakdown.
Tunde Aladeloba
•
October 11, 2026
•
6 min read
A new job offer can feel straightforward until you reach the part of the contract that describes your employment status. The salary may look attractive and the role may seem like the right next step, but being hired as an independent contractor rather than an employee can change what you take home, who handles your taxes and whether you receive benefits such as paid leave or health insurance.
An independent contractor runs their own business and controls how they work, while an employee works under the employer's direction. Employers withhold tax and provide benefits for employees, but not for contractors, who handle their own taxes
The difference is more than a job title, and getting it wrong can leave you with unexpected tax bills or fewer workplace protections than you expected. In this guide, we’ll break down the key differences between an independent contractor and an employee, so you can understand where you stand before signing your next contract.
Independent contractor vs employee: Key differences
This table compares the main differences between contractors and employees, from workplace control and taxes to benefits, job security, tools, and financial risk.
| Feature | Independent Contractor | Employee |
|---|---|---|
| Control | Dictates own hours, methods, and routine | Employer dictates schedule, location, and tasks |
| Tax | Pays own income and self-employment taxes | Employer automatically withholds income and payroll taxes |
| Benefits | Responsible for own health insurance and retirement | Eligible for company healthcare, 401(k), and PTO |
| Tools | Provides own specialised equipment and software | Employer provides necessary tools and equipment |
| Permanence | Defined by project completion or contract end | Indefinite, ongoing relationship until termination |
| Financial Risk | Can experience a financial profit or loss | Receives a guaranteed wage or salary |
What is an independent contractor?
An independent contractor is a self-employed person who provides services to a business or individual under a contract rather than working as a traditional employee. Think of a freelance designer hired to create a company’s new website, a consultant brought in to solve a business problem, or a writer paid to produce a series of articles. They work independently and are generally responsible for deciding how, when, and where the work gets done, as long as they deliver what was agreed in the contract.
In the US, independent contractors are commonly paid as 1099 workers, meaning businesses generally report their payments to the contractor using a Form 1099-NEC when applicable. Unlike employees, contractors typically do not have income tax, Social Security, or Medicare taxes withheld from their payments, so they need to plan for these taxes themselves.
Being an independent contractor also comes with responsibilities beyond completing the work. Contractors usually handle their own tax filings, business expenses, insurance and retirement planning, while keeping records of income and expenses. The trade-off is greater control over how they work and, in many cases, the ability to work with multiple clients.
What is an Employee?
An employee is a person who works for a company or organisation under an employment relationship, where the employer generally controls what work is done, how it is performed and when it is completed. Unlike an independent contractor, an employee works as part of the organisation and is typically entitled to protections and benefits provided under their employment arrangement.
W-2 Pay
In the US, employees are generally paid through payroll and receive a W-2 form from their employer at the end of the tax year. The W-2 reports their wages and the taxes already withheld from their pay.
Tax Withholding
Employers typically withhold federal income tax, Social Security and Medicare taxes from an employee’s wages and send these amounts to the relevant authorities. This means employees do not usually need to set aside the full tax amount themselves.
Employee Benefits
Depending on the employer and role, employees may receive health insurance, retirement plans, paid time off and other benefits. If you encounter the term “what a 1099 employee is,” it is important to understand that a 1099 worker is generally an independent contractor, not an employee.
How the IRS tests classification
The difference between an employee and an independent contractor is not always obvious from a job title or contract. A company might call someone a contractor, but the IRS looks at the actual working relationship to determine how that person should be classified for tax purposes. It generally considers three categories of control.
Behavioral Control
The IRS considers whether the business has the right to direct how, when and where the worker performs their job. Detailed instructions, set working hours, training and supervision can indicate an employee relationship.
Financial Control
The IRS looks at how much control the business has over the worker’s financial and business activities. Factors include who provides tools and equipment, whether expenses are reimbursed, how the worker is paid and whether they can make a profit or experience a loss.
Relationship Factors
The nature of the relationship also matters, including written contracts, employee benefits, how permanent the arrangement is and whether the worker provides services that are a key part of the business. No single factor determines classification; the IRS considers the entire relationship.
How taxes and paperwork differ for Contractors and Employees
Getting paid as a contractor or employee does not just change the amount that lands in your bank account; it also changes the paperwork you receive, who handles your tax withholding and what happens if your worker classification is wrong.
1099 vs. W-2
Employees generally receive a W-2 showing their wages and taxes withheld by their employer, while independent contractors typically receive a 1099-NEC for qualifying payments. Understanding 1099 vs. W-2 can help clarify how each worker is paid, what taxes are withheld, who is responsible for reporting income, and what paperwork to expect.
Self-Employment Tax
Contractors generally have to account for both the employer and employee portions of Social Security and Medicare taxes through self-employment tax, meaning they need to plan for these payments themselves rather than relying on payroll withholding.
Misclassification risk
Calling a worker a contractor does not automatically make them one. If a business treats an employee as an independent contractor, it may face additional taxes, penalties and other consequences, while the worker could miss protections and benefits they should have received.
How to pay contractors in the US and abroad
Paying a contractor can look simple until the person doing the work lives in another country. A US-based company might have a designer in the Philippines, a developer in Nigeria or a marketing consultant in Brazil, and suddenly the payment process involves exchange rates, transfer fees, payment details and waiting times.
This is where Grey can make contractor payments easier. Businesses can use Grey to pay contractors from the US and send payments internationally without having to navigate a complicated process for every contractor. The platform supports transfers across multiple currencies, allowing businesses to hold and convert funds before sending money to contractors in supported countries.
For example, a US company paying a contractor in the Philippines can use Grey to send money from the US to the Philippines, while the contractor receives the funds in the supported local currency. For businesses working with international talent regularly, having one place to manage these payments can make cross-border contracting much simpler.
Frequently asked questions
What is the difference between a contractor and an employee?
An employee works under an employer’s direction and typically receives payroll withholding and benefits, while an independent contractor runs their own business and controls how they complete their work. Contractors generally handle their own taxes, business expenses and insurance, while employees receive greater workplace protections and employer-provided benefits.
How does the IRS decide?
The IRS looks beyond a worker’s job title or contract and examines the actual working relationship. It considers behavioural control, financial control and the relationship between the worker and business. No single factor automatically determines classification, so businesses should consider the full arrangement when deciding whether someone is an employee or contractor.
Do contractors get benefits?
Independent contractors generally do not receive employee benefits such as employer-sponsored health insurance, paid vacation or retirement contributions. Instead, they are responsible for arranging their own insurance, retirement savings and other benefits. However, a contractor’s specific agreement can provide certain perks or payments, depending on what the business and contractor negotiate.
What is misclassification?
Misclassification happens when a business treats a worker as an independent contractor when the person legally qualifies as an employee. This can affect taxes, benefits and workplace protections. For the business, misclassification can lead to unpaid employment taxes, penalties and other costs, while the worker may lose benefits they should have received.
Can someone be both?
Yes, someone can potentially work as an employee for one business while independently contracting for another. For example, a person could have a full-time W-2 job and provide freelance consulting services to separate clients. However, the classification of each working relationship depends on the specific facts and circumstances involved.
How do I pay an overseas contractor?
Paying an overseas contractor typically involves choosing a payment method, confirming the contractor’s banking details and considering currency conversion, transfer fees and tax documentation. Platforms such as Grey can help businesses make international payments, allowing them to send money across borders without relying on traditional bank transfers for every contractor.
How to start an LLC in Texas: Step-by-step guide
How to start an LLC in Texas. $300 filing fee, step-by-step filing process, franchise tax rules, and what to do after formation. Read the full guide.
Priscila Marotti
•
October 7, 2026
•
6 min read
Texas has no personal state income tax. That alone makes it one of the most popular states for LLC formation. But Texas does have a franchise tax, and ignoring it is the single most common mistake new LLC owners make. We'll cover that alongside every other step.
The full Texas LLC formation process takes about an hour of your time and $300 in state fees. You can do it entirely online through the Texas Secretary of State's SOSDirect system. No lawyer required for a straightforward single-member or two-member LLC, though complex ownership structures or real estate holdings benefit from legal guidance.
To form an LLC in Texas, choose a registered agent and file a Certificate of Formation with the Secretary of State ($300). Then get an EIN from the IRS, open a business bank account, and apply for any required permits. You can file online through SOSPortal, although processing times vary.
This guide walks through each step in the order you actually do them, with the costs and timelines you'll encounter. For choosing a name, see LLC naming guide.
Step 1: Choose your LLC name
Your Texas LLC name must include "LLC" or "Limited Liability Company" and be distinguishable from any existing entity registered in Texas. Search the Texas Secretary of State's SOSPortal database to check availability. The search is free and returns results instantly.
Texas is relatively lenient on name similarity. "Bright Studio LLC" and "Bright Studios LLC" would likely both be accepted as distinguishable. But being legally distinguishable doesn't mean your customers won't confuse the two. Search broadly and consider trademark implications before committing.
If your name is available but you're not ready to file immediately, Texas allows name reservations for 120 days at $40. This prevents someone else from registering it while you prepare your formation documents.
You can also file a DBA (Assumed Name Certificate) if you want to operate under a different name than your legal LLC name. The DBA filing costs $25 per county where you do business in Texas. This lets "Smith Holdings LLC" operate publicly as "Bright Studio" without changing the legal entity name.
Step 2: Choose a registered agent
Every Texas LLC must have a registered agent with a physical street address in Texas. No PO boxes. The agent receives legal documents (lawsuits, government notices, tax correspondence) on behalf of the LLC. This is a legal requirement, not optional.
Option 1: Be your own agent. Free, but your home address becomes public record on the Texas SOS website. Anyone can look up your LLC and find your personal address. You also must be available at that address during normal business hours to accept documents in person. If you're travelling or working remotely, you can miss a critical legal notice. A virtual mailbox can give you a US mailing address for business post, but it does not replace a registered agent.
Option 2: Use a registered agent service. $50 to $199/year. The service provides a Texas address, forwards documents to you, and ensures nothing gets missed while you're unavailable. Northwest Registered Agent ($125/year) and ZenBusiness ($199/year after the first free year) are popular options. For service comparisons, see best LLC formation services.
Option 3: Use a friend or family member in Texas. Free, but they must be available at the registered address during business hours and they'll see every legal document your LLC receives, including lawsuits. Most people prefer the privacy of a paid service.
Step 3: File the Certificate of Formation
This is the actual formation step. You file the Certificate of Formation (Form 205) with the Texas Secretary of State.
Online filing (recommended): Visit the Texas Secretary of State's SOSPortal and create an account. Complete the Certificate of Formation (Form 205) with your LLC name, registered agent information, management structure, organiser details, and effective date. The filing fee is $300, payable by ACH or credit card, although credit card payments carry an additional convenience fee. Processing times vary, and expedited filing options are available for an additional charge.
Mail filing: Download Form 205, complete it, and mail it with the $300 filing fee to the Texas Secretary of State. Processing times vary, so check the state's current turnaround times before submitting.
The $300 fee is non-refundable. If your filing is rejected (usually because the name is too similar to an existing entity or required information is missing), you can correct and resubmit without paying again, but the original fee isn't returned if you abandon the filing.
Member-managed vs manager-managed: most single-member and small multi-member LLCs choose member-managed, meaning all owners participate in running the business. Manager-managed is for LLCs with passive investors who own a share but don't participate in daily operations. If you're not sure, choose member-managed. You can change this later by filing an amendment ($150).
Step 4: Create an Operating Agreement
Texas doesn't legally require an operating agreement, but you should have one anyway. Banks require it to open a business account. It also protects your personal liability shield: without an operating agreement, a court could argue the LLC isn't a separate entity from you personally (called "piercing the corporate veil"), exposing your personal assets to business debts.
Your operating agreement should cover: ownership percentages, profit and loss distribution, voting rights, member responsibilities, process for adding or removing members, what happens if a member dies or becomes incapacitated, and the process for dissolving the LLC.
For single-member LLCs, the operating agreement is simpler but still essential. It establishes the LLC as a separate entity and documents how the business operates. A basic single-member operating agreement is 3 to 5 pages. Most LLC formation services include a template. Free templates are available from the Texas Secretary of State website and SCORE (SBA's mentoring arm).
Step 5: Get an EIN (Employer Identification Number)
The EIN is free and takes 10 minutes. Apply online at irs.gov/ein. You'll need your LLC's legal name, Texas address, and the responsible party's SSN or ITIN. The EIN is issued immediately upon completion of the online application.
Every LLC needs an EIN, even single-member LLCs. Banks require it to open business accounts. The IRS uses it for tax filings. Vendors and clients use it on W-9 forms. Don't pay an LLC formation service $70 to $99 for this. It's free and faster to do yourself.
One EIN per LLC. If you dissolve and reform, the new LLC needs a new EIN. If you change your LLC's name or address, you keep the same EIN. If you change from single-member to multi-member entity, you keep the same EIN.
Step 6: Open a business bank account
Separate your personal and business finances immediately. Mixing them is the fastest way to lose your personal liability protection. Courts use "commingling of funds" as evidence that the LLC isn't a real separate entity.
What you need to open a business bank account: Certificate of Formation (the approved filing from the Texas SOS), EIN confirmation letter, operating agreement, government-issued ID, and a business address.
Traditional banks: Chase, Bank of America, Wells Fargo all offer business checking in Texas. Expect monthly fees of $10 to $30 (often waivable with minimum balances of $1,500 to $5,000). In-person branch visit required.
Online options: Grey Business lets you open a multi-currency business account in your LLC name with US routing and account details, no branch visit required. You get USD, GBP, and EUR accounts. If your Texas LLC works with international clients or vendors, the multi-currency capability eliminates the need for separate foreign currency accounts or expensive wire transfers for each currency. The Grey conversion fee is 1% capped at $6, compared to bank wire fees of $25 to $50 per international transfer.
Step 7: Texas franchise tax
This is the step most guides bury at the bottom. Don't skip it. Texas LLCs are generally subject to franchise tax rules, but that doesn't mean every LLC owes tax or must file a franchise tax report. Businesses with annualised total revenue at or below the state's no-tax-due threshold generally owe no franchise tax and don't need to file a franchise tax report. However, they must still submit an annual Public Information Report (PIR) or Ownership Information Report (OIR), unless an exception applies.
For 2026 and 2027, the no-tax-due threshold is $2.65 million in annualised total revenue. LLCs at or below this threshold generally owe $0 in franchise tax and no longer need to file a No Tax Due Report. They must still submit the applicable annual information report.
Missing required franchise tax filings or annual information reports can put your LLC's good standing at risk and may lead to forfeiture of its right to transact business in Texas. Even when no franchise tax is owed, it's important to submit the required PIR or OIR on time.
Filing deadlines: the initial franchise tax report is due May 15 of the year after formation. If you form your LLC in September 2026, your first report is due May 15, 2027. Annual reports are due May 15 every year after that. File electronically through the Texas Comptroller's Webfile system.
Tax rates (for LLCs above $2.65 million): 0.375% for retail and wholesale businesses, 0.75% for all other businesses, applied to the LLC's "taxable margin" (roughly, the lesser of total revenue minus cost of goods sold, total revenue minus compensation, 70% of total revenue, or total revenue minus $1 million).
After formation: What comes next
Business licences and permits. Texas doesn't have a general business licence, but specific industries require state or local permits. Food service needs a health department permit. Construction needs a contractor's licence. Check with your city and county clerk for local requirements.
Sales tax permit. If you sell taxable goods or services in Texas, apply for a sales tax permit through the Texas Comptroller. The permit is free. Texas sales tax is 6.25% state rate plus up to 2% local rate (total up to 8.25%). Don't collect sales tax without a permit, and don't sell taxable items without collecting it.
Business insurance. Not legally required for single-member LLCs in Texas (unless you have employees, in which case workers' compensation is recommended but not mandatory in Texas). General liability insurance ($30 to $100/month) protects against third-party claims. Professional liability (errors and omissions) is worth considering if you provide professional services.
Separate credit. Apply for a business credit card in your LLC name to start building business credit. Use it for business expenses and pay in full each month. Business credit is separate from personal credit and can help you secure financing later.
Ready to start your Texas LLC? Open a Grey Business account and get US banking details in your LLC name from day one.
Frequently asked questions about how to start an LLC in Texas
How much does it cost to start an LLC in Texas?
$300 state filing fee for the Certificate of Formation. Optional costs: registered agent service ($50 to $199/year), name reservation ($40), DBA filing ($25 per county), and EIN (free from IRS). Total out-of-pocket for a basic LLC: $300 to $500 in the first year. For cost breakdowns across states, see LLC cost guide.
How long does it take to form a Texas LLC?
Processing times for Texas LLC formation vary depending on the filing method and current workload. Online applications can be submitted through SOSPortal, and expedited same-day or next-day processing is available for an additional fee. Once your LLC is approved, you can apply for an EIN and open a business bank account. The overall timeline depends on how quickly your filing is approved and your bank account is set up.
Does a Texas LLC pay state income tax?
Texas has no personal state income tax, but LLCs are generally subject to the state's franchise tax rules. For 2026 and 2027, LLCs with annualised total revenue of $2.65 million or less generally owe no franchise tax and don't need to file a franchise tax report. However, they must still submit an annual Public Information Report or Ownership Information Report, unless exempt. LLCs above the threshold generally pay 0.375% (retail/wholesale) or 0.75% (other businesses) on their taxable margin, although an alternative EZ computation method is available for eligible businesses. For filing details, see LLC tax guide.
Do I need a lawyer to form an LLC in Texas?
Not for a straightforward single-member or small multi-member LLC. The SOSDirect online filing system is user-friendly and walks you through each section. A lawyer ($500 to $2,000) is worth the cost if your LLC involves complex ownership structures, significant assets, real estate holdings, or multiple members with different contribution levels. For dissolution guidance, see dissolve an LLC.
Can a non-US resident start an LLC in Texas?
Yes. Texas does not require LLC owners to be US citizens or residents. You'll need a registered agent with a Texas address, an EIN from the IRS (apply by mail using Form SS-4 if you don't have a US SSN), and a business bank account that accepts non-resident LLCs. Grey Business serves international founders without requiring a US branch visit.
Start your Texas LLC and open Grey Business for US banking details in your LLC name.
Disclaimer: This article is for informational purposes only. All costs and details are estimates based on mid-2026 data. Verify current information before making decisions. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.
How to dissolve an LLC: Steps and costs
How to dissolve an LLC step by step. State filings, final tax returns, and asset distribution explained. Close your LLC properly. Read the guide.
Priscila Marotti
•
October 7, 2026
•
6 min read
A surprising number of business owners stop operating their LLC but never formally close it. The LLC stays registered, the state keeps expecting filings, and fees or penalties accumulate quietly in the background. In California, that can mean an $800 annual LLC tax for a business you thought you'd already shut down. In Delaware, LLCs generally owe a $300 annual tax until they properly cancel their registration. These obligations don't stop when you stop working.
Don't dissolve if you might restart the business within a year. It's easier and cheaper to keep the LLC dormant (file the required reports, pay any minimum fees) than to dissolve and re-form later. Reforming means new filing fees, a new EIN application, new bank accounts, and updated contracts with every vendor and client.
To dissolve an LLC, you vote to dissolve (if multi-member), settle debts, and distribute remaining assets. Then file Articles of Dissolution with your state, file final tax returns, cancel your EIN, and close all business accounts. The process takes 2 to 8 weeks depending on the state.
This guide covers every step, including the tax obligations most dissolution guides skip. For the formation side, see LLC costs.
Step 1: Vote to dissolve
The following steps outline the general process for dissolving an LLC in the US. However, requirements vary by state, including voting rules, tax obligations, filing documents, and processing times. Always check your state's specific requirements before proceeding.
If your LLC has more than one member, the members must formally vote to dissolve. Check your operating agreement for the voting threshold. Common options are unanimous consent, majority vote, or supermajority (two-thirds). If you don't have an operating agreement, your state's default LLC act applies, which typically requires the majority consent of all members.
For single-member LLCs, you make the decision yourself. Either way, document it in writing. Draft a written resolution that states the LLC name, the date of the vote, the result (unanimously approved, majority approved, etc.), and the signatures of all voting members. Keep this resolution with your LLC records permanently.
This documentation protects you if anyone later disputes whether the dissolution was authorised. It also protects you if creditors challenge the dissolution as fraudulent (attempting to avoid debts). A properly documented vote shows the dissolution was deliberate and orderly, not evasive.
If your operating agreement doesn't address dissolution, draft a simple dissolution resolution. One page is enough. Date it, state the decision, and have every member sign it. This becomes the legal record of consent.
Step 2: Wind up business affairs
Before you file anything with the state, resolve everything the LLC owes and is owed. This is the most time-consuming step and the one most people rush through, leading to problems months or years later.
Pay all debts and obligations. Outstanding invoices, business loans, credit card balances, vendor contracts, lease obligations, and any pending legal claims. If the LLC can't pay all debts from its assets, consult a business attorney before proceeding. Dissolving an LLC while debts are outstanding can expose members to personal liability in some situations, particularly if creditors can argue the dissolution was intended to evade payment.
Collect what's owed to you. Chase outstanding receivables aggressively. Send final invoices immediately. Once the LLC is dissolved, collecting becomes dramatically harder. You may lose standing to sue in the LLC's name. Some states allow a "winding up" period after dissolution during which you can still collect, but this varies. Don't rely on it.
Cancel contracts and subscriptions. Leases, software subscriptions, insurance policies, recurring services, domain registrations, hosting accounts, phone plans, and any other recurring commitments. Notify each provider in writing that the LLC is closing and request written confirmation of cancellation. Keep these confirmations. A verbal cancellation that isn't documented can lead to continued billing.
Notify your customers and clients. If you have ongoing client relationships, give them reasonable notice. Provide referrals to alternative providers if appropriate. This isn't legally required in most states, but it's professional and protects your personal reputation for future ventures.
Distribute remaining assets. After debts are paid and receivables collected, distribute the remaining cash and assets to members according to the operating agreement. If there's no agreement, follow your state's default rules, which typically allocate proportionally based on ownership percentage. Document every distribution with amounts, dates, and member signatures.
Step 3: File final tax returns
Your LLC must file a final tax return for the year it dissolves. Check the "final return" box on the applicable form. The specific form depends on how your LLC is taxed:
Single-member LLC (disregarded entity): Report the business's final income and expenses on Schedule C of your personal Form 1040, if applicable. Schedule C does not have a separate "final return" checkbox.
Multi-member LLC (partnership): File Form 1065, check the "final return" box, and issue final Schedules K-1 to each member. Each member reports their share of the LLC's income and other applicable tax items on their personal return.
LLC taxed as an S corporation: File Form 1120-S and mark it as the final return. If the LLC adopts a plan of corporate dissolution or liquidation, Form 966 is generally required within 30 days of adopting that plan.
LLC taxed as a C corporation: File Form 1120 and mark it as the final return. Form 966 is generally required within 30 days of adopting a plan of corporate dissolution or liquidation.
Don't forget state tax obligations. If your state has a franchise tax, income tax, or sales tax, file final returns with the state as well. In Texas, file a final franchise tax report with the Comptroller. In California, LLCs generally owe the $800 annual tax for their final taxable year, even if they stop operating partway through it. The tax is not normally prorated, although certain exceptions apply. In New York, the filing fee is $0, but you must file a final partnership return. For guidance, see how to file LLC taxes.
Sales tax: if your LLC collected sales tax, file a final sales tax return and remit any remaining tax. Notify your state's revenue department that the sales tax permit should be cancelled.
Payroll taxes: if you had employees, file final Forms 941 (quarterly) and W-2s (annual). Pay any remaining payroll tax deposits. File Form 940 (federal unemployment tax) marked "final."
Step 4: File Articles of Dissolution
File the required dissolution or cancellation documents with your state's Secretary of State or equivalent filing authority. The exact form, filing process, and requirements vary by state. Some states also require tax clearance or additional documentation before the LLC can be formally terminated.
Filing fees vary by state. Some states allow LLCs to dissolve at no charge, while others charge a filing fee. For example, California does not charge a fee for LLC termination filings, while Texas charges $40 for a Certificate of Termination. Check your state's current filing fees before submitting your dissolution documents.
The form is typically short: LLC name, date of formation, reason for dissolution (voluntary), effective date of dissolution, and confirmation that debts have been paid or provisions made for payment. Some states require a tax clearance certificate from the revenue department before accepting the dissolution filing. Ohio, for example, requires a tax clearance letter.
If your LLC operates in multiple states, you must also file for withdrawal (or termination of foreign qualification) in each state where you registered as a foreign LLC. Each state charges its own fee for this. Missing a foreign state registration means that the state keeps expecting filings and fees.
Processing time: 1 to 4 weeks for most states. Expedited processing is available in many states for an additional fee ($50 to $200). Once approved, the state issues a certificate of dissolution or cancellation. Keep this permanently with your LLC records.
Step 5: Cancel your EIN and close accounts
Close your IRS business account. An EIN cannot be permanently cancelled, but you can ask the IRS to close the business tax account associated with it. Send a letter containing the LLC's legal name, EIN, business address, and reason for closure to the Internal Revenue Service, Cincinnati, OH 45999. Include a copy of your EIN assignment notice if available. The IRS will close the account once all required tax returns have been filed and outstanding taxes paid.
Close all business accounts. Bank accounts, credit cards, payment processors (Stripe, PayPal, Square), and any merchant accounts. Transfer any remaining balances to members before closing. Request written confirmation from each institution that the account is closed. A "closed" bank account that still has a $2.50 monthly maintenance fee will eventually go to collections.
Cancel your registered agent service if you were using a professional agent. Cancel any business licences or permits with your city, county, and state. Cancel your DBA (doing business as) registration if you filed one. Update your website to indicate the business is no longer operating, or take it down entirely. Update social media profiles similarly.
Notify creditors formally. Many states require or recommend sending a written notice to known creditors that the LLC is dissolving. This starts a statutory claims period (typically 90 to 120 days) after which creditors who don't file claims lose their right to collect. This is your legal protection against surprise claims years later.
Common dissolution mistakes
1. Not filing Articles of Dissolution. This is the most common and most expensive mistake. The LLC continues to exist in the state's records, annual fees keep accumulating, franchise taxes keep accruing, and your registered agent keeps billing you. Five years of California's $800 annual LLC tax can mean $4,000 in unpaid taxes, plus applicable penalties and interest. The tax can apply even if the LLC earned no income, unless an exemption or exception applies.
2. Not filing final tax returns. The IRS expects a final return. Not filing triggers a substitute return (SFR), which estimates your tax liability, usually too high, and starts penalties and interest from the original due date. State revenue departments are equally aggressive. Don't assume that dissolving the LLC means the tax obligations disappear.
3. Distributing assets before paying debts. Members who receive distributions while debts are outstanding can be held personally liable for those debts, up to the amount they received. This is called a "fraudulent transfer" or "fraudulent conveyance" in legal terms. Pay every creditor first. Distribute to members last.
4. Forgetting state-specific requirements. Some states require additional steps before an LLC can be formally dissolved, including obtaining tax clearance or notifying creditors. These requirements vary, so check the rules in the state where your LLC was formed. Some states have mandatory waiting periods. Check your specific state's requirements before filing.
5. Not cancelling foreign state registrations. If your LLC is registered to do business in three states, you need to file for dissolution in your home state and withdrawal in the other two. Miss one and that state keeps expecting annual reports and fees.
Closing your LLC? Make sure all financial accounts are settled and final returns are filed before you dissolve.
Frequently asked questions about how to dissolve an LLC
How much does it cost to dissolve an LLC?
The cost of dissolving an LLC depends on the state and whether you need professional assistance. Some states charge no filing fee, while others charge $40, $100, or more. For example, California has no filing fee for LLC termination, while Texas charges $40. If you hire an attorney, dissolution service, or accountant, you'll also need to budget for their fees. Outstanding taxes, annual fees, and other obligations can increase the total cost.
How long does LLC dissolution take?
The state filing itself takes 1 to 4 weeks for processing, longer in busy states like California and New York. But the full wind-up process (paying debts, collecting receivables, distributing assets, filing final taxes, notifying creditors) can take 2 to 6 months. Start the wind-up well before you file with the state. The statutory creditor claims period adds 90 to 120 days after filing.
Can I dissolve an LLC with debt?
You can, but you must handle the debt first. The LLC's assets should be used to pay creditors before any distributions to members. If the LLC's assets aren't sufficient to cover all debts, consult a business attorney. Dissolving with unpaid debts can expose members to personal liability in some cases, particularly if creditors argue the dissolution was intended to avoid payment.
What happens to the LLC name after dissolution?
In most states, the name becomes available for others to use after dissolution. The timeline varies: some states release names immediately, others hold them for 1 to 3 years. If you want to protect the name for future use, consider registering it as a federal trademark before dissolving (costs $250 to $350). For starting a new LLC later, see start a Texas LLC or name an LLC.
Do I still need to file taxes after dissolving my LLC?
You must file a final tax return for the year of dissolution. After that, no. But if you didn't file returns for prior years, those obligations survive dissolution. The IRS can pursue unfiled returns against the LLC's former members. Clean up any back filings before or during dissolution.
Starting fresh? Open a Grey Business account for your next venture.
Disclaimer: This article is for informational purposes only. All costs and details are estimates based on mid-2026 data. Verify current information before making decisions. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.
11 best LLC formation services: Cheapest ways to file
Compare the best and cheapest LLC formation services, what each includes, and how to fund your new LLC in USD once it is registered. Compare.
Tunde Aladeloba
•
September 24, 2026
•
6 min read
A business idea can be exciting until the paperwork starts. Choosing a business structure, checking your state’s requirements, paying the filing fee, and making sure everything is submitted correctly can quickly make LLC formation feel more complicated than expected.
The good news is that forming an LLC does not always require paying a company to do it for you. In many cases, you can file directly with your state and pay the required state filing fee. However, handling everything yourself means taking care of the paperwork, registered agent requirements, and other state-specific steps.
For people who prefer convenience, LLC formation services can handle much of this process for an additional fee. Some even advertise free formation, although you may still need to pay the state filing cost and may encounter additional charges for optional services.
With so many providers available, comparing the best LLC formation services means looking beyond the headline price. The registered agent cost, turnaround time, included features, renewal fees, and overall filing process can all affect what you actually pay. This guide compares your options so you can find a formation service that fits your budget and needs.
Also read: How much does it cost to start an LLC?
The cheapest way to form an LLC without paying for extras
Starting an LLC does not have to mean paying a formation company to handle everything for you. The cheapest route is usually filing directly with your state, where your main cost is the required state filing fee. The trade-off is that you are responsible for getting the paperwork right and meeting every state requirement.
When DIY makes sense
Filing yourself can be a good fit when you have a straightforward business and enough time to handle the process. You will typically need to:
- Choose and check your LLC name.
- Prepare and file the required formation documents.
- Appoint a registered agent where required.
- Pay the state filing fee.
- Complete any additional state requirements.
When a formation service makes sense
Paying for a service may be worthwhile when you want someone else to handle the filing or help you avoid administrative mistakes. Some providers offer low-cost or free formation packages, although you still pay the state fee and may be charged for extras such as registered agent services or compliance support.
The right choice comes down to whether saving money or saving time matters more for your situation.
The comparison below looks at base pricing, registered agent costs, processing times, and the features that distinguish each LLC formation service.
Also read: Open a USD business account without a US address
11 best LLC formation services compared
| LLC formation service | Starting base price | Registered agent cost | Turnaround / filing time | Key extras and distinctive traits |
|---|---|---|---|---|
| Northwest Registered Agent | $39 + state fee | 1 year included ($125/year renewal) | Same-day / 1–6 days | Privacy by Default, which uses its office address on public documents; free corporate email and website. |
| ZenBusiness | $0 + state fee | Add-on ($199/year) | 1–10 days; rush available | Beginner-friendly platform, Velo AI assistant, and compliance protection in higher tiers. |
| Bizee (formerly Incfile) | $0 + state fee | 1 year included ($119/year renewal) | Standard state time; expedited options | Free tax consultation and a $0 base plan, with additional services available as paid extras. |
| LegalZoom | $0 + state fee | Add-on ($249/year) | 5–14 days; expedited options | Comprehensive filing workflow, legal subscription plans, and access to attorneys. |
| Inc Authority | $0 + state fee | 1 year included ($249/year renewal) | 24–48 hours | Free EIN and express filing included in the base tier; additional services are offered as paid upgrades. |
| Swyft Filings | $0 + state fee | Add-on ($149/year) | 1–5 days, plan dependent | Phone support and an unbundled service structure, with additional features available at extra cost. |
| Tailor Brands | $0 + state fee | Add-on | Up to 14 days | Built for creators, with logo creation, brand kits, domain registration, and website-building tools. |
| CorpNet | $99 + state fee | Add-on ($149/year) | 24 hours to 1 week | Multi-state entity management, compliance alerts, and support for more complex business structures. |
| MyCompanyWorks | $79 + state fee | Add-on ($119/year) | Same-day processing | Startup wizard checklist, corporate minutes, and free trademark consultations. |
| FileNow | $49 + state fee | 1 year included | 24-hour processing | Fast internal processing, a 15-minute onboarding process, and fewer secondary features. |
| Harbor Compliance | $99 + state fee | Add-on (99–125/year) | 1–3 days | Compliance software designed for growing companies and businesses operating across multiple states. |
Also read: How to File Taxes for an LLC: A Step-by-Step Guide
Where can you form an LLC for the least money?
The cost of forming an LLC can change quite a bit depending on where you file. The formation service may advertise a $0 price, but you still have to pay the state filing fee, and some states charge annual fees that can make a cheap setup more expensive over time.
For the lowest upfront cost, look for a provider with a $0 base fee, such as Bizee or ZenBusiness, then compare the government fee and ongoing costs in your state.
Here are four states with some of the lowest government filing costs:
- Montana: Bizee or ZenBusiness ($0) + $35 state filing fee; $20 annual upkeep.
- Kentucky: Bizee or ZenBusiness ($0) + $40 state filing fee; $15 annual upkeep.
- New Mexico: Bizee or ZenBusiness ($0) + $50 state filing fee; $0 annual upkeep.
- Missouri: Bizee or ZenBusiness ($0) + $50 online filing fee; $0 annual upkeep.
New Mexico and Missouri can be particularly interesting when you look beyond the initial filing cost because there is no annual report or recurring state fee listed here.
Why California can cost much more than it first appears
California is a good example of why the lowest filing fee does not necessarily mean the least expensive LLC to maintain.
The initial state filing fee is $70, and you must also file a Statement of Information within 90 days, which costs $20. The bigger expense is the $800 annual franchise tax. That means the ongoing cost can quickly outweigh what you saved by choosing a $0 formation service.
Before choosing a state, look at the full cost of keeping the LLC active, not just what it costs to file on day one.
What to check before you pay for an LLC formation service
A formation service can look incredibly cheap when you first land on its pricing page. The number that catches your eye may only cover basic filing, while important services are added at checkout or automatically renewed the following year. Before entering your card details, take a few minutes to check what you are actually paying for.
- Check renewal prices: A registered agent may be free for the first year but costs $100 or more at renewal. Check the recurring price, not just the introductory offer.
- Look for upsells: EIN applications, operating agreements, compliance services, business licences, and other extras may be presented during checkout. Decide which ones you actually need.
- Check what the base plan includes: A $0 formation package may only cover the provider’s service fee, while your state filing fee still applies.
- Review cancellation terms: Find out whether optional services renew automatically and how to cancel them before the next billing date.
The cheapest price at checkout is not always the cheapest cost over the life of your LLC.
Once your LLC is registered, set up how you will receive and spend money
Getting your LLC approved is an important step, but there is still the practical side of running the business. Once the paperwork is done, you need a reliable way to receive payments, manage business income, and access your money when clients start paying you.
For freelancers and business owners working with US clients, a Grey USD account can give you a way to receive USD income without asking clients to deal with unfamiliar international payment processes. Funds can be managed from your Grey account, giving you a clearer way to separate business income from your personal finances.
The Grey virtual card can also help when you need to spend your business funds online or pay for services and subscriptions. Keeping your income and business spending organised from the beginning can make your finances easier to manage as the company grows.
You can sign up for Grey or download the app to get started and set up your account for international payments.
Frequently asked questions
What is the cheapest way to start an LLC?
The cheapest way is usually filing the Articles of Organization yourself through your state's Secretary of State portal and paying only the mandatory state government fee. You avoid the service fee charged by formation companies, although you remain responsible for completing the paperwork and meeting all state requirements.
Are formation services worth it?
They can be useful if you want to save time, keep your home address off public business records where possible, or get help managing compliance requirements. The value depends on what the service includes and what you would otherwise handle yourself. Compare the upfront price with recurring fees and optional add-ons.
Can I form an LLC myself?
Absolutely. You can generally visit your state's official business registration website, complete the required formation documents, and pay the applicable state filing fee. The exact process varies by state, so check the requirements before submitting your application and make sure you understand any follow-up obligations.
What is a registered agent?
A registered agent is a person or company designated to receive legal documents, official notices, and certain government correspondence for your LLC. The agent generally needs a physical address in the state where your LLC is registered and must be available to receive documents during required business hours.
How long does LLC approval take?
The processing time depends on the state and how you file. Online applications can sometimes be processed within a few business days, while paper filings may take longer. Some states offer expedited processing for an additional fee. Check your state's current processing times before submitting your application.
How much does it cost to maintain an LLC?
The ongoing cost depends on your state. Some states charge annual or biennial report fees, franchise taxes, or other recurring charges, while others have little or no annual upkeep. Check your state’s requirements so you know what you will pay after the initial filing.
Can I change my LLC name after forming it?
Yes. Most states allow you to change your LLC’s legal name by filing an amendment with the appropriate state agency and paying a fee. Before making the change, check your state’s naming rules and confirm that your preferred new name is available.

