<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#article","headline":"How to pay for Google Ads in Nigeria (2026)","description":"Want to pay for Google Ads in Nigeria? See which payment methods work in 2026, why Nigerian cards get declined and how to fix payment issues.","inLanguage":"en","url":"https://grey.co/blog/pay-for-google-ads-in-nigeria","mainEntityOfPage":{"@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#webpage"},"datePublished":"2026-08-29T22:24:27.884Z","dateModified":"2026-08-30T09:00:00+01:00","author":{"@type":"Organization","@id":"https://grey.co/authors/grey-team#person","name":"The Grey Team","url":"https://grey.co/authors/grey-team"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a935b63fda54184911608d8_How%20to%20Pay%20for%20Google%20Ads%20in%20Nigeria%20(2026)-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a935b63fda54184911608d8_How%20to%20Pay%20for%20Google%20Ads%20in%20Nigeria%20(2026)-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#webpage","url":"https://grey.co/blog/pay-for-google-ads-in-nigeria","name":"How to Pay for Google Ads in Nigeria (2026)","description":"Want to pay for Google Ads in Nigeria? See which payment methods work in 2026, why Nigerian cards get declined and how to fix payment issues.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to pay for Google Ads in Nigeria (2026)","item":"https://grey.co/blog/pay-for-google-ads-in-nigeria"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#faq","mainEntity":[{"@type":"Question","name":"Can I pay for Google Ads with naira?","acceptedAnswer":{"@type":"Answer","text":"No. Google Ads does not offer naira billing for Nigerian accounts. Your billing currency must be USD. You need a dollar-denominated card."}},{"@type":"Question","name":"Can I use my GTBank or Access Bank naira card for Google Ads?","acceptedAnswer":{"@type":"Answer","text":"Unlikely for sustained use. Nigerian banks resumed international card transactions in July 2025, but the CBN caps international naira card spending at $20 per month. Any advertiser spending more than $20 per month needs a virtual dollar card or domiciliary account card."}},{"@type":"Question","name":"What is the minimum amount to start Google Ads from Nigeria?","acceptedAnswer":{"@type":"Answer","text":"Google does not enforce a strict minimum, but realistic testing starts at $5 to $10 per day. You need at least $5 USD to create a Grey virtual card, plus your ad budget. A practical starting point: $30 in your Grey wallet ($5 for the card, $25 for your first few days)."}},{"@type":"Question","name":"How often does Google charge my card?","acceptedAnswer":{"@type":"Answer","text":"Google uses threshold billing. New accounts start at $50. When your spend reaches the threshold, Google charges your card. The threshold increases over time ($50, $200, $350, $500). Google also charges any remaining balance at the end of the month."}},{"@type":"Question","name":"Will my Google Ads stop if my Grey card runs out of funds?","acceptedAnswer":{"@type":"Answer","text":"Yes. Failed threshold charges pause your campaigns. Google retries within 24 hours. Top up your Grey balance and campaigns resume on the next successful charge."}},{"@type":"Question","name":"What is the small $0.50 charge after I added my card?","acceptedAnswer":{"@type":"Answer","text":"Google's verification hold. It confirms your card is valid and drops off within 3 to 5 business days. It is not a real charge."}},{"@type":"Question","name":"Can I use one Grey virtual card for multiple Google Ads accounts?","acceptedAnswer":{"@type":"Answer","text":"Yes. The same card number can be added as a payment method on multiple Google Ads accounts, including accounts linked under a Manager (MCC) account."}},{"@type":"Question","name":"Is a virtual dollar card safe for Google Ads?","acceptedAnswer":{"@type":"Answer","text":"Yes. Google uses PCI-DSS payment security. Your Grey card details are encrypted and tokenised. You can freeze or delete the card from the Grey app at any time."}},{"@type":"Question","name":"Can I get a refund from Google Ads to my Grey card?","acceptedAnswer":{"@type":"Answer","text":"Yes. Overpayments, paused campaigns with unused balance, or account closure trigger refunds to the card on file. Refunds typically take 5 to 15 business days to appear in Grey."}},{"@type":"Question","name":"My Google Ads account got suspended. Can I create a new one with the same Grey card?","acceptedAnswer":{"@type":"Answer","text":"Do not bypass a suspension by creating a new account. Google links accounts by payment method, device, and IP address. Resolve the suspension through the original account first. Billing-related suspensions usually clear within 24 hours once the outstanding balance is paid."}}]},{"@context":"https://schema.org","@type":"ItemList","@id":"https://grey.co/blog/pay-for-google-ads-in-nigeria#list","name":"How to pay for Google Ads in Nigeria (2026)","numberOfItems":3,"itemListElement":[{"@type":"ListItem","position":1,"name":"Virtual dollar card","url":"https://grey.co/cards"},{"@type":"ListItem","position":2,"name":"Domiciliary account card"},{"@type":"ListItem","position":3,"name":"Bank-issued USD prepaid card"}]}] </script>

How to pay for Google Ads in Nigeria (2026)

The Grey Team

TABLE OF CONTENT

SHARE THIS POST

You set up your Google Ads account. You build the campaign, write the ad copy, and set the budget. Google asks for a payment method. You enter your GTBank Mastercard. Declined. Access Bank Visa. Declined. You check your balance. The money is there. Google gives you nothing useful, just "Your payment method was declined. Please update your billing information."

This is the single most common barrier Nigerian advertisers hit on Google Ads. Unlike Facebook, which offers naira billing via local payment processors, Google Ads does not accept naira payments from Nigeria. Your billing currency must be USD. Every Nigerian advertiser on Google Ads needs a dollar-denominated card, and most Nigerian bank cards cannot reliably process international USD charges.

This guide covers why your card keeps getting declined, every payment method that works in 2026, how Google Ads billing actually works (threshold charges, spending limits, verification holds), and a week-by-week ramp-up plan for new accounts. There is also a section for agencies and creators managing campaigns across multiple platforms and clients.

Why your Nigerian bank card gets declined on Google Ads

Google Ads processes all payments as international USD transactions, with no local billing option for Nigeria. When you add a Nigerian bank card, the charge is processed by your bank as a foreign merchant's request for dollars. Three layers of failure can block it.

Your bank's international transaction policy. Nigerian banks resumed international naira card transactions in July 2025 after blocking them for nearly three years. GTBank, UBA, Access Bank, First Bank, Zenith, and Wema/ALAT are all back online. But the CBN still enforces a $ 20-per-month cap on international naira card spending. A single week of Google Ads budget can exceed that. If you have used any of that $20 elsewhere (Netflix, Spotify, an app store purchase), there is nothing left for Google.

Google's payment processor. Google uses its own payment infrastructure with additional risk checks on cards from certain regions. New cards from unfamiliar issuers, cards with billing addresses that do not match the account's country setting, and cards that have previously been declined on Google all face higher rejection rates. Google's system learns from failures. A card that gets declined three times in a row may be flagged permanently for that account.

The $20 ceiling is the real problem. Even if your bank permits international transactions and Google's system accepts your card, the $20 monthly cap means your campaigns die mid-month the moment your cumulative charges cross that threshold. For any advertiser spending more than $20 per month on Google Ads (which is essentially all of them), a naira bank card is not a viable payment method.

Payment methods that work for Google Ads in Nigeria

Since Google Ads requires USD billing, your options are limited to dollar-denominated cards. These three methods work reliably in 2026.

1. Virtual dollar card (recommended)

A virtual dollar card is a USD-denominated Visa or Mastercard issued by a fintech app. You fund it with naira, the app converts to dollars, and the card balance is in USD. When Google charges the card, it is a standard USD transaction. No international gateway friction, no CBN cap, no bank-level blocks.

This is the method most Nigerian digital marketers use in 2026. The card is created in minutes, funded from any Nigerian bank account, and starts working on Google Ads immediately. It also works on Facebook Ads, TikTok Ads, and every other platform that accepts Visa, which means one card covers all your ad platforms.

2. Domiciliary account card

A domiciliary account is a USD-denominated bank account at a Nigerian commercial bank. It comes with a physical USD Visa or Mastercard that Google Ads accepts without international transaction issues.

Bank Min. Balance Card Type Notes
GTBank $100 Visa Most commonly used dom account for ads; online banking available
Zenith Bank $100 Visa/Mastercard Good card acceptance rate; branch setup required
UBA $100 Visa Africard prepaid also available as a lighter option
Access Bank $100 Visa Online and mobile banking support

‍

The advantage: no per-transaction conversion fees. The balance is already in dollars. The disadvantage: funding it. You need actual dollars. If you do not receive USD income directly, you buy forex at market rates through your bank, which typically adds a 1% to 3% spread and requires a visit to a branch. Opening the account takes 1 to 3 business days, including paperwork, ID verification, and a minimum deposit.

As of May 2026, the CBN requires all international money transfer operators to pay remittances in naira at the official rate, which further tightens dollar availability for individuals. For established businesses with regular USD income, a domiciliary account works well. For freelancers and creators who earn in naira, a virtual card is faster and cheaper to set up.

3. Bank-issued USD prepaid card

UBA Africard, Wema/ALAT dollar card, and Zenith USD prepaid cards can be loaded with dollars and used online. They work on Google Ads because they are USD-denominated. The catch: funding them often requires visiting a branch, minimum load amounts apply, and some cards have monthly spending caps lower than what active advertisers need. These work as a backup but not as a primary payment method for scaling campaigns.

How to set up a Grey virtual card for Google Ads

With Grey, the setup takes about 10 minutes:

Step 1: Create your Grey account. Download the Grey app or go to grey.co. Sign up with your email and phone number, then verify your identity with your NIN. Grey is a licensed financial services provider, not a bank.

Step 2: Convert naira to USD. Transfer naira from your bank to your Grey account, then convert to dollars inside the app. Grey deducts a 1% conversion fee from the naira amount before converting. The fee is capped at the naira equivalent of $6, so on larger conversions, you never pay more than $6, regardless of the amount.

Here is what the conversion looks like on N100,000:

Step Amount
Naira you enter N100,000
Grey conversion fee (1%) - N1,000
Amount that gets converted N99,000
Multiplied by today's rate (check the app) x rate shown at time of conversion
USD you receive Displayed before you confirm

‍

You see the rate and the exact USD output on screen before confirming. If the rate moves between opening the screen and tapping Convert, the app updates it.

Step 3: Create your virtual card. Go to Cards in the Grey app and create a new virtual card. It costs $4 to create, with a $1 funding deduction from your USD balance. You need at least $5 USD when creating the card. It’s a one-time cost, no monthly or annual fee.

Step 4: Add the card to Google Ads. In your Google Ads account:

  1. Click the tools icon in the top navigation bar.
  2. Under Billing, select Payment Methods.
  3. Click Add Payment Method.
  4. Select Credit or Debit Card.
  5. Enter the card number, expiration date, and CVV from your Grey app.
  6. Confirm your billing currency is set to USD (it should be by default for Nigerian accounts).
  7. Save.

Google will send a small verification charge to your card (usually $0.00 to $1.00). This is not an actual charge. It is a test to confirm the card is valid. The hold drops off within a few days. Do not worry if you see a small pending transaction immediately after adding the card.

Step 5: Run your campaigns. Google charges your card when you hit a billing threshold or at the end of the month. The card works like any standard Visa.

For a detailed explanation of how threshold billing works, how to find your invoices, and how to reconcile Google Ads spend with your naira-denominated business accounts, see Google Ads Billing and Invoices for Nigerian Businesses.

Since both your Google Ads billing and your Grey virtual card are in USD, the transaction is a domestic USD charge. Grey's 2% + $0.50 cross-border fee only applies to non-USD merchant charges. For standard Google Ads payments billed in USD, you pay the ad cost and nothing else beyond your initial naira-to-dollar conversion.

How Google Ads billing works

Google Ads uses threshold billing, and understanding it prevents the most common payment surprises.

When you create your account, Google sets a billing threshold, typically $50. Every time your ad spend reaches that threshold, Google charges your card. If you spend $50 in three days, you get charged on day three. If it takes two weeks to spend $50, you get charged at the two-week mark. At the end of each month, Google also charges any remaining balance below the threshold.

As your account builds payment history, Google raises the threshold automatically:

Threshold Level Typical Amount When It Increases
Starting $50 Set when account is created
Second $200 After several successful payments at $50
Third $350 After consistent payment history
Fourth $500 Established accounts with no payment issues

‍

Higher thresholds mean fewer charges, but larger individual amounts hitting your card. A $20/day advertiser with a $200 threshold gets charged roughly $200 every 10 days, not $20 per day. If your Grey virtual card has $150 when a $200 threshold charge hits, the payment fails, and campaigns pause.

How to check your current threshold and payment history: In Google Ads, click the tools icon, go to Billing, then Summary. Your current threshold is shown under How you pay. Your full transaction history, including pending charges and completed payments, is listed under Transactions. You can download invoices from here as PDFs for accounting purposes.

Switching your payment method: To replace one card with another, go to Payment Methods, click Manage next to your current card, and select Remove. Then add your new card. Google does not support multiple active payment cards. Only one card can be the primary payment method at a time.

New account ramp-up: the week-by-week plan

Google restricts new accounts to a low daily spend limit, typically $50 per day or less. This is separate from the billing threshold. Even if your Grey virtual card has $1,000, Google will not let a brand-new account spend $500 on day one.

Most Nigerian advertisers who hit "payment declined" on a new account are actually hitting the spending limit, not a card problem. Here is the ramp-up plan that avoids both payment declines and account flags:

Timeline Action Daily Budget Grey Balance Needed
Day 1 Create account, add Grey card, launch first campaign with a low budget. Google sends a verification hold ($0-$1). $10-15/day $30 minimum ($5 card + $25 budget)
Day 3-4 First threshold charge hits (~$30-50). Confirm it has been processed. If it did, your card is verified with Google. $10-15/day Top up if balance dropped below $50
Day 7 Increase daily budget. Google's system has seen a successful payment cycle. $20-30/day $100+ recommended
Day 14 Increase again if performance justifies it. Google may raise your threshold from $50 to $200 around this time. $30-50/day $200+ to cover new threshold
Day 30 Account is established. Spending limits are significantly higher. Scale to your target budget. Your target Keep 2x your threshold as buffer

‍

The key principle: Google rewards patience and consistency. A new account that spends $15/day for two weeks with zero payment failures has more credibility than one that tries to spend $200 on day one and gets declined three times. Those three declines can flag your card on that account permanently.

When Google charges you in a currency that is not USD

When you run Google Ads campaigns targeting audiences outside Nigeria, Google may bill some charges in the target country's local currency rather than your account's billing currency. Campaigns targeting Brazilian audiences may generate charges in BRL. UK campaigns may bill in GBP. European campaigns in EUR. Indian campaigns in INR. This happens because Google prices some ad inventory in the local currency of the market you are targeting, regardless of what your billing currency is set to.

When any of these non-USD charges hit your Grey virtual card, the 2% + $0.50 cross-border fee applies to that specific charge. The fee is per transaction and applies only to the non-USD portion. If you spend $100 across campaigns and $50 is billed in a foreign currency, the cross-border fee applies to the $50 foreign-currency portion only. Your USD-billed charges are unaffected.

If you run campaigns targeting multiple countries, budget an extra 2%-3% on top of your ad spend for non-USD markets. For campaigns targeting Nigeria, the US, or any other market where Google bills in USD, no cross-border fee applies.

YouTube Ads and Google Shopping

Both YouTube Ads and Google Shopping campaigns run through the same Google Ads account and use the same payment method. If your Grey virtual card is set up for Google Search campaigns, it automatically works for YouTube and Shopping with no additional configuration.

YouTube Ads for creators

Nigerian creators promoting their YouTube channels use Google Ads to run video discovery campaigns and in-stream ads. Billing works the same way as search campaigns: USD threshold billing is charged to your Grey virtual card. YouTube ad costs in Nigeria are lower than in many other markets, typically $0.01 to $0.05 per view for well-targeted campaigns. A $10/day budget can generate 200 to 1,000 views depending on your targeting and creative.

One thing to note: YouTube ad campaigns cannot be created from the YouTube app. You must use Google Ads (ads.google.com) to set up and manage YouTube campaigns. The payment method is the one attached to your Google Ads account, not any payment method linked to your YouTube channel.

Google Shopping for e-commerce

Nigerian e-commerce businesses using Google Shopping (Performance Max or standard Shopping campaigns) face the same payment setup. Connect your Google Merchant Center to your Google Ads account, and Shopping campaigns bill through the same Grey virtual card. No separate payment method needed. Product feed issues are more common than payment issues for Shopping campaigns, so if your Shopping ads are not running, check Merchant Center diagnostics before assuming it is a billing problem.

How to calculate your actual cost

Google Ads from Nigeria has one path: USD. Here is the cost formula:

Your cost = (ad budget in USD x Grey app's naira-to-USD rate) + 1% conversion fee (capped at ~$6) + $5 one-time card creation (first time only).

On a $100 campaign: open the Grey app, check the conversion rate, and multiply. If the rate gives you $1 for every N1,415, you deposit approximately N141,500. Grey takes 1% (N1,415) as the conversion fee, converts the remaining N140,085, and you receive roughly $99. Add $5 for card creation on your first campaign. Second campaign onward: just the deposit plus the 1% fee.

Grey Virtual Card Domiciliary Account Ad Reseller
Conversion fee 1% (capped at ~$6) Bank forex spread (1-3%) 5%-15% markup
Card/setup cost $5 one-time $100+ minimum deposit + branch visit None
Cross-border fee None on USD charges None on USD charges N/A
Funding speed Minutes (bank transfer to Grey) Days (forex purchase + branch) Hours to days
Time to first campaign 10 minutes 1-3 business days Depends on reseller
Works on Facebook/TikTok? Yes, same card Yes, same card Depends on reseller
Exchange rate visibility Shown before you confirm Bank-set, may vary Hidden

‍

For agencies: Manager accounts and multi-client billing

If you run a digital marketing agency or manage Google Ads for multiple clients, Google's Manager account (MCC) lets you oversee all client ad accounts from one dashboard. The billing question: can one Grey virtual card pay for multiple client accounts?

Yes, but with a structured decision. Google offers two billing models for Manager accounts:

Per-account billing: Each client ad account has its own payment method. You add your Grey virtual card (or the client's card) to each account individually. Charges appear separately per account in your Grey transaction history. This is the cleanest setup for reconciliation because each charge maps to one client.

Consolidated billing (Manager account pays): The Manager account's payment method covers all linked client accounts. One Grey virtual card, one set of charges. Google consolidates the billing, and you receive a single invoice covering all accounts. This is simpler to manage but harder to reconcile per-client spend. You need to cross-reference Google Ads reporting with your Grey transaction history to allocate costs.

For most Nigerian agencies, per-account billing is the better choice. If a client's campaigns overspend or a client's account gets flagged, it does not affect billing on your other accounts. One Grey card can be added to multiple Google Ads accounts. The card number is the same across accounts.

Google Ads promotional credits

Google frequently offers promotional credits to new Nigerian advertisers. These typically follow a "spend X, get X free" format: spend N10,000 in ad budget and Google adds N10,000 in free credits to your account. The exact offer varies by promotion and changes regularly.

A few things to know about how credits interact with virtual cards:

Credits apply after your real spend. You need to fund and then spend the qualifying amount. Google bills your Grey card for the qualifying spend, then adds the promotional credit to your account. The credit burns down on subsequent ad spend before Google charges your card again.

Credits are denominated in your billing currency. Since your account is in USD, credits appear as dollar amounts. If you received the promotion through a naira-denominated landing page, Google converts it to your billing currency.

Credits expire. Most promotional credits expire 60 to 90 days after being applied. If you do not use them within that window, they disappear. Plan your campaign spend accordingly.

Credits do not change your billing setup. You still need a valid payment method (your Grey virtual card) attached to the account, even if your current spend is covered by credits. Google will not run campaigns without a backup payment method on file.

Troubleshooting: common issues

"Payment method declined" on first attempt

Start small. Add $10 to $20 to your Grey virtual card and let Google process the first charge. Google flags new cards from unfamiliar issuers more aggressively. Once the first payment clears, increase your budget over the first week.

Small $0.50 or $1.00 charge you did not expect

This is Google's card verification hold. When you add a new payment method, Google sends a small temporary charge to confirm the card is valid. It is not a real charge and drops off within 3 to 5 business days. Do not remove your card or dispute the charge. It resolves itself.

Card worked before but now fails

Check two things. First, your Grey USD balance: Google charges at billing thresholds, not daily. A $200 threshold charge, with a $150 balance, will fail. Second, whether Google raised your threshold recently. If it jumped from $50 to $200, your next charge is significantly larger than the previous ones. Keep at least 2x your current threshold in your Grey wallet.

"This card has been declined too many times"

Google tracks the decline history per card. After multiple failures, Google may permanently flag that card number. Remove the card from Payment Methods, then re-add it. If the card number changed (Grey occasionally rotates numbers for security), update with the current details from the app. If the same number still gets rejected, contact Google Ads support to clear the decline flag.

Charged in a non-USD currency unexpectedly

Check your campaign targeting settings. Google bills some ad inventory in the target country's local currency (BRL for Brazil, GBP for the UK, EUR for Europe, INR for India, and others). This is normal. The cross-border fee on your Grey virtual card applies to these non-USD charges. To avoid it, restrict targeting to USD-billed markets, though this limits your reach.

Google suspended my account after payment failure

Google suspends accounts with unpaid balances. Go to Billing & Payments and resolve the outstanding balance with your Grey virtual card. Suspension lifts within 24 hours in most cases. Do not create a new account to bypass it. Google links accounts by payment method, device, and IP address. A second account with the same card gets suspended immediately.

Ads approved but not spending

If your ads are approved but show zero impressions, the issue is usually the new account spending limit, not your payment method. Google has approved your ads but is throttling delivery because the account is new. Follow the ramp-up plan above. Wait 3 to 5 days for delivery to start, then check again. If it persists for more than a week with a $10-$20 daily budget, contact Google support.

Using the same card for Facebook Ads and TikTok

If you are already running Google Ads with a Grey card, adding it to other platforms takes seconds. The same card works on Meta Ads Manager (Facebook and Instagram), TikTok Ads, Amazon Advertising, LinkedIn Ads, Twitter/X Ads, and any platform that accepts Visa.

For Nigerian creators and agencies managing spend across multiple platforms, the main advantage is this: one USD balance, one card, one transaction history. If you are also paying for subscriptions (ChatGPT Plus, Canva Pro, Shopify, and domain renewals), the same card covers those as well.

For the Facebook-specific guide, including the naira billing path that Google does not offer, see How to Pay for Facebook Ads in Nigeria.

Frequently asked questions

Can I pay for Google Ads with naira?

No. Google Ads does not offer naira billing for Nigerian accounts. Your billing currency must be USD. You need a dollar-denominated card.

Can I use my GTBank or Access Bank naira card for Google Ads?

Unlikely for sustained use. Nigerian banks resumed international card transactions in July 2025, but the CBN caps international naira card spending at $20 per month. Any advertiser spending more than $20 per month needs a virtual dollar card or domiciliary account card.

What is the minimum amount to start Google Ads from Nigeria?

Google does not enforce a strict minimum, but realistic testing starts at $5 to $10 per day. You need at least $5 USD to create a Grey virtual card, plus your ad budget. A practical starting point: $30 in your Grey wallet ($5 for the card, $25 for your first few days).

How often does Google charge my card?

Google uses threshold billing. New accounts start at $50. When your spend reaches the threshold, Google charges your card. The threshold increases over time ($50, $200, $350, $500). Google also charges any remaining balance at the end of the month.

Will my Google Ads stop if my Grey card runs out of funds?

Yes. Failed threshold charges pause your campaigns. Google retries within 24 hours. Top up your Grey balance and campaigns resume on the next successful charge.

What is the small $0.50 charge after I added my card?

Google's verification hold. It confirms your card is valid and drops off within 3 to 5 business days. It is not a real charge.

Can I use one Grey virtual card for multiple Google Ads accounts?

Yes. The same card number can be added as a payment method on multiple Google Ads accounts, including accounts linked under a Manager (MCC) account.

Is a virtual dollar card safe for Google Ads?

Yes. Google uses PCI-DSS payment security. Your Grey card details are encrypted and tokenised. You can freeze or delete the card from the Grey app at any time.

Can I get a refund from Google Ads to my Grey card?

Yes. Overpayments, paused campaigns with unused balance, or account closure trigger refunds to the card on file. Refunds typically take 5 to 15 business days to appear in Grey.

My Google Ads account got suspended. Can I create a new one with the same Grey card?

Do not bypass a suspension by creating a new account. Google links accounts by payment method, device, and IP address. Resolve the suspension through the original account first. Billing-related suspensions usually clear within 24 hours once the outstanding balance is paid.

Related reading

How to Pay for Facebook Ads in Nigeria (2026) covers naira and USD payment paths for Meta Ads, including bank-by-bank card compatibility.

Google Ads Billing, Invoices and Payments for Nigerian Businesses covers threshold billing, VAT invoices, reconciliation, and month-end accounting for established advertisers.

Best Virtual Dollar Cards in Nigeria (2026) compares virtual card options for all international payments.

How to Pay for ChatGPT Plus from Nigeria covers subscription payments using the same Grey card setup.

Alternatives to Domiciliary Accounts in Nigeria compares Grey to traditional bank-issued dollar accounts.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to use Apple Pay worldwide with your Grey card

•

•

2 min read

There’s a specific kind of fatigue that comes from living globally. Not from flights or visas, but from the tiny negotiations of daily life. Figuring out which card will work. Wondering if the terminal will accept it. Keeping mental notes of what to try next.

When you add your Grey virtual card to Apple Pay, you remove one layer of uncertainty. All you need to do is tap, and the payment goes through.

Why your Grey virtual card pairs so well with Apple Pay

If you’ve ever struggled with cards that randomly fail abroad or get blocked on international platforms, you’ll feel the difference immediately. We built the Grey virtual card built for global use, and Apple Pay simply amplifies that experience.

Let's discuss why the Grey card + Apple Pay  combination works so seamlessly.

One card that adapts to your life

Your Grey virtual card is directly linked to your balance. There’s no need to top up before paying or shuffle funds between wallets. You choose what you want to buy, Apple Pay handles the tap, and the payment goes through.

Designed for international spending

Fewer card declines. Better compatibility with global merchants. Clearer transactions. Whether you’re paying locally or online, Apple Pay with Grey is consistent and predictable, at home and abroad

Contactless, effortless, and global

Apple Pay is accepted in millions of locations worldwide. From supermarkets and cafés to trains, taxis, and co-working spaces, your phone becomes your payment tool. Combined with Grey’s global card functionality, spending across countries becomes second nature.

Built-in security that travels with you

Apple Pay never shares your full card details with merchants, and the Grey virtual card supports 3D Secure for online transactions. Together, they offer a safer way to shop, subscribe, and spend internationally without constant worry.

Also read: How to use your Grey card to manage all your subscriptions

Who benefits most from using Apple Pay with the Grey Visa card?

This Grey Card + Apple Pay setup is designed for people who spend often across borders.

Travellers and frequent movers

When your Grey Visa card is added to Apple Pay, you can move through airports, metros, shops, and cafés with just your phone. No fumbling, no cash exchanges, no stress at the counter.

Freelancers and remote professionals

If you earn from international clients or pay for tools hosted abroad, Apple Pay gives you a fast, reliable way to manage everyday spending. Subscriptions, software, ads, and services all become easier to handle.

Business owners and creators

From running ads to paying for platforms like Canva, Google Workspace, or Notion, Apple Pay with Grey keeps your operations smooth and interruption-free.

How to add your Grey Visa card to Apple Pay

Setting up Apple Pay with your Grey virtual card takes just a minute:

__wf_reserved_inherit

Once added, you can use Apple Pay for in-store contactless payments, online checkouts, in-app purchases, and public transport wherever Apple Pay is accepted.

Where you can use Apple Pay with your Grey virtual card

With Apple Pay accepted in dozens of countries, your Grey virtual card becomes a global companion. You can use it to:

  • Pay in cafés, shops, and supermarkets worldwide
  • Book flights, hotels, and short stays
  • Subscribe to services like Spotify, Apple Music, Netflix, Canva, and YouTube
  • Pay for transport, food delivery, and everyday essentials
  • Handle online payments securely across international platforms

Your Grey balance does the heavy lifting, while Apple Pay keeps everything fast and contactless.

Why is it important to use a virtual card with Apple Pay?

Too many people are still dealing with cards that weren’t built for global lives. Unexpected declines. Confusing restrictions. Payments that work one day and fail the next.

The Grey virtual card changes that. Paired with Apple Pay, it creates a payment experience that feels modern, reliable, and genuinely global.

Create your Grey virtual card now, add it to Apple Pay, and tap your way through the world with confidence.

often spend

Grey virtual card vs Chipper, Geegpay, and others: 2026 comparison

•

•

2 min read

Different virtual cards work differently depending on how you spend, where you shop, and which currencies you use. Some excel at simple travel spending, others at multi-currency holding. Some support crypto, others don’t. Understanding the real differences helps you pick which one works for you.

Today, I’m comparing the Grey card with six other well-known virtual card options, just so you know which one works best for you.

1. Wise multi-currency card

If you’ve ever needed a card that is like a multi-currency wallet first and a spending card, Wise probably fits that bill. Wise is widely used as a borderless account with a card that lets you tap into more than 50 currencies and spend internationally at transparent exchange rates.

For many global workers and travellers, such simplicity is appealing. You get the real exchange rate plus a small, clear fee. There are generally no hidden surprises, and you can hold currencies like USD, EUR, or GBP in one place.

Wise also doesn’t support crypto balances, so if you’re someone who keeps part of your funds in digital assets and wants to spend crypto, your Wise card won’t help.

People who want to hold and spend multiple currencies with clear exchange pricing, especially for everyday purchases and travel, will love the Wise card.

Also read: How to shop in the US or Europe with your Grey card

2. Revolut card

Revolut is one of the most talked-about fintech platforms in the world, and its card ecosystem reflects that breadth. You can have both virtual and physical cards, generate disposable virtual cards for added security, and even manage budgeting, investments, and crypto trading all in one app.

It ticks many boxes: multi-currency support, budgeting tools, and virtual card creation. However, the complexity of features can become a hurdle, especially when key perks are tucked behind paid tiers.

Revolut is strong as part of a broader lifestyle finance app, especially for travellers and users who want added perks like travel insurance, purchase protection, and trip disruption coverage, which are included in higher-tier plans such as Premium, Metal, or Ultra. However, these benefits depend on subscription level and eligibility requirements, and coverage is provided through third-party insurers rather than built directly into the card experience.

Its virtual cards can still face issues on international platforms, and the way it converts currencies, including weekend markups, adds a layer of unpredictability for some users.

3. Payoneer card

Payoneer is a name many freelancers, online sellers, and international businesses know quite well. Its card, especially the virtual prepaid card, is excellent for receiving payments from global marketplaces, handling international transfers, and covering business expenses in multiple currencies.

However, many users report sudden card blocks, limited personal support, and slow resolution times, which can be frustrating when you’re trying to pay for everyday subscriptions or online purchases.

In many regions, Payoneer is ideal for business payouts and marketplace earnings; however, it may not be the best option if you require a card for personal multi-currency spending or flexible international use.

Freelancers and businesses requiring comprehensive currency support with global payouts, especially via marketplaces, will appreciate the Payoneer card.

Also read: How to pay online and in stores worldwide with your phone

4. N26 Card

N26 operates as a digital bank primarily across the EU and EEA. Its cards, both physical and virtual, are built around simplicity, with no foreign transaction fees for many currencies and straightforward Mastercard exchange rates.

It works well for everyday spending both within and outside the Eurozone, and virtual cards can be issued quickly as part of the account opening process.

The big limitation, a practical one, is its availability. N26’s services were pulled back from the U.S. and some other markets in recent years, and it remains focused on European customers.

So if you travel frequently within Europe or spend in EUR, N26 cards can be a solid choice. But outside that context, it’s less flexible, especially for global needs.

LDMAG1

5. Crypto-linked cards

Crypto cards deserve their own mention. Cards like the Coinbase Card and Crypto.com Visa Card allow you to spend cryptocurrency by instantly converting it to fiat at the point of sale. These are especially interesting for people who live or earn in digital assets and want to use them without extra conversion steps.

For example, Binance’s card (in regions where it is still supported) offers significant cashback rewards in BNB, and Coinbase lets you spend multiple crypto assets directly, with rewards in crypto.

The downside is that these cards often tie you into a specific exchange ecosystem, may carry higher fees for some transactions, and their rewards are typically token-based — valuable if you’re bullish on crypto, less so if you’re not.

I’ll recommend these cards for crypto holders who want to spend digital assets with conversion at checkout and enjoy token rewards.

6. Traditional bank virtual cards

There’s a whole category of virtual cards issued by traditional or app-based banks, like Monzo (UK), Starling (UK), or wallet-front cards like Curve.

These are solid for everyday use, especially in their home markets, and often integrate well with Apple Pay/Google Pay. However, international currency support varies widely; some have foreign transaction fees, others rely on slower underlying banking rails, and they’re sometimes limited in where they’ll work for recurring payments or certain ad platforms.

For many users, these cards are excellent backups or complementary payment methods. But if your life or work relies on consistent, global spending, their limitations become noticeable.

7. Grey card offers a more flexible virtual global spending experience

By now, it should be clear: not all virtual cards are the same. Some are designed for holding money, others for daily banking, and others still for specific ecosystems.

Grey’s approach sits in a different space from the others above. Your card works across fiat (USD, EUR, GBP, local currency) and stablecoins (USDC), eliminating the need to get an extra crypto card. Your Grey card automatically pulls funds from your available balances in the following order: USD, USDC, and then the next highest available balance.

You can also create multiple cards for different purposes, such as travel, subscriptions, personal, and business. Still, each card will work seamlessly without requiring you to select which balance to spend from. We built the Grey virtual card for people who:

  • Spend in multiple currencies regularly
  • Want predictable outcomes at checkout
  • Value clear messaging and control
  • Need support for both fiat and crypto balances

Instead of requiring top-ups or rigid currency conversion steps, your Grey card automatically draws from your available balances, making spending across fiat and stablecoin currencies effortless.

Many of the other options we’ve discussed above are great in their contexts. However, each has trade-offs that make it difficult to be everything to everyone.

Also read: How to budget in foreign currencies using the Grey card

So, which card is right for you?

There’s no single answer, but here’s a quick way to think about it:

  • If you want clear, no-nonsense multi-currency holding and spending, Wise or N26 are strong choices.
  • If you’re looking for a financial super app with perks, Revolut is a great fit.
  • If you earn or spend in crypto and enjoy token rewards, crypto cards like Coinbase or Crypto.com are worth exploring.
  • If you want a card that automatically draws from different balances, supports multiple cards, and makes international or multi-currency spending predictable globally, we built Grey for your lifestyle.

Different cards shine in various life scenarios. The key is knowing which trade-offs matter to you, and how your day-to-day spending looks.

Choose with clarity, and let your card work for you, not the other way around. Create your Grey visa card and enjoy a smoother, more inclusive, and more predictable global spending experience.

‍

How to budget in foreign currencies using the Grey card

•

•

2 min read

Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.

Then remote work happened.

Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you also need structure because, without proper structure, even the most careful spender can lose track of where their money is going.

Your Grey card is a practical budgeting tool for people who live, work, earn, and spend across borders. I’ll explain.

Why budgeting in multiple currencies breaks down so easily

Many people who overspend don't do so because they’re irresponsible. But because their money isn’t organised in a way that reflects how they live.

It’s pretty common to be juggling subscriptions in USD, running ads in EUR, buying coffee in GBP, and somehow all on the same card. Eventually, everything blurs together. You can no longer track your Netflix renewal, that Facebook ad campaign, the flight you booked last week, or the coworking space membership. Then one day you check your balance and think, “Where did all that money go?” You know you spent it. You just can’t figure out where, or why, it felt like so much more than you expected.

It’s not that you’re careless. It’s that your money isn’t organised in a way that matches how you actually live and work. And once things start blurring, it’s nearly impossible to untangle without spending an hour combing through statements, converting currencies in your head, and still not feeling certain you’ve caught everything.

At that point, your budget is broken.

Also read: How to use your Grey card to manage all your subscriptions

What should budgeting look like when you earn and spend globally?

Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:

  • See exactly what each type of spending is costing you.
  • Stop or pause spending instantly when needed.
  • Protect one part of your budget from another.
  • Make changes without disrupting everything else.

The Grey card is designed around solving these exact needs.

How does the Grey card help with budgeting?

Use multiple cards to separate your spending

One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes. Your Grey virtual card helps you structure your spending as such.

For example, you can create:

  • One card for subscriptions and recurring tools
  • One card for ads and growth experiments
  • One card for travel or everyday spending
  • One card per client or project

Each card acts like its own budget lane, pulling from the same balance. You don’t need to guess where the money went because you already know.

This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.

Also read: How to pay for ads easily with your Grey card

Freeze cards instantly when spending goes off-track

Budgets fail when you can’t act fast enough.

With the Grey card, you can instantly freeze or unfreeze any card in the app. If a digital ad campaign starts burning through too cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.

Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.

Set limits that protect your budget

Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.

You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.

For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.

Track spending clearly in one place

When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.

When budgeting time comes around, you’re not sitting there trying to remember what that mysterious €47 charge was three weeks ago or why your USD balance dropped. Everything’s already categorised. The structure did the work for you.

Spend confidently across borders

Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.

A quick note on protection when spending abroad

An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.

When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.

It’s one less thing to worry about while managing money across borders.

Also read: How to claim your Visa card benefits

What budgeting in foreign currencies is like with the Grey card

When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency your spend is coming from and more importantly, when something changes.

Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.

If you’re ready to make your budget work wherever you are, create or update your Grey card today and start spending and budgeting in the ways that matter to you.

‍

How to shop in the US or Europe with your Grey card

•

•

2 min read

A few months ago, I was eyeing a pair of sneakers on a US website for weeks. Then the store started running sales and I decided to buy them (hashtag #YOLO), but my bank card declined the payment.

Not once, not twice… but four times!.

The same card that worked perfectly in Nigeria where I live, and the same details I’d used for years. I tried to get another card, but by then, sales had ended, and the sneakers were out of stock. It was annoying, but I just had to accept my L.

If you’ve ever tried to shop internationally, on sites like ASOS UK, Amazon US, Zara EU, or even the Apple Store, you may already be familiar with this pain. Sometimes the website rejects your card. Sometimes your bank blocks the transaction. Sometimes the currency conversion takes too long, and the payment times out.

It shouldn’t be this difficult to buy something online in big 2026… yet for many people, it still is.

But if you use a Grey card, you'll eliminate the uncertainty of thoughts like, “Will this payment go through?”, and transform your international shopping into a simple and predictable process.

Why shopping abroad is often frustrating

Shopping from US or European stores usually comes with these hurdles:

1. Many foreign merchants decline local cards

Some US/UK online stores automatically reject certain African-issued cards, even if you have more than enough balance.

2. Stores bill strictly in USD, GBP, or EUR

If your card requires manual currency conversion, it can cause payment delays that may result in declines.

3. Banks block “suspicious” international transactions

This usually happens when the merchant is unfamiliar.

4. Conversion errors and hidden fees

Some cards convert long after the purchase, leading to surprises on your statement.

These problems are common, but they’re also exactly what Grey card is built to avoid.

How your Grey card makes shopping internationally easy

Smart spending across multiple currencies and USDC

Your Grey card doesn’t require you to pick or switch wallets before paying. Instead, it automatically spends from your balances. Your USD account is debited first; if that’s empty, your USDC, and then the highest of your remaining balances.

This means your payment goes through as long as you have funds available in your account, without requiring you to consider currencies at checkout.

Works across major US and European stores

Your Grey card is an international spend card, so you can pay at 150 million merchants worldwide.

Use Apple Pay and Google Pay

For stores that support mobile wallets, you can simply add your Grey Visa card to Apple Pay or Google Pay. This is more secure and makes for much faster checkouts.

Create multiple cards for better organisation

If you shop frequently or mix personal and business purchases, you can:

  • Use one card for personal shopping
  • another for business imports
  • another for gift purchases

It keeps your spending clean and easy to track.

Freeze and unfreeze anytime

You can always freeze your cards to control your spending.

Better protection for online transactions

You receive real-time notifications, card controls, and instant limits - everything you need for peace of mind when buying from foreign sites.

LDMAG1

How to shop in the US or Europe with your Grey card

1. Request your Grey visa card

Create a Grey account and go to the cards section of your Grey app to request a Grey card for $5.

2. Add your card to the store’s checkout

Enter your card details or simply pay through Apple Pay/Google Pay.

3. Make your purchase normally

Shipping, duties, and taxes will be displayed as they are for every other international shopper.

4. Track everything in your Grey app

Every charge, refund, or verification appears instantly, so there are no surprises later.

Tips for smarter international shopping

  • Use a separate card for business or bulk purchases so you can easily track expenses.
  • Keep a bit extra in your wallet for shipping fees and taxes.
  • Use Apple Pay/Google Pay when available. It’s the most seamless way to tap and pay, and also supports contactless payments.

Shopping abroad doesn’t have to be stressful

Your Grey card helps you shop with confidence. There are no random declines or conversion drama. Ahead of your next international purchase, you can create your Grey card and enjoy a smoother, more predictable shopping experience.

‍

Best way to receive US dollar payments in India

•

•

2 min read

The default way Indian banks handle inbound USD is: receive the wire, convert to INR immediately at their own rate, credit your account in rupees, and deduct fees at every step. You never see the dollars. You never choose the conversion rate. You never decide when to convert. The bank decides all three, and the bank's rate is never the mid-market rate. That automatic conversion is where freelancers, consultants, and remote workers lose the most money on international payments.

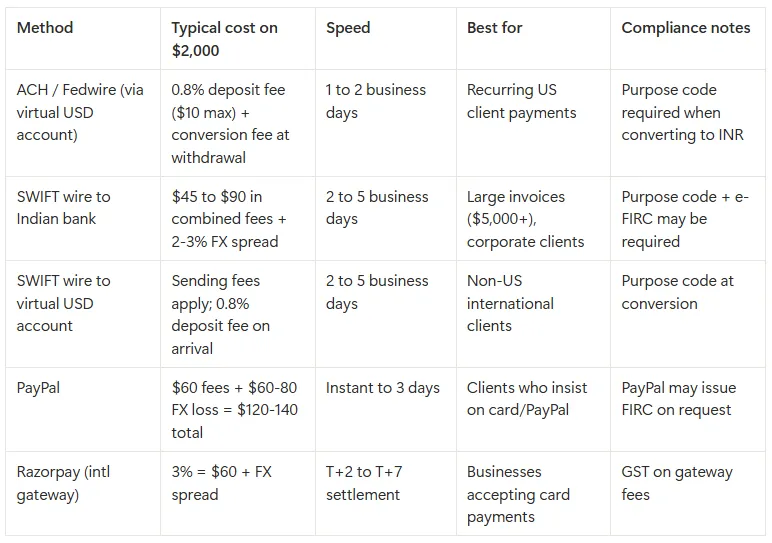
The cost of this setup is not small. A 2% to 3% FX spread on every transfer, intermediary deductions on SWIFT wires, and receiving bank charges add up to lakhs lost annually for anyone earning regular USD income. This guide covers the four main ways to receive US dollar payments in India, what each one actually costs on a real invoice, the compliance requirements (purpose codes, FIRC, FEMA) that most payment guides skip entirely, and how to set up an infrastructure that gives you control over when and at what rate your dollars become rupees.

The four main ways to receive USD in India

1. US ACH or Fedwire transfers

ACH (Automated Clearing House) and Fedwire are US domestic transfer systems. When a US client pays you via ACH or Fedwire, the money moves within the US banking system to a US-based account. This is important because US companies strongly prefer paying vendors through their domestic payment rails. Their finance teams process ACH payments the same way they pay local contractors, which means less friction on the client side and faster approval on yours.

ACH transfers typically cost the sender nothing or a small flat fee (usually under $1). Fedwire transfers may cost the sender $15 to $30, depending on their bank. On your end, the cost depends on where the funds land. If you are receiving into a virtual USD account from a fintech provider, the provider charges a deposit fee (Grey charges 0.8%, minimum $2, maximum $10). There is no intermediary bank deduction because the payment never leaves the US banking system.

ACH is best for recurring payments from US-based clients, such as monthly retainers, project milestones, or regular consulting fees. If most of your clients are American, setting up a virtual USD account that supports ACH and Fedwire deposits is typically the lowest-cost option for regular income.

2. International wire transfers (SWIFT)

SWIFT is the global messaging network that banks use to route cross-border payments. When a client outside the US (or a US client whose bank does not support ACH to your provider) sends you a wire transfer, it travels through the SWIFT network. This is the most universally accepted method, but it is also the most expensive.

The costs stack up at multiple points. The sending bank charges a wire fee, typically $20 to $50, depending on the country and bank. If the payment routes through an intermediary (correspondent) bank, that bank deducts another $10 to $25 from the transfer amount. Your receiving bank may charge an additional inward remittance fee of $5 to $15. On a $2,000 invoice, total fees can range from $45 to $90, which is 2.25% to 4.5% before any currency conversion. Settlement takes 2 to 5 business days.

SWIFT makes sense for large, infrequent payments where the fixed fees represent a smaller percentage of the total: invoices above $5,000, corporate contracts, or one-off project payments. For smaller recurring payments, the per-transfer cost makes SWIFT significantly more expensive than ACH.

Also read: Top platforms to earn US dollars in India

3. Payment aggregators

Payment aggregators collect funds from your client (usually via card or local bank transfer) and remit the proceeds to your Indian bank account. The most common ones Indian freelancers encounter are PayPal, Razorpay (for businesses accepting international payments), and Stripe (with limited availability for payouts in India).

PayPal charges 2.99% on incoming goods and services payments, plus a currency conversion spread of 3% to 4% above mid-market when you withdraw to INR. On a $2,000 payment, that is roughly $60 in transaction fees plus $60 to $80 in conversion loss, totalling $120 to $140. Razorpay's international payment gateway charges 3% per transaction for international cards. These platforms are convenient for clients who prefer paying by card or who are not set up for bank transfers, but the cumulative cost is the highest of all four methods.

Aggregators are best for small, one-off projects where the client insists on paying by card, or for marketplace payouts (Upwork, Fiverr) where the platform dictates the payment method.

4. Cross-border transaction caps

India's cross-border payment framework includes transaction-level limits in certain categories. Some payment setups cap individual cross-border transactions at ₹25 lakh per unit of goods or services. If your invoice size approaches that range, bank-led rails such as SWIFT are usually more suitable than aggregator platforms. Having access to a USD receiving account through a provider like Grey gives you more flexibility when handling higher-value international payments, because the funds arrive in USD first and you control the conversion timing and method.

How the four methods compare

__wf_reserved_inherit

The compliance layer most freelancers overlook

Receiving USD payments in India is regulated under the Foreign Exchange Management Act (FEMA) and RBI reporting guidelines. Getting the compliance right upfront prevents delays, frozen transfers, and problems during audits.

Purpose codes

Indian banks require a purpose code on every inward remittance to classify the transaction under FEMA. Common codes for freelancers include those for software development, consulting, and marketing services. These codes are defined under the RBI purpose code list for inward remittances. Providing the correct code on your invoice and communicating it to your client's bank reduces the risk of your payment being held for manual review. Vague or missing purpose codes are one of the most common reasons for delayed credits.

You may also like: How to receive money from UK clients in India

FIRC and e-FIRC

If you export services (which includes freelancing for foreign clients), you may need a Foreign Inward Remittance Certificate (FIRC or e-FIRC) for GST export documentation, audits, and platform compliance. Only authorised dealer banks issue e-FIRC documentation. Confirm your bank's process for issuing these certificates in advance, because requesting them after the fact can take weeks. If you receive payments through a virtual USD account and then transfer to your Indian bank, the e-FIRC is issued by the Indian bank that receives the final INR credit.

‍

Export realisation timelines

India requires that export proceeds be realised (received in India) within a prescribed period. Long-pending invoices can create compliance issues. Keep your documentation organised and follow up on overdue payments early. For a complete explanation of FIRC requirements, tax implications, and RBI compliance rules, see Grey's guide on FIRC, taxes, and compliance for Indians earning foreign currency.

Which setup is right for your situation

The right payment method depends on three factors: where your clients are located, your average invoice size, and whether you want to hold USD or convert to INR immediately.

For most clients in the US, a virtual USD account that supports ACH and Fedwire is typically the lowest-cost option. Your US client pays you the same way they pay a local vendor. You receive the funds in USD, hold them until you are ready to convert, and withdraw to your Indian bank at a rate and time you choose. SWIFT works as a backup for clients whose banks do not support ACH to their provider.

Global clients across multiple countries: Ensure your account can receive international SWIFT wires without intermediary deductions eating into your payment. A multi-currency account lets you hold USD, GBP, or EUR and convert only when the rate is favourable, rather than accepting your bank's automatic conversion on arrival.

Large invoices ($5,000+): Direct bank rails (SWIFT or Fedwire) are preferable to aggregator platforms. The fixed fees are lower as a percentage of the total than the percentage-based fees aggregators charge. A $10,000 invoice through PayPal costs roughly $600-$700 in combined fees and FX losses. The same invoice received via SWIFT to a virtual USD account costs $10 in deposit fees plus the conversion cost when you move to INR.

Priority is maximising take-home INR. Compare the total cost at every step: incoming transfer fees, deposit fees, FX margin versus the mid-market rate, and withdrawal fees. Small differences in FX margins compound significantly over a year of regular payments. A 1% difference on $3,000 per month is $360 annually.

Also read: A guide for Indians getting paid by clients abroad

Common mistakes to avoid

Relying on a single payment method leaves you exposed if that channel has downtime, compliance issues, or fee changes. The safest setup is ACH or Fedwire as your primary rail with SWIFT as a fallback. Ignoring FX spreads is the most expensive mistake: the difference between mid-market and a 3% markup on $2,000 is $60 per transfer. Waiting until a compliance request arrives to organise your documentation can delay your funds for days or weeks. Sending invoices without detailed service descriptions triggers manual review at Indian banks because the purpose of the remittance is unclear. Include the service type, project reference, and your client's details on every invoice.

How Grey works for Indian freelancers receiving USD

Grey provides Indian freelancers, consultants, and remote professionals with USD, GBP, and EUR foreign currency accounts that can receive payments via ACH, Fedwire, or international SWIFT wire transfers. The setup is fully digital: sign up at grey.co or download the Grey app, complete KYC verification with your PAN card, Aadhaar, and proof of address, and your account details are available within 24 hours.

When a payment arrives via ACH or Fedwire, Grey charges a 0.8% deposit fee (minimum $2, maximum $10). The funds sit in your USD wallet. You can hold them in dollars for as long as you need, which is useful if you want to wait for a more favourable exchange rate or if you have USD expenses (software subscriptions, SaaS tools, advertising spend) that you can pay directly using a Grey virtual card. The virtual card costs $5 to create with no monthly maintenance fee. Transactions on USD-priced sites incur no additional fee; purchases on non-USD websites carry a 2% + $0.50 cross-border fee.

When you are ready to convert to INR, Grey charges a 1% conversion fee capped at $6 per transaction. The conversion rate is displayed before you confirm, so you see exactly how much INR you will receive. Transfers to your Indian bank account require your IFSC code and typically arrive the same day. You can check Grey's fee calculator to see the exact cost for any transaction amount before you commit.

Instead of relying on automatic bank conversions that happen at arrival, or juggling multiple platforms for different currencies, you receive USD through one account, manage your balance in dollars, and convert to INR when the timing and rate suit you.

Grey charges a 0.8% fee on deposits (minimum $2, maximum $10), a 1% conversion fee (capped at $6), and a withdrawal fee that varies by currency. Exchange rates on Grey are variable and include a margin over the mid-market rate. Cross-border card transactions on non-USD websites incur a 2% + $0.50 fee. Always review fees and the conversion rate before confirming a transaction.

How creators receive payouts from international platforms

•

•

2 min read

I remember my first international payout like it was yesterday. I’d spent months building an audience, finally hit the YouTube monetisation threshold, and eagerly waited for the payment from Google AdSense. When the notification came through saying the money had been sent, I felt brilliant. Proper creator now, getting paid for my work. “Tell Mr Beast to come outside!” I said.

When I checked my account, the platform had sent the money, yes, but somewhere between California and my bank account, a part of it just vanished.

That moment taught me that understanding how you get paid is just as crucial as understanding how to create content people want to watch. Over the years, I’ve learned the hard way how international payouts actually work, where money gets lost, and how to structure things so you keep more of what you earn. This is what I wish someone had told me before that first disappointing payout.

Also read: How remote employees receive salaries from abroad

How international platforms actually pay creators

Platforms don’t just send money directly to your bank account like a friend transferring you a tenner. They use intermediaries called payout processors because they’re dealing with millions of creators across dozens of countries, all expecting payment, some even in their local currency.

YouTube pays through Google AdSense. TikTok uses various regional processors. Patreon, Twitch, and Substack all rely on third-party systems to handle the actual movement of money across borders. This makes sense from their perspective. They can’t open bank accounts in every country or navigate every local banking regulation themselves.

LDMAG1

The most common payout methods

I’ve used nearly every payout method available to creators, and each has taught me something different.

Direct bank transfers

Direct bank transfers via wire seemed more professional when I started getting larger payments. But international wire transfers involve multiple banks, each charging fees. I once received a $2,000 payment that cost me nearly $90 in combined bank charges and poor exchange rates. The sender paid $25, an intermediary bank took $20, my bank charged a receiving fee, and then converted USD at a rate significantly worse than the mid-market rate. It added up fast.

Platform-specific systems

Platform-specific systems like Payoneer work better for creators on freelance marketplaces. Payoneer integrates smoothly with platforms like Upwork and Fiverr, and it’s cheaper than PayPal. I still lost 1-2% on currency conversion, though, and withdrawal fees applied depending on how I accessed the money.

Multi-currency fintech accounts

The breakthrough for me came when I discovered multi-currency fintech accounts. Services like Wise, Revolut, and Grey offer virtual bank accounts in multiple currencies, such as USD, EUR, and GBP, so you can receive payments easily. This changed everything for me.

Also read: How Nigerians working remotely protect income from FX swings

How smart creators structure their payout systems

After years of losing money unnecessarily, I finally sorted out a proper system, and it made an immediate difference.

First, I opened a multi-currency account that let me receive USD, EUR, and GBP without forced conversion. I went with Grey because it gave me proper banking details with an account number, sort code, and routing number so that platforms and clients could pay into it directly.

Next, I updated my payout details across every platform. YouTube, Patreon, freelance platforms, and direct clients, I gave them all my new account details. Some platforms required verification periods, others had specific payout cycles. But once everything was switched over, the difference was clear.

Finally, I started converting currency strategically instead of immediately. If I’m not spending the money right away, I hold it in USD until the exchange rate improves. Sometimes this saves me 2-3%, which compounds significantly over months.

Also read: How to budget in foreign currencies using the Grey card

How Grey simplifies international payouts

I’m not here to give you a sales pitch, but I do want to explain why Grey made such a difference for me specifically.

Grey gives you virtual bank accounts in USD, EUR, and GBP with proper banking details. When a platform or client pays you, the funds are deposited directly into the relevant currency account. There’s no forced conversion, no intermediary banks taking unexpected fees, and no waiting two weeks for international wires to clear.

The exchange rates are transparent. Whenever I convert, I know exactly what I’m paying, as there are no hidden fees buried in exchange-rate spreads.

For creators earning from multiple countries and platforms, having one system that handles everything is genuinely valuable. I used to juggle different platforms, but now everything flows into Grey, and I manage it all in one place.

The clarity this provides also makes tax filing significantly easier. I have clean records of what I earned, in which currency, and when.

Also read: Switching from banks to global accounts: What to know

Getting paid is part of the strategy

Treating your payout infrastructure as part of your overall creator strategy isn’t boring back-office admin. It’s keeping more of the money you’ve worked hard to earn. It’s having control over your finances instead of just accepting whatever arrives in your account. It’s being professional about your business.

The platforms will keep paying you, but they won’t optimise how you receive that money. That’s your job. Understand the fees, use the right tools, and structure your systems intelligently. Your future self will thank you.

Open your free Grey account or download the app and start receiving international payouts transparently, efficiently, and without losing money you’ve already earned.

‍

Arrow (up)

Back to top