


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/freelancer-vs-employee-tax#article","headline":"Freelancer vs employee tax: What you actually owe and how to prepare","description":"Freelancer vs employee tax: freelancers pay more in self-employment tax but can deduct expenses. Learn what you owe and how to prepare. Compare your options.","inLanguage":"en","url":"https://grey.co/blog/freelancer-vs-employee-tax","mainEntityOfPage":{"@id":"https://grey.co/blog/freelancer-vs-employee-tax#webpage"},"datePublished":"2026-07-07T21:50:27.140Z","dateModified":"2026-08-05T09:10:41.939Z","author":{"@type":"Person","@id":"https://grey.co/authors/adeolu-titus-adekunle#person","name":"Adeolu Titus Adekunle","url":"https://grey.co/authors/adeolu-titus-adekunle","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/titusadeoluadekunle/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/freelancer-vs-employee-tax#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a4d755a849a8f0f8b041d18_Freelancer%20vs%20employee%20tax%20what%20you%20actually%20owe%20and%20how%20to%20prepare-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a4d755a849a8f0f8b041d18_Freelancer%20vs%20employee%20tax%20what%20you%20actually%20owe%20and%20how%20to%20prepare-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/freelancer-vs-employee-tax#webpage","url":"https://grey.co/blog/freelancer-vs-employee-tax","name":"Freelancer vs Employee Tax: What You Owe Compared | Grey","description":"Freelancer vs employee tax: freelancers pay more in self-employment tax but can deduct expenses. Learn what you owe and how to prepare. Compare your options.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/freelancer-vs-employee-tax#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/freelancer-vs-employee-tax#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/freelancer-vs-employee-tax#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Freelancer vs employee tax: What you actually owe and how to prepare","item":"https://grey.co/blog/freelancer-vs-employee-tax"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/freelancer-vs-employee-tax#faq","mainEntity":[{"@type":"Question","name":"Do freelancers pay more tax than employees?","acceptedAnswer":{"@type":"Answer","text":"In the US, yes, primarily because freelancers pay both halves of the self-employment tax (15.3% of net income) rather than just the employee half (7.65%). At the same gross income, a freelancer pays approximately $4,000 to $7,000 more in federal tax before deductions, depending on income level. Legitimate business expense deductions narrow this gap significantly."}},{"@type":"Question","name":"What is the self-employment tax?","acceptedAnswer":{"@type":"Answer","text":"Self-employment tax in the US is the freelancer's equivalent of the combined employer and employee FICA contributions that fund Social Security and Medicare. It is charged at 15.3% on 92.35% of net self-employment income (the adjustment accounts for the SE tax deduction). It applies on top of regular federal and state income tax."}},{"@type":"Question","name":"Do I need to pay quarterly taxes as a freelancer?","acceptedAnswer":{"@type":"Answer","text":"In the US, yes, if you expect to owe more than $1,000 in federal income tax for the year. The IRS charges underpayment penalties for quarterly amounts that are substantially below the tax owed. Quarterly due dates in the US are April 15, June 17, September 16, and January 15. In the UK, self-assessment tax returns are due annually by January 31, but payment on account applies for bills above £1,000."}},{"@type":"Question","name":"Can I write off my home office as a freelancer?","acceptedAnswer":{"@type":"Answer","text":"Yes, in both the US and UK, provided the space is used exclusively and regularly for business. In the US, the simplified method allows $5 per square foot up to 300 square feet. In the UK, HMRC allows either a flat-rate deduction or a deduction for the proportion of home costs attributable to the business space. Mixed-use spaces, such as a desk in a bedroom, require careful documentation, and only the business-use portion is deductible."}},{"@type":"Question","name":"How do I report freelance income to the IRS?","acceptedAnswer":{"@type":"Answer","text":"US freelancers report self-employment income on Schedule C (Profit or Loss from Business) and Schedule SE (Self-Employment Tax), attached to their Form 1040 annual return. If income from a single client exceeds $600 in a year, that client is required to send you a Form 1099-NEC. Income must be reported regardless of whether a 1099 is received. Quarterly estimated payments are submitted via Form 1040-ES."}},{"@type":"Question","name":"Can I receive my freelance income internationally via Grey?","acceptedAnswer":{"@type":"Answer","text":"Yes. Grey provides virtual USD, GBP, and EUR accounts with real foreign banking details. US clients pay via ACH to a US routing number and account number. UK clients pay via Faster Payments to a UK sort code and account number. EU clients pay via SEPA. All three payment methods are domestic transfers from the sender's perspective, with no international wire fees or SWIFT correspondent bank deductions. Income arrives in full and is held in the original currency until you choose to convert. Managing your income across various currencies makes record-keeping for tax filing easier. Open a multi-currency account with Grey to receive your freelance payments in USD, GBP, and EUR."}}]}] </script>

Freelancer vs employee tax: What you actually owe and how to prepare

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

If 80% of freelancers see tax filing as grunt work, the 20% who love it are probably tax professionals. It can be confusing enough to make you contemplate opting for traditional employment or outsourcing it if you could. Moving from employment to freelancing changes your relationship with tax in ways most people underestimate before the first tax season. As an employee, tax is deducted at source through payroll, handled largely invisibly. As a freelancer, you calculate, set aside, and pay tax yourself, often quarterly rather than annually, and on income that can fluctuate significantly from month to month.

Freelancers in the US pay self-employment tax of 15.3% on top of regular income tax, covering both employer and employee portions of Social Security and Medicare. Employees only pay 7.65% because their employer covers the other half. Freelancers can offset this by deducting business expenses, home office costs, and half of the self-employment tax.

Understanding the tax difference between freelance and employee income is useful for planning your finances, how much of each payment you should set aside, noting your deductibles, and pricing your services to account for the additional tax burden. This article sheds some light on freelancer and employee taxes, the differences and how to calculate how much you owe.

How freelancer and employee taxes differ

One of the biggest differences between being an employee and working as a freelancer is how you’re taxed. Employees have taxes automatically deducted from their salaries. As an employee, your employer typically handles income tax and social security contributions on your behalf. These are usually withheld directly from your paycheck, so you receive your net salary without having to manage payments yourself.

On the other hand, freelancers are responsible for calculating, reporting, and paying their own taxes. As a freelancer, you must track your income, manage your expenses, and pay taxes directly to the government. This is often paid in lump sums throughout the year. Because freelancers pay in lump sums, as opposed to monthly deductions directly from their paycheck, freelancers might feel they “pay more” in taxes, even when the overall rates are similar.

In the United States, self-employed individuals must pay self-employment tax, which covers both the employee and employer portions of Social Security and Medicare. This currently stands at 15.3% on net earnings (up to a certain threshold), significantly increasing the total tax burden compared to traditional employment.

In the United Kingdom, freelancers pay Class 4 National Insurance Contributions on their profits, in addition to income tax. Usually, employees split the National Insurance payment with their employer, while freelancers are responsible for the full amount, since there is no employer.

All things considered, managing taxes as a freelancer is usually more complex than as an employee. And even when the base income tax rates for freelancers and employees are similar, freelancers bear more of the tax and social security burden that would otherwise be shared with an employer.

Self-employed tax vs employee tax

The comparison between self-employed and employee tax structures differs between the US and the UK, but the core principle is the same in both countries. The freelancer bears more of the combined tax burden because they lack an employer to absorb part of it.

United States

Employees pay Social Security and Medicare taxes through payroll deductions, known as FICA tax. The total rate is 15.3%, but it is split equally between the employee and employer:

  • Employee pays 7.65%
  • Employer pays 7.65%

Freelancers, however, pay the full 15.3% themselves as self-employment tax on their net income (income after business expenses). They also still pay regular federal income tax and, where applicable, state income tax.

Freelancers can deduct half of the self-employment tax (7.65%) before calculating their income tax. This reduces the tax burden slightly, but does not eliminate it.

United Kingdom

Employees pay Class 1 National Insurance Contributions (NICs):

  • 8% on earnings between £12,570 and £50,270
  • 2% on earnings above £50,270

Employers also separately pay 13.8% employer NICs on qualifying earnings.

Self-employed workers’ pay:

  • Class 4 NICs at 6% on profits between £12,570 and £50,270
  • 2% above that threshold
  • A small flat Class 2 NIC if profits exceed the minimum threshold

Unlike employees, freelancers do not have an employer paying additional NICs on their behalf. However, the self-employed NIC structure is generally lower than the combined employee-plus-employer contribution system.

In both countries, freelancers and employees still pay the same standard income tax rates based on their earnings.

What is the tax difference between freelance and employed?

At the same income level, a freelancer in the US consistently pays more in total tax than an employee, primarily because of the additional 7.65% self-employment tax representing the employer's share of FICA.

Employee (US) Freelancer (US)
Income $80,000 $80,000 gross
Self-employment tax None (employer pays half) 15.3% on net income
Federal income tax Standard brackets apply Standard brackets apply
(slightly lower base due to SE tax deduction)
Total FICA/SE tax 7.65% employee portion 15.3% full SE tax
Extra tax vs employee Baseline Approximately $6,120 extra at $80,000
(before deductions)

In the UK, at £40,000:

Employee (UK) Freelancer (UK)
Income £40,000 £40,000 gross
NICs 8% Class 1 on earnings above £12,570 6% Class 4 on profits above £12,570
Extra tax vs employee Baseline Slightly less in NICs at this income level, but no employer contribution to benefits
Income tax Same brackets apply Same brackets apply

In the UK, the Class 4 NIC rate for freelancers is lower than the Class 1 rate for employees at the same income level, which means the NIC disadvantage is less pronounced than in the US. However, UK freelancers also receive fewer employment benefits (sick pay, pension contributions, maternity/paternity) that are effectively subsidised by the employer for employees.

How much more tax does a freelancer pay than an employee?

US worked example at $80,000

As an employee:

  • Gross income: $80,000
  • FICA (employee share, 7.65%): $6,120
  • Federal income tax (2026 brackets, standard deduction, single filer): approximately $11,000 to $13,000
  • Total: approximately $17,000 to $19,000 in federal tax

As a freelancer at the same gross revenue:

Assume $10,000 in business expenses (software, equipment, home office, professional services).

  • Net income after expenses: $70,000
  • Self-employment tax (15.3% on 92.35% of net income, per IRS formula): approximately $9,900
  • SE tax deduction (half of SE tax reduces taxable income): reduces taxable income by approximately $4,950
  • Federal income tax on approximately $65,050 after standard deduction and SE deduction: approximately $9,500 to $11,000
  • Total: approximately $19,400 to $20,900 in federal tax

The freelancer pays approximately $1,400 to $3,000 more in federal tax, even after the SE tax deduction. At higher income levels, the gap increases. The key variable that narrows it is legitimate business expenses: the more you can deduct, the lower your net taxable income and SE tax base.

UK worked example at £40,000

As an employee:

  • Income tax (basic rate, standard allowances): approximately £5,486
  • Class 1 NICs (employee, 8% above £12,570): approximately £2,194
  • Total deducted: approximately £7,680

As a freelancer with £5,000 in business expenses:

  • Net profit after expenses: £35,000
  • Class 4 NICs (6% on profit above £12,570): approximately £1,346
  • Class 2 NICs: approximately £180
  • Income tax (on £35,000 after personal allowance): approximately £4,486
  • Total: approximately £6,012

In the UK, at this income and expense level, the freelancer actually pays slightly less in total tax than the employee, primarily because business expenses reduce the profit base and because Class 4 NICs are lower than the combined Class 1 NICs for the employer and employee. The difference disappears at higher income levels and when expenses are lower.

Also read: Best invoicing tools for freelancers working with international clients

What freelancers can deduct that employees cannot

Freelancers can reduce their taxable income by deducting business expenses directly related to their work. These deductions help offset the additional tax burden that comes with being self-employed.

Common deductions in both the US and UK include:

  • Home office expenses: If you work from home, you may be able to deduct part of your rent, utilities, internet, and electricity based on the percentage of your home used exclusively for work.
  • Work equipment: Laptops, monitors, cameras, microphones, desks, and other tools used for your freelance work are generally deductible. In the US, some equipment can be deducted immediately rather than spread over several years.
  • Software and subscriptions: Tools like Adobe Creative Cloud, Canva, Notion, Zoom, accounting software, hosting services, and other work-related subscriptions qualify as business expenses.
  • Professional services: Fees paid to accountants, lawyers, consultants, or tax advisers for business purposes are deductible.
  • Training and education: Online courses, certifications, workshops, conferences, and books directly related to your profession can usually be claimed.
  • Business travel: Transport, accommodation, coworking spaces, and certain meal expenses during work-related trips may qualify as deductions.
  • Self-employment tax deduction (US): US freelancers can deduct half of their self-employment tax before calculating their regular income tax.

The general rule is simple: if an expense is necessary for running your freelance business, it may be deductible. Purely personal expenses usually are not, even if the same item is used partly for work and partly for personal use. In those cases, only the business-use portion can typically be claimed.

For freelancers generating passive income alongside active client work, the deduction rules apply to each income stream separately, and keeping clear records by stream from the outset makes tax preparation significantly more manageable.

How to prepare for freelance taxes

Freelance taxes are easier to manage when handled consistently throughout the year rather than rushed during tax season.

  • Set aside part of every payment for taxes: A common rule is to reserve 25–30% of every payment received. This helps cover income tax and self-employment tax without running around for a large amount later.
  • Pay taxes quarterly if required: In the US, freelancers usually need to make quarterly estimated tax payments if they expect to owe more than $1,000 in taxes for the year. Missing these deadlines can lead to penalties. Similar advance payment systems exist in countries like the UK.
  • Track expenses and keep receipts: Every deductible business expense should be documented with receipts or invoices. A spreadsheet, accounting software, or expense-tracking app is usually enough to stay organised.
  • Work with an accountant if possible: A tax professional familiar with freelance income can help reduce mistakes, identify deductions, and avoid penalties. For many freelancers, the savings and peace of mind outweigh the cost.
  • Manage international income carefully: Freelancers receiving income in multiple currencies face additional problems. The conversion rate margin when you receive your payment affects how much you will receive at the end of the day. Opening a multi-currency account with Grey allows you to receive USD, EUR, and GBP and keep in the original currency. You can then convert whenever you want. Receiving international payments with Grey gives you more control over your finances.

Frequently asked questions

Do freelancers pay more tax than employees?

In the US, yes, primarily because freelancers pay both halves of the self-employment tax (15.3% of net income) rather than just the employee half (7.65%). At the same gross income, a freelancer pays approximately $4,000 to $7,000 more in federal tax before deductions, depending on income level. Legitimate business expense deductions narrow this gap significantly.

What is the self-employment tax?

Self-employment tax in the US is the freelancer's equivalent of the combined employer and employee FICA contributions that fund Social Security and Medicare. It is charged at 15.3% on 92.35% of net self-employment income (the adjustment accounts for the SE tax deduction). It applies on top of regular federal and state income tax.

Do I need to pay quarterly taxes as a freelancer?

In the US, yes, if you expect to owe more than $1,000 in federal income tax for the year. The IRS charges underpayment penalties for quarterly amounts that are substantially below the tax owed. Quarterly due dates in the US are April 15, June 17, September 16, and January 15. In the UK, self-assessment tax returns are due annually by January 31, but payment on account applies for bills above £1,000.

Can I write off my home office as a freelancer?

Yes, in both the US and UK, provided the space is used exclusively and regularly for business. In the US, the simplified method allows $5 per square foot up to 300 square feet. In the UK, HMRC allows either a flat-rate deduction or a deduction for the proportion of home costs attributable to the business space. Mixed-use spaces, such as a desk in a bedroom, require careful documentation, and only the business-use portion is deductible.

How do I report freelance income to the IRS?

US freelancers report self-employment income on Schedule C (Profit or Loss from Business) and Schedule SE (Self-Employment Tax), attached to their Form 1040 annual return. If income from a single client exceeds $600 in a year, that client is required to send you a Form 1099-NEC. Income must be reported regardless of whether a 1099 is received. Quarterly estimated payments are submitted via Form 1040-ES.

Can I receive my freelance income internationally via Grey?

Yes. Grey provides virtual USD, GBP, and EUR accounts with real foreign banking details. US clients pay via ACH to a US routing number and account number. UK clients pay via Faster Payments to a UK sort code and account number. EU clients pay via SEPA. All three payment methods are domestic transfers from the sender's perspective, with no international wire fees or SWIFT correspondent bank deductions. Income arrives in full and is held in the original currency until you choose to convert.

Managing your income across various currencies makes record-keeping for tax filing easier. Open a multi-currency account with Grey to receive your freelance payments in USD, GBP, and EUR.

Last updated:

October 9, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Grey virtual card vs Chipper, Geegpay, and others: 2026 comparison

•

•

2 min read

Different virtual cards work differently depending on how you spend, where you shop, and which currencies you use. Some excel at simple travel spending, others at multi-currency holding. Some support crypto, others don’t. Understanding the real differences helps you pick which one works for you.

Today, I’m comparing the Grey card with six other well-known virtual card options, just so you know which one works best for you.

1. Wise multi-currency card

If you’ve ever needed a card that is like a multi-currency wallet first and a spending card, Wise probably fits that bill. Wise is widely used as a borderless account with a card that lets you tap into more than 50 currencies and spend internationally at transparent exchange rates.

For many global workers and travellers, such simplicity is appealing. You get the real exchange rate plus a small, clear fee. There are generally no hidden surprises, and you can hold currencies like USD, EUR, or GBP in one place.

Wise also doesn’t support crypto balances, so if you’re someone who keeps part of your funds in digital assets and wants to spend crypto, your Wise card won’t help.

People who want to hold and spend multiple currencies with clear exchange pricing, especially for everyday purchases and travel, will love the Wise card.

Also read: How to shop in the US or Europe with your Grey card

2. Revolut card

Revolut is one of the most talked-about fintech platforms in the world, and its card ecosystem reflects that breadth. You can have both virtual and physical cards, generate disposable virtual cards for added security, and even manage budgeting, investments, and crypto trading all in one app.

It ticks many boxes: multi-currency support, budgeting tools, and virtual card creation. However, the complexity of features can become a hurdle, especially when key perks are tucked behind paid tiers.

Revolut is strong as part of a broader lifestyle finance app, especially for travellers and users who want added perks like travel insurance, purchase protection, and trip disruption coverage, which are included in higher-tier plans such as Premium, Metal, or Ultra. However, these benefits depend on subscription level and eligibility requirements, and coverage is provided through third-party insurers rather than built directly into the card experience.

Its virtual cards can still face issues on international platforms, and the way it converts currencies, including weekend markups, adds a layer of unpredictability for some users.

3. Payoneer card

Payoneer is a name many freelancers, online sellers, and international businesses know quite well. Its card, especially the virtual prepaid card, is excellent for receiving payments from global marketplaces, handling international transfers, and covering business expenses in multiple currencies.

However, many users report sudden card blocks, limited personal support, and slow resolution times, which can be frustrating when you’re trying to pay for everyday subscriptions or online purchases.

In many regions, Payoneer is ideal for business payouts and marketplace earnings; however, it may not be the best option if you require a card for personal multi-currency spending or flexible international use.

Freelancers and businesses requiring comprehensive currency support with global payouts, especially via marketplaces, will appreciate the Payoneer card.

Also read: How to pay online and in stores worldwide with your phone

4. N26 Card

N26 operates as a digital bank primarily across the EU and EEA. Its cards, both physical and virtual, are built around simplicity, with no foreign transaction fees for many currencies and straightforward Mastercard exchange rates.

It works well for everyday spending both within and outside the Eurozone, and virtual cards can be issued quickly as part of the account opening process.

The big limitation, a practical one, is its availability. N26’s services were pulled back from the U.S. and some other markets in recent years, and it remains focused on European customers.

So if you travel frequently within Europe or spend in EUR, N26 cards can be a solid choice. But outside that context, it’s less flexible, especially for global needs.

LDMAG1

5. Crypto-linked cards

Crypto cards deserve their own mention. Cards like the Coinbase Card and Crypto.com Visa Card allow you to spend cryptocurrency by instantly converting it to fiat at the point of sale. These are especially interesting for people who live or earn in digital assets and want to use them without extra conversion steps.

For example, Binance’s card (in regions where it is still supported) offers significant cashback rewards in BNB, and Coinbase lets you spend multiple crypto assets directly, with rewards in crypto.

The downside is that these cards often tie you into a specific exchange ecosystem, may carry higher fees for some transactions, and their rewards are typically token-based — valuable if you’re bullish on crypto, less so if you’re not.

I’ll recommend these cards for crypto holders who want to spend digital assets with conversion at checkout and enjoy token rewards.

6. Traditional bank virtual cards

There’s a whole category of virtual cards issued by traditional or app-based banks, like Monzo (UK), Starling (UK), or wallet-front cards like Curve.

These are solid for everyday use, especially in their home markets, and often integrate well with Apple Pay/Google Pay. However, international currency support varies widely; some have foreign transaction fees, others rely on slower underlying banking rails, and they’re sometimes limited in where they’ll work for recurring payments or certain ad platforms.

For many users, these cards are excellent backups or complementary payment methods. But if your life or work relies on consistent, global spending, their limitations become noticeable.

7. Grey card offers a more flexible virtual global spending experience

By now, it should be clear: not all virtual cards are the same. Some are designed for holding money, others for daily banking, and others still for specific ecosystems.

Grey’s approach sits in a different space from the others above. Your card works across fiat (USD, EUR, GBP, local currency) and stablecoins (USDC), eliminating the need to get an extra crypto card. Your Grey card automatically pulls funds from your available balances in the following order: USD, USDC, and then the next highest available balance.

You can also create multiple cards for different purposes, such as travel, subscriptions, personal, and business. Still, each card will work seamlessly without requiring you to select which balance to spend from. We built the Grey virtual card for people who:

  • Spend in multiple currencies regularly
  • Want predictable outcomes at checkout
  • Value clear messaging and control
  • Need support for both fiat and crypto balances

Instead of requiring top-ups or rigid currency conversion steps, your Grey card automatically draws from your available balances, making spending across fiat and stablecoin currencies effortless.

Many of the other options we’ve discussed above are great in their contexts. However, each has trade-offs that make it difficult to be everything to everyone.

Also read: How to budget in foreign currencies using the Grey card

So, which card is right for you?

There’s no single answer, but here’s a quick way to think about it:

  • If you want clear, no-nonsense multi-currency holding and spending, Wise or N26 are strong choices.
  • If you’re looking for a financial super app with perks, Revolut is a great fit.
  • If you earn or spend in crypto and enjoy token rewards, crypto cards like Coinbase or Crypto.com are worth exploring.
  • If you want a card that automatically draws from different balances, supports multiple cards, and makes international or multi-currency spending predictable globally, we built Grey for your lifestyle.

Different cards shine in various life scenarios. The key is knowing which trade-offs matter to you, and how your day-to-day spending looks.

Choose with clarity, and let your card work for you, not the other way around. Create your Grey visa card and enjoy a smoother, more inclusive, and more predictable global spending experience.
‍

How to budget in foreign currencies using the Grey card

•

•

2 min read

Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.

Then remote work happened.

Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you also need structure because, without proper structure, even the most careful spender can lose track of where their money is going.

Your Grey card is a practical budgeting tool for people who live, work, earn, and spend across borders. I’ll explain.

Why budgeting in multiple currencies breaks down so easily

Many people who overspend don't do so because they’re irresponsible. But because their money isn’t organised in a way that reflects how they live.

It’s pretty common to be juggling subscriptions in USD, running ads in EUR, buying coffee in GBP, and somehow all on the same card. Eventually, everything blurs together. You can no longer track your Netflix renewal, that Facebook ad campaign, the flight you booked last week, or the coworking space membership. Then one day you check your balance and think, “Where did all that money go?” You know you spent it. You just can’t figure out where, or why, it felt like so much more than you expected.

It’s not that you’re careless. It’s that your money isn’t organised in a way that matches how you actually live and work. And once things start blurring, it’s nearly impossible to untangle without spending an hour combing through statements, converting currencies in your head, and still not feeling certain you’ve caught everything.

At that point, your budget is broken.

Also read: How to use your Grey card to manage all your subscriptions

What should budgeting look like when you earn and spend globally?

Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:

  • See exactly what each type of spending is costing you.
  • Stop or pause spending instantly when needed.
  • Protect one part of your budget from another.
  • Make changes without disrupting everything else.

The Grey card is designed around solving these exact needs.

How does the Grey card help with budgeting?

Use multiple cards to separate your spending

One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes. Your Grey virtual card helps you structure your spending as such.

For example, you can create:

  • One card for subscriptions and recurring tools
  • One card for ads and growth experiments
  • One card for travel or everyday spending
  • One card per client or project

Each card acts like its own budget lane, pulling from the same balance. You don’t need to guess where the money went because you already know.

This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.

Also read: How to pay for ads easily with your Grey card

Freeze cards instantly when spending goes off-track

Budgets fail when you can’t act fast enough.

With the Grey card, you can instantly freeze or unfreeze any card in the app. If a digital ad campaign starts burning through too cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.

Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.

Set limits that protect your budget

Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.

You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.

For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.

Track spending clearly in one place

When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.

When budgeting time comes around, you’re not sitting there trying to remember what that mysterious €47 charge was three weeks ago or why your USD balance dropped. Everything’s already categorised. The structure did the work for you.

Spend confidently across borders

Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.

A quick note on protection when spending abroad

An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.

When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.

It’s one less thing to worry about while managing money across borders.

Also read: How to claim your Visa card benefits

What budgeting in foreign currencies is like with the Grey card

When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency your spend is coming from and more importantly, when something changes.

Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.

If you’re ready to make your budget work wherever you are, create or update your Grey card today and start spending and budgeting in the ways that matter to you.

‍

How to shop in the US or Europe with your Grey card

•

•

2 min read

A few months ago, I was eyeing a pair of sneakers on a US website for weeks. Then the store started running sales and I decided to buy them (hashtag #YOLO), but my bank card declined the payment.

Not once, not twice… but four times!.

The same card that worked perfectly in Nigeria where I live, and the same details I’d used for years. I tried to get another card, but by then, sales had ended, and the sneakers were out of stock. It was annoying, but I just had to accept my L.

If you’ve ever tried to shop internationally, on sites like ASOS UK, Amazon US, Zara EU, or even the Apple Store, you may already be familiar with this pain. Sometimes the website rejects your card. Sometimes your bank blocks the transaction. Sometimes the currency conversion takes too long, and the payment times out.

It shouldn’t be this difficult to buy something online in big 2026… yet for many people, it still is.

But if you use a Grey card, you'll eliminate the uncertainty of thoughts like, “Will this payment go through?”, and transform your international shopping into a simple and predictable process.

Why shopping abroad is often frustrating

Shopping from US or European stores usually comes with these hurdles:

1. Many foreign merchants decline local cards

Some US/UK online stores automatically reject certain African-issued cards, even if you have more than enough balance.

2. Stores bill strictly in USD, GBP, or EUR

If your card requires manual currency conversion, it can cause payment delays that may result in declines.

3. Banks block “suspicious” international transactions

This usually happens when the merchant is unfamiliar.

4. Conversion errors and hidden fees

Some cards convert long after the purchase, leading to surprises on your statement.

These problems are common, but they’re also exactly what Grey card is built to avoid.

How your Grey card makes shopping internationally easy

Smart spending across multiple currencies and USDC

Your Grey card doesn’t require you to pick or switch wallets before paying. Instead, it automatically spends from your balances. Your USD account is debited first; if that’s empty, your USDC, and then the highest of your remaining balances.

This means your payment goes through as long as you have funds available in your account, without requiring you to consider currencies at checkout.

Works across major US and European stores

Your Grey card is an international spend card, so you can pay at 150 million merchants worldwide.

Use Apple Pay and Google Pay

For stores that support mobile wallets, you can simply add your Grey Visa card to Apple Pay or Google Pay. This is more secure and makes for much faster checkouts.

Create multiple cards for better organisation

If you shop frequently or mix personal and business purchases, you can:

  • Use one card for personal shopping
  • another for business imports
  • another for gift purchases

It keeps your spending clean and easy to track.

Freeze and unfreeze anytime

You can always freeze your cards to control your spending.

Better protection for online transactions

You receive real-time notifications, card controls, and instant limits - everything you need for peace of mind when buying from foreign sites.

LDMAG1

How to shop in the US or Europe with your Grey card

1. Request your Grey visa card

Create a Grey account and go to the cards section of your Grey app to request a Grey card for $5.

2. Add your card to the store’s checkout

Enter your card details or simply pay through Apple Pay/Google Pay.

3. Make your purchase normally

Shipping, duties, and taxes will be displayed as they are for every other international shopper.

4. Track everything in your Grey app

Every charge, refund, or verification appears instantly, so there are no surprises later.

Tips for smarter international shopping

  • Use a separate card for business or bulk purchases so you can easily track expenses.
  • Keep a bit extra in your wallet for shipping fees and taxes.
  • Use Apple Pay/Google Pay when available. It’s the most seamless way to tap and pay, and also supports contactless payments.

Shopping abroad doesn’t have to be stressful

Your Grey card helps you shop with confidence. There are no random declines or conversion drama. Ahead of your next international purchase, you can create your Grey card and enjoy a smoother, more predictable shopping experience.

‍

Payment mistakes freelancers make when scaling income

•

•

2 min read

Recently, I listened to Justin Welsh talk about scaling his freelance writing business, and it really hit home. As he shared his journey, I remembered my own early freelance days, more clients, more invoices, and definitely more money. I even hired a few people to help me manage the workload. But despite the growth, the money wasn’t always well accounted for.

Thinking back, those were learning moments, and I’m seeing so many freelancers make the same mistakes today. Scaling your freelance business is exciting and essential for growth, building credibility and a better professional reputation.

But it can quickly become frustrating if that growth is slowed by payment mistakes,  not clients. In this post, I’ll show you the most common payment mistakes freelancers make when scaling.

Also read: Best ways freelancers get paid internationally

What every freelancer should know before scaling

Scaling as a freelancer is about creating systems, optimising resources, and increasing efficiency. Recently, I realised that the freelancers who grow sustainably aren’t necessarily the busiest, but those who structure their work, automate repetitive tasks, and manage cash flow smartly. Think of it like moving from constantly tapping your phone to letting Alexa handle tasks, achieving more with less effort.

By focusing on processes and smart growth, you can reduce stress, handle bigger projects confidently, and expand your business without chaos. These advantages show why having structured systems and smart processes is essential for scaling your freelance business effectively.

  • Structured systems help you handle more projects without burning out while staying organised and focused.
  • Increase your income efficiently while maintaining high-quality work and consistent professional standards.
  • Automation saves hours weekly, giving freedom to focus on strategic, high-value tasks that grow your business.
  • Organised workflows boost credibility and improve client perception, helping secure larger and repeat projects.

Avoid these payment mistakes when scaling your freelance work

Scaling your freelance business is exciting, but it can uncover payment pitfalls that slow growth, hurt cash flow, and cause unnecessary stress. Here are the most common mistakes to avoid.

1. Not invoicing promptly

I once delayed sending an invoice for a big client and ended up waiting over a month to get paid. Late invoicing disrupts cash flow and increases the risk of payments being delayed or forgotten. Sending invoices promptly keeps your business running smoothly and shows professionalism.

2. Mixing personal and business accounts

I used to route client payments to my personal account. It felt easier, but reconciling income and expenses became messy. Mixing accounts makes it harder to track pending payments and complicates taxes. Separating business and personal accounts from the start saves time and avoids headaches later.

3. Ignoring currency conversion fees

Freelancers working internationally can lose $25–$40 on a $1,000 transfer due to conversion fees. Over a year, that adds up significantly. Using low-fee, multi-currency platforms ensures more of your earnings stay in your pocket instead of being lost to unnecessary charges.

4. Failing to set clear payment terms

Nicolas Cole, a business writer for executives, once emphasised that clear contracts and payment terms are essential. Freelancers who leave payment schedules vague often chase clients for payment. I’ve seen peers struggle with disputes simply because expectations weren’t clearly defined. Setting firm, written payment terms protects your time, ensures accountability, and signals that your work is professional.

5. Overlooking automated payment reminders

If you rely on memory to follow up with clients, payments can get delayed. Using automated reminders through platforms or software ensures your clients pay on time without extra effort. It keeps your cash flow steady, reduces the stress of chasing payments, and lets you focus on delivering your work instead of worrying about unpaid invoices.

6. Not reviewing payment methods before scaling

Before you scale, don’t assume every platform can handle high-volume transactions. If you don’t test your payment methods under expected growth, you risk delays or failed transfers. Checking your system ahead of time ensures it can handle more payments, avoids unnecessary issues, and reassures clients that their payments will always go through reliably.

7. Failing to track overdue payments

Not tracking overdue invoices hurts cash flow and business planning. I use spreadsheets and platform dashboards to monitor unpaid payments weekly. This allows me to follow up promptly, forecast income, and prevent surprises. Staying on top of overdue payments keeps your freelance business healthy and scalable.

Scale your freelance income with Grey

As your freelance business grows and you take on more clients globally, managing payments shouldn’t hold you back. Grey provides a fast, secure, and reliable solution, helping you scale without worrying about delays or hidden fees. With competitive conversion rates, multi-currency support, and seamless withdrawals, you can focus on expanding your business, delivering great work, and onboarding more clients.

To scale your freelance operations smoothly with Grey, follow these steps:

  • Sign up on the Grey website or download the mobile app.
  • Verify your identity by submitting your personal details.
  • Link your preferred bank account for effortless withdrawals.
  • Start receiving payments from clients locally or internationally, efficiently managing higher volumes as your business grows.

‍

Digital banks vs traditional banks for non-US residents

•

•

2 min read

Across the globe, non-US residents are finding it easier than ever to access US dollar accounts, without stepping foot in the United States. Whether you travel to the US occasionally or earn USD virtually from freelance work, digital and traditional banks now offer ways to “own” a US account. Some provide full online onboarding, instant virtual cards, and competitive exchange rates, while others stick to the classic branch-and-paperwork model.

In this blog, you’ll learn the real differences between digital banks and traditional US banks for non-residents, including fees, convenience, and access to services. By the end, you’ll know which option fits your lifestyle, whether it’s managing international payments, receiving USD from clients, or simply holding a dollar account securely.

Also read: How non-US citizens can open a US bank account online

How digital banks are changing the game

Digital banks are financial institutions that operate entirely online, without physical branches. They provide most of the same services as traditional banks, checking and savings accounts, debit cards, transfers, and bill payments, but through apps or web platforms. By eliminating physical locations, digital banks often offer lower fees, faster account setup, and user-friendly interfaces, making everyday banking simpler and more convenient.

For non-US residents, digital banks also often include innovative features such as instant notifications and budgeting tools. They cater to people who prefer managing their finances on mobile devices, value convenience, and want seamless access to accounts from anywhere, at any time.

And here are reasons why digital banks are ideal for non-US residents:

  • Quick online account setup without needing to visit a US branch.
  • Access to US dollar accounts and virtual cards from anywhere in the world.
  • Lower fees and better currency conversion rates compared to traditional banks.
  • Convenient international money transfers for work, freelancing, or personal needs.
  • Easy integration with global payment platforms for receiving and sending funds.

Also read: How non-residents open international bank accounts online

Challenges of traditional banks for non-US residents

Traditional US banks like Chase, Bank of America, Citibank, and Wells Fargo offer full-service banking with in-person support, physical branches, and long-established reputations. They provide checking and savings accounts, debit cards, loans, and investment services.

However, for non-US residents, accessing these services often involves extensive paperwork, identity verification, and strict residency requirements, making it less convenient than digital alternatives. These challenges include:

  • Lengthy account opening processes requiring physical presence.
  • High fees for international transfers and currency conversions.
  • Limited access to online-only services or virtual cards.
  • Strict residency or identification requirements that many cannot meet.
  • Slow processing of payments from international clients or freelance earnings.

Digital vs traditional banks: choosing the right option for non-US residents

Non-US residents often struggle with accessing traditional US banking. This guide explores digital alternatives, comparing convenience, fees, and services to help you find the best fit.

1. Account access & onboarding

  • Digital banks: Fully online account opening, often within minutes. Many accept non-US residents with passports and proof of address. Minimal paperwork.
  • Traditional banks: Require in-person visits, social security or tax ID, local proof of address, and more documentation. Onboarding can take days to weeks.

2. Fees & costs

  • Digital banks: Low to no monthly maintenance fees, low foreign transaction fees, competitive FX rates. Transparent fee structures.
  • Traditional banks: Higher fees for account maintenance, international wire transfers, and currency conversion. Hidden fees are more common.

3. Cross-border transactions

  • Digital banks: Designed for international payments and currency exchanges. Some provide multi-currency accounts, local banking details in multiple countries, and real-time transfers.
  • Traditional banks: Slower international transfers, higher fees, and less flexibility for holding multiple currencies.

4. Residency requirements

  • Digital banks: Often more flexible. Many accept applicants from dozens of countries without requiring local residency or a Social Security Number (SSN)/ITIN. Some even let you open accounts before arriving in the country.
  • Traditional banks: Typically require stronger local ties — such as a local address, SSN/ITIN (in the US), visa/residence permit — and sometimes proof of employment or landlord letters. This makes opening accounts as a foreigner more difficult.

5. Interest rates & returns

  • Digital banks: Tend to offer higher interest rates on savings or checking balances because of lower overhead costs. Some also offer tiered or crypto‑linked yield products.
  • Traditional banks: Often pay very low or negligible interest on savings and checking accounts, especially for basic accounts; premium rates may require high minimum balances.

Also read: Best banks for non-residents to open UK and US accounts

The best digital banks for non-US residents

For non-US residents earning or holding USD, digital banks offer convenient, secure, and accessible options to manage dollars from anywhere in the world.

Grey

Grey provides non-residents with US dollar accounts, fast conversions, and competitive exchange rates. Its platform bypasses paperwork, making it easy to receive international payments instantly from clients globally.

HSBC Expat

HSBC Expat offers multi-currency accounts for non-US residents, combining the reliability of a global bank with online access. It’s ideal for managing savings, investments, and USD transactions abroad.

Zenus

Zenus charges a $5 monthly fee but allows non-residents to open a US bank account online with zero transfer costs. Perfect for freelancers or remote workers earning in USD.

Wise

Wise lets non-residents receive and send USD with no monthly fees, though transfers incur about 2% cost. Its transparent rates and global access make it ideal for international payments.

Managing online banking for non-US residents

For non-US residents, accessing traditional US banking can be slow and complicated, with paperwork, strict verification, and branch visits often required. Digital banks offer a simpler alternative, letting you manage accounts and transfers entirely online. Grey is an ideal choice, providing competitive exchange rates and multi-currency support in USD, EUR, and GBP.

Non-residents can open an account, handle payments, and manage funds without ever being in the US. Simply download the Grey app or sign up on the website to get started instantly.

‍

Best way to receive US dollar payments in India

•

•

2 min read

The default way Indian banks handle inbound USD is: receive the wire, convert to INR immediately at their own rate, credit your account in rupees, and deduct fees at every step. You never see the dollars. You never choose the conversion rate. You never decide when to convert. The bank decides all three, and the bank's rate is never the mid-market rate. That automatic conversion is where freelancers, consultants, and remote workers lose the most money on international payments.

The cost of this setup is not small. A 2% to 3% FX spread on every transfer, intermediary deductions on SWIFT wires, and receiving bank charges add up to lakhs lost annually for anyone earning regular USD income. This guide covers the four main ways to receive US dollar payments in India, what each one actually costs on a real invoice, the compliance requirements (purpose codes, FIRC, FEMA) that most payment guides skip entirely, and how to set up an infrastructure that gives you control over when and at what rate your dollars become rupees.

The four main ways to receive USD in India

1. US ACH or Fedwire transfers

ACH (Automated Clearing House) and Fedwire are US domestic transfer systems. When a US client pays you via ACH or Fedwire, the money moves within the US banking system to a US-based account. This is important because US companies strongly prefer paying vendors through their domestic payment rails. Their finance teams process ACH payments the same way they pay local contractors, which means less friction on the client side and faster approval on yours.

ACH transfers typically cost the sender nothing or a small flat fee (usually under $1). Fedwire transfers may cost the sender $15 to $30, depending on their bank. On your end, the cost depends on where the funds land. If you are receiving into a virtual USD account from a fintech provider, the provider charges a deposit fee (Grey charges 0.8%, minimum $2, maximum $10). There is no intermediary bank deduction because the payment never leaves the US banking system.

ACH is best for recurring payments from US-based clients, such as monthly retainers, project milestones, or regular consulting fees. If most of your clients are American, setting up a virtual USD account that supports ACH and Fedwire deposits is typically the lowest-cost option for regular income.

2. International wire transfers (SWIFT)

SWIFT is the global messaging network that banks use to route cross-border payments. When a client outside the US (or a US client whose bank does not support ACH to your provider) sends you a wire transfer, it travels through the SWIFT network. This is the most universally accepted method, but it is also the most expensive.

The costs stack up at multiple points. The sending bank charges a wire fee, typically $20 to $50, depending on the country and bank. If the payment routes through an intermediary (correspondent) bank, that bank deducts another $10 to $25 from the transfer amount. Your receiving bank may charge an additional inward remittance fee of $5 to $15. On a $2,000 invoice, total fees can range from $45 to $90, which is 2.25% to 4.5% before any currency conversion. Settlement takes 2 to 5 business days.

SWIFT makes sense for large, infrequent payments where the fixed fees represent a smaller percentage of the total: invoices above $5,000, corporate contracts, or one-off project payments. For smaller recurring payments, the per-transfer cost makes SWIFT significantly more expensive than ACH.

Also read: Top platforms to earn US dollars in India

3. Payment aggregators

Payment aggregators collect funds from your client (usually via card or local bank transfer) and remit the proceeds to your Indian bank account. The most common ones Indian freelancers encounter are PayPal, Razorpay (for businesses accepting international payments), and Stripe (with limited availability for payouts in India).

PayPal charges 2.99% on incoming goods and services payments, plus a currency conversion spread of 3% to 4% above mid-market when you withdraw to INR. On a $2,000 payment, that is roughly $60 in transaction fees plus $60 to $80 in conversion loss, totalling $120 to $140. Razorpay's international payment gateway charges 3% per transaction for international cards. These platforms are convenient for clients who prefer paying by card or who are not set up for bank transfers, but the cumulative cost is the highest of all four methods.

Aggregators are best for small, one-off projects where the client insists on paying by card, or for marketplace payouts (Upwork, Fiverr) where the platform dictates the payment method.

4. Cross-border transaction caps

India's cross-border payment framework includes transaction-level limits in certain categories. Some payment setups cap individual cross-border transactions at ₹25 lakh per unit of goods or services. If your invoice size approaches that range, bank-led rails such as SWIFT are usually more suitable than aggregator platforms. Having access to a USD receiving account through a provider like Grey gives you more flexibility when handling higher-value international payments, because the funds arrive in USD first and you control the conversion timing and method.

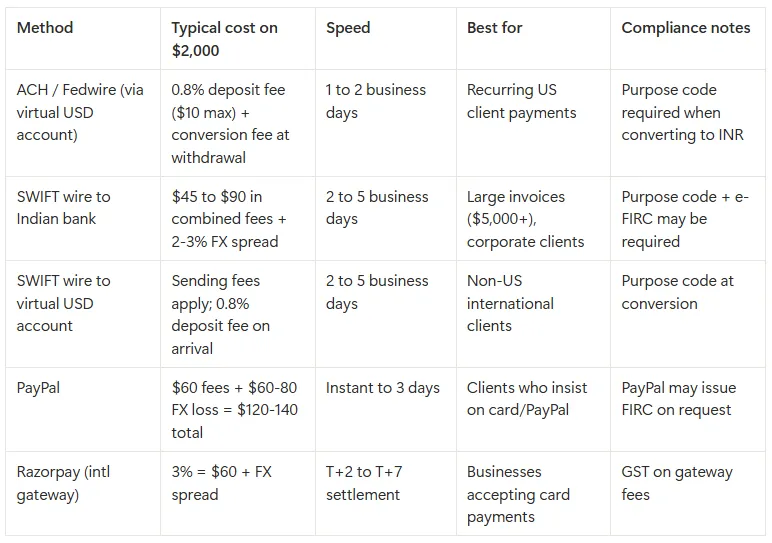
How the four methods compare

__wf_reserved_inherit

The compliance layer most freelancers overlook

Receiving USD payments in India is regulated under the Foreign Exchange Management Act (FEMA) and RBI reporting guidelines. Getting the compliance right upfront prevents delays, frozen transfers, and problems during audits.

Purpose codes

Indian banks require a purpose code on every inward remittance to classify the transaction under FEMA. Common codes for freelancers include those for software development, consulting, and marketing services. These codes are defined under the RBI purpose code list for inward remittances. Providing the correct code on your invoice and communicating it to your client's bank reduces the risk of your payment being held for manual review. Vague or missing purpose codes are one of the most common reasons for delayed credits.

You may also like: How to receive money from UK clients in India

FIRC and e-FIRC

If you export services (which includes freelancing for foreign clients), you may need a Foreign Inward Remittance Certificate (FIRC or e-FIRC) for GST export documentation, audits, and platform compliance. Only authorised dealer banks issue e-FIRC documentation. Confirm your bank's process for issuing these certificates in advance, because requesting them after the fact can take weeks. If you receive payments through a virtual USD account and then transfer to your Indian bank, the e-FIRC is issued by the Indian bank that receives the final INR credit.

‍

Export realisation timelines

India requires that export proceeds be realised (received in India) within a prescribed period. Long-pending invoices can create compliance issues. Keep your documentation organised and follow up on overdue payments early. For a complete explanation of FIRC requirements, tax implications, and RBI compliance rules, see Grey's guide on FIRC, taxes, and compliance for Indians earning foreign currency.

Which setup is right for your situation

The right payment method depends on three factors: where your clients are located, your average invoice size, and whether you want to hold USD or convert to INR immediately.

For most clients in the US, a virtual USD account that supports ACH and Fedwire is typically the lowest-cost option. Your US client pays you the same way they pay a local vendor. You receive the funds in USD, hold them until you are ready to convert, and withdraw to your Indian bank at a rate and time you choose. SWIFT works as a backup for clients whose banks do not support ACH to their provider.

Global clients across multiple countries: Ensure your account can receive international SWIFT wires without intermediary deductions eating into your payment. A multi-currency account lets you hold USD, GBP, or EUR and convert only when the rate is favourable, rather than accepting your bank's automatic conversion on arrival.

Large invoices ($5,000+): Direct bank rails (SWIFT or Fedwire) are preferable to aggregator platforms. The fixed fees are lower as a percentage of the total than the percentage-based fees aggregators charge. A $10,000 invoice through PayPal costs roughly $600-$700 in combined fees and FX losses. The same invoice received via SWIFT to a virtual USD account costs $10 in deposit fees plus the conversion cost when you move to INR.

Priority is maximising take-home INR. Compare the total cost at every step: incoming transfer fees, deposit fees, FX margin versus the mid-market rate, and withdrawal fees. Small differences in FX margins compound significantly over a year of regular payments. A 1% difference on $3,000 per month is $360 annually.

Also read: A guide for Indians getting paid by clients abroad

Common mistakes to avoid

Relying on a single payment method leaves you exposed if that channel has downtime, compliance issues, or fee changes. The safest setup is ACH or Fedwire as your primary rail with SWIFT as a fallback. Ignoring FX spreads is the most expensive mistake: the difference between mid-market and a 3% markup on $2,000 is $60 per transfer. Waiting until a compliance request arrives to organise your documentation can delay your funds for days or weeks. Sending invoices without detailed service descriptions triggers manual review at Indian banks because the purpose of the remittance is unclear. Include the service type, project reference, and your client's details on every invoice.

How Grey works for Indian freelancers receiving USD

Grey provides Indian freelancers, consultants, and remote professionals with USD, GBP, and EUR foreign currency accounts that can receive payments via ACH, Fedwire, or international SWIFT wire transfers. The setup is fully digital: sign up at grey.co or download the Grey app, complete KYC verification with your PAN card, Aadhaar, and proof of address, and your account details are available within 24 hours.

When a payment arrives via ACH or Fedwire, Grey charges a 0.8% deposit fee (minimum $2, maximum $10). The funds sit in your USD wallet. You can hold them in dollars for as long as you need, which is useful if you want to wait for a more favourable exchange rate or if you have USD expenses (software subscriptions, SaaS tools, advertising spend) that you can pay directly using a Grey virtual card. The virtual card costs $5 to create with no monthly maintenance fee. Transactions on USD-priced sites incur no additional fee; purchases on non-USD websites carry a 2% + $0.50 cross-border fee.

When you are ready to convert to INR, Grey charges a 1% conversion fee capped at $6 per transaction. The conversion rate is displayed before you confirm, so you see exactly how much INR you will receive. Transfers to your Indian bank account require your IFSC code and typically arrive the same day. You can check Grey's fee calculator to see the exact cost for any transaction amount before you commit.

Instead of relying on automatic bank conversions that happen at arrival, or juggling multiple platforms for different currencies, you receive USD through one account, manage your balance in dollars, and convert to INR when the timing and rate suit you.

Grey charges a 0.8% fee on deposits (minimum $2, maximum $10), a 1% conversion fee (capped at $6), and a withdrawal fee that varies by currency. Exchange rates on Grey are variable and include a margin over the mid-market rate. Cross-border card transactions on non-USD websites incur a 2% + $0.50 fee. Always review fees and the conversion rate before confirming a transaction.

Arrow (up)

Back to top

