


How to get an Airtel eSIM
Convert your Airtel SIM to an eSIM by SMS or in the Airtel Thanks app, with no store visit. See the steps and timings. Start the switch today.
Tunde Aladeloba
•
October 22, 2026
•
2 min read


From cash and M-Pesa to mobile wallets and PAPSS, see how money really moves across Africa, and send it across borders for less with Grey. Send.
Tunde Aladeloba
•
10 min read
In Douala’s busy markets, a supplier’s next order depends on getting paid for the last one. Not long ago, a trader sending money across a border might have relied on a travelling relative, a trusted intermediary or a bank transfer that took days to clear. Today, digital payment services are changing that reality, allowing money to move across borders in seconds along supported payment routes.
The significance goes beyond speed. When a trader can pay a supplier on time, stock arrives sooner. When a freelancer receives an international payment and can access the money locally, distance becomes less of a barrier to earning a living. These are everyday transactions, but together they are changing how people work, trade and do business across Africa.
Grey is part of this shift, connecting international transfers with local financial systems, including mobile money in supported markets such as Cameroon. For users, the value is practical: paying a collaborator, restocking a shop or supporting family abroad without having to navigate the process alone.
Africa’s money-moving story has travelled from cash carried on buses to transfers initiated on a phone. Yet the digital economy presents an interesting contrast: information can cross the world almost instantly, but moving money still involves national borders, different currencies, regulations and financial networks. The next chapter is not simply about making payments faster. It is about making cross-border transactions work as naturally as the trade, work and family relationships that already connect the continent.
Money has always moved across Africa, but the systems for moving it have rarely been simple.
For much of the continent's history, formal banking was concentrated in major cities and commercial centres. Large parts of the population operated outside the formal financial system, relying heavily on cash and informal networks to earn, save and transfer money.
Then there is the question of currency. Africa is home to more than 40 currencies, each operating within different monetary systems and financial regulations. Moving money between two African countries can involve currency conversion, intermediary banks and additional transaction fees. For example, Cameroon uses the Central African CFA franc (XAF), Côte d’Ivoire uses the West African CFA franc (XOF), while Rwanda uses the Rwandan franc (RWF). To make cross-border transactions easier, Grey has expanded into these markets, supporting regional currencies such as XAF and XOF and enabling users to move money across borders.
That fragmentation has had consequences for ordinary people as well as businesses. A family might have relatives living in another country. A trader might buy stock from across the border. Someone working in a city might earn their income hundreds of kilometres away from where their family lives.
As Africans moved across borders for work, trade and family, money had to follow. A trader in Lagos paying a supplier in Accra, for instance, could face currency conversion, intermediary banks and transfer fees before the money reached its destination. Historically, people relied on travelling relatives, traders and informal agents to bridge this gap.
Digital payments have changed how money moves, but sending money across African borders can still be costly and complicated. Grey helps simplify this process by enabling users to hold and exchange multiple currencies and make international transfers without relying on the traditional chain of intermediaries for every transaction. The goal is to make moving money across borders more accessible, convenient and transparent.
The arrival of mobile money changed the African financial landscape.
Mobile money has transformed financial access across Africa, and Kenya’s M-Pesa is one of its most successful examples. Launched in 2007, it allows people to send, receive and store money using their phones, with local agents providing cash-in and cash-out services. By March 2022, M-Pesa had reached 52.4 million customers across its African markets, processing more than 19 billion transactions that year. Its growth shows how mobile technology, agent networks and everyday payment services can bring financial services to people beyond traditional bank branches.
But sending money within Kenya is different from paying someone in another country. A freelancer in Nairobi paying a supplier in London or supporting family in Lagos needs a way to convert shillings and deliver the money to a foreign bank account. Grey lets users in Kenya fund their accounts through M-Pesa or a bank transfer and send money internationally. This includes Kenyan shillings to British pounds, euros to 30 European countries through SEPA, and Nigerian naira. SEPA, or the Single Euro Payments Area, is a payment network that standardises euro bank transfers across participating countries. Grey shows the exchange rate and fee before users confirm the transfer.
At the same time, infrastructure such as the Pan-African Payment and Settlement System (PAPSS), is being developed to make payments between African countries easier and reduce some of the dependence on international intermediary currencies.
The result is a financial system that looks increasingly different from the one that existed just two decades ago.
There is no single African way of sending money.
In Nigeria, instant bank transfers have become part of everyday life. The country’s fintech industry has also created a large network of digital payment services and agent banking, making it possible to move between bank accounts, wallets and cash.
Kenya’s story is more closely associated with mobile money. M-Pesa became deeply embedded in everyday transactions, from sending money to family to paying businesses.
In Rwanda, services such as MTN MoMo allow people to send money, pay bills and make purchases using their phones. The country’s 2024 FinScope survey found that 86% of Rwandans had used mobile money, showing how widely these services have been adopted. For international transfers, Grey supports sending money to Rwanda, making it easier to move funds across borders.
Ghana has also embraced mobile money, with approximately 73 million registered accounts by the end of 2024. Its payment infrastructure allows users to transfer funds across different mobile money providers and bank accounts. Grey also supports transfers to Ghana, connecting international payments with local receiving methods.
In South Africa, where bank transfers are already part of everyday life, the next step is to make it easier to move money out of the country. Grey enables users to send and receive money internationally without relying solely on traditional banking channels.
A person sending money from Nigeria may be using a bank account. The recipient in Cameroon may be using MTN MoMo. Someone in Kenya may expect the money to arrive through M-Pesa.
For the payment to work smoothly, all those systems have to communicate.
The differences are not accidental.
Each country has developed its payment ecosystem around its own regulations, infrastructure, economy and consumer behaviour.
Kenya’s mobile-money success was helped by an environment in which telecommunications companies could play a major role in financial services. Other markets have placed greater emphasis on commercial banks and licensed fintech companies.
Infrastructure also shapes behaviour. Where bank branches and formal financial services are easily accessible, consumers have more options. Where banking access is limited, mobile money agents can become a practical alternative.
Currency conditions matter too.
In countries experiencing significant currency volatility, people may look for ways to hold or receive money in stronger foreign currencies. For businesses operating across borders, access to foreign-currency accounts and efficient conversion can become particularly important.
This is why there cannot be a single solution for the entire continent. A payment product has to fit the market it enters, and increasingly, it also has to connect that market to others.
Behind all this infrastructure are very ordinary transactions.
A parent sends money to a child studying in another city. Someone working in construction sends part of their wages home. A trader pays a supplier. A family member abroad sends money to relatives. A small business receives payment from a customer in another country.
The amounts may vary enormously, but the importance of the transaction does not necessarily depend on its size. For someone running a market stall, a delayed payment can mean missing the chance to buy stock. For a family, it can mean waiting for money needed for food, transport or school fees. This is why the development of digital payments has been so significant. It is not simply making financial transactions faster. It is changing how people organise their economic lives across distance.
The next challenge is connecting all these systems.
Cameroon provides a useful example. Mobile-money services such as MTN MoMo and Orange Money have become important parts of the country's financial ecosystem. International remittance services can increasingly connect people outside Cameroon with recipients using these local wallets.
That creates a very different experience from the traditional bank wire. A recipient does not necessarily need a conventional bank account. Money can be deposited directly into the mobile wallet already used for everyday transactions. Grey is part of this emerging cross-border infrastructure, enabling supported users to send money to Cameroon via local payment networks, including MTN and Orange mobile money wallets.
One of the biggest challenges when moving money across Africa is that cross-border payments can be more complicated than they should be. A Nigerian business paying a supplier in Cameroon, for example, may face currency conversion requirements, intermediary banks, additional fees and delays, depending on the banks and payment route involved.
The Pan-African Payment and Settlement System (PAPSS), developed by Afreximbank in collaboration with the African Union, was created to address this problem. It connects participating banks and payment systems, allowing payments between African countries to be processed in local currencies without always routing them through third-party currencies such as the US dollar. PAPSS is expanding its network of participating countries and financial institutions to make cross-border payments easier and support trade under the African Continental Free Trade Area (AfCFTA). The goal is to make it easier for African businesses to buy and sell across borders without the cost and complexity of traditional international payment routes.
The significance of these developments goes beyond remittances. If money can move more easily between African countries, businesses can trade more easily. Freelancers can work for clients in other markets. Families can support relatives across borders. Traders can buy stock without relying on someone to physically carry cash. Africa’s payments story began with people finding ways to move money when formal systems could not do so easily.
It moved from cash carried by people, to money sent through mobile phones, to digital wallets and increasingly connected payment networks. The next stage is not simply about making transfers faster. It is about making the continent’s different financial systems work together.
And when that happens, sending money across Africa may finally become less about crossing borders, and more about simply moving money where it is needed.
Convert your Airtel SIM to an eSIM by SMS or in the Airtel Thanks app, with no store visit. See the steps and timings. Start the switch today.
Tunde Aladeloba
•
October 22, 2026
•
2 min read
Switching to an Airtel eSIM lets you use your mobile number without inserting a physical SIM card into your phone. Instead, your device stores the SIM profile digitally, making it easier to activate your line on a compatible smartphone and manage your mobile connection.
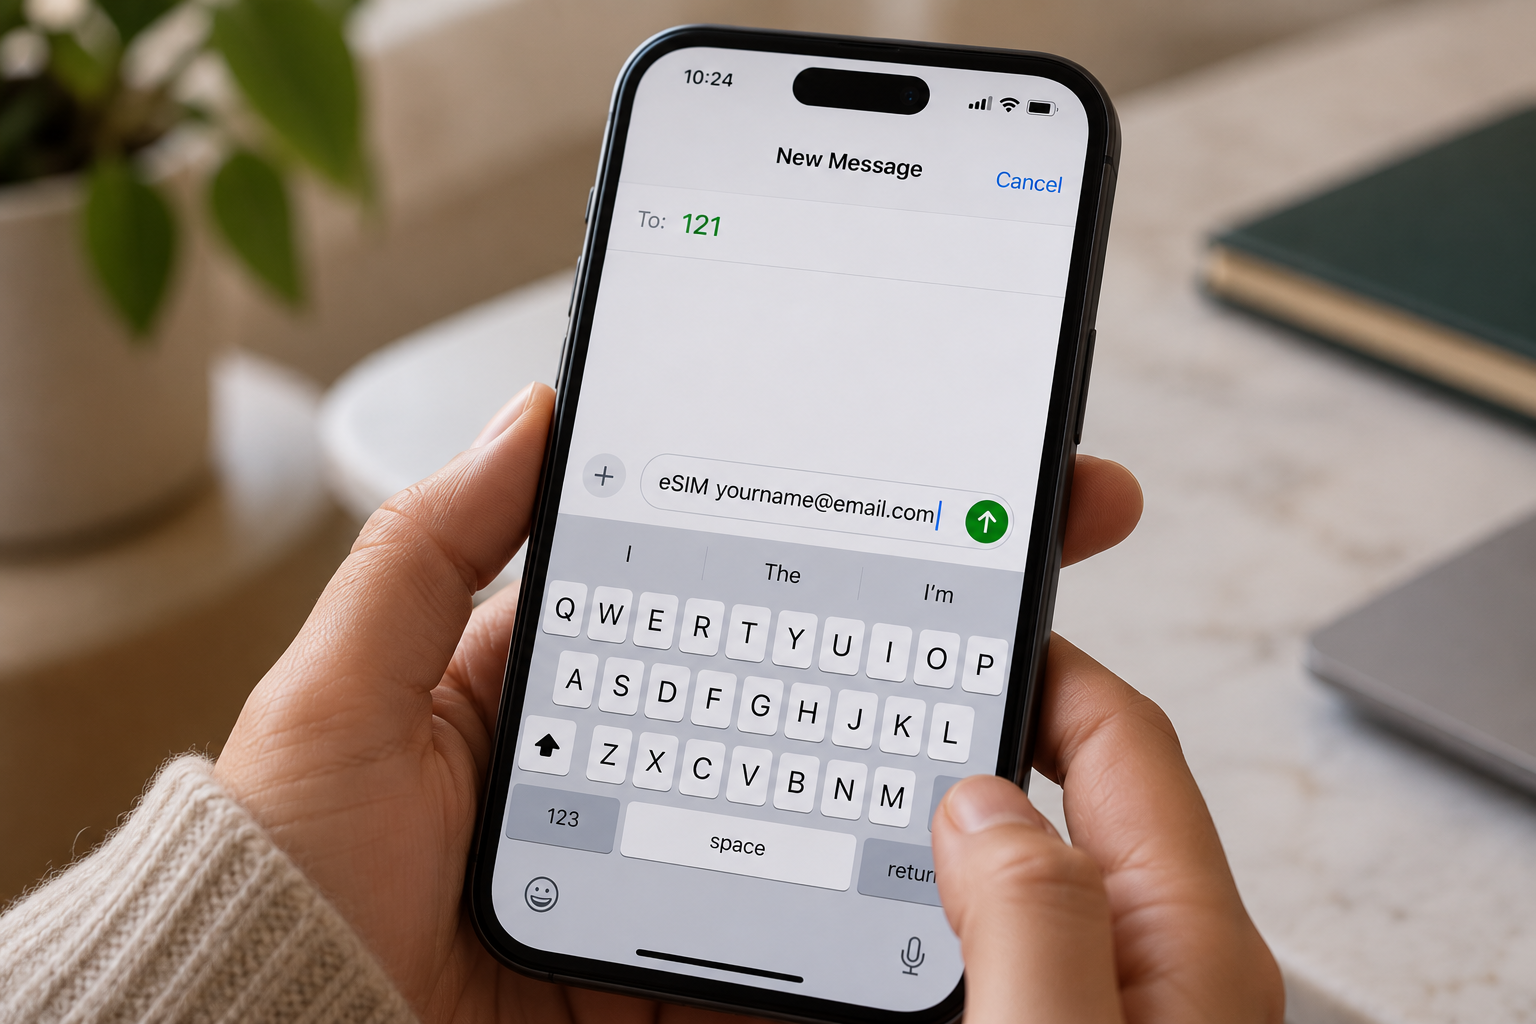
If you want to convert your existing Airtel SIM to an eSIM, you'll typically need to send a text message, confirm your request and scann a QR code sent to your email address. The exact steps and eligibility requirements may vary depending on your country and Airtel’s current eSIM service.
Before you begin, check that your phone supports eSIM technology and that your Airtel line qualifies for conversion. You should also have access to the email address linked to your request and a reliable internet connection to download your eSIM profile. This guide explains the steps to follow and what to know before switching.
Before converting your Airtel SIM to an eSIM, make sure you have a compatible smartphone, an active Airtel number and access to a registered email address. These are essential for completing the conversion and receiving the eSIM activation details.
1. An eSIM-compatible smartphone
Your phone must support eSIM technology. Common eSIM-capable devices include the iPhone XS, XS Max and newer models, selected Samsung Galaxy S20 and newer models, Google Pixel 4 and newer models, and certain newer Motorola devices. However, compatibility varies by model, region and carrier, so confirm that your specific handset supports eSIM.
2. A registered email address
You need a working email address to receive the eSIM QR code and activation instructions from Airtel. Check that you can access your inbox before starting the process.
3. An active Airtel number
Keep your existing Airtel SIM active so you can send the conversion request and confirm it when prompted. You may also need your phone to receive verification messages during activation.
Check Airtel’s local requirements before beginning, as procedures differ by country.
Convert your Airtel SIM to an eSIM by texting Airtel, confirming your request, waiting for activation and scanning the emailed QR code.
You can convert your physical Airtel SIM to an eSIM through the Airtel Thanks app without visiting a store, provided your number and device are eligible. The steps below apply to Airtel India; menu options may vary by app version.
To activate your Airtel eSIM, scan the QR code provided by Airtel using your phone’s mobile network settings. Keep your phone connected to Wi-Fi during setup, as the eSIM profile needs an internet connection to download.
If you’re moving to a new iPhone, follow this guide to transfer an eSIM from one iPhone to another.
After the eSIM activates, your physical Airtel SIM for that number is deactivated. You can remove it from your phone. If activation fails, contact Airtel before deleting any installed eSIM profile
Your Airtel eSIM may fail to activate because of a problem with your identity verification, phone compatibility, registered email address or activation timing. Identifying the specific issue helps you determine the right fix without unnecessarily repeating the conversion process.
If you need mobile connectivity while travelling, Grey lets you top up airtime and buy eSIMs. You can also manage cross-border expenses by using Grey to send money from the US to India or send money from the UK to India, helping you handle payments while staying connected abroad
An Airtel eSIM usually activates within two hours after you download and enable the eSIM profile on your compatible phone. During processing, your physical SIM may continue working. Keep your device connected to Wi-Fi and follow Airtel’s instructions to complete activation. Timings may vary by country and request.
No, converting your existing Airtel physical SIM to an eSIM generally keeps your current mobile number. The process replaces the physical SIM with a digital profile linked to the same line. You can continue using your number for calls, messages and mobile data once activation is complete.
Yes, eligible Airtel prepaid customers can convert their physical SIM to an eSIM in supported markets. However, the process differs by country. Airtel India provides an app-based conversion process, while Airtel Nigeria directs customers to a service centre for assistance. Confirm your line’s eligibility before starting.
Once your Airtel eSIM activates successfully, the physical SIM linked to that number becomes inactive. You can remove it from your phone because the eSIM now provides your mobile connection. Keep the physical SIM in place until activation is confirmed to avoid losing service during the transition.
Yes, you can generally switch your Airtel eSIM back to a physical SIM by requesting a SIM replacement. In India and Nigeria, Airtel directs customers to a service centre or showroom for assistance. Bring the required identification and complete any verification steps before using the replacement SIM.
The cost depends on your country and Airtel’s current policy. Airtel Nigeria currently states that eSIM activation has no charge, while other SIM replacement services or markets may have different fees. Before converting, check with your local Airtel provider whether activation, replacement or related services incur additional costs.
Dual citizenship brings double tax filing, military duty and travel limits in some countries. See the real costs before applying. Compare your options.
Tunde Aladeloba
•
October 22, 2026
•
2 min read
Dual citizenship allows you to be a legal citizen of two countries at the same time. It can give you more freedom to live, work and travel, but it also comes with responsibilities that may affect your finances, legal status and personal choices.
Before applying for a second nationality, it is important to understand the potential downsides of dual citizenship. You may need to file tax returns in both countries, meet military service obligations or follow different laws depending on where you live. You could also face limits on consular assistance while in your other country of citizenship.
In some cases, holding two nationalities can make it difficult to renounce one later. Certain countries also restrict dual citizenship or may withdraw your original nationality when you acquire another. Understanding these rules before making a decision helps you weigh the benefits against the possible risks and avoid unexpected legal or financial complications.
Dual citizenship taxes can be confusing because you may have tax obligations in both countries. Filing two tax returns is common, but paying tax twice on the same income usually is not. Whether you owe taxes in both countries depends on the tax laws of both countries, where you live, where your income comes from, and your citizenship status. Some countries tax residents on worldwide income, while others also tax citizens living abroad.
Tax treaties between countries can help reduce double taxation. These agreements may determine which country has the primary right to tax certain income or allow you to claim relief for taxes paid elsewhere. However, not every country has a tax treaty with every other country, and the rules differ by agreement. A treaty may reduce your tax burden without removing every filing requirement.
If you are a US citizen living abroad, the foreign earned income exclusion may allow you to exclude qualifying foreign-earned income from US federal income tax if you meet specific requirements. It does not automatically eliminate all US tax obligations. Before making decisions, check the rules in both countries and consult a qualified tax professional for guidance on your circumstances.
Countries have different rules on dual citizenship, with some prohibiting it altogether or withdrawing nationality when citizens voluntarily acquire another citizenship. Here are some countries that do not allow dual citizenship or impose restrictions on it:
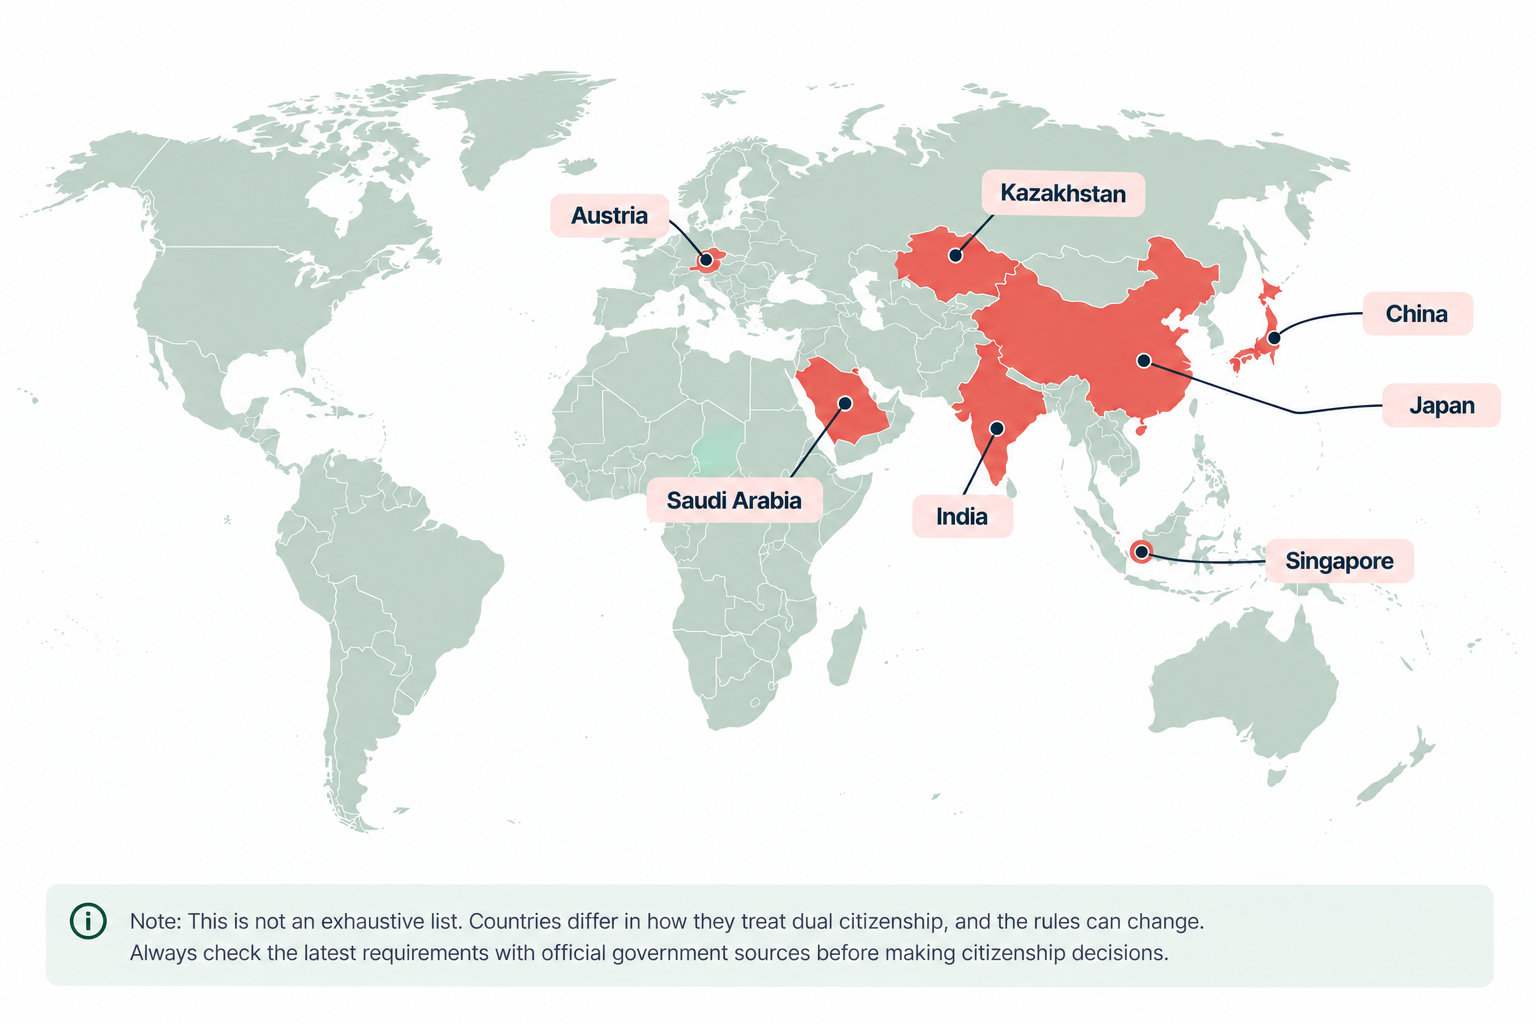
China does not recognise dual nationality under its Nationality Law. Chinese citizens who voluntarily settle abroad and acquire foreign nationality may automatically lose Chinese nationality. However, the application of this rule depends on legal circumstances, so verify current requirements before pursuing another citizenship.
India does not permit full dual citizenship. Indian citizens who voluntarily acquire another country’s citizenship generally lose Indian citizenship and must surrender their Indian passport. The Overseas Citizen of India (OCI) scheme offers eligible foreign citizens of Indian origin certain benefits, but it is not citizenship.
Japan generally requires people with multiple nationalities to choose one nationality under its Nationality Act. Those who acquire another nationality voluntarily may lose Japanese nationality. People who hold dual nationality from birth face a nationality-selection requirement, with deadlines and procedures depending on their circumstances.
Singapore generally prohibits adult citizens from holding dual citizenship. People who acquire Singapore citizenship may need to renounce their foreign nationality, while Singapore citizens who voluntarily acquire another nationality risk losing Singapore citizenship. Rules for minors differ, so check official requirements before making citizenship decisions.
Saudi Arabia restricts dual nationality. Saudi citizens generally require prior permission to acquire another nationality, and obtaining foreign citizenship without approval may lead to loss of Saudi citizenship under applicable law. The consequences depend on individual circumstances, so confirm current rules with Saudi authorities before applying.
Also read: How to receive international freelance payments in Saudi Arabia
Austria generally withdraws Austrian citizenship when a citizen voluntarily acquires another nationality, unless they obtain permission to retain Austrian citizenship beforehand. Exceptions may apply in specific circumstances, including certain cases involving citizenship by birth. Always check the legal requirements before pursuing naturalisation in another country.
Kazakhstan does not recognise dual citizenship under its nationality laws. Citizens who acquire another nationality are generally required to report it and surrender their Kazakh documents within the applicable period. Failure to comply may result in penalties, so confirm the current reporting and citizenship-loss rules with official authorities.
Consular protection is assistance your government provides when you encounter problems abroad, such as arrest, illness, lost travel documents or an emergency. If you hold dual citizenship, you may expect both countries to help you when something goes wrong. However, your ability to receive assistance from one country can be limited when you are inside the other country where you are also a citizen.
For example, if you are a dual citizen of the United States and Nigeria and face arrest while in Nigeria, US officials may be unable to intervene on your behalf. Nigerian authorities may treat you solely as a Nigerian citizen and may not recognise your American nationality. This can limit access to US consular assistance, including visits or representations to local authorities.
These restrictions do not mean you lose all consular protection whenever you travel. Your options depend on the countries involved, their laws and any applicable agreements. Before travelling, check your government’s guidance on dual nationality, local laws and emergency contacts so you understand what support may be available.
Dual citizenship can bring legal responsibilities in both countries, even when you live permanently in one. Depending on each country’s laws, you may be required to complete military service, respond to jury duty summons or meet compulsory voting requirements while living abroad.
Military conscription can be particularly important if one of your countries requires eligible citizens to serve in its armed forces. Some countries provide exemptions, deferments or alternative service arrangements, but these depend on factors such as your age, residency and circumstances. Jury duty and voting obligations also vary, and some countries allow citizens overseas to fulfil these duties remotely or qualify for exemptions.
Ignoring a legal obligation may lead to fines, travel restrictions, difficulties renewing documents or other penalties, depending on the country and the specific law. Before acquiring a second nationality, check the civic duties attached to both citizenships. Understanding these requirements can help you avoid unexpected obligations when travelling, relocating or returning to either country.
Also read: D7 visa Portugal: Requirements and how to apply
Renouncing citizenship is not always straightforward. The process depends on the country’s laws, and you may need to apply through an embassy or consulate, attend an appointment, submit original documents and prove that you hold another nationality. Some countries will not allow you to renounce citizenship if doing so would leave you stateless.
Fees and waiting times vary considerably. You may pay an application or administrative fee, cover document certification and translation costs, and wait several months or longer for approval. In some cases, additional checks or incomplete paperwork can delay the process.
Tax obligations can make renunciation more complicated. For example, the United States generally requires certain citizens who renounce their nationality to complete final tax filings, and some may face an expatriation tax if they meet specific criteria. Other countries may impose outstanding tax obligations or departure-related requirements, depending on their laws. Renouncing citizenship does not automatically erase unpaid taxes or other liabilities. Before proceeding, check the official requirements of your country and consider seeking qualified legal or tax advice.
Yes, dual citizens may have tax obligations in both countries, depending on residency, citizenship and income sources. The United States taxes citizens on worldwide income, even when they live abroad. Tax treaties and foreign tax credits can help reduce double taxation, although filing requirements may still apply.
Countries such as China, India, Japan and Singapore restrict or generally prohibit dual citizenship under specific circumstances. Saudi Arabia, Austria, Kazakhstan and Indonesia also impose restrictions. However, rules and exceptions vary, so check each country’s current nationality laws before applying for another citizenship.
Yes, some countries may withdraw your original citizenship when you voluntarily acquire another nationality. India generally ends Indian citizenship upon voluntary acquisition of foreign citizenship, while China does not recognise dual nationality and applies specific rules to citizens who settle abroad and acquire foreign citizenship.
Yes, dual citizens may face military service obligations in either country, depending on its laws. Requirements can depend on age, residency and nationality status. Some countries have exemptions or agreements to prevent double service, so check the rules before travelling or relocating.
Dual citizens may need to use a particular country’s passport when entering or leaving that country. For example, US citizens generally must use a US passport to enter and leave the United States. Check both countries’ requirements and use the appropriate passport for international travel.
Renouncing citizenship can involve application fees, official documents, interviews and waiting periods. US citizens must generally complete an in-person renunciation appointment and may have tax filing obligations, including potential expatriation tax. Other countries have different procedures, so confirm the requirements before beginning.
Managing money across borders becomes easier when you have the right tools. With Grey, you can send money internationally, including transfers from the US to Canada, while holding and managing multiple currencies. Whether you’re travelling, working remotely or receiving payments from abroad, Grey helps you manage international payments and access your money across borders with greater convenience and flexibility.
Compare 11 virtual PO box and mail scanning services for digital nomads on price, locations and forwarding. See which suits life on the road. Pick yours.
Tunde Aladeloba
•
October 21, 2026
•
2 min read
A virtual PO box, or virtual mailbox, gives you a real street address where a provider receives your post, scans it and forwards or shreds it on request. Digital nomads use one to keep a stable address for banks, tax letters and deliveries, even when they move between countries.
Without a permanent home, managing important mail can become complicated. You might miss a bank statement, struggle to receive a replacement card or need an address to register a business. A virtual mailbox helps you handle these tasks without relying on friends or family to collect your post.
However, providers differ in their locations, monthly fees, mail-scanning limits, forwarding options and international shipping costs. Some offer additional services, such as check deposits and package consolidation.
This guide covers 11 virtual mailbox services worth considering, helping you compare their features, pricing and availability to find an option that fits your travel routine and mailing needs.
A virtual PO box is a mail-handling service that gives you a physical mailing address without requiring you to rent or visit a mailbox in person. As a digital nomad, you can use it to receive letters, bank statements and packages while travelling or living abroad.
Unlike a traditional PO box, a virtual mailbox typically provides a real street address. When you sign up, your provider assigns you an address at its mail-handling facility. You can use this address for eligible correspondence, and the provider receives your mail on your behalf.
Your address may include a private mailbox (PMB) number, such as 123 Main Street, PMB 456. This identifies your individual mailbox within the provider’s facility. The exact format varies by provider, and you should follow its instructions when entering your address on forms.
A USPS PO box, by contrast, is rented directly from the United States Postal Service and usually uses a PO box number rather than a street address. A virtual mailbox may accept deliveries from multiple carriers, depending on its policies, and lets you view scanned mail online, request forwarding or arrange secure shredding.
The 11 best virtual mailbox services offer different address locations, mail scanning features, forwarding options and pricing plans. Whether you travel frequently, live abroad or run a remote business, compare each provider’s features to find a mailbox service that fits your needs.
Choosing a virtual mailbox starts with understanding how much mail you receive and how you want to manage it. Compare each provider’s scanning allowance, including the number of incoming envelopes covered and the cost of opening and scanning their contents. If you receive important documents regularly, a plan with generous scanning limits may offer better value than a cheaper subscription with extra fees.
Next, consider forwarding costs. Providers may charge handling fees in addition to postage, and international deliveries can become expensive. Look for options such as mail consolidation, which combines multiple items into one shipment, and check whether storage limits apply before forwarding.
Your address type also matters. A commercial address may suit general correspondence and business mail, but some banks or government agencies require a residential address. Confirm that the address meets the requirements of the organisations where you intend to use it.
Finally, check the provider’s process for USPS Form 1583. This form authorises a commercial mail receiving agency to handle your mail. You generally need to provide identification and complete the required notarisation or identity verification process before your mailbox becomes active.
Also read: Virtual US accounts explained: Who they work for
Yes, you can use a virtual mailbox for some banking and business purposes, but acceptance depends on the bank, service provider and intended use. Many virtual mailboxes provide a business mailing address for receiving bank statements, tax notices and official correspondence. However, a mailing address is not necessarily accepted as proof of your physical residential address. Before applying, review the bank’s address requirements and its rules for opening a business account.
Banks may flag a virtual mailbox as a commercial mail receiving agency (CMRA), which means it may not satisfy their physical-address verification requirements. This does not automatically prevent you from opening an account, but you must provide accurate details and any additional documents requested.
For business registration, a virtual mailbox may serve as your mailing address, depending on state rules. An LLC may also need a registered agent with a physical address in its state of registration to receive legal notices. Before applying, review this guide on how to open a business bank account and confirm the bank’s requirements.
Managing money while travelling can get complicated when your income, savings and expenses involve different currencies. You might earn dollars from a US client, pay for accommodation in another country and still need money for expenses back home. Keeping track of exchange rates, transfer fees and spending limits can quickly become frustrating.
Grey helps simplify cross-border money management by giving you a way to receive international payments and manage multiple currencies. Instead of constantly converting money whenever you get paid, you can hold supported currencies and exchange them when it suits your needs.
When you need to pay for flights, accommodation or online subscriptions, Grey’s virtual card for spending abroad gives you another way to make international payments. And if you’re travelling while working remotely, you can get paid from the US while abroad by sharing your Grey USD account details with clients. That way, earning and spending across borders becomes easier to manage
A virtual PO box, also called a virtual mailbox, gives you a mailing address where a provider receives your letters and packages. You can view scanned images of incoming mail online and choose to have items forwarded, stored or shredded. It is useful for travellers, remote workers and businesses that need reliable mail access.
Yes, virtual mailboxes are legal in the United States when used in accordance with applicable laws and postal regulations. Providers receiving USPS mail on behalf of customers operate as Commercial Mail Receiving Agencies (CMRAs) and must follow USPS requirements. You must provide accurate identification, complete required forms and avoid using the address for unlawful activities.
You can use a virtual mailbox as a long-term mailing address, even when you travel frequently. However, it may not qualify as your legal residence or physical address for every purpose. Government agencies, banks, insurers and licensing authorities may require a residential address, so check their specific rules before using one.
Some banks accept virtual mailbox addresses for mailing statements and correspondence, but others may reject them for account verification. A virtual mailbox is generally a commercial mailing address, not proof of where you live. Banks may require a separate residential or physical business address to meet identity-verification and compliance requirements.
USPS Form 1583 is an application that authorises a Commercial Mail Receiving Agency to receive mail on your behalf. You must provide identifying information and acceptable identification documents. Your signature must be witnessed by the provider or an authorised employee, or acknowledged before a qualified notary. Requirements should be confirmed with your mailbox provider.
A virtual mailbox typically costs around $5 to $40 per month, depending on the provider, address location and plan features. Basic plans may include limited mail scanning, while higher-priced options offer more scans, storage or business services. Budget for additional charges such as postage, forwarding, document scanning, package handling and international shipping.
USDC does not pay interest by default. See how exchange programmes, lending platforms and DeFi protocols compare on rate and risk. Compare options.
Tunde Aladeloba
•
October 21, 2026
•
2 min read
USDC is a stablecoin designed to maintain a value close to one US dollar, making it an option for people who want to hold digital dollars without the usual price swings associated with cryptocurrencies like Bitcoin. However, holding USDC in a wallet does not automatically generate interest. To earn a return, you need to invest your holdings in a programme or platform that pays a yield.
USDC itself pays no interest. Yield comes from lending it out through a centralised exchange programme, a crypto lending platform, or a DeFi protocol such as a lending pool or liquidity pair. Rates ranged from about 2 to 8% APY in 2026, depending on the platform, strategy and market conditions.
Each option comes with different levels of risk, access requirements and withdrawal conditions. Before choosing where to earn yield, understand how returns are generated, whether your funds are protected, and what could happen if a platform fails or a smart contract is exploited.
No, holding USDC in a crypto wallet does not earn interest by itself. USDC is a stablecoin designed to maintain a value close to one US dollar, but simply owning it does not generate additional income. Whether it sits in a personal wallet or an exchange account, your balance remains unchanged unless you receive additional USDC through another transaction or service.
To earn yield, you need to use a separate financial product built on top of USDC. These products generate returns through activities such as lending your stablecoins to borrowers, supplying liquidity to decentralised finance (DeFi) protocols, or participating in yield programmes offered by cryptocurrency exchanges.
Each option works differently and carries its own risks. A lending platform may pay interest from borrower repayments, while a DeFi protocol may distribute fees or lending revenue to participants. Centralised exchanges may offer promotional rates or rewards under specific conditions.
Before depositing USDC into any yield product, understand how returns are generated, what fees apply, and whether you can withdraw your funds when needed. Yield is never guaranteed.
Also read: How USDC compares with USDT
Centralised exchanges and crypto lending platforms allow you to earn yield by depositing your USDC into programmes that generate returns. Exchange earn programmes may lend your USDC to borrowers or use other permitted strategies to generate revenue, sharing a portion of the earnings with you.
Crypto lending platforms work similarly, connecting you with borrowers and paying interest on the funds you supply.
The annual percentage yield (APY) you receive depends on the platform, market demand, lending activity and programme conditions. Rates can change, and promotional offers may have limits or eligibility requirements.
Custody is another important consideration. When you deposit USDC into a centralised platform, the platform typically controls your assets rather than you holding the private keys directly. It may lend, transfer or otherwise use your deposited coins according to its terms.
This exposes you to counterparty risk. If the platform becomes insolvent, freezes withdrawals or suffers a hack, you may struggle to access your funds or lose them entirely. Before depositing your USDC, review the withdrawal terms, fees, security measures and how the platform uses your assets.
Decentralised finance (DeFi) offers another way to earn yield on USDC without relying on a traditional financial intermediary. Two common options are lending pools and liquidity pairs, each generating returns in different ways.
With a lending pool, you deposit USDC into a protocol where borrowers can access the funds and pay interest. A portion of that interest is distributed to depositors as yield. Your returns depend on borrowing demand, utilisation rates and the protocol’s rules.
With a liquidity pair, you deposit USDC alongside another cryptocurrency into a trading pool. Traders use this pool to swap assets, and liquidity providers may earn a share of trading fees. However, the value of the two deposited assets can change relative to each other, creating impermanent loss.
Both strategies carry risks. Smart contract bugs can expose deposited funds to theft or loss. Impermanent loss can reduce returns compared with simply holding the assets. Depegging occurs when USDC falls below its intended one-dollar value, reducing the value of your holdings even when the yield remains positive.
When you earn yield on USDC, your biggest risks depend on where you deposit your funds and how the platform generates returns. Counterparty risk, smart contract risk and depeg risk can all affect how much you earn and whether you recover your initial deposit.
Counterparty risk arises when you trust a centralised exchange or lending platform with your USDC. If the provider fails or freezes withdrawals, you may lose access to your funds. Smart contract risk affects you when a vulnerability in a DeFi protocol allows your deposited funds to be stolen or lost. Depeg risk means your USDC falls below its intended $1 value, reducing the value of your holdings.
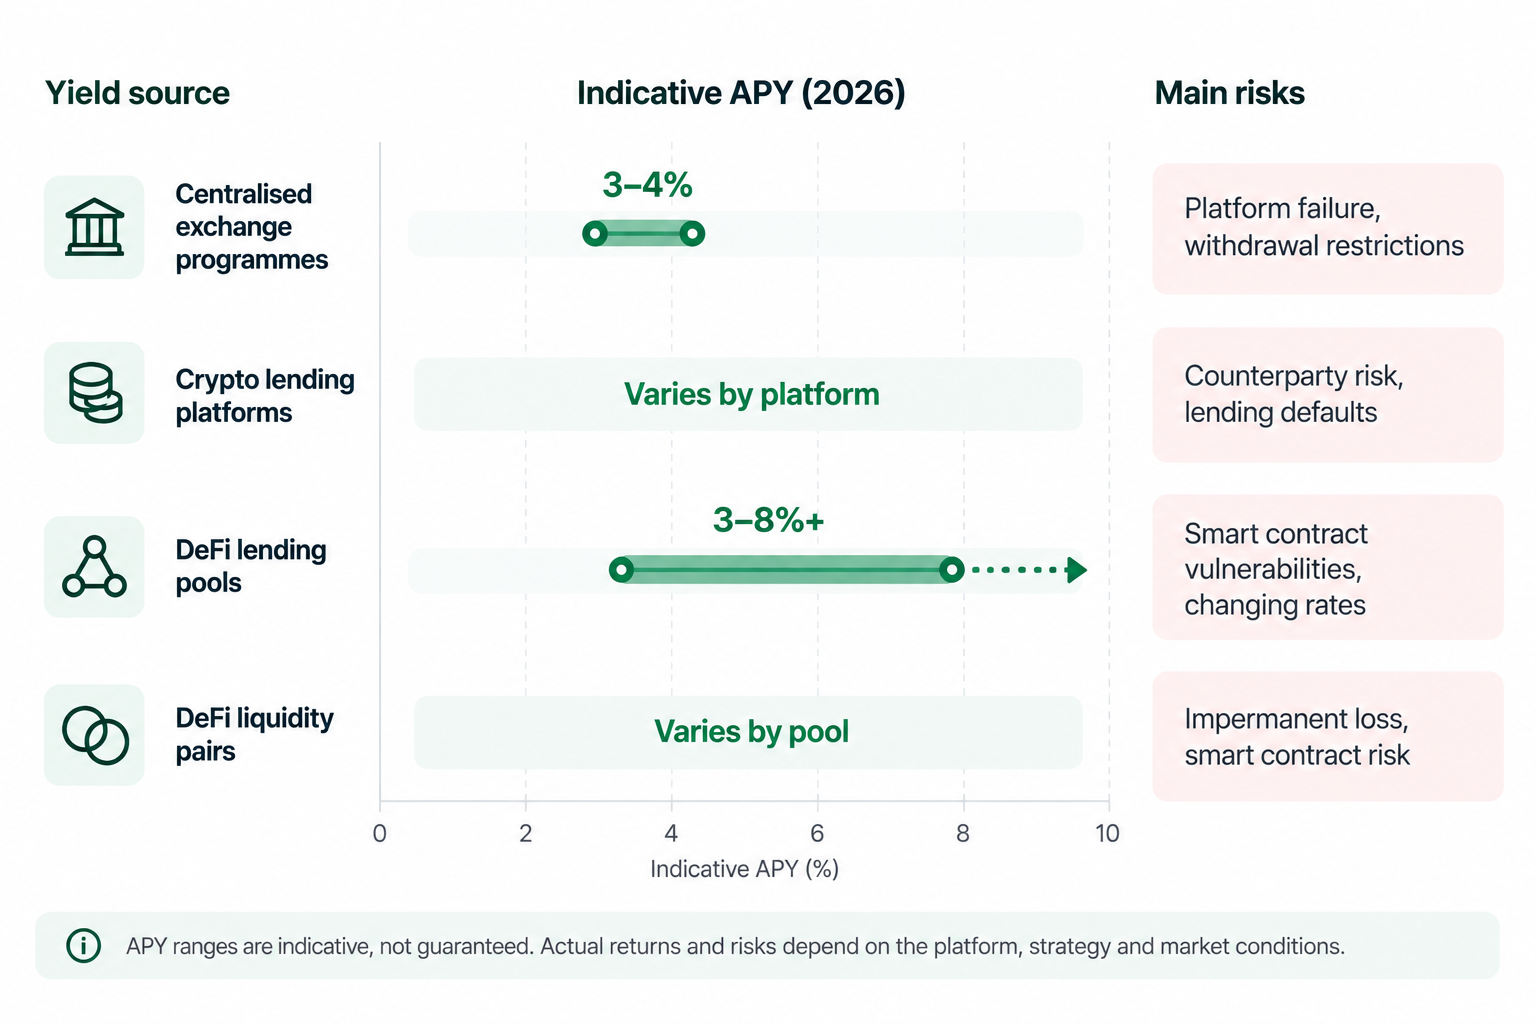
There is no universal ranking because your exposure depends on the product you choose. However, higher advertised APY usually means higher risk. Before depositing, consider how returns are generated, who controls your funds and what could go wrong.
Your choice of blockchain also matters. Learn how USDC on Solana compares with Ethereum when considering transaction fees, network activity and the platforms available to you.
USDC yield can offer a potentially higher return than a regular savings account, but you give up an important protection: USDC does not have government-backed deposit insurance. Your returns depend on the platform and strategy you use, and higher yields often come with greater risk. A bank savings account may offer less, but eligible deposits have protection and more predictable access to your money.
Before choosing USDC for yield, consider whether you can afford the risks, including platform failure, smart contract vulnerabilities and changes in USDC’s value. It is generally better to keep emergency funds in an insured bank account rather than expose money you need urgently to crypto-related risks.
USDC can also make moving money across borders easier. For example, if you need to send money from the US to Nigeria, you can use a platform that supports USDC transfers and local withdrawals. With Grey, you can send, receive and spend USDC, then convert your balance and withdraw funds to a supported local bank account.
The right choice depends on your priorities: bank deposits for protection, USDC for global access and potential yield.
Earning yield on USDC carries risks, including platform failure, smart contract vulnerabilities and loss of funds. Although USDC is designed to maintain a one-dollar value, your investment is not guaranteed. Review the platform’s security, withdrawal terms and yield strategy before depositing funds, and never invest money you cannot afford to lose.
USDC yield varies by platform, market conditions and strategy. In 2026, some centralised reward programmes offer around 3–4% APY, while DeFi lending may offer approximately 3–8% or more. These are indicative ranges, not guaranteed rates. Check current offers, fees and risks before choosing a platform.
Yes, USDC yield may be taxable, depending on your country’s tax laws and how you earn it. In the United States, rewards are generally reportable as income. Keep records of payments, dates and amounts, and consult a qualified tax professional to understand your reporting obligations.
Yes, you can lose some or all of your USDC principal. Platform insolvency, lending defaults, smart contract exploits and liquidity problems can prevent withdrawals or cause losses. USDC can also trade below one dollar. Assess the risks carefully, diversify where appropriate and avoid committing essential savings.
USDC yield usually comes from lending, reward programmes or providing liquidity through a platform or DeFi protocol. Staking typically involves locking cryptocurrency to support a proof-of-stake blockchain. USDC does not use proof-of-stake itself, so products marketed as USDC staking generally involve a different yield-generating mechanism.
First, withdraw your USDC and earn rewards to a supported exchange or financial platform. Convert the balance into your preferred currency, then withdraw it to an eligible bank account or payment method. With Grey, you can send, receive and spend USDC, subject to supported services, currencies and applicable fees.
While USDC yield offers the potential for higher returns, a bank savings account provides greater protection for eligible deposits. For international transactions, Grey gives you a practical way to send, receive and spend USDC, with access to supported currencies for your everyday financial needs.
The currency in France is the euro (EUR, €). See the notes and coins, where the CFP franc still applies, and how to pay without extra fees. Plan ahead.
Tunde Aladeloba
•
October 19, 2026
•
2 min read
The currency in France is the euro, represented by the symbol € and the ISO currency code EUR. If you are travelling to Paris, shopping in Lyon or paying for accommodation in Nice, you will use euros for everyday transactions. France replaced the French franc with euro banknotes and coins in 2002, making the euro its official currency.
The euro is used across mainland France and its outermost regions, including Guadeloupe, Martinique, Réunion, French Guiana and Mayotte. However, not all French territories use the euro. French Polynesia, New Caledonia and Wallis and Futuna use the CFP franc (XPF), a separate currency pegged to the euro at a fixed rate.
When budgeting for a trip, remember that prices are generally displayed in euros, whether you are paying for meals, transport or shopping. If your money is in another currency, check the exchange rate and any conversion fees before making payments. Using a suitable travel card or payment service can also help you manage spending abroad.
France uses the euro (€), with the ISO currency code EUR. If you are planning a trip to Paris, exploring the French Riviera or shopping in Marseille, you will pay for most goods and services in euros.
France previously used the French franc as its national currency. The country adopted the euro for electronic and financial transactions in 1999, before euro banknotes and coins entered circulation on 1 January 2002. The franc was then gradually withdrawn, completing France’s transition to the shared European currency.
When checking prices during your visit, look for the € symbol, which usually appears before or after the amount depending on the format. For example, €25 represents twenty-five euros. If you are converting money from naira, pounds or US dollars, the amount you receive will depend on the current exchange rate and any fees charged by your bank or payment provider.
Before travelling, compare conversion costs and payment options so you can manage your spending in France more confidently.
France no longer uses the French franc as its official currency. The euro (€), code EUR, replaced it, with euro banknotes and coins introduced in 2002. However, France still uses a different franc in some of its Pacific territories: the CFP franc (XPF).
If you travel to French Polynesia, New Caledonia or Wallis and Futuna, you will encounter the CFP franc rather than the euro for everyday payments. Although these territories are French, they have a separate currency arrangement suited to their regional economies.
The CFP franc is linked to the euro at a fixed exchange rate of €1 = 119.3317 XPF. This means its value against the euro does not fluctuate with ordinary market exchange-rate movements. However, when converting your money from another currency, such as US dollars or Nigerian naira, the amount you receive can still change with exchange rates and provider fees.
If you are visiting these Pacific territories, check whether your bank card supports local payments and compare conversion charges before travelling. The CFP franc remains distinct from the former French franc, despite sharing the name.
When paying in France, you can use euro banknotes, coins and payment cards. Euro banknotes come in €5, €10, €20, €50, €100 and €200 denominations, while coins range from 1 cent to €2. Prices are displayed in euros, so check the total before paying.
Debit and credit cards are widely accepted in shops, hotels, restaurants and supermarkets. Contactless payments are common, allowing you to tap your card or compatible phone at checkout. However, some transactions may require a PIN, and individual merchants can set minimum card payment amounts where permitted.
Cash remains useful when visiting local markets, buying from smaller vendors, using certain public facilities or making purchases at businesses that do not accept cards. Keeping a little cash available can help you avoid payment difficulties.
If you need a convenient way to pay while travelling, Grey’s virtual card can help you make online and supported card payments in euros. Before your trip, check the card’s currency conversion rates, applicable fees and acceptance conditions so you can plan your spending with confidence.
Also read: Cheapest cities in France for international students
You can get euros for your trip to France through bank ATMs, currency exchange bureaux or your bank before departure. Withdrawing euros from an ATM in France can be convenient, but check your bank’s foreign transaction fees and the ATM operator’s charges. Use ATMs attached to established banks where possible.
Exchange bureaux at airports and tourist areas are easy to find, but they may offer less favourable rates. Compare the final amount you will receive after fees rather than relying only on advertised exchange rates.
When paying by card or withdrawing cash, you may be asked whether you want to pay in euros or your home currency. Choose euros to decline dynamic currency conversion. This usually lets your card provider handle the conversion, which may offer a better rate, although your provider’s fees still apply.
For cross-border payments, Grey offers a way to send money from the US to France. Compare the available exchange rate, transfer fees and delivery times before sending funds, so you can budget for your trip and manage your euros more effectively.
Whether you are paying rent, covering tuition or supporting family, choosing the right transfer service can help you manage international payments to France. Grey supports cross-border money transfers, allowing you to send money from the UK to France and manage international payments through its platform.
Before sending money, compare exchange rates, transfer fees and delivery times to understand how much your recipient will receive. Bank transfers can include intermediary charges, while card payments may attract foreign transaction fees depending on your provider.
Grey’s multi-currency account helps you hold and manage supported currencies in one place, making it easier to organise international finances. Its virtual card also lets you make eligible online payments and pay for supported purchases in euros. Depending on your card terms and transaction, this may help you avoid certain foreign transaction fees.
France uses the euro as its official currency. The French franc was replaced by euro banknotes and coins in 2002. However, some French Pacific territories still use the CFP franc, a separate currency linked to the euro at a fixed exchange rate.
The euro symbol is €, and its three-letter ISO currency code is EUR. You will see the symbol on price tags, receipts and menus across France. For example, €50 means fifty euros. When exchanging money, use EUR to identify the currency correctly.
US dollars are not generally accepted for everyday purchases in France. You will usually need euros to pay for meals, transport, shopping and accommodation. Exchange your dollars before travelling or withdraw euros from an ATM. Check conversion rates and fees to manage costs.
Cards are widely accepted across France, including in hotels, restaurants and shops. Contactless payments are common, making cards convenient for everyday spending. However, cash remains useful at local markets and smaller businesses. Carrying a little of both gives you greater flexibility during your trip.
French Polynesia uses the CFP franc, abbreviated XPF, rather than the euro for everyday transactions. The currency is pegged to the euro at a fixed rate of €1 = 119.3317 XPF. Check your card’s international payment fees before travelling to the islands.
You can send money to France through a bank or an international transfer service. Compare exchange rates, transfer fees and delivery times before choosing. Grey supports cross-border payments, including transfers from the US to France. Confirm service availability and recipient details before sending.
The IRS lets you gift up to the annual exclusion per recipient with no tax owed and no form to file. See the current limits. Check the limits.
Tunde Aladeloba
•
October 19, 2026
•
2 min read
Giving money to another person may seem straightforward, but large financial gifts can come with tax reporting requirements. In the United States, the Internal Revenue Service (IRS) determines how much you can give each year before you may need to report the gift. Understanding these rules is particularly important when transferring substantial sums, sharing wealth, or planning your finances.
The good news is that exceeding the annual gift tax limit does not automatically mean you owe tax. The IRS provides a lifetime exemption that allows you to give more than the annual limit before gift tax becomes payable. Knowing the difference between the annual exclusion, reporting requirements and lifetime exemption can help you make informed financial decisions.
The IRS annual gift tax exclusion lets you give up to a set amount per recipient each year with no tax owed and no form to file. Gifts above that amount count against your lifetime exemption and require Form 709, though tax is rarely owed until the lifetime exemption itself is used up.
For 2026, you can give up to $19,000 per recipient per year without owing federal gift tax or generally needing to file a gift tax return. This annual exclusion applies to qualifying gifts of money or property under US Internal Revenue Service (IRS) rules.
The limit resets every calendar year, beginning January 1. This means gifts made in 2026 are counted separately from gifts made in 2025. You can give money to multiple recipients in the same year, provided each recipient’s total qualifying gifts from you stays within the annual limit.
The exclusion applies per giver and per recipient, rather than as one combined limit for all your gifts. For example, you could give $19,000 each to three people in 2026, totalling $57,000, without exceeding the annual exclusion for any recipient. If two spouses each give the same recipient $19,000, their combined gifts can reach $38,000 under their separate exclusions, subject to applicable IRS rules.
For 2026, the US lifetime gift and estate tax exemption is $15 million per individual. This is the total amount an individual can transfer through qualifying gifts during their lifetime and leave to beneficiaries at death before federal gift or estate taxes generally apply, subject to applicable rules.
The lifetime exemption works alongside the annual gift tax exclusion. While the annual exclusion allows qualifying gifts of up to $19,000 per recipient in 2026 without using the lifetime exemption, larger gifts generally count toward the $15 million limit. Gifts exceeding the annual exclusion may require you to file IRS Form 709, even when no tax is due.
The important distinction is that the lifetime gift tax exemption and estate tax exemption are shared, not separate allowances. For example, if you make $2 million in taxable gifts during your lifetime, that amount generally reduces the exemption remaining for your estate. Any unused exemption may apply to assets transferred at death, helping determine whether your estate owes federal estate tax.
You generally need to file IRS Form 709 if you give more than $19,000 to one person in 2026, unless a specific exception applies. The form reports gifts exceeding the annual exclusion and helps the IRS track your use of the lifetime gift tax exemption.
The filing requirements, deadline and potential tax implications are important to understand before submitting your return.
Who Must File Form 709?
The person giving the gift is generally responsible for filing. You may need to file if your gifts to one recipient exceed the annual exclusion, you transfer certain future interests, or you elect to split gifts with your spouse.
When Is Form 709 Due?
The deadline is generally April 15 of the year following the gift. For gifts made in 2026, the filing deadline is April 15, 2027. An extension may be available, but it does not automatically extend the deadline for paying tax owed.
Does Filing Form 709 Mean You Owe Tax?
No. Filing the form does not automatically mean you owe gift tax. Gifts above the annual exclusion generally reduce your lifetime gift and estate tax exemption. Federal gift tax is typically payable only after your available exemption has been exhausted.
Gift tax and estate tax share one combined lifetime exemption. In 2026, the federal gift and estate tax exemption is $15 million per individual. This means large gifts made during your lifetime and assets transferred after your death generally count toward the same exemption.
If you give a substantial amount of money while alive, the portion exceeding the annual gift tax exclusion generally reduces the exemption remaining for your estate. For example, if you make $2 million in taxable gifts, that amount generally reduces your remaining exemption to $13 million, assuming no other taxable transfers or adjustments.
Alternatively, leaving the money in your estate means its value may be considered when calculating estate tax after your death. If your total taxable estate and applicable prior gifts remain within your available exemption, federal estate tax generally will not be due.
The main difference is when the transfer happens and how the assets are valued. Lifetime gifting can help transfer wealth earlier, but the best approach depends on your financial circumstances, future needs and estate planning goals.
If you're sending money as a gift to family members abroad, it's also worth considering transfer fees and exchange rates. For example, you can send money from the US to Mexico or send money from the US to India using available international transfer services. Just remember that sending money internationally doesn't automatically exempt a gift from US tax reporting requirements.
Generally, no. Under US federal tax rules, the recipient does not pay income tax on money received as a gift. The person giving the gift is usually responsible for any applicable gift tax reporting and payment. However, income generated by gifted assets may be taxable to the recipient.
Yes. Gifts exceeding the 2026 annual exclusion of $19,000 per recipient may require you to file Form 709. However, the excess generally reduces your lifetime gift and estate tax exemption rather than triggering immediate tax. Gift tax usually becomes payable after the available exemption is exhausted.
Generally, gifts to a US-citizen spouse qualify for the unlimited marital deduction and do not count toward the annual exclusion. Gifts to a non-US citizen spouse have a separate annual limit, which is $194,000 for 2026. Special rules may apply depending on the circumstances.
Yes. Money sent to relatives abroad may qualify as a gift under US tax rules. If the giver is subject to US gift tax, the annual exclusion and reporting requirements may apply regardless of where the recipient lives.
You may need to. US persons who receive gifts exceeding $100,000 in total from a nonresident alien individual or foreign estate generally must report them on Form 3520. Different thresholds apply to gifts from foreign corporations or partnerships.
Failure to file Form 709 when required may result in penalties based on the unpaid gift tax, generally 5% per month, up to 25%. If no tax is due, penalties may differ, but the IRS can still assess consequences for noncompliance. Filing requirements should be checked carefully.
Managing money across borders involves more than understanding gift tax. Whether you are supporting family abroad, making international payments or managing everyday expenses, having the right financial tools matters. Grey offers multi-currency accounts and virtual cards that make it easier to manage international finances, pay for online services and handle supported cross-border transactions.
See who qualifies for the UAE Golden Visa and how to apply. Routes, thresholds and steps, checked against official sources. Start planning your move.
Tunde Aladeloba
•
October 15, 2026
•
2 min read
The UAE Golden Visa offers long-term residency to investors, entrepreneurs, skilled professionals and individuals with exceptional talent who want to live and build their future in the United Arab Emirates. Depending on the eligibility category, the visa is typically valid for five or ten years and can be renewed.
Unlike standard residency permits, the UAE Golden Visa allows eligible holders to live, work and study in the country without requiring a national sponsor. It also offers greater flexibility for individuals seeking long-term stability, career opportunities and business growth in the UAE.
Eligibility depends on factors such as professional qualifications, salary, investment value, business ownership or recognised achievements. Applicants must meet the specific requirements for their chosen category and provide supporting documents.
The application process generally involves identifying the appropriate eligibility route, gathering the required documents and submitting an application through the relevant UAE government authority or approved channel.
Understanding the eligibility criteria, documentation requirements and application process can help prospective applicants make informed decisions before applying for the UAE Golden Visa.
The UAE Golden Visa is a long-term residence permit introduced by the United Arab Emirates to attract investors, entrepreneurs, skilled professionals, scientists and individuals with exceptional talents. It allows eligible foreign nationals to live in the country and pursue career, business or educational opportunities without needing a traditional national sponsor.
The visa is generally issued for five or ten years, depending on the applicant’s eligibility category and the applicable requirements. It is renewable, provided the holder continues to meet the relevant conditions. The validity period offers greater stability for individuals and families planning to establish long-term roots in the UAE.
One of the key benefits of the UAE Golden Visa is self-sponsored residency. Unlike many standard employment-based residence permits, holders do not need an employer or UAE national to sponsor their residency. This provides greater independence when changing jobs, managing businesses or exploring professional opportunities.
For eligible applicants, the UAE Golden Visa offers more than extended residency. It provides flexibility to build a career, invest, study and plan for the future in one of the Middle East’s leading business and lifestyle destinations, subject to applicable laws and visa conditions.
Your eligibility for the UAE Golden Visa depends on your professional achievements, investments, qualifications or exceptional abilities, with specific requirements for each applicant category.
Investors may qualify through eligible public investments or real estate investments that meet the UAE’s financial and regulatory requirements. Applicants must provide supporting documents to demonstrate that their investments satisfy the applicable criteria.
Entrepreneurs may qualify through business ownership, approved projects or demonstrated entrepreneurial achievements, depending on the relevant eligibility category. Applicants must meet the applicable conditions and provide evidence of their business activities or project qualifications.
Skilled professionals may be eligible based on their occupation, educational qualifications, employment status, salary and other requirements. Eligibility depends on the applicant’s professional category and the relevant government regulations.
Outstanding students and graduates may qualify based on academic performance, examination results and recognised institutional criteria. Specific requirements apply depending on their educational background and the relevant eligibility pathway.
Individuals with exceptional abilities in fields such as science, technology, arts, culture and sports may qualify through relevant approvals. Applicants may need to demonstrate recognised achievements, specialised expertise or professional distinction, depending on their field.
The UAE Golden Visa offers long-term residency to eligible investors through property ownership and qualifying capital investments. The minimum investment threshold for these routes is generally AED 2 million, subject to the applicable eligibility criteria and documentation requirements.
The property investment route requires real estate with a combined value of at least AED 2 million. Multiple properties may be combined to meet the threshold. Certain off-plan and mortgaged properties may qualify, depending on the emirate and applicable conditions.
Investors may qualify by investing at least AED 2 million in an eligible UAE investment fund or qualifying business. An approved bank deposit may also meet the requirements, subject to the relevant regulations and supporting documentation.
Online claims about a UAE Golden Visa costing approximately ₹23 lakh, or AED 100,000, have caused confusion. This amount should not be mistaken for the standard investment threshold for the Golden Visa. Any offer promising residency at a significantly lower cost should be verified through official UAE government channels before payment.
Also read: How UAE freelancers save on currency exchange with Grey
1. Check your eligibility and apply
Choose the appropriate Golden Visa category and submit your application or nomination request through the relevant authority. Upload supporting documents, such as your property title deed, investment evidence or salary certificate, as required.
2. Obtain an entry permit if required
If you are applying from outside the UAE, check whether you need an entry permit to complete the residency process. Eligible applicants may use a six-month multiple-entry permit, subject to approval and applicable rules.
3. Complete your medical fitness test
Once in the UAE, complete the required medical fitness examination at an authorised centre. This typically includes a blood test and chest X-ray.
4. Submit your final application
Provide the remaining documents, including your medical fitness results and proof of health insurance, where required. Pay the applicable fees and wait for the authorities to process your application.
5. Complete biometrics and receive your Emirates ID
Attend your biometrics appointment if required. Once your application is approved, your Emirates ID and Golden Residency will be processed.
You can submit your UAE Golden Visa application online through the relevant government portal or get assistance in person at an authorised service centre.
Prepare the following documents before applying. Additional requirements depend on your eligibility category.
Read also: How to open a virtual bank account as a freelancer in the UAE
The UAE dirham (AED) is the country’s official currency and is pegged to the US dollar. Understanding money and banking in the UAE helps you manage everyday expenses, receive your salary and plan your finances. Opening a local bank account typically requires identification, residency documents and other information, depending on the bank.
If you manage money across countries, a multi-currency account makes it easier to handle international finances. Grey offers a convenient way to manage multiple currencies, giving you greater flexibility when receiving, holding and moving money across borders.
When you need to send money from the UAE to Nigeria, Grey provides a practical solution for cross-border transfers. Its multicurrency services help simplify international money management, whether you are supporting family, handling personal expenses or managing business payments. With Grey, you can streamline your international finances and make cross-border money transfers more convenient.
Eligible applicants include real estate investors, entrepreneurs, skilled professionals, exceptional talents and outstanding students. Each category has specific financial, academic or professional requirements. Applicants must meet the relevant criteria and provide supporting documents to qualify for long-term UAE residency.
The UAE Golden Visa is generally valid for five or ten years, depending on your eligibility category. It can be renewed if you continue to meet the applicable requirements. This long-term residency offers greater stability for professionals, investors and families planning to live in the UAE.
The minimum investment threshold for qualifying property and capital investment routes is generally AED 2 million. Skilled professionals may qualify through a separate route, subject to salary, qualification and employment requirements, including a monthly salary threshold of AED 30,000 for eligible categories.
Yes. Golden Visa holders can sponsor eligible family members, including their spouse and children, subject to applicable requirements. They may also sponsor domestic workers under the relevant rules. This allows families to enjoy greater stability while living together in the UAE.
Applications can be submitted through the relevant government authority, including ICP or GDRFA Dubai, depending on your emirate and category. Prepare your supporting documents, submit the application, complete required medical checks and biometrics, and pay applicable fees.
You can transfer funds to the UAE through international bank transfers or authorised money transfer providers. A local UAE bank account can help manage incoming funds and everyday expenses. Keep supporting documents for larger transfers and comply with applicable banking and anti-money laundering requirements.
Convert an eSIM back to a physical SIM without losing your number, whichever carrier you use. See what each one asks for. Start the swap today.
Tunde Aladeloba
•
October 15, 2026
•
2 min read
A phone upgrade is usually a straightforward process, until the SIM becomes part of the equation. Let's say the new device supports an eSIM, the number transfers successfully, and everything seems ready to go, then comes a trip abroad, a change of network or an older mobile phone that only accepts a physical SIM card.
At that point, the question is simple: what happens to the eSIM?
Unlike changing a setting on the phone, moving from an eSIM back to a physical SIM is handled by the mobile carrier. The network provider needs to deactivate the existing eSIM and issue a replacement physical SIM linked to the same mobile number. The exact process can vary, but most carriers allow the request through an app, over the phone or at a physical store.
The switch itself is usually straightforward once the replacement SIM arrives. After activation, the physical SIM takes over the number and the old eSIM profile can be removed from the device.
Also read: How to activate an eSIM: Step-by-step guide
Yes, you can switch from an eSIM to a physical SIM through your mobile carrier. However, your phone cannot make this conversion on its own. You'll need to contact your carrier to request a physical SIM card and transfer your number to it.
An eSIM is a digital SIM profile stored securely within the phone, while a physical SIM is a separate chip that needs to be issued and activated by the mobile network. Your carrier controls the connection between your mobile number, account and SIM credentials, so the switch has to happen on the network provider’s side.
The process is usually treated as a SIM swap or SIM replacement. Your carrier deactivates the existing eSIM and issues a physical SIM linked to the same number and account. Depending on the provider, the request may be available through its app, customer service team or a physical store.
Once the replacement SIM is activated, the old eSIM can be removed from your device.
Requesting a physical SIM from your mobile carrier usually involves choosing a replacement method, completing an identity check, receiving the SIM and activating it on your existing number.
Before removing your eSIM, make sure the replacement physical SIM is fully activated and working. Test it by making a call, sending a text message and checking that mobile data works. Deleting the eSIM too early could leave your phone without cellular service if the physical SIM has not yet been activated.
The wording can vary slightly depending on your iOS version and region:
Android settings differ between manufacturers, so the menu names may not be identical on every device:
Afterwards, check that your physical SIM remains selected for calls, texts and mobile data. If anything stops working, contact your carrier before making further changes.
Also read: eSIM vs Google Fit: Which is better for international travel?
Choosing between an eSIM vs a physical SIM often comes down to how, where and why a phone is being used. An eSIM is convenient for digital setup and travel, but a physical SIM still has practical advantages that can make it the better option in certain situations.
Selling or handing down a handset is one example. A physical SIM can simply be removed before the phone changes hands, leaving the new owner to insert their own SIM. This makes the separation between your mobile number and the device straightforward, particularly when the phone is being resold.
Travel is another consideration. Some dual-SIM phones make it easy to combine a physical SIM with an eSIM, allowing a local travel SIM to work alongside a primary number. This can be useful when moving between countries while keeping the main line active.
In some regions, eSIM support remains limited across carriers, plans and devices. A physical SIM can therefore provide greater flexibility when travelling or changing networks. For anyone comparing eSIM vs physical SIM, checking carrier and country compatibility before switching can prevent unexpected connectivity problems.
The quickest way to replace your eSIM with a physical SIM is usually a store visit, but ordering online can be more convenient. Here is what you can generally expect from major US carriers:
While ordering your replacement SIM, you may also need to make a payment. Grey can make that easier, with a multi-currency account and virtual card for international payments. If you're travelling, you can also buy an eSIM through Grey and manage your connectivity and spending from the same platform.
No, your phone number remains exactly the same. Your carrier simply transfers your existing mobile account and number from the eSIM to the new physical SIM. Once the replacement card is activated, you can continue making calls, sending messages and using mobile data as before.
Replacement fees vary by carrier, location and how you request the SIM. In many cases, you may pay between $0 and $25. Some major networks provide replacement cards free at corporate stores, while budget or prepaid providers may charge a separate SIM replacement fee.
No, you generally cannot keep both SIM profiles active on the same number. Your carrier links the number to the newly activated SIM during the replacement process, which deactivates the previous eSIM. Your phone may support two SIMs, but they cannot share one number simultaneously.
An in-store SIM replacement can often be completed within 10 to 15 minutes once your identity and account details have been verified. Ordering a physical SIM online usually takes longer, with standard delivery commonly taking around 3 to 5 business days, depending on your carrier.
No. Keep your eSIM active until the replacement physical SIM has arrived, been activated and successfully connects to the network. Deleting the eSIM too early can leave your phone without mobile service, particularly when the new SIM has not yet been activated.
Many carriers still offer physical SIM cards, but availability depends on the network and your device. Before requesting one, check that your handset has a physical SIM tray. Some newer phones, including certain regional models, are designed as eSIM-only devices and cannot accept a physical card.
Find out if you qualify for the D7 visa Portugal offers passive income earners. Income thresholds, documents and timings explained. Apply with confidence.
Tunde Aladeloba
•
October 11, 2026
•
2 min read
Portugal has become an attractive option for people who want to build a life in Europe without relying on a local job offer. For retirees, property owners and others with regular passive income, the Portugal D7 visa offers a way to apply for residency while continuing to support yourself from income earned outside the country.
The Portugal D7 visa is a residency route for non-EU nationals with a stable passive income, such as pensions, rental income or dividends. You must show income at least equal to the Portuguese minimum wage, plus proof of accommodation.
But having enough income is only one part of the application. You also need to understand the documentation, accommodation requirements, application process and what happens after your visa is approved. If you are considering Portugal as your next home, knowing what the D7 visa requires before you apply can help you avoid delays, prepare the right documents and decide whether this residency route fits your circumstances.
Also read: Portugal transfer limits from US banks: Rules explained
The Portugal D7 visa is a residency visa for non-EU nationals with stable passive income who want to live in Portugal.
The D7 visa is designed for non-EU nationals who can support themselves through regular passive income. Applicants must demonstrate sufficient financial means and provide accommodation evidence, making it suitable for people planning to relocate rather than simply visit Portugal.
Retirees are among the most common D7 applicants because pensions can qualify as passive income. Someone receiving a regular pension from another country may use that income to demonstrate financial stability while moving to Portugal for retirement.
The D7 can also appeal to people earning a regular income from sources outside Portugal. This may include rental properties, investments or other recurring income streams. However, remote workers whose income comes from active employment or freelancing should check whether another Portuguese visa is more appropriate.
The D7 is based on demonstrating reliable financial resources rather than securing a Portuguese job. Applicants generally need to show recurring income, such as pensions, rental income or dividends, alongside sufficient savings to support their stay and meet the visa requirements.
Understanding the Portugal D7 visa requirements gives you a clearer picture of what to prepare before submitting your application, from proving your finances to securing accommodation and meeting the health and character requirements.
For highly qualified professionals moving to Portugal for work, the EU Blue Card route provides another residency option. The route is designed for skilled workers with an eligible employment offer and comes with specific requirements
Also read: Real budgeting tips for nomads living in Lisbon
If you are applying for the Portugal D7 visa, following the process in the right order helps you prepare your documents, avoid unnecessary delays and know what to expect at each stage.
Start by preparing proof of income or financial resources, accommodation in Portugal, valid health insurance, a criminal record certificate, your passport and any other supporting documents required. You may also need to have certain documents authenticated or translated before submitting your application.
Next, submit your D7 visa application through the Portuguese consulate or visa application centre responsible for your country of residence. You will provide your documents, complete the application process and attend an appointment or interview if requested.
Once your residence visa is approved, you can travel to Portugal within the validity period shown on your visa. This gives you permission to enter Portugal and complete the next stage of your residency application.
After arriving in Portugal, you will attend your appointment with AIMA and submit the documents required for your residence permit. Once your application is approved, you will receive your Portuguese residence card, allowing you to live in Portugal legally.
Once you have your D7 residence permit, the focus shifts from getting approved to maintaining your residency and planning for the years ahead. That means understanding renewal dates, how much time you need to spend in Portugal, the route to citizenship and how becoming a tax resident could affect your income.
Your D7 journey begins with a two-year residence card, followed by a three-year renewal, provided you continue meeting the residency requirements and maintaining your ties to Portugal. You should also plan around the minimum-stay requirement, especially if you work remotely or are registering as self-employed abroad while living in Portugal.
A D7 residence permit is intended for people who genuinely live in Portugal, so your travel plans matter. You generally need to spend at least six consecutive months or eight non-consecutive months in Portugal each year. If your work takes you abroad frequently, factor these limits into your plans before choosing this residency route.
After five years of legal residency, D7 holders may become eligible to apply for Portuguese citizenship, subject to the applicable requirements, including an A2-level Portuguese language test. For someone building a long-term life in Portugal, this can turn the D7 from a temporary relocation decision into a potential pathway towards permanent belonging.
Getting a D7 residence permit does not automatically mean every tax obligation is the same; your tax residency depends on your circumstances and time spent in Portugal.
Portugal generally considers factors such as spending more than 183 days in the country or having a home there that indicate an intention to maintain it as your habitual residence. Once you become a tax resident, Portuguese IRS rules can apply to your income, including foreign-source income, subject to applicable exemptions, credits and tax treaties.
As you prepare your Portugal D7 Visa application, Grey can help you manage the money side of your move. Its multi-currency account lets you hold and manage different currencies, while giving you access to a euro account for receiving, holding and spending euros once you start settling into Portugal.
You will still need to prove that you have stable funds or a regular income to support yourself. Your bank statements and financial documents should clearly show where your money comes from and that you can cover your living costs. Having a euro account can also make everyday payments in Portugal more straightforward.
Whether you are moving money from the UK to Portugal or the US to Portugal, Grey gives you a way to move funds across currencies without having to juggle multiple accounts. You can convert your money to euros when needed and use your euro balance for expenses such as rent, bills and everyday spending.
The D7 visa is a Portuguese residence visa for non-EU citizens who have a stable income or sufficient financial resources. It is commonly associated with passive income, including pensions, investments and rental income, and allows eligible applicants to live in Portugal with their families.
The minimum income requirement is linked to Portugal’s minimum wage and currently starts at €920 per month for the main applicant. You need additional funds for dependents. You should also be prepared to demonstrate that your income or savings can support your planned life in Portugal.
Yes. Although your initial D7 application is based on demonstrating sufficient income or financial resources, holding Portuguese residency allows you to work legally in Portugal. This means you can take up employment, become self-employed or develop a business after your residency has been granted.
The initial D7 visa process can take around 60 days once your application is submitted, although processing times vary by consulate and individual circumstances. After receiving the visa, you travel to Portugal and complete the required steps to obtain your residence permit.
The D7 can provide a route towards Portuguese citizenship. Under the rules applicable to your application, you may become eligible after meeting the required period of legal residence and other conditions, including Portuguese language requirements. Check the current nationality rules before relying on a specific timeline.
You can transfer money internationally into your Portuguese bank account to support your move and everyday expenses. Grey can also help you move money across currencies, including transfers from the UK or US to Portugal, while its multi-currency account gives you access to a euro balance.
Know where contractor vs employee status really differs. Compare control, tax, benefits and the IRS classification tests in one place. Get the breakdown.
Tunde Aladeloba
•
October 11, 2026
•
2 min read
A new job offer can feel straightforward until you reach the part of the contract that describes your employment status. The salary may look attractive and the role may seem like the right next step, but being hired as an independent contractor rather than an employee can change what you take home, who handles your taxes and whether you receive benefits such as paid leave or health insurance.
An independent contractor runs their own business and controls how they work, while an employee works under the employer's direction. Employers withhold tax and provide benefits for employees, but not for contractors, who handle their own taxes
The difference is more than a job title, and getting it wrong can leave you with unexpected tax bills or fewer workplace protections than you expected. In this guide, we’ll break down the key differences between an independent contractor and an employee, so you can understand where you stand before signing your next contract.
This table compares the main differences between contractors and employees, from workplace control and taxes to benefits, job security, tools, and financial risk.
An independent contractor is a self-employed person who provides services to a business or individual under a contract rather than working as a traditional employee. Think of a freelance designer hired to create a company’s new website, a consultant brought in to solve a business problem, or a writer paid to produce a series of articles. They work independently and are generally responsible for deciding how, when, and where the work gets done, as long as they deliver what was agreed in the contract.
In the US, independent contractors are commonly paid as 1099 workers, meaning businesses generally report their payments to the contractor using a Form 1099-NEC when applicable. Unlike employees, contractors typically do not have income tax, Social Security, or Medicare taxes withheld from their payments, so they need to plan for these taxes themselves.
Being an independent contractor also comes with responsibilities beyond completing the work. Contractors usually handle their own tax filings, business expenses, insurance and retirement planning, while keeping records of income and expenses. The trade-off is greater control over how they work and, in many cases, the ability to work with multiple clients.
An employee is a person who works for a company or organisation under an employment relationship, where the employer generally controls what work is done, how it is performed and when it is completed. Unlike an independent contractor, an employee works as part of the organisation and is typically entitled to protections and benefits provided under their employment arrangement.
In the US, employees are generally paid through payroll and receive a W-2 form from their employer at the end of the tax year. The W-2 reports their wages and the taxes already withheld from their pay.
Employers typically withhold federal income tax, Social Security and Medicare taxes from an employee’s wages and send these amounts to the relevant authorities. This means employees do not usually need to set aside the full tax amount themselves.
Depending on the employer and role, employees may receive health insurance, retirement plans, paid time off and other benefits. If you encounter the term “what a 1099 employee is,” it is important to understand that a 1099 worker is generally an independent contractor, not an employee.
The difference between an employee and an independent contractor is not always obvious from a job title or contract. A company might call someone a contractor, but the IRS looks at the actual working relationship to determine how that person should be classified for tax purposes. It generally considers three categories of control.
The IRS considers whether the business has the right to direct how, when and where the worker performs their job. Detailed instructions, set working hours, training and supervision can indicate an employee relationship.
The IRS looks at how much control the business has over the worker’s financial and business activities. Factors include who provides tools and equipment, whether expenses are reimbursed, how the worker is paid and whether they can make a profit or experience a loss.
The nature of the relationship also matters, including written contracts, employee benefits, how permanent the arrangement is and whether the worker provides services that are a key part of the business. No single factor determines classification; the IRS considers the entire relationship.
Getting paid as a contractor or employee does not just change the amount that lands in your bank account; it also changes the paperwork you receive, who handles your tax withholding and what happens if your worker classification is wrong.
Employees generally receive a W-2 showing their wages and taxes withheld by their employer, while independent contractors typically receive a 1099-NEC for qualifying payments. Understanding 1099 vs. W-2 can help clarify how each worker is paid, what taxes are withheld, who is responsible for reporting income, and what paperwork to expect.
Contractors generally have to account for both the employer and employee portions of Social Security and Medicare taxes through self-employment tax, meaning they need to plan for these payments themselves rather than relying on payroll withholding.
Calling a worker a contractor does not automatically make them one. If a business treats an employee as an independent contractor, it may face additional taxes, penalties and other consequences, while the worker could miss protections and benefits they should have received.
Paying a contractor can look simple until the person doing the work lives in another country. A US-based company might have a designer in the Philippines, a developer in Nigeria or a marketing consultant in Brazil, and suddenly the payment process involves exchange rates, transfer fees, payment details and waiting times.
This is where Grey can make contractor payments easier. Businesses can use Grey to pay contractors from the US and send payments internationally without having to navigate a complicated process for every contractor. The platform supports transfers across multiple currencies, allowing businesses to hold and convert funds before sending money to contractors in supported countries.
For example, a US company paying a contractor in the Philippines can use Grey to send money from the US to the Philippines, while the contractor receives the funds in the supported local currency. For businesses working with international talent regularly, having one place to manage these payments can make cross-border contracting much simpler.
An employee works under an employer’s direction and typically receives payroll withholding and benefits, while an independent contractor runs their own business and controls how they complete their work. Contractors generally handle their own taxes, business expenses and insurance, while employees receive greater workplace protections and employer-provided benefits.
The IRS looks beyond a worker’s job title or contract and examines the actual working relationship. It considers behavioural control, financial control and the relationship between the worker and business. No single factor automatically determines classification, so businesses should consider the full arrangement when deciding whether someone is an employee or contractor.
Independent contractors generally do not receive employee benefits such as employer-sponsored health insurance, paid vacation or retirement contributions. Instead, they are responsible for arranging their own insurance, retirement savings and other benefits. However, a contractor’s specific agreement can provide certain perks or payments, depending on what the business and contractor negotiate.
Misclassification happens when a business treats a worker as an independent contractor when the person legally qualifies as an employee. This can affect taxes, benefits and workplace protections. For the business, misclassification can lead to unpaid employment taxes, penalties and other costs, while the worker may lose benefits they should have received.
Yes, someone can potentially work as an employee for one business while independently contracting for another. For example, a person could have a full-time W-2 job and provide freelance consulting services to separate clients. However, the classification of each working relationship depends on the specific facts and circumstances involved.
Paying an overseas contractor typically involves choosing a payment method, confirming the contractor’s banking details and considering currency conversion, transfer fees and tax documentation. Platforms such as Grey can help businesses make international payments, allowing them to send money across borders without relying on traditional bank transfers for every contractor.
See who qualifies for the EU Blue Card and how to apply. Degree and salary thresholds, plus the German route, explained. Start your application today.
Tunde Aladeloba
•
October 11, 2026
•
2 min read
Moving to Europe for work can feel complicated when you are trying to understand which visa, residence permit and eligibility requirements apply to you. The EU Blue Card offers a route for highly qualified non-EU nationals who have the skills and qualifications European employers need.
To qualify for an EU Blue Card, you generally need a recognised university degree or equivalent professional qualification, a qualifying employment contract or job offer, and a salary that meets the required threshold in the EU country where you plan to work. Requirements can vary between countries, so checking the rules for your destination matters before you apply.
The EU Blue Card combines the right to live and work in a participating EU country with a pathway to greater mobility within the EU. Understanding the eligibility criteria, salary requirements and application process can help you decide whether it is the right route for your move.
Also read: Expat living in Germany: Banking, visas and costs
The EU Blue Card is a work and residence permit for highly qualified non-EU nationals who have a qualifying job offer in a participating European Union country. It is designed to attract skilled professionals from outside the EU by giving them the right to live and work in the country where they are employed, provided they meet the required qualifications, salary and employment conditions.
The “highly qualified” requirement generally means you need higher education qualifications, such as a recognised university degree, or qualifying professional skills recognised under the rules of the country where you apply. You also need a binding job offer or employment contract that meets the required salary threshold. Because these thresholds and application requirements vary by country, your eligibility can depend on where you plan to work.
Most EU countries participate in the EU Blue Card scheme, including Germany, France, the Netherlands, Spain and Italy. Denmark and Ireland do not participate, so you need to consider the specific immigration route available in your chosen destination before applying.
You may qualify for the EU Blue Card if you are a highly qualified non-EU national with a qualifying job offer in a participating EU country. You generally need higher professional qualifications, a work contract or binding job offer lasting at least six months, and a salary that meets your destination country’s threshold.
A university degree is the most common way to meet the qualification requirement, typically through a recognised higher education programme of at least three years. However, some countries also recognise relevant professional experience as an alternative, particularly for certain occupations such as IT. Your job must also match the qualifications or professional skills you are using to qualify for the card.
There is no single euro salary figure for the whole EU. Under the current rules, each participating country sets its own threshold, generally between 1 and 1.6 times its average gross annual salary. For example, Germany’s 2026 threshold is €50,700, with a lower €45,934.20 threshold for shortage occupations and certain recent graduates.
Germany is the largest issuer of EU Blue Cards in Europe, making it an important destination for highly qualified professionals looking to work in the EU. In 2024, Germany issued 56,252 Blue Cards, representing 72% of all cards issued across the EU.
For 2026, the standard salary threshold in Germany is €50,700 gross per year. A lower threshold of €45,934.20 applies to shortage occupations, provided the Federal Employment Agency approves the employment. Recent graduates can also qualify at the lower threshold, while certain IT specialists may qualify without a university degree if they have the required professional experience.
Germany’s shortage occupations include academic STEM professionals, doctors, veterinarians, dentists, pharmacists, nurses and midwives, teachers and educators, as well as certain managers in manufacturing, logistics, ICT and professional services. This means that when searching for German companies that sponsor work visas, your occupation and the salary offered can directly affect your EU Blue Card eligibility.
Once you have confirmed that you qualify, the EU Blue Card application usually follows a straightforward sequence, although the exact process depends on the country where you will work.
Also read: How to open US, UK and Euro bank accounts in Germany
The EU Blue Card offers more than permission to work, giving you options for family reunification, mobility across participating EU countries and eventually permanent residence.
Your EU Blue Card can make it easier to bring eligible family members to join you in your destination country. Spouses and dependent children may qualify for residence permits, with specific rights depending on national rules. In many cases, family members can also access employment without needing a separate work permit, helping your household settle more easily.
After legally living in an EU country with an EU Blue Card, you can gain greater mobility within participating EU countries. After 12 months of legal residence in your first member state, you may be able to move to another participating country for highly qualified employment, although you must apply for a new Blue Card under that country’s rules.
The EU Blue Card can also contribute towards long-term residence, although the timeline depends on your circumstances and national rules. Under EU rules, Blue Card holders can generally qualify for EU long-term resident status after five years of continuous legal residence, with periods spent in other participating EU countries potentially counting towards the requirement.
Once you start working in Germany, your salary will typically be paid into a German or European bank account in euros. If you regularly move money across borders, opening a euro account can give you a place to receive and hold your earnings before deciding when to convert or transfer them, rather than exchanging everything as soon as you are paid.
Grey can help you manage this money through a multi-currency account where you can receive and hold supported currencies, manage international payments and convert funds when needed. This means your euros can remain available while you decide whether to spend them, convert them or send them elsewhere.
When you are ready to move your money, you can use supported payment routes to send money from Germany or send money to India, depending on the currencies and transfer routes available to you. Whether you are supporting your family, paying expenses abroad or moving your own savings, keeping your money in the currency you receive can give you more control over when you transfer.
The EU Blue Card is a work and residence permit for highly qualified non-EU citizens who want to live and work in participating EU countries. It provides a legal route to employment for professionals who meet the required education, salary and job conditions in their chosen destination.
You may qualify as a non-EU professional with a recognised higher education qualification and a qualifying employment contract or binding job offer. In certain cases, particularly for IT professionals, relevant professional experience can replace a traditional degree, depending on the country’s rules.
Your salary must meet the threshold set by the country where you will work. Under EU rules, the threshold generally falls between 1.0 and 1.6 times the national average gross annual salary, with lower thresholds potentially applying to shortage occupations and other qualifying groups.
The EU Blue Card is available in 25 EU member states. Denmark and Ireland do not participate in the EU Blue Card scheme, so professionals planning to work there need to explore their separate national work and residence routes instead.
Yes. Your eligible family members can generally join you through family reunification procedures, and EU Blue Card rules provide favourable conditions for accompanying family members. Spouses may also have access to employment, although the exact application process and requirements depend on the country where you live.
Once you are working in Europe, you can send money home through your bank or an international payment platform such as Grey. Grey lets you receive and hold supported currencies in a multi-currency account, manage international payments and choose when to convert your money, giving you greater control over exchange rates and transfers.

The Thai baht is Thailand's currency, with its own symbol, code and notes. Grey gets you a fair rate on every transfer. Send money to Thailand today.
Olayoyin Olorunmota
•
October 10, 2026
•
2 min read
Recently, Thailand has become one of the most sought-after destinations for vacationers. Now, before you hop on that flight, you need to understand the country’s currency, which denominations are in circulation, and how to get a fair rate when you convert or send money, so you save time and money from the moment you land.
This guide covers everything you need to know about Thailand’s currency, the Thai baht: its symbol, currency code, history, denominations, and practical advice for travellers and anyone sending money to Thailand.
The currency of Thailand is the Thai baht, and it’s the only legal tender accepted across Thailand for everyday transactions, from street food and tuk-tuks to hotels and department stores. The baht has been Thailand’s official currency since the late 19th century and is issued and regulated by the Bank of Thailand.
The baht is a relatively stable emerging-market currency that trades on international foreign-exchange markets. It floats within a managed regime overseen by the Bank of Thailand, which intervenes periodically to limit volatility. For most travellers and remittance senders, the baht is freely exchangeable at banks, authorised money changers, hotels, and through online platforms.
Thailand’s economy is among the largest in Southeast Asia, and the baht reflects it. It is widely recognised, commonly held by foreign exchange desks around the world, and straightforward to convert from major currencies, including USD, EUR, GBP, and SGD.
The Thai baht uses the symbol ฿ and the ISO 4217 currency code THB. On price tags, menus, and payment receipts in Thailand, you will see the ฿ symbol placed before the amount: ฿500, ฿1,200. In international financial contexts and money transfer platforms, the code THB is used to identify the currency.
One baht is divided into 100 satang, which is the subunit of the baht. The word “satang” comes from the Sanskrit “śataṅga,” meaning “one hundredth.” In practical terms, satang coins are used but rarely noticed by visitors, as most purchases are priced in whole baht.
The Thai baht is issued in both banknotes and coins, covering a range of denominations suited to everyday transactions from small street purchases to larger payments.
All current banknotes feature the reigning monarch, King Vajiralongkorn (Rama X), on the front face. Earlier series featured King Bhumibol Adulyadej (Rama IX), who reigned until 2016. Older Rama IX notes remain legal tender and are still widely in circulation. You will encounter both in everyday transactions.
The ฿20 note is the most commonly used for small transactions. The ฿1,000 note is the largest denomination and is standard for paying at hotels, shops, and restaurants. The ฿500 is also widely accepted.
Street vendors and tuk-tuk drivers often cannot make change for a ฿1,000 note. Keeping a supply of ฿20, ฿50, and ฿100 notes makes small daily purchases easier, so always keep that in mind.
The ฿10 coin is the most prevalent in Thailand. It is bimetallic, with a gold-coloured outer ring and a silver-coloured centre, and is used across all types of transactions from vending machines to street markets. The ฿1, ฿2, and ฿5 coins are also common. Satang coins appear primarily in supermarket and pharmacy change.
Thailand is primarily a cash economy in many contexts, though card acceptance has expanded significantly in urban areas and tourist zones. Understanding when cash is essential and when cards work best helps you plan your spending and avoid unnecessary fees.
Street food and markets: Almost all food stalls, night markets, floating markets, and local vendors across Thailand operate on a cash-only basis. The famous Chatuchak Weekend Market in Bangkok, every night market from Chiang Mai to Phuket, and virtually all local restaurants expect baht in hand.
Tuk-tuks, songthaews (shared trucks), and motorbike taxis: While ride-hailing apps like Grab now offer card payment for cars, traditional transport remains cash-dependent.
Temples and tourist sites: Some accept cards, but many require cash for entry fees, donations, and purchases at site stalls.
Small guesthouses and bungalows: particularly on the islands and in rural areas, smaller accommodations often operate cash only or charge a fee for card payments.
Shopping malls, department stores, and major supermarkets (Central, The Mall, Big C, Lotus’s) accept Visa and Mastercard. Chain restaurants, international hotels, and larger tourist restaurants also take cards. Grab rides booked in-app, accept card payment.
ATMs in Thailand dispense baht directly from your foreign debit or virtual debit card. The exchange rate is typically close to the interbank rate, but Thai ATMs charge a fixed fee of 220 baht per withdrawal at most banks. This fee is charged by the Thai bank, not your home bank. If your home bank also charges an international ATM fee, withdrawing larger amounts less frequently reduces the total fee paid.
Currency exchange booths in Thailand, particularly authorised money changers rather than hotel desks, typically offer better rates than airport exchanges. SuperRich (orange and green) and Vasu Exchange are well-regarded in Bangkok. Airport exchange booths are convenient but tend to offer worse rates.
Using your card for direct purchases abroad triggers your card network’s exchange rate plus any foreign transaction fee charged by your card issuer. To understand how card exchange rates work before your trip, see our guide on how card exchange rates work. For practical steps to keep those costs down, our guide on avoiding foreign transaction fees covers the main options.
For travellers who earn in multiple currencies or want to hold baht and other currencies in one place, Grey lets you hold multiple currencies in a single account and convert at a transparent rate before you travel.
Carry small denominations. ฿20, ฿50, and ฿100 notes are used for most daily transactions. Having ฿1,000 notes is fine for hotels and shops, but annoying for markets and street food.
Keep coins. Thai coins accumulate quickly and are useful for small purchases, vending machines, and motorcycle taxi fares.
Don’t exchange money at the airport unless necessary. Rates at airport exchange counters are typically worse than in-city authorised money changers. Exchange a small amount at the airport for immediate needs (transport, first meal) and exchange the bulk once you’re in the city.
Decline dynamic currency conversion at ATMs and card terminals. When a Thai ATM or card payment machine offers to charge you in your home currency rather than baht, decline. This is called dynamic currency conversion, and the rate applied by the machine is almost always significantly worse than your card’s standard rate.
If you’re sending money to family, paying rent, covering business expenses, or supporting someone in Thailand from abroad, the method you use determines how much they receive.
The Thai baht is freely receivable at all major Thai banks, including Bangkok Bank, Kasikorn Bank (KBank), Siam Commercial Bank (SCB), Krung Thai Bank, and TMBThanachart Bank. International transfers arrive as THB after conversion, or as USD/EUR/GBP for foreign currency accounts held at Thai banks.
The main cost considerations when sending money to Thailand are the exchange rate applied on conversion and any transfer fees or correspondent bank charges. Traditional bank wire transfers to Thailand typically carry an outbound fee of $25 to $50 from the sending bank, plus a conversion spread of 2 to 4% above the mid-market rate at the receiving end. Correspondent bank fees can reduce the amount further in transit.
With Grey, you make transfers to Thailand for a flat fee of $1.80, regardless of the amount. Regular deposits via ACH, SEPA, or Faster Payments carry a 0.8% fee capped at $10. This is significantly cheaper than the combined cost of a bank wire plus a bank conversion spread on larger transfers.
To get started, send money to Thailand with Grey and see the current rate and total fee before committing to the transfer. For US-based senders specifically, our send money from the US to Thailand page covers the process in detail.
The currency of Thailand is the Thai baht, abbreviated THB and symbolised as ฿. It is the sole legal tender in Thailand and is issued and regulated by the Bank of Thailand. One baht divides into 100 satang. The baht is used for all transactions across the country, from small street food purchases to large hotel bills and business payments.
The Thai baht symbol is ฿. It is placed before the amount in Thai pricing conventions, for example, ฿100 or ฿1,500. In international financial contexts, the three-letter ISO code THB is used to identify the currency in exchange rates, bank transfers, and financial systems.
The currency code for the Thai baht is THB, as assigned under the ISO 4217 international currency standard. This code is used on money transfer platforms, bank statements, foreign exchange rate boards, and financial software to identify transactions denominated in Thai baht.
A satang is the subunit of the Thai baht. One baht equals 100 satang. Satang appear as coins in denominations of 25 satang and 50 satang, and are occasionally used in supermarket and pharmacy pricing. In most everyday Thai transactions, prices are rounded to the nearest whole baht, so satang coins are not frequently encountered in street markets or restaurants.
Both are useful, but cash remains essential in Thailand. Street food stalls, local markets, motorbike taxis, small guesthouses, and many tourist attractions operate on cash only. Cards are accepted reliably at shopping malls, chain supermarkets, international hotels, and larger restaurants. A practical approach is to carry baht cash for daily spending and markets, and use a card at larger establishments. Avoid dynamic currency conversion at ATMs and card terminals, and withdraw larger amounts to minimise the ฿220 per-transaction ATM fee that Thai banks charge.
To send money to Thailand, you need the recipient’s Thai bank name, account number, and the bank’s SWIFT code. Grey provides international transfers to Thailand for a flat fee of $1.80, with the rate shown before you confirm. Traditional bank wire transfers typically carry a $25 to $50 outbound fee plus a 2 to 4% conversion spread, making fintech transfers significantly cheaper for most amounts.



