<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/eu-blue-card-guide#article","headline":"EU Blue Card: How to qualify and apply","description":"See who qualifies for the EU Blue Card and how to apply. Degree and salary thresholds, plus the German route, explained. Start your application today.","inLanguage":"en","url":"https://grey.co/blog/eu-blue-card-guide","mainEntityOfPage":{"@id":"https://grey.co/blog/eu-blue-card-guide#webpage"},"datePublished":"2026-10-11T22:39:45.507Z","dateModified":"2026-10-11T22:48:11.420Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/eu-blue-card-guide#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6acc12099848d81d2d310bc1_EU%20Blue%20Card-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6acc12099848d81d2d310bc1_EU%20Blue%20Card-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/eu-blue-card-guide#webpage","url":"https://grey.co/blog/eu-blue-card-guide","name":"EU Blue Card: Who qualifies and how to apply | Grey","description":"See who qualifies for the EU Blue Card and how to apply. Degree and salary thresholds, plus the German route, explained. Start your application today.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/eu-blue-card-guide#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/eu-blue-card-guide#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/eu-blue-card-guide#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"EU Blue Card: How to qualify and apply","item":"https://grey.co/blog/eu-blue-card-guide"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/eu-blue-card-guide#faq","mainEntity":[{"@type":"Question","name":"What is the EU Blue Card?","acceptedAnswer":{"@type":"Answer","text":"The EU Blue Card is a work and residence permit for highly qualified non-EU citizens who want to live and work in participating EU countries. It provides a legal route to employment for professionals who meet the required education, salary and job conditions in their chosen destination."}},{"@type":"Question","name":"Who is eligible?","acceptedAnswer":{"@type":"Answer","text":"You may qualify as a non-EU professional with a recognised higher education qualification and a qualifying employment contract or binding job offer. In certain cases, particularly for IT professionals, relevant professional experience can replace a traditional degree, depending on the country’s rules."}},{"@type":"Question","name":"What salary do I need?","acceptedAnswer":{"@type":"Answer","text":"Your salary must meet the threshold set by the country where you will work. Under EU rules, the threshold generally falls between 1.0 and 1.6 times the national average gross annual salary, with lower thresholds potentially applying to shortage occupations and other qualifying groups."}},{"@type":"Question","name":"Which countries offer it?","acceptedAnswer":{"@type":"Answer","text":"The EU Blue Card is available in 25 EU member states. Denmark and Ireland do not participate in the EU Blue Card scheme, so professionals planning to work there need to explore their separate national work and residence routes instead."}},{"@type":"Question","name":"Can my family join me?","acceptedAnswer":{"@type":"Answer","text":"Yes. Your eligible family members can generally join you through family reunification procedures, and EU Blue Card rules provide favourable conditions for accompanying family members. Spouses may also have access to employment, although the exact application process and requirements depend on the country where you live."}},{"@type":"Question","name":"How do I send money?","acceptedAnswer":{"@type":"Answer","text":"Once you are working in Europe, you can send money home through your bank or an international payment platform such as Grey. Grey lets you receive and hold supported currencies in a multi-currency account, manage international payments and choose when to convert your money, giving you greater control over exchange rates and transfers."}}]}] </script>

EU Blue Card: How to qualify and apply

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Moving to Europe for work can feel complicated when you are trying to understand which visa, residence permit and eligibility requirements apply to you. The EU Blue Card offers a route for highly qualified non-EU nationals who have the skills and qualifications European employers need.

To qualify for an EU Blue Card, you generally need a recognised university degree or equivalent professional qualification, a qualifying employment contract or job offer, and a salary that meets the required threshold in the EU country where you plan to work. Requirements can vary between countries, so checking the rules for your destination matters before you apply.

The EU Blue Card combines the right to live and work in a participating EU country with a pathway to greater mobility within the EU. Understanding the eligibility criteria, salary requirements and application process can help you decide whether it is the right route for your move.

Also read: Expat living in Germany: Banking, visas and costs

What is the EU Blue Card?

The EU Blue Card is a work and residence permit for highly qualified non-EU nationals who have a qualifying job offer in a participating European Union country. It is designed to attract skilled professionals from outside the EU by giving them the right to live and work in the country where they are employed, provided they meet the required qualifications, salary and employment conditions.

The “highly qualified” requirement generally means you need higher education qualifications, such as a recognised university degree, or qualifying professional skills recognised under the rules of the country where you apply. You also need a binding job offer or employment contract that meets the required salary threshold. Because these thresholds and application requirements vary by country, your eligibility can depend on where you plan to work.

Most EU countries participate in the EU Blue Card scheme, including Germany, France, the Netherlands, Spain and Italy. Denmark and Ireland do not participate, so you need to consider the specific immigration route available in your chosen destination before applying.

Who qualifies for the EU Blue Card?

You may qualify for the EU Blue Card if you are a highly qualified non-EU national with a qualifying job offer in a participating EU country. You generally need higher professional qualifications, a work contract or binding job offer lasting at least six months, and a salary that meets your destination country’s threshold.

A university degree is the most common way to meet the qualification requirement, typically through a recognised higher education programme of at least three years. However, some countries also recognise relevant professional experience as an alternative, particularly for certain occupations such as IT. Your job must also match the qualifications or professional skills you are using to qualify for the card.

There is no single euro salary figure for the whole EU. Under the current rules, each participating country sets its own threshold, generally between 1 and 1.6 times its average gross annual salary. For example, Germany’s 2026 threshold is €50,700, with a lower €45,934.20 threshold for shortage occupations and certain recent graduates.

The Blue Card in Germany

Germany is the largest issuer of EU Blue Cards in Europe, making it an important destination for highly qualified professionals looking to work in the EU. In 2024, Germany issued 56,252 Blue Cards, representing 72% of all cards issued across the EU.

For 2026, the standard salary threshold in Germany is €50,700 gross per year. A lower threshold of €45,934.20 applies to shortage occupations, provided the Federal Employment Agency approves the employment. Recent graduates can also qualify at the lower threshold, while certain IT specialists may qualify without a university degree if they have the required professional experience.

Germany’s shortage occupations include academic STEM professionals, doctors, veterinarians, dentists, pharmacists, nurses and midwives, teachers and educators, as well as certain managers in manufacturing, logistics, ICT and professional services. This means that when searching for German companies that sponsor work visas, your occupation and the salary offered can directly affect your EU Blue Card eligibility.

How to apply for the EU Blue Card step by step

Once you have confirmed that you qualify, the EU Blue Card application usually follows a straightforward sequence, although the exact process depends on the country where you will work.

  1. Secure a qualifying job: Get a signed employment contract or binding job offer that meets the required salary threshold and runs for at least six months.
  2. Prepare your documents: Gather your valid passport, employment contract, CV, degree certificates, proof of qualifications and health insurance. Your destination country may require foreign documents to be translated, legalised or accompanied by a statement of comparability.
  3. Apply for the required visa: If you need an entry visa, submit your application through the relevant embassy or consulate in your country of residence, including your supporting documents and biometrics.
  4. Enter your destination country: Once your visa is approved, travel to the country where you will work and complete any required address registration or other local formalities.
  5. Apply for your Blue Card: Depending on the country and your circumstances, you may apply before travelling or after arrival. The immigration authority reviews your application and, once approved, issues your biometric EU Blue Card residence permit.

Also read: How to open US, UK and Euro bank accounts in Germany

EU Blue Card benefits and path to permanent residence

The EU Blue Card offers more than permission to work, giving you options for family reunification, mobility across participating EU countries and eventually permanent residence.

Family reunification

Your EU Blue Card can make it easier to bring eligible family members to join you in your destination country. Spouses and dependent children may qualify for residence permits, with specific rights depending on national rules. In many cases, family members can also access employment without needing a separate work permit, helping your household settle more easily.

EU mobility

After legally living in an EU country with an EU Blue Card, you can gain greater mobility within participating EU countries. After 12 months of legal residence in your first member state, you may be able to move to another participating country for highly qualified employment, although you must apply for a new Blue Card under that country’s rules.

Path to permanent residence

The EU Blue Card can also contribute towards long-term residence, although the timeline depends on your circumstances and national rules. Under EU rules, Blue Card holders can generally qualify for EU long-term resident status after five years of continuous legal residence, with periods spent in other participating EU countries potentially counting towards the requirement.

Getting paid in euros and sending money home

Once you start working in Germany, your salary will typically be paid into a German or European bank account in euros. If you regularly move money across borders, opening a euro account can give you a place to receive and hold your earnings before deciding when to convert or transfer them, rather than exchanging everything as soon as you are paid.

Grey can help you manage this money through a multi-currency account where you can receive and hold supported currencies, manage international payments and convert funds when needed. This means your euros can remain available while you decide whether to spend them, convert them or send them elsewhere.

When you are ready to move your money, you can use supported payment routes to send money from Germany or send money to India, depending on the currencies and transfer routes available to you. Whether you are supporting your family, paying expenses abroad or moving your own savings, keeping your money in the currency you receive can give you more control over when you transfer.

Frequently asked questions

What is the EU Blue Card?

The EU Blue Card is a work and residence permit for highly qualified non-EU citizens who want to live and work in participating EU countries. It provides a legal route to employment for professionals who meet the required education, salary and job conditions in their chosen destination.

Who is eligible?

You may qualify as a non-EU professional with a recognised higher education qualification and a qualifying employment contract or binding job offer. In certain cases, particularly for IT professionals, relevant professional experience can replace a traditional degree, depending on the country’s rules.

What salary do I need?

Your salary must meet the threshold set by the country where you will work. Under EU rules, the threshold generally falls between 1.0 and 1.6 times the national average gross annual salary, with lower thresholds potentially applying to shortage occupations and other qualifying groups.

Which countries offer it?

The EU Blue Card is available in 25 EU member states. Denmark and Ireland do not participate in the EU Blue Card scheme, so professionals planning to work there need to explore their separate national work and residence routes instead.

Can my family join me?

Yes. Your eligible family members can generally join you through family reunification procedures, and EU Blue Card rules provide favourable conditions for accompanying family members. Spouses may also have access to employment, although the exact application process and requirements depend on the country where you live.

How do I send money?

Once you are working in Europe, you can send money home through your bank or an international payment platform such as Grey. Grey lets you receive and hold supported currencies in a multi-currency account, manage international payments and choose when to convert your money, giving you greater control over exchange rates and transfers.

Last updated:

October 12, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Portugal D7 visa: How to apply for the passive income visa

•

•

2 min read

Portugal has become an attractive option for people who want to build a life in Europe without relying on a local job offer. For retirees, property owners and others with regular passive income, the Portugal D7 visa offers a way to apply for residency while continuing to support yourself from income earned outside the country.

The Portugal D7 visa is a residency route for non-EU nationals with a stable passive income, such as pensions, rental income or dividends. You must show income at least equal to the Portuguese minimum wage, plus proof of accommodation.

But having enough income is only one part of the application. You also need to understand the documentation, accommodation requirements, application process and what happens after your visa is approved. If you are considering Portugal as your next home, knowing what the D7 visa requires before you apply can help you avoid delays, prepare the right documents and decide whether this residency route fits your circumstances.

Also read: Portugal transfer limits from US banks: Rules explained

What is the D7 visa?

The Portugal D7 visa is a residency visa for non-EU nationals with stable passive income who want to live in Portugal.

Who Can Apply?

The D7 visa is designed for non-EU nationals who can support themselves through regular passive income. Applicants must demonstrate sufficient financial means and provide accommodation evidence, making it suitable for people planning to relocate rather than simply visit Portugal.

Retirees

Retirees are among the most common D7 applicants because pensions can qualify as passive income. Someone receiving a regular pension from another country may use that income to demonstrate financial stability while moving to Portugal for retirement.

Remote-Income Earners

The D7 can also appeal to people earning a regular income from sources outside Portugal. This may include rental properties, investments or other recurring income streams. However, remote workers whose income comes from active employment or freelancing should check whether another Portuguese visa is more appropriate.

The Passive-Income Requirement

The D7 is based on demonstrating reliable financial resources rather than securing a Portuguese job. Applicants generally need to show recurring income, such as pensions, rental income or dividends, alongside sufficient savings to support their stay and meet the visa requirements.

What are the D7 visa requirements for Portugal?

Understanding the Portugal D7 visa requirements gives you a clearer picture of what to prepare before submitting your application, from proving your finances to securing accommodation and meeting the health and character requirements.

  • Income: Financial stability is central to the D7 application. You need to demonstrate sufficient regular income or financial resources to support your life in Portugal. For 2026, Portugal’s minimum wage is €920 per month, giving a €11,040 annual reference amount for a single applicant.
  • Accommodation: Before applying, arrange a suitable place to live in Portugal. This could be a rental property or a home you own. Your documents should provide evidence of your intended address and show that you have somewhere to live during your stay.
  • Health insurance: Appropriate health insurance is another part of the application. Your policy should cover necessary medical expenses, including urgent treatment and potential repatriation. Once you become a resident, different healthcare requirements may apply depending on your circumstances.
  • Clean record: Your application also needs to demonstrate good character. This usually means providing a criminal record certificate from your country of nationality or the relevant country of residence, with the required authentication. Portuguese authorities will also check your Portuguese criminal record.

For highly qualified professionals moving to Portugal for work, the EU Blue Card route provides another residency option. The route is designed for skilled workers with an eligible employment offer and comes with specific requirements

Also read: Real budgeting tips for nomads living in Lisbon

How to apply for the Portugal D7 visa

If you are applying for the Portugal D7 visa, following the process in the right order helps you prepare your documents, avoid unnecessary delays and know what to expect at each stage.

1. Gather your documents

Start by preparing proof of income or financial resources, accommodation in Portugal, valid health insurance, a criminal record certificate, your passport and any other supporting documents required. You may also need to have certain documents authenticated or translated before submitting your application.

2. Submit your visa application

Next, submit your D7 visa application through the Portuguese consulate or visa application centre responsible for your country of residence. You will provide your documents, complete the application process and attend an appointment or interview if requested.

3. Travel to Portugal

Once your residence visa is approved, you can travel to Portugal within the validity period shown on your visa. This gives you permission to enter Portugal and complete the next stage of your residency application.

4. Apply for your residence permit

After arriving in Portugal, you will attend your appointment with AIMA and submit the documents required for your residence permit. Once your application is approved, you will receive your Portuguese residence card, allowing you to live in Portugal legally.

Residency, taxes and the path to citizenship

Once you have your D7 residence permit, the focus shifts from getting approved to maintaining your residency and planning for the years ahead. That means understanding renewal dates, how much time you need to spend in Portugal, the route to citizenship and how becoming a tax resident could affect your income.

Renewal timeline

Your D7 journey begins with a two-year residence card, followed by a three-year renewal, provided you continue meeting the residency requirements and maintaining your ties to Portugal. You should also plan around the minimum-stay requirement, especially if you work remotely or are registering as self-employed abroad while living in Portugal.

Minimum stay

A D7 residence permit is intended for people who genuinely live in Portugal, so your travel plans matter. You generally need to spend at least six consecutive months or eight non-consecutive months in Portugal each year. If your work takes you abroad frequently, factor these limits into your plans before choosing this residency route.

Citizenship route

After five years of legal residency, D7 holders may become eligible to apply for Portuguese citizenship, subject to the applicable requirements, including an A2-level Portuguese language test. For someone building a long-term life in Portugal, this can turn the D7 from a temporary relocation decision into a potential pathway towards permanent belonging.

How moving to Portugal can affect your tax residency

Getting a D7 residence permit does not automatically mean every tax obligation is the same; your tax residency depends on your circumstances and time spent in Portugal.

Portugal generally considers factors such as spending more than 183 days in the country or having a home there that indicate an intention to maintain it as your habitual residence. Once you become a tax resident, Portuguese IRS rules can apply to your income, including foreign-source income, subject to applicable exemptions, credits and tax treaties.

Proving income and moving money when preparing for life in Portugal

As you prepare your Portugal D7 Visa application, Grey can help you manage the money side of your move. Its multi-currency account lets you hold and manage different currencies, while giving you access to a euro account for receiving, holding and spending euros once you start settling into Portugal.

You will still need to prove that you have stable funds or a regular income to support yourself. Your bank statements and financial documents should clearly show where your money comes from and that you can cover your living costs. Having a euro account can also make everyday payments in Portugal more straightforward.

Whether you are moving money from the UK to Portugal or the US to Portugal, Grey gives you a way to move funds across currencies without having to juggle multiple accounts. You can convert your money to euros when needed and use your euro balance for expenses such as rent, bills and everyday spending.

Frequently asked questions about Portugal D7 visa

What is the D7 visa?

The D7 visa is a Portuguese residence visa for non-EU citizens who have a stable income or sufficient financial resources. It is commonly associated with passive income, including pensions, investments and rental income, and allows eligible applicants to live in Portugal with their families.

How much income do I need?

The minimum income requirement is linked to Portugal’s minimum wage and currently starts at €920 per month for the main applicant. You need additional funds for dependents. You should also be prepared to demonstrate that your income or savings can support your planned life in Portugal.

Can I work on a D7?

Yes. Although your initial D7 application is based on demonstrating sufficient income or financial resources, holding Portuguese residency allows you to work legally in Portugal. This means you can take up employment, become self-employed or develop a business after your residency has been granted.

How long does it take?

The initial D7 visa process can take around 60 days once your application is submitted, although processing times vary by consulate and individual circumstances. After receiving the visa, you travel to Portugal and complete the required steps to obtain your residence permit.

Does it lead to citizenship?

The D7 can provide a route towards Portuguese citizenship. Under the rules applicable to your application, you may become eligible after meeting the required period of legal residence and other conditions, including Portuguese language requirements. Check the current nationality rules before relying on a specific timeline.

How do I move money to Portugal?

You can transfer money internationally into your Portuguese bank account to support your move and everyday expenses. Grey can also help you move money across currencies, including transfers from the UK or US to Portugal, while its multi-currency account gives you access to a euro balance.
EU Blue Card: How to qualify and apply

•

•

2 min read

Moving to Europe for work can feel complicated when you are trying to understand which visa, residence permit and eligibility requirements apply to you. The EU Blue Card offers a route for highly qualified non-EU nationals who have the skills and qualifications European employers need.

To qualify for an EU Blue Card, you generally need a recognised university degree or equivalent professional qualification, a qualifying employment contract or job offer, and a salary that meets the required threshold in the EU country where you plan to work. Requirements can vary between countries, so checking the rules for your destination matters before you apply.

The EU Blue Card combines the right to live and work in a participating EU country with a pathway to greater mobility within the EU. Understanding the eligibility criteria, salary requirements and application process can help you decide whether it is the right route for your move.

Also read: Expat living in Germany: Banking, visas and costs

What is the EU Blue Card?

The EU Blue Card is a work and residence permit for highly qualified non-EU nationals who have a qualifying job offer in a participating European Union country. It is designed to attract skilled professionals from outside the EU by giving them the right to live and work in the country where they are employed, provided they meet the required qualifications, salary and employment conditions.

The “highly qualified” requirement generally means you need higher education qualifications, such as a recognised university degree, or qualifying professional skills recognised under the rules of the country where you apply. You also need a binding job offer or employment contract that meets the required salary threshold. Because these thresholds and application requirements vary by country, your eligibility can depend on where you plan to work.

Most EU countries participate in the EU Blue Card scheme, including Germany, France, the Netherlands, Spain and Italy. Denmark and Ireland do not participate, so you need to consider the specific immigration route available in your chosen destination before applying.

Who qualifies for the EU Blue Card?

You may qualify for the EU Blue Card if you are a highly qualified non-EU national with a qualifying job offer in a participating EU country. You generally need higher professional qualifications, a work contract or binding job offer lasting at least six months, and a salary that meets your destination country’s threshold.

A university degree is the most common way to meet the qualification requirement, typically through a recognised higher education programme of at least three years. However, some countries also recognise relevant professional experience as an alternative, particularly for certain occupations such as IT. Your job must also match the qualifications or professional skills you are using to qualify for the card.

There is no single euro salary figure for the whole EU. Under the current rules, each participating country sets its own threshold, generally between 1 and 1.6 times its average gross annual salary. For example, Germany’s 2026 threshold is €50,700, with a lower €45,934.20 threshold for shortage occupations and certain recent graduates.

The Blue Card in Germany

Germany is the largest issuer of EU Blue Cards in Europe, making it an important destination for highly qualified professionals looking to work in the EU. In 2024, Germany issued 56,252 Blue Cards, representing 72% of all cards issued across the EU.

For 2026, the standard salary threshold in Germany is €50,700 gross per year. A lower threshold of €45,934.20 applies to shortage occupations, provided the Federal Employment Agency approves the employment. Recent graduates can also qualify at the lower threshold, while certain IT specialists may qualify without a university degree if they have the required professional experience.

Germany’s shortage occupations include academic STEM professionals, doctors, veterinarians, dentists, pharmacists, nurses and midwives, teachers and educators, as well as certain managers in manufacturing, logistics, ICT and professional services. This means that when searching for German companies that sponsor work visas, your occupation and the salary offered can directly affect your EU Blue Card eligibility.

How to apply for the EU Blue Card step by step

Once you have confirmed that you qualify, the EU Blue Card application usually follows a straightforward sequence, although the exact process depends on the country where you will work.

  1. Secure a qualifying job: Get a signed employment contract or binding job offer that meets the required salary threshold and runs for at least six months.
  2. Prepare your documents: Gather your valid passport, employment contract, CV, degree certificates, proof of qualifications and health insurance. Your destination country may require foreign documents to be translated, legalised or accompanied by a statement of comparability.
  3. Apply for the required visa: If you need an entry visa, submit your application through the relevant embassy or consulate in your country of residence, including your supporting documents and biometrics.
  4. Enter your destination country: Once your visa is approved, travel to the country where you will work and complete any required address registration or other local formalities.
  5. Apply for your Blue Card: Depending on the country and your circumstances, you may apply before travelling or after arrival. The immigration authority reviews your application and, once approved, issues your biometric EU Blue Card residence permit.

Also read: How to open US, UK and Euro bank accounts in Germany

EU Blue Card benefits and path to permanent residence

The EU Blue Card offers more than permission to work, giving you options for family reunification, mobility across participating EU countries and eventually permanent residence.

Family reunification

Your EU Blue Card can make it easier to bring eligible family members to join you in your destination country. Spouses and dependent children may qualify for residence permits, with specific rights depending on national rules. In many cases, family members can also access employment without needing a separate work permit, helping your household settle more easily.

EU mobility

After legally living in an EU country with an EU Blue Card, you can gain greater mobility within participating EU countries. After 12 months of legal residence in your first member state, you may be able to move to another participating country for highly qualified employment, although you must apply for a new Blue Card under that country’s rules.

Path to permanent residence

The EU Blue Card can also contribute towards long-term residence, although the timeline depends on your circumstances and national rules. Under EU rules, Blue Card holders can generally qualify for EU long-term resident status after five years of continuous legal residence, with periods spent in other participating EU countries potentially counting towards the requirement.

Getting paid in euros and sending money home

Once you start working in Germany, your salary will typically be paid into a German or European bank account in euros. If you regularly move money across borders, opening a euro account can give you a place to receive and hold your earnings before deciding when to convert or transfer them, rather than exchanging everything as soon as you are paid.

Grey can help you manage this money through a multi-currency account where you can receive and hold supported currencies, manage international payments and convert funds when needed. This means your euros can remain available while you decide whether to spend them, convert them or send them elsewhere.

When you are ready to move your money, you can use supported payment routes to send money from Germany or send money to India, depending on the currencies and transfer routes available to you. Whether you are supporting your family, paying expenses abroad or moving your own savings, keeping your money in the currency you receive can give you more control over when you transfer.

Frequently asked questions

What is the EU Blue Card?

The EU Blue Card is a work and residence permit for highly qualified non-EU citizens who want to live and work in participating EU countries. It provides a legal route to employment for professionals who meet the required education, salary and job conditions in their chosen destination.

Who is eligible?

You may qualify as a non-EU professional with a recognised higher education qualification and a qualifying employment contract or binding job offer. In certain cases, particularly for IT professionals, relevant professional experience can replace a traditional degree, depending on the country’s rules.

What salary do I need?

Your salary must meet the threshold set by the country where you will work. Under EU rules, the threshold generally falls between 1.0 and 1.6 times the national average gross annual salary, with lower thresholds potentially applying to shortage occupations and other qualifying groups.

Which countries offer it?

The EU Blue Card is available in 25 EU member states. Denmark and Ireland do not participate in the EU Blue Card scheme, so professionals planning to work there need to explore their separate national work and residence routes instead.

Can my family join me?

Yes. Your eligible family members can generally join you through family reunification procedures, and EU Blue Card rules provide favourable conditions for accompanying family members. Spouses may also have access to employment, although the exact application process and requirements depend on the country where you live.

How do I send money?

Once you are working in Europe, you can send money home through your bank or an international payment platform such as Grey. Grey lets you receive and hold supported currencies in a multi-currency account, manage international payments and choose when to convert your money, giving you greater control over exchange rates and transfers.

Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

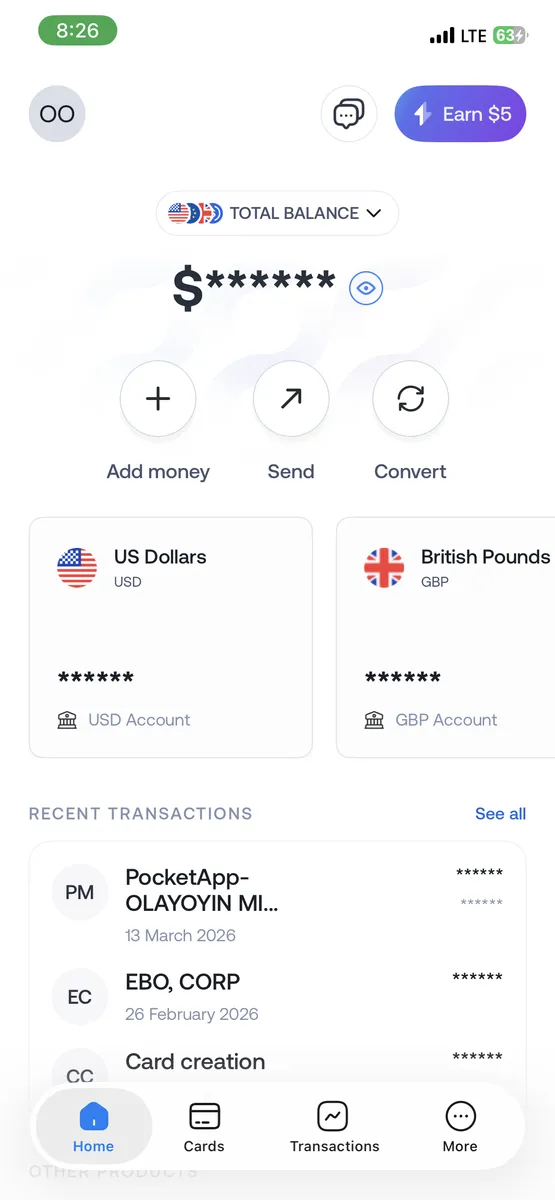
  1. Log in to your Grey account.
    ‍
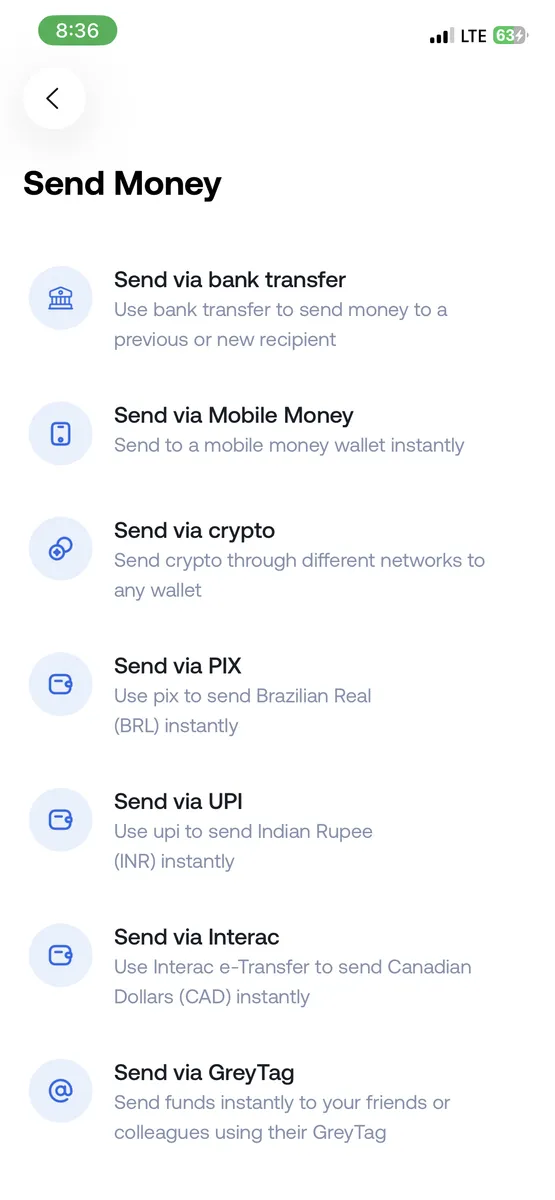
  2. Click “Send”.
Send Canadian dollars with Grey

‍

2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

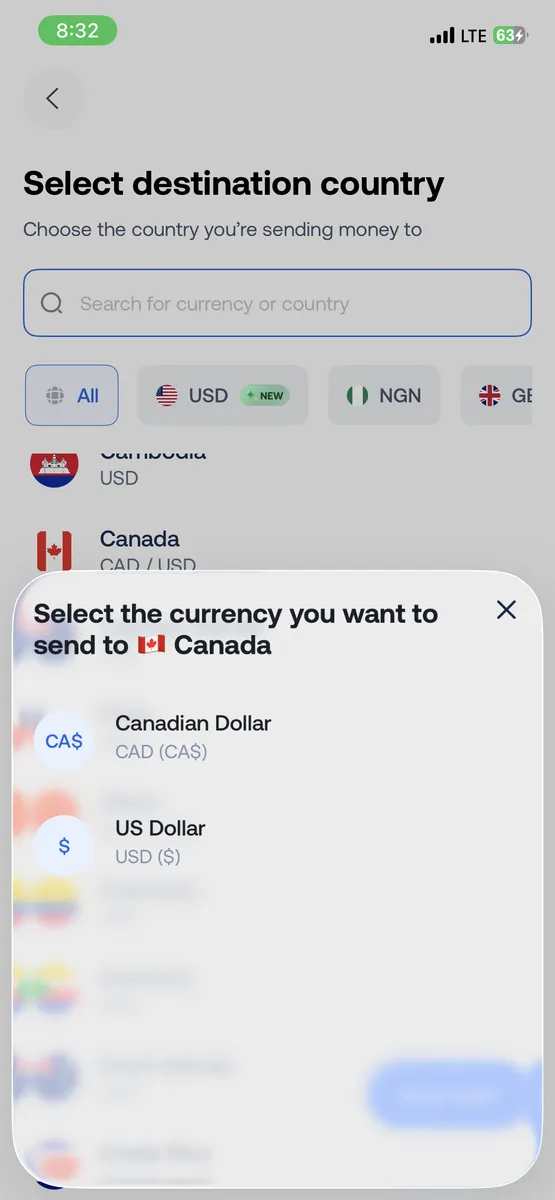
3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

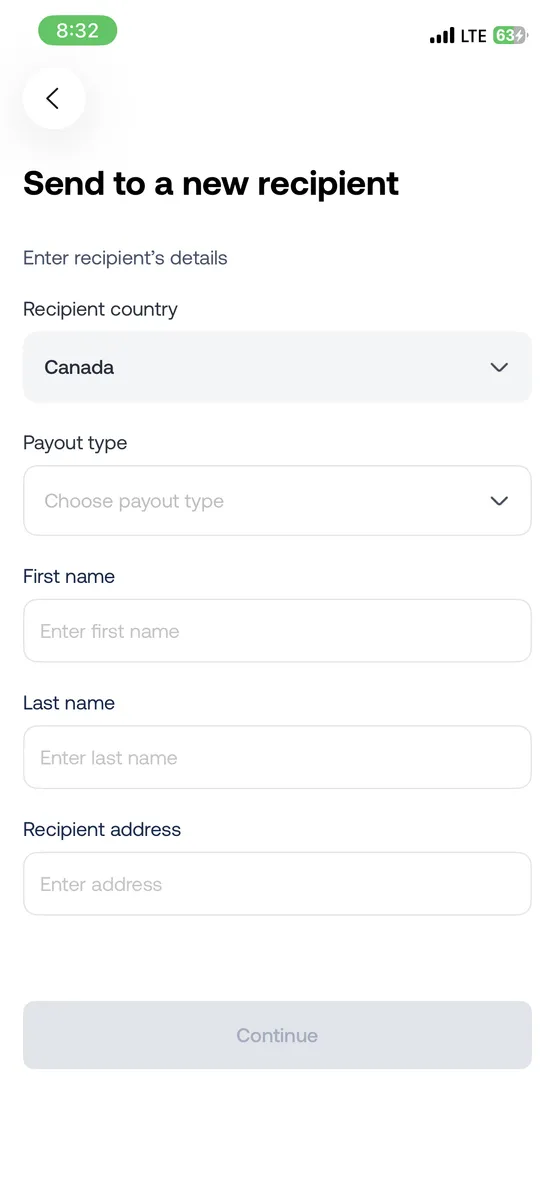
4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

How to shop in the US or Europe with your Grey card

•

•

2 min read

A few months ago, I was eyeing a pair of sneakers on a US website for weeks. Then the store started running sales and I decided to buy them (hashtag #YOLO), but my bank card declined the payment.

Not once, not twice… but four times!.

The same card that worked perfectly in Nigeria where I live, and the same details I’d used for years. I tried to get another card, but by then, sales had ended, and the sneakers were out of stock. It was annoying, but I just had to accept my L.

If you’ve ever tried to shop internationally, on sites like ASOS UK, Amazon US, Zara EU, or even the Apple Store, you may already be familiar with this pain. Sometimes the website rejects your card. Sometimes your bank blocks the transaction. Sometimes the currency conversion takes too long, and the payment times out.

It shouldn’t be this difficult to buy something online in big 2026… yet for many people, it still is.

But if you use a Grey card, you'll eliminate the uncertainty of thoughts like, “Will this payment go through?”, and transform your international shopping into a simple and predictable process.

Why shopping abroad is often frustrating

Shopping from US or European stores usually comes with these hurdles:

1. Many foreign merchants decline local cards

Some US/UK online stores automatically reject certain African-issued cards, even if you have more than enough balance.

2. Stores bill strictly in USD, GBP, or EUR

If your card requires manual currency conversion, it can cause payment delays that may result in declines.

3. Banks block “suspicious” international transactions

This usually happens when the merchant is unfamiliar.

4. Conversion errors and hidden fees

Some cards convert long after the purchase, leading to surprises on your statement.

These problems are common, but they’re also exactly what Grey card is built to avoid.

How your Grey card makes shopping internationally easy

Smart spending across multiple currencies and USDC

Your Grey card doesn’t require you to pick or switch wallets before paying. Instead, it automatically spends from your balances. Your USD account is debited first; if that’s empty, your USDC, and then the highest of your remaining balances.

This means your payment goes through as long as you have funds available in your account, without requiring you to consider currencies at checkout.

Works across major US and European stores

Your Grey card is an international spend card, so you can pay at 150 million merchants worldwide.

Use Apple Pay and Google Pay

For stores that support mobile wallets, you can simply add your Grey Visa card to Apple Pay or Google Pay. This is more secure and makes for much faster checkouts.

Create multiple cards for better organisation

If you shop frequently or mix personal and business purchases, you can:

  • Use one card for personal shopping
  • another for business imports
  • another for gift purchases

It keeps your spending clean and easy to track.

Freeze and unfreeze anytime

You can always freeze your cards to control your spending.

Better protection for online transactions

You receive real-time notifications, card controls, and instant limits - everything you need for peace of mind when buying from foreign sites.

LDMAG1

How to shop in the US or Europe with your Grey card

1. Request your Grey visa card

Create a Grey account and go to the cards section of your Grey app to request a Grey card for $5.

2. Add your card to the store’s checkout

Enter your card details or simply pay through Apple Pay/Google Pay.

3. Make your purchase normally

Shipping, duties, and taxes will be displayed as they are for every other international shopper.

4. Track everything in your Grey app

Every charge, refund, or verification appears instantly, so there are no surprises later.

Tips for smarter international shopping

  • Use a separate card for business or bulk purchases so you can easily track expenses.
  • Keep a bit extra in your wallet for shipping fees and taxes.
  • Use Apple Pay/Google Pay when available. It’s the most seamless way to tap and pay, and also supports contactless payments.

Shopping abroad doesn’t have to be stressful

Your Grey card helps you shop with confidence. There are no random declines or conversion drama. Ahead of your next international purchase, you can create your Grey card and enjoy a smoother, more predictable shopping experience.

‍

How to budget in foreign currencies using the Grey card

•

•

2 min read

Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.

Then remote work happened.

Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you also need structure because, without proper structure, even the most careful spender can lose track of where their money is going.

Your Grey card is a practical budgeting tool for people who live, work, earn, and spend across borders. I’ll explain.

Why budgeting in multiple currencies breaks down so easily

Many people who overspend don't do so because they’re irresponsible. But because their money isn’t organised in a way that reflects how they live.

It’s pretty common to be juggling subscriptions in USD, running ads in EUR, buying coffee in GBP, and somehow all on the same card. Eventually, everything blurs together. You can no longer track your Netflix renewal, that Facebook ad campaign, the flight you booked last week, or the coworking space membership. Then one day you check your balance and think, “Where did all that money go?” You know you spent it. You just can’t figure out where, or why, it felt like so much more than you expected.

It’s not that you’re careless. It’s that your money isn’t organised in a way that matches how you actually live and work. And once things start blurring, it’s nearly impossible to untangle without spending an hour combing through statements, converting currencies in your head, and still not feeling certain you’ve caught everything.

At that point, your budget is broken.

Also read: How to use your Grey card to manage all your subscriptions

What should budgeting look like when you earn and spend globally?

Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:

  • See exactly what each type of spending is costing you.
  • Stop or pause spending instantly when needed.
  • Protect one part of your budget from another.
  • Make changes without disrupting everything else.

The Grey card is designed around solving these exact needs.

How does the Grey card help with budgeting?

Use multiple cards to separate your spending

One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes. Your Grey virtual card helps you structure your spending as such.

For example, you can create:

  • One card for subscriptions and recurring tools
  • One card for ads and growth experiments
  • One card for travel or everyday spending
  • One card per client or project

Each card acts like its own budget lane, pulling from the same balance. You don’t need to guess where the money went because you already know.

This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.

Also read: How to pay for ads easily with your Grey card

Freeze cards instantly when spending goes off-track

Budgets fail when you can’t act fast enough.

With the Grey card, you can instantly freeze or unfreeze any card in the app. If a digital ad campaign starts burning through too cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.

Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.

Set limits that protect your budget

Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.

You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.

For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.

Track spending clearly in one place

When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.

When budgeting time comes around, you’re not sitting there trying to remember what that mysterious €47 charge was three weeks ago or why your USD balance dropped. Everything’s already categorised. The structure did the work for you.

Spend confidently across borders

Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.

A quick note on protection when spending abroad

An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.

When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.

It’s one less thing to worry about while managing money across borders.

Also read: How to claim your Visa card benefits

What budgeting in foreign currencies is like with the Grey card

When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency your spend is coming from and more importantly, when something changes.

Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.

If you’re ready to make your budget work wherever you are, create or update your Grey card today and start spending and budgeting in the ways that matter to you.

‍

How to pay online and in stores worldwide with your phone

•

•

2 min read

I was halfway through buying coffee in Lisbon when I patted my pockets looking for my wallet and realised I’d left it in my hotel room. I wasn’t moved in the slightest. A worthy, some would even argue, better alternative — my phone — was already hovering over the card reader to complete the payment.

That was a moment of realisation of how much things had changed. A few years ago, travelling required carrying multiple cards, worrying about foreign transaction fees, and hoping the ATM wouldn’t “swallow” my card in some random city. Now I pay for nearly everything with my phone. Subscriptions, flights, groceries in foreign countries, late-night takeaway orders, anything in fact.

How does it work?

How paying with your phone actually works

When I first started using mobile payments, I assumed my phone was doing something complicated and vaguely magical. In a way, I was right.

Your phone can store your card details securely in a digital wallet. Apple Pay if you’re on iPhone, Google Pay on Android, or other regional options, depending on where you are. When you pay, your phone communicates with the payment terminal via NFC (Near Field Communication), the same technology that powers contactless cards.

You authenticate the payment using Face ID, fingerprint, or a passcode, and the transaction goes through. The money comes out of whichever card or account is linked to that digital wallet. From the merchant’s perspective, it looks like a normal card payment. From your perspective, it’s faster and more convenient than fumbling for a physical card.

Online payments work similarly. When checking out, you can use Apple Pay or Google Pay instead of typing in card details. Your phone authenticates using biometrics, and the payment processes are instant. No manually entering sixteen-digit card numbers, expiry dates, or security codes.

The convenience is brilliant. But convenience doesn’t mean cost-free.

Also read: How to budget in foreign currencies using the Grey card

Paying online from anywhere in the world

I spend a lot of money online, honestly, probably more than I should, and most of it involves foreign currencies. Subscriptions to US software services. European design tools. UK-based platforms. Occasionally, buying something from an online shop halfway across the world because it’s not available locally.

For years, I paid for everything with a local bank card and didn’t think twice about it. Every transaction went through, so I assumed it was working fine. Then I started looking at my statements more carefully and realised how much I was losing.

When you pay for something online in a foreign currency using a regular bank card, three things usually happen. Your bank converts the currency at its exchange rate, which is almost always 2 - 4% worse than the real mid-market rate. They might charge a foreign transaction fee, sometimes 2 - 3% of the purchase. And if the merchant offers to convert the currency for you at checkout (something called dynamic currency conversion), that’s usually even worse.

On a $100 subscription, you might lose $5 - $7 just to fees and poor conversion rates. Multiply that across every international payment you make in a year, and it adds up fast. I calculated mine once, it was over $600 annually. Six hundred quid, gone, for no reason other than using the wrong card.

Also read: How to use your Grey card to manage all your subscriptions

Paying in physical stores globally

Paying with your phone in physical stores works the same way contactless cards do, just more conveniently. You tap your phone on the terminal, authenticate, and the payment goes through. It’s particularly useful when travelling because you don't have to worry about carrying the right physical cards or whether a shop accepts your card network.

I’ve paid for coffee in Berlin, groceries in Dubai, transport in Tokyo and dinners in Cape Town, all with my phone. It’s seamless, and merchants barely look up because contactless payments are standard nearly everywhere now.

But again, the ease of payment doesn’t mean you’re paying efficiently. Every time I tapped my phone abroad using my regular bank card, I was getting hit with foreign transaction fees and terrible exchange rates. The transaction felt instant and painless, but my bank was quietly taking 4 - 5% every time.

The worst part is you don't see it happening. The payment just says "approved." You don't get a breakdown of fees or exchange rate markups. You only notice when you check your statement later and realise that €50 dinner somehow cost you £47 instead of £43.

LDMAG1

Why your card setup matters

If you link a regular bank card with high foreign transaction fees and poor exchange rates, your mobile payments will still cost you money. The phone is just the interface. The financial infrastructure behind it, meaning the card, the account and the currency handling, is what actually matters.

I realised this after a trip to France. I’d paid for everything with my phone, felt very modern and efficient, then checked my statement and saw I’d lost nearly £80 to conversion fees and markups over one week. My phone wasn’t the problem. My card was.

That’s when I started looking for a better setup, something designed for people who regularly spend money internationally and don’t want to lose a percentage of every transaction to avoidable fees.

Also read: How tax-free shopping works for international travellers

How Grey makes global phone payments easier

Apple Pay and Google Pay are brilliant. They make payments faster and more secure. But they don’t solve the underlying problem of whether you’re paying efficiently or expensively.

Grey changed how I think about paying with my phone because it solved the card problem, not just the payment method.

When you open a Grey account, you get USD, GBP and EUR multi-currency accounts.

The Grey card connects directly to these accounts.

What really impressed me was the control. Grey lets you create multiple cards. I've got one for subscriptions, one for travel, and one for general spending. If a card is compromised or I'm worried about a particular merchant, I can instantly freeze it in the app and create a new one in seconds. I can set spending limits, track exactly where my money is going, and budget more intelligently by separating spending categories across different cards.

For someone who earns in multiple currencies or regularly spends internationally, this setup makes a material difference. I’m not losing money every time I tap my phone. I’m spending efficiently, with full visibility and control.

The right card changes everything

I love paying with my phone. It’s faster, more secure, and more convenient than carrying a wallet full of cards.

But payments are only as good as the card linked to them. If you’re paying with your phone but using a card with high fees and poor exchange rates, you’re still losing money on every transaction. The tap is convenient, but the cost is hidden.

The right card makes mobile payments genuinely efficient, not just convenient. That’s the difference between losing hundreds annually to avoidable fees and keeping the money you earn.

Get it right by opening a free Grey account today and getting the card that works globally and transparently.

‍

Arrow (up)

Back to top