<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria#article","headline":"How to receive and convert foreign currencies to USDC in Bulgaria","description":"Discover how freelancers in Bulgaria can receive foreign payments and convert them to USDC easily with Grey.","inLanguage":"en","url":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria","mainEntityOfPage":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria#webpage"},"datePublished":"2024-11-29T13:00:29.105Z","dateModified":"2026-06-15T17:43:31.816Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301860d61be9a66a752919_6a30185fd96c1362f2e67779_how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301860d61be9a66a752919_6a30185fd96c1362f2e67779_how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria#webpage","url":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria","name":"How to receive and convert foreign currencies to USDC in Bulgaria","description":"Discover how freelancers in Bulgaria can receive foreign payments and convert them to USDC easily with Grey.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to receive and convert foreign currencies to USDC in Bulgaria","item":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-bulgaria"}]}] </script>

How to receive and convert foreign currencies to USDC in Bulgaria

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

If you’re a freelancer working with international clients in Bulgaria, managing your payment process doesn’t need to be hectic. USD Coin (USDC) offers a streamlined, stable solution for this.

This guide explains how freelancers and remote workers in Bulgaria can efficiently receive foreign currencies, convert them into USDC, and take control of their earnings with Grey.

Why convert foreign payments to USDC as a freelancer in Bulgaria?

For freelancers working with clients abroad, converting foreign currencies to USDC offers several advantages:

Stable value: USDC is pegged to the U.S. dollar, offering predictable value without the volatility associated with other cryptocurrencies.

Lower fees: USDC transaction fees are typically lower than traditional bank transfers, saving you money.

Quick access to funds: Blockchain technology enables quick transfers, ensuring freelancers have almost instant access to their funds.

Flexible conversion: USDC allows you to hold your earnings in a stable digital form and convert them to Bulgarian lev (BGN) or other currencies when exchange rates are favourable.

Also Read: Send instant USDC payouts to 40+ countries with Grey

How to receive and convert foreign currency to USDC

Grey offers a secure and straightforward method for freelancers to manage USDC payments. Here’s how you can send and convert USDC using Grey:

Open the Grey app

Log into your Grey account using the app or website. This will give you secure access to your USD and other currency balances.

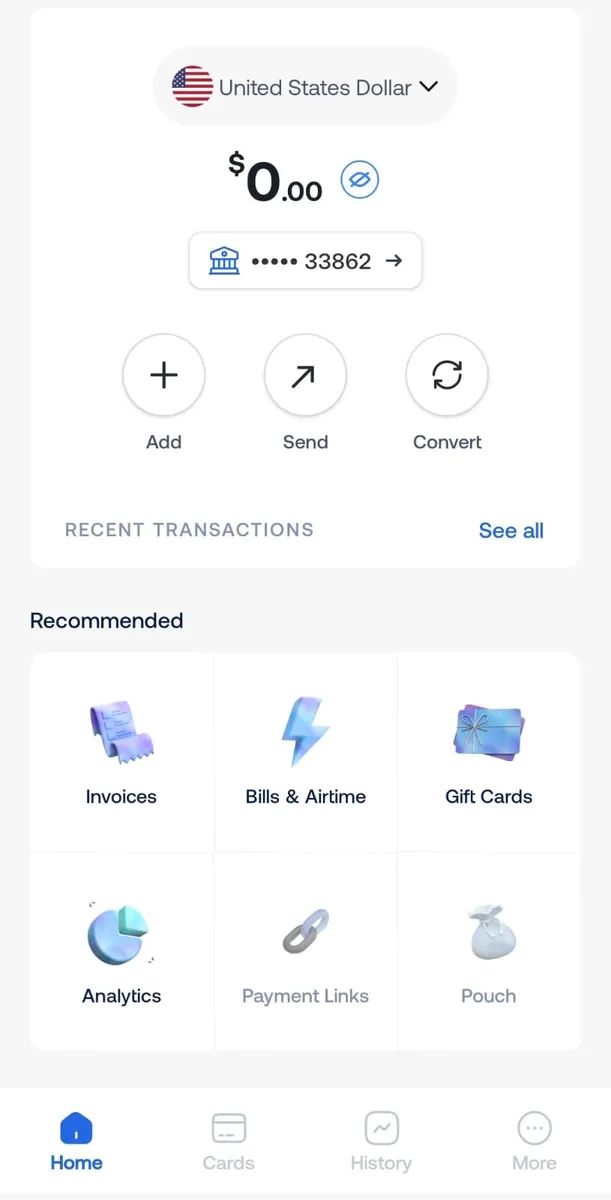
Select your USD balance

Navigate to the “Accounts” section and select your USD balance. This will serve as the starting point for initiating USDC transfers.

__wf_reserved_inherit

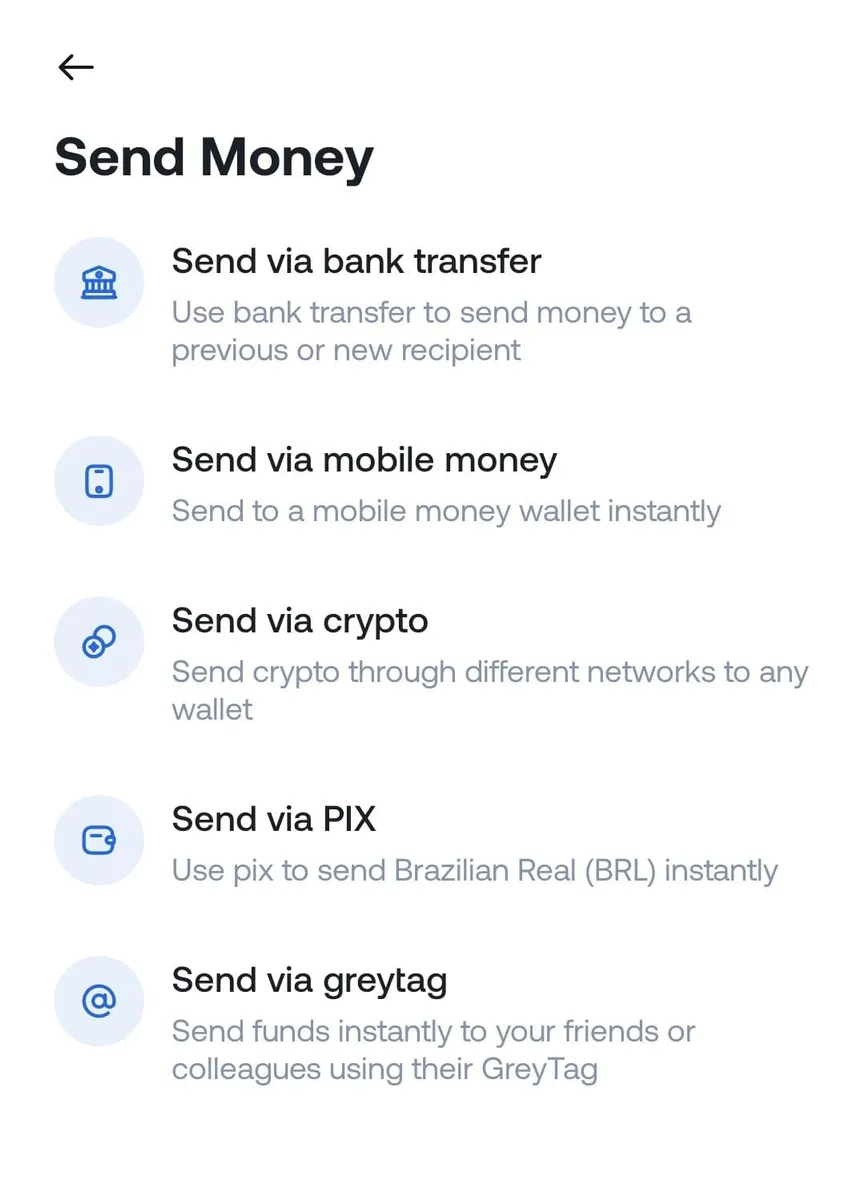
Tap “Send via crypto”

Choose the “Send money” option, then select “Send via crypto” to start the USDC transfer process.

__wf_reserved_inherit

Enter transaction details

Input the recipient’s wallet address carefully. Ensure you select the correct network, as Grey supports Solana (SOL) and Binance Smart Chain (BEP-20).

__wf_reserved_inherit

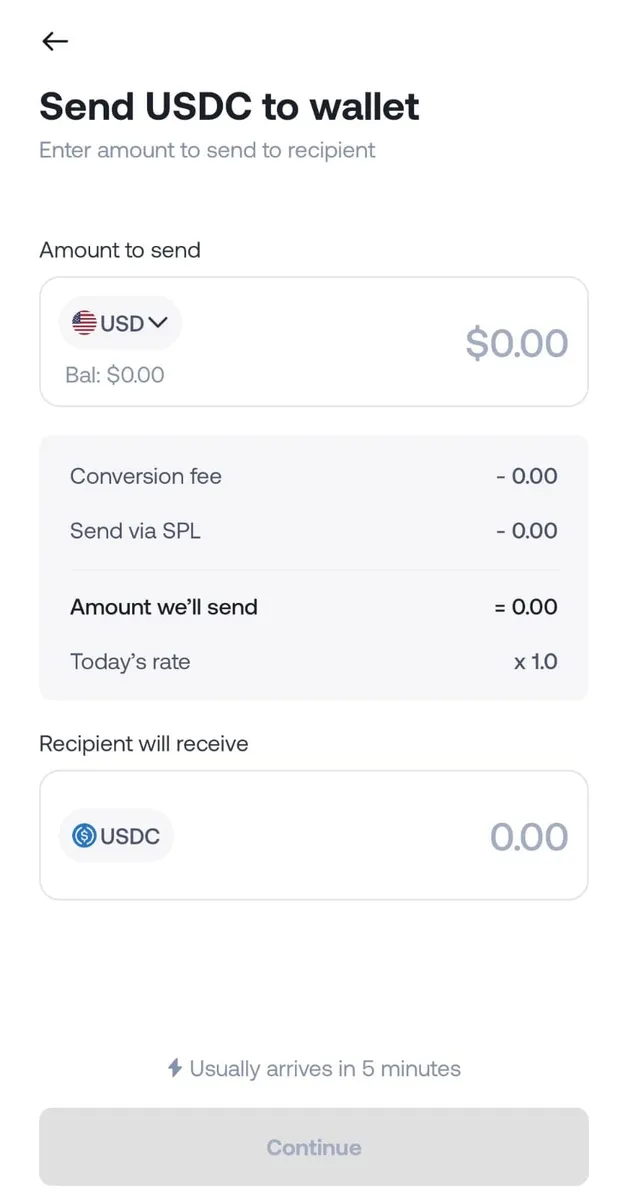
Input the transfer amount and review the details

Specify the amount you want to send and make sure to double-check the wallet address and network to ensure your transaction goes in the right place.

__wf_reserved_inherit

Confirm and complete the transfer

Once satisfied with the details, tap “Send.” Grey will prompt you to enter your two-factor authentication (2FA) code for added security.

Transaction success

After processing, the USDC will arrive in the recipient’s wallet. The recipient can keep it, convert it into local currency, or use it as needed.

Also Read: How to receive and convert foreign currencies to USDC in the Philippines

How to convert USDC to Bulgarian Lev (BGN)

To convert USDC into BGN, use a cryptocurrency exchange or a local service that supports USDC-to-BGN conversions. Some platforms offer direct conversions, while others may require intermediary trades through USD or BTC.

Also Read: How to receive and convert foreign currencies to USDC in Indonesia

What are the considerations for freelancers holding and converting USDC?

While holding USDC is convenient, here are a few things freelancers in Bulgaria should consider:

  • Network compatibility: Ensure the network used for USDC matches your wallet and conversion service to avoid transaction errors.
  • Transaction fees: While USDC has lower transaction fees than traditional methods, network fees can vary depending on the blockchain.
  • Tax compliance: Bulgaria’s tax regulations treat cryptocurrency as a financial asset. Consult with a local tax advisor to stay compliant when holding or converting USDC.

Using Grey to simplify USDC management

Grey offers freelancers in Bulgaria an easy way to manage USDC transactions. With its user-friendly interface, secure systems, and support for multiple networks, Grey ensures a seamless experience when receiving and managing foreign payments.

Ready to simplify your international transactions? Create your Grey account today and unlock the power of global financial freedom.

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to earn yield on USDC: Best options in 2026

•

•

2 min read

USDC is a stablecoin designed to maintain a value close to one US dollar, making it an option for people who want to hold digital dollars without the usual price swings associated with cryptocurrencies like Bitcoin. However, holding USDC in a wallet does not automatically generate interest. To earn a return, you need to invest your holdings in a programme or platform that pays a yield.

USDC itself pays no interest. Yield comes from lending it out through a centralised exchange programme, a crypto lending platform, or a DeFi protocol such as a lending pool or liquidity pair. Rates ranged from about 2 to 8% APY in 2026, depending on the platform, strategy and market conditions.

Each option comes with different levels of risk, access requirements and withdrawal conditions. Before choosing where to earn yield, understand how returns are generated, whether your funds are protected, and what could happen if a platform fails or a smart contract is exploited.

Does USDC pay interest on its own?

No, holding USDC in a crypto wallet does not earn interest by itself. USDC is a stablecoin designed to maintain a value close to one US dollar, but simply owning it does not generate additional income. Whether it sits in a personal wallet or an exchange account, your balance remains unchanged unless you receive additional USDC through another transaction or service.

To earn yield, you need to use a separate financial product built on top of USDC. These products generate returns through activities such as lending your stablecoins to borrowers, supplying liquidity to decentralised finance (DeFi) protocols, or participating in yield programmes offered by cryptocurrency exchanges.

Each option works differently and carries its own risks. A lending platform may pay interest from borrower repayments, while a DeFi protocol may distribute fees or lending revenue to participants. Centralised exchanges may offer promotional rates or rewards under specific conditions.

Before depositing USDC into any yield product, understand how returns are generated, what fees apply, and whether you can withdraw your funds when needed. Yield is never guaranteed.

Also read: How USDC compares with USDT

Centralised exchange and lending platforms

Centralised exchanges and crypto lending platforms allow you to earn yield by depositing your USDC into programmes that generate returns. Exchange earn programmes may lend your USDC to borrowers or use other permitted strategies to generate revenue, sharing a portion of the earnings with you.

Crypto lending platforms work similarly, connecting you with borrowers and paying interest on the funds you supply.
The annual percentage yield (APY) you receive depends on the platform, market demand, lending activity and programme conditions. Rates can change, and promotional offers may have limits or eligibility requirements.

Custody is another important consideration. When you deposit USDC into a centralised platform, the platform typically controls your assets rather than you holding the private keys directly. It may lend, transfer or otherwise use your deposited coins according to its terms.

This exposes you to counterparty risk. If the platform becomes insolvent, freezes withdrawals or suffers a hack, you may struggle to access your funds or lose them entirely. Before depositing your USDC, review the withdrawal terms, fees, security measures and how the platform uses your assets.

DeFi options: lending pools and liquidity pairs

Decentralised finance (DeFi) offers another way to earn yield on USDC without relying on a traditional financial intermediary. Two common options are lending pools and liquidity pairs, each generating returns in different ways.

With a lending pool, you deposit USDC into a protocol where borrowers can access the funds and pay interest. A portion of that interest is distributed to depositors as yield. Your returns depend on borrowing demand, utilisation rates and the protocol’s rules.

With a liquidity pair, you deposit USDC alongside another cryptocurrency into a trading pool. Traders use this pool to swap assets, and liquidity providers may earn a share of trading fees. However, the value of the two deposited assets can change relative to each other, creating impermanent loss.

Both strategies carry risks. Smart contract bugs can expose deposited funds to theft or loss. Impermanent loss can reduce returns compared with simply holding the assets. Depegging occurs when USDC falls below its intended one-dollar value, reducing the value of your holdings even when the yield remains positive.

How the main risks compare

When you earn yield on USDC, your biggest risks depend on where you deposit your funds and how the platform generates returns. Counterparty risk, smart contract risk and depeg risk can all affect how much you earn and whether you recover your initial deposit.

Counterparty risk arises when you trust a centralised exchange or lending platform with your USDC. If the provider fails or freezes withdrawals, you may lose access to your funds. Smart contract risk affects you when a vulnerability in a DeFi protocol allows your deposited funds to be stolen or lost. Depeg risk means your USDC falls below its intended $1 value, reducing the value of your holdings.
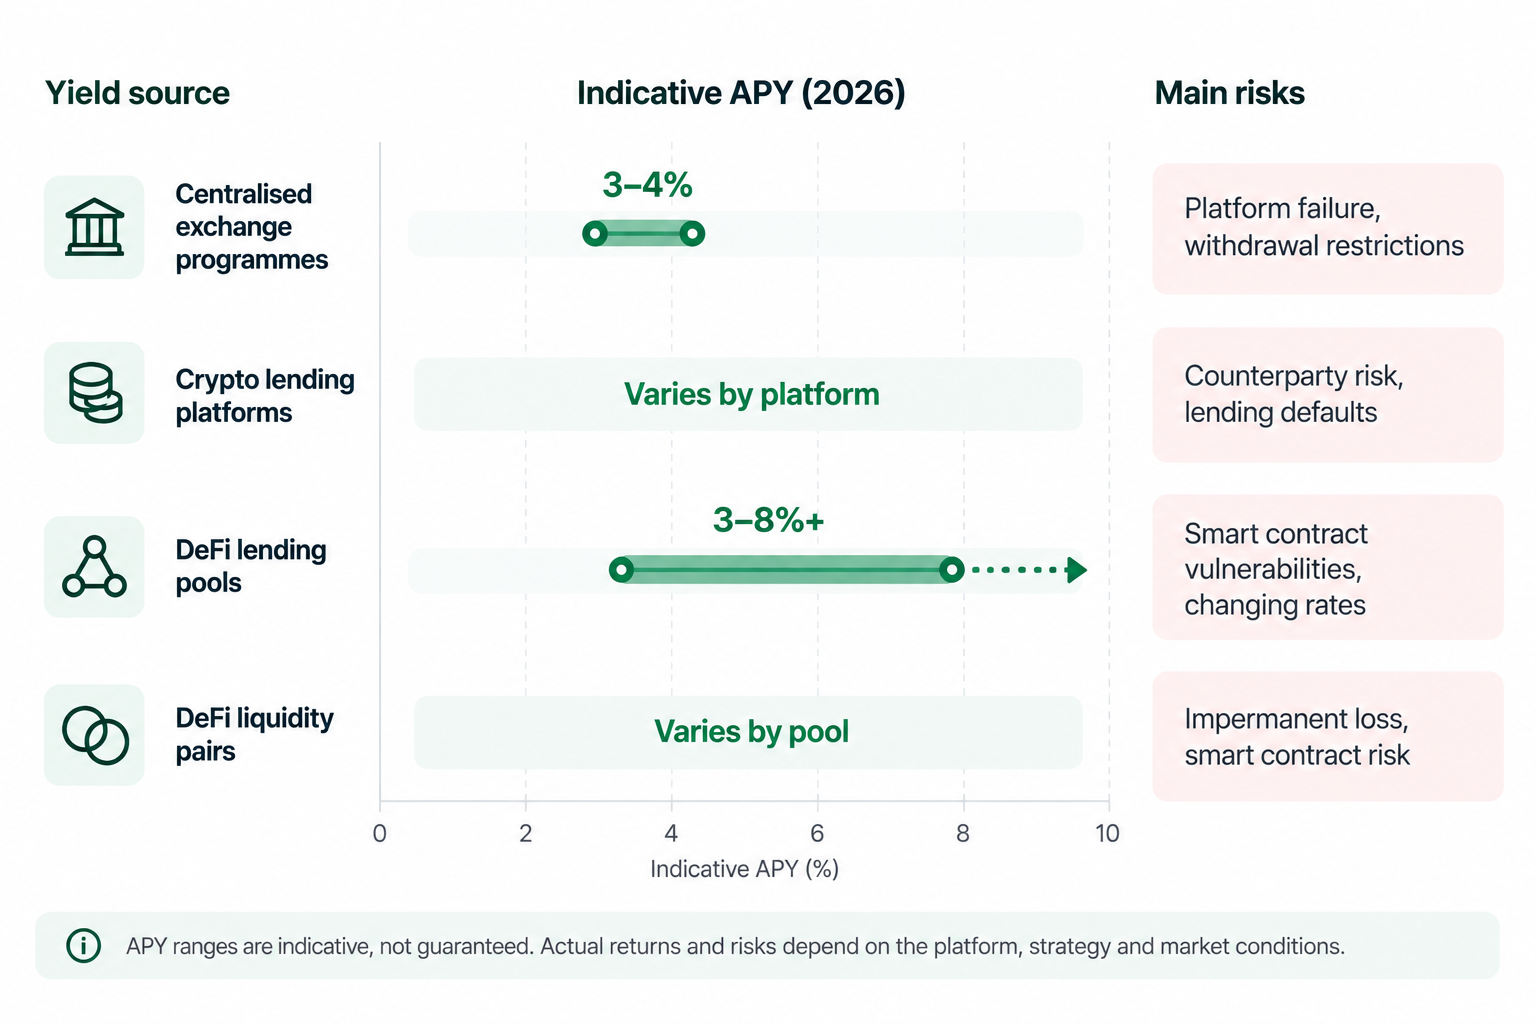
Chart comparing USDC yield options by risk and return.

There is no universal ranking because your exposure depends on the product you choose. However, higher advertised APY usually means higher risk. Before depositing, consider how returns are generated, who controls your funds and what could go wrong.

Your choice of blockchain also matters. Learn how USDC on Solana compares with Ethereum when considering transaction fees, network activity and the platforms available to you.

USDC yield vs a bank savings account

USDC yield can offer a potentially higher return than a regular savings account, but you give up an important protection: USDC does not have government-backed deposit insurance. Your returns depend on the platform and strategy you use, and higher yields often come with greater risk. A bank savings account may offer less, but eligible deposits have protection and more predictable access to your money.

Before choosing USDC for yield, consider whether you can afford the risks, including platform failure, smart contract vulnerabilities and changes in USDC’s value. It is generally better to keep emergency funds in an insured bank account rather than expose money you need urgently to crypto-related risks.

USDC can also make moving money across borders easier. For example, if you need to send money from the US to Nigeria, you can use a platform that supports USDC transfers and local withdrawals. With Grey, you can send, receive and spend USDC, then convert your balance and withdraw funds to a supported local bank account.

The right choice depends on your priorities: bank deposits for protection, USDC for global access and potential yield.

Frequently asked questions about how to earn yield on USDC

1. Is earning yield on USDC safe?

Earning yield on USDC carries risks, including platform failure, smart contract vulnerabilities and loss of funds. Although USDC is designed to maintain a one-dollar value, your investment is not guaranteed. Review the platform’s security, withdrawal terms and yield strategy before depositing funds, and never invest money you cannot afford to lose.

2. What is a typical USDC APY in 2026?

USDC yield varies by platform, market conditions and strategy. In 2026, some centralised reward programmes offer around 3–4% APY, while DeFi lending may offer approximately 3–8% or more. These are indicative ranges, not guaranteed rates. Check current offers, fees and risks before choosing a platform.

3. Do you pay tax on USDC yield?

Yes, USDC yield may be taxable, depending on your country’s tax laws and how you earn it. In the United States, rewards are generally reportable as income. Keep records of payments, dates and amounts, and consult a qualified tax professional to understand your reporting obligations.

4. Can you lose your USDC principal earning yield?

Yes, you can lose some or all of your USDC principal. Platform insolvency, lending defaults, smart contract exploits and liquidity problems can prevent withdrawals or cause losses. USDC can also trade below one dollar. Assess the risks carefully, diversify where appropriate and avoid committing essential savings.

5. What is the difference between USDC yield and USDC staking?

USDC yield usually comes from lending, reward programmes or providing liquidity through a platform or DeFi protocol. Staking typically involves locking cryptocurrency to support a proof-of-stake blockchain. USDC does not use proof-of-stake itself, so products marketed as USDC staking generally involve a different yield-generating mechanism.

6. How do you convert USDC yield into cash you can spend?

First, withdraw your USDC and earn rewards to a supported exchange or financial platform. Convert the balance into your preferred currency, then withdraw it to an eligible bank account or payment method. With Grey, you can send, receive and spend USDC, subject to supported services, currencies and applicable fees.

While USDC yield offers the potential for higher returns, a bank savings account provides greater protection for eligible deposits. For international transactions, Grey gives you a practical way to send, receive and spend USDC, with access to supported currencies for your everyday financial needs.

Gift tax: How much money can you give tax-free?

•

•

2 min read

Giving money to another person may seem straightforward, but large financial gifts can come with tax reporting requirements. In the United States, the Internal Revenue Service (IRS) determines how much you can give each year before you may need to report the gift. Understanding these rules is particularly important when transferring substantial sums, sharing wealth, or planning your finances.

The good news is that exceeding the annual gift tax limit does not automatically mean you owe tax. The IRS provides a lifetime exemption that allows you to give more than the annual limit before gift tax becomes payable. Knowing the difference between the annual exclusion, reporting requirements and lifetime exemption can help you make informed financial decisions.

The IRS annual gift tax exclusion lets you give up to a set amount per recipient each year with no tax owed and no form to file. Gifts above that amount count against your lifetime exemption and require Form 709, though tax is rarely owed until the lifetime exemption itself is used up.

How much can you gift tax-free per year?

For 2026, you can give up to $19,000 per recipient per year without owing federal gift tax or generally needing to file a gift tax return. This annual exclusion applies to qualifying gifts of money or property under US Internal Revenue Service (IRS) rules.

The limit resets every calendar year, beginning January 1. This means gifts made in 2026 are counted separately from gifts made in 2025. You can give money to multiple recipients in the same year, provided each recipient’s total qualifying gifts from you stays within the annual limit.

The exclusion applies per giver and per recipient, rather than as one combined limit for all your gifts. For example, you could give $19,000 each to three people in 2026, totalling $57,000, without exceeding the annual exclusion for any recipient. If two spouses each give the same recipient $19,000, their combined gifts can reach $38,000 under their separate exclusions, subject to applicable IRS rules.

What is the lifetime gift tax exemption?

For 2026, the US lifetime gift and estate tax exemption is $15 million per individual. This is the total amount an individual can transfer through qualifying gifts during their lifetime and leave to beneficiaries at death before federal gift or estate taxes generally apply, subject to applicable rules.

The lifetime exemption works alongside the annual gift tax exclusion. While the annual exclusion allows qualifying gifts of up to $19,000 per recipient in 2026 without using the lifetime exemption, larger gifts generally count toward the $15 million limit. Gifts exceeding the annual exclusion may require you to file IRS Form 709, even when no tax is due.

The important distinction is that the lifetime gift tax exemption and estate tax exemption are shared, not separate allowances. For example, if you make $2 million in taxable gifts during your lifetime, that amount generally reduces the exemption remaining for your estate. Any unused exemption may apply to assets transferred at death, helping determine whether your estate owes federal estate tax.

When do you need to file form 709?

You generally need to file IRS Form 709 if you give more than $19,000 to one person in 2026, unless a specific exception applies. The form reports gifts exceeding the annual exclusion and helps the IRS track your use of the lifetime gift tax exemption.

The filing requirements, deadline and potential tax implications are important to understand before submitting your return.

Who Must File Form 709?

The person giving the gift is generally responsible for filing. You may need to file if your gifts to one recipient exceed the annual exclusion, you transfer certain future interests, or you elect to split gifts with your spouse.

When Is Form 709 Due?

The deadline is generally April 15 of the year following the gift. For gifts made in 2026, the filing deadline is April 15, 2027. An extension may be available, but it does not automatically extend the deadline for paying tax owed.

Does Filing Form 709 Mean You Owe Tax?

No. Filing the form does not automatically mean you owe gift tax. Gifts above the annual exclusion generally reduce your lifetime gift and estate tax exemption. Federal gift tax is typically payable only after your available exemption has been exhausted.

Gift tax vs Estate tax: how they connect

Gift tax and estate tax share one combined lifetime exemption. In 2026, the federal gift and estate tax exemption is $15 million per individual. This means large gifts made during your lifetime and assets transferred after your death generally count toward the same exemption.

If you give a substantial amount of money while alive, the portion exceeding the annual gift tax exclusion generally reduces the exemption remaining for your estate. For example, if you make $2 million in taxable gifts, that amount generally reduces your remaining exemption to $13 million, assuming no other taxable transfers or adjustments.

Alternatively, leaving the money in your estate means its value may be considered when calculating estate tax after your death. If your total taxable estate and applicable prior gifts remain within your available exemption, federal estate tax generally will not be due.

The main difference is when the transfer happens and how the assets are valued. Lifetime gifting can help transfer wealth earlier, but the best approach depends on your financial circumstances, future needs and estate planning goals.

If you're sending money as a gift to family members abroad, it's also worth considering transfer fees and exchange rates. For example, you can send money from the US to Mexico or send money from the US to India using available international transfer services. Just remember that sending money internationally doesn't automatically exempt a gift from US tax reporting requirements.

Frequently asked questions about gift taxes

Does the person receiving a Gift pay tax on it?

Generally, no. Under US federal tax rules, the recipient does not pay income tax on money received as a gift. The person giving the gift is usually responsible for any applicable gift tax reporting and payment. However, income generated by gifted assets may be taxable to the recipient.

Can you gift more than the annual exclusion without paying tax?

Yes. Gifts exceeding the 2026 annual exclusion of $19,000 per recipient may require you to file Form 709. However, the excess generally reduces your lifetime gift and estate tax exemption rather than triggering immediate tax. Gift tax usually becomes payable after the available exemption is exhausted.

Do Gifts to a spouse count toward the annual exclusion?

Generally, gifts to a US-citizen spouse qualify for the unlimited marital deduction and do not count toward the annual exclusion. Gifts to a non-US citizen spouse have a separate annual limit, which is $194,000 for 2026. Special rules may apply depending on the circumstances.

Is money sent to family abroad treated as a Gift for tax purposes?

Yes. Money sent to relatives abroad may qualify as a gift under US tax rules. If the giver is subject to US gift tax, the annual exclusion and reporting requirements may apply regardless of where the recipient lives.

Do you have to report a Gift from a foreign relative?

You may need to. US persons who receive gifts exceeding $100,000 in total from a nonresident alien individual or foreign estate generally must report them on Form 3520. Different thresholds apply to gifts from foreign corporations or partnerships.

What is the penalty for not filing Form 709 when required?

Failure to file Form 709 when required may result in penalties based on the unpaid gift tax, generally 5% per month, up to 25%. If no tax is due, penalties may differ, but the IRS can still assess consequences for noncompliance. Filing requirements should be checked carefully.

Managing money across borders involves more than understanding gift tax. Whether you are supporting family abroad, making international payments or managing everyday expenses, having the right financial tools matters. Grey offers multi-currency accounts and virtual cards that make it easier to manage international finances, pay for online services and handle supported cross-border transactions.

USDC on Solana vs Ethereum: Which should you use?

•

•

2 min read

Solana or Ethereum? Both can move the same dollar-backed stablecoin, but the difference becomes clear when speed and transaction fees matter.

Solana can settle a USDC transfer in a few seconds, usually for a fraction of a cent. Ethereum, on the other hand, can take several minutes, with fees that increase when the network is busy. For a straightforward payment, Solana can be the more practical option when keeping costs low matters.

Both versions of USDC are issued by Circle and designed to maintain a 1:1 value with the US dollar. The real choice is therefore not between two different stablecoins, but between two networks. The better option depends on where the money is going, which network the recipient supports, and whether speed, low fees or access to Ethereum’s wider ecosystem matters most.

What is the difference between USDC on Solana and Ethereum?

The main difference between USDC on Solana and Ethereum is the blockchain network used to settle your transaction, even though both versions are issued by Circle, designed to maintain a 1:1 value with the US dollar and redeemable through the same issuer. When you choose between them, you are therefore choosing a different settlement layer, with Solana generally offering faster and cheaper transfers while Ethereum can become more expensive when the network is busy.

The distinction becomes more important when you come across native and bridged USDC. Native USDC is issued directly by Circle on the blockchain where you hold it, so USDC issued natively on Solana is Circle-issued USDC on Solana, while native USDC on Ethereum is issued directly on Ethereum. This means you should not assume that every token labelled “USDC” has the same issuance structure.

Bridged USDC represents USDC that has been moved between blockchains using a bridge, rather than being directly issued by Circle on the destination network. Before sending your USDC, check the network supported by the recipient and whether you are dealing with native or bridged USDC, because sending through an unsupported network can make it difficult or impossible to recover your funds.

How fees and settlement times compare

When you compare Ethereum and Solana for USDC transfers, the biggest differences you'll notice are the network fee and how quickly your transaction settles. Ethereum fees change with supply and demand, so when more people compete for limited block space, the base fee rises and you may pay an additional tip to have your transaction prioritised. Solana generally offers lower and more predictable fees, which can make it more practical for frequent transfers.

On Ethereum Layer 1, you may pay around 0.01–0.20, with settlement taking roughly 12 seconds to several minutes depending on network conditions and the level of finality you require. Solana typically settles transactions within seconds at a fraction of a cent.

Ethereum Layer 2 networks can reduce the cost further by processing transactions away from the main chain and later posting transaction data to Ethereum. This gives you faster execution and lower fees, although the final settlement process works differently from a direct Layer 1 transaction. Network conditions change, so check current fees before sending.

Also read: USDC to USD: How to convert your stablecoin to cash

What happens if you send USDC to the wrong network?

Sending USDC to the wrong network can put your funds at risk, and whether you can recover them depends on where the money was sent and who controls the receiving wallet. If the destination supports the network you used, recovery may be possible, but if it does not, you may need help from the exchange or wallet provider, with no guarantee that the funds can be recovered.

Before sending, check that the network selected on your platform matches the network supported by the recipient. Do not rely on the wallet address alone, because the same address format can sometimes work across different networks. If you use a USD bridge to move USDC between blockchains, confirm the destination network and the type of USDC being received before approving the transaction.

For a large transfer, send a small test amount first, then check the network name, token and destination address before sending the remaining balance. Once a blockchain transaction is confirmed, it generally cannot be reversed.

Also read: How to convert and use USDC in Nigeria

How to choose a network for your transfer

Choosing a network for your USDC transfer comes down to three things: how much you are sending, where the money is going and how quickly you need it to arrive. Start with the destination, because the cheapest or fastest network is not useful if the recipient’s wallet or exchange does not support it. Check the supported networks before you enter the amount or confirm the transaction.

Next, consider the amount you are sending. For a small transfer, a network with very low transaction fees can help you avoid losing a noticeable percentage of your money to fees. For a larger transfer, the fee may matter less, but you should still confirm that the network supports the exact USDC you are sending.

Finally, consider urgency. If you need the money to arrive within seconds or minutes, a faster network may make more sense. If timing is flexible, you can compare fees and choose the cheaper option. Whatever you choose, confirm the network on both sides before sending.

Open a multi-currency account to send and receive USDC

Turning USDC into local currency usually involves one more step after receiving your payment: moving the funds from your crypto wallet or exchange into a bank account where you can spend them. A multi-currency account can fit between these steps, giving you a place to receive and hold funds before converting them into the currency you need.

With Grey, you can open a multi-currency account and use it to manage your international payments in one place. Once you receive USDC, you can move the funds through the available conversion and withdrawal options rather than immediately sending everything to a local bank account. This can give you more control over when you convert and where your money goes.

The process is straightforward: receive your USDC, convert or off-ramp it through a supported route, then withdraw the resulting currency to your local bank account. The exact steps depend on the currencies and payment routes available to you, so check the supported options before starting your transfer.

Frequently asked questions

Is USDC on Solana the same as USDC on Ethereum?

USDC on Solana and USDC on Ethereum are both issued by Circle and designed to maintain a 1:1 value with the US dollar, but they operate on different blockchains. The main differences are transaction speed, network fees and where you can send or receive each version of USDC.

Which network has lower USDC fees?

Solana generally has lower USDC transaction fees than Ethereum, with transfers typically costing a fraction of a cent. Ethereum fees can increase when the network is busy because users compete for limited block space. Before sending, check the current network fee and make sure the recipient supports your chosen network.

Can I send USDC from Solana to an Ethereum wallet?

You cannot send native USDC on Solana directly to an Ethereum-only address and expect it to arrive correctly. To move USDC between networks, you need a supported bridge or exchange that handles the transfer. Always confirm both the sending and receiving networks before approving the transaction.

What happens if I pick the wrong network?

Choosing the wrong network can make your USDC difficult or impossible to recover, depending on the receiving wallet or exchange. Before sending, check the network supported by the recipient and make sure it matches the network selected in your wallet. For larger amounts, consider sending a small test transaction first.

Is USDC on Solana safe?

USDC on Solana can be safe when you use the official, native version of USDC and send it through a supported wallet or exchange. Your biggest risks usually come from choosing the wrong network, using an unsupported token or sending funds to an incorrect address. Always verify the token and destination.

How do I convert USDC to my local currency?

To convert USDC into your local currency, you typically send it to a supported exchange or financial platform, sell or convert the USDC, then withdraw the resulting funds to your bank account. A multi-currency account can also give you a place to receive and manage funds before converting them.

How to save money in USD in Nigeria: Best ways and apps

•

•

2 min read

If you saved NGN 1,000,000 in a Nigerian bank account five years ago, that money has lost more than half its purchasing power in dollar terms. The naira has depreciated from roughly NGN 410/USD to over NGN 1,500/USD since 2021. Saving in naira means watching your wealth shrink. Saving in dollars means preserving it.

Nigerians can save in USD through domiciliary accounts at commercial banks, fintech apps like Grey, PiggyVest, and Bamboo, or by holding dollar-denominated stablecoins. Each method has different costs, access requirements, and risk profiles. The best option depends on how much you're saving, how quickly you need access, and how comfortable you are with digital platforms.

This guide compares every method available in Nigeria for saving in dollars, with the real costs, risks, and trade-offs for each. For a broader look at saving in foreign currencies from anywhere, see how to save in foreign currency.

Why save in USD from Nigeria?

The case for saving in dollars is straightforward: the naira has lost value against the dollar consistently for over a decade. This isn't a temporary dip. It's a structural trend driven by Nigeria's dependence on oil exports, foreign exchange shortages, and monetary policy decisions.

Saving in naira means your money buys less every year, even when the number in your account stays the same or grows. A Nigerian who saved NGN 5 million in 2020 had roughly $13,000 at the time. That same NGN 5 million is now worth under $3,500. The account balance didn't change. The purchasing power collapsed.

Saving in USD preserves your purchasing power relative to the global economy. Your dollar savings buy the same amount of imported goods, school fees, medical treatment, and international services regardless of what happens to the naira.

That said, saving in USD isn't without risk. If the naira strengthens (it has happened in short bursts, usually after CBN interventions), your dollar savings lose value in naira terms temporarily. Converting naira to dollars also carries a cost: the exchange rate spread, which runs 1 to 5% depending on the method. The decision to save in dollars should be a long-term one, not a short-term speculation on the naira.

Don't convert your rent money or next month's food budget to dollars. Keep 3 to 6 months of living expenses in naira for immediate needs. Save in dollars with what you can afford to hold for at least 6 to 12 months.

Method 1: Domiciliary accounts

A domiciliary account ("dom account") is a foreign currency account at a Nigerian commercial bank. You hold USD, GBP, or EUR in the account and can deposit or withdraw in those currencies. GTBank, Access Bank, Zenith Bank, First Bank, and UBA all offer them. For a step-by-step guide, see how to open a domiciliary account.

Requirements: BVN, NIN, a valid ID (international passport or national ID card), a utility bill not older than 3 months, two reference letters (some banks still require these; others have dropped the requirement), and a minimum opening deposit (typically $100 to $500, depending on the bank). The process requires a branch visit, and the documentation verification can take 3 to 7 business days.

Pros: Regulated by CBN, funds are NDIC-insured (up to NGN 500,000 equivalent per depositor per bank), physical branch access for withdrawals, and you can receive international wire transfers directly into the account via SWIFT.

Cons: The biggest issue is sourcing dollars. Nigerian banks don't sell USD to individuals at the official rate. You need to deposit dollars you already have, whether from exports, remittances, freelance income, or the parallel market. Interest is typically 0% on most domiciliary accounts. Withdrawals can be restricted during FX shortages, with some banks limiting cash withdrawals to $5,000 per month. Monthly maintenance fees of $1 to $5 are common, and some banks charge for incoming wire transfers.

Who should use this: Anyone with large dollar savings ($10,000+) who wants maximum regulatory protection and doesn't need frequent access. The NDIC insurance and CBN regulation make this the safest option on paper.

Method 2: Fintech apps

Several Nigerian fintech apps let you save in dollars or dollar-equivalent instruments from your phone. They're faster to set up than dom accounts, don't require a branch visit, and typically have lower minimum deposits. The trade-off is different (and sometimes less clear) regulatory protection.

PiggyVest: One of Nigeria's most popular savings apps. Offers USD savings with up to 7% annual interest through their dollar savings feature. You buy dollars within the app at the prevailing rate.

Pros: User-friendly interface, competitive interest rates, automated savings features.

Cons: $20 fee to transfer USD out to a domiciliary account, USD isn't always available for purchase (demand often exceeds supply), and the platform is not a bank, so deposit insurance works differently. Best for people who want to save small amounts regularly and don't mind limited withdrawal windows.

Bamboo: Primarily an investment app for US stocks and ETFs, but its fixed-income dollar product lets you save idle USD at up to 8% interest for 90-day lock-in periods.

Pros: Dollar-denominated, SEC-regulated (for the stocks side), accessible from Nigeria.

Cons: the 90-day lock-in means no access during that period, and the platform is more investment-oriented than a pure savings product. Best for people who want to park $500+ for 3 months and earn yield while they wait.

Rise: Another investment platform with dollar savings features. Offers fixed-income and real estate dollar funds alongside stock investments.

Pros: Diversified dollar savings options, regulated, and accessible.

Cons: Returns vary by fund, minimum investments apply, and liquidation times depend on the fund type. Real estate funds can take days to liquidate. Best for people who want dollar exposure beyond simple savings.

Cowrywise: Offers naira and dollar mutual fund investments. Dollar savings come through dollar-denominated fixed-income funds managed by licensed fund managers.

Pros: Automated savings, SEC-regulated fund managers, and accessible.

Cons: Dollar availability can be limited during high-demand periods, returns aren't guaranteed (they're based on fund performance, not a fixed interest rate), and withdrawals may take 24 to 72 hours.

Who should use fintech apps: anyone saving $50 to $5,000 monthly who wants easy access, doesn't want a branch visit, and is comfortable with digital platforms. Compare the interest rates, lock-in periods, and withdrawal policies before committing.

Method 3: Stablecoins (USDT, USDC)

Stablecoins are cryptocurrencies pegged 1:1 to the US dollar. Buying USDT (Tether) or USDC (Circle) is effectively buying digital dollars. You purchase them on exchanges like Binance, Bybit, or Luno using naira via P2P trading.

Pros: Instant access at any hour, no bank involved, 24/7 liquidity (you can convert back to naira at 2am on a Sunday), and the ability to earn yield through DeFi protocols (though this adds substantial risk). Converting back to naira via P2P is straightforward and settles within minutes.

Cons: Not regulated by CBN, which means no deposit insurance. The exchange rate spread on P2P purchases runs 1 to 3% above the mid-market rate, eating into your savings immediately. Platform insolvency is a real risk (FTX collapsed owing billions to depositors). You need basic crypto knowledge to manage wallets, avoid scams, and understand the difference between custodial and non-custodial storage. P2P trading also carries counterparty risk: the counterparty could fail to deliver.

Who should use stablecoins: People comfortable with crypto who want maximum flexibility and don't mind managing their own security. Keep holdings on reputable exchanges (Binance, Bybit) or in a hardware wallet for larger amounts. This isn't a savings account. It's holding a digital asset pegged to the dollar.

Method 4: Grey USD account

Grey lets Nigerian residents open a USD account that holds real dollars with US routing and account details. You can receive USD from international clients, freelance platforms, or transfers, hold the dollars, and convert to naira when you choose.

What makes it different: Grey isn't a savings app that lets you buy dollars at a markup. It's an account that receives and holds USD directly. If you earn in dollars (freelancing, remote work, exports), the money lands in your Grey account as USD. You decide when to convert to naira, based on the rate you see in the app. No forced conversion, no lock-in period, no minimum balance.

You can also spend directly from your USD balance using a Grey virtual card for online purchases, subscriptions, and international payments. This means you don't need to convert to naira just to pay for a Netflix subscription or buy something from an international merchant.

To organise money for a specific goal (a trip, tuition, an emergency fund), set it aside in a Grey Pouch so it's visually separate from your spending balance.

Pros: Real USD account details (ACH routing number and account number), no minimum deposit, no lock-in period, instant setup, virtual card for spending.

Cons: No interest earned on balances; 1% conversion fee (capped at $6) when you swap to naira.

Who should use Grey: Anyone earning in dollars who wants to hold those dollars and convert on their own terms. Especially freelancers, remote workers, and small business owners receiving payments from US clients.

Cost comparison: Converting NGN 500,000 to USD

Here's what it costs to convert NGN 500,000 (roughly $330 at parallel market rates) into dollars through each method:

Domiciliary account: You bring cash dollars to the bank. The cost is whatever you paid to source those dollars, typically the parallel market rate, which includes a 1 to 3% premium over the official rate. No conversion fee from the bank, but you're paying the spread on acquisition.

PiggyVest: You buy dollars within the app at their rate, which includes a spread. The effective cost is typically 1 to 3% above the parallel market rate. On $330, that's $3 to $10 in spread.

Stablecoins (P2P): Binance P2P rates for USDT include a 1 to 3% spread over the mid-market rate. On $330, that's $3 to $10 in spread, plus any trading fees (typically 0%).

Grey: If you're receiving dollars from clients, the cost is zero on receiving. When you convert from naira to dollars within Grey, the 1% swap fee (capped at $6) applies. On $330, that's $3.30.

The real cost isn't the platform fee. It's the exchange rate you get when sourcing dollars. Compare the effective rate (how many naira per dollar) across methods before converting a large amount.

Which method should you use?

If you earn in dollars (freelancing, remote work, exports): Grey. Your income arrives in USD and stays in USD until you choose to convert. No intermediary, no markup on receiving.

If you want to convert naira to dollars for long-term savings: PiggyVest or a domiciliary account. PiggyVest is easier to set up and pays interest; dom accounts offer more regulatory protection. If the amount is large ($10,000+), the dom account's NDIC insurance matters.

If you want dollar-denominated investments: Bamboo or Rise. These go beyond simple savings into fixed-income and equity products that earn returns.

If you're comfortable with crypto: Stablecoins (USDT/USDC) offer the most flexibility and 24/7 access, but with no deposit insurance and additional platform risk. Keep no more than you can afford to lose on any single exchange.

If you want both savings and spending: Grey. Hold dollars, spend with a virtual card, convert to naira when you need to. One account covers receiving, saving, and spending.

Frequently asked questions about saving in USD in Nigeria

Is it legal to save in dollars in Nigeria?

Yes. Nigerian residents can legally hold and operate domiciliary accounts in USD, GBP, or EUR at commercial banks. The CBN permits individuals to hold foreign currency for legitimate purposes, including savings, investment, and business transactions. Fintech apps operate under different regulatory frameworks depending on the specific licence. Stablecoins exist in a regulatory grey area but are not prohibited for individual holding.

How much interest can I earn on dollar savings in Nigeria?

Domiciliary accounts at banks: typically 0% (banks don't pay interest on foreign currency deposits). PiggyVest: up to 7% annually. Bamboo: up to 8% on 90-day fixed-income lock-in. Stablecoin DeFi yields vary widely (2 to 15%) but carry proportionally higher risk. Grey doesn't pay interest on USD balances but lets you hold and convert on your terms with no lock-in.

What is the safest way to save in dollars in Nigeria?

A domiciliary account at a CBN-regulated bank offers the most regulatory protection, with NDIC insurance covering up to NGN 500,000 equivalent per depositor per bank. Fintech apps offer convenience but may not carry the same level of deposit insurance. Stablecoins offer no deposit protection. For amounts under $5,000, a regulated fintech app is a reasonable balance of convenience and safety. For larger amounts, consider splitting across a dom account and a fintech platform.

Can I open a domiciliary account without a salary account at the same bank?

Yes. You don't need a salary account at the same bank to open a dom account. You need your BVN, NIN, valid ID, proof of address, and the minimum opening deposit ($100 to $500, depending on the bank). Some banks ask for reference letters. The process requires a branch visit at most banks, though some now offer partial online applications.

Ready to save in dollars? Open a Grey USD account and hold real dollars with US account details.

Disclaimer: This article is for informational purposes only. All costs and details are estimates based on mid-2026 data. Verify current information before making decisions. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

How to save in foreign currency: A practical guide

•

•

2 min read

Saving in a foreign currency is a hedge, not a guaranteed win. If the currency you save in depreciates against yours, you lose money. If it appreciates, you gain. Most people save in foreign currency because they don't trust their local currency to retain its value, not because they've run the numbers on exchange-rate forecasts.

That's a reasonable instinct. Over the past decade, the Nigerian naira has lost roughly 70% of its value against the US dollar. The Egyptian pound lost about 60% of its value. The Pakistani rupee lost about 40%. If you earned in those currencies and saved locally, your purchasing power eroded every year. Saving in USD, EUR, or GBP protects against that erosion.

To save in foreign currency, open a domiciliary account at a local bank or a multi-currency fintech account with a provider like Grey or Wise. Dom accounts have limited access and high minimums. Fintech accounts offer flexible digital holding with lower conversion costs. Stablecoins (USDC, USDT) offer a third path for crypto-comfortable savers who want dollar exposure without a bank account.

This guide covers every option, the costs involved, and who each one is actually for.

Why save in foreign currency?

Three reasons make the case for most people.

1. Currency depreciation protection. If your country's currency has a history of losing value against the dollar or euro, holding savings in a stronger currency preserves your purchasing power. This isn't speculation. It's insurance. The naira's depreciation from approximately 360/USD in 2020 to over 1,500/USD in 2026 turned NGN savings into a losing position regardless of interest rates earned. An NRE account earning 7% in naira still loses purchasing power compared to someone holding dollars at 0% interest.

2. Planning for international expenses. If you'll pay for education abroad, travel, medical treatment, or property in another country, saving in that country's currency eliminates exchange-rate uncertainty. You know exactly how much you have in the currency you'll spend. Converting from a depreciating currency at the last minute means you need more of it every month you wait.

3. Diversification. Financial advisors recommend diversifying across asset classes. Currency diversification applies the same logic: don't hold all your savings in a single currency, especially one with high inflation or political instability. Even a small allocation (10 to 20% of savings) in a stable foreign currency reduces portfolio volatility.

Who should NOT save in foreign currency: if your local currency is stable (USD, EUR, GBP, CHF, SGD), the benefits are minimal, and the conversion costs eat into returns. Swiss residents don't need to save in dollars. Americans don't need to save in euros unless they have specific euro-denominated expenses. If you live in a strong-currency country, invest rather than hedge currency risk.

Option 1: Domiciliary accounts

A domiciliary account (dom account) is a foreign-currency account held at a local bank. In Nigeria, most major banks (GTBank, Access Bank, Zenith Bank, UBA, First Bank) offer USD, GBP, and EUR domiciliary accounts. Similar products exist in Ghana (forex accounts), Kenya (FCY accounts), and other African and Asian markets.

How it works: you deposit foreign currency into the account, and it stays in that currency. No conversion on deposit. No conversion until you choose to withdraw in local currency. The bank holds your dollars as dollars. Interest rates are typically 0 to 1% on domiciliary accounts, sometimes zero.

Pros: Your foreign currency is held at a regulated local bank. NDIC insurance (up to NGN 500,000 equivalent in Nigeria). Familiar banking interface. You can receive SWIFT transfers directly into the account from abroad.

Cons: The access friction is real. Opening requires a branch visit with ID, utility bills, and sometimes a minimum deposit of $100 to $1,000. Withdrawals often require another branch visit. Some banks restrict online transfers from domiciliary accounts. The SWIFT fees on incoming transfers (ranging from $10 to $25 at many Nigerian banks) reduce the value of smaller deposits. And the bank's exchange rate when you convert to local currency includes a 1-3% spread over the mid-market rate, which is higher than fintech alternatives.

Best for: people who want to keep foreign currency at a traditional bank they already use, and who make infrequent, larger deposits ($500+) where the fixed SWIFT fee is proportionally small.

Option 2: Multi-currency fintech accounts

Fintechs like Grey, Wise, and Revolut let you hold multiple currencies in a single digital account. No branch visit. No minimum balance in most cases. Currency conversion happens instantly in the app at rates close to the mid-market rate.

Grey: Hold USD, EUR, and GBP with real account details. Receive payments via ACH (USD), SEPA (EUR), or FPS (GBP). Convert between currencies at a 1% fee, capped at $6. Withdraw to a local bank in 50+ countries. Virtual card for online spending directly from your foreign currency balance. No minimum balance. No monthly fee.

The Grey advantage for savers in Africa and South Asia: you get real US account details (routing and account numbers) that let you receive ACH transfers from US employers and clients with no receiving fees. A dom account can only receive SWIFT transfers, which cost $15 to $50 per incoming payment.

Wise: Multi-currency account with 40+ currencies. Conversion fees vary by currency pair (typically 0.5 to 1.5%). No receiving fee on major currencies. Real account details in USD, GBP, EUR, and several others. Competitive on per-transfer cost for smaller amounts.

Revolut: Similar to Wise. 30+ currencies. Free exchanges up to a monthly limit (standard plan), then 0.5 to 1%. Full banking features in the UK and EU. Limited availability in Africa and South Asia. If you're in Nigeria, Kenya, or India, Revolut likely isn't an option for you right now.

Best for: People who save foreign currency regularly (monthly income in USD, for example), who want instant access and low conversion costs, and who value the ability to spend directly from the foreign currency balance using a virtual card. If you'd otherwise lose 2 to 3% on every bank conversion, the fintech route saves $20 to $30 per $1,000 converted over a dom account.

Option 3: Stablecoins (USDC, USDT)

Stablecoins are cryptocurrencies pegged to a fiat currency, usually the US dollar. USDC (issued by Circle) and USDT (issued by Tether) are the two largest. Holding USDC is functionally similar to holding digital dollars, without needing a bank account.

How it works: buy USDC or USDT on a crypto exchange (Binance, Bybit, Luno, Quidax) using local currency. Hold the stablecoins in the exchange wallet or a personal crypto wallet (MetaMask, Trust Wallet, Phantom). When you want to convert back to local currency, sell on the exchange at the current rate.

Pros: accessible from almost any country. No bank required. No minimum balance. Transfers between wallets are fast and cheap on certain networks (Solana USDC transfers cost less than $0.01 and settle in seconds). You can hold dollar-equivalent value without a US bank account, which matters in countries where USD bank accounts are restricted or expensive.

Cons: you're holding crypto, even if it's a stablecoin. Exchange risk exists (the exchange could freeze your account, get hacked, or face regulatory action). USDT's reserve backing has been questioned repeatedly, though it has maintained its peg. USDC is considered more transparent but has occasionally frozen addresses at law enforcement request. Selling USDC back to local currency on peer-to-peer platforms can involve a 1 to 3% premium or discount depending on demand. No deposit insurance of any kind.

Grey's USDC integration: Grey supports receiving, holding, sending, and spending USDC. You can receive USDC via Solana or BNB Smart Chain, hold it in your Grey account alongside your fiat balances, and spend it directly with your Grey virtual card (the card draws from USD first, then USDC, then other balances). This bridges the gap between stablecoin holding and everyday spending without a manual conversion step. See Grey virtual cards for details.

Best for: crypto-comfortable savers in countries where foreign currency bank accounts are restricted, expensive, or unreliable. Not for people uncomfortable with crypto custody and exchange risks.

How to Time Your Currency Conversions

The honest answer: you probably shouldn't try to time currency conversions. Academic research consistently shows that even professional currency traders struggle to beat a simple dollar-cost-averaging strategy (converting the same amount at regular intervals regardless of the rate).

Dollar-cost averaging: convert a fixed amount every week or month. Some conversions will be at good rates, some at bad rates, and over time, they average out. This eliminates the paralysis of waiting for "the right rate" and the regret of converting at a bad one.

Rate alerts: set a target rate and convert when it hits. Grey and Wise both offer rate alert notifications. If you're not in a rush, setting a rate alert for 2 to 3% above the current rate and converting when it triggers gives you a consistent discount without the stress of monitoring daily.

Don't hold indefinitely. If you're saving in foreign currency for a specific purpose (tuition, property, travel), convert when you have enough, regardless of the rate. The goal is certainty of the amount in the target currency, not maximising the exchange rate. A bad conversion rate is better than being short of funds when the tuition bill arrives.

The costs of saving in foreign currency

Every method has costs. Account for them before assuming foreign currency savings are pure profit.

Conversion costs: 0.5 to 3% per conversion, depending on the method. Grey charges 1% capped at $6. Wise charges 0.5 to 1.5% depending on the pair. Dom accounts charge 1 to 3% via the bank's exchange rate spread. Stablecoin exchanges charge 0.1 to 0.5% in trading fees plus the spread.

Transfer fees: SWIFT transfers cost $15 to $50. ACH transfers to a Grey account are free. SEPA transfers to a Wise account are free. Stablecoin transfers vary by network (nearly free on Solana, $1 to $5 on Ethereum).

Holding costs: Dom accounts may charge monthly maintenance fees ($5 to $20). Fintech accounts are typically free. Stablecoins have no holding cost, but exchange wallets may have withdrawal fees.

Opportunity cost: dollars held in a zero-interest account lose purchasing power to US inflation (~3 to 4% annually). If you're holding $10,000 in a Grey account earning 0%, you're losing $300 to $400 per year in real purchasing power. An FCNR deposit at 4% offsets this. A US high-yield savings account at 4 to 5% does too, but that requires a US bank account.

Total your costs before committing. If you convert $500 per month at 1% cost ($5), that's $60 per year in conversion fees. If the currency you're saving in appreciates 5% against your local currency, you've gained $300 minus $60 in fees, netting $240. If it doesn't appreciate, you've spent $60 for no benefit. Know your break-even.

Want to start saving in foreign currency? Open a Grey account and hold USD, EUR, or GBP with real account details and no monthly fee.

Frequently asked questions about saving in foreign currency

What is the safest currency to save in?

The US dollar is the most common choice because it's the world's reserve currency, widely accepted, and relatively stable. The euro and British pound are alternatives. The Swiss franc (CHF) is traditionally the safest haven but conversion costs are higher for most people. No currency is risk-free. Dollar inflation means USD savings lose 3 to 4% in purchasing power annually unless earning interest.

Can I save in foreign currency without a bank account?

Yes. Stablecoins (USDC, USDT) let you hold dollar-equivalent value without a bank account. Buy on a crypto exchange using local currency, hold in a wallet. You can also use fintech accounts (Grey, Wise) that aren't traditional banks but offer regulated, insured foreign currency holding. For Grey specifically, sign up at grey.co/foreign-accounts.

How much should I save in foreign currency?

A common rule of thumb is 10 to 20% of total savings for currency diversification. If you have specific foreign currency expenses planned (education abroad, property, medical travel), save the full estimated cost in that currency. Don't convert your entire savings to foreign currency. Keep enough in local currency for 3 to 6 months of expenses.

Is saving in dollars better than investing?

Different purposes. Dollar savings protect purchasing power and provide liquidity. Investing (stocks, bonds, real estate) aims for growth and carries higher risk. Use dollar savings for emergency funds, short-term goals, and currency hedging. Use investments for long-term wealth building. They're complementary, not competing strategies.

Does Grey pay interest on foreign currency balances?

Grey does not currently pay interest on USD, EUR, or GBP balances held in the account. The value proposition is holding foreign currency with real account details, low conversion costs (1% capped at $6), and the ability to spend directly from the balance using a virtual card, not interest income. For interest-earning options, consider FCNR deposits (for NRIs) or US high-yield savings accounts (if you have US banking access).

Start saving in foreign currency. Open a Grey account and hold USD, EUR, or GBP.

Disclaimer: This article is for informational purposes only. All costs and details are estimates based on mid-2026 data. Verify current information before making decisions. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

FX futures trading: How currency futures work

•

•

2 min read

If you’ve read our FX trading beginner's guide, you already know that the forex market is primarily an over-the-counter market, with no central exchange and trades happening directly between participants. FX futures are different. They are exchange-traded, standardised contracts regulated by a recognised authority, with fixed contract sizes, set expiration dates, and publicly visible prices.

That distinction matters. It shapes everything from how you access the market to who regulates it to how much it costs to trade. This guide explains how FX futures work mechanically, how they compare to spot FX, and when they’re the right tool for a specific financial problem, and when they’re not.

What is FX futures trading?

FX futures trading is the buying and selling of standardised contracts that commit the holder to exchange a specified amount of one currency for another at a predetermined price on a specific future date.

Unlike spot FX, where currencies are bought and sold for immediate delivery (typically two business days), FX futures contracts have a defined expiration date in the future, typically quarterly: March, June, September, and December. You don’t have to hold the contract until expiration: most futures positions are closed before the contract expires by taking the opposite position.

The major FX futures markets are operated by CME Group, which runs the Chicago Mercantile Exchange (CME). The CME is one of the world’s largest derivatives exchanges and lists futures contracts on major currency pairs, including EUR/USD, GBP/USD, USD/JPY, AUD/USD, CAD/USD, CHF/USD, and MXN/USD, among others.

Because FX futures trade on a regulated exchange rather than over-the-counter, all participants see the same prices, all transactions are cleared through a central counterparty (the CME Clearing House), and the Commodity Futures Trading Commission (CFTC) in the US regulates the market. This centralised structure is one of the primary differences from spot FX.

Currency futures explained

Understanding the mechanics of a currency futures contract requires knowing its key specifications. Here is how the major CME EUR/USD futures contract works, using CME Group’s published contract specifications.

Contract size: Each EUR/USD futures contract represents 125,000 euros. This is the standardised unit. You cannot trade a partial contract: if you want exposure to EUR/USD, the minimum is one full contract worth 125,000 euros.

Tick size: The minimum price movement (tick) for EUR/USD futures is 0.00005 dollars per euro, which equals $6.25 per contract (125,000 × 0.00005). This is the smallest profit or loss increment per contract per tick.

Expiration months: EUR/USD futures expire quarterly: March, June, September, and December. The contract expiration date is the third Wednesday of the delivery month. The front-month contract (the one with the nearest expiration date) is typically the most liquid.

Settlement: CME currency futures are physically settled, meaning the actual exchange of currency can occur at expiration if a position is held open. In practice, most traders close their positions before expiration by taking the opposite trade, avoiding physical delivery.

Margin requirements: To trade FX futures, you don’t pay the full value of the contract upfront. You deposit an initial margin, a percentage of the contract’s notional value, as a performance bond. CME publishes initial and maintenance margin requirements. For EUR/USD futures, initial margin requirements vary but are typically between $2,000 and $3,000 per contract, depending on market volatility. This means you’re controlling a contract worth approximately $137,500 (at EUR/USD 1.10) with a margin of a few thousand dollars.

Mark-to-market: Unlike some financial instruments, futures positions are marked to market daily. At the end of each trading session, gains and losses are calculated based on the day’s settlement price and credited or debited from your margin account. If your account falls below the maintenance margin level, you receive a margin call and must deposit additional funds or have your position liquidated.

How to trade FX futures

Trading FX futures requires access to a futures broker and a funded margin account. The process differs from opening a standard retail forex account.

  1. Choose a CFTC-regulated futures broker
    FX futures must be traded through a registered Futures Commission Merchant (FCM). Check CFTC registration at cftc.gov before depositing funds with any broker. Major regulated FCMs include Interactive Brokers, TD Ameritrade Futures, and others. Verify that the broker specifically offers access to CME currency futures.
  2. Open a futures account and complete compliance requirements
    Futures accounts require more documentation than standard brokerage accounts. You’ll complete risk disclosures, provide financial information, and confirm you understand the risks of leveraged derivatives trading.
  3. Deposit initial margin
    Transfer funds to meet the initial margin requirement for the number of contracts you intend to trade. Remember that margin requirements can change based on market volatility: CME can raise them at any time.
  4. Place an order. Select the contract (e.g., EURO FX Futures, symbol 6E), the expiration month, the direction (buy or sell), and the order type (market, limit, or stop). Your broker’s platform will show the current bid and ask price for the contract.
  5. Monitor your position and margin
    Because futures are marked to market daily, your account balance will change each day based on price movement. Monitor your account to ensure it remains above the maintenance margin.
  6. Close or roll before expiration
    To exit a long position, sell the same number of contracts in the same expiration month. To exit a short position, buy. To maintain exposure beyond the current contract’s expiration, “roll” the position by closing the front-month contract and opening the next expiration month.

FX futures vs spot trading

The two primary ways to trade currency markets are FX futures (exchange-traded, standardised, regulated) and spot FX (over-the-counter, flexible, broker-dependent). Here’s how they compare:

Feature FX futures Spot FX (retail forex)
Trading venue Regulated exchange (CME, ICE) Over-the-counter, through brokers
Regulation CFTC (US), FCA (UK), other regulators Varies; some markets lightly regulated
Price transparency Full order book visible; same price for all participants Broker-set spread; prices can vary between brokers
Contract size Standardised (EUR/USD = 125,000 EUR) Flexible; can trade micro lots (1,000 units)
Minimum trade size One contract (typically large notional value) Much smaller; micro lots available
Settlement Physical delivery at expiration (usually closed before) Cash settled; no physical delivery
Leverage Yes; margin-based Yes; margin-based (often higher leverage available)
Expiration Quarterly expiration dates No expiration; positions held indefinitely
Counterparty risk Cleared by exchange (low; exchange guarantees trades) Counterparty is the broker (higher risk with unregulated brokers)
Transaction costs Commission per contract plus bid-ask spread Spread only (plus sometimes swap/overnight fees)
Who uses it Institutional hedgers, professional traders Retail traders, smaller hedgers
Access Requires futures broker account Retail forex broker account

‍

The key practical differences: FX futures offer greater regulatory protection and price transparency, but the standardised contract sizes make them less accessible for small-volume traders. Spot FX offers more flexibility on position size, but with variable broker quality and less regulatory oversight in some jurisdictions.

Hedging with FX futures

One of the primary legitimate uses of FX futures, beyond speculation, is hedging: locking in an exchange rate for a future transaction to protect against adverse currency movement.

Worked example: a UK exporter hedging a USD receivable

A UK manufacturer has agreed to sell £500,000 worth of equipment to a US buyer. The invoice is denominated in USD at today’s GBP/USD rate of 1.27, making the USD invoice amount approximately $635,000. Payment is due in three months.

The risk: if the pound strengthens against the dollar (GBP/USD rises) over those three months, the $635,000 will convert to fewer pounds when received. At GBP/USD 1.35, for example, the same $635,000 would only convert to approximately £470,000, a loss of £30,000 versus today’s rate.

The hedge: the exporter sells GBP/USD futures contracts with an approximate notional value of $635,000. If GBP/USD rises to 1.35, the exporter’s futures position profits, offsetting the loss on the physical receivable. If GBP/USD falls (good news for the exporter), the futures position loses money, but that loss is offset by the better conversion rate on the physical USD received.

The hedge doesn’t make the exporter money. It removes the currency risk, allowing the business to plan based on a known effective exchange rate rather than an unknown future rate. This is what hedging is for.

Who uses FX futures to hedge:

Exporters and importers who invoice in foreign currencies, multinational companies consolidating overseas earnings, and fund managers with foreign currency exposure in their portfolios. For most of these users, the objective is risk reduction, not profit generation.

Risks of FX futures trading

The risks in FX futures are specific and worth naming precisely.

Leverage risk: A $3,000 margin controls a contract worth approximately $137,500. A 1% adverse move in EUR/USD costs approximately $1,375 per contract, nearly 50% of the initial margin. The same move in the favourable direction yields the same gain, but most traders focus on the asymmetry: losses can quickly exceed the initial deposit.

Margin calls: If the market moves against your position and your account balance falls below the maintenance margin level, your broker will issue a margin call: deposit more funds immediately or have your position closed at the current market price, potentially at a significant loss.

Expiration management: Futures contracts expire. If you’re not actively monitoring your position, a contract you intended to hold can expire without you realising it, resulting in automatic closing at the expiration settlement price or, for physically settled contracts, an obligation to deliver or receive currency.

Basis risk for hedgers: FX futures hedge currency risk but introduce basis risk: the risk that the futures price and the spot price don’t move perfectly in tandem. For most major currency pairs, basis risk is small, but it exists and means a futures hedge is rarely a perfect offset.

Liquidity risk in less active contracts: Front-month contracts for major pairs (EUR/USD, GBP/USD, USD/JPY) are highly liquid. Further-out expiration months and minor pair contracts can be less liquid, meaning wider bid-ask spreads and potentially difficulty closing positions at the desired price.

A simpler way to manage real-world currency exposure

FX futures are a sophisticated tool designed primarily for institutional hedgers and experienced traders who need to manage specific, quantifiable currency exposures. For most freelancers, remote workers, expats, and small business owners, the practical currency problem is different: receiving income in one currency, holding it efficiently, and converting at a fair rate when needed.

That doesn’t require a futures account. It requires a multi-currency account with a competitive conversion rate.

Grey lets you hold balances in USD, EUR, and GBP, receive payments from international clients through local payment rails (ACH for USD, SEPA for EUR, Faster Payments for GBP), and convert currencies at mid-market rates with Grey at a conversion fee of 1%, capped at $6. The conversion rate is shown before you confirm; there’s no expiration date to manage, no margin calls, and no leverage amplifying your exposure.

For someone who needs to hold USD earned from US clients and convert it to GBP or local currency at an appropriate time, opening a multi-currency account with Grey is a more practical approach than establishing a futures hedging programme. FX futures are the right tool for managing large, quantifiable, time-specific currency exposures. For everyday multi-currency financial management, a Grey account is more practical.
Download the Grey app today to begin.

Frequently asked questions

What is the minimum to trade FX futures?

The minimum to trade FX futures is the initial margin requirement for one contract, plus enough buffer to avoid an immediate margin call if the market moves against you. For EUR/USD futures on the CME, initial margin requirements are typically $2,000 to $3,000 per contract, but this varies with market volatility and can be raised by the exchange at any time. In practice, most experienced futures traders maintain significantly more than the minimum margin in their account to absorb adverse moves without being forced out of a position.

How are FX futures different from forex spot trading?

FX futures are standardised contracts traded on regulated exchanges like the CME, with fixed contract sizes, quarterly expiration dates, and prices visible to all participants equally. Spot forex is traded over-the-counter through brokers, with flexible position sizes, no expiration dates, and prices set by the broker. Futures offer greater regulatory oversight and price transparency but require larger minimum positions. Spot forex is more accessible to retail traders, but broker quality and regulatory protection vary by jurisdiction.

Are FX futures suitable for beginners?

No. FX futures involve leverage, daily mark-to-market settlement, contract expiration management, and margin call risk. The standardised contract sizes mean a single EUR/USD futures contract controls 125,000 euros, which represents significant notional exposure for a beginning trader. Beginners who want to understand currency markets should start with educational reading rather than live trading, practice on simulated accounts before risking capital, and understand leverage mechanics fully before entering any leveraged position. The FX trading beginner's guide covers foundational concepts for those starting from scratch.

What is the contract size for EUR/USD futures?

One EUR/USD futures contract on the CME represents 125,000 euros. At an exchange rate of EUR/USD 1.10, one contract has a notional value of approximately $137,500. The minimum price move (tick) is 0.00005, worth $6.25 per contract. CME also offers E-micro EUR/USD futures contracts at one-tenth the size (12,500 euros per contract), which lowers the capital required per contract and may be more accessible for smaller traders.

When do FX futures expire?

CME currency futures expire quarterly: in March, June, September, and December. The specific expiration date is the third Wednesday of the delivery month, though the last trading day is typically the Monday before that Wednesday. Most traders close their positions before expiration to avoid the settlement process. Those who want to maintain exposure beyond the front-month contract “roll” their position by closing the expiring contract and opening the next quarterly contract.

Is Grey an alternative to FX futures for hedging small businesses?

For small businesses with straightforward multi-currency needs, Grey addresses the practical problem more simply than futures contracts do. A Grey multi-currency account lets you hold USD, EUR, and GBP balances, receive payments from international clients at low cost, and convert at a transparent rate. This is effective for managing the timing of currency conversion and avoiding forced conversion at poor bank rates, which covers the currency exposure most small businesses actually face. FX futures are appropriate when a business has a specific, large, time-defined currency exposure it needs to hedge precisely, such as a confirmed export contract in a foreign currency with a known settlement date. For most small businesses, that level of complexity and capital commitment isn’t justified.

Convert currencies with Grey

Arrow (up)

Back to top