<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/fbar-filing-guide#article","headline":"FBAR filing: What international freelancers and expats must know","description":"FBAR filing is required for US persons with foreign accounts over $10,000. Learn the deadline, who must file, penalties, and how to submit. File on time today.","inLanguage":"en","url":"https://grey.co/blog/fbar-filing-guide","mainEntityOfPage":{"@id":"https://grey.co/blog/fbar-filing-guide#webpage"},"datePublished":"2026-07-27T21:32:26.262Z","dateModified":"2026-07-30T09:00:00+01:00","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/fbar-filing-guide#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a67ce52672859c0bc89d32e_FBAR%20Filing%20What%20International%20Freelancers%20and%20Expats%20Must%20Know-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a67ce52672859c0bc89d32e_FBAR%20Filing%20What%20International%20Freelancers%20and%20Expats%20Must%20Know-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/fbar-filing-guide#webpage","url":"https://grey.co/blog/fbar-filing-guide","name":"FBAR Filing: Requirements, Deadline and How to File | Grey","description":"FBAR filing is required for US persons with foreign accounts over $10,000. Learn the deadline, who must file, penalties, and how to submit. File on time today.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/fbar-filing-guide#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/fbar-filing-guide#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/fbar-filing-guide#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"FBAR filing: What international freelancers and expats must know","item":"https://grey.co/blog/fbar-filing-guide"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/fbar-filing-guide#faq","mainEntity":[{"@type":"Question","name":"What is the FBAR threshold?","acceptedAnswer":{"@type":"Answer","text":"You must generally file an FBAR if the combined value of all your foreign financial accounts exceeds $10,000 at any point during the calendar year. It doesn't matter if no single account reaches $10,000; the rule looks at the highest aggregate balance across all reportable foreign accounts."}},{"@type":"Question","name":"Do I need to file an FBAR every year?","acceptedAnswer":{"@type":"Answer","text":"Only if you meet the filing threshold for that calendar year. If your reportable foreign financial accounts never exceed an aggregate value of $10,000, you generally don't need to file. Review your account balances annually, as your filing obligation can change from year to year."}},{"@type":"Question","name":"Are joint accounts reportable on an FBAR?","acceptedAnswer":{"@type":"Answer","text":"Yes. Jointly owned foreign financial accounts are generally reportable if you're required to file an FBAR. When determining whether you've crossed the reporting threshold, the entire value of the joint account is usually considered, not just the portion you believe belongs to you."}},{"@type":"Question","name":"What if I missed an FBAR filing?","acceptedAnswer":{"@type":"Answer","text":"Don't ignore it. If your failure to file was unintentional, you may be able to correct the issue through the IRS Streamlined Filing Compliance Procedures or another available relief programme. Acting quickly is usually far better than waiting for the omission to be discovered."}},{"@type":"Question","name":"Is a Grey account reportable on an FBAR?","acceptedAnswer":{"@type":"Answer","text":"It depends. The reporting requirement is based on where the underlying financial account is held and whether it qualifies as a foreign financial account under FBAR rules. If you're unsure, review your account details and consult a qualified U.S. CPA or tax adviser."}},{"@type":"Question","name":"Where do I file an FBAR?","acceptedAnswer":{"@type":"Answer","text":"FBARs are filed electronically through FinCEN's BSA E-Filing System, not with your federal tax return. The required form is FinCEN Form 114. Once submitted, keep the confirmation and supporting records for your personal files."}}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/fbar-filing-guide#terms","name":"FBAR filing: What international freelancers and expats must know glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"FBAR","description":"As more Americans began opening foreign bank accounts for work, investment and international business, governments faced a growing challenge: ensuring overseas accounts weren't being used to hide money or evade financial reporting. In response, the Bank Secrecy Act of 1970 introduced the Foreign Bank Account Report (FBAR), creating a reporting system that improves transparency without preventing people from banking abroad. The requirement has become increasingly relevant as freelancers, digital nomads and expats manage finances across multiple countries.","inDefinedTermSet":{"@id":"https://grey.co/blog/fbar-filing-guide#terms"}},{"@type":"DefinedTerm","name":"penalties for not filing an FBAR","description":"Failing to file an FBAR can be expensive, but the consequences depend on whether the violation was accidental or intentional. Understanding the different penalties and the options for correcting past mistakes can help you respond appropriately.","inDefinedTermSet":{"@id":"https://grey.co/blog/fbar-filing-guide#terms"}},{"@type":"DefinedTerm","name":"FBAR (Report of Foreign Bank and Financial Accounts)","description":"FBAR (Report of Foreign Bank and Financial Accounts) is a US filing requirement for any US person whose foreign financial accounts had an aggregate value over $10,000 at any point during the calendar year.","inDefinedTermSet":{"@id":"https://grey.co/blog/fbar-filing-guide#terms"}}]}] </script>

FBAR filing: What international freelancers and expats must know

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Remote work and global banking have made it easier than ever to live in one country, earn money in another and hold funds across multiple financial accounts. For millions of U.S. citizens, permanent residents and other U.S. persons living or working abroad, maintaining foreign bank accounts has become part of everyday life rather than an exception.

What many people don't realise is that having a foreign account may trigger a U.S. reporting obligation, even if no tax is owed. The Foreign Bank Account Report (FBAR) applies when the combined value of your foreign financial accounts exceeds $10,000 at any point during the calendar year. It is a disclosure requirement, not a tax, but failing to file can lead to significant penalties.

Whether you're a freelancer receiving international payments, an expat managing local finances or an investor with overseas accounts, understanding the FBAR rules is essential to staying compliant and avoiding costly mistakes.

What is FBAR?

As more Americans began opening foreign bank accounts for work, investment and international business, governments faced a growing challenge: ensuring overseas accounts weren't being used to hide money or evade financial reporting. In response, the Bank Secrecy Act of 1970 introduced the Foreign Bank Account Report (FBAR), creating a reporting system that improves transparency without preventing people from banking abroad. The requirement has become increasingly relevant as freelancers, digital nomads and expats manage finances across multiple countries.

FBAR (Report of Foreign Bank and Financial Accounts) is a US filing requirement for any US person whose foreign financial accounts had an aggregate value over $10,000 at any point during the calendar year. The annual deadline is 15 April with an automatic extension to 15 October. FBAR is filed electronically through FinCEN Form 114, separately from your tax return.

Also read: How to handle foreign income taxes as a remote worker

Who must file an FBAR? Who needs to file an FBAR?

The FBAR rules don't apply only to people living in the United States. They also cover many Americans living abroad who use foreign bank accounts for everyday banking, freelance income or investments. In general, you must file an FBAR if you are a U.S. person, including a U.S. citizen, Green Card holder or resident under U.S. tax rules, and the combined value of all your foreign financial accounts exceeds $10,000 at any point during the calendar year.

The keyword is aggregate. You don't need a single account with more than $10,000. Instead, FinCEN considers the total value of all qualifying foreign financial accounts. These include savings accounts, current accounts, securities accounts, brokerage accounts and certain foreign pension or investment accounts. Even if each account holds only a few thousand dollars, you may still have an FBAR filing obligation.

For example, a freelancer with $4,000 in a UK account, $3,500 in a EUR account and $3,000 in another foreign account reaches $10,500 in total. Because the combined balance exceeded the threshold, that person would generally be required to file an FBAR.

Read also: Navigating forex regulations as a freelancer in Africa

Which foreign accounts must expats report?

Living outside the United States doesn't automatically exempt you from FBAR rules. Understanding which foreign accounts count and which don't can help you stay compliant and avoid unnecessary reporting errors.

  • Foreign banks: Savings, current, and other deposit accounts held with foreign financial institutions generally count toward the FBAR threshold, even if they're used only for everyday banking.
  • Brokerage accounts: Foreign brokerage, securities and investment accounts are typically reportable if you own them or have signature authority over the funds during the calendar year.
  • Pension accounts: Certain foreign pension and retirement accounts may also be reportable, depending on how the account is structured and the applicable U.S. reporting rules.
  • Joint accounts: Jointly owned foreign accounts are generally included when calculating your filing obligation. The full account balance counts toward the aggregate $10,000 reporting threshold.
  • Signature authority: You may need to file even if you don't own the account but can control or authorise transactions, such as an employer's foreign business account.
  • Excluded accounts: U.S.-based bank accounts and financial accounts held with domestic institutions are generally excluded because the FBAR applies only to qualifying foreign financial accounts.

When is the FBAR filing deadline?

Unlike many tax forms that require you to request extra time, the FBAR follows a simpler process. The standard filing deadline is 15 April each year, covering foreign financial accounts from the previous calendar year. If you miss that date, you automatically receive an extension until October 15. There is no separate extension form to complete or submit, making the FBAR one of the few U.S. reporting requirements with an automatic filing extension.

Although the extension provides extra time, it should not be treated as an excuse to delay unnecessarily. Filing after 15 October without a valid reason can expose you to penalties, particularly if the failure is considered wilful. Even non-wilful violations may result in financial consequences, although the U.S. government offers procedures that can help taxpayers correct genuine mistakes in certain circumstances. Filing on time, keeping accurate records and reviewing your foreign accounts each year remain the safest way to stay compliant.

How to file an FBAR: Step-by-step guide

Filing an FBAR is completed online through the BSA E-Filing System. Preparing the right information before you begin speeds up the process and helps you avoid reporting errors.

  • Collect records: Gather the name of each foreign financial institution, account number, account type and the highest account balance reached during the calendar year in U.S. dollars.
  • Access portal: Visit the BSA E-Filing System, where FinCEN's electronic Report of Foreign Bank and Financial Accounts (FinCEN Form 114) is completed and submitted.
  • Enter details: Complete Form 114 by providing your personal information, foreign account details and the maximum value of every reportable account held during the reporting year.
  • Review information: Check every entry carefully before submitting. Incorrect account numbers, balances or institution names can delay processing and may require you to file a corrected report later.
  • Submit report: File the completed FBAR electronically and save the confirmation for your records. Keeping copies of supporting documents is recommended if questions arise in the future.

FBAR penalties for non-compliance

What are the penalties for not filing an FBAR?

Failing to file an FBAR can be expensive, but the consequences depend on whether the violation was accidental or intentional. Understanding the different penalties and the options for correcting past mistakes can help you respond appropriately.

Civil penalties

Non-willful FBAR violations can attract civil penalties of up to $10,000 per violation, depending on the facts and applicable law. Wilful violations are significantly more severe, with penalties of the greater of $100,000 or 50% of the balance in the unreported foreign account at the time of the violation. These penalties apply even if no additional U.S. tax is owed.

Criminal penalties

In cases involving intentional concealment, fraud or other criminal conduct, the U.S. government may pursue criminal prosecution. Convictions can result in substantial fines, imprisonment or both, particularly where foreign accounts were deliberately used to hide income or assets from U.S. authorities.

How to catch up

If you failed to file an FBAR but your mistake was non-wilful, you may be able to correct it through the IRS Streamlined Filing Compliance Procedures or other available relief programmes. Acting early and voluntarily generally provides a better outcome than waiting for the issue to be discovered during an investigation.

FBAR vs. FATCA: What's the difference?

  • FBAR and FATCA are often confused because both require U.S. taxpayers to report foreign financial assets. However, they are separate reporting obligations with different filing agencies, thresholds and forms. Filing one does not replace the other, and many taxpayers may need to file both.
Feature FBAR (FinCEN Form 114) FATCA (IRS Form 8938)
Administered by FinCEN (U.S. Treasury) Internal Revenue Service (IRS)
Purpose Reports foreign financial accounts Reports specified foreign financial assets
Where to file Through the BSA E-Filing System With your annual federal tax return
Reporting threshold More than $10,000 combined in foreign financial accounts at any point during the year Starts at $50,000 for many U.S.-based single filers, with higher thresholds depending on filing status and residency
What is reported Foreign bank and financial accounts A broader range of foreign financial assets, including some assets not covered by the FBAR
Can both apply? Yes Yes. Filing Form 8938 does not remove your FBAR obligation if you also meet the FBAR requirements.

Do Grey accounts count toward your FBAR filing?

Cross-border banking has made it possible to receive payments, hold multiple currencies and work with clients worldwide without opening a traditional overseas bank account. As more freelancers, remote workers and expats use platforms like Grey, one question comes up repeatedly: Do these accounts need to be reported on an FBAR? The answer isn't based on the brand you use; it depends on where the underlying financial account is legally held and whether it meets the FBAR reporting rules.

For that reason, there isn't a one-size-fits-all answer. Your FBAR obligation depends on your individual circumstances and the jurisdiction of the underlying account. This guide provides general educational information only and should not be treated as tax or legal advice. If you're uncertain whether your Grey account or any other foreign financial account must be reported, speak with a qualified U.S. CPA or tax adviser who can assess your specific situation and help you stay compliant.

Frequently asked questions

What is the FBAR threshold?

You must generally file an FBAR if the combined value of all your foreign financial accounts exceeds $10,000 at any point during the calendar year. It doesn't matter if no single account reaches $10,000; the rule looks at the highest aggregate balance across all reportable foreign accounts.

Do I need to file an FBAR every year?

Only if you meet the filing threshold for that calendar year. If your reportable foreign financial accounts never exceed an aggregate value of $10,000, you generally don't need to file. Review your account balances annually, as your filing obligation can change from year to year.

Are joint accounts reportable on an FBAR?

Yes. Jointly owned foreign financial accounts are generally reportable if you're required to file an FBAR. When determining whether you've crossed the reporting threshold, the entire value of the joint account is usually considered, not just the portion you believe belongs to you.

What if I missed an FBAR filing?

Don't ignore it. If your failure to file was unintentional, you may be able to correct the issue through the IRS Streamlined Filing Compliance Procedures or another available relief programme. Acting quickly is usually far better than waiting for the omission to be discovered.

Is a Grey account reportable on an FBAR?

It depends. The reporting requirement is based on where the underlying financial account is held and whether it qualifies as a foreign financial account under FBAR rules. If you're unsure, review your account details and consult a qualified U.S. CPA or tax adviser.

Where do I file an FBAR?

FBARs are filed electronically through FinCEN's BSA E-Filing System, not with your federal tax return. The required form is FinCEN Form 114. Once submitted, keep the confirmation and supporting records for your personal files.

Staying compliant with FBAR requirements is just as important as managing your money wisely. As international work and cross-border banking become more common, understanding your reporting obligations can help you avoid unnecessary penalties. For seamless global payments, open a Grey account or download the app to receive and manage USD, GBP and EUR with confidence.

Last updated:

October 6, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Saving vs investing for short-term goals: Which is right?

•

•

2 min read

Saving and investing can both help you reach your financial goals, but choosing the wrong approach could leave you short when you need the money. The difference comes down to when you plan to use it and how much risk you can afford to take.

Saving is usually the better choice for short-term goals, such as paying for a holiday, covering moving expenses, or building an emergency fund within the next one to three years. Your money stays accessible, and you avoid the risk of losing part of it to a market downturn just before your deadline.

Investing may be more suitable for goals that are at least five years away, giving your money more time to recover from market fluctuations and potentially grow.

But how do you decide what to set aside and where to put it? Understanding how much you should invest each month starts with your income, expenses, financial priorities, and timeline. The right choice depends on your goal, not just the returns you hope to earn.

Saving vs investing: The key differences

Saving means putting money aside in a safe, accessible place, such as a savings account. It works best for money you may need soon, whether for rent, school fees, a holiday, or an unexpected bill. The main benefit is that your money is less exposed to market losses, and you can usually withdraw it when needed. However, savings may grow slowly, especially when inflation reduces what your money can buy.

Investing means putting money into assets such as stocks, bonds, or mutual funds to grow your wealth over time. Unlike savings, investments can lose value, particularly in the short term. You may earn higher returns, but there is no guarantee. Risk is the key difference: savings balances are generally more stable, while investment values can rise or fall. Access also varies; some investments take days to sell, and others may charge withdrawal fees or have restrictions.

Your timeline should guide your choice. For goals within one to three years, saving is generally safer. For longer-term goals, investing may help your money grow. Before investing, build an emergency fund first so unexpected expenses do not force you to sell investments at a loss.

How to invest for short-term goals (and when not to)

Imagine you are saving for a wedding next year, a car in 18 months, or your tuition fees in two years. You know exactly when you need the money, so the last thing you want is to discover that your investment has lost value just before payment is due.

That is why short-term goals usually favour saving over investing. The stock market can rise or fall within weeks, and you may not have enough time to recover from a loss. Keeping your money in a savings account helps protect it while making it available when you need it. You may earn less, but you have more certainty about your balance.

If you want your money to earn some interest, consider lower-risk options such as high-yield savings accounts, money market funds, or short-term government Treasury bills. Each comes with different risks, access rules, and possible fees, so check the terms before choosing.

Avoid putting money you cannot afford to lose into volatile investments for a deadline that is only months away. The goal is to have your money ready on time, not to chase the highest return.

How much of your income should you invest?

Deciding how much to invest each month can feel difficult when rent, groceries, bills, and other expenses already take a big chunk of your income. The good news is that you do not need a large salary to start investing. What matters is choosing an amount you can afford consistently without struggling to cover your basic needs.

A common rule of thumb is to invest 10% to 15% of your income, especially when you have covered essential expenses and built an emergency fund. However, this is a guide, not a strict rule. Start with a smaller amount if money is tight, and increase it as your income grows.

For example, imagine you earn $3,000 a month after tax. Investing 10% means putting aside $300 monthly. You could use the remaining $2,700 for rent, food, bills, savings, and other expenses. If $300 feels too high, start with $100 and build gradually.

Before deciding what to invest, work out how much to save each payday for emergencies and upcoming expenses. Invest only money you can leave untouched for the time your goal requires.

Where to keep your short-term money

Short-term savings need a home where your money stays accessible when you need it. For example, if you are saving for a holiday in six months or a laptop next year, you do not want to risk losing that money in the stock market just before making your purchase. A savings account or another low-risk option can help you keep your money available. Before choosing, check the interest rate, fees, and withdrawal conditions.

You should also consider the currency you save in. If you plan to pay for a trip, course, or online purchase in US dollars, keeping your savings in your local currency could leave you short if the exchange rate changes. Holding USD may help you prepare for dollar expenses, although exchange rates can move in either direction.

Grey Pouch gives you a way to set money aside for specific goals. You can keep short-term money in a Pouch goal to organise your savings, while holding USD may help you protect your money from currency swings when saving for expenses priced in dollars. Check the applicable fees, terms, and access conditions before deciding.

Frequently asked questions

1. Should I save or invest?

Save when you need your money within the next few years or cannot afford to lose it. Investing is generally better for long-term goals because your money has more time to recover from market losses. Your timeline, financial situation, and comfort with risk should guide your decision.

2. How much should I invest each month?

A common starting point is 10% to 15% of your monthly income, but you do not have to meet this target immediately. Cover essential expenses, manage expensive debt, and build an emergency fund first. Start with an affordable amount and increase it as your income grows.

3. Is it worth investing for two years?

Investing for two years can be risky because market prices may fall just before you need your money. For goals with a fixed deadline, savings accounts or suitable low-risk options may be better. Choose investments only when you understand the risks and can handle potential losses.

4. What is the safest place to keep short-term savings?

A savings account with a regulated financial institution is often suitable for short-term money. Depending on your country, deposit protection may apply within certain limits. Check withdrawal conditions, fees, and interest rates to ensure your money remains accessible when you need it.

5. Can I save and invest at the same time?

Yes, you can save and invest simultaneously. Keep savings for emergencies, upcoming bills, and goals within the next few years. Invest money intended for longer-term goals, such as retirement. This approach helps you prepare for immediate expenses while giving some of your money time to grow.

6. Should I save in USD or my local currency?

Choose based on what you plan to spend the money on. Local currency may suit everyday expenses, while USD savings may help prepare for dollar-priced costs, such as international travel or tuition. Exchange rates can move both ways, so consider conversion fees and when you will need the money.

Keep short-term goal money safe and separate. Open a Grey account, hold it in USD, and track it in a Pouch.
What is a W-2 form? How to read yours

•

•

2 min read

Tax season can be confusing, especially when you are trying to figure out how much you earned and how much tax you paid. Your W-2 form helps you understand both. What is a W-2? It is a US tax form your employer sends you each year. It shows your total earnings and the taxes taken out of your pay. You need it to file your income tax return.

Your employer generally sends your W-2 by January 31 for the previous year. The form has different boxes showing your wages, taxes, and other details about your pay.

If you work as an employee, you will usually receive a W-2. Independent contractors generally receive a 1099 instead. Knowing what a W-2 means and how to read yours can help you file your taxes correctly. Let’s look at what the boxes on your form mean.

What is a W-2 form?

A W-2 form shows how much you earned from your job during the year and how much tax your employer took out of your pay. You need it to file your US income tax return and report your earnings correctly.

Your employer prepares and sends you the form. If you worked for multiple employers during the year, each one should give you a separate W-2. Check your name, wages, and tax details when it arrives to make sure everything is correct.

The deadline for employers to send W-2 forms is generally January 31 each year. The form covers the previous tax year, so your W-2 received in January 2027 will usually report your 2026 earnings.

A W-2 reports what you earned and the taxes withheld. A W-4, on the other hand, helps your employer determine how much federal income tax to withhold from your paycheck. Understanding the difference between the two forms can help you manage your tax paperwork and avoid confusion when filing your return.

How to read your W-2 box by box

Your W-2 form contains several boxes that show your earnings and the taxes taken from your paycheck. Knowing what each box means helps you check your details before filing your tax return.

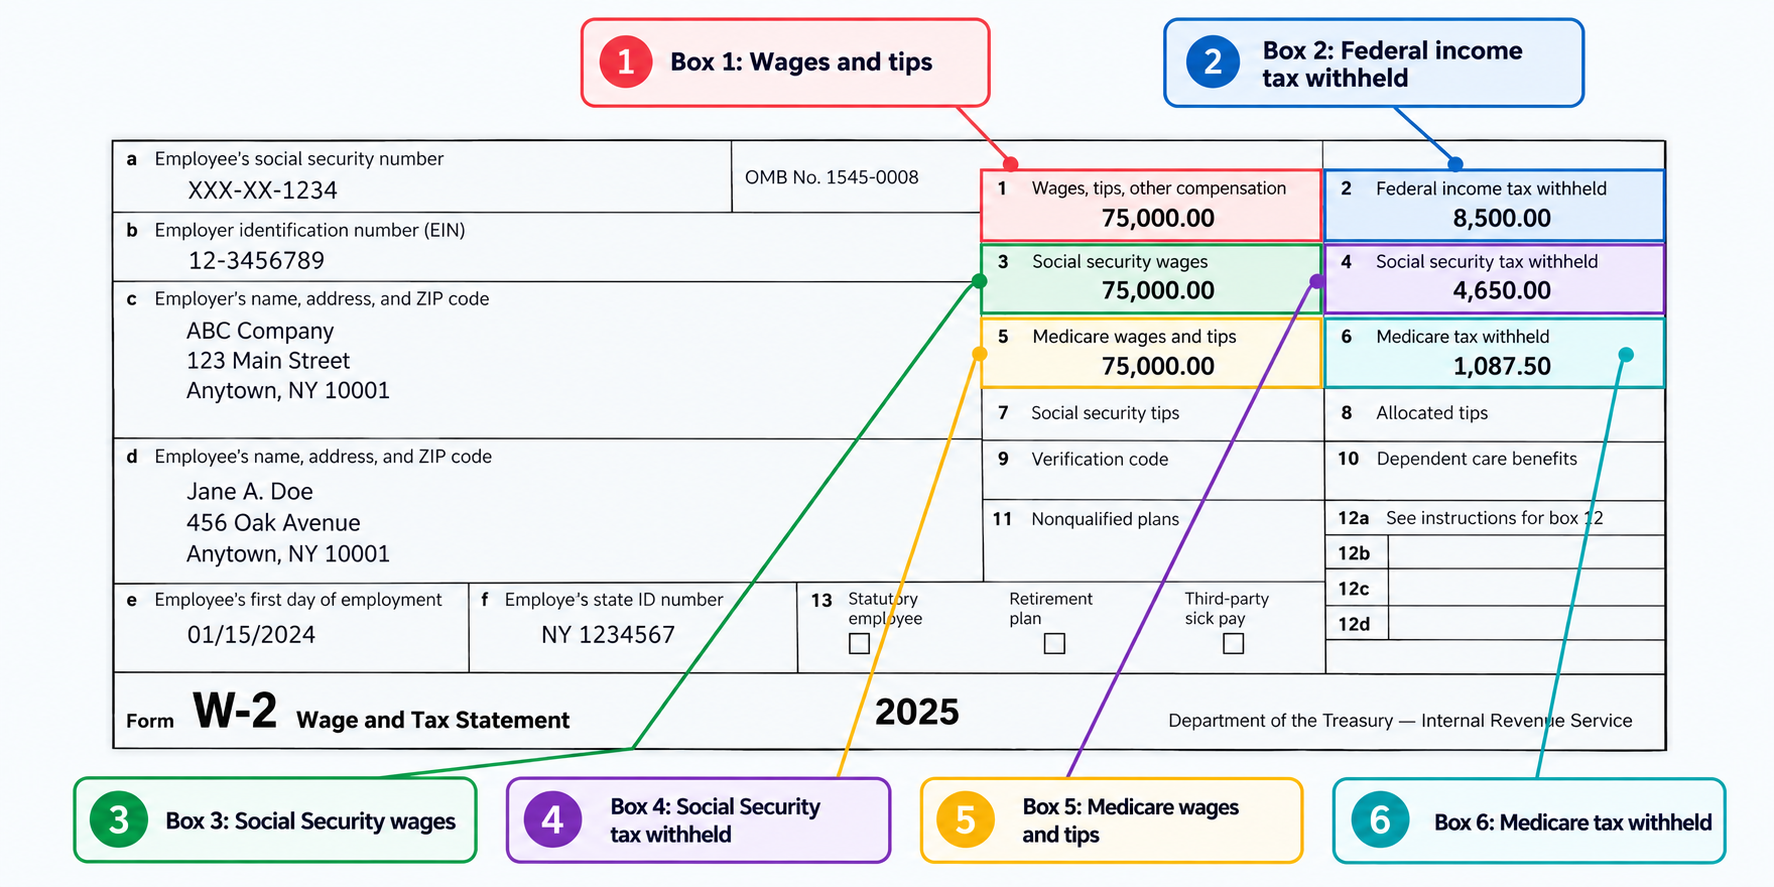
An annotated W-2 form with callouts on the wages, withholding, Social Security and Medicare boxes.
  • Box 1: Wages and tips. Shows the income subject to federal income tax.
  • Box 2: Federal income tax withheld. Shows how much federal income tax your employer took from your pay.
  • Box 3: Social Security wages. Shows the earnings subject to Social Security tax.
  • Box 4: Social Security tax withheld. Shows the Social Security tax deducted from your paycheck.
  • Box 5: Medicare wages and tips. Shows the earnings used to calculate Medicare tax.
  • Box 6: Medicare tax withheld. Shows the Medicare tax withheld from your pay.

These boxes help you understand your reported income and tax payments. Compare the figures with your pay records, and contact your employer if you notice any errors. Correct information helps you file your tax return accurately.

W-2 vs. 1099: What is the difference?

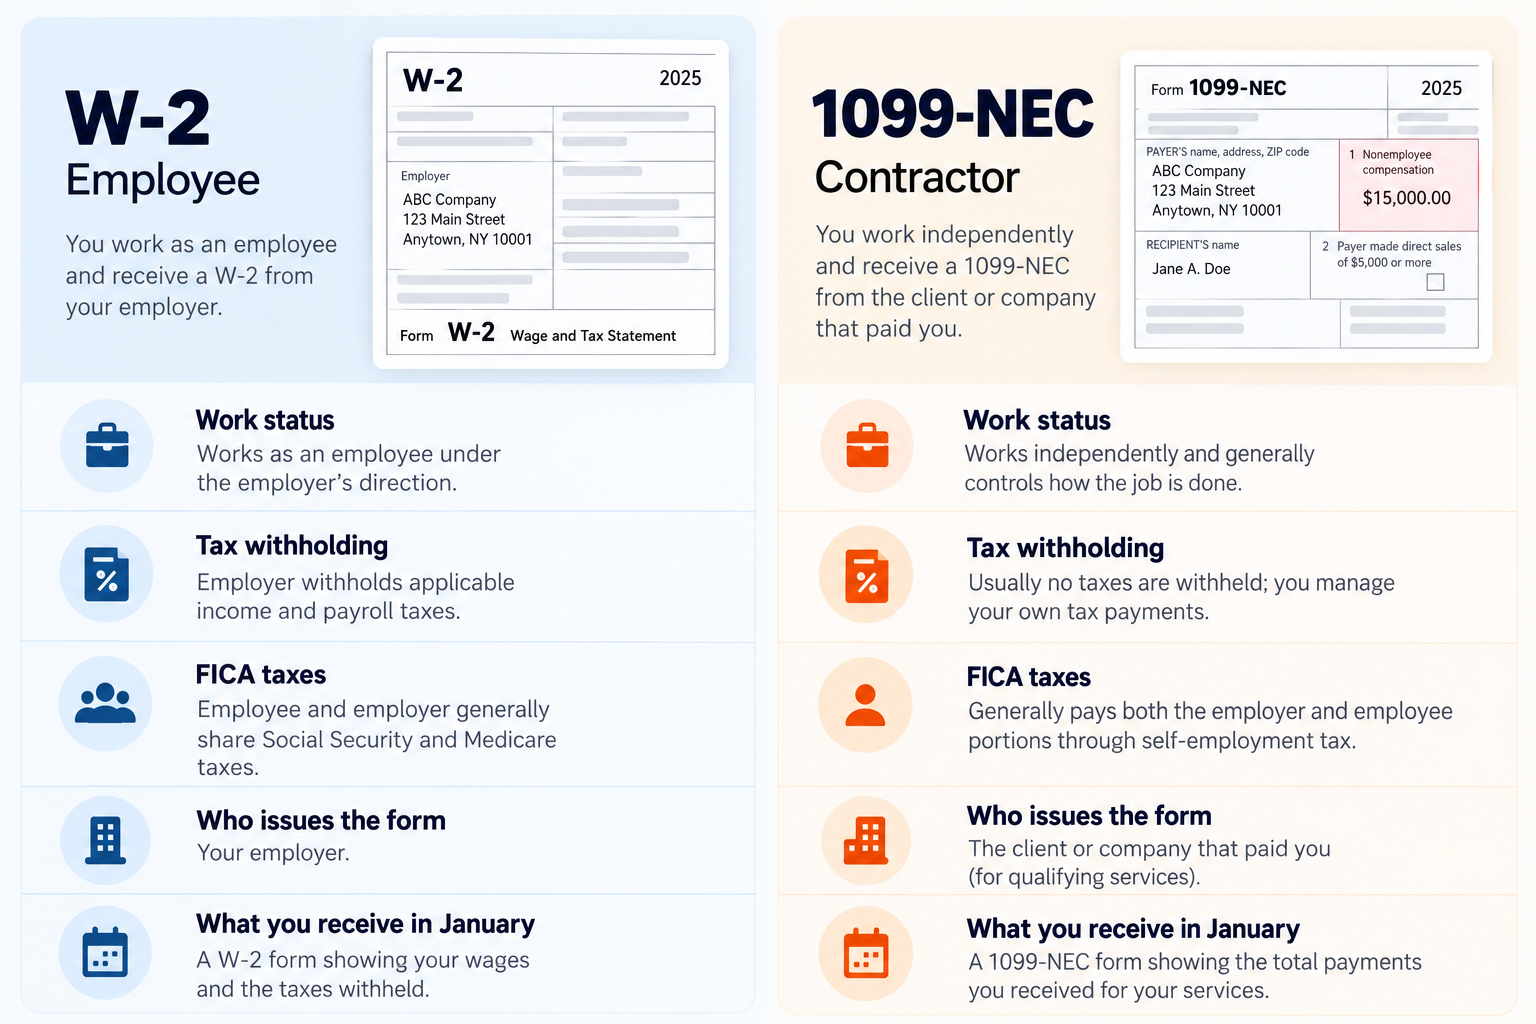
The main difference between a W-2 and a 1099-NEC is your work status and how you pay taxes. A W-2 is for employees, while a 1099-NEC is generally used to report payments to independent contractors. Understanding the difference between 1099 and W-2 can help you know which form applies to your work.

Comparison graphic showing the differences between a W-2 employee and a 1099 contractor.

Your classification affects how you handle taxes and other work responsibilities. If you are unsure whether you are an employee or an independent contractor, look at the nature of your working relationship, not just the form you receive.

What to do if your W-2 is wrong or missing

If your W-2 has the wrong income, tax details, or Social Security number, or you have not received it, do not ignore the problem. You need the correct information to file your tax return.

Contact your employer first: Explain what is wrong or ask when your missing W-2 will arrive. If your original form has an error, your employer can issue a corrected form called Form W-2c. Check the updated details before filing your taxes.

Contact the IRS if the problem continues: If your W-2 is still missing or has not been corrected by the end of February, call the IRS at 800-829-1040 for help. The IRS can contact your employer and explain your next steps.

What if the deadline is near: If you cannot get your W-2 in time to file, the IRS may direct you to use Form 4852, which serves as a substitute. Use your pay records to estimate your wages and taxes accurately. If you already filed using incorrect figures, you may need to submit an amended tax return.

Getting paid across borders

Getting paid by a US employer or client should not be difficult just because you live in another country. You still need a reliable way to receive your money, manage it in dollars, and use it where you live. This is where getting paid across borders becomes important, especially for freelancers, remote workers, and businesses working with international clients.

Grey helps you receive international payments through a foreign currency account. With a Grey USD account, you can share your account details with eligible US employers or clients to get paid from the US without relying on a traditional US bank account. You can then keep your money in dollars or convert it to your local currency when you need it.

To get started, you can open a USD account with Grey, complete identity verification, and check the available receiving options and fees for your location. This makes it easier to manage your international earnings from one place.

Frequently asked questions about the W-2 form

What is a W-2 form?

A W-2 form is an official US tax document that shows how much you earned from your employer during the year and how much tax was withheld from your pay. You use it to report your earnings and taxes when filing your annual income tax return.

When should I get my W-2?

Employers generally must send your W-2 by January 31 each year for the previous tax year. You may receive it by mail or through your employer’s online payroll portal. If it has not arrived by early February, contact your employer to confirm when it will be available.

How do I read a W-2?

Box 1 shows wages subject to federal income tax, while Box 2 shows federal income tax withheld. Boxes 3 and 4 cover Social Security wages and tax, while Boxes 5 and 6 show Medicare wages and tax withheld.

What is the difference between a W-2 and a 1099?

W-2 employees generally have income and payroll taxes withheld by their employers. 1099 contractors usually receive payments without tax withholding and must manage their own tax payments, including self-employment taxes when applicable.

What if my W-2 is wrong?

Contact your employer’s payroll department as soon as possible and explain the error. Ask them to issue a corrected form called Form W-2c. Check the corrected details carefully and use accurate information when filing your tax return.

What if I do not receive my W-2?

Contact your employer first to request your missing form. If it has not arrived by the end of February, call the IRS at 800-829-1040 for assistance. Keep your pay stubs handy to help estimate your earnings and taxes if needed.

USDC vs USDT: 11 major differences

•

•

2 min read

The rise of stablecoins has made it possible to hold and transfer digital dollars without relying on traditional bank transfers for every transaction. Two of the most widely used options are USDT (Tether) and USDC (USD Coin). Although both aim to maintain a value of $1 per token, they differ in several important ways that can affect how you use them.

Understanding USDT vs USDC starts with knowing who issues each stablecoin. Tether issues USDT, while Circle issues USDC. Both use reserves to support their dollar pegs, but their reserve disclosures, reporting practices, regulatory approaches, blockchain availability, and adoption differ.

USDT generally has a larger circulating supply and broad trading support, making it popular across crypto markets. USDC is known for its regular reserve attestations and emphasis on transparency and regulatory compliance.

These differences matter if you want to trade crypto, transfer money internationally, or hold digital dollars. This guide compares 11 major differences to help you understand how each stablecoin works and which may suit your needs.

What is the main difference between USDT and USDC?

The main differences between USDT and USDC are their issuer, reserve transparency, and adoption across crypto markets. USDT is issued by Tether, while USDC is issued by Circle. Both aim to maintain a value of $1 per token, but they differ in how they disclose their reserves, approach regulatory compliance, and support trading and transfers across blockchain networks.

USDT is widely used for crypto trading because of its large circulating supply and broad exchange support. USDC emphasises reserve transparency, with backing primarily in cash and short-term US Treasury securities.

Neither stablecoin is risk-free. Their value can temporarily move away from $1, and their availability, transaction costs, and protections depend on the platform and blockchain you use.

Feature USDT (Tether) USDC (USD Coin)
Issuer
Tether Circle
Dollar peg
Aims for $1 Aims for $1
Reserve composition Primarily US Treasury bills and other assets, including repurchase agreements and money market funds Cash and eligible cash-equivalent assets, including short-term US Treasuries and overnight Treasury-backed repurchase agreements
Reserve reporting
Independent quarterly attestations Monthly third-party reserve attestations
Market adoption
Generally broader global trading use Strong adoption among institutions and regulated financial services
Blockchain support
Multiple networks, including Tron and Ethereum Multiple networks, including Ethereum and Solana

‍

Circle publishes monthly third-party reserve assurances, while Tether also publishes independent reserve attestations. These are attestations, not full independent audits of all reserve holdings.

Which one should you choose?

  • USDT: May suit you if you prioritise exchange liquidity and broad trading-pair support.
  • USDC: May suit you if you prioritise published reserve disclosures and its institutional payment ecosystem.

How the reserves compare

When comparing USDT vs USDC, one of the biggest differences is how each stablecoin backs its dollar peg. USDC, issued by Circle, is backed by cash and short-term US Treasury securities held in its reserve structure. USDT, issued by Tether, once held significant amounts of commercial paper but has since shifted its reserves toward US Treasury bills and other assets.

Both issuers publish independent attestations to provide information about their reserves and liabilities. However, an attestation reflects the position at a specific point in time. It does not guarantee continuous backing, immediate access to every reserve asset, or protection against legal and liquidity problems during a sudden market sell-off.

Why does this matter to you? If you hold stablecoins to preserve dollar value or plan to convert them into cash, reserve quality and redemption access are important considerations. Before cashing out, learn how USDC to USD conversion works so you understand the process and what to consider when turning your stablecoins into dollars.

Transparency, audits, and regulation

When comparing USDT vs USDC, transparency and regulation can help you understand how each stablecoin manages its reserves and reports financial information. However, it is important to distinguish between an attestation and a full audit.

An attestation checks whether reported assets and liabilities match at a specific point in time. A full audit examines financial records, transactions, internal controls, and other relevant information over a defined period. Both provide useful information, but neither automatically guarantees that a stablecoin will maintain its dollar peg under every market condition.

Circle, the issuer of USDC, operates within applicable US regulatory frameworks, including state money transmission requirements. Tether is registered with FinCEN as a Money Services Business (MSB). However, MSB registration is not the same as federal approval or insurance of a stablecoin's reserves.

If you use stablecoins for international payments, consider their transparency, regulatory status, and availability across your preferred platforms. Understanding how USDC compares with other stablecoins for global transactions can help you weigh these factors before choosing a suitable option.

Network support and transaction costs

When comparing USDT vs USDC, the blockchain you choose can make a big difference in how much you pay to send money. Both stablecoins operate across multiple networks, but their availability varies. USDT is widely used on Tron and Ethereum, while USDC is available on Ethereum, Solana, Base, and other supported blockchains.

Transaction fees depend mainly on the network, its congestion, and the type of transaction, rather than the stablecoin itself. For example, sending USDC on Ethereum can cost several dollars during busy periods, while transferring USDC on Solana typically costs a fraction of a cent. Base can also offer low-cost transfers. Tron is a popular option for USDT transfers, often with different fees depending on your wallet and available network resources.

Network Typical fee level What it means for you
Ethereum Can be several dollars or more Costs can rise when the network is busy.
Solana Usually a fraction of a cent for a basic transfer A low-cost option for sending USDC.
Base Generally low Can make USDC transfers cheaper than Ethereum mainnet.
Tron Varies with account resources and wallet fees Commonly used for USDT transfers.

‍

Ethereum fees fluctuate with demand, while Solana's standard transaction fees are generally very low.

What should you choose? If you are sending USDC, compare Solana, Base, and Ethereum before confirming your transaction. Check the estimated fee displayed in your wallet or exchange, and make sure the recipient supports the same network. Also account for any withdrawal or service fees charged by your platform, as these are separate from blockchain fees.

Also read: USDC on Solana compared with Ethereum

Converting USDT and USDC into money in your bank account

To turn stablecoins into money you can spend through a bank account, you need a platform that converts cryptocurrency into traditional currency. One option is to use a crypto exchange such as Coinbase or Kraken, where supported. You can deposit USDT or USDC, sell your tokens for USD or another available currency, and withdraw the funds to a linked bank account.

Another option is to use an off-ramp service. Circle Mint, for example, supports eligible institutional customers converting USDC into USD. Access depends on your location and account eligibility.

Once your funds are converted, a multi-currency account can help you manage your dollars and international payments. Grey supports sending and receiving USDC and offers multi-currency financial services for eligible users. Depending on your account and location, this can help you manage USD alongside cross-border transactions without converting everything immediately into your local currency. Before transferring funds, check supported networks, conversion rates, fees, and withdrawal options to understand the full cost of moving your money.

Frequently asked questions

1. Is USDC safer than USDT?

USDC may appeal to users who prioritize reserve transparency and regular reporting, while USDT benefits from broad market adoption and liquidity. However, neither stablecoin is risk-free. Both depend on their issuers, reserve management, redemption arrangements, and market conditions. Compare their disclosures and consider your intended use before choosing either option.

2. Which stablecoin is more widely accepted?

USDT generally has broader adoption across global cryptocurrency exchanges and trading pairs, particularly in markets where stablecoins support everyday crypto trading. USDC is also widely supported and has strong adoption among institutions and payment platforms. Acceptance varies by exchange, wallet, blockchain network, and country, so check compatibility before transferring funds.

3. Can you swap USDT for USDC?

Yes, you can swap USDT for USDC through supported cryptocurrency exchanges and decentralized trading platforms. You typically deposit USDT, select USDC as the asset you want to receive, and confirm the transaction. Check the exchange rate, trading fees, network costs, and withdrawal options before completing your swap.

4. Do USDT and USDC ever lose the dollar peg?

Yes, both USDT and USDC can temporarily trade above or below $1. These deviations may occur during market volatility, liquidity shortages, or concerns about an issuer's reserves. Although both aim to maintain their dollar pegs, neither guarantees a constant market price. Check current market prices before buying or selling.

5. Which has lower transfer fees?

Neither USDT nor USDC always has lower transfer fees. Costs depend mainly on the blockchain network, network congestion, and any exchange or wallet charges. For example, transfers on Solana or Base can be inexpensive, while Ethereum fees may rise during busy periods. Compare the estimated total cost before sending.

6. How do you turn a stablecoin into cash?

You can convert USDT or USDC into cash by selling it through a supported cryptocurrency exchange and withdrawing the proceeds to your bank account. Alternatively, eligible services may offer stablecoin conversion and payment options. Check your country's availability, supported networks, exchange rates, withdrawal fees, and identity verification requirements before proceeding.

How to earn yield on USDC: Best options in 2026

•

•

2 min read

USDC is a stablecoin designed to maintain a value close to one US dollar, making it an option for people who want to hold digital dollars without the usual price swings associated with cryptocurrencies like Bitcoin. However, holding USDC in a wallet does not automatically generate interest. To earn a return, you need to invest your holdings in a programme or platform that pays a yield.

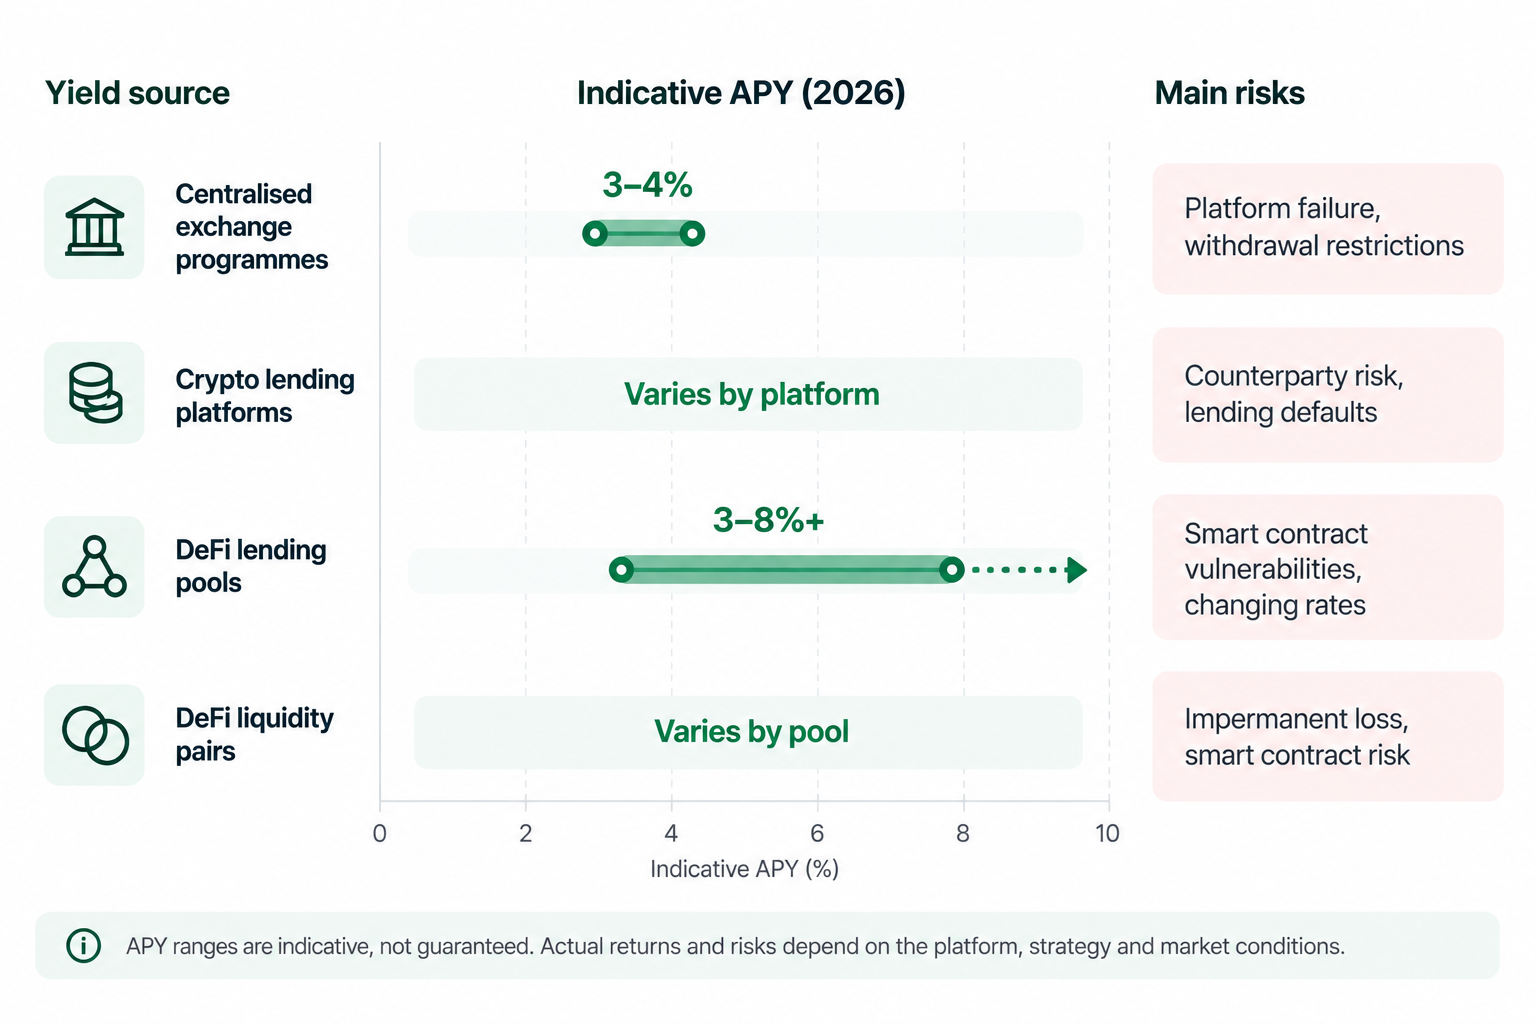
USDC itself pays no interest. Yield comes from lending it out through a centralised exchange programme, a crypto lending platform, or a DeFi protocol such as a lending pool or liquidity pair. Rates ranged from about 2 to 8% APY in 2026, depending on the platform, strategy and market conditions.

Each option comes with different levels of risk, access requirements and withdrawal conditions. Before choosing where to earn yield, understand how returns are generated, whether your funds are protected, and what could happen if a platform fails or a smart contract is exploited.

Does USDC pay interest on its own?

No, holding USDC in a crypto wallet does not earn interest by itself. USDC is a stablecoin designed to maintain a value close to one US dollar, but simply owning it does not generate additional income. Whether it sits in a personal wallet or an exchange account, your balance remains unchanged unless you receive additional USDC through another transaction or service.

To earn yield, you need to use a separate financial product built on top of USDC. These products generate returns through activities such as lending your stablecoins to borrowers, supplying liquidity to decentralised finance (DeFi) protocols, or participating in yield programmes offered by cryptocurrency exchanges.

Each option works differently and carries its own risks. A lending platform may pay interest from borrower repayments, while a DeFi protocol may distribute fees or lending revenue to participants. Centralised exchanges may offer promotional rates or rewards under specific conditions.

Before depositing USDC into any yield product, understand how returns are generated, what fees apply, and whether you can withdraw your funds when needed. Yield is never guaranteed.

Also read: How USDC compares with USDT

Centralised exchange and lending platforms

Centralised exchanges and crypto lending platforms allow you to earn yield by depositing your USDC into programmes that generate returns. Exchange earn programmes may lend your USDC to borrowers or use other permitted strategies to generate revenue, sharing a portion of the earnings with you.

Crypto lending platforms work similarly, connecting you with borrowers and paying interest on the funds you supply.
The annual percentage yield (APY) you receive depends on the platform, market demand, lending activity and programme conditions. Rates can change, and promotional offers may have limits or eligibility requirements.

Custody is another important consideration. When you deposit USDC into a centralised platform, the platform typically controls your assets rather than you holding the private keys directly. It may lend, transfer or otherwise use your deposited coins according to its terms.

This exposes you to counterparty risk. If the platform becomes insolvent, freezes withdrawals or suffers a hack, you may struggle to access your funds or lose them entirely. Before depositing your USDC, review the withdrawal terms, fees, security measures and how the platform uses your assets.

DeFi options: lending pools and liquidity pairs

Decentralised finance (DeFi) offers another way to earn yield on USDC without relying on a traditional financial intermediary. Two common options are lending pools and liquidity pairs, each generating returns in different ways.

With a lending pool, you deposit USDC into a protocol where borrowers can access the funds and pay interest. A portion of that interest is distributed to depositors as yield. Your returns depend on borrowing demand, utilisation rates and the protocol’s rules.

With a liquidity pair, you deposit USDC alongside another cryptocurrency into a trading pool. Traders use this pool to swap assets, and liquidity providers may earn a share of trading fees. However, the value of the two deposited assets can change relative to each other, creating impermanent loss.

Both strategies carry risks. Smart contract bugs can expose deposited funds to theft or loss. Impermanent loss can reduce returns compared with simply holding the assets. Depegging occurs when USDC falls below its intended one-dollar value, reducing the value of your holdings even when the yield remains positive.

How the main risks compare

When you earn yield on USDC, your biggest risks depend on where you deposit your funds and how the platform generates returns. Counterparty risk, smart contract risk and depeg risk can all affect how much you earn and whether you recover your initial deposit.

Counterparty risk arises when you trust a centralised exchange or lending platform with your USDC. If the provider fails or freezes withdrawals, you may lose access to your funds. Smart contract risk affects you when a vulnerability in a DeFi protocol allows your deposited funds to be stolen or lost. Depeg risk means your USDC falls below its intended $1 value, reducing the value of your holdings.

Chart comparing USDC yield options by risk and return.

There is no universal ranking because your exposure depends on the product you choose. However, higher advertised APY usually means higher risk. Before depositing, consider how returns are generated, who controls your funds and what could go wrong.

Your choice of blockchain also matters. Learn how USDC on Solana compares with Ethereum when considering transaction fees, network activity and the platforms available to you.

USDC yield vs a bank savings account

USDC yield can offer a potentially higher return than a regular savings account, but you give up an important protection: USDC does not have government-backed deposit insurance. Your returns depend on the platform and strategy you use, and higher yields often come with greater risk. A bank savings account may offer less, but eligible deposits have protection and more predictable access to your money.

Before choosing USDC for yield, consider whether you can afford the risks, including platform failure, smart contract vulnerabilities and changes in USDC’s value. It is generally better to keep emergency funds in an insured bank account rather than expose money you need urgently to crypto-related risks.

USDC can also make moving money across borders easier. For example, if you need to send money from the US to Nigeria, you can use a platform that supports USDC transfers and local withdrawals. With Grey, you can send, receive and spend USDC, then convert your balance and withdraw funds to a supported local bank account.

The right choice depends on your priorities: bank deposits for protection, USDC for global access and potential yield.

Frequently asked questions about how to earn yield on USDC

1. Is earning yield on USDC safe?

Earning yield on USDC carries risks, including platform failure, smart contract vulnerabilities and loss of funds. Although USDC is designed to maintain a one-dollar value, your investment is not guaranteed. Review the platform’s security, withdrawal terms and yield strategy before depositing funds, and never invest money you cannot afford to lose.

2. What is a typical USDC APY in 2026?

USDC yield varies by platform, market conditions and strategy. In 2026, some centralised reward programmes offer around 3–4% APY, while DeFi lending may offer approximately 3–8% or more. These are indicative ranges, not guaranteed rates. Check current offers, fees and risks before choosing a platform.

3. Do you pay tax on USDC yield?

Yes, USDC yield may be taxable, depending on your country’s tax laws and how you earn it. In the United States, rewards are generally reportable as income. Keep records of payments, dates and amounts, and consult a qualified tax professional to understand your reporting obligations.

4. Can you lose your USDC principal earning yield?

Yes, you can lose some or all of your USDC principal. Platform insolvency, lending defaults, smart contract exploits and liquidity problems can prevent withdrawals or cause losses. USDC can also trade below one dollar. Assess the risks carefully, diversify where appropriate and avoid committing essential savings.

5. What is the difference between USDC yield and USDC staking?

USDC yield usually comes from lending, reward programmes or providing liquidity through a platform or DeFi protocol. Staking typically involves locking cryptocurrency to support a proof-of-stake blockchain. USDC does not use proof-of-stake itself, so products marketed as USDC staking generally involve a different yield-generating mechanism.

6. How do you convert USDC yield into cash you can spend?

First, withdraw your USDC and earn rewards to a supported exchange or financial platform. Convert the balance into your preferred currency, then withdraw it to an eligible bank account or payment method. With Grey, you can send, receive and spend USDC, subject to supported services, currencies and applicable fees.

While USDC yield offers the potential for higher returns, a bank savings account provides greater protection for eligible deposits. For international transactions, Grey gives you a practical way to send, receive and spend USDC, with access to supported currencies for your everyday financial needs.

Gift tax: How much money can you give tax-free?

•

•

2 min read

Giving money to another person may seem straightforward, but large financial gifts can come with tax reporting requirements. In the United States, the Internal Revenue Service (IRS) determines how much you can give each year before you may need to report the gift. Understanding these rules is particularly important when transferring substantial sums, sharing wealth, or planning your finances.

The good news is that exceeding the annual gift tax limit does not automatically mean you owe tax. The IRS provides a lifetime exemption that allows you to give more than the annual limit before gift tax becomes payable. Knowing the difference between the annual exclusion, reporting requirements and lifetime exemption can help you make informed financial decisions.

The IRS annual gift tax exclusion lets you give up to a set amount per recipient each year with no tax owed and no form to file. Gifts above that amount count against your lifetime exemption and require Form 709, though tax is rarely owed until the lifetime exemption itself is used up.

How much can you gift tax-free per year?

For 2026, you can give up to $19,000 per recipient per year without owing federal gift tax or generally needing to file a gift tax return. This annual exclusion applies to qualifying gifts of money or property under US Internal Revenue Service (IRS) rules.

The limit resets every calendar year, beginning January 1. This means gifts made in 2026 are counted separately from gifts made in 2025. You can give money to multiple recipients in the same year, provided each recipient’s total qualifying gifts from you stays within the annual limit.

The exclusion applies per giver and per recipient, rather than as one combined limit for all your gifts. For example, you could give $19,000 each to three people in 2026, totalling $57,000, without exceeding the annual exclusion for any recipient. If two spouses each give the same recipient $19,000, their combined gifts can reach $38,000 under their separate exclusions, subject to applicable IRS rules.

What is the lifetime gift tax exemption?

For 2026, the US lifetime gift and estate tax exemption is $15 million per individual. This is the total amount an individual can transfer through qualifying gifts during their lifetime and leave to beneficiaries at death before federal gift or estate taxes generally apply, subject to applicable rules.

The lifetime exemption works alongside the annual gift tax exclusion. While the annual exclusion allows qualifying gifts of up to $19,000 per recipient in 2026 without using the lifetime exemption, larger gifts generally count toward the $15 million limit. Gifts exceeding the annual exclusion may require you to file IRS Form 709, even when no tax is due.

The important distinction is that the lifetime gift tax exemption and estate tax exemption are shared, not separate allowances. For example, if you make $2 million in taxable gifts during your lifetime, that amount generally reduces the exemption remaining for your estate. Any unused exemption may apply to assets transferred at death, helping determine whether your estate owes federal estate tax.

When do you need to file form 709?

You generally need to file IRS Form 709 if you give more than $19,000 to one person in 2026, unless a specific exception applies. The form reports gifts exceeding the annual exclusion and helps the IRS track your use of the lifetime gift tax exemption.

The filing requirements, deadline and potential tax implications are important to understand before submitting your return.

Who Must File Form 709?

The person giving the gift is generally responsible for filing. You may need to file if your gifts to one recipient exceed the annual exclusion, you transfer certain future interests, or you elect to split gifts with your spouse.

When Is Form 709 Due?

The deadline is generally April 15 of the year following the gift. For gifts made in 2026, the filing deadline is April 15, 2027. An extension may be available, but it does not automatically extend the deadline for paying tax owed.

Does Filing Form 709 Mean You Owe Tax?

No. Filing the form does not automatically mean you owe gift tax. Gifts above the annual exclusion generally reduce your lifetime gift and estate tax exemption. Federal gift tax is typically payable only after your available exemption has been exhausted.

Gift tax vs Estate tax: how they connect

Gift tax and estate tax share one combined lifetime exemption. In 2026, the federal gift and estate tax exemption is $15 million per individual. This means large gifts made during your lifetime and assets transferred after your death generally count toward the same exemption.

If you give a substantial amount of money while alive, the portion exceeding the annual gift tax exclusion generally reduces the exemption remaining for your estate. For example, if you make $2 million in taxable gifts, that amount generally reduces your remaining exemption to $13 million, assuming no other taxable transfers or adjustments.

Alternatively, leaving the money in your estate means its value may be considered when calculating estate tax after your death. If your total taxable estate and applicable prior gifts remain within your available exemption, federal estate tax generally will not be due.

The main difference is when the transfer happens and how the assets are valued. Lifetime gifting can help transfer wealth earlier, but the best approach depends on your financial circumstances, future needs and estate planning goals.

If you're sending money as a gift to family members abroad, it's also worth considering transfer fees and exchange rates. For example, you can send money from the US to Mexico or send money from the US to India using available international transfer services. Just remember that sending money internationally doesn't automatically exempt a gift from US tax reporting requirements.

Frequently asked questions about gift taxes

Does the person receiving a Gift pay tax on it?

Generally, no. Under US federal tax rules, the recipient does not pay income tax on money received as a gift. The person giving the gift is usually responsible for any applicable gift tax reporting and payment. However, income generated by gifted assets may be taxable to the recipient.

Can you gift more than the annual exclusion without paying tax?

Yes. Gifts exceeding the 2026 annual exclusion of $19,000 per recipient may require you to file Form 709. However, the excess generally reduces your lifetime gift and estate tax exemption rather than triggering immediate tax. Gift tax usually becomes payable after the available exemption is exhausted.

Do Gifts to a spouse count toward the annual exclusion?

Generally, gifts to a US-citizen spouse qualify for the unlimited marital deduction and do not count toward the annual exclusion. Gifts to a non-US citizen spouse have a separate annual limit, which is $194,000 for 2026. Special rules may apply depending on the circumstances.

Is money sent to family abroad treated as a Gift for tax purposes?

Yes. Money sent to relatives abroad may qualify as a gift under US tax rules. If the giver is subject to US gift tax, the annual exclusion and reporting requirements may apply regardless of where the recipient lives.

Do you have to report a Gift from a foreign relative?

You may need to. US persons who receive gifts exceeding $100,000 in total from a nonresident alien individual or foreign estate generally must report them on Form 3520. Different thresholds apply to gifts from foreign corporations or partnerships.

What is the penalty for not filing Form 709 when required?

Failure to file Form 709 when required may result in penalties based on the unpaid gift tax, generally 5% per month, up to 25%. If no tax is due, penalties may differ, but the IRS can still assess consequences for noncompliance. Filing requirements should be checked carefully.

Managing money across borders involves more than understanding gift tax. Whether you are supporting family abroad, making international payments or managing everyday expenses, having the right financial tools matters. Grey offers multi-currency accounts and virtual cards that make it easier to manage international finances, pay for online services and handle supported cross-border transactions.

USDC on Solana vs Ethereum: Which should you use?

•

•

2 min read

Solana or Ethereum? Both can move the same dollar-backed stablecoin, but the difference becomes clear when speed and transaction fees matter.

Solana can settle a USDC transfer in a few seconds, usually for a fraction of a cent. Ethereum, on the other hand, can take several minutes, with fees that increase when the network is busy. For a straightforward payment, Solana can be the more practical option when keeping costs low matters.

Both versions of USDC are issued by Circle and designed to maintain a 1:1 value with the US dollar. The real choice is therefore not between two different stablecoins, but between two networks. The better option depends on where the money is going, which network the recipient supports, and whether speed, low fees or access to Ethereum’s wider ecosystem matters most.

What is the difference between USDC on Solana and Ethereum?

The main difference between USDC on Solana and Ethereum is the blockchain network used to settle your transaction, even though both versions are issued by Circle, designed to maintain a 1:1 value with the US dollar and redeemable through the same issuer. When you choose between them, you are therefore choosing a different settlement layer, with Solana generally offering faster and cheaper transfers while Ethereum can become more expensive when the network is busy.

The distinction becomes more important when you come across native and bridged USDC. Native USDC is issued directly by Circle on the blockchain where you hold it, so USDC issued natively on Solana is Circle-issued USDC on Solana, while native USDC on Ethereum is issued directly on Ethereum. This means you should not assume that every token labelled “USDC” has the same issuance structure.

Bridged USDC represents USDC that has been moved between blockchains using a bridge, rather than being directly issued by Circle on the destination network. Before sending your USDC, check the network supported by the recipient and whether you are dealing with native or bridged USDC, because sending through an unsupported network can make it difficult or impossible to recover your funds.

How fees and settlement times compare

When you compare Ethereum and Solana for USDC transfers, the biggest differences you'll notice are the network fee and how quickly your transaction settles. Ethereum fees change with supply and demand, so when more people compete for limited block space, the base fee rises and you may pay an additional tip to have your transaction prioritised. Solana generally offers lower and more predictable fees, which can make it more practical for frequent transfers.

On Ethereum Layer 1, you may pay around 0.01–0.20, with settlement taking roughly 12 seconds to several minutes depending on network conditions and the level of finality you require. Solana typically settles transactions within seconds at a fraction of a cent.

Ethereum Layer 2 networks can reduce the cost further by processing transactions away from the main chain and later posting transaction data to Ethereum. This gives you faster execution and lower fees, although the final settlement process works differently from a direct Layer 1 transaction. Network conditions change, so check current fees before sending.

Also read: USDC to USD: How to convert your stablecoin to cash

What happens if you send USDC to the wrong network?

Sending USDC to the wrong network can put your funds at risk, and whether you can recover them depends on where the money was sent and who controls the receiving wallet. If the destination supports the network you used, recovery may be possible, but if it does not, you may need help from the exchange or wallet provider, with no guarantee that the funds can be recovered.

Before sending, check that the network selected on your platform matches the network supported by the recipient. Do not rely on the wallet address alone, because the same address format can sometimes work across different networks. If you use a USD bridge to move USDC between blockchains, confirm the destination network and the type of USDC being received before approving the transaction.

For a large transfer, send a small test amount first, then check the network name, token and destination address before sending the remaining balance. Once a blockchain transaction is confirmed, it generally cannot be reversed.

Also read: How to convert and use USDC in Nigeria

How to choose a network for your transfer

Choosing a network for your USDC transfer comes down to three things: how much you are sending, where the money is going and how quickly you need it to arrive. Start with the destination, because the cheapest or fastest network is not useful if the recipient’s wallet or exchange does not support it. Check the supported networks before you enter the amount or confirm the transaction.

Next, consider the amount you are sending. For a small transfer, a network with very low transaction fees can help you avoid losing a noticeable percentage of your money to fees. For a larger transfer, the fee may matter less, but you should still confirm that the network supports the exact USDC you are sending.

Finally, consider urgency. If you need the money to arrive within seconds or minutes, a faster network may make more sense. If timing is flexible, you can compare fees and choose the cheaper option. Whatever you choose, confirm the network on both sides before sending.

Open a multi-currency account to send and receive USDC

Turning USDC into local currency usually involves one more step after receiving your payment: moving the funds from your crypto wallet or exchange into a bank account where you can spend them. A multi-currency account can fit between these steps, giving you a place to receive and hold funds before converting them into the currency you need.

With Grey, you can open a multi-currency account and use it to manage your international payments in one place. Once you receive USDC, you can move the funds through the available conversion and withdrawal options rather than immediately sending everything to a local bank account. This can give you more control over when you convert and where your money goes.

The process is straightforward: receive your USDC, convert or off-ramp it through a supported route, then withdraw the resulting currency to your local bank account. The exact steps depend on the currencies and payment routes available to you, so check the supported options before starting your transfer.

Frequently asked questions

Is USDC on Solana the same as USDC on Ethereum?

USDC on Solana and USDC on Ethereum are both issued by Circle and designed to maintain a 1:1 value with the US dollar, but they operate on different blockchains. The main differences are transaction speed, network fees and where you can send or receive each version of USDC.

Which network has lower USDC fees?

Solana generally has lower USDC transaction fees than Ethereum, with transfers typically costing a fraction of a cent. Ethereum fees can increase when the network is busy because users compete for limited block space. Before sending, check the current network fee and make sure the recipient supports your chosen network.

Can I send USDC from Solana to an Ethereum wallet?

You cannot send native USDC on Solana directly to an Ethereum-only address and expect it to arrive correctly. To move USDC between networks, you need a supported bridge or exchange that handles the transfer. Always confirm both the sending and receiving networks before approving the transaction.

What happens if I pick the wrong network?

Choosing the wrong network can make your USDC difficult or impossible to recover, depending on the receiving wallet or exchange. Before sending, check the network supported by the recipient and make sure it matches the network selected in your wallet. For larger amounts, consider sending a small test transaction first.

Is USDC on Solana safe?

USDC on Solana can be safe when you use the official, native version of USDC and send it through a supported wallet or exchange. Your biggest risks usually come from choosing the wrong network, using an unsupported token or sending funds to an incorrect address. Always verify the token and destination.

How do I convert USDC to my local currency?

To convert USDC into your local currency, you typically send it to a supported exchange or financial platform, sell or convert the USDC, then withdraw the resulting funds to your bank account. A multi-currency account can also give you a place to receive and manage funds before converting them.

Arrow (up)

Back to top