<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/countries-that-speak-german#article","headline":"6 countries that speak German as an official language","description":"Which countries speak German as an official language? Here is the full list, from Germany and Austria to Switzerland and beyond. Explore the list now.","inLanguage":"en","url":"https://grey.co/blog/countries-that-speak-german","mainEntityOfPage":{"@id":"https://grey.co/blog/countries-that-speak-german#webpage"},"datePublished":"2026-08-17T22:33:34.093Z","dateModified":"2026-08-18T09:00:00+01:00","author":{"@type":"Person","@id":"https://grey.co/authors/adeolu-titus-adekunle#person","name":"Adeolu Titus Adekunle","url":"https://grey.co/authors/adeolu-titus-adekunle","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/titusadeoluadekunle/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/countries-that-speak-german#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a838c34c267d678e2daa354_Countries%20That%20Speak%20German%20as%20an%20Official%20Language-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a838c34c267d678e2daa354_Countries%20That%20Speak%20German%20as%20an%20Official%20Language-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/countries-that-speak-german#webpage","url":"https://grey.co/blog/countries-that-speak-german","name":"Countries That Speak German: Full List | Grey","description":"Which countries speak German as an official language? Here is the full list, from Germany and Austria to Switzerland and beyond. Explore the list now.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/countries-that-speak-german#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/countries-that-speak-german#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/countries-that-speak-german#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"6 countries that speak German as an official language","item":"https://grey.co/blog/countries-that-speak-german"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/countries-that-speak-german#faq","mainEntity":[{"@type":"Question","name":"How many countries speak German?","acceptedAnswer":{"@type":"Answer","text":"German is an official national language in six countries: Germany, Austria, Switzerland, Liechtenstein, Luxembourg, and Belgium. It also holds co-official or regionally recognised status in South Tyrol (Italy), parts of Poland, and several Brazilian states. It is widely spoken unofficially in diaspora communities worldwide."}},{"@type":"Question","name":"Which country has the most German speakers?","acceptedAnswer":{"@type":"Answer","text":"Germany has by far the most German speakers, both native and total, with its population accounting for about 78% of the world's German-speaking population. Austria has the second-largest concentration of native speakers, followed by Switzerland."}},{"@type":"Question","name":"Is German spoken in Switzerland?","acceptedAnswer":{"@type":"Answer","text":"Yes. German is one of Switzerland's four national languages, alongside French, Italian, and Romansh, and it is the majority language, spoken natively by roughly 63% of the Swiss population, concentrated in the northern, central, and eastern cantons. Swiss German dialects differ significantly from Standard German in everyday spoken use, though Standard German is used in writing and formal contexts."}},{"@type":"Question","name":"What currency do German-speaking countries use?","acceptedAnswer":{"@type":"Answer","text":"Five of the six German-speaking countries use the euro: Germany, Austria, Luxembourg, and Belgium as EU members, plus the effective use of the euro in parts of Liechtenstein. Switzerland uses the Swiss franc, as it is not part of the eurozone or the European Union. Liechtenstein officially uses the Swiss franc as its currency, given its close economic ties to Switzerland."}},{"@type":"Question","name":"Can I spend abroad with a Grey card?","acceptedAnswer":{"@type":"Answer","text":"Yes. The Grey virtual card is linked to your foreign currency balance and can be used wherever Visa is accepted, including in Germany, Austria, Switzerland, Luxembourg, and Belgium."}},{"@type":"Question","name":"How do I send money to Germany?","acceptedAnswer":{"@type":"Answer","text":"Grey allows you to send money to Germany at transparent rates, with the fee and exchange rate shown before you confirm the transfer. This applies whether you are sending from the US or another country, and covers both personal transfers and business payments."}}]},{"@context":"https://schema.org","@type":"ItemList","@id":"https://grey.co/blog/countries-that-speak-german#list","name":"6 countries that speak German as an official language","numberOfItems":6,"itemListElement":[{"@type":"ListItem","position":1,"name":"Germany","url":"https://grey.co/blog/living-in-germany-expat"},{"@type":"ListItem","position":2,"name":"Austria"},{"@type":"ListItem","position":3,"name":"Switzerland"},{"@type":"ListItem","position":4,"name":"Liechtenstein"},{"@type":"ListItem","position":5,"name":"Luxembourg"},{"@type":"ListItem","position":6,"name":"Belgium"}]}] </script>

6 countries that speak German as an official language

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

German is spoken by around 130 million people worldwide, making it one of Europe’s major languages. While many people associate it only with Germany, it is actually an official language in a few other countries and is spoken in various territories and expat communities.

German is an official language in six countries: Germany, Austria, Switzerland, Liechtenstein, Luxembourg, and Belgium. It is also widely spoken in parts of Italy (South Tyrol) and by communities worldwide. Germany and Austria have the largest number of native speakers.

This article explores countries where German is spoken, whether as an official language or widely spoken without official status.

How many countries speak German?

German is an official national language in six countries: Germany, Austria, Switzerland, Liechtenstein, Luxembourg, and Belgium. When you add the autonomous region of South Tyrol in Italy to these countries, they make up the German Sprachraum, or German-speaking area.

Together, these countries form the main German-speaking region of Europe. German is also widely spoken in parts of Italy and Poland, as well as by German-speaking communities in countries such as the US, Canada, Brazil, and Argentina.

Germany has by far the largest German-speaking population, with around 78% of the world's estimated 130 million German speakers living there.

Countries where German is official

Country Status Notes
Germany Sole official language German is the main language spoken across the country.
Austria Sole official language Austrian German has some differences in vocabulary and pronunciation.
Switzerland Co-official (with French, Italian, Romansh) German is the country's most widely spoken language (63% of the population). Swiss German dialects differ significantly from Standard German.
Liechtenstein Sole official language German is the country's only official language.
Luxembourg Co-official (with French and Luxembourgish) German is used in government, media, and education, though Luxembourgish is the national language spoken most in daily life.
Belgium Co-official (with Dutch and French) German is official in the German-speaking Community in eastern Belgium.

If you're thinking about moving to a German-speaking country, our guide to living in Germany as an expat covers practical topics such as banking, visas, and the cost of living.

Regions where German is widely spoken

German is not limited to these six countries. Several other regions have sizeable German-speaking populations.

South Tyrol, Italy

This is an autonomous province in northern Italy that borders Austria. German is its co-official language alongside Italian. The majority of the local population speaks German as their first language. This is because of the region's history as part of Austria-Hungary before being annexed to Italy after the First World War.

Poland

German is a recognised minority language in southern Poland, particularly in the Opole and Silesian voivodeships. These regions are home to communities with historical German heritage.

Brazil

German is spoken by communities in southern Brazil, particularly in Espírito Santo, Santa Catarina, and Rio Grande do Sul. Some municipalities also recognise German as a co-official language. This is because Germans migrated to southern Brazil in the 19th and 20th centuries.

Diaspora communities

German-speaking communities can also be found in the US, Canada, Argentina, and other countries with a history of German immigration. However, German is not recognised as an official language in these countries.

German dialects and variation

Spoken German can sound very different depending on where you are. Standard German (Hochdeutsch) is the version taught in schools and used in formal writing, business, education, and the media. It provides a common form of communication across German-speaking countries.

  • Swiss German (Schweizerdeutsch): Differs significantly from Standard German and can be difficult for native German speakers to understand. Pronunciation, vocabulary, and even some grammar can be different. Swiss German is used in everyday conversation, while Standard German is generally used for writing and formal contexts.
  • Austrian German: This is much closer to Standard German than Swiss German, but it has its own distinct vocabulary, particularly in food, administrative terms, and everyday expressions. It also has a distinct, recognisable accent.
  • Regional dialects in Germany: German dialects vary considerably. Bavarian in southern Germany, for example, can sound very different from the Low German dialects in the north. However, almost everyone understands Standard German, which is used in formal settings throughout the country.

For travellers and language learners, however, Standard German is usually enough. You may notice different accents and expressions, but you should be able to communicate across all six countries.

Travelling and sending money to German-speaking countries

The currencies used across German-speaking countries are not all the same. Germany, Austria, Luxembourg, and Belgium use the euro (€/EUR). Liechtenstein and Switzerland use the Swiss franc (CHF), as they are not members of the EU. Some shops, especially in tourist centres in Liechtenstein, might, however, accept euros.

Card acceptance in German-speaking countries

In Germany, Austria, Luxembourg, and Belgium, Visa and Mastercard are widely accepted in cities. However, smaller businesses in Germany might favour cash payments or local debit systems (EC-Karte) more than in many other European countries. In Switzerland, card payments are widely accepted and reliable nationwide.

If you ever find yourself in any of these countries, spending abroad with a Grey card connected to a foreign-currency balance avoids foreign transaction fees. This differs from many home bank cards, which charge extra fees on international transactions and convert your currency to euros at undisclosed, marked-up rates.

Read our guide on how to avoid foreign transaction fees before travelling.

Sending money to Germany

Germany is one of the world's largest economies and a common destination for business and personal transfers. If you are sending money from the US to Germany, Grey allows you to access USD, EUR, and GBP accounts with the associated account details. This means you can send money to Germany or euro accounts in other countries from anywhere using SEPA. This avoids the international wire transfer fees associated with cross-border payments using traditional banks.

Grey shows the applicable exchange rate and fees before you confirm your transfer, so you know the cost upfront.  You can receive EUR payments at a 0.8% deposit fee, capped at 10 EUR. Conversions cost 0.5% to 1%, and sometimes are capped at $6 (EUR equivalent), depending on the corridor.

Whether you're travelling through Germany, paying for something in Switzerland, or sending money to someone in Europe, managing multiple currencies can make international payments easier. Spend and send money abroad with Grey across German-speaking countries with fees and exchange rates shown upfront.

Frequently asked questions about German-speaking countries

How many countries speak German?

German is an official national language in six countries: Germany, Austria, Switzerland, Liechtenstein, Luxembourg, and Belgium. It also holds co-official or regionally recognised status in South Tyrol (Italy), parts of Poland, and several Brazilian states. It is widely spoken unofficially in diaspora communities worldwide.

Which country has the most German speakers?

Germany has by far the most German speakers, both native and total, with its population accounting for about 78% of the world's German-speaking population. Austria has the second-largest concentration of native speakers, followed by Switzerland.

Is German spoken in Switzerland?

Yes. German is one of Switzerland's four national languages, alongside French, Italian, and Romansh, and it is the majority language, spoken natively by roughly 63% of the Swiss population, concentrated in the northern, central, and eastern cantons. Swiss German dialects differ significantly from Standard German in everyday spoken use, though Standard German is used in writing and formal contexts.

What currency do German-speaking countries use?

Five of the six German-speaking countries use the euro: Germany, Austria, Luxembourg, and Belgium as EU members, plus the effective use of the euro in parts of Liechtenstein. Switzerland uses the Swiss franc, as it is not part of the eurozone or the European Union. Liechtenstein officially uses the Swiss franc as its currency, given its close economic ties to Switzerland.

Can I spend abroad with a Grey card?

Yes. The Grey virtual card is linked to your foreign currency balance and can be used wherever Visa is accepted, including in Germany, Austria, Switzerland, Luxembourg, and Belgium.

How do I send money to Germany?

Grey allows you to send money to Germany at transparent rates, with the fee and exchange rate shown before you confirm the transfer. This applies whether you are sending from the US or another country, and covers both personal transfers and business payments.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

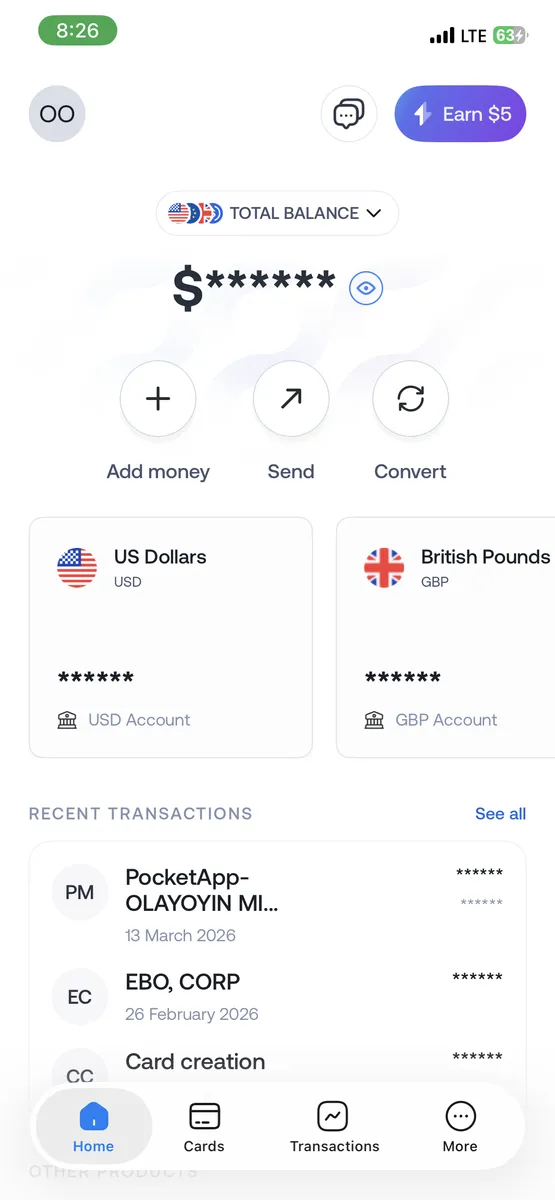
  1. Log in to your Grey account.
    ‍
  2. Click “Send”.
Send Canadian dollars with Grey

‍

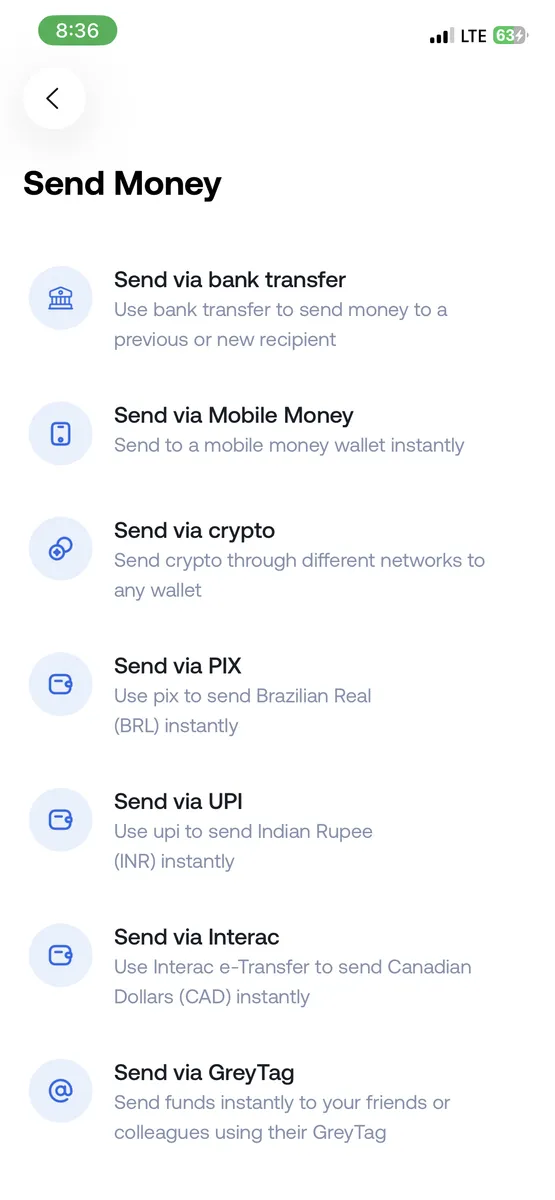
2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

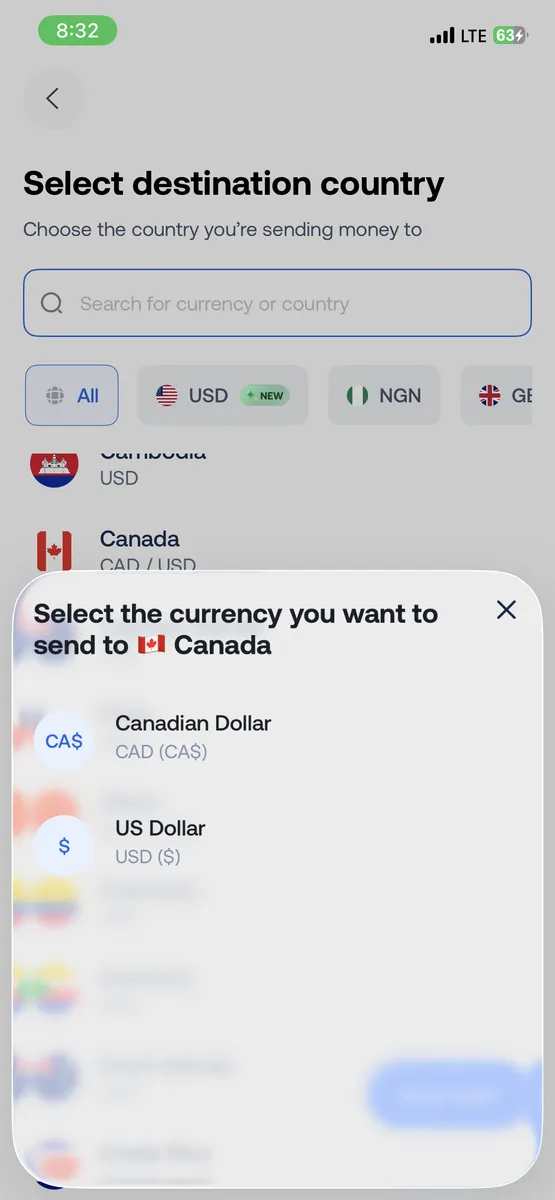
3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

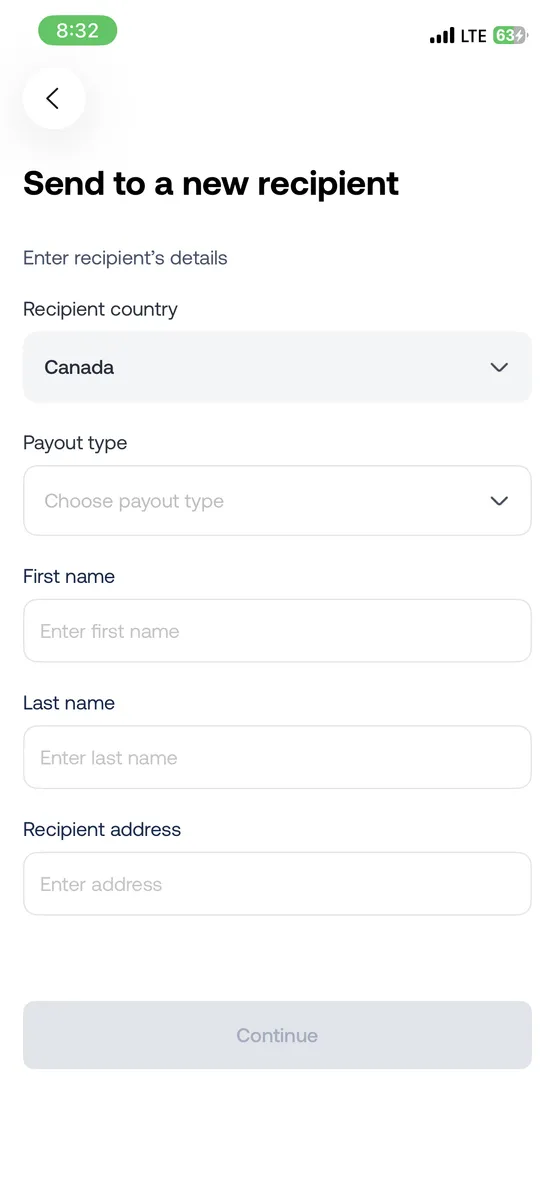
4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

Cheapest ways to send money home for Eid

•

•

2 min read

Eid is a cherished time for Muslims, a season of gratitude, generosity, and togetherness. Families come together to pray, share meals, and exchange gifts, celebrating faith and community in meaningful ways.

For those living or working abroad, sending money home is an important way to participate in the festivities and support loved ones during this special season. Ensuring funds arrive safely and promptly allows families to celebrate Eid fully, even across distances.

This article highlights the cheapest ways to send money home for Eid, helping you stay connected and share generosity while keeping transfer costs low.

Also read: Cheaper ways Nigerians abroad can send money home for Detty December

Why should you choose a cheap way to send money home?

But why does choosing an affordable way to send money matter during Eid?

Using a cost-effective method ensures your family receives the full amount you intend to send, allowing them to celebrate the festival properly and enjoy your gift as you envisioned.

Lower fees also make it easier to send money more frequently if needed, helping support multiple family members or cover extra festive expenses without putting pressure on your budget.

With the right transfer method, you can be confident your family gets everything they need, while staying within your financial limits and avoiding dipping into savings.

Also read: How to send money to Nigeria in time for Christmas

Cheapest ways to send money home for Eid

During Eid, getting money home affordably is important. Using low-cost methods ensures your family receives funds quickly, securely, and ready to enjoy the celebrations fully.

1. Wise

Wise allows you to send money home quickly and reliably with transparent fees. Transfers are made in local currencies at competitive exchange rates, so your family gets more of what you send. The platform supports multiple countries, making it ideal for global workers or expats who want to ensure funds arrive safely for Eid celebrations without surprises or unnecessary deductions.

2. Transfer Galaxy

Transfer Galaxy is designed for sending money to loved ones efficiently and affordably. During Ramadan, a special code allows 0-fee transfers, making it perfect for Eid gifts. The service is available in over 20 countries, allowing families abroad to celebrate together financially. Using Transfer Galaxy ensures that the full amount you intend reaches your family, supporting meals, gifts, and festivities without adding extra costs.

3. Revolut

Revolut makes sending money abroad seamless for Eid, offering multi-currency accounts and fast transfers. Exchange rates are competitive, so you know your family will receive value in their local currency. Transfers can be done directly from the app, making it convenient to support loved ones during the celebrations. Whether funding meals, gifts, or other Eid expenses, Revolut ensures your money moves quickly and efficiently.

4. Remitly

Remitly allows global users to send money quickly for Eid, with options for bank deposits or cash pickups. Transfers are reliable and easy to track, ensuring funds reach your family in time for celebrations. Whether it’s for meals, gifts, or festival needs, Remitly makes sending money abroad simple, giving confidence that your contribution is received promptly and ready to be used exactly as intended.

5. ACE Money

ACE Money supports transfers to over 100 countries and allows fee-free sending during Eid using Ramadan codes. Money can be sent directly to bank accounts or as cash pickups, giving families flexibility in how they receive and use funds. It is a practical solution for ensuring that your Eid gifts arrive quickly, affordably, and ready to fund celebrations without exceeding your budget.

6. Botim

Botim is ideal for UAE residents looking to send money to 170 countries. For Eid 2026, there’s a special 10x cashback offer during Ramadan, making transfers even more rewarding. The platform ensures money reaches your loved ones quickly, supporting meals, gifts, and festival needs. Botim’s wide reach and fast processing make it easy to participate in Eid celebrations globally without worrying about fees or delays.

7. Grey (recommended)

Grey is highly recommended for sending money home for Eid because it offers fast, secure transfers with multi-currency accounts and competitive exchange rates. It removes administrative bottlenecks and allows instant payouts, making it simple to support family members during the festival. With Grey, you can ensure the full gift reaches your loved ones without extra effort, letting you focus on the meaning of Eid rather than logistics.

Tips for sending money home safely during Eid

Sending money for Eid requires careful planning to ensure your loved ones receive funds on time, without unnecessary costs or delays.

1. Plan ahead

Avoid last-minute transfers that may delay your family’s Eid celebrations. Sending money a few days before the holiday ensures that funds arrive safely and on time, giving your loved ones the opportunity to use the money for meals, gifts, and festivities.

2. Compare rates

Always check for the best exchange rates and lowest fees before sending money. Many providers offer special promotions during Ramadan or Eid, so comparing options helps you maximise the amount your family receives and avoid losing value during transfers.

3. Check limits

Be aware of transfer limits, as they vary depending on the provider and recipient country. Knowing these limits in advance prevents incomplete transfers, ensures the full amount reaches your family, and avoids the need to make multiple small transactions.

4. Verify recipient details

Double-check your recipient’s account or cash pickup details before sending money. Accurate information reduces the risk of failed transfers or delays, ensuring that your family receives the funds in time for Eid without confusion or additional follow-ups.

For sending money home this Eid, Grey stands out as the best option, offering fast, secure, and reliable transfers. With competitive exchange rates and a user-friendly platform, it ensures your family receives the full amount you send, making celebrations complete. Getting started is simple: just sign up on the Grey website or download the app. With Grey, supporting loved ones across borders is easy, affordable, and worry-free, letting you focus on the joy of Eid.

‍

How to shop in the US or Europe with your Grey card

•

•

2 min read

A few months ago, I was eyeing a pair of sneakers on a US website for weeks. Then the store started running sales and I decided to buy them (hashtag #YOLO), but my bank card declined the payment.

Not once, not twice… but four times!.

The same card that worked perfectly in Nigeria where I live, and the same details I’d used for years. I tried to get another card, but by then, sales had ended, and the sneakers were out of stock. It was annoying, but I just had to accept my L.

If you’ve ever tried to shop internationally, on sites like ASOS UK, Amazon US, Zara EU, or even the Apple Store, you may already be familiar with this pain. Sometimes the website rejects your card. Sometimes your bank blocks the transaction. Sometimes the currency conversion takes too long, and the payment times out.

It shouldn’t be this difficult to buy something online in big 2026… yet for many people, it still is.

But if you use a Grey card, you'll eliminate the uncertainty of thoughts like, “Will this payment go through?”, and transform your international shopping into a simple and predictable process.

Why shopping abroad is often frustrating

Shopping from US or European stores usually comes with these hurdles:

1. Many foreign merchants decline local cards

Some US/UK online stores automatically reject certain African-issued cards, even if you have more than enough balance.

2. Stores bill strictly in USD, GBP, or EUR

If your card requires manual currency conversion, it can cause payment delays that may result in declines.

3. Banks block “suspicious” international transactions

This usually happens when the merchant is unfamiliar.

4. Conversion errors and hidden fees

Some cards convert long after the purchase, leading to surprises on your statement.

These problems are common, but they’re also exactly what Grey card is built to avoid.

How your Grey card makes shopping internationally easy

Smart spending across multiple currencies and USDC

Your Grey card doesn’t require you to pick or switch wallets before paying. Instead, it automatically spends from your balances. Your USD account is debited first; if that’s empty, your USDC, and then the highest of your remaining balances.

This means your payment goes through as long as you have funds available in your account, without requiring you to consider currencies at checkout.

Works across major US and European stores

Your Grey card is an international spend card, so you can pay at 150 million merchants worldwide.

Use Apple Pay and Google Pay

For stores that support mobile wallets, you can simply add your Grey Visa card to Apple Pay or Google Pay. This is more secure and makes for much faster checkouts.

Create multiple cards for better organisation

If you shop frequently or mix personal and business purchases, you can:

  • Use one card for personal shopping
  • another for business imports
  • another for gift purchases

It keeps your spending clean and easy to track.

Freeze and unfreeze anytime

You can always freeze your cards to control your spending.

Better protection for online transactions

You receive real-time notifications, card controls, and instant limits - everything you need for peace of mind when buying from foreign sites.

LDMAG1

How to shop in the US or Europe with your Grey card

1. Request your Grey visa card

Create a Grey account and go to the cards section of your Grey app to request a Grey card for $5.

2. Add your card to the store’s checkout

Enter your card details or simply pay through Apple Pay/Google Pay.

3. Make your purchase normally

Shipping, duties, and taxes will be displayed as they are for every other international shopper.

4. Track everything in your Grey app

Every charge, refund, or verification appears instantly, so there are no surprises later.

Tips for smarter international shopping

  • Use a separate card for business or bulk purchases so you can easily track expenses.
  • Keep a bit extra in your wallet for shipping fees and taxes.
  • Use Apple Pay/Google Pay when available. It’s the most seamless way to tap and pay, and also supports contactless payments.

Shopping abroad doesn’t have to be stressful

Your Grey card helps you shop with confidence. There are no random declines or conversion drama. Ahead of your next international purchase, you can create your Grey card and enjoy a smoother, more predictable shopping experience.

‍

How to budget in foreign currencies using the Grey card

•

•

2 min read

Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.

Then remote work happened.

Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you also need structure because, without proper structure, even the most careful spender can lose track of where their money is going.

Your Grey card is a practical budgeting tool for people who live, work, earn, and spend across borders. I’ll explain.

Why budgeting in multiple currencies breaks down so easily

Many people who overspend don't do so because they’re irresponsible. But because their money isn’t organised in a way that reflects how they live.

It’s pretty common to be juggling subscriptions in USD, running ads in EUR, buying coffee in GBP, and somehow all on the same card. Eventually, everything blurs together. You can no longer track your Netflix renewal, that Facebook ad campaign, the flight you booked last week, or the coworking space membership. Then one day you check your balance and think, “Where did all that money go?” You know you spent it. You just can’t figure out where, or why, it felt like so much more than you expected.

It’s not that you’re careless. It’s that your money isn’t organised in a way that matches how you actually live and work. And once things start blurring, it’s nearly impossible to untangle without spending an hour combing through statements, converting currencies in your head, and still not feeling certain you’ve caught everything.

At that point, your budget is broken.

Also read: How to use your Grey card to manage all your subscriptions

What should budgeting look like when you earn and spend globally?

Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:

  • See exactly what each type of spending is costing you.
  • Stop or pause spending instantly when needed.
  • Protect one part of your budget from another.
  • Make changes without disrupting everything else.

The Grey card is designed around solving these exact needs.

How does the Grey card help with budgeting?

Use multiple cards to separate your spending

One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes. Your Grey virtual card helps you structure your spending as such.

For example, you can create:

  • One card for subscriptions and recurring tools
  • One card for ads and growth experiments
  • One card for travel or everyday spending
  • One card per client or project

Each card acts like its own budget lane, pulling from the same balance. You don’t need to guess where the money went because you already know.

This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.

Also read: How to pay for ads easily with your Grey card

Freeze cards instantly when spending goes off-track

Budgets fail when you can’t act fast enough.

With the Grey card, you can instantly freeze or unfreeze any card in the app. If a digital ad campaign starts burning through too cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.

Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.

Set limits that protect your budget

Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.

You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.

For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.

Track spending clearly in one place

When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.

When budgeting time comes around, you’re not sitting there trying to remember what that mysterious €47 charge was three weeks ago or why your USD balance dropped. Everything’s already categorised. The structure did the work for you.

Spend confidently across borders

Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.

A quick note on protection when spending abroad

An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.

When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.

It’s one less thing to worry about while managing money across borders.

Also read: How to claim your Visa card benefits

What budgeting in foreign currencies is like with the Grey card

When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency your spend is coming from and more importantly, when something changes.

Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.

If you’re ready to make your budget work wherever you are, create or update your Grey card today and start spending and budgeting in the ways that matter to you.

‍

How to pay online and in stores worldwide with your phone

•

•

2 min read

I was halfway through buying coffee in Lisbon when I patted my pockets looking for my wallet and realised I’d left it in my hotel room. I wasn’t moved in the slightest. A worthy, some would even argue, better alternative — my phone — was already hovering over the card reader to complete the payment.

That was a moment of realisation of how much things had changed. A few years ago, travelling required carrying multiple cards, worrying about foreign transaction fees, and hoping the ATM wouldn’t “swallow” my card in some random city. Now I pay for nearly everything with my phone. Subscriptions, flights, groceries in foreign countries, late-night takeaway orders, anything in fact.

How does it work?

How paying with your phone actually works

When I first started using mobile payments, I assumed my phone was doing something complicated and vaguely magical. In a way, I was right.

Your phone can store your card details securely in a digital wallet. Apple Pay if you’re on iPhone, Google Pay on Android, or other regional options, depending on where you are. When you pay, your phone communicates with the payment terminal via NFC (Near Field Communication), the same technology that powers contactless cards.

You authenticate the payment using Face ID, fingerprint, or a passcode, and the transaction goes through. The money comes out of whichever card or account is linked to that digital wallet. From the merchant’s perspective, it looks like a normal card payment. From your perspective, it’s faster and more convenient than fumbling for a physical card.

Online payments work similarly. When checking out, you can use Apple Pay or Google Pay instead of typing in card details. Your phone authenticates using biometrics, and the payment processes are instant. No manually entering sixteen-digit card numbers, expiry dates, or security codes.

The convenience is brilliant. But convenience doesn’t mean cost-free.

Also read: How to budget in foreign currencies using the Grey card

Paying online from anywhere in the world

I spend a lot of money online, honestly, probably more than I should, and most of it involves foreign currencies. Subscriptions to US software services. European design tools. UK-based platforms. Occasionally, buying something from an online shop halfway across the world because it’s not available locally.

For years, I paid for everything with a local bank card and didn’t think twice about it. Every transaction went through, so I assumed it was working fine. Then I started looking at my statements more carefully and realised how much I was losing.

When you pay for something online in a foreign currency using a regular bank card, three things usually happen. Your bank converts the currency at its exchange rate, which is almost always 2 - 4% worse than the real mid-market rate. They might charge a foreign transaction fee, sometimes 2 - 3% of the purchase. And if the merchant offers to convert the currency for you at checkout (something called dynamic currency conversion), that’s usually even worse.

On a $100 subscription, you might lose $5 - $7 just to fees and poor conversion rates. Multiply that across every international payment you make in a year, and it adds up fast. I calculated mine once, it was over $600 annually. Six hundred quid, gone, for no reason other than using the wrong card.

Also read: How to use your Grey card to manage all your subscriptions

Paying in physical stores globally

Paying with your phone in physical stores works the same way contactless cards do, just more conveniently. You tap your phone on the terminal, authenticate, and the payment goes through. It’s particularly useful when travelling because you don't have to worry about carrying the right physical cards or whether a shop accepts your card network.

I’ve paid for coffee in Berlin, groceries in Dubai, transport in Tokyo and dinners in Cape Town, all with my phone. It’s seamless, and merchants barely look up because contactless payments are standard nearly everywhere now.

But again, the ease of payment doesn’t mean you’re paying efficiently. Every time I tapped my phone abroad using my regular bank card, I was getting hit with foreign transaction fees and terrible exchange rates. The transaction felt instant and painless, but my bank was quietly taking 4 - 5% every time.

The worst part is you don't see it happening. The payment just says "approved." You don't get a breakdown of fees or exchange rate markups. You only notice when you check your statement later and realise that €50 dinner somehow cost you £47 instead of £43.

LDMAG1

Why your card setup matters

If you link a regular bank card with high foreign transaction fees and poor exchange rates, your mobile payments will still cost you money. The phone is just the interface. The financial infrastructure behind it, meaning the card, the account and the currency handling, is what actually matters.

I realised this after a trip to France. I’d paid for everything with my phone, felt very modern and efficient, then checked my statement and saw I’d lost nearly £80 to conversion fees and markups over one week. My phone wasn’t the problem. My card was.

That’s when I started looking for a better setup, something designed for people who regularly spend money internationally and don’t want to lose a percentage of every transaction to avoidable fees.

Also read: How tax-free shopping works for international travellers

How Grey makes global phone payments easier

Apple Pay and Google Pay are brilliant. They make payments faster and more secure. But they don’t solve the underlying problem of whether you’re paying efficiently or expensively.

Grey changed how I think about paying with my phone because it solved the card problem, not just the payment method.

When you open a Grey account, you get USD, GBP and EUR multi-currency accounts.

The Grey card connects directly to these accounts.

What really impressed me was the control. Grey lets you create multiple cards. I've got one for subscriptions, one for travel, and one for general spending. If a card is compromised or I'm worried about a particular merchant, I can instantly freeze it in the app and create a new one in seconds. I can set spending limits, track exactly where my money is going, and budget more intelligently by separating spending categories across different cards.

For someone who earns in multiple currencies or regularly spends internationally, this setup makes a material difference. I’m not losing money every time I tap my phone. I’m spending efficiently, with full visibility and control.

The right card changes everything

I love paying with my phone. It’s faster, more secure, and more convenient than carrying a wallet full of cards.

But payments are only as good as the card linked to them. If you’re paying with your phone but using a card with high fees and poor exchange rates, you’re still losing money on every transaction. The tap is convenient, but the cost is hidden.

The right card makes mobile payments genuinely efficient, not just convenient. That’s the difference between losing hundreds annually to avoidable fees and keeping the money you earn.

Get it right by opening a free Grey account today and getting the card that works globally and transparently.

‍

How creators receive payouts from international platforms

•

•

2 min read

I remember my first international payout like it was yesterday. I’d spent months building an audience, finally hit the YouTube monetisation threshold, and eagerly waited for the payment from Google AdSense. When the notification came through saying the money had been sent, I felt brilliant. Proper creator now, getting paid for my work. “Tell Mr Beast to come outside!” I said.

When I checked my account, the platform had sent the money, yes, but somewhere between California and my bank account, a part of it just vanished.

That moment taught me that understanding how you get paid is just as crucial as understanding how to create content people want to watch. Over the years, I’ve learned the hard way how international payouts actually work, where money gets lost, and how to structure things so you keep more of what you earn. This is what I wish someone had told me before that first disappointing payout.

Also read: How remote employees receive salaries from abroad

How international platforms actually pay creators

Platforms don’t just send money directly to your bank account like a friend transferring you a tenner. They use intermediaries called payout processors because they’re dealing with millions of creators across dozens of countries, all expecting payment, some even in their local currency.

YouTube pays through Google AdSense. TikTok uses various regional processors. Patreon, Twitch, and Substack all rely on third-party systems to handle the actual movement of money across borders. This makes sense from their perspective. They can’t open bank accounts in every country or navigate every local banking regulation themselves.

LDMAG1

The most common payout methods

I’ve used nearly every payout method available to creators, and each has taught me something different.

Direct bank transfers

Direct bank transfers via wire seemed more professional when I started getting larger payments. But international wire transfers involve multiple banks, each charging fees. I once received a $2,000 payment that cost me nearly $90 in combined bank charges and poor exchange rates. The sender paid $25, an intermediary bank took $20, my bank charged a receiving fee, and then converted USD at a rate significantly worse than the mid-market rate. It added up fast.

Platform-specific systems

Platform-specific systems like Payoneer work better for creators on freelance marketplaces. Payoneer integrates smoothly with platforms like Upwork and Fiverr, and it’s cheaper than PayPal. I still lost 1-2% on currency conversion, though, and withdrawal fees applied depending on how I accessed the money.

Multi-currency fintech accounts

The breakthrough for me came when I discovered multi-currency fintech accounts. Services like Wise, Revolut, and Grey offer virtual bank accounts in multiple currencies, such as USD, EUR, and GBP, so you can receive payments easily. This changed everything for me.

Also read: How Nigerians working remotely protect income from FX swings

How smart creators structure their payout systems

After years of losing money unnecessarily, I finally sorted out a proper system, and it made an immediate difference.

First, I opened a multi-currency account that let me receive USD, EUR, and GBP without forced conversion. I went with Grey because it gave me proper banking details with an account number, sort code, and routing number so that platforms and clients could pay into it directly.

Next, I updated my payout details across every platform. YouTube, Patreon, freelance platforms, and direct clients, I gave them all my new account details. Some platforms required verification periods, others had specific payout cycles. But once everything was switched over, the difference was clear.

Finally, I started converting currency strategically instead of immediately. If I’m not spending the money right away, I hold it in USD until the exchange rate improves. Sometimes this saves me 2-3%, which compounds significantly over months.

Also read: How to budget in foreign currencies using the Grey card

How Grey simplifies international payouts

I’m not here to give you a sales pitch, but I do want to explain why Grey made such a difference for me specifically.

Grey gives you virtual bank accounts in USD, EUR, and GBP with proper banking details. When a platform or client pays you, the funds are deposited directly into the relevant currency account. There’s no forced conversion, no intermediary banks taking unexpected fees, and no waiting two weeks for international wires to clear.

The exchange rates are transparent. Whenever I convert, I know exactly what I’m paying, as there are no hidden fees buried in exchange-rate spreads.

For creators earning from multiple countries and platforms, having one system that handles everything is genuinely valuable. I used to juggle different platforms, but now everything flows into Grey, and I manage it all in one place.

The clarity this provides also makes tax filing significantly easier. I have clean records of what I earned, in which currency, and when.

Also read: Switching from banks to global accounts: What to know

Getting paid is part of the strategy

Treating your payout infrastructure as part of your overall creator strategy isn’t boring back-office admin. It’s keeping more of the money you’ve worked hard to earn. It’s having control over your finances instead of just accepting whatever arrives in your account. It’s being professional about your business.

The platforms will keep paying you, but they won’t optimise how you receive that money. That’s your job. Understand the fees, use the right tools, and structure your systems intelligently. Your future self will thank you.

Open your free Grey account or download the app and start receiving international payouts transparently, efficiently, and without losing money you’ve already earned.

‍

Arrow (up)

Back to top