


<script type="application/ld+json">[{"@context": "https://schema.org", "@type": "BlogPosting", "@id": "https://grey.co/blog/how-to-receive-payments-from-upwork-in-nigeria-in-2026#article", "headline": "How to receive payments from Upwork in Nigeria in 2026", "description": "Learn how freelancers and remote workers in Nigeria can use Grey to receive payments from Upwork seamlessly", "inLanguage": "en", "url": "https://grey.co/blog/how-to-receive-payments-from-upwork-in-nigeria-in-2026", "mainEntityOfPage": "https://grey.co/blog/how-to-receive-payments-from-upwork-in-nigeria-in-2026", "datePublished": "2024-12-06T08:58:20.799Z", "dateModified": "2026-05-29T23:44:06.338Z", "author": {"@type": "Person", "name": "Tunde Aladeloba"}, "publisher": {"@type": "Organization", "@id": "https://grey.co/#organization", "name": "Grey", "url": "https://grey.co"}, "image": "https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6752bc7854f0af0ae6ddace1_How%20to%20receive%20payments%20from%20Upwork%20in%20Nigeria%20in%202025.webp"}, {"@context": "https://schema.org", "@type": "BreadcrumbList", "@id": "https://grey.co/blog/how-to-receive-payments-from-upwork-in-nigeria-in-2026#breadcrumb", "itemListElement": [{"@type": "ListItem", "position": 1, "name": "Home", "item": "https://grey.co/"}, {"@type": "ListItem", "position": 2, "name": "Blog", "item": "https://grey.co/blog"}, {"@type": "ListItem", "position": 3, "name": "How to receive payments from Upwork in Nigeria in 2026", "item": "https://grey.co/blog/how-to-receive-payments-from-upwork-in-nigeria-in-2026"}]}]</script>

How to receive payments from Upwork in Nigeria in 2026

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Updated: January 2026

The gig economy is thriving in Nigeria, with platforms like Upwork connecting skilled freelancers to global clients. However, a common challenge remains: how to efficiently receive payments in Nigeria. With over 45% of Nigerian internet users engaged in remote work or freelancing, finding cost-effective and reliable payment solutions is essential. Grey, a multi-currency account platform, is revolutionising how freelancers handle their payments, offering speed, transparency, and ease.

Here’s how to receive your Upwork payments in Nigeria seamlessly in 2026.

Also read: The best digital nomad jobs to earn from anywhere in Nigeria

Understanding how Upwork payments work

Upwork provides multiple payment options for freelancers, including:

  • Direct to local bank: Payments are converted to Naira (NGN) and sent directly to your bank account, but the conversion rates may not be favourable, and processing can take up to five business days.
  • PayPal and Payoneer: Popular for freelancers but often involve high fees and may take longer to withdraw funds to local accounts.
  • Wire transfers: Reliable for large sums but usually involve large banking fees and delays.

While these methods work, they can reduce your earnings due to fees and poor exchange rates. That’s why many Nigerian freelancers are turning to Grey.

Also read: How to receive US Dollars in Nigeria with Grey

How to use Grey to receive Upwork payments in Nigeria

Grey offers a streamlined way to manage international payments, making it perfect for freelancers in Nigeria.

  1. Download the Grey app or visit the website.
  2. Sign up and complete verification with your ID.
  3. Get your international bank details and start managing your earnings like a pro.

How to link your Grey account to Upwork

Grey makes connecting to Upwork hassle-free:

  1. Log in to Upwork and go to Settings > Get Paid.
  2. Select 'Add a Payment Method' and choose the type of bank account that matches your Grey account (e.g., USD, GBP, or EUR).
  3. Input your Grey bank details and confirm.
  4. Select the account type(Individual Checking) and enter the routing number(ACH routing).
  5. Enter your account number and select Add Bank Account.
  6. Confirm and start receiving payments directly to your Grey wallet.

Benefits of using Grey for Upwork payments

Grey is designed to cater to the unique needs of Nigerian freelancers. Here’s why it’s the ideal choice:

  • Low fees, better rates: Avoid high conversion and transfer fees while enjoying competitive exchange rates.
  • Fast transactions: Receive payments faster than traditional bank transfers.
  • Multi-currency: Hold and manage USD, GBP, and EUR, and convert to Naira (NGN) only when needed.

Get started with Grey today

With over 122 million Nigerians online and an increasing number turning to freelancing, having a robust payment solution is non-negotiable. Grey simplifies global transactions, helping freelancers maximise their earnings while staying compliant with local regulations.

Sign up for a free Grey account and join thousands of Nigerian freelancers who trust Grey to manage their payments seamlessly in 2026.

Last updated:

September 16, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

11 best free invoicing tools

2 min read

Here is the problem with most "free" invoicing tools: they are free until you actually want to get paid. Then a 2.9% transaction fee shows up, or a client cap locks you out, or the feature you need is behind a $19/month paywall. The word "free" is doing a lot of heavy lifting in this category.

The best free invoicing tools let freelancers create, send, and track invoices without a subscription fee. Top options include Wave, Grey, Invoice Ninja, and PayPal. Each has different strengths: Wave suits sole traders doing basic accounting; Grey suits freelancers paid in multiple currencies; Invoice Ninja suits those who need recurring invoices and time tracking.

This guide cuts through the marketing. Eleven tools, ranked by what they genuinely offer at zero cost, where the charges start, and which type of freelancer each one actually fits. The best invoicing software for freelancers is not the one with the longest feature list. It is the one that matches the way you bill.

What to Look for in a Free Invoicing Tool

Before you compare tools, get clear on what "free" actually means in online invoicing for small business contexts. There are three models, and they are not the same thing:

Model 1: Free to send, fees on payment. This is Wave, PayPal, and Stripe. You never pay a subscription, but when a client pays your invoice through the platform, the tool takes a cut. Wave charges 2.9% + $0.60 per card payment. PayPal charges up to 3.49% + a fixed fee. On a $3,000 invoice, that is $87 to $105 gone before the money reaches you. These fees are comparable to what Stripe charges directly, so you are not overpaying, but you are not invoicing for free either.

Model 2: Free up to a limit. Zoho Invoice gives you 1,000 invoices per year for free. Invoice Ninja and Hiveage cap the number of clients on their free plans. These tools are genuinely free if you stay within the ceiling. Once you outgrow it, you pay, or you switch.

Model 3: Free invoicing, paid for other features. Grey and Canva fall here. Invoicing is free because the product earns revenue elsewhere (multi-currency accounts, design subscriptions). No per-invoice fee, no payment processing cut, no client cap on the invoicing feature itself.

Beyond the pricing model, four things matter: whether the tool supports the currencies your clients pay in, whether it sends automatic payment reminders (the single biggest lever for getting paid on time), whether it connects to your accounting software, and whether the free plan stamps the tool's branding on your invoices.

The 11 Best Free Invoicing Tools for Freelancers

Ranked by the strength of their free offering. Paid tools are included only where the trial or all-in-one value genuinely earns a spot. If a tool calls itself free but charges per payment, that is noted up front.

1. Wave

Wave is the tool most freelancers should start with, and many never leave. It is genuinely free: unlimited invoices, unlimited clients, no time limit, no "starter plan" that expires after 30 days. You get invoicing, basic double-entry accounting, receipt scanning, and financial reports without paying a cent. Wave makes money when clients pay through its payment processing (2.9% + $0.60 per card, 1% per ACH). If your clients pay by bank transfer outside Wave, you pay nothing at all.

Use it if: you want invoicing and bookkeeping in one place without spending anything. Skip it if: you need time tracking (Wave does not have it) or you bill in multiple currencies and want to hold those currencies (Wave converts everything).

2. Grey

Grey is the pick for freelancers whose clients pay in different currencies. You create an invoice in USD for your New York client and another in GBP for your London client, and both payments land in your Grey account in those currencies. No forced conversion, no bank markup, no surprise fees on arrival. Invoicing is free and built into the account. Grey earns its revenue from the multi-currency account and virtual card products, not from invoicing. See Grey invoicing for freelancers and get paid from the US.

Use it if: you have international clients paying in USD, GBP, or EUR, and you are tired of losing 2 to 3% on every conversion. Skip it if: you only bill domestic clients in one currency (Wave is simpler for that).

3. Invoice Ninja

The developer's choice. Invoice Ninja is open-source, which means you can self-host it on your own server for free with no limits at all. The hosted cloud version has a free tier with a client cap (check invoiceninja.com for the current number). Either way, you get invoices, quotes, recurring billing, time tracking, a client portal, and over 250 payment gateway integrations.

Use it if: you want full control over your data, or you need time tracking baked into your invoicing workflow.

Skip it if: you are not comfortable with the technical setup (Wave or Grey is more plug-and-play).

4. Zoho Invoice

Zoho gives you 1,000 invoices per year for free, which is roughly 80 per month. That is more headroom than most solo freelancers need. The free plan includes recurring invoices, automated payment reminders (email and SMS), a client portal, time tracking, expense tracking, and multi-currency support. It connects to Zoho Books and the broader Zoho ecosystem if you grow into it.

Use it if: you want polished automation (scheduled sends, automatic follow-ups) without paying, and you might eventually use Zoho's other business tools.

Skip it if: you want something simpler (Zoho's interface can feel heavy for basic invoicing).

5. FreshBooks

FreshBooks is not free. The Lite plan costs $19 per month after a 30-day trial. It is on this list because the invoicing experience is the best in the category, and it is worth knowing what the paid benchmark looks like before you commit to a free tool. Five billable clients, unlimited invoices, time tracking, expense tracking, automatic reminders, and a client portal with a polished "Pay Now" button. An invoice takes 30 seconds to create, and the client gets a professional page, not a PDF attachment.

Use it if: you bill 5 to 30 clients and value UX enough to pay $19/month for it.

Skip it if: you are on a strict $0 budget (use Wave) or you need multi-currency without conversion (use Grey).

6. PayPal Invoicing

PayPal's strength is not the invoicing tool itself. The fact is that nearly every business on the planet can pay a PayPal invoice without signing up for anything new. You create the invoice inside PayPal, the client pays with their PayPal balance, a card, or a bank account, and the money lands in your PayPal account. Free to send. PayPal charges up to 3.49% + a fixed fee when the client pays. On a $5,000 invoice, that is roughly $175.

Use it if: your clients are in multiple countries and you want the lowest-friction payment method they already recognise.

Skip it if: your invoices are consistently large. At $175 per $5,000 invoice, PayPal's fees add up fast.

7. Bonsai

Bonsai is $21 per month (Starter), so it is not free. But it is here because it replaces five separate tools: invoicing, CRM, proposals, contracts with e-sign, and time tracking. If you would otherwise be paying for Wave ($0) plus Calendly ($12) plus DocuSign ($25) plus a proposal tool ($25), Bonsai at $21/month is the cheaper option. The invoicing module alone is not as slick as FreshBooks, but the all-in-one package is hard to beat.

Use it if: you manage 5 to 20 clients and want proposals, contracts, and invoicing in one place.

Skip it if: invoicing is all you need (Wave or Zoho is simpler and free).

8. Canva Invoice

Canva is the simplest free invoice generator on this list, and also the most limited. You pick an invoice template, customise it with drag-and-drop, export as a PDF, and email it yourself. No payment link, no automatic reminders, no tracking, no accounting integration. What it does have: the most visually polished invoice you can send for free. If you are a photographer, designer, or creative whose clients care about brand presentation, a Canva invoice looks better than anything auto-generated by a billing tool.

Use it if: you send fewer than 5 invoices per month and want full visual control.

Skip it if: you need any automation, tracking, or payment processing.

9. Harvest

Harvest is a time tracker first and an invoicing tool second, and that is exactly why it is good. The free plan covers 1 user and 2 projects. Pro is $13.75 per month per seat. The killer feature: you track your hours, click "Create Invoice," and the invoice auto-populates from your logged time. No re-entering hours, no maths, no mistakes. It integrates with Stripe, PayPal, QuickBooks, Xero, and Asana.

Use it if: you bill hourly and want tracked time to flow directly into invoices.

Skip it if: you bill flat-rate or retainer (FreshBooks or Bonsai covers more of that workflow).

10. Stripe Invoicing

If you already use Stripe for payments, adding invoicing takes two minutes. No subscription. Stripe charges 0.4% per paid invoice on top of standard processing (2.9% + $0.30 per card). The invoices are basic: line items, a payment link, and automatic receipts. No time tracking, no recurring automation worth mentioning, no accounting features. It is the simplest path from "I need to bill someone" to "they paid."

Use it if: you send fewer than 10 invoices per month and already live inside Stripe.

Skip it if: you need anything beyond a payment link with line items.

11. Hiveage

Hiveage is the quiet pick for retainer-based freelancers. Free plan available with limits on clients and invoices (check hiveage.com for current terms). It handles recurring invoices, time and expense tracking, multi-currency support, and a client portal. The interface is clean and minimal. Set the billing schedule once, and invoices go out automatically every cycle. No fuss, no complexity.

Use it if: you are on monthly retainers and want set-and-forget billing.

Skip it if: you need time-to-invoice conversion (Harvest is better) or full accounting (Wave is better).

How to Send Your First Invoice as a Freelancer

Whether you use a dedicated invoicing platform or a simple free invoice generator like Canva, every invoice needs the same core information. Miss any of these, and you either look unprofessional or delay your own payment, or both.

  1. Your full name or business name, address, and contact details. This is the "from" section. If you operate under a business name, use it. If you are a sole proprietor using your personal name, that is fine too.
  2. Your client's name, company name, and billing address. Get this right. A misspelt company name on an invoice can delay processing in larger organisations where accounts payable matches invoice details against purchase orders.
  3. A unique invoice number. Start at 001 or INV-001 or whatever system you will maintain consistently. Sequential numbers make it easier to track what has been paid, what is outstanding, and what to report at tax time.
  4. The invoice date and the payment due date. Do not just write "Net 30." Write "Net 30, due 15 October 2026." A specific date creates a deadline. A payment term creates a calculation that the client will not do.
  5. An itemised list of services with rates and totals. If you bill hourly, show the hours and the rate. If you bill per project, describe the deliverable and the agreed price. Be specific enough that the client can match the invoice to the work without having to ask questions. For guidance on setting rates, see how to set your freelance rates.
  6. The total amount due, including any applicable taxes (sales tax, VAT, GST, depending on your jurisdiction).
  7. Your payment details. Bank account number, routing number or sort code, PayPal address, or a direct payment link. Include the currency. If your client is in a different country, give them the details in their local payment format so they do not have to figure it out.
  8. Late payment terms. "A fee of 1.5% per month applies to invoices overdue by more than 14 days." Stating this on the invoice (not buried in a contract) significantly improves on-time payment rates.

Getting Paid Faster: What to Put on Your Invoice

The gap between getting paid in 7 days and getting paid in 47 days is almost never about the client's intent. It is about the invoice. Four changes make a measurable difference:

Put a real date on it, not just a payment term. A client who reads "Due 15 October" feels a deadline. A client who reads "Net 30" has to do maths they will not do. Both should appear, but the date is what drives action.

Embed a payment link in the invoice PDF. Every extra step between reading the invoice and completing the payment is a point where the client thinks, "I will do this later." A one-click payment link inside the PDF itself removes all of them.

Invoice in your client's currency. If a US client receives an invoice in GBP, they have to calculate the conversion, wonder about the exchange rate, and navigate their bank's international transfer process. Invoice them in USD, and they pay in five minutes. Grey invoicing for freelancers lets you create invoices in USD, GBP, or EUR and receive the payment in that same currency. If your US clients need a W-8BEN before they can pay you, see how to complete a W-8BEN for US clients.

Put your late payment terms on the invoice, not in a separate contract. The invoice is the document that the accounts payable team actually sees. If the late fee is only in your contract, nobody in the payment queue reads it. Put it where it counts. For a full setup to receive international payments, open a Grey account to receive international payments.

Request a deposit before starting work on new or large projects. A 25 to 50% deposit upfront protects you from non-payment, filters out clients who are not serious, and gives you working capital during the project. State the deposit requirement in your proposal, and send the deposit invoice before you begin.

Open a Grey account and send professional invoices in any currency, for free, from the same place you receive your payments.

Frequently Asked Questions

What is the best free invoicing app for freelancers?

It depends on your situation. Wave if you want free invoicing plus free accounting in one tool. Grey if your clients pay in multiple currencies and you want to hold those currencies without forced conversion. Invoice Ninja, if you are technical and want open-source software, you can self-host. PayPal if you just need the fastest way to bill international clients who already have PayPal accounts. There is no single "best" because invoicing needs vary wildly by billing volume, client geography, and what else you need the tool to do.

How do I handle taxes if I use a free invoicing tool?

Free invoicing tools track what you billed and what you received. They do not calculate, set aside, or file taxes for you. In the US, you need to make quarterly estimated tax payments to the IRS, typically 25 to 30% of your net freelance income. In the UK, self-assessment requires you to save for an annual tax bill plus payments on account. Wave is the only free tool on this list that includes basic accounting to help with tax preparation. Tools like Zoho Invoice and FreshBooks integrate with TurboTax and QuickBooks. But no free invoicing tool files your taxes. Set aside tax money in a separate account from your first invoice.

Can I invoice clients without a registered business?

Yes. In both the US and the UK, you can invoice as a sole proprietor or sole trader without registering a company. Your invoice should include your legal name, address, and tax identification number where required (Social Security number or EIN in the US, National Insurance number in the UK). Some US clients will ask for a W-9 before processing your first payment.

What invoicing tool is best for international clients?

Grey, if you want to invoice and receive in the client's currency without conversion. PayPal, if your clients already have PayPal accounts and you want the lowest-friction option (but watch the fees: up to 3.49% + fixed per transaction). Zoho Invoice supports multi-currency on its free plan, but relies on third-party payment processors to actually collect the money. For large or recurring international invoices, Grey's approach of holding multiple currencies saves more over time than PayPal's convenience.

Do I need accounting software if I just use an invoicing tool?

Not right away, but you will eventually. Invoicing tracks what you billed. Accounting tracks what you spent, what you owe in taxes, and whether you are actually profitable. Wave bridges this gap by bundling free accounting alongside free invoicing, which is why it is the default recommendation for freelancers just starting out. Beyond roughly $30,000 per year in freelance income, connecting your invoicing tool to QuickBooks, Xero, or Zoho Books saves real time at tax season. See Grey for freelancers for how Grey fits into a broader financial setup.

Open a Grey account and send professional invoices in any currency, for free, from the same place you receive your payments.

Disclaimer: This article is for informational purposes only. Pricing, free plan limits, and transaction fees change frequently. Verify all figures directly with each provider before making a financial or business decision. Grey is not a bank. Grey is a licensed financial services provider offering multi-currency accounts.

FIRC certificate: What it is, how to get one, and what every Indian freelancer needs to know

2 min read

A FIRC certificate (Foreign Inward Remittance Certificate) is an official document issued by authorised dealer banks in India that proves you received a payment from abroad. It records the foreign currency amount, the INR equivalent, the exchange rate applied, and the sender's details. For freelancers, exporters, and businesses receiving international payments in India, an FIRC can be important for proving receipt of foreign funds, supporting GST refund claims, and maintaining records for foreign-exchange compliance. Since 2016, most FIRCs have been issued electronically as e-FIRCs through the RBI's Export Data Processing and Monitoring System (EDPMS).

That is the short version. The rest of this guide covers the details that actually matter when you are sitting in front of your CA at tax time, trying to claim a GST refund that has been stuck for months, or figuring out why your bank is asking for documents you have never heard of. If you are looking for the broader picture, start there and come back here for the FIRC specifics.

Who actually needs a FIRC (and who does not)

Not every international payment requires you to obtain a FIRC. The documentation available depends on how the payment reaches India, the bank or payment provider handling it, and what you need the document for.

Freelancers and businesses may need an FIRC, FIRA, BRC, or another form of remittance evidence when documenting export proceeds, supporting certain GST refund claims, or maintaining records of international payments. If you're receiving personal transfers or payments that don't qualify as exports, the requirements may be different.

You probably do not need one if you received a small personal gift from a family member abroad (though it is still wise to keep the documentation if the amount is substantial). You are receiving a salary from an Indian entity that happens to have foreign funding. Or the payment was made entirely in INR through a domestic payment rail.

What a FIRC actually contains

Every FIRC, whether physical or electronic, includes a standard set of fields. Understanding these helps you spot errors before they cause problems during an audit or refund claim.

UTR (Unique Transaction Reference). The transaction identifier assigned by the banking system. This is the single most important number on the document. If you ever need to trace, dispute, or verify the payment, the UTR is what your bank will ask for first.

Transaction amount in foreign currency and INR. Both figures appear on the FIRC. The foreign currency amount matches what your client sent. The INR amount reflects what was credited after conversion. If these do not match your invoice or contract, flag the discrepancy immediately.

Exchange rate applied. The conversion rate used by the bank or payment platform at the time of processing. This is not necessarily the mid-market rate. The difference between the applied rate and the mid-market rate is effectively part of the cost of the transaction.

Date of remittance. When the foreign funds were sent, not when they were credited to your account. The gap between these two dates matters for accounting purposes.

Sender details. Name and country of the person or business that sent the payment. This must match your invoice or contract. Mismatches (for example, a payment coming from a subsidiary entity rather than the client named on your invoice) can complicate audit trails.

RBI Purpose Code. This code identifies the reason for receiving the international payment and is used for regulatory reporting. The correct code depends on the service or transaction involved. For example, software consultancy, data-processing services, business consultancy, advertising, and other professional services can fall under different RBI purpose codes. If you're unsure which one applies, check the current RBI purpose-code list or confirm it with your bank or payment provider.

Recipient details. Your name, address, and bank account details. Verify that these match your records exactly. Typographical errors here create problems during tax assessment.

Also read: 9 best platforms to earn US dollars in India

Physical FIRC vs digital remittance documentation

Foreign-remittance documentation has increasingly moved online, but the exact document you receive depends on the bank or payment provider handling the transaction. You may come across terms including FIRC, FIRA, BRC, and electronic remittance advice.

These documents serve related purposes but shouldn't automatically be treated as interchangeable. If you need proof of an international payment for a GST refund, export documentation, or another regulatory process, check which document is accepted for your specific situation.

Some banks and payment providers now make remittance documentation available digitally, which can make it easier to access and store records without requesting a physical certificate from a branch.

One distinction to keep clear: a FIRC is issued per transaction. A FIRS (Foreign Inward Remittance Statement) is a consolidated statement covering multiple remittances over a period. For GST refund claims and most compliance purposes, you need the individual per-transaction FIRC, not the consolidated FIRS.

How to get your FIRC: two routes

Route 1: Requesting from your bank directly

If you receive foreign payments directly into your Indian bank account (not through a payment platform), you should request the FIRC from the bank that credited the funds.

1. Contact your bank branch or use their online banking portal if available.

2. Provide transaction details: UTR number, sender's name and country, amount received, date of the remittance, RBI purpose code, and your account details.

3. Pay the processing fee. Typically 100-500 rupees, depending on the bank.

4. Wait for processing. 3 to 7 business days in most cases.

The main friction point is purpose codes. If the sender's bank used an incorrect purpose code when initiating the transfer, your FIRC will reflect that error. Correcting it requires a formal amendment request to your bank, accompanied by supporting documentation (your invoice, contract, or engagement letter). This can add another week to the process.

Practical tip: Make sure the correct RBI purpose code is used for your payment. The appropriate code depends on the type of service or transaction, so confirm it with your bank or payment provider if you're unsure.

Route 2: Through a multi-currency account

If you or a cross-border payment platform, the FIRC process is typically handled by the platform and its banking partners.

The workflow: your international client pays into your USD, GBP, or EUR account. You hold the funds in foreign currency until you are ready to convert. When you withdraw to your Indian bank account, the conversion happens, and the inward remittance is processed through the platform's authorised dealer banking partner. The e-FIRC is generated as part of this process.

The advantage of this route is that you do not need to chase your bank. The FIRC is either generated automatically when you withdraw or available on request through the platform's support team. The purpose code is set correctly by default because the platform understands the nature of the transaction.

With Grey, Indian freelancers and businesses receive international payments into a dedicated USD, GBP, or EUR account. When you withdraw to your Indian bank account via bank transfer or UPI, the funds settle instantly (UPI) or next business day (bank transfer), and Grey provides FIRC on request through its banking partners. You are not visiting a branch, filling out forms, or waiting a week for a certificate.

Why your FIRC matters more than you think

Income tax records

If you earn income from overseas clients, keeping clear records of each payment can make tax reporting and reconciliation much easier. Remittance documentation can help establish where a payment came from, the currency involved, and the purpose of the transaction.

Your invoices, contracts, bank statements, and FIRC or FIRA, where available, can form part of that record. The documents you need will depend on your tax situation and how you receive international payments, so consider checking with a chartered accountant if you regularly earn income from abroad.

GST refunds on export of services

This is where FIRC becomes directly connected to your bottom line. Under the GST law, exports of services are zero-rated supplies. You do not charge GST on your export invoices, and you can claim a refund on the input tax credit you paid on goods and services used to deliver your export work.

But to claim this refund, you must prove that payment was received in convertible foreign exchange. The FIRC is this proof. Without it, your refund claim can be rejected. For a freelancer or small business with several lakhs in input tax credits annually, the difference between having FIRCs and not having them is the difference between recovering that money and writing it off.

The process: file your GST returns with export details, submit the refund claim through the GST portal, and attach the FIRC for each transaction as supporting documentation. If you are filing quarterly, batch your FIRCs accordingly. Do not wait until the annual return to collect them.

FEMA compliance

Foreign-exchange transactions in India are governed by the Foreign Exchange Management Act (FEMA) and related RBI regulations. Banks and authorised dealers are responsible for maintaining and reporting relevant information about international transactions.

Keeping your remittance documentation gives you a record of where your funds came from and why they were received. This can be particularly useful for freelancers and small businesses managing multiple international payments without a dedicated finance or compliance team.

Five FIRC mistakes that cost freelancers money

Waiting until tax season to collect FIRCs. This is the most common mistake. If you received a payment in April and you request the FIRC in January of the following year, the bank may take weeks to locate the transaction details and issue the certificate. Some banks charge higher fees for historical FIRC requests. Request within 30 days of each payment.

Not checking the purpose code. Your sender's bank may default to a generic purpose code (P0101, for example, which covers "import of goods") even when your transaction is a service payment. An incorrect purpose code on your FIRC can lead to a mismatch with your GST filing, which triggers manual review and delays your refund by months.

Confusing FIRS with FIRC. Your bank may offer you a Foreign Inward Remittance Statement (FIRS) as a consolidated summary. This is not the same as a FIRC. For GST refund claims and most compliance purposes, you need individual per-transaction FIRCs. A FIRS may be useful for your own record-keeping, but it does not substitute for the transaction-level certificate.

Using a FIRC with errors for a refund claim. If the amount, sender name, or purpose code on your FIRC does not match your invoice, your refund claim will be rejected. Check every FIRC against the corresponding invoice when you receive it. If there is a discrepancy, request an amendment from your bank immediately. Do not submit an incorrect FIRC hoping it will pass.

Not keeping a tracking system. If you receive payments from multiple clients across different platforms and bank accounts, it is easy to lose track of which payments have FIRCs and which do not. Maintain a simple spreadsheet with the following columns: date of payment, client name, amount (foreign currency), amount (INR), UTR number, platform or bank used, FIRC received (yes/no), and FIRC date. Update it with every payment, not once a quarter.

Frequently asked questions

What is a FIRC certificate?

A FIRC (Foreign Inward Remittance Certificate) is an official document issued by authorised dealer banks in India that confirms you received a payment from abroad. It records the foreign currency amount, the INR equivalent, the exchange rate, the sender's details, and the RBI purpose code. You need it for income tax filing, GST refund claims, and FEMA compliance.

Is FIRC the same as a bank statement?

No. A bank statement records money entering your account, while an FIRC or similar remittance document provides additional information about an international payment, which may include its foreign-currency value, sender, purpose, and conversion details. Which document you need depends on what you're using it for.

How long does it take to get a FIRC?

Through a bank directly, typically 3 to 7 business days after you submit your request. With modern payment platforms that automate the process, the e-FIRC is usually available within 24 to 48 hours after the withdrawal is processed. Requesting promptly (within 30 days of payment) avoids delays.

Do freelancers need a FIRC for every payment?

Not necessarily. The documentation you receive depends on the bank or payment provider handling the remittance. Some provide transaction-level documents, while others may issue documentation covering multiple remittances. If you need proof of payment for GST or another compliance purpose, check which document is accepted and make sure all relevant transactions are covered.

What happens if my FIRC has the wrong purpose code?

An incorrect purpose code can cause your GST refund claim to be rejected or trigger a mismatch during tax assessment. Contact the issuing bank immediately with supporting documents (your invoice or contract) and request a formal amendment. To prevent this, share the correct RBI purpose code with your client before they send the payment.

Can I get a FIRC for PayPal payments?

PayPal India provides digital Foreign Inward Remittance Advice (FIRA) for eligible international transactions. Its current system provides a weekly digital FIRA through PayPal Business accounts, covering qualifying withdrawals during that period. If you need documentation for a specific transaction or purpose, check PayPal's current FIRA process and requirements.

Does a FIRC expire?

An FIRC or similar remittance document records a completed transaction and doesn't generally have an expiry date like an identity document. However, tax, GST, and regulatory processes can have their own filing and record-retention requirements, so keep your remittance documents with your financial records.

Is FIRC required for personal gifts from family abroad?

A FIRC is generated for any foreign inward remittance, including gifts. For genuine gifts from specified relatives (parents, siblings, spouse), the amount is typically exempt from tax under Section 56 of the Income Tax Act. However, retaining the FIRC is advisable if the source of funds is questioned during a tax assessment.

How does Grey handle FIRC for Indian users?

Grey provides FIRC on request for users in India who receive international payments into their Grey multi-currency account and withdraw to an Indian bank account. The documentation is handled through Grey's authorised dealer banking partners as part of the withdrawal process. INR payouts settle instantly via UPI or next business day via bank transfer.

Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion. Grey is a financial technology company, not a bank. Banking services are provided by licensed banking partners. This article is general information, not financial, tax, or legal advice. Consult a qualified chartered accountant or tax professional for advice specific to your situation.

11 signs it is time to go full-time freelance

2 min read

The question is never really "should I freelance full-time?" Most people asking already know the answer. The real question is whether the timing is right, the finances are in order, and the pipeline is strong enough to survive the first quarter without a salary. If you are wondering whether you should freelance full-time, here is how to tell.

Signs you are ready to freelance full-time include steady client demand, a healthy financial buffer, income that rivals your salary, and a clear pipeline. Before you leap, build several months of expenses in savings and set up a reliable way to get paid by clients anywhere.

These 11 signs are not aspirational. They are practical checkpoints. If you can tick off eight or more, the jump is likely sound. If you are hitting four or five, keep building on the side. There is no prize for leaping early, and the downside of jumping without preparation is months of financial stress that makes your worst day at a job look comfortable.

11 signs you are ready to freelance full time

1. You are turning down work because of your day job

This is the clearest signal. When clients are reaching out, and you cannot take the project because your 9-to-5 schedule will not allow it, you are leaving money on the table. One or two missed opportunities are normal. But if you are consistently saying no to paid work three or four times a quarter, your side hustle has outgrown its container. The question shifts from "can I afford to leave?" to "can I afford to stay?"

2. Your freelance income has matched 70 to 80% of your salary for three or more months

Not one good month. Not a single large project that inflated the numbers. Three consecutive months where your side income consistently reaches 70 to 80% of your take-home pay. That threshold matters because full-time freelancing comes with costs your salary currently absorbs: health insurance (in the US), retirement contributions, equipment, software, and the time you will spend on invoicing, admin, and finding new work instead of doing billable work. If your freelance income already covers most of your salary before you go full-time, you have a margin for those costs.

3. You have three to six months of living expenses saved

Not three to six months of income. Living expenses. Calculate what you actually spend each month on rent or mortgage, utilities, food, transport, insurance, and minimum debt payments. Multiply by at least three, ideally six. This is your buffer, the money that keeps the lights on if your pipeline dries up for a month or two after you leave. Do not count this fund as "available." It is emergency-only. You will sleep better knowing it exists, and that calm shows in how you negotiate with clients.

4. You have at least two retainer or recurring clients

Project-based freelancing is feast or famine. Retainer clients, those who pay you a set amount monthly for ongoing work, are the foundation of a sustainable freelance business. Two retainers that together cover your essential expenses mean you can survive even if no new projects land for a month. If all your income is project-based, you are one dry spell away from dipping into your buffer before you have even started.

5. You have a system for finding new work that does not depend on luck

Referrals are wonderful, but they are unpredictable. A sustainable freelance business needs at least one reliable channel for generating new leads: a personal website that ranks for your service, a LinkedIn presence that attracts inbound enquiries, a network of collaborators who refer overflow work, or a platform profile (Upwork, Toptal, Contra) with reviews and history. If every project you have ever won came from a friend-of-a-friend, you do not yet have a system. You have luck, and luck is not a business model.

6. You can name your rate without flinching

Confidence in your pricing is a prerequisite, not a perk. If you are still discounting because you feel uncomfortable quoting your real rate, you will underprice yourself as a full-timer and work twice the hours for half the income. The test: can you send a proposal at your target rate, receive pushback, and hold your price without panic? If yes, you are ready. If you fold at the first objection, spend more time on the side hustle, building your portfolio and your confidence before you depend on it for rent.

7. You have a professional network outside your employer

Your colleagues at your day job are not your freelance network. When you leave, those relationships cool quickly. A strong freelance network includes other freelancers in your field (for referrals and overflow), freelancers in adjacent fields (a designer if you are a writer, a developer if you are a designer), past clients who would hire you again, and at least one mentor or peer who has already made the jump. If your entire professional world is inside your current company, spend six months building external relationships before you hand in your notice.

8. You can set boundaries with clients

Full-time freelancing without boundaries is a fast track to burnout. You need to be able to tell a client that a Friday evening request will be handled on Monday, that scope creep requires a revised quote, and that "just one more round of changes" has a cost. If you currently say yes to everything because you are afraid of losing the client, that pattern will intensify when freelancing is your only income. Practice setting boundaries now, while you still have a salary as a safety net.

9. You have a plan for health insurance

In the US, this is the single biggest financial obstacle to leaving a salaried job. Employer-sponsored health insurance costs the average employee roughly $1,400 per year for individual coverage, but the full premium (which you will now pay yourself) is closer to $7,500 to $8,500 per year on the ACA marketplace, more if you are over 40 or have dependents. COBRA lets you keep your employer plan for up to 18 months, but at full cost plus a 2% admin fee. In the UK, the NHS covers healthcare regardless of employment status, so this sign is less relevant for UK freelancers. Either way, do not leap without knowing exactly what your health coverage will cost and where it will come from.

10. You have handled (or have a plan for) taxes

Your employer currently withholds income tax, Social Security, and Medicare (US) or Income Tax and National Insurance (UK) from every pay cheque. As a freelancer, nobody does this for you. In the US, you will need to make quarterly estimated tax payments to the IRS (typically 25 to 30% of your freelance income). Miss a payment, and you face penalties. In the UK, self-assessment requires you to save for a single annual tax bill, plus payments on account for the following year. If you have never set aside money for taxes, practice for three months while you still have a salary: put 30% of every freelance payment into a separate account and do not touch it.

11. You feel ready, not desperate

The worst time to go full-time freelance is when you are running from a bad job. Desperation leads to underpricing, accepting bad clients, and skipping the preparation that makes freelancing sustainable. The best time to jump is when your current situation is tolerable, but your freelance work is pulling you forward. You should feel excited about the possibility, not relieved to be escaping something. If your primary motivation is "I hate my job," fix that first. If your primary motivation is "my freelance business is growing, and I want to give it my full attention," that is the right signal.

Getting your finances ready before you leap

Financial readiness is the difference between a planned transition and a panicked one. Even if you tick every sign above, skipping the money side turns a strong position into a fragile one.

Start with separation. If your freelance income is still flowing into the same account as your salary, split it now. A dedicated account for freelance earnings makes tax reporting cleaner, budgeting simpler, and the psychological shift to "this is my business" more real.

Build your buffer in a place you will not accidentally spend it. Grey's Pouch feature lets you build a freelance buffer fund in a Pouch that is separate from your spending balance, so your emergency savings do not blur into your operating cash. If your clients pay in different currencies, a multi-currency account lets you get paid by clients anywhere without losing money to forced conversion on every invoice.

Set up your invoicing before you need it, not after your first client asks for one. And separate work spending on a virtual card so that software subscriptions, hosting fees, and contractor payments are clearly business expenses from day one.

Ready to go full-time? Build a buffer in a Grey Pouch and get paid by clients anywhere with a Grey account.

Your First 90 Days as a Full-Time Freelancer

The first three months set the tone for everything that follows. Do not treat them as a holiday from employment. Treat them as the launch of a business.

Weeks 1 to 2: Lock in your existing clients. Confirm ongoing projects, agree on deliverables and timelines, and send invoices for any outstanding work. Set your working hours, your communication channels, and your availability. Tell clients when you are and are not reachable.

Weeks 3 to 6: Build your operational rhythm. Set a weekly invoicing day, a monthly accounting review, and a recurring block for business development (pitching, networking, content). Use the best free invoicing tools and best time-tracking apps to systematise what you currently do by hand.

Weeks 7 to 12: Evaluate. Are you hitting your income target? Is your pipeline refilling as fast as you are completing projects? Have you dipped into your buffer? If income is on track and the buffer is untouched, you are in a strong position. If you have already drawn down your savings, investigate why: is it a pipeline problem (not enough leads), a pricing problem (too cheap), or a scope problem (too much unbillable work)?

Frequently Asked Questions

When should I go full-time freelance?

When your freelance income has consistently matched 70 to 80% of your salary for at least three months, you have three to six months of living expenses saved, and you have at least two retainer or recurring clients. Meeting all three conditions simultaneously means you have a financial foundation, not just momentum.

How much savings do I need before going freelance full-time?

Three to six months of living expenses, not income. Calculate your essential monthly costs (rent, food, utilities, insurance, minimum debt payments) and multiply. Six months is safer, especially if you have dependents or live in a high-cost area. This money is your buffer against dry spells, not your operating budget. Do not count it as spendable.

How do I get paid as a freelancer with international clients?

You need an account that can receive payments in the currencies your clients send. If a US client pays in dollars and a UK client pays in pounds, a multi-currency account lets you hold both without forced conversion. This avoids losing 1.5 to 3% on every payment to exchange rate markups. Grey lets you hold USD, GBP, and EUR in one account and convert on your own terms.

What is the biggest mistake people make when going freelance?

Jumping before they have a repeatable system for finding new work. Referrals dry up, one-off projects end, and without a consistent lead generation method, you are back to zero every month. The second biggest mistake is not accounting for taxes: the first quarterly estimated tax bill in the US (or the first self-assessment payment in the UK) catches new freelancers off guard because they have already spent the money.

Should I quit my job before I have any freelance clients?

No. The safest path is to build your freelance income while employed, even if it means working evenings and weekends for six to twelve months. Quitting before you have clients means you are funding a job search from your savings, which creates pressure that leads to underpricing and accepting work you do not want. The exception is if you have been laid off and have severance to bridge the gap, in which case, treat the severance period as your runway to build the client base.

How do I handle health insurance as a freelancer in the US?

You have three main options. COBRA lets you keep your employer plan for up to 18 months, but you pay the full premium (typically $500 to $700 per month for individual coverage) plus a 2% admin fee. The ACA marketplace offers plans starting around $300 per month for basic coverage, with subsidies available depending on your income. A spouse's employer plan is the cheapest option if it is available to you. Budget for health insurance as a fixed monthly cost before you calculate whether your freelance income is "enough."

Ready to go full-time? Build a buffer in a Grey Pouch and get paid by clients anywhere with a Grey account.

Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or employment advice. Tax obligations, health insurance costs, and employment law vary by country and individual circumstance. Consult a qualified professional before making career or financial decisions. Grey is not a bank. Grey is a licensed financial services provider offering multi-currency accounts.

Freelancing vs consulting: What is the difference and which pays more?

2 min read

A clear breakdown of how freelancers and consultants differ in how they work, what they charge, and how they get paid, with real rate ranges by field and a practical guide to transitioning between the two.

The difference between freelancing and consulting is not just a label. It affects how you price your work, how clients perceive you, how long engagements last, and how much you ultimately earn. If you are considering freelancing vs full-time employment or are already freelancing and wondering whether repositioning as a consultant would increase your income, this guide breaks down the real distinctions.

Freelancers deliver specific outputs, often on a per-project or per-hour basis. Consultants advise on strategy and are typically engaged for longer periods at a higher day rate. Consultants generally earn more because they are selling expertise and outcomes rather than time or deliverables. The distinction affects how you price, contract, and position yourself.

Freelancer vs consultant: What is the difference?

The core difference between a freelancer and a consultant is what the client is paying for. A freelancer is hired to produce something: a website, an article, a logo, a codebase. A consultant is hired to advise on something: a strategy, a process, a decision, a transformation. Both work independently, both can work remotely, and both can earn well. But the nature of the engagement, the pricing model, and the client relationship are fundamentally different.

Dimension Freelancer Consultant
What the client pays for
A deliverable: copy, design, code, video Advice, strategy, or a decision framework
Pricing model
Hourly rate or fixed project fee Day rate, retainer, or value-based project fee
Engagement length Days to weeks per project; multiple clients simultaneously Weeks to months per engagement; often one primary client at a time
Client relationship
Vendor: client directs the work Adviser: the consultant shapes the direction
Positioning
"I build, write, or design this for you" "I help you decide what to build, write, or design"
Typical seniority
Any level; juniors can freelance Mid to senior; requires demonstrated expertise

There is also a third term that causes confusion: contractor. In the US, "independent contractor" is an IRS classification for anyone who is self-employed, whether they freelance or consult. In the UK, "contractor" often refers to someone working through a limited company on a fixed-term engagement, typically in IT or engineering. The consultant vs contractor distinction is mostly about positioning and industry convention, not a legal or tax difference.

Which pays more: freelancing or consulting?

Consultants typically earn more per hour or per day than freelancers in the same field. So, how much do consultants charge compared to freelancers, and why? The reason is not that consulting work is harder. It is that consultants price expertise and outcomes, while freelancers price time and deliverables. A freelance designer who charges $100 per hour to produce a landing page is selling their execution. A design consultant who charges $2,000 per day to audit a company's entire brand system and recommend a redesign strategy is selling their judgment.

The gap varies significantly by industry and seniority. Here are representative ranges:

Field Freelancer rate Consultant rate
Software development $75 to $200/hour $150 to $300/hour or $1,000 to $2,000/day
Marketing and content $50 to $150/hour $100 to $250/hour or $800 to $1,500/day
Design and UX $60 to $175/hour $125 to $275/hour or $1,000 to $2,000/day
Management and strategy N/A (rarely freelanced) $200 to $500+/hour or $1,500 to $3,000+/day
Finance and accounting $50 to $125/hour (bookkeeping, tax prep) $150 to $350/hour (CFO advisory, M&A)

The premium reflects two things: consultants typically have more years of experience, and they are positioned as advisers rather than vendors. A freelancer with ten years of experience who repositions as a consultant can often raise their effective rate by 30 to 50% without changing the quality of their work, simply by changing how they frame and price it. For more on pricing strategy, see how to set and raise your rates.

How to know whether to call yourself a freelancer or a consultant

The label you use should match what the client is actually buying. If you deliver tangible outputs (writing, designs, code, videos), you are a freelancer. If you advise on what should be written, designed, built, or changed, you are a consultant. If you do both (which is common), choose the label that reflects the higher-value part of your work.

The label matters because it sets expectations. A client hiring a "freelance copywriter" expects to send a brief and receive finished copy. A client hiring a "content strategy consultant" expects to discuss business goals, receive a content plan, and then possibly commission the writing as a separate deliverable. The consultant vs contractor question is similar: if you are brought in for strategic input, "consultant" positions you correctly. If you are filling a seat on a team for a fixed term, "contractor" is more accurate.

There is no legal distinction between calling yourself a freelancer or a consultant. The IRS and HMRC do not differentiate. The difference is entirely in how you position yourself to clients and, consequently, how much you can charge.

How freelancers can transition to consulting

If you have been freelancing for several years and find that clients increasingly ask for your opinion before you start the work, you are already consulting. You are just not charging for it. Here is how to make the transition deliberate:

  1. Identify the expertise you are giving away for free. Most experienced freelancers advise clients on strategy, process, or direction during kickoff calls, feedback rounds, or casual conversations. That advice has value. Start noticing when you are doing it.
  2. Reframe your offer around outcomes, not outputs. Instead of "I will design your website," try "I will audit your current site, identify the three changes most likely to increase conversion, and deliver a redesign brief your team can execute." The deliverable shifts from a website to a strategy.
  3. Raise your rates to match the new positioning. If you are selling strategic advice, charge a day rate or project fee, not an hourly rate. Hourly pricing commoditises expertise. A day rate of $1,200 signals a different level of engagement than $150 per hour, even though the maths is similar. Your consulting menu might include strategy sessions (60 to 90 minutes, focused on a single decision), audits (a full assessment of the client's current approach with a recommendations report), roadmaps (a multi-month plan with milestones), or ongoing advisory retainers (a monthly fee for regular strategic access).
  4. Create case studies that emphasise results, not deliverables. "Redesigned the client's checkout flow" is a freelancer case study. "Identified a 23% cart abandonment rate, recommended three UX changes, and helped the client recover $140,000 in annual revenue" is a consulting case study. The second one justifies a higher fee. If you are new to positioning for international clients, see how to land your first international client.
  5. Start with existing clients. Your first consulting engagement should be with someone who already trusts your work. Propose a strategy session, an audit, or a roadmap as an additional service alongside your usual deliverables. This lets you test consulting without abandoning your freelance income.

Getting paid as a freelancer or consultant working internationally

Whether you bill as a freelancer or a consultant, getting paid by international clients introduces the same friction. A US client sends a wire transfer, and your bank deducts $25 to $45 in receiving fees. A UK client pays in pounds, and your account auto-converts to dollars at a rate 2 to 3% worse than the mid-market rate. A retainer client in Europe pays in euros, and you lose money every month on the conversion without realising it.

These costs compound. On a $5,000 monthly retainer from a UK client, a 2.5% conversion loss is $125 per month, $1,500 per year, quietly disappearing from every invoice. A multi-currency account eliminates this. With Grey, you receive consulting fees in any currency, hold USD, GBP, and EUR in one account, and convert on your own terms. You can also send a professional invoice with Grey and get paid from the US or any other market without losing margin to your bank. For consultants billing higher day rates, even a small percentage lost to conversion fees adds up to thousands per year.

Frequently Asked Questions

What qualifications do I need to be a consultant?

In most fields, none. There is no universal certification or license required to call yourself a consultant. Clients hire consultants for demonstrated expertise and a track record of results, not for credentials. Some industries (management consulting at large firms, financial advisory) value MBAs or professional certifications, but independent consultants working directly with businesses are judged on their portfolio, case studies, and referrals. If you have been solving problems in your field for five or more years and clients already ask for your strategic input, you are qualified.

How do I know if I am undercharging as a consultant?

Three signals suggest you are priced too low. First, clients accept your rate without negotiation more than 80% of the time. Some acceptance is normal, but if nobody ever pushes back, your rate is below what the market will bear. Second, you are billing hourly rather than daily or per project. Hourly billing signals freelance-level positioning and caps your earning potential at the number of hours you can work. Third, competitors with similar experience and specialisation charge 30-50% more. The issue is usually positioning, not skill: they are framing the same expertise as strategic advice, while you are framing it as task execution.

Can I be both a freelancer and a consultant?

Yes, and many people are. A common model is to consult on strategy with one client while freelancing on execution with another. The risk is that juggling both can dilute your positioning. If you want to charge consulting rates, your public-facing brand should lead with the consulting offer, even if freelance execution is still part of your revenue.

How long does the transition from freelancer to consultant take?

Most freelancers take 6 to 12 months to transition fully. The hybrid phase, where you mix freelance execution with consulting engagements, is normal and necessary. It lets you test consulting pricing, build case studies, and develop your advisory skills without abandoning the freelance income that pays your bills. Rushing the transition by dropping all execution work at once creates income instability. A measured approach is to shift 10-20% of your work toward consulting each quarter until the balance tips.

Do consultants charge by the hour or by the day?

Most consultants charge by the day or by the project, not by the hour. Day rates signal a different level of engagement and avoid the perception that the consultant is watching the clock. Retainer arrangements (a fixed monthly fee for ongoing advisory access) are also common, especially for long-term strategic work. Hourly billing is more typical of freelancers.

Do I need a company to consult?

No. In both the US and the UK, you can consult as a sole proprietor or sole trader without forming a company. However, many consultants choose to form an LLC (US) or limited company (UK) for liability protection and tax efficiency, especially once their income exceeds $50,000 to $75,000 per year. The structure does not change the work; it changes the legal and tax wrapper around it.

Open a Grey account and get paid in your client's currency, whether you bill as a freelancer or a consultant.

Disclaimer: This article is for informational purposes only and does not constitute financial, tax, or legal advice. Rate ranges are estimates based on publicly available market data and vary by industry, geography, and seniority. Consult a qualified professional before making career or financial decisions. Grey is not a bank. Grey is a licensed financial services provider offering multi-currency accounts.
How to receive payments on Etsy as a seller in Sweden

2 min read

Sweden has a long-standing tradition of craftsmanship, from intricate woodworking to contemporary design. Today, many Swedish artisans are looking for global platforms to showcase and sell their unique creations. Etsy provides the perfect solution — an international marketplace that connects creative entrepreneurs with millions of buyers worldwide. However, receiving payments as a Swedish seller can sometimes be challenging.

This guide will walk you through how to receive Etsy payments seamlessly using Grey, ensuring smooth transactions and better financial management.

Why use Grey for Etsy payments?

Grey simplifies the payment process for Swedish Etsy sellers. Here’s why it’s the best choice:

  • Competitive exchange rates: Maximise your earnings when converting to Swedish kronor (SEK).
  • Secure transactions: Grey’s robust security features ensure your funds are protected.
  • Hassle-free withdrawals: Transfer your earnings to your local bank account with ease.

Also read: How to receive payments on Etsy as a seller in Denmark

How to receive payments on Etsy using Grey in Sweden

Grey provides an easy solution for receiving international payments as a Swedish Etsy seller. Follow these steps to get started:

1. Open your Grey app

Log in to your Grey account or create one to access your international USD bank account.

2. Link your Grey account to Etsy

How to receive payments on Etsy as a seller in Sweden
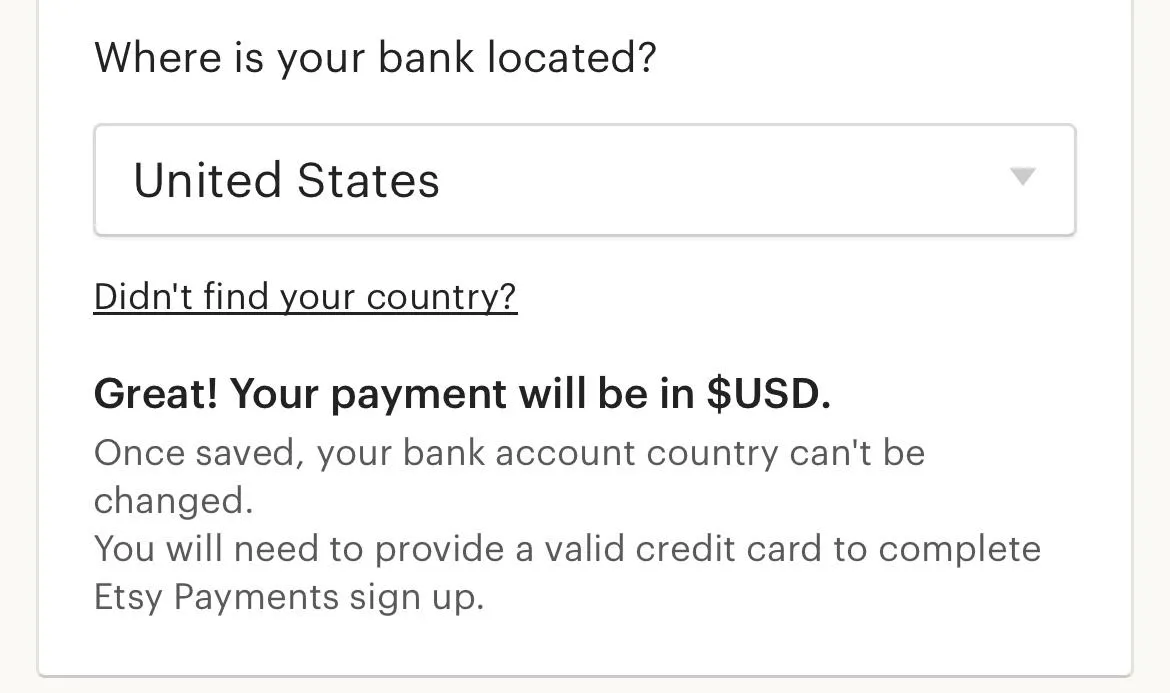
  • Select your bank’s country.
How to receive payments on Etsy as a seller in Sweden
  • Choose whether you’re registering as an individual or a business.
How to receive payments on Etsy as a seller in Sweden
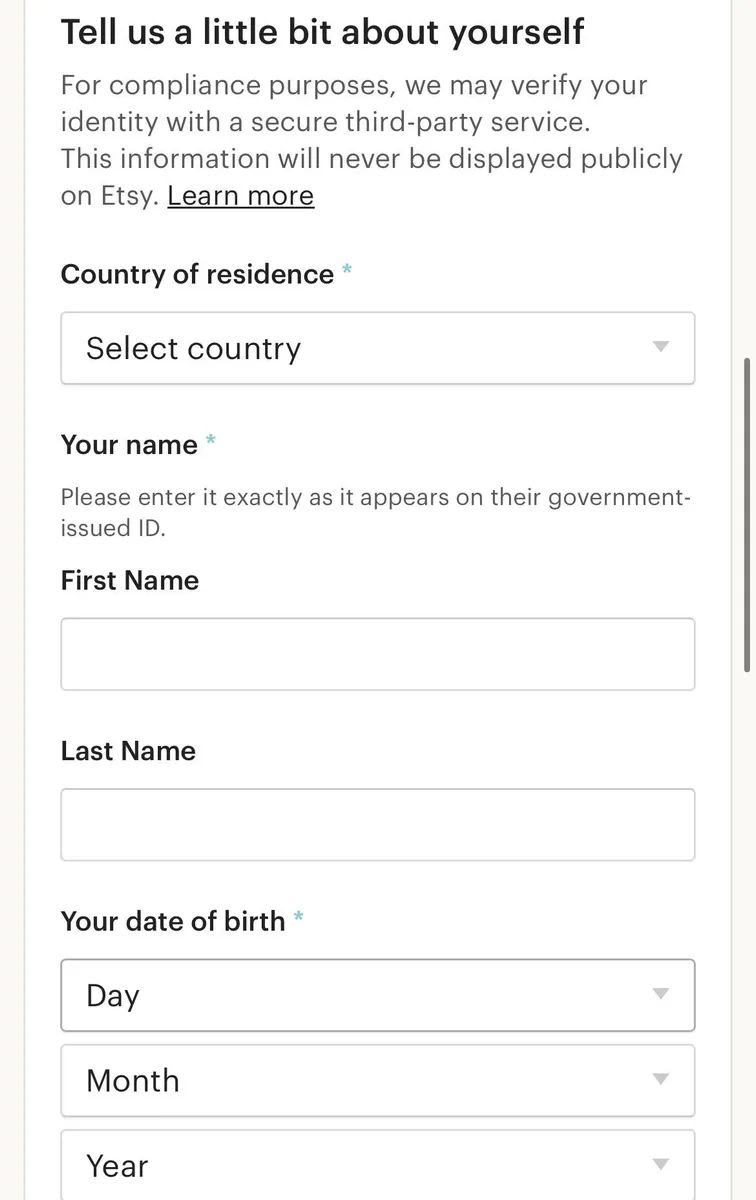
  • Enter your personal information, i.e. name and address.
How to receive payments on Etsy as a seller in Sweden
  • Add your Grey US, EU, or UK bank account details, depending on your preference.
How to receive payments on Etsy as a seller in Sweden
  • Etsy will process payments to your Grey account, making it easy to manage your earnings.

With your Grey account linked, you can receive Etsy payouts directly into your international bank account.It's important to note that you will have to provide a valid ID and depending on the location you pick, may have to fill in a valid address and social security number for your account to be verified.

Also read: How to receive payments on Etsy as a seller in Hungary

Tips for succeeding as a Swedish seller on Etsy

  • Optimise your listings: Use high-quality photos and detailed descriptions to make your products stand out.
  • Offer international shipping: Expand your customer base by providing global shipping options.
  • Respond quickly: Engage with buyers by answering queries promptly and addressing concerns professionally.
  • Leverage social media: Promote your products on apps like Instagram and Pinterest to drive traffic to your Etsy shop.

Also read: How to receive payments on Etsy as a seller in Romania

Simplify Etsy payments with Grey

With Grey, you can stop worrying about receiving Etsy payouts or converting your earnings from Etsy. Manage your finances seamlessly and focus on growing your creative business.

Sign up for a Grey account today and unlock a world of possibilities for your Etsy shop in Sweden.

How to create US and UK bank accounts as a migrant worker in the UK

2 min read

As a migrant worker in the UK, you likely already have a local bank account. But if you work with international clients or send money abroad, you’ve probably had a few challenges — high fees, unfavourable exchange rates, and slow transaction times.

A US bank account can make things easier by allowing you to receive and hold USD without conversion losses. And if you want better financial flexibility, having an additional UK account with a digital bank can help you manage your money more efficiently.

With Grey, you can open US and UK bank accounts easily.

Why do migrant workers in the UK need a US or extra UK bank account?

Even with a UK bank account, opening a US account (or an extra UK account) can be a game-changer. Here’s why:

1. Receiving USD payments without extra fees

If you work for US-based companies or freelance for international clients, you probably receive payments in USD. UK banks often charge high fees for converting USD to GBP. With a US account, you can receive payments directly in dollars without losing money on exchange rates.

2. Holding USD as savings

Slight currency fluctuations can affect your earnings. Holding part of your money in USD instead of GBP gives you more financial stability, especially if you send money abroad regularly.

3. Avoiding expensive international transfers

Sending money across borders? UK banks often have high international transfer fees. With Grey, you can move money seamlessly between your US and UK accounts, saving time and money.

4. Managing finances with an extra UK account

Some workers prefer multiple accounts to separate savings, salary payments, or different income sources. A second UK account can help with budgeting or receiving payments from multiple employers.

Also read: How to manage multiple currencies as an expatriate in Mexico using Grey

Step-by-step guide to opening US and UK bank accounts using Grey

The process is pretty straightforward. Here’s how you can get started:

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

How to create US and UK bank accounts as a migrant worker in the UK
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location.
How to create US and UK bank accounts as a migrant worker in the UK
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
How to create US and UK bank accounts as a migrant worker in the UK
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
How to create US and UK bank accounts as a migrant worker in the UK
  • Once you’re set-up, you’re ready for identity verification — a step required for secure access to financial services.

2. Verify your identity for secure access

Grey requires some basic documents to confirm your identity and keep your funds secure:

  • A valid government-issued ID: A passport or national ID card will do.
  • Proof of address – A recent utility bill or bank statement confirming your residence in the UK.

Verification usually takes a few business days, but accurate and clear uploads speed up the process.

3. Access your US and UK bank accounts

Once your identity is verified, you’re all set to create your foreign accounts:

  • Log in to your Grey account.
  • Go to “Accounts” and select “Create Account.”
  • Choose your preferred currency (USD for a US bank account or GBP for a UK account).
  • Get your virtual bank details instantly.

Your US and UK bank accounts are now ready for use.

Also read: How to manage multiple currencies as an expatriate in Brazil using Grey

Benefits of using Grey as a migrant worker in the UK

  • No hidden fees – Transparent pricing means you keep more of your money.
  • Fast transactions – Receive payments and transfer money without long delays.
  • Global access – Use the Grey app to manage your finances from anywhere, anytime.

Tips for managing finances as a migrant worker

  • Budget wisely: Allocate your income across savings, daily expenses, and remittances to your family.
  • Use secure banking options – Enable two-factor authentication (2FA) for extra security.

Simplify banking across borders with Grey

Managing international payments as a migrant worker in the UK doesn’t have to be complicated. With Grey, you can open a US or extra UK bank account, receive payments seamlessly, and move money across borders.Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

Arrow (up)

Back to top

