



Waiting for a physical card to arrive feels so 1900s, especially when you need it urgently. Beyond the daily inconvenience of carrying a physical card, using one also puts you at risk of data theft. These are some reasons financial institutions now widely offer online debit cards.
An online debit card, also called a virtual debit card, is a card number you can use for online payments without a physical card. Many providers issue one instantly through an app once you set up your account. It draws from your own balance, so no borrowing is involved.
Whether you need a card for a one-off online purchase, want to avoid exposing your main card number to a new merchant, or simply want to start spending online without waiting days for a physical card to arrive in the post, an online debit card solves the problem immediately. This guide explains what these cards actually are, how to get one, and how to use one safely.
What is an online debit card?
An online debit card is a digital card with the same details as a physical card, including a card number, expiry date, and security code. So, it functions like a standard debit card but is digital rather than a physical piece of plastic.
Online debit cards usually charge directly from a linked account balance. So you only spend money you already have, unlike with virtual credit cards.
How does a virtual card differ from a physical card?
A physical debit card usually arrives by post, which might take days. Some banks let you pick up the card at a branch, which usually takes a few minutes, without queues. On the other hand, an online (virtual) debit card is usually generated instantly from the bank or payment platform’s app once your account and identity are verified. This means you can create an account, get a debit card, and start using it within minutes of signing up.
How does a virtual card differ from a prepaid card?
A virtual debit card is also different from a prepaid card. A prepaid card usually requires you to load money onto it before spending. The card balance is somewhat separate from your account balance. Meanwhile, a virtual debit card connects directly to your account and serves as a spending tool for that account.
Where do digital cards work?
You can use a virtual debit card on any online checkout that accepts card payments. The payment is processed just like a physical card number. Depending on the provider, your card may also support Apple Pay and Google Pay, which you can use for contactless payments at physical stores and on public transport.
How to get one instantly
Getting a virtual debit card typically takes minutes, not days, by following this general process.
Step 1: Choose a provider: Look for a bank or fintech that offers instant virtual cards. Check the supported currencies, fees, spending limits, and other account features.
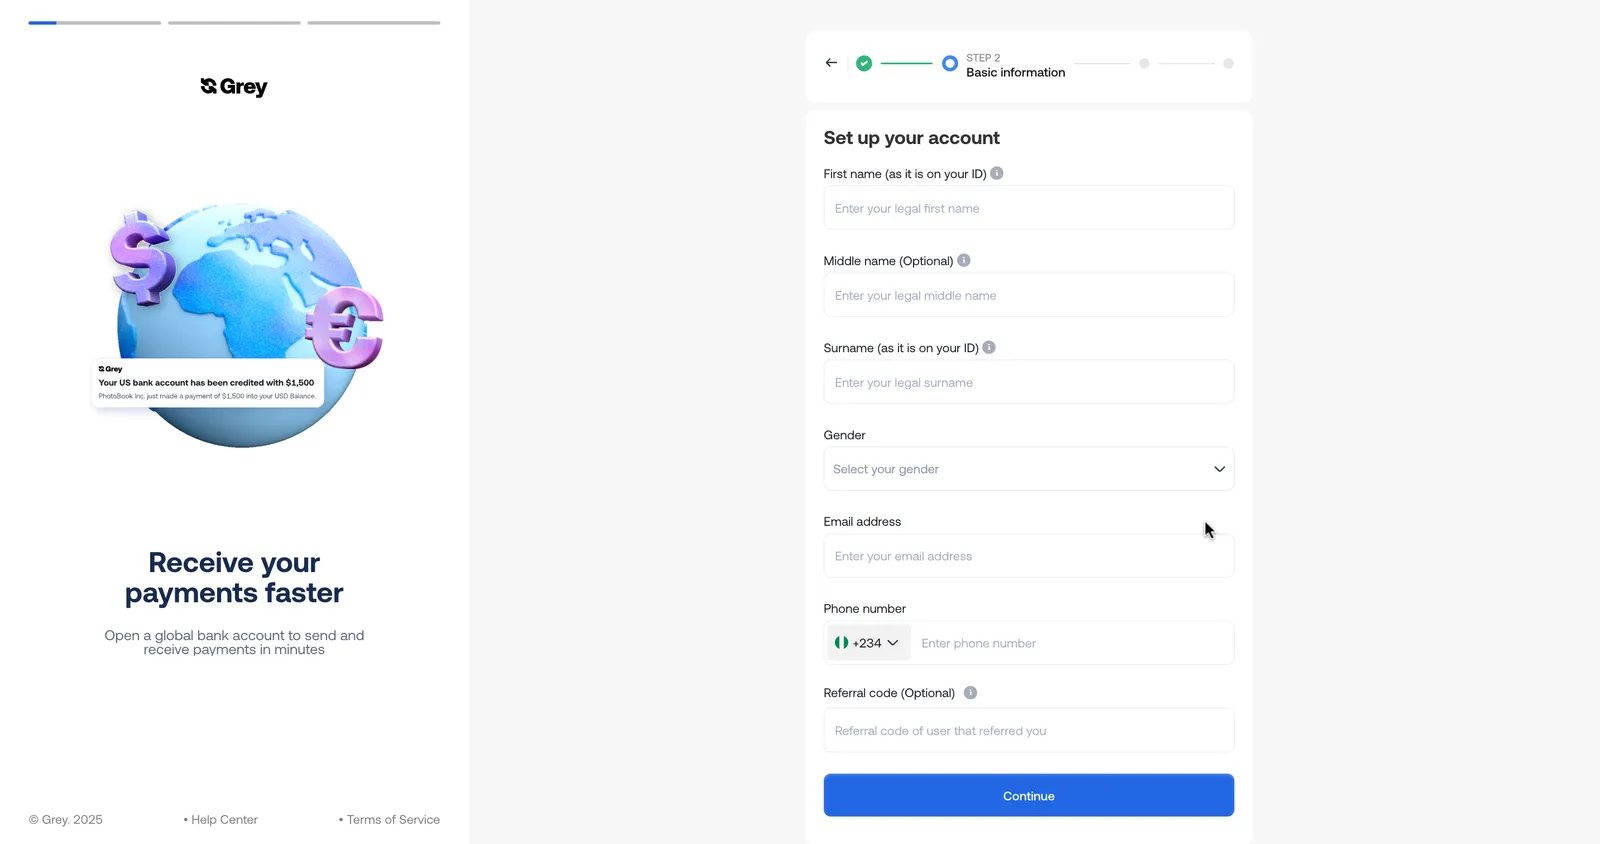
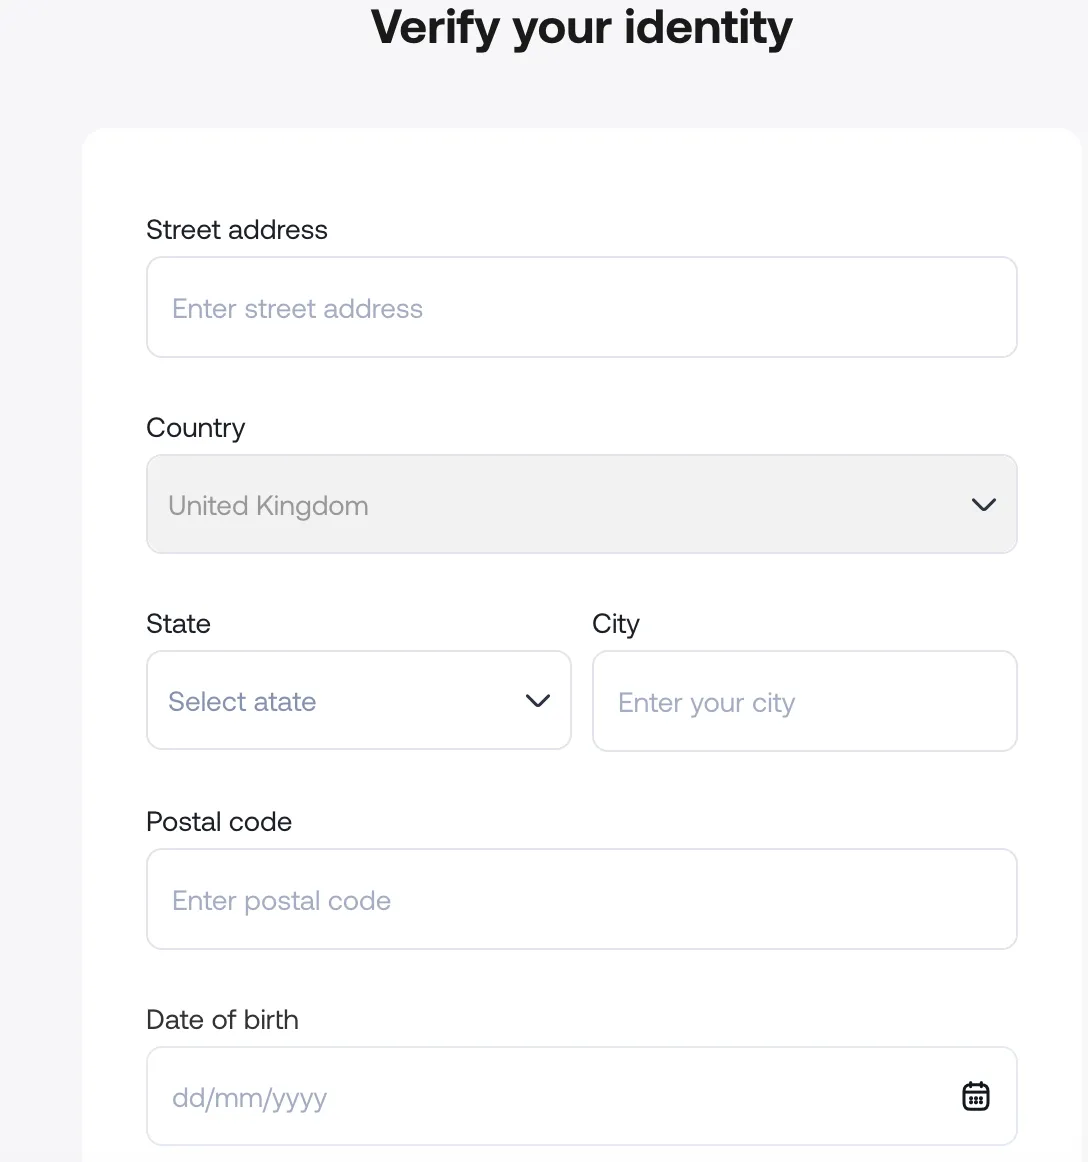
Step 2: Sign up and verify your identity: Provide the required details and complete identity verification. The platform usually requests a valid government-issued ID (passport, driving licence, or national ID), proof of address, and sometimes a selfie for verification. You usually complete this process entirely within the provider's app.
Step 3: Fund your account: Once your account is created and verified, you can deposit money using a bank transfer or other funding options supported by the bank.
Step 4: Generate the card: Once your account is funded, go to the card section in the app and create your virtual card. This may cost money, which is why you need to fund your account beforehand. You should get your card number, expiry date, and security code almost immediately.
Step 5: Start using your card: Enter the card details into any online checkout. Use the card details to pay for online purchases, subscriptions, and other services that accept card payments. Some providers also let you add the virtual card directly to Apple Pay or Google Pay for auto-fill and contactless payments.
Some providers charge a one-time card creation fee, while others issue the first virtual card for free. Check the specific provider's fee structure before proceeding.
How to use an online debit card safely
Virtual cards can make online spending safer because you do not always have to share your main card details.
- One-time or per-merchant card numbers: Some payment platforms let you generate a card number for each merchant or transaction. This limits your risk exposure if that merchant's platform ever gets compromised.
- Spending limits: Setting a specific spending limit on your virtual card prevents unexpected large transactions. This also helps you manage subscriptions and trial periods if you forget to cancel.
- Freezing the card: If you suspect your card details have been compromised, or you simply want to temporarily pause spending, many providers let you freeze the card instantly in the app. Only that card is frozen, so you can still continue using your account and other cards.
- Creating multiple cards for different purposes. Rather than reusing the same virtual card number everywhere, creating separate cards for subscriptions, one-off purchases, and recurring bills makes it easier to track spending and limit the blast radius if any single card's details are exposed.
Online debit card vs prepaid and physical cards
Read more about digital Visa gift cards and how they are different from virtual debit cards.
Using a virtual card for international payments
Beyond everyday online shopping, a virtual debit card is particularly useful if you spend, receive, or manage money in more than one currency.
The Grey virtual card is issued instantly within the Grey app and connects directly to your USD, GBP, or EUR balance. This means purchases in the same currency as your balance draw directly from that balance with no cross-border conversion fee. This is considerably better than a domestic virtual card when shopping internationally or paying for services in a foreign currency.
You can also create multiple cards on Grey for different needs, each with set limits. You can have a card for your Meta ads, one for your international trips, and another for your subscriptions and online shopping. This makes budgeting easy, and you can freeze any card at any time.
After a one-time $5 payment, you can access a Grey card instantly, which works anywhere Visa cards are accepted. Link your Grey card with Google Pay and Apple Pay for extra security and auto-fill on trusted websites. You can also use the card for contactless payments at physical stores, or tap at paypoints when using public transport in supported regions.
Beyond the card itself, holding multiple currencies in one Grey account means you can manage USD, GBP, and EUR balances side by side and convert between them at a disclosed rate whenever it suits you, rather than being forced to convert at the point of every purchase.
If you also need to receive payments from US clients or employers, you can send money from the US directly into your Grey USD account via ACH, with the full amount arriving without correspondent bank deductions.
Get an instant virtual card with Grey at $5 and start spending online in minutes.
Frequently asked questions about online debit cards
What is a virtual debit card?
A virtual debit card is a set of card details (number, expiry, security code) that functions like a physical debit card for online payments, but exists digitally rather than as a physical card. It draws from your own linked account balance, so there is no borrowing involved, and it is typically issued instantly within a banking or fintech app.
Can I get one instantly?
Yes, with most modern banking and fintech providers. Once your identity is verified and your account is set up, generating a virtual card typically takes seconds within the app, with card details available for immediate use at online checkout. This is significantly faster than waiting for a physical card to arrive by post, which can take several business days.
Is it safe to use online?
Yes, generally safer than repeatedly sharing your primary physical card details. Many virtual card providers allow you to set specific spending limits, freeze the card instantly if compromised, and, in some cases, generate per-merchant or one-time card numbers, all of which reduce your exposure compared to using the same physical card everywhere.
Can I use it abroad?
Depends on the specific card and provider. Some virtual debit cards work internationally for online purchases with no restrictions, while others may be limited to domestic use. If you plan to make international purchases regularly, check whether your provider supports foreign-currency balances (to avoid conversion fees) and whether the card works for in-store contactless payments abroad via digital wallets.
Do I need a bank account?
You need an account with the provider issuing the virtual card, which functions like a bank account for most practical purposes (holding balance, receiving deposits, and enabling the card). This doesn't necessarily need to be a traditional bank; many fintech platforms offer fully functional accounts with virtual card issuance without requiring a separate traditional bank relationship.
What is the difference from a prepaid card?
A prepaid card requires you to load funds onto the card before use and often exists as a standalone balance rather than a full account. A virtual debit card is typically tied to a full account, with standard features (transfers, deposits, and often a physical card option) available, and the virtual card is simply the digital spending instrument that draws from that account balance.