Cost of living in London vs New York: A full comparison
Olayoyin Olorunmota
TABLE OF CONTENT
SHARE THIS POST
London and New York. Two cities that define ambition, opportunity, and the art of expensive living. They’re often compared for their energy, culture, and global influence, but there’s one comparison that never gets old: which city is more expensive to live in?
Both have that irresistible, big-city energy: the feeling that something exciting is always happening just one train stop away. Not so exciting, however, are the expenses that would make even a well-paid professional wince at their bank statement. Still, they’re magnets for dreamers, freelancers, and global workers who want to live at the centre of everything.
So, you want the old-world charm of London, with its cobblestones, museums, and rainy-day cafés? Or the nonstop buzz of New York, where everyone always seems to be on the move?
This is a detailed breakdown of the actual living costs in each city. I have everything covered: rent, food, transport, utilities, and even childcare. I even touched on how Grey can help you manage your money.
Grab your calculator, let’s find out which city really costs more to call home.
How much is the typical rent?
Rent is where both cities truly test your patience and financial endurance. No matter how you slice it, housing eats up the biggest portion of anyone’s monthly budget, and both London and New York are notorious for it.
In London, a one-bedroom flat in the city centre, areas like Shoreditch, Southbank, or Notting Hill, costs around $3,100 per month. If you cross the Thames or move a few Tube stops outward to areas like Stratford or Greenwich, and rent dips to around $2,300. While that’s still steep, it’s relatively manageable compared to New York’s rental market.
In New York, a one-bedroom apartment in Manhattan or prime Brooklyn averages around $4,100 monthly, with similar spaces in Queens or the Bronx costing closer to $2,500. That’s a nearly 30% higher average rent than in London for central locations, though the gap narrows in outer boroughs.
Larger homes follow the same trend. A three-bedroom apartment in central London costs roughly $5,100, compared to a staggering $7,800 in Manhattan. It’s this kind of price tag that makes flat sharing so common. Even outside the city centres, the difference remains: an average of $3,700 in London versus $5,100 in New York.
To put it simply, you’ll need to earn about $100,000 a year to rent comfortably in central London, but closer to $130,000 - $150,000 to manage the same standard of living in New York. In both cases, rent alone can take up 40 - 50% of your monthly income if you’re not careful.
Verdict: London is expensive, but New York is on a whole other level. The average renter in NYC spends roughly 20 - 25% more than their London counterpart for the same space.
When it comes to buying a home, both cities make you pay dearly for the privilege of saying “I live here.”
In London, buying property is often less about owning a space and more about investing in history. Yeah, it’s that expensive.
A square metre of city-centre real estate costs around $21,250, making it one of the most expensive property markets in the world. That means a modest 70 m² flat in Central London (think Shoreditch, South Kensington, or Westminster) could cost upwards of $1.48 million before taxes or fees. Step just outside the heart of the city, say, to areas like Stratford, Walthamstow, or Greenwich and the average drops to $11,000 per square metre, bringing that same flat down to about $770,000.
New York, surprisingly, comes in slightly cheaper per square metre, around $15,500 in the city centre. A 70 m² apartment in Manhattan would cost approximately $1.08 million. However, buyers there face higher ongoing costs, including property taxes averaging 1.7% per year, as well as maintenance fees that can add several thousand dollars per month in co-op or condo buildings. Outside central boroughs like Brooklyn, Queens, or the Bronx, property prices average $11,100 per square metre, roughly $777,000 for the same 70 m² flat, which is nearly identical to London’s suburban equivalents.
But price per square metre doesn’t tell the whole story. In London, you’ll often find smaller, older properties that come with preservation restrictions, while New York’s market leans toward high-rise living with modern amenities but sky-high building costs.
If you’re buying as an investor, rental yields are another factor: London averages 3 - 4% annually, compared to 4 - 5% in New York.
Verdict: London wins for long-term prestige and property value stability, but New York offers more substantial returns and newer builds for your money. Either way, in both cities, you’ll need to plan well for a purchase.
If rent is where London and New York empty your wallet, food is where they tempt you to open it again. Both cities are global dining capitals, home to celebrity chefs, street food icons, and everything in between. Regardless of your preference, whether grabbing a quick bite or splurging on fine dining, the numbers tell a fascinating story about how much it really costs to eat well in each city.
In London, an inexpensive meal at a local café or casual restaurant costs around $27, while in New York, that same plate would be roughly $25. It’s a negligible difference, well, until you start dining out regularly. A three-course dinner for two in a mid-range restaurant costs approximately $106 in London, compared to $150 in New York. That’s almost a 40% jump, showing how New York’s dining scene rewards indulgence but punishes your credit card.
For the average person eating out three to four times a week, that difference soon becomes a problem. You could spend $450 - $600 monthly on casual meals in London or nearly $700 - $900 in New York, and that’s before drinks or tips.
Fast food and casual chains paint a slightly different picture. A McDonald’s combo meal costs $11 in London and $14 in New York, making the UK marginally friendlier to quick, low-cost dining. Drinks, however, are where the playing field levels out. A domestic beer costs around $9 in London and $8 in New York, while an imported beer might flip the comparison, $8 in London versus $10 in New York.
And if you’re one of those people who can’t start the day without caffeine (no judgement here), you’ll pay $5.50 for a cappuccino in London and around $6 in New York. Over a month of daily café runs, that’s about $165 vs. $180, proof that even your coffee habit costs more in Manhattan.
Verdict: London wins if you’re eating on a budget, or prefer home-cooked meals and pub lunches over fine dining. But New York outshines for culinary variety: you’ll find everything from $3 pizza slices to $300 tasting menus, often on the same block.
Markets
When it comes to everyday shopping, you’ll find plenty of options in either city, and how far your grocery budget stretches depends on what you buy and where you buy it.
In London, chain supermarkets like Tesco, Sainsbury’s, and Aldi offer solid value, while Waitrose or Marks & Spencer cater to those who don’t mind paying a premium for imported or organic goods. A typical grocery basket, which will include milk, bread, rice, eggs, and fresh fruit, comes to around $40 - $50 weekly for one person, or roughly $200 a month if you mostly cook at home. Prices stay fairly stable, though imported foods (like cheese or wine) push the total higher.
A litre of milk costs $1.70, and a loaf of bread averages $2, which is affordable by big-city standards. But a dozen eggs go for about $4.70, and chicken fillets hover around $9 per kilo. Meat and dairy tend to be where your grocery bill spikes. On the brighter side, locally grown produce like apples ($3.50/kg) or bananas ($1.70/kg) remains budget-friendly, especially at weekend markets or local greengrocers.
New York, however, turns grocery shopping into an Olympic event, one that your wallet rarely wins. Supermarkets like Whole Foods, Trader Joe’s, and Key Food charge noticeably more, with prices varying wildly by borough. Expect to spend around $350 - $450 per month if you cook regularly, and easily more if you shop organic or prefer imported brands.
Basic items tell the story well: a loaf of bread is $4.90 (more than double London’s), and eggs cost $7.20 per dozen. Even staples like rice ($8.20/kg) and milk ($1.60/L) come with a New York markup. Meat and produce are consistently higher too, as chicken fillets average $16/kg, and apples hit $7.50/kg, nearly twice London’s cost.
The gap widens further when you factor in alcohol and tobacco. A bottle of wine costs $11.50 in London but $18 in New York. Cigarettes? $4.50 in London versus a staggering $19 in NYC, making it one of the most expensive places in the world for smokers.
Verdict: London gives you more value for money, especially if you cook often.
Transportation
Let’s be honest, both cities have world-famous public transport systems. London’s red double-decker buses and the New York subway come to mind almost immediately.
In London, getting around isn’t cheap, but it’s incredibly well-connected. A one-way Tube or bus ticket costs around $4.20, and a monthly travel pass averages $240, still one of the most expensive in the world. Daily commuters can save money using Oyster cards or contactless payments, which cap your daily fare at around $10 - $15, depending on the zones.
Taxi rides are another story. A standard black cab starts at $5.50, but the fare rises quickly during rush hour or late at night. Ride-hailing services like Uber tend to be slightly cheaper, though not by much. Fuel costs around $1.80 per litre, making car ownership in London more of a luxury than a necessity. Due to the congestion charges, parking fees, and insurance, most people stick to public transport or cycling.
Over in New York, transportation is slightly more affordable, at least on paper. A single subway or bus fare costs $3, and a monthly MetroCard is $133, nearly half of London’s cost. For daily riders, that’s a massive saving. Taxis start around $5, and while surge pricing can spike fares in Manhattan traffic, ride-sharing apps like Lyft and Uber are everywhere. Fuel is far cheaper, averaging $0.90 per litre, making car ownership less punishing for those outside the boroughs.
Verdict: New York wins for affordability, hands down. But London’s system is better integrated. If you value comfort and connectivity, you’ll tolerate London’s higher costs. But if saving money matters more, New York’s MetroCard is still the golden ticket, even if it sometimes comes with the scent of pizza and street jazz.
Utilities might not be the most exciting topic, but they’re what truly determine whether your apartment feels like home or just an expensive box with windows.
In London, basic utilities for an 85 m² apartment — electricity, heating, cooling, water, and garbage — come to around $330 per month. Prices fluctuate depending on the season; winter heating bills can push the cost closer to $400, while the summer months offer some relief. What’s great, though, is that energy-efficient buildings are becoming more common, especially in newer developments outside central London.
The internet is reasonably priced by global standards. A high-speed plan (60 Mbps or more) averages $42, and most providers offer reliable service. Mobile plans are also competitive, with rates starting at around $19 per month for calls, texts, and 10 GB or more of data. That’s significantly cheaper than in the U.S., and it’s one of the few areas where London actually saves you money.
Meanwhile, in New York, utilities can be a mixed bag. The average cost for the same 85 m² apartment is around $200 per month, but don’t let that fool you; many older buildings in New York have outdated systems, meaning you’ll likely need to budget extra for heating or air conditioning, especially during extreme weather. Some apartments include water and heat in the rent, but electricity can still add up fast.
Where New York really pulls ahead (or falls behind, depending on how you see it) is in connectivity. Internet costs about $66.60 per month, and while speeds are great, it’s nearly 60% more expensive than in London. Mobile plans are also higher, averaging $62 monthly, roughly three times London’s rate.
Verdict:. In London, you’ll pay less for mobile and internet services and enjoy reliable utilities across the board. New York’s older infrastructure and higher data costs make it the slightly more expensive option, especially for remote workers or freelancers who depend on stable, high-speed connections.
LDMAG1
Sports and leisure
The one thing Londoners and New Yorkers take seriously, besides their morning coffee, is staying active and entertained. However, depending on where you live, the cost of staying fit (or just having fun) can vary significantly.
In London, Gym memberships average $64 a month, and you’ll find everything from sleek chains like PureGym and Virgin Active to boutique studios with yoga, spin, or boxing. Public sports centres are affordable too; some charge as little as $8 per session for swimming or fitness classes. If you’re into tennis, court rentals on weekends cost around $25 an hour, and for the less sporty, catching a movie at your local cinema is about $20.
What’s great about London is that so many of the fun activities are free; long runs through Hyde Park, weekend cycling along the Thames, or joining a neighbourhood football group — everyone loves Sunday League. Outdoor activities thrive in London, especially in the summer when the weather finally cooperates.
New York, on the other hand, turns fitness into a high-end affair. A basic gym pass can cost $130 per month, with premium clubs like Equinox charging up to $250 for memberships that include saunas, classes, and towel service (because, of course, it’s New York). Tennis court rentals are pricier too, averaging $59 per hour, and even outdoor recreation in Central Park isn’t entirely free if you want to join an organised sport or use maintained courts.
Entertainment prices are roughly comparable to those in London. A cinema ticket is $20, but New York’s nightlife, concerts, and Broadway shows can make that number skyrocket quickly. A night out with drinks, dinner, and a show can easily top $250, especially in Manhattan.
Verdict: London offers better value and more free fitness options, while New York delivers more variety and experience, if you’re willing to pay the price.
Childcare
If you plan on raising kids in either London or New York, brace yourself, childcare is one of the biggest expenses you’ll face, no matter which side of the Atlantic you’re on.
In London, a full-day private preschool costs around $2,550 per month, depending on the borough and curriculum. Central neighbourhoods, such as Kensington or Islington, tend to be pricier, while outer zones, like Croydon or Walthamstow, have slightly lower fees. London offers a diverse range of childcare options, including local nurseries, Montessori schools, and nanny shares. The UK government also provides subsidies for working parents, with 15 to 30 hours of free childcare available for eligible children aged three to four.
Although primary education is free for state-funded schools, tuition in private schools averages $27,400 per year. However, top-tier institutions such as the American School in London or Southbank International can exceed $35,000 annually. Still, the structure and global curriculum often justify the price.
New York, however, raises the stakes and the fees. Preschool in the city costs approximately $2,230 per month, which may sound slightly lower than in London, but the difference quickly fades once you factor in registration fees, supplies, and additional care hours. For many working parents, hiring a nanny becomes the norm, with costs ranging from $3,000 to $4,500 per month, depending on the hours and experience required.
Private education is where the gap truly widens. An international or private primary school in New York costs a staggering $58,300 per year on average, making it one of the most expensive cities in the world for schooling. Even mid-tier private schools range between $35,000 and $45,000 annually — roughly equivalent to a small mortgage.
Conclusion
Choosing between London and New York is a personal decision. You’ll need to consider the trade-offs you’re willing to live with: rent versus salary, dining versus groceries, public transport versus car costs, and the necessary but often overlooked realities of paying for childcare and schooling.
If you earn abroad or have income in foreign currencies, those trade-offs start to look a little different. Suddenly, a higher salary in New York might cover steeper rents and school fees; a London paycheck might stretch further on everyday items or childcare. The smart move is to think of your finances as a system: how you get paid, how you hold money, and how you convert it all matter as much as the numbers on a job offer.
The right platforms make a real difference. Holding the right currency, timing conversions, and avoiding hidden fees can save you hundreds, even thousands, of dollars a year. For remote workers, freelancers, and families juggling international income and local costs, a multi-currency account with transparent rates and fast payouts is no longer a nice-to-have but a necessity.
That problem exactly is what Grey solves. It doesn’t matter if you’re paid in dollars, pounds or euros, you can receive funds on Grey, hold them in the currency that works best for you, and convert or withdraw at competitive rates, quickly and transparently. That means less guesswork when you’re planning rent, school fees or monthly bills in either city, and more control over how much of your hard-earned money actually reaches you.
Disclaimer: This article is based on researched data and is intended to give you a general overview of the cost of living in London and New York. The figures provided are estimates gathered at the time of writing and may vary depending on location, lifestyle, and market changes.
Morocco is a favourite destination for digital nomads and remote workers for many reasons. The North African nation is the only place in the world with both the Atlantic and Mediterranean coastlines. You also get the Sahara Desert and a ski resort in the Atlas Mountains. Morocco offers a diverse culture, adventure, and lifestyle, complemented by affordable living costs and an impressive digital infrastructure.
Picking the best digital nomad spots in Morocco wasn’t easy, since there are so many great places to choose from. Here’s what we considered when making this list:
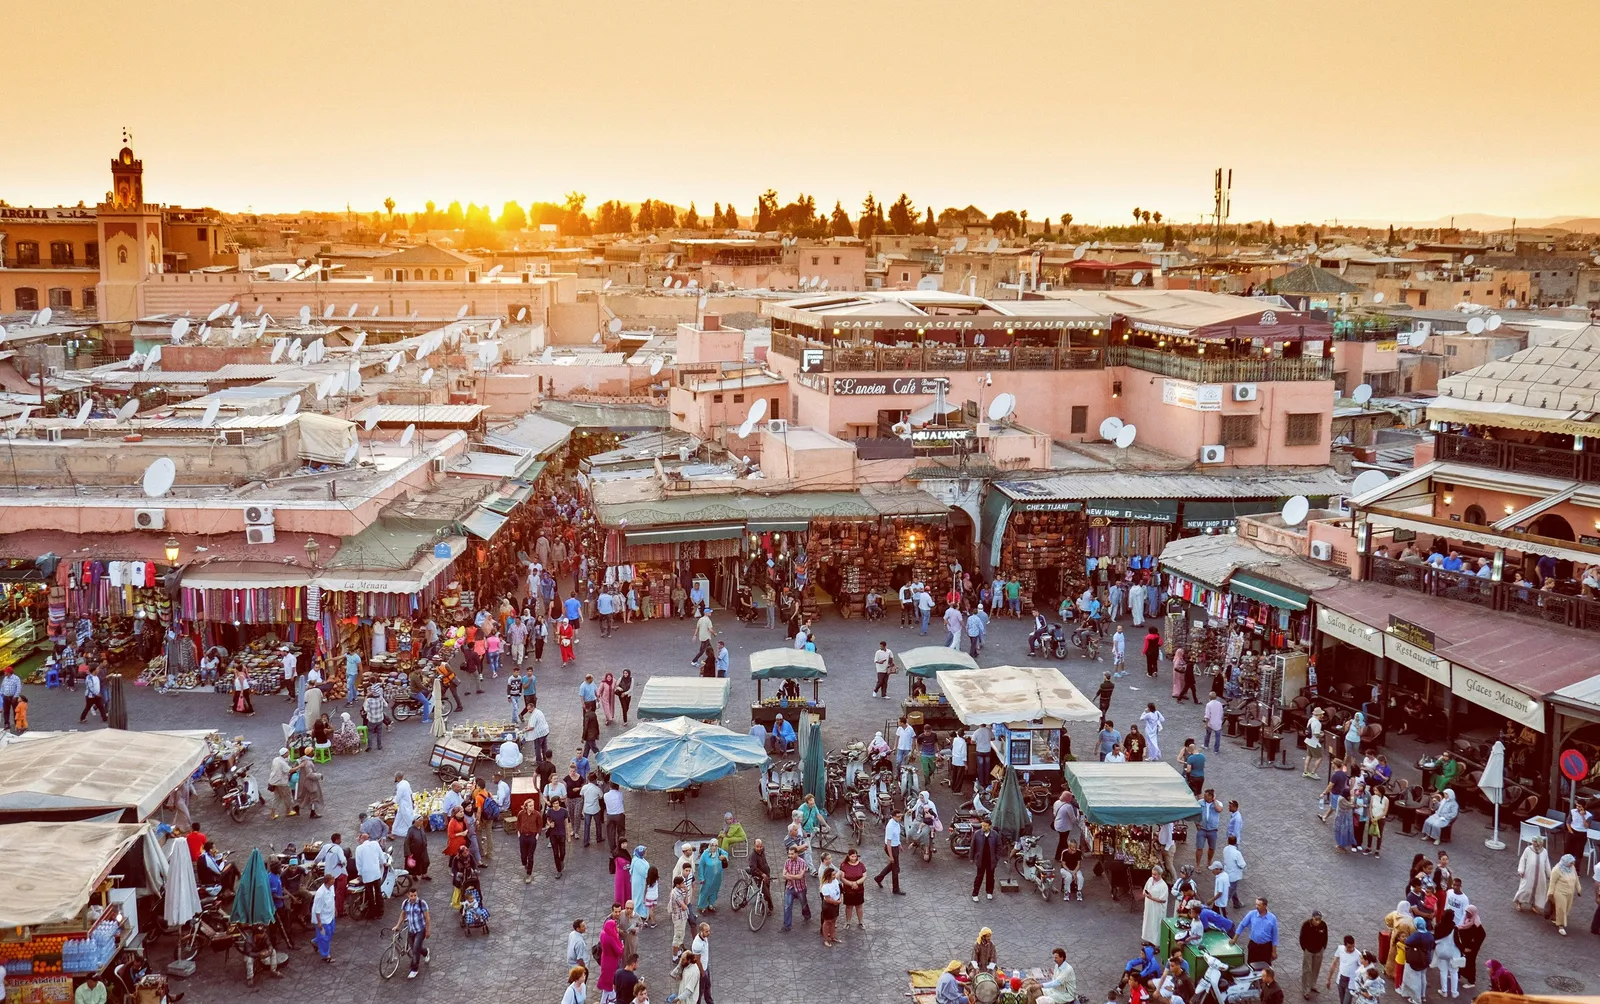
Marrakech is an emerging hub for digital nomads and one of Morocco's imperial cities. It offers a blend of rich cultural background and modern amenities at a low cost of living. There is a growing digital nomad and expat community, along with great coworking spaces offering fast internet speeds. From the labyrinthine souks of its medina to Jardin Majorelle, Bahia Palace, and Yves Saint Laurent Museum, Marrakech has a lot to explore when you are off work.
Essaouira
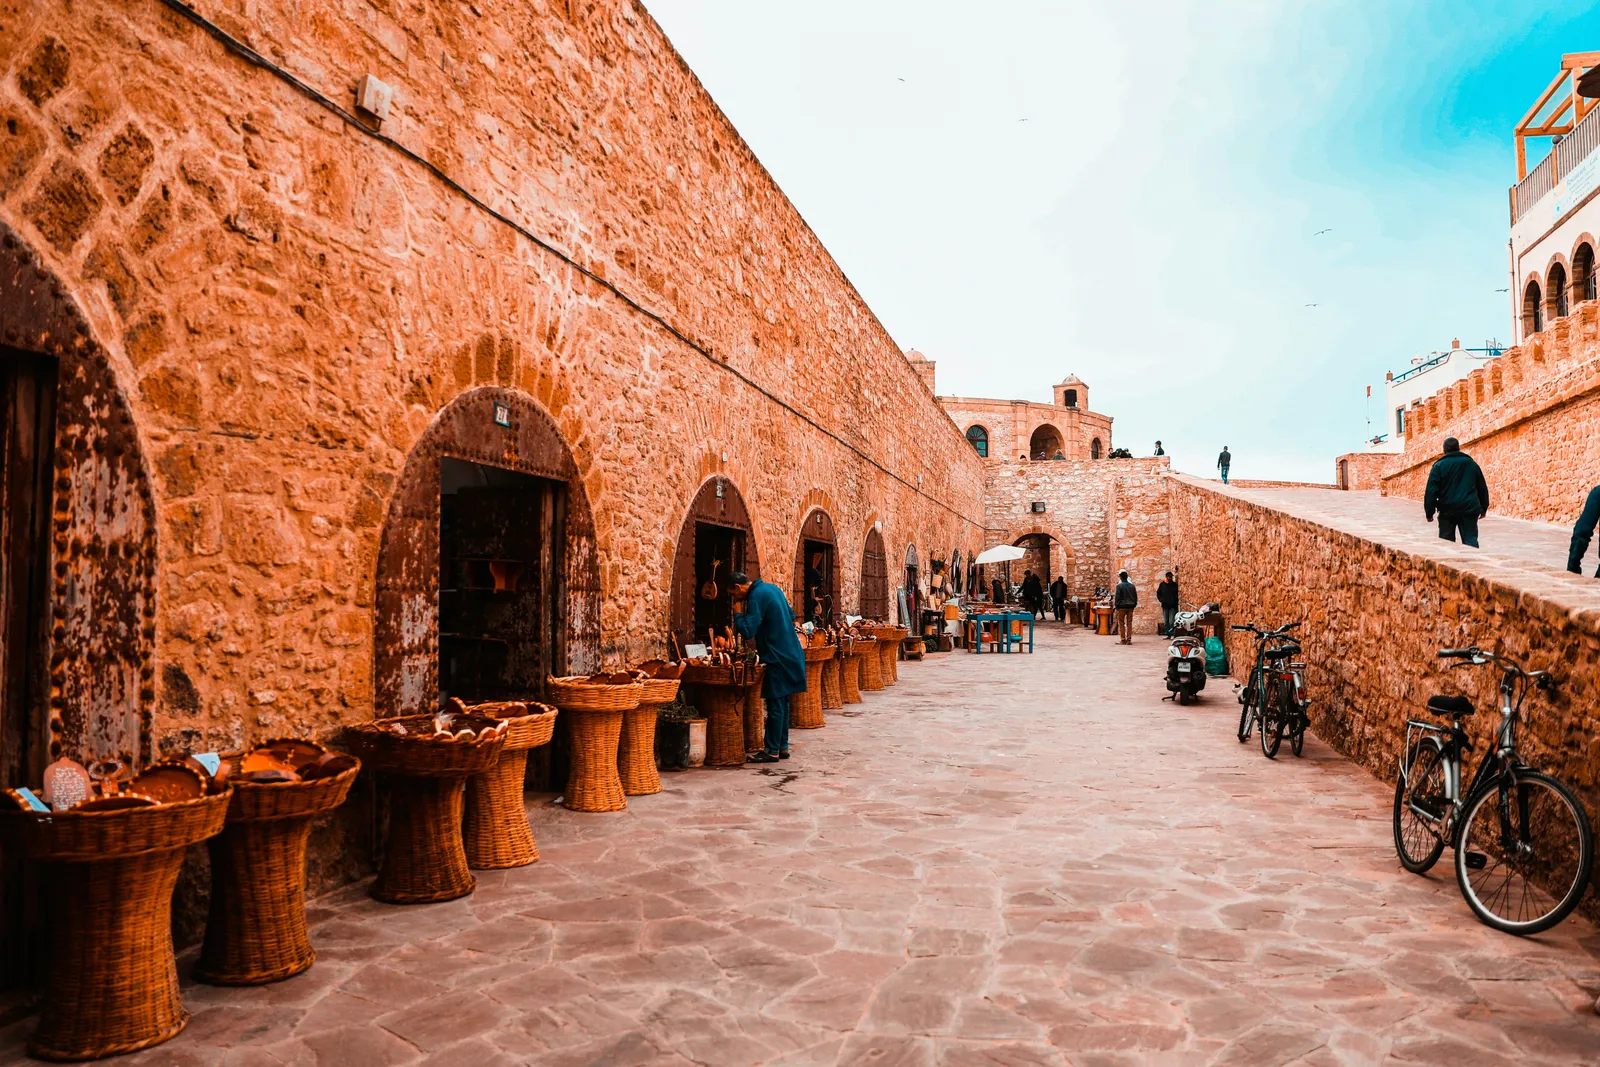
If you want a more laid-back city by the Atlantic, Essaouira is the perfect place for you. It is a port town with many beautiful beaches, art galleries, and the UNESCO-listed 18th-century medina. Sample the local cuisine and exquisite seafood options. Everything about Essaouira inspires creativity. Its serenity and clean air create the perfect environment for productivity. There are workspaces and cafes with great internet access and the appropriate comfort to get work done.
Taghazout
This is a small fishing village near Agadir with a vibrant surfing culture. While it isn’t as popular as the bigger cities on this list, digital nomads flock to Taghazout for its calm, golden beaches, yoga studios, and excellent accommodation options. You also get many coworking spaces scattered across the village, surf camps, yoga retreats, and a growing community of remote workers. The locals are very welcoming, and it is a great town for networking. The natural pools, waterfalls, and mountain villages of Paradise Valley are a must-see. You can also explore the Atlas Mountains, view the town from a cable car, or sandboard during your leisure hours.
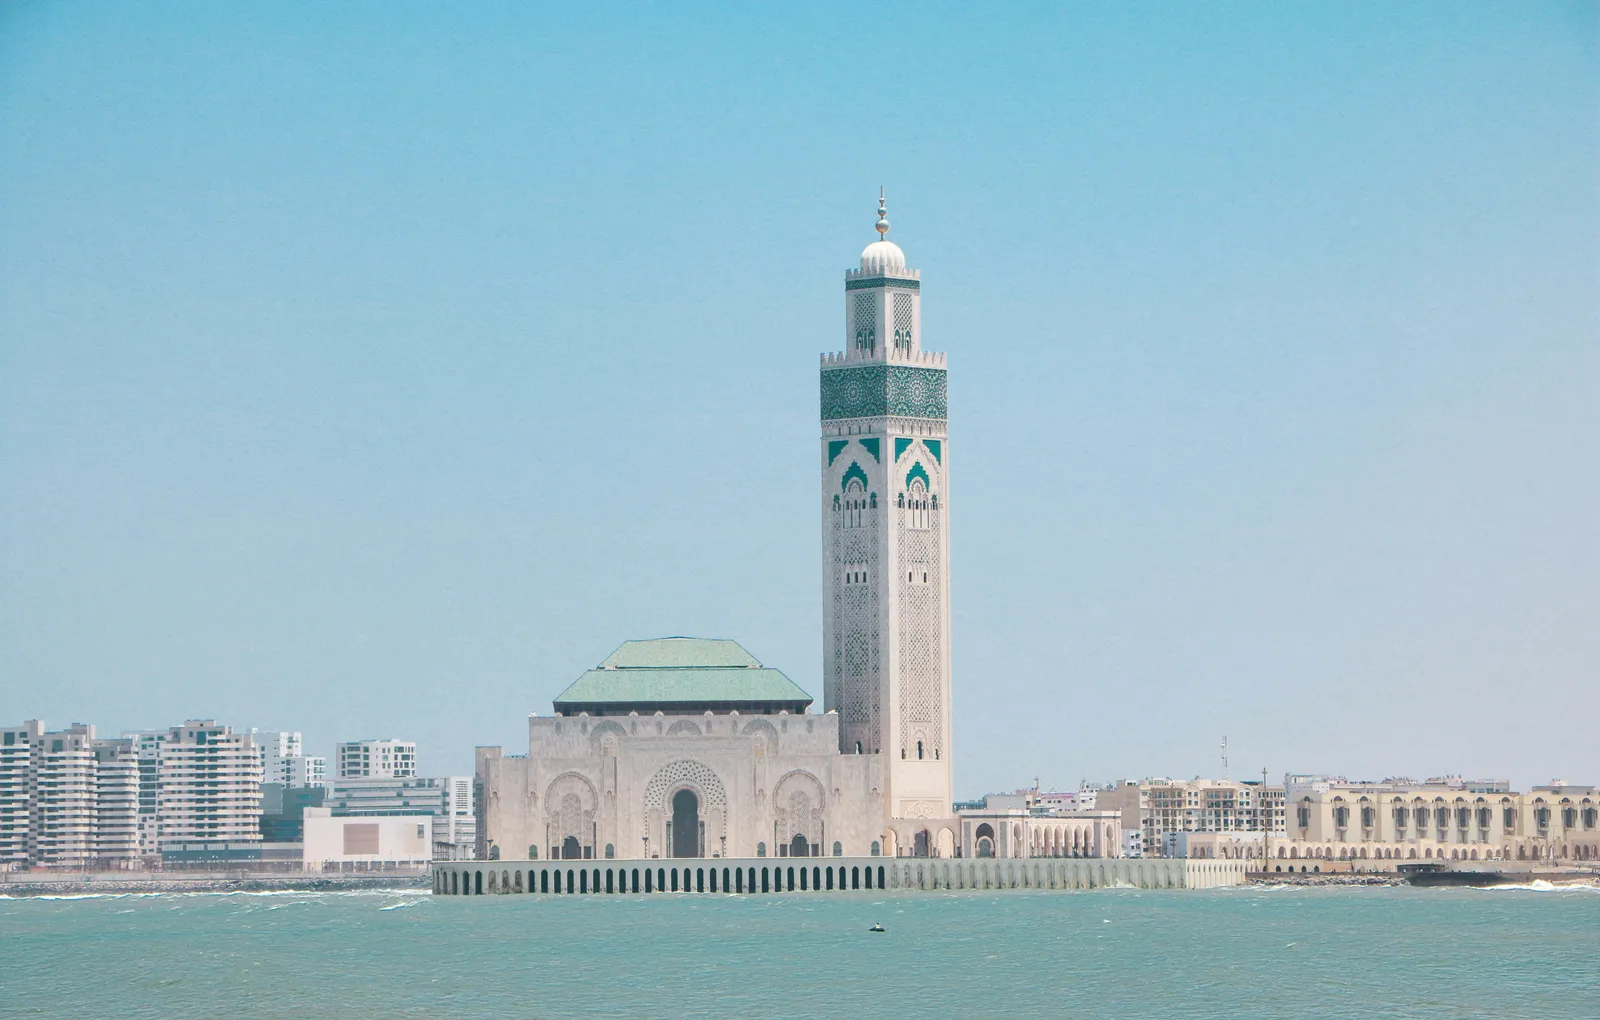
The economic centre of Morocco is home to many remote workers, who work and explore the beauty of the coastal city. Casablanca is Morocco’s largest city, offering an urban landscape, great digital infrastructure, and some cultural exposure. If you are a fan of a bustling city, you get all that a modern city anywhere in the world has to offer, even the traffic in Casablanca. Its vibrant nightlife and efficient transportation system make it an ideal city for adventure. The magnificent view of Hassan II Mosque, fine dining at Rick’s Cafe, and La Corniche’s waterfront promenade will make you look forward to your leisure hours.
Rabat
Rabat offers a delicate balance between the bustling Casablanca, the laidback Essouira, and the historical Marrakech. The capital city boasts a coastal landscape with exquisite beaches and is home to historic sites such as the Kasbah of the Udayas, the Royal Palace of Rabat, the Mausoleum of Mohammed V, and the iconic Hassan Tower. There are many parks, such as the Andalusian Gardens and the Rabat Zoo (Jardin Zoologique de Rabat), for outdoor relaxation. As the political and administrative nexus of Morocco, Rabat has a budding community of expats and digital nomads with a strong sense of community. Compared to other capital cities in the world, Rabat is very affordable with co-working spaces, diverse accommodation options, and robust modern infrastructure.
Morocco has so much to offer, but you’ll want a reliable way to manage your money while you’re there. Grey makes it easy with multi-currency accounts, fast payments, low fees, and competitive exchange rates. You also get a virtual USD debit card for easy online payments.
Freelancers live for creativity. You sit down to create, ideas flowing, momentum building, then suddenly you remember that invoice you haven’t sent, or that overdue client payment. Just like that, the spark fizzles.
Bad financial admin essentially hijacks your creativity. That’s why you need to manage it well, to give you more time to focus on creativity.
Before writing this article, I conducted a thorough study to determine what freelancers find most difficult. One of the most common answers was “sorting out finances.” Okay, looking back now, maybe asking a couple of my freelancer friends shouldn’t count as a “thorough study,” but you get the point.
You can also try it. Ask any freelancer what they dread most, and chances are “chasing payments” will rank near the top. Add in tracking expenses, converting currencies, and worrying about tax season, and you’ve got a recipe for constant distraction.
Switching between “creative brain” and “spreadsheet brain” is exhausting. Every time you break focus to send a reminder email or check an exchange rate, you lose momentum. That lost flow is harder to get back than the admin was worth.
Creativity thrives on freedom, exploration, and uninterrupted focus. Admin is its opposite: rigid, repetitive, and structured. Trying to balance the two can be a problem.
The problem isn’t that admin exists, it’s that it constantly interrupts the creative process. And the more interruptions, the less space your brain has to experiment, imagine, and innovate.
The real cost for freelancers
When admin creeps into your creative hours, three things happen:
Lost time: Hours spent sending invoices or calculating fees are not spent creating or earning.
Lost money: Late payments, hidden transaction fees, or missed deductions quietly reduce your income.
Lost opportunities: Stress kills creativity. The more admin weighs you down, the harder it is to produce your best work, leading to burnout.
Your creativity is your biggest asset as a freelancer. The goal isn’t to eliminate financial admin — that’s impossible — but to manage it in a way that lets your creativity thrive.
Because at the end of the day, clients don’t hire you for your invoicing skills. They hire you for the fresh ideas, the bold designs, and the creative spark that only you can bring. Don’t let financial admin snuff that out.
With Grey, you can open multi-currency accounts, have instant conversions, and enjoy stress-free payments. We take the admin off your plate so you can focus on what you do best, creating.
If you were one of those who used to argue for remote work and all its endless possibilities long before the pandemic and the hype, then you know exactly what I mean. Our moment has arrived. And it’s changing not just how we work, but everything around us.
The rise of remote work culture has untied careers from postcodes. Work has expanded across borders, redefined itself digitally, and reshaped how millions think about life and income.
Talent beyond geography
The internet has made geography negotiable. I’m in Brazil, writing for a US-based company alongside colleagues living in Nigeria, Morocco, Canada and the UK. A designer in Nairobi can shape the brand of a startup in Berlin. A developer in Rabat can debug code for a team in San Francisco. And a strategist in Cairo can run campaigns for an e-commerce store in London.
Borders are still there, but now in the form of time zones, currency conversions, and international contracts. And culturally, something shifted. Instead of asking, “Where do you live?” more people now ask, “What do you do?”
If you think about it, the old fixed office schedule was built for a world where everyone worked in the same building. That’s not true anymore.
Global teams now stretch across continents, which means deadlines, meetings, and collaboration happen around the clock. For some, this creates flexibility: you might start your day when someone else is ending theirs, handing over tasks like runners in a relay. For others, it introduces challenges, early morning and midnight calls, or the constant mental math of “What time is it over there?”
The upside is that you’re no longer confined to opportunities in your own country’s time zone. Work is now continuous, and income can be, too.
New money habits for a global workforce
Here’s the part people don’t always talk about: once work went global, money had to follow.
That same designer in Nairobi isn’t paid in Berlin’s euros. That developer in Rabat isn’t always receiving US dollars directly into a local bank. And the strategist in Cairo might get paid in British pounds before converting them back home.
Earning globally means changing money habits and learning to live in different currencies, exchange rates, and platforms. It has given rise to an entire ecosystem of tools, from multi-currency accounts to crypto wallets, that make it easier for people to actually access the money they work for.
Remote work culture is becoming part of our identity
When you can work from anywhere, the boundaries between work and life blur. That has downsides (answering emails at dinner, never fully “logging off”), but also upsides.
For many people, global work has become a way to fund a digital nomad lifestyle. You can take your laptop to Bali, work from a co-working hub in Mexico City, or split your year between Cape Town and Lisbon.
The story isn’t only about digital nomads, though. Even expatriates and locals working remotely for foreign companies are rethinking what career stability looks like. Flexibility and choice now sit much higher on the list than climbing a corporate ladder.
Culture is blending in real time
Workplaces have become microcosms of cultural exchange.
Maybe this is the most underrated part of global work. In a single day, you might brainstorm with someone in New Delhi, send deliverables to Paris, and attend a virtual coffee chat with a client in New York.
Over time, this changes how people think, communicate, and live. Global slang spreads faster, humour travels across borders, and working styles evolve.
Global work culture is changing how we think about success, how we structure our days, how we handle money, and how we see the world.
For me, this moment is about designing a life that connects my career, my income, and the freedom to live how (and where) I want.
Grey was built to make it easier to embrace this new way of living. You can get paid in dollars, euros, or pounds, manage multiple balances in one place, and spend easily wherever your work takes you.
I encourage you to sign up on Grey today and start building your life without borders.
When you walk into a physical office, you see culture everywhere: the buzz of conversations, the posters on the walls, even the way people queue at the coffee machine. But when our “office” is a Zoom link and a Slack thread, culture has to be something you intentionally design.
For those of us working from different countries, culture almost feels like a passport that makes us feel like we belong, gives a shared identity, and helps everyone work together even when we’re scattered across the world.
Why culture matters more in remote work
While researching this topic, I found that companies with strong cultures actually see up to four times more revenue growth than those that don’t. It really shows how much culture matters. I’d say it’s basically the glue that holds people together across time zones and continents.
One more thing that came up, which is curious but not so surprising, is that people working fully remotely often report being more engaged with their work, but also struggle more with stress and isolation. This shows why emotional and social support is important.
So, yes, building a strong culture matters more than we sometimes give it credit for.
To build belonging without physical walls, remote-first companies experiment with practices replicating (and sometimes improving) the office experience. Here are some patterns that stand out:
1. They write everything down
People naturally absorb culture in an office by overhearing conversations, watching how decisions are made, or noticing meeting dynamics. Remote teams don’t have that luxury, so they turn to documentation as their backbone. They create living handbooks, playbooks, and culture decks that explain everything from how feedback is given to how holidays are celebrated.
Instead of leaving culture unspoken, remote-first companies document expectations, values, and processes in a shared source. This clarity makes onboarding smoother, reduces ambiguity, and helps everyone feel included and aligned.
Remote companies know that trust has to be built. That’s why many of them budget for home office setups, co-working passes, or in-person retreats. Day to day, they use rituals like virtual coffee chats, Slack channels for non-work interests, or online competitions to spark organic bonds.
Culture shows up in these small, consistent moments. Weekly all-hands calls, monthly AMAs, async video updates, or even shared playlists give people ways to connect. These rhythms help maintain a sense of team identity and belonging, even without a shared office.
3. They balance async with face time
Remote teams thrive when they avoid the trap of “always online.” Instead, they balance asynchronous tools, like shared docs, Loom videos, and written updates, with live touchpoints for collaboration. This approach respects time zones and reduces burnout while still leaving space for real-time brainstorming when it matters.
Intentional communication is the key. Casual spaces like random coffee pairings or hobby channels replicate watercooler chats, while structured video calls keep big-picture discussions alive. The balance ensures that work moves forward efficiently without sacrificing human connection.
Without the commute and in-office perks, remote culture shifts toward supporting the whole person. Companies often provide home office stipends, wellness budgets, or mental health days, recognising that healthy employees will surely result in stronger teams.
This emphasis reflects a culture that values people’s lives outside of work, ensuring they have the energy and support to thrive professionally and personally.
5. They put transparency front and centre
In distributed teams, it’s easy for people to feel left out if information doesn’t flow. That’s why remote-first companies embrace radical transparency, from company-wide updates to open Q&As with leadership. The goal is to build trust through openness.
Instead of “management by walking around,” leaders focus on visibility and honesty. When employees feel informed about decisions, they’re more likely to feel empowered, trusted, and engaged in contributing to the company’s success.
Remote culture is designed. By documenting clearly, balancing communication styles, investing in connection, prioritising transparency, and creating rituals, remote teams prove you don’t need an office to feel like a team.
Keeping your money safe at any given time can be challenging, and when you’re relocating or travelling internationally, it becomes even trickier. Carrying too much cash is risky, so it’s smarter to rely on secure banking options like international accounts or multi-currency cards. Trusted money transfer services and strong online security measures, like two-factor authentication, also go a long way in preventing fraud.
In this article, we’ll share practical tips on how to safeguard your money while moving abroad. From avoiding common scams to choosing the safest transfer methods, you’ll learn how to protect your finances and travel with peace of mind.
Key benefits of relocating abroad for modern workers
1. Broader career opportunities
Relocating exposes you to global job markets, giving access to roles, projects, and industries that may not exist in your home country. It opens doors to unique experiences, promotions, and skill-building opportunities that accelerate your career growth.
2. Cultural intelligence
Living in a new country teaches you to understand and navigate different cultures. You gain empathy, adaptability, and communication skills, which are invaluable in today’s diverse and interconnected workplaces.
3. Personal growth
Relocation challenges you to step out of your comfort zone. You build independence, resilience, and confidence, learning to handle unexpected situations and adapt to change effectively.
4. Expanded professional network
Working abroad helps you connect with professionals from different industries and backgrounds. These connections provide mentorship, collaboration opportunities, and insights that can enhance your career and open doors worldwide.
Proven tips to keep your money safe while relocating abroad
1. Password-protect devices
Always secure your phones, tablets, and laptops with strong passwords or biometric locks. Enable two-factor authentication on banking apps and email accounts to prevent unauthorised access. If a device is lost or stolen, remote wipe features can protect sensitive financial information from being compromised.
2. Avoid isolated ATMs
When withdrawing cash, choose well-lit, busy ATMs in safe locations such as banks or shopping centres. Isolated machines increase the risk of theft or skimming devices. Staying vigilant reduces the chances of fraud or robbery, keeping your money and card details safer while you navigate a new city.
3. Spread your money
Don’t keep all your cash or cards in one place. Use a combination of wallets, travel pouches, or secure bags to distribute funds. Spreading money reduces risk; if one stash is lost or stolen, you’ll still have access to other funds for emergencies and daily expenses.
4. Keep money discreet
Avoid flashing cash or expensive cards in public. Use slim wallets or hidden pouches under clothing. Being discreet minimises attention from pickpockets or opportunistic thieves, helping you move through unfamiliar areas safely without drawing unnecessary attention to your valuables.
5. Be attentive with bags
Always keep bags and backpacks close, ideally in front of you or secured to your body. Choose anti-theft bags with lockable zippers. Being attentive and cautious in crowded areas reduces the risk of snatching or accidental loss, keeping your belongings and money safe while you travel.
Simplify relocation with Grey
Relocating comes with lessons, opportunities, and the responsibility of keeping your money safe. From learning adaptability as a modern worker to staying vigilant with your finances, every step matters. With Grey, you can move funds securely, access multiple currencies, and settle in with ease.
Moving money across borders has always been tricky. If you’ve ever tried sending dollars from one country to another, you’ll know the story too well. Delays, high fees, confusing exchange rates, and sometimes even failed transfers. But things are changing. With digital banking, fintech platforms, and the rise of crypto-based assets like USDC, cross-border transfers are becoming more accessible.
Today, freelancers, businesses, and everyday professionals are discovering new ways to move money faster, cheaper, and smarter.
In this article, I’ll explain how USD and USDC transfers work, what sets them apart, where they overlap, and how to choose the right option for your needs.
Why do cross-border transfers matter more than ever?
The internet, not borders, now defines opportunity. However, many payment systems still trail a bit in their development. Transfers can take days and often pass through outdated banking systems that weren’t built for the pace of the current digital economy.
This is why new forms of money movement have become more common. The US dollar remains the foundation of international trade. At the same time, USDC, a digital stablecoin pegged 1:1 to the dollar, is redefining what’s possible by offering near-instant, low-cost transfers without relying on traditional banking rails.
Together, USD and USDC are shaping a new era of cross-border payments that’s faster, more flexible, and better suited to how people and businesses work today.
USD transfers: The familiar option
The US dollar has long been the backbone of international trade. In fact, more than 80% of global forex transactions involve USD, making it the most trusted and widely accepted currency for cross-border payments. Whether you’re a freelancer invoicing a client abroad or a company paying international suppliers, USD will likely be the default choice.
When you send money in dollars, there are a few common routes. The most traditional is the SWIFT network, the global messaging system connecting banks. It’s reliable and secure, but transfers can take several days and incur hefty fees.
Then there are fintech platforms like Grey, Wise, or Payoneer, which use more innovative infrastructure to speed things up and reduce costs, making USD transfers more accessible for everyday professionals.
For bigger transactions, businesses often still rely on bank-to-bank wires, which get the job done but aren’t always friendly to smaller amounts thanks to steep charges and hidden exchange markups.
The strength of USD transfers lies in their universal acceptance. It’s a stable, recognised currency that works seamlessly for individuals and businesses. But that familiarity comes with trade-offs. Transfers via banks can be expensive, with fees that quietly reduce earnings, and delays that turn a simple payment into a waiting game. For anyone relying on regular cross-border income, these inefficiencies can be discouraging.
Unlike volatile cryptocurrencies such as Bitcoin or Ethereum, USDC is a stablecoin designed to mirror the value of the US dollar 1:1. Every USDC in circulation is backed by equivalent dollar reserves, which means its price doesn’t swing up and down. You get the speed of crypto without the drama of speculation.
The real magic of USDC lies in its movement. Instead of waiting days for a SWIFT transfer to crawl through banking rails, a USDC transaction can land in someone’s wallet within minutes, no matter where they are. Payments move across blockchain networks like Ethereum, Solana, or Binance Smart Chain. A client in London could send you USDC at midnight, and you’d see it in your wallet almost instantly.
From there, you have options. You could hold it as digital dollars, spend it with platforms that accept USDC directly, or automatically receieve it as USD with Grey. For freelancers and businesses, this means fewer middlemen, lower costs, and much faster access to funds compared to traditional banking.
That said, USDC isn’t without potential drawbacks. To use it confidently, you need at least a basic understanding of how crypto wallets and transfers work. And while sending and receiving is simple, converting it into spendable cash usually requires exchanges or fintech platforms, which adds an extra step. Grey lets you receive USDC as USD, allowing you to receive funds without needing a manual exchange or a third-party platform.
Finally, the regulation of stablecoins is still evolving worldwide. The status isn’t crystal clear in some countries.
Still, for anyone tired of waiting days and losing money to hidden fees, USDC offers a glimpse into the future of borderless money: fast, cheap, and globally accessible.
It’s not really an either-or situation as they play different roles in the cross-border ecosystem, but the smartest creators and businesses are learning to use them side by side.
If you’re dealing with corporate clients or large organisations, they’ll likely stick to what they know: USD via bank transfer. It’s the default language of global commerce, universally recognised, and often required for official contracts and large invoices. The small trade-off is speed and cost.
On the flip side, if your income comes from digital-first platforms, startups, or international freelancers, you’ll start to see more USDC in the mix. These players care about speed and efficiency. With USDC, you could receive funds in minutes, often at a fraction of the cost. That means faster access to cash flow, essential for independent creators and small businesses that can’t afford delays.
The real edge comes when you’re able to manage both. Having accounts that can handle USD and USDC gives you maximum flexibility. You can accept traditional corporate client transfers while tapping into the new, faster rails of stablecoins without missing a beat.
What to watch out for in cross-border transfers
Here are significant things you shouldn’t overlook when making cross-border payments:
Conversion fees
This is the silent killer of international payments. Banks and some platforms often hide markups on the exchange rate, meaning you lose money every time you convert. Always compare the offered rate against the mid-market rate before hitting send. Grey shows transparent FX rates so you know exactly what you’re paying.
Transfer speed
This depends on your situation. A corporate payment in USD via SWIFT might take several business days, while a USDC transfer could land in your wallet in minutes. If cash flow is critical, say paying contractors or covering ad spend, opting for faster rails can make a big difference.
Security and compliance
Money moves fastest when it’s trusted. Using regulated platforms like Grey that follow AML (Anti-Money Laundering) and KYC (Know Your Customer) rules ensures your transfers aren’t flagged, delayed, or frozen.
Scalability
A one-off transfer is easy to manage, but what happens when you pay 20 freelancers monthly or receive recurring payments from multiple clients? Look for solutions that offer bulk payouts, automated reporting, and clean transaction histories. The focus is on making your business operations sustainable as you grow.
Cross-border payments are moving toward hybrid models. USD may remain the anchor for stability, while USDC and other stablecoins will bring speed and efficiency. According to a report by PwC, more than 60% of financial institutions are exploring blockchain solutions for payments.
For freelancers and businesses, the takeaway is simple: don’t box yourself into one method. The smartest professionals are already combining both currencies, holding USD for big client contracts while leveraging USDC for quick transfers or digital-first clients.
The global economy is moving fast; the winners will be those who can adapt, choose the right platforms, and keep more of what they earn. One of such platforms is Grey, which gives you the freedom to earn, hold, and transfer in the way that suits your global work life best.