<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt#article","headline":"How to open US bank accounts in Egypt","description":"Learn how to easily open a US bank account while living and working in Egypt","inLanguage":"en","url":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt","mainEntityOfPage":{"@id":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt#webpage"},"datePublished":"2025-01-30T06:46:24.681Z","dateModified":"2026-06-15T17:12:40.002Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/679b1e2ffda6fe1d855b64d6_egypt%20us%20bank%20account.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/679b1e2ffda6fe1d855b64d6_egypt%20us%20bank%20account.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt#webpage","url":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt","name":"How to open US bank accounts in Egypt","description":"Learn how to easily open a US bank account while living and working in Egypt","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to open US bank accounts in Egypt","item":"https://grey.co/blog/how-to-open-us-bank-accounts-in-egypt"}]}] </script>

How to open US bank accounts in Egypt

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Egypt, a land where ancient history meets modern ambition, is quickly becoming a hub for professionals embracing global opportunities. From freelancers working with international clients to entrepreneurs expanding their reach, the demand for smooth and reliable cross-border transactions has never been higher. Grey steps in to simplify global payments, offering access to US bank accounts that empower you to manage your finances seamlessly and focus on growth.

In this guide, we’ll show you how to easily set up your account and make cross-border banking accessible from Egypt.

Also read: Top digital nomad cities for long-term rentals in Africa

Why open a US bank account in Egypt?

  • Simplify global payments: Whether you’re working with clients in the US or expanding your business internationally, a US account ensures faster and smoother transactions without the typical banking delays.
  • Cut down on conversion fees: High exchange rates can eat into your earnings. A US account allows you to receive payments directly in USD, saving you money on unnecessary conversion costs.
  • Tap into global markets: Egypt’s strategic location makes it a bridge between continents. With a US account, you can engage with international clients and partners more efficiently, boosting your professional credibility.

Also read: How to receive and convert foreign currencies to USDC in Egypt

Who benefits from a US bank account in Egypt?

  • Freelancers and remote workers: A growing number of Egyptians are offering their skills to international clients. A US account ensures hassle-free payments, keeping your focus on delivering great work.
  • Small business owners: Entrepreneurs working with global partners can streamline their payment processes, enhancing their cash flow and simplifying operations.
  • Digital nomads: For those exploring the world while working remotely, a US account offers the financial stability needed to thrive without borders.

Also read: 5 top sites to get remote foreign jobs for Africans

How to open a Grey account

Opening a Grey account is straightforward and can be done in minutes.

  • First, visit grey.co on your browser and sign up by creating an account with your email.
https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/671bb64c436b546c4df3ec1a_671bb482c2a42a937d97a4a2_image%2520(10).png
  • Then follow the prompts and ensure you enter your correct details for a seamless setup.
__wf_reserved_inherit
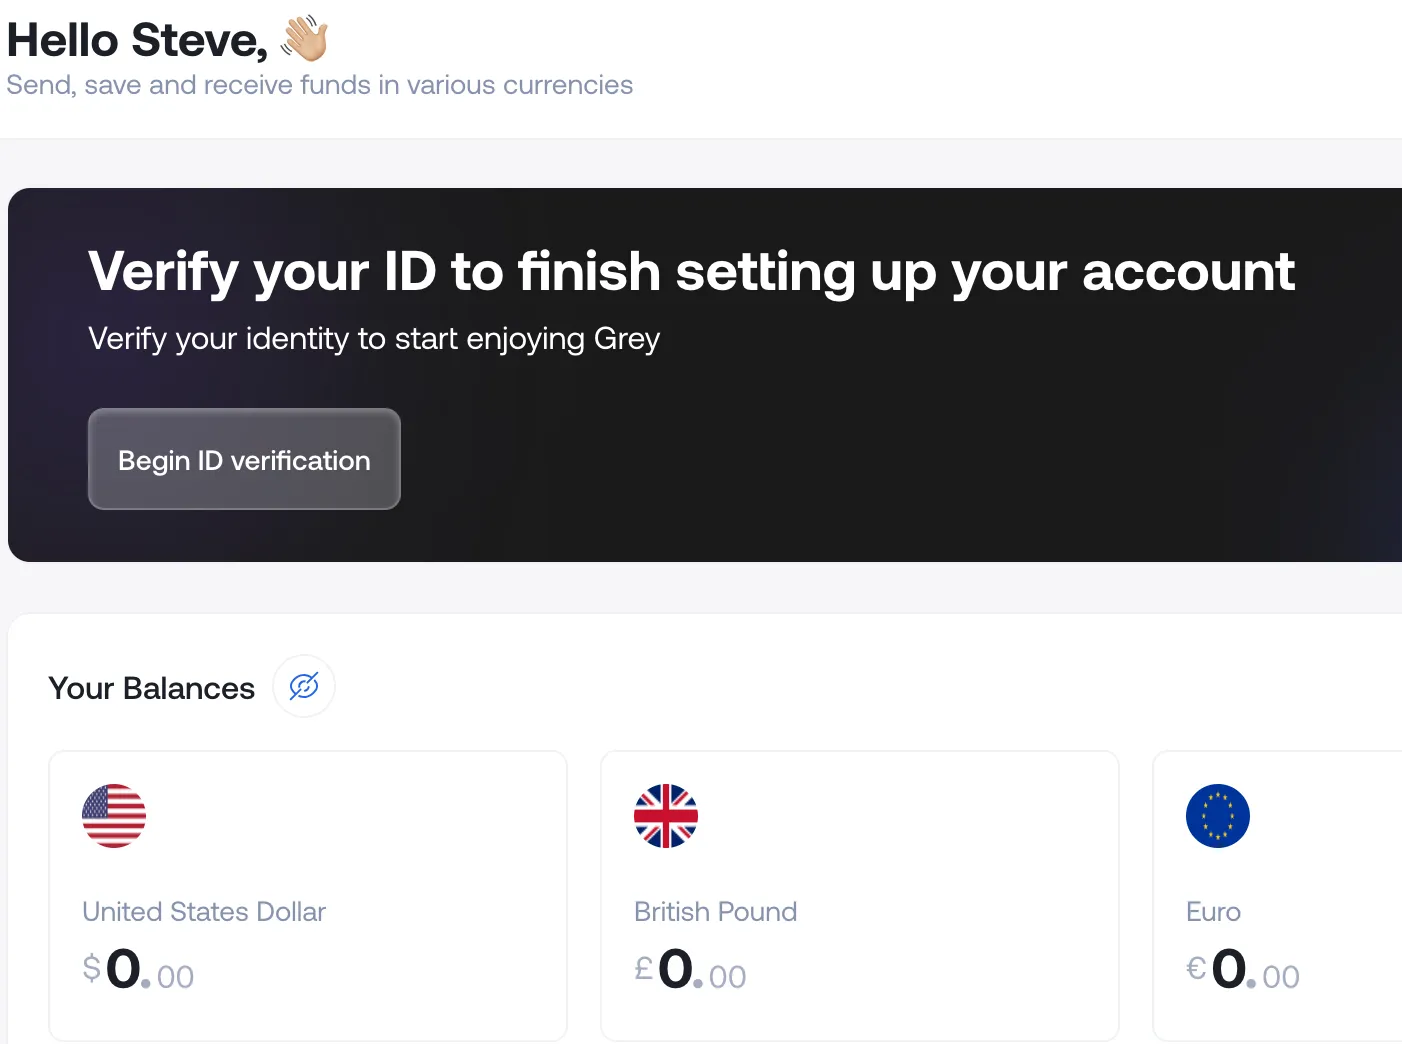
  • Next, you’ll need to verify your identity — a crucial step to comply with regulatory requirements. This process is particularly important for non-U.S. residents, as Grey specialises in providing accounts for individuals outside the United States.
__wf_reserved_inherit

‍

Verification process for Egypt

1. Gather your documents: Have a valid government-issued ID, such as a passport or national ID, and proof of address, like a utility bill or bank statement, ready.

2. Submit your details: Upload your documents through the Grey platform, ensuring clarity and accuracy to avoid any delays.

3. Get verified quickly: Grey’s verification process is efficient and secure, typically approving accounts within minutes or up to 24 hours.

Step confidently into the global financial world—open your free Grey account today.

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

7 best virtual dollar cards in Nigeria

•

•

2 min read

Running ads or paying for subscriptions from Nigeria can be difficult. Standard bank cards are often declined on platforms like TikTok, Facebook, and Google Ads. Missed payments may lead to suspended ad accounts, while foreign transaction fees reduce your profits.

A virtual dollar card solves these problems. With no hidden fees or surprise blocks, you get simple and reliable USD payments every time.

This guide compares eight virtual dollar cards available in Nigeria. Each card has been tested for real-world payments. You'll find honest information on pricing, spending limits, and potential drawbacks, helping you choose the best option for your needs.

What is a virtual dollar card?

A virtual dollar card is a digital payment card issued in US dollars. You can create one online, receive your card details instantly in your app, and start using it right away. There's no physical card, no bank branch visit, and no delivery wait time.

Common uses include: paying for TikTok Ads, Facebook Ads, Google Ads, Netflix, Spotify, Apple Music, AliExpress, Amazon, AWS, Shopify, Canva, and ChatGPT subscriptions.

The main difference between providers is how you fund the card. There are three models:

Multi-currency balance: You hold USD in your account and spend from it directly. No conversion at the point of payment. Grey, Cleva, and Wise work this way.

Wallet top-up: You convert Naira to USD and load a wallet. The card is spent from the wallet. Geegpay, Cardtonic, Eversend, and Chipper Cash work this way.

Bank conversion: You convert Naira to USD at the bank's exchange rate every time you fund the card. ALAT works this way.

The funding model directly impacts your transaction costs. Providers that allow you to hold and spend USD avoid the conversion fees and foreign exchange markups that wallet and bank models apply to every top-up.

Virtual dollar cards in Nigeria: compared

We compare eight providers based on card fees, funding methods, spending limits, card networks, and transaction fees.

Provider Card fee Funding Max balance Card network Currencies Fees Apple/Google Pay
Grey $5 one-time USD/EUR/GBP balance No limit Mastercard USD
EUR
GBP
$0 per txn,
$0 declined
Yes
ALAT

₦1,075 + ₦50/qtr NGN to USD US$20,000 Mastercard USD Not disclosed No
Cleva $3 one-time USD account
(ACH, wire, stablecoins, Naira)
Not published Visa USD $0 per txn,
$0.30 declined
Yes
Geegpay

$3 one-time USD wallet (Naira, P2P) US$60,000/mo Not confirmed USD $0.50 per txn Not confirmed
Cardtonic

$1.50 (Reg) /
$5 (Plat)
Naira wallet (2% funding fee) $5,000/top-up Visa + Mastercard USD $0 per txn,
$0.50 declined
Platinum only
Eversend

$1/mo or $3 Digital wallet Varies Visa USD 3.5%+$0.50
non-USD,
$0.35 declined
No
Chipper Cash

Free Wallet US$20,000/mo Visa USD $0.90 per txn No
Wise

Free (select) Multi-currency balance No limit Visa/Mastercard 40+ $0 per txn,
$0 declined
Yes

‍

1. Grey

Grey lets you hold money in multiple currencies. You get local bank details for the US, UK, and Europe. Clients pay you like you have a bank account in their country. The funds arrive in your Grey balance as USD, GBP, or EUR. Your virtual dollar card spends straight from your USD balance. No Naira conversion. No extra steps or top-ups.

If a client sends you $500, it goes to your USD balance. When TikTok charges $50 for ads, it comes out of that same balance. Nothing lost to conversions or fees.

Best for

Freelancers who earn in USD. Creators or businesses that pay for ads or subscriptions in dollars. Users who want to receive and spend from the same balance without extra steps.

Pricing

$5 one-time card creation fee. You need at least $5 in your USD balance. $4 pays for the card. $1 stays as your minimum balance. No monthly fees. No FX markup when spending in USD from your USD balance. No per-transaction fees. No penalty for failed payments.

Card details

Card network: Mastercard. Apple Pay and Google Pay supported. Accepted at 150 million+ merchants worldwide.

Limitations

Not available in all countries. Check grey.co/cards to confirm availability.

2. ALAT by Wema Bank

ALAT is Wema Bank's digital banking app. You create a virtual dollar card by converting Naira to USD at the bank's exchange rate. Each time you add money, there is a foreign-exchange markup. Your cost depends on the rate Wema sets that day.

Best for

Nigerians who already use Wema Bank and want to keep their dollar card inside their existing banking relationship.

Pricing

₦1,075 to create the card. ₦50 every quarter as a maintenance fee. FX markup on every Naira-to-USD conversion. Maximum card balance: US$20,000. Card validity: 3 years.

Card details

Card network: Mastercard. No Apple Pay or Google Pay support.

Limitations

You always convert from Naira, even if you earn in dollars elsewhere. You cannot receive or hold USD directly in your ALAT account. The bank sets the exchange rate, not the market. This adds cost on every funding event and gives you less control over your real cost.

3. Cleva

Cleva is a USD banking platform for Nigerian freelancers and remote workers. You get a US-based USD account with ACH and wire receiving details. The virtual dollar card is funded directly from your USD balance. Cleva also accepts stablecoin deposits (USDC and USDT), which is unique among Nigerian providers.

Best for

Freelancers on Upwork (free deposits throughout 2026), remote workers receiving USD via ACH or wire, and users who earn in crypto and want to spend via a card.

Pricing

$3 one-time card creation fee. $2 pays for the card. $1 is added to your card balance. No monthly maintenance fee. No per-transaction fee on successful payments. $0.30 fee on declined transactions. USD deposit fee: $1 for deposits under $300; $3 for deposits over $300. Free Upwork deposits throughout 2026. Zero conversion markup when converting USD to Naira. Zero withdrawal fees to Nigerian banks.

Card details

Card network: Visa. Apple Pay and Google Pay are supported. Accepted wherever Visa is accepted online. Cleva Points rewards programme lets you earn back value redeemable as USD or to your Naira account.

Limitations

Cleva charges $0.30 for declined transactions. For ad spend, this is lower than Eversend ($0.35) and Cardtonic ($0.50) but still a cost if your balance runs short.

Multiple user reviews on Google Play report that cards get deactivated unexpectedly, requiring a new $3 purchase to get a replacement card. USD only. No EUR or GBP balances.

4. Geegpay

Geegpay provides a USD account and virtual dollar card for Nigerian freelancers and remote workers. You receive USD directly into your Geegpay wallet. You can also fund via Naira bank transfer (converted at their rate) or through a P2P marketplace where you buy USD from other users. The card draws from your USD wallet balance.

Best for

Freelancers on Upwork, Fiverr, or similar platforms who receive USD and need a card for online spending.

Pricing

$3 one-time card creation fee. No monthly maintenance fee. $0.50 per-transaction fee on every card payment. This is the critical number. At 10 transactions per month, you pay $5 in transaction fees. At 20 transactions, $10. Over three months of moderate use, the transaction fees alone cost more than the card creation fees of most competitors. Inactivity fee: ₦300/month after 6 months of no activity.

Card details

Spending limits: up to $20,000/day and $60,000/month at the highest KYC verification level. Card network not confirmed, but accepted on major platforms.

Limitations

The $0.50 per-transaction fee makes Geegpay expensive for frequent spenders. If you pay for multiple subscriptions or run recurring ad campaigns, these fees compound. The ₦300 inactivity fee means you pay even when you are not using the card. USD only. No EUR or GBP.

5. Cardtonic

Cardtonic offers virtual dollar cards funded through a Naira wallet. You load your wallet via bank transfer or gift cards, convert Naira to USD, and spend. Cardtonic offers two card tiers: Regular and Platinum. The Platinum card adds support for Apple Pay and Google Pay. Cardtonic accepts both Visa and Mastercard, which gives broader merchant coverage than most competitors.

Best for

Budget users who want the cheapest card creation. Users who value Visa and Mastercard dual support. Users are comfortable with a wallet-based funding model.

Pricing

Regular card: $1.50 creation. Platinum card: $5 creation. No monthly maintenance fee. Wallet top-up fee: 1.5% of Naira amount (capped at ₦2,000). Card funding fee: 2% of the Naira value on every funding transaction. Cross-border fee: 2.5% plus $0.50 on non-USD transactions. Declined transaction fee: $0.50. Withdrawal fee: $1. Card funding limit: $5,000 per transaction with no daily limit.

Card details

Card network: Visa and Mastercard (both available). Platinum card adds Apple Pay and Google Pay. Accepted on TikTok, Facebook, Google Ads, Netflix, Amazon, Spotify, ChatGPT, Canva, AWS, and more.

Limitations

The 2% funding fee applies every time you load the card. On a $100 top-up, you pay $2 in funding fees. On $500, you pay $10. Over time this makes Cardtonic more expensive than it appears at the $1.50 creation price. The $0.50 declined transaction fee is a risk for ad spend users. If your TikTok or Facebook ad payment fails, you pay a penalty on top of the failed payment.

6. Eversend

Eversend offers a prepaid virtual dollar card for users in Nigeria, Kenya, and Ghana. You fund the card through your Eversend wallet. It works anywhere Visa is accepted.

Best for

People in Nigeria, Kenya, or Ghana who want a USD card for online shopping or subscriptions.

Pricing

Free card creation. $1 monthly maintenance fee, or $3 one-time to skip monthly charges. FX fees: approximately 3.5% plus $0.50 on non-USD payments. Declined transaction penalty: $0.35.

Card details

Card network: Visa. No Apple Pay or Google Pay support.

Limitations

The $0.35 declined transaction penalty matters for ad spend. If your TikTok or Facebook ad payment fails due to a low balance, Eversend charges you a penalty. For creators running ads, this is a real risk. FX fees of 3.5% plus $0.50 are higher than most competitors. No Apple Pay or Google Pay.

7. Chipper Cash

Chipper Cash offers a virtual dollar card for users in Nigeria and Ghana. You fund the card from your Chipper wallet. The card works anywhere Visa is accepted online.

Best for

People who make online purchases from time to time and want a basic USD card with no upfront cost.

Pricing

Free card creation. $0.90 per transaction. Max spend per transaction: $5,000. Monthly limit: $20,000. Minimum funding: $5.

Card details

Card network: Visa. No Apple Pay or Google Pay support.

Limitations

The $0.90 per-transaction fee is the highest in this comparison. Twenty transactions per month cost $18 in fees alone. Over three months, that is $54 in transaction fees on a card that was free to create. Not suitable for frequent spenders, recurring subscriptions, or ad spend. The monthly $20,000 spend limit may restrict businesses with higher ad budgets.

8. Wise

Wise is a global multi-currency platform. It supports over 40 currencies with exchange rates at near mid-market rates. The virtual card is available only in supported countries. Wise is the broadest option for currency coverage but is not specifically built for the Nigerian market.

Best for

People who move money between countries often and want a multi-currency card for global payments. Users who need currency coverage beyond USD.

Pricing

Free card creation in supported regions. Currency conversion fees are approximately 0.5%. No per-transaction fees. No declined payment penalties.

Card details

Card network: Visa and Mastercard (varies by region). Apple Pay and Google Pay are supported in most regions.

Limitations

You only get a Wise card if your country is on their supported list. Wise is built for money transfers and conversions, not for spending directly from a received USD balance. You may need extra steps to move funds before spending.

What virtual dollar cards really cost over time

Card creation fees are misleading. A free card with $0.90 per-transaction fees costs more in one month than a $5 card with zero transaction fees. This table shows the cost of each provider over three months of regular use (20 transactions per month).

Provider Creation fee Txn fees
(10/mo)
Txn fees
(20/mo)
Declined fee Total
(3mo at 20/mo)
Notes
Grey $5 $0 $0 $0 $5 One-time cost only
Cleva $3 $0 $0 $0.30/fail $3 Plus deposit fees
Geegpay $3 $5 $10 N/A $33 $0.50/txn adds up
Cardtonic (Reg) $1.50 $0 $0 $0.50/fail $1.50 + funding fees 2% on every top-up
Eversend $3 FX fees FX fees $0.35/fail $3 + FX fees 3.5% + $0.50 non-USD
Chipper Cash $0 $9 $18 N/A $54 Highest total cost
Wise $0 $0 $0 $0 $0 If card available

‍

The cheapest card to create is not the cheapest card to use. Chipper Cash is free to create but costs $54 in transaction fees over three months. Grey costs $5 to create and $0 after that. Geegpay costs $3 to create but $30 in transaction fees over three months. Cardtonic costs $1.50 to create but adds 2% on every top-up. The total cost depends on how often you use the card.

Best virtual dollar card by use case

Use case Best provider Why
TikTok and Facebook ad spend Grey Spend from the USD balance. $0 per-transaction. $0 declined penalty. No forced conversion.
Google Ads Grey or Wise Both spend from held USD. Wise covers 40+ currencies for multi-market advertisers.
Freelancers receiving USD Grey or Cleva Both offer USD accounts with local bank details. Cleva has zero withdrawal fees. Grey has no per-transaction fee on card spend.
Subscriptions (Netflix, Spotify, Apple) Grey or Geegpay Both handle recurring payments. Grey links to balance directly. Geegpay charges $0.50 per transaction in each billing cycle.
E-commerce (AliExpress, Amazon) Grey or Cardtonic Both work on major platforms. Cardtonic Regular card costs $1.50. Cardtonic charges 2% funding fee on every top-up.
Budget / light use Cardtonic or Chipper Cash Lowest creation fees. Cardtonic Regular is $1.50 with $0 per-txn. Chipper Cash is free, but $0.90/txn.
Business SaaS (AWS, Shopify) Grey or WorldFirst WorldFirst issues up to 20 cards per business. Grey is simpler for solo operators.
Stablecoin/crypto earners Cleva Only provider accepting USDC/USDT funding. Relevant for crypto-paid freelancers.

‍

Best dollar card for TikTok and Facebook ads in Nigeria

Most people in Nigeria use virtual dollar cards for ad spend. TikTok, Facebook, and Google Ads account for the majority of international card transactions from Nigeria.

If an ad payment fails, your account can get suspended. That stops your campaigns and hurts your sales. You need a card that works without hidden fees or penalties.

Three factors determine which card works for ad spend:

Avoid cards that force Naira-to-USD conversion. Hold USD and spend in USD to avoid extra costs and failed payments. Grey, Cleva, and Wise allow this. ALAT requires conversion on every top-up. Cardtonic charges 2% on every wallet funding.

Check for penalty fees on failed payments. Eversend charges $0.35 per failed transaction. Cardtonic charges $0.50. Cleva charges $0.30. Grey and Wise charge nothing.

Watch out for per-transaction fees. Chipper Cash charges $0.90 per transaction. Geegpay charges $0.50. Grey, Cleva, Cardtonic, and Wise charge nothing per successful transaction.

For creators and businesses running ads from Nigeria, Grey offers a straightforward solution: receive USD, hold USD, and spend USD with no conversions, penalties, or per-transaction fees.

How to get a virtual dollar card in Nigeria

Setup takes minutes.

1. Sign up at grey.co. Free account. Email and basic details.

2. Verify your identity. Upload a government-issued ID.

3. Open your USD account. Create a USD balance with local bank details to receive payments.

4. Fund your account. Receive from clients, transfer in, or convert from another balance.

5. Create your card. $5 one-time fee. $4 pays for the card. $1 stays as your minimum balance. Card is available immediately.

6. Start spending. Pay for ads, subscriptions, or online purchases. Works with Apple Pay and Google Pay.

Frequently asked questions

Does Kuda have a virtual dollar card?

Kuda offers Naira-based virtual cards. For a USD virtual dollar card, use a provider like Grey, Cleva, Alat, or Geegpay.

Does Opay offer a virtual dollar card?

Opay offers Naira card services. For USD virtual cards, Grey, Cardtonic, Cleva, and Eversend are built for foreign currency spending.

How do I get a US virtual card in Nigeria?

Sign up with a multi-currency platform like Grey or Cleva. Verify your identity. Create a USD account. Generate your virtual card. The process takes a few minutes.

Which is the best virtual dollar card in Nigeria?

It depends on the use case. Grey is best for freelancers and creators who earn in USD and want to spend from their balance with no per-transaction fees. Cleva is best for Upwork freelancers (free deposits) and crypto earners (stablecoin support). Wise is best for users who need 40+ currencies. Cardtonic is best for users who want the cheapest creation fee. ALAT is best for users who prefer a traditional bank.

Can I use a virtual dollar card for TikTok ads?

Yes. Grey, Cleva, and Wise are the most reliable for ad spend because they charge no per-transaction fees. Grey and Wise also charge no penalties for declined payments. Cleva charges $0.30 per declined transaction.

What is the cheapest virtual dollar card in Nigeria?

Cheapest to create: Chipper Cash and Cardtonic Regular (free and $1.50). Cheapest to use over time: Grey ($5 one-time, $0 per transaction) and Cleva ($3 one-time, $0 per transaction). Free creation with $0.90 per-transaction fees (Chipper Cash) costs $54 over three months of regular use. $5 upfront with zero transaction fees (Grey) costs $5 total.

Are virtual dollar cards safe?

Yes. You control spending limits, can freeze or delete your card from the app, and your main account details stay hidden during transactions.

Can I receive money on a virtual dollar card?

Most virtual dollar cards are spend-only. Grey and Cleva are exceptions. Both offer USD accounts with bank details that allow you to receive payments directly from international clients. You can then spend from the same balance using your card.

Get your virtual dollar card

Open a Grey account, create your card, and start spending in USD, EUR, or GBP today.

Get started at grey.co.

Mastercard virtual card: How to get one for online shopping

•

•

2 min read

Online shopping has transformed the way people buy everything, from software subscriptions to airline tickets. But with every click comes a familiar concern: Is it safe to enter my card details? Data breaches, phishing scams and merchant hacks have made many shoppers think twice before using their primary debit or credit card online. As a result, digital payment tools that reduce the risk of exposing sensitive card information are becoming increasingly popular worldwide.

One of the most practical solutions is a Mastercard virtual card. Unlike a physical card, it exists only in digital form and is designed for online transactions. It's important to note, however, that Mastercard does not issue virtual cards directly. Instead, banks and financial technology companies provide Mastercard-powered virtual cards to their customers.

This guide explains how Mastercard virtual cards work, where to get one, their advantages, limitations and what you should know before using one for online shopping or international payments.

Also read: How non-US residents can get a virtual dollar card in 2026

What is a Mastercard virtual card and how does it work?

Online payments have become faster than ever, but they've also changed what people expect from a payment card. Instead of waiting days for a plastic card to arrive in the mail, many consumers now want immediate access to a secure payment method they can use within minutes. That's exactly where a Mastercard virtual card fits.

A Mastercard virtual card is a digital payment card linked to a Mastercard account that can be used for online purchases anywhere Mastercard is accepted. Many providers issue virtual cards instantly, allowing users to start shopping online almost immediately. Another advantage is flexibility.

Virtual cards can often be paused, frozen or replaced through an app without waiting for a new card to be delivered. Because your physical card details remain hidden, virtual cards also provide an extra layer of protection against fraud and unauthorised online transactions.

Also read: Mastercard Exchange Rate: How It Works and What You Pay

Best ways to use a Mastercard virtual card for online shopping

Not every online purchase carries the same level of risk. Paying for a monthly streaming subscription, buying software from an overseas website or shopping with a retailer you've never used before often means sharing your card details with merchants you don't know well. A Mastercard virtual card gives you a safer way to complete these transactions without exposing your primary payment card.

Virtual cards are commonly used for subscription services, purchases from international websites, online marketplaces and merchants you haven't used before. Since they work like a regular Mastercard, they're accepted anywhere Mastercard payments are supported online, making them a convenient option for both local and cross-border shopping.

Using one is simple. At checkout, enter the virtual card number, expiry date and CVV security code just as you would with a physical card. If the payment is approved, the transaction is completed normally, while your physical card details remain protected behind the virtual card.

Also read: How non-US residents can get a virtual dollar card in 2026

Where to get a free Mastercard virtual card

The growing demand for secure online payments has encouraged both banks and fintech companies to offer virtual Mastercard options. Today, many providers issue virtual cards that can be activated within minutes, giving users a fast way to shop online, pay for subscriptions and make international purchases without waiting for a physical card to arrive.

When a provider advertises a free Mastercard virtual card, it usually means there is no card issuance fee. However, "free" doesn't always mean there are no costs at all. Some providers charge monthly maintenance fees, foreign transaction fees, currency conversion markups or inactivity charges. Others may require you to fund your account before the card can be used.

Before choosing a provider, read the pricing page carefully. Compare card issuance fees, ongoing charges, funding costs and spending limits. A truly cost-effective virtual card should not only be free to obtain but also affordable to use for your everyday online and international payments.

When should you use a Mastercard virtual card?

Mastercard virtual cards are designed for situations where convenience and security matter most. Here are some of the best ways to use one for everyday online payments.

  • International shopping: Buy from overseas retailers that accept Mastercard without exposing your primary payment card, making cross-border purchases more secure and easier to manage.
  • Free trials: Use a virtual card when signing up for free trials, helping separate recurring subscriptions from your main card and making future billing easier to monitor.
  • One-off purchases: Pay merchants you'll only use once without sharing your everyday card details, reducing the risk of future unauthorised charges or stored payment information.
  • Subscription payments: Manage streaming services, software licences and other recurring payments more efficiently, especially when you want greater control over renewals and online spending.
  • New merchants: Shop confidently with unfamiliar online stores by using a virtual card instead of your primary payment card, adding an extra layer of protection against fraud.

How does a Grey Visa card work?

Waiting days for a payment card to arrive can slow you down, especially when you need to pay for a subscription or make an international purchase. That's why eligible Grey users can create a virtual Visa card in less than five minutes. The card is issued instantly, so you can start paying online almost immediately after completing the setup process.

Your Grey virtual Visa card spends directly from your available foreign currency balances and can be used anywhere Visa is accepted. If you need separate cards for different purposes, you can create more than one virtual Visa card, making it easier to organise spending for subscriptions, work expenses or personal purchases.

Frequently asked questions

Does Mastercard issue virtual cards directly?

No. Mastercard provides the global payment network but does not issue virtual cards to consumers. Instead, banks and licensed fintech companies issue Mastercard virtual cards under their own programmes, giving customers access to digital payment cards that can be used anywhere Mastercard is accepted online.

Can I use a Mastercard virtual card at any online store?

In most cases, yes. A Mastercard virtual card can be used at online merchants that accept Mastercard payments. However, some retailers, hotels or car rental companies may require a physical card for identity verification or security deposits, so it's worth checking their payment policies beforehand.

Is a virtual Mastercard safer than a physical card?

For online shopping, it often is. A virtual Mastercard keeps your physical card details hidden, reducing the risk of fraud if a merchant's systems are compromised. Many providers also let you freeze, replace or manage the card instantly through their mobile app.

Can I get a free Mastercard virtual card?

Yes. Many banks and fintech providers offer Mastercard virtual cards without an issuance fee. Before signing up, check whether there are other costs, such as monthly maintenance fees, currency conversion charges, funding fees or inactivity fees that could increase the overall cost.

Does the Grey visa card work everywhere Mastercard is accepted?

The Grey Visa is designed for online payments at merchants that accept Mastercard. While it works with many international websites and digital services, acceptance ultimately depends on the individual merchant, their payment policies and any country-specific restrictions that may apply.

How do I top up my Grey virtual Visa card?

You don't need to top up your Grey virtual Visa card separately. Simply add money to your Grey account. Your card spends from your USD balance first. If there isn't enough USD available, Grey will automatically use your available balance in another supported currency to complete the payment.

A Mastercard virtual card offers a faster and more secure way to shop online, especially when making international purchases or paying for digital services. Ready to start? Open a Grey account or download the app to get a Grey virtual Mastercard and spend globally with confidence using your USD, GBP or EUR balance.

Google Pay virtual card: How it works and where to use it

•

•

2 min read

Contactless payments have become part of everyday life in countries that support them. Whether you're buying groceries, booking flights, or shopping online, chances are you've used a digital wallet like Google Pay. But every time you enter your card details on a website, you expose your card number to another merchant. That's where Google Pay's virtual card feature comes in.

A Google Pay virtual card is a tokenised version of your physical card that Google generates for online purchases in Chrome, masking your real card number. It is currently available with select US bank-issued Visa and Mastercard cards. To use one, add your card to Google Pay, enable virtual card numbers in your card settings, and use the autofill option at checkout.

Since Google introduced this feature in 2022, it is now available with Visa, Mastercard, and American Express cards. In this guide, you'll learn how Google Pay virtual cards work, which banks support them, how to set one up, and when they're a better option than using your physical card online.

What is a Google Pay virtual card?

Google Pay (via Google Wallet) handles virtual cards in two ways: you can add a pre-existing third-party virtual debit/credit card to your wallet, or Google Wallet automatically creates a secure virtual account number (token) when you link a physical card.

A Google Pay virtual card is a digital version of your debit or credit card generated by Google during online checkout. Instead of sharing your actual card number with a website, Google creates a unique virtual card number. The payment still comes from your real card, but the merchant never sees your actual card details.

According to Google's official support pages, the feature works through Google Chrome's autofill functionality. When you reach a payment form on a supported website, Chrome detects that a virtual card is available and offers to automatically enter the tokenised number.

This works through a process called tokenisation. Your real card number is replaced by a different number that is mathematically linked to your account. Let’s say there is a data breach on the platform where you used your card, and the virtual number is stolen. The number cannot be used to access your bank account or to make transactions elsewhere.

Which banks support Google Pay virtual cards?

While Google Wallet is available in most parts of the world, Google Pay virtual cards are mostly only available with some US card issuers. However, the list has been growing since the 2022 launch.

Currently supported in the US:

  • Capital One (Visa and Mastercard cards)
  • American Express (selected cards)
  • Citi (selected Visa and Mastercard cards)
  • Several other US bank-issued Visa and Mastercard products

Some international markets have access to elements of Google Wallet's tokenisation features, but the full virtual card number feature for Chrome autofill is not universally available outside the US.

The feature usually works with both Visa and Mastercard from supported issuers. Some American Express cards might also be supported, depending on the bank. Check your specific card in Google Wallet to confirm whether virtual card numbers are available for it.

To check if your bank supports Google Pay virtual cards:

  1. Open the Google Wallet app.
  2. Add your debit or credit card (if it hasn't already been added).
  3. Look for an option for virtual cards when paying online, or in the card details.
  4. Alternatively, contact your bank and ask: “Does my card support Google Pay virtual card numbers for online payments?”

If your card or bank is not yet supported, we will provide alternatives you can choose. Also, not all payment gateways accept Google Pay virtual card numbers. If this happens, you'll need to use your physical card details instead.

How to use Google Pay virtual card

Using the feature requires Google Chrome on a desktop or Android device, and a supported card added to Google Wallet. Here is how to use a Google Pay virtual card:

Step 1: Add your card to Google Wallet

Open Google Wallet at wallet.google.com or through the Google Wallet app. Add your eligible card by entering the card details or scanning it. Google may send a verification code to your bank.

Step 2: Enable virtual card numbers

Once your card is added, go to the card details in Google Wallet. Look for the option to enable virtual card numbers. Not all cards show this option. If you do not see it, your card may not be eligible yet.

Step 3: Open Chrome and go to a shopping website

The feature works in Chrome on desktop and Android. It might not work in other browsers, such as Safari, Firefox, or Edge.

Step 4: Proceed to checkout.

When you reach the payment form, Chrome will detect your saved Google Pay card and offer autofill. If a virtual card is available, Chrome will show you the option to use a virtual card number instead of your real number.

Step 5: Select the virtual card option

Click or tap to use the virtual card. Chrome fills in the tokenised card number, expiry date, and security code automatically.

Step 6: Complete your purchase

The merchant processes the payment using the virtual number. The charge appears on your real card statement as a normal transaction.

How to find your Google Pay card number

Google doesn’t issue a permanent virtual card number, so you cannot just copy the numbers and use them for other transactions. Instead, the virtual card number is generated every time you need to use your card, which is part of what makes it safe.

To find your Google Pay card number, open your Google Wallet, go to the card, and look for the virtual card or device account number section. This shows you the tokenised card number associated with your account on that device or browser. This is not the same as your real card number printed on the physical card.

Google's system can generate merchant-specific or session-specific numbers. This means the number used at one retailer may differ from the number used at another, even on the same card. This limits the damage if one merchant's systems are compromised.

For many online purchases, the virtual number is passed directly through Chrome's autofill without being displayed to you. This is by design. The system handles the masking automatically, so you do not need to manually copy a virtual number for each purchase.

Google Pay virtual card limitations

Google Pay virtual cards offer extra security for online shopping, but they do have a few limitations.

  • Works only in Google Chrome: You can't use the virtual card feature in browsers like Safari, Firefox, or Microsoft Edge.
  • Limited device support: It works in Chrome on desktop and Android devices. However, this feature is not available on iPhones or iPads due to iOS restrictions.
  • Not every bank is supported. You can only use a Google Pay virtual card if your bank and card issuer support it.
  • Available mainly in the US. Most users outside the United States won't have access to Google Pay virtual cards yet.
  • May not work on every website. While rare, some online stores don't accept virtual card numbers. If this happens, you'll need to use your physical card details instead.

Alternatives to Google Pay virtual cards

If your bank does not support Google Pay virtual cards, or if you need virtual card functionality that works across more platforms and currencies, there are other options.

  • Bank-issued virtual cards

Some US banks issue their own virtual card numbers outside of Google. These virtual cards typically work on any browser, not just Chrome. Check with your specific bank whether they offer this feature.

  • Fintech virtual cards

Digital banks and payment platforms like Grey, Payoneer, and Wise issue virtual Visa or Mastercard cards connected to a foreign currency balance. These are separate from your regular bank card and can be used for online purchases anywhere Visa or Mastercard is accepted.

The Grey virtual card is a virtual Visa card connected to USD, GBP, or EUR balances. Unlike Google Pay virtual cards, it works in any browser and on any device. It is particularly useful for international purchases because you can hold the spending currency in your balance and avoid cross-border conversion fees on same-currency transactions.

Feature Google Pay virtual card Grey virtual card
How to get it Enable in Google Wallet if eligible Sign up with Grey, create card instantly
Browser compatibility Chrome only Works everywhere (card number at checkout)
Country availability Primarily US Available in supported countries globally
Requires existing bank card Yes No
Multi-currency support No Yes (USD, GBP, EUR)
Works on iOS No Yes
One-time card creation fee None $5 one-time
Apple Pay and Google Pay support Via Google Pay Yes (supported regions)

Once you open a multi-currency account with Grey, you can access USD, GBP, or EUR accounts to receive and hold international payments. You can then get a Grey virtual card linked directly to your foreign currency balance, add it to Google Wallet, and make international or contactless purchases with your phone without currency conversions.

Frequently asked questions

Does Google Pay generate a virtual card for every purchase?

Google Pay uses tokenised card numbers to protect your real card details. Depending on your bank, the virtual number may be unique to a merchant or change over time, helping reduce the risk of fraud.

Which countries support Google Pay virtual cards?

The feature is currently available mainly for eligible cards issued by participating US banks. Availability in other countries is still limited.

Can I use Google Pay virtual card on Safari or Firefox?

No. The Google Pay virtual card autofill feature only works in Google Chrome. On iOS devices, Chrome does not support the feature even after installation, because Apple restricts browser-level payment APIs on the iPhone and iPad.

Is Google Pay virtual card safer than a regular card?

Yes, in the specific sense that your real card number is not exposed to the merchant. If a merchant's payment system is breached, the tokenised number that was stolen cannot be used at other merchants. Your real card number remains safe. Standard card security still applies for all other types of fraud.

What is the best alternative to Google Pay virtual cards?

If you need a virtual card that works across all browsers and devices, or if your bank does not support Google Pay virtual cards, a fintech virtual card is the most flexible option. The Grey Plus Card works on any website in any browser and connects to a multi-currency balance, making it particularly useful for international online purchases.

How do I get a Grey virtual card?

Create a Grey account, complete identity verification, and open a USD, GBP, or EUR balance. You can then create a Grey virtual card from the Cards section of the app. A one-time $5 card creation fee applies.

Virtual dollar cards in the UAE: How to get one

•

•

2 min read

A virtual dollar card can make international spending easier, especially when your regular UAE card is not the most convenient option for dollar payments. Instead of carrying a physical card, you get digital card details that can be used for eligible online purchases, subscriptions, advertising platforms and international shopping. Some providers link the card directly to a USD balance, while others convert your funds when you make a payment.

For UAE residents looking for a virtual dollar card UAE option, the important thing is not simply whether the card is available. You should also check how you fund it, the exchange rate, card issuance fees, transaction limits and where the card can be used. Some providers offer USD cards linked to multi-currency balances, while others require specific funding methods.

This guide explains how to get a virtual dollar card in the UAE, what you can use it for, and the costs to check before signing up.

Also read: 7 best virtual cards in the UK (2026)

What is a virtual dollar card?

In simple terms, a virtual dollar card is a digital payment card designed for online transactions in US dollars. It gives you card details such as a number, expiry date and security code, but there is no physical card to carry. You can use it for eligible subscriptions, online services, advertising and international purchases.

The key difference for UAE residents is the currency behind the payment. Most local UAE cards are connected to AED accounts, meaning a purchase priced in USD may require the bank to convert your dirhams into dollars before the payment goes through. The provider may also add a foreign transaction fee or exchange-rate markup.

USD billing can be more convenient when most of your online expenses are priced in dollars. With a virtual dollar card linked to a USD balance, you can pay in the same currency rather than converting AED for every transaction. This can make international spending easier to track and manage.

It also helps to understand what a virtual wallet is and how it stores balances separately from your bank card. You can also compare virtual and physical card use cases to decide whether you only need card details for online USD payments or you also want a physical card later.

How to get a virtual dollar card in the UAE

Getting a virtual dollar card in the UAE does not usually require opening a US bank account. The main requirement is finding a provider that accepts UAE customers and can give you access to a USD balance for online payments. From there, the process is fairly simple, although each provider has its own verification and funding requirements.

After choosing a provider, create an account and complete the identity checks. This may involve providing your personal details and a government-issued ID. Once your account has been approved, the next step is getting money into it. If your funds are in AED or another currency, you may need to convert them to USD before using the card. Check the exchange rate and any funding or conversion fees at this stage.

Once the USD balance is ready, you can generate the virtual card from the provider’s app or online account. Your card details can then be used for eligible USD payments, such as subscriptions, software, advertising and international shopping.

Grey also offers a virtual Visa card for eligible customers, combining international card payments with access to supported currency balances. Availability and requirements depend on the country where you live, so UAE residents should check the latest eligibility before signing up.

Also read: Debit card vs Credit card: What is the difference?

What can you use a virtual dollar card for?

A virtual dollar card can cover many everyday international payments, particularly when the merchant charges in USD.

  • Subscriptions: Pay for streaming services, software, cloud storage, AI tools and other subscriptions that bill in US dollars. Using a card designed for USD payments can make recurring charges easier to manage.
  • Online advertising: Businesses, freelancers and creators can use virtual dollar cards to pay for advertising on platforms that accept international cards, including campaigns billed in USD.
  • Online shopping: Use the card for purchases on international websites that accept Visa or Mastercard. It can be useful when a local UAE card creates additional conversion costs or payment restrictions.
  • Travel: A virtual dollar card can also help with travel-related online payments, such as booking flights, hotels, transport and other services priced in USD. However, check the provider's country restrictions and card acceptance before relying on it while travelling.

Fees and limits to check before choosing a virtual dollar card

The real cost can appear when you fund the card, convert currencies, or reach a spending limit. Checking these charges before signing up can help you avoid unpleasant surprises later.

  • Issuance fee: Some providers charge a one-off fee when you create a virtual dollar card, while others offer card creation for free. Check this before opening an account.
  • Funding fees: Adding money may attract a fixed fee or percentage charge, depending on how you fund the card. Compare the available funding methods and their costs.
  • FX fees: Converting AED or another currency into USD can involve an exchange-rate markup or separate conversion fee. Check the rate you receive, especially when funding larger amounts.
  • Spending limits: Virtual dollar cards may have daily, monthly or per-transaction spending limits. Make sure the limits are high enough for your subscriptions, advertising payments, shopping and other regular expenses.

With Grey, you can open an account, create a virtual Mastercard, and use it for eligible dollar payments like subscriptions and online services, all from one place.

Frequently asked questions

Can I get a dollar card in the UAE?

Yes, UAE residents can access USD-denominated virtual cards, although eligibility depends on the provider. Some UAE-based services offer virtual cards linked to your account, while international providers may have separate residency requirements. Always check the provider’s current UAE availability, verification requirements, and regulatory status before signing up.

How do I fund a virtual dollar card?

Funding depends on the provider. You may be able to transfer money from a bank account, add funds through a supported payment method or fund the card from an existing USD wallet. Some providers only allow specific funding sources, so check the available options and any conversion or funding fees first.

Is a virtual dollar card safe?

A virtual card can add protection by keeping your main bank card details separate from online payments. However, safety also depends on the provider’s security controls, regulations, and how you protect your account. Choose a reputable provider, enable available security features and never share your card details or login information.

Can I use a virtual dollar card for subscriptions?

Yes, many virtual dollar cards are designed for online payments such as streaming services, software, advertising platforms and other subscriptions billed in USD. Before subscribing, check that the merchant accepts your card network and that the provider supports recurring payments.

Can I use a virtual dollar card outside the UAE?

You can often use a virtual dollar card for international online payments, but acceptance depends on the card network, provider restrictions and the merchant. Check supported countries and transaction limits before relying on the card for important payments abroad.

How to use Google Pay in Nigeria

•

•

2 min read

Google Pay launched in Nigeria on 28 October 2026, through the Google Wallet app on Android. Google’s current list covers eligible cards from five banks: FirstBank, GTBank, Providus Bank, UBA, and Zenith Bank, mostly Mastercard. Verve, AfriGO, and cards from banks like OPay, Moniepoint, Kuda, and PalmPay are not on it, and contactless terminals remain limited.

Whether tapping works depends on three things: your card, your phone, and the terminal. This guide takes them in that order, then covers what to do if your card is not supported.

Does Google Pay work in Nigeria?

Yes. Google launched Google Wallet, including Google Pay, in Nigeria on 28 October 2026 for Android and Wear OS users. Google says it lets you pay by tapping in stores, in apps, and online, using a card stored on your phone.

Both names cause confusion, so here is the difference. Google Wallet is the app that holds all your payment cards and can also store loyalty cards, event tickets, and boarding passes. Google Pay is the payment function inside it, the part that passes your card to a terminal or a checkout page. You install one app, add a card, and pay with Google Pay.

Unfortunately, Google Pay won’t work for everyone. Three things have to line up:

  • Your card: It has to be on Google’s list, and your bank decides whether a given card works.
  • Your phone: It has to run Android and have a screen lock. Tapping in stores also needs NFC.
  • The place you are paying. An online shop has to offer Google Pay, and a physical shop needs a contactless-enabled terminal.

The next section covers the first of these: the banks and cards.

Nigerian banks and cards that work with Google Pay

The table below follows Google’s Nigeria payment methods page, as at the time of publishing.

Bank Supported cards
First Bank of Nigeria Mastercard debit
Guaranty Trust Bank (GTBank) Mastercard debit and prepaid
Providus Bank Mastercard credit, debit, and prepaid
United Bank for Africa (UBA) Mastercard credit, debit, and prepaid; Visa prepaid
Zenith Bank Mastercard credit, debit, and prepaid

An account at a listed bank is not enough. Google has stressed that your bank decides whether its cards work with Google Wallet. The card network (Mastercard or Visa) and the card type (debit, credit, or prepaid) both count. A bank that issues Mastercard and Verve cards may support one but not the other, so find your bank’s row, then check the network and card type you hold. Both are usually shown on the card itself or in your banking app.

What is not supported:

  • Verve cards. Google currently only supports Mastercard and Visa.
  • AfriGO cards.
  • Cards from OPay, Moniepoint, Kuda, and PalmPay. None of these providers appears on the list.
  • Visa debit cards from the listed banks. Visa appears only as a prepaid card at UBA.

If your card is not covered, the section below on unsupported cards outlines your options.

How to set up Google Pay in Nigeria

You need an Android phone, a screen lock, and a card from the table above. For tapping in stores, the phone also needs NFC. Google Wallet generally requires a recent version of Android, so update your phone first if it is running an older version.

  1. Install Google Wallet. Download it from the Google Play Store and open it
  2. ‍Set a screen lock. Wallet requires a PIN, pattern, password, or fingerprint before it can store a payment card.‍
  3. Add the card. Tap Add to Wallet, then Payment card, then New credit or debit card.‍
  4. Enter the card details. Scan the card with the camera, or type the number, expiry date, and CVV.‍
  5. Accept the terms and verify. Your bank may send an SMS code or ask you to confirm in its app. Complete this step to activate the card.‍
  6. Set a default. Open Wallet settings and choose the card you want Google Pay to use first.‍
  7. Check NFC. In your phone's settings, search for NFC and switch it on if you plan to tap in stores.

If the verification message does not arrive, or the card is declined, call the number on the back of the card. Google's page says to contact your bank when a card cannot be set up for mobile payments.

Virtual cards go in the same way. Grey's guide on how to add a virtual card to Apple Pay or Google Pay covers it in more detail.

How to set up Google Pay with your Grey card

If your bank card is not on Google's list, a Grey virtual dollar card is another card you can try in Google Wallet. Grey's guide says its virtual cards can be added to Google Wallet on Android, and that Google Pay accepts virtual debit cards on the Mastercard and Visa networks as long as the issuer supports it. Google decides which countries and cards Wallet supports, so availability can vary by region.

What you need: an active, funded Grey virtual card and an Android phone with a screen lock. A frozen or expired card, or one with a $0 balance, can fail verification.

  1. In the Grey app, go to Cards, tap your virtual card, and copy the card number, expiry date, and CVV.
  2. Open Google Wallet, tap Add to Wallet, then Payment card.
  3. Tap New credit or debit card and enter the details.
  4. Tap Save. Google checks the card with the issuer.
  5. Accept the terms and complete the verification step. This may be an SMS code, an email link, or a confirmation in the Grey app.
  6. Open Wallet settings and set the card as your default payment method.

Adding a card to Google Pay is free. Any fees come from the card issuer.

What it is good for

A Grey virtual card holds US dollars, so it suits payments priced in dollars:

  • International online checkouts that show Google Pay at the payment step.
  • Subscriptions billed abroad in dollars, such as software and streaming.
  • Spending when your Nigerian bank card is not on Google's list.

It is a dollar card, so it does not replace a naira bank card for everyday spending in Nigerian shops. For that, a card on Google's list is the simpler fit.

You can get a Grey virtual card from the app, and fund your card from a USD balance so it is ready when you need to pay.

Fees and rates: a Grey virtual card costs $5 to create, once, with no monthly fee. Payments on non-US websites can carry a cross-border fee of 2% plus $0.50. If you fund the card from a non-USD balance, currency conversion applies, and Grey's exchange rates vary with a margin over the mid-market rate. See grey.co/pricing for current fees.

Where you can actually use Google Pay in Nigeria

Online checkout is the realistic use for most people right now. Tapping in stores is possible, but only at terminals that support it, and those are still uncommon.

Online. Paystack has offered Google Pay at checkout for Nigerian merchants since September 2026, and Interswitch's payment gateway supports it too. Each merchant has to switch it on, so you will not see it at every shop. A business turns it on in its Paystack dashboard, and Paystack's help page lists the requirements. Paystack supports Visa and Mastercard for Google Pay, and the option appears only when your device, browser, card, and Wallet setup all support it. If a checkout shows no Google Pay button, the cause is usually one of those four, or the merchant has not enabled it.

In apps. Some apps offer Google Pay at the payment step. The same rule applies: the app has to support it, and your card has to be on Google's list.

In stores. Tapping needs two things: a phone with NFC and a terminal with contactless enabled. Many point-of-sale terminals in use today lack the hardware, and contactless is still a very small share of payments in Nigeria. Even at a terminal that accepts taps, your bank's fraud systems have to recognise the payment, or it may be declined.

How to tell whether a terminal will work:

  • Look for the contactless symbol, four curved lines, on the terminal or its screen.
  • Ask the cashier before the bill is settled: "Does this take tap to pay?"
  • Unlock your phone, switch NFC on, and hold the back of the phone close to the reader for a few seconds.
  • If nothing happens after two or three tries, pay another way.

A practical rule is to use Google Pay online first and treat tapping in stores as a bonus where the terminal supports it. Keep a physical card or cash with you either way.

If your card is not supported

Your card may not be on Google's list. What you do next depends on what you wanted to pay for.

If you want to use the tap-to-pay feature with your card, you may need to wait for your bank to be added or switch to a supported card type. Google’s list can change, and your bank decides which card types are enabled. If you are trying to pay while shopping online, enter your card details as usual. Google Pay is a quick checkout option. If your transaction is in dollars, a virtual dollar card is a better fit, as it is designed for international dollar payments.

Waiting for your bank. The list was shorter at launch than it is now, so more banks and card types may follow. There is no published timetable, so do not plan around it.

Switching to a supported card type. If you bank with one of the five listed banks but hold a Verve or Visa card, ask whether the bank can issue a Mastercard debit or prepaid card. Then check that exact type against Google's list. This keeps you paying from your naira account.

Using a virtual dollar card. For international online payments, Google Pay is rarely the blocker, because you can type a card's details at any checkout that accepts it. A virtual dollar card gives you a dollar card number for those payments. To compare your choices, read about free virtual dollar cards and how to get a virtual dollar card in Nigeria. A dollar card does not replace a naira bank card at home. If you also need to move money between Nigeria and another country, you can send and receive money in Nigeria with Grey.

Fees apply to Grey virtual cards, including a one-time $5 creation fee, and currency conversion can add cost. See grey.co/pricing for current fees.

Frequently asked questions

Does Google Pay work in Nigeria?

Yes. Google launched Google Wallet, including Google Pay, in Nigeria on 28 October 2026 for Android and Wear OS. It works only with cards on Google's list, and only at online shops and terminals that support it.

Which banks support Google Pay in Nigeria?

Google's list currently shows First Bank of Nigeria, GTBank, Providus Bank, UBA, and Zenith Bank. Support depends on the specific card, mostly Mastercard debit, credit, or prepaid. The table in this guide shows the exact types for each bank, and the list can change.

Why was my card rejected?

The most likely cause is that the card is not on Google's list, or your bank has not enabled that card type. Verve and AfriGO cards are not supported. Other causes are a missing screen lock, an unfinished verification step, or a bank fraud check that blocked the payment. Call the number on the back of your card and ask the bank.

Can I tap to pay in Nigerian stores?

Only at terminals with contactless enabled, and many terminals in Nigeria lack the hardware. Your phone also needs NFC. Look for the contactless symbol, and keep another way to pay.

Does my Kuda, OPay, or Moniepoint card work with Google Pay?

Not at the moment. Cards from Kuda, OPay, Moniepoint, and PalmPay are not on Google's list. Check the list again later, because it can change. For dollar payments online, a virtual dollar card is another option.

Is Google Wallet the same as Google Pay?

Not exactly. Google Wallet is the app that stores your cards, tickets, and passes. Google Pay is the payment function inside it. You install Google Wallet, add a card, and pay with Google Pay.

Paying for things abroad? Open a Grey account and get a virtual card for online payments.

How to send money from Europe to India

•

•

2 min read

Here's a question: if you send €500 from Germany to India today, how much will your family actually receive? You'd think there would be one simple answer, but check a few money transfer apps and you'll probably get three different amounts.

And if you're regularly sending money from Europe to India, those differences matter. Every euro spent on transfer fees or conversion charges is money your family could be receiving instead.

So, if you're wondering how to send money from Europe to India, this guide will help you compare transfer methods, understand the fees, find the cheapest way to send money and make sure more rupees reach your recipient.

Quick answer: The easiest way to send money from Europe to India is usually through a transfer app that supports Indian bank deposits or UPI payouts. Create an account, verify your identity, enter the amount, review the exchange rate and fees, then confirm. Transfers may arrive within minutes or take several working days, depending on the provider.

What is the best way to send money from Europe to India?

For most people, a money transfer app offering Indian bank deposits or UPI payouts is a convenient option. You can usually see how many Indian rupees (INR) the recipient will receive before confirming.

Traditional bank wires are another option, particularly for larger payments, but may involve additional charges and longer processing times.

Transfer method How it works What to consider
Money transfer app Pays into an Indian bank account Usually shows fees and INR amount upfront
UPI payout Sends to an eligible UPI ID Fast and convenient where supported
International bank wire Transfers between bank accounts May involve intermediary fees and longer processing

‍

Grey, for example, supports INR payouts to Indian bank accounts and UPI IDs. You can manage supported foreign currencies in your account and review the exchange rate, fees and final amount before sending. Available options depend on your location and account eligibility.

You can also compare the best apps to send money internationally or check how to send money from the UK to India if you're based in Britain.

Also read: What is the best app to send money to India from the US?

How to send money from Europe to India step by step

You can send money from Europe to India in six steps using a provider that supports Indian bank transfers or UPI payouts.

1. Choose a transfer provider

Check which services operate in your country and support payments to India. Fees and funding methods can differ between Germany, France, Ireland and other European countries.

If you're based in Germany, for example, check the available options to send money from Germany to India.

2. Create an account and verify your identity

Sign up and complete the required identity checks. You'll usually need personal details and a valid identity document. Larger transfers may require additional verification.

3. Enter the amount

Choose your sending currency, usually EUR, and enter how much you want to transfer. Check the estimated INR amount alongside the exchange rate and fees.

4. Add the recipient's details

For an Indian bank transfer, you'll generally need the recipient's name, account number and IFSC code. If UPI is supported, you may be able to use an eligible UPI ID instead.

Grey supports both payout methods for eligible INR transfers. Your recipient doesn't need a Grey account, but their bank details or UPI ID must be correct.

5. Review and confirm

Check the exchange rate, fees, recipient amount and estimated delivery time.

With Grey, you can review these details in the app before authorising the transfer through the required security verification.

6. Track your payment

Keep the transfer confirmation and follow its status in the app. Some transfers arrive within minutes, while others take longer because of bank processing or verification checks.

If you regularly earn in euros, you can also check whether you're eligible to open a euro account with Grey and receive supported EUR payments through SEPA.

What it costs: fees and EUR to INR rates

The cost of sending money to India comes down to three things: the transfer fee, the exchange rate and any additional charges.

A service advertising a €0 transfer fee isn't necessarily cheaper than one charging €4. The exchange rate can change how much your recipient actually receives.

Understanding the exchange rate margin

Some providers offer a rate below the reference EUR to INR exchange rate. The difference is called the exchange rate margin, and it affects the amount delivered even when the transfer itself is advertised as free.

Example: sending €500 to India

Imagine the reference rate is €1 = ₹100. This is an illustrative example, not a live exchange rate.

Provider A Provider B
Amount sent €500 €500
Transfer fee €0 €4
Exchange rate ₹98/€1 ₹100/€1
Amount converted €500 €496
Recipient receives ₹49,000 ₹49,600

‍

Despite charging €4, Provider B delivers ₹600 more.

That's why the cheapest way to send money from Europe to India is to compare the final INR amount rather than the advertised fee alone.

What fees does Grey charge for transfers to India?

Grey's published USD-to-INR pricing includes a 1% conversion fee without a percentage-fee cap. Its withdrawal-fee guidance also lists a $1.50 fee for eligible INR bank and UPI payouts.

For example, converting $500 from USD to INR would cost $5 in conversion fees. Including the listed $1.50 payout charge, the combined fees would be $6.50, excluding funding costs and any exchange rate difference.

If you receive euros into Grey through SEPA or SEPA Instant, the published deposit fee is 0.8%, with a €2 minimum and €10 maximum.

These charges apply to different transactions. The USD-to-INR fee shouldn't be treated as the price of a direct EUR-to-INR transfer, so check the available route and final quote in your account.

Grey's published US-to-India information also lists limits of ₹450,000 per bank transfer and ₹100,000 per UPI transfer. Limits for European corridors may differ.

If you're based in the Netherlands, you can check how to send money from the Netherlands to India and compare the available quote.

Sending money home? Send money from Europe to India with Grey and check the available exchange rate, fees and payout options before confirming.

Can you send money from Europe to India without charges?

You may find providers offering fee-free transfers, but that doesn't always mean there are no costs.

Some offer introductory promotions, while others include their charges in the exchange rate. A provider offering ₹99 per euro will deliver less than one offering ₹100, even if neither charges a transfer fee.

If you're looking for how to send money from Europe to India without charges, compare the total amount paid with the rupees delivered.

With Grey, for example, check the applicable conversion and payout fees. If you first need to fund your account, include any deposit charges too.

Receiving money in India: NRE, NRO and UPI

Money sent from Europe can arrive in an eligible Indian bank account or, where supported, through a UPI payout.

For non-resident Indians (NRIs), the type of receiving account can also matter.

NRE accounts

A Non-Resident External (NRE) account allows eligible NRIs to hold funds received from abroad in Indian rupees.

Permitted overseas remittances can generally be deposited into an NRE account, and the funds are repatriable under applicable rules. Interest is generally exempt from Indian income tax while the account holder meets the relevant eligibility conditions.

NRO accounts

A Non-Resident Ordinary (NRO) account is commonly used to manage income arising in India, including rent, dividends and other eligible payments. It can also receive permitted overseas remittances.

Interest earned on NRO accounts is generally taxable in India. Repatriation is subject to applicable rules, documentation and tax compliance. Certain eligible remittances fall under a USD 1 million annual limit per Indian financial year.

The Reserve Bank of India provides further guidance on NRE and NRO accounts.

What about UPI?

UPI allows payments to eligible Indian bank accounts using a linked UPI ID. Some international transfer services, including Grey, support UPI payouts for eligible INR transfers.

This means you may be able to send money without entering the recipient's full bank details. However, the receiving account must be eligible, and provider-specific limits apply.

Grey's published US-to-India corridor information lists a ₹100,000 UPI transfer limit, but you should check the limit applicable to your own sending country and account.

Is money received from abroad taxable in India?

Money received from overseas isn't automatically taxable. The treatment depends on the purpose of the payment, the relationship between sender and recipient, and the recipient's tax circumstances.

Qualifying gifts from specified relatives are generally exempt, while income from work, business or investments may be taxable. Other gifts may also be taxable depending on the amount and circumstances.

For larger transfers or complex situations, consider speaking with a qualified tax professional.

Frequently asked questions about sending money from Europe to India

What is the cheapest way to send money from Europe to India?

The cheapest option is the provider that delivers the highest INR amount for the same total cost. Compare transfer fees, exchange rates and additional charges. A zero-fee transfer may still cost more through the exchange rate.

How long does it take to send money from Europe to India?

Transfers can arrive within minutes or take several working days, depending on the provider, payout method and bank processing. Grey supports eligible INR transfers that may arrive within minutes, although verification and banking delays can affect delivery.

Can I send money to a UPI ID from Europe?

Yes, some international transfer services support UPI payouts to eligible Indian bank accounts. Grey also supports UPI payouts for eligible INR transfers. Check availability for your sending country before confirming.

Should I use an NRE or NRO account?

An NRE account is generally suited to eligible NRIs holding overseas earnings in India. An NRO account is commonly used for income arising in India. Both can receive permitted overseas remittances, but their tax and repatriation rules differ.

Is there a limit on sending money to India?

Limits depend on the provider, sending country, payout method and verification requirements. Grey's published US-to-India limits are ₹450,000 for bank transfers and ₹100,000 for UPI payouts. European corridor limits may differ, so check your account before sending.

Is money received in India from abroad taxed?

Not necessarily. Qualifying gifts from specified relatives are generally exempt from Indian income tax, while payments for services, business activities or investments may be taxable. The recipient's circumstances determine the treatment.

Arrow (up)

Back to top