<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india#article","headline":"How to pay for subscriptions in US dollars from India","description":"Learn how Indians can pay for international subscriptions in USD without failed payments, hidden fees, or poor exchange rate","inLanguage":"en","url":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india","mainEntityOfPage":{"@id":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india#webpage"},"datePublished":"2025-06-19T16:20:51.054Z","dateModified":"2026-06-15T14:54:56.236Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a30124065c4f70f3dd173b8_6a30123ffbe40500dc35694b_how-to-pay-for-subscriptions-in-us-dollars-from-india__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a30124065c4f70f3dd173b8_6a30123ffbe40500dc35694b_how-to-pay-for-subscriptions-in-us-dollars-from-india__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india#webpage","url":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india","name":"How to pay for subscriptions in US dollars from India","description":"Learn how Indians can pay for international subscriptions in USD without failed payments, hidden fees, or poor exchange rate","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to pay for subscriptions in US dollars from India","item":"https://grey.co/blog/how-to-pay-for-subscriptions-in-us-dollars-from-india"}]}] </script>

How to pay for subscriptions in US dollars from India

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Have you ever tried signing up for a global service only to have your payment declined without a clear reason? For many Indians, paying for USD subscriptions has become a source of frustration. Between card restrictions, forex charges, and failed transactions, something as simple as renewing a monthly plan can turn into a headache.

Whether you’re a student learning online, a freelancer using global tools, or just someone who enjoys international content, finding a reliable payment method is essential.

This guide breaks down the real reasons behind failed payments, how to choose the right solution, and why Grey is the best solution for Indians to pay for USD subscriptions.

Also read: The fastest and easiest ways to send USD from India to the US.

Why your USD subscription payments keep failing

  • Card restrictions: Not all Indian debit cards support international payments. Many, especially those from smaller banks or basic account types, simply don’t work for  USD subscriptions.
  • Hidden fees: Banks often apply silent charges like inflated exchange rates, currency conversion fees, and processing costs. These deductions reduce your available balance, causing your transaction to cost far more than expected.
  • Security blocks: Banks frequently flag international transactions as suspicious, to protect you from fraud. They may also block the payment without any prior notice.  To protect the user, the system blocks the payment without warning.
  • Transaction Limits: Even when your card is enabled for international transactions, most Indian banks set monthly or per-transaction limits on overseas spending. If your USD subscription exceeds this limit, the payment may be declined.

Also read: The best virtual debit cards in India for safe and easy online payments.

Common payment platforms Indians use for USD subscriptions

  • Indian bank cards: Most debit and credit cards from Indian banks are either not enabled for international payments or have strict spending limits. Many cards are also blocked by default for USD transactions unless manually activated.
  • PayPal: While PayPal supports international payments, linking it to Indian cards that allow USD billing can be tricky. Withdrawal limitations failed billing attempts, and unexpected fees make it unreliable for consistent subscription use.
  • Payoneer: Popular among freelancers, Payoneer offers virtual USD accounts and cards. However, the onboarding process can be lengthy for non-freelancers, and fees for maintenance, ATM withdrawals, or transfers often reduce its appeal for regular subscriptions.
  • Forex cards: Originally designed for travel, some users try using Forex cards for USD payments. But these aren’t ideal for monthly subscriptions, as they require manual top-ups, may expire, and are often rejected by certain global platforms.

Also read: How to get an instant USD debit card in India.

What to look for in a USD payment solution from India

Before choosing a payment provider, make sure it checks these boxes:

  • Global acceptance: Choose a payment method that works seamlessly across major international platforms, from Canva and Coursera to domain services and productivity tools. The more widely accepted, the better.
  • Transparent fees: Avoid providers with hidden forex charges or poor exchange rates. Transparent pricing makes a huge difference and saves you from unexpected costs.
  • Ease of use: No one wants to fill out long forms or wait days to get started. Look for a platform with instant card generation and a simple  KYC process.
  • Responsive support: Payment failures can be frustrating. Whether it’s a blocked transaction or a card issue, your provider should offer fast and helpful support.

Steps to pay for subscriptions in USD using Grey

Paying for your subscriptions through Grey is easy and efficient. Here’s how to do it:

  • Create a Grey account: Visit Grey’s website or download the app. Sign up with your details and verify your identity. It’s quick and doesn’t require complex paperwork.‍
  • Complete your KYC: Submit your full name, date of birth, phone number, address, valid ID, and a clear selfie. This quick step verifies your identity and secures your account.‍
  • Generate a virtual USD card: Create a virtual USD card on Grey. You’ll get card details instantly, ready to use on Spotify, Netflix, Canva, Apple, and more.‍
  • Use your card for payments: Enter your Grey virtual card details when checking out or renewing your subscription. It’s accepted on most global platforms that support USD billing.

Wrapping up

If you’re in India and need a reliable way to pay for subscriptions in dollars, whether for work, learning, or entertainment, Grey is your go-to solution. Create your Grey account today and enjoy seamless USD subscriptions.

‍

Last updated:

October 3, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to send USD to a Nigerian domiciliary account

•

•

2 min read

Most of the information you’ll find online on sending money to Nigeria will most likely focus on naira delivery. But that’s not what you need if the recipient has a domiciliary account and wants to receive USD without converting to naira.

A Nigerian domiciliary account holds foreign currency, typically US dollars, without forcing an immediate conversion. Sending USD to one keeps that option in the recipient’s hands. It’s a decent choice for freelancers holding dollar savings, importers managing USD expenses, or anyone who wants to preserve dollar value rather than convert at a potentially unfavourable rate.

The mechanics of getting USD from a US bank account into a Nigerian domiciliary account are specific. You need to understand the required details, the fees you’ll encounter, and the mistakes that cause transfers to fail or arrive short before you send. For a broader overview of receiving dollar income in Nigeria, see our guide on how to receive US dollars in Nigeria and the options available for opening a Nigerian dollar account.

What is a domiciliary account?

A domiciliary account, also commonly called a dom account, is a bank account held at a Nigerian commercial bank that stores foreign currency without converting it to naira. The Central Bank of Nigeria (CBN) permits individuals and businesses to hold certain foreign currencies in domiciliary accounts at licensed Nigerian banks.

The key distinction from a standard naira savings account is that funds credited to a domiciliary account remain in the foreign currency in which they were credited. The account holder decides when and whether to convert, and at what rate. This matters because the naira has historically depreciated against major currencies, and holding USD can protect against the value erosion of naira conversions.

Domiciliary accounts are the primary mechanism by which Nigerians receive international SWIFT wire transfers in USD. CBN’s foreign exchange regulations require that inbound USD transfers be credited to a domiciliary account or converted to naira at the official rate. If a sender directs a USD wire to a standard naira account, the bank will convert it on arrival. If the recipient wants the money to remain in USD, the wire must be sent to the domiciliary account number, not the naira account number.

Both the naira and domiciliary accounts exist at the same bank for the same person and may look similar. They are different accounts with different account numbers. Confirm the domiciliary account number explicitly with the recipient before initiating the wire.

How to send USD via SWIFT wire: step by step

A SWIFT wire from a US bank to a Nigerian domiciliary account requires specific information, and if you miss any, it can cause delays, returns, or the transfer landing in the wrong account.

Step one: Collect the recipient’s domiciliary account details.

You need all of the following:

  • Recipient’s full legal name, exactly as registered with the Nigerian bank
  • The domiciliary account number (not the naira account number)
  • The bank name and branch address
  • The bank’s SWIFT code

The SWIFT codes for some major Nigerian banks are as follows: Access Bank: ABNGNGLA, GTBank (Guaranty Trust Bank): GTBINGLA, Zenith Bank: ZEIBNGLA, First Bank of Nigeria: FBNINGLA, United Bank for Africa (UBA): UNAFNGLA, Stanbic IBTC Bank: SBICNGLX, Ecobank Nigeria: ECOCNGLA, Fidelity Bank: FBNKNGLA, FCMB (First City Monument Bank): FCMBNGLA.

Always verify the SWIFT code directly with the recipient’s bank before initiating a high-value transfer, as branch-specific codes sometimes differ from the head office code.

Step two: Initiate the wire transfer at your US bank.

Log in to your online banking or visit a branch. Navigate to international wire transfers. Enter the recipient’s details: full name, domiciliary account number, bank name, branch address, and SWIFT code. Specify USD as the transfer currency. Nigeria is a USD-only wire destination at Bank of America; Bank of America requires international wires to Nigeria to be sent in US dollars due to local regulations, and foreign currency transfers are not available to this destination.

Step three: Select your charge instruction.

Depending on your bank, you may be asked whether to use SHA (shared charges) or OUR (sender pays all). Under SHA, correspondent bank fees are deducted from the transfer amount in transit, meaning the recipient receives less than what you send. Under OUR, you pay all correspondent fees upfront, and the recipient receives the full amount. For transfers where the recipient needs a specific USD amount, OUR is the right choice. For transfers where the fee deductions are acceptable, SHA is the standard default.

Step four: The wire routes through the SWIFT network.

Not all US banks have direct correspondent relationships with Nigerian banks. A US-to-Nigeria wire might involve two or three correspondent bank hops due to limited direct banking relationships. Each correspondent bank in the chain processes and forwards the payment, and under SHA, each one can deduct a fee from the transfer amount before forwarding the remainder.

Step five: The money arrives in the domiciliary account.

SWIFT transfers to Nigeria typically take one to three business days. Large transfers may be held for CBN compliance review, which can extend the timeline. Once that is cleared, the USD is credited to the domiciliary account and remains in dollars until the account holder decides to convert or withdraw.

What a SWIFT wire really costs

The posted fee at your US bank is not the full cost of a SWIFT wire to Nigeria. Three fee layers stack on every transfer.

Layer one: Your US bank’s outgoing wire fee
A 2026 NerdWallet survey reported a median outgoing international wire transfer fee of $45, with major US banks charging $35 to $50 per send. Chase charges $40 online for USD wires. Bank of America charges $35 for online transfers. Wells Fargo charges $25 to $45, depending on account type.

Layer two: Correspondent bank deductions in transit
Correspondent banks that relay the payment along the SWIFT chain can each deduct $10 to $30 in fees from the transferred amount before it reaches its destination. On a US-to-Nigeria wire routed through two correspondent banks, that’s $20 to $60 deducted from the transfer amount. Neither you nor the recipient is notified of these deductions in advance.

Layer three: The Nigerian receiving bank’s incoming wire fee
Nigerian banks charge an inbound wire fee on SWIFT receipts. This is typically deducted from the funds upon arrival before they are credited to the domiciliary account.

Here’s what this looks like on real transfers:

$500 transfer $5,000 transfer
US bank outgoing wire fee $40 $40
Correspondent bank deductions (estimated) $30–$50 $30–$50
Nigerian receiving bank fee $10–$15 $10–$15
Total fees $80–$105 $80–$105
As a percentage of transfer 16–21% 1.6–2.1%
USD received in domiciliary account $395–$420 $4,895–$4,920

‍

Also read: Sending USD from Nigeria to the USA: Step-by-step guide

Cheaper alternatives to a SWIFT wire transfer

For smaller or regular payments, the SWIFT route is difficult to justify. Here are the practical alternatives and when each one makes sense.

Multi-currency accounts (the recommended alternative for most senders)

Platforms like Grey provide USD accounts with US routing numbers and account numbers that senders can use to pay as a standard domestic US transfer, with no SWIFT correspondent chain involved.

The sender pays via ACH from their US bank account to a US account number. The money arrives in the recipient’s Grey USD balance without correspondent bank deductions. The recipient then controls when to convert or hold the USD. Multi-currency fintech accounts route payments through their own infrastructure rather than the SWIFT correspondent chain.

Grey’s deposit fee via ACH is 0.8%, capped at $10. On a $500 transfer, the fee is $4. On a $5,000 transfer, the fee is $10. Currency conversion is charged at 1% capped at $6 when the recipient converts to naira.

Stablecoin route

Some senders use USDC to move dollar value to Nigeria. The sender buys USDC on a US-licensed exchange, transfers to the recipient’s wallet address, and the recipient converts to USD or naira via a licensed Nigerian platform. This route avoids SWIFT entirely and can be faster, but requires both parties to be comfortable with crypto infrastructure and introduces volatility risk if either party converts at an unfavourable moment.

When SWIFT is still the right choice

If the recipient holds a domiciliary account and wants to receive funds in dollars without naira conversion, a bank wire is one of the most practical routes. SWIFT confirmations from US banks carry institutional credibility that other receipts may not in certain legal contexts. Nigerian property lawyers, courts, and some financial institutions require a bank-generated wire confirmation to authenticate a large transfer.

For transfers above $5,000 where the fixed fees are a small percentage, for institutional or legal documentation requirements, and for recipients who specifically need a SWIFT credit advice from a Nigerian bank, the traditional wire remains appropriate.

Sending USD to Nigeria with Grey

Grey provides a USD account with real US banking details, including a routing number and an account number issued by Grey's partner bank. Senders in the US use these details to pay as if they were paying any domestic US account. The payment goes out as a standard ACH transfer, bypasses the SWIFT correspondent chain entirely, and arrives in the recipient’s Grey USD balance within one to two business days.

For the recipient, the USD sits in their Grey account and can be held, converted to naira at a rate shown before confirmation, or used directly for USD-denominated expenses via the Grey virtual card.

The practical comparison on a $500 transfer: SWIFT costs $80 to $105 in stacked fees, leaving the recipient with $395 to $420. Grey costs $4 on the deposit, leaving the recipient with $496. On a monthly transfer of $500, that’s a difference of approximately $900 per year.

For senders who regularly send money to Nigeria with Grey, providing the Grey USD account details to the sender once removes all SWIFT complexity.

For those evaluating their full range of options, see our guide on sending money from the US for a broader comparison of methods and costs on the US-to-Nigeria corridor.

Send USD to Nigeria with Grey

Frequently asked questions on how to send USD from the USA to a Nigerian domiciliary account

Can I send USD to a Nigerian domiciliary account from the US?

Yes. A USD SWIFT wire from any US bank to a Nigerian domiciliary account is the standard method for sending dollars that land in Nigeria and remain there as dollars. You need the recipient’s domiciliary account number (not their naira account number), their bank’s SWIFT code, and the bank’s branch address. Alternatively, if the recipient holds a Grey USD account, you can send via ACH as a domestic US transfer, which avoids the SWIFT fee chain entirely.

How much does a SWIFT wire to a Nigerian domiciliary account cost?

Sending USD to a Nigerian domiciliary account via SWIFT can cost up to $60 to $100 in stacked fees across the three layers: the US bank’s outgoing wire fee ($35 to $50), correspondent bank deductions in transit ($10 to $30 per bank), and the Nigerian receiving bank’s incoming wire fee. These fees apply regardless of the transfer amount, which is why SWIFT wires only make financial sense on larger transfers where the fixed cost is a small percentage of the total.

How long does a SWIFT wire to Nigeria take?

SWIFT transfers to Nigeria typically take one to three business days after the US bank initiates the transfer. Large transfers may be held for CBN compliance review, which can extend the timeline. Transfers initiated late in the US banking day or on Fridays may not begin processing until the following business day. Grey ACH transfers to a US account number typically arrive in one to two business days.

Is there a cheaper way to get USD into Nigeria without using SWIFT?

Yes. A USD account through a multi-currency platform like Grey receives ACH transfers from US senders at a fraction of the cost of SWIFT transfers. Grey’s deposit fee is 0.8%, capped at $10, compared to $60-$100 in SWIFT fees for the same transfer. The tradeoff is that the USD lands in a Grey account rather than a Nigerian bank domiciliary account. For recipients who need SWIFT credit advice from a Nigerian bank for legal or institutional purposes, traditional wire transfers remain necessary. For everyday dollar receipts, the ACH route through Grey is significantly cheaper.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH incur a 0.8% fee (minimum $2, maximum $10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction.
Receive ACH payments from US clients in India

•

•

2 min read

As soon as you start working with US clients, three letters will likely become part of your monthly routine: ACH.

It will show up in payment instructions, invoices, onboarding forms.

The problem is, ACH only works within the US banking system. So if you’re based in India, you can’t receive these payments directly into your bank account, which means dealing with workarounds, fees, or the wrong setup.

This guide explains how to receive ACH payments in India and how to set things up so those three letters don’t cost you more than they should.

What is an ACH payment?

ACH (Automated Clearing House) is a US domestic payment network used for bank-to-bank transfers.

It’s commonly used for freelance payments, salaries from US-based companies, vendor payments, and recurring transfers like subscriptions or retainers.

For US clients, ACH is not considered an international transfer. It’s the standard way to send money within the country. That’s why many clients expect you to accept ACH payments, even if you’re based in India.

Also read: Safe ways to receive international payments in India

Can you receive ACH payments in India?

No, not directly.

ACH transfers only work between US bank accounts, and Indian bank accounts are not part of this network.

This means you can’t receive ACH payments into a regular Indian savings or current account, and your client cannot send funds to your IFSC account using ACH.

To receive ACH payments from US clients in India, you need access to US banking details first.

Why US clients prefer ACH payments

If you work with US clients, understanding this is key.

ACH is widely preferred because it is cheaper than international wire transfers, already integrated into payroll and accounting systems, and supports recurring or automated payments without requiring SWIFT setup.

From your client’s perspective, it’s the simplest option. So if you can accept ACH payments, you remove friction and make it easier (and faster) to get paid.

Best ways to receive US payments in India

There are three main ways to receive USD payments from US clients in India:

  • SWIFT (international wire transfer)
  • PayPal
  • Virtual US account (ACH access)

Each option works differently in terms of fees, speed, and control over your money.

You may also like: Top platforms to earn US dollars in India

Option 1: SWIFT (wire transfer to Indian bank)

This is the traditional method for receiving international payments in India.

How it works

Your client sends money via SWIFT to your Indian bank account. The funds pass through intermediary banks before reaching your account, where they are automatically converted to INR.

What to expect

Processing typically takes 2 to 5 business days. During this process, multiple deductions can occur, and you have no control over the exchange rate used.

Typical costs

You may encounter several charges, including:

  • Sending fee (paid by client or shared)
  • Intermediary bank fees (around USD 10–30 per bank)
  • Exchange rate markup (usually 2% to 4%)
  • Receiving bank charges

India-specific note

Indian banks usually issue an FIRC (Foreign Inward Remittance Certificate) for these payments. This is important for tax filing and GST compliance when exporting services.

Also read: Best ways Indians get paid by US and UK companies

Option 2: PayPal

PayPal is a popular option for freelancers in India because it is easy to set up and widely accepted.

How it works

Clients send USD via PayPal, but the funds are automatically converted to INR before being withdrawn to your Indian bank account.

What to expect

PayPal is generally faster than SWIFT and has a simpler onboarding process.

Costs to consider

The trade-off is cost. PayPal charges receiving fees depending on the transaction type and applies a currency conversion markup, typically between 3% and 5%.

Important for India

PayPal India does not allow you to hold USD balances. All funds are automatically converted to INR, which means you cannot control when or at what rate conversion happens.

Option 3: Virtual US account (best way to receive ACH in India)

For many freelancers and remote workers, this is the most efficient way to receive USD payments from the US.

Platforms like Grey, Wise, and Payoneer provide virtual US bank account details that allow you to receive ACH payments.

How it works

You open a multi-currency account, get US account details (routing number and account number), and share them with your client.

From your client’s side, this is a local US transfer. From your side, you receive USD directly.

Why more Indians are choosing this method

This setup is becoming more common because it gives you more control and reduces unnecessary costs.

You can receive USD without forced conversion, avoid multiple intermediary fees, choose when to convert based on the exchange rate, and benefit from more predictable payments.

Over time, this can significantly improve how much you actually keep from each payment.

Read more: How Indians access USD banking without a US address

Using Grey to receive ACH payments in India

With Grey, you can open a multi-currency account and get US banking details without needing an SSN or a US address.

The setup is designed for freelancers, remote workers, and businesses that need a flexible way to receive USD and manage multiple currencies.

Once your account is ready, you can receive USD via ACH, hold your balance in USD, convert when it suits you (you can check rates using Grey’s currency converter), and send money to your Indian bank account.

You can also estimate your costs in advance using Grey’s fee calculator, or spend directly from your balance using the Grey virtual card.

Fees to expect

  • Receiving USD (ACH): 0.8% (min $2, max $10)
  • Conversion: 1% (capped for certain currency pairs)
  • Withdrawals: typically low and fixed depending on destination

Grey is registered with FinCEN in the US and FINTRAC in Canada and operates under applicable financial regulations.

RBI, FEMA, and compliance for receiving foreign payments in India

Receiving USD payments in India comes with regulatory considerations.

Payments from abroad are treated as export of services, and you may need an FIRC or equivalent documentation. Banks may also request details about the source of funds, and GST may apply depending on your business structure.

What about LRS?

The Liberalised Remittance Scheme (LRS) mainly applies to sending money out of India, not receiving it. However, it is often mentioned alongside cross-border payments, so it’s useful to understand the distinction.

What affects how much you receive from US payments

The amount you actually receive depends on more than just the transfer fee.

Exchange rate

Banks typically apply a markup of 2% to 4%, while PayPal often ranges from 3% to 5%. Fintech platforms usually offer more competitive rates.

Transfer method

SWIFT transfers involve multiple deductions, while ACH (via a US account) reduces intermediaries. Wallet-based systems apply their own fee structures.

Timing of conversion

If your funds are converted immediately, you have no control over the rate. Holding USD and converting later gives you more flexibility and can help you optimise your earnings.

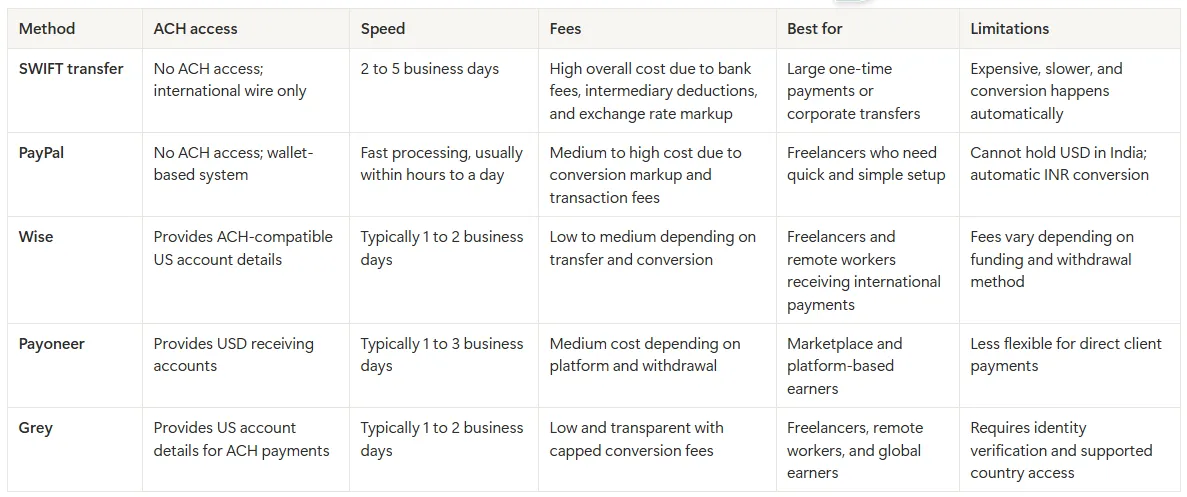
Comparison: ways to receive US payments in India

table comparing ways to receive US payments in India

Common mistakes to avoid when receiving US payments in India

Even with the right setup, a few common habits can quietly reduce how much you actually earn from each payment.

Accepting forced conversion every time

If your provider automatically converts USD to INR on arrival, you lose control over the exchange rate. Over time, this can lead to consistent losses, especially when rates fluctuate.

Not tracking exchange rates

Exchange rates change daily. Even small differences can add up across multiple payments, particularly if you’re working with international clients long-term.

Using SWIFT as the default

SWIFT transfers are reliable, but they are often the most expensive option. Between intermediary fees and exchange rate markups, the total cost can be higher than it initially appears.

Choosing the right setup for receiving ACH payments

Receiving ACH payments from US clients in India is less about the payment method itself and more about how your setup is structured.

The right setup gives you more control over your money and helps reduce unnecessary costs over time. Instead of relying on automatic conversions or multiple intermediaries, you can create a system that works in your favour.

With a well-optimised setup, you can:

  • Receive USD without forced conversion
  • Reduce total fees across multiple transactions
  • Decide when and how to convert based on exchange rates

For many Indian freelancers, remote workers, and businesses, accessing US banking details is the key step that makes everything else simpler and more predictable.

Also read: A guide for Indians getting paid by clients abroad

A simpler way to receive ACH payments from US clients

If you work with US clients and want a more predictable way to get paid, setting up access to US banking details can make a significant difference.

With Grey, you can open a free account, receive ACH payments from US clients in India, and manage your money across currencies in one place. You can hold USD, convert when it suits you, and move funds internationally without relying on traditional banking systems.

FAQs: Receiving ACH payments in India

Can I receive ACH payments directly in India?

No. ACH payments only work between US bank accounts, so you need US banking details to receive them.

Do I need a US bank account?

Not necessarily. Virtual US accounts provide the same functionality, allowing you to receive ACH payments without opening a traditional US bank account.

What is the best way to receive USD in India?

It depends on your priorities, but setups that avoid repeated currency conversions and reduce intermediary fees are usually more cost-effective.

Do I need an FIRC for every payment?

In most cases, yes. An FIRC (or equivalent documentation) is typically required for compliance, tax filing, and GST purposes.

Is it legal to receive foreign payments in India?

Yes. Receiving foreign payments is legal as long as you comply with RBI and FEMA regulations.

How to convert and send USD to Ugandan Shillings (UGX) online

•

•

2 min read

Managing cross-border payments doesn’t have to be complicated. Whether you’re a freelancer, remote worker, or supporting family in Uganda, converting USD to Ugandan Shilling (UGX) can be quick, secure, and hassle-free with Grey.

This guide shows you how to easily convert and send USD to UGX online, highlighting key benefits, costs, and tips for seamless transactions.

Why use Grey to convert and send USD to UGX?

Grey is a digital banking platform designed for global citizens who want to manage multiple currencies easily. Here’s why Grey is an excellent choice for converting and sending USD to UGX:

  • Competitive exchange rates: Grey offers real-time rates to ensure you get the most value when converting USD to UGX.
  • Low fees: Avoid the high conversion and transfer fees associated with traditional banks.
  • Quick transfers: Funds are processed quickly, ensuring your recipients get the money without delays.
  • User-friendly platform: Grey’s app and website are designed to make international transactions simple and accessible for everyone.

Exchange rates fluctuate for various reasons, so we’ve designed a handy, real time currency converter for you.

Also read: How to convert and send USD with Grey

How to convert and send USD to UGX with Grey

1. Create your Grey account

First, sign up for a free Grey account via the website or app, available on iOS and Android. Registration is straightforward and requires you to:

  • Provide basic personal information.
  • Verify your identity by uploading the required documents.
  • Set up your virtual wallet for multiple currencies, including USD.

2. Add USD to your Grey account

Once your account is active, deposit USD into your Grey wallet. You can do this in several ways:

  • Bank transfer: Link your USD bank account and transfer funds directly.
  • Freelance platforms: Receive payments from platforms like Upwork or Fiverr directly into your Grey USD wallet.
  • Wire transfers: Accept payments from international clients or businesses.

With USD in your account, you can convert it into UGX.

3. Convert USD to Ugandan Shilling with Grey

Follow these steps to convert your USD to UGX:

  1. Log into your account: Open the Grey app or website and sign in.
  2. Navigate to currency exchange: Select the “Convert” option from the dashboard.
  3. Choose currencies: Select USD as the source currency and UGX as the destination currency.
  4. Enter the amount: Specify the amount of USD you want to convert.
  5. Confirm the transaction: Review the exchange rate, fees, and total amount in UGX, then click “Convert.” The converted funds will appear in your UGX wallet instantly.

4. Send UGX to your recipient

Once your USD is converted to UGX, it’s time to transfer the funds to your recipient in Uganda. Here’s how:

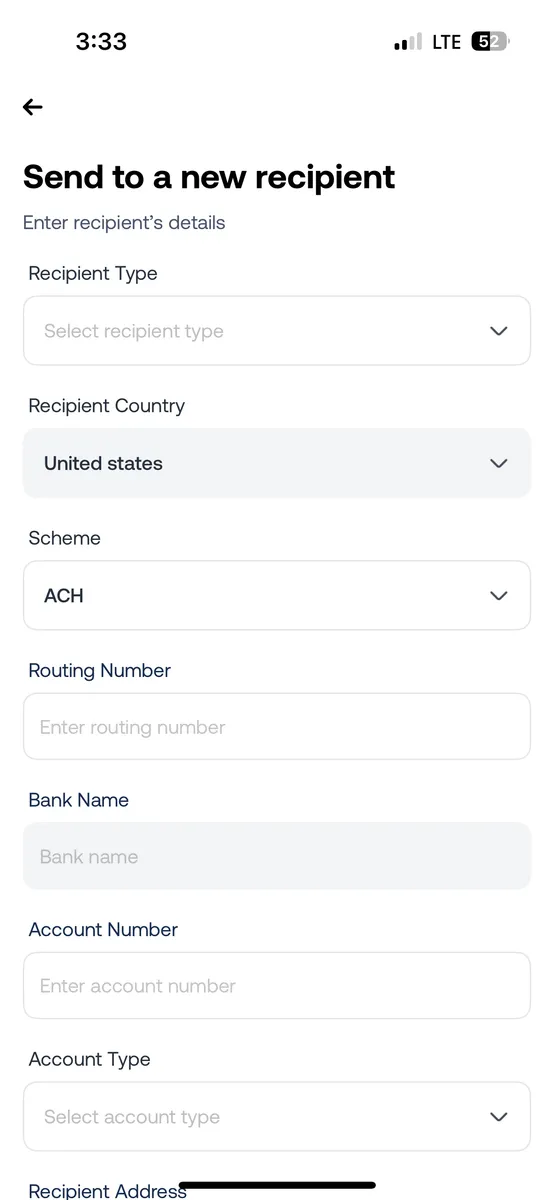
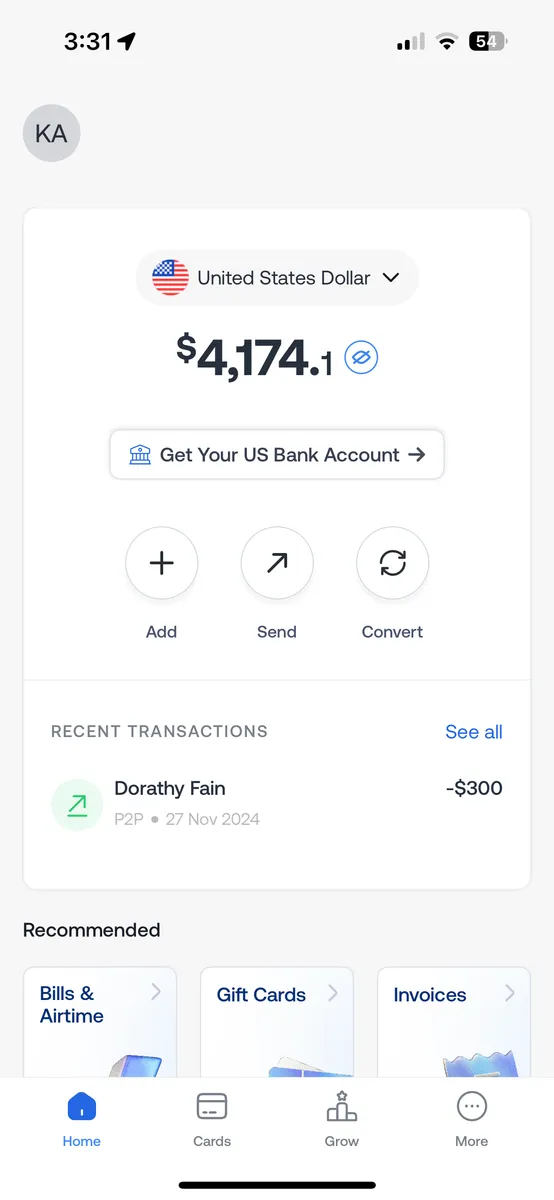
1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

676ec441190ed0b08ba00d26 676ebd9e62b40f1197672db7 send us dollars grey 6

2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

676ec442190ed0b08ba00d42 676ebd4d245072006253a99c send us dollars grey 4

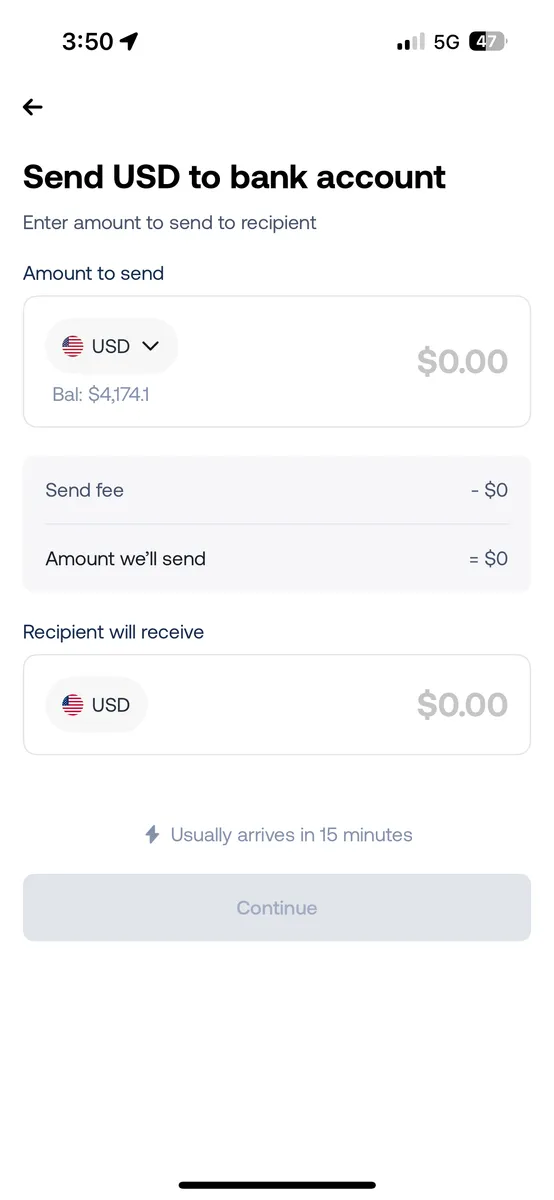
3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

676ec442190ed0b08ba00d3f 676ec3b94c9821344d4d5d63 IMG 0368

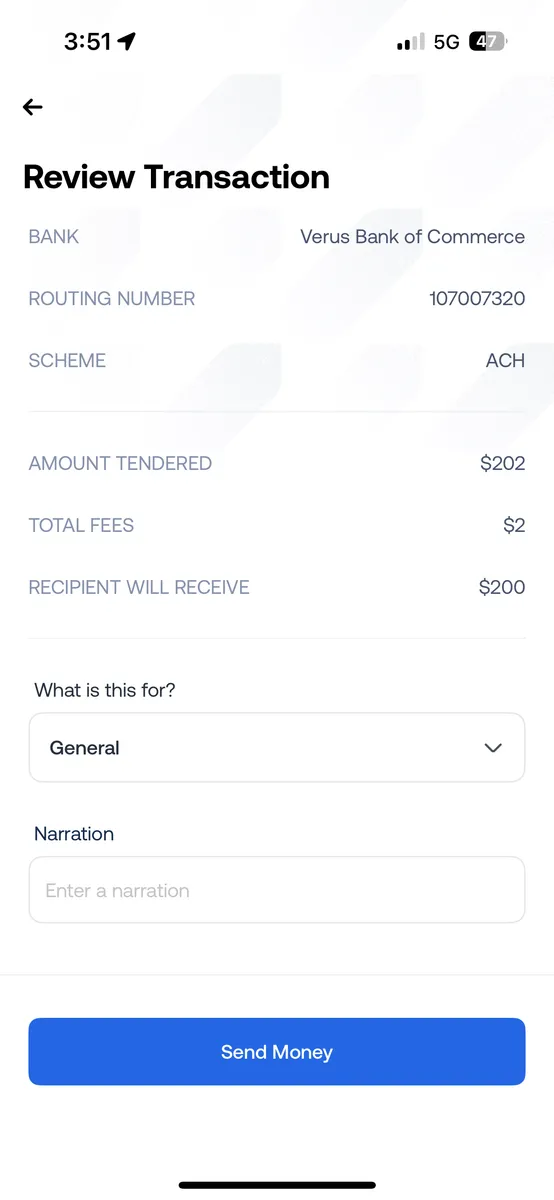
4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

676ec442190ed0b08ba00d79 676ec3c426d44aa2a43d7fc8 IMG 0370

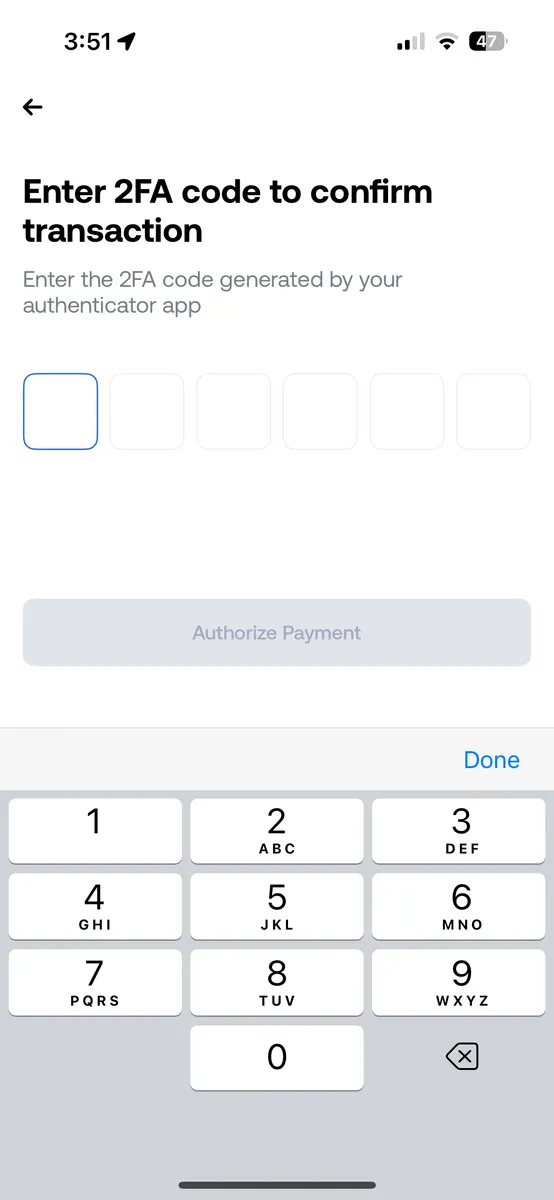
5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

676ec442190ed0b08ba00d45 676ec3d1138ab1eb14571c89 IMG 0371

‍

‍You may also like: How to convert and send USD to TZS online

Key tips for converting and sending USD to UGX

  1. Monitor exchange rates: Keep an eye on the exchange rate to convert your funds at the best possible time.
  2. Double-check recipient details: Ensure the accuracy of bank account or mobile wallet information to avoid delays.
  3. Use Grey’s multi-currency wallets: Store USD and UGX in your Grey account to avoid frequent conversions and save on fees.
  4. Track your transactions: Grey offers a transaction history feature to easily track conversions and transfers.

Why Grey is the best option for USD to UGX transfers

Grey stands out as a reliable and cost-effective platform for handling international payments. Here’s why it’s a top choice:

  • Speed: Transfers are processed faster than most traditional banks, so your recipients get their money quickly.
  • Savings: With low fees and competitive exchange rates, you keep more of your hard-earned money.
  • Flexibility: Manage multiple currencies from one account and send funds anytime, anywhere.
  • Security: Grey prioritises secure transactions, giving you peace of mind.

Take control of your cross-border payments with Grey

Converting and sending USD to Ugandan Shilling has never been easier. Whether supporting family, paying vendors, or managing personal finances, Grey’s seamless platform saves you time, money, and effort.

Ready to simplify your financial transactions? Sign up with Grey today and enjoy a hassle-free way to convert and send USD to UGX online.

‍

How to convert and send US dollars (USD) with Grey

•

•

2 min read

As a digital nomad your finances should work as flexibly as you do. With Grey, converting and sending USD becomes effortless, no matter where you are. From managing payments with US clients to handling multiple income streams, Grey makes accessing and transferring your funds quick, affordable, and hassle-free.

In this guide, we’ll walk you through effortlessly converting and sending US dollars with Grey, revealing how to maximise savings, cut through complexity, and make global financial management a breeze.

Why Grey is perfect for sending and converting US dollars

Managing your finances can be challenging, especially when working with clients or employers in different currencies. Whether you’re based in Asia, Europe, or anywhere else, having a platform that supports multi-currency accounts and provides transparent exchange rates is essential.

Grey offers several advantages for digital nomads and remote workers:

  • Multi-currency accounts: Grey lets you hold and manage funds in multiple currencies, including USD, EUR, GBP, and more, making it easy to convert and send money.
  • Low fees and competitive rates: Grey provides low conversion fees and competitive exchange rates, ensuring that more of your earnings stay with you.
  • Global accessibility: Whether in Bali, Mexico, or Spain, Grey’s mobile app allows you to manage your finances anywhere with an internet connection.
  • Seamless transfers: Sending USD or any other currency is fast and simple. Grey allows instant transfers to various bank accounts and wallets globally.
  • Easy account integration: You can link your Grey account to platforms like Amazon, freelance job sites, and other payment systems, simplifying the process of receiving and sending payments.

Exchange rates often fluctuate for several reasons, so we’ve created a special currency converter for you.

The benefits of converting and sending USD with Grey

Before diving into the conversion and sending process, let’s take a moment to explore why Grey is a great option for converting USD into local currencies or sending it to other accounts.

  1. Competitive exchange rates

Grey offers competitive exchange rates compared to traditional banks and other payment platforms. While rates vary based on market conditions, Grey provides real-time rates with a transparent view of conversion fees.

  1. Low conversion fees

Grey’s conversion fees are designed to be transparent and affordable.

  1. Efficient cross-border transfers

Fast and secure transfers are key when working internationally. Grey enables you to send USD to international accounts almost instantly. This feature is particularly useful for remote workers who must pay international invoices or send money to family members in other countries.

Grey also allows for quick transfers between different currency accounts, so if you need to convert USD into GBP, EUR, or any other supported currency, you can do so easily.

  1. Global accessibility

Since Grey is a fully digital platform, you can access it from anywhere in the world. This is particularly advantageous for digital nomads who frequently travel or live abroad, as it provides a consistent and reliable way to manage your finances regardless of location.

Step-by-step guide: How to convert and send USD with Grey

Now that you understand the benefits of using Grey, let’s walk through the detailed process of converting USD to another currency and sending it to a recipient, whether for personal or business reasons.

Step 1: Sign up for a Grey account

If you haven’t already, the first step is to create an account with Grey. Visit Grey’s website or download the app from the App Store or Google Play. The sign-up process is straightforward and typically takes just a few minutes.

To start, you’ll need to provide personal details, verify your identity, and set up your account.

Step 2: Deposit USD into your Grey account

Once you’ve created your account, you can deposit USD into your Grey account. You can do this through several methods:

  • Bank transfer: Link your bank account to Grey and deposit funds directly into your USD account.
  • Payment platforms: If you receive payments from platforms like PayPal, Stripe, or other freelance networks, you can transfer your earnings directly to your Grey account.
  • Wire transfer: If you’re working with clients or employers who prefer wire transfers, you can provide them with your Grey account details so they can receive USD payments.

You can begin the conversion process after depositing USD into your Grey account.

Step 3: Convert USD to another currency

To convert USD into another currency, follow these steps:

  1. Open the Grey app: Log into your Grey account and navigate to the currency conversion section.
  2. Select the currencies: Choose USD as the source currency and select the destination currency (e.g., EUR, GBP, ZAR).
  3. Check the exchange rate: Grey will display the current exchange rate for the conversion, along with the conversion fees.
  4. Confirm the conversion: Once you’re satisfied with the rate and fees, confirm the transaction. Your funds will be converted and reflected in your Grey account in the new currency.

Step 4: Send USD or converted funds to a recipient

To send funds to another individual or account, you’ll need to:

1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

__wf_reserved_inherit

2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

__wf_reserved_inherit

3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

__wf_reserved_inherit

4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

__wf_reserved_inherit

5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

__wf_reserved_inherit

Convert and send USD: Key tips for remote workers

  1. Minimise fees: Always review Grey’s exchange rates and conversion fees before confirming any transaction. While Grey offers competitive rates, you may still want to plan your conversions to avoid unnecessary fees, especially if you’re sending large sums.
  2. Use local currency accounts: If you’re working in a country with a stable currency, consider holding a local currency account to avoid frequent conversions and fees.
  3. Monitor exchange rates: Grey updates its exchange rates in real time. If you’re converting large sums, it may be worth monitoring rates for a few days to ensure you get the best deal.
  4. Use Grey’s app for convenience: Grey’s mobile app allows you to convert and send USD or other currencies from anywhere in the world, which is a huge advantage for digital nomads who need to manage their finances on the go. Download Grey now and get started.

Simplify converting and sending USD with Grey

Converting and sending USD with Grey is an efficient and cost-effective way for remote workers and digital nomads to manage their finances. With competitive exchange rates, low fees, and the convenience of a fully digital platform, Grey provides a seamless solution for handling cross-border transactions.

Ready to start using Grey? Sign up today and take control of your global finances.

‍

How freelancers in Kenya can receive payments from international clients

•

•

2 min read

With the gig economy expanding to over 1.57 billion freelancers worldwide, many skilled professionals in Kenya are tapping into the global market. These professionals are writers, designers, software developers and engineers, content creators, data scientists, digital marketers, et cetera. However, despite this opportunity, many Kenyans still face a recurring problem: how to conveniently and safely receive payments from foreign clients.

Fortunately, there’s an easy solution to this. With Grey, you can receive payments in GBP and EUR and withdraw them directly into your Kenyan bank account, all from the comfort of your home.

In this article, we’ll show you how to  receive international payments from the UK and the European Union in Kenya. But first, let’s explore why Grey is the best solution for you as a resident freelancer or digital nomad in Kenya.

Why Grey is the best online global bank for freelancers in Kenya

  • No hidden fees: Our transparent pricing ensures you know exactly where your money goes, allowing you to keep more of your earnings in your pocket.
  • Competitive rates: Save on transaction fees and currency converter to stay updated, ensuring you convert your earnings at the best possible rates.
  • Fast payments: Receive funds without unnecessary delays.
  • Global access: Easily manage your money anytime and anywhere you are in the world.
  • Hold multiple currencies: Manage your finances in GBP or EUR without forced conversions.
  • Integrates with freelance platforms: Grey seamlessly integrates with freelance platforms like Upwork and Fiverr, so you can receive your earnings without hassle.

Also read: How to receive payments from freelance platforms easily in 2025

Now that you know why you should use Grey, here’s how to quickly get started:

How freelancers in Kenya can receive payments from the US, UK and EU clients with Grey

1. Create a Grey account

Register on the Grey website or download the mobile app to get started.

2. Complete identity verification

To verify your identity and ensure security, Grey requires Know Your Customer (KYC) verification before you can fully use your account. This involves submitting a valid ID, proof of address, and a selfie for security purposes. The process is quick and ensures smooth transactions.

Also read: Top reasons your KYC verification is failing and how to fix them

3. Request your foreign bank accounts

Once verified, navigate to the ‘Accounts’ section to generate your UK or EU bank account to receive global payments. Your account will be generated instantly, and you’ll receive your bank account details and your IBAN, sort code or routing number.

4. Link your account to freelancing platforms or share your details with clients

Once you’ve created your foreign account, you can easily share it with clients or add it to freelance platforms to receive payments directly. You can also convert your earnings to Kenyan Shillings (Ksh) and withdraw them to your local bank account or mobile money.

Simplify banking across borders with Grey

Receiving payments in Kenya shouldn’t be complicated — and with Grey, it’s easier than ever. Plus, you can rest assured that your funds are secure.

Create your free Grey account to start enjoying inclusive banking designed just for you.

How South African freelancers can receive payments from the US, UK & EU clients

•

•

2 min read

South Africa is home to a growing community of freelancers, remote workers, and digital entrepreneurs offering services to clients across the US, UK, and Europe.

However, while working with international clients can be highly rewarding, receiving payments remains a major challenge. High transfer fees, poor exchange rates, and long processing times often reduce earnings and cause unnecessary delays.

With a Grey account, freelancers in South Africa can receive payments in USD, GBP, and EUR, convert at competitive rates, and withdraw directly to their South African bank accounts.

Also read: How freelancers in Morocco can receive payments from US, UK & EU clients

How to open a USD, GBP or EUR account with Grey

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

How South African freelancers can receive payments from the US, UK & EU clients
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location. In this case, it’s South Africa.
How South African freelancers can receive payments from the US, UK & EU clients
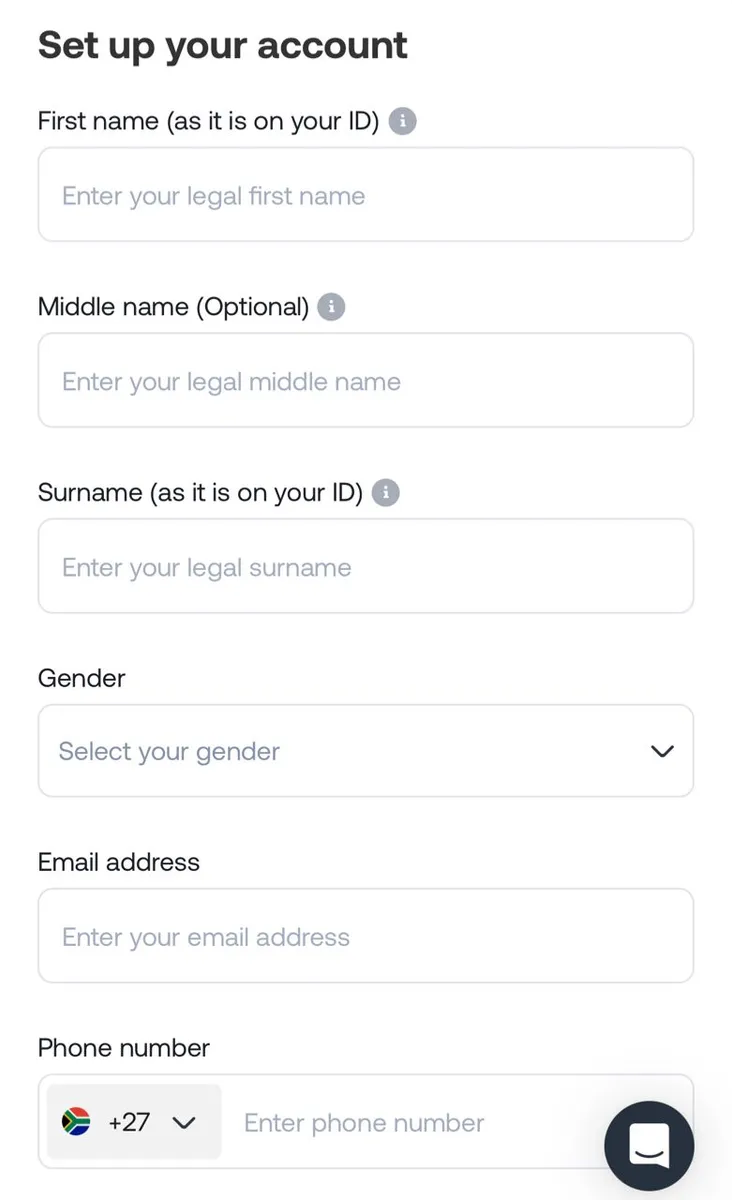
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
How South African freelancers can receive payments from the US, UK & EU clients
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
How South African freelancers can receive payments from the US, UK & EU clients
  • Once you’re set up, you’re ready for identity verification.

2. Verify your identity for secure access

Here’s what you’ll need to provide:

  • Government-issued ID: A valid passport or national ID card is required. Make sure it’s clear and up-to-date.
  • Proof of address: A recent utility bill or bank statement will verify your location. Grey uses this document to confirm your residency.
  • Submit your documents for review: Once uploaded, Grey will review your documents, a process that typically takes a few business days. Clear and accurate documentation speeds up approval.

3. Access your global bank accounts

Once your identity is verified, log in to your Grey account.

  • Navigate to the “Accounts” section and select “Create Account.”
  • Choose the currency (USD, GBP or EUR).
  • Your global bank account details, including your account number and routing number, will be generated instantly.

Also read: How to receive payments from Guru in South Africa in 2025

How to receive payments from US, UK & EU clients

Once you’ve created your Grey account, receiving payments is easy. Here’s how:

  • Log in to your Grey account via the app or website to securely access your currency balances.
  • Navigate to "Home" and select your preferred currency account (e.g., USD, EUR, GBP).
  • Share your account details (IBAN, sort code, or account number) with international clients, employers, or payment platforms like PayPal and Upwork.
  • The funds will be deposited into the Grey account.

Also read: How to receive Amazon payments in South Africa

Why Grey is the best online global bank for South African freelancers

Here are major reasons Grey stands out as the best online bank for freelancers in South Africa:

  • No hidden fees – Transparent pricing so you keep more of your earnings.
  • Hold multiple currencies – Manage your finances in USD, GBP, or EUR without forced conversions.
  • Fast international transfers – Receive and send money globally without delays.
  • Global access – Manage your money anytime, anywhere with Grey.
  • Direct withdrawals – Transfer funds seamlessly to your South African bank account.

Simplify banking across borders with Grey

Receiving international payments in South Africa doesn’t have to be complicated. With Grey, you can open a foreign bank account and accept payments seamlessly.

Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

‍

Arrow (up)

Back to top