<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada#article","headline":"The biggest financial challenges expats face in UK, US and Canada","description":"Learn how Grey can help expats in the UK, US, and Canada manage banking, currency exchange, and financial challenges.","inLanguage":"en","url":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada","mainEntityOfPage":{"@id":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada#webpage"},"datePublished":"2025-02-07T19:49:51.955Z","dateModified":"2026-06-15T16:33:32.117Z","author":{"@type":"Person","@id":"https://grey.co/authors/priscila-marotti#person","name":"Priscila Marotti","url":"https://grey.co/authors/priscila-marotti","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/priscila-marotti/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3015bad96c1362f2e57af5_6a3015b9f530256f0c489f60_the-biggest-financial-challenges-expats-face-in-uk-us-and-canada__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3015bad96c1362f2e57af5_6a3015b9f530256f0c489f60_the-biggest-financial-challenges-expats-face-in-uk-us-and-canada__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada#webpage","url":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada","name":"The biggest financial challenges expats face in UK, US and Canada","description":"Learn how Grey can help expats in the UK, US, and Canada manage banking, currency exchange, and financial challenges.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"The biggest financial challenges expats face in UK, US and Canada","item":"https://grey.co/blog/the-biggest-financial-challenges-expats-face-in-uk-us-and-canada"}]}] </script>

The biggest financial challenges expats face in UK, US and Canada

Priscila Marotti

TABLE OF CONTENT

SHARE THIS POST

Moving to a new country brings exciting opportunities but also financial challenges. UK, US, and Canada expats often struggle with banking, currency exchange, taxation, and managing expenses across borders. Understanding these challenges can help expatriates better navigate their financial lives abroad and avoid unnecessary financial stress.

Opening a bank account

One of the first financial hurdles expats face is setting up a local bank account. Many banks require proof of residence, employment, or a credit history, which can be difficult for newcomers.

  • UK: Expats often struggle to provide utility bills or rental agreements in their name since many landlords include rent bills or require long-term residency. Non-resident accounts are available but come with higher fees and limited functionality.
  • US and Canada: Social Security Numbers (SSN) or Social Insurance Numbers (SIN) are required to open an account, and local employment or a permanent address may be necessary. This creates added complexity for those still settling in.

Also read: How to create US and UK bank accounts as a migrant worker

Currency exchange and international transfers

Managing finances across different currencies can be costly. Traditional banks and money transfer services often charge high fees and offer unfavourable exchange rates.

  • High fees: Some banks charge up to 5% in conversion fees, and international wire transfers may have hidden costs.
  • Fluctuating exchange rates: Exchange rate volatility can reduce the value of an expat’s salary or savings when converted to their home currency.

Credit history and access to loans

Credit scores do not transfer between countries, meaning expats must build their credit from scratch.

  • US and Canada: Credit scores heavily influence financial opportunities, making it difficult for expats without a local credit history to access loans, mortgages, or even credit cards.
  • UK: Some banks offer ‘international accounts’ with limited credit options, but they come with higher fees and stricter eligibility requirements.

You may also like: How to create a Grey US virtual card

Taxation complexities

Understanding tax obligations is another major challenge. Expats may be subject to double taxation if both their home country and host country require them to file tax returns.

  • United States: Expats must file annually with the IRS, even if they live abroad, and are subject to worldwide income taxation. However, exclusions like the Foreign Earned Income Exclusion (FEIE) may apply.
  • United Kingdom: Expats pay taxes only on UK-earned income unless they remain domiciled in the UK for tax purposes.
  • Canada: Tax residency is based on ties to the country, meaning expats may still owe taxes even after moving abroad unless they sever most financial and social ties.

Cost of living and financial planning

The cost of living in major cities like London, New York, and Toronto can be significantly higher than in other parts of the world. Expats often underestimate housing, healthcare, and insurance expenses.

  • Housing: In cities like London and New York, rent can consume more than 50% of an individual’s income. Landlords often require multiple months’ rent upfront if the tenant lacks a local credit history.
  • Healthcare: The NHS provides free healthcare in the UK, but some services require out-of-pocket expenses or private insurance. Healthcare is expensive in the US, with many employers offering private insurance. Public healthcare in Canada exists but comes with long waiting times, prompting many to opt for private coverage. For expatriates navigating these healthcare systems, Insured Nomads offers an affordable, flexible health insurance plan designed to provide coverage globally.
  • Pensions and taxes: Expats may need to continue contributing to pensions in their home country or transfer pension benefits to the new country, a process that can be complicated and subject to tax penalties.

Expats may struggle with unexpected costs without careful budgeting, making financial planning essential.

How Grey simplifies financial management for expats

Grey offers a seamless solution to many of these financial challenges, making life easier for expats by providing a modern, borderless banking experience. With a Grey account, expats can:

  • Open international accounts easily: No need for local credit history, permanent residency, or complex paperwork.
  • Send and receive money affordably: Access competitive exchange rates and low fees on international transfers, helping expats save money.
  • Manage multiple currencies: You can hold and exchange money in different currencies without worrying about high conversion costs or exchange rate volatility.
  • Simplify financial transactions: Enjoy fast, secure, and transparent banking without hidden fees, making it easier to manage finances across different countries.

Grey provides a hassle-free way for expats in the UK, US, and Canada to manage finances across borders. It helps them avoid high banking fees, currency exchange losses, and administrative headaches. Open a Grey account today and easily control your international finances.

‍

Last updated:

October 13, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to send USD to a Nigerian domiciliary account

•

•

2 min read

Most of the information you’ll find online on sending money to Nigeria will most likely focus on naira delivery. But that’s not what you need if the recipient has a domiciliary account and wants to receive USD without converting to naira.

A Nigerian domiciliary account holds foreign currency, typically US dollars, without forcing an immediate conversion. Sending USD to one keeps that option in the recipient’s hands. It’s a decent choice for freelancers holding dollar savings, importers managing USD expenses, or anyone who wants to preserve dollar value rather than convert at a potentially unfavourable rate.

The mechanics of getting USD from a US bank account into a Nigerian domiciliary account are specific. You need to understand the required details, the fees you’ll encounter, and the mistakes that cause transfers to fail or arrive short before you send. For a broader overview of receiving dollar income in Nigeria, see our guide on how to receive US dollars in Nigeria and the options available for opening a Nigerian dollar account.

What is a domiciliary account?

A domiciliary account, also commonly called a dom account, is a bank account held at a Nigerian commercial bank that stores foreign currency without converting it to naira. The Central Bank of Nigeria (CBN) permits individuals and businesses to hold certain foreign currencies in domiciliary accounts at licensed Nigerian banks.

The key distinction from a standard naira savings account is that funds credited to a domiciliary account remain in the foreign currency in which they were credited. The account holder decides when and whether to convert, and at what rate. This matters because the naira has historically depreciated against major currencies, and holding USD can protect against the value erosion of naira conversions.

Domiciliary accounts are the primary mechanism by which Nigerians receive international SWIFT wire transfers in USD. CBN’s foreign exchange regulations require that inbound USD transfers be credited to a domiciliary account or converted to naira at the official rate. If a sender directs a USD wire to a standard naira account, the bank will convert it on arrival. If the recipient wants the money to remain in USD, the wire must be sent to the domiciliary account number, not the naira account number.

Both the naira and domiciliary accounts exist at the same bank for the same person and may look similar. They are different accounts with different account numbers. Confirm the domiciliary account number explicitly with the recipient before initiating the wire.

How to send USD via SWIFT wire: step by step

A SWIFT wire from a US bank to a Nigerian domiciliary account requires specific information, and if you miss any, it can cause delays, returns, or the transfer landing in the wrong account.

Step one: Collect the recipient’s domiciliary account details.

You need all of the following:

  • Recipient’s full legal name, exactly as registered with the Nigerian bank
  • The domiciliary account number (not the naira account number)
  • The bank name and branch address
  • The bank’s SWIFT code

The SWIFT codes for some major Nigerian banks are as follows: Access Bank: ABNGNGLA, GTBank (Guaranty Trust Bank): GTBINGLA, Zenith Bank: ZEIBNGLA, First Bank of Nigeria: FBNINGLA, United Bank for Africa (UBA): UNAFNGLA, Stanbic IBTC Bank: SBICNGLX, Ecobank Nigeria: ECOCNGLA, Fidelity Bank: FBNKNGLA, FCMB (First City Monument Bank): FCMBNGLA.

Always verify the SWIFT code directly with the recipient’s bank before initiating a high-value transfer, as branch-specific codes sometimes differ from the head office code.

Step two: Initiate the wire transfer at your US bank.

Log in to your online banking or visit a branch. Navigate to international wire transfers. Enter the recipient’s details: full name, domiciliary account number, bank name, branch address, and SWIFT code. Specify USD as the transfer currency. Nigeria is a USD-only wire destination at Bank of America; Bank of America requires international wires to Nigeria to be sent in US dollars due to local regulations, and foreign currency transfers are not available to this destination.

Step three: Select your charge instruction.

Depending on your bank, you may be asked whether to use SHA (shared charges) or OUR (sender pays all). Under SHA, correspondent bank fees are deducted from the transfer amount in transit, meaning the recipient receives less than what you send. Under OUR, you pay all correspondent fees upfront, and the recipient receives the full amount. For transfers where the recipient needs a specific USD amount, OUR is the right choice. For transfers where the fee deductions are acceptable, SHA is the standard default.

Step four: The wire routes through the SWIFT network.

Not all US banks have direct correspondent relationships with Nigerian banks. A US-to-Nigeria wire might involve two or three correspondent bank hops due to limited direct banking relationships. Each correspondent bank in the chain processes and forwards the payment, and under SHA, each one can deduct a fee from the transfer amount before forwarding the remainder.

Step five: The money arrives in the domiciliary account.

SWIFT transfers to Nigeria typically take one to three business days. Large transfers may be held for CBN compliance review, which can extend the timeline. Once that is cleared, the USD is credited to the domiciliary account and remains in dollars until the account holder decides to convert or withdraw.

What a SWIFT wire really costs

The posted fee at your US bank is not the full cost of a SWIFT wire to Nigeria. Three fee layers stack on every transfer.

Layer one: Your US bank’s outgoing wire fee
A 2026 NerdWallet survey reported a median outgoing international wire transfer fee of $45, with major US banks charging $35 to $50 per send. Chase charges $40 online for USD wires. Bank of America charges $35 for online transfers. Wells Fargo charges $25 to $45, depending on account type.

Layer two: Correspondent bank deductions in transit
Correspondent banks that relay the payment along the SWIFT chain can each deduct $10 to $30 in fees from the transferred amount before it reaches its destination. On a US-to-Nigeria wire routed through two correspondent banks, that’s $20 to $60 deducted from the transfer amount. Neither you nor the recipient is notified of these deductions in advance.

Layer three: The Nigerian receiving bank’s incoming wire fee
Nigerian banks charge an inbound wire fee on SWIFT receipts. This is typically deducted from the funds upon arrival before they are credited to the domiciliary account.

Here’s what this looks like on real transfers:

$500 transfer $5,000 transfer
US bank outgoing wire fee $40 $40
Correspondent bank deductions (estimated) $30–$50 $30–$50
Nigerian receiving bank fee $10–$15 $10–$15
Total fees $80–$105 $80–$105
As a percentage of transfer 16–21% 1.6–2.1%
USD received in domiciliary account $395–$420 $4,895–$4,920

‍

Also read: Sending USD from Nigeria to the USA: Step-by-step guide

Cheaper alternatives to a SWIFT wire transfer

For smaller or regular payments, the SWIFT route is difficult to justify. Here are the practical alternatives and when each one makes sense.

Multi-currency accounts (the recommended alternative for most senders)

Platforms like Grey provide USD accounts with US routing numbers and account numbers that senders can use to pay as a standard domestic US transfer, with no SWIFT correspondent chain involved.

The sender pays via ACH from their US bank account to a US account number. The money arrives in the recipient’s Grey USD balance without correspondent bank deductions. The recipient then controls when to convert or hold the USD. Multi-currency fintech accounts route payments through their own infrastructure rather than the SWIFT correspondent chain.

Grey’s deposit fee via ACH is 0.8%, capped at $10. On a $500 transfer, the fee is $4. On a $5,000 transfer, the fee is $10. Currency conversion is charged at 1% capped at $6 when the recipient converts to naira.

Stablecoin route

Some senders use USDC to move dollar value to Nigeria. The sender buys USDC on a US-licensed exchange, transfers to the recipient’s wallet address, and the recipient converts to USD or naira via a licensed Nigerian platform. This route avoids SWIFT entirely and can be faster, but requires both parties to be comfortable with crypto infrastructure and introduces volatility risk if either party converts at an unfavourable moment.

When SWIFT is still the right choice

If the recipient holds a domiciliary account and wants to receive funds in dollars without naira conversion, a bank wire is one of the most practical routes. SWIFT confirmations from US banks carry institutional credibility that other receipts may not in certain legal contexts. Nigerian property lawyers, courts, and some financial institutions require a bank-generated wire confirmation to authenticate a large transfer.

For transfers above $5,000 where the fixed fees are a small percentage, for institutional or legal documentation requirements, and for recipients who specifically need a SWIFT credit advice from a Nigerian bank, the traditional wire remains appropriate.

Sending USD to Nigeria with Grey

Grey provides a USD account with real US banking details, including a routing number and an account number issued by Grey's partner bank. Senders in the US use these details to pay as if they were paying any domestic US account. The payment goes out as a standard ACH transfer, bypasses the SWIFT correspondent chain entirely, and arrives in the recipient’s Grey USD balance within one to two business days.

For the recipient, the USD sits in their Grey account and can be held, converted to naira at a rate shown before confirmation, or used directly for USD-denominated expenses via the Grey virtual card.

The practical comparison on a $500 transfer: SWIFT costs $80 to $105 in stacked fees, leaving the recipient with $395 to $420. Grey costs $4 on the deposit, leaving the recipient with $496. On a monthly transfer of $500, that’s a difference of approximately $900 per year.

For senders who regularly send money to Nigeria with Grey, providing the Grey USD account details to the sender once removes all SWIFT complexity.

For those evaluating their full range of options, see our guide on sending money from the US for a broader comparison of methods and costs on the US-to-Nigeria corridor.

Send USD to Nigeria with Grey

Frequently asked questions on how to send USD from the USA to a Nigerian domiciliary account

Can I send USD to a Nigerian domiciliary account from the US?

Yes. A USD SWIFT wire from any US bank to a Nigerian domiciliary account is the standard method for sending dollars that land in Nigeria and remain there as dollars. You need the recipient’s domiciliary account number (not their naira account number), their bank’s SWIFT code, and the bank’s branch address. Alternatively, if the recipient holds a Grey USD account, you can send via ACH as a domestic US transfer, which avoids the SWIFT fee chain entirely.

How much does a SWIFT wire to a Nigerian domiciliary account cost?

Sending USD to a Nigerian domiciliary account via SWIFT can cost up to $60 to $100 in stacked fees across the three layers: the US bank’s outgoing wire fee ($35 to $50), correspondent bank deductions in transit ($10 to $30 per bank), and the Nigerian receiving bank’s incoming wire fee. These fees apply regardless of the transfer amount, which is why SWIFT wires only make financial sense on larger transfers where the fixed cost is a small percentage of the total.

How long does a SWIFT wire to Nigeria take?

SWIFT transfers to Nigeria typically take one to three business days after the US bank initiates the transfer. Large transfers may be held for CBN compliance review, which can extend the timeline. Transfers initiated late in the US banking day or on Fridays may not begin processing until the following business day. Grey ACH transfers to a US account number typically arrive in one to two business days.

Is there a cheaper way to get USD into Nigeria without using SWIFT?

Yes. A USD account through a multi-currency platform like Grey receives ACH transfers from US senders at a fraction of the cost of SWIFT transfers. Grey’s deposit fee is 0.8%, capped at $10, compared to $60-$100 in SWIFT fees for the same transfer. The tradeoff is that the USD lands in a Grey account rather than a Nigerian bank domiciliary account. For recipients who need SWIFT credit advice from a Nigerian bank for legal or institutional purposes, traditional wire transfers remain necessary. For everyday dollar receipts, the ACH route through Grey is significantly cheaper.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH incur a 0.8% fee (minimum $2, maximum $10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction.
How to convert and send USD to Ugandan Shillings (UGX) online

•

•

2 min read

Managing cross-border payments doesn’t have to be complicated. Whether you’re a freelancer, remote worker, or supporting family in Uganda, converting USD to Ugandan Shilling (UGX) can be quick, secure, and hassle-free with Grey.

This guide shows you how to easily convert and send USD to UGX online, highlighting key benefits, costs, and tips for seamless transactions.

Why use Grey to convert and send USD to UGX?

Grey is a digital banking platform designed for global citizens who want to manage multiple currencies easily. Here’s why Grey is an excellent choice for converting and sending USD to UGX:

  • Competitive exchange rates: Grey offers real-time rates to ensure you get the most value when converting USD to UGX.
  • Low fees: Avoid the high conversion and transfer fees associated with traditional banks.
  • Quick transfers: Funds are processed quickly, ensuring your recipients get the money without delays.
  • User-friendly platform: Grey’s app and website are designed to make international transactions simple and accessible for everyone.

Exchange rates fluctuate for various reasons, so we’ve designed a handy, real time currency converter for you.

Also read: How to convert and send USD with Grey

How to convert and send USD to UGX with Grey

1. Create your Grey account

First, sign up for a free Grey account via the website or app, available on iOS and Android. Registration is straightforward and requires you to:

  • Provide basic personal information.
  • Verify your identity by uploading the required documents.
  • Set up your virtual wallet for multiple currencies, including USD.

2. Add USD to your Grey account

Once your account is active, deposit USD into your Grey wallet. You can do this in several ways:

  • Bank transfer: Link your USD bank account and transfer funds directly.
  • Freelance platforms: Receive payments from platforms like Upwork or Fiverr directly into your Grey USD wallet.
  • Wire transfers: Accept payments from international clients or businesses.

With USD in your account, you can convert it into UGX.

3. Convert USD to Ugandan Shilling with Grey

Follow these steps to convert your USD to UGX:

  1. Log into your account: Open the Grey app or website and sign in.
  2. Navigate to currency exchange: Select the “Convert” option from the dashboard.
  3. Choose currencies: Select USD as the source currency and UGX as the destination currency.
  4. Enter the amount: Specify the amount of USD you want to convert.
  5. Confirm the transaction: Review the exchange rate, fees, and total amount in UGX, then click “Convert.” The converted funds will appear in your UGX wallet instantly.

4. Send UGX to your recipient

Once your USD is converted to UGX, it’s time to transfer the funds to your recipient in Uganda. Here’s how:

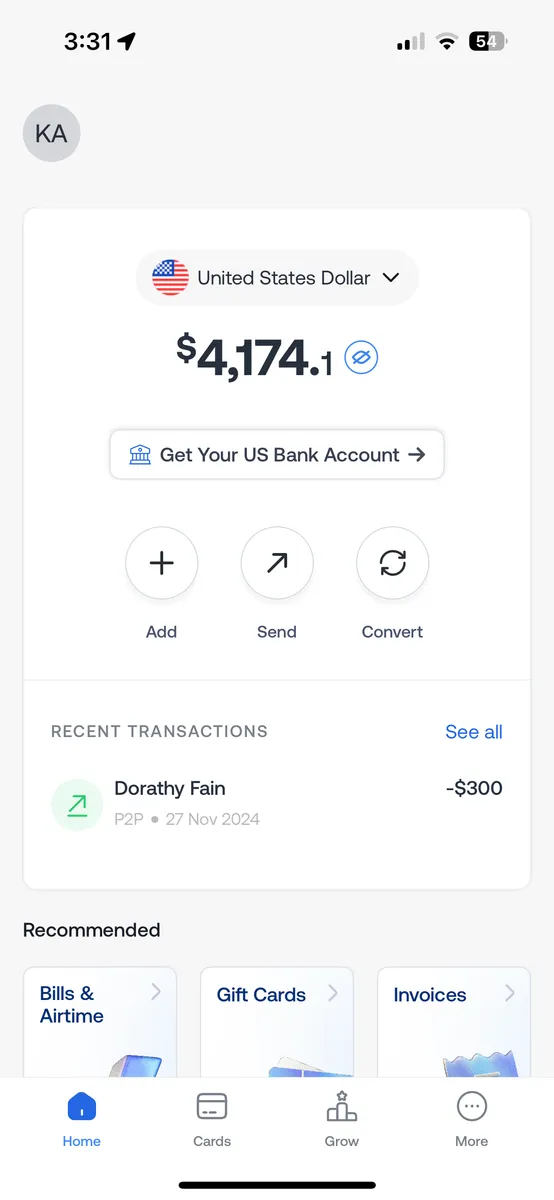
1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

676ec441190ed0b08ba00d26 676ebd9e62b40f1197672db7 send us dollars grey 6

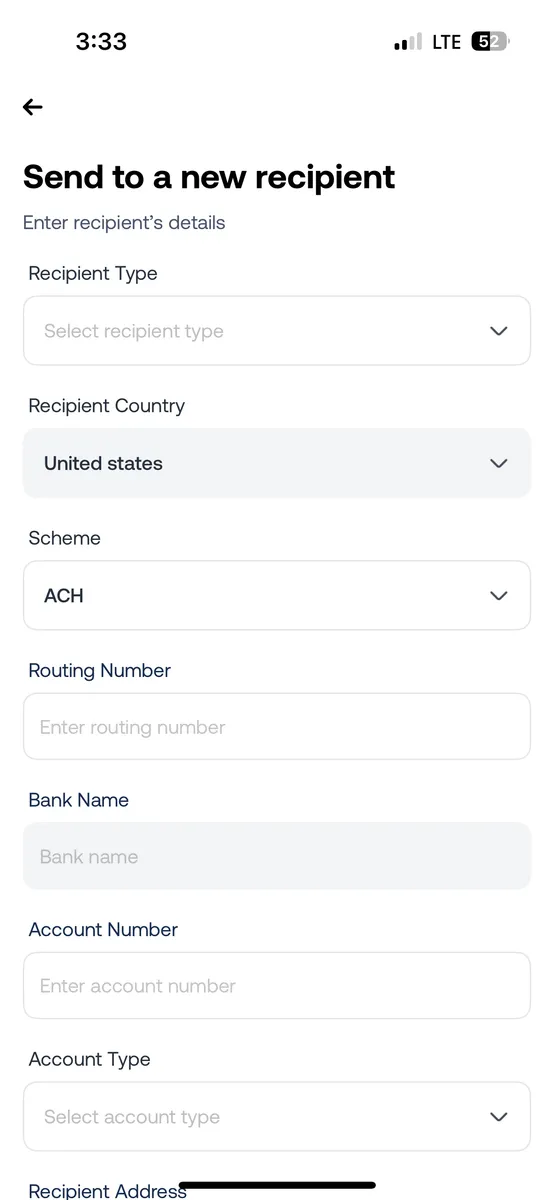
2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

676ec442190ed0b08ba00d42 676ebd4d245072006253a99c send us dollars grey 4

3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

676ec442190ed0b08ba00d3f 676ec3b94c9821344d4d5d63 IMG 0368

4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

676ec442190ed0b08ba00d79 676ec3c426d44aa2a43d7fc8 IMG 0370

5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

676ec442190ed0b08ba00d45 676ec3d1138ab1eb14571c89 IMG 0371

‍

‍You may also like: How to convert and send USD to TZS online

Key tips for converting and sending USD to UGX

  1. Monitor exchange rates: Keep an eye on the exchange rate to convert your funds at the best possible time.
  2. Double-check recipient details: Ensure the accuracy of bank account or mobile wallet information to avoid delays.
  3. Use Grey’s multi-currency wallets: Store USD and UGX in your Grey account to avoid frequent conversions and save on fees.
  4. Track your transactions: Grey offers a transaction history feature to easily track conversions and transfers.

Why Grey is the best option for USD to UGX transfers

Grey stands out as a reliable and cost-effective platform for handling international payments. Here’s why it’s a top choice:

  • Speed: Transfers are processed faster than most traditional banks, so your recipients get their money quickly.
  • Savings: With low fees and competitive exchange rates, you keep more of your hard-earned money.
  • Flexibility: Manage multiple currencies from one account and send funds anytime, anywhere.
  • Security: Grey prioritises secure transactions, giving you peace of mind.

Take control of your cross-border payments with Grey

Converting and sending USD to Ugandan Shilling has never been easier. Whether supporting family, paying vendors, or managing personal finances, Grey’s seamless platform saves you time, money, and effort.

Ready to simplify your financial transactions? Sign up with Grey today and enjoy a hassle-free way to convert and send USD to UGX online.

‍

How South African freelancers can receive payments from the US, UK & EU clients

•

•

2 min read

South Africa is home to a growing community of freelancers, remote workers, and digital entrepreneurs offering services to clients across the US, UK, and Europe.

However, while working with international clients can be highly rewarding, receiving payments remains a major challenge. High transfer fees, poor exchange rates, and long processing times often reduce earnings and cause unnecessary delays.

With a Grey account, freelancers in South Africa can receive payments in USD, GBP, and EUR, convert at competitive rates, and withdraw directly to their South African bank accounts.

Also read: How freelancers in Morocco can receive payments from US, UK & EU clients

How to open a USD, GBP or EUR account with Grey

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

How South African freelancers can receive payments from the US, UK & EU clients
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location. In this case, it’s South Africa.
How South African freelancers can receive payments from the US, UK & EU clients
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
How South African freelancers can receive payments from the US, UK & EU clients
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
How South African freelancers can receive payments from the US, UK & EU clients
  • Once you’re set up, you’re ready for identity verification.

2. Verify your identity for secure access

Here’s what you’ll need to provide:

  • Government-issued ID: A valid passport or national ID card is required. Make sure it’s clear and up-to-date.
  • Proof of address: A recent utility bill or bank statement will verify your location. Grey uses this document to confirm your residency.
  • Submit your documents for review: Once uploaded, Grey will review your documents, a process that typically takes a few business days. Clear and accurate documentation speeds up approval.

3. Access your global bank accounts

Once your identity is verified, log in to your Grey account.

  • Navigate to the “Accounts” section and select “Create Account.”
  • Choose the currency (USD, GBP or EUR).
  • Your global bank account details, including your account number and routing number, will be generated instantly.

Also read: How to receive payments from Guru in South Africa in 2025

How to receive payments from US, UK & EU clients

Once you’ve created your Grey account, receiving payments is easy. Here’s how:

  • Log in to your Grey account via the app or website to securely access your currency balances.
  • Navigate to "Home" and select your preferred currency account (e.g., USD, EUR, GBP).
  • Share your account details (IBAN, sort code, or account number) with international clients, employers, or payment platforms like PayPal and Upwork.
  • The funds will be deposited into the Grey account.

Also read: How to receive Amazon payments in South Africa

Why Grey is the best online global bank for South African freelancers

Here are major reasons Grey stands out as the best online bank for freelancers in South Africa:

  • No hidden fees – Transparent pricing so you keep more of your earnings.
  • Hold multiple currencies – Manage your finances in USD, GBP, or EUR without forced conversions.
  • Fast international transfers – Receive and send money globally without delays.
  • Global access – Manage your money anytime, anywhere with Grey.
  • Direct withdrawals – Transfer funds seamlessly to your South African bank account.

Simplify banking across borders with Grey

Receiving international payments in South Africa doesn’t have to be complicated. With Grey, you can open a foreign bank account and accept payments seamlessly.

Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

‍

Why is international payment so complex for migrant workers?

•

•

2 min read

Migrant workers play a vital role in the global economy, working for companies worldwide and supporting their families across borders. But the simple act of transferring money across borders is anything but straightforward. Outdated financial systems, hidden fees, and frustrating delays turn a lifeline into a source of stress. This article uncovers the challenges migrant workers face with international payments and introduces Grey — a game-changing solution that makes sending money home faster, easier, and more affordable.

The challenges of international payments for migrant workers

For migrant workers, navigating international payments is crucial, whether it’s sending money home or getting paid by companies abroad. Here’s a look at the key challenges they face.

  • High costs eat into earnings: Traditional banks and many transfer services charge multiple fees, including transaction fees, intermediary charges, and currency conversion markups.
  • Unpredictable delays: Traditional systems often involve lengthy processing times. Transfers can take days or weeks to reach their destination, causing stress and uncertainty, especially during emergencies.
  • Lack of transparency: Hidden fees and unclear exchange rates are common issues. Workers are often surprised by the final amount received or sent, as traditional systems rarely offer upfront transparency about costs.
  • Complex banking requirements: Not all workers have access to traditional bank accounts, and even when they do, opening and maintaining one in a foreign country can be daunting. Regulations, documentation requirements, and language barriers add to the complexity.

Why Grey is the ideal solution for migrant workers

Grey helps migrants and digital nomads navigate cross-border more easily. Grey is:

  • Accessible: Open an account from anywhere without the hassle of traditional banks.
  • Affordable: Keep more of your money with low fees and competitive exchange rates.
  • Reliable: Ensure your payments arrive on time, every time.

Also read: How can I sign up on Grey?

International payments: Key benefits of using Grey as a migrant worker

1. Free and quick account creation

With Grey, users can open a free account online in minutes. Grey provides   USD, GBP, and EUR bank accounts to enable migrants to easily get paid or send money globally.

2. Affordable cross-border transfers

Grey offers highly competitive fees for international transactions. Unlike traditional banks, which add layers of hidden costs, Grey ensures you know exactly how much you’re paying upfront. This transparency allows you to plan your finances without surprises.

3. Fast and reliable transfers

Say goodbye to long waits. Grey processes transactions quickly. For workers who depend on timely payments, Grey’s reliability is invaluable.

4. Multi-currency wallets

Grey’s platform supports multi-currency wallets, allowing users to hold and manage funds in USD, GBP, and EUR. This feature is particularly useful for remote workers with clients in different countries, enabling them to receive payments in various currencies without worrying about poor exchange rates.

You can also send money using USD Coin (USDC) to over 40 countries. Designed for freelancers, digital nomads, and remote professionals, this feature simplifies international payments, ensuring secure and seamless transactions.

5. Seamless currency conversion

Currency conversion is often a costly challenge for migrant workers sending money home. Grey offers fair exchange rates, allowing users to convert money at competitive rates directly within the app.

Check out Grey’s live currency converter tool.

6. User-friendly platform

Grey’s app is intuitive and straightforward, catering to users of all skill levels. From checking balances to initiating transfers, every feature is designed with simplicity in mind, ensuring workers can confidently manage their finances.

With Grey, migrants, travellers, and digital nomads can stop worrying about high costs, delays, and hidden fees and instead focus on what truly matters — supporting their families, growing their businesses, and enjoying  peace of mind.

International payments can be easy for migrant workers

As the global workforce continues to expand, the need for accessible and efficient payment solutions has never been more pressing. Grey leads the way in empowering migrant workers with the tools they need to thrive in a connected world.

By simplifying international payments, offering competitive rates, and ensuring transparency, Grey is more than a financial platform — it’s a trusted partner for anyone navigating the complexities of cross-border work and remittances.

Sign up with Grey today and take control of your international payments. Your hard-earned money deserves to travel as far as you do.

‍

How to convert and send USD to Ghanaian Cedi online (GHS)

•

•

2 min read

Navigating international transactions doesn’t have to be overwhelming. Whether you’re supporting loved ones in Ghana, managing personal finances, or handling business payments, converting USD to Ghanaian Cedi (GHS) online is now fast, convenient, and cost-effective with Grey.

This guide will show you how to convert and send USD to GHS effortlessly while making the most of your transactions.

Why choose Grey for USD to GHS conversions?

Grey is a digital banking solution designed to simplify cross-border transactions. Here’s why Grey is the smart choice for converting and transferring USD to GHS (GH₵):

  • Transparent exchange rates: Enjoy real-time rates without any hidden charges.
  • Affordable fees: Keep more of your money with Grey’s low transaction costs.
  • Rapid transfers: Getting funds to your recipient quickly saves time and stress.
  • Easy-to-use platform: Whether on the app or website, Grey ensures a smooth user experience.

Steps to convert and send USD to GHS with Grey

1. Open your Grey account

Start by signing up for a free Grey account on the website or app (available on iOS and Android). Setting up your account is straightforward:

  • Enter your personal details.
  • Complete identity verification by uploading the required documents.
  • Access all your foreign and local currencies from a single app (USD, EUR, GH₵, and GBP)

2. Add funds to your US bank account

Add funds to your Grey USD wallet through:

  • Bank transfers: Link your bank account for seamless deposits.
  • Freelancing income: Get paid directly into your USD wallet by clients or platforms like Fiverr, Upwork, etc.
  • International wire transfers: Receive payments from businesses or individuals abroad.

3. Exchange US dollars (USD) to Ghanaian cedis (GHS)

When your wallet is funded, follow these steps to convert your money:

  1. Log in to your Grey account using the app or website.
  2. Go to the “Convert” section in your dashboard.
  3. Select USD as the source currency and GHS as the target currency.
  4. Input the amount you want to convert and confirm.
  5. The exchanged GHS will be instantly available in your wallet.

4. Transfer GHS to your recipient

With your converted funds ready, sending GHS to a recipient in Ghana is easy:

  1. Click on “Send Money” in your dashboard.
  2. Enter your recipient’s details, such as their Ghanaian bank account or mobile wallet.
  3. Specify the amount in GHS.
  4. Review the transfer details and confirm the transaction.
  5. Your recipient will typically receive the funds within minutes.

Also read: How to convert and send USD with Grey [will link it once it’s published]

Tips for a smooth transfer experience

  • Monitor rates: Use Grey’s real-time currency converter to exchange at the best rates.
  • Verify details: Double-check recipient information to avoid errors or delays.
  • Store currencies: Use Grey’s foreign bank accounts to hold multiple currencies (EUR, USD, GBP) and reduce frequent exchange costs.
  • Stay organised: Keep track of your transaction history within the app for easy reference.

Why Grey stands out for international payments

Grey offers a reliable way to handle personal or business international transactions. Key benefits include:

  • Faster processing: Transfers are completed in record time.
  • Lower costs: Enjoy competitive fees and save more on conversions.
  • Multi-currency convenience: Manage multiple currencies and bank accounts effortlessly in one app.
  • Enhanced security: Grey prioritises the safety of every transaction.

Start sending money to Ghana with Grey

Converting and sending USD to Ghanaian cedis has never been this simple. Grey provides the tools you need for efficient and affordable cross-border payments.

Sign up with Grey today and make your international transactions faster, cheaper, and hassle-free.

How international banking works for freelancers and independent contractors

•

•

2 min read

Getting paid is the primary goal for any freelancer, regardless of the platform they use or the country they come from. The Platform you use to get your gigs, your client’s home country, and the available payment method in your country will determine how you will receive your payments. USD, EUR, and GBP are among the currencies freelancers and independent contractors prefer to receive their payments.

Freelancers and independent contractors use international banking to receive, send, and convert funds. Freelancing platforms like Upwork, Fiverr, and Guru allow freelancers and independent contractors to accept payments directly from their clients, so having basic knowledge of how international banking works is a must for them.

Below is how international banking works for freelancers and independent contractors

Wire transfer

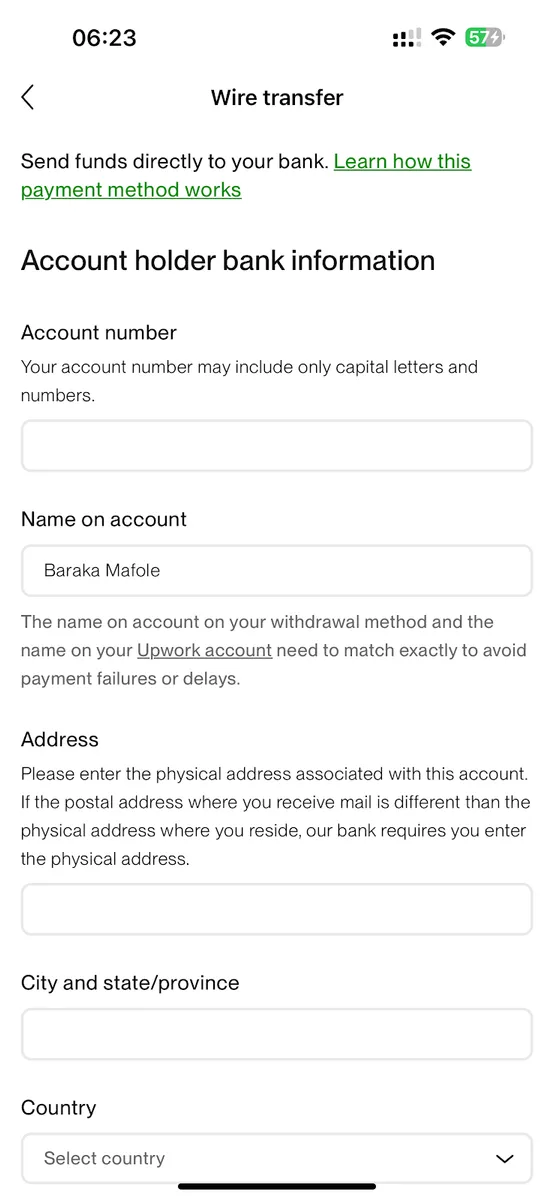
This method allows freelancers and remote workers to receive payment directly to their local bank accounts. For a freelancing platform like Upwork, all you need to do is choose the wire transfer method as a method you will likely receive your payments and insert your local bank account details there.

Payments via wire transfer methods are expensive and take a long time to process; in particular, you might be charged up to 50 USD as a service fee and wait up to 7 days for your payment to arrive. Some of the details you might asked by your clients or freelancing platforms when requesting payment using this method are

  • Your account number
  • SWIFT/BIC or routing code
  • Name of your bank
  • Address of your bank
  • IBAN
  • City
__wf_reserved_inherit

Direct to US banks

According to Freelancers in America (FIA), over 57.3 million freelancers in the USA contribute more than 1.4 trillion USD to their national economy. Due to the high number of freelancers and independent contractors in the USA, many freelancing platforms prefer to pay US freelancers directly.

This method is cheaper and faster than other methods used in freelancing platforms. Freelancers in the USA can easily use this method directly through their home country’s bank account.Non-US freelancers can take advantage of third-party platforms that will enable them to use this method.

Below are two methods which freelancers and independent contractors can use to get a foreign US bank account

1.Grey

Grey helps freelancers and independent contractors create free USD, EUR, and GBP accounts, which they can use to send, receive, and convert foreign currencies.Grey also helps freelancers and digital nomads create automatic invoices and send them to clients anywhere in the world.

Many freelancers and digital nomads use Grey virtual dollar cards, which they can use to pay for online subscriptions, such as Adobe and Canva, and shop online anywhere in the world.

Lastly, Grey has multiple payout methods, such as through bank accounts, mobile money, and crypto (USDC), which are essential to ensure you receive your cash instantly regardless of the country you are in.

Also, read how non-US citizens can open a US bank account online.

2.PayPal

This is the most common means freelancers and independent contractors use to receive their clients’ payments. PayPal is a digital payment system which lets individuals and businesses to make and receive payments online. It is widely accepted by merchants and online retailers, making it a popular choice for online transactions. Almost all freelancing platforms allow freelancers to receive payments through PayPal, and many clients prefer to use this method to pay their freelancers.

Paypal might be a difficult method to use for freelancers living in developing countries, as it doesn’t operate in many of them. With Grey, you can get a free US, UK, or Euro bank account, link to Paypal, receive payments, and withdraw funds from Paypal into your local currency.

Read more: How to receive payments from PayPal

3.Payoneer

This is also the oldest and most common method freelancers and independent clients use to receive payment from their clients. All you need to do is sign up with Payoneer and get your Payoneer account, which you can use to receive payments.

After receiving payments, you can withdraw from Payoneer to your international bank accounts.

STEP 1 - Create a foreign account on Grey (US, UK, EUR).

STEP 2 - Add your foreign account to Payoneer and withdraw.

STEP 3 - You can leave your funds in your Grey balance or convert them to any of our supported currencies.

4.Cryptocurrency

Cryptocurrency technologies have revolutionised the financial sector by reducing transactional fees and making transactions faster. Many international clients, especially those from countries with complex financial restrictions, prefer to pay their freelancers using cryptocurrencies. Some freelancing platforms also allow cryptocurrency payouts.

Having a crypto wallet is the only way freelancers and independent contractors can receive crypto payments. However, you can receive foreign currencies (USD, GBP, and EUR) and convert them to USDC with Grey. You can send USDC to a compatible crypto wallet or exchange it for your local currency. Grey supports networks like Solana and Binance Smart Chain, adding security and convenience to the transaction process.

Also read: How to receive and convert foreign currencies to USDC

Freelancers and independent contractors worldwide use Grey to receive payment from their clients directly and via freelancing platforms. Be part of 1M+ freelancers who use Grey to receive their payments. Get your free foreign bank accounts now.

‍

Arrow (up)

Back to top