


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/usdc-to-usd#article","headline":"USDC to USD: How to convert your stablecoin to cash","description":"Converting USDC to USD takes a few steps on a crypto exchange or platform. Learn how to convert, cash out, and move your USDC to a bank account. Start now.","inLanguage":"en","url":"https://grey.co/blog/usdc-to-usd","mainEntityOfPage":{"@id":"https://grey.co/blog/usdc-to-usd#webpage"},"datePublished":"2026-07-10T12:28:46.196Z","dateModified":"2026-08-05T09:29:39.107Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/usdc-to-usd#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a50e551c36fc7f011cedd22_USDC%20to%20USD%20How%20to%20Convert%20Your%20Stablecoin%20to%20Cash-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a50e551c36fc7f011cedd22_USDC%20to%20USD%20How%20to%20Convert%20Your%20Stablecoin%20to%20Cash-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/usdc-to-usd#webpage","url":"https://grey.co/blog/usdc-to-usd","name":"USDC to USD: How to Convert Your Stablecoin to Cash | Grey","description":"Converting USDC to USD takes a few steps on a crypto exchange or platform. Learn how to convert, cash out, and move your USDC to a bank account. Start now.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/usdc-to-usd#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/usdc-to-usd#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/usdc-to-usd#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"USDC to USD: How to convert your stablecoin to cash","item":"https://grey.co/blog/usdc-to-usd"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/usdc-to-usd#faq","mainEntity":[{"@type":"Question","name":"Does USDC always stay at exactly $1?","acceptedAnswer":{"@type":"Answer","text":"USDC is designed to maintain a 1:1 value with the US dollar, but its market price can fluctuate slightly due to supply, demand, or market conditions. These movements are usually minimal, and the stablecoin is intended to return close to its one-dollar peg."}},{"@type":"Question","name":"Do you have to pay tax when converting USDC to USD?","acceptedAnswer":{"@type":"Answer","text":"Tax treatment depends on your country of residence. In some jurisdictions, converting USDC to USD may be a taxable event, while in others it may not. If you're unsure, consult your local tax authority or a qualified tax adviser before converting."}},{"@type":"Question","name":"Can you cash out USDC without using a crypto exchange?","acceptedAnswer":{"@type":"Answer","text":"Yes, in some cases. Certain payment providers, crypto wallets, and over-the-counter (OTC) services allow you to convert or redeem USDC without trading through a traditional cryptocurrency exchange. Availability depends on your location and the services supported."}},{"@type":"Question","name":"Is there a minimum amount required to convert USDC to USD?","acceptedAnswer":{"@type":"Answer","text":"Most platforms set a minimum conversion or withdrawal amount, but the limit varies by provider. Before initiating a transaction, check the platform's conversion rules and bank withdrawal requirements to ensure your balance meets the minimum threshold."}},{"@type":"Question","name":"Is converting USDC to USD safe?","acceptedAnswer":{"@type":"Answer","text":"It can be, provided you use a reputable and regulated platform, enable two-factor authentication, and verify all wallet and banking details before confirming a transaction. Avoid sending funds to unknown addresses or using unverified services offering unrealistic exchange rates."}},{"@type":"Question","name":"Can you receive USD in your Grey account?","acceptedAnswer":{"@type":"Answer","text":"Yes. Grey provides foreign account details that allow you to receive USD from international clients. After receiving the funds, you can convert them to your local currency at competitive exchange rates and low fees before transferring the money to your local bank account."}},{"@type":"Question","name":"Can you convert only part of your USDC balance?","acceptedAnswer":{"@type":"Answer","text":"Yes. You don't have to convert your entire balance unless the platform requires it. Most exchanges and payment providers let you choose the exact amount of USDC you want to convert, giving you greater flexibility over when and how much you cash out."}}]}] </script>

USDC to USD: How to convert your stablecoin to cash

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Converting USDC to USD is one of the most common ways to turn your digital assets into spendable cash. Whether you've been paid in USDC, received crypto from a client, or hold stablecoins as part of your portfolio, knowing how to convert them safely and efficiently helps you access your money when you need it. The process is straightforward, but choosing the right platform can affect how much you pay in fees and how quickly you receive your funds.

To convert USDC to USD, you'll need a crypto exchange or platform that supports USDC. Once your USDC is in your account, you can sell or swap it for USD and withdraw the proceeds to your linked bank account. Depending on the platform, the withdrawal process typically takes between one and three business days, while conversion fees generally range from 0% to around 1.5% of the transaction.

This guide explains how to convert USDC to USD step by step, the fees and timelines you should expect, and the key factors to consider when choosing a reliable platform for your conversion.

Also read: USDC vs. other stablecoins: what's best for global transactions?

What is USDC and how does it work?

USDC (USD Coin) is a stablecoin. It'sa type of cryptocurrency designed to maintain a stable value by being pegged to the US dollar. Unlike cryptocurrencies such as Bitcoin or Ethereum, which can experience significant price swings, one USDC is equal to one US dollar. It's issued by Circle and is backed by reserves of cash and cash-equivalent assets, making it one of the most widely used dollar-backed stablecoins.

USDC maintains its 1:1 peg through a reserve system. When a new USDC is issued, an equivalent value in US dollars or highly liquid assets is held in reserve. Likewise, when USDC is redeemed for cash, the tokens are removed from circulation. This mint-and-redeem process helps keep its value close to one US dollar, while regular reserve attestations provide additional transparency.

Many individuals and businesses hold USDC because it offers the stability of the US dollar while retaining the speed and flexibility of blockchain technology. It's commonly used for international payments, cross-border transfers, online trading, and protecting funds from the price volatility associated with other cryptocurrencies.

How to convert USDC to USD

Converting USDC to USD is a straightforward process if you use a platform that supports stablecoin trading and bank withdrawals. Before you begin, make sure your account is verified, and your bank account is linked.

  1. Choose a platform and sign in: Select a cryptocurrency exchange or payment platform that supports USDC and USD conversions. Create an account if you're new, complete any required identity verification, and log in securely before starting the transaction.
  2. Deposit your USDC: Transfer the amount of USDC you want to convert into your platform account. Double-check the blockchain network and wallet address before sending your funds to avoid irreversible transfer mistakes.
  3. Sell your USDC for USD: Navigate to the trading or conversion section, choose the USDC-to-USD option, review the exchange rate and fees, then confirm the transaction once you're satisfied with the details.
  4. Withdraw the USD to your bank account: After the conversion is complete, request a withdrawal to your linked bank account. Review the withdrawal fee, processing time, and banking details before confirming the transfer.

Also read: Understanding USDC and how it enables safe global payments

How to cash out USDC to your bank account

After converting your USDC to USD, the final step is withdrawing the funds to your bank account.

  • Choose your withdrawal method: Most platforms let you withdraw via ACH or bank wire. ACH transfers are typically cheaper but may take one to three business days, while wire transfers are often faster but usually come with higher fees.
  • Link and verify your bank account: Before withdrawing, you'll need to connect a bank account in your name. Many platforms require identity verification and may ask you to confirm your bank details for security and regulatory compliance.
  • **Check the minimum withdrawal amount:**Some platforms set a minimum USD withdrawal limit. Review the withdrawal page to ensure your balance meets the requirement before submitting your request.
  • Review fees and processing times: Withdrawal fees and timelines differ by provider and payment method. Always check the estimated delivery time and total cost before confirming the transaction to avoid surprises.
  • Confirm the withdrawal and monitor its status: Once you've reviewed the details, submit the withdrawal request. Most platforms provide a transaction status or reference number so you can track the transfer until the funds reach your bank account.

How much does it cost to withdraw USDC to a bank account?

Converting USDC to cash can involve several charges depending on the platform and payment method you choose. Understanding each fee helps you estimate your total cost and identify opportunities to reduce unnecessary expenses before completing your withdrawal.

What it covers Typical cost When it's charged How to reduce it
Platform fee Converting USDC into USD 0%–1.5% of the transaction When you sell or convert USDC Compare conversion rates and fees before trading
Network gas fee Processing the USDC transfer on the blockchain Varies by blockchain network and congestion When transferring USDC to or from a platform Use a lower-cost supported network where available
Bank withdrawal fees Sending USD from the platform to your bank account Free to around $30, depending on the method When withdrawing USD Choose lower-cost withdrawal options, such as ACH where available
Bank charges Fees charged by your receiving or intermediary bank Varies by bank After the transfer is processed Choose providers that use local payment rails and offer transparent fees.

How long does it take to convert USDC to USD?

The time it takes to convert USDC to USD depends on how want to withdraw and where you're sending the funds. Converting USDC to USD within a cryptocurrency exchange or wallet is usually completed instantly or within a few minutes, provided there's enough market liquidity. If you choose an instant cash-out option, such as a supported debit card payout or instant ACH transfer, you could receive your money in as little as 30 minutes, although these services may attract additional fees.

The longest part of the process is typically transferring your USD to a bank account. Standard ACH transfers to US banks generally take one to three business days, while international wire transfers sent through the SWIFT network can take between two and five business days, depending on the receiving bank and country.

Processing times can also be affected by identity verification, bank holidays, compliance checks, blockchain network congestion, and your chosen payment method. Checking these factors before you start can help you avoid delays and receive your funds as quickly as possible.

Also read: How USDC is revolutionising international money transfers

Receiving USD payments internationally with Grey

If you earn in USDC or USD as a freelancer, remote worker, or online business owner, getting your money into your local bank account shouldn't be complicated. While many clients prefer paying in US dollars, accessing those funds locally can involve multiple platforms, high fees, or lengthy processing times. Having reliable foreign account details simplifies the payment process and gives clients a familiar way to pay you.

With Grey, you receive dedicated foreign account details, including US accounts, that you can share with international clients as your payment destination. Clients can send USD directly to these account details just as they would with a local bank account. Once the funds arrive, you can convert your USD to your local currency within Grey and transfer the money to your local bank account when you're ready.

This creates a practical bridge between international earnings and everyday banking. Whether your income comes from freelance projects, remote employment, or clients who prefer paying in USD, Grey helps you receive payments more easily, manage your foreign currency, and access your money without the complexity often associated with cross-border payments.

Frequently asked questions

1. Does USDC always stay at exactly $1?

USDC is designed to maintain a 1:1 value with the US dollar, but its market price can fluctuate slightly due to supply, demand, or market conditions. These movements are usually minimal, and the stablecoin is intended to return close to its one-dollar peg.

2. Do you have to pay tax when converting USDC to USD?

Tax treatment depends on your country of residence. In some jurisdictions, converting USDC to USD may be a taxable event, while in others it may not. If you're unsure, consult your local tax authority or a qualified tax adviser before converting.

3. Can you cash out USDC without using a crypto exchange?

Yes, in some cases. Certain payment providers, crypto wallets, and over-the-counter (OTC) services allow you to convert or redeem USDC without trading through a traditional cryptocurrency exchange. Availability depends on your location and the services supported.

4. Is there a minimum amount required to convert USDC to USD?

Most platforms set a minimum conversion or withdrawal amount, but the limit varies by provider. Before initiating a transaction, check the platform's conversion rules and bank withdrawal requirements to ensure your balance meets the minimum threshold.

5. Is converting USDC to USD safe?

It can be, provided you use a reputable and regulated platform, enable two-factor authentication, and verify all wallet and banking details before confirming a transaction. Avoid sending funds to unknown addresses or using unverified services offering unrealistic exchange rates.

6. Can you receive USD in your Grey account?

Yes. Grey provides foreign account details that allow you to receive USD from international clients. After receiving the funds, you can convert them to your local currency at competitive exchange rates and low fees before transferring the money to your local bank account.

7. Can you convert only part of your USDC balance?

Yes. You don't have to convert your entire balance unless the platform requires it. Most exchanges and payment providers let you choose the exact amount of USDC you want to convert, giving you greater flexibility over when and how much you cash out.

Holding USDC is a smart way to protect the value of your funds while enjoying the flexibility of digital payments. When it's time to receive or manage USD internationally, Grey makes the process simple and seamless. Open a Grey account or download the Grey app today to start receiving USD payments with ease.

Last updated:

October 9, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Grey Business vs Grey personal banking

•

•

2 min read

“Should I be using Grey Business, or is my personal Grey account enough?”

It’s a common question, especially once your income starts growing.

At the beginning, everything feels simple. You get paid and you withdraw your money easily. But as your work evolves, whether that’s taking on more clients, earning from multiple platforms, or starting a company, the way you manage money needs to evolve too.

Grey offers two account types for this exact reason: Grey Personal and Grey Business. They are not better or worse than each other. They are built for different stages of your earning process.

This guide breaks down the differences, including fees, features, and when to switch, so you can choose the right setup without second-guessing.

‍Also read: Receiving foreign income as a solo founder

What is a Grey personal account?

A Grey personal account is designed for individuals who receive and manage international payments.

If you are a freelancer, remote worker, or creator earning from global clients or platforms, this is the account you are expected to use.

With a personal account, you can open USD, GBP, and EUR balances with real banking details. This allows clients to pay you as if they were making a local transfer in their own country. Instead of receiving an expensive international wire, you receive money through local rails like ACH, SEPA, and FPS.

Once the money arrives, you can hold it in foreign currency, convert it when the rate works for you, or withdraw it to your local bank account. You can also spend directly using your Grey virtual card without needing to manually move funds around.

The focus here is simplicity. You are managing your own income, and the account is designed to make that as flexible as possible.

What fees does Grey Personal charge?

Understanding fees is where most people get confused, so here’s how it actually works.

When you receive money through ACH, SEPA, or FPS, Grey charges a 0.8% fee, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. This means larger payments become proportionally cheaper because of the cap.

Currency conversion depends on the currency pair. Some routes are free, while others range from 0.5% to 1%. For certain major pairs, the fee is capped at $6. The important detail is that Grey shows the rate before you confirm, so there are no hidden charges after the fact.

Withdrawals vary depending on the country, but for major currencies like EUR and GBP, the fee is typically 0.5%, with a minimum and maximum cap. Other corridors may use fixed fees instead.

For less common deposit methods like Fedwire, BACS, or CHAPS, fixed fees apply. These are generally used less often, since local rails like ACH or FPS are cheaper.

Read more: Grey charges explained: what every transaction costs

What is Grey Business?

Grey Business is designed for companies rather than individuals.

If you are running a registered business, working under a company name, or managing revenue that belongs to a business entity, this is the account structure you need.

Unlike a personal account, a Grey Business account is built for your company. This means you can receive payments on behalf of the business, manage funds at a company level, and keep financial records properly organised for accounting and compliance.

The functionality goes beyond receiving payments. Grey Business allows you to manage team access, assign roles, and give multiple people control over finances without sharing a single login.

You can also pay contractors globally, send payments in local currencies, and handle bulk payouts by uploading recipient details. This becomes important as soon as you are working with a team or scaling operations.

The goal of Grey Business is not just to receive money, but to structure how your business handles it.

What fees does Grey Business charge?

Grey Business follows the same core pricing model as personal accounts.

Receiving payments still comes with the 0.8% fee capped at $10. Conversion fees follow the same tiered structure, and withdrawals depend on the payout country.

The difference is not in lower fees, but in what the account enables.

With Grey Business, you are paying for structure, team management, and the ability to operate at scale without mixing personal and company finances.

Grey Personal vs Grey Business: what is the difference?

The main difference comes down to ownership.

A personal account is for money that belongs to you as an individual. A business account is for money that belongs to a company.

Everything else builds from that.

Grey Personal is simpler, quicker to set up, and designed for individuals managing their own income. Grey Business requires verification of a registered company but provides tools to manage payments, teams, and operations effectively.

If you are working alone and getting paid for your own work, a personal account is enough. If you are invoicing as a company, hiring people, or managing shared finances, you need a business account.

‍Also read: Can non-residents open a US bank account online in 2026?

When should you use Grey for personal use?

You should use a personal account if you are earning in your own name.

This includes freelancers, remote employees, and creators earning from platforms like YouTube, TikTok, or Upwork. At this stage, your income is still personal, even if it comes from multiple sources.

A personal account keeps things simple.

When should you use Grey Business?

You should use Grey Business when your income is no longer just yours.

If you have registered a company, invoice under a business name, or manage revenue that belongs to a business entity, a personal account is no longer the right structure.

This is especially important if you are paying contractors, working with a team, or preparing financial records for accounting and tax purposes.

Can you have both Grey for personal use and Grey Business?

Yes, and in many cases, this is the best setup.

If you run a company but also earn income personally, keeping both accounts separate helps avoid confusion. Your business transactions stay within the business account, while your personal income remains separate.

This makes accounting cleaner and reduces the risk of mixing funds.

Grey for personal use vs Grey Business: key differences

Feature Grey Personal Grey Business
Who it’s for Individuals (freelancers, creators, remote workers) Registered companies, startups, agencies
Account ownership Personal use Business entity
Currencies supported USD, GBP, EUR, USDC USD, USDC (business-focused)
Receiving payments Yes (ACH, SEPA, FPS) Yes (for business transactions)
Team access No Yes (multi-user access with roles)
Bulk payouts No Yes (CSV uploads supported)
Virtual cards Yes (for personal use) Yes (multiple cards for teams, tools, ads)
Best use case Getting paid individually Managing company finances and scaling operations
Setup process Fast (ID verification) More detailed (business verification required)

So, which Grey account should you choose?

Most people overthink this decision, but it comes down to one simple question:

Who does the money belong to?

If you’re earning as an individual, whether that’s freelancing, remote work, or content creation, a Grey Personal account is the right fit. It keeps things simple and flexible while giving you full access to international payments.

If you’re operating as a registered business, invoicing clients under a company name, or managing team payments, Grey Business is the structure you need. It helps you separate finances properly and handle growth without creating confusion later.

If you’re in between, which is common, you can start with a personal account and move to business when your setup requires it. Many users also keep both, using one for personal income and the other for company operations.

The goal isn’t to pick the most advanced option. It’s to choose the one that fits how you earn today and won’t slow you down as you grow.

Getting started with Grey

Opening a Grey Personal account takes just a few minutes. You can sign up in under 5 minutes, and once your identity is verified, you can usually start receiving payments the same day.

Opening Grey Business takes a bit longer because it involves business verification. You’ll need to submit your company registration and ownership details, and approval typically takes 1 to 3 business days, depending on the documents provided. This ensures your account is set up correctly from the start.

Frequently asked questions

What is the difference between Grey for persona use and Grey Business?

Grey Personal is for individuals receiving and managing their own income, such as freelancers, creators, and remote workers. Grey Business is for registered companies that need to manage business revenue, pay contractors, and give team members access to finances.

The main difference is ownership. Personal accounts are for your money. Business accounts are for company funds.

Can I use a Grey Personal account for business payments?

You can use a personal account while you are freelancing under your own name. However, once you register a company or start invoicing under a business name, it is better to switch to Grey Business.

Using a personal account for business transactions can create confusion with accounting, taxes, and financial tracking.

Does Grey Business have different fees from Grey Personal?

Grey Business follows the same core pricing structure as personal accounts. Receiving fees are typically 0.8% with a cap, and conversion fees depend on the currency pair.

The main difference is not pricing, but functionality. Grey Business adds tools for team access, bulk payments, and structured financial management.

Can I have both a Grey Personal and Grey Business account?

Yes. Many users have both accounts.

This is useful if you have personal income, such as freelance work or creator earnings, and also run a registered business. Keeping them separate makes accounting cleaner and easier to manage.

When should I switch from Grey Personal to Grey Business?

You should consider switching when your income becomes business revenue instead of personal income.

This usually happens when you register a company, start invoicing clients as a business, hire contractors, or need proper financial records for tax and reporting purposes.

What documents are required to open a Grey Business account?

To open a Grey Business account, you will need to provide company registration documents, ownership details, and verification information about the business.

The process is more detailed than a personal account because it involves verifying a legal entity.

Is Grey Personal enough for freelancers and creators?

Yes. For most freelancers, remote workers, and creators, Grey Personal is more than enough.

It allows you to receive international payments, hold foreign currency, convert when needed, and withdraw locally without needing business-level setup.

Can I receive USD, GBP, and EUR with both accounts?

Yes. Both Grey Personal and Grey Business support multi-currency functionality.

Personal accounts focus on individual income, while business accounts structure those same capabilities for company use.

Which Grey account is better?

Neither is better. They are designed for different use cases.

Grey Personal is better for individuals managing their own income. Grey Business is better for companies managing business finances and scaling operations.

Ready to get started?

Open your Grey Personal account to start receiving international payments as an individual, or set up Grey Business if you’re managing company finances and need a more structured setup.
What is a domiciliary account? How it works in Nigeria and better alternatives

•

•

2 min read

For a long time, a domiciliary account was the go-to answer for Nigerians who needed to hold or receive foreign currency. If you had reasons to manage USD, GBP, or EUR, you would need to visit a Nigerian bank and complete the rigorous paperwork to open a domiciliary account at a local bank. Despite the transaction delays and restricted access to foreign currency, it seemed like the best thing since sliced bread. Dom accounts were all we had, and we had to make do with them.

Things have now changed. We have better options for managing foreign currency and many Nigerians are looking away from dom accounts. This article explores the alternatives, what each offers, and helps you pick the right one for how you earn and spend.

What is a domiciliary account?

A domiciliary account is a foreign currency account offered by Nigerian commercial banks. It lets you hold USD, GBP, or EUR without immediate conversion to naira, and receive international transfers directly into a local account.

On paper, that sounds like a reasonable way to manage international payments. In practice, the experience rarely matches the description.

Opening a dom account typically requires a visit to a physical branch, a referee who already holds an account at the bank, a utility bill, a passport photograph, and, depending on the bank, an opening deposit of $100 to $200. The process can take days or longer. If you need to start receiving international payments urgently, going the dom account route means you are standing on a long thing.

Then there are the costs. SWIFT transfers to a domiciliary account incur charges on both the sending and receiving ends. The sender's bank charges a fee, intermediary banks take their cut ($15 to $50 is common), and your own bank charges a receiving fee on top. By the time the money settles, you could be looking at $30 to $70 less than what was sent, with no clear line-item breakdown of why. Some banks also impose monthly maintenance fees, withdrawal limits (both cash and transfers), and minimum balance requirements, which add friction to every interaction.

Despite the downsides, dom accounts still make sense for certain situations. If you are receiving large, infrequent wire transfers, or you want to hold a significant USD balance long-term under the regulation and deposit protection of a licensed Nigerian bank, a dom account serves that purpose. But for freelancers, remote workers, and entrepreneurs managing regular international income, the costs and friction add up quickly. That is where the alternatives come in.

Also read: Managing foreign currency earnings as a remote worker in Nigeria

What are the alternatives to dom accounts in Nigeria?

Here are the real options, with enough detail on each to make a decision.

Virtual foreign currency accounts

This is where most Nigerians who have moved away from dom accounts have landed, and the reasons are straightforward.

Platforms like Grey give you real USD, EUR, and GBP account details, including routing numbers, account numbers, and IBANs. These work the same way as foreign bank accounts from the sender's perspective. When your client in New York pays you via ACH using your Grey USD account details, it looks like a standard domestic transfer on their end. There is no SWIFT involved, which means no intermediary bank fees eat into your payment. The funds arrive in your Grey wallet, typically the same day for ACH transfers, and you can see the balance in the app immediately.

From there, you have options. You can hold the dollars in your wallet and convert to naira when the rate works for you, rather than being forced to convert at your bank's rate on the day the transfer arrives. You can spend the dollars directly using a Grey virtual card on subscriptions, software, advertising, or anything else that charges in USD. The card works everywhere Visa is accepted and supports Apple Pay and Google Pay, so you can tap to pay at physical stores in supported regions. Or you can withdraw to your Nigerian bank account when you need naira.

Virtual foreign currency accounts open in minutes, completely online. There is no branch visit, no referee, and no minimum deposit. You see the exchange rate before you confirm a conversion, so you know exactly what you are paying. This is the biggest contrast with dom accounts, where SWIFT fees and conversion costs are often opaque until after the transaction has settled.

Grey is the platform on which this article is published, so take that into account. Other platforms in this category include Geegpay (popular with freelancers, offers USD/GBP/EUR wallets and a virtual dollar card), Eversend (multi-currency wallets across several African countries), and Cleva (US-based USD account with FinCEN registration). Each has a slightly different fee structure, supported currencies, and feature set. Compare them based on the currencies you need, the exchange rate spread, and how quickly you can access your funds.

Best for: Freelancers, remote workers, consultants, and anyone receiving regular international payments from clients or employers. This is the most direct replacement for a dom account for day-to-day use.

Also read: How Nigerian freelancers scale income beyond one platform

Wise

Wise (formerly TransferWise) is one of the most well-known names in international money movement, and many Nigerians use it. You can open a Wise account from Nigeria and get USD, GBP, and EUR account details for receiving payments. Wise's biggest selling point is that it uses the mid-market exchange rate with a transparent fee on top, rather than hiding the cost in the rate spread. For outbound transfers, this is genuinely cheaper than most alternatives.

However, Wise has significant limitations for Nigerian residents that are worth understanding before you rely on it as your primary account.

No physical card in Nigeria. The Wise multi-currency card is not available for Nigerian residents, which limits your spending options to transfers and online payments.

Service disruptions. Wise has periodically adjusted its operations in Nigeria. In 2022, it suspended USD transfers to Nigeria due to infrastructure constraints. These disruptions can be disruptive if Wise is your only receiving option.

Strict anti-crypto policy. Wise prohibits transactions related to cryptocurrency. If the platform detects a transfer to or from a crypto exchange, it may permanently close your account. For Nigerian professionals who also deal in stablecoins, this is a real risk.

Not a bank. Wise is an Electronic Money Institution, not a bank. Your funds are held in safeguarding accounts, not in a bank account in your name. This is a technical distinction, but it matters if you are considering where to hold a large balance in the long term.

Best for: One-off or occasional international transfers where you want the best exchange rate. Less suitable as a primary account for Nigerian residents who need a card, regular access, or crypto flexibility.

Payoneer

Payoneer is an option many Nigerian freelancers encounter first, largely because of its strong integration with major international platforms. Upwork, Fiverr, Amazon, and dozens of other marketplaces offer Payoneer as a payout option. If your income comes primarily through those platforms, Payoneer remains a viable option.

However, Payoneer's conversion rates are not as transparent as those of newer platforms. There are also annual fees for accounts that do not meet certain activity thresholds, relatively high transaction charges compared to fintech alternatives, and an occasionally frustrating customer support experience. The NGN withdrawal rate is not always the best either; you may find better naira conversion rates on platforms like Grey or Geegpay.

Payoneer works best when your income flows through freelancing platforms that have native Payoneer integration. For direct client payments where you control the payment method, a virtual foreign currency account is typically a better option.

Best for: Freelancers receiving payouts from Upwork, Fiverr, Amazon, and other marketplaces that integrate Payoneer natively.

Also read: Top PayPal and Payoneer alternatives for African freelancers

Stablecoins and crypto

Despite the evolving regulatory landscape around crypto in Nigeria, stablecoins remain a practical option for professionals who know how to use them. Some Nigerian freelancers and entrepreneurs receive payments in USDT or USDC because they retain their dollar value, transactions settle in minutes, and fees are low.

The challenge is not in holding stablecoins. It is in the off-ramp: converting USDC or USDT back to naira. Peer-to-peer conversions are popular but carry counterparty risk if the buyer is not trustworthy. Exchange platforms offer more structure but may have their own fees and verification requirements. Some fintech platforms, including Grey, support USDC alongside their multi-currency offering, which bridges the gap between the crypto and traditional banking worlds.

One important note for 2026: under the new Nigeria Tax Act, stablecoin payments are treated as foreign income. If you receive $1,000 in USDC on a given date, that income must be converted to naira at the CBN exchange rate on the date of receipt for tax purposes. The same self-declaration and filing obligations that apply to USD bank transfers apply to crypto income. This does not make stablecoins impractical, but it means you need to track your receipts the same way you would track any other foreign income.

Best for: Crypto-native professionals, developers in the Web3 space, and anyone whose clients or platforms pay in stablecoins. Not a replacement for a bank account or virtual foreign account for most people, but a useful complement.

How the alternatives compare

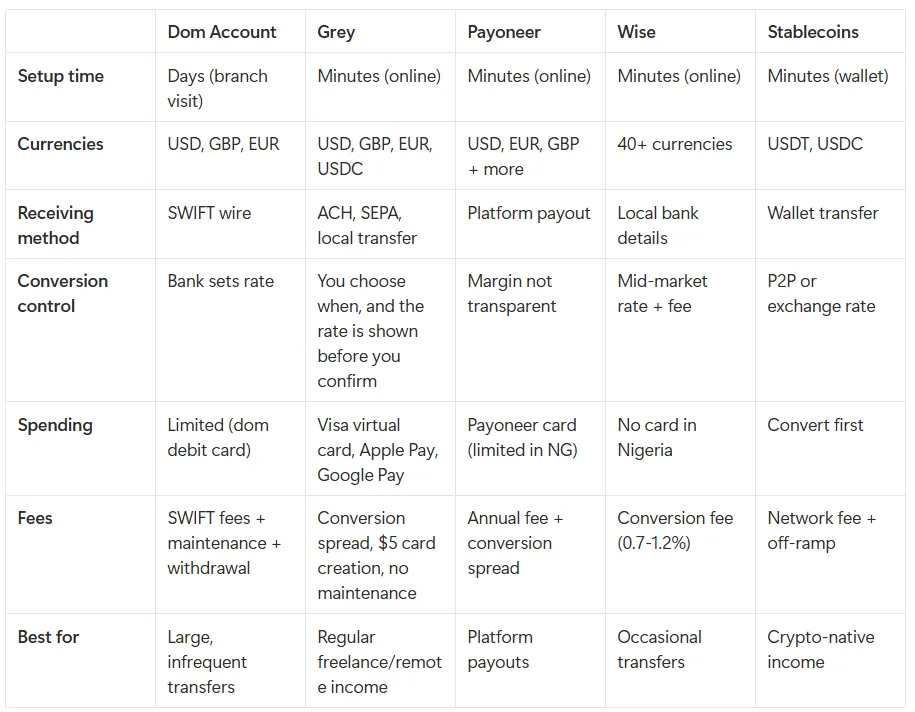
Here is a side-by-side comparison of the key factors that matter when choosing how to manage foreign currency in Nigeria.

Table comparing domiciliary accounts, Grey, Payoneer, Wise and stablecoins

Which is right for you?

You earn regularly from international clients or an employer. A virtual foreign currency account is your best option. You get foreign bank details to share with clients, control over when you convert, and a card to spend directly in USD. This replaces a dom account for most day-to-day use cases.

Your income comes through Upwork, Fiverr, or Amazon. Start with Payoneer since these platforms integrate it natively. If you find the conversion rates eating into your earnings, consider adding a Grey or similar account and routing future direct client payments there instead.

You need to send a one-off international transfer and want the best rate. Wise is hard to beat on exchange rates for single transactions. Just be aware of its limitations as a full-time financial tool for Nigerian residents.

You receive large, infrequent transfers and want to hold USD for the long term. A dom account at a reputable Nigerian bank still works for this. The setup friction is a one-time cost, and the banking regulation provides a level of institutional protection that fintech platforms do not.

You are paid in crypto or stablecoins. Hold your stablecoins and use a platform that supports USDC conversion to naira when you need to spend locally. Track your receipts for tax purposes under the 2026 NRS rules.

Most Nigerians managing regular international income end up using a combination of methods. A virtual foreign account for the majority of their income, Payoneer for platform payouts, and occasionally a dom account or Wise for specific transactions. The key is to stop defaulting to the dom account for everything, because for regular use, the alternatives are faster, cheaper, and more flexible.

Manage your international income with Grey

Grey gives you USD, EUR, GBP, and USDC account details to receive international payments, a virtual Visa card with Apple Pay and Google Pay support for spending, a built-in invoicing tool for billing clients, and naira withdrawals to your Nigerian bank account. Sign up at grey.co or download the app to get started.

Note: Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion.

Frequently asked questions

Is a domiciliary account still worth it in 2026?

For specific use cases, yes. If you receive large wire transfers infrequently, want to hold a significant USD balance under banking regulation, or need the institutional credibility of a commercial bank account, a dom account still serves those purposes. For regular freelance income and everyday USD spending, virtual foreign accounts are more practical.

Can I receive USD in Nigeria without a domiciliary account?

Yes. Virtual foreign currency accounts from platforms like Grey, Geegpay, and Cleva give you USD account details that work as US bank accounts from the sender's perspective. Your client pays via ACH or wire, and the funds are deposited into your wallet without ever touching a Nigerian bank.

What is the cheapest way to receive dollars in Nigeria?

Virtual foreign currency accounts that support ACH transfers are typically the cheapest because they avoid SWIFT intermediary fees entirely. The main cost is the exchange rate spread when you convert to naira, which varies by provider (typically 1% to 3%).

Is Wise or Grey better for Nigerian freelancers?

They serve different needs. Wise offers the mid-market exchange rate, which is excellent for occasional transfers, but it has no card in Nigeria and has periodically disrupted its services in Nigeria. Grey offers a virtual card, Apple Pay/Google Pay, USDC support, and an invoicing tool, making it more practical for Nigerian residents managing regular international income. Many freelancers use both.

Are stablecoins legal in Nigeria?

The regulatory landscape around crypto in Nigeria is evolving. Holding stablecoins is not illegal, and many professionals use them for international payments. Under the 2026 Nigeria Tax Act, stablecoin income is treated as foreign income and must be declared. The main risk is in the off-ramp: converting to naira through unregulated channels can expose you to fraud or compliance issues.

Do I need a Dom account to receive a wire transfer?

Not necessarily. A virtual foreign currency account with SWIFT or wire receiving capability can also receive wire transfers. However, some senders (particularly corporate treasury departments) may prefer to send to a traditional bank account. Check with your payment source whether they accept fintech account details.

Ready to move beyond the dom account? Sign up at grey.co and get your USD, EUR, and GBP account details in minutes.

How consultants structure international client payments

•

•

2 min read

A consultant who sends a rough invoice three weeks late tells a different story than one who has clear terms, structured milestones, and a payment setup that works seamlessly regardless of the client's location. Being your own boss is cool and all, but there are other responsibilities you might not have been informed about. If you work with global clients, you need to manage foreign income. How well you do this can make or mar your experience. So, getting that structure right matters. It is not just about the money coming in, but also how it makes you appear to clients who are constantly evaluating your professionalism. This article covers structuring international client payments for consultants.

One of the biggest mistakes consultants make with international clients is waiting until invoicing to think about payment. By that time, key decisions have already been missed, which can cause problems starting work. Make sure your contract clearly states the billing currency, payment schedule, payment method, what happens if a payment is late, and who covers any transaction or conversion fees.

Also read: Negotiating cross-border freelance contracts: Tips and templates

Choose your billing currency deliberately

Most international consultants bill in USD, EUR, or GBP. Choose your currency based on where most of your clients are, which currency you prefer to hold or convert, and which gives you the clearest pricing when converting to your local currency. You can bill in your local currency, but this can make things harder for international clients, especially if your currency is unstable or unfamiliar. Billing in a major foreign currency and converting when you withdraw, using a platform with good rates, usually gives you more control and predictability over your earnings.

Decide on your payment structure

Payment structures consultants commonly use include

Full upfront payment

This means the client pays the full fee before any work starts. It is most common for short, clearly defined projects, such as a one-day workshop, a strategy review, or a specific deliverable with a fixed scope.

With international clients, upfront payment removes the risk of not getting paid and makes administration easier. However, not all clients will agree to this, especially for bigger projects or if they have not worked with you before. You need enough credibility and a proven track record to ask for full payment upfront.

Deposit plus balance

A more common setup for mid-sized projects is to take a deposit, usually 30% to 50% of the total fee, before starting work. The rest is paid at a set time, often on delivery or a specific date.

This approach balances risk for both sides. The consultant gets some payment before putting in a lot of work, and the client does not pay for something they have not received yet. For international projects, this is a practical default that most clients know and accept.

LDMAG1

Milestone-based payments

Longer projects can be divided into phases, and sometimes, your role is a long-term arrangement. Milestone-based payments usually make the most sense for such projects. You get paid after each phase is finished. This ensures money keeps coming without  waiting until the end. It also gives both you and the client regular points to check progress.

Monthly retainer

For ongoing advisory or long-term consulting relationships, a monthly retainer is a great structure. The client pays you a fixed monthly amount to cover a set number of hours, calls, or deliverables. Retainers are excellent for consultants because they provide a predictable income stream. They are also attractive to clients who want reliable access to expertise without having to go through a scoping and contracting process every time they need something. A payment setup that supports recurring payments can eliminate the back-and-forth of invoicing for every interaction.

Also read: Setting up payment terms and timelines with international clients

Other things consultants should note while setting their payment structure

  • Net terms. You might have heard of Net 15, Net 30, and Net 45. These are the number of days the client has to pay an invoice from the date it is issued. For international clients, shorter terms are better. Net 30 is a reasonable standard. For new clients, consider offering Net 14 or Net 15.
  • Late payment clauses. Your contract should specify what happens when an invoice is not paid on time. Your options include a late payment fee, interest on the outstanding balance, or the right to pause work until you receive the payment.
  • Currency fluctuation. If you are billing in a foreign currency and the engagement spans several months, it is worth deciding in advance how to handle exchange rate movements.
  • Transaction costs. International transfers often come with fees on both ends. Be specific about who pays what. A common approach is to specify that the client is responsible for ensuring the full invoiced amount arrives, net of any fees — meaning they cover the sending fees on their end.

Also read: Managing money across countries as an expat: A complete guide

Set up your payment option

You need to choose a payment option that is convenient for you and your clients while maximising your income. An account that supports multi-currency payments at low transaction fees should be a priority. Your choice should also support withdrawals in local currency at competitive exchange rates, without unnecessary cost or delay.

Digital payment platforms like Grey offer  USD, EUR, and GBP account details that you can include directly on your invoices. Your client pays as though they are making a local transaction, which is often faster and cheaper for them. The money arrives in your account in the foreign currency, and you convert and withdraw to your local bank when you are ready.

Automate your invoicing

Automating your invoicing on platforms like Grey gives your operation a professional touch. You also don’t have to think too much about that happening for long-term projects. For international clients, the invoice should include all the details they need to make a transfer.

Also read: How expats are saving hours each week with Grey

Receive international consulting income with Grey

Grey provides consultants with virtual USD, EUR, and GBP accounts that come with real foreign account details. You can put these details directly on your invoice, making it easy for clients to pay. Payments arrive quickly, conversion rates are good, and you can withdraw to your local bank in minutes. With virtual cards that simplify online payments, you can easily pay for your tools, travels, online shopping, and subscriptions.

Sign up on Grey or download the app to get started.

‍

Why creators move away from Payoneer and PayPal

•

•

2 min read

If you are from where I am from, then you’ll understand when I say Payoneer and PayPal are the “Old Takers” of cross-border payments. For a long time, they were the popular answers to the question of how creators get paid online. If you were monetising content, selling digital products, or working with international brands, one or both of these platforms were almost certainly part of the conversation.

That still holds true for many creators. However, for some reason, many creators seem to be drifting away from both platforms, and it's easy to understand their frustration. This article explores the experiences of these looks at the real reasons behind that shift.

Also read: How creators receive payouts from international platforms

Why are creators moving away from Payoneer?

Payoneer built its reputation on marketplace integrations. Amazon, Upwork, Fiverr, and many other global platforms integrated seamlessly with Payoneer, allowing users to manage their payouts from these platforms.  However, seamless integration is not enough to keep creators using the platform. Here are some reasons Payoneer might not be as favoured:

  • High fees: Payoneer charges multiple fees that add up into significant transaction cost. Key costs include up to 3.99% to receive credit card payments, 1% for ACH bank debits, and 0-1% for currency conversions. While receiving payments from other Payoneer users is free, a $29.95 annual fee applies if the account is inactive for 12 months or if you receive less than $2,000 in a year.
  • Poor exchange rates: Payoneer does not charge a visible conversion fee like some other platforms do. Instead, it builds a margin into the exchange rate it applies when converting your balance. Payoneer generally charges a markup of 0.5% to 2% (up to 3.5% for cards/wallets) above the mid-market exchange rate. While often cheaper than traditional banks', this fee is higher than competitors'.
  • Customer support might not be responsive: From delayed responses, confusing account freezes, and unresolved disputes, Payoneer users often complain about the customer support.
  • Limited reach in some regions: Despite being a global platform, Payoneer's ability to pay out in local currencies is inconsistent. In some markets, your only option is to receive USD and convert it yourself. In others, certain features are restricted or unavailable entirely. Creators who assumed global coverage sometimes discover the gaps at precisely the wrong moment.

Why are creators moving away from PayPal?

PayPal is a big name in the cross-border payment space, widely used by creators for the reliance adnd familiariy. Again, these benefits are not enough, as emerging digital payment platforms offer more perks. These are the reasons creators are moving from PayPay.

  • High fees: Like Payoneer, PayPal users face high fees as the platform charges a percentage fee on incoming payments, and a fixed fee depending on the currency.
  • Holds and freezes are common: Sometimes, it just feels like PayPal's fraud detection is aggressive. Creators often experience account restrictions and suspensions that lead to losses or getting stranded.
  • It is not available everywhere: Theoretically, PayPal is available in over 200 countries, but in reality, creators in either cannot receive PayPal payments at all or face such significant limitations.
  • Limited feature: Over the years, PayPal has not evolved much compared to what fintech platforms now offer creators. With multi-currency accounts, real-time conversion, instant local withdrawals, and invoicing tools, PayPal seems to be running behind platforms like Grey and Wise.

What creators are moving towards

The shift away from Payoneer and PayPal is not a move away from digital payments. It is a move towards better digital payments. And the things creators are looking for when they switch are fairly consistent.

  • Transparent fee structure
  • Low transaction fees
  • Swift payment processing
  • Responsive customer service
  • Competitive exchange rates
  • Reliable access to funds
  • Multi-currency flexibility

Also read: How to collect international creator funds in local currency

Making the move with Grey

As creators move away from Payoneer and PayPal, platforms like Grey offer virtual USD, EUR, and GBP accounts that they can share directly with clients and integrate with other platforms. Payments are swift, conversion rates are competitive, fees aretransparent, and withdrawals to local bank accounts are processed in minutes.

Sign up on Grey or download the app to get started.

‍

How to shop in the US or Europe with your Grey card

•

•

2 min read

A few months ago, I was eyeing a pair of sneakers on a US website for weeks. Then the store started running sales and I decided to buy them (hashtag #YOLO), but my bank card declined the payment.

Not once, not twice… but four times!.

The same card that worked perfectly in Nigeria where I live, and the same details I’d used for years. I tried to get another card, but by then, sales had ended, and the sneakers were out of stock. It was annoying, but I just had to accept my L.

If you’ve ever tried to shop internationally, on sites like ASOS UK, Amazon US, Zara EU, or even the Apple Store, you may already be familiar with this pain. Sometimes the website rejects your card. Sometimes your bank blocks the transaction. Sometimes the currency conversion takes too long, and the payment times out.

It shouldn’t be this difficult to buy something online in big 2026… yet for many people, it still is.

But if you use a Grey card, you'll eliminate the uncertainty of thoughts like, “Will this payment go through?”, and transform your international shopping into a simple and predictable process.

Why shopping abroad is often frustrating

Shopping from US or European stores usually comes with these hurdles:

1. Many foreign merchants decline local cards

Some US/UK online stores automatically reject certain African-issued cards, even if you have more than enough balance.

2. Stores bill strictly in USD, GBP, or EUR

If your card requires manual currency conversion, it can cause payment delays that may result in declines.

3. Banks block “suspicious” international transactions

This usually happens when the merchant is unfamiliar.

4. Conversion errors and hidden fees

Some cards convert long after the purchase, leading to surprises on your statement.

These problems are common, but they’re also exactly what Grey card is built to avoid.

How your Grey card makes shopping internationally easy

Smart spending across multiple currencies and USDC

Your Grey card doesn’t require you to pick or switch wallets before paying. Instead, it automatically spends from your balances. Your USD account is debited first; if that’s empty, your USDC, and then the highest of your remaining balances.

This means your payment goes through as long as you have funds available in your account, without requiring you to consider currencies at checkout.

Works across major US and European stores

Your Grey card is an international spend card, so you can pay at 150 million merchants worldwide.

Use Apple Pay and Google Pay

For stores that support mobile wallets, you can simply add your Grey Visa card to Apple Pay or Google Pay. This is more secure and makes for much faster checkouts.

Create multiple cards for better organisation

If you shop frequently or mix personal and business purchases, you can:

  • Use one card for personal shopping
  • another for business imports
  • another for gift purchases

It keeps your spending clean and easy to track.

Freeze and unfreeze anytime

You can always freeze your cards to control your spending.

Better protection for online transactions

You receive real-time notifications, card controls, and instant limits - everything you need for peace of mind when buying from foreign sites.

LDMAG1

How to shop in the US or Europe with your Grey card

1. Request your Grey visa card

Create a Grey account and go to the cards section of your Grey app to request a Grey card for $5.

2. Add your card to the store’s checkout

Enter your card details or simply pay through Apple Pay/Google Pay.

3. Make your purchase normally

Shipping, duties, and taxes will be displayed as they are for every other international shopper.

4. Track everything in your Grey app

Every charge, refund, or verification appears instantly, so there are no surprises later.

Tips for smarter international shopping

  • Use a separate card for business or bulk purchases so you can easily track expenses.
  • Keep a bit extra in your wallet for shipping fees and taxes.
  • Use Apple Pay/Google Pay when available. It’s the most seamless way to tap and pay, and also supports contactless payments.

Shopping abroad doesn’t have to be stressful

Your Grey card helps you shop with confidence. There are no random declines or conversion drama. Ahead of your next international purchase, you can create your Grey card and enjoy a smoother, more predictable shopping experience.

‍

How to budget in foreign currencies using the Grey card

•

•

2 min read

Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.

Then remote work happened.

Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you also need structure because, without proper structure, even the most careful spender can lose track of where their money is going.

Your Grey card is a practical budgeting tool for people who live, work, earn, and spend across borders. I’ll explain.

Why budgeting in multiple currencies breaks down so easily

Many people who overspend don't do so because they’re irresponsible. But because their money isn’t organised in a way that reflects how they live.

It’s pretty common to be juggling subscriptions in USD, running ads in EUR, buying coffee in GBP, and somehow all on the same card. Eventually, everything blurs together. You can no longer track your Netflix renewal, that Facebook ad campaign, the flight you booked last week, or the coworking space membership. Then one day you check your balance and think, “Where did all that money go?” You know you spent it. You just can’t figure out where, or why, it felt like so much more than you expected.

It’s not that you’re careless. It’s that your money isn’t organised in a way that matches how you actually live and work. And once things start blurring, it’s nearly impossible to untangle without spending an hour combing through statements, converting currencies in your head, and still not feeling certain you’ve caught everything.

At that point, your budget is broken.

Also read: How to use your Grey card to manage all your subscriptions

What should budgeting look like when you earn and spend globally?

Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:

  • See exactly what each type of spending is costing you.
  • Stop or pause spending instantly when needed.
  • Protect one part of your budget from another.
  • Make changes without disrupting everything else.

The Grey card is designed around solving these exact needs.

How does the Grey card help with budgeting?

Use multiple cards to separate your spending

One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes. Your Grey virtual card helps you structure your spending as such.

For example, you can create:

  • One card for subscriptions and recurring tools
  • One card for ads and growth experiments
  • One card for travel or everyday spending
  • One card per client or project

Each card acts like its own budget lane, pulling from the same balance. You don’t need to guess where the money went because you already know.

This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.

Also read: How to pay for ads easily with your Grey card

Freeze cards instantly when spending goes off-track

Budgets fail when you can’t act fast enough.

With the Grey card, you can instantly freeze or unfreeze any card in the app. If a digital ad campaign starts burning through too cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.

Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.

Set limits that protect your budget

Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.

You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.

For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.

Track spending clearly in one place

When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.

When budgeting time comes around, you’re not sitting there trying to remember what that mysterious €47 charge was three weeks ago or why your USD balance dropped. Everything’s already categorised. The structure did the work for you.

Spend confidently across borders

Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.

A quick note on protection when spending abroad

An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.

When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.

It’s one less thing to worry about while managing money across borders.

Also read: How to claim your Visa card benefits

What budgeting in foreign currencies is like with the Grey card

When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency your spend is coming from and more importantly, when something changes.

Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.

If you’re ready to make your budget work wherever you are, create or update your Grey card today and start spending and budgeting in the ways that matter to you.

‍

Arrow (up)

Back to top

