


<script type="application/ld+json">[{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/open-pounds-account#article","headline":"How to open a British pounds sterling account as a non-UK resident","description":"Need a Pounds account as a non-UK resident? Open one easily with Grey—send, receive, and transact in GBP seamlessly","inLanguage":"en","url":"https://grey.co/blog/open-pounds-account","mainEntityOfPage":"https://grey.co/blog/open-pounds-account","datePublished":"2022-11-30T17:29:55.196Z","dateModified":"2022-11-30T17:29:55.196Z","author":{"@type":"Person","name":"Winner Ajibola"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co"},"image":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6389dc38ba3cce6251eec3ad_Blogpost_How-to-Open-a-Pounds-Account-as-a-UK-Non-Resident-2-1024x536.webp"},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/open-pounds-account#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to open a British pounds sterling account as a non-UK resident","item":"https://grey.co/blog/open-pounds-account"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/open-pounds-account#faq","mainEntity":[{"@type":"Question","name":"What Countries Can Send Me Payments?","acceptedAnswer":{"@type":"Answer","text":"With your Grey Pounds account, you can receive funds from any country in the United Kingdom and other countries in the EEA region. This means you cannot receive payments from countries outside the EEA region."}},{"@type":"Question","name":"What type of currencies can I receive in my account?","acceptedAnswer":{"@type":"Answer","text":"Great British Pounds. So you cannot receive any other currencies into this account."}},{"@type":"Question","name":"What supported payment types can I receive with a Grey Pounds Account?","acceptedAnswer":{"@type":"Answer","text":"Your Grey foreign account is addressable in Faster Payments (FPS), Bacs, and CHAPS. Unfortunately, you cannot receive SWIFT and WIRE transfers to your GBP Grey account."}}]}]</script>

How to open a British pounds sterling account as a non-UK resident

Winner Ajibola

TABLE OF CONTENT

SHARE THIS POST

Do you need to carry out essential transactions in Pounds, but you reside in an African country? Does the limitation of not having a BRP force you into constantly converting your local currency into Pounds before carrying out a transaction? Perhaps you just need a more accessible and stable way to receive GBP from your employers as a freelancer. What you need is a Pounds bank account.

Since most high-street banks in the UK require your resident permit or proof of accommodation before you can open an account, you’re probably looking for alternatives. Fortunately, there are still alternative ways to open a Pounds Account even when you are an African resident. 

This post will show you how to open one as a non-UK resident. We’d also look through the requirements, and some frequently asked questions we think will come in handy. 

The Challenges of Opening a Pounds Account as a Non-UK Resident

If you’ve been researching online UK bank alternatives, you may have seen online banking options like Monese and Revolut. Unfortunately, while these are more flexible options, they still require proof of residency in an EU country. And so, if you reside in Africa, you’re faced with either opening a Pounds Domiciliary account or a Grey foreign account.

You cannot process withdrawals from anywhere or open an account without a Domiciliary account referee. You’d also face high withdrawal charges and constantly have to visit a bank branch to carry out transactions. This is why having a Grey Pounds account is the best option for a non-UK resident. 

Requirements for Opening a Pounds Bank Account

While the requirements for opening an account vary for each bank, there are some consistent documents you’d have to present. 

For a Domiciliary Account, they include;

  • A completed account opening form 
  • Recent passport photographs
  • Two referee letters
  • A valid means of identity, e.g., a Passport
  • A minimum account balance (varies from bank to bank)
  • Proof of address: a utility bill in your name, showing your address in your country of residence. 

For a Grey Foreign account, all you need is a Valid ID, utility bill, internet connectivity, and a smartphone/PC. 

How to Open a Pounds Account as a Non-UK Resident or Citizen

As a non-UK resident, the best option you have is to open a foreign bank account via Grey. With a Grey foreign account, you can send, receive, swap, and transfer funds in GBP. You can open a bank account on Grey without a residence permit or referee letter.

You also don’t need to visit any branch as everything you need to set up your account is online. Here’s a step-by-step process on how to open a Pounds account via Grey;

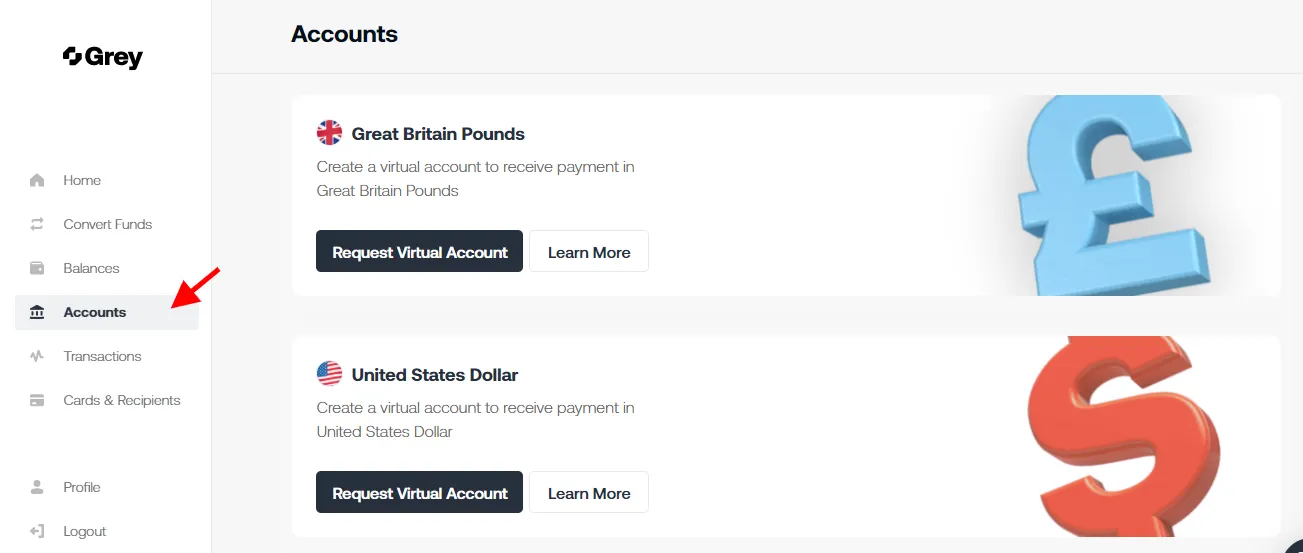
  • Log in to your Grey account. If you don’t have an account, you can create one here.
  • On the navigation panel on your screen’s left side, click on ‘Accounts.’
67222e16c9ee7fc522c90ff9 638793134c600ec246892dd4 TSayxFc7Z28ifeLc3 9lonPjW6MsHnDSvykWUL8sxjFVvAxTX8AUGSd6KWroXwI VUaE8AjnZcjqEQilYiL0fwsEqtxW3wzKTLBtmXJzOHLEJO5wUV094bhCNwgg5K8UHFi6C2LhXvErWkNgRY ph9o0WdpbZif0BeailA1OffftXOp2o6TYF8vjmA
  • Scroll and tap on ‘Request Virtual Account’ under the GBP account option
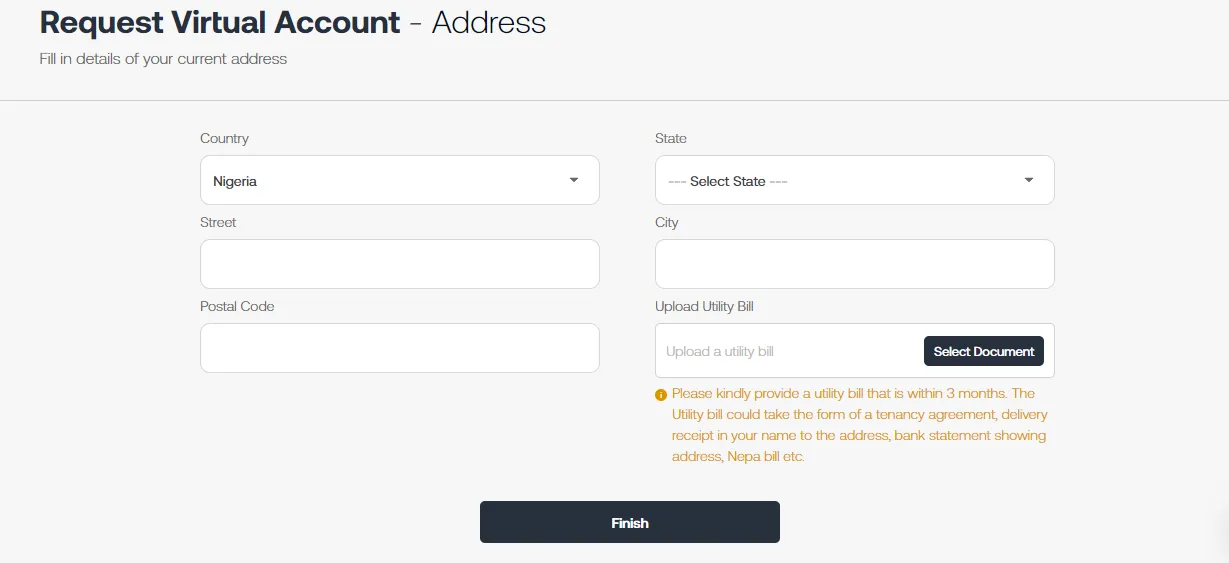
  • On the form displayed, fill in your address and upload a utility bill no farther than three months ago
67222e15c9ee7fc522c90ff5 6387931194ff1f17a38c6b1a vQQQOlHUPTaAtfpDpJGNo9HjloUigf1xw7TFxIzmnwHRiLwQ28AHK27Pz17F5DN Jud1zeEqL rUcj1jX1jp rkbv6iuDypOzy4hCDd ZAR2bB54vDO RqdikmAXgCyLASmPv9tThPicEs01Mk4yyRT63Yum6RaQB 77SreCDZKPq2boEr3aLxue9w
  • Review your information and tap on ‘Finish.’

You’ll get a notification once it’s been approved or whether there’s a needed update on your application. So ensure you enter valid and accurate information to prevent any delays. 

Benefits of Opening a Grey Pounds Account

With a host of other online banks, why should you opt for a Grey foreign account? Well, asides from being able to carry out transactions whenever you like, you can also;

  • Easily open an account without a residence permit or referee letter
  • Opening an account on Grey is entirely free.
  • There’s no need to visit a physical bank branch to open an account
  • You get international bank account details, including an IBAN and routing number, which makes your bank account suitable for official purposes
  • Online customer support to help you with all your banking needs
  • Seamless withdrawals to your local account and unlimited transfers
  • Receive payments immediately you open an account - no further restrictions
  • Faster KYC and verification process so you can get started with your Pounds account almost immediately
  • Enjoy low withdrawal rates and instant currency exchange whenever you want to

FAQs on Using a Grey GBP Bank Account

  • What Countries Can Send Me Payments?

With your Grey Pounds account, you can receive funds from any country in the United Kingdom and other countries in the EEA region. This means you cannot receive payments from countries outside the EEA region. 

  • What type of currencies can I receive in my account?

Great British Pounds. So you cannot receive any other currencies into this account. 

  • What supported payment types can I receive with a Grey Pounds Account?

Your Grey foreign account is addressable in Faster Payments (FPS), Bacs, and CHAPS. Unfortunately, you cannot receive SWIFT and WIRE transfers to your GBP Grey account. 

Next Steps

Opening a Pounds account as a Non-UK resident doesn’t have to be difficult anymore. Start by downloading the Grey mobile app from the comfort of your home via Playstore or the iOS App Store and get your UK foreign account to start a transaction. 

Last updated:

September 13, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to send money from the US to the Philippines in 2026

•

•

2 min read

The Philippines receives more remittances from the United States than from any other country. Over four million Filipino Americans send money home regularly to cover everything from monthly household expenses and school fees to hospital bills and property payments. The Bangko Sentral ng Pilipinas (BSP) reported record remittance inflows in recent years, with the US remaining the largest source.

The good news is that sending money from the US to the Philippines has become significantly cheaper and faster than it was even five years ago. The bad news is that the cheapest option depends on how your recipient wants to receive: bank transfer, mobile wallet (GCash, Maya), or cash pickup. This guide covers the fees, speed, and delivery methods available in 2026, so you can find the right option for your specific situation. If you also send to other countries, see our broader.

What it costs to send money from the US to the Philippines with Grey

Grey charges a 1% conversion fee when converting USD to PHP, plus a $0.85 payout fee. The payout fee is the same whether you send the money to a Philippine bank account or a supported mobile wallet.

Here’s what the total fees look like at different transfer amounts:

Transfer amount Conversion fee (1%) Payout fee Total fees
$500 $5.00 $0.85 $5.85
$1,000 $10.00 $0.85 $10.85
$2,000 $20.00 $0.85 $20.85

‍

For example, sending $500 costs $5 to convert USD to PHP, plus the $0.85 payout fee, bringing the total fees to $5.85.

You can send PHP by bank transfer or mobile money. Grey supports wallets including GCash and Maya, and both bank and mobile money transfers are typically completed instantly or up to 1 business day. Processing can occasionally take longer depending on the recipient's bank or network conditions.

Bank transfer or mobile wallet: how your recipient gets the money

Bank transfer

Grey delivers PHP to all major Philippine banks. Your recipient needs a peso bank account, and you need their full name (as it appears on the account), the bank name, and the account number. The funds arrive as a standard deposit.

Bank transfer is the right choice for larger payments: hospital bills, tuition fees, property transactions, or any amount where the recipient needs the funds in their bank account. There are no receiving limits on the bank side beyond whatever the bank itself imposes.

Mobile wallets: GCash and Maya

If your recipient uses GCash or Maya, you can send directly to their mobile wallet using their registered name and mobile number. Mobile wallet delivery is often faster than bank transfer for smaller amounts and more convenient for recipients who do not use a bank account regularly.

Mobile wallets typically have per-transaction and monthly receiving limits set by the wallet provider. For larger medical bills or tuition payments, a bank transfer is usually the better option. For regular household support, groceries, or smaller medical expenses, a mobile wallet is practical and fast.

Also read: Best apps to send money internationally from the US in 2026

What Filipino Americans are sending money home for

Understanding the common use cases helps you choose the right delivery method and timing.

Monthly family support. Regular transfers to parents, siblings, or extended family can help cover household expenses, groceries, utilities, and daily needs. Grey charges a 1% conversion fee when converting USD to PHP, plus a $0.85 payout fee. Before sending, you can review the fees and the final PHP amount your recipient will receive.

Medical bills. Philippine hospital bills are typically paid to the hospital's bank account. Ask the hospital for their full business name, bank name, and account number. Send the exact PHP amount of the bill so the hospital receives the full payment without any shortfall from fees. Grey shows the exact amount your recipient will receive before you confirm, so you can match it to the billing statement.

Education and tuition. Philippine universities and schools accept bank transfers. Tuition payments tend to be large and time-sensitive (with fixed due dates). Send via bank transfer and keep the transaction receipt as proof of payment.

Property and investments. Buying property, paying mortgage instalments, or investing in the Philippines from the US can involve larger transfers. For these payments, it helps to check the exchange rate, fees, and recipient details carefully before confirming the transfer.

Emergency expenses. Typhoons, medical emergencies, or unexpected costs. Speed matters. Check whether mobile wallet delivery is instant and whether it fits within the amount limits. For larger emergency amounts, a bank transfer with confirmed delivery timing is more reliable.

How to send money from the US to the Philippines with Grey

1. Open your Grey account. Download the Grey app, sign up, and verify your identity. US residents need a government-issued ID. Grey is licensed by FinCEN as a Money Services Business.

2. Fund your account. Transfer USD from your US bank account into your Grey wallet. You can fund via ACH (free, arrives same day) or wire transfer.

3. Choose your destination. Tap Send, select PHP (Philippine Peso), and choose bank transfer or mobile wallet.

4. Enter your recipient's details. For bank transfer: their full name, bank name, and account number. For mobile wallet: their registered name and mobile number. Grey shows the exchange rate, conversion fee, payout fee, and the exact PHP amount your recipient will receive before you confirm.

5. Confirm and send. Review the summary and confirm with your PIN. Your recipient does not need a Grey account. The funds arrive as a standard deposit in their bank account or mobile wallet.

Three ways to save on US-to-Philippines transfers

Check the total cost before you send. Grey charges a 1% conversion fee when converting USD to PHP, plus a $0.85 payout fee. Before confirming your transfer, you can review the exchange rate, fees, and exact PHP amount your recipient will receive, so there are no surprises after you send.

Use ACH to fund your Grey account. ACH transfers from your US bank to your Grey wallet are free and arrive the same day. Wire transfers cost $25 (SWIFT) and are unnecessary for most users. Fund via ACH unless you need to move a very large sum urgently.

Send the exact PHP amount for bills. When paying a hospital bill, tuition fee, or any fixed-amount obligation, enter the amount in PHP rather than USD. Grey will calculate exactly how much USD is needed to deliver that PHP amount after all fees. This ensures the recipient receives the full bill amount with no shortfall.

You may also like: How to receive an international wire transfer: Fees, timing, and what to tell the sender

Frequently asked questions about sending money from the US to the Philippines

What is the cheapest way to send money from the US to the Philippines?

The cheapest option depends on the amount, exchange rate, fees, and delivery method. With Grey, USD-to-PHP conversions have a 1% conversion fee, plus a $0.85 payout fee. Before confirming, you can see the applicable fees and final PHP amount your recipient will receive, making it easier to compare the total cost with other transfer options.

How long does it take to send money from the US to the Philippines?

Bank transfers to the Philippines typically arrive within 1 to 2 business days. Mobile wallet transfers, including GCash and Maya, may arrive faster. Actual delivery times can vary depending on the recipient’s bank or mobile wallet provider and network conditions.

Can I send money from the US to GCash in the Philippines?

Yes. Grey supports delivery to GCash using the recipient's registered name and mobile number. Per-transaction and monthly limits may apply based on GCash's own policies." If no, replace with: "Grey currently delivers PHP via bank transfer to all major Philippine banks.

How do I pay a hospital bill in the Philippines from the US?

Ask the hospital for their full business name, bank name, and bank account number. Send the exact PHP amount of the bill through Grey, using the hospital's bank details as the recipient. Grey shows the exact PHP amount your recipient will receive before you confirm, so you can match it to the billing statement. Keep the transaction receipt as proof of payment.

Do I need to pay tax on money sent to the Philippines from the US?

Personal remittances sent from the US to the Philippines are generally not taxable for the sender. The US does not tax outgoing personal transfers. However, if you send more than $16,000 to a single individual in a calendar year, you may need to file a gift tax return (IRS Form 709), though no tax is typically owed until you exceed the lifetime exemption. Consult a tax professional for your specific situation.

What exchange rate does Grey use for USD to PHP?

The exchange rate available for USD to PHP is shown in the Grey app before you confirm the conversion. Grey charges a 1% conversion fee, and you can review the rate, applicable fees, and final PHP amount before completing the transaction.

Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion. Grey is a financial technology company, not a bank. Banking services are provided by licensed banking partners. This article is general information, not financial or tax advice. Consult a qualified professional for tax questions.


SWIFT code vs routing number: What is the difference?

•

•

2 min read

Someone asks for your "routing number." Someone else asks for your "SWIFT code." They sound like they might be the same thing, and the confusion costs people real money. Use the wrong code and your transfer fails, you get charged a fee for the failed attempt, and the money sits in limbo for days while the banks sort it out.

A routing number is a 9-digit code that identifies a US bank for domestic transfers such as ACH and direct deposit. A SWIFT code (also called a BIC) identifies a bank internationally for cross-border transfers. Use a routing number for US payments and a SWIFT code for international payments. Some transactions, like receiving a wire from abroad into a US bank, require both.

The distinction is simple once you see it. This guide covers both codes, shows you exactly when to use each, and explains what to do when someone abroad needs to pay you.

What is a routing number?

A routing number is a 9-digit code assigned by the American Bankers Association (ABA) to every US bank and credit union. It identifies which financial institution holds your account. The system has been in use since 1910, originally designed to process paper cheques. Today it's used for every domestic electronic transfer.

Format: always exactly 9 digits, always numeric. No letters. Example: Wells Fargo California is 121042882. JPMorgan Chase New York is 021000021. Large banks have different routing numbers for different states because they acquired regional banks over the decades and kept the existing infrastructure.

When you need it: setting up direct deposit with your employer, paying bills online, transferring money between US bank accounts (ACH), receiving tax refunds, linking your bank to payment apps (Venmo, Cash App, PayPal). Essentially, any time money moves domestically within the US banking system, a routing number is involved.

Where to find it: bottom left of a paper cheque (first 9 digits in MICR font), in your bank's mobile app under Account Details, on your bank's website, or by calling customer service. For a complete state-by-state list for one of the largest US banks, see "Find a Bank Routing Number".

Key point: routing numbers only work within the United States. They have no function in international transfers. If someone outside the US asks for your routing number, they probably need your SWIFT code instead (or both, if they're sending a wire to your US bank account).

What is a SWIFT/BIC code?

A SWIFT code (also called a BIC, Bank Identifier Code) is an 8 or 11-character alphanumeric code that identifies a specific bank on the global SWIFT network. SWIFT stands for Society for Worldwide Interbank Financial Telecommunication. The network connects over 11,000 financial institutions across 200+ countries and handles the messaging layer for most international wire transfers.

Format: 8 or 11 characters, mixing letters and numbers. The structure tells you exactly what bank, in what country, at what location:

Characters 1 to 4: bank code (letters). Characters 5 to 6: country code (letters). Characters 7 to 8: location code (letters or numbers). Characters 9 to 11 (optional): branch code.

Example: WFBIUS6S is Wells Fargo. WF = Wells Fargo bank code, BI = part of the bank identifier, US = United States, 6S = San Francisco location. CHASUS33 is JPMorgan Chase: CHAS = Chase, US = United States, 33 = New York.

When you need it: sending money from the US to another country, receiving money from someone abroad, making international wire transfers, receiving freelance payments from overseas clients. Any time money crosses a national border via the banking system, a SWIFT code is involved.

Where to find it: your bank's website (usually in the wire transfer or international payments section), on your bank statement, by calling customer service, or by searching the official SWIFT directory at swift.com. Not every bank has a SWIFT code. Smaller credit unions and online-only banks may not participate in the SWIFT network, which can complicate the receipt of international payments.

SWIFT code vs routing number: Side by side

Here's the difference between SWIFT codes and routing numbers at a glance:

Feature Routing Number SWIFT/BIC Code
Purpose Identifies US banks for domestic transfers Identifies banks globally for international transfers
Format 9 digits (numeric only) 8 or 11 characters (letters + numbers)
Scope United States only 200+ countries worldwide
Issued by American Bankers Association (since 1910) SWIFT network (since 1973)
Used for ACH, direct deposit, bill pay, domestic wires International wire transfers, cross-border payments
Example 121042882 (Wells Fargo CA) WFBIUS6S (Wells Fargo)
Where to find Cheque, bank app, bank website Bank website, statements, swift.com
International use None Primary code for cross-border banking

‍

The simplest way to remember: routing number = US domestic, SWIFT code = international. If money stays inside the US, you need a routing number. If money crosses a border, you need a SWIFT code. If money is sent from abroad to a US bank account, the sender usually needs both your SWIFT code (to identify your bank internationally) and your account number (to identify your specific account).

Which do you need for your transfer?

The answer depends entirely on where the money is going and where it's coming from.

Sending money within the US

You need the recipient's routing number and account number. This covers ACH transfers, domestic wire transfers, direct deposit setup, online bill payments, and linking bank accounts to apps. No SWIFT code needed. For domestic-only tasks like filling out payment forms, see how to fill out a money order.

Sending money from the US to another country

You need the recipient's SWIFT code (or BIC) and their account number (or IBAN for European recipients). Your bank initiates the transfer through the SWIFT network. You'll pay an outgoing wire fee ($25 to $50 at most US banks). If something goes wrong, see how to cancel a wire transfer. You can also send money internationally with Grey, which bypasses SWIFT entirely and uses its own transfer rails at lower cost.

Receiving money from abroad into a US bank account

The sender needs your bank's SWIFT code plus your account number. Some sending banks also ask for your bank's routing number as a secondary reference. Provide both to avoid delays. Your bank may charge an incoming wire fee ($10 to $20).

Receiving money from abroad without a US bank

If you're outside the US and need to receive USD, GBP, or EUR from international clients, you don't need a US bank's SWIFT code or routing number. Grey provides account details for each currency: a US routing number + account number for USD, a UK sort code + account number for GBP, and an IBAN for EUR. Your clients send the funds to those details through their normal banking channels, and the money arrives in your Grey account. No SWIFT fees, no intermediary deductions.

Receiving international payments with Grey

The SWIFT code vs routing number question usually comes up when someone abroad is trying to pay you. The traditional answer is: give them your SWIFT code and account number, wait 1 to 5 days, and accept whatever intermediary fees get deducted along the way.

Grey simplifies this. When you open a Grey account, you receive real account details for each currency you hold:

USD: ACH routing number + account number. Clients in the US pay you via ACH (free or near-free for them, no SWIFT involved).

‍GBP: UK sort code + account number. Clients in the UK pay you via Faster Payments (arrives in minutes).

‍EUR: IBAN. Clients in Europe pay you via SEPA (funds arrive within 1 business day).

Each payment arrives through local payment rails, not SWIFT. That means no intermediary bank deductions, no $15 incoming wire fees, and no 3- to 5-day wait. Your clients don't need to know your SWIFT code because they're sending payments through their country's domestic payment system. The money lands in your Grey account in the currency you chose, and you decide when to convert. You can also hold what you receive in multiple currencies.

Receive international payments with a Grey account. Get your own USD routing number, UK sort code, and EUR IBAN. No SWIFT fees, no intermediary deductions.

Frequently asked questions

Is a SWIFT code the same as a routing number?

No. A SWIFT code identifies a bank internationally for cross-border transfers. A routing number identifies a US bank for domestic transfers. They serve similar purposes (identifying the right bank) but operate in different systems. SWIFT codes are 8 or 11 alphanumeric characters long and are used across 200+ countries. Routing numbers are 9 digits long and are used only within the US.

Do I need both a SWIFT code and a routing number?

It depends on the transfer. For US domestic transfers, you only need a routing number. For international transfers from the US, you only need the recipient's SWIFT code. To receive international wires into a US bank account, the sender usually needs your SWIFT code and account number. Some sending banks also request the routing number as a secondary reference. Provide both to avoid delays.

Where do I find my SWIFT code?

Check your bank's website (usually in the international transfers or wire transfer section), your bank statement, your mobile banking app, or search the official SWIFT directory at swift.com. You can also call your bank's customer service. Note that smaller credit unions and some online-only banks may not have a SWIFT code.

Can I use a SWIFT code for domestic US transfers?

No. SWIFT codes are not used for domestic US transactions. For any transfer within the US, including ACH, direct deposit, bill payments, and domestic wires, you need the bank's routing number and the recipient's account number.

What happens if I use the wrong code?

The transfer will typically fail and the money will be returned to the sender, but this can take days. Some banks charge a fee for failed transfers ($10 to $25). In rare cases, the money could be routed to the wrong account. Always double-check the code before confirming any transfer. Verify the SWIFT code or routing number directly with the recipient rather than relying on third-party lookup sites.

Can I receive international payments without a SWIFT code?

Yes. Services like Grey provide local account details (US routing number, UK sort code, EUR IBAN) that your international clients can use to pay via their own domestic payment systems. The payment never touches the SWIFT network, so there are no SWIFT fees or intermediary deductions. This is the simplest way to receive international payments without dealing with SWIFT codes.

Receiving money from abroad? Open a Grey account and share your details to get paid, without the guesswork.

Disclaimer: This article is for informational purposes only. SWIFT codes and routing numbers should be verified directly with your bank before use. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

7 best AI prompt generators (free and paid)

•

•

2 min read

Most AI prompt generators are just forms. Pick a tone, pick a length, click generate, and out comes a prompt that's marginally better than what a beginner would write on their own. A few, though, do something genuinely useful: they restructure how the AI receives instructions, add constraints that prevent generic output, and let teams reuse tested prompts across dozens of projects. The gap between the best prompt generators and the worst is enormous, and most listicles rank them without ever testing the difference in output quality.

AI prompt generators help you write and refine prompts to get better results from AI tools. The best offer templates, tone controls, and prompt libraries, with free and paid tiers. Popular options include prompt-builder tools built into major AI apps and dedicated prompt marketplaces. Choose one that fits your tasks.

This guide covers 7 tools, what each actually does (not marketing claims), and which ones are worth paying for.

What is an AI prompt generator?

An AI prompt generator takes a simple idea ("write an email to my landlord about a broken pipe") and expands it into a detailed prompt that tells the AI exactly what to produce: the tone, the structure, the length, what to include, what to leave out. Think of it as an automated prompt engineer.

Some tools do this by applying prompt templates. Others optimise your existing prompt by adding structure and specificity. A few are full-featured platforms with prompt libraries, version history, and team collaboration. The simplest are just form-based interfaces that plug your inputs into a pre-written prompt skeleton.

Who needs one? Anyone who uses AI regularly and wants consistent, high-quality results without spending 10 minutes crafting each prompt manually. Freelancers producing client content, marketers running campaigns through AI tools, developers generating code, and teams building AI-powered workflows all benefit. If you write the same types of prompts repeatedly, a generator can save time and improve consistency.

Who doesn't? If you use ChatGPT once a week for casual questions, a prompt generator is overkill. You'll get more value from learning a few prompting principles than from adding another tool to your stack.

The 7 best AI prompt generators compared

Tool Best for Free tier Price (paid)
PromptPerfect Optimising prompts across multiple AI models Yes (limited) From $16.67/mo
ChatGPT (built-in) General-purpose prompt refinement Yes (GPT-4o free tier) $20/mo (Plus)
Claude Projects Reusable prompt systems with context Yes (free tier) $20/mo (Pro)
Taskade Team workflows with prompt automation Yes (limited) From $8/mo
Jotform AI Form-based prompt building for non-technical users Yes From $34/mo
AIPRM Chrome extension with prompt library for ChatGPT Yes (limited) From $9/mo
PromptBase Marketplace for buying and selling tested prompts Browse free Per-prompt ($1.99 to $9.99)

‍

1. PromptPerfect

PromptPerfect takes a prompt you've written and optimises it for a specific AI model. You paste in "write a product description for a water bottle," select your target model (GPT-4, Claude, Midjourney, Stable Diffusion), and PromptPerfect rewrites the prompt with added specificity, formatting instructions, and model-specific syntax. It's not a prompt generator from scratch. It's a prompt improver. Best for people who already write their own prompts but want them tuned for maximum output quality. Free tier is limited to a few optimisations per day.

2. ChatGPT (Built-In Prompt Refinement)

You don't always need a separate tool. ChatGPT itself can generate and refine prompts. Type "help me write a better prompt for [task]" and it'll restructure your request with role assignments, step-by-step instructions, and output formatting. The custom instructions feature lets you set default behaviour (tone, audience, format) so every conversation starts from a better baseline. GPT-4o is available on the free tier. If you're already paying for ChatGPT Plus ($20/mo), this is the zero-friction option.

3. Claude Projects

Anthropic's Claude lets you create Projects: reusable workspaces with uploaded reference documents and custom instructions that persist across conversations. This isn't a prompt generator in the traditional sense. It's a system for building reusable prompt environments. Upload your brand guidelines, your writing samples, and your formatting rules into a Project, and every conversation inside it uses those as context. Best for freelancers and teams who need consistent output across dozens of similar tasks.

4. Taskade

Taskade combines AI prompts with project management. You create AI-powered workflows where each step runs a prompt automatically. For example: step 1 generates a blog outline, step 2 writes the draft, and step 3 creates social media posts from the draft. Each step uses a pre-built or custom prompt. It's more of a workflow automation tool than a standalone prompt generator, but the prompt-building interface is solid. Best for teams that want to chain multiple AI steps into repeatable processes. Free tier covers basic usage. Paid starts at $8/mo.

5. Jotform AI

Jotform built an AI agent system that generates prompts through a form-like interface. You fill in fields (topic, audience, tone, length, format) and it constructs a prompt from your inputs. The output is visible and editable before you run it. It's the most accessible option for people who find writing prompts intimidating. No prompt-engineering knowledge required. The free tier is generous. Paid plans start at $34/mo but include Jotform's full form-building suite, not just the AI features.

6. AIPRM

AIPRM is a Chrome extension that adds a prompt library directly to the ChatGPT interface. It gives you thousands of community-contributed prompt templates organised by category: marketing, coding, writing, SEO, HR. Click a template, fill in the variables, and it inserts the prompt into ChatGPT. The value is the library, not the technology. You're browsing other people's tested prompts rather than writing your own. Quality varies. The best templates are excellent. The worst are no better than what you'd write yourself. The free tier gives limited access. Premium starts at $9/mo.

7. PromptBase

PromptBase is a marketplace, not a generator. People sell tested prompts for $1.99 to $9.99 each. Categories cover GPT, DALL-E, Midjourney, Stable Diffusion, and Claude. The idea is that someone else has already spent hours refining a prompt for a specific use case (say, generating real estate listing photos in Midjourney), and you buy the result instead of building it from scratch. Best for image generation prompts where the right phrasing makes a dramatic difference in output quality. Browsing is free. You pay per prompt.

Free vs paid: What you get

Free tiers are enough for most individual users. ChatGPT's built-in prompt refinement costs nothing. AIPRM's free library covers the most popular categories. PromptPerfect gives you a few optimisations per day for free. If you write fewer than 10 prompts a week, you probably don't need to pay.

Paid plans add three things: volume (more optimisations, more templates, more storage), team features (shared prompt libraries, role-based access, workflow automation), and model support (PromptPerfect's paid plans cover Midjourney, Stable Diffusion, and other image models that the free tier limits).

When to pay: if you're a freelancer or agency producing AI-assisted content daily, the time savings from a paid plan justify the cost. If AI prompting is part of your job, $9 to $20 per month for a prompt tool is a reasonable productivity investment. If you're using AI casually, stick with free.

How to choose the right one

Start with what you're actually doing:

Writing content (blogs, emails, copy)? ChatGPT's built-in features or Claude Projects. Both are free or included in your existing subscription. Build custom instructions once and reuse them across conversations.

Generating images (Midjourney, DALL-E, Stable Diffusion)? PromptPerfect or PromptBase. Image prompts are highly model-specific. The right phrasing can be the difference between a professional result and a blurry mess. Either optimise your own prompts (PromptPerfect) or buy proven ones (PromptBase).

Running team workflows? Taskade. Chain multiple prompts into automated sequences that your whole team can run. The project management layer means prompts live alongside tasks, not in a separate tool.

Just starting out? Jotform AI or AIPRM. Jotform's form interface removes the blank-page problem. AIPRM's template library lets you learn by example. Both are good training wheels that you'll probably outgrow within a few months.

Don't stack multiple prompt tools. Pick one that fits your primary use case and learn it well. A prompt generator is only useful if you use it consistently enough to build muscle memory around how it structures prompts.

Paying for AI tools and getting paid for AI work

Most AI tools are billed in USD. ChatGPT Plus is $20/mo. Midjourney is $10 to $60/mo. Claude Pro is $20/mo. If you're outside the US, your bank's foreign transaction fee (1.5 to 3%) adds a hidden cost to every subscription payment. Over a year, that's $15 to $40 in fees on a single $20/mo subscription.

Pay for AI tools billed in USD with a Grey virtual card. Your subscriptions pull from your USD balance with no per-transaction conversion.

On the earning side: prompt engineering, AI content creation, and AI consulting are growing freelance categories. If you're doing AI work for international clients, you need a way to receive payments in their currency. Get paid for AI work from anywhere with Grey's multi-currency accounts: a US routing number for USD clients, a UK sort code for GBP clients, an IBAN for European clients.

If you're thinking about going full-time freelance as an AI specialist, you'll also need invoicing. See the best free invoicing tools for options that integrate with your payment workflow.

Working with AI tools? Pay for USD-billed subscriptions on a Grey virtual card and get paid by clients anywhere.

Frequently asked questions about AI prompt generators

What is the best AI prompt generator?

It depends on what you're doing. For optimising text prompts across multiple AI models, PromptPerfect is the most focused tool. For general prompt refinement without a separate app, ChatGPT's built-in features are free and effective. For reusable prompt systems with uploaded context, Claude Projects is the strongest option. For team workflows, Taskade chains multiple prompts into automated sequences.

Are there free AI prompt generators?

Yes. ChatGPT (free tier with GPT-4o) can refine prompts in conversation. AIPRM offers a free Chrome extension with limited access to community prompt templates. Jotform AI has a generous free tier with form-based prompt building. PromptPerfect offers a few free optimisations per day. For most individual users, free tiers are sufficient.

Do I need an AI prompt generator?

If you use AI tools daily for work and want consistent results, a prompt generator saves time and improves output quality. If you use AI casually for occasional questions, you don't need one. Learning a few prompting principles (be specific, assign a role, define the output format) will get you most of the way without adding another tool.

Can ChatGPT generate prompts for other AI tools?

Yes. You can ask ChatGPT to write prompts for Midjourney, Stable Diffusion, Claude, or any other AI tool. Describe what you want the output to look like and which tool you're using, and ChatGPT will format the prompt with the right syntax and keywords. This is free and works on the basic tier.

What is the difference between a prompt generator and a prompt marketplace?

A prompt generator creates or optimises prompts from your inputs (PromptPerfect, Taskade, Jotform). A prompt marketplace sells pre-made prompts that other people have tested and refined (PromptBase). Generators are for people who want custom prompts. Marketplaces are for people who want proven prompts without the trial-and-error.

How much do AI prompt generators cost?

Free tiers cover basic individual use. Paid plans range from $8/mo (Taskade) to $34/mo (Jotform, which includes the full form suite). PromptPerfect Pro is $16.67/mo. AIPRM Premium is $9/mo. PromptBase charges per prompt ($1.99 to $9.99) with no subscription. Most freelancers can stay under $20/mo for prompt tooling.

Working with AI tools? Pay for USD-billed subscriptions on a Grey virtual card and get paid by clients anywhere.

Disclaimer: Pricing and features are accurate as of the date of writing and may change. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts and virtual cards.

How to send money from Nigeria to a US bank account in 2026

•

•

2 min read

Sending money from Nigeria to someone in the United States used to mean a trip to your bank's forex desk, SWIFT transfer paperwork, fees that ran anywhere from 2% to 5%, and a wait of several business days with no clear tracking. For a lot of people, the alternative was to ask someone travelling to carry cash, which came with its own risks.

That has changed. A few fintech apps now let you send money from Nigeria directly to a US bank account from your phone, with the total cost and delivery time shown before you confirm. No branch visit, no SWIFT form, no intermediary banks taking a cut along the way.

This guide walks through how to send money from Nigeria to the United States using Grey, what it costs, how long it takes, which US banks are supported, and how the main alternatives compare.

What you need before you start

On your side (the sender in Nigeria), you need a verified Grey account. Verification requires a government-issued ID (international passport, national ID card, or driver's licence) and your Bank Verification Number (BVN). Most accounts are verified within minutes.

On your recipient's side (the person in the US), you need their US bank account details: the bank name, the ACH routing number (9 digits), and the account number. Your recipient does not need a Grey account. The money lands directly in their US bank account.

Grey supports all major US banks, including Wells Fargo, Bank of America, Chase, Citibank, and every other institution that accepts ACH deposits. If your recipient has a US bank account with a routing number, Grey can deliver to it.

How to fund your Grey account for a US transfer

Before you can send USD, you need naira in your Grey wallet. Transfer naira from your Nigerian bank account into Grey via a standard bank transfer. Grey does not charge a fee to receive naira deposits. Once your naira balance is in the app, you can convert to USD at the live rate and send immediately, or hold the naira and convert later when the rate suits you.

If you already hold a USD, EUR, or GBP balance in your Grey account from a previous deposit or an incoming payment, you can send directly from that balance without converting from naira first. This is useful if you receive international payments into your Grey account and want to forward them to a US recipient without a double conversion.

How to send money from Nigeria to the US: step by step

1. Open the Grey app and tap Send. From the home screen, tap Send to start a new transfer.

2. Select US Dollar (USD). Search for "US Dollar" or "USD" in the currency list and select it.

3. Add a USD recipient. Tap "Add USD recipient" and choose bank transfer. Enter your recipient's full name, their ACH routing number, and their account number. Double-check these details, because ACH transfers cannot be recalled once processed.

4. Enter the amount. Type the amount you want to send in USD or in your source currency (NGN, EUR, or GBP). Grey shows the live exchange rate, the conversion fee, and exactly how many dollars your recipient will receive, all on one screen.

5. Review and confirm. Check the summary. The total cost is the conversion fee (1% capped at the equivalent of $6) plus any payout fee. For USD transfers to the US, there is no separate payout fee. Confirm with your PIN or 2FA code.

That is it. The transfer is submitted and your recipient's US bank account is credited within 1 to 2 business days via ACH.

What it costs

Transfer amount Conversion fee Payout fee (US) Total cost
$200 $2.00 (1%) $0 $2.00
$500 $5.00 (1%) $0 $5.00
$1,000 $6.00 (cap applies) $0 $6.00
$2,000 $6.00 (cap applies) $0 $6.00
$5,000 $6.00 (cap applies) $0 $6.00

‍

Conversion fee is 1% of the amount, capped at the naira equivalent of $6 for Group A currency pairs (USD, EUR, GBP, NGN). There is no separate payout fee for USD transfers to the US. Grey fee data from support.grey.co, September 2026.

The fee cap is what makes this corridor particularly cost-effective for larger transfers. At $500, you pay $5. At $5,000, you still pay $6. Compare that to a typical Nigerian bank SWIFT transfer, where fees can run $25 to $50 or more on the same amount, plus a less favourable exchange rate.

There is no monthly fee, no account maintenance charge, and no minimum balance requirement. You pay only when you send.

Understanding the exchange rate

The conversion fee is only one part of the total cost. The other part is the exchange rate itself. Grey shows the live NGN-to-USD rate on the same screen as the fee before you confirm. The rate includes a margin over the mid-market rate, which is standard across all transfer platforms and is how Grey generates revenue alongside the capped fee.

You can check the mid-market rate on xe.com or Google at the time of your transfer and compare it to the rate Grey is offering. The difference between the two is the effective rate margin. On most transfers, the combination of Grey's capped fee plus the rate margin is still significantly cheaper than a Nigerian bank SWIFT transfer, where both the fee and the rate margin are typically wider.

If the rate is not where you want it, you do not have to send it immediately. You can fund your Grey account with naira and wait. When the rate moves in your favour, convert and send. Grey does not charge you for holding a naira balance.

How long it takes

Weekends and US public holidays are not business days. If you send on a Friday evening, the transfer will typically arrive on Monday or Tuesday. If you need funds to arrive on a specific date, send at least two business days in advance.

Grey does not currently offer instant or same-day delivery to US bank accounts. If your recipient needs funds faster, they may want to consider receiving via GreyTag, which allows direct transfers between Grey accounts.

How Grey compares to other options for Nigeria to the US

Grey: 1% capped at the equivalent of $6. No payout fee on USD. 1-2 business days via ACH. No branch visit. Transparent rate shown before you confirm.

Flutterwave Send: 1% with no cap. On a $2,000 transfer, Flutterwave charges $20 versus Grey's $6. Both deliver to US bank accounts.

Pesa: $0 visible fee. Cost is in the exchange rate markup. You need to compare the final received amount to know the true cost. Claims instant delivery on some corridors.

Eversend: Fee shown in-app but not published. Supports the Nigeria-to-US corridor. Also offers USDC/USDT stablecoin wallets for users who hold crypto.

Nigerian bank SWIFT: Fees typically 2-5% plus flat charges ($25-$50+). Requires a branch visit and forex desk approval. Takes 3-5 business days. The exchange rate includes a bank margin. The only advantage is that some recipients or institutions may specifically require a wire transfer rather than ACH.

For a full comparison of all apps that support outbound transfers from Nigeria, see how to send money from Nigeria to any country in 2026.

What your recipient sees in the US

Your recipient receives a standard ACH deposit in their US bank account. It appears as a standard domestic deposit. There are no intermediary bank deductions and no additional fee charged to the recipient.

The deposit shows the amount in USD that you confirmed before sending. What you see on the confirmation screen is what your recipient gets. Grey does not route through the SWIFT network, which means there are no correspondent bank fees deducted from the transfer amount.

What to do if the transfer does not arrive

ACH transfers are reliable, but occasionally there are delays. If your recipient has not received the funds after 2 business days, here is what to do.

Check the transfer status in the Grey app. Open the app, go to your transaction history, and check whether the transfer shows as completed, pending, or failed. If it shows as completed, the funds have left Grey and are in the ACH system.

Ask your recipient to check with their bank. Some US banks hold incoming ACH deposits for review, particularly if the account is new or if the deposit amount is unusually large. Your recipient should call their bank and ask whether a deposit is being held.

Contact Grey support. If the transfer shows as completed but your recipient's bank has no record of it, reach out to Grey support with the transaction ID. They can provide the transfer reference details that the recipient's bank can use to trace the deposit.

Also read: Cheapest way to send money from Nigeria in 2026

Frequently asked questions

How much does it cost to send money from Nigeria to the US?

Grey charges a 1% conversion fee capped at the naira equivalent of $6 on major currency pairs. There is no separate payout fee for USD transfers to the US. On a $1,000 transfer, the total cost is $6. On a $500 transfer, the total cost is $5.

How long does it take to send money from Nigeria to a US bank account?

Transfers arrive within 1 to 2 business days via ACH. Weekends and US public holidays are not counted. If you send on a Friday, expect delivery on Monday or Tuesday.

Which US banks does Grey support?

Grey delivers to any US bank account that accepts ACH deposits. This includes Wells Fargo, Bank of America, Chase, Citibank, and all other major US banks and credit unions.

Does my recipient in the US need a Grey account?

No. Your recipient does not need Grey or any other app. The money arrives as a standard ACH deposit in their US bank account. They do not need to take any action to receive it.

Can I send money from Nigeria to a US savings account or only a checking account?

Grey delivers via ACH, which works with both checking and savings accounts in the US. As long as your recipient provides a valid routing number and account number, the deposit will go through regardless of the account type.

What happens if I enter the wrong account number?

If the account number does not match a valid account at the receiving bank, the ACH transfer will be returned to Grey, and the funds will be credited back to your Grey balance. This process can take 3 to 5 business days. If the account number matches a different valid account, the funds may be deposited into the wrong account. Always double-check the routing number and account number before confirming.

Can I send money from Nigeria to the US without going to a bank?

Yes. Grey handles the entire transfer from your phone. You fund your Grey account from your Nigerian bank account, convert to USD, and send to your recipient's US bank details. No branch visit, no SWIFT form, and no forex desk queue.

Is it cheaper to use Grey or a Nigerian bank to send money to the US?

Grey is significantly cheaper for most transfer amounts. A $1,000 transfer costs $6 on Grey versus $25 to $50 or more through a typical Nigerian bank SWIFT transfer. Grey also shows the exchange rate upfront, while banks often apply a less transparent rate with a wider margin.

‍

Related reading

How to send money from Nigeria to any country in 2026 covers the full range of outbound Nigeria options, including which apps work and which do not.

Cheapest way to send money from Nigeria in 2026 compares fees at $500, $1,000, and $2,000 across Grey, Flutterwave Send, Pesa, and Eversend.

Paying US school fees from Nigeria covers how to handle tuition payments specifically, including timing and payment office requirements.

Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion. Grey is a financial technology company, not a bank. Banking services are provided by licensed banking partners. This article is general information, not financial advice.

Wells Fargo routing number: All states listed

•

•

2 min read

A payment is ready to go, but the form asks for one more detail: your Wells Fargo routing number. You know your account number and which Wells Fargo branch you use, but finding the right nine-digit number can be less obvious than expected. And getting it wrong can delay the payment or send you back to the form to start again.

Wells Fargo uses different routing numbers depending on the state where the account was opened. The most commonly used numbers are 121042882 for California ACH, 082900736 for the South, and 121000248 for domestic wire transfers across all states. Always confirm your specific routing number in the Wells Fargo app or by calling the number on the back of your card.

Knowing which Wells Fargo routing number to use matters when setting up direct deposits, receiving ACH payments, or sending a domestic wire. The right number depends on the transaction, so checking before submitting your payment details can help you avoid unnecessary delays.

Also read: How to open a Wells Fargo account from outside the US

Wells Fargo ACH Routing Numbers by state

The Wells Fargo routing number you need depends on the state where your account was opened. While some states share the same number, others have their own ACH routing number. The table below lists the routing numbers provided for each state, including the specific number shown for El Paso, Texas. Before using any of these numbers for a payment or direct deposit, check your Wells Fargo account details to confirm that you have the correct routing number for your transaction.

State ACH Routing Number State ACH Routing Number
Alabama 062000080 Montana 092905278
Alaska 125200057 Nebraska 104000058
Arizona 122105278 Nevada 321270742
Arkansas 111900659 New Hampshire 121042882
California 121042882 New Jersey 021200025
Colorado 102000076 New Mexico 107002192
Connecticut 021101108 New York 026012881
Delaware 031100869 North Carolina 053000219
Florida 063107513 North Dakota 091300010
Georgia 061000227 Ohio 041215537
Hawaii 121042882 Oklahoma 121042882
Idaho 124103799 Oregon 123006800
Illinois 071101307 Pennsylvania 031000503
Indiana 074900275 Rhode Island 121042882
Iowa 073000228 South Carolina 053207766
Kansas 101089292 South Dakota 091400046
Kentucky 121042882 Tennessee 064003768
Louisiana 121042882 Texas 111900659 (El Paso: 112000066)
Maine 121042882 Utah 124002971
Maryland 055003201 Vermont 121042882
Massachusetts 121042882 Virginia 051400549
Michigan 091101455 Washington 125008547
Minnesota 091000019 West Virginia 121042882
Mississippi 062203751 Wisconsin 075911988
Missouri 113105449 Wyoming 102301092

Wells Fargo wire transfer Routing number

When you send a domestic wire transfer from your Wells Fargo account, you use a single nationwide routing number rather than a state-specific number. The routing number for domestic wires is 121000248, so you do not need to search for a different number based on where your account was opened.

For an international inbound wire, you will need the Wells Fargo SWIFT code instead. The primary SWIFT code is WFBNDDNYXXXX, which helps identify Wells Fargo when money is being sent internationally. Understanding the difference between a SWIFT code and a routing number becomes important here because each one identifies your bank for a different type of payment.

The same distinction helps when looking at ACH vs wire transfers. ACH payments move through delayed electronic batches using state-specific regional clearinghouses, while wire transfers are processed individually in real time. When you send a wire, the transaction is settled directly through the Federal Reserve system rather than waiting for an ACH batch. That difference in processing is why the correct routing or SWIFT details matter when sending money to your Wells Fargo account.

Where to find your Wells Fargo routing number

Finding your Wells Fargo routing number is usually straightforward, and the quickest method depends on whether you have access to the mobile app, a cheque or online banking.

Check the Wells Fargo mobile app

Open the Wells Fargo app and sign in to your account. Select the account you need, then look for Account Details. Your routing number should appear alongside your account number and other account information.

Look at a Wells Fargo cheque

A Wells Fargo cheque also shows the routing number. Turn the cheque over to the bottom-left section of the front. The first nine-digit number in the sequence is the routing number, followed by your account number and cheque number.

Find it through Wells Fargo online banking

Sign in through the Wells Fargo website and select the relevant account. Open the account details or information section to view the routing number associated with that account. Make sure you are checking the correct account before sharing the details.

Need a USD account without Wells Fargo?

Getting paid by a US client can become frustrating when the payment requires US banking details that you do not have. Opening a traditional US bank account may not be practical either, especially when you live abroad and do not have a US residential address or the documents a local bank expects.

Grey gives eligible users access to USD account details that can be used to receive supported ACH and wire transfers, without requiring a US residential address. So when a client or employer asks for US banking details, you can provide the relevant information without opening a traditional Wells Fargo account.

Once your account is approved, the USD account details are available digitally, giving you a simpler way to receive eligible payments and manage the money online. Sign up for Grey or download the app to get started.

Frequently asked questions about Wells Fargo routing numbers

What is Wells Fargo's routing number for direct deposit?

The routing number for Wells Fargo direct deposit depends on the type of account and payment. Unlike domestic wire transfers, direct deposits use the ACH routing number associated with your account. Check your Wells Fargo account details or cheque rather than assuming the wire routing number applies.

Is the Wells Fargo ACH number different from the wire number?

Yes. ACH payments and domestic wire transfers can use different routing numbers. Wells Fargo uses 121000248 for domestic wire transfers, while your ACH routing number may differ. Checking the payment instructions before sending or receiving money helps ensure the transaction reaches the correct account without unnecessary delays.

Does Wells Fargo have one routing number for all states?

Wells Fargo uses a single routing number for domestic wire transfers nationwide: 121000248. However, ACH routing numbers can vary depending on where your account was opened. That means the answer depends on the type of payment you are making and the specific Wells Fargo account involved.

Where is the routing number on a Wells Fargo cheque?

Your Wells Fargo routing number appears along the bottom of the cheque. It is the first nine-digit number in the sequence, followed by your account number and cheque number. Looking at the bottom-left corner of the cheque makes it easy to identify the routing number quickly.

Can I use my Wells Fargo routing number for international transfers?

A routing number alone is generally not enough for an international wire transfer. International payments usually require Wells Fargo’s SWIFT code, along with your account details. For inbound international wires, Wells Fargo’s primary SWIFT code is WFBNDDNYXXXX, while domestic wires use the routing number.

Virtual Dollar Cards in the UAE: How to Get One

•

•

2 min read

A virtual dollar card can make international spending easier, especially when your regular UAE card is not the most convenient option for dollar payments. Instead of carrying a physical card, you get digital card details that can be used for eligible online purchases, subscriptions, advertising platforms and international shopping. Some providers link the card directly to a USD balance, while others convert your funds when you make a payment.

For UAE residents looking for a virtual dollar card UAE option, the important thing is not simply whether the card is available. You should also check how you fund it, the exchange rate, card issuance fees, transaction limits and where the card can be used. Some providers offer USD cards linked to multi-currency balances, while others require specific funding methods.

This guide explains how to get a virtual dollar card in the UAE, what you can use it for, and the costs to check before signing up.

Also read: 7 best virtual cards in the UK (2026)

What is a virtual dollar card?

In simple terms, a virtual dollar card is a digital payment card designed for online transactions in US dollars. It gives you card details such as a number, expiry date and security code, but there is no physical card to carry. You can use it for eligible subscriptions, online services, advertising and international purchases.

The key difference for UAE residents is the currency behind the payment. Most local UAE cards are connected to AED accounts, meaning a purchase priced in USD may require the bank to convert your dirhams into dollars before the payment goes through. The provider may also add a foreign transaction fee or exchange-rate markup.

USD billing can be more convenient when most of your online expenses are priced in dollars. With a virtual dollar card linked to a USD balance, you can pay in the same currency rather than converting AED for every transaction. This can make international spending easier to track and manage.

It also helps to understand what a virtual wallet is and how it stores balances separately from your bank card. You can also compare virtual and physical card use cases to decide whether you only need card details for online USD payments or you also want a physical card later.

How to get a virtual dollar card in the UAE

Getting a virtual dollar card in the UAE does not usually require opening a US bank account. The main requirement is finding a provider that accepts UAE customers and can give you access to a USD balance for online payments. From there, the process is fairly simple, although each provider has its own verification and funding requirements.

After choosing a provider, create an account and complete the identity checks. This may involve providing your personal details and a government-issued ID. Once your account has been approved, the next step is getting money into it. If your funds are in AED or another currency, you may need to convert them to USD before using the card. Check the exchange rate and any funding or conversion fees at this stage.

Once the USD balance is ready, you can generate the virtual card from the provider’s app or online account. Your card details can then be used for eligible USD payments, such as subscriptions, software, advertising and international shopping.

Grey also offers a virtual Visa card for eligible customers, combining international card payments with access to supported currency balances. Availability and requirements depend on the country where you live, so UAE residents should check the latest eligibility before signing up.

Also read: Debit card vs Credit card: What is the difference?

What can you use a virtual dollar card for?

A virtual dollar card can cover many everyday international payments, particularly when the merchant charges in USD.

  • Subscriptions: Pay for streaming services, software, cloud storage, AI tools and other subscriptions that bill in US dollars. Using a card designed for USD payments can make recurring charges easier to manage.
  • Online advertising: Businesses, freelancers and creators can use virtual dollar cards to pay for advertising on platforms that accept international cards, including campaigns billed in USD.
  • Online shopping: Use the card for purchases on international websites that accept Visa or Mastercard. It can be useful when a local UAE card creates additional conversion costs or payment restrictions.
  • Travel: A virtual dollar card can also help with travel-related online payments, such as booking flights, hotels, transport and other services priced in USD. However, check the provider's country restrictions and card acceptance before relying on it while travelling.

Fees and limits to check before choosing a virtual dollar card

The real cost can appear when you fund the card, convert currencies, or reach a spending limit. Checking these charges before signing up can help you avoid unpleasant surprises later.

  • Issuance fee: Some providers charge a one-off fee when you create a virtual dollar card, while others offer card creation for free. Check this before opening an account.
  • Funding fees: Adding money may attract a fixed fee or percentage charge, depending on how you fund the card. Compare the available funding methods and their costs.
  • FX fees: Converting AED or another currency into USD can involve an exchange-rate markup or separate conversion fee. Check the rate you receive, especially when funding larger amounts.
  • Spending limits: Virtual dollar cards may have daily, monthly or per-transaction spending limits. Make sure the limits are high enough for your subscriptions, advertising payments, shopping and other regular expenses.

With Grey, you can open an account, create a virtual Mastercard, and use it for eligible dollar payments like subscriptions and online services, all from one place.

Frequently asked questions

Can I get a dollar card in the UAE?

Yes, UAE residents can access USD-denominated virtual cards, although eligibility depends on the provider. Some UAE-based services offer virtual cards linked to your account, while international providers may have separate residency requirements. Always check the provider’s current UAE availability, verification requirements, and regulatory status before signing up.

How do I fund a virtual dollar card?

Funding depends on the provider. You may be able to transfer money from a bank account, add funds through a supported payment method or fund the card from an existing USD wallet. Some providers only allow specific funding sources, so check the available options and any conversion or funding fees first.

Is a virtual dollar card safe?

A virtual card can add protection by keeping your main bank card details separate from online payments. However, safety also depends on the provider’s security controls, regulations, and how you protect your account. Choose a reputable provider, enable available security features and never share your card details or login information.

Can I use a virtual dollar card for subscriptions?

Yes, many virtual dollar cards are designed for online payments such as streaming services, software, advertising platforms and other subscriptions billed in USD. Before subscribing, check that the merchant accepts your card network and that the provider supports recurring payments.

Can I use a virtual dollar card outside the UAE?

You can often use a virtual dollar card for international online payments, but acceptance depends on the card network, provider restrictions and the merchant. Check supported countries and transaction limits before relying on the card for important payments abroad.

Arrow (up)

Back to top
