A guide for Filipinos getting paid by clients overseas
Tunde Aladeloba
TABLE OF CONTENT
SHARE THIS POST
Working with clients abroad is a huge opportunity for Filipinos. Suddenly, your skills or services are in demand worldwide, and your work is being appreciated far beyond local borders. But along with the excitement comes a real challenge: getting your money safely and efficiently. You don’t have to travel or open foreign accounts to receive payments, you just need the right tools and know-how.
Whether you’re freelancing, consulting, or providing digital services, this guide will help you navigate international payments, track your earnings, and make sure your hard work pays off here in the Philippines.
If you want to work with clients abroad, it helps to know what they actually pay for. Knowing these makes it easier for you to find good projects and get paid fairly.
1. Freelance work
Overseas clients pay you for freelance work because they need your skills without hiring full-time. Whether it’s writing, design, or programming, your expertise is valuable globally. You set your rates, choose your projects, and work on your own schedule. For Filipinos, freelancing internationally opens doors to higher earnings and experience beyond local opportunities.
2. Remote employment
Remote employment lets you work for foreign companies while staying in the Philippines. You get a steady salary, benefits, and global experience without relocating. Companies hire you because you bring unique skills or perspectives, and working remotely gives you flexibility while still earning international rates. It’s a practical way to expand your career horizons from home.
3. Online consulting
Clients abroad pay for your expertise. Whether you’re advising on business strategies, marketing campaigns, or tech solutions, your knowledge solves real problems. A Filipino consultant might host online workshops for startups in Singapore or provide strategy sessions for a UK company. Consulting lets you turn what you know into high-value services, all from your home in the Philippines, while charging competitive international rates.
4. Digital products
Digital products can earn money while you sleep. You could sell an ebook on Filipino cuisine to readers abroad, create online courses teaching local crafts, or design templates for global entrepreneurs. Once your product is live, it can keep generating income without extra effort. For Filipinos, this is a way to share skills and creativity worldwide, earn in stronger currencies, and diversify income streams.
5. Creator work
Overseas clients pay for content you create; videos, graphics, music, or social media campaigns. Your creativity becomes a service that crosses borders. As a Filipino, you can leverage platforms or direct contracts to get international exposure and higher earnings. It’s not just about sharing your talent; it’s about building a global portfolio and earning in foreign currencies.
Essential tips for Filipinos to get paid from abroad
Working with clients overseas is exciting, but getting your money safely is another story. Before your earnings reach your bank, there are a few essentials you’ll need to make the process smooth, professional, and stress-free.
1. A contract
A contract protects you and your client. It clearly states what you’ll deliver, the payment terms, deadlines, and other expectations. For Filipinos, having a written agreement ensures everyone is on the same page and prevents confusion. Even a simple digital contract sent via email can save you headaches and make your work appear professional.
What to include in a contract:
Scope of work: what you will deliver and what’s excluded
Payment terms: rates, currency, and schedule
Deadlines: milestones and final delivery dates
Dispute resolution: how issues will be handled
2. Invoice
An invoice is how you officially request payment. It should include your services, the amount due, the due date, and payment details. For Filipinos working internationally, a well-formatted invoice adds credibility and speeds up payment. Tools like Google Docs, Canva, or invoicing software can make this process easy and polished.
What to include in an invoice:
Your full name or business name and contact info
Client’s name and contact details
Description of services, quantity, and price
Payment details: currency, bank account, or payment link
3. Clear communication
Never underestimate the power of clear communication. Confirm project scope, deadlines, and payment expectations with your client before starting. For Filipinos working remotely, keeping open lines via email, WhatsApp, or Zoom builds trust and reduces delays. Clear communication ensures you get paid on time and helps maintain long-term international relationships.
Tips for clear communication:
Confirm project scope and expectations upfront
Set and agree on deadlines together
Choose preferred channels (email, WhatsApp, Zoom)
4. Payment solution
You need a reliable way to receive money from abroad. Options include PayPal, Wise, Revolut, Payoneer, or Grey. The right solution makes transfers fast, secure, and cost-effective. For Filipinos, choosing the right platform means avoiding unnecessary fees, receiving payments in stronger currencies, and getting access to funds without hassle.
How to set up your payment solution:
Choose a trusted platform suitable for your work type
Set up accounts in required currencies (USD, EUR, GBP)
Link your local bank account for easy withdrawals
LDMAG1
Manage global payments with Grey
Getting paid with Grey makes receiving international payments simple and stress-free. As a Filipino working with clients abroad, you can hold multiple currencies like USD, EUR, or GBP, enjoy low fees, and access competitive exchange rates. Whether you’re freelancing, consulting, or selling digital products, Grey helps you manage your earnings professionally.
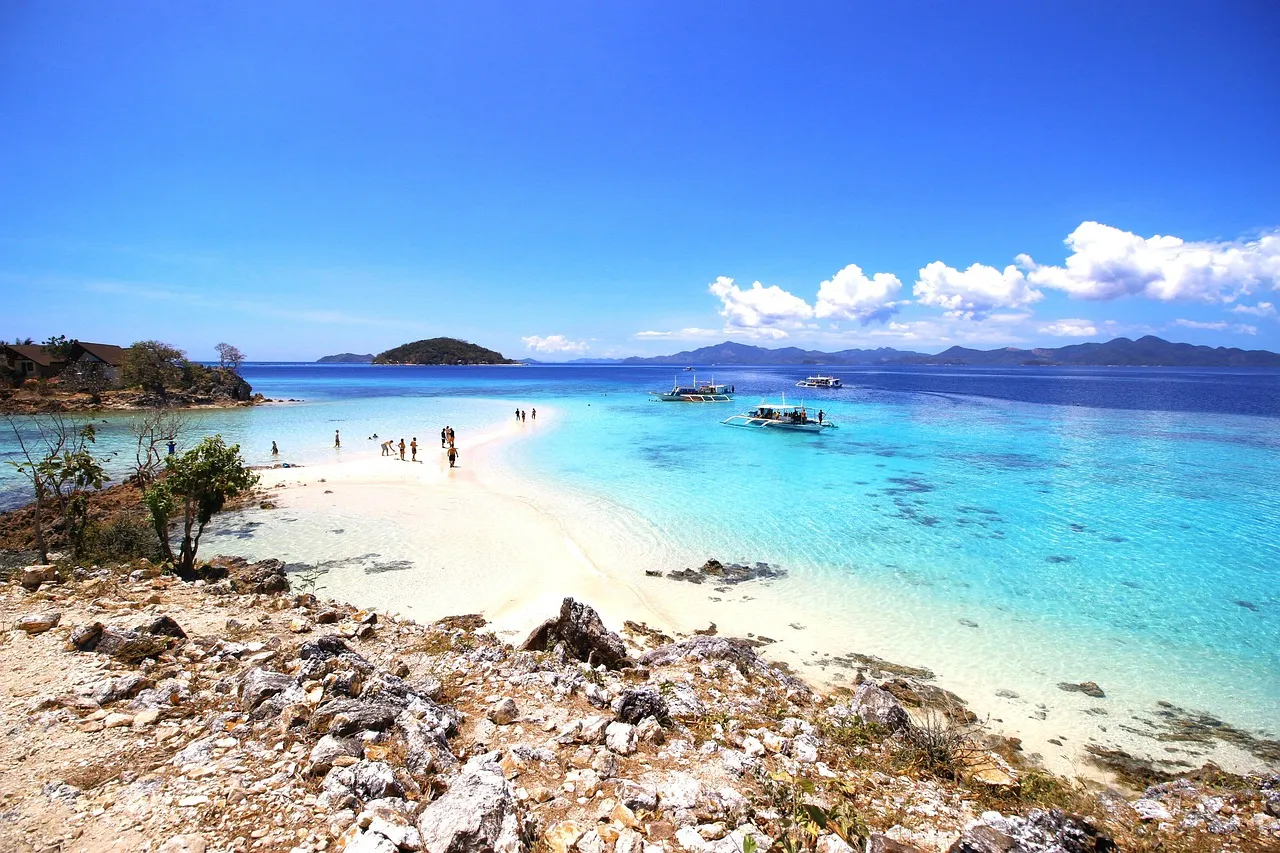
Have you ever dreamed of escaping to a place where turquoise waters meet powdery white sand, where lush mountains rise in the distance, and every sunset looks like it was painted just for you? That’s the Philippines, a country made up of more than 7,600 islands, each with its own charm. Every time I visit, I find something new to fall in love with.
Whether you’re craving adventure, a quiet beach retreat, or a deep dive into rich cultural experiences, the Philippines has something for you. And let’s not forget the warm hospitality — Filipinos are known for their friendliness, making visitors feel right at home from the moment they arrive.
If you’re thinking about a summer holiday in the Philippines, here are some of the best places to visit that will make your trip unforgettable.
Best places to visit in the Philippines for summer holidays
From world-famous beaches to hidden gems, here are some of my top must-visit places for an unforgettable summer escape:
1. Boracay – The island of white sand beaches
Boracay is one of those places that feels like a postcard come to life. The powdery white sand is so soft it almost feels unreal, and the sunsets? Absolutely breathtaking. White Beach is where most of the action happens, but depending on what you’re in the mood for, you can pick your vibe:
Station 1 – Home to upscale resorts and the widest stretch of fine white sand, ideal for a quieter and more luxurious experience.
Station 2 – The heart of Boracay’s action, where shopping, restaurants, and nightlife come to life.
Station 3 – A more peaceful area with budget-friendly accommodations and a laid-back vibe.
Beyond White Beach, you will love spending time at Puka Shell Beach for a quieter escape, Bulabog Beach for kitesurfing, and Diniwid Beach for a cosy sunset spot away from the crowds.
Must-do experiences in Boracay:
Try parasailing, snorkelling, or paddleboarding in the turquoise waters.
Take a sunset paraw (local sailboat) ride — it’s pure magic.
If you’re feeling adventurous, go cliff diving at Ariel’s Point.
Experience Boracay’s nightlife, where fire dancers and beachside cocktails set the mood.
2. Palawan – A paradise of lagoons and limestone cliffs
If you ask me about my happy place, it’s Palawan. It’s where you find those impossibly blue lagoons, towering limestone cliffs, and hidden beaches straight out of a travel magazine. Every corner of Palawan feels untouched and breathtaking.
Here’s where you should go:
El Nido – Stunning lagoons, dramatic cliffs, and secret beaches. Island hopping here is a must.
Coron – A diver’s paradise with crystal-clear lakes and World War II shipwrecks.
Puerto Princesa – Home to the Puerto Princesa Underground River, one of the New Seven Wonders of Nature.
Port Barton – A quieter, more relaxed alternative to El Nido, with incredible island-hopping adventures.
What makes Palawan special?
Snorkelling in coral-filled waters and swimming alongside sea turtles.
Kayaking through hidden lagoons and mangroves.
Exploring remote islands where you’ll feel like the only person in the world.
Watching the sunset from a secluded beach, surrounded by nothing but nature.
3. Cebu – A mix of history and adventure
Cebu has it all — history, adventure, and some of the best beaches in the Philippines. One day, you could be exploring Spanish-era churches, and the next, swimming with whale sharks or chasing waterfalls.
Places you can’t miss in Cebu:
Cebu City – Visit Magellan’s Cross, the Basilica Minore del Santo Niño, and the Taoist Temple.
Oslob – Swim with the gentle giants — whale sharks (don’t worry, it’s safe).
Moalboal – Witness the incredible sardine run and dive into a world of colourful corals.
Kawasan Falls – Go canyoneering through turquoise waterfalls and jungle trails.
Bantayan & Malapascua Islands – Tranquil, beautiful, and perfect for escaping the crowds.
If you love food, don’t leave Cebu without trying lechon (roast pig) and the famous dried mangoes.
Siargao is my ultimate chill-out spot. It’s known as the surfing capital of the Philippines, but even if you don’t surf, you’ll fall in love with its island vibes. Palm trees line the roads, fresh coconut stalls are everywhere, and life moves at a slow, blissful pace.
Siargao highlights:
Cloud 9 – The world-famous surf break, even if you’re just there to watch.
Sugba Lagoon – Perfect for paddleboarding and kayaking in emerald-green waters.
Magpupungko Rock Pools – Crystal-clear tidal pools that appear during low tide.
Island hopping – Naked Island, Daku Island, and Guyam Island are must-visits.
Sohoton Cove – Swim with stingless jellyfish in a magical lagoon.
Why Siargao stole my heart:
The sunrises and sunsets here are something else.
The food scene is incredible — smoothie bowls, fresh seafood, and local delicacies.
Riding a motorbike around the island is the best way to explore hidden beaches.
The island’s laid-back energy makes it impossible to leave.
5. Bohol – Home to the Chocolate Hills
Bohol is one of those destinations that surprises you. It has one of the most unique landscapes in the world — the Chocolate Hills — but that’s just the beginning.
Must-see places in Bohol:
Chocolate Hills – Over 1,200 perfectly rounded hills that turn brown in the dry season.
Tarsier Conservation Area – Get up close (but not too close!) to the adorable, wide-eyed tarsiers.
Loboc River Cruise – Enjoy a peaceful lunch while floating down a jungle river.
Panglao Island – White-sand beaches, world-class diving, and snorkelling with sea turtles.
Hinagdanan Cave – An underground lagoon where sunlight creates a magical glow.
Bohol is for you if:
You love nature and wildlife.
You want a mix of adventure, culture, and relaxation.
You enjoy exploring places that feel untouched by mass tourism.
The best way to manage payments while travelling to the Philippines
One thing I’ve learned while travelling is that managing money can be tricky, especially when dealing with currency exchange and international transactions. That’s where Grey makes life easier — you can send, receive, and exchange money in multiple currencies without the crazy fees traditional banks charge. It’s a game-changer when you’re travelling.
Make your summer travel to the Philippines stress-free with Grey
So, if the Philippines is on your summer bucket list (which it absolutely should be!), get ready for the adventure of a lifetime. Pack your bags, explore these incredible destinations, and let Grey handle your international payments seamlessly.
Brazil is a country of vibrant culture, stunning landscapes, and diverse ecosystems. Imagine a place where the Amazon Rainforest breathes life into the planet, producing 20% of the world’s oxygen, while samba rhythms pulse through the streets of Rio. From golden beaches and lush rainforests to lively cities and historic towns, the nation offers something for every traveller. Brazil is the perfect summer getaway if you’re looking for adventure, relaxation, or cultural experiences.
Must-visit destinations in Brazil for summer vacation
With so much to explore, narrowing down my must-visit destinations in Brazil was no easy task. But if you’re planning a trip, these are the places that left me in awe.
1. Rio de Janeiro – A city of breathtaking views and beaches
Rio de Janeiro is pure magic. It’s one of those places that just takes your breath away, whether you’re gazing up at Christ the Redeemer or sinking your toes into the golden sands of Copacabana. The city is vibrant, energetic, and full of contrasts—one moment, you’re hiking through a rainforest, and the next, you’re sipping a caipirinha by the beach.
Must-do experiences in Rio:
Take the cable car up to Sugarloaf Mountain for panoramic coastline views.
Stroll along Ipanema Beach, where the scenery is as beautiful as the people.
Explore the historic streets of Santa Teresa, filled with colourful street art and lively samba bars.
Hike through Tijuca National Park, the largest urban rainforest in the world.
Experience the electric energy of Lapa, where music and dancing never stop.
2. The Amazon Rainforest – A journey into the wild
Stepping into the Amazon felt like entering another world. The sheer scale of it is overwhelming—lush greenery stretching endlessly, rivers teeming with life, and the sounds of nature creating an orchestra all around you. It’s a place where adventure is guaranteed.
Unmissable experiences in the Amazon:
Visit Manaus, the gateway to the rainforest, and explore its bustling markets.
Witness the “Meeting of the Waters”, where two rivers flow side by side without mixing.
Go on a wildlife-spotting tour to see pink river dolphins, macaws, and even jaguars.
Stay in a jungle lodge and wake up to the calls of exotic birds.
Learn about indigenous cultures and their deep connection to the forest.
3. Salvador – The heart of Afro-Brazilian culture
Salvador is a city that dances to its own rhythm. Every street bursts with history, from the colonial architecture of Pelourinho to the powerful beats of drum circles in the squares. The mix of African, Portuguese, and indigenous influences creates a culture unlike any other.
Why I love Salvador:
Wandering through Pelourinho, a UNESCO-listed district with colourful buildings and cobbled streets.
Watching the sunset from Elevador Lacerda, overlooking the stunning bay.
Tasting Bahian delicacies like acarajé and moqueca — absolute flavour explosions.
Relaxing at Praia do Forte, a gorgeous beach town with sea turtle conservation projects.
Experiencing Carnival in Salvador, where the energy is unmatched.
4. Florianópolis – Island paradise for beach lovers
Florianópolis, or “Floripa” as the locals call it, is a slice of heaven. It’s a place where you can find a beach for every mood—whether you want to surf, relax, or go on an adventure. The island has a laid-back charm that makes it easy to lose track of time.
Floripa highlights:
Surfing at Joaquina Beach, one of Brazil’s top surf spots.
Kayaking and dining by the water at Lagoa da Conceição.
Taking a boat trip to Campeche Island, home to crystal-clear waters and ancient rock carvings.
Hiking to hidden beaches with breathtaking views.
Indulging in the freshest oysters and seafood—you won’t find better.
5. Pantanal – The world’s largest tropical wetland
For wildlife lovers, the Pantanal is paradise. It’s one of the best places on Earth to see animals in their natural habitat, from jaguars prowling the banks to flocks of vibrant birds soaring overhead. Unlike the dense Amazon, the open landscapes here make spotting wildlife an unforgettable experience.
Why I would highly recommend you to visit the Pantanal:
Going on a jaguar safari, where you have a high chance of spotting these elusive big cats.
Birdwatching and spotting the iconic hyacinth macaw.
Exploring the wetlands on horseback, just like the pantaneiros (local cowboys).
Embarking on a night safari to see nocturnal creatures like anteaters and tapirs.
Trying your hand at piranha fishing — yes, really!
Managing your money while travelling in Brazil
If there’s one travel lesson I’ve learned, it’s that managing money abroad can be trickier than expected — especially when juggling different currencies. With Grey, you can easily send, receive, and exchange money internationally without the high fees of traditional banks. Whether you’re booking a tour, paying for a beachside meal, or splitting costs with friends, Grey keeps it simple.
Brazil is a country that stays with you long after you’ve left. The landscapes, the people, the culture — everything about it makes you want to return. If you’re dreaming of an unforgettable summer trip, start planning now. Make the most of your trip by planning ahead and managing your finances efficiently with Grey.
Sending money abroad has become a vital aspect of both personal and business transactions. With the advancement of technology, traditional methods like SWIFT have been challenged by more modern alternatives, such as USDC. In this article, we’ll explore the differences between USDC and SWIFT, why you should consider USDC for international payments, and how to convert payments to USDC using Grey.
USDC: Transactions are processed almost instantly, taking just minutes to complete.
SWIFT: Payments can take anywhere from 1-5 business days to clear, depending on the banks involved.
Transaction fees
USDC: Low transaction fees, often just a small network fee, making it an affordable option for sending money.
SWIFT: High fees, including intermediary bank charges, conversion fees, and the receiving bank’s fees.
Accessibility
USDC: Accessible to anyone with a cryptocurrency wallet, enabling easy transfers without needing a bank account.
SWIFT: Requires both the sender and receiver to have bank accounts, often limiting accessibility for non-bank users.
Currency conversion
USDC: Since USDC is pegged to the US dollar, there’s no need for currency conversion when transferring between USD and USDC.
SWIFT: Currency conversions are often involved, especially if the sending and receiving countries use different currencies, leading to additional costs and exchange rate risks.
Why you should choose USDC for foreign payments
Faster transactions: With USDC, money is transferred instantly, making it ideal for urgent payments and business transactions. No waiting for days like with SWIFT.
Lower fees: The cost of sending USDC is significantly lower than traditional SWIFT payments, which can incur high transfer and currency conversion fees.
Global reach: USDC allows you to send money to anyone, anywhere in the world, without the need for bank intermediaries. This opens up opportunities for people in countries with limited access to banking.
Enhanced security: USDC transactions are secured by blockchain technology, providing transparency and reducing the risks associated with traditional bank transfers, like fraud and chargebacks.
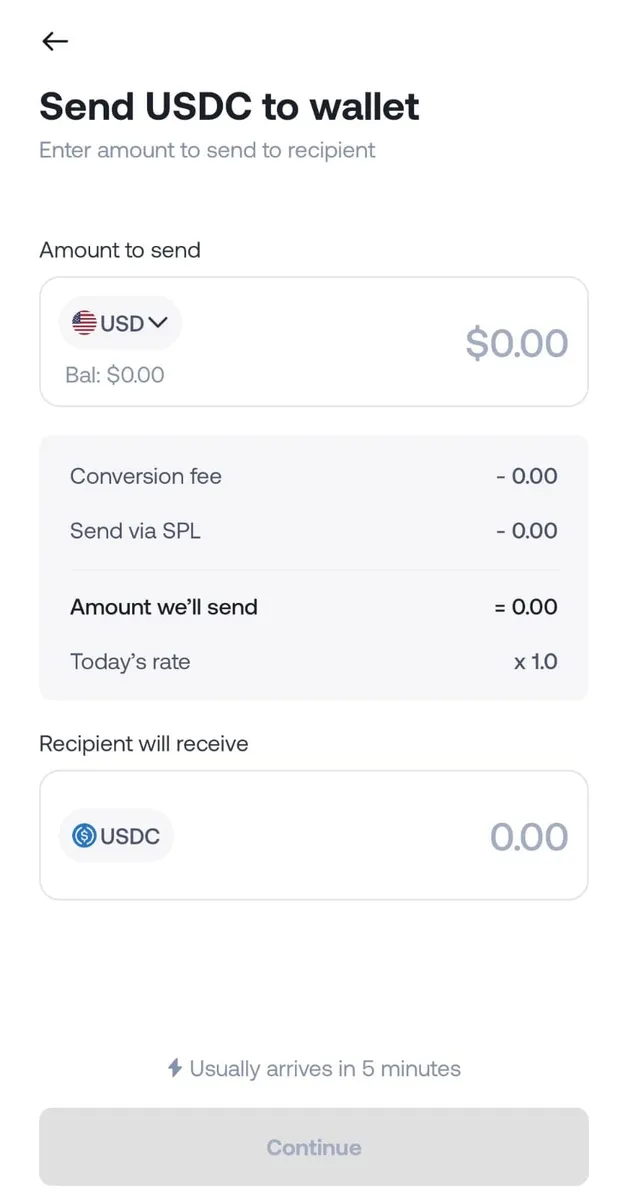
Grey makes sending and receiving USDC payments easy and fast. Convert traditional foreign payments to USDC in seconds, whether for paying suppliers, receiving client funds, or sending money to loved ones. With minimal fees and instant transfers, Grey offers a seamless, secure, and cost-effective solution for international payments. Sign up for free and choose USDC with Grey for efficient global transactions.
Best virtual Mastercards for online payments in Egypt
In October 2023, the Central Bank of Egypt announced that Egyptians could no longer use their debit cards for international payments. The move, intended to preserve the country’s dwindling USD reserves, left millions cut off from the global economy. Practically overnight, Egyptians couldn’t make international payments, and even simple subscriptions like Spotify, Netflix, or paying tuition fees abroad became inaccessible.
To date, many Egyptian bank cards remain unreliable for international transactions, particularly on USD-billed platforms. Some cards work intermittently. Others require pre-approval for each international transaction. Some platforms block Egyptian-issued cards entirely, regardless of whether the cardholder has sufficient funds.
The practical solution for Egyptian freelancers, students, remote workers, and anyone who regularly pays for international tools and subscriptions is a virtual Mastercard issued outside Egypt’s banking system, denominated in USD, and not subject to the Central Bank of Egypt’s domestic restrictions.
This article covers how virtual Mastercards work in Egypt, why Egyptian bank cards fail on international platforms, and how the five best options compare on fees, funding methods, and functionality in 2026.
Why Egyptian bank cards fail on international platforms
Understanding the problem clarifies what to look for in a solution. There are three specific reasons Egyptian bank cards get declined on international platforms.
The Central Bank restriction
The Central Bank of Egypt’s 2023 restriction on international debit card use was intended to preserve the country’s USD reserves. While some restrictions have been partially relaxed since then, many Egyptian banks still block international payments on standard debit accounts. The specific rules vary by bank and account type, creating an unpredictable experience where the same card works on one platform but not another.
The currency denomination problem
Egyptian bank cards are denominated in EGP. When you use the card on a USD-billed platform, it attempts a real-time conversion at the bank’s commercial rate. Many international platforms specifically require a USD-denominated card for billing verification, particularly for subscription services, cloud platforms, and advertising systems. A card that technically supports international transactions can still be declined if the platform’s billing system requires a USD-issued card rather than an EGP card attempting a conversion.
The platform-level blocking problem
Most local debit cards issued by Egyptian banks don’t work for international transactions, especially if the merchant charges in a foreign currency like USD. Some platforms detect Egyptian-issued cards and apply additional restrictions, regardless of the cardholder’s bank settings. A virtual card from a non-Egyptian provider bypasses this entirely.
A virtual USD card solves all three problems simultaneously. It is denominated in USD, issued outside Egypt’s banking system, and funded from a foreign currency balance rather than converted from EGP at the point of transaction.
What to look for in a virtual Mastercard for Egypt
Not all virtual cards provide the same functionality. Before choosing a provider, four things are worth evaluating.
Funding method: How do you load money onto the card? Options include EGP bank transfer (converted to USD on loading), USDT crypto deposit, foreign currency transfer from an international account, or a linked multi-currency balance. The funding method determines your access: if you have a foreign currency income source, a card linked to that balance is most efficient. If your primary funds are in EGP, a card that accepts local currency top-ups matters more.
Transaction fee structure: The visible card creation fee is rarely the largest cost. Transaction fees (percentage per purchase), foreign currency conversion fees (for non-USD charges on a USD card), and monthly maintenance fees are where ongoing costs accumulate. Calculate total annual cost based on your actual spending patterns, not just the upfront fee.
International platform compatibility: Not all virtual cards work on all platforms. Verify that the specific platforms you use, whether AWS, Google Ads, Netflix, Shopify, or others, accept the card before committing.
Multi-currency account: A card linked only to a prepaid USD balance is useful for spending. A card linked to a full multi-currency account, where you can receive international income in USD, EUR, and GBP and pay directly from those balances, is meaningfully more functional for Egyptian freelancers and remote workers who earn internationally.
The five best virtual cards for online payments in Egypt
Card-Y
Card-Y was founded specifically in response to the Central Bank of Egypt’s 2023 international payment restriction. Its founder identified the gap and built a solution for Egyptian users to reconnect with the global economy.
Card-Y allows users to top up in Egyptian Pounds, which are instantly converted to USD balances, with instant issuance and funding. From registration to the first online purchase takes less than 20 minutes.
Card issuance fee: $20 USD, valid for one year, not added to the card balance as spending credit. Transaction fee: 1% per transaction, minimum $1, maximum $5. Renewal fee after first year: $5 per year. Monthly spending limit: $10,000 USD.
Card-Y also provides virtual USD and EUR bank accounts through its partner Bridge, with a 5% deposit fee on incoming international transfers.
Best for: Egyptian users who primarily hold EGP and want the fastest local-currency-to-USD card setup, and who make regular transactions above $100 where the 1% fee is proportionally manageable.
Limitation: the $20 issuance fee is not added to the card balance, meaning it’s a pure setup cost. The exchange rate from EGP to USD at the point of funding has been flagged as a concern by some reviewers.
EverTry
EverTry offers a virtual USD card for Egyptian users that can be funded via local currency and USDT, making it accessible to users comfortable with crypto. It works on a wide range of international platforms, including Netflix, Spotify, AWS, DigitalOcean, Namecheap, Facebook Ads, and Google Ads. Card creation costs $2.50 with no monthly maintenance fee.
The $2.50 creation fee is the lowest of the options compared. Funding via USDT makes it fast and convenient for crypto-friendly users. For users without crypto access, the local currency funding option is available.
Best for: crypto-comfortable Egyptian users who want the lowest upfront creation fee and primarily need a card for a specific set of international platforms.
Limitation: the platform is less well-known than Grey or Card-Y, with a smaller user base and less established track record. Verify current platform availability and fee structure at EverTry’s official site before applying.
AstroPay
For Egyptian users, AstroPay works as a prepaid spending tool. You load funds onto your wallet using a local payment method, then use the virtual card for international purchases on platforms that accept Visa or Mastercard. Card details are issued instantly through the app, and the platform supports one-time or multi-use cards. Bank withdrawals from AstroPay can attract fees of up to 6%, depending on the institution. The FX markup is 1% to 3% on non-native currency transactions. Transaction fees run 2 to 5% depending on the payment method used.
AstroPay’s strengths are its prepaid model and recognition on major international platforms. It is widely accepted and doesn’t require a full account setup with the same KYC depth as Grey or Card-Y.
Best for: one-off international purchases or users who want a prepaid card without a full account relationship.
Limitation: the combination of transaction fees (2 to 5%) and FX markup (1 to 3%) makes it among the more expensive options for regular or high-volume spending. Bank withdrawals are up to 6% make it unsuitable as a primary income account.
Fyatu
Fyatu provides instant virtual Mastercards that support multiple currencies, ideal for global payments and managing online subscriptions. Onboarding is digital, and card issuance is immediate. Fyatu is primarily a spending card rather than a full multi-currency account with receiving capability.
Best for: users who need a straightforward multi-currency spending card with instant issuance for managing international subscriptions.
Grey
Unlike the others on the list, Grey provides a virtual USD Visa card rather than a Mastercard. It launched its upgraded virtual card in January 2026, adding support for Apple Pay and Google Pay. The card costs $5 and works at 150 million merchants worldwide. The upgraded Grey card comes with 3D Secure protection, requiring users to approve each transaction before it completes, and the ability to create multiple cards for different purposes, such as separating business expenses from personal spending.
The Grey virtual USD card is linked to a full multi-currency account. Egyptian users receive USD, EUR, and GBP account details along with local banking information, allowing international clients to pay directly into the Grey account via ACH, SEPA, or Faster Payments. The card draws from the USD balance in that account.
If the platform charges in USD (the same currency as the card), there is no additional fee beyond what you paid to fund the card. If the platform charges in a different currency, a cross-border fee of 2% plus $0.50 per transaction applies.
Creation fee: $5 one-time, no monthly fee. Deposit fee via ACH/SEPA/FPS: 0.8%, capped at $10/€10/£10. Conversion: 1%, capped at $6.
Grey is regulated by FINTRAC and FinCEN.
Best for: Egyptian freelancers and remote workers who earn internationally and want a virtual card linked to a full multi-currency account, with Apple Pay and Google Pay support.
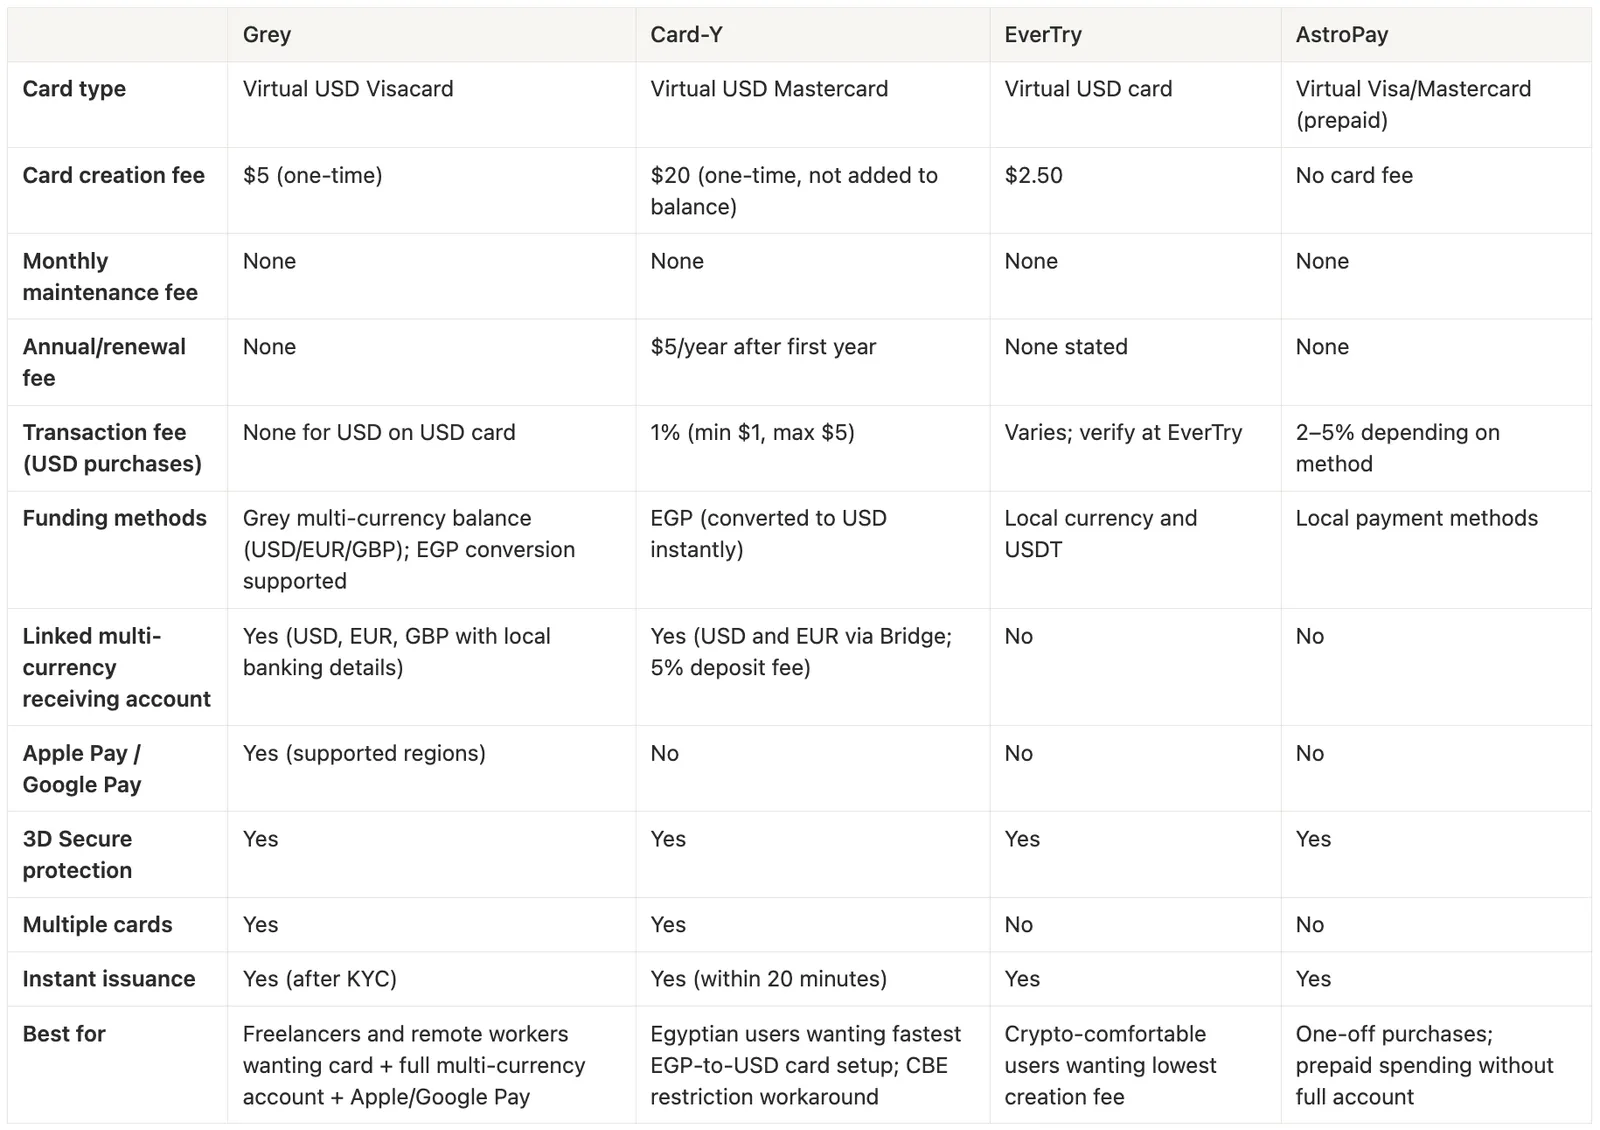
Comparison table: best virtual cards for online payments in Egypt
All fee figures verified against published platform data as of May 2026. Rates and features are subject to change; verify with each provider before applying.
How does the Grey virtual card work in practice?
Egyptian users can receive international payments in USD, EUR, or GBP into Grey accounts with local banking details, or fund their account in EGP and convert to USD to spend on their cards directly. When a US client pays via ACH to your Grey USD account, the full amount is credited to your USD balance. You spend from that balance on the Grey virtual card, paying for AWS, Google Ads, Figma, ChatGPT Plus, or any USD-billed platform with no cross-border fee because the card and the merchant are both in USD.
The ability to create multiple cards for different purposes, such as separating business expenses from personal spending, is particularly useful for Egyptian freelancers managing professional and personal international payments from the same account.
Apple Pay and Google Pay support means the card works for contactless payments at any of 150 million merchants worldwide, not just for online transactions. For Egyptian professionals who travel or work abroad, this extends the card’s utility beyond the online-only use case.
Sign up with your email address and create a secure password
Complete KYC verification: upload your Egyptian national ID or passport, proof of address, and a photo
Verification typically completes within one to three business days
Once verified, access your USD, EUR, and GBP account details from the Accounts section
Fund your USD balance via international transfer, EGP conversion, or USDC
Navigate to the Cards section and select “Virtual card”
Pay the $5 one-time card creation fee
Your virtual USD card is issued instantly with a card number, expiry, and CVV
Add to Apple Pay or Google Pay for contactless payments, or use the card number directly for online purchases
The bottom line
The Central Bank of Egypt’s 2023 restriction affected approximately 98% of the population, cutting off access to the global economy through standard bank cards. The virtual card ecosystem that developed in response has given Egyptian users real, practical alternatives, but not all alternatives are equal.
For one-off purchases or users who primarily hold EGP, Card-Y’s instant EGP-to-USD conversion makes it the fastest way to convert local currency into international spending. For crypto-comfortable users who want the lowest creation fee, EverTry covers that use case. For prepaid spending without account setup, AstroPay works.
For Egyptian freelancers and remote workers who earn internationally and want a virtual card linked to a full USD, EUR, and GBP account with Apple Pay support, no transaction fee on USD purchases, and multiple card capabilities, Grey provides the most complete package of the options compared here.
Your ability to participate in the global digital economy shouldn’t depend on whether your local bank has lifted its international payment restrictions this week.
Frequently asked questions
Why do Egyptian bank cards get declined on international platforms?
The Central Bank of Egypt restricted the use of international debit cards in October 2023 to preserve USD reserves. While some restrictions have eased, many Egyptian bank cards remain unreliable for USD-billed international platforms. A virtual card issued by a non-Egyptian provider in USD bypasses these restrictions entirely because it operates outside Egypt’s domestic banking system.
What is the cheapest virtual card to create in Egypt?
Based on verified data as of May 2026, EverTry has the lowest creation fee at $2.50. Grey charges $5 one-time with no monthly fee. Card-Y charges $20 upfront, which is not added to the card balance. AstroPay and Fyatu have no card creation fee, but apply transaction and FX fees on spending. The cheapest card to create is not always the cheapest to use. On USD transactions, Grey charges no transaction fee, while Card-Y charges 1% minimum of $1 per transaction. For regular spending above $100 per transaction, Grey’s total annual cost is lower than Card-Y’s despite the higher creation fee.
Can I use a Grey virtual card for Facebook Ads and Google Ads from Egypt?
Yes. The Grey virtual USD card is accepted for secure online transactions, subscriptions, and business payments worldwide, including advertising platforms. Because the card is denominated in USD and issued by a non-Egyptian provider, it is not subject to the Central Bank of Egypt’s domestic card restrictions.
Does Grey support Apple Pay and Google Pay in Egypt?
Grey added Apple Pay and Google Pay support to its virtual cards in January 2026, enabling users in supported regions to make contactless payments directly from their multi-currency balances. Availability in Egypt should be confirmed at grey.co/cards, as supported regions may vary.
Is it legal for Egyptians to use virtual cards from foreign providers?
Using a regulated virtual card from a licensed international provider for legitimate personal and professional transactions is legal. What Egypt’s regulations restrict is the use of domestic bank cards for certain international transactions, not the use of internationally issued virtual cards. Grey is regulated by FINTRAC and FinCEN. Card-Y operates with FDIC-insured partner banks via Bridge. Using these platforms for legitimate purposes is consistent with Egyptian law. Consult a legal professional familiar with Egyptian financial regulations for advice specific to your situation.
Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Virtual card creation: $5 one-time fee, no monthly fee. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and current product availability at grey.co/pricing before transacting.
From the stunning beaches of Bali to the cultural richness of Yogyakarta, Indonesia is every tourist's dream. But before packing our bags, we need to figure out the visa requirements for EU citizens. If you’re planning a trip to Indonesia, here’s everything you need to know about getting the right visa.
Visa-free entry for short stays
For many EU citizens, visiting Indonesia for a short holiday is incredibly simple. Indonesia offers visa-free entry for up to 30 days for passport holders from most European Union countries. This is perfect for tourists who plan to explore the country briefly without worrying about extra paperwork.
However, there are a few things to keep in mind:
The visa-free entry is non-extendable, so if you plan to stay longer than 30 days, you'll need to apply for a visa before arriving.
You must enter and exit through designated international airports or seaports that allow visa-free travel.
Your passport should be valid for at least six months from the date of arrival.
You need a return or onward ticket to prove you won’t overstay.
If 30 days isn’t enough, you can opt for a Visa on Arrival (VOA), which allows you to stay in Indonesia for up to 60 days. This visa is granted for 30 days initially but can be extended once for another 30 days at an immigration office.
Key details:
The VOA costs $35, payable in cash or by card upon arrival.
You can apply for an extension before the first 30 days expire.
The VOA is available at major international airports and seaports, including Jakarta, Bali, and Surabaya.
For more details and updates on visa fees, visit Indonesia’s immigration website.
Applying for a visa before arrival
For those planning to stay longer or for purposes beyond tourism (such as work or study), you’ll need to apply for a visa before entering Indonesia.
Single-entry tourist visa
If you want to stay beyond 60 days, a single-entry tourist visa allows you to stay for up to 60 days, with the option of extending it for another 30 days. You need to apply at an Indonesian embassy or consulate in your home country before travelling.
Multiple-entry visa
Frequent travellers to Indonesia can apply for a multiple-entry visa, which is valid for one year, allowing stays of up to 60 days per visit. This is ideal for business visitors or those who plan to visit multiple times.
Digital nomad and remote work considerations
Indonesia is a hotspot for digital nomads, especially in Bali. While there is no official digital nomad visa yet, many remote workers enter the country on a business visa (B211A) or a social-cultural visa. These visas allow longer stays but may require sponsorship from an Indonesian company or organisation.
Before you embark on your journey to Indonesia, it’s essential to keep a few important travel tips in mind. These can help ensure a smooth trip, avoid unexpected fines, and make your stay more comfortable. Here are some key things to remember:
Overstaying penalties: If you exceed your permitted stay, you’ll be fined IDR 1,000,000 (around $65) per day. Long overstays could lead to deportation.
Proof of funds: Some visas require you to show sufficient funds for your stay. Carrying a bank statement or proof of income can help.
Travel insurance: While not a visa requirement, having travel insurance is highly recommended for medical emergencies and trip cancellations.
Managing finances in Indonesia with Grey
Travelling in Indonesia requires efficient financial management. Grey simplifies international transactions for tourists:
Multi-currency accounts: Hold and manage funds in IDR, USD, EUR, and GBP with Grey.
Competitive exchange rates: Convert currencies at low fees and real-time rates.
Fast international transfers: Send and receive money seamlessly.
Secure mobile banking: Manage your travel expenses through the Grey app.
Indonesia is a breathtaking destination, and navigating the visa process as an EU citizen is relatively straightforward. Whether you’re visiting for a short getaway, an extended adventure, or even remote work, planning ahead ensures a hassle-free experience.
Before you book your flight, double-check the latest visa requirements on Indonesia’s official immigration website or consult your nearest Indonesian consulate. Safe travels!
Morocco is one of the world’s top remittance-receiving countries. The Moroccan diaspora, concentrated primarily in France, Spain, Italy, Belgium, and, more recently, the US and Canada, sends billions of dirhams home each year to support families, cover education costs, invest in property, and fund small businesses.
At the same time, Morocco has a fast-growing freelance and professional class that consists of developers, designers, and consultants who work for European clients and receive payments in EUR. Both groups, those sending money into Morocco and those receiving it for professional work, face the same underlying challenge. Morocco’s currency, the dirham (MAD), is not freely convertible outside the country. Every inbound transfer is converted to MAD through the Moroccan banking system, and each provider applies a different margin to that conversion.
This article covers how different apps for sending money compare, the Moroccan regulatory framework you need to understand, and how Grey fits into the picture for Moroccan freelancers receiving EUR from European clients.
What makes the Morocco corridor specific?
Before comparing apps, two things about Morocco’s financial system are worth understanding, because they shape how every transfer actually works.
The dirham is a managed, non-convertible currency
The Moroccan dirham cannot easily be bought or sold abroad, and international banks rarely stock it. Morocco has been gradually moving toward a more flexible exchange rate regime since 2018, widening the dirham’s fluctuation band. Still, the currency remains managed relative to a basket weighted 60% EUR and 40% USD. In practice, this means every inbound international transfer must be converted to MAD through Bank Al-Maghrib’s official exchange rate framework. Providers use this as their base and apply their own margin on top. Understanding that the margin, not the visible fee, is where most of the cost sits, is the key insight for anyone sending money to Morocco.
Bank Al-Maghrib regulates all inbound transfers
Bank Al-Maghrib (BAM) is Morocco’s principal financial regulator. It’s responsible for regulating and supervising banks and credit institutions, and for ensuring the stability of the financial system. All international money transfers received in Morocco pass through BAM’s regulated framework. Large or unusual transfers may require source-of-funds documentation from Moroccan banks, consistent with standard AML procedures.
For the sender, this means using a licensed, regulated provider matters.
With Wise, you can send funds directly to Moroccan bank accounts. Fees for USD-to-MAD transfers range from 0.42% to about 2.5% of the send amount. You’ll always see the full cost before confirming.
Wise supports bank transfers to Moroccan accounts at major Moroccan banks, although cash pickup isn’t available.
It’s best for senders prioritising the lowest total cost and full fee transparency on bank-to-bank transfers.
Sendwave
On the EUR-MAD corridor, Sendwave offers competitive rates, particularly for smaller, frequent transfers. Sendwave charges no visible transfer fee and builds its margin into the exchange rate, typically 1 to 2% above mid-market on the USD-MAD corridor. The rate shown before confirmation includes all costs.
Interestingly, Sendwave’s parent company, Zepz Group, also owns WorldRemit. The FCA regulates it in the UK and FinCEN in the US.
WorldRemit
WorldRemit supports bank transfers and cash pickup in Morocco. Transfer limits for US senders are capped at $9,000 per day, which is worth noting for larger transfers. Fees vary by payment method and amount. The exchange rate typically includes a 1.5 to 2.5% margin above mid-market on the USD-MAD corridor.
WorldRemit is regulated by the FCA in the UK and licensed as a money transmitter in the US. It is a strong option for recipients who prefer cash pickup over bank deposit, particularly in areas where bank access is less convenient.
Western Union
Western Union has one of the largest cash pickup networks in Morocco, with thousands of agent locations including Banque Populaire branches, Wafacash outlets, and dedicated Western Union agents. For recipients without bank accounts, or in areas where cash is the preferred delivery method, Western Union’s network reach is unmatched.
The cost of that reach is in the exchange rate. Western Union’s margin on the USD-MAD corridor typically runs 2 to 4% above the mid-market rate, depending on the payment method. Bank transfers usually cost less than cash pickup.
Western Union is one of the oldest and most regulated money transfer companies in the world. For the specific use case of cash delivery to recipients without Moroccan bank accounts, no other provider in this comparison matches its network.
Grey
With Grey, you can send MAD directly to local Moroccan bank accounts. at a flat rate of $2, making the transfer process even simpler. A big part of where Grey fits for Moroccan users is on the receiving side. Grey provides GBP and EUR accounts with an IBAN, allowing European clients to pay via SEPA as they would with any local vendor.
This way, there’s no forced conversion at the moment of receipt. The EUR sits in the Grey account until you are ready to convert and withdraw to a Moroccan bank.
Western Union and WorldRemit’s cash pickup networks exist for a reason, as not every recipient in Morocco has a convenient bank account, and not every city has the same bank branch density. For those situations, the higher rate margin is the cost of access, and it’s a legitimate trade-off.
Grey’s flat $2 sending fee is a fantastic choice. And for Moroccan freelancers and professionals receiving EUR from European clients, the receiving side of the equation matters as much as the sending side. A SEPA-capable EUR account solves this problem entirely and puts conversion timing in the receiver’s hands rather than your bank’s.
Can I send USD directly to a Moroccan bank account?Yes, through apps like Grey, you can convert and send USD to MAD at very competitive rates
Is it safe to send money to Morocco through these apps?Yes. Recognised financial authorities regulate all five providers in this comparison: the FCA in the UK, FinCEN in the US, or both.
Can Moroccan freelancers use Grey to receive payments from European clients?Yes, for EUR payments. Grey provides an EUR account with an IBAN that Moroccan users can share with European clients for SEPA transfers.
What is the mid-market rate?The mid-market rate is the midpoint between buy and sell prices in the global currency market at any given moment.
Grey charges fees on deposits, conversions, and withdrawals. Deposits via SEPA incur a 0.8% fee (minimum €2, maximum €10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: 0.5% for EUR (minimum €2, maximum €10). Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction. Visit grey.co/pricing for current rates.