<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/revolut-business-account#article","headline":"Revolut business account: Fees, features and who it suits","description":"Is Revolut Business right for your business? Compare fees, features, limits, and alternatives. Get an honest review to help you choose. Compare options now.","inLanguage":"en","url":"https://grey.co/blog/revolut-business-account","mainEntityOfPage":{"@id":"https://grey.co/blog/revolut-business-account#webpage"},"datePublished":"2026-07-31T22:26:49.449Z","dateModified":"2026-08-02T09:00:00+01:00","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/revolut-business-account#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a6d210e6e620aa856f6af46_Revolut%20Business%20Account%20Fees%2C%20Features%20and%20Who%20It%20Suits-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a6d210e6e620aa856f6af46_Revolut%20Business%20Account%20Fees%2C%20Features%20and%20Who%20It%20Suits-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/revolut-business-account#webpage","url":"https://grey.co/blog/revolut-business-account","name":"Revolut Business Account: Fees, Features, Review | Grey","description":"Is Revolut Business right for your business? Compare fees, features, limits, and alternatives. Get an honest review to help you choose. Compare options now.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/revolut-business-account#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/revolut-business-account#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/revolut-business-account#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Revolut business account: Fees, features and who it suits","item":"https://grey.co/blog/revolut-business-account"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/revolut-business-account#faq","mainEntity":[{"@type":"Question","name":"Does Revolut Business support all countries?","acceptedAnswer":{"@type":"Answer","text":"No. Revolut Business is available only in selected markets and primarily supports businesses incorporated in countries such as the United Kingdom, the European Economic Area (EEA), the United States, Australia, Singapore and India. If your business is registered outside supported regions, you may need to consider an alternative provider."}},{"@type":"Question","name":"What is the cheapest Revolut Business plan?","acceptedAnswer":{"@type":"Answer","text":"The Basic plan is Revolut Business's lowest-priced option, costing £10 per month. It includes limited free local transfers, no free international transfers and a small monthly foreign exchange allowance. Businesses with higher transaction volumes may find better value in one of the higher-tier plans."}},{"@type":"Question","name":"Can sole traders use Revolut Business?","acceptedAnswer":{"@type":"Answer","text":"Yes. Revolut Business is available to eligible freelancers, sole traders and self-employed professionals, allowing them to separate business and personal finances. Users can receive international payments, hold multiple currencies, issue invoices and manage business spending from a dedicated account."}},{"@type":"Question","name":"Does Revolut Business charge for incoming international transfers?","acceptedAnswer":{"@type":"Answer","text":"Incoming transfers are not always free. Costs depend on the payment method, currency and your pricing plan. Some transfer types are included within monthly allowances, while others may attract additional charges after you exceed your plan's limits. Always review the latest pricing before receiving payments."}},{"@type":"Question","name":"Is Revolut Business safe?","acceptedAnswer":{"@type":"Answer","text":"Yes. Revolut Business operates under financial regulations in the markets where it is licensed and uses encryption, fraud monitoring and security controls to protect customer accounts. Like other regulated financial platforms, it also carries out compliance checks that may occasionally require additional account verification."}},{"@type":"Question","name":"What is the best Revolut Business alternative for emerging markets?","acceptedAnswer":{"@type":"Answer","text":"If your business regularly sends or receives payments across Africa or Asia, Grey Business is an ideal alternative. It provides global accounts for receiving foreign currencies, transparent pricing and cross-border payment tools without requiring your business to be incorporated in Western markets."}}]}] </script>

Revolut business account: Fees, features and who it suits

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Running a business across borders used to mean opening multiple bank accounts, waiting days for international payments and juggling expensive transfer fees. Today, business owners expect one platform that can receive payments, pay suppliers, manage team expenses and hold multiple currencies without unnecessary complexity. That's why digital business accounts have become increasingly popular with freelancers, startups and growing companies.

Among the biggest names in this space is Revolut Business. Built for modern businesses, it combines multi-currency accounts, international transfers, expense management and accounting software integrations into a single platform. For many companies, it has become an attractive alternative to traditional business banking.

But is Revolut Business the right fit for your company? The answer depends on how you get paid, where your customers are and which features you actually use. This guide explains Revolut Business fees, key features, limitations and the types of businesses that benefit most from the platform.

What is Revolut Business and who is it for?

Businesses no longer need separate banking tools for receiving payments, paying suppliers and managing multiple currencies. As more companies sell internationally, the demand has shifted towards digital platforms that simplify cross-border finance. Revolut Business was created to meet that need, giving businesses one place to manage global payments and day-to-day financial operations.

Revolut Business is a digital financial platform designed for freelancers, small businesses, startups and larger companies. It allows businesses to hold, exchange and transfer money in more than 30 currencies, while sending payments to suppliers in over 150 countries. It is available in several markets, including the United Kingdom, the European Economic Area (EEA), the United States, Australia, Singapore and India, with availability depending on your business location.

In the United Kingdom, Revolut is regulated by the Financial Conduct Authority (FCA) for relevant financial services. Rather than replacing every traditional banking service, Revolut Business serves as a central platform for managing international transactions, multi-currency balances, corporate spending and cross-border business payments from one account.

Key features of a Revolut Business account

Revolut Business combines banking, payments and expense management into one platform, helping businesses manage domestic and international finances more efficiently.

  • Multi-currency accounts: Hold, receive and exchange more than 30 currencies from one account, making it easier to work with international clients, suppliers and business partners across different markets.
  • International transfers: Send payments to businesses and suppliers in over 150 countries, with competitive exchange rates and faster cross-border transfers than many traditional business banking services.
  • Expense cards: Issue physical and virtual expense cards to employees, set spending limits, monitor transactions in real time and maintain better control over company expenses.
  • Accounting integrations: Connect directly with Xero and QuickBooks to automatically sync transactions, simplify bookkeeping and reduce the amount of manual financial administration required.
  • Payment links: Create secure payment links that allow customers to pay online without requiring a website, making it easier for businesses to collect payments from anywhere.
  • Bulk payments: Upload multiple payments at once instead of sending them individually, saving time when paying suppliers, contractors, employees or other business expenses.

Revolut Business account fees and pricing plans

Revolut Business offers four pricing plans, with each tier increasing your free allowances for transfers, foreign exchange and business features before additional fees apply.

Feature Basic Grow Scale Enterprise
Best for Freelancers and
small businesses
Growing businesses Established businesses Large organisations
Monthly fee
£10 £30 £90 Custom
Free local transfers 10/month 100/month 1,000/month Bespoke
Free international transfers 0/month 5/month 25/month Bespoke
Free FX exchange
Up to £1,000/month Up to £15,000/month Up to £60,000/month Negotiated limits

Additional fees

Fee Charge
Excess local transfers £0.20 per transfer
Excess international transfers £5.00 per transfer (or local currency equivalent)
Excess FX exchange 0.6% markup above your monthly allowance
Weekend currency exchange 1.0% markup
ATM cash withdrawals 2% fee

Revolut Business reviews: What real users actually think

Revolut Business receives strong ratings on independent review platforms, but user experiences are far more balanced once you look beyond marketing pages.

The positives

  • Excellent user experience: Many users describe the mobile and web apps as intuitive, modern and easy to navigate, making day-to-day banking straightforward.
  • Strong multi-currency features: Businesses that work internationally value the ability to hold, exchange and spend multiple currencies from one account.
  • Fast onboarding: Many reviewers report opening an account quickly and sending or receiving international payments without the lengthy setup associated with traditional banks.

The negatives

  • Account freezes: The most common criticism is automated compliance reviews that can temporarily freeze accounts or funds after unusually large or unexpected transactions.
  • Customer support delays: Users on forums such as Reddit frequently mention difficulty reaching specialist compliance teams, especially when urgent account issues arise.
  • Extra charges: Some businesses report unexpected costs after exceeding monthly allowances for transfers or foreign exchange, making it important to understand the pricing structure before choosing a plan

Also read: Best USD Accounts for UK Residents: 7 Options Compared

Who should use Revolut Business?

Revolut Business works best for companies operating in supported markets with regular international payments.

Best suited for

  • UK and EU freelancers earning from overseas clients and managing payments in multiple currencies.
  • Startups with international customers in developed markets that need fast cross-border payments and multi-currency business accounts.
  • Small teams looking for employee expense cards, spending controls and accounting integrations in one platform.

May not be the best fit

  • Businesses operating in or regularly paying into markets ****where Revolut's business services and local payment capabilities are more limited such as Nigeria, Pakistan and Egypt, .
  • Companies needing broader emerging-market coverage, particularly those with customers, suppliers or contractors in countries where Revolut Business has limited support or functionality.

Best alternatives to Revolut Business

Platform Inbound fee Currency conversion fee Weekend FX penalty Best for
Grey Business 0.8% (capped at $10) 1.0% (capped at $6) None Businesses receiving and sending money across Africa, Asia and other emerging markets with predictable, low-cost pricing
Revolut Business Free (with paid plan) 0.6% after free allowance 1.0% Teams needing corporate cards, expense management and banking in supported markets
Wise Business Variable 0.4%–0.5% (uncapped) None Businesses making frequent international contractor and supplier payments
Payoneer 1.0% 0.5%–2.0% None Sellers receiving payments from global marketplaces like Amazon, Fiverr and Upwork

Also read: Grey Business vs Grey personal banking

Frequently asked questions

Does Revolut Business support all countries?

No. Revolut Business is available only in selected markets and primarily supports businesses incorporated in countries such as the United Kingdom, the European Economic Area (EEA), the United States, Australia, Singapore and India. If your business is registered outside supported regions, you may need to consider an alternative provider.

What is the cheapest Revolut Business plan?

The Basic plan is Revolut Business's lowest-priced option, costing £10 per month. It includes limited free local transfers, no free international transfers and a small monthly foreign exchange allowance. Businesses with higher transaction volumes may find better value in one of the higher-tier plans.

Can sole traders use Revolut Business?

Yes. Revolut Business is available to eligible freelancers, sole traders and self-employed professionals, allowing them to separate business and personal finances. Users can receive international payments, hold multiple currencies, issue invoices and manage business spending from a dedicated account.

Does Revolut Business charge for incoming international transfers?

Incoming transfers are not always free. Costs depend on the payment method, currency and your pricing plan. Some transfer types are included within monthly allowances, while others may attract additional charges after you exceed your plan's limits. Always review the latest pricing before receiving payments.

Is Revolut Business safe?

Yes. Revolut Business operates under financial regulations in the markets where it is licensed and uses encryption, fraud monitoring and security controls to protect customer accounts. Like other regulated financial platforms, it also carries out compliance checks that may occasionally require additional account verification.

What is the best Revolut Business alternative for emerging markets?

If your business regularly sends or receives payments across Africa or Asia, Grey Business is an ideal alternative. It provides global accounts for receiving foreign currencies, transparent pricing and cross-border payment tools without requiring your business to be incorporated in Western markets.

Choosing the right business account depends on where your customers are, how you receive payments and the markets you serve. If your business operates across Africa, Asia or other global markets, open a Grey Business account to simplify cross-border payments and manage foreign currencies seamlessly.

Last updated:

October 4, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How African businesses source from and pay suppliers in China

•

•

2 min read

Say you’re dealing with a factory whose quote is in dollars, and they want a deposit before production starts, and the account details arrive by email under a company name that isn’t quite the one on the invoice. For a first-time importer in Lagos or Nairobi, nothing about that moment is unusual, and each part of it is a place where a small mistake costs real money.

Many African businesses usually pay Chinese suppliers by international bank transfer, in US dollars or yuan. A common pattern is a deposit before production and the balance before shipment, though terms are negotiable. Importers in Nigeria must also register a Form M with their bank. Platform escrow, where offered, adds protection for first orders.

However, with cross-border and global payments making it easier for businesses to settle renminbi (RMB) transactions, trading with China has become easier, and more options are available to people and businesses to send yuan directly to local bank accounts in China.

In this article, I cover how to find and check a supplier, what an order should cost, how to manage the relationship, and how to pay.

Why China, and why now?

If you are looking to start or scale a business, China is hard not to consider. China is a major source of manufactured goods for African businesses, and the volumes show it. Trade between China and Africa reached a record US$348.05 billion in 2025, up 17.7% on the year, according to a report from the NTU-SBF Centre for African Studies. Chinese exports to Africa accounted for US$225.03 billion, up 25.8%, while imports from Africa were US$123.02 billion, up 5.4%. The same report puts Africa’s deficit with China at US$102.01 billion, meaning African buyers are importing far more than they export.

Behind those totals are the businesses this guide is for: shop owners, online sellers, and small manufacturers who buy fabric, electronics, machine parts, packaging, and finished goods. A growing number go a step further and develop private-label products, in which a factory makes a product to the importer's specifications and under the importer’s brand. That raises the stakes on everything that follows: choosing the factory, agreeing the order size, checking quality, and moving the money.

What has changed in China-Africa trade in the last five years

China opened its market to African exports
Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.

China opened its market to African exports
Since 1 May 2026, China has applied zero-tariff treatment to imports from the 53 African countries with which it has diplomatic relations, per Reuters’ report. The measure covers goods entering China. It helps African exporters and does not lower what an importer pays for Chinese goods, so the cost of buying from China still depends on the factory price, shipping, home duties, and the cost of moving money.

Nigeria’s foreign exchange policy has been updated
The CBN issued a new foreign exchange manual in May 2026. Coverage states that importers must submit exchange control documents within 90 days of negotiating shipping documents, and that importers who fail to do so may be restricted from the foreign exchange market. We’ll talk about this a bit more in the section on paying suppliers.

There are more ways to pay in yuan
Some payment providers, like Grey, now deliver yuan directly to Chinese bank accounts, giving importers an alternative to paying only in dollars.

How to find a reliable Chinese supplier

For businesses looking to source from China, finding a supplier often starts with an online marketplace, especially for first-time importers.

Alibaba.com is built for export buyers and lists suppliers that work with overseas customers. 1688 is China’s domestic wholesale platform. It is written in Chinese, prices are often lower, and most foreign buyers use a sourcing agent or a translator to work with it. Trade fairs such as the Canton Fair in Guangzhou let you meet suppliers and handle samples in person, and referrals from other importers in your market often lead to suppliers that already ship to Africa.

Factory or trading company?
When you make contact, you have to ask directly: “Do you own the factory?” A trading company is not a bad choice, since it can combine products from several factories and handle export paperwork, but it adds its own margin and puts you one step further from the people making your product. A factory can usually show its production line on a video call and explain who works on your order.

Check that the company exists
Ask for the business licence, which carries an 18-character Unified Social Credit Code. China’s National Enterprise Credit Information Publicity System at gsxt.gov.cn lets you search for that code to see whether the company is registered, who its legal representative is, and whether it has abnormal operation records. The site is in Chinese with no official English version and can be slow from outside China, so browser translation helps. Two limits matter. A matching code proves that a company exists, not that the person you are talking to works for it. And the English name on a supplier’s profile often differs from its registered Chinese name, so make sure the name on the licence, contract, invoice, and bank account all match.

Order samples before you commit
Pay for samples, test them yourself, and then compare the first production units with the approved sample. Making one good sample is easy. What you want to know is whether the supplier can repeat it.

Document exactly what you want
A supplier can only build what is written down. Send specifications with photos, dimensions, materials, colours, packaging, and tolerances, and confirm every decision in writing, even if you also talk on WeChat or WhatsApp. Ask the supplier to repeat back what they will make.

Warning signs
A price far below every other quote, a refusal to join a video call, pressure to pay quickly, a request to pay a personal account for a company order, or a request to move the payment outside the platform you are using.

The real cost of sourcing from China: MOQs, shipping and duties

The price in the quote is the starting point, not the end. What matters is the landed cost: everything you have paid by the time the goods are in your warehouse.

MOQs
A minimum order quantity (MOQ) is the smallest order a supplier will produce. It varies by product and factory, and custom or private-label work tends to carry higher minimums than catalogue items because the factory has to set up materials and tooling for you. MOQs are often negotiable, especially if you accept a higher unit price, a later delivery date, or a promise of repeat orders. A smaller first order costs more per unit, but it limits your potential losses while you test the supplier and the market.

Shipping
Sea freight costs less per unit and takes longer. Air freight is faster but more expensive, making it suitable for samples and urgent restocks. For sea freight, a full container (FCL) gives you the entire container, while a less-than-container load (LCL) lets smaller orders share space at a higher per-unit cost. Ask every quote to state its Incoterm, which says who pays for what and where responsibility passes to you. Under FOB, the supplier delivers the goods to the port in China, and you pay the freight from that point onward. Under CIF, the supplier also pays freight and insurance to your destination port.

Duties and clearing
Import duty depends on how the product is classified under the Harmonised System (HS) code, and rates differ by product. Check the HS code and the current rate with a licensed clearing agent before you place the order, because a wrong classification can change the bill after the goods arrive. In Nigeria, the goods also need a registered Form M, covered in the section on paying suppliers.

Payment costs
Bank fees and exchange rate margins sit on top. For a thin-margin product, a percentage point or two can decide whether an order is worth repeating.

The numbers below are made up and rounded to show how a quote grows. They are not real prices or rates.

Cost Example amount
Goods: 1,000 units at US$4.00 US$4,000
Sea freight and insurance US$650
Duties, taxes, and clearing US$1,200
Quality inspection US$300
Payment fees and exchange margin (2% of goods) US$80
Landed cost US$6,230

‍

On these made-up figures, a unit quoted at US$4.00 costs US$6.23 once it lands, about 56% more. Work out your own version before you agree a price, and repeat it for each product.

Managing suppliers across time zones and currencies

Time zones
China runs on UTC+8. Lagos is seven hours behind it, and Nairobi is five hours behind it. A supplier’s working day, roughly 9 am to 6 pm in China, runs from about 2 am to 11 am in Lagos, so the useful overlap is the morning. Agree on a fixed weekly call time, and use written updates for everything else, so nothing depends on both of you being online at once.

Milestones, not trust
Split the order into stages and tie each stage to evidence: a confirmed specification and a signed sample; production started, with photos or a video; finished goods before packing; and a pre-shipment inspection. An independent inspection company can check quantity, workmanship, and packaging before you pay the balance. Include these stages in the contract, along with what happens if the goods do not match the sample.

Holidays
Chinese New Year and the National Day holiday in early October can close factories for days or weeks, and orders placed just before them can slip. Build the dates into your plan and place orders early.

One record
Keep one shared order sheet with the product, specification, quantity, price, currency, deposit paid, balance due, and expected dates. When a supplier changes a price or a date, ask for it in writing and update the sheet.

Currencies
Decide the invoice currency at the start. A quote is a snapshot, so ask how long the price is valid. If your local currency weakens between the quote and payment, the same dollar or yuan amount costs more to buy. Where you can, hold or earn the currency you pay in, so a swing in the exchange rate does not change the size of the bill. Splitting a large order into a deposit and a balance paid weeks apart also spreads the exchange rate risk, though it can work in either direction.

How to pay Chinese suppliers from Nigeria and the rest of Africa

There is no single best way to pay a supplier. The right route depends on the size of the order, how well you know the supplier, and what your bank and customs require.

The main ways to pay

Method How it works Best for Watch for
Bank wire (telegraphic transfer) Your bank sends US dollars, or another currency, to the supplier's bank account, usually through the SWIFT network Established suppliers and larger orders Intermediary and receiving bank fees, your bank's exchange rate, and no protection if the supplier does not deliver
Platform payment with escrow You pay through the marketplace, which protects the payment under its own terms, for example bank wire with escrow protection on Alibaba.com First orders with a new supplier Protection applies only if you keep the payment on the platform, and only as far as its terms cover
Letter of credit

Your bank promises to pay the supplier once agreed documents are presented Large orders where trust is low Higher bank charges and strict paperwork
Yuan payout through a payment provider The provider delivers yuan to the supplier's Chinese bank account Regular small to mid-sized payments Per-transfer limits, the provider's rate and fee, and whether your bank accepts the route for import documentation
Informal channels and payment agents A third party pays the supplier for you Not recommended You may lack the paperwork your bank and customs expect, and the money is hard to trace if something goes wrong

‍

What Nigerian importers need to know

In Nigeria, an importer must complete Form M for goods entering the country. GTBank’s guide to Form M calls it a mandatory statutory document for all importers who are registered with an authorised dealer (a bank) when the order is placed, whether or not the transaction requires foreign exchange. It is submitted electronically on the CBN’s Trade Portal, which works with the Nigeria Customs Service. It is valid for 180 days for general merchandise and 365 days for plant and machinery, and the bank can extend it.

The CBN’s foreign exchange manual, issued in May 2026, adds a second deadline. Coverage of it says importers must submit exchange control documents within 90 days of negotiating shipping documents with overseas correspondent banks, and that importers who do not can be barred from foreign exchange transactions, including Form M processing, for periods that lengthen with repeat offences. Keep every invoice, contract, and shipping document organised so you can produce them when needed.

Before you pay, ask your bank how it wants the Form M and supporting documents handled for your route, and whether payments made through a payment provider fit its documentation requirements. Rules change, so confirm the current position with your bank or the CBN, not from a blog.

Protect the payment itself

  • Pay only to an account in the supplier’s registered company name, as shown on the contract and invoice.
  • Confirm bank details by a second channel, such as a video call, before the first payment and whenever they change. A change of account details sent by email is a common fraud.
  • Size the deposit to what you can afford to lose on a first order, and tie the balance to the inspection result.
  • Get the invoice in writing, with the currency, amount, and bank details.

Comparing what you pay

Quotes are hard to compare because the cost is split between a fee and an exchange rate. To compare them, divide the total naira you pay by the amount the supplier receives, then compare the resulting rate with the mid-market rate for the same day. The gap, plus any fee, is the real cost of the transfer. Do the same for each route, and ask the supplier whether the price changes depending on whether you pay in dollars or yuan.

Paying with Grey

Grey recently launched payouts to China, giving Nigerian importers another option.

  • The supplier receives yuan in their own Chinese bank account with ICBC, Bank of China, China Construction Bank, or Agricultural Bank of China and does not need a Grey account.
  • Before you confirm, Grey shows the rate and the fee as two separate numbers, and the yuan amount your recipient receives does not change after you confirm.
  • The account name you enter must match the account name on the supplier’s invoice, so copy it from there.

Grey charges a flat fee of $2.80 per bank transfer, with a limit of 50 to 21,000 yuan per transfer. Transfers are typically completed within 24 hours on banking days, with a 10:00 GMT cut-off; transfers made after this time may take longer. A limit of 21,000 yuan per transfer means a large factory deposit may need to be split into several transfers or paid another way, so check the limit shown in the app for your route before relying on it.

To hold US dollars and convert them when you need to pay, see Grey's foreign accounts. For small-order samples on platforms that accept cards, a virtual card is another option, though payments on non-US websites may incur a cross-border fee. If you pay several suppliers, Grey also offers a business account for cross-border trade with bulk payouts and payment status tracking. Check whether it is available in your country first.

Grey is a financial technology company, not a bank, and works with CBN-licensed banking partners in Nigeria. Its US services are regulated by FinCEN and its Canadian services by FINTRAC.

Frequently asked questions

How do African businesses pay Chinese suppliers?

Most pay through international bank transfer in US dollars or yuan, often with a deposit before production and the balance before shipment. Other routes include platform payments with escrow, letters of credit, and yuan payouts through payment providers. The right choice depends on the order size, the supplier, and your bank’s requirements.

Do they need a Form M to import from China into Nigeria?

Yes. GTBank’s guide describes Form M as a mandatory statutory document for all importers, which must be registered with a bank when the order is placed, whether or not the transaction requires foreign exchange. Confirm the current process with your bank.

Is it better to pay a Chinese supplier in dollars or yuan?

Neither is better by default. Ask the supplier for the price in both currencies, then compare the total you pay in your local currency, including fees and the exchange rate, against the mid-market rate on the day.

How can I check that a Chinese supplier is real?

Ask for the business licence and search its Unified Social Credit Code on China’s National Enterprise Credit Information Publicity System. Make sure the name on the licence, contract, invoice, and bank account match; order samples first; and join a video call before you pay a deposit.

Can I pay a supplier in China with Grey from Nigeria?

Grey offers payouts to Chinese bank accounts, delivered in yuan, from a naira top-up or a USD balance. The recipient does not need a Grey account. Check the fee, rate, and limit shown in the app before you confirm, as per-transfer limits apply.

Does China’s zero-tariff policy make imports from China cheaper?

No. The policy, in force from 1 May 2026, covers goods entering China from 53 African countries. It helps African exporters without changing what importers pay for Chinese goods.

How much deposit should I pay a new supplier?

Terms are negotiable, and a deposit before production, with the balance due before shipment, is a common pattern. For a first order, pay only what you can afford to lose, use platform protection where available, and tie the balance to an inspection result. This is general guidance, not financial advice.

Paying a supplier in China? See the rate and fee before you send.

Fees and rates: Grey's CNY payout post lists a flat fee of $2.80 per bank transfer and a limit of 21,000 yuan per transfer. Currency conversion is listed at 1% (capped at $6) on USD, GBP, and EUR transfers, so check the fee shown in the app for your route. A virtual card costs $5 to create once, with no monthly fee, and payments on non-US websites may incur a cross-border fee of 2% plus $0.50. Exchange rates vary with a margin over the mid-market rate, and delivery times depend on the bank, the route, and cut-off times.
Single-member LLC: How it works and how to set one up

•

•

2 min read

A client’s accounts team emails you: before they can pay the next invoice, they need your business name and an EIN. Until now, you’ve invoiced under your own name, and a friend has told you a single-member LLC (sometimes called a single-member LLC) will sort it all out. It gives you a separate legal entity, but it won’t change how you pay tax unless you ask it to. This guide explains what the structure does, how it’s taxed, and the five steps to set one up.

A single-member LLC is a limited liability company with one owner. It limits your personal liability for business debts and, by default, is taxed as a disregarded entity, so profits pass through to your personal tax return. You set one up by filing formation documents with your state and getting an EIN.

What is a single-member LLC?

A single-member LLC is a limited liability company with exactly one owner, called the member, who owns the business and keeps its profits. You create it by filing with a US state, and the state treats the LLC as a legal entity that is separate from you. The member can be an individual or another company.

People also search for this structure as a single-member LLC. It’s the same thing: the name only describes how many owners the company has. Freelancers, consultants, online sellers, and solo founders use it because it adds a legal layer between the owner and the business without the paperwork required for a corporation.

That legal layer is the main reason to form one. An LLC generally limits your personal liability for the business’s debts, so a creditor of the company can normally go after what the company owns, not your home or savings. The protection has limits:

  • It can be undone if you mix personal and business money, so keep a separate business bank account.
  • It doesn’t cover debts you’ve personally guaranteed, such as a loan or a lease you signed in your own name.
  • It doesn’t shield you from liability for your own wrongdoing.

A sole proprietor has no such separation, because the owner and the business are legally the same person. If you’re weighing the two, LLC vs sole proprietorship compares them side by side.

Owners don’t need to live in the US. A non-resident can own a US LLC, which is why many freelancers abroad form one to invoice American clients. The tax and reporting rules for them differ, and the FAQ below covers the basics.

How a single-member LLC is taxed

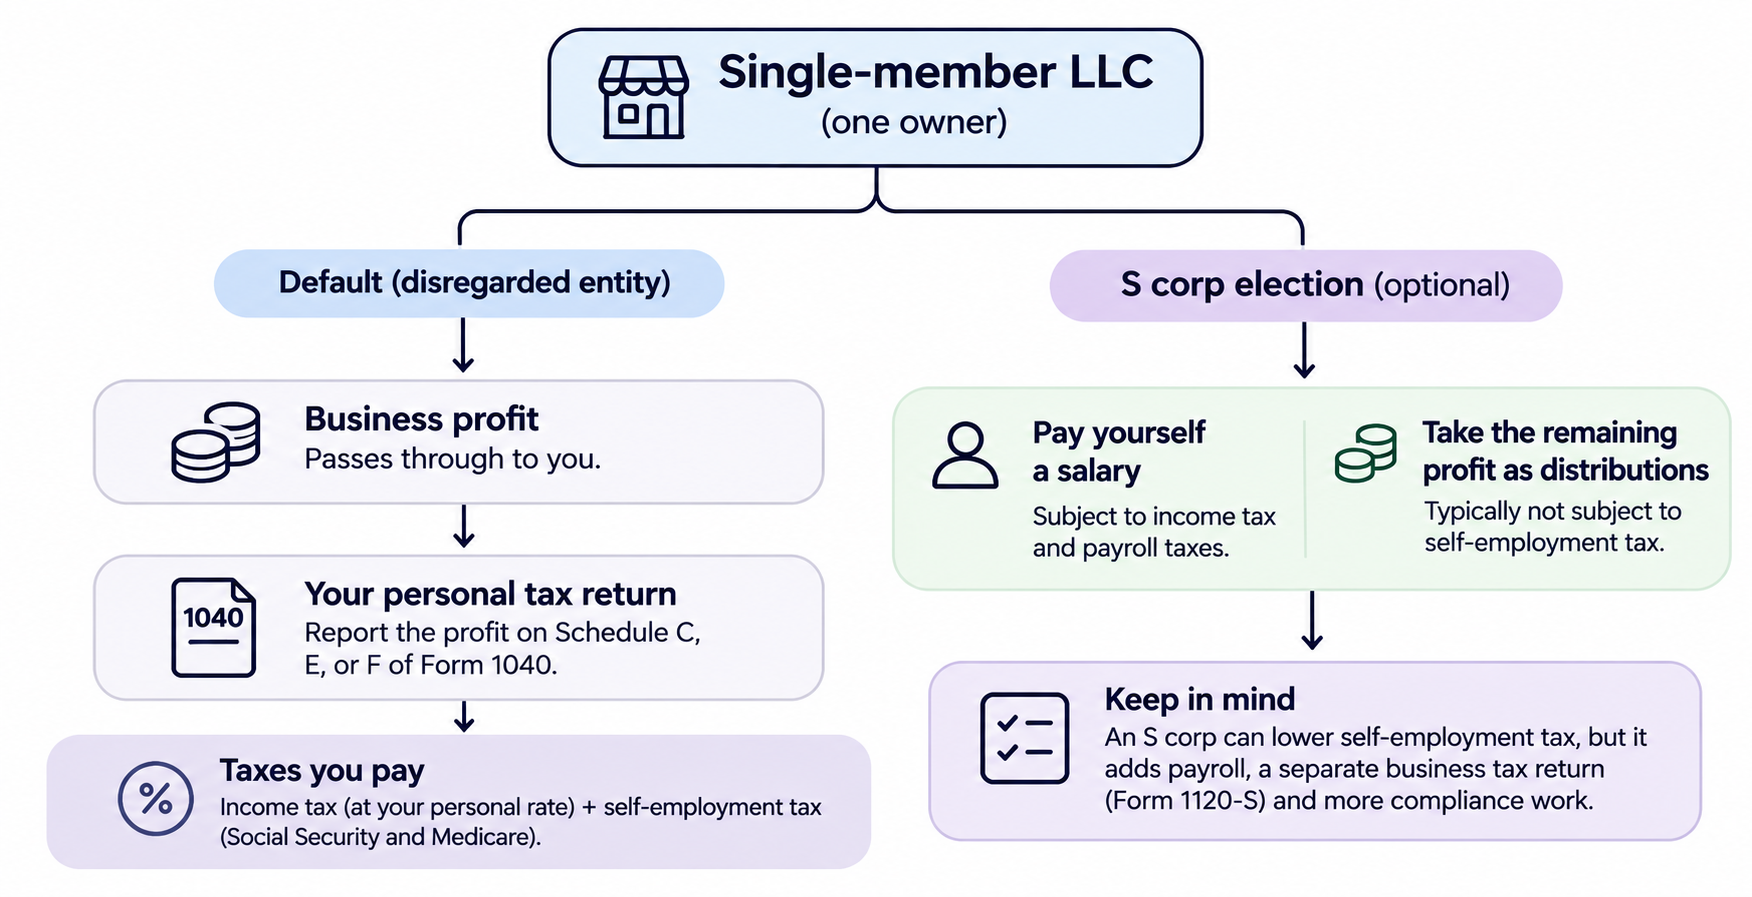
By default, the IRS treats a single-member LLC as a disregarded entity: it ignores the LLC for income tax and taxes the profit as your own. The LLC doesn’t file a federal income tax return of its own. Per IRS guidance on single-member LLCs, an individual owner reports the business on Schedule C, E, or F of Form 1040, depending on the type of income.

This is what “pass-through” means: the profit passes through the LLC to your personal return and is taxed there, at your personal rate, with no separate tax at the company level.

Flow diagram showing how profit from a single-member LLC passes through to the owner's personal tax return.

Self-employment tax

An individual owner also pays self-employment tax on the LLC’s net earnings, the same as a sole proprietor. This is the tax that funds Social Security and Medicare for people who don’t have an employer paying into them, and it’s charged on top of income tax. It’s the part of the bill that the options below can change.

Forms your clients may send

If you’re paid for services by US clients, they may send you a Form 1099-NEC at the end of the year. The 1099 form for contractors records what a client paid you, and it’s a reporting document, not a bill. You report all your business income whether or not a client sends you one, so keep your own invoices and bank records.

Taxed as a corporation or an S corp

A single-member LLC isn’t locked into the default. You can file Form 8832 to elect to be taxed as a corporation, and you can also elect S corporation status. An S corp election can lower self-employment tax because you pay yourself a salary and take the remaining profit as distributions, but it adds payroll, a separate business tax return and more compliance work. S corp vs LLC covers when the switch is worth considering.

One exception applies even to a disregarded LLC. For employment and excise taxes, the IRS treats the LLC as a separate entity, so an LLC with employees reports payroll under its own name and EIN.

This is general guidance, not professional tax advice. Consult a certified tax professional for your specific situation.

How to set up a single-member LLC step by step

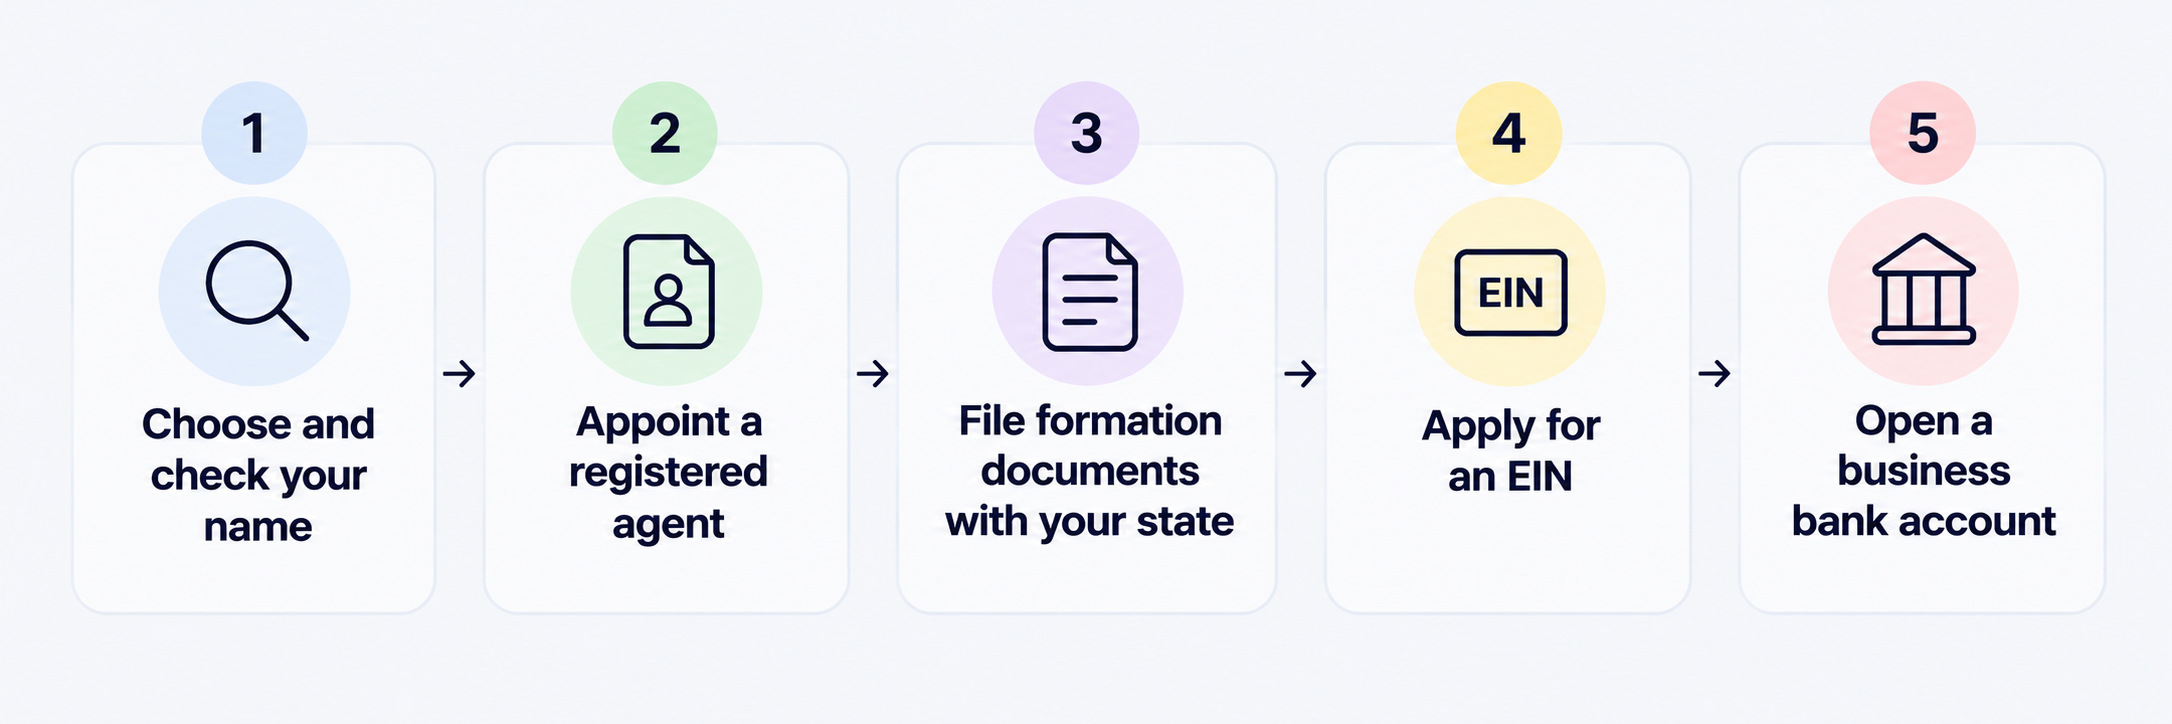
You set up a single-member LLC in five steps: choose a name, appoint a registered agent, file formation documents with your state, get an EIN, and open a business bank account. The SBA’s guide to registering a business sets out the same sequence. The details vary by state, so check your state’s Secretary of State or business agency website before you file.

Five-step checklist for setting up a single-member LLC.
  1. Choose and check your name: State registration protects your entity name at the state level, and most states won’t let you register a name another business already holds. Search your state’s business register before you commit to one, and check that the matching domain is free.
  2. Appoint a registered agent: This is the person or service that receives official papers and legal notices for the LLC, and the agent must have an address in the state where the LLC is registered. Many owners pay a registered agent service rather than use their own address.
  3. File your formation documents: For an LLC, these are usually called the articles of organisation. Most states take them through the Secretary of State or a business agency, some online and some by post. The SBA usually puts the total cost under $300, though fees vary by state. An operating agreement is widely recommended even where your state doesn’t require one: it records how the LLC is run, and for a single owner, it also helps show the LLC is genuinely separate from you.
  4. Apply for an EIN: An EIN is the IRS’s nine-digit number for your business. Applying is free through the IRS, so avoid any site that charges for it. The IRS says most new single-member LLCs need one, and you’ll need one for employees, for excise taxes, or to open a bank account.
  5. Open a business bank account: Keep the LLC’s money separate from yours from day one. Banks usually ask for your formation documents and EIN, and a separate account is the simplest way to protect the liability separation described earlier.

After you register, check whether your state wants anything further. Some states require an initial report within 30 to 90 days of registering, and some require a state tax ID depending on their income and employment tax rules. If you operate in more than one state, you may need to register as a foreign LLC in each of them, even if you’re a US resident. That’s a state-law term, not a reference to where you live.

Pros and cons of a single-member LLC

A single-member LLC is worth it when the liability protection and client credibility matter more to you than the added cost and admin, and it’s not worth it if you earn little and have no business debts to protect against. This table weighs each factor from both sides.

Factor What you gain What it costs you
Liability Limits your personal liability for the business's debts Doesn't cover personal guarantees or your own wrongdoing, and only holds if you keep finances separate
Tax Taxed as a disregarded entity by default, with no separate federal income tax return Self-employment tax still applies, and an S corp election adds payroll and a separate return
Cost A one-off state filing fee, usually under $300 according to the SBA Registered agent fees, and in some states annual reports or fees. Check your state's schedule
Admin A clear record of what belongs to the business A separate bank account, an operating agreement, and state filings to keep up with
Credibility A business name and EIN that clients' accounts teams can process No direct cost, but a client's own paperwork may still ask for more
Ownership abroad A non-resident can own one Extra IRS reporting can apply to foreign-owned LLCs, so get tax advice first

‍

The pattern is that the protection and the credibility come with a fixed cost and a regular admin routine. If you’re a freelancer with few assets and a single client, a sole proprietorship may be enough until your income or your risk grows. If you sign contracts, hold stock, employ people or work with larger clients, the case for an LLC gets stronger.

Getting paid as a single-member LLC

Once the LLC and its bank account exist, the next question is how clients pay it. US clients usually pay by bank transfer into a US account, while overseas clients may need to pay in euros or pounds. If your clients are spread across currencies, or you run the LLC from outside the US, a business account that holds several currencies can save you from collecting each payment through a separate route.

You can open a Grey Business account for your LLC to hold USD, EUR and GBP in one place. Grey is a financial technology company, not a bank: banking services are provided by licensed banking partners. Its invoicing tool is free, lets you send an invoice by email or download it as a PDF, and automatically fills in your Grey account details, so a client can pay in the currency they’re sending.

If your clients are in the US, get paid from the US covers how to receive money from the US. If your LLC pays contractors or relatives in India, you can also send money from the US to India. Whichever route you use, keep the business’s income in the business account and pay yourself from it, so your records stay clear for tax time.

Before you move money, check three costs: the fee charged when money arrives, the fee for converting between currencies, and the exchange-rate margin. The margin is built into the rate rather than shown as a line item, so Grey states it up front in the app before you confirm a transaction.

Frequently asked questions

What is a single-member LLC?

A single-member LLC is a limited liability company with one owner. It's a legal entity separate from you that limits your personal liability for business debts, and by default, the IRS ignores it for income tax and taxes the profit on your personal return.

How is a single-member LLC taxed?

By default, it’s taxed as a disregarded entity, so you report the profit on your own return, usually on Schedule C, and pay self-employment tax on net earnings. You can instead elect corporate or S corporation treatment, which changes how profits and salaries are taxed and adds payroll and filing requirements.

Do I need an EIN for a single-member LLC?

Usually, yes. The IRS says most new single-member LLCs need an EIN, and you need one if you have employees or excise tax liability. You’ll also use it to open a business bank account.

How do I set up a single-member LLC?

Choose a name, appoint a registered agent, file your formation documents with your state, apply for an EIN, and open a business bank account. State fees vary, and the SBA usually puts the total cost under $300.

Does a single-member LLC protect my personal assets?

Generally, yes: it limits your personal liability for the LLC’s debts, so creditors of the business normally can’t reach your own property. It doesn’t protect debts you’ve personally guaranteed, and the protection can be lost if you mix personal and business money.

Can a non-resident own a single-member LLC?

Yes, a non-resident can own a US LLC. If you have no US address, the IRS’s online EIN application isn’t available to you, so you apply by phone, fax or post using Form SS-4, and the IRS instructions for Form SS-4 explain how to complete it without an SSN or ITIN. A foreign-owned single-member LLC may also have to file Form 5472 each year, so take advice from a certified tax professional before you form one.

Get paid in USD with Grey

How to verify a company EIN number: Free lookup methods

•

•

2 min read

An Employer Identification Number (EIN) is a nine-digit number the IRS assigns to businesses for tax reporting and identification. If you work with a new supplier, verify a company’s tax details, or prepare business documents, you may need to confirm that its EIN is valid.

However, finding a company’s EIN is not always straightforward. The IRS does not provide a public database where anyone can search for any business’s EIN. Your options depend on the type of company and your reason for checking its details.

Fortunately, there are several free methods you can use. You can request a signed Form W-9 directly from the business, search SEC EDGAR filings for publicly traded companies, or use the IRS Tax Exempt Organization Search to find eligible nonprofits. If you file information returns, the IRS TIN Matching service may also help you verify taxpayer identification details.

This guide explains how to complete an employer identification number lookup using these methods, what information you can access, and when each option is appropriate.

Can you look up any company's EIN?

No, you can't look up every company's Employer Identification Number (EIN) through a single public database. The IRS does not provide a public search tool that reveals the EIN of every registered business. This restriction helps protect business tax information from unauthorised access and misuse.

However, some EINs are publicly available. For example, you can find tax identification details in certain public company filings on SEC EDGAR or search for eligible nonprofits through the IRS Tax Exempt Organization Search.

Who can verify a company's EIN depends on the situation. Business owners can confirm their EIN through IRS notices and tax records. Banks, employers, and other authorised organisations may verify taxpayer identification details when permitted and necessary for their responsibilities. Businesses can also request a completed Form W-9 from vendors or contractors to confirm the information provided for tax reporting.

If you need to verify an EIN, start by asking the company directly or checking the relevant public records. The appropriate method depends on the company's status and your reason for verification.

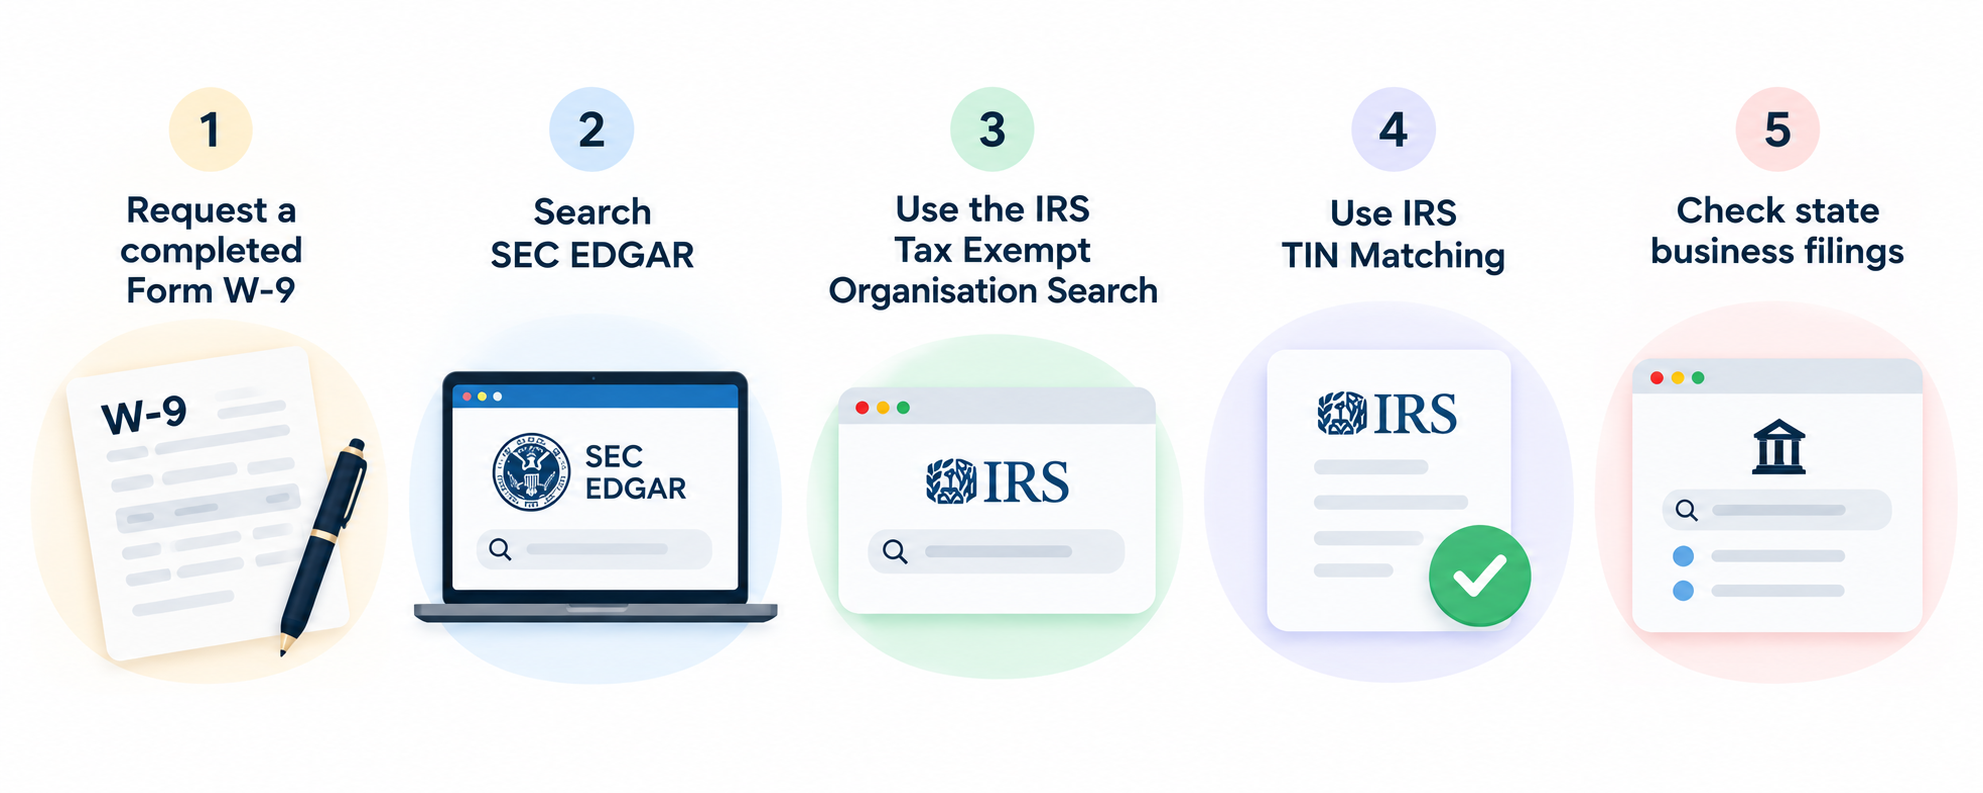
Five free ways to verify a company EIN

Five free ways to verify a company EIN.

1. Request a completed Form W-9

Ask the company to provide a signed Form W-9 containing its legal business name and taxpayer identification number. This is one of the simplest ways to obtain an EIN for vendor payments and tax reporting. Compare the details with your business records before proceeding.

2. Search SEC EDGAR

Publicly traded companies may disclose their EINs in regulatory filings. Visit SEC EDGAR and search for the company's name. Review relevant filings, such as annual reports, for available tax identification details. Not every filing includes an EIN.

3. Use the IRS Tax Exempt Organisation Search

If the company is a nonprofit, use the IRS Tax Exempt Organisation Search to find eligible organisations and review their publicly available tax records. This tool is not designed to look up every for-profit business.

4. Use IRS TIN Matching

Businesses authorised to use IRS TIN Matching can check taxpayer identification information against IRS records for eligible payees when filing information returns. This service is restricted to qualifying payers and cannot be used for unrestricted public searches.

5. Check state business filings

Visit the relevant state's official business registry to search for the company's registration details. Some filings may include federal tax identification information, but many do not. Start with the state's official government website, as access and available records vary by state.

Also read: How to complete a W-8BEN form as a non-US resident

How to find your own EIN

If you have misplaced your Employer Identification Number (EIN), you do not need to apply for a new one immediately. There are several ways to recover your existing number, depending on the records you have and whether you have previously used it for business activities.

1. Check your CP 575 confirmation letter. When the IRS assigns your EIN, it sends a confirmation notice called CP 575. Check your business files, emails, or saved documents for this letter, which contains your EIN.

2. Review previous tax returns. Look at your federal business tax returns and other tax documents. Your EIN is typically listed near the top of the relevant forms.

3. Contact your bank. If you used your EIN when opening a business account, your bank may have it on file. Contact your bank and ask how to retrieve your business tax identification details. If you are still setting up your finances, learn how to open a business bank account to understand the documents you may need.

4. Call the IRS. Contact the IRS Business and Specialty Tax Line at 800-829-4933, Monday through Friday, 7 a.m. to 7 p.m. local time. After verifying your identity and authorisation, an IRS representative can help you recover your EIN.

Paying verified vendors and contractors abroad

Paying an overseas contractor involves more than sending money. You also need the right tax documents and a reliable way to deliver their payment. For foreign individuals working outside the US, request Form W-8BEN when applicable to document their foreign status for US tax purposes. Foreign entities may need Form W-8BEN-E instead.

Once you have verified the contractor's details and confirmed the appropriate tax documentation, you can arrange payment. For example, if your LLC hires a developer in the Philippines, you can use Grey to send money from the US to the Philippines and pay them through a supported transfer method.

If you also hire US-based independent contractors, understanding what a 1099 employee is can help you distinguish contractors from employees and understand your reporting responsibilities. The term “1099 employee” is informal; independent contractors are generally not classified as employees for tax reporting.

For businesses managing multiple international payments, you can open a Grey Business account to explore tools for paying vendors and contractors across borders.

Frequently asked questions about a company EIN number

1. Is there a free EIN lookup?

Yes, you can find some company EINs for free through public records. Try SEC EDGAR for publicly traded companies or the IRS Tax Exempt Organisation Search for eligible nonprofits. However, there is no single public IRS database that lists every company's EIN.

2. How do I verify an EIN with the IRS?

If you are an eligible payer filing information returns, you can use the IRS TIN Matching service to check taxpayer identification details. Business owners who have lost their EIN can contact the IRS Business and Specialty Tax Line for assistance after verifying their identity.

3. Can I find a company's EIN online?

Sometimes. Public company filings, nonprofit tax records, and certain business documents may disclose an EIN. Search official sources such as SEC EDGAR or the IRS Tax Exempt Organisation Search. If the number is not publicly available, ask the company directly for a completed Form W-9.

4. How do I find my own EIN?

Check your IRS CP 575 confirmation letter, previous business tax returns, or bank records. If you cannot locate your number, contact the IRS Business and Specialty Tax Line at 800-829-4933. After verifying your identity and authorisation, an IRS representative can help you recover it.

5. Is an EIN public information?

An EIN is not universally public information. Some businesses disclose it in public filings, while other companies' EINs may not be readily available. Although you can access certain tax identification details through official records, the IRS does not provide unrestricted public access to every business's EIN.

6. Is an FEIN the same as an EIN?

Yes, an FEIN (Federal Employer Identification Number) generally refers to the same nine-digit federal tax identification number as an EIN. Businesses use this number for tax reporting, banking, hiring employees, and other official purposes. The term FEIN simply emphasises that the identification number is federal rather than state-issued.

11 best business bank accounts to have in the US

•

•

2 min read

Choosing the right business account in the US can make a real difference in how you manage your company’s money, from receiving customer payments to paying suppliers and tracking everyday expenses. However, with so many banks and financial platforms offering different account types, fees and features, knowing which one fits your business can be difficult.

The best business bank accounts pair low or waivable monthly fees with strong online banking, cards and integrations. The right one depends on your size, transaction volume and whether you handle international payments. Compare fees, minimums and features side by side before opening one.

For example, a freelancer receiving occasional payments may prioritise low fees and simple digital banking, while a growing company may need higher transaction limits, cash deposit options and tools for managing payroll. If you work with international clients or suppliers, access to cross-border payments and multiple currencies may also influence your decision.

This guide compares 11 business bank accounts available in the US, highlighting their fees, minimum balance requirements, key features and suitability to help you choose an account that works for your business.

Also read: Best business bank accounts for an LLC

How to choose a business bank account

Choosing a business bank account starts with understanding how your business earns, spends and manages money. The right account should support your daily operations without adding unnecessary costs or making payments difficult to track.

Fees and charges: Compare monthly maintenance fees, transaction limits, cash deposit charges, wire transfer costs and ATM fees. An account advertised as free may still charge for certain services.

Minimum balance requirements: Check the opening deposit and ongoing balance requirements. If your cash flow fluctuates, choose an account with no minimum balance or an achievable fee waiver.

Banking tools: Look for reliable online banking, mobile cheque deposits, debit cards, accounting software integrations and payment processing. Growing businesses may also benefit from payroll support and cash management tools.

Access and eligibility: Confirm that your business structure qualifies, whether you can apply online and which documents you need. Some providers require a US address, while others have additional residency restrictions.

If you receive international payments, compare foreign exchange rates, supported currencies and transfer fees before deciding. Your account should fit your current needs while leaving room for your business to grow.

11 best business bank accounts in the US

The following comparison ranks 11 business banking options by monthly fees, key features, limitations and suitability, helping you identify the right fit for your company's size, cash flow and banking needs.

Rank Bank / Platform Monthly Fees and waivers Core pros Core cons Best for
1 Chase Business Complete Banking $15; waivable with qualifying balances or activity Card processing, extensive branch network, credit card options Wire fees, cash deposit limits, no interest Storefronts needing branch access
2 Mercury $0 standard tier; paid plans available Digital tools, wire transfers, API integrations No physical cash handling, premium features cost extra Tech startups and online businesses
3 Bluevine $0 Standard plan; paid tiers available Interest potential, sub-accounts, accounting integrations Conditions for earning interest, wire fees Online businesses prioritising interest
4 U.S. Bank Business Essentials $0 monthly fee Branch access, no ongoing maintenance fee Transaction limits, credit approval requirements Small retailers
5 Bank of America Business Advantage $16; waivable with qualifying balance Rewards programme, national network, credit integration Balance requirements, potential extra fees Established businesses
6 American Express Business Checking $0 monthly fee Interest potential, Membership Rewards, support No cash deposits, limited branch access Existing Amex customers
7 Relay $0 basic plan; Pro costs extra Multiple sub-accounts, team access, bill management Some tools require paid plan, ATM fees Growing teams and agencies
8 Novo $0 monthly fee Invoicing tools, ATM fee refunds, online dashboard No built-in interest, limited user controls Freelancers and sole proprietors
9 Wells Fargo Navigate Business Checking Tiered fees; waivers may apply Branch network, cash handling, lending services Fees and service costs vary Cash-heavy businesses
10 Found $0 base tier; paid Plus plan Tax tracking, receipt capture, invoicing Limited international features, fewer team tools Sole proprietors and independent contractors
11 Rho $0 platform fee; service eligibility applies Corporate cards, expense controls, accounts payable US business eligibility restrictions, credit criteria Established companies managing expenses

‍

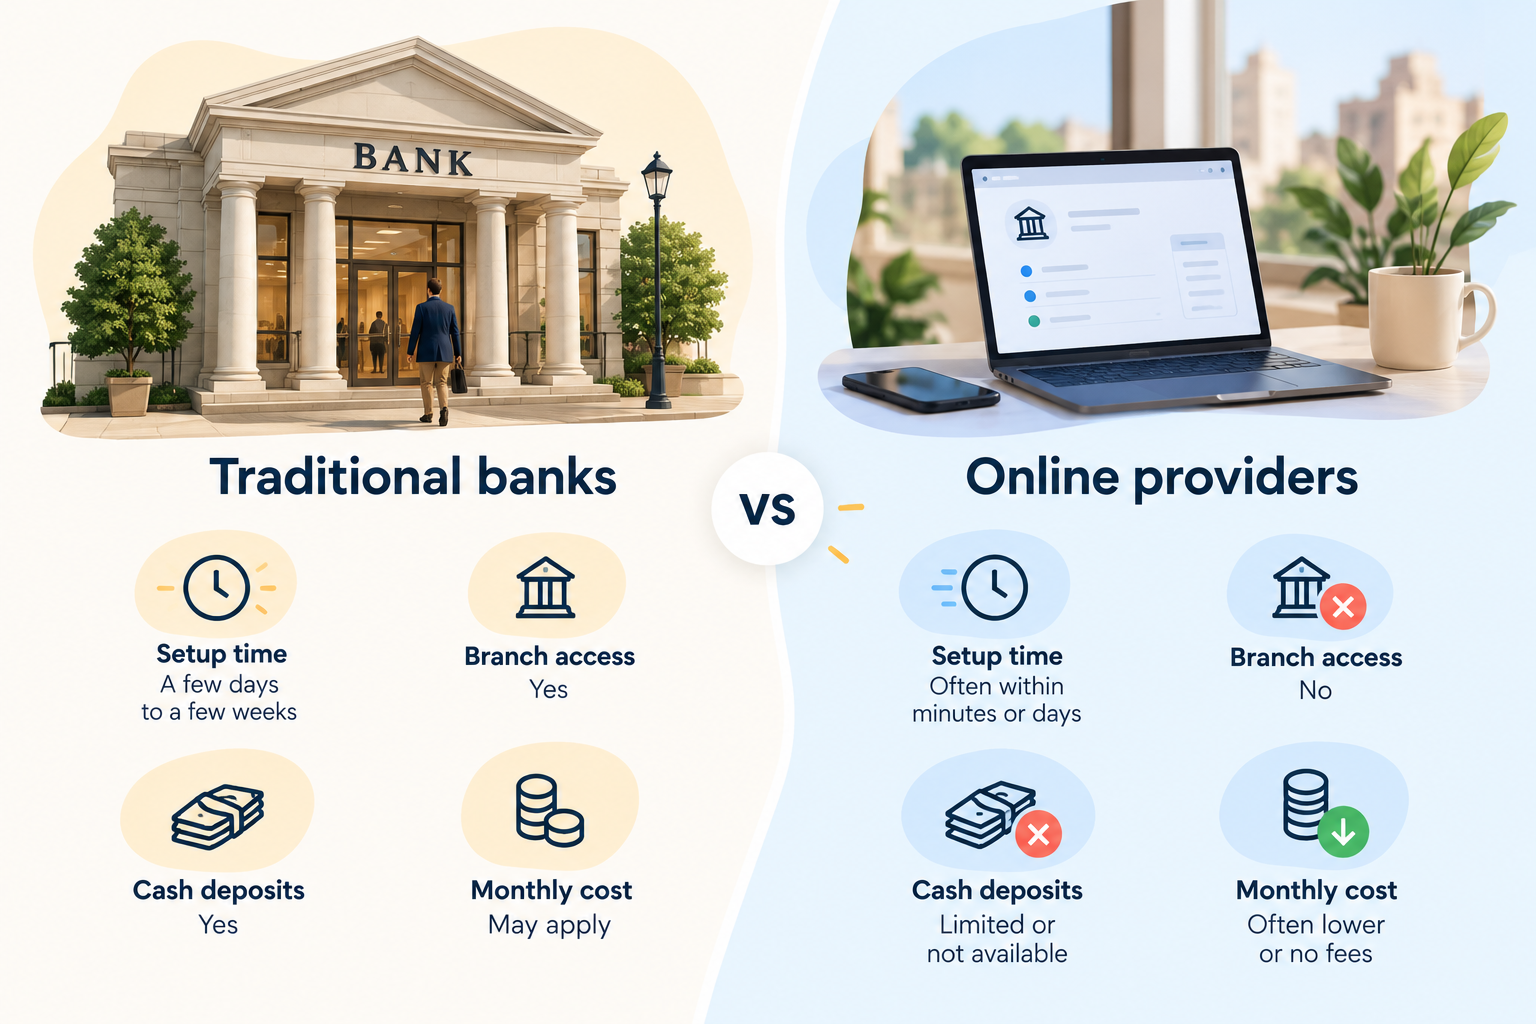
Traditional banks vs. online providers for your LLC

When choosing a business bank account for your LLC, consider how you receive payments, manage expenses, and access your money. Traditional banks and online providers offer different benefits, so the right choice depends on how your business operates.

Traditional US banks compared with online business account providers on setup time, branch access and fees.

Traditional banks such as Chase, Bank of America, and U.S. Bank give you access to physical branches. You can deposit cash, speak with bank staff, and explore business loans or other financial services. However, some accounts charge monthly maintenance fees unless you meet specific requirements.

Online providers such as Bluevine, Mercury, Relay, and Grey let you manage your finances digitally. While Bluevine, Mercury, and Relay offer business banking tools, Grey supports cross-border payments, making it useful for businesses that send or receive money internationally. Online providers may offer lower fees, faster account setup, and convenient payment management. However, cash deposits and in-person support may be limited.

Before you decide, compare monthly fees, transaction limits, deposit options, and eligibility requirements. If you need branch access, a traditional bank may suit you better. If you value convenience and digital payments, an online provider may be the better fit.

Also read: Can non-residents open a US bank account online in 2026?

Adding international payments

Opening an LLC in the US can help you establish your business, but what happens when your customers, suppliers, or team are in different countries? You need a simple way to move money across borders without disrupting your day-to-day operations.

That is where Grey comes in. With Grey, you can send and receive money from the US to support international business transactions, whether you are collecting payments from clients or paying partners overseas. Instead of relying on your traditional business bank account for every cross-border transaction, you can add a dedicated payment solution to your setup.

To get started, open a Grey Business account and explore the options available for your business.

Frequently asked questions about the best business bank accounts to have in the US

What is the best business bank account for an LLC?

The best business bank account depends on your LLC’s needs. Chase and Bank of America offer branch access, while Bluevine, Mercury, and Relay provide digital banking tools. Compare fees, transaction limits, payment options, and eligibility requirements to find an account that suits your business.

Which business bank account has the lowest fees?

Online providers such as Bluevine, Mercury, and Relay offer business accounts with no monthly maintenance fees on certain plans. However, other charges may apply for specific transactions or services. Compare each provider’s fee schedule and account requirements before making your decision.

Can I open a business bank account online?

Yes, many banks and online providers let you apply for a business bank account online. You will typically need your LLC formation documents, identification, and business details. Approval times and requirements vary by provider, so check the application process before applying.

Do I need an EIN to open a business bank account?

Many banks require an Employer Identification Number (EIN) to open an LLC business account. Some single-member LLCs may qualify to use other tax identification details, depending on the bank’s policies. Check the provider’s requirements and obtain an EIN from the IRS if needed.

What about international payments for my LLC?

If your LLC works with overseas clients or suppliers, look for accounts that support international transfers and multiple currencies. Grey can complement your business banking setup by helping you send and receive money from the US. Compare transfer fees, exchange rates, supported currencies, and eligibility before choosing a provider.

Are online business bank accounts safe?

Online business accounts can offer strong security features, including encryption, multi-factor authentication, and transaction monitoring. However, protections vary by provider. Check whether deposits are held at an FDIC-insured bank, understand applicable coverage limits, and review the provider’s security policies before opening an account.

PNC business account: Fees, features and how to open

•

•

2 min read

Choosing the right business bank account can make it easier to manage daily expenses, receive customer payments and keep your business finances organised. However, monthly maintenance fees, transaction limits and minimum balance requirements can affect how much you pay for banking services. If you are considering a PNC Bank business account, understanding these costs and features can help you decide whether it suits your business needs.

PNC offers several business checking accounts designed for businesses with different transaction volumes and banking needs. Each account comes with its own fee structure, transaction allowances and requirements for waiving monthly maintenance fees. Depending on the account you choose, maintaining a qualifying balance may help you avoid these charges.

Opening an account is also relatively straightforward, with options to apply online or visit a branch. You will generally need your employer identification number (EIN), business formation documents and valid identification. This guide covers PNC business account fees, key features, eligibility requirements and how to open an account, helping you understand what to expect before applying.

Also read: Best business bank accounts for an LLC

PNC Business account options: which checking tier fits your business?

PNC offers several business checking options designed for different transaction volumes, cash handling needs and business sizes. Choosing the right tier depends on your monthly activity, available balance and financial management needs.

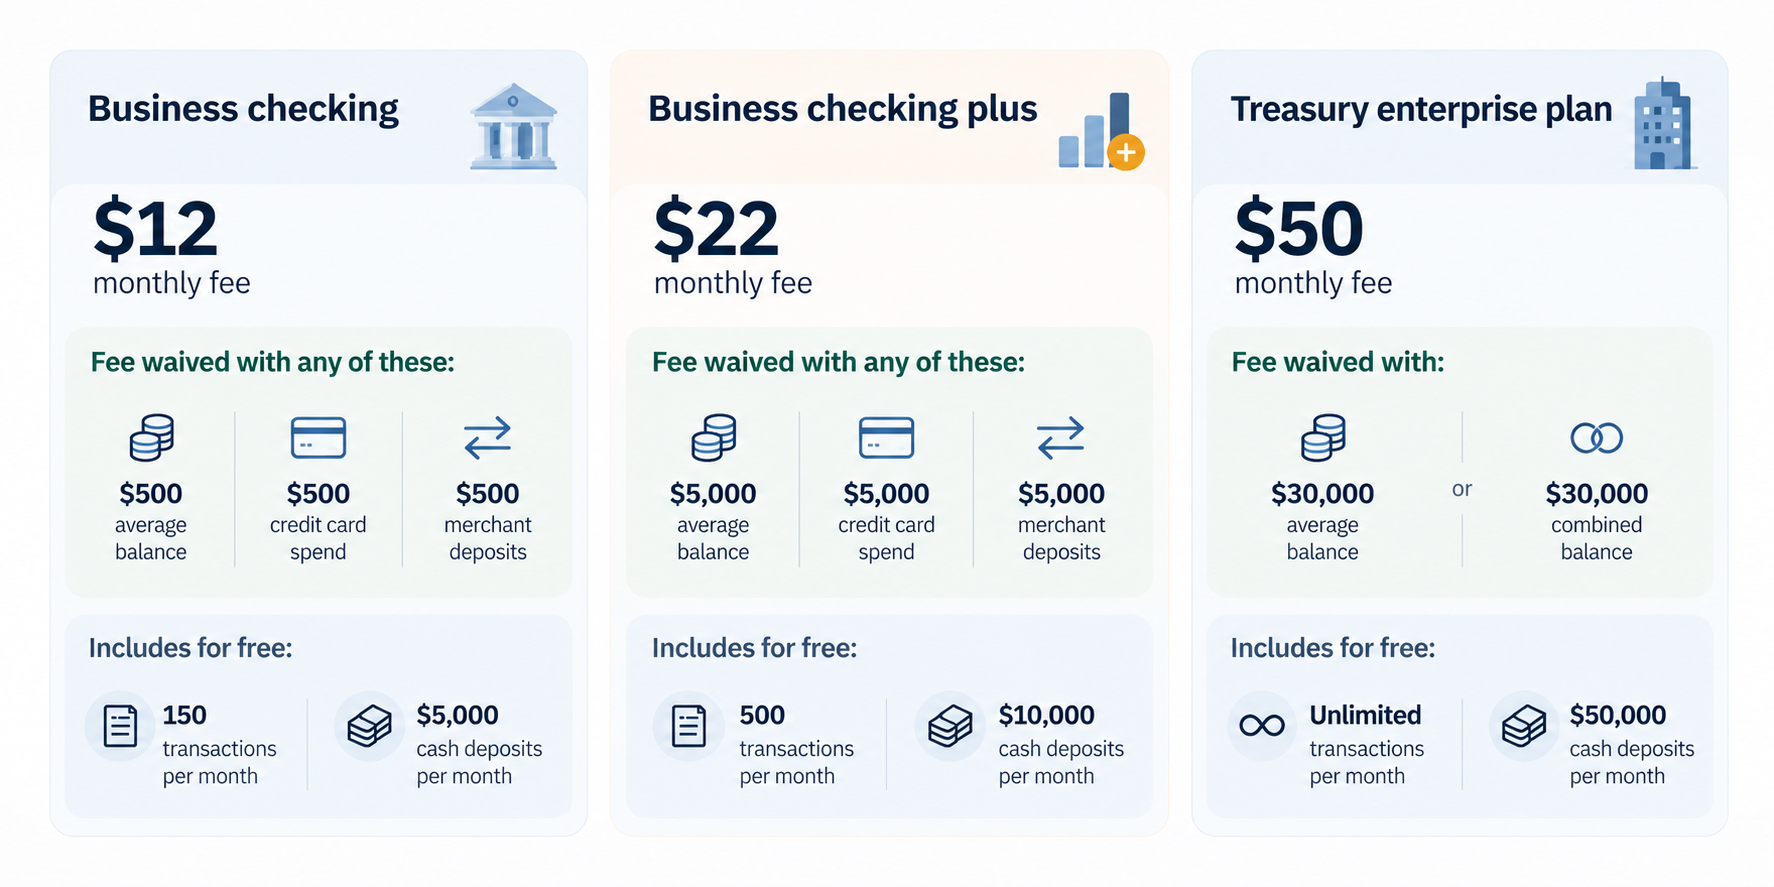
Business Checking: Best for freelancers, sole proprietors and micro-businesses with fewer transactions. Its $500 balance waiver threshold can help eligible account holders avoid the monthly maintenance fee.

Business Checking Plus: Suits local retailers, storefronts and growing businesses that handle more payments. It accommodates up to 500 monthly items and $10,000 in cash deposits before additional charges may apply.

Treasury Enterprise: Designed for businesses managing multiple entities or accounts. It allows up to four linked accounts to qualify toward a combined $30,000 balance requirement.

Analysis: Best suited to large enterprises with substantial cash flows. Earnings Credits can help offset eligible account service charges, making it worth considering for businesses with complex treasury management needs.

PNC business checking line-up (2026)

Account tier Monthly fee /
waiver minimum
Free transactions Free cash deposits Ideal for
Business Checking $12 / $500 balance 150/month $5,000/month Freelancers, side hustles and startups
Business Checking Plus $22 / $5,000 balance 500/month $10,000/month Growing businesses and local retailers
Treasury Enterprise Plan $50 / $30,000 combined balance Unlimited across linked accounts $50,000/month Established mid-sized businesses
Analysis Business Checking Variable / Earnings Credit Custom Custom Large enterprises with complex cash flows

‍

PNC business account fees and how to avoid them

 Graphic showing how a monthly business checking fee can be waived by meeting a balance requirement.

1. Business checking — $12 monthly fee

How to avoid the fee:

  • Maintain a $500 average monthly balance.
  • Spend $500 on a linked PNC Business Credit Card.
  • Process $500 in deposits through a linked PNC merchant account.

How to avoid extra charges:

  • Keep monthly transactions within the 150 free-item limit.
  • Keep monthly cash deposits within the $5,000 free allowance.

2. Business checking plus — $22 monthly fee

How to avoid the fee:

  • Maintain a $5,000 average monthly balance.
  • Maintain a combined $20,000 balance across eligible linked checking and money market accounts.
  • Spend $5,000 on a linked PNC Business Credit Card.
  • Process $5,000 in deposits through a linked PNC merchant account.

How to avoid extra charges:

  • Keep monthly transactions within the 500 free-item limit.
  • Keep monthly cash deposits within the $10,000 free allowance.

3. Treasury enterprise plan — $50 monthly fee

How to avoid the fee:

  • Maintain a $30,000 average monthly balance.
  • Alternatively, maintain a combined $30,000 balance across eligible linked corporate accounts.

How to avoid extra charges:

  • Enjoy unlimited transactions across linked accounts.
  • Keep monthly cash deposits within the $50,000 free allowance.

PNC Business account features and tools

PNC provides digital banking, business debit cards, payment processing and cash management tools to help businesses handle everyday transactions, monitor cash flow and manage finances more efficiently.

Digital tools: PNC Business Online Banking and mobile deposit capabilities help business owners check balances, review transactions, deposit eligible checks and manage accounts without visiting a branch.

Cards: Eligible account holders can access PNC Bank Visa Business Debit cards for convenient business purchases. The Purchase Payback® programme may offer cash-back rewards on qualifying purchases from participating merchants, subject to applicable terms.

Integrations: Businesses with more complex financial needs can use PINACLE®, PNC's treasury management platform, to access cash management services and tools that support cash-flow forecasting, payment management and account visibility.

Payment processing: PNC Merchant Services helps businesses accept customer payments and manage transactions. When used alongside available cash-flow tracking tools, these services can make it easier to monitor incoming payments, reconcile transactions and manage accounts receivable.

Together, these features give businesses tools to manage routine banking, track incoming funds and oversee payments. Availability, eligibility and fees may vary by account type and service, so review PNC's current terms before enrolling.

Also read: How to open a business bank account

Handling international payments

While a PNC business account can help you manage everyday banking in the US, businesses working with international clients, suppliers or remote teams may need additional options for cross-border payments. This is where Grey can complement your banking setup.

With a Grey Business account, eligible businesses can send and receive money from the US, making it easier to manage international payments when working with American clients, paying overseas suppliers or serving customers across borders.

Grey adds a multi-currency layer to your financial operations, helping you handle international transactions alongside your regular business banking. Before choosing a service, review supported currencies, transfer fees, exchange rates and account eligibility to understand the costs involved.

Frequently asked questions

1. What business accounts does PNC offer?

PNC offers several business checking options, including Business Checking, Business Checking Plus, Treasury Enterprise Plan and Analysis Business Checking. Each serves different needs, from freelancers and small businesses to larger companies managing substantial cash flows. The right account depends on your transaction volume, cash deposits and treasury management requirements.

2. What are the fees?

Monthly maintenance fees vary by account tier. Business Checking costs $12, Business Checking Plus costs $22, and Treasury Enterprise Plan costs $50, based on the fee schedule outlined above. Analysis Business Checking has variable fees. Eligible accounts may qualify for waivers by meeting balance or other requirements. Transaction and cash deposit limits may also trigger additional charges.

3. Can I open one online?

Yes, PNC allows eligible customers to apply for certain business checking accounts online. You can also visit a branch to complete the application. Availability may depend on your business structure, location and eligibility. Before applying, review the account requirements and prepare the necessary identification and business documents to help avoid delays.

4. What documents do I need?

PNC generally requires your business Tax Identification Number (TIN), or Social Security number for eligible sole proprietors, business registration documents and proof of authority to operate the business. You will also need identification. Online applicants need a valid email address. Requirements vary by business structure.

5. Is there a minimum balance?

PNC Business Checking has a $100 minimum opening deposit. This differs from the $500 average monthly balance that can waive its $12 maintenance fee. Other account tiers have different waiver requirements. You may avoid monthly fees through qualifying linked credit card purchases or merchant deposits, depending on the account.

6. How do I handle overseas payments?

You can use PNC international wire transfers to send money overseas or receive payments from abroad, although transfer fees and currency conversion costs may apply. For additional cross-border flexibility, eligible businesses can use a Grey Business account to send and receive money from the US. Compare fees and supported currencies before choosing a service.

Independent contractor vs employee: How to tell the difference

•

•

2 min read

A new job offer can feel straightforward until you reach the part of the contract that describes your employment status. The salary may look attractive and the role may seem like the right next step, but being hired as an independent contractor rather than an employee can change what you take home, who handles your taxes and whether you receive benefits such as paid leave or health insurance.

An independent contractor runs their own business and controls how they work, while an employee works under the employer's direction. Employers withhold tax and provide benefits for employees, but not for contractors, who handle their own taxes

The difference is more than a job title, and getting it wrong can leave you with unexpected tax bills or fewer workplace protections than you expected. In this guide, we’ll break down the key differences between an independent contractor and an employee, so you can understand where you stand before signing your next contract.

Independent contractor vs employee: Key differences

This table compares the main differences between contractors and employees, from workplace control and taxes to benefits, job security, tools, and financial risk.

Feature Independent Contractor Employee
Control Dictates own hours, methods, and routine Employer dictates schedule, location, and tasks
Tax Pays own income and self-employment taxes Employer automatically withholds income and payroll taxes
Benefits Responsible for own health insurance and retirement Eligible for company healthcare, 401(k), and PTO
Tools Provides own specialised equipment and software Employer provides necessary tools and equipment
Permanence Defined by project completion or contract end Indefinite, ongoing relationship until termination
Financial Risk Can experience a financial profit or loss Receives a guaranteed wage or salary

‍

What is an independent contractor?

An independent contractor is a self-employed person who provides services to a business or individual under a contract rather than working as a traditional employee. Think of a freelance designer hired to create a company’s new website, a consultant brought in to solve a business problem, or a writer paid to produce a series of articles. They work independently and are generally responsible for deciding how, when, and where the work gets done, as long as they deliver what was agreed in the contract.

In the US, independent contractors are commonly paid as 1099 workers, meaning businesses generally report their payments to the contractor using a Form 1099-NEC when applicable. Unlike employees, contractors typically do not have income tax, Social Security, or Medicare taxes withheld from their payments, so they need to plan for these taxes themselves.

Being an independent contractor also comes with responsibilities beyond completing the work. Contractors usually handle their own tax filings, business expenses, insurance and retirement planning, while keeping records of income and expenses. The trade-off is greater control over how they work and, in many cases, the ability to work with multiple clients.

What is an Employee?

An employee is a person who works for a company or organisation under an employment relationship, where the employer generally controls what work is done, how it is performed and when it is completed. Unlike an independent contractor, an employee works as part of the organisation and is typically entitled to protections and benefits provided under their employment arrangement.

W-2 Pay

In the US, employees are generally paid through payroll and receive a W-2 form from their employer at the end of the tax year. The W-2 reports their wages and the taxes already withheld from their pay.

Tax Withholding

Employers typically withhold federal income tax, Social Security and Medicare taxes from an employee’s wages and send these amounts to the relevant authorities. This means employees do not usually need to set aside the full tax amount themselves.

Employee Benefits

Depending on the employer and role, employees may receive health insurance, retirement plans, paid time off and other benefits. If you encounter the term “what a 1099 employee is,” it is important to understand that a 1099 worker is generally an independent contractor, not an employee.

How the IRS tests classification

The difference between an employee and an independent contractor is not always obvious from a job title or contract. A company might call someone a contractor, but the IRS looks at the actual working relationship to determine how that person should be classified for tax purposes. It generally considers three categories of control.

Behavioral Control

The IRS considers whether the business has the right to direct how, when and where the worker performs their job. Detailed instructions, set working hours, training and supervision can indicate an employee relationship.

Financial Control

The IRS looks at how much control the business has over the worker’s financial and business activities. Factors include who provides tools and equipment, whether expenses are reimbursed, how the worker is paid and whether they can make a profit or experience a loss.

Relationship Factors

The nature of the relationship also matters, including written contracts, employee benefits, how permanent the arrangement is and whether the worker provides services that are a key part of the business. No single factor determines classification; the IRS considers the entire relationship.

How taxes and paperwork differ for Contractors and Employees

Getting paid as a contractor or employee does not just change the amount that lands in your bank account; it also changes the paperwork you receive, who handles your tax withholding and what happens if your worker classification is wrong.

1099 vs. W-2

Employees generally receive a W-2 showing their wages and taxes withheld by their employer, while independent contractors typically receive a 1099-NEC for qualifying payments. Understanding 1099 vs. W-2 can help clarify how each worker is paid, what taxes are withheld, who is responsible for reporting income, and what paperwork to expect.

Self-Employment Tax

Contractors generally have to account for both the employer and employee portions of Social Security and Medicare taxes through self-employment tax, meaning they need to plan for these payments themselves rather than relying on payroll withholding.

Misclassification risk

Calling a worker a contractor does not automatically make them one. If a business treats an employee as an independent contractor, it may face additional taxes, penalties and other consequences, while the worker could miss protections and benefits they should have received.

How to pay contractors in the US and abroad

Paying a contractor can look simple until the person doing the work lives in another country. A US-based company might have a designer in the Philippines, a developer in Nigeria or a marketing consultant in Brazil, and suddenly the payment process involves exchange rates, transfer fees, payment details and waiting times.

This is where Grey can make contractor payments easier. Businesses can use Grey to pay contractors from the US and send payments internationally without having to navigate a complicated process for every contractor. The platform supports transfers across multiple currencies, allowing businesses to hold and convert funds before sending money to contractors in supported countries.

For example, a US company paying a contractor in the Philippines can use Grey to send money from the US to the Philippines, while the contractor receives the funds in the supported local currency. For businesses working with international talent regularly, having one place to manage these payments can make cross-border contracting much simpler.

Frequently asked questions

What is the difference between a contractor and an employee?

An employee works under an employer’s direction and typically receives payroll withholding and benefits, while an independent contractor runs their own business and controls how they complete their work. Contractors generally handle their own taxes, business expenses and insurance, while employees receive greater workplace protections and employer-provided benefits.

How does the IRS decide?

The IRS looks beyond a worker’s job title or contract and examines the actual working relationship. It considers behavioural control, financial control and the relationship between the worker and business. No single factor automatically determines classification, so businesses should consider the full arrangement when deciding whether someone is an employee or contractor.

Do contractors get benefits?

Independent contractors generally do not receive employee benefits such as employer-sponsored health insurance, paid vacation or retirement contributions. Instead, they are responsible for arranging their own insurance, retirement savings and other benefits. However, a contractor’s specific agreement can provide certain perks or payments, depending on what the business and contractor negotiate.

What is misclassification?

Misclassification happens when a business treats a worker as an independent contractor when the person legally qualifies as an employee. This can affect taxes, benefits and workplace protections. For the business, misclassification can lead to unpaid employment taxes, penalties and other costs, while the worker may lose benefits they should have received.

Can someone be both?

Yes, someone can potentially work as an employee for one business while independently contracting for another. For example, a person could have a full-time W-2 job and provide freelance consulting services to separate clients. However, the classification of each working relationship depends on the specific facts and circumstances involved.

How do I pay an overseas contractor?

Paying an overseas contractor typically involves choosing a payment method, confirming the contractor’s banking details and considering currency conversion, transfer fees and tax documentation. Platforms such as Grey can help businesses make international payments, allowing them to send money across borders without relying on traditional bank transfers for every contractor.

Arrow (up)

Back to top