How distributed teams manage expenses with virtual cards
Adeolu Titus Adekunle
TABLE OF CONTENT
SHARE THIS POST
When your designers are in Lagos, your developers are in Bangalore, your marketing lead is in Lisbon, and your finance manager is in Toronto, managing expenses across such a distributed team might be complicated. The usual approach of handing out a company card and collecting receipts at the end of the month, as in physical offices, doesn’t work when the team is spread across the globe.
Distributed teams definitely need better ways to manage expenses across board, and virtual cards seem like a promising solution. How virtual cards fit into that system? Can they solve this problem effectively? This article explains how distributed teams can manage their expenses with virtual cards.
What are the problems distributed teams face when managing expenses?
Before we show you how virtual cards work for distributed teams, it is important to understand the scope of the problem.
Access barriers: Imagine a physical card stuck with the CEO in Berlin, while a marketer in Manila tries to pay for a software subscription at midnight. The purchase either gets delayed or someone uses their personal card and submits a claim later.
Reimbursement problems: Employees pay bills on personal accounts, then wait days or weeks for reimbursement. The accounting team ends up with cash-flow disruptions, piles of receipts, and endless reconciliation work.
Oversight and security headaches: Issuing multiple physical cards across countries makes tracking who spent what, when, and whether it was approved nearly impossible. Cards get lost, compromised, or misused. Replacing them across borders is a logistical nightmare.
Currency conversion issues: A distributed team spends in multiple currencies. When accounting, the company would have to convert each local purchase back to its base currency at the card network’s prevailing rate at the time of the transaction. This already sounds like an accounting nightmare.
This is why virtual cards make a lot of sense. But are virtual cards really a magic bullet for international teams?
A virtual card is a payment card that exists entirely in digital form. It has a card number, an expiry date, and a CVV, exactly like a physical card. Still, it is issued instantly, managed through software, and can be created, modified, or cancelled without any physical infrastructure involved.
The payment process with virtual cards is the same as with physical cards. When a team member uses a virtual card to pay for a Figma subscription or a Google Workspace licence, the card network (Visa or Mastercard, depending on the issuing platform) sends an authorisation request to the issuing institution. The institution checks whether the transaction is permitted on the card and approves or declines in real time. This should be done within minutes or a couple of days.
What can you do with a virtual card?
Virtual cards give you more control, which comes in handy when managing a distributed team. Here are some things you can set on a virtual card:
Spending limits. Each virtual card can be issued with a maximum spend per transaction, per day, or per month. A card issued to a freelance designer for paying Figma has a $20 monthly limit. A card issued for running Facebook Ads campaigns has a $5,000 monthly limit. Neither card can be used to spend beyond those limits, regardless of who holds it, unless it is reviewed.
Merchant category locking. Most virtual card platforms let you restrict a card to specific merchant category codes (MCCs), which are the classification codes assigned to every business type by card networks. A card created for software subscriptions can be locked to the MCC codes for software and SaaS. If a transaction is initiated from a restaurant or retail store, it will be declined automatically because the card’s configuration prevents it.
Single-use cards. For one-off purchases, such as a team member booking a flight ticket, a single-use virtual card can be generated. This card is used once and automatically cancelled. The card number is useless after the transaction completes, so it cannot be used fraudulently even if it is intercepted or exposed in a data breach.
Recurring subscription cards. This is the direct opposite of single-use cards. You can link a card to recurring expenses, such as subscriptions. One can be a card for Notion and another for Slack or the team’s design tool. If any of those subscriptions is cancelled or the service provider is changed, the card is cancelled without affecting any other card in the system. More than you realise, many teams keep paying for subscriptions they no longer need, which can be avoided by using dedicated cards for recurring costs.
Real-time visibility. Every transaction on every virtual card is displayed on the platform’s dashboard as it happens, without waiting for a monthly statement or financial report. This means errors can be detected in real time and sorted immediately.
How can distributed teams set up their virtual cards?
The way a team structures its virtual cards depends on team size, spending volume, and the degree of freedom individual team members have over work expenses.
Per-person cards: Each team member receives their own virtual card with a monthly spending limit tailored to their role and budget. A developer might have $200 per month for tools and learning resources. A marketing manager might have $2,000 per month for ads and marketing software. This approach works well for teams where individuals manage their own tooling.
Per-project cards: A single virtual card is created for each active project, depending on the budget. All spending related to that project is charged to that card. At the end of the project, the card is cancelled, and the spending is reconciled against the project budget.
Service cards: You can have one card per recurring vendor. All work-related tools and services from Notion and Slack to AWS, GitHub, Figma, and Loom can get their own card with the exact subscription amount as the limit. This removes the risk of vendor overcharging and makes subscriptions easier to manage. If you want to cancel a subscription, you can cancel the card.
Contractor cards: When a contractor is hired for a specific project and needs to make purchases on the company’s behalf, like paying for tools or running ads, they can be issued a virtual card with a defined budget and a defined expiry date. The card stops working once the project is completed or the budget is exhausted.
Managing foreign exchange problems with virtual cards
Distributed teams spend in multiple currencies, which creates a cost that is easy to underestimate when it is buried in card network conversion rates.
When a virtual card denominated in USD is used to pay for a subscription charged in EUR, the card network applies a foreign exchange conversion at the time of the transaction. Most card networks apply the Visa or Mastercard daily rate, which typically has a 1% to 1.5% markup above the mid-market rate. On top of that, the card issuing platform may add a cross-border transaction fee of 1% to 3%.
On a single $50 subscription, a 2.5% markup costs $1.25. While this might seem small, in the long run, across teams and campaigns, the cost might turn out significant.
A solution for high-volume distributed teams is to keep money in the currencies they use for payments and issue cards that draw from those balances rather than converting during payments. If a card is being funded from an EUR balance to pay EUR subscriptions, there is no conversion or conversion markup.
Maximising virtual cards across teams
Virtual cards solve a lot of problems for dispersed teams. But they still have their limitations. The company still needs to put measures in place to maximise the benefits and avoid loopholes.
Receipts: It is still important to collect receipts to help the finance team balance their accounting books and manage tax deductions.
Approvals: Even when cardholders can initiate transactions, approvals should still be in place. Teams that need pre-approval workflows where a manager signs off before a purchase is made, rather than reviewing it after.
Regular reviews: While it is easy to track spending across cards on most platforms, it can only work if someone is actually looking at it. Regularly review card spending against budgets and check for unused subscriptions, inconsistent transactions, and budget excesses.
Virtual card options for distributed teams
Here are some of the top virtual card recommendations for distributed teams managing international payments:
Airwallex: built for businesses that spend internationally. It issues virtual USD, EUR, and GBP cards, supports multi-currency accounts in over 23 currencies, and integrates with major accounting platforms. The foreign exchange rates are competitive relative to traditional bank cards. It is primarily designed for businesses rather than individuals, which makes it better suited to teams with formal company structures.
Deel: manages contractor payments and expense cards for distributed teams in a single platform. For teams already using Deel for international payroll, the expense card functionality extends naturally from the same infrastructure.
Brex/Ramp: are US-based corporate card platforms that have expanded their virtual card capabilities significantly. Both offer per-card limits, merchant restrictions, and real-time visibility. International use is more limited outside the US market, and both require a US entity for full access.
Grey: a FinCEN and FINTRAC-regulated payment platform that issues a virtual Visa card that connects directly to your available Grey multi-currency account (USD, EUR, and GBP). When a transaction is initiated, such as the engineering team paying for AWS cloud hosting in GBP, the card automatically debits the GBP currency balance, without requiring a manual top-up beforehand. The card supports Apple Pay and Google Pay, which means contactless payments online and in-store. Users can create multiple virtual cards for different purposes with their own limits and settings.
Fund your account to complete the request. A one-time creation fee of $5 is typical ($4 for the card and $1 credited to the balance)
Grey cards are secure with built-in 3DS protection and encryption, ensuring you verify transactions yourself, automatically flag suspicious activity, and prevent fraudulent transactions. It works with Google Pay and Apple Pay for online and contactless payments.
Grey offers a unique way for distributed teams to manage expenses with a virtual card that simplifies cross-border payments. Download the app today to get started and create your cards.
Vatican City, the heart of Catholicism and a landlocked enclave within Rome, is a place of immense historical, religious, and cultural significance. While this unique location might not be the first place you associate with freelancers or digital nomads, some of the professionals who live in Rome visit Vatican City relatively frequently.
These freelancers and professionals often deal with the complexities of managing cross-border payments. That’s where USD Coin (USDC) — a stablecoin pegged to the U.S. dollar — comes in. It’s revolutionising how payments are received and managed across borders.
This guide will show you how to use Grey to receive foreign currencies and convert them into USDC efficiently while in Vatican City.
International money transfer is one of the bedrocks of the rapidly growing global market. It connects people across countries and continents and makes international trade easy. In today's world, managing cross-border payments with ease is essential for migrants and expatriates in Asia. Whether it's sending money to family back home or receiving payments from abroad, they need a fast, reliable, and cost-effective solution.
For many reasons, Grey is the preferred choice for international money transfers among migrants and expatriates in Asia.
In this article, we explore why migrants and expatriates in Asia are choosing Grey for international money transfers.
The challenges of international money transfers faced by migrants and expatriates in Asia
Migrants and expatriates often face significant challenges when transferring money internationally. Here are some of those challenges.
High transaction fees: Traditional banks and remittance platforms charge exorbitant fees, which can eat into the funds sent or received.
Unfavourable exchange rates: Many traditional international payment options offer lower value for your money with their unfavourable exchange rates.
Slow processing time: International money transfers in Asia require long bureaucratic processes and a ton of paperwork. Sometimes, it might require days to process. This can be inconvenient for urgent payment needs.
Grey's international payment solution addresses these challenges. It offers innovative features and user-friendly services. Here are some reasons migrants and expatriates in Asia are choosing Grey for international money transfers
1. Multi-currency accounts
Grey provides international accounts in USD, GBP, and EUR. A multi-currency account allows users to receive payments directly in foreign currencies. This avoids the hassle of opening local bank accounts in different countries. Migrants and expatriates can hold and manage multiple currencies in a single, convenient app.
2. Competitive exchange rates
Grey offers highly competitive real-time exchange rates. Users can monitor the exchange rates and convert at the best possible rates.
3. Fast and seamless transfers
Grey enables instant international money transfers. You can send funds to family and friends quickly. You can also receive payments from overseas clients without delays.
4. Transparent and low fees
Grey is committed to transparency. It offers low transaction fees for transfers and conversions and no hidden charges.
5. Convenience and accessibility
With Grey, you can manage your finances effortlessly from anywhere and anytime.
6. Register with ease
You can create an account on Grey in a few quick steps. Create an account using the Grey website or download the app. Proceed to complete your Know Your Customer (KYC) verification, and once verified, you can request your multi-currency account.
You can get a virtual USD card within minutes of creating an account. This USD card integrates seamlessly with any payment platform that allows MasterCard, providing financial flexibility.
Migrants and expatriates in Asia deserve a smarter way to manage their finances. This is why migrants and expatriates in Asia are choosing Grey for international money transfers. Grey combines the power of multi-currency accounts, competitive rates, and fast transfers into one platform.
Migrant workers and expatriates often face challenges with international transactions. From sending remittances and receiving salaries, to making investments, covering travel expenses and managing their savings, navigating financial systems across multiple countries can be complex and frustrating.
However, having US and UK bank accounts makes this easier. It offers greater convenience and financial flexibility. With reliable cross-border payment platforms like Grey, you can now create US and UK bank accounts remotely, without needing to visit these countries physically. This allows you manage your international financial transactions quicker and without breaking a sweat.
This article provides a step-by-step guide on how migrant workers and expatriates can create US and UK bank accounts.
Why migrant workers and expatriates need US and UK bank accounts
Many US and UK bank accounts can help migrant workers and expatriates in many ways, including:
Efficient remittances: While living abroad, you can easily send money to your loved ones in your home country using US and UK bank accounts with lower transaction fees.
Direct access to salaries: Receive payments from employers or international clients directly in USD or GBP without losing money to conversion fees.
Simplified financial management: Hold and manage multiple currencies in one place to improve your bookkeeping.
Access to global financial services: Using a multi-currency account helps manage international payment platforms like PayPal, Stripe, or Wise seamlessly.
Save on currency conversions: Avoid losing money to unfavourable exchange rates when dealing with USD or GBP by opening a US and UK bank account.
Step-by-step guide to creating US and UK bank accounts with Grey
You can create US and UK bank accounts with Grey in these quick steps in a few minutes.
First, sign up on Grey
Getting started with Grey is simple:
Visit the website or app: Go to Grey’s official website or download the app on your smartphone.
Register your account: Provide your name, email, and phone number.
Create a password: Use a strong password to ensure account security. Your password should be a minimum of eight characters, including upper and lowercase letters, a number and a special character.
Verify your email: Enter the OTP sent to your registered email address to activate your account.
Next, complete the verification process
In compliance with global financial regulations and to protect you, Grey requires that you complete the Know Your Customer (KYC) verification process to gain complete access to your account. This requires you to:
Upload a valid ID: Submit a photo or scanned copy of your international passport, national ID, or any valid government-issued identification.
Provide proof of address: Upload a utility bill, rental agreement, or bank statement showing your residential address.
Upload your picture: Upload a clear picture of yourself.
Submit your details: Fill in your address and other information on the KYC form to complete the process.
The verification process should only take a short while unless there are issues with the validity or clarity your uploaded documents.
Once verified, request your US and UK accounts
Once your KYC verification is approved:
Go to your dashboard: Log in to your Grey account and navigate to the “Bank accounts” section.
Select the currency accounts: Choose “USD” for a US bank account and “GBP” for a UK bank account.
Receive account details: Grey will provide your US and UK account numbers, including routing codes or sort codes for seamless banking.
Finally, start using your accounts
Once you have your account details, you can:
Receive payments: Share your US or UK account details with employers, clients, or family members.
Send funds: Transfer money internationally at competitive exchange rates.
Withdraw locally: Move funds from your Grey account to your local bank or e-wallet.
Final thoughts
Managing international transactions used to be a tough nut to crack for migrant workers and expatriates anywhere in the world. However, with Grey, creating US and UK bank accounts has never been easier. You can enjoy simplified cross-border financial management, access to global banking services, and lower transaction fees when you use Grey.
Ready to take control of your finances? Sign up on Grey today!
The United Arab Emirates is a hub for global business and travel. Whether you're a freelancer, digital nomad, or frequent online shopper, managing international payments in USD is often necessary. However, traditional banks in the UAE make getting a USD debit card a slow and costly process.
With Grey, you can enjoy a fast, secure, and affordable way to get an instant USD debit card.
This guide explains how to get started and why a USD debit card is essential for global transactions.
Why you need a USD debit card in the UAE
Hassle-free online shopping: Buy from international stores like Amazon or eBay without dealing with dirham-to-dollar conversions.
Save on fees: Avoid high currency exchange rates and conversion charges.
Travel convenience: Pay for flights, hotels, and transport in USD while travelling abroad.
Subscription payments: Simplify payments for services like Netflix, Spotify, and Adobe in USD.
Next, complete the KYC (Know Your Customer) process by uploading a government-issued ID, such as a passport.
Pro Tip: If your KYC verification fails, it's likely due to unclear documents. Ensure your uploads are clear, complete, and valid. Learn more in Grey's KYC troubleshooting guide.
Step 2: Open and fund a foreign currency account
Once your KYC is approved, request a USD account through the app. This account will store your USD funds for transactions.
You'll need to fund your account via bank transfer to activate your virtual USD debit card.
Step 3: Get your virtual USD debit card
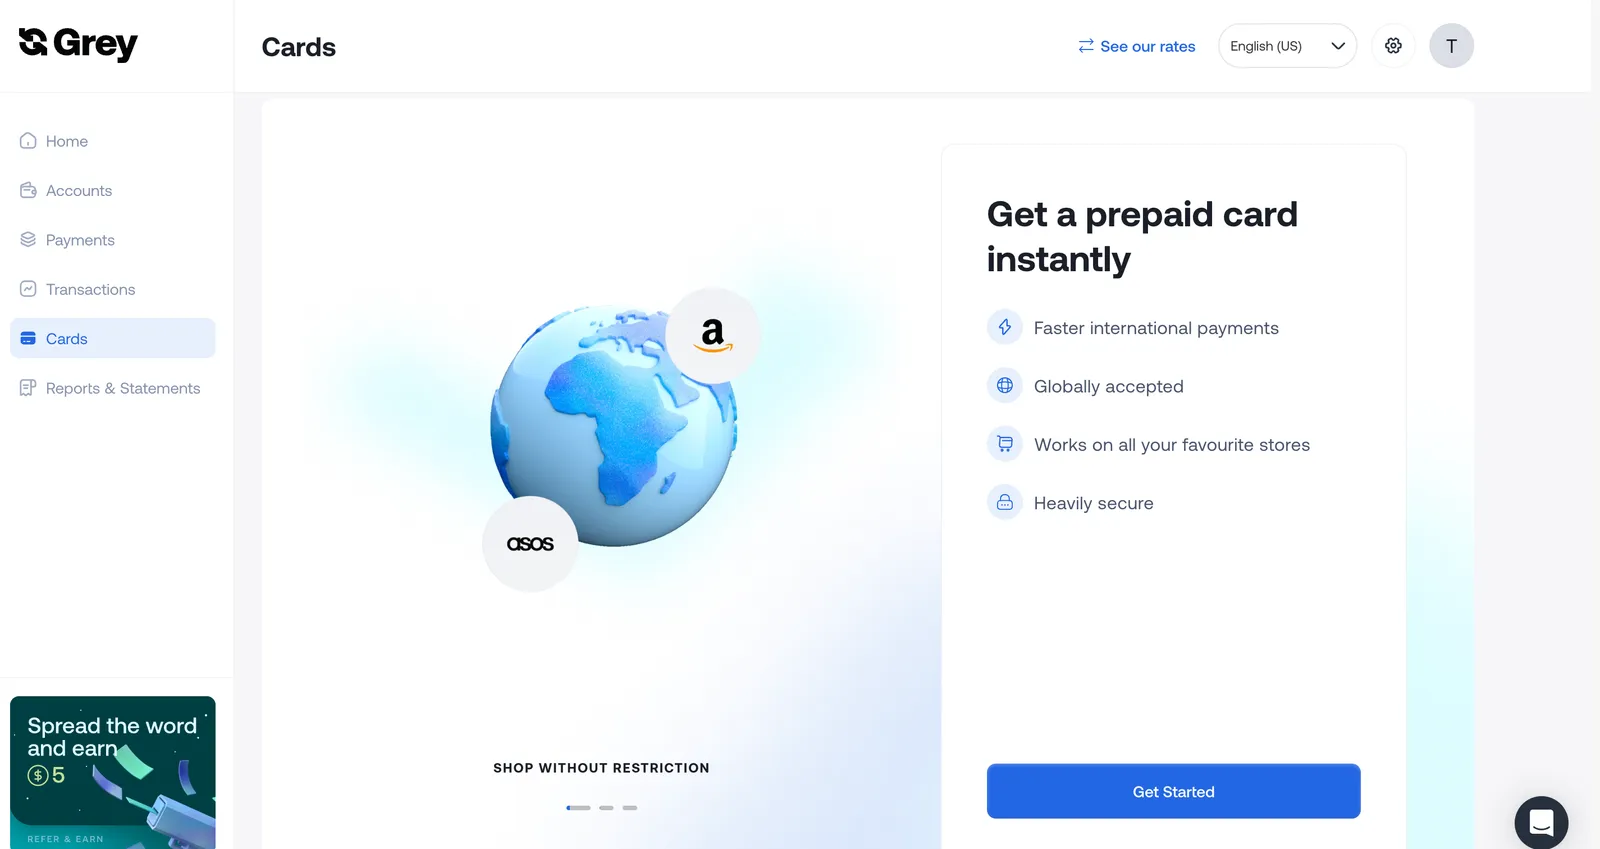
After funding your account, head to the "Card" section in the app and click "Get started."
To activate your virtual card, pay a one-time fee of $4 and deposit a minimum of $1. Once completed, your card will be ready for use.
Fast setup: Get your USD debit card instantly after completing the process.
Wide use: Make payments on any platform that accepts MasterCard.
Transparent fees: Enjoy low pricing with no hidden charges.
Secure transactions: Your payments are protected by advanced security measures.
Easy funding: Quickly transfer money to your card from your USD account.
Conclusion
A USD debit card is essential for those working or shopping internationally from the UAE. It simplifies global payments, reduces transaction costs, and provides financial flexibility. Whether paying for a subscription, shopping online, or travelling abroad, a Grey USD debit card makes it all easier. You can manage your global transactions seamlessly with instant access and no hidden fees.
Sign up with Grey today to get started on your journey to hassle-free international payments!
Amazon is the most popular online shopping platform, with over 310 million active users worldwide and over two million active sellers. It generates over $1.4 billion in sales every day.
Tanzanians widely use Amazon to purchase electronics and beauty/home care products. Apart from using Amazon as a platform to buy products, some Tanzanians use Amazon for other purposes, such as selling, promotions, and affiliate marketing products.
This article will discuss how you can receive Amazon payments in Tanzania.
But before that, let’s look at how people living in Tanzania make money through Amazon.
How Tanzanians can make money on Amazon
Amazon offers several ways for people to make money. For Tanzanians, there are two common ways people make money through Amazon. Those ways include directly from Amazon associates’ programs, a unique e-program for affiliate marketers, and Amazon Kindle Direct Publishing (Amazon KDP), which allows people to publish books directly on Amazon.
Below is how Amazon associates and Amazon KDP works:
Making money as an Amazon affiliate through the Amazon Associates program
Amazon has a unique program that awards users a commission for each sale they make through their affiliate links. This program is commonly known as the Amazon associate program.
Although the Amazon associate program is the most straightforward program for creators and affiliates, it has a few criteria you need to meet to be Eligible. Below are the requirements to meet to be accepted for the Amazon associate program
Eligibility criteria’s for the Amazon Associates program
The website you want to use to promote products should be owned by you and have a minimum of 10 blog posts with at least one blog article published within the last 60 days.
For promotions through mobile apps, your app should firstly look and function differently from Amazon’s shopping app, and it should be free in major app stores with original content
If you want to use social media to join a program, you need only an established following base and an active social media presence on platforms like Twitter(x), Instagram, Facebook, and TikTok.
Note: Although commissions differ in percentages depending on product categories, many products average between 3% and 5% commission per sale.
Making money by selling books through Amazon Kindle Direct Publishing (KDP)
This is a popular publishing service offered by Amazon. Through Amazon Kindle Direct Publishing, independent writers can upload their books and sell them worldwide as paperbacks, hardbacks, and ebooks in minutes.
Selling books on Amazon KDP has several perks, such as
You can get paid per page people read in your book
Amazon KDP offers special royalties, such as Amazon Kindle Unlimited. This program lets you earn money based on how many pages people read from your book.
You can earn up to 70% per each ebook you sold
Amazon KDP offers two royalty options for each ebook you sell. Two royalties’ options are 30% and 70%. Each loyalty option has requirements.
You can earn up to 60% on printed books.
Earn up to 60% royalty on paperback and hardcover books sold through Amazon KDP.
Note: For new Tanzania writers, selling books on Amazon KDP might be difficult, and thus Amazon KDP has unique systems that allow people to sell low- or medium-content books, which means selling colouring books, planners, word search books, and journals.
Now that you’ve made your first money through Amazon associates programs or Amazon KDP, the next step is receiving your payment.
Amazon offers two ways for associates and affiliates in Tanzania to receive their payments: Gift cards and International bank accounts.
1. Gift cards
With this option, you can use your earnings from Amazon’s affiliate program to purchase directly from the platform.
While this is an excellent option if you have short-term needs, there are also shipping fees to consider.
2. International bank account
Amazon pays directly to international bank accounts; all you need to have is either US, UK or Euro bank accounts from one among 52 Amazon-supported countries.
Tanzania is not among these 52 countries. This means that if you have a USD bank account domiciled in a non-supported country like Tanzania, you will not be able to receive your payments.
Fortunately, you can receive Amazon payments through your US, UK or Euro bank account with Grey, as these accounts are domiciled in supported countries.
For you to be able to receive payment through Grey, all you need to have is a foreign bank account from Grey. Follow these steps to open a foreign bank account from Grey.
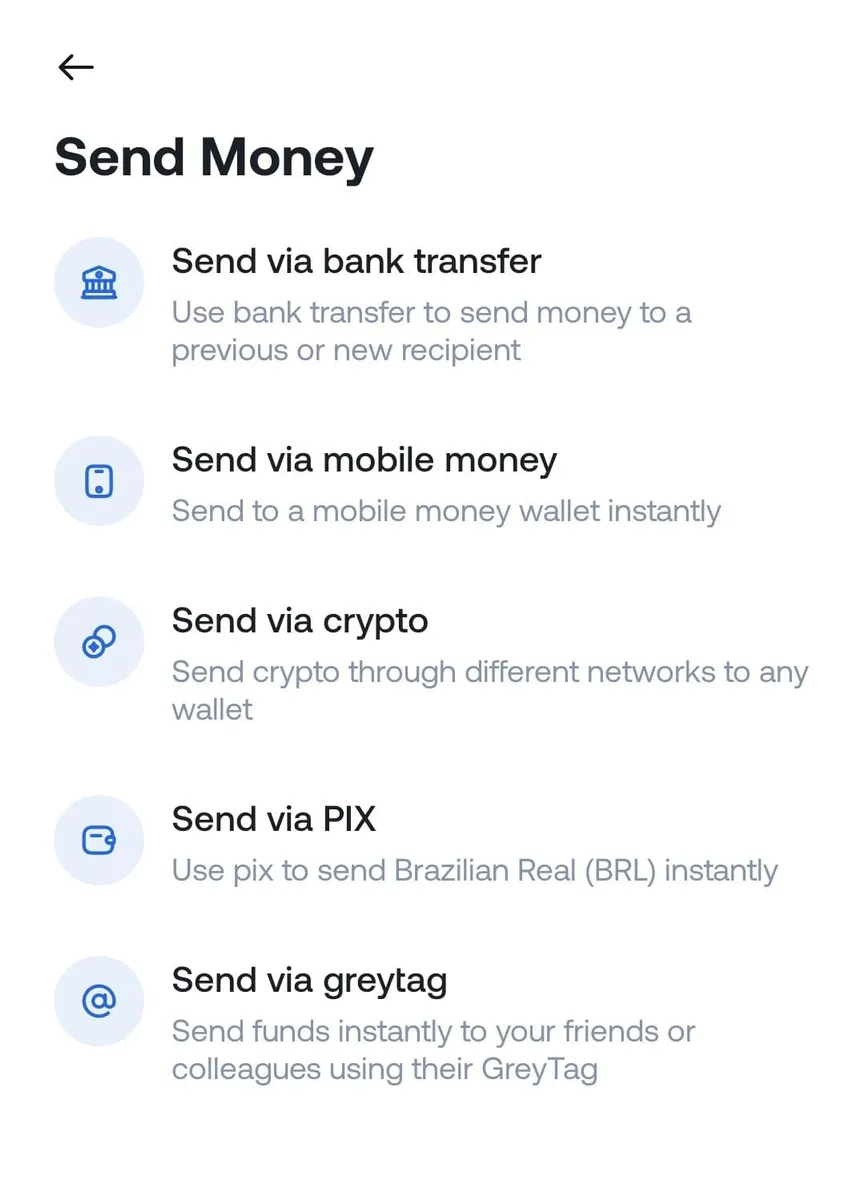
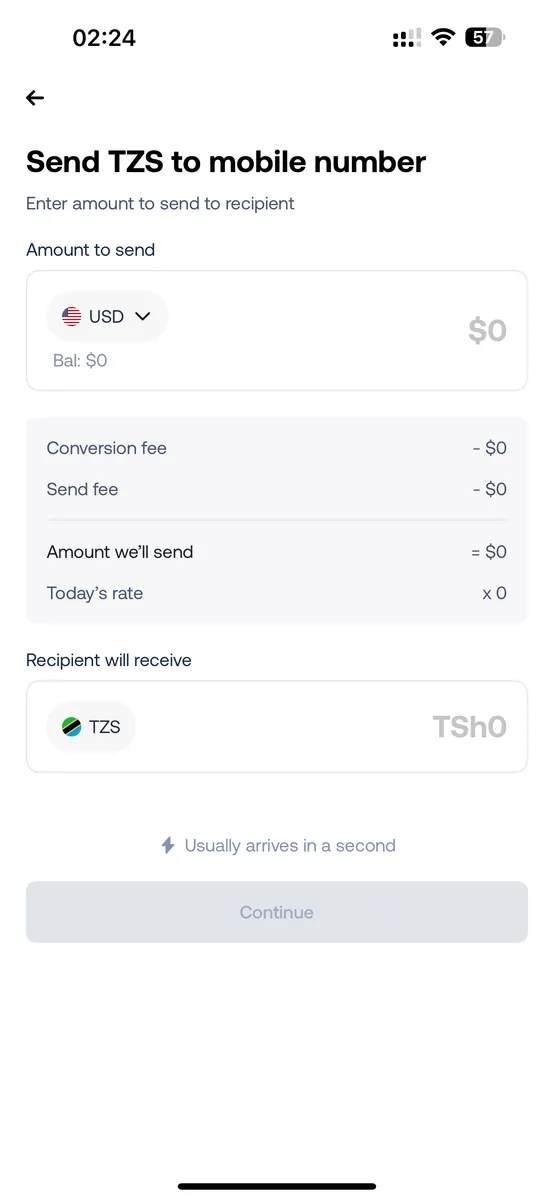
Then click " Send via mobile money" to send directly to your TZS mobile money account in Tanzania.
Getting your freelance payments from Amazon shouldn’t be tough. With a Grey account, you can receive money from anywhere worldwide and swap it for your local currency.
We hope this article has made your work easier. Sign up with Grey today to experience seamless cross-border payments tailored to your needs as an Amazon seller.
If you have ever tried to pay for an Amazon order, a Netflix subscription, or a US visa application fee with your Ghanaian bank card, you have probably encountered recurring declines, a mysterious extra charge, or both. This is simply because local bank cards are not the best for international payments. The easiest fix to get a USD debit card.
To get an instant USD debit card in Ghana, open a Grey account, complete verification, then create a virtual USD card in the app for a small one-time fee. Fund it from your USD balance and use it on any international site that accepts Mastercard, without the declines and markups that are common with local cards.
This guide explains why you might experience challenges with your card payments, and exactly how to get a virtual USD debit card that works well on international platforms.
Why do local Ghanaian cards get declined abroad?
Ghanaian cedi (GHS) cards can sometimes be declined for international transactions, even when you have enough money in your account, because they are mostly designed for local transactions. Other reasons can include foreign exchange restrictions, card limits, currency conversion costs and restrictions imposed by individual merchants or payment processors.
Foreign exchange restrictions and card limits
Like many central banks across Africa, the Bank of Ghana imposes foreign exchange rules that guide how much foreign currency individuals and banks can access. Hence, Ghanaian banks often impose limits on how much you can spend internationally with a GHS card. These limits can vary by bank, card type and transaction. So, a card is declined once it reaches the stipulated limit even when you have enough money in your account.
Currency conversion when you pay
When you use a GHS card to pay a platform that charges in USD, your bank or card provider needs to convert the transaction from cedis into dollars. The exchange rate used often includes a margin or a conversion cost, which might not be disclosed. This makes the purchase more expensive than the original USD price displayed by the platform.
Merchant and payment processor restrictions
Some international merchants and payment processors do not accept cards issued in every country or may apply additional checks to cards issued outside their target markets. As a result, a Ghana-issued card can occasionally be declined even when it works normally for other international merchants.
These issues can make international spending with a Ghanaian card less predictable. A USD virtual card offers a more reliable option. Instead of your bank or card provider converting GHS every time you make a USD purchase, you can fund your USD balance in advance and pay directly from that balance.
What a virtual dollar card is
A virtual dollar card is a digital payment card denominated in US dollars. It has the same basic details as a physical card, including a card number, expiry date and security code, but exists within an app rather than as a physical piece of plastic.
When you use a USD card to make a purchase priced in USD, the transaction can be charged directly to your USD balance. This avoids converting GHS to USD for each purchase. It also avoids the risk of payment decline and the unfavourable exchange rate associated with GHS cards.
The card works anywhere Visa is accepted online: shopping sites, subscription services, software tools, and payment for services like visa application fees that specifically require USD payment.
How to get a Grey virtual card in Ghana
Grey offers multi-currency accounts that let Ghanaians receive and manage USD, EUR, and GBP in one place. Grey’s virtual card is linked to the multi-currency account. So, it is more than a USD card. You can pay directly in any of these currencies without conversions.
Getting a Grey card takes only a few minutes. Just follow these steps:
Complete identity verification: Upload a valid ID, and complete the standard verification steps within the app. This typically takes some minutes.
Open a USD account: Once your account is verified, open a USD account within the app. This gives you a USD account number and a routing number.
Fund your USD balance: Deposit into your USD balance either by receiving USD payments directly (from clients, employers, or platforms paying you in dollars) or by converting from your GHS balance within the app.
Create your virtual card: Navigate to the Cards section and create your card. A $5 one-time card creation fee applies. Your full card number, expiry, and CVV are displayed instantly.
Start using it: Enter your new card details at any international checkout. The transaction is charged directly from your USD balance with no conversion at the point of payment.
Fees and funding
Card creation fee: A $5 one-time fee applies when you create your Grey card. Confirm the exact current fee in the app, as pricing is reviewed periodically.
Funding your USD balance: You can fund your USD account by receiving USD payments directly from international clients, employers, or platforms. Grey’s deposit fee is 0.8%, pegged at $10. You can also fund your account by converting from your GHS balance within the app at the displayed exchange rate.
Conversion costs: If you are converting from GHS to USD to fund your USD account, a 1% conversion fee applies and is clearly shown before you confirm the conversion. So you always know the exact cost before committing.
No hidden markup at checkout: Because purchases in USD draw directly from your USD balance without a currency conversion step at the point of sale, you avoid the point-of-sale markup that GHS cards typically apply on international transactions.
Maintenance and cross-border fee: Grey doesn’t charge maintenance fees on your multicurrency account or virtual card. However, using a Grey card on a non-US platform may incur a 2% cross-border fee plus $0.50 per transaction. This is a non-refundable fee fee is imposed by the payment network, not Grey.
Grey card does not need separate funding in advance because the card draws directly from your USD, EUR, or GBP account. You just need to fund your account in advance, so you are not scrambling to convert funds under time pressure when it is time to renew a subscription or pay for a service that has constrained timing.
What you can pay for with a virtual card
A virtual USD card can be useful for a range of international purchases, provided the merchant accepts Visa cards.
International shopping: You can use your USD card to shop online from Ghana. Whether it is an order from Amazon, Temu, Shein, or other international retailers, a virtual card ensures you do not have to worry about transaction declines.
Subscriptions: Renew your Netflix, Spotify, YouTube Premium, and other USD-priced subscriptions each month without failed payment notifications. For a deeper look at this specific use case, see our guide on paying for subscriptions in USD from Ghana.
Software and professional tools: Adobe Creative Cloud, cloud hosting services, and other USD-billed software subscriptions.
Visa application fees: Many embassy and visa processing fees are required in USD, and a virtual USD card handles this cleanly without the conversion issues that GHS cards encounter.
Online courses and certifications: Coursera, Udemy, and similar platforms billed in USD.
Freelance tools and business subscriptions: For entrepreneurs and freelancers paying for USD-denominated business software and services.
Frequently asked questions about getting an instant USD debit card in Ghana
How quickly can I get a virtual USD card in Ghana?
Once your Grey account is verified and you have enough money in your USD balance, you can create your virtual USD card directly in the app. Account verification times may vary, but creating the card itself only takes a few moments.
How much does a virtual USD card cost?
There is a one-time fee to create your Grey virtual USD card, with no monthly maintenance fee. If you need to convert another currency to USD to fund your card, you’ll see the applicable exchange rate and fees before confirming the conversion.
Can I use a virtual USD card on Amazon?
Yes. You can use your Grey virtual USD card to make USD payments on Amazon and other international platforms that accept the card. As with any card, individual transactions may still be subject to the merchant’s payment and security checks.
Do I need a USD account before creating the card?
Yes. Your virtual USD card is funded from your Grey USD balance. You can set up your USD account and create your virtual card within Grey, so you don’t need to apply for them through separate providers.