


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#article","headline":"How to receive and convert foreign currencies to USDC in the United Arab Emirates","description":"Discover how freelancers and remote workers in the United Arab Emirates can receive foreign payments and convert them to USDC easily with Grey.","inLanguage":"en","url":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates","mainEntityOfPage":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#webpage"},"datePublished":"2024-11-26T08:26:22.805Z","dateModified":"2026-06-15T18:06:57.150Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301913291eb1c909621436_6a3019123b28501995d3dfa4_how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301913291eb1c909621436_6a3019123b28501995d3dfa4_how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#webpage","url":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates","name":"How to receive and convert foreign currencies to USDC in the United Arab Emirates","description":"Discover how freelancers and remote workers in the United Arab Emirates can receive foreign payments and convert them to USDC easily with Grey.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to receive and convert foreign currencies to USDC in the United Arab Emirates","item":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates"}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#terms","name":"How to receive and convert foreign currencies to USDC in the United Arab Emirates glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"USDC","description":"a stablecoin solution that’s pegged against the US dollar","inDefinedTermSet":{"@id":"https://grey.co/blog/how-to-receive-and-convert-foreign-currencies-to-usdc-in-the-united-arab-emirates#terms"}}]}] </script>

How to receive and convert foreign currencies to USDC in the United Arab Emirates

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

The United Arab Emirates is famous for its ambitious projects. It’s been able to transform huge chunks of its arid lands into futuristic metropolises. It’s no surprise that the region has become a magnet for global freelancers. However, managing international payments can still be a tricky oasis to find.

That’s where USD Coin (USDC) comes in, a stablecoin solution that’s pegged against the US dollar.

This guide will walk you through the process of receiving foreign payments, converting them to USDC, and managing funds efficiently using Grey.

Also read: How to receive and convert foreign currencies to USDC

Why convert foreign payments to USDC in the UAE?

For freelancers working with international clients, USDC offers several advantages:

  • Stable value: USDC is tied to the U.S. dollar, ensuring predictable value and shielding you from cryptocurrency volatility.
  • Lower fees: Compared to traditional bank transfers, USDC transactions often come with lower fees, saving you money on cross-border payments.
  • Fast transfers: Blockchain technology allows near-instant transactions, giving you quick access to your funds.
  • Flexibility: Hold USDC for stability or convert it to AED when exchange rates are favourable, giving you greater control over your finances.

Also Read: Send instant USDC payouts to 40+ countries with Grey

Receiving and converting foreign currency to USDC

Grey offers a seamless way to receive and convert foreign currencies into USDC. Here's how:

Open the Grey app

Log in to your Grey account via the app or website to securely access your USD and other currency balances.

Select your USD balance

Navigate to the “Accounts” section and select your USD balance to start the USDC transfer process.

__wf_reserved_inherit

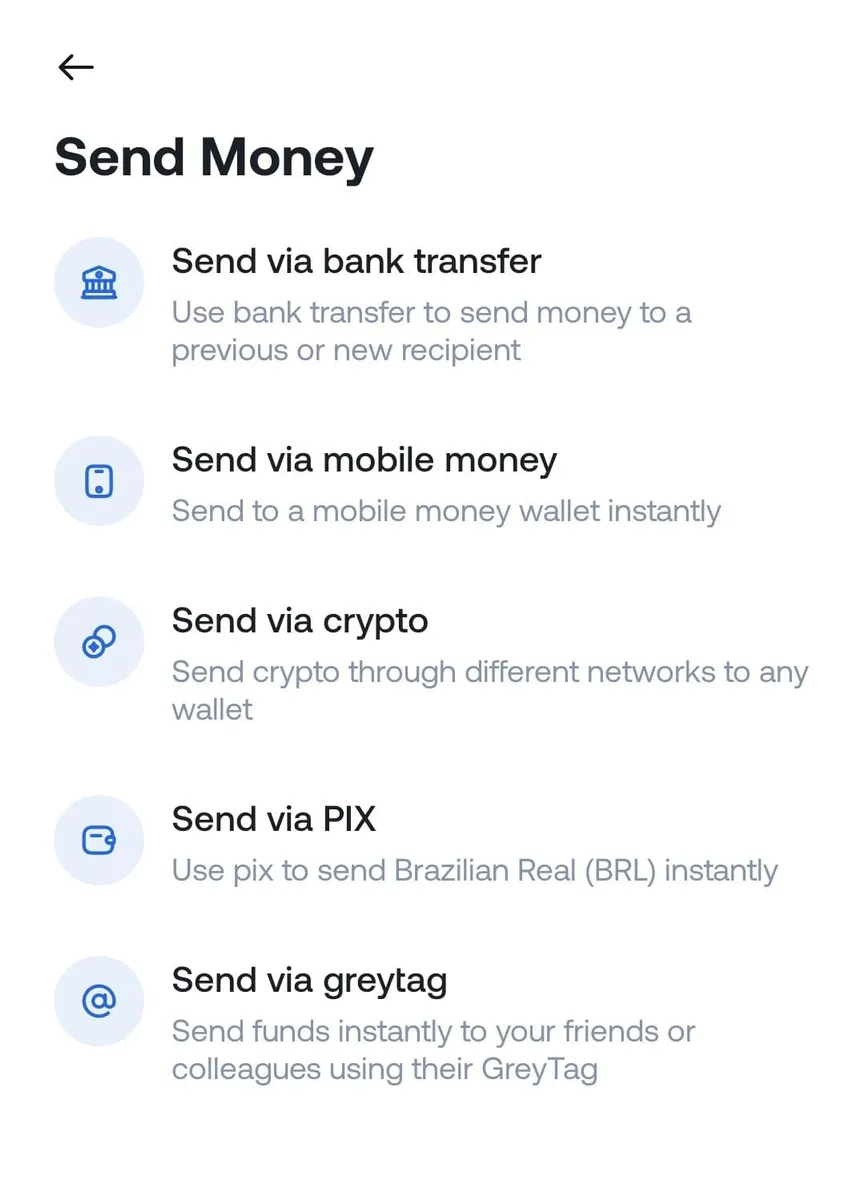
Tap “Send via crypto”

Choose the “Send money” option, then select “Send via crypto” to initiate a USDC transfer.

__wf_reserved_inherit

Enter transaction details

Input the recipient’s wallet address carefully and select the correct network. Grey supports Solana (SOL) and Binance Smart Chain (BEP-20).

__wf_reserved_inherit

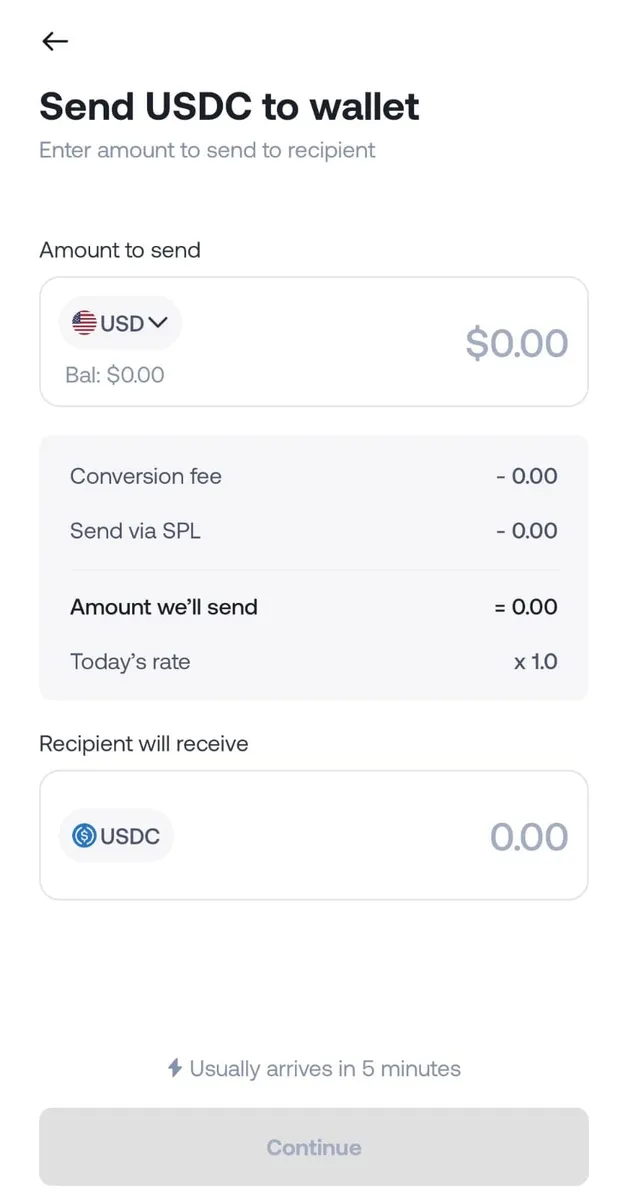
Input the transfer amount and review the details

Enter the amount of USDC to send. Double-check all information, including the wallet address and network, before proceeding.

__wf_reserved_inherit

Confirm and complete the transfer

Once all details are verified, tap “Send” to complete the transaction. Grey will request two-factor authentication (2FA) for added security.

Transaction success

The recipient will receive the USDC shortly after processing. They can hold it, convert it to local currency, or use it for other purposes.

Also Read: How to receive dollar payments and convert to USDC in Mexico

Converting USDC to United Arab Emirates Dirham (AED)

To convert USDC into AED, use a crypto exchange or local service that supports USDC-to-AED transactions. Many platforms offer direct conversions, while others may require intermediary trades through USD or BTC.

Considerations for freelancers holding and converting USDC

While USDC is a practical solution for financial management for freelancers, here are a few things to consider:

  • Network compatibility: Ensure the network used for USDC matches your wallet and conversion services to avoid transaction issues.
  • Fee awareness: USDC has low transaction fees, but network fees may vary depending on the blockchain.
  • Tax compliance: The UAE has evolving regulations for cryptocurrencies. Stay updated on tax requirements to ensure compliance when holding or converting USDC.

Also Read: How to receive dollar payments and convert to USDC in Chile

Using Grey to simplify USDC management

With Grey, you can send USDC to supported wallets, easily manage funds, and take advantage of robust security measures like two-factor authentication (2FA).

Create your Grey account today to unlock the full potential of USDC as a freelancer in the UAE.

How to receive and convert foreign currencies to USDC in the United Arab Emirates

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Virtual cards in Egypt for online payments

•

•

2 min read

It is one thing to have the funds for online payments; it is another thing to have the means to complete the payment without getting frustrated. Managing international payments in Egypt can be quite a hassle. If you’ve tried paying for an international subscription, a work tool, online shopping, or an online course from Egypt, perhaps you can relate to the struggle. Local Egyptian bank cards are often restricted from international transactions, offer poor exchange rates, or aren’t supported by global platforms.

Virtual cards exist mostly to solve these problems, and they have become one of the most efficient options for anyone who shops online, pays for subscriptions, or needs a reliable way to spend in foreign currency without the limitations of a standard local bank card.

This article explains how virtual cards work, who they are for, and the main options available to people in Egypt right now.

What is a virtual card, and how does it work?

A virtual card is a digital payment card that works just like a traditional debit or credit card, except it exists only electronically. Instead of receiving a plastic card, you get the card details instantly on your phone or computer, including the card number, expiration date, and CVV security code.

Because virtual cards are issued digitally, they are typically available within minutes, unlike physical cards that must be printed and delivered.

Most virtual cards operate as prepaid or debit cards, meaning you spend funds you already have. In many cases, the card is connected to a multi-currency account, so payments are deducted directly from your balance in currencies such as USD, GBP, or EUR. This eliminates the need to manually top up the card before each purchase.

For example, Grey virtual cards are linked directly to your foreign currency balance, allowing you to pay online or in apps without transferring funds to the card first.

In practice, using a virtual card is no different from using a physical one. You simply enter the card details at checkout when making online payments, subscriptions, or international purchases. Many virtual cards can also be added to Apple Pay or Google Pay, enabling secure contactless payments with your phone wherever mobile wallets are supported.

Also read: Managing USD income as a remote worker in Egypt

What to look for when choosing

Not all virtual cards work the same way. The best option for you will depend on how you plan to use it, which currencies you deal with most often, and how frequently you make international payments. Before choosing a provider, it’s worth looking closely at a few key factors.

Currency support. Many virtual cards are designed primarily for USD payments, but international platforms often charge in other currencies such as EUR or GBP. If you regularly use services based in Europe or the UK, a card that supports multiple currencies can help you avoid additional conversion fees. Choosing a provider with a multi-currency account allows you to hold and spend different currencies more efficiently.

Funding options. Different platforms allow you to add funds in different ways. Some accept local bank transfers, others allow crypto deposits such as USDT, and some link directly to a multi-currency account balance, like Grey. Before signing up, check that the funding method available actually works for your situation and location.

Platform compatibility. Not every virtual card works equally well across all international platforms. Some services, particularly advertising platforms or large marketplaces, may reject certain cards depending on the issuing network or region. If you plan to use your card for a specific purpose, such as paying for Google Ads or cloud hosting, it’s worth confirming that the card is widely accepted on those platforms.

Fees and exchange rates. Virtual card costs can vary significantly between providers. Some charge a card creation fee, others add transaction fees, and most apply a small markup on currency conversions. A card that appears free at first glance may become more expensive if the exchange rate spread is high. Always look at the total cost of using the card, not just the upfront fee.

Security and regulation. Security should always be a priority when choosing a financial platform. Look for providers that follow proper identity verification processes and operate with licensed financial partners. Features such as two-factor authentication, transaction alerts, spending limits, and the ability to instantly freeze your card add an important layer of protection.

Contactless payments. Some virtual cards can be added to mobile wallets like Apple Pay or Google Pay, allowing you to make contactless payments with your phone. This can be particularly useful when travelling or making in-store purchases abroad. If this feature matters to you, make sure the card supports mobile wallet integration in your region.

Taking a few minutes to compare these factors can help you choose a virtual card that fits your spending habits and avoids unnecessary fees or payment issues later.

The top virtual cards in Egypt for online payments

While cards issued by local banks work well for domestic spending, they are not always reliable for international payments. Here is a list of the top virtual cards in Egypt for online payments.

Grey

Grey offers virtual cards linked to a multi-currency account that supports USD, EUR, and GBP. You can create multiple cards for various uses to properly plan your finances. One card can be for online shopping while another could be for subscriptions and or online course. Grey cards are globally accepted and works with the full range of international platforms

You can receive international payments into your Grey USD, GBP, or EUR account or fund your account in EGP and convert to USD to spend on your cards directly.

Fees: Grey virtual USD cards cost a one-time creation fee of $4, plus a minimum of $1 to fund the card, totalling $5 to get started. There are no monthly maintenance fees.

EverTry

EverTry offers a solution for international payment restrictions in Egypt through their virtual dollar card platform. It allows Egyptian users to pay for global services that often decline local bank cards. It supports funding in local currency and USDT, making it accessible to users who are comfortable with crypto. The card works across a wide range of international platforms, including Netflix, Spotify, AWS, DigitalOcean, Namecheap, Facebook Ads, and Google Ads.

Fees: Card creation typically costs $2.5, with no monthly maintenance fees.

Card-Y

Card-Y is a fintech platform that offers multi-currency global accounts with a linked virtual card, designed for Egyptian freelancers and remote workers. It offers USD and EUR account details for receiving international payments, with a free virtual card included that draws from those account balances. It also issues local Egyptian bank cards to subscribers.

Fees: Card-Y offers virtual Mastercard issuance for a $20 USD fee, which is valid for one year and does not add to the card balance. The service features a $1 monthly maintenance fee, a 1% USD transaction fee ($1 min/$5 max), and a 1.5% foreign currency conversion fee.

Fyatu

Fyatu provides instant virtual Mastercards with support for multiple currencies, aimed at users who need to make global payments and manage international subscriptions. Onboarding is digital, and card issuance is immediate. It is a straightforward option for users whose primary need is an international spending card rather than a full suite of banking features.

Fees: Fyatu virtual card costs include a 1.5% fee for card usage (for either withdrawal or payments), with card replacement fees of $5 for World cards and $10 for Platinum cards. A $1.00 fee applies to declined transactions. Funding methods vary, with fees such as 3% for MTN MoMo and various percentages for online wallets like PayPal (3.5% + $0.30).

AstroPay

AstroPay is a globally recognised digital wallet and virtual card platform, available in over 150 countries, including Egypt. It has been around since 2009 and has a particularly strong footprint in emerging markets across Africa, Latin America, and Asia. The platform supports more than 50 currencies, issues virtual prepaid cards instantly, and does not require a traditional bank account to sign up.

For Egyptian users, AstroPay works as a prepaid spending tool. You load funds onto your wallet using a local payment method, then use the virtual card for international purchases on platforms that accept Visa or Mastercard. Card details are issued instantly through the app, and the platform supports one-time or multi-use cards depending on the denomination.

However, bank withdrawals from AstroPay can attract fees of up to 6% depending on the institution. There is a margin of 1% to 3% on exchange rate.

Fees: No card purchase or maintenance fee. No annual fee. Transaction fees of 2–5% depending on the payment method used. FX markup of approximately 1–3% on non-native currency transactions. Withdrawals to a bank account: up to 6%.

Comparison of the top virtual cards in Egypt

Before exploring each option in detail, the table below summarises some of the key differences between the most popular virtual cards available to users in Egypt, including supported currencies, card type, and typical fees.
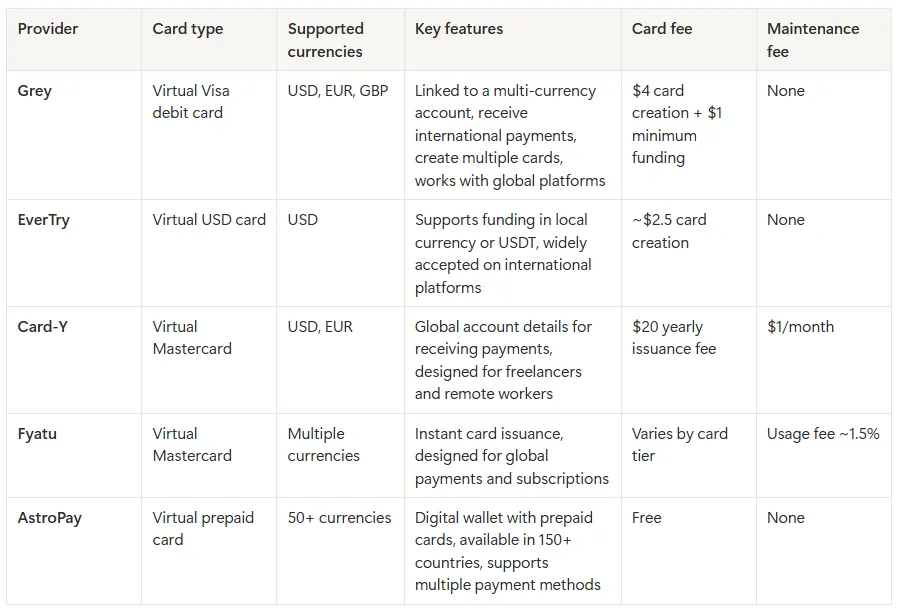
Table comparing virtual cards from Grey, EverTry, Card-Y, Fyatu and AstroPay

Quick recommendations

If you’re not sure which virtual card to choose, here’s a quick guide based on common use cases in Egypt.
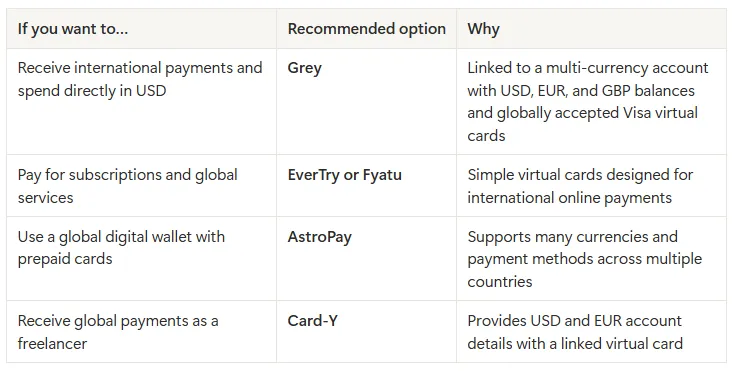
Table recomending different cards for each need

For most freelancers, remote workers, and online entrepreneurs in Egypt, a virtual card linked to a multi-currency account is often the most practical option. It allows you to receive money from abroad, hold foreign currencies, and pay for global services without converting funds every time you make a transaction.

Also read: Grey card vs other virtual cards: What you should know

Make international payments with Grey

The advent of virtual cards has brought significant flexibility to managing international payments. Grey gives Egyptians a virtual card linked to your multi-currency account. This allows you to receive international payments and spend internationally from the same platform. Whether you are paying for software subscriptions, running digital ads, shopping on international platforms, or managing online tools for your work, Grey's virtual card is accepted globally and straightforward to set up.

Ready to get your virtual card? Sign up on Grey and download the app to create your virtual USD card in minutes.


‍

What is the currency of Thailand? Baht symbol and code

•

•

2 min read

Recently, Thailand has become one of the most sought-after destinations for vacationers. Now, before you hop on that flight, you need to understand the country’s currency, which denominations are in circulation, and how to get a fair rate when you convert or send money, so you save time and money from the moment you land.

This guide covers everything you need to know about Thailand’s currency, the Thai baht: its symbol, currency code, history, denominations, and practical advice for travellers and anyone sending money to Thailand.

What is the currency of Thailand?

The currency of Thailand is the Thai baht, and it’s the only legal tender accepted across Thailand for everyday transactions, from street food and tuk-tuks to hotels and department stores. The baht has been Thailand’s official currency since the late 19th century and is issued and regulated by the Bank of Thailand.

The baht is a relatively stable emerging-market currency that trades on international foreign-exchange markets. It floats within a managed regime overseen by the Bank of Thailand, which intervenes periodically to limit volatility. For most travellers and remittance senders, the baht is freely exchangeable at banks, authorised money changers, hotels, and through online platforms.

Thailand’s economy is among the largest in Southeast Asia, and the baht reflects it. It is widely recognised, commonly held by foreign exchange desks around the world, and straightforward to convert from major currencies, including USD, EUR, GBP, and SGD.

The Thai baht: symbol and code

The Thai baht uses the symbol ฿ and the ISO 4217 currency code THB. On price tags, menus, and payment receipts in Thailand, you will see the ฿ symbol placed before the amount: ฿500, ฿1,200. In international financial contexts and money transfer platforms, the code THB is used to identify the currency.

One baht is divided into 100 satang, which is the subunit of the baht. The word “satang” comes from the Sanskrit “śataṅga,” meaning “one hundredth.” In practical terms, satang coins are used but rarely noticed by visitors, as most purchases are priced in whole baht.

Notes and coins

The Thai baht is issued in both banknotes and coins, covering a range of denominations suited to everyday transactions from small street purchases to larger payments.

Banknotes

Denomination Colour What is featured
฿20 Green King Rama X on the front; national landmarks on the reverse
฿50 Blue King Rama X on the front; national landmarks on the reverse
฿100 Red King Rama X on the front; national landmarks on the reverse
฿500 Purple King Rama X on the front; national landmarks on the reverse
฿1,000 Brown/grey King Rama X on the front; national landmarks on the reverse

‍

All current banknotes feature the reigning monarch, King Vajiralongkorn (Rama X), on the front face. Earlier series featured King Bhumibol Adulyadej (Rama IX), who reigned until 2016. Older Rama IX notes remain legal tender and are still widely in circulation. You will encounter both in everyday transactions.

The ฿20 note is the most commonly used for small transactions. The ฿1,000 note is the largest denomination and is standard for paying at hotels, shops, and restaurants. The ฿500 is also widely accepted.

Street vendors and tuk-tuk drivers often cannot make change for a ฿1,000 note. Keeping a supply of ฿20, ฿50, and ฿100 notes makes small daily purchases easier, so always keep that in mind.

Coins

Denomination Composition Notes
25 satang Aluminium bronze Small; used primarily in supermarkets
50 satang Aluminium bronze Occasionally used in supermarket pricing
฿1 Nickel-clad steel Common in everyday use
฿2 Nickel-clad steel Common in everyday use
฿5 Nickel-clad steel Common in everyday use
฿10 Bimetallic Most commonly used coin; appears in nearly all transactions

‍

The ฿10 coin is the most prevalent in Thailand. It is bimetallic, with a gold-coloured outer ring and a silver-coloured centre, and is used across all types of transactions from vending machines to street markets. The ฿1, ฿2, and ฿5 coins are also common. Satang coins appear primarily in supermarket and pharmacy change.

Using the baht as a traveller

Thailand is primarily a cash economy in many contexts, though card acceptance has expanded significantly in urban areas and tourist zones. Understanding when cash is essential and when cards work best helps you plan your spending and avoid unnecessary fees.

When is cash essential?

Street food and markets: Almost all food stalls, night markets, floating markets, and local vendors across Thailand operate on a cash-only basis. The famous Chatuchak Weekend Market in Bangkok, every night market from Chiang Mai to Phuket, and virtually all local restaurants expect baht in hand.

Tuk-tuks, songthaews (shared trucks), and motorbike taxis: While ride-hailing apps like Grab now offer card payment for cars, traditional transport remains cash-dependent.

Temples and tourist sites: Some accept cards, but many require cash for entry fees, donations, and purchases at site stalls.

Small guesthouses and bungalows: particularly on the islands and in rural areas, smaller accommodations often operate cash only or charge a fee for card payments.

When are cards accepted?

Shopping malls, department stores, and major supermarkets (Central, The Mall, Big C, Lotus’s)  accept Visa and Mastercard. Chain restaurants, international hotels, and larger tourist restaurants also take cards. Grab rides booked in-app, accept card payment.

Getting baht at a fair rate

ATMs in Thailand dispense baht directly from your foreign debit or virtual debit card. The exchange rate is typically close to the interbank rate, but Thai ATMs charge a fixed fee of 220 baht per withdrawal at most banks. This fee is charged by the Thai bank, not your home bank. If your home bank also charges an international ATM fee, withdrawing larger amounts less frequently reduces the total fee paid.

Currency exchange booths in Thailand, particularly authorised money changers rather than hotel desks, typically offer better rates than airport exchanges. SuperRich (orange and green) and Vasu Exchange are well-regarded in Bangkok. Airport exchange booths are convenient but tend to offer worse rates.

Using your card for direct purchases abroad triggers your card network’s exchange rate plus any foreign transaction fee charged by your card issuer. To understand how card exchange rates work before your trip, see our guide on how card exchange rates work. For practical steps to keep those costs down, our guide on avoiding foreign transaction fees covers the main options.

For travellers who earn in multiple currencies or want to hold baht and other currencies in one place, Grey lets you hold multiple currencies in a single account and convert at a transparent rate before you travel.

Practical tips for using baht

Carry small denominations. ฿20, ฿50, and ฿100 notes are used for most daily transactions. Having ฿1,000 notes is fine for hotels and shops, but annoying for markets and street food.

Keep coins. Thai coins accumulate quickly and are useful for small purchases, vending machines, and motorcycle taxi fares.

Don’t exchange money at the airport unless necessary. Rates at airport exchange counters are typically worse than in-city authorised money changers. Exchange a small amount at the airport for immediate needs (transport, first meal) and exchange the bulk once you’re in the city.

Decline dynamic currency conversion at ATMs and card terminals. When a Thai ATM or card payment machine offers to charge you in your home currency rather than baht, decline. This is called dynamic currency conversion, and the rate applied by the machine is almost always significantly worse than your card’s standard rate.

Sending money to Thailand

If you’re sending money to family, paying rent, covering business expenses, or supporting someone in Thailand from abroad, the method you use determines how much they receive.

The Thai baht is freely receivable at all major Thai banks, including Bangkok Bank, Kasikorn Bank (KBank), Siam Commercial Bank (SCB), Krung Thai Bank, and TMBThanachart Bank. International transfers arrive as THB after conversion, or as USD/EUR/GBP for foreign currency accounts held at Thai banks.

The main cost considerations when sending money to Thailand are the exchange rate applied on conversion and any transfer fees or correspondent bank charges. Traditional bank wire transfers to Thailand typically carry an outbound fee of $25 to $50 from the sending bank, plus a conversion spread of 2 to 4% above the mid-market rate at the receiving end. Correspondent bank fees can reduce the amount further in transit.

With Grey, you make transfers to Thailand for a flat fee of $1.80, regardless of the amount. Regular deposits via ACH, SEPA, or Faster Payments carry a 0.8% fee capped at $10. This is significantly cheaper than the combined cost of a bank wire plus a bank conversion spread on larger transfers.

To get started, send money to Thailand with Grey and see the current rate and total fee before committing to the transfer. For US-based senders specifically, our send money from the US to Thailand page covers the process in detail.

Frequently asked questions about the Thai baht

What is the currency of Thailand?

The currency of Thailand is the Thai baht, abbreviated THB and symbolised as ฿. It is the sole legal tender in Thailand and is issued and regulated by the Bank of Thailand. One baht divides into 100 satang. The baht is used for all transactions across the country, from small street food purchases to large hotel bills and business payments.

What is the symbol for the Thai baht?

The Thai baht symbol is ฿. It is placed before the amount in Thai pricing conventions, for example, ฿100 or ฿1,500. In international financial contexts, the three-letter ISO code THB is used to identify the currency in exchange rates, bank transfers, and financial systems.

What is the currency code for the Thai baht?

The currency code for the Thai baht is THB, as assigned under the ISO 4217 international currency standard. This code is used on money transfer platforms, bank statements, foreign exchange rate boards, and financial software to identify transactions denominated in Thai baht.

What is a satang?

A satang is the subunit of the Thai baht. One baht equals 100 satang. Satang appear as coins in denominations of 25 satang and 50 satang, and are occasionally used in supermarket and pharmacy pricing. In most everyday Thai transactions, prices are rounded to the nearest whole baht, so satang coins are not frequently encountered in street markets or restaurants.

Should I use cash or card in Thailand?

Both are useful, but cash remains essential in Thailand. Street food stalls, local markets, motorbike taxis, small guesthouses, and many tourist attractions operate on cash only. Cards are accepted reliably at shopping malls, chain supermarkets, international hotels, and larger restaurants. A practical approach is to carry baht cash for daily spending and markets, and use a card at larger establishments. Avoid dynamic currency conversion at ATMs and card terminals, and withdraw larger amounts to minimise the ฿220 per-transaction ATM fee that Thai banks charge.

How do I send money to Thailand?

To send money to Thailand, you need the recipient’s Thai bank name, account number, and the bank’s SWIFT code. Grey provides international transfers to Thailand for a flat fee of $1.80, with the rate shown before you confirm. Traditional bank wire transfers typically carry a $25 to $50 outbound fee plus a 2 to 4% conversion spread, making fintech transfers significantly cheaper for most amounts.

Send money to Thailand with Grey

What is the RTP network? Real-time payments in the US

•

•

2 min read

Imagine a US business paying a freelancer on a Friday evening and the freelancer receiving the money within seconds, rather than waiting until the next business day for a traditional bank transfer to clear. That is the kind of experience real-time payments are designed to make possible, and it is where the RTP network comes in.

The RTP network is a US real-time payments system run by The Clearing House that settles payments instantly, 24/7, every day of the year. Funds are available to the recipient within seconds and payments are final. It is used for payroll, bill pay and business-to-business transfers.

For you, the biggest difference is speed. Instead of planning around banking hours, weekends or public holidays, an RTP payment can move whenever the sending and receiving institutions support the network. That makes real-time payments particularly useful when getting paid, settling an urgent bill or moving money between businesses.

What is the RTP Network?

The RTP Network is a US real-time payments network that allows participating banks and financial institutions to send and receive eligible payments within seconds, rather than waiting for traditional banking processing windows. If you are sending money through a participating institution, the payment can move at any time, including nights, weekends and holidays, making it useful when waiting until the next business day is not an option.

The network is operated by The Clearing House, a US payments company owned by a group of major banks. Unlike traditional payment systems that may process transactions in batches, the RTP Network is designed for continuous, real-time processing, so funds can become available to the recipient almost immediately after the payment is sent.

For you, the key features are speed, availability and finality. RTP payments operate 24 hours a day, seven days a week, 365 days a year, and payments sent through the network are generally irrevocable once completed. The network supports use cases including business payments, bill payments, payroll and other account-to-account transfers.

How RTP payments work

An RTP payment can start with a request for payment or a direct credit push, before the network processes and settles the transaction almost immediately.

Request for payment

A request for payment allows the recipient or business to ask you to make a payment electronically. You receive the request through your participating bank or financial institution, review the payment details and authorise it. Once approved, the payment can be sent through the RTP Network without waiting for normal banking hours.

Credit push

A credit push is the more direct option, where you instruct your bank or financial institution to send money to the recipient's account. You provide the required account and payment details, confirm the amount and authorise the transaction. The sending institution then submits the payment through the RTP Network for processing.

Instant settlement

Once the payment is submitted, the RTP Network processes it in real time and settles the transaction between participating financial institutions. The recipient can typically access the funds within seconds, while the payment becomes final after settlement. Because RTP operates continuously, payments can be made on weekends, holidays and outside traditional banking hours.

RTP vs FedNow vs ACH vs wire transfers

This comparison shows how RTP, FedNow, ACH and wire transfers differ across speed, cost, operating hours and payment finality, helping you choose the right rail.

Payment Rail Speed Cost (Network / Retail) Operating Hours Finality (Irrevocability)
RTP Immediate (seconds) Network: $0.045;
Retail: free to low fee
24/7/365 Immediate and final
FedNow Immediate (seconds) Network: $0.045;
Retail: free to low fee
24/7/365 Immediate and final
ACH 1–3 business days Network: <$0.01;
Retail: free to $1.00
Business hours (batches) Reversible
(60-day consumer window)
Wire 1–2 hours Network: Variable;
Retail: 15–50
Varies by institution Generally final

‍

When should you use real-time payments?

You should use real-time payments when you need money to reach someone within seconds, rather than waiting for traditional banking hours or batch processing. They are particularly useful for urgent payments, payroll, bills and business-to-business transfers where immediate access to funds matters.

Payroll

If you run payroll and need employees or contractors to receive their money immediately, real-time payments can shorten the gap between sending funds and availability. This can be particularly useful for urgent payments, off-cycle payroll or businesses paying workers outside traditional banking hours.

Bill payments

Real-time payments can help you settle bills when waiting several business days is not practical. If a payment is due today, sending it through a participating institution can make funds available quickly, helping you avoid delays, missed deadlines or interruptions to important services.

Business-to-business payments

For B2B payments, real-time payments can help you pay suppliers, contractors or business partners without waiting for traditional payment batches. Faster settlement can improve cash flow, speed up fulfillment and give the recipient access to funds almost immediately after the payment is sent.

Also read: How to choose a cross-border payments platform you can trust

How cross-border payments work when domestic instant rails stop at the border

Real-time payment networks such as RTP are built for domestic transfers, which means the speed you experience within the US does not automatically apply when you make a cross-border payment. For example, someone looking to send money from the US to Mexico may still need a different payment route because the transaction involves another country, currency, banking system and regulatory requirements.

That does not mean international transfers have to be difficult. With a multi-currency account, you can receive and hold money in different currencies before deciding when to convert or move it. This gives you more control, particularly when you regularly receive payments from abroad and do not want every transaction converted immediately.

For example, with Grey, you can manage multiple currencies in one account and use supported payment routes for international transfers. Whether you need to send money from the US to Mexico or manage payments across other countries, holding your funds in the currency you receive them in can give you more control over when and how you move your money.

Also read: Best cross-border payment platforms compared 2026

Frequently asked questions about the RTP Network

What is the RTP network?

The RTP network is a US real-time payments system operated by The Clearing House. It allows participating banks and financial institutions to send and receive payments instantly, 24/7, 365 days a year. Unlike traditional payment methods that process in batches, RTP transactions settle individually, with funds available within seconds.

Who runs it?

The RTP network is operated by The Clearing House, a US payments organisation owned by major banks. It provides the infrastructure that participating financial institutions use to send and receive real-time payments. Your bank or payment provider must participate in RTP for you to make or receive an RTP payment.

How fast is it?

RTP payments typically reach the recipient within seconds, rather than taking one or several business days. The network operates continuously, including weekends and public holidays, so you do not have to wait for normal banking hours. Once an RTP payment settles, the funds are generally available to the recipient immediately.

How is RTP different from FedNow?

RTP and FedNow are both US real-time payment networks that enable near-instant transfers 24/7. The main difference is who operates them: The Clearing House runs RTP, while the Federal Reserve operates FedNow. Your choice usually depends on which real-time payment network your bank or financial institution supports.

Is RTP the same as ACH?

No. RTP and ACH are different US payment rails. RTP processes payments individually in real time, allowing recipients to access funds within seconds, while ACH payments are generally processed in batches and can take longer. ACH transactions can also have different rules around reversals and payment processing compared with RTP.

Can I use it internationally?

RTP is primarily designed for domestic payments within the US, so you generally cannot use it as a direct international payment network. Sending money across borders, such as from the US to Mexico, requires a separate international payment route that can handle different currencies, banking systems and regulatory requirements.

21 best apps to send money internationally

•

•

2 min read

Sending money internationally can seem fairly simple, well, that's until you reach the payment screen and start comparing fees, exchange rates and delivery times. The app that looks cheapest at first may not be the one that leaves the recipient with the most money.

Your choice can make a noticeable difference, especially when you are sending money regularly to family, paying someone abroad, or moving your own money between countries. Some apps focus on low fees, while others compete on faster delivery, better exchange rates or wider coverage.

The best apps to send money internationally combine low fees, a small exchange rate margin and fast delivery to the country you are sending to. Grey, Wise, Remitly and WorldRemit are strong starting points, but the right option depends on where you are sending money, how much you are transferring and how quickly it needs to arrive.

This guide compares 21 international money transfer apps so you can see what each one offers and choose the option that fits your needs.

How to choose an international money transfer app

Before picking from the best apps for transferring money internationally, check these things:

  • Fees: Look beyond the advertised transfer fee and check the total amount you will pay, including any charges that apply to larger or more frequent transfers.
  • Exchange rate margin: Compare the exchange rate offered with the current market rate, because even a small difference can reduce the amount your recipient receives.
  • Speed: Check how quickly the transfer should arrive, particularly when you are sending money for an urgent bill, family expense, or time-sensitive payment.
  • Payout methods: Check how your recipient can collect the money, whether that means a bank account, mobile wallet, cash pickup, or another available option.
  • Coverage: Make sure the app supports both the country you are sending money from and the destination where your recipient lives.
  • Registration: Check what you need before sending your first transfer, including identity verification, personal information, account details, and any required supporting documents.

The 21 best apps for sending money internationally

These 21 money transfer apps combine lower fees, competitive exchange rates and faster international payments for individuals, freelancers and businesses worldwide

1. Grey

  • Fees: 1% conversion fee capped at $6 for USD/GBP/EUR (uncapped for KES).
  • Rate margin: Competitive real-time market exchange rates with transparent tracking.
  • Speed: Instant for UK/Europe/Kenya; 1–2 business days for US ACH wires.
  • Countries: Supports transfers to 80+ countries including the US, UK, and Eurozone.
  • Best for: Remote workers and freelancers requiring dedicated foreign virtual accounts.

2. Wise

  • Fees: Small variable percentage fee shown upfront.
  • Rate margin: 0% markup using the true mid-market exchange rate.
  • Speed: Real-time processing up to 2 business days.
  • Countries: Operates across 145+ destination countries.
  • Best for: Most affordable bank-to-bank international personal transfers.

3. Remitly

  • Fees: Variable structure tiered by chosen tier (Express vs. Economy).
  • Rate margin: Small retail markup layered on top of mid-market rates.
  • Speed: Instant delivery for Express option; 3 days for Economy.
  • Countries: Sends funds globally to over 150 countries.
  • Best for: Family remittances requiring specific arrival time guarantees.

4. WorldRemit

  • Fees: Flat or percentage fees determined by payout destination.
  • Rate margin: Standard commercial markup added to currency conversions.
  • Speed: Immediate for mobile wallets and physical cash collections.
  • Countries: Extensive coverage across more than 130 countries.
  • Best for: Sending money straight to digital mobile money wallets.

5. LemFi

  • Fees: Zero or ultra-low platform transfer fees.
  • Rate margin: Competitive exchange rates with minimal built-in spread.
  • Speed: Transactions complete within a few minutes.
  • Countries: Diaspora sending from US/UK/Canada to Africa, Asia, and Latin America.
  • Best for: Immigrant communities seeking zero-fee remittance corridors.

6. Eversend

  • Fees: 1.5% to 3.5% currency exchange processing fee.
  • Rate margin: Tight spreads close to official mid-market numbers.
  • Speed: 1-minute mobile money payouts and swift wallet swaps.
  • Countries: Focuses on inter-Africa corridors alongside Western channels.
  • Best for: Managing a robust multi-currency digital wallet in Africa.

7. Revolut

  • Fees: Free standard allowance; weekend currency conversion surcharges apply.
  • Rate margin: Interbank rates with near-zero markups on weekdays.
  • Speed: Instant within network; 1–3 days for traditional banks.
  • Countries: Sends to 160+ countries across 70 currencies.
  • Best for: Tech-forward travelers requiring multi-currency card spending.

8. XE Money Transfer

  • Fees: Free for large transfers; minor fee for small amounts.
  • Rate margin: Tiered markup that drops significantly on massive transactions.
  • Speed: Typically 1 to 4 business days.
  • Countries: Serves over 130 destination countries worldwide.
  • Best for: Tracking live exchange pairs and executing wire transfers.

9. Sendwave

  • Fees: Zero base fee on primary remittance routes.
  • Rate margin: Fixed retail spread built seamlessly into the rate.
  • Speed: Instant delivery directly into recipient mobile wallets.
  • Countries: Sends from North America and Europe to selective target markets.
  • Best for: No-fuss, instant one-way family remittance payments.

10. Western Union

  • Fees: Scale scales with speed, funding source, and destination.
  • Rate margin: Higher combined markup compared to specialised fintechs.
  • Speed: Minutes for agent pickup; days for bank routing.
  • Countries: Unrivaled footprint spanning over 200 countries.
  • Best for: Reaching recipients located in remote, cash-reliant locations.

11. OFX

  • Fees: Fee-free transfers for major commercial volumes.
  • Rate margin: Declining scale margin optimised for larger amounts.
  • Speed: 1 to 4 business days, depending on location.
  • Countries: Covers international payments across more than 170 countries.
  • Best for: High-value corporate transactions or cross-border property acquisitions.
  1. MoneyGram
  • Fees: Highly dynamic rates depending on credit vs. bank funding.
  • Rate margin: Variable retail spread added over global markets.
  • Speed: Cash payouts clear in minutes; wires take 3 days.
  • Countries: Network extends across more than 200 physical countries.
  • Best for: Urgent retail cash collections via global agent stands.

13. Xoom

  • Fees: Flat fees mapped directly to underlying PayPal integrations.
  • Rate margin: Standard commercial percentage markup added to conversions.
  • Speed: Fast execution when utilising debit cards or bank balances.
  • Countries: Sends seamlessly across more than 160 countries.
  • Best for: Existing PayPal account holders prioritising transfer convenience

14. Payoneer

  • Fees: Standard receiving fees scaling up to 3%.
  • Rate margin: Competitive foreign exchange conversion spreads applied.
  • Speed: 1 to 3 business days to hit local bank.
  • Countries: Wide availability across 200+ countries and territories.
  • Best for: Marketplace payouts for e-commerce platforms and global networks.

15. Afriex

  • Fees: Zero platform fees for transactions passing standard guidelines.
  • Rate margin: Low-spread markup integrated into structural transfers.
  • Speed: Settles within minutes to bank rails or wallets.
  • Countries: Connects North America and Europe to key African hubs.
  • Best for: Rapid diaspora money transfers with minimal fee overhead.

16. Geegpay

  • Fees: Around 1% processing charge on incoming wallet setups.
  • Rate margin: Competitive, freelancer-focused retail currency exchange spreads.
  • Speed: Local distributions clear instantly; global wires take 3 days.
  • Countries: Supports Western inbound billing routes for African contractors.
  • Best for: African remote workers billing international clients via foreign bank rails.

17. Chipper Cash

  • Fees: Free peer-to-peer domestic and cross-border app transactions.
  • Rate margin: Variable currency conversion margin added on foreign swaps.
  • Speed: Wallet-to-wallet transactions execute instantly across borders.
  • Countries: Operational across core African nations, the US, and UK.
  • Best for: Quick mobile peer-to-peer payments between supported countries.

18. Atlantic Money

  • Fees: Flat fixed cost of £3 or €3 per transaction.
  • Rate margin: Strict 0% markup utilising true live mid-market rates.
  • Speed: 1 to 3 standard business days to settle.
  • Countries: Focused predominantly on UK and Eurozone banking rails.
  • Best for: High-volume transfers within Europe at flat predictable costs.

19. Airwallex

  • Fees: Clear volume pricing geared toward digital company infrastructure.
  • Rate margin: Commercial interbank spreads tailored for wholesale enterprises.
  • Speed: Real-time processing ranging up to 2 days.
  • Countries: Worldwide operational scale covering over 150 countries.
  • Best for: Tech startups managing multi-currency SaaS billing infrastructure.

20. Send App (by Flutterwave)

  • Fees: Clear flat rates depending on the selected currency pair.
  • Rate margin: Structured retail spread built into regional corridors.
  • Speed: Settles within minutes into standard destination bank accounts.
  • Countries: Channels money from Europe and the US into 30+ destinations.
  • Best for: Quick remittance tracking via a major African gateway engine.

21. Sendcash

  • Fees: Free underlying platform interaction charges.
  • Rate margin: Blended rates calculated through crypto-backed payment rails.
  • Speed: Direct bank settlement within 24 hours.
  • Countries: Inbound global remittances targeted toward the Nigerian market.
  • Best for: Sending funds internationally, utilising underlying digital currency paths seamlessly.

The best apps for each popular money transfer route

The right app depends on where the money is coming from, where it needs to go and whether speed, exchange rates, fees or flexible payment options matter most.

US to Mexico

Top pick: TapTap Send

  • Why it stands out: TapTap Send focuses on international remittances, with fast transfers to supported Mexican bank accounts and cash-pickup locations.

Alternative: Remitly

  • Why consider it: Remitly offers different delivery speeds and cash-pickup options, giving you flexibility when you need to send money from the US to Mexico.

US to Nigeria

Top pick: Grey

  • Why it stands out: Grey gives eligible users a digital way to manage USD and NGN, making it easier to send money from the US to Nigeria while seeing the applicable rate and fees before confirmation.

Alternative: LemFi

  • Why consider it: LemFi focuses on international remittances and offers a straightforward option for sending money from the US to Nigeria.

UK to India

Top pick: Wise

  • Why it stands out: Wise uses the real exchange rate and shows the conversion fee separately, making the cost easier to understand before you complete the transfer.

Alternative: ZoltMoney and Grey

  • Why consider it: ZoltMoney focuses specifically on transfers between the UK and India, so it is worth comparing its live payout against Wise before choosing. Grey also makes it easy to send money from the UK to India, giving you another simple option for the transfer.

Europe to Africa

Top pick: Grey

  • Why it stands out: Grey is useful when you regularly move money between Europe and Africa because eligible users can receive and hold supported currencies, manage international payments and convert funds when needed.

Alternative: Eversend

  • Why consider it: Eversend supports selected Africa-focused corridors and multiple currencies, depending on your destination and payment needs.

How to avoid hidden fees when converting foreign currency

Check the rate before converting.

Do not look at the advertised fee alone. Check the exchange rate you will actually receive. If the market rate is ₦1,350 per dollar but you receive ₦1,327, the difference reduces the amount you receive per conversion. On $500, a ₦23 difference per dollar means you receive ₦11,500 less than the market rate.

Time your conversions.

You do not always have to convert your money as soon as it arrives. If you receive $500 when the rate is ₦1,327 and it later moves to ₦1,350, waiting could give you about ₦11,500 more. Of course, exchange rates can also move in the opposite direction, so timing only makes sense when you can afford to wait.

Understand where you can hold your money.

Holding foreign currency before converting is only possible on platforms that let you maintain a foreign currency balance. With a platform such as Grey, you can receive USD into your account and decide when to convert it. This gives you more control than receiving a foreign currency payment directly into a bank account where the conversion may happen automatically.

Compare the total cost, not just conversion fees.

Different platforms use different fee structures. One may charge a visible conversion fee, while another may build costs into the exchange rate or charge for receiving or withdrawing funds. Look at the receiving fee, conversion fee, exchange rate and withdrawal cost together to see how much you will actually receive.

Also read: Cheapest way to send money from Nigeria in 2026

A $500 example

Here is a simple example of what happens when you compare the full cost of converting and withdrawing $500 using Grey

Grey is built for freelancers and uses a dedicated virtual receiving account model.

  • Receiving fee: $4.00 (0.8% ACH deposit fee), leaving $496.00 in the wallet.
  • Conversion fee: $4.96 (1% flat conversion fee), leaving $491.04 to convert.
  • Exchange rate: ₦1,327.
  • Bank withdrawal fee: ₦35 flat.
  • Amount received: ₦651,575.

The fees are shown as separate costs, so you can see exactly what is deducted before the money reaches your Nigerian bank account.

Is it safe to send money with an app?

Yes, sending money with a reputable app can be safe, but you should check how the platform protects your money and personal information before using it. Start with registration: use the official app or website, create a strong password and complete any identity checks required. Avoid signing up through links sent by unknown people or messages.

Look for security features such as two-factor authentication, transaction notifications, device verification and encryption. It is also worth checking whether the app is regulated or licensed to provide financial services in the countries where it operates. These safeguards can reduce the risk of someone accessing your account or making a transaction without your knowledge.

Scams are often easier to avoid when you slow down before sending money. Check the recipient's details carefully, especially when making a first payment, and never share your password, PIN or one-time verification code. Be cautious of anyone asking you to send money urgently or promising unusually favourable exchange rates. Use the app's official support channels if something looks suspicious.

Frequently asked questions

1. What is the best app to send money internationally?

The best app depends on your destination, transfer speed, fees and how you want the recipient to receive the money. Compare the exchange rate and total cost before choosing. Grey is an option for freelancers who need to receive and manage international payments across currencies.

2. Which money transfer app has the lowest fees?

There is no single app with the lowest fees for every transfer. Costs can change based on the amount, currency and payment method. Compare the total amount the recipient receives, not just the advertised transfer fee, before deciding which app offers better value.

3. What is the fastest way to send money abroad?

The fastest option depends on the currencies, countries and payout method involved. Some apps can deliver money almost instantly, while bank transfers may take longer. Before sending, check the estimated delivery time shown by the app and whether the recipient can receive funds directly into their bank account.

4. Is it safe to send money with an app?

Yes, reputable money transfer apps use security measures such as encryption, two-factor authentication, identity verification and transaction alerts. You should still protect your login details, verify recipient information and only download apps from official sources. Never share your password, PIN or one-time verification code with anyone.

5. How much can I send internationally with an app?

Transfer limits vary between apps and can depend on your country, currency, account verification level and payment method. Some platforms may also set daily or monthly limits. Check the app's sending limits before starting a large transfer, particularly if you need to send money regularly.

6. Do money transfer apps show the exchange rate before I send?

Most reputable apps show the exchange rate and fees before you confirm a transfer. This lets you see how much you will pay and how much the recipient should receive. Grey also shows the applicable exchange rate and fees before you complete your transaction, helping you understand the total cost upfront.

USD savings accounts for NRIs: How to save in dollars from India

•

•

2 min read

As an NRI, you earn in dollars, but your financial roots are in India. The question isn't whether to save in USD. It's where to park those dollars, so they're accessible, earning returns, and not eroding from conversion fees every time you move money.

NRIs can save in USD through FCNR deposits at Indian banks (3 to 5% interest, 1 to 5-year terms). NRE accounts hold rupees but are tax-free and fully repatriable. Multi-currency fintech accounts hold USD with real local account details. The best choice depends on whether you prioritise returns, liquidity, or tax efficiency.

This guide compares every option for NRIs who want to build a dollar cushion, whether you're saving for a future return to India, hedging against rupee depreciation, or simply keeping your income in the currency you earned it. For the broader perspective, see how to save in foreign currency.

Understanding NRI account types

Before diving into USD savings specifically, you need to understand the three account types available to NRIs in India. Each serves a different purpose, and mixing them up leads to tax problems and repatriation headaches.

NRE (Non-Resident External) Account. Rupee-denominated. You deposit foreign currency, and it's converted to INR at the bank's rate on the day of deposit. Interest earned on an NRE account is generally exempt from income tax in India while you meet the applicable non-resident eligibility conditions. Both the principal and interest are fully repatriable, subject to banking and regulatory requirements. NRE accounts come in savings and fixed deposit variants. The fixed deposit rates typically run 6 to 7% for 1-year terms, which sounds attractive until you realise the deposit is in rupees, not dollars. If the rupee depreciates 5% against the dollar during your deposit term, your effective return drops to 1 to 2% in dollar terms.

NRO (Non-Resident Ordinary) Account. Also rupee-denominated. Designed for income earned in India: rental income, dividends from Indian stocks, pension payments, or sale proceeds from Indian property. Interest earned on an NRO account is taxable in India and generally subject to tax deducted at source (TDS), with the applicable rate depending on tax rules and treaty benefits. NRIs can generally repatriate up to USD 1 million per Indian financial year from eligible NRO balances and other qualifying assets, subject to applicable taxes, documentation and bank requirements. Current income, including eligible interest and rent, may be remitted separately under RBI rules. NRO accounts are not ideal for USD savings because of the tax hit and repatriation cap.

FCNR (Foreign Currency Non-Resident) Account. This is the one most NRIs looking for USD savings should focus on. FCNR deposits hold your money in foreign currency (USD, GBP, EUR, JPY, CAD, AUD). No currency conversion on deposit or withdrawal. Interest rates typically 3 to 5% for USD deposits. Tax-free in India. Fully repatriable. The FCNR is the closest thing to a traditional dollar savings account available through the Indian banking system. For how much you can send from India, see LRS guide.

FCNR deposits: The traditional NRI dollar savings

FCNR deposits are term deposits, not savings accounts. FCNR(B) deposits have a minimum tenure of one year and a maximum of five years under RBI rules. They are term deposits rather than regular savings accounts, and premature withdrawal may reduce or eliminate the interest earned, depending on the bank's terms. Think of them as CDs (certificates of deposit) denominated in foreign currency.

Current USD rates (approximate, mid-2026):

SBI: 3.0 to 4.5% (varies by tenure; longer terms generally offer higher rates)

HDFC Bank: 3.15% to 3.80% (typically the most competitive among private banks)

ICICI Bank: 3.25% to 4% (similar range to SBI, sometimes with promotional rates)

Axis Bank: 3.0 to 4.25% (slightly lower ceiling than HDFC)

Kotak Mahindra Bank: 3.0 to 4.5% (competitive with public sector banks)

These rates change frequently, sometimes monthly. Check with your bank before committing. Longer tenures typically offer higher rates. A 5-year USD FCNR at HDFC might yield 4.75%, while a 1-year deposit at the same bank yields 3.25%. The rate is locked at the time of deposit and doesn't change during the term.

Pros: no currency risk (your principal stays in USD), tax-free in India under current law, fully repatriable without limit, and backed by Indian bank deposit insurance (DICGC covers up to INR 5 lakh per depositor per bank, though the dollar equivalent fluctuates with the exchange rate).

Cons: locked for 1 to 5 years with no additions allowed mid-term, early withdrawal penalties (typically 1% reduction in the applicable interest rate, meaning you might earn 2% instead of 3%), minimum deposit requirements ($1,000 to $10,000 depending on the bank), and you need an NRE or NRO account at the same bank to open an FCNR. The branch visit requirement is the biggest friction point. While some banks allow remote FCNR opening via video KYC, many still require either an in-person visit or a notarised application from abroad.

The tax question most NRIs miss: FCNR interest is tax-free in India, but it may be taxable in your country of residence. US-resident NRIs must report FCNR interest on their US tax returns. UK-resident NRIs must report it to HMRC. The India tax benefit doesn't eliminate the foreign tax obligation. Consult a cross-border tax advisor before assuming the interest is truly tax-free.

Multi-currency accounts: The flexible alternative

If the rigidity of FCNR deposits doesn't suit you, maybe you want access to your dollars without a lock-in period, or you want to hold smaller amounts and add to them regularly, a multi-currency fintech account offers more flexibility at the cost of interest.

Key differences from FCNR:

No lock-in period. Add or withdraw anytime. Your dollars are liquid, not frozen for 1 to 5 years.

No minimum deposit. Start with any amount. FCNR requires $1,000 to $10,000 upfront. A Grey account has no minimum balance requirement.

No branch visit. Open online, manage from your phone. The entire process takes minutes, not the days or weeks that FCNR paperwork takes.

Real USD account details. A Grey account provides you with a US routing number and an account number. Your US employer or client can pay you directly via ACH. An FCNR requires a SWIFT transfer to fund it, which costs $15-$50 per deposit.

No interest (in most cases). The trade-off for flexibility is that most multi-currency accounts don't pay interest on balances. You hold dollars, but they don't grow. On a $10,000 balance, an FCNR at 4% earns you $400 per year. A Grey account earns $0. The question is whether the flexibility and lower costs offset the lost interest.

If you earn in USD regularly and want to hold dollars flexibly, a multi-currency account (Grey, Wise). You receive payments, hold USD, and convert to INR when the rate is favourable. No lock-in. Use this for your active income and short-term savings.

Common mistakes NRIs make with USD savings

Leaving dollars in a US checking account earning 0%. If you're not going to invest the money, at least move it to an FCNR where it earns 3 to 5%. Idle dollars in a Chase or Bank of America checking account lose purchasing power to inflation every year.

Converting to rupees immediately upon receiving payment. If you don't need the rupees right now, why convert? Every conversion costs 0.5 to 1.5%. Hold the dollars and convert when you actually need INR, or when the rate is favourable. A Grey account lets you time your conversions without FCNR lock-in.

Ignoring the rupee depreciation trend. Over the past 10 years, the Indian rupee has depreciated roughly 3 to 5% per year against the US dollar. That means your NRE fixed deposit earning 7% in rupees effectively earns 2 to 4% in dollar terms after currency depreciation. An FCNR earning 4% in actual dollars may outperform the NRE on a dollar-adjusted basis.

Not claiming DTAA benefits. India has Double Taxation Avoidance Agreements with many countries. If you're paying tax on FCNR interest in your country of residence, you may be able to claim a credit for taxes paid (or exempted) in India. Most NRIs don't bother with the paperwork and end up overpaying.

Saving in USD with Grey

Grey lets you hold USD in a Grey USD account with real US routing and account details. You receive payments from US clients or employers via ACH (no SWIFT fees), hold the dollars for as long as you want, and convert to INR through Grey when the rate works for you. No FCNR lock-in, no branch visit, no minimum balance.

Earn in dollars? Hold them in a Grey account and convert to INR on your terms.

Frequently asked questions about USD savings accounts for NRIs

Are FCNR deposits taxable in India?

No. Interest earned on FCNR deposits is tax-free in India for NRIs under Section 10(15)(iv)(fa) of the Income Tax Act. However, it may be taxable in your country of residence (the US taxes worldwide income; the UK taxes on a remittance basis or on an arising basis, depending on your status). Check with a cross-border tax advisor in both jurisdictions before assuming the interest is tax-free overall.

Can I open an FCNR account from abroad?

Yes. Most major Indian banks (SBI, HDFC, ICICI, Axis) allow NRIs to open FCNR accounts remotely through their online banking platforms or NRI service centres. You'll need your NRE or NRO account with the same bank, a valid passport, proof of overseas address, and sometimes a video KYC call. Processing takes 3 to 10 business days, depending on the bank.

What happens to my FCNR deposit when I return to India?

If you return to India and your NRI status changes to resident, your FCNR deposit can be held until maturity at the original rate. At maturity, the proceeds must be converted to INR and credited to a resident savings or fixed deposit account. The interest earned during NRI status remains tax-free in India. You cannot renew the FCNR after returning.

Does the $250,000 LRS limit apply to NRIs?

The Liberalised Remittance Scheme allows Indian residents (not NRIs) to remit up to $250,000 per financial year abroad. NRIs are not subject to LRS for repatriation of NRE and FCNR funds, which are fully repatriable without limit. LRS applies to resident Indians sending money abroad, not to NRIs bringing money home. See the full LRS guide for details.

Should I save in USD or invest in US stocks?

Different goals. USD savings (FCNR, Grey) protect your principal and provide liquidity. US stock investments offer growth potential but carry market risk. For emergency funds and short-term savings, keep dollars in FCNR or a Grey account. For long-term wealth building, consider both. The two aren't either/or.

Hold USD as an NRI. Open a Grey account and receive US payments with real account details.

Disclaimer: This article is for informational purposes only. All costs and details are estimates based on mid-2026 data. Verify current information before making decisions. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

Navy Federal wire transfer: Routing number and how to send

•

•

2 min read

Sending money by wire transfer is one of the fastest ways to move funds when timing matters. Whether you're paying for a property purchase, covering an urgent bill, supporting family, or transferring large sums securely, getting every detail right is essential. A single incorrect routing number or missing banking detail can delay your payment, cause unnecessary stress, or even result in additional fees. That's why understanding how Navy Federal wire transfers work before you initiate one can save you both time and money.

If you bank with Navy Federal Credit Union, knowing the correct routing number is only the first step. You'll also need to understand the differences between domestic and international wire transfers, what information recipients must provide, and the costs involved. Having this information ready helps ensure your transfer reaches its destination without avoidable complications.

This guide explains the Navy Federal wire transfer routing number, how to send both domestic and international wire transfers, the details you'll need before you begin, applicable fees, and practical tips to help your transfer go through smoothly the first time.

Also read: Wire transfer vs ACH: cheapest way to receive USD

Navy Federal routing number for wire transfers

The Navy Federal Credit Union wire transfer routing number is 256074974. This is the routing number you should use when sending or receiving a domestic wire transfer through your Navy Federal account. Entering the correct routing number is essential, as it helps ensure your funds are routed to the right financial institution and prevents processing delays.

You may also see the wire transfer routing number referred to as an ABA routing number or ABA transit number. Assigned by the American Bankers Association (ABA), this unique nine-digit number identifies financial institutions in the United States for wire transfers and other banking transactions. Whenever you're asked to provide the ABA routing number for a Navy Federal wire transfer, use 256074974.

Also read: How ACH payments work for freelancers outside the US

How to send a domestic wire transfer with Navy Federal

Sending a domestic wire transfer with Navy Federal Credit Union is straightforward. You can complete it through online banking or by visiting a branch if you prefer in-person assistance. Before you begin, make sure you have the recipient's banking details ready to avoid delays or errors.

  1. Log in to your Navy Federal online banking account.
  2. Navigate to "Transfers" and select the "Wire Transfer" option.
  3. Enter the recipient's details, including their full name, account number, bank routing number, and the receiving bank's name.
  4. Review all the information carefully, as incorrect details can delay or misdirect your transfer.
  5. Confirm and submit the wire transfer, then save or print the confirmation for your records.

Domestic wire transfers are typically processed on the same business day if submitted before Navy Federal's cut-off time. Transfers requested after the daily cut-off, on weekends, or on public holidays are usually processed on the next business day. Processing times may also vary depending on the receiving bank.

How to send an international wire from Navy Federal

Sending an international wire transfer through Navy Federal requires a few more details than a domestic transfer because the payment must pass through the global banking network. Before starting your transfer, confirm the recipient's banking information to minimise delays or rejected payments.

To complete the transfer, provide the recipient's full name, account number, recipient bank name and address, the bank's SWIFT/BIC code, and the IBAN (International Bank Account Number) where applicable. Some countries may also require additional payment instructions or the details of an intermediary bank. Navy Federal recommends using the wiring instructions provided by the recipient's financial institution to ensure the funds are routed correctly.

International wire transfers typically take 1 to 5 business days, although some destinations or intermediary banks may extend the delivery time. Navy Federal requires that certain wire requests exceeding $5,000, such as third-party transfers, be submitted in writing via a secure message or at a branch. There is no published maximum limit for standard international wire transfers, but larger transactions may be subject to additional verification.

How much does a Navy Federal wire transfer cost?

Before sending a wire transfer, it's important to understand the fees involved. Navy Federal Credit Union charges different fees depending on whether you're sending or receiving a wire and whether the transfer is domestic or international. While incoming wire transfers are free, outgoing transfers attract a flat fee.

Wire transfer type Navy Federal fee Traditional bank fees Grey fees
Incoming Domestic $0 $10–$15 0.8% via ACH/FedNow (Min $2, Max $10)
Outgoing Domestic $20 $25–$35 $20 flat via Fedwire
Incoming International $0 $15–$25 0.8% via local networks (Max $10)
Outgoing International $25 $35–$50+ 1% conversion (capped at $6) + network fee

Overall, Navy Federal's pricing is competitive compared with many traditional banks, particularly because it does not charge for incoming domestic or international wire transfers. However, international payments can still become expensive once exchange rate mark-ups and intermediary bank charges are added.

Navy Federal wire transfer limits

Navy Federal Credit Union sets a daily outgoing limit of $100,000 for digital wire transfers initiated through online or mobile banking. This limit applies to outgoing domestic and international wires submitted electronically. If you need to transfer more than the online limit, the digital cap cannot be increased. Instead, you'll need to complete and sign a wire transfer request form and submit it through Navy Federal's secure eMessaging service or visit a branch to have the transfer processed. Larger transactions may also be subject to additional identity verification and security checks.

If your wire transfer exceeds the $100,000 daily limit, you have several options. You can split the transfer into multiple transactions over consecutive days, submit the wire directly through a Navy Federal representative by calling 1-888-842-6328, or visit a branch for assistance. Another alternative is to transfer your funds to an external bank account via ACH and initiate the larger wire transfer from that financial institution if it better suits your transfer needs.

Why Grey is a smarter choice for international transfers

While Navy Federal Credit Union offers a reliable way to send money abroad, international wire transfers can become expensive once wire fees, exchange rate markups, and intermediary bank charges are factored in. Some larger transfers may also require signed forms or an in-branch visit, adding extra time to the process. If you send money internationally on a regular basis, a digital money transfer platform can provide a faster and more cost-effective experience.

Navy Federal Credit Union Grey Finance
Transfer Process May require in-branch visits or manual forms for some transfers 100% digital via web or mobile app
Outbound International Wire Fee $25 flat fee per transfer $0 send fee (network fee only)
Exchange Rate Markup Typically 3%–5% above the mid-market rate Real-time mid-market exchange rates
Conversion costs Often built into the exchange rate 1% conversion fee (capped at $6)

For anyone who frequently sends money overseas, Grey can offer significant savings compared with traditional bank wires. By eliminating hidden exchange rate markups, reducing conversion costs, and providing a fully digital transfer experience, it makes international payments faster, more transparent, and often considerably cheaper than conventional banking options.

Frequently asked questions

How long does a Navy Federal wire transfer take?

Domestic wire transfers are typically processed on the same business day if submitted before the daily cut-off time. International wire transfers generally take one to five business days, depending on the destination country, intermediary banks, time zones, and whether all recipient banking details were provided correctly.

Can I cancel a Navy Federal wire transfer?

You may be able to cancel a wire transfer if it has not yet been processed or released by Navy Federal. Contact the credit union immediately if you notice an error or wish to stop the transfer. Once a wire has been completed, it is generally difficult or impossible to reverse.

What happens if I enter the wrong routing number?

Entering an incorrect routing number can delay your transfer, cause it to be rejected, or send the funds to the wrong financial institution. Always verify the recipient's banking details before submitting a wire transfer. Contact Navy Federal immediately if you realise you've entered incorrect information.

Does Navy Federal charge for incoming wire transfers?

No. Navy Federal Credit Union does not charge a fee to receive domestic or international wire transfers. However, if you're receiving an international wire, intermediary or correspondent banks involved in processing the payment may deduct their own fees before the funds reach your account.

Can I send a wire transfer from the Navy Federal app?

Yes. Eligible members can initiate domestic and international wire transfers through the Navy Federal mobile app or online banking. However, certain transactions, particularly higher-value transfers, may require additional verification, a signed request submitted through secure messaging, or assistance from a branch representative.

Is there a minimum amount for a Navy Federal wire transfer?

Navy Federal does not publish a minimum amount for sending a wire transfer. You can generally send any amount that meets your needs, provided it falls within the applicable daily transfer limits and you satisfy the credit union's verification and account eligibility requirements.

Whether you're sending money within the US or abroad, understanding Navy Federal's wire transfer routing number, fees, limits, and processing times can help you avoid costly mistakes and delays. For international transfers, if you're looking for lower fees, better exchange rates, and a fully digital experience, Grey is a smart alternative. Open a Grey account today or download the Grey app to send money internationally faster, more affordably, and with complete transparency.

Arrow (up)

Back to top
