<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/best-prepaid-travel-cards#article","headline":"The best prepaid travel cards for international payments","description":"Best prepaid travel cards for international payments ranked by fees, exchange rates, and acceptance. Find the right card for your trip. Compare now.","inLanguage":"en","url":"https://grey.co/blog/best-prepaid-travel-cards","mainEntityOfPage":{"@id":"https://grey.co/blog/best-prepaid-travel-cards#webpage"},"datePublished":"2026-09-16T12:17:23.521Z","dateModified":"2026-09-16T13:20:31.610Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/best-prepaid-travel-cards#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6aaa88be4f753203c86a8a20_image%20(21).jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6aaa88be4f753203c86a8a20_image%20(21).jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/best-prepaid-travel-cards#webpage","url":"https://grey.co/blog/best-prepaid-travel-cards","name":"Best Prepaid Travel Cards for International Payments | Grey","description":"Best prepaid travel cards for international payments ranked by fees, exchange rates, and acceptance. Find the right card for your trip. Compare now.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/best-prepaid-travel-cards#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/best-prepaid-travel-cards#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/best-prepaid-travel-cards#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"The best prepaid travel cards for international payments","item":"https://grey.co/blog/best-prepaid-travel-cards"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/best-prepaid-travel-cards#faq","mainEntity":[{"@type":"Question","name":"What is the best prepaid travel card in the UK?","acceptedAnswer":{"@type":"Answer","text":"Wise is a strong choice for travellers who want competitive exchange rates and multi-currency spending. Other options, including Revolut and Post Office Travel Money Card, may suit different needs, so compare fees, currencies and ATM costs before choosing."}},{"@type":"Question","name":"Are prepaid travel cards better than credit cards for travel?","acceptedAnswer":{"@type":"Answer","text":"It depends on how you travel. Prepaid cards can help you control spending because you use money loaded onto the card, while travel credit cards may offer rewards, purchase protection or other benefits. Compare exchange rates, fees, insurance and spending habits before deciding."}},{"@type":"Question","name":"Do prepaid travel cards charge ATM fees?","acceptedAnswer":{"@type":"Answer","text":"Some do, while others offer a fee-free allowance. For example, Revolut Standard allows fee-free withdrawals up to £200 per month, while Post Office charges withdrawal fees that vary by destination. The ATM itself may also add a separate charge."}},{"@type":"Question","name":"What is dynamic currency conversion and should I avoid it?","acceptedAnswer":{"@type":"Answer","text":"Dynamic currency conversion lets a foreign merchant or ATM convert your purchase into your home currency. The exchange rate can include a markup, making the transaction more expensive. When given the choice, paying in the local currency usually lets your card provider handle the conversion instead."}},{"@type":"Question","name":"Can I use a prepaid travel card in any country?","acceptedAnswer":{"@type":"Answer","text":"Not necessarily. Acceptance depends on the card network, supported currencies and the provider's country restrictions. Some cards can still process payments in unsupported currencies, but additional conversion or cross-border fees may apply. Always check your destination before travelling."}},{"@type":"Question","name":"What happens if I lose my prepaid travel card abroad?","acceptedAnswer":{"@type":"Answer","text":"Most providers let you freeze a lost card to prevent further spending, while some offer replacement options. Because a prepaid card uses a loaded balance rather than your main bank account, keeping the card separate can also limit your exposure if it is lost."}}]}] </script>

The best prepaid travel cards for international payments

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

The cost of travelling abroad does not stop when you have paid for your flight and hotel. Once you arrive, everyday spending can become more expensive when your bank adds foreign transaction fees, uses a poor exchange rate or charges you each time you take out cash. A prepaid travel card can help you avoid some of these costs by letting you load money before your trip and spend from that balance in supported currencies.

But choosing one is not simply about finding a card with no transaction fee. The exchange rate, ATM charges, loading fees, supported currencies, and where the card is accepted can all affect how much your trip really costs. Some cards also work better for international payments than others, particularly when you need to pay online or use your card across several countries.

This guide compares the best prepaid travel cards for international payments, so you can choose one that keeps your travel money easier to manage and helps you avoid unnecessary fees.

Also read: How non-US residents can get a virtual dollar card in 2026

A prepaid travel card lets you load money before you travel and spend in local currencies without paying foreign transaction fees on every purchase. The best options avoid ATM fees, charge the mid-market exchange rate or close to it, and work in most countries. Top picks include Grey, Wise, Revolut, and Caxton.

What is a prepaid travel card, and how does it work?

When you travel abroad, the way you pay can affect your budget almost as much as where you stay or what you eat. A prepaid travel card lets you set money aside before your trip, load it onto the card, and spend from that balance when you arrive. Most work much like debit cards, but you are spending money you have already loaded rather than borrowing from a credit provider.

This is where a prepaid travel card differs from a standard debit card or credit card. A normal debit card does not automatically protect you from foreign transaction fees, while a credit card lets you spend borrowed money and may charge interest if you do not repay the balance in full. Prepaid cards give you tighter control because you can only spend what you have loaded.

The exchange rate is another important difference. Some cards let you convert your money when you load the card, locking in that rate before you travel. Others convert your balance when you make a purchase, using the rate in effect at that time.

For travellers, live-rate cards can be more flexible because you are not locked into a rate chosen days or weeks before your trip. If the provider uses a competitive rate with a low markup, your money can be converted closer to the time you actually spend it.

Also read: What is a dollar card and how does it work?

What to look for in a prepaid travel card

The right prepaid travel card should keep international spending simple, with low fees, competitive exchange rates, wide acceptance and easy access to your money.

  • Foreign transaction fees and FX markups. When comparing a prepaid travel card, start with the cost of spending abroad. Check whether the provider charges a foreign transaction fee or adds an FX markup to its exchange rate.
  • ATM withdrawal fees. ATM costs matter too, particularly if you expect to withdraw cash during your trip. Check the withdrawal fee and the monthly withdrawal limit before charges apply.
  • Supported currencies. Look at the currencies supported. Some cards let you hold several currencies, while others automatically convert your balance when you pay.
  • Visa or Mastercard acceptance. Visa and Mastercard are both widely accepted internationally. Check whether the card works in the countries you plan to visit and whether you can add it to Apple Pay or Google Wallet.
  • Easy top-ups. Finally, consider how easily you can top up the card from your local bank account. A simple funding process means you can add money when needed without unnecessary steps or delays

The best prepaid travel cards compared

Here’s how popular prepaid travel cards compare on exchange rates, ATM costs, monthly fees, supported currencies and the travellers they suit best.

Card FX markup on spending ATM free allowance ATM fee above allowance Monthly fee Currencies supported Best for
Grey Custom spread (~1% to 2%) + 2% on non-USD payments N/A (virtual-only setup, no cash access) N/A $0.00 3 (USD, GBP, EUR wallets) African freelancers and remote workers receiving international payments
Wise 0% (mid-market rate). Small variable processing fee from 0.24% £250/month (maximum 2 withdrawals) 2% + £0.50 per transaction $0.00 (£7 one-time physical card fee) 40+ currencies Travellers who want transparent multi-currency spending and clear conversion fees.
Revolut 0% on weekdays up to £1,000/month; 1% markup on weekends £200/month (maximum 5 withdrawals) 2% of the amount withdrawn $0.00 30+ currencies Online spending and flexible card management
Monzo 0% (direct Mastercard exchange rate) £200/month outside the UK/EEA 3% of the amount withdrawn $0.00 (paid plans offer higher limits) GBP base balance with automatic conversion Everyday spending and managing travel money
Caxton 0% when spending pre-loaded currencies; 2.49% for unsupported currencies Unlimited free withdrawals abroad when using a pre-loaded currency £0.00 abroad; £1.50 at UK domestic ATMs $0.00 (£2/month after 12 months of inactivity) 15 pre-loadable currencies Locking in an exchange rate before travelling
Post Office Travel Money Card 0% for loaded currencies; 3% when spending across currencies or when the balance drops Unlimited free withdrawals abroad for pre-loaded currencies Fixed network fee of roughly £1.50 / €2.00 / $2.50 $0.00 (£2/month after 18 months of inactivity) 22 currencies -

Grey Visa travel card for international spending

Travelling with one card can make payments easier, especially when you are moving between countries with different currencies. The Grey Card is a Visa virtual card that can be used globally wherever Visa is accepted, giving you a convenient way to pay for online purchases, subscriptions and other eligible card payments while abroad.

One useful feature is that you can hold money in different currencies through your Grey account, including USD, GBP and EUR. When you make a payment, you can spend from the balance that suits the transaction, rather than converting your money before every purchase. This can make managing travel spending simpler when you already hold funds in more than one currency.

Grey also charges no foreign transaction fee on eligible card spending. If you regularly receive money internationally or travel between countries, the Grey virtual card lets you keep your supported currencies together and use them for everyday international payments.

Also read: Best prepaid and virtual cards for travellers

How to avoid hidden fees when paying abroad

Paying abroad can cost more than expected when exchange rates and card fees are factored in for everyday purchases. One of the easiest ways to avoid unnecessary charges is to always pay in the local currency. If a card machine or ATM asks whether you want to pay in your home currency, choose the local currency instead. This avoids dynamic currency conversion, where the merchant or ATM provider sets the exchange rate, which may be less favourable.

You can also reduce costs by using your card directly for purchases whenever possible, rather than withdrawing cash. Cash withdrawals may come with ATM fees, provider charges or additional limits, so check your card's withdrawal terms before relying on cash while travelling.

Before your trip, take a few minutes to check your card’s foreign exchange terms, particularly if you will be travelling over a weekend.

  1. Check whether weekend FX markups apply.
  2. Check the exchange rate used for card payments.
  3. Check ATM fees and your free withdrawal allowance.
  4. Check any fees for topping up or converting currencies.

Knowing these charges before you travel makes it easier to choose how and when to spend your money abroad.

Which prepaid travel card is best for your trip?

There is no single best prepaid travel card for every traveller. The right choice depends on how often you travel, whether you are visiting one country or several, and whether you mainly need a card for spending or a broader way to manage international money.

Use the table as a starting point, then check the card’s current fees, supported currencies, spending limits and availability in your destination before making a choice.

Traveller type Card to consider Why it may suit you
Budget traveller Wise or Grey For keeping international spending cost low
Frequent traveller Revolut premium More travel perks
Single country traveller Single currency prepaid card When you need only one currency
Digital nomad Grey Multicurrency management

Frequently asked questions

What is the best prepaid travel card in the UK?

Wise is a strong choice for travellers who want competitive exchange rates and multi-currency spending. Other options, including Revolut and Post Office Travel Money Card, may suit different needs, so compare fees, currencies and ATM costs before choosing.

Are prepaid travel cards better than credit cards for travel?

It depends on how you travel. Prepaid cards can help you control spending because you use money loaded onto the card, while travel credit cards may offer rewards, purchase protection or other benefits. Compare exchange rates, fees, insurance and spending habits before deciding.

Do prepaid travel cards charge ATM fees?

Some do, while others offer a fee-free allowance. For example, Revolut Standard allows fee-free withdrawals up to £200 per month, while Post Office charges withdrawal fees that vary by destination. The ATM itself may also add a separate charge.

What is dynamic currency conversion and should I avoid it?

Dynamic currency conversion lets a foreign merchant or ATM convert your purchase into your home currency. The exchange rate can include a markup, making the transaction more expensive. When given the choice, paying in the local currency usually lets your card provider handle the conversion instead.

Can I use a prepaid travel card in any country?

Not necessarily. Acceptance depends on the card network, supported currencies and the provider's country restrictions. Some cards can still process payments in unsupported currencies, but additional conversion or cross-border fees may apply. Always check your destination before travelling.

What happens if I lose my prepaid travel card abroad?

Most providers let you freeze a lost card to prevent further spending, while some offer replacement options. Because a prepaid card uses a loaded balance rather than your main bank account, keeping the card separate can also limit your exposure if it is lost.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to plan a road trip in the US (plus the best scenic routes)

•

•

2 min read

You've got two weeks off, a car, and roughly $2,000. That's enough for an incredible US road trip if you plan it right, and barely enough for a frustrating one if you don't. Most people start by picking a route. That's actually step two. Step one is deciding how many hours you're willing to drive each day, because that single number determines where you can go, how many stops you can make, and whether you'll enjoy the trip or just survive it.

To plan a road trip, pick your route and stops, set a daily driving limit, budget for fuel, food, and stays, book key accommodation early, and prepare your car. Build in buffer time for detours. Use a card with no foreign transaction fees if you're visiting from abroad.

We've planned this guide around the decisions in the order you actually need to make them, not the order most articles put them in. You'll also find the four best scenic road trips in the US with real distances, costs, and timing, so you can compare routes before committing.

How to plan a road trip: step by step

Planning a road trip comes down to six decisions, made in this order. Skip one and the rest get harder.

1. Choose your route. Start with a destination or a theme. Do you want coastline (Pacific Coast Highway), desert (Utah's Mighty Five parks), history (Route 66), or mountains (Blue Ridge Parkway)? Once you've picked the theme, map the route and identify overnight stops roughly every 3 to 5 hours of driving. Google Maps and Roadtrippers are the two best tools for this.

2. Set a daily driving limit. The number one mistake on road trips is overestimating how far you want to drive in a day. 4 to 5 hours of actual driving is sustainable. Six is fine occasionally. Eight is miserable and dangerous. Plan your stops around a 4-hour average, and you'll enjoy the drive instead of enduring it.

3. Book accommodation for your first and last nights, plus any national parks. Everything in between can stay flexible. But the first night sets the tone (don't arrive exhausted because you drove too far), and national park lodges and campsites book months in advance. If you're visiting in summer, book Yosemite, Zion, or Yellowstone accommodation 3 to 6 months ahead.

4. Budget the trip before you leave. Fuel, food, accommodation, tolls, park entrance fees, and one unexpected cost. We'll break this down below with a worked example.

5. Prepare the car. Tyres, oil, coolant, wipers, and a safety kit. A breakdown 100 miles from the nearest town is the kind of adventure nobody wants. If you're renting, inspect the car before you leave the lot and document any existing damage.

6. Download offline maps. Cell coverage is patchy in rural America, especially through the desert Southwest, mountain passes, and stretches of Montana and Wyoming. Download your entire route on Google Maps or Maps.me before you leave. If you're visiting from abroad and need data on the road, a travel eSIM is cheaper and more reliable than roaming on your home plan.

Best scenic road trips in the US

If you're looking for road trip ideas, these are the four routes that consistently rank as the best road trips in the USA. Here's a quick comparison:

Route Distance Days Est. fuel cost Best season
Pacific Coast Highway ~650 mi 5 to 7 $80 to $120 Apr to Oct
Route 66 ~2,400 mi 10 to 14 $250 to $400 May to Sep
Blue Ridge Parkway ~469 mi 3 to 5 $60 to $90 Sep to Nov
Utah Mighty Five ~900 mi 7 to 10 $120 to $180 Mar to May, Sep to Nov

‍

Pacific Coast Highway is probably the most photographed road trip in the country. San Francisco to Los Angeles (or the reverse), hugging the coast through Big Sur, Monterey, Santa Barbara, and Malibu. It's short enough for a long weekend if you push it, but 5 to 7 days lets you stop at every viewpoint without rushing.

Route 66 is the classic. 2,400 miles from Chicago to Santa Monica, crossing eight states and three time zones. It's a trip through small-town America, roadside diners, and neon signs. Budget at least 10 days. Some stretches of the original route have been replaced by interstate, but most of the iconic stops are still there.

Blue Ridge Parkway is the most underrated route on this list. 469 miles through the Appalachian Mountains from Virginia to North Carolina, with no commercial traffic (trucks are banned). In autumn, the foliage is extraordinary. It's also one of the cheapest road trips because there are no tolls and fuel distances are short.

Utah's Mighty Five hits all five of Utah's national parks in a single loop: Arches, Canyonlands, Capitol Reef, Bryce Canyon, and Zion. The landscape is unlike anything else in the US. Spring and autumn are the sweet spots; summer is brutally hot and parks are overcrowded. An America the Beautiful pass ($80 per vehicle per year), from the National Park Service, covers entrance fees for all five parks.

All fuel costs are estimates based on a vehicle averaging 25 to 30 mpg at mid-2026 US fuel prices. Your actual cost will vary by vehicle, driving style, and fuel price at the time of travel.

How to budget for a road trip

The number that catches most people off guard isn't fuel. It's food. A two-week road trip where you eat at restaurants for every meal can easily cost $1,500 to $2,000 per person. Pack a cooler, buy groceries, and save restaurants for the stops that deserve them.

Here's a worked budget for a 7-day Pacific Coast Highway trip for two people:

Expense Estimated cost (2 people, 7 days)
Fuel (650 mi, 25 mpg, ~$4/gal) $100 to $120
Accommodation (motels + Airbnb mix) $700 to $1,200
Food (groceries + 3 restaurant meals) $400 to $600
Tolls (Golden Gate Bridge + minor) $10 to $20
Park and attraction fees $30 to $80
Unexpected (flat tyre, parking, etc.) $100 to $200
TOTAL $1,340 to $2,220

‍

The range is wide because accommodation drives most of the variance. Camping ($20 to $40 per night) versus a beachfront motel in Big Sur ($250+ per night) changes the total dramatically. If you're saving up for the trip, save for your road trip in a Pouch so the money is set aside and visible, separate from your everyday spending.

All costs are estimates based on mid-2026 prices. Fuel, accommodation, and food costs vary seasonally and by region.

Road trip packing and car prep

Two lists: one for the car, one for you.

Car prep (do this at least a week before you leave): check tyre pressure and tread depth (including the spare), check oil level and coolant, test all lights (headlights, brake lights, indicators, fog lights), replace wiper blades if they streak, and make sure your breakdown cover is active and covers your route.

Safety kit: jump cables or a portable jump starter, a basic tool kit, a torch with fresh batteries, a first aid kit, a reflective warning triangle or flares, and a printed copy of your route (in case your phone dies and there's no signal).

Packing for you: pack light. Road trip luggage lives in the boot, not in overhead bins, so you have more space than flying, but overpacking means less room for souvenirs and groceries. Bring layers (mountain and coastal temperatures swing 15 to 20 degrees between morning and afternoon), comfortable driving shoes, sunscreen, a reusable water bottle, and a cooler if you're planning to buy groceries.

One thing most people forget: a phone mount for the dashboard. Using your phone as a GPS while it sits in your lap is unsafe and illegal in many states. A $15 mount solves this completely.

How to pay on a US road trip

If you live in the US, your regular debit or credit card handles everything. Fuel, tolls, accommodation, food. The only thing to watch is whether your card charges foreign transaction fees if you cross into Canada or Mexico during the trip.

If you're visiting the US from abroad, paying for a road trip gets more complicated. Your home bank card works at most fuel stations and restaurants, but foreign transaction fees of 1.5 to 3% add up fast over a two-week trip. On $3,000 in spending, that's $45 to $90 in fees you didn't need to pay.

A card with no foreign transaction fees is the simplest fix. Grey's virtual Mastercard works at US fuel stations, restaurants, and toll booths. You load USD before you leave and spend from your dollar balance, so there's no conversion markup on every transaction. Pay for fuel and tolls on a virtual card.

For data and navigation, a travel eSIM is cheaper than international roaming. You buy it before you leave, activate it when you land, and get US data for maps, music, and booking accommodation on the road. Buy a travel eSIM for the US. And if you need to move money before you travel, Grey handles that too.

Cash tip: carry $100 to $200 in small bills. Some rural fuel stations, farm stands, and small-town diners are cash-only.

Frequently asked questions about planning a road trip IN the US

How do I plan a road trip for the first time?

Start with a route (pick a destination or a scenic drive). Map your overnight stops every 3 to 5 hours of driving. Book your first night, last night, and any national park accommodation in advance. Budget for fuel, food, stays, and one unexpected cost. Prep the car (tyres, oil, lights). Download offline maps. Everything else can be flexible.

What is the best US road trip for beginners?

The Pacific Coast Highway from San Francisco to Los Angeles. It's short (650 miles, 5 to 7 days), the route is well-marked, accommodation is plentiful, and the scenery is spectacular from start to finish. Reliable cell coverage for most of the route makes navigation easy.

How much does a road trip across the US cost?

A coast-to-coast trip (roughly 2,800 miles, 10 to 14 days) typically costs $2,500 to $5,000 per person. Budget roughly: $300 to $500 for fuel, $1,000 to $2,500 for accommodation, $500 to $1,000 for food, and $200 to $500 for tolls, attractions, and unexpected costs. Camping and cooking drop the total significantly.

How far should I drive per day on a road trip?

4 to 5 hours of actual driving (200 to 300 miles on highways) is the sweet spot. You can push to 6 to 8 hours on long transfer days, but doing that daily will burn you out by day three. Plan around a 4-hour average and add a rest day every three or four driving days.

Do I need an America the Beautiful pass?

If you're visiting two or more national parks, yes. The pass costs $80 per vehicle per year and covers all 400+ National Park Service sites. A single park entry is typically $30 to $35, so the pass pays for itself after three parks. For the Utah Mighty Five loop, it saves roughly $95 in entrance fees.

Can I do a US road trip without a car?

You'll need a car. Public transport doesn't cover most scenic routes. If you don't own a car, rent one early for the best rates. Airport pickup is usually cheaper than city-centre. Under-25 drivers can expect a surcharge of $20 to $30 per day. International visitors need a valid driving licence from their home country.

Hitting the road? Save for your trip in a Grey Pouch and pay for fuel and tolls on a virtual card, wherever the highway takes you.

Disclaimer: This article is for informational purposes only. Fuel prices, accommodation rates, park fees, and toll charges change seasonally. All cost estimates are based on mid-2026 data. Verify current prices before you travel. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

How to avoid foreign transaction fees when travelling abroad

•

•

2 min read

Foreign transaction fees: how to avoid paying extra

Let’s say you land in Tokyo, check into your hotel, decide to grab dinner, and then pay with your card. Nothing feels unusual. Well, until your bank statement arrives, and every single transaction has a small percentage added on. That’s a foreign transaction fee, and over a two-week trip with daily card spending, it quietly adds up to a meaningful sum.

The good news is that foreign transaction fees are avoidable. They’re not a fixed cost of travelling, rather a result of using the wrong card or making the wrong choice at the payment terminal. This guide explains what foreign transaction fees are, how to avoid them, and what to look for in a card that won’t charge you for spending in another country.

What is a foreign transaction fee?

A foreign transaction fee is a charge your bank or card issuer applies when you complete a transaction in a foreign currency, or when a transaction is processed through a foreign bank, even if you’re physically in your home country. According to the Consumer Financial Protection Bureau, foreign transaction fees typically range from 1% to 3% of the purchase amount.

The fee is not charged by the card networks but by the bank or financial institution that issued your card. Two people with Visa cards from different banks can make the same purchase abroad: one pays a foreign transaction fee, and the other doesn’t, depending purely on what their card issuer charges.

Foreign transaction fees apply in several situations:

  • Purchasing something in a foreign currency while travelling abroad
  • Shopping on an international website that processes payments in a foreign currency
  • Making a purchase at a foreign merchant, even if the amount is displayed in your home currency

The fee is typically a percentage of the total transaction value, deducted automatically, so it usually won’t appear as a separate line item at the payment terminal. It shows up later, on your statement, alongside dozens of other charges. Most people don’t notice it until they add everything up.

How to avoid foreign transaction fees

Avoiding foreign transaction fees doesn’t require complicated financial planning. You just need to know which tools to use before you travel.

Use a card with no foreign transaction fee: This is the most straightforward solution. Many travel-oriented cards, premium cards, and digital banking accounts charge zero foreign transaction fees as standard. If your current card charges a foreign transaction fee, switching to one that doesn’t is the single most effective change you can make.

Always pay in the local currency: When you use your card abroad, the payment terminal may offer to charge you in your home currency instead of the local one. Always decline this. It’s called dynamic currency conversion, and it typically adds a significant surcharge on top of whatever fees your card already charges. Paying in local currency means your bank or card issuer handles the conversion, which is almost always cheaper than the merchant doing it.

Withdraw cash strategically at ATMs: If you need cash in local currency, withdraw larger amounts less frequently rather than making multiple small withdrawals. Many cards charge a flat fee per ATM withdrawal abroad, so fewer withdrawals at larger amounts reduce the fixed cost per transaction. Check whether your card has ATM withdrawal fees and whether there’s a network of fee-free ATMs available in your destination.

Use a multi-currency account for extended travel: If you’re travelling for weeks or months, or visiting multiple countries, a multi-currency account lets you hold balances in several currencies and spend from the relevant one without triggering conversion fees. You convert when the rate suits you, not at the moment of every transaction.

Tell your bank you’re travelling: This doesn’t avoid foreign transaction fees, but it prevents your card from being blocked for suspected fraud when you use it abroad, which is a separate problem that costs time rather than money.

Cards with no foreign transaction fee

Not every card charges foreign transaction fees. Knowing which categories typically waive them helps you choose the right one before your next trip.

Travel rewards cards: These are specifically designed for frequent travellers and almost universally offer no foreign transaction fees as a baseline feature. They often include additional travel benefits, such as airport lounge access, travel insurance, and points on international spending.

Premium cards: You’ll usually find these at the higher tier of a bank’s product range, typically waive foreign transaction fees alongside other premium features. The trade-off is usually a higher annual fee.

Digital banking accounts and fintech platforms: Many of these have made no foreign transaction fees a standard feature rather than a premium one. Many digital-first accounts charge zero foreign transaction fees on all purchases, offer competitive exchange rates, and provide virtual cards for secure online spending. This combination makes them meaningfully cheaper than traditional cards, even when the traditional card also claims no foreign transaction fee but still applies an exchange rate markup.

What to look for when comparing cards:

  • Zero foreign transaction fee explicitly stated in the terms, not just a low fee
  • Exchange rate used for currency conversion: mid-market is better than a proprietary rate with a margin built in
  • ATM withdrawal fees abroad, and whether there’s a monthly free allowance
  • Whether the card is virtual, physical, or both
  • Fraud protection and the ability to freeze the card instantly if needed

Read the terms carefully. A card that advertises no foreign transaction fee can still apply an exchange rate margin that costs you 1 to 2% on every conversion. The total cost of spending abroad is the fee plus the rate margin, not just one or the other.

Best travel cards with no foreign fees

The best travel card for spending abroad has several features working together, not just one. Here’s what to look for.

Zero foreign transaction fee: This is the baseline. Any card you use regularly abroad should have this as a confirmed feature, not something to check each time.

Mid-market or near-mid-market exchange rate: The exchange rate is where many cards recoup costs even when they advertise no foreign transaction fee. A card that charges 0% in fees but applies a 2.5% margin to the exchange rate costs you 2.5% on every transaction. The closest rate to the interbank mid-market rate is always better.

No or low ATM withdrawal fees: If you’ll need cash, check the ATM fee structure. Some cards charge a flat fee per withdrawal, others charge a percentage, and some offer a monthly allowance of free withdrawals before fees kick in.

Instant freeze and fraud protection: If your card is lost or compromised while you’re abroad, the ability to freeze it instantly from an app is a practical necessity. Physical cards take days to replace. A virtual card can be frozen in seconds, and a replacement can be issued without waiting for the post.

Multiple currencies in one account: For travellers visiting more than one country, a card linked to a multi-currency account means you’re spending from the right currency balance in each country, avoiding conversion entirely where you’ve pre-loaded the local currency.

The Grey virtual debit card covers all of these. Grey charges no foreign transaction fee on purchases made in the card’s base currency, applies a conversion fee of 1% capped at $6 for currency conversions, and gives you a virtual USD card you can get the Grey virtual debit card and add to Apple Pay or Google Pay in minutes. Grey accounts hold USD, GBP, EUR, and other currencies, allowing you to convert and spend from whichever balance you need.

The cross-border card fee on the Grey virtual card (non-USD purchases on a USD card) is 2% plus $0.50. For travellers who pre-convert to the local currency within Grey before spending, this fee is avoidable entirely.

Dynamic currency conversion: the hidden fee

Dynamic currency conversion (DCC) is the practice where a foreign merchant or ATM offers to convert your transaction into your home currency at the point of sale, rather than charging you in the local currency. It sounds convenient, but it’s more expensive.

Here’s how it works in practice. You’re in Paris, paying €80 for a meal. The card reader asks whether you’d like to pay in euros or in US dollars. If you choose dollars, the merchant’s payment provider handles the conversion, typically at a rate that includes a 5% to 10% margin above the mid-market rate. If you choose euros, your card issuer handles the conversion, almost always at a better rate.

A concrete example: €80 at the mid-market rate on a given day might be $87.20. The same transaction processed via DCC might show as $91.50 or higher, with the merchant’s payment provider keeping the difference. On a single transaction, this is a few dollars. Across ten days of dining, hotels, and activities, it adds up to a meaningful amount paid for no service.

The way to avoid DCC is to always choose to pay in the local currency when given the option. If a card reader asks whether you want to pay in your home currency, decline. If an ATM offers to convert your withdrawal to your home currency, decline. For more details on how card network exchange rates work, see our guide on how Mastercard exchange rates work.

Some merchants apply DCC automatically without asking. In that case, ask to redo the transaction in local currency or dispute the DCC charge with your bank after the fact if the margin applied was excessive.

How to use a multi-currency account when travelling

A multi-currency account improves the travel payment experience in practical ways. Instead of converting every transaction at the point of sale, you convert in advance at a rate you can see and confirm, then spend from the converted balance without any further conversion cost.

For example, before travelling to Japan, you convert $500 to JPY in your multi-currency account at the current mid-market rate, with a transparent conversion fee. For the rest of your trip, every yen you spend comes from that balance.

If you’re travelling to multiple countries, you hold balances in each currency and spend from whichever one applies. Euros in France, pounds in the UK, dirhams in Morocco. Each balance is pre-converted at a rate you confirmed before travel.

Grey lets you hold and convert multiple currencies from one account. You can convert currencies at mid-market rates with Grey and load the converted balance to your Grey virtual card before you travel.

For travellers who earn in one currency and spend in another, such as a remote worker earning USD who spends in EUR, GBP, or NGN while travelling, Grey removes the double conversion problem: converting from USD to local currency at your bank’s rate every time you make a purchase, twice each time, once in and once out.

Frequently asked questions

What is the average foreign transaction fee?

The typical foreign transaction fee charged by traditional banks and card issuers ranges from 1% to 3% of the transaction value. According to the Consumer Financial Protection Bureau, 3% is the most common fee rate among US-issued cards that charge it. On $3,000 in travel spending, a 3% foreign transaction fee costs $90 before any exchange rate margin is applied.

Do all cards charge foreign transaction fees?

No. Many travel-oriented cards, premium cards, and digital banking accounts charge zero foreign transaction fees. The fee is set by the card issuer, not by Visa or Mastercard. Whether your card charges a foreign transaction fee is stated in your card’s terms and conditions, usually in the fees section. If it’s not clearly stated as zero, check before travelling.

Does using a debit card abroad avoid foreign transaction fees?

Not automatically. Whether a debit card charges foreign transaction fees depends on the issuing bank, not the card type. A debit card from a traditional bank can charge the same 1% to 3% as a traditional card. A debit card from a digital banking platform like Grey may charge zero. The card type (debit versus card) matters less than the issuer’s fee policy.

What is dynamic currency conversion, and how do I avoid it?

Dynamic currency conversion (DCC) is when a foreign merchant or ATM offers to charge you in your home currency rather than the local currency. It typically adds 5% to 10% to the effective cost of the transaction because the merchant’s payment provider sets the conversion rate, almost always worse than your card issuer’s rate. Avoid it by always choosing to pay in the local currency when given the option. If a payment terminal asks whether you want to pay in your home currency, decline.

Is it cheaper to pay in cash or by card abroad?

It depends on how you obtain the cash and which card you’re comparing. Withdrawing cash from an ATM abroad with a card that charges withdrawal fees and a poor exchange rate can be more expensive than paying by card with no foreign transaction fee. Conversely, a card with a high foreign transaction fee can make cash, obtained at a fair exchange rate, cheaper. The answer depends on your specific card’s fee structure. A card with no foreign transaction fee, a mid-market exchange rate, and no ATM withdrawal fees is typically the cheapest way to access money abroad, whether for card or cash spending.

Does Grey charge foreign transaction fees?

Grey does not charge a foreign transaction fee on purchases made in the card’s base currency (USD for the Grey virtual USD card). A cross-border card fee of 2% plus $0.50 applies to non-USD purchases made on the USD card. To avoid this fee when spending in non-USD currencies abroad, convert the amount you need to the local currency within your Grey account before travelling and spend from that converted balance.

Exploring Cairo as a city for digital nomads: amenities and culture

•

•

2 min read

Cairo is home to ancient wonders like the Pyramids of Giza and the Sphinx, and also a growing number of digital nomads from across the world seeking diverse work experience and cultural adventures. Cairo has increasingly attracted digital nomads drawn to its low cost of living, rich cultural immersion, and improving digital infrastructure. This article examines the amenities supporting remote work in Cairo, alongside its vibrant culture, to give you a taste of what to expect if you visit.

Also read: Side hustle in Egypt? Here’s how to receive international payments

Amenities for digital nomads in Egypt

Cairo offers a mix of budget-friendly essentials and emerging facilities for remote workers, though it demands adaptability to its chaotic energy. As of 2025, the city ranks among Africa's top destinations for nomads, thanks to its affordability.

  • Internet and connectivity

Internet reliability varies, with average speeds around 20-50 Mbps in central areas. This is good enough for most tasks, but outages can still occur. However, digital nomads have a better experience in co-working spaces or cafes. Portable Wi-Fi devices or SIM cards from providers like Vodafone offer backups, with data plans costing $7-15 monthly.

  • Co-working spaces and workspaces

The co-working scene is growing, with options like Regus offering high-speed internet, meeting rooms, and a professional workspace. Urban Station in central Cairo provides cosy, quiet environments with modern amenities. Other spots include cafes in Zamalek or Maadi with free Wi-Fi. Membership subscriptions range from around $5 per day to $100 per month. These spaces also foster networking among digital nomads, expats and local remote workers.

  • Cost of living

Cairo's affordability is a major plus. You can live comfortably on a monthly budget under $1,000. One-bedroom apartments cost around $350-$500 in areas like Maadi or Heliopolis. Meals are often under $5. If you add around $150 for groceries, you're living way below what you’ll spend monthly in Western cities. Healthcare is cheap, even with out-of-pocket payments. You can also get an affordable health insurance package covering your stay.

  • Accommodation options

Cairo offers a wide range of affordable housing. Digital nomads can find short- and long-term rentals through Airbnb, Booking.com, or local agents. Neighbourhoods like Zamalek, Maadi, and Heliopolis are favourites for their safety, greenery, and proximity to coworking hubs

  • Transport and mobility

Cairo’s public transport system includes buses, taxis, and the metro. Ride-hailing apps like Careem and Uber are widely used and inexpensive. For daily commuting, many nomads prefer Uber due to its safety and comfort. The Cairo International Airport is also well-connected, offering direct flights to major cities in Europe, Africa, and Asia.

  • Financial accessibility

International payments can sometimes be a challenge in Egypt due to local banking restrictions. Traditional banks often limit foreign currency transactions or impose high transfer fees. That’s where platforms like Grey come in, offering multi-currency accounts that let you receive and send money internationally with ease. For remote workers paid in USD, GBP, or EUR, this ensures smooth financial management without the hassle of traditional exchange controls.

Cultural experiences for digital nomads in Cairo

Cairo is culturally vibrant, offering many exciting experiences to explore.

  • Historical and architectural edifices

Egypt is home to many architectural wonders, from mosques like Al-Azhar to ancient churches. The Giza pyramids and the Sphinx are iconic destinations for exploring ancient Egypt.

  • Food and culinary scene

You should whet your taste buds with some Egyptian cuisine, which is usually affordable. The kushari, falafel, and grilled meats are generally under $7.

  • Lifestyle and community

The growing digital nomad and expat communities make it easy to connect with like-minded individuals through meetups and events, often found at the various coworking and co-living spaces. Cairo can be fast-paced with festivals and lively souks.

Also read: How to get an instant USD debit card in Egypt

Managing international payments with Grey

Cairo is an interesting hub for digital nomads with affordability, modern amenities, and cultural diversity. It’s a place where you can immerse yourself in millennia of history while working from a modern coworking hub or a cosy café.  For remote workers, Cairo delivers an unforgettable balance of old and new.  If you’re planning to work from Egypt**,** a Grey multi-currency account simplifies your international payments. You can manage multiple currencies seamlessly while you explore the wonders of Cairo.

Get started on Grey today for seamless international payments in Egypt.

‍

Cost of living in London vs New York: A full comparison

•

•

2 min read

London and New York. Two cities that define ambition, opportunity, and the art of expensive living. They’re often compared for their energy, culture, and global influence, but there’s one comparison that never gets old: which city is more expensive to live in?

Both have that irresistible, big-city energy: the feeling that something exciting is always happening just one train stop away. Not so exciting, however, are the expenses that would make even a well-paid professional wince at their bank statement. Still, they’re magnets for dreamers, freelancers, and global workers who want to live at the centre of everything.

So, you want the old-world charm of London, with its cobblestones, museums, and rainy-day cafés? Or the nonstop buzz of New York, where everyone always seems to be on the move?

This is a detailed breakdown of the actual living costs in each city. I have everything covered: rent, food, transport, utilities, and even childcare. I even touched on how Grey can help you manage your money.

Grab your calculator, let’s find out which city really costs more to call home.

How much is the typical rent?

Rent is where both cities truly test your patience and financial endurance. No matter how you slice it, housing eats up the biggest portion of anyone’s monthly budget, and both London and New York are notorious for it.

In London, a one-bedroom flat in the city centre, areas like Shoreditch, Southbank, or Notting Hill, costs around $3,100 per month. If you cross the Thames or move a few Tube stops outward to areas like Stratford or Greenwich, and rent dips to around $2,300. While that’s still steep, it’s relatively manageable compared to New York’s rental market.

In New York, a one-bedroom apartment in Manhattan or prime Brooklyn averages around $4,100 monthly, with similar spaces in Queens or the Bronx costing closer to $2,500. That’s a nearly 30% higher average rent than in London for central locations, though the gap narrows in outer boroughs.

Larger homes follow the same trend. A three-bedroom apartment in central London costs roughly $5,100, compared to a staggering $7,800 in Manhattan. It’s this kind of price tag that makes flat sharing so common. Even outside the city centres, the difference remains: an average of $3,700 in London versus $5,100 in New York.

To put it simply, you’ll need to earn about $100,000 a year to rent comfortably in central London, but closer to $130,000 - $150,000 to manage the same standard of living in New York. In both cases, rent alone can take up 40 - 50% of your monthly income if you’re not careful.

__wf_reserved_inherit

Verdict: London is expensive, but New York is on a whole other level. The average renter in NYC spends roughly 20 - 25% more than their London counterpart for the same space.

Also read: Cost of living in London

What if you prefer to buy a condo or apartment?

When it comes to buying a home, both cities make you pay dearly for the privilege of saying “I live here.”

In London, buying property is often less about owning a space and more about investing in history. Yeah, it’s that expensive.

A square metre of city-centre real estate costs around $21,250, making it one of the most expensive property markets in the world. That means a modest 70 m² flat in Central London (think Shoreditch, South Kensington, or Westminster) could cost upwards of $1.48 million before taxes or fees. Step just outside the heart of the city, say, to areas like Stratford, Walthamstow, or Greenwich and the average drops to $11,000 per square metre, bringing that same flat down to about $770,000.

New York, surprisingly, comes in slightly cheaper per square metre, around $15,500 in the city centre. A 70 m² apartment in Manhattan would cost approximately $1.08 million. However, buyers there face higher ongoing costs, including property taxes averaging 1.7% per year, as well as maintenance fees that can add several thousand dollars per month in co-op or condo buildings. Outside central boroughs like Brooklyn, Queens, or the Bronx, property prices average $11,100 per square metre, roughly $777,000 for the same 70 m² flat, which is nearly identical to London’s suburban equivalents.

But price per square metre doesn’t tell the whole story. In London, you’ll often find smaller, older properties that come with preservation restrictions, while New York’s market leans toward high-rise living with modern amenities but sky-high building costs.

If you’re buying as an investor, rental yields are another factor: London averages 3 - 4% annually, compared to 4 - 5% in New York.

__wf_reserved_inherit

Verdict: London wins for long-term prestige and property value stability, but New York offers more substantial returns and newer builds for your money. Either way, in both cities, you’ll need to plan well for a purchase.

Also read: Cost of living in Paris

Restaurants

If rent is where London and New York empty your wallet, food is where they tempt you to open it again. Both cities are global dining capitals, home to celebrity chefs, street food icons, and everything in between. Regardless of your preference, whether grabbing a quick bite or splurging on fine dining, the numbers tell a fascinating story about how much it really costs to eat well in each city.

In London, an inexpensive meal at a local café or casual restaurant costs around $27, while in New York, that same plate would be roughly $25. It’s a negligible difference, well, until you start dining out regularly. A three-course dinner for two in a mid-range restaurant costs approximately $106 in London, compared to $150 in New York. That’s almost a 40% jump, showing how New York’s dining scene rewards indulgence but punishes your credit card.

For the average person eating out three to four times a week, that difference soon becomes a problem. You could spend $450 - $600 monthly on casual meals in London or nearly $700 - $900 in New York, and that’s before drinks or tips.

Fast food and casual chains paint a slightly different picture. A McDonald’s combo meal costs $11 in London and $14 in New York, making the UK marginally friendlier to quick, low-cost dining. Drinks, however, are where the playing field levels out. A domestic beer costs around $9 in London and $8 in New York, while an imported beer might flip the comparison, $8 in London versus $10 in New York.

And if you’re one of those people who can’t start the day without caffeine (no judgement here), you’ll pay $5.50 for a cappuccino in London and around $6 in New York. Over a month of daily café runs, that’s about $165 vs. $180, proof that even your coffee habit costs more in Manhattan.

__wf_reserved_inherit

Verdict: London wins if you’re eating on a budget, or prefer home-cooked meals and pub lunches over fine dining. But New York outshines for culinary variety: you’ll find everything from $3 pizza slices to $300 tasting menus, often on the same block.

Markets

When it comes to everyday shopping, you’ll find plenty of options in either city, and how far your grocery budget stretches depends on what you buy and where you buy it.

In London, chain supermarkets like Tesco, Sainsbury’s, and Aldi offer solid value, while Waitrose or Marks & Spencer cater to those who don’t mind paying a premium for imported or organic goods. A typical grocery basket, which will include milk, bread, rice, eggs, and fresh fruit, comes to around $40 - $50 weekly for one person, or roughly $200 a month if you mostly cook at home. Prices stay fairly stable, though imported foods (like cheese or wine) push the total higher.

A litre of milk costs $1.70, and a loaf of bread averages $2, which is affordable by big-city standards. But a dozen eggs go for about $4.70, and chicken fillets hover around $9 per kilo. Meat and dairy tend to be where your grocery bill spikes. On the brighter side, locally grown produce like apples ($3.50/kg) or bananas ($1.70/kg) remains budget-friendly, especially at weekend markets or local greengrocers.

New York, however, turns grocery shopping into an Olympic event, one that your wallet rarely wins. Supermarkets like Whole Foods, Trader Joe’s, and Key Food charge noticeably more, with prices varying wildly by borough. Expect to spend around $350 - $450 per month if you cook regularly, and easily more if you shop organic or prefer imported brands.

Basic items tell the story well: a loaf of bread is $4.90 (more than double London’s), and eggs cost $7.20 per dozen. Even staples like rice ($8.20/kg) and milk ($1.60/L) come with a New York markup. Meat and produce are consistently higher too, as chicken fillets average $16/kg, and apples hit $7.50/kg, nearly twice London’s cost.

The gap widens further when you factor in alcohol and tobacco. A bottle of wine costs $11.50 in London but $18 in New York. Cigarettes? $4.50 in London versus a staggering $19 in NYC, making it one of the most expensive places in the world for smokers.

__wf_reserved_inherit

Verdict: London gives you more value for money, especially if you cook often.

Transportation

Let’s be honest, both cities have world-famous public transport systems. London’s red double-decker buses and the New York subway come to mind almost immediately.

In London, getting around isn’t cheap, but it’s incredibly well-connected. A one-way Tube or bus ticket costs around $4.20, and a monthly travel pass averages $240, still one of the most expensive in the world. Daily commuters can save money using Oyster cards or contactless payments, which cap your daily fare at around $10 - $15, depending on the zones.

Taxi rides are another story. A standard black cab starts at $5.50, but the fare rises quickly during rush hour or late at night. Ride-hailing services like Uber tend to be slightly cheaper, though not by much. Fuel costs around $1.80 per litre, making car ownership in London more of a luxury than a necessity. Due to the congestion charges, parking fees, and insurance, most people stick to public transport or cycling.

Over in New York, transportation is slightly more affordable, at least on paper. A single subway or bus fare costs $3, and a monthly MetroCard is $133, nearly half of London’s cost. For daily riders, that’s a massive saving. Taxis start around $5, and while surge pricing can spike fares in Manhattan traffic, ride-sharing apps like Lyft and Uber are everywhere. Fuel is far cheaper, averaging $0.90 per litre, making car ownership less punishing for those outside the boroughs.

__wf_reserved_inherit

Verdict: New York wins for affordability, hands down. But London’s system is better integrated. If you value comfort and connectivity, you’ll tolerate London’s higher costs. But if saving money matters more, New York’s MetroCard is still the golden ticket, even if it sometimes comes with the scent of pizza and street jazz.

Also read: Cost of living in Mumbai

Utilities

Utilities might not be the most exciting topic, but they’re what truly determine whether your apartment feels like home or just an expensive box with windows.

In London, basic utilities for an 85 m² apartment — electricity, heating, cooling, water, and garbage — come to around $330 per month. Prices fluctuate depending on the season; winter heating bills can push the cost closer to $400, while the summer months offer some relief. What’s great, though, is that energy-efficient buildings are becoming more common, especially in newer developments outside central London.

The internet is reasonably priced by global standards. A high-speed plan (60 Mbps or more) averages $42, and most providers offer reliable service. Mobile plans are also competitive, with rates starting at around $19 per month for calls, texts, and 10 GB or more of data. That’s significantly cheaper than in the U.S., and it’s one of the few areas where London actually saves you money.

Meanwhile, in New York, utilities can be a mixed bag. The average cost for the same 85 m² apartment is around $200 per month, but don’t let that fool you; many older buildings in New York have outdated systems, meaning you’ll likely need to budget extra for heating or air conditioning, especially during extreme weather. Some apartments include water and heat in the rent, but electricity can still add up fast.

Where New York really pulls ahead (or falls behind, depending on how you see it) is in connectivity. Internet costs about $66.60 per month, and while speeds are great, it’s nearly 60% more expensive than in London. Mobile plans are also higher, averaging $62 monthly, roughly three times London’s rate.

__wf_reserved_inherit

Verdict:. In London, you’ll pay less for mobile and internet services and enjoy reliable utilities across the board. New York’s older infrastructure and higher data costs make it the slightly more expensive option, especially for remote workers or freelancers who depend on stable, high-speed connections.

LDMAG1

Sports and leisure

The one thing Londoners and New Yorkers take seriously, besides their morning coffee, is staying active and entertained. However, depending on where you live, the cost of staying fit (or just having fun) can vary significantly.

In London, Gym memberships average $64 a month, and you’ll find everything from sleek chains like PureGym and Virgin Active to boutique studios with yoga, spin, or boxing. Public sports centres are affordable too; some charge as little as $8 per session for swimming or fitness classes. If you’re into tennis, court rentals on weekends cost around $25 an hour, and for the less sporty, catching a movie at your local cinema is about $20.

What’s great about London is that so many of the fun activities are free; long runs through Hyde Park, weekend cycling along the Thames, or joining a neighbourhood football group — everyone loves Sunday League. Outdoor activities thrive in London, especially in the summer when the weather finally cooperates.

New York, on the other hand, turns fitness into a high-end affair. A basic gym pass can cost $130 per month, with premium clubs like Equinox charging up to $250 for memberships that include saunas, classes, and towel service (because, of course, it’s New York). Tennis court rentals are pricier too, averaging $59 per hour, and even outdoor recreation in Central Park isn’t entirely free if you want to join an organised sport or use maintained courts.

Entertainment prices are roughly comparable to those in London. A cinema ticket is $20, but New York’s nightlife, concerts, and Broadway shows can make that number skyrocket quickly. A night out with drinks, dinner, and a show can easily top $250, especially in Manhattan.

__wf_reserved_inherit

Verdict: London offers better value and more free fitness options, while New York delivers more variety and experience, if you’re willing to pay the price.

Childcare

If you plan on raising kids in either London or New York, brace yourself, childcare is one of the biggest expenses you’ll face, no matter which side of the Atlantic you’re on.

In London, a full-day private preschool costs around $2,550 per month, depending on the borough and curriculum. Central neighbourhoods, such as Kensington or Islington, tend to be pricier, while outer zones, like Croydon or Walthamstow, have slightly lower fees. London offers a diverse range of childcare options, including local nurseries, Montessori schools, and nanny shares. The UK government also provides subsidies for working parents, with 15 to 30 hours of free childcare available for eligible children aged three to four.

Although primary education is free for state-funded schools, tuition in private schools averages $27,400 per year. However, top-tier institutions such as the American School in London or Southbank International can exceed $35,000 annually. Still, the structure and global curriculum often justify the price.

New York, however, raises the stakes and the fees. Preschool in the city costs approximately $2,230 per month, which may sound slightly lower than in London, but the difference quickly fades once you factor in registration fees, supplies, and additional care hours. For many working parents, hiring a nanny becomes the norm, with costs ranging from $3,000 to $4,500 per month, depending on the hours and experience required.

Private education is where the gap truly widens. An international or private primary school in New York costs a staggering $58,300 per year on average, making it one of the most expensive cities in the world for schooling. Even mid-tier private schools range between $35,000 and $45,000 annually — roughly equivalent to a small mortgage.

__wf_reserved_inherit

Conclusion

Choosing between London and New York is a personal decision. You’ll need to consider the trade-offs you’re willing to live with: rent versus salary, dining versus groceries, public transport versus car costs, and the necessary but often overlooked realities of paying for childcare and schooling.

If you earn abroad or have income in foreign currencies, those trade-offs start to look a little different. Suddenly, a higher salary in New York might cover steeper rents and school fees; a London paycheck might stretch further on everyday items or childcare. The smart move is to think of your finances as a system: how you get paid, how you hold money, and how you convert it all matter as much as the numbers on a job offer.

The right platforms make a real difference. Holding the right currency, timing conversions, and avoiding hidden fees can save you hundreds, even thousands, of dollars a year. For remote workers, freelancers, and families juggling international income and local costs, a multi-currency account with transparent rates and fast payouts is no longer a nice-to-have but a necessity.

That problem exactly is what Grey solves. It doesn’t matter if you’re paid in dollars, pounds or euros, you can receive funds on Grey, hold them in the currency that works best for you, and convert or withdraw at competitive rates, quickly and transparently. That means less guesswork when you’re planning rent, school fees or monthly bills in either city, and more control over how much of your hard-earned money actually reaches you.

Open a free Grey account or download the app to keep more of your income and, by extension, spend it on the things that truly matter.

Disclaimer: This article is based on researched data and is intended to give you a general overview of the cost of living in London and New York. The figures provided are estimates gathered at the time of writing and may vary depending on location, lifestyle, and market changes.

‍

Cost of living in London

•

•

2 min read

I must have been about five or six years old the first time I heard about London. It was from the “London Bridge is falling down” rhyme, which every child my age seemed to know by heart. Unfortunately, I can’t say the same for myself anymore. I barely remember the full lyrics now.

Imagine my surprise when, years later, I learned that the actual London Bridge had never fallen; instead, it required many repairs over the years.

These days, I associate London less with collapsing bridges and more with people falling head over heels for the chance to visit or stay.

It’s one of the most cosmopolitan cities in the world, and you’ll find communities of nearly every nationality there. Rumour has it that even Martians have settled there. Don’t quote me, please. I’m just a writer who happens to believe in aliens.

Now, if you still want to move to London despite the presence of the imaginary Martian community I’ve created, I’m sure you’ll be wondering what living there is like and, more importantly, what it costs.

Here’s a breakdown of all the expenses you’ll encounter. We’ll cover rent, transportation, food, utilities, and other essential expenses that people often overlook. And of course, everything will be in British, not Martian pounds.

Also read: How Grey differs from a UK bank

Is London more expensive than other big cities?

Short answer, yes.

It consistently ranks among Europe’s most expensive cities, often compared to Paris, and New York when it comes to housing, dining, and transport costs. Rent alone can take up anywhere from 40-60% of your monthly income, depending on where you live and how you manage expenses.

For a single person, excluding rent, you’re looking at around £1,000 - £1,200, while a family of four might spend £3,500 - £4,000. London’s appeal is undeniable, but you’ll need to budget carefully to enjoy it without breaking the bank.

How much is the typical rent in London?

London’s housing market is huge, and rent prices vary dramatically depending on which zone you live in. The city is divided into six main zones, with Zone 1 being the heart of London. It’s home to landmarks like Westminster, Soho, and Kensington, and Zone 6 covers the farthest suburban areas.

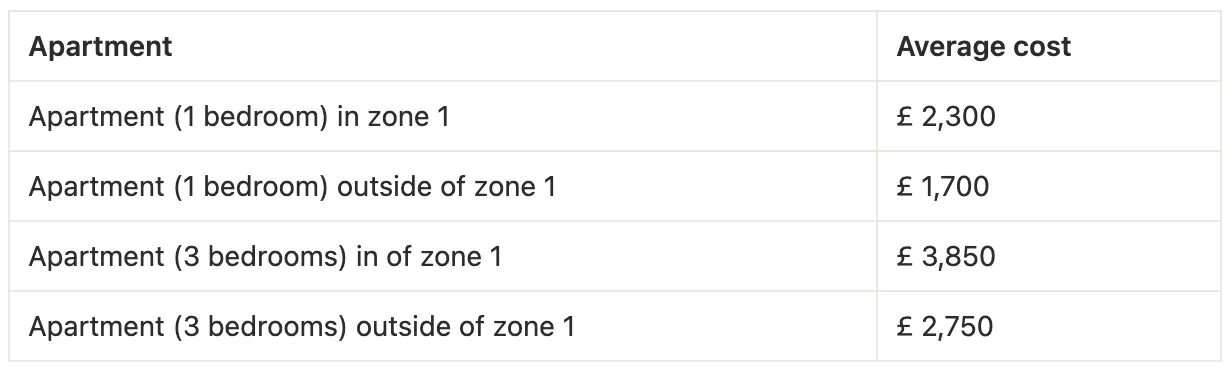
The closer you are to Zone 1, the more you’ll pay for the convenience of being near offices, restaurants, and nightlife. A one-bedroom apartment in Zone 1 can cost around £2,300 - £2,700 per month, while neighbourhoods in Zone 2, such as Stratford or Greenwich, average £1,700 -£2,000. When you move farther out to Zones 4 - 6, in places like Croydon, Ilford, or Hounslow, you can find similar flats for £1,200 - £1,500, though your daily commute will take longer.

Most Londoners balance affordability and access by living between Zones 2 and 4, where you’ll still have reliable Tube connections without the central London price tag. Sharing accommodation or renting a room in a flatshare remains one of the most practical ways to save.

__wf_reserved_inherit

What if you prefer to buy an apartment in London?

Buying a home in London isn’t for the faint of heart or the light of wallet. The city consistently ranks among the most expensive property markets in the world, with prices varying sharply across transport zones and property types.

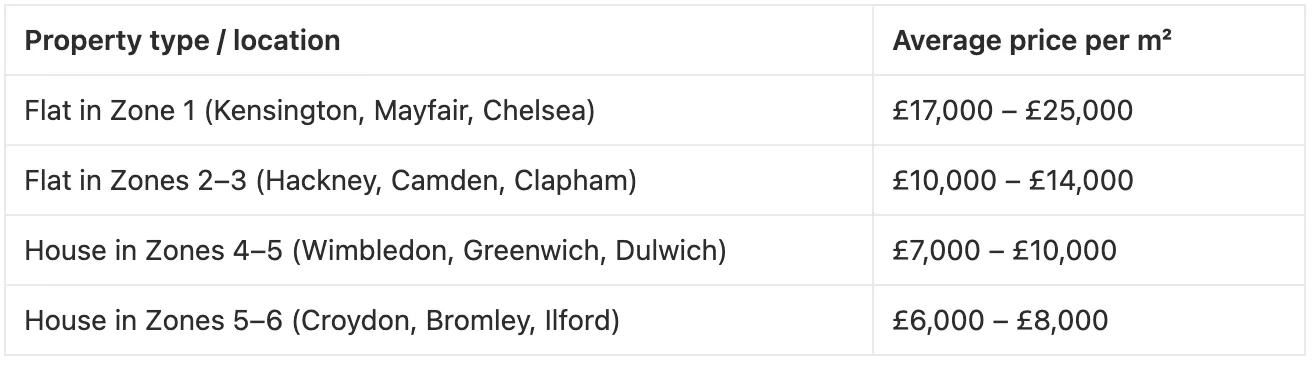
Most London homes fall into two main categories: flats (apartments), which dominate Zones 1-3, and houses, which are more common in outer Zones 4 - 6. If you’re eyeing a flat in central areas like Chelsea, Kensington, or Mayfair, prepare to pay around £17,000 - £20,000 per square metre, with luxury developments reaching as high as £25,000 - £30,000. Even smaller one-bedroom units in these postcodes can easily exceed £1 million.

Moving outward makes a dramatic difference. In Zones 3 - 4 (Wimbledon, Greenwich, or Hackney), average prices fall to £9,000 – £12,000 per square metre, while in Zones 5 - 6 (Croydon, Bromley, or Ilford), you’ll find newer builds or family houses for £6,000 - £8,000 per square metre. However, commuting costs tend to increase, so it’s a trade-off between affordability and convenience.

For most expats, students, and digital nomads, renting remains the more practical option. However, if you’re staying long-term, London offers several first-time buyer schemes, such as Shared Ownership and Help to Buy, which allow for partial ownership or reduced deposits. Mortgages for foreign buyers are also possible, though they often require higher down payments (typically 25–40%) and proof of UK income.

__wf_reserved_inherit

Also read: Cost of living in Manila

Restaurants

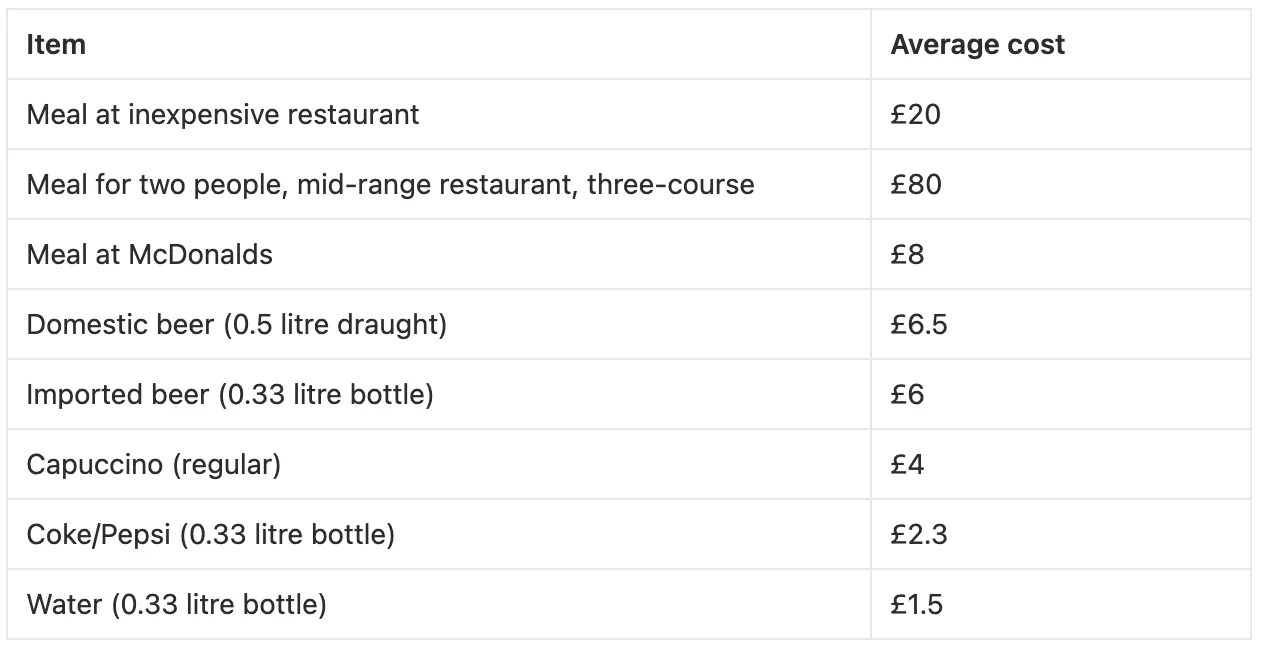
London’s food scene is huge. The city caters to every taste and well, most budgets. Eating out regularly can get expensive. A meal for two at a mid-range restaurant averages £70 - £80, while a casual lunch might set you back £15 - £20.

That said, you can save quite a bit by mixing in home cooking or quick bites. Supermarket meal deals (typically around £4 - £5) are a local favourite for office workers, and markets like Borough, Camden, or Maltby Street offer gourmet options without the fine-dining markup. Coffee lovers should expect to pay around £3.50 - £4.50 for a cappuccino, depending on the café and neighbourhood.

__wf_reserved_inherit

LDMAG1

Markets

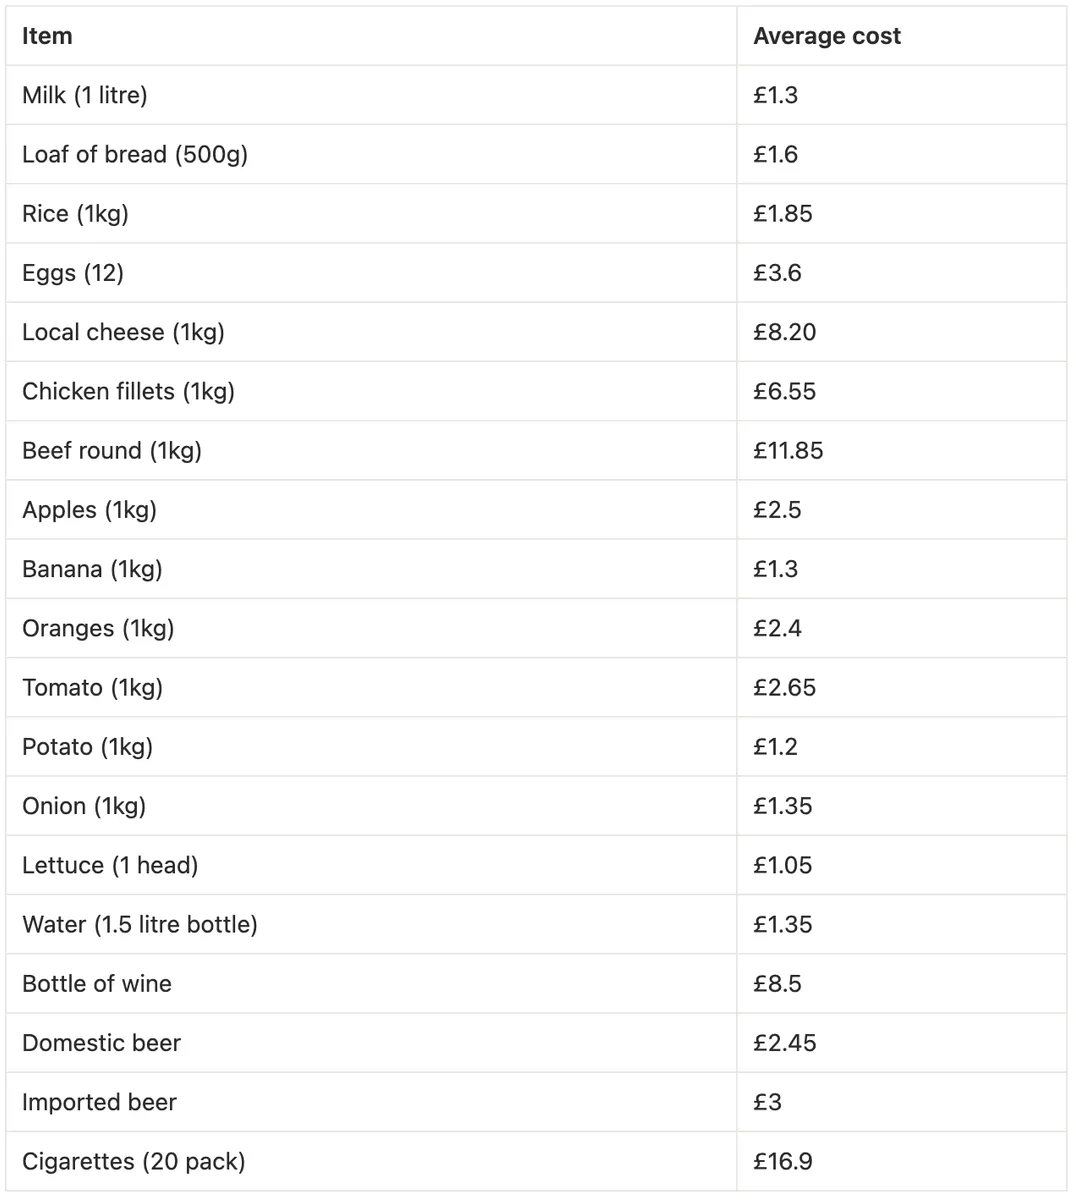
Prices vary depending on where you shop. Premium stores like Waitrose and M&S are more expensive, while Aldi, Lidl, and Asda are generally cheaper. A weekly grocery run for one person typically falls between £40 and £70, depending on dietary preferences and shopping habits.

Buying local produce or opting for supermarket brands can make a noticeable difference. For example, a litre of milk costs about £1.30, a loaf of bread £1.60, and a dozen eggs around £3.50. Meat and dairy products are pricier, while fruits and vegetables remain reasonably priced year-round. Londoners who shop at farmers’ markets may pay a little extra, but the freshness and quality often justify the spend.

__wf_reserved_inherit

Transportation

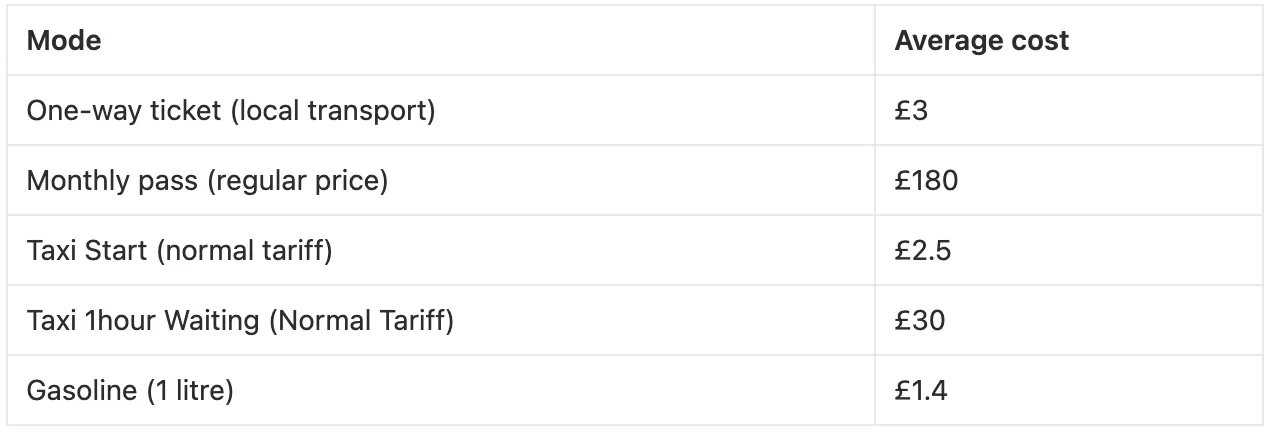
London’s public transport is reliable and well-integrated, but it’s not cheap. The Oyster card and contactless payment system make commuting convenient, though prices depend on your travel zones. A single Tube ride in Zone 1 costs about £2.80 - £3.40, while a monthly pass covering Zones 1 - 3 costs around £180.

Many digital nomads and remote workers skip the commute altogether and rely on walking or cycling, especially in central neighbourhoods. Gasoline prices are around £1.40 per litre, so many people consider owning a car to be impractical unless you live outside the city centre. However, London’s buses make getting around relatively stress-free.

__wf_reserved_inherit

Also read: Cost of living in London vs New York: A full comparison

Utilities

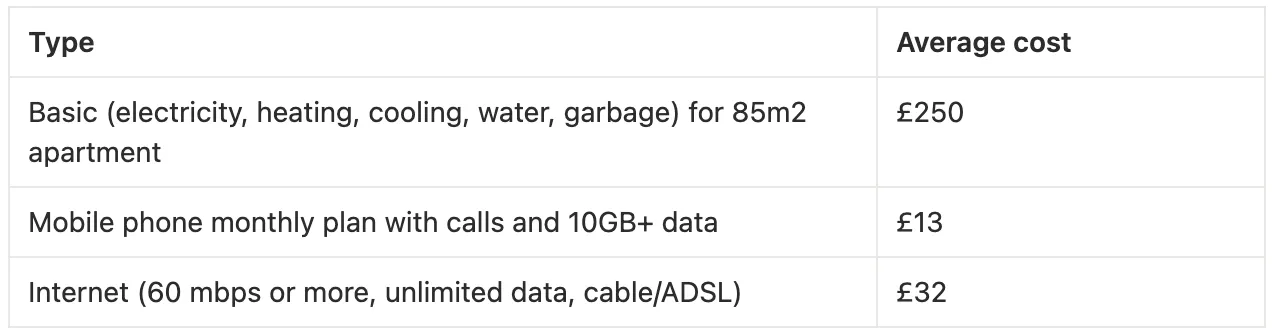
Once you’ve settled in,  Monthly utilities will add roughly £250 - £300 to your expenses. This covers electricity, heating, water, and waste collection for an average 85m² apartment. London’s chilly winters can increase energy bills, especially in older flats with poor insulation.

The internet is fast and reliable, with unlimited broadband plans starting around £30 - £35 per month, while mobile plans average £10 - £15 with generous data bundles. Many digital nomads also rely on public Wi-Fi, which is widely available in cafés and libraries. Overall, utilities remain manageable as long as you’re mindful of seasonal fluctuations.

__wf_reserved_inherit

Also read: Cost of living in Cairo

Sports and leisure

You can never run out of things to do in London. London never runs out of things to do. There are concerts, exhibitions, football matches, cinemas, and a pub around almost every corner. One of my life’s wishes is to watch an actual Chelsea FC match at Stamford Bridge. We’re the pride of London anyway. The Premier League ticket prices vary widely for each club, but the Premier League has capped away game tickets at £30.

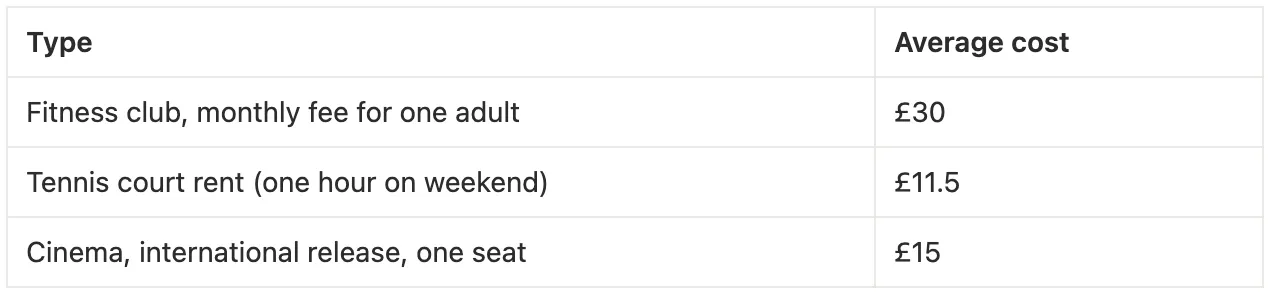
A gym membership typically costs around £30 - £50 per month, although premium studios can charge more. If you prefer something indoors, cinemas are really popular. A movie ticket is about £15. In contrast, a pint at the pub costs around £6 - £7. There are many other enjoyable experiences, including museums, galleries, and public parks, which are open to everyone. Finding a balance between paid activities and free exploration is the key to enjoying London without overspending.

__wf_reserved_inherit

Childcare

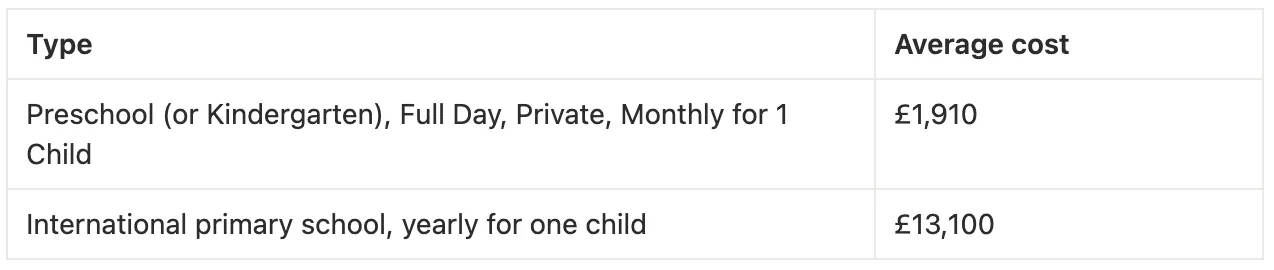
Raising children in London is rewarding but undeniably expensive. Private preschool fees average around £1,900 per month, while international schools can charge upwards of £13,000 per year. Many families explore public school options or relocate to commuter towns for more affordable childcare and housing.

Childcare costs often rival rent in smaller cities, so careful budgeting is key for families relocating to London. Digital nomads with kids may want to research flexible daycare options or community programmes, especially if both parents work remotely. Some even choose to homeschool to cut costs. What matters best is choosing what works for you.

__wf_reserved_inherit

Is living in London worth it?

Yes, if you plan wisely. London rewards ambition, creativity, and curiosity. The city’s career opportunities, cultural diversity, and sheer energy are unmatched. Still, living comfortably here depends on your income and how you manage expenses.

With the right budget strategy, you can enjoy everything London has to offer without being weighed down by the high costs.

Also read: Summer vacation ideas for families in the UK

How can you manage foreign paycheques in London?

Managing money as an international student or freelancer in London can get tricky, especially if you’re earning in a foreign currency. The UK has a well-developed banking system, but fees and exchange rates vary depending on the type of account you open.

Major players like Barclays, Lloyds, HSBC, and NatWest are all solid options for everyday banking. You can open student and international accounts that come with debit cards, online banking, and access to thousands of ATMs across the UK. HSBC is particularly popular with international students due to its global presence, while Monzo and Revolut stand out for their digital-first experiences, budgeting tools, and low domestic transfer fees.

That said, most UK banks charge high conversion and international transfer fees, sometimes between 2% and 5%, when you’re receiving money from abroad. Processing times can also stretch to several days, depending on your sender’s bank or currency region. This makes traditional banking less efficient for freelancers or students who get paid in foreign currency.

If you’re paid in foreign currencies, you’ll want something more flexible. A multicurrency account is perfect for this. It allows you to receive, hold, and convert various currencies at competitive rates, without the hidden costs that banks typically add.

Personally, I’d recommend Grey. It’s a reliable option built specifically for people who live and earn globally. You can open a free multicurrency account in minutes, receive payments in USD, GBP, or EUR, and convert seamlessly to pounds when rates work best for you.

With Grey, you get more control over your money, spend less on conversion, and save time managing multiple accounts. It’s a small switch that makes a big difference when living and earning abroad. Open a free Grey account or download the app and take the stress out of getting paid in London.

Disclaimer: This article is based on researched data and is intended to give readers a general overview of the cost of living in London. The figures provided are estimates gathered at the time of writing and may vary depending on location, lifestyle, and market changes.

‍

Cost of living in London for international students

•

•

2 min read

There are only a handful of moments quite as exciting as a confirmation mail from the university you applied to.

It’s that single moment when months of applications, essays, and anxious email refreshing finally pay off. It’s even more surreal when the university is in London, one of the world’s most popular and cosmopolitan cities.

However, once the excitement subsides, the important question of how much it will cost to live in London inevitably arises.

That’s why I’ve put together this guide. It’s a complete breakdown of what it really costs to live as an international student in London. We’ll cover everything from accommodation to entertainment, and I’ll show you how Grey helps you to make your pounds stretch further (especially if you’re receiving money from home).

So, let’s unpack the numbers, shall we?

Accommodation

Rent is almost always the biggest part of a student’s budget. It varies depending on where you live. Central areas like Bloomsbury, Shoreditch, and South Kensington are pricier because they’re near top universities (UCL, LSE, Imperial). If you’re okay with a longer commute, you’ll find cheaper options in areas like Stratford, Lewisham, or Wembley.

Cost of living in London for international students

Many students save by sharing flats. Websites like SpareRoom or UniAcco help you find affordable, student-friendly housing. Remember that bills (electricity, Wi-Fi, water) often aren’t included in private rentals, so you’ll need to add another £150 - £250 monthly.

LDMAG1

Food and groceries

How much you spend on groceries depends entirely on your lifestyle. Cooking at home can save a lot, especially if you shop smart. Supermarkets like Aldi, Lidl, Tesco, and Asda are student favourites, while M&S and Waitrose are pricier but great for the occasional treat.

Cost of living in London for international students

If you cook most of your meals, you’ll likely spend around £150 - £250 per month on groceries. Eating out regularly or relying on takeaways can double that. You can also get student discounts in nearby restaurants and cafes. Also, meal prepping on weekends helps cut weekday costs and saves you from impulsive buying.

Also read: Cost of living in Alexandria

Transportation

Public transport in London is excellent but pricey, so plan ahead as much as you can. Most students rely on the Tube, buses, and trains, with discounted Oyster cards or Student Travelcards to keep costs down. I recommend using Trainpal or Trainline to book trains ahead, especially when you’ll be travelling outside London.

Cost of living in London for international students

If your classes are close to home, cycling can save a ton. Santander Cycles (Boris Bikes) cost just £20/month for unlimited 60-minute rides. Walking is also underrated in central London; you’ll be surprised how much you can explore on foot. It’s important to note that mobile maps, such as Google or Apple Maps, are helpful. The London commute can be very confusing, so it’s a great way to stay informed about your location. Ensure your device is charged, type in the address, and you’re all set.

Utilities and internet

If you live in university housing, utilities are usually included. However, if you’re renting privately, you may need to pay separately for essentials such as electricity, gas, and Wi-Fi. You can also find private accommodation with all bills included, but these are usually in the form of flatshares.

Cost of living in London for international students

Students are exempt from paying Council Tax if they’re enrolled full-time, so make sure to get a letter from your university confirming your status.

Study materials and personal expenses

Books, printing, and supplies might not seem like much, but the costs can quickly add up. Most universities have libraries stocked with required textbooks; however, some courses may require specific editions or software (you can use the Grey virtual card for this).

Cost of living in London for international students

Most students also budget for occasional entertainment, streaming services, and social activities. It’s London. You’ll want to see a play, visit museums, or just enjoy a pint with friends now and then.

Also read: Cost of living in London vs New York: A full comparison

Entertainment and leisure

London is full of free and low-cost experiences. Museums like the Tate Modern, British Museum, and V&A are all free, and many theatres have discounted student tickets. Still, it’s nice to have a small leisure budget. A modest £150 - £250 per month for entertainment covers the occasional night out, gym membership, or city exploration.

Cost of living in London for international students

Total estimated monthly cost of living for international students

‍

Cost of living in London for international students

Total estimated monthly cost: £1,500 - £2,500

Your exact budget depends on where you live and how you spend, but a realistic figure for most international students in London falls between £18,000 and £25,000 per year.

Also read: Cost of living in London

Managing money in London with Grey

While studying your course in school, you’ll also need to learn how to manage your money outside of it. Many international students face the challenge of finding a reliable way to receive funds from outside the country or send some money back home occasionally.

Grey completely solves that. With a multicurrency account, you can receive money from home in USD, GBP, or EUR, convert at competitive rates, and spend directly in pounds, all without worrying about hidden fees or bad exchange rates.

So, if your parents send you funds monthly or even if you freelance part-time, Grey helps you manage your finances like a local.

Open a Grey account today or download the app and take one more thing off your student to-do list.

‍

Disclaimer: This article is based on researched data and is intended to give you a general overview of the cost of living in London. The figures provided are estimates gathered at the time of writing and may vary depending on location, lifestyle, and market changes.

‍

Arrow (up)

Back to top