<script type="application/ld+json"> [ { "@context": "https://schema.org", "@type": "BlogPosting", "@id": "https://grey.co/blog/liberalised-remittance-scheme#article", "headline": "Liberalised Remittance Scheme (LRS): Complete RBI Guide | Grey", "description": "The Liberalised Remittance Scheme lets Indian residents send up to USD 250,000 abroad per year. How LRS works, what it covers, and the tax rules. Read now.", "inLanguage": "en", "url": "https://grey.co/blog/liberalised-remittance-scheme", "mainEntityOfPage": "https://grey.co/blog/liberalised-remittance-scheme", "datePublished": "2026-09-18T20:35:32.419Z", "dateModified": "2026-09-18T20:37:22.836Z", "author": { "@type": "Person", "name": "Priscila Marotti" }, "publisher": { "@type": "Organization", "@id": "https://grey.co/#organization", "name": "Grey", "url": "https://grey.co" }, "image": "https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6aada07f2a9e700a8cdc00c8_Liberalised%20Remittance%20Scheme-compressed.jpg" }, { "@context": "https://schema.org", "@type": "BreadcrumbList", "@id": "https://grey.co/blog/liberalised-remittance-scheme#breadcrumb", "itemListElement": [ { "@type": "ListItem", "position": 1, "name": "Home", "item": "https://grey.co/" }, { "@type": "ListItem", "position": 2, "name": "Blog", "item": "https://grey.co/blog" }, { "@type": "ListItem", "position": 3, "name": "Liberalised Remittance Scheme (LRS): Complete guide", "item": "https://grey.co/blog/liberalised-remittance-scheme" } ] }, { "@context": "https://schema.org", "@type": "FAQPage", "@id": "https://grey.co/blog/liberalised-remittance-scheme#faq", "mainEntity": [ { "@type": "Question", "name": "What is the LRS limit for 2026?", "acceptedAnswer": { "@type": "Answer", "text": "The LRS limit is USD 250,000 per individual per financial year (April 2025 to March 2026). This is aggregate across all purposes and all remittances. Verify the current limit from the latest RBI circular, as the limit can change with policy updates." } }, { "@type": "Question", "name": "Is TCS refundable under LRS?", "acceptedAnswer": { "@type": "Answer", "text": "Yes. TCS collected on your LRS remittances is a credit against your income tax liability. When you file your income tax return (ITR), the TCS amount is deducted from your total tax payable. If the TCS exceeds your tax liability, the excess is refunded to you. It's a prepayment of tax, not an additional tax." } }, { "@type": "Question", "name": "Can I use LRS to invest in US stocks?", "acceptedAnswer": { "@type": "Answer", "text": "Yes. Investment in foreign securities, including US stocks, bonds, and mutual funds, is a permitted purpose under LRS. You can invest up to USD 250,000 per financial year through this route. The 20% TCS rate applies to investment remittances above the threshold. Many Indian investors use LRS to invest via platforms such as Vested and INDmoney, or directly through international brokerages." } }, { "@type": "Question", "name": "Does LRS apply to NRIs?", "acceptedAnswer": { "@type": "Answer", "text": "No. LRS applies only to resident individuals in India. NRIs have different foreign exchange provisions under the Foreign Exchange Management Act (FEMA). If you're an NRI, your ability to remit funds from India depends on the type of account you hold (NRE, NRO) and the specific FEMA rules for non-residents." } }, { "@type": "Question", "name": "What is Form A2 under LRS?", "acceptedAnswer": { "@type": "Answer", "text": "Form A2 is the RBI-mandated application form for outward remittance under LRS. It captures the remitter's details, PAN number, purpose of remittance, beneficiary information, and the amount. You fill it out at your bank (authorised dealer) when initiating an LRS remittance. Most large banks also offer digital Form A2 submission through their online banking or app." } }, { "@type": "Question", "name": "Can a minor remit under LRS?", "acceptedAnswer": { "@type": "Answer", "text": "Yes. A minor can remit under LRS through their natural guardian or court-appointed guardian. The remittance uses the minor's own LRS limit (USD 250,000 per financial year), not the guardian's. The guardian signs the Form A2 on behalf of the minor and provides the minor's PAN card or the guardian's PAN if the minor doesn't have one." } } ] }, { "@context": "https://schema.org", "@type": "DefinedTermSet", "@id": "https://grey.co/blog/liberalised-remittance-scheme#terms", "name": "Liberalised Remittance Scheme (LRS): Complete guide glossary", "hasDefinedTerm": [ { "@type": "DefinedTerm", "name": "Liberalised Remittance Scheme (LRS)", "description": "The liberalised remittance scheme is an RBI policy that allows resident individuals in India to remit foreign exchange abroad for any permitted purpose, up to a specified annual limit.", "inDefinedTermSet": { "@id": "https://grey.co/blog/liberalised-remittance-scheme#terms" } }, { "@type": "DefinedTerm", "name": "Tax Collected at Source (TCS)", "description": "TCS under LRS isn't a separate tax. It's an advanced tax collection mechanism. Your bank collects TCS when you remit, and you claim it as a credit against your income tax liability when you file your return.", "inDefinedTermSet": { "@id": "https://grey.co/blog/liberalised-remittance-scheme#terms" } } ] } ] </script>

Liberalised Remittance Scheme (LRS): Complete guide

Priscila Marotti

TABLE OF CONTENT

SHARE THIS POST

The name "Liberalised Remittance Scheme" sounds like a restriction. It's actually the opposite. Before LRS existed, Indian residents needed RBI approval for nearly every foreign exchange transaction. The LRS scheme India introduced in 2004 removed that bottleneck and gave individual residents the right to send up to USD 250,000 abroad each year without asking anyone's permission.

The Liberalised Remittance Scheme (LRS) allows Indian residents to remit up to USD 250,000 per financial year abroad for permitted purposes, including education, travel, investment, and maintenance of close relatives. All remittances under LRS require a PAN card. Tax Collected at Source (TCS) applies to remittances above specified thresholds. Verify current thresholds with your bank or a tax adviser.

If you're an Indian resident sending money abroad for any reason, LRS is the framework you're operating within. Here's how it works, what it covers, and what it costs in tax.

What Is the Liberalised Remittance Scheme?

The liberalised remittance scheme is an RBI policy that allows resident individuals in India to remit foreign exchange abroad for any permitted purpose, up to a specified annual limit. The current limit is USD 250,000 per financial year (April to March).

LRS applies to resident individuals only. NRIs (Non-Resident Indians) aren't covered because they already have different foreign exchange provisions under FEMA. Companies and firms can't use LRS either. Minors can remit under LRS through a guardian.

The RBI introduced LRS in February 2004 with an initial limit of USD 25,000. The limit has been revised several times and currently stands at USD 250,000. This covers all permitted remittances in a financial year, aggregated across all transactions and purposes.

What Can You Use LRS For? Permitted Purposes

LRS covers a broad range of personal and investment purposes. The RBI's list of permitted transactions includes:

Private visits abroad (tourism). Gift or donation to a person or institution abroad. Going abroad for employment. Emigration. Maintenance of close relatives abroad. Business travel. Medical treatment abroad. Education abroad. Purchase of immovable property abroad. Investment in foreign securities (stocks, bonds, mutual funds). Opening and maintaining a foreign currency account abroad.

What LRS cannot be used for:

Purchasing lottery tickets or sweepstakes. Margin trading or leveraged forex trading. Remittance to countries or entities identified by the Financial Action Task Force (FATF) as non-cooperative. Remittance to individuals or entities sanctioned by the RBI or OFAC. Capital account remittances to Nepal and Bhutan (covered by separate bilateral agreements). Any transaction explicitly prohibited under FEMA.

The permitted list is broad enough that most personal international financial needs fall within it. If you're paying for a child's university fees in the US, investing in American stocks, or buying property in Dubai, LRS is the legal pathway.

LRS Annual Limit and How It Is Calculated

The LRS limit is USD 250,000 per individual per financial year. The financial year in India runs from 1 April to 31 March. Here's how it works in practice:

The limit is aggregate. If you send USD 100,000 for your child's education in June and USD 50,000 to invest in US stocks in October, you've used USD 150,000 of your USD 250,000 allowance. You have USD 100,000 remaining for the rest of that financial year.

Each family member gets their own limit. A family of four has a combined theoretical allowance of USD 1,000,000 per year. A parent can't transfer their unused allowance to another person, but a minor can remit through a guardian using the minor's own LRS limit.

The limit resets every 1 April. Unused allowance doesn't carry over to the next year. There's no rollover, no accumulation, and no penalty for not using it.

The limit is denominated in USD, but the actual remittance can be in any freely convertible foreign currency: GBP, EUR, AUD, CAD, JPY, and others. The equivalent USD value at the time of remittance is what counts against your limit.

Tax Collected at Source (TCS) Under LRS

This is the section most people search for. TCS under LRS isn't a separate tax. It's an advanced tax collection mechanism. Your bank collects TCS when you remit, and you claim it as a credit against your income tax liability when you file your return. You don't lose this money; you get it back as a tax offset.

Purpose Up to threshold Above threshold
Education (funded by a loan) Nil 0.5% above the threshold
Education (self-funded) Nil 5% above the threshold
Medical treatment Nil 5% above the threshold
All other purposes (travel, investment, property, gifts) Nil 20% above the threshold

The threshold below which TCS doesn't apply is currently set at a specific amount per financial year. Verify the exact threshold with your bank or from the latest Finance Act, as it has changed in recent budgets.

Two things most guides don't explain clearly:

TCS is refundable. If your total TCS collected exceeds your actual income tax liability for the year, the excess is refunded when you file your ITR. It's not a cost; it's a prepayment.

TCS applies per remittance type. Education funded by a loan attracts a much lower TCS rate (0.5%) than investment remittances (20%). If you're remitting for multiple purposes, ensure your bank categorises each remittance correctly under the right purpose code.

Consult a qualified chartered accountant or tax adviser for your specific situation. TCS rates and thresholds change with each Union Budget, and the interaction with your personal tax position depends on your individual circumstances.

How to Remit Under LRS: Process and Documents Required

The remittance process goes through your bank (called an "authorised dealer" in RBI terminology). You can't remit directly; the bank processes the foreign exchange transaction on your behalf.

  1. Visit your bank or use their online banking platform. Not all banks offer LRS remittance online. Larger banks (SBI, HDFC, ICICI, Axis) typically support it digitally. Smaller banks may require a branch visit.
  2. Complete Form A2. This is the RBI-mandated application form for outward remittance. It declares the purpose, amount, beneficiary details, and your PAN number. Your bank provides the form.
  3. Provide your PAN card. PAN is mandatory for all LRS remittances, regardless of amount. No PAN, no remittance.
  4. Submit purpose-specific documents.
  5. Education: an admission letter from the foreign institution plus a fee invoice.
  6. Medical: a recommendation letter from an Indian hospital or doctor.
  7. Investment: No additional document beyond Form A2 for most banks, but some require a declaration of the investment type.
  8. Bank processes the remittance. The bank converts your INR to the foreign currency at their exchange rate, deducts any applicable TCS, and initiates the SWIFT transfer. Funds typically arrive in 1 to 3 business days. For the difference between wire and ACH, see ACH vs wire transfer explained.

LRS and Grey: Using Your Foreign Account

There's a distinction that matters for Indian freelancers and remote workers: LRS governs outward remittance from India. It doesn't apply to foreign income you earn from international clients.

If you're a freelancer in India receiving USD payments from a US client, that income is credited directly to your foreign account. It isn't an LRS transaction because the money never leaves India as a remittance. You can open a Grey foreign account to hold USD, GBP, or EUR from international clients, spend with a virtual card, and convert to INR on your terms.

LRS becomes relevant if you want to send money out of India for investment, education, or other purposes. But receiving foreign income? That's a different regulatory pathway entirely. See Grey for Indian freelancers and how to complete a W-8BEN for US clients for more on the receiving side.

Frequently Asked Questions

What is the LRS limit for 2026?

The LRS limit is USD 250,000 per individual per financial year (April 2025 to March 2026). This is aggregate across all purposes and all remittances. Verify the current limit from the latest RBI circular, as the limit can change with policy updates.

Is TCS refundable under LRS?

Yes. TCS collected on your LRS remittances is a credit against your income tax liability. When you file your income tax return (ITR), the TCS amount is deducted from your total tax payable. If the TCS exceeds your tax liability, the excess is refunded to you. It's a prepayment of tax, not an additional tax.

Can I use LRS to invest in US stocks?

Yes. Investment in foreign securities, including US stocks, bonds, and mutual funds, is a permitted purpose under LRS. You can invest up to USD 250,000 per financial year through this route. The 20% TCS rate applies to investment remittances above the threshold. Many Indian investors use LRS to invest via platforms such as Vested and INDmoney, or directly through international brokerages.

Does LRS apply to NRIs?

No. LRS applies only to resident individuals in India. NRIs have different foreign exchange provisions under the Foreign Exchange Management Act (FEMA). If you're an NRI, your ability to remit funds from India depends on the type of account you hold (NRE, NRO) and the specific FEMA rules for non-residents.

What is Form A2 under LRS?

Form A2 is the RBI-mandated application form for outward remittance under LRS. It captures the remitter's details, PAN number, purpose of remittance, beneficiary information, and the amount. You fill it out at your bank (authorised dealer) when initiating an LRS remittance. Most large banks also offer digital Form A2 submission through their online banking or app.

Can a minor remit under LRS?

Yes. A minor can remit under LRS through their natural guardian or court-appointed guardian. The remittance uses the minor's own LRS limit (USD 250,000 per financial year), not the guardian's. The guardian signs the Form A2 on behalf of the minor and provides the minor's PAN card or the guardian's PAN if the minor doesn't have one.

Open a Grey account to receive your international income in USD, GBP, or EUR, separate from your LRS remittance allowance.

Disclaimer: This article is for informational purposes only and does not constitute tax, legal, or financial advice. LRS limits, TCS rates, and RBI regulations change periodically. All figures cited must be verified against the current RBI master circular on LRS and the latest Finance Act before acting on them. Consult a qualified chartered accountant or tax adviser for your individual situation. Grey is not a bank. Grey is a licensed financial services provider offering multi-currency accounts.

Last updated:

September 23, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to receive payments on Etsy as a seller in Sweden

2 min read

Sweden has a long-standing tradition of craftsmanship, from intricate woodworking to contemporary design. Today, many Swedish artisans are looking for global platforms to showcase and sell their unique creations. Etsy provides the perfect solution — an international marketplace that connects creative entrepreneurs with millions of buyers worldwide. However, receiving payments as a Swedish seller can sometimes be challenging.

This guide will walk you through how to receive Etsy payments seamlessly using Grey, ensuring smooth transactions and better financial management.

Why use Grey for Etsy payments?

Grey simplifies the payment process for Swedish Etsy sellers. Here’s why it’s the best choice:

  • Competitive exchange rates: Maximise your earnings when converting to Swedish kronor (SEK).
  • Secure transactions: Grey’s robust security features ensure your funds are protected.
  • Hassle-free withdrawals: Transfer your earnings to your local bank account with ease.

Also read: How to receive payments on Etsy as a seller in Denmark

How to receive payments on Etsy using Grey in Sweden

Grey provides an easy solution for receiving international payments as a Swedish Etsy seller. Follow these steps to get started:

1. Open your Grey app

Log in to your Grey account or create one to access your international USD bank account.

2. Link your Grey account to Etsy

How to receive payments on Etsy as a seller in Sweden
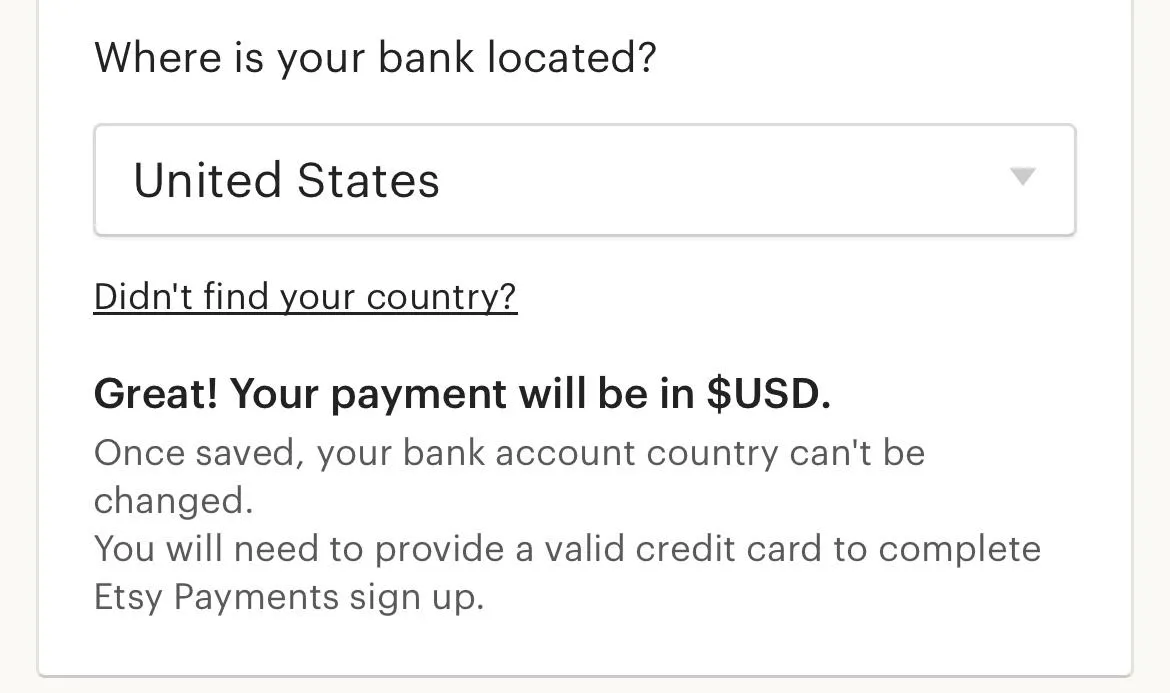
  • Select your bank’s country.
How to receive payments on Etsy as a seller in Sweden
  • Choose whether you’re registering as an individual or a business.
How to receive payments on Etsy as a seller in Sweden
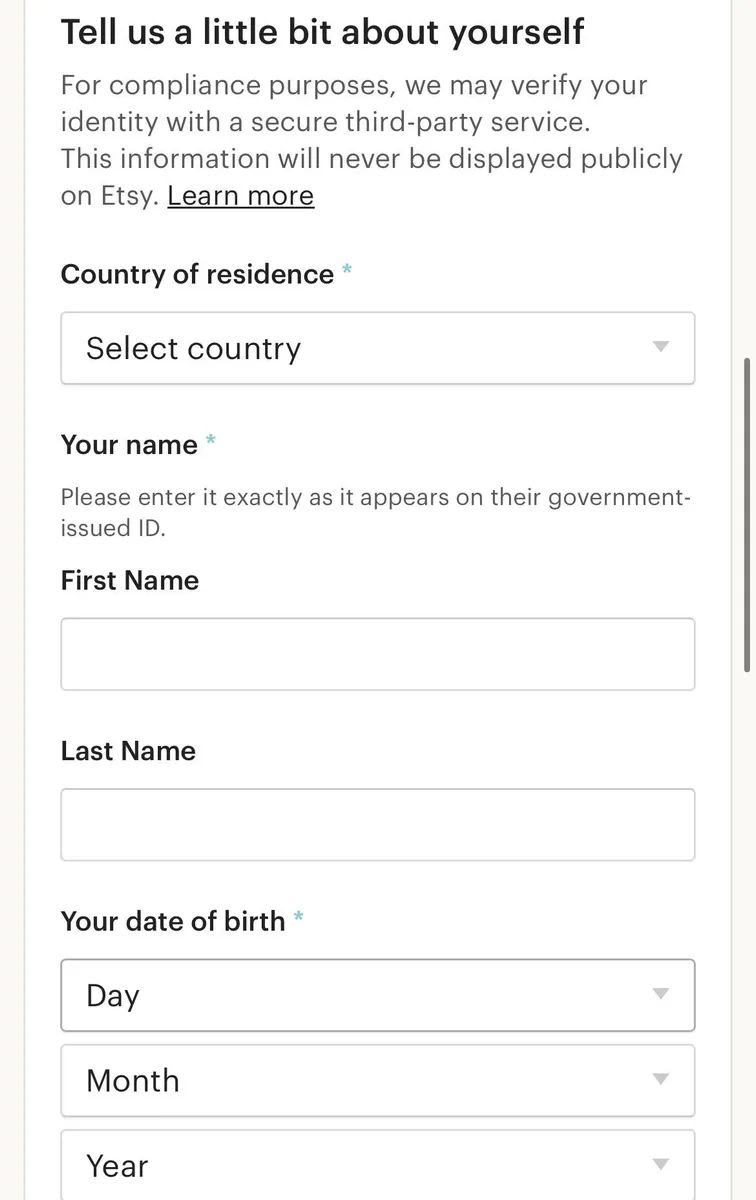
  • Enter your personal information, i.e. name and address.
How to receive payments on Etsy as a seller in Sweden
  • Add your Grey US, EU, or UK bank account details, depending on your preference.
How to receive payments on Etsy as a seller in Sweden
  • Etsy will process payments to your Grey account, making it easy to manage your earnings.

With your Grey account linked, you can receive Etsy payouts directly into your international bank account.It's important to note that you will have to provide a valid ID and depending on the location you pick, may have to fill in a valid address and social security number for your account to be verified.

Also read: How to receive payments on Etsy as a seller in Hungary

Tips for succeeding as a Swedish seller on Etsy

  • Optimise your listings: Use high-quality photos and detailed descriptions to make your products stand out.
  • Offer international shipping: Expand your customer base by providing global shipping options.
  • Respond quickly: Engage with buyers by answering queries promptly and addressing concerns professionally.
  • Leverage social media: Promote your products on apps like Instagram and Pinterest to drive traffic to your Etsy shop.

Also read: How to receive payments on Etsy as a seller in Romania

Simplify Etsy payments with Grey

With Grey, you can stop worrying about receiving Etsy payouts or converting your earnings from Etsy. Manage your finances seamlessly and focus on growing your creative business.

Sign up for a Grey account today and unlock a world of possibilities for your Etsy shop in Sweden.

How to create US and UK bank accounts as a migrant worker in the UK

2 min read

As a migrant worker in the UK, you likely already have a local bank account. But if you work with international clients or send money abroad, you’ve probably had a few challenges — high fees, unfavourable exchange rates, and slow transaction times.

A US bank account can make things easier by allowing you to receive and hold USD without conversion losses. And if you want better financial flexibility, having an additional UK account with a digital bank can help you manage your money more efficiently.

With Grey, you can open US and UK bank accounts easily.

Why do migrant workers in the UK need a US or extra UK bank account?

Even with a UK bank account, opening a US account (or an extra UK account) can be a game-changer. Here’s why:

1. Receiving USD payments without extra fees

If you work for US-based companies or freelance for international clients, you probably receive payments in USD. UK banks often charge high fees for converting USD to GBP. With a US account, you can receive payments directly in dollars without losing money on exchange rates.

2. Holding USD as savings

Slight currency fluctuations can affect your earnings. Holding part of your money in USD instead of GBP gives you more financial stability, especially if you send money abroad regularly.

3. Avoiding expensive international transfers

Sending money across borders? UK banks often have high international transfer fees. With Grey, you can move money seamlessly between your US and UK accounts, saving time and money.

4. Managing finances with an extra UK account

Some workers prefer multiple accounts to separate savings, salary payments, or different income sources. A second UK account can help with budgeting or receiving payments from multiple employers.

Also read: How to manage multiple currencies as an expatriate in Mexico using Grey

Step-by-step guide to opening US and UK bank accounts using Grey

The process is pretty straightforward. Here’s how you can get started:

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

How to create US and UK bank accounts as a migrant worker in the UK
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location.
How to create US and UK bank accounts as a migrant worker in the UK
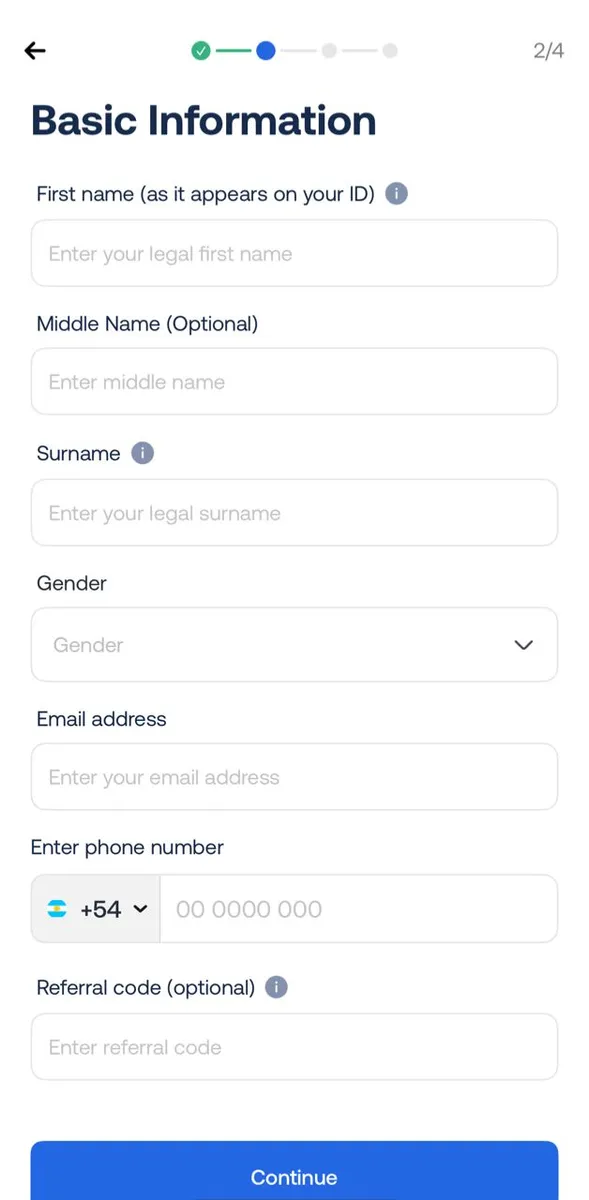
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
How to create US and UK bank accounts as a migrant worker in the UK
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
How to create US and UK bank accounts as a migrant worker in the UK
  • Once you’re set-up, you’re ready for identity verification — a step required for secure access to financial services.

2. Verify your identity for secure access

Grey requires some basic documents to confirm your identity and keep your funds secure:

  • A valid government-issued ID: A passport or national ID card will do.
  • Proof of address – A recent utility bill or bank statement confirming your residence in the UK.

Verification usually takes a few business days, but accurate and clear uploads speed up the process.

3. Access your US and UK bank accounts

Once your identity is verified, you’re all set to create your foreign accounts:

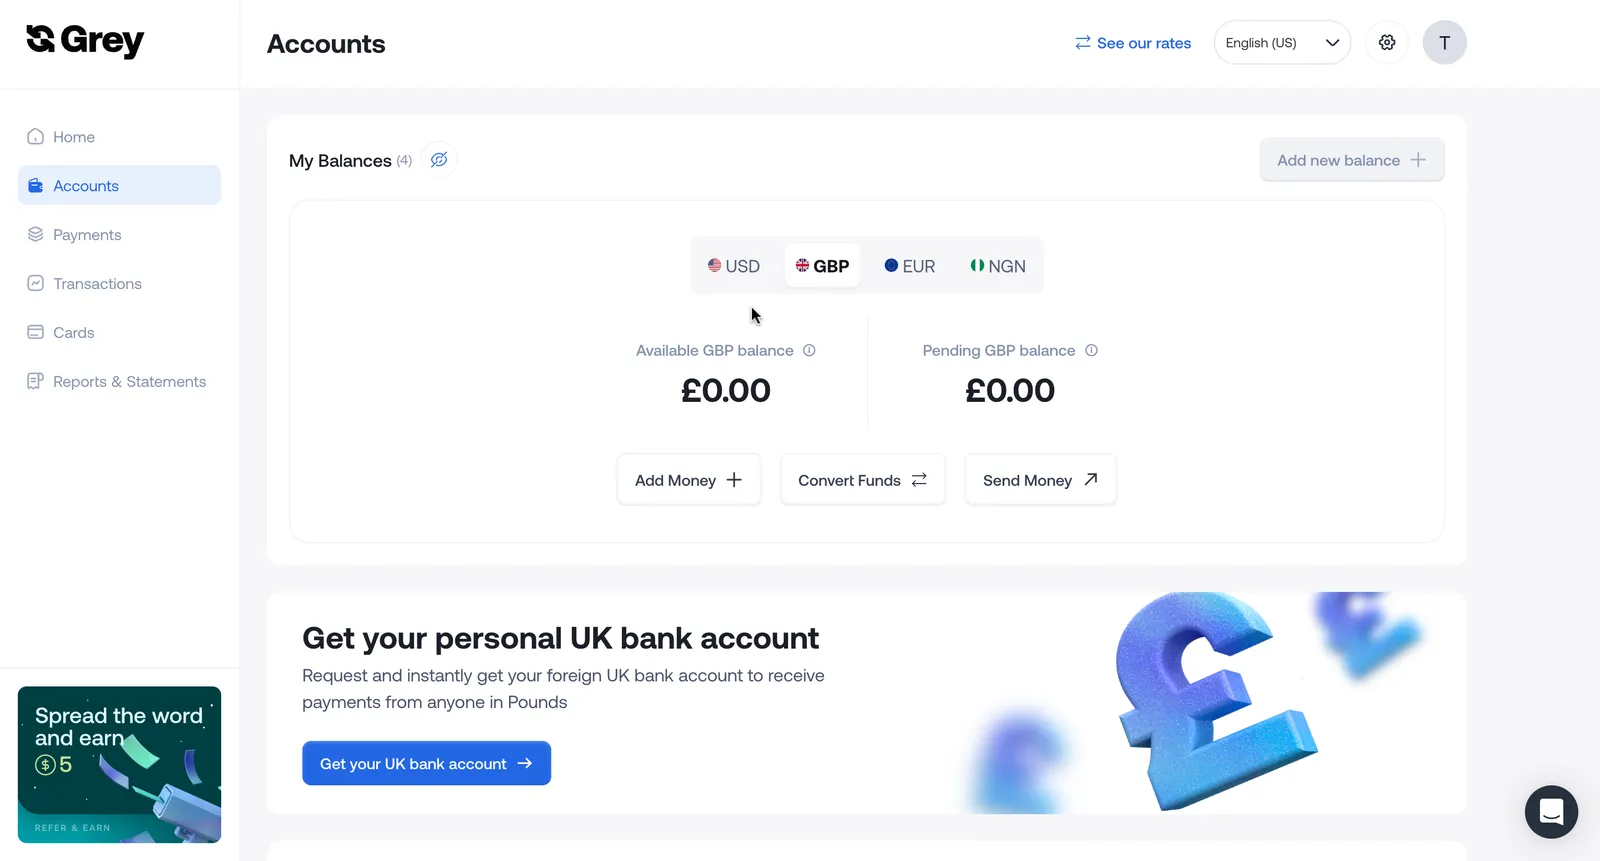
  • Log in to your Grey account.
  • Go to “Accounts” and select “Create Account.”
  • Choose your preferred currency (USD for a US bank account or GBP for a UK account).
  • Get your virtual bank details instantly.

Your US and UK bank accounts are now ready for use.

Also read: How to manage multiple currencies as an expatriate in Brazil using Grey

Benefits of using Grey as a migrant worker in the UK

  • No hidden fees – Transparent pricing means you keep more of your money.
  • Fast transactions – Receive payments and transfer money without long delays.
  • Global access – Use the Grey app to manage your finances from anywhere, anytime.

Tips for managing finances as a migrant worker

  • Budget wisely: Allocate your income across savings, daily expenses, and remittances to your family.
  • Use secure banking options – Enable two-factor authentication (2FA) for extra security.

Simplify banking across borders with Grey

Managing international payments as a migrant worker in the UK doesn’t have to be complicated. With Grey, you can open a US or extra UK bank account, receive payments seamlessly, and move money across borders.Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

How to create US and UK bank accounts as a migrant worker

2 min read

As a migrant worker, managing your finances across borders can be tricky. Whether you receive payments, send money back home, or even pay bills, having a UK or US bank account can help make your financial life much easier.

Thankfully, with Grey, you can do this and more from one app without visiting a physical bank. In this guide, we’ll walk you through how to open a US or UK bank account from the comfort of your home. But first, let’s take a look at why you need an international bank account as a migrant:

Also read: How to create US and UK bank accounts for migrant workers and expatriates

Why should migrant workers open a US or UK bank account?

  • Receive payments: Easily receive payments without delays in USD or GBP, whether you are a freelancer or employed locally.
  • Easier transactions: Make seamless payments for international services, subscriptions, or goods.
  • Better exchange rates: Avoid the hidden fees and poor exchange rates associated with traditional money transfer services.
  • Easily send money internationally: Send money to your loved ones back home through US and UK bank accounts, enjoying lower transaction fees.
  • Save on currency conversions: Avoid losing money to unfavourable exchange rates when dealing with USD or GBP by opening a US and UK bank account.

However, while having US or UK bank accounts offers convenience, opening one is often challenging for migrant workers. Some common issues they usually face include:

  • High fees: Traditional banks often charge expensive fees for receiving and sending foreign payments.
  • Long processing times: Setting up an account can take weeks, especially if you’re not physically present.
  • Minimum balance requirements: Some banks require a minimum deposit to keep the account active.
  • Employment verification: Banks may require documents like a contract or payslips, which can be difficult for new workers to provide.

Also read: Why is international payment so complex for migrant workers?

Why open a US or UK bank account with Grey?

  • Instant access: There are no long waiting or processing times; you can access your US or UK bank account in minutes.
  • No hidden fees: Transparent pricing ensures you keep more of your money.
  • Competitive rates: Maximise your earnings when converting currencies.
  • Fast transactions: Receive and transfer money instantly, without delays.
  • Global accessibility: Manage your finances anytime, anywhere through the Grey app.

How to open US and UK bank accounts with Grey.

Creating international bank accounts with Grey is easy. Here’s how to get started:

1. Sign up for Grey:

  • Visit the Grey website or download the Grey app to create an account.
  • Choose your country: Select your current country of residence; this helps Grey tailor the setup to your location.
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
  • Verify your email: Grey will send a one-time password (OTP) to your email address. To complete this step, simply enter the code on the site.

2. Complete your KYC verification

To get access to your account’s full features, you’ll need to complete your Know Your Customer (KYC) verification. Here’s what you need to do:

  • Upload an image of a government-issued ID, i.e., a driver’s licence, national ID card or international passport.
  • Upload a proof of address, e.g. a recent utility bill or bank statement that can verify your location. Grey uses this document to confirm your residency.
  • Submit your documents for review, typically within a few minutes to 24 hours.

3. Request for a US or UK bank account

Once you’ve been verified, you can easily access your foreign accounts. Here’s how to request for one:

  • Once your identity is verified, log in to your Grey account.
  • Navigate to the “Accounts” section and select “Create Account.”
  • Choose the currency (USD for a US bank account or GBP for a UK account).
__wf_reserved_inherit
  • Your bank account details, including your account and routing numbers, will be generated instantly.

Also read: Why migrants and expatriates in Asia are choosing Grey for international money transfers

Tips for managing finances as a migrant worker

  • Set a budget: Keep track of your expenses to ensure you live within your means. And you can easily do this with Grey’s expense insights feature.
  • Know your tax obligations: Research the tax laws in your host country and home country to ensure you comply with regulations. If you need extra help, reach out to a tax expert.
  • Have an emergency fund: It’s important to always have funds for rainy days in cases of unexpected job loss or expenses.

Also read: Personal finance tips for millennials and gen-z’s: building a solid financial foundation

As a migrant worker in a new country, you often have to deal with many uncertainties, but with Grey, you have one less thing to worry about. You can easily create UK and US bank accounts to manage your finances, sending and receiving global payments seamlessly and hassle-free.

Get started for free today by creating your Grey account.

How to create US and UK bank accounts as a migrant worker in Argentina

2 min read

If you’re a migrant worker earning in foreign currency in any country at all, you’ve probably faced one major challenge —getting paid. Migrant workers in Argentina aren’t any different and are often left scrambling for a solution.

Having a US or UK bank account solves this problem. In this article, you’ll learn how to open a US or UK bank account from Argentina using Grey.

Why should you open a US or UK bank account as a migrant worker in Argentina?

Whether you're a freelancer, remote worker, or an employee of an international company, having a foreign bank account can make a huge difference. Here’s why:

  • Seamless international payments: Get paid directly in USD or GBP without high transaction fees.
  • Better exchange rates: Convert your earnings to Argentine peso (ARS) when rates are most favourable.
  • Easy online transactions: Make seamless international transactions for online shopping, subscriptions, and global services.
  • Financial stability: Holding funds in stronger currencies like USD or GBP can protect you from local currency fluctuations.

With Grey, you can enjoy all these benefits directly from your phone.

Also read: How to manage multiple currencies as an expatriate in Mexico using Grey

Step-by-step guide to opening US and UK bank accounts using Grey

The process is pretty straightforward. Here’s how you can get started:

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

  • Visit Grey.co: On your browser, enter Grey.co and click on “Get started – it’s free.”
How to create US and UK bank accounts as a migrant worker in Argentina
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location.
How to create US and UK bank accounts as a migrant worker in Argentina
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
How to create US and UK bank accounts as a migrant worker in Argentina
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
How to create US and UK bank accounts as a migrant worker in Argentina

Once you’re set-up, you’re ready for identity verification — a step required for secure access to financial services.

2. Verify your identity for secure access

To keep your account safe and compliant with international regulations, Grey requires some basic documents:

  • A government-issued ID (passport or national ID card).
  • Proof of address (a recent utility bill or bank statement).

Upload these documents in the Grey app, and your verification will typically be processed within a few business days. Make sure your documents are clear and up to date to avoid delays.

3. Access your US and UK bank accounts

Once your identity is verified, you’re all set to create your foreign accounts:

  • Log in to your Grey account.
  • Go to “Accounts” and select “Create Account.”
  • Choose your preferred currency (USD for a US bank account or GBP for a UK account).
  • Get your virtual bank details instantly.

Your US and UK bank accounts are now ready for use.

Also read: How to manage multiple currencies as an expatriate in Brazil using Grey

Benefits of using Grey as a migrant worker in Argentina

  • No hidden fees: Transparent pricing ensures you keep more of your money.
  • Competitive exchange rates: Maximise your earnings when converting currencies.
  • Fast transactions: Receive and transfer money instantly, without delays.
  • Global accessibility:  Use the Grey app to manage your finances from anywhere, anytime.

Tips for managing finances as a migrant worker

  • Budget wisely: Allocate your income across savings, daily expenses, and remittances to your family.
  • Track exchange rates: Use Grey’s real-time rates to convert funds at the best times.
  • Secure your accounts: Enable two-factor authentication (2FA) for added security.

Simplify banking across borders with Grey

Managing your earnings as a migrant worker in Argentina shouldn’t be complicated. With Grey, you can open a US or UK bank account, receive payments seamlessly, and withdraw in your local currency —all from your phone.

Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

How Moroccans can open US, UK, and Euro bank accounts online in 2026

2 min read

Morocco, famous for its bustling souks and stunning architecture, is becoming a rising hub for global professionals. From freelancers working with international clients to entrepreneurs expanding their global reach, the need for reliable cross-border payments has become . Grey simplifies these transactions, offering access to international bank accounts that enable you to manage your global finances with ease and focus on growing your opportunities.

In this guide, we’ll walk you through the steps to set up your account and unlock seamless international banking directly from Morocco.

Also read: How to receive and convert foreign currencies to USDC in Morocco

Why open international bank accounts in Morocco?

  1. Reduced currency conversion costs: With Morocco’s growing participation in international markets, currency conversion can be costly. Having access to UK or Euro accounts allows you to bypass high conversion fees, making every transaction more cost-effective.
  2. Simplified global payments: Whether working with clients across Europe or the UK, having accounts in these currencies ensures quicker and easier transactions. This is particularly vital for remote workers and businesses working with global partners.
  3. Access to international markets: Morocco’s thriving gig economy is unlocking opportunities worldwide. With these accounts, freelancers and entrepreneurs can seamlessly integrate into global markets, enhancing financial flexibility.

Also Read: How to receive and convert foreign currencies to USDC in the United Arab Emirates

Who benefits from global bank accounts in Morocco?

  • Freelancers and digital nomads: With Morocco attracting a growing digital workforce, these accounts simplify receiving payments in foreign currencies, reducing delays and fees.
  • Entrepreneurs: Startups and businesses operating globally can benefit from streamlined invoicing, payments, and currency management.
  • Digital nomads: For nomads exploring the world while working remotely in Morocco, these accounts offers the financial stability needed to thrive without borders.

Also read: 5 top sites to get remote foreign jobs for Africans

How to open a Grey account

Opening a Grey account is straightforward and can be done in minutes.

  • First, visit grey.co on your browser and sign up by creating an account with your email.
https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/671bb64c436b546c4df3ec1a_671bb482c2a42a937d97a4a2_image%2520(10).png
  • Then follow the prompts and ensure you enter your correct details for a seamless setup.
__wf_reserved_inherit
  • Next, you’ll need to verify your identity — a crucial step to comply with regulatory requirements. This process is particularly important for non-U.S. residents, as Grey specialises in providing accounts for individuals outside the United States.
__wf_reserved_inherit

How to verify your Grey account in Morocco

  1. Gather your documents: Have a valid government-issued ID, such as a passport or national ID, and proof of address, like a utility bill or bank statement, ready.
  2. Submit your details: Upload your documents through the Grey platform, ensuring clarity and accuracy to avoid any delays.
  3. Get verified quickly: Grey’s verification process is efficient and secure, typically approving accounts within minutes or up to 24 hours.

Step confidently into the global financial world — open your free Grey account today.

How to create US and UK bank accounts as a migrant worker in India

2 min read

India is home to over 1.4 billion people, making it the most populous country in the world. Among them are millions of migrant workers who have moved to India for job opportunities or remote work with international companies. While the country offers a vibrant economy and diverse culture, managing foreign earnings can be challenging.

For these migrant workers, having a US or UK bank account is the answer. This guide will show you how to open a US or UK bank account from India using Grey, so you can access your earnings without any issues.

Why should you open a US or UK bank account as a migrant worker?

Whether you're a freelancer, remote worker, or an employee of an international company, having a foreign bank account can make a huge difference. Here’s why:

  • Seamless international payments: Get paid directly in USD or GBP without high transaction fees.
  • Better exchange rates: Convert your earnings to Indian rupees (IDR) when rates are most favourable.
  • Easy online transactions: Pay for global services, subscriptions, and shopping without currency restrictions.
  • Financial stability: Holding funds in stronger currencies like USD or GBP can protect you from local currency fluctuations.

With Grey, you can enjoy all these benefits without visiting a physical bank branch.

Also read: How to manage multiple currencies as an expatriate in Mexico using Grey

Step-by-step guide to opening US and UK bank accounts using Grey

The process is pretty straightforward. Here’s how you can get started:

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

  • Visit Grey.co: On your browser, enter Grey.co and click on “Get started – it’s free.”
__wf_reserved_inherit
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location.
__wf_reserved_inherit
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
__wf_reserved_inherit
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
__wf_reserved_inherit
  • Once you’re set-up, you’re ready for identity verification — a step required for secure access to financial services.

2. Verify your identity for secure access

Here’s what you’ll need to provide:

  • Government-issued ID: A valid passport or national ID card is required. Make sure it’s clear and up-to-date.
  • Proof of address: A recent utility bill or bank statement will verify your location. Grey uses this document to confirm your residency.
  • Submit your documents for review: Once uploaded, Grey will review your documents, a process that typically takes a few business days. Clear and accurate documentation speeds up approval.

3. Access your US and UK bank accounts

  • Once your identity is verified, log in to your Grey account.
  • Navigate to the “Accounts” section and select “Create Account.”
  • Choose the currency (USD for a US bank account or GBP for a UK account).
  • Your virtual bank account details, which include your account number and routing number, will be generated instantly.

Also read: How to manage multiple currencies as an expatriate in Brazil using Grey

Benefits of using Grey as a migrant worker in India

  • No hidden fees: Transparent pricing ensures you keep more of your money.
  • Competitive exchange rates: Maximise your earnings when converting currencies.
  • Fast transactions: Receive and transfer money instantly, without delays.
  • Global accessibility: Use the Grey app to manage your finances from anywhere, anytime.

Tips for managing finances as a migrant worker

  • Budget wisely: Allocate your income across savings, daily expenses, and remittances to your family.
  • Track exchange rates: Use Grey’s real-time rates to convert funds at the best times.
  • Secure your accounts: Enable two-factor authentication (2FA) for added security.

Simplify banking across borders with Grey

Managing your earnings as a migrant worker in India shouldn’t be complicated. With Grey, you can open a US or UK bank account, receive payments seamlessly, and withdraw in your local currency —all from your phone.

Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

Arrow (up)

Back to top