

<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers#article","headline":"How Moroccan businesses receive payments from overseas customers","description":"Moroccan businesses lose thousands to poor payment structures. Here's how to receive overseas payments efficiently and keep more of what you earn.","inLanguage":"en","url":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers","mainEntityOfPage":{"@id":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers#webpage"},"datePublished":"2026-02-27T21:04:14.229Z","dateModified":"2026-06-15T14:23:02.135Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300ac5b9d7b6ebaad27413_6a300ac4131376fd2525d47d_how-moroccan-businesses-receive-payments-from-overseas-customers__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300ac5b9d7b6ebaad27413_6a300ac4131376fd2525d47d_how-moroccan-businesses-receive-payments-from-overseas-customers__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers#webpage","url":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers","name":"How Moroccan businesses receive payments from overseas customers","description":"Moroccan businesses lose thousands to poor payment structures. Here's how to receive overseas payments efficiently and keep more of what you earn.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How Moroccan businesses receive payments from overseas customers","item":"https://grey.co/blog/how-moroccan-businesses-receive-payments-from-overseas-customers"}]}] </script>

How Moroccan businesses receive payments from overseas customers

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

I’ll never forget the first time I invoiced an overseas client. The project had gone brilliantly. Weeks of work went into it, I delivered on time, the client was delighted, and I happily sent the invoice. I waited for the payment, expecting it to arrive smoothly within a few days. When the money finally appeared in my bank account, it was significantly less than I’d invoiced. Nearly 6% had vanished to fees I didn’t know existed, and an exchange rate that bore no resemblance to what Google told me USD/MAD should be.

Running a successful international business in Morocco is hard. You can build a brilliant product, land clients in Paris or London or Dubai, deliver exceptional work, but if you don’t understand how cross-border payments work, you’ll lose money you’ve already earned. Quietly and consistently, to systems designed to be “opaque”.

If you’re a Moroccan business owner receiving payments from abroad or planning to this is what I wish someone had explained to me from the start.

Why are more Moroccan businesses going global?

Morocco’s business landscape has shifted dramatically over the past decade. What used to be primarily export-focused industries — agriculture, textiles, and manufacturing — have expanded into digital services, software development, creative agencies, consulting, and e-commerce.

I’ve watched Moroccan developers build SaaS products for European markets. Design agencies in Casablanca are working with clients in the Gulf. Marketing consultants in Marrakech serving American startups. The internet removed geographic barriers to finding customers, and Moroccan businesses capitalised on that opportunity.

The appeal is obvious. International clients often pay in stronger currencies, usually EUR, GBP and the global standard USD, which translates to better margins when converted to dirhams. Time zone proximity to Europe also makes collaboration easier.

But while finding international customers has become easier, receiving payment from them remains complicated. Morocco’s currency regulations, banking infrastructure, and the nature of cross-border transactions create friction that catches many business owners off guard.

Also read: Meet Grey Business: the growth engine for global finances

The regulatory reality in Morocco

Morocco operates under foreign exchange controls managed by the Office des Changes. Its regulatory infrastructure is designed to manage currency flow and maintain economic stability.

When you receive payment from overseas, Moroccan banks must verify the transaction’s legitimacy. You’ll need to provide invoices, contracts, or other documentation proving the payment relates to legitimate business activity. This is standard practice, but it creates administrative overhead that purely domestic transactions don’t require.

Moroccan businesses also can’t easily maintain foreign currency accounts with local banks, unlike businesses in the UK or the UAE. Most foreign payments are converted to dirhams upon arrival, and you have limited control over the timing or rate of that conversion.

I’m not saying the system is broken, as it functions as it’s designed to. But understanding these realities upfront helps you structure your payment processes to comply with regulations, not work against them.

Common ways Moroccan businesses receive overseas payments

Over the years, I’ve learned nearly every method available to Moroccan businesses, and each has taught me something different about what works and what doesn’t.

SWIFT

SWIFT bank transfers are the traditional approach. Your client sends USD via international wire transfer to your Moroccan bank account. The money passes through intermediary banks, arrives in Morocco, and gets converted to dirhams. In theory, it’s straightforward. In practice, it’s slow, often taking five to ten business days, and expensive. Your client’s bank charges a sending fee, intermediary banks take their cut, your Moroccan bank applies a receiving fee and converts the currency at a rate typically 2 - 4% worse than the mid-market rate. On a €10,000 payment, you can lose €300-500 to fees and poor exchange rates.

PayPal

PayPal is popular for smaller transactions and international freelance work. It’s fast and familiar to overseas clients. The problem for Moroccan businesses is that PayPal Morocco has limitations. You can receive payments, but withdrawing to a Moroccan bank account involves fees and unfavourable conversion rates.

Stripe

Stripe and similar payment gateways work well for e-commerce or subscription services. Overseas customers pay by card, Stripe processes the payment, and you receive funds in your connected account. However, Stripe’s availability and payout options in Morocco are limited compared to Europe or North America. Many Moroccan businesses use Stripe through offshore company structures, which adds complexity and compliance considerations.

Fintechs and payment platforms

The newer approach involves fintech services that provide virtual foreign currency accounts. These give Moroccan businesses foreign account details that clients can pay into directly, without the funds immediately passing through Moroccan banking infrastructure or being forced converted. You hold the funds in the original currency, convert when you choose, and withdraw to your Moroccan account as needed.

Also read: How to budget in foreign currencies using the Grey card

How Moroccan businesses can structure payments smarter

After years of losing money to inefficient payment structures, I’ve learned a few things that make a genuine difference.

First, invoice in the currency you want to receive. If your client is European and paying in EUR, invoice in EUR. If they’re American and paying in USD, invoice in USD. Don’t invoice in MAD and expect them to convert, as you will lose control over the exchange rate, and they’ll often use unfavourable rates that cost you money.

Second, match your receiving account to your invoice currency. If you’re invoicing in EUR, having a EUR receiving account means the client’s payment arrives without unnecessary currency conversion steps. The money stays in EUR until you decide to convert it to MAD, giving you control over timing and rates.

Third, consolidate payments where possible. Instead of receiving five small payments monthly with fees on each, negotiate with clients to pay less frequently but in larger amounts. Fewer transactions mean fewer fees.

Fourth, build currency conversion timing into your financial planning. If you don’t need the money immediately, hold it in the foreign currency and convert when exchange rates are favourable.

Fifth, work with service providers who understand cross-border payments. Not all banks or fintech platforms operate the same way in Morocco. Choose partners who specialise in international transactions and offer transparent pricing.

Also read: Freelancing legally in Morocco: licences, taxes and foreign income rules

Using Grey to receive overseas payments

Grey changed how I think about receiving international payments. Instead of forcing every payment through traditional banking infrastructure with all its fees and delays,  Grey provides virtual EUR, GBP, and USD accounts with proper banking details that clients can pay into directly. And if you want the perks of a business account with bulk payouts, you can also create that.

Here’s how it works in practice: when a client needs to pay me in USD, I give them my Grey USD account details. From their perspective, they’re making a simple USD bank transfer to a USD account.

I hold the USD in my Grey account until I’m ready to convert it, so when rates are good, I convert.

For Moroccan businesses that receive regular payments from overseas clients, this structure makes a significant difference. You’re not losing 4-6% to fees and poor exchange rates on every transaction. You control the timing of currency conversion. Payments arrive faster, predictably, and with full transparency about costs.

Grey isn’t replacing your Moroccan bank account; rather, it’s a layer that sits alongside it, handling the complexity of international payments so your local bank can focus on local operations.

LDMAG1

Global revenue needs global-ready banking

I’ve watched Moroccan businesses build incredible products and services for international markets. They compete globally and win clients against companies worldwide. But too many still lose significant money simply because their payment infrastructure wasn’t designed for the global reality of their business.

Efficiently receiving overseas payments directly affects your profitability.

The good news is you don’t have to accept this as inevitable. Better infrastructure exists. Services designed specifically for cross-border payments can save you significant money whilst reducing administrative headaches.

If you’re running a Moroccan business with overseas customers, treat your payment infrastructure as seriously as you do your product, marketing, or client relationships. Because getting paid properly is part of running a successful global business.

Open your Grey business account today and start receiving overseas payments the way they should work, without losing the money you’ve already earned.

‍

Last updated:

October 17, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

What you need to open a business bank account in the US

•

•

2 min read

In the early days of running a business, many people just use their personal accounts. However, as you expand your client base and start to cover business expenses, your personal account won’t cut it. Your business needs to have a business account.

It makes it easier to receive and spend money in a separate account; it’s also easier to track monthly expenses without reading multiple bank statements.

What do you need to open a business bank account? The list is short, but it varies slightly depending on your business type, your tax ID, and where you, the owner, live. Here’s what you will need to open a US business account, how the requirements differ by structure, and what founders and business owners living outside the United States should expect.

To open a US business bank account, you typically need your EIN, business formation documents, ownership and control details, and a personal photo ID for each owner. Sole proprietors may use a Social Security number instead of an EIN. Some banks also ask for a business licence and an opening deposit.

The full checklist

Most business bank accounts require the same set of documents:

  1. Your EIN: The employer identification number is the IRS tax ID for your business. Some sole proprietors can use their Social Security number instead.
  2. Business formation documents: For an LLC, this is usually the Articles of Organisation or Certificate of Formation. For a corporation, it is the Articles or Certificate of Incorporation. Sole proprietors who trade under a name other than their own may need a DBA (doing business as) or assumed name certificate.
  3. Ownership agreement, if you have one: Banks commonly ask for an operating agreement (for an LLC) or a partnership agreement that shows who owns the business.
  4. Ownership and control details: For legal entities, US banks must collect the name, date of birth, address, and ID number of each person who owns 25% or more of the business, plus one person with significant control, such as a CEO or managing member. Foreign owners can provide a passport number. The FinCEN guidance on the customer due diligence rule explains the rule.
  5. A personal photo ID for each owner: A driver’s licence or passport is typical, and some banks also ask for a second form of ID.
  6. A physical business address: Some large banks do not accept a registered agent address, virtual address, or PO box as your business address.
  7. Proof the business is registered, or a business licence: Banks may ask for a document showing your business is registered with a government agency, and for any state or local licences you hold.
  8. An opening deposit: Initial deposits and minimum balances vary by bank and account type, and some banks waive them.

Requirements vary by bank, so check your chosen bank’s own list before you go. This is general information, not legal advice.

Requirements by business type

This list is the same for every business, but what you have to provide changes depending on your structure. A sole proprietor has the fewest requirements, and a corporation or partnership has the most paperwork.

Sole proprietor LLC Corporation Partnership
Tax ID Social Security number, or an EIN EIN EIN EIN
Registration documents A DBA or assumed name certificate, if you use a business name Articles of Organization or Certificate of Formation Articles or Certificate of Incorporation Partnership agreement or business registration
Ownership agreement Not applicable Operating agreement, usually for multi-member LLCs Ask your bank what it needs, such as bylaws or a board resolution Partnership agreement, or a signed statement if none exists
Photo ID The owner Each owner with 25% or more, plus one person with control Each owner with 25% or more, plus one person with control Each owner with 25% or more, plus one person with control

having to readPlease note:

  • Sole proprietors are not covered by the beneficial ownership rule because a sole proprietorship is not a separate legal entity. You are the owner, so your own ID is usually enough.
  • LLCs are the most common structure for freelancers and small online businesses. Multi-member LLCs are more likely to be asked for an operating agreement. Our guide to the best business bank accounts for an LLC compares the options.
  • Corporations and partnerships are asked to provide the founding documents showing who owns the business and who can sign on its behalf.

Not sure a separate account is worth it yet? Read our guide on whether you need a business bank account as a freelancer.

Do you need an EIN?

Not always, but banks prefer you have one. Some sole proprietors can open an account using their Social Security number, while LLCs, corporations, and partnerships are usually required to provide an EIN. Having one also keeps your personal number off your business records.

An EIN, or employer identification number, is a nine-digit tax ID assigned by the IRS to a business. It is free. The IRS says you never have to pay a fee for an EIN, so be wary of sites that charge.

Here is how to get one:

  1. Apply online if you qualify: The IRS online tool is for businesses formed in the US or its territories that have a principal place of business there. You need the responsible party’s Social Security number or individual taxpayer identification number (ITIN).
  2. Use the IRS hours: The online application runs at set times in Eastern Time, so check the IRS page before you start.
  3. Apply once per day. You can apply for only one EIN per responsible party per day.
  4. Keep the confirmation. Banks may ask for the IRS letter confirming your EIN, not just the number.

The IRS page on getting an EIN has the full details. If you do not qualify to apply online, for example, because your business is outside the US, you can apply by phone, fax, or mail instead. We cover that in the non-resident section below.

Requirements for non-residents

Non-residents can open a US business bank account, but it’s usually more difficult, and it depends on the bank. No federal rule bars it, yet each bank sets its own requirements for identity, address, and tax ID, and some do not accept foreign owners at all.

Here is what overseas founders usually need:

  • A US business entity and an EIN: Most founders form a US company, such as an LLC, and then get an EIN.
  • A valid passport: It usually replaces the Social Security number as your ID. US banks may record a passport number for foreign beneficial owners.
  • Formation documents and an ownership agreement: The same documents as in the checklist above.
  • Address evidence: A home address abroad, and a physical business address that the bank accepts.
  • Proof of what the business does: Some banks ask for contracts, invoices, a website, or evidence of the source of funds.

You can still get an EIN without a Social Security number or ITIN. The IRS instructions for Form SS-4 say you enter “foreign” on line 7b if the responsible party has neither. The online tool is not available to you if you have no residence or principal place of business in the US, so you apply by phone, fax, or mail. Fax usually returns the EIN within about four business days. By mail, allow about four to five weeks.

The common hurdles are:

  • Social Security number rules: Some banks require an SSN from each owner, and an EIN does not replace it.
  • Address rules: A registered agent address, virtual address, or PO box is often rejected as your business address.
  • In-person visits: Some traditional banks expect you to visit a branch.
  • Country and industry limits: Providers may exclude some countries or business types.
  • Extra checks: A bank may ask follow-up questions before approving the account, and incomplete answers can slow the process.

Before you apply, ask the bank exactly what it accepts from non-resident owners. Our guide to what non-US residents need to open a US bank account covers the major banks.

Handling international payments

Opening the account is one step, and getting paid across borders is another. A US business account is designed for domestic payments, so if you invoice clients abroad or pay suppliers in other countries, you may want a second layer to handle foreign currencies.

Grey offers multi-currency accounts, with no account opening fees, no maintenance charges, and no minimum deposit, so adding it does not require an additional opening deposit. You can also create a proper USD business account in your business name.

Grey also helps you send and receive money from the US. You can fund a transfer from a US bank account via ACH or wire, choose the destination, and check the exchange rate and fees before confirming. If you work with people or suppliers in Nigeria, you can send money from the US to Nigeria without the recipient needing a Grey account.

Transfer times and fees depend on the destination, the funding method, and the recipient’s bank, so check the details on Grey before you send.

Frequently asked questions

What documents do I need?

You typically need your EIN, formation documents, ownership and control details, and a personal photo ID for each owner. Some banks also ask for a business licence, proof of address, and an opening deposit.

Do I need an EIN?

Not always. Some sole proprietors can use their Social Security number, but LLCs, corporations, and partnerships are usually required to provide an EIN, and many banks prefer one for each business. An EIN is free from the IRS.

Can a sole proprietor open one?

Yes. A sole proprietor can open a business account using a personal ID and a Social Security number or an EIN. If you trade under a name other than your own, you may also need a DBA or assumed name certificate.

Can a non-resident open one?

Sometimes. It depends on the bank. Non-residents usually need a US business entity, an EIN, and a passport; some banks also require a Social Security number or an in-person visit. Ask the bank what it accepts before you apply.

Do I need a deposit?

It depends on the bank and the account. Initial deposits and minimum balances vary, and some banks waive them. Check the account terms before you apply.

Can I open one online?

Often yes. Many banks let you apply online and upload your documents, though some ask you to visit a branch. Have your documents ready as digital copies either way.

Ready to add a multi-currency layer to your business banking? Open a multi-currency account with Grey.

Grey is a financial technology company, not a bank. Exchange rates, fees, limits, and transfer times vary by destination and are subject to change.
How South African YouTubers receive YouTube payments in 2026

•

•

2 min read

YouTube is now considered one of the most popular search engines in the world, and South African creators are taking full advantage of it, with over 25 million South Africans actively using the platform. This shows that there’s a huge market for you as a creator. And you can, of course, make money from it.

How?

First, you create videos that people watch worldwide; next, your account gets monetised, and then the money accumulates in your AdSense account. After that, you can withdraw and then start spending.

Except... I’ve spoken to many creators who waited weeks for transfers, lost significant portions of their earnings due to unfavourable exchange rates, or had payments rejected because their bank didn’t accept international wire transfers. None of those stories need to be yours. Below, I’ll explain how YouTube pays, the pain points most South Africans face, and most importantly, practical, step-by-step options to receive your money quickly and with minimal fees.

Also read: Send US dollars to South Africa from anywhere

Why do USD earnings matter for South African creators?

As a South African creator, your payments from YouTube are made in US dollars. Earning in USD gives your income more global value. Great yeah? Well, most local bank accounts in South Africa can’t receive USD directly. For those that do, when your earnings are converted into South African Rand (ZAR), they often take a significant cut due to high transfer fees and unfavourable exchange rates.

Sometimes, currency fluctuations can make this worse. Your income’s real value may drop the moment it’s converted. By holding part of your earnings in USD, you can protect yourself from these swings and preserve the value of what you’ve earned.

Earning in a stable foreign currency helps you stay in control by keeping more of your money, allowing you to decide when to convert it, and ultimately, getting paid on your own terms.

How does YouTube pay?

Before you can cash out your earnings, it’s important to understand how YouTube’s payment system works.

1. Join the YouTube Partner Program (YPP)

You can only start earning from ads once you’re part of the YouTube Partner Program (YPP). To qualify, your channel needs to meet one of YouTube’s monetisation thresholds within the past 12 months:

  • Option 1: 1,000 subscribers and 4,000 valid public watch hours, or
  • Option 2: 1,000 subscribers and 10 million valid public Shorts views

Once your channel is approved, you’ll be able to monetise through ads, channel memberships, Super Chats, Super Stickers, and YouTube Premium revenue. Essentially, every view or engagement can start earning you money, as long as it happens on monetised content.

2. Set up a Google AdSense account

YouTube doesn’t send money directly to your bank. All payments are processed through Google AdSense, so setting it up is a crucial step.

Here’s what you’ll need to do:

  1. Create or link an AdSense account to your YouTube channel.
  2. Submit your tax information. This ensures compliance with YouTube’s global payment policies.
  3. Choose your preferred payout method, such as direct bank transfer or wire transfer.

Your AdSense dashboard is where you’ll monitor your estimated earnings, payment history, and any deductions for taxes or invalid activity.

3. Reach the payment threshold

YouTube doesn’t pay out every time you make a few dollars; it works on a minimum payment threshold system. You’ll need to earn at least $100 in your AdSense account before Google processes a payout.

If your earnings for the month fall short, the amount will simply roll over to the next month until you reach the threshold. Once you cross that mark and your account is verified, YouTube will automatically schedule your payment in the next payment cycle.

For most creators, payments will be sent around the 21st of each month, covering your total earnings up to the end of the previous month. So, if you hit $100 in March, you’ll typically get paid in April.

4. Understand the payment timeline

So, let's talk more about the payment cycle. The payment system runs on a monthly cycle, but payments aren’t instant. There’s a short delay while your earnings are verified and processed.

Here’s how it works:

  • Earnings are finalised between the 3rd and 10th of the following month. During this time, YouTube reviews your ad revenue to confirm everything’s valid.
  • Payments are processed between the 21st and 26th, once your balance reaches the $100 threshold.
  • You’ll only receive your payout if there are no payment holds, such as missing tax information or pending account verification.

So, for example, if you earned $200 in April, those funds will appear in your AdSense account in early May, but you’ll actually receive the money later in May. Once Google processes that month’s payouts.

It’s a simple system. Once you understand the rhythm, you just need a bit of patience between creating the content and seeing the cash hit your account.

Also read: How to pay for subscriptions in US dollars from South Africa

How to receive USD from YouTube in South Africa with Grey

Grey allows South African YouTubers to open a USD account effortlessly, all without leaving the country.

1. Create your Grey account

Visit the Grey website or download the app. Sign up and complete your KYC verification.

2. Access your USD account details

After approval, you’ll get your account information, including a US routing number, account number, and SWIFT code.

3. Connect your Grey USD account to AdSense

Log in to AdSense, select “Add payment method,” and enter your Grey account details.

4. Receive payments in USD

YouTube will deposit your earnings directly into your Grey account in USD, eliminating the need for automatic currency conversion.

5. Convert whenever you want

Use Grey’s in-app exchange to convert USD to ZAR at competitive rates or hold your USD in your account if you prefer.

Also read: How to send and receive British pounds in South Africa

What other ways can South African YouTubers boost earnings?

Once you’ve set up a reliable payment method, you can turn your channel into a sustainable income source. The most successful creators don’t rely on just one revenue stream; they layer multiple income sources to protect against dips in views or ad rates.

Here’s how you can do the same:

Channel memberships

Offer loyal fans exclusive perks like members-only videos, live Q&As, or custom emojis in exchange for a monthly subscription. This builds community and gives you a predictable monthly income.

Super chat & super stickers

These features allow viewers to pay to have their messages highlighted or to send animated stickers during live chats, providing a fun way for fans to support you in real-time.

Affiliate marketing

By adding affiliate links in your video descriptions, you can earn a commission every time someone buys a product you recommend. This works well if you review gear, software, or services your audience already needs.

Brand sponsorships

You can partner with companies to feature their products or services in your content. Sponsored deals often pay far more than ad revenue, especially if you have a niche audience that brands want to reach.

Also read: How to get paid as a creator on social media from anywhere in the world

At the end of the day, the more diverse your income streams, the more stable your creator career will be. If ad rates drop or one revenue source slows down, your other income channels keep you afloat.

Why Grey is the best option for South African creators

Now to the solution. Grey is built to accommodate how modern creators work, earn, and spend across borders. If you’re a South African YouTuber, influencer, or freelancer receiving international payments, Grey removes the friction that usually comes with getting paid from abroad.

Free USD account setup

Grey lets you open a USD account, providing you with the same payment details (routing and account numbers) that US-based creators typically use.

Low, transparent FX rates

Grey offers competitive exchange rates that are visible upfront, so you know exactly how much you’ll receive before confirming a transfer.

Multi-currency accounts to grow your income

With Grey, you can also hold EUR, GBP and USD, which is perfect if you land brand deals in Europe or work with clients in the UK.

Fast, reliable payouts

You no longer need to wait weeks for your money to clear. Grey processes transfers quickly, so you can move your earnings to your local bank account without delay, helping you maintain a steady cash flow.

Built with creators in mind

Every feature is designed to make life easier for people who get paid globally, so you can focus on making content instead of chasing payments. This makes it easier to keep more of your hard-earned YouTube income and avoid the usual international payment frustrations.

Being a YouTuber in South Africa is a great way to share your voice with the world and earn a living from it. By setting up a USD account with Grey, you can receive your YouTube earnings quickly, securely, and without incurring losses due to unfavourable exchange rates.

Create your free Grey account today or download the app to make your creator journey easier, smarter, and borderless.

‍

Grey vs traditional banks: which saves you more time

•

•

2 min read

The global digital evolution has not left the banking sector untouched. A fast-paced generation requires fast transactions. Many employees now work with clients they’ve never met, living in foreign countries they’ve never visited. The educational sector is seeing a growing number of international students. Digital nomads work remotely while hopping from country to country. Businesses are expanding, with growing cross-border trade. Our banking needs are evolving. We now need seamless and swift borderless payment solutions at the lowest cost possible.

Fintech companies like Grey offer solutions that fit today’s needs and help solve problems that traditional banks haven’t fixed.

In this article, we compare the new and the old, Grey vs. traditional banks, and examine where each stands in terms of time conservation.

Also read: Global accounts vs traditional banks: What remote workers should know

How Grey works

With Grey, you can open international bank accounts and manage money across borders easily. It’s made for freelancers, expats, and remote workers. You can open an account in just a few minutes, all online, with no need to visit a branch or fill out lots of paperwork. Grey offers:

  • Multi-currency support: Receive, send, hold, and convert between USD, GBP, EUR, and local currencies.
  • Swift conversions and transfers: Currency conversions and international transfers are completed within minutes to a few hours.
  • Additional feature: Grey also offers automated invoicing, expense tracking, and virtual USD debit cards for seamless online payments.
  • Security: Grey is fully regulated by FINTRAC and FinCEN, ensuring that your funds and data are adequately protected.

Unlike traditional banks, which are often constrained by regulatory hurdles and official bottlenecks, Grey leverages digital provisions to enable faster processing.

Also read: Global accounts vs traditional exchange houses: which is better?

How traditional banks work

Traditional banks, such as Chase and HSBC, as well as local branches in various countries, offer a wide array of banking services, including savings accounts, loans, mortgages, and investment advice. They operate through physical branches, ATMs, and digital platforms. They offer more robust banking services compared to emerging fintechs. However, many traditional banks remain traditional in practice, with lengthy paperwork and cumbersome processes, such as waiting in lines, scheduling appointments, or dealing with international money transfer delays, in a fast-paced economy.

Grey vs traditional banks: Which saves you more time

Fintechs like Grey don’t replace traditional banks, but they do some things differently. Let’s see which one saves you more time by looking through important banking processes.

1. Account opening

The onboarding process of a banking system basically shows you what to expect from them. This is why many strive for a streamlined account opening process. Now, let’s compare Grey and traditional banks.

  • Grey: Signing up and verifying your identity on Grey is a seamless process that takes only a few minutes. The process is entirely through the app or website and doesn’t require a physical branch visit or mailing documents. You simply need to upload a valid ID, proof of residence, and a selfie for Know Your Customer (KYC) compliance. Accounts in USD, GBP, or EUR can be opened from anywhere in the world, making it ideal for non-residents or travellers.
  • Traditional banks: Opening an account typically involves visiting a branch, filling out forms, providing multiple documents (e.g., proof of address, income statements), and waiting for approval, which can take days to weeks. For international accounts, additional hurdles, such as residency requirements or embassy verifications, may extend this to several months.

Grey takes the show here, with a swift account opening and verification process, with the ease of opening an account remotely without visiting a physical bank branch.

2. Transactions and money transfers

Transaction processing speed is crucial during emergencies, such as paying bills. Delayed payments can leave you stranded.

  • Grey: Transactions on Grey are swift, usually completed within minutes to a few hours using networks like SEPA or ACH. Users receive real-time notifications, and the app handles everything without the need for intermediary banks.
  • Traditional banks: Transfers, especially international ones (via SWIFT), can take 1-5 business days due to the involvement of multiple intermediaries, compliance checks, and banking hours. Even domestic transactions may require branch visits or phone confirmations, which can increase wait times.

With Grey, cross-border payments are done much faster, often saving you days compared to traditional banks.

3. Currency exchange and management

Many people now deal with different currencies, especially remote workers, students abroad, expats, and global businesses. Managing money across several banks or apps can take a lot of time, and converting currencies isn’t always quick.

  • Grey: Conversions occur within seconds in the app at competitive rates, with no hidden fees. Users can manage multiple currencies on a single platform, track expenses, and automate invoicing to streamline client payments.
  • Traditional banks: Exchanges often require branch visits or calls, with markups on exchange rates and fees. Processing may take hours or days, and managing multiple accounts requires logging into separate systems or handling paperwork for each currency.

Grey simplifies international finance management with multi-currency accounts and swift conversions.

4. Customer support and issue resolution

How quickly can your banking solution resolve your payment crisis? What mechanisms are available?

  • Grey: As a digital-first payment service, Grey offers fully digital support services that avoid phone queues. and features like language switching enhance accessibility. However, as a fintech, it may lack the depth required for complex issues, such as loans.
  • Traditional banks: Support involves calling hotlines with uncertain waiting times, visiting branches, or scheduling appointments. Traditional banks are evolving to offer 24/7 digital support through chats.

Grey generally offers faster initial responses and saves time on routine queries. Traditional banks offer a wide range of support, whether you visit a bank branch or use one of their remote options.

Also read: How to switch from traditional banking to Grey for remote work payments

Swift transactions with Grey

Grey is a payment solution designed for a fast-paced era, offering swift processing compared to traditional banks. From instant account openings to quick transfers and seamless multicurrency support, Grey removes the need for physical visits, paperwork, and delays.

Get started on Grey today for faster international transactions.

‍

How to receive your Shopify earnings in South Africa

•

•

2 min read

Right now, there’s a fashion entrepreneur in Capetown selling handmade jewellery to customers in New York. In Durban, someone is running a thriving skincare brand with orders pouring in from Germany. This is the power of Shopify, a platform that has democratised global e-commerce.

Shopify enables entrepreneurs to create online stores, manage inventory, process payments, and ship products globally from a single dashboard. Its ease of use, integration with payment providers, and access to a global audience have made it a favourite for small business owners and side hustlers across South Africa.

But while Shopify helps you sell worldwide, getting paid isn't always as straightforward, especially if you're based in South Africa. Shopify doesn’t directly support local banking infrastructure, and many South African merchants struggle with receiving payouts from international customers.

If you’re wondering how to receive your Shopify earnings in South Africa without the frustration of high fees or delays, this is for you.

How does Shopify pay sellers globally?

Shopify facilitates payouts through two main channels:

  • Shopify Payments: Shopify’s in-house payment system is available only in select countries like the US, UK, Canada, and Australia.Note: Shopify Payments is not available in South Africa.
  • Third-party payment gateways: These include platforms like PayPal, Payoneer, and Stripe. These providers process customer payments and deposit your earnings into a bank account you provide.

In South Africa, most Shopify sellers rely on third-party options to receive their money. However, even then, receiving and converting these funds into South African rand (ZAR) can be frustrating and expensive.

Also read: Sending money to South Africa from the US? Here’s the cheapest way

Why South African sellers struggle with Shopify payouts

Selling internationally is only half the battle. The real challenge for many South African merchants begins when it’s time to collect their funds. Here’s why:

  • No access to Shopify Payments: You’re forced to use third-party providers, which often have limitations for non-US or non-EU users.
  • Foreign bank requirements: Platforms like Payoneer and PayPal often require you to link a USD, GBP, or EUR bank account. Most local banks don’t provide that.
  • High currency conversion fees: Even when you manage to get paid, converting earnings to ZAR through traditional banks can chip away at your income.
  • Slow withdrawal processes: Payments often take days to clear, and moving money to a local bank account can take even longer.

How to receive Shopify earnings in South Africa with Grey

Grey is a digital banking platform that offers virtual foreign accounts in USD, GBP, and EUR. It’s built specifically for freelancers, creators, remote workers, and e-commerce sellers like you.

Here’s how you can start receiving your Shopify earnings in South Africa with Grey:

1. Create your Grey account

Visit Grey's website or download the app from the App Store or Google Play. Sign up using your email and complete your profile with basic details.

2. Verify your identity

To comply with financial regulations, you’ll need to upload a valid form of ID and proof of address. This process is usually completed within 24 hours.

3. Open your virtual foreign account

Once verified, you’ll have access to foreign bank accounts in:

  • USD (US bank details)
  • GBP (UK bank details)
  • EUR (EU/SEPA bank details)

These accounts come with your account number, routing code, SWIFT/BIC, and IBAN, depending on the region — making them ready to receive international payouts.

4. Connect Grey to your Shopify payment provider

If you’re using PayPal, Payoneer, or Stripe, simply input your Grey account details as your payout destination:

  • Go to Shopify Seller Central
  • Navigate to Settings > Payments
  • Add or update your payout account details using your Grey virtual bank info

Once set, Shopify will route your earnings to your chosen payment gateway, and your earnings will land in your Grey account.

5. Convert your earnings and withdraw in ZAR

Log in to your Grey dashboard to view your balance in USD, GBP, or EUR. You can:

Also read: Best ways to receive international wire transfers in South Africa

Why Grey is ideal for South African Shopify sellers

Grey takes the complexity out of international payments, helping South African merchants manage earnings more efficiently. Here’s what makes it a perfect fit:

  • No need for a foreign residency: Open USD, GBP, and EUR accounts from within South Africa
  • Low fees: Avoid the high fees of PayPal withdrawals and traditional currency exchanges
  • Fast transactions: Get paid quickly and convert or withdraw funds in minutes
  • Real exchange rates: No hidden markups — what you see is what you get
  • Mobile-first platform: Manage all your international earnings from your phone

Additional tips for Shopify entrepreneurs in South Africa

  • Track exchange rates: Use the Grey currency converter to monitor the best times to convert earnings.
  • Keep financial records: Export transaction history from Grey to stay tax-compliant and plan your cash flow.
  • Diversify your payment options: Offer multiple gateways (e.g., PayPal and Payoneer) to give customers flexibility and speed up payments.
  • Leverage Grey for other platforms: Use your Grey account to also receive funds from Fiverr, Upwork, Amazon, or affiliate platforms.

Also read: How to receive your Shopify earnings using Grey

Get paid globally, spend locally with Grey

You’ve worked hard to build your brand and sell to international customers — now it’s time to get paid properly. Grey makes it possible to receive your Shopify earnings in USD, GBP, or EUR, convert them at fair rates, and access your funds from anywhere in South Africa.

Create your Grey account today or download the app to enjoy inclusive global banking, designed to help you carry your dreams across borders.

‍

Earn from TikTok in India without a UK bank account | Grey

•

•

2 min read

Somewhere in the world right now, there’s a student frantically revising for their exam. After procrastinating over the past few months, they now have 72 hours to learn an entire semester’s worth of content. What’s their plan? Binge-watch a series of crash course TikToks from a witty Indian tutor.

This scenario might sound dramatic, but it happens every day. Indian creators — tutors, dancers, comedians, chefs, fashionistas — are educating and entertaining global audiences through TikTok. The platform has become a powerful space for sharing creativity and making money. And while creators can earn through the TikTok Creator Fund, brand sponsorships, and live gifts, there's a catch: you usually need a UK or US bank account to get paid.

If you're a creator in India, Grey allows you to receive TikTok payments in USD, GBP, or EUR and convert them to INR seamlessly. Here’s everything you need to know.

Also read: How to receive payments from Toptal in India in 2025

How do Indian creators earn money on TikTok?

TikTok has expanded far beyond viral dances and lip-sync videos. It's now a viable income stream for Indian creators across niches. Here are the main ways they get paid:

  • TikTok creator fund: This is TikTok’s in-house monetisation programme. Once you meet the eligibility requirements (age, follower count, engagement), you get paid based on the performance of your videos. It is based on views and interactions.
  • Brand sponsorships: Companies, both local and international, often reach out to creators to promote their products or services. These deals are usually negotiated off the platform and paid out in USD or GBP.
  • Live gifts & tips: During livestreams, fans can send virtual gifts that translate to real money. The more engaging your content, the more support you receive.
  • Affiliate links & product sales: Some creators build thriving businesses by promoting their own products or affiliate links, using TikTok as a powerful funnel.

However, all these payment methods typically rely on international payout systems, and that's where the challenges begin.

Also read: Earn from TikTok in Nigeria without a UK bank account

Why can’t you use a regular Indian bank account for TikTok payments?

Here’s the reality: TikTok’s payment processors don’t support direct INR deposits for most monetisation channels. That means Indian creators must link a US, UK, or EU bank account to access their earnings. This comes with several issues:

  • Limited access: Most Indians can’t open a traditional foreign bank account unless they’re physically present abroad, or go through a lengthy (and expensive) process.
  • High fees: Some workaround services come with painful conversion charges or middlemen that eat into your earnings.
  • Delays: International transfers through traditional banks can take days or even weeks to clear.
  • Rejected payments: If account details don’t match exactly, payments might bounce and recovering them is often a bureaucratic nightmare.

So what’s the best alternative? Let’s talk about Grey.

How can you earn from TikTok in India without a UK bank account?

Grey is a digital banking platform that gives Indian creators free virtual accounts in USD, GBP, or EUR. This makes it easier to receive international payments like a local.

Here’s how it works:

  • Open a free Grey account from India and access a virtual foreign bank account in minutes.
  • Link your Grey USD or GBP account to TikTok or share it with brands for sponsorship payouts.
  • Convert your earnings to INR inside the app at competitive rates.
  • Withdraw your funds to your regular Indian bank account.

You don’t need to jump through hoops, use a VPN, or worry about rejected payments. With Grey, your TikTok income flows just like your content: smoothly.

Also read: How freelancers in India can invoice abroad clients easily

How to set up Grey and start getting paid from TikTok in India

Here’s a step-by-step guide to get started:

Create a Grey account

Visit grey.co or download the Grey app from the App Store or Play Store.

Verify your identity

Upload a valid Indian government-issued ID (like your PAN or Aadhaar card), proof of address, and a selfie for verification.

Open your USD or GBP account

Once verified, you can generate your virtual foreign bank account details instantly — including IBAN/SWIFT codes.

Link to TikTok or brand deals

Enter your Grey USD or GBP account details into the TikTok Creator Fund payout system or share them with brands for direct deposit.

Receive your earnings and convert to INR

When payments land in your Grey account, you can monitor exchange rates and convert your funds to INR with a few taps. Withdraw directly to your Indian bank account.

Why Grey is the best solution for Indian TikTok creators

Still on the fence? Here’s why thousands of remote workers, creators, and freelancers trust Grey:

  • Multiple currencies, one account: Hold and manage USD, EUR, and GBP from one app.
  • No hidden fees: Transparent pricing with excellent currency conversion rates.
  • Fast transfers: Receive and withdraw your money quickly, without the delays of traditional banking.
  • Built for global creators: Whether you’re monetising TikTok, YouTube, Upwork, or selling online, Grey works across platforms.

Also read: How to receive money from UK clients in India

Start earning from TikTok with Grey

As TikTok continues to empower creators globally, Indian talent is leading the charge by teaching, entertaining, and inspiring millions. But what’s the point of creating content that pays if the payment system doesn’t work for you?

You just need a phone, your creativity, and the right payment partner.

Create your Grey account now and start earning from TikTok.

‍

How Egyptians earn foreign currencies online

•

•

2 min read

Egyptians are increasingly expanding beyond local employment as remote work and digital income opportunities reshape how people earn. Across the country, more professionals, students, and creatives are targeting foreign currency earnings as a way to improve financial stability. With global connectivity improving, it is now common for Egyptians to earn in USD, EUR, or GBP without ever leaving the country. These incomes come from clients in the Gulf, Europe, the United States, and beyond, powered by freelance platforms, remote job boards, and digital marketplaces.

Below are the most practical and widely used ways Egyptians are earning foreign currency online today, along with what it takes to succeed in each path.

Also read: How Egypt is becoming a MENA hub for remote workers

Content creation and monetisation

Content creation has become one of the most visible ways Egyptians earn foreign income. Platforms like YouTube, TikTok and Instagram allow creators to monetise attention through ads, brand partnerships, affiliate marketing, and subscriptions. Egyptian creators span comedy, lifestyle, tech, gaming, and education, proving there is no single path to success. The key is consistency and audience targeting rather than location.

Creators earn mainly in USD through platform monetisation systems and sponsorship deals with international brands. While competition is high, creators who focus on niche topics or global audiences often scale faster. Monetisation also extends beyond ads into memberships, Patreon-style support, and paid collaborations, giving creators multiple income streams rather than relying on a single platform.

Freelancing for international clients

Freelancing remains the most direct and scalable way to earn foreign currency online. Egyptians offer services in software development, graphic design, copywriting, digital marketing, SEO, video editing, data analysis, and customer support. Platforms such as Upwork, Fiverr, and Freelancer connect them to clients worldwide, while LinkedIn and cold outreach help secure higher-paying direct contracts.

Success in freelancing depends on positioning and specialisation. Generalists often struggle, while specialists in high-demand skills like AI development, UI/UX design, and performance marketing command higher rates. Payments are typically received in USD or EUR, giving freelancers access to stronger earning power compared to local currency jobs.

Also read: Opportunities for Egyptian remote workers in the Middle East

Remote jobs with international companies

Remote employment has become one of the most stable ways Egyptians earn foreign income. Instead of project-based work, professionals secure full-time or long-term contracts with foreign companies in tech, finance, customer support, operations, and marketing. These roles provide predictable monthly salaries paid in foreign currency.

Unlike freelancing, remote jobs offer structure, benefits, and long-term stability. Many companies hiring remotely look for English proficiency, technical skills, and time zone flexibility. With the rise of distributed teams, Egyptians can now work for companies in Europe, the US, or the Gulf without relocating.

Online businesses and digital products

Another growing path is building online businesses that sell globally. Egyptians are creating e-commerce stores, SaaS platforms, digital templates, courses, ebooks, and subscription communities. Platforms like Shopify, Amazon, Etsy, and Gumroad make it easier to reach international buyers and collect payments in USD.

Digital products are especially attractive because they scale without physical inventory. A single course, template, or software tool can generate recurring income over time. Many creators also combine content creation with product sales, turning audiences into customers through email lists and social media funnels.

Tutoring, coaching, and consulting

Online tutoring/coaching is another strong income stream. Egyptians teach languages, academic subjects, fitness, business skills, and professional certifications to global students. Platforms like Preply, Italki, and Zoom-based private sessions allow educators to charge hourly rates in foreign currency.

Consulting is the higher-income version of this path. Professionals with experience in marketing, finance, HR, or tech offer advisory services to international startups and small businesses. These services often pay significantly more per hour than traditional jobs in Egypt.

Also read: How to open a UK bank account remotely from Egypt

How to receive money online from Egypt

Payoneer

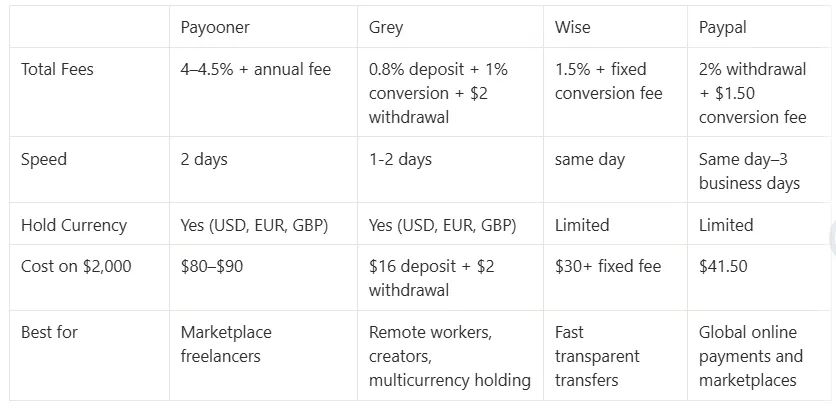
Payoneer remains one of the most widely used payment platforms among Egyptian freelancers and remote workers. It provides users with virtual receiving accounts in USD, EUR, and GBP, making it easier to receive payments from international clients, freelance marketplaces, and global companies. Funds can then be withdrawn directly into Egyptian bank accounts. Payoneer typically applies combined conversion and withdrawal charges of about 4–4.5%, which can significantly affect larger payouts over time. The platform also charges an annual maintenance fee of $29.95, although this fee is waived for users processing at least $100 in yearly transactions. Its global acceptance remains one of its strongest advantages for freelancers earning internationally.

Grey

Grey is becoming increasingly popular among Egyptians receiving payments from abroad because of its multicurrency flexibility and cleaner fee structure. Users can receive, hold, and manage USD, EUR, or GBP balances within one account before sending to their local accounts when they prefer. This gives users greater control over exchange timing instead of relying on automatic bank conversions. Grey charges a 0.8% deposit fee depending on funding method, while currency conversion costs 1%, capped at $6. Compared to traditional banking routes, this structure makes costs more predictable for freelancers, creators, remote workers, and online business owners receiving regular international payments from clients and global platforms.

Wise

Wise is widely recognised for transparent pricing and exchange rates that closely match the real mid-market rate. Egyptians can receive payments in foreign currencies such as USD and transfer funds directly into local bank accounts with fewer hidden markups than many traditional providers. Wise generally charges around 1.5% plus a small fixed conversion fee depending on the currency route and payout method selected. One of its strongest advantages is clarity, allowing users to see the exact conversion rate and total charges before confirming transactions. This makes Wise particularly attractive to freelancers, consultants, and remote professionals who prioritise predictable international payment costs and fast transfer processing.

PayPal

PayPal remains one of the most globally recognised online payment platforms and is commonly used by freelancers, online sellers, and creators receiving international payments. However, withdrawing funds into Egyptian bank accounts can become expensive due to combined withdrawal and conversion costs. PayPal charges approximately 2% for withdrawals, while USD account conversion fees can add another $1.50, and exchange rate markups can reduce the final amount received. Despite these costs, many people still use PayPal because of its global acceptance and compatibility with international websites, marketplaces, and digital services. It is especially common among beginners entering freelance or online business work for the first time.

How the platforms compare

__wf_reserved_inherit

The cheapest platform is not always the one with the lowest visible fee. Focus on how much finally reaches your Egyptian account after conversion, withdrawal, and hidden FX costs. If you receive payments regularly, even small percentage differences across platforms can save or cost you hundreds of dollars yearly.

Also read: How freelancers in Egypt earn and store foreign currency

How to avoid losing money when receiving payment online in Egypt

Look at what you actually receive

Do not focus on “zero fee” claims when receiving money online in Egypt. Many platforms hide costs inside exchange rates. A service may charge no visible fee but apply a 2%–3% conversion margin, reducing your final USD value more than a small fixed charge. Always compare the actual amount credited to your account from the same payment.

Watch the conversion rate before cashing out

Money received online is often held in USD before conversion into Egyptian pounds. Rates change daily, and timing affects your payout. On a $1,000 payment, even a 1% difference equals $10 lost or gained. If your platform allows holding balances, compare rates before converting instead of accepting automatic conversion.

Use timing to your advantage when converting funds

If your platform allows you to hold funds in USD or other currencies, avoid immediate conversion. Waiting for better rates before withdrawing into Egyptian pounds can improve your final payout. For regular online earners, this simple timing habit reduces long-term losses without needing to predict currency movements.

Frequently asked questions

What is the cheapest way to receive money online in Egypt?

The cheapest option depends on volume and frequency. For larger incoming payments (around $1,000+), platforms that offer low conversion fees and capped charges like Grey can reduce total cost because the effective percentage drops. For smaller or frequent receipts, instant platforms like Wise or PayPal alternatives may feel easier, but exchange rate margins often determine the real cost. Always compare the final USD or EGP amount credited, not just the fee.

How long does it take for international payments to reach Egypt?

Speed depends on the provider and payout method. Fintech platforms like Wise typically settle within minutes to 1 business day. Grey processes payments within 1–2 business days, depending on the route used. Traditional SWIFT bank transfers can take 2–5 business days due to intermediary banks and compliance checks. Cash-based services like Western Union can be instant, but are less common for online earnings.

Can I receive money in USD and convert it later in Egypt?

Yes, but only with certain platforms. Many services convert funds immediately into Egyptian pounds upon receipt, limiting control over timing. Platforms like Grey allow you to hold USD, EUR, or GBP balances before converting. This gives you the flexibility to choose better exchange rates instead of accepting automatic conversion at a weaker rate, improving your final payout.

What documents do I need to receive international payments in Egypt?

For most online payment platforms, basic KYC is required, such as a national ID and proof of address. For higher-value or frequent transactions, providers may request additional information like the source of funds, invoices, or the purpose of payment. This ensures compliance with international AML rules and Egyptian banking regulations governing foreign currency inflows.

Why do two people receiving the same amount get different payouts in Egypt?

Because payment routes differ. One transaction may pass through SWIFT banks with FX spreads and intermediary deductions, while another uses fintech platforms with tighter rates. Timing also matters, exchange rates fluctuate daily. Even when the original amount is identical, the final EGP or USD received can vary based on fees, conversion points, and processing channels.

Also read: Freelance platforms with high payout rates in Egypt

Managing online earnings with Grey

Earning foreign currency is only half the equation. You need to find a way to manage your international earnings without incurring high transfer fees or forced conversions when receiving payments through traditional banks or some digital wallets. Grey is a leading payment platform that helps Egyptians earn globally by offering foreign currency accounts, competitive exchange rates, and easy local withdrawals. You can also get a virtual USD debit card to manage your online payments without stress.

Sign up on Grey or download the app to manage your foreign currency payments and protect your income.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN, 0.5% for EUR/GBP (minimum €2/£2, maximum €10/£10), and $2 for Egypt. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction. Visit grey.co/pricing for current rates.

‍

Arrow (up)

Back to top

