<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026#article","headline":"How Fiverr freelancers in Nigeria can receive payments easily in 2026","description":"Learn how Grey helps Nigerian freelancers get paid smoothly through Fiverr","inLanguage":"en","url":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026","mainEntityOfPage":{"@id":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026#webpage"},"datePublished":"2024-12-19T08:40:26.758Z","dateModified":"2026-06-01T10:10:54.730Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6763dbca7860f72872c03508_How%20Fiverr%20freelancers%20in%20Nigeria%20can%20receive%20payments%20easily%20in%202025%20(1).webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6763dbca7860f72872c03508_How%20Fiverr%20freelancers%20in%20Nigeria%20can%20receive%20payments%20easily%20in%202025%20(1).webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026#webpage","url":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026","name":"How Fiverr freelancers in Nigeria can receive payments easily in 2026","description":"Learn how Grey helps Nigerian freelancers get paid smoothly through Fiverr","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How Fiverr freelancers in Nigeria can receive payments easily in 2026","item":"https://grey.co/blog/how-fiverr-freelancers-in-nigeria-can-receive-payments-easily-in-2026"}]}] </script>

How Fiverr freelancers in Nigeria can receive payments easily in 2026

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

Updated: January 2026

In Nigeria, Fiverr has opened up global opportunities for creatives, writers, developers, and marketers, enabling them to work with clients worldwide and earn in foreign currencies. However, as exciting as this is, navigating international payments can feel like a hurdle — one that Grey helps you overcome seamlessly.

In this guide, we’ll show you how freelancers in Nigeria can easily use Grey to receive Fiverr payments.

Why Nigerian freelancers use Grey for Fiverr payments

  1. Receive payments in multiple currencies: With Grey, you can receive Fiverr earnings in USD, GBP, or EUR directly into your virtual foreign account. This eliminates the limitations of naira-only transactions and makes working with international clients even smoother.
  2. Save money on fees: Grey offers lower transaction fees, ensuring you get the most out of your earnings.
  3. Faster access to funds: Grey processes your payments quickly, so you can access your funds without delay.
  4. Competitive exchange rates: Enjoy favourable exchange rates that maximise the value of your earnings when converted to NGN.

Also read: How to receive payments from Fiverr in Nigeria

How to connect Fiverr with Grey payments

  1. Open a Grey account
    • Visit the Grey website and sign up for a free account.
    • Gain access to virtual multi-currency accounts in USD, GBP, and EUR.
  2. Update your Fiverr payment details
    • Log in to Fiverr, navigate to your payment settings, and add your Grey account details.
    • Fiverr will process your withdrawals directly into your Grey account.
  3. Withdraw and convert your funds
    • Once your payment lands in your Grey account, you can convert it to naira and transfer it to your local bank account instantly.

Also read: How to send money to Nigeria in time for Christmas

Thriving as a freelancer in Nigeria

In 2026, platforms like Fiverr will enable Nigerians to earn in foreign currencies, while solutions like Grey make accessing those earnings seamless.

Sign up for Grey today and take full control of your freelancing income.

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

9 best platforms to earn US dollars in India

•

•

2 min read

You do not need to relocate to earn in dollars. Thousands of Indians are already doing it, working remotely for US companies, freelancing on global platforms, selling digital products, and teaching online. The platforms exist. The demand for Indian talent exists. The only question is how you set yourself up to earn, receive, and keep more of that income.

This guide covers the best platforms to earn US dollars in India, the types of work that pay in USD, and how to withdraw your earnings to your Indian bank account without incurring steep conversion fees or slow bank transfers.

Why earning in USD makes sense for Indians

The Indian rupee has depreciated consistently over the past decade, and inflation continues to pressure salaries and savings. At the same time, global demand for digital services in development, design, writing, marketing, and education continues to grow. Earning in a stable currency like USD gives you a structural advantage.

Beyond currency stability, dollar income gives you stronger purchasing power for international tools, courses, and subscriptions. It gives you better returns when saving or investing. And it gives you more control over when and how you convert, so you can time your conversions around exchange rate movements instead of being forced into bad rates by your bank.

What kind of work pays in USD from India?

Indians are earning dollars in more ways than most people realise. Some of the most common paths include:

  • Freelancing: Writing, web development, video editing, translation, graphic design, and digital marketing on platforms that connect you with international clients.
  • Remote contract jobs: Especially with US-based startups that hire globally for engineering, product, operations, and customer support roles.
  • Online tutoring and teaching: Conversational English, test prep (SAT, GRE, GMAT), and academic subjects through platforms that pay per session or per minute in USD.
  • Content creation: YouTube ad revenue via AdSense, Instagram Reels bonuses, podcast sponsorships, and newsletter monetisation.
  • Selling digital products: Online courses, design templates, printables, stock photography, and music through global marketplaces.
  • Affiliate marketing and dropshipping: Promoting international products and earning commissions in USD.
  • User testing and surveys: Getting paid to review websites, apps, and prototypes for US companies.

Whatever your skill set, there is likely a global market for it, and platforms to help you access it. If you are freelancing for international clients, Grey also lets you invoice clients abroad directly from the app.

Top platforms to earn US dollars in India

Here are 9 platforms Indians use to get paid in USD, with practical details on how each works.

1. Upwork

Upwork is one of the largest freelance marketplaces globally, and Indian professionals regularly secure contracts with US and European clients across fields such as software development, writing, design, data analysis, and virtual assistance. Upwork pays in USD and lets you withdraw via direct bank transfer, PayPal, Payoneer, or wire transfer.

The platform takes a sliding service fee: 20% on the first $500 with each client, dropping to 10% after that, and 5% after $10,000. Long-term contracts are where the real value is. Once you build a relationship with a client and move past the initial fee bracket, Upwork becomes significantly more cost-effective than other platforms.

Best for: Developers, writers, designers, VAs, and marketers with at least some portfolio work to show.

2. Fiverr

Fiverr works differently from Upwork. Instead of bidding on projects, you list fixed-price services ("gigs") and buyers come to you. This suits creatives and service providers who prefer packaging their skills into clear deliverables, such as logo design, video editing, voiceover work, social media management, or website builds.

Fiverr takes a flat 20% commission on every order. Earnings are in USD and can be withdrawn via PayPal, bank transfer, or Fiverr Revenue Card. The key to earning well on Fiverr is niche positioning and strong reviews. Generic gigs get buried.

Best for: Designers, video editors, voiceover artists, and anyone who can package a service into a clear deliverable.

3. Toptal

Toptal is a premium platform that accepts only the top 3% of applicants in software engineering, design, and finance. The vetting process is rigorous (multiple interviews and a test project), but the payoff is access to high-quality, well-paying contracts with major companies. Rates are significantly higher than general freelance platforms, often $60-$150+/hour depending on the role.

Best for: Experienced developers, designers, and finance professionals who can pass the vetting process and want premium rates.

4. Amazon KDP (Kindle Direct Publishing)

If you can write, Amazon KDP lets you self-publish eBooks, paperbacks, and low-content books (journals, planners, workbooks) and earn royalties in USD. Royalties range from 35% to 70%, depending on pricing and distribution. The income is passive once a book is published, and some Indian authors have built meaningful monthly income streams with a catalog of 10-20 books in specific niches.

Best for: Writers, educators, and anyone willing to learn self-publishing. Works well as a side income that compounds over time.

5. YouTube Partner Program

Once your channel hits 1,000 subscribers and 4,000 watch hours (or 10 million Shorts views), you can monetise through Google AdSense. Ad revenue is paid in USD. Indian creators in English-language niches (tech reviews, personal finance, education, productivity) tend to earn higher CPMs than Hindi-language content because advertisers pay more for English-speaking audiences.

Best for: Creators with a niche, consistency, and willingness to build an audience over 6-12 months before meaningful income kicks in.

6. Cambly

Cambly pays you to teach conversational English to learners worldwide. There is no lesson prep required; you simply have conversations. Pay is $0.17/minute ($10.20/hour), paid weekly via PayPal. The sessions are casual and unstructured, which makes it one of the lowest-effort ways to earn USD if you are a fluent English speaker.

Best for: Fluent English speakers looking for flexible, low-commitment side income. Particularly popular with students and professionals with flexible schedules.

7. Teachable and Gumroad

If you have expertise in any subject, you can package it as an online course (Teachable) or as a digital product, such as templates, guides, or design assets (Gumroad). Both platforms serve a global audience and pay in USD. Earning potential scales with your audience and your marketing. Some Indian creators earn $1,000-$5,000+/month from a single well-positioned course.

Best for: Subject matter experts, designers, and educators who can build or already have an audience to sell to.

8. UserTesting and TryMyUI

These platforms pay you to test websites and apps and share your feedback via screen recording. Each test takes 15-20 minutes and pays $4-$10 (UserTesting pays $10 for most tests). Availability depends on your demographic profile matching what companies need, so it works best as supplemental income rather than a primary source of income.

Best for: Anyone with clear English communication skills and a computer with a microphone. Good for side income between other work.

9. Etsy

Even without shipping physical products, you can sell digital downloads on Etsy: printable planners, resume templates, wedding invitations, digital art, and social media templates. Etsy charges a $0.20 listing fee plus a 6.5% transaction fee. Earnings are in USD. The platform has a built-in audience of buyers searching for these products, so you do not need to drive your own traffic.

Best for: Designers and creatives who can produce templates or digital art. Works well as passive income once listings are live.

Also read: Best way to receive euros in India

How to actually receive your USD earnings in India

Landing a client or getting approved on a platform is only half the problem. Withdrawing your earnings to India is where most people lose money.

Traditional Indian banks typically charge 1.5-3% on foreign currency conversion, add wire transfer fees of $15-$30 per transaction, offer exchange rates 2-4% worse than the mid-market rate, take 3-5 business days to process, and require paperwork that slows everything down. PayPal is faster but takes a 3-4% cut when converting USD to INR, in addition to withdrawal fees.

How Grey works for USD earnings in India

Grey gives you a free USD account with US bank details (routing number and account number). You can share these details with clients, connect them to freelance platforms, or use them to receive payments from any US-based source.

Here is how the flow works:

  1. Receive USD: Share your Grey US bank details with your client or platform. Payments arrive as standard ACH transfers.
  2. Hold or convert: Your USD sits in your Grey wallet. No forced conversion. You decide when to move it to INR based on the exchange rate.
  3. Withdraw to India: When you are ready, send to any Indian bank account using the recipient's IFSC code and account number. Grey charges a 1% conversion fee on USD to INR.
  4. Spend in USD: Need to pay for tools, subscriptions, or courses in dollars? Use your Grey virtual USD card to pay directly without converting first.

For a detailed walkthrough with screenshots, see the step-by-step guide to sending money to India. For a full breakdown of costs, check Grey's fees and charges.

Grey vs other ways to receive USD in India

Method Conversion Cost Speed Hold USD?
Grey 1% conversion fee Same day to 1 business day Yes, convert when you choose
Indian bank wire 1.5–3% + wire fee ($15–30) 3–5 business days Requires separate forex account
PayPal 3–4% total (conversion + withdrawal) 1–3 business days Limited, auto-converts
Payoneer Up to 2% + withdrawal fee 2–5 business days Yes, but fees on holding

You can check the current USD-to-INR rate and see the exact amount you would receive using Grey's fee calculator.

Also read: How to receive British pounds in India

Tips to maximise your USD earnings from India

Work directly with clients when possible

Platforms like Upwork and Fiverr take 10-20% in service fees. Once you have built a relationship with a client, consider moving to direct contracts with invoicing. You save the platform fee and get paid faster.

Time your conversions

The USD/INR rate fluctuates daily. If you can hold your dollars in your Grey account and convert when the rate is favourable, you keep more of your earnings. Watch exchange rate trends and convert in batches rather than converting every payment immediately.

Diversify your income sources

Relying on a single platform or client is risky. Combine freelancing with passive income (KDP, digital products) or side income (tutoring, user testing) to stabilise your cash flow.

Track everything

Use a simple Google Sheet or Notion database to track invoices, payment dates, conversion rates, and net INR received. This helps you understand your effective hourly rate across platforms and makes tax filing easier.

Understand the tax implications

Income earned in USD is taxable in India. Freelance income falls under "Income from Business and Profession" and is subject to your applicable income tax slab. You can deduct legitimate business expenses (software, equipment, and internet). If your gross receipts exceed Rs 50 lakh, you may need a tax audit. Consult a CA who understands freelance and foreign income if you regularly earn in USD.

This article is intended for general guidance and does not replace professional tax advice. Readers should consult a chartered accountant for personalised recommendations.

Start earning and receiving USD today. Open a free Grey account and get US bank details you can share with clients and platforms immediately.

Frequently asked questions

How can I earn US dollars from India?

You can earn USD from India through freelancing platforms (Upwork, Fiverr, Toptal), teaching English online (Cambly), selling digital products (Amazon KDP, Gumroad, Etsy), content creation (YouTube), and user testing (UserTesting). Most of these platforms pay in USD and allow you to withdraw to an Indian bank account or a USD account like Grey.

How do I receive USD payments in India?

You can receive USD payments through a Grey USD account, which gives you US bank details (routing number and account number) to share with clients or platforms. When you are ready to withdraw, you can send the funds to any Indian bank account using the recipient's IFSC code and account number. Grey charges a 1% conversion fee.

Is it legal to earn in USD from India?

Yes. Earning foreign currency for services rendered from India is legal under FEMA (Foreign Exchange Management Act) guidelines. You are required to declare the income for tax purposes, and it is taxable under the Indian income tax law based on your slab rate.

Which platform pays the most for freelancers in India?

Toptal pays the highest rates (often $60-$150+/hour) but only accepts the top 3% of applicants. For most freelancers, Upwork offers the best balance of volume and rate, especially once you move past the initial 20% fee bracket with repeat clients.

How do I avoid losing money on USD to INR conversion?

Avoid using traditional bank wires (1.5-3% markup) or PayPal (3-4% total cost). Use a platform like Grey that charges a transparent 1% conversion fee and lets you hold USD until the exchange rate is favourable. Check the exact amount you would receive using the fee calculator before converting.

Can NRIs use Grey to receive USD?

Grey provides USD accounts that NRIs can use to receive payments from US clients or employers. You can hold dollars in the account and send INR to any Indian bank account when you need to transfer money home.

More from Grey:

Visiting Morocco? Here’s how to avoid ATM issues and FX losses

•

•

2 min read

Morocco saw a 20% increase in visitors in 2024, driven by major infrastructure investment, improved air connectivity, and its growing reputation as both a cultural destination and a base for digital nomads. From the medinas of Fes to the Sahara dunes near Merzouga, and the Atlantic coast at Essaouira, Morocco offers memorable experiences.

One thing most travel accounts leave out is the currency situation. Getting local currency (MAD) can be tricky because ATMs sometimes run out of cash, especially on weekends and holidays. Withdrawal limits per transaction are low, so it requires multiple trips and multiple fees. Exchange rates at airports and hotels can be 5% to 8% below the mid-market rate. And informal street exchange offers, while sometimes tempting given the quoted rate, carry documented risks of counterfeit notes and short-changing.

This guide covers how to access cash in Morocco without unnecessary cost or frustration, and how to avoid the exchange rate traps that can quietly reduce what your trip costs relative to what it should.

Also read: How to exchange currency safely when visiting Morocco

Understanding Morocco's cash culture

Morocco is predominantly a cash economy outside major urban centres, such as tourist hotels and restaurants in Casablanca, Rabat, and Marrakech. Taxis, street food vendors, souks, small riads, medina shops, and most transport options expect cash payment in Moroccan dirhams (MAD). Cards are accepted at larger establishments and cab-hailing services. But if you assume card payments will always work, you might set yourself up for awkward situations.

The Moroccan dirham is not traded freely, so you cannot buy dirhams at most exchange services outside Morocco, and you cannot easily convert leftover dirhams back to your home currency once you leave Morocco. This means you must plan your cash management carefully before visiting Morocco and while you’re there.

Bank Al-Maghrib sets a reference exchange rate each day. The rates offered by commercial banks and bureau de change operators are derived from this reference rate, which means there is less variation across formal exchange channels than in fully floating currency markets. The differences that do exist come from the fee or spread each institution applies on top of the reference rate.

Some ATM issues you may face in Morocco

ATMs are available across all major cities and tourist centres, and the infrastructure has improved in recent years. The problems are specific and predictable enough that knowing them in advance removes most of the stress.

Cash availability

ATMs at popular tourist sites, busy souks, and small towns run out of banknotes more frequently than in most Western countries. Banks are closed on weekends and may not reload quickly enough if cash is exhausted. Keeping enough cash on hand to cover a day's expenses, rather than planning to withdraw on demand, is the practical solution.

Withdrawal limits

Most ATMs in Morocco cap single withdrawals at 2,000 to 4,000 MAD, which is approximately $215 to $230. For a traveller trying to cover a week's expenses in a single withdrawal, this means multiple transactions and multiple fees. The fee structure typically involves a charge from the Moroccan bank operating the ATM and a foreign transaction fee from your home bank. Most Moroccan banks charge 22–50 MAD (around $2.50 to $5.50) for ATM withdrawals, while your bank likely charges an additional 1.5%–3% international transaction fee, unless you use a travel-friendly card.

Card acceptance

Visa and Mastercard are both widely accepted at ATMs. American Express is less reliably supported outside major hotel cashpoints. Debit cards from European and US banks generally work without issue at the main commercial bank networks.

Dynamic currency conversion (DCC)

This is the most avoidable of the ATM cost problems. When an ATM asks whether you want to be charged in your home currency rather than in dirhams, always choose dirhams. The DCC option uses the ATM operator's exchange rate rather than your bank's. The catch is that the ATM operator rate is typically 5% to 8% worse than your bank's rate. The ATM presents this as a convenience, but it is actually a way for them to make more money.

Also read: Where to buy Moroccan dirham online

The best ATM networks in Morocco

Not all ATMs are equal in terms of fees and reliability. The networks worth prioritising:

Société Générale Maroc runs one of the most reliable ATM networks in Morocco, with machines in major cities and tourist centres. International cardholders typically do not face additional surcharges beyond standard foreign card fees.

Attijariwafa Bank is Morocco's largest commercial bank with the widest ATM network. Machines are generally well-maintained and frequently restocked in urban areas.

BMCE Bank (now Bank of Africa) has a strong urban network and reliably accepts Visa and Mastercard. Some branches have ATMs that process larger withdrawals than the average.

Banque Populaire is another widely distributed network, particularly strong in smaller cities and towns.

Avoid ATMs at airports for anything other than immediate cash needs upon arrival. Airport ATMs typically apply worse exchange rates than city centre machines, and the premium for the convenience of accessing cash immediately on arrival is real.

Where to exchange currency in Morocco

Official bureau de change operators are the most reliable option for exchanging EUR, GBP, or USD to MAD outside of ATMs. They are licensed, regulated, and publicly display their rates. The spread above the mid-market rate typically ranges from 0.5% to 2%, significantly better than airport fees, hotel surcharges, or dynamic currency conversion at ATMs. Bureau de change offices are clustered near major tourist areas, near banks, and in town centres. Always check their posted rate before handing over cash and count your notes before leaving.

Bank branches offer exchange services at rates similar to those of bureau de change operators. The disadvantage is queuing time and branch hours. For small amounts, a bureau de change is faster. For larger amounts, a bank branch provides a more auditable transaction with a receipt.

Hotels and riads offer the worst exchange rates among formal channels, typically 5% to 8% below mid-market. Using hotel exchange as anything other than a last resort for a small emergency amount costs meaningfully more than the alternatives.

Airport exchange booths are similarly expensive, with rates comparable to hotel desks. If you arrive needing immediate cash for transport, exchanging MAD 200 to MAD 300 (approximately €18 to €27) at the airport for a taxi into the city and then finding a bureau de change in the city centre minimises the cost of airport exchange rates.

Street exchanges. The informal exchange market exists in Morocco, particularly around medina entrances and popular tourist areas. The quoted rates are sometimes higher than those in formal channels. The risks are documented and real: counterfeit notes, short-counting, and transactions deliberately designed to confuse and manipulate the amount received. The formal bureau de change system is accessible enough and competitive enough that there is no financial case for accepting the risk of informal exchange.

How digital payment solutions and virtual cards reduce FX losses

Most standard debit and credit cards from US and European banks apply a foreign transaction fee of 1.5% to 3% per international transaction. That fee applies to every individual card payment and every ATM withdrawal, which can add up over time.

Cards issued through multi-currency fintech platforms change this. A card connected to a MAD balance, or to a balance that converts at a competitive disclosed rate, removes the per-transaction foreign fee. The conversion happens once, at a known rate, rather than piecemeal on each transaction.

Grey provides a virtual Visa card linked directly to your foreign-currency accounts in USD, EUR, and GBP. When you convert from a foreign currency to MAD within Grey, the rate is shown before confirmation and conversions are charged at 1%. Apple Pay and Google Pay are supported in eligible regions for contactless payments. Multiple cards can be created for different spending purposes, each with its own limit. Withdrawals to a local MAD account cost $2.

Grey charges fees on deposits, conversions, withdrawals, and cross-border card transactions. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%. Exchange rates are variable and include a margin over the mid-market rate. Always review the rate before confirming a transaction. Visit https://grey.co/blog/fees-and-charges-on-grey for current rates.

Comparing the best ways to get and send MAD in Morocco

Method Typical Cost / Spread (over mid-market) Convenience Safety & Reliability Best For
Official Bureau de Change (City centres) 0.5% – 2% High (fast, widespread in tourist areas) Very High (licensed & regulated) Cash exchange of EUR, USD, GBP
Bank Branches 1% – 3% + possible small commission Medium (limited hours, queues) Highest (official receipt) Larger amounts, need receipt
International ATM Card (Traditional bank card) 2% – 5%+ (FX fee 1.5-3% + ATM fee ~35 MAD + possible DCC) High (24/7 availability) High Small to medium cash withdrawals
Grey Virtual Card / Multi-currency 1% conversion  + $2 withdrawal to MAD account Very High (digital, instant) High (regulated fintech + virtual cards) Online payments, controlled spending, holding foreign currency
Hotels / Riads 5% – 10% Very High (on-site) High Emergency small amounts only
Airport Exchange Booths 3% – 8%+ (often 8-15% worst case) High on arrival High (official) Very small emergency cash (taxi)
Street / Informal Exchange Sometimes better quoted rates Very High Very Low (counterfeit risk, short-changing) None (not recommended)

How to avoid foreign exchange losses in Morocco

A few habits that consistently reduce currency costs and ATM friction for Morocco visitors:

  • Withdraw larger amounts less frequently rather than small amounts on demand. Even if the per-transaction fee is fixed, two withdrawals of MAD 2,000 each cost twice the fee of a single withdrawal at the daily limit.
  • Keep cash in MAD rather than converting back to your home currency at the end of the trip. The Moroccan dirham cannot be reconverted abroad through most channels, and Morocco's own departure exchange rates are no better than arrival rates. Spend what you have or donate the remaining small amount.
  • Notify your home bank of travel dates before departure. Bank fraud systems that flag unusual geographic activity are the most common reason cards are declined at Moroccan ATMs for travellers whose banks operate aggressive fraud monitoring. A brief call or app notification before travel prevents this entirely.
  • Use ATMs in public areas during daylight hours rather than late at night in isolated locations. Basic safety practices apply in most countries, including Morocco.
  • Keep a small cash reserve separate from your main wallet. Pickpocketing is not widespread in Morocco but does occur in busy medina areas. Having MAD 200 to MAD 300 accessible separately from the rest of your cash means losing your wallet does not mean being entirely without funds.

Frequently asked questions

Can I use my credit card for most payments in Morocco?

Cards are accepted at major hotels, upmarket restaurants, larger shops, and some tourist sites, but Morocco's economy outside these settings is cash-based. Taxis, street food, souks, small guesthouses, and most everyday transactions require dirhams in cash. Relying on card payment without carrying adequate cash creates practical problems in Morocco that would not arise in most Western European countries.

How much Moroccan dirham should I bring or withdraw at the start of my trip to Morocco?

A useful starting point for a typical tourist visit is MAD 500 to MAD 800 per day for moderate spending on food, transport, entry fees, and shopping. For a seven-day trip, having MAD 3,500 to MAD 5,600 accessible without relying on multiple ATM visits is comfortable. Withdrawing a larger amount at once from a reliable ATM in a city centre, rather than making daily small withdrawals, reduces total ATM fees.

Is it safe to use ATMs in Morocco?

ATMs operated by major licensed Moroccan banks are generally safe. Skimming devices, which criminals attach to ATM card readers to steal card data, are less common in Morocco than in some other tourist destinations, but do exist. Using ATMs inside bank branches or in well-lit, high-traffic locations reduces risk. Covering the keypad while entering your PIN is standard practice regardless of location.

What is the best exchange rate I can realistically get in Morocco?

The best rate available to tourists through formal channels is typically the bureau de change rate, which is 0.5% to 2% below the mid-market rate shown on Google or XE. Bank branches offer comparable rates. Fintech platforms that convert foreign currency to MAD at disclosed rates, with fees shown before confirmation, are competitive with the best bureau de change rates and offer the advantage of being accessible from anywhere, without needing to physically visit an exchange office.

—

Ready to visit Morocco without worrying about ATM issues? Sign up on Grey today or download the mobile app to avoid FX losses when visiting Morocco.

‍

Top travel destinations to visit in South Africa

•

•

2 min read

Planning a trip to South Africa? With its wild savannahs, iconic coastlines, and vibrant cities, this country delivers more than just postcard view. It gives you a mix of culture, adventure, and unforgettable memories. But with so many incredible places to visit, choosing where to go can feel like a lot.

Don’t worry, we’ve made it easier.

In this article, we’ll walk you through six of the top destinations to add to your South Africa itinerary. From the cost of visiting each location to the must-do activities and travel tips, you’ll have everything you need to start planning your adventure.

Read also: Hidden travel gems to explore in South Africa this summer

1. Cape town

Cape Town is a vibrant coastal city known for its breathtaking landscapes, rich culture, and iconic landmarks. Nestled between mountains and ocean, it offers the perfect blend of adventure, relaxation, and history. From Table Mountain to Robben Island, this city has something for everyone, whether you're a foodie, a hiker, or a history lover.

__wf_reserved_inherit

Best things to do:

  • Take the cable car up Table Mountain for panoramic views.
  • Explore Robben Island, where Nelson Mandela was imprisoned.
  • Stroll through the V&A Waterfront for shopping, dining, and live music.

2. Kruger national park

Kruger is one of Africa’s largest and most famous game reserves. Home to the Big Five, it offers an unforgettable safari experience. With a mix of self-drive and guided tours, you can get up close with lions, elephants, rhinos, and more ideal for nature lovers and wildlife photographers.

__wf_reserved_inherit

Best things to do:

  • Go on a sunrise or sunset game drive.
  • Visit a waterhole to watch animals gather.
  • Stay overnight in a bush lodge for an immersive experience.

Read also: Top 7 must-visit historical sites in South Africa

3. The Garden route

The Garden Route is a stunning stretch along South Africa’s southern coast, filled with coastal towns, forests, and lagoons. Perfect for road trippers, it offers a mix of adventure, relaxation, and natural beauty. The scenic drive between Mossel Bay and Storms River is truly one of the world’s great journeys.

__wf_reserved_inherit

Best things to do:

4. Durban

Durban is South Africa’s warm, beach-loving city with strong Indian and Zulu influences. Famous for its golden beaches and spicy street food, it’s a hub for surfing, culture, and casual fun. The tropical climate makes it a great destination all year round, especially for sun seekers.

__wf_reserved_inherit

Best things to do:

  • Walk or cycle along the Golden Mile.
  • Try authentic Durban curry at a local market.
  • Visit uShaka Marine World for family-friendly adventure.

5. Johannesburg

Johannesburg, South Africa’s largest city, is the heart of its economy and culture. Often called Jozi or Joburg, it's rich in history and modern flair. The city is home to world-class art galleries, bustling markets, and powerful museums that reflect South Africa’s complex past and vibrant present.

__wf_reserved_inherit

Best things to do:

  • Visit the Apartheid Museum for deep historical insight.
  • Explore Maboneng Precinct for arts, cafes, and nightlife.
  • Take a guided tour of Soweto, including Vilakazi Street.

Read also: How to obtain a South Africa business visa

6. Drakensberg Mountains

The Drakensberg range offers some of South Africa’s most dramatic scenery. With soaring peaks, ancient rock art, and crystal-clear rivers, it’s a haven for hikers and nature enthusiasts. Whether you want a quiet retreat or a high-altitude adventure, the Drakensberg delivers.

__wf_reserved_inherit

Best things to do:

  • Hike to the top of Amphitheatre or Tugela Falls.
  • Discover San rock art in secluded caves.
  • Relax in a mountain lodge with spectacular views.

Travel smart with Grey

From safaris to coastlines, South Africa offers unforgettable adventures. With Grey, you can pay for hotels, tours, and travel essentials securely and without hidden fees. Travel smarter and stress-free. Sign up today or download the Grey app to make your next trip smooth from start to finish.

‍

How to avoid hidden FX fees as a remote worker in Kenya

•

•

2 min read

Kenyan remote workers already know that landing international gigs is only half the journey. It takes hours of pitching to clients, navigating tricky time zones, and pushing through tight deadlines, all with the hope that the hard work eventually pays off. And when the payment finally arrives, you expect to feel relieved.

But instead, you're left doing the math, wondering where a chunk of your money disappeared to. After the currency conversion, the amount that lands in your account is far less than what you had in mind. It feels like you're being shortchanged for work you poured your energy into.

Grey helps Kenyan freelancers receive foreign payments, convert at real-time rates, and withdraw with no hidden charges, so you can focus on your work and earn what you truly worked for.

Read also: How freelancers in Kenya can receive payments from US, UK & EU clients.

The impact of hidden FX fees on Kenyan remote workers

  1. Lower take-home pay: No matter how much your client pays you in USD, GBP, or EUR, hidden FX fees silently reduce your take-home income. You may think you’re earning $1,000, but after conversions, deductions, and bank fees, you might end up with far less.
  2. Harder to save: With every transaction eating into your money, it becomes tougher to build savings or reinvest in tools that grow your work.
  3. Less trust in global gigs: The stress of losing money to FX fees can make you second-guess working with international clients, limiting your earning potential.
  4. Difficult money planning: Hidden fees create uncertainty. If you don’t know exactly how much you'll receive or when it will arrive, it makes budgeting, paying bills, or investing in your goals more difficult.

Read also: How to receive foreign payments in Kenya as a freelancer or remote worker.

How traditional banks make FX expensive for Kenyan freelancers

  1. Hidden deductions: Most banks don’t tell you exactly what you’re paying. Instead of showing a clear FX fee, they give you a weaker exchange rate and keep the difference.
  2. Old systems: Traditional banks still run on legacy systems built for large corporations. They're slow, complicated, and not designed for freelancers or remote workers. That’s why your money takes days to reflect and comes with layers of charges.
  3. Middlemen: When your client sends money from abroad, it doesn’t come straight to your bank. It goes through several intermediary banks, each one taking a small cut. By the time it gets to your account in Kenya, what’s left can be disappointing.
  4. No flexibility: Most banks don’t let you hold USD, GBP, or EUR. They convert your money automatically to KES at poor rates, giving you no choice or control over the value of your income.

How Grey helps Kenyan freelancers beat FX fees

  1. Receive like a local with foreign accounts: Grey gives you access to UK, US, and EU bank accounts so that you can receive money in GBP, USD, or EUR directly. No third parties, no wire deductions.
  2. Convert at better rates: Grey uses mid-market exchange rates and shows you exactly how much you’ll get before you convert. No hidden margins, no bad surprises.
  3. Get paid faster: Clients can send payments directly to your Grey account. No long waits, no excuses, just quicker access to your money.
  4. Easy local withdrawals: Once you’ve converted your funds, you can withdraw directly to your M-Pesa or local bank account in Kenya. Fast, reliable, and easy.

The smarter way for Kenyan remote workers to get paid

Grey gives Kenyan freelancers exactly what they need: real-time currency conversion with full transparency and no hidden charges. You earn in USD, GBP, or EUR, convert at fair rates, and withdraw easily into your local account. With Grey, you save more, earn what you truly worked for, and finally take control of your international payments.

Sign up on Grey today and keep more of your hard-earned income.

‍

The best way to receive euros in Algeria

•

•

2 min read

A freelancer has just finished a project for a client in Paris, and a message comes in: payment sent in euros. For a moment, it feels like everything has worked.

By the next morning, a different question takes over. How does that €300 or €500 actually reach Algeria without being reduced from what was originally sent?

That question is not unusual. It reflects a wider reality for many people working remotely in Algeria today, especially those earning from Europe, where getting paid is straightforward, but receiving the money locally is not always as smooth.

This article explains the best ways to receive euros in Algeria, what affects the amount you keep, and how to avoid unnecessary losses during the process.

Challenges of receiving Euros from Algeria

Receiving euros in Algeria is often more complex than it appears. While international payments are possible, individuals and freelancers frequently face structural barriers that affect how quickly, and how much, they actually receive.

Official vs. black market rates

One of the most significant challenges is the gap between official exchange rates and the informal “square” market rate. When euros are processed through official banking channels, they are converted at the government-regulated rate, which can be up to 30% lower in real purchasing power compared to the parallel market. This creates a hidden loss for recipients, especially freelancers and remote workers who depend on foreign income. While the official system is legal and secure, the financial trade-off often feels substantial and discouraging.

Also read: The ultimate digital bank account for freelancers in Algeria

Currency conversion pressure

In many cases, euros sent into Algerian bank accounts are automatically converted into Algerian Dinars (DZD) upon arrival. This means recipients may not have the flexibility to hold or manage their funds in foreign currency. For individuals working with international clients, this reduces financial control and limits the ability to save in a stable currency. It also exposes earnings to local inflation and exchange rate fluctuations, which can affect long-term financial planning and stability.

Bureaucracy and delays

Bank transfers in Algeria are often subject to strict regulatory checks, which can result in long processing times. It is not uncommon for payments to be delayed for weeks or even months while banks request documentation such as invoices, contracts, or proof of income source. Although these measures are designed to prevent fraud and ensure compliance, they can create frustration for recipients who rely on timely payments for living expenses or business operations. The uncertainty can also make cash flow planning difficult.

Limited receiving options

Another key challenge is the limited range of formal channels available for receiving euros. Many international payment platforms either do not operate fully in Algeria or offer restricted services. As a result, individuals often rely on traditional bank transfers, which are slower and less flexible. This lack of diversified payment infrastructure reduces choice and can push users towards informal or less secure alternatives. It also slows down the integration of Algerian freelancers into the global digital economy.

Platforms to receive euros from Algeria

Receiving euros in Algeria is increasingly possible through digital platforms that simplify cross-border payments, reduce friction, and give users more control over how they access and convert funds.

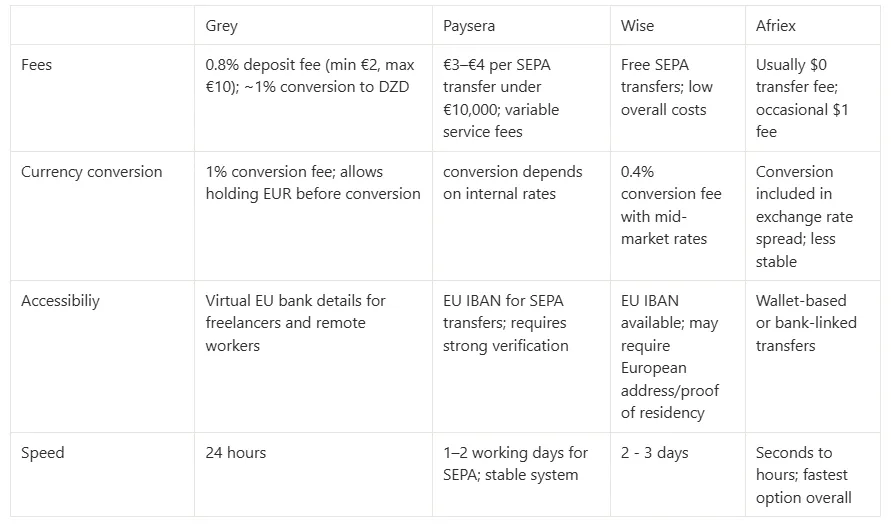
Grey

Grey allows users to receive euros into a digital account with virtual European banking details, making it suitable for freelancers and remote workers. Deposit channels such SEPA, and FPS typically attract a 0.8% fee, with a minimum charge of €2 and a maximum cap of €10, depending on transaction size. When converting euros to Algerian dinars, a 1% conversion fee is applied. This structure makes costs relatively predictable, while still giving users flexibility to hold euros before converting. Processing times are generally fast, supporting quicker access to funds compared to traditional banks.

Paysera

Paysera provides users with a European IBAN, enabling direct receipt of euros via SEPA transfers from clients or businesses across Europe. Incoming payments are generally charged between €3 and €4 for transactions below €10,000, making it cost-effective for moderate inflows. Users can keep funds in euros within the account, avoiding automatic conversion and giving more control over timing. However, additional fees may apply when withdrawing or transferring funds to other currencies. The platform is widely used for its stability, though verification requirements and compliance checks can extend onboarding time.

Wise

Wise supports multi-currency accounts, allowing users to receive, hold, and convert euros at low and transparent costs. SEPA transfers into Wise accounts are usually free, making it attractive for regular euro inflows. Currency conversion to Algerian dinars typically carries a low fee of around 0.4%, applied transparently using mid-market exchange rates. Users benefit from clear pricing without hidden spreads, helping them understand exact costs before transactions. However, full account functionality may require a European address and proof of residency, which can be a limitation for some users in Algeria.

Afriex

Afriex is designed for fast, low-cost international transfers, particularly across Africa and diaspora payment routes. Most transfers are free, though a small fee of around $1 may apply depending on the transaction type or corridor used. The platform focuses on speed, with many transactions processed almost instantly or within a few hours. Conversion rates are generally competitive, with costs embedded in the exchange spread rather than explicit charges. While convenient and accessible, features may vary based on user verification level and regional availability.

Comparing platforms to receiving euros in Algeria

__wf_reserved_inherit

When do you need Euros in Algeria?

There are several practical situations in Algeria where holding or receiving euros becomes important, especially for individuals engaged in global work, financial planning, or cross-border transactions.

International expenses

You need euros when paying for international services such as online subscriptions, foreign tuition fees, software tools, or freelance platforms. Many global companies price their services in EUR or USD, making local currency conversion unavoidable. Holding euros helps reduce repeated conversion costs and gives more control over timing payments when exchange rates are favourable. It also ensures smoother payments without delays or card failures when transacting on global platforms regularly.

Portfolio diversification

Euros are useful for diversifying savings beyond the Algerian dinar, which can be exposed to inflation and currency volatility. By holding part of your income in euros, you spread financial risk across currencies. This approach is especially valuable for freelancers and remote workers who earn internationally and want to protect long-term purchasing power. It also provides financial stability during periods of local currency instability and supports better long-term planning for savings and investments.

Wealth preservation

In uncertain economic conditions, euros can serve as a stable store of value amid local currency fluctuations. Many individuals save in euros to preserve wealth and shield themselves from inflation pressures within the broader African economic environment. It also provides flexibility for travel, investment, or future relocation plans.

Also read: Algeria visa requirements for EU citizens

How to optimise euro payments in Algeria

Optimising euro payments in Algeria requires more than just selecting a platform; it involves building habits that improve consistency and reduce financial leakage over time.

Hold euros before converting

Use platforms that allow you to store euros instead of forcing immediate conversion. This gives you more control over timing and helps you decide when exchange rates are most favourable. Instead of converting at the point of receipt, you can monitor market movements and convert when the rate works better for your income. Over time, this simple flexibility can make a noticeable difference in how much you actually retain from international payments, especially if you are earning consistently in euros.

Consolidate payments

Instead of receiving multiple small payments, try to combine invoices where possible. Each transaction often comes with a fee, and when payments are split, those charges repeat unnecessarily. By consolidating your earnings into fewer, larger payments, you reduce the number of times fees are applied. This improves overall cost efficiency and also makes it easier to track income, manage cash flow, and plan expenses more accurately. It is a small operational change that can significantly improve how much you keep over time.

Compare platforms regularly

Payment platforms are not static. Fees, exchange rates, and processing speeds can change, and new competitors often enter the market with better terms. Regularly reviewing your options ensures you are not locked into outdated or expensive systems. A platform that was cost-effective last year may no longer be the best choice today. By comparing periodically, you stay informed and positioned to move to better options that improve your overall earnings retention and reduce unnecessary losses.

Separate spending and savings

Keep a portion of your income in euros for stability while converting only what you need for local expenses. This approach helps you reduce exposure to currency fluctuations and protects your earnings from sudden naira depreciation. It also encourages better financial discipline by separating operational spending from long-term value storage. Over time, this balance gives you more control, smoother budgeting, and a stronger buffer against inflation risks.

Frequently asked questions

Can I legally receive euros in Algeria through digital platforms?

Yes, you can receive euros in Algeria through regulated digital platforms and international transfer services. However, funds are often subject to local banking rules, documentation checks, and currency controls. While the platforms are legal, the way funds are converted or accessed may still depend on Algerian financial regulations.

Why do I lose money when receiving euros through banks in Algeria?

Losses usually come from currency conversion and exchange rate differences. Banks often apply the official rate, which is lower than the parallel market value. In addition, hidden service fees and automatic conversion to dinars reduce overall value. This gap creates a real difference in purchasing power for recipients.

Is it better to hold euros or convert immediately to dinars?

Holding euros is often more financially strategic, especially during inflation or currency instability. Euros maintain stronger global value compared to local currency fluctuations. However, immediate conversion may be necessary for daily expenses. The best approach depends on your financial goals, urgency of spending, and risk tolerance.

Why are international transfers sometimes delayed in Algeria?

Delays often result from strict compliance checks, anti-money laundering regulations, and documentation requirements. Banks may request invoices, contracts, or proof of income source before releasing funds. While these processes ensure security, they can significantly slow down payments, especially for freelancers who receive frequent international transactions.

Receiving EUR payments from Algeria

Managing international payments from Europe is now easier for freelancers and remote workers in Algeria. Grey provides users with  EUR accounts, complete with European banking details that allow clients to send payments as if they were making a local transfer within the SEPA network. This eliminates unnecessary friction and significantly simplifies cross-border transactions.

You can also manage multiple currencies, including EUR and GBP, all within the same platform, giving you greater control over your earnings. With competitive exchange rates and flexible conversion options, you can decide when and how to convert your funds.

Sign up on Grey and download the app to get your EUR banking details within minutes.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN, 0.5% for EUR/GBP (minimum €2/£2, maximum €10/£10), and $0.50-$0.65 for KES/UGX/TZS. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction. Visit grey.co/pricing for current rates.

All you need to know about Afro Nation 2025

•

•

2 min read

Not all heroes wear capes. Sometimes, they’re just articles you stumble upon on the internet, like this one. It’s wild to think that Afro Nation started just a few years ago, in 2019, and now it’s one of the most anticipated music festivals in the world. Born on the golden beaches of Portimão, Portugal, the idea was bold: a space where Afrobeats, Amapiano, hip-hop, dancehall, and Black diasporic music could be celebrated.

What started as a fairly massive gathering of music lovers quickly snowballed. It became a global pilgrimage for the culture. By the time the Ghana edition hit in December 2019, everyone was talking about it.

Afro Nation festivals happen in multiple countries today. Now, Afro Nation 2025 is on the horizon, and if you’re planning to go, here’s everything you need to know.

Also read: How to apply for a digital nomad visa in Portugal

A quick look back: Afro Nation through the years

  • 2019 - Portugal: The inaugural festival. A sold-out show with over 20,000 people on the beach of Portimão. Burna Boy, Davido, and Wizkid all headlined.
  • 2019 - Ghana: The first African edition. Accra’s beaches turned into a musical haven for the diaspora returning home. Alkaline, Burna Boy, Shatta Wale, Wizkid, Davido and Stonebwoy.
  • 2022 - Portugal returns: After COVID-19 paused the world, Afro Nation made a roaring comeback, bigger than before.
  • 2023 - Expansion: Afro Nation hits Miami and Detroit, bringing African sounds to North American shores.
  • 2024 - Global growth: More cities, more dates, and a bolder lineup with Amapiano taking equal spotlight alongside Afrobeats.

Afro Nation has grown from a one-off dream into a globe-trotting festival series. And the formula stays the same: sun, sand, and the sound of the diaspora.

When and where is Afro Nation 2025?

  • Dates: 9 –11 July 2025
  • Location: Praia da Rocha, Portimão, Portugal

This iconic beach spot is the heart of the festival. Think golden sand, ocean views, and music echoing across the waves from sunset till dawn.

Who’s performing?

The lineup for Afro Nation 2025 is packed with global icons and rising stars:

  • Burna Boy – The African Giant himself, bringing timeless energy and hits.
  • Davido – A fan favourite, known for crowd-pleasing anthems and endless charisma.
  • Mary J. Blige – Yes, the Queen of Hip-Hop Soul joins the stage, showing just how global Afro Nation has become.
  • Tems – Her soulful sound and global appeal are unmatched.
  • Plus dozens more from Afrobeats, Amapiano, Dancehall, and Hip-hop scenes.
Afro Nation 2025 Goes Global with TRACE+ Digital Experience - The Beat  Lagos 99.9FM
Afronation 20225 Lineup

‍

Also read: How to receive and convert foreign currencies to USDC in Portugal

How do you get tickets for Afro Nation 2025?

When tickets drop, it’s a mad dash. You’ll get access via:

  • Afro Nation’s official website
  • Authorised partners listed on the site

There are usually three ticket types:

  • General Admission – festival entry.
  • VIP – faster queues, VIP viewing zones, private bars.
  • Golden Circle – ultra-premium, closest to the stage with VIP perks.

How to prepare for Afro Nation 2025

Tickets:

Pre-sale tickets typically sell out within days. General tickets are released in waves. The earlier you buy, the cheaper it is.

Accommodation:

Portimão is a holiday hotspot, so book accommodation early. Choose between beachfront hotels, Airbnbs, or budget hostels.

Getting there:

The closest airport is Faro, about 60 minutes away by car. You can also fly into Lisbon, then drive or take a train to Portimão.

Festival essentials:

  • Sunscreen (lots of it).
  • Comfortable shoes—you’ll be dancing for hours.
  • Portable charger (your phone will be busy).
  • Light clothing for the heat but something warm for late nights.

How expensive is Afro Nation, and how do you manage money abroad?

It’s not cheap. Here’s a rough breakdown:

  • Tickets: $200–$800 depending on tier.
  • Flights: $400–$1,000+ depending on where you fly from.
  • Hotels: $100–$250 a night in peak season.
  • Spending money: Food, drinks, after-parties, and transport add up.

That’s why smart money management matters. Grey makes it seamless:

  • Open virtual USD, EUR, and GBP accounts from your home country.
  • Pay for tickets, Airbnbs, flights, and festival expenses without poor exchange rates or hidden FX fees.
  • Hold foreign currencies and convert back to your local currency whenever the rates are best.

No need to stress about card declines or bad rates from your home bank while you’re partying on the beach.

Create your Grey account today or download the app to plan your global adventures smartly.

‍

Arrow (up)

Back to top