<script type="application/ld+json" data-schema-version="grey-blog-v4">
[{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#article","headline":"Visiting Morocco? Here’s how to avoid ATM issues and FX losses","description":"Find the best ways to get Moroccan Dirham (MAD) safely and understand Morocco’s cash culture while avoiding high ATM fees and exchange rate traps.","inLanguage":"en","url":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses","mainEntityOfPage":{"@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#webpage"},"datePublished":"2025-06-27T06:09:23.249Z","dateModified":"2026-06-15T14:53:01.396Z","author":{"@type":"Person","@id":"https://grey.co/authors/tunde-aladeloba#person","name":"Tunde Aladeloba","url":"https://grey.co/authors/tunde-aladeloba","jobTitle":"Content Writer","sameAs":["https://ng.linkedin.com/in/aladeloba-babatunde-b1114b100"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3011cdfdca1a64ceb5e896_6a3011ccbdec0e786af65a9b_visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3011cdfdca1a64ceb5e896_6a3011ccbdec0e786af65a9b_visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#webpage","url":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses","name":"Visiting Morocco? Here’s how to avoid ATM issues and FX losses","description":"Find the best ways to get Moroccan Dirham (MAD) safely and understand Morocco’s cash culture while avoiding high ATM fees and exchange rate traps.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Visiting Morocco? Here’s how to avoid ATM issues and FX losses","item":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/visiting-morocco-heres-how-to-avoid-atm-issues-and-fx-losses#faq","mainEntity":[{"@type":"Question","name":"Can I use my credit card for most payments in Morocco?","acceptedAnswer":{"@type":"Answer","text":"Cards are accepted at major hotels, upmarket restaurants, larger shops, and some tourist sites, but Morocco's economy outside these settings is cash-based. Taxis, street food, souks, small guesthouses, and most everyday transactions require dirhams in cash. Relying on card payment without carrying adequate cash creates practical problems in Morocco that would not arise in most Western European countries."}},{"@type":"Question","name":"How much Moroccan dirham should I bring or withdraw at the start of my trip to Morocco?","acceptedAnswer":{"@type":"Answer","text":"A useful starting point for a typical tourist visit is MAD 500 to MAD 800 per day for moderate spending on food, transport, entry fees, and shopping. For a seven-day trip, having MAD 3,500 to MAD 5,600 accessible without relying on multiple ATM visits is comfortable. Withdrawing a larger amount at once from a reliable ATM in a city centre, rather than making daily small withdrawals, reduces total ATM fees."}},{"@type":"Question","name":"Is it safe to use ATMs in Morocco?","acceptedAnswer":{"@type":"Answer","text":"ATMs operated by major licensed Moroccan banks are generally safe. Skimming devices, which criminals attach to ATM card readers to steal card data, are less common in Morocco than in some other tourist destinations, but do exist. Using ATMs inside bank branches or in well-lit, high-traffic locations reduces risk. Covering the keypad while entering your PIN is standard practice regardless of location."}},{"@type":"Question","name":"What is the best exchange rate I can realistically get in Morocco?","acceptedAnswer":{"@type":"Answer","text":"The best rate available to tourists through formal channels is typically the bureau de change rate, which is 0.5% to 2% below the mid-market rate shown on Google or XE. Bank branches offer comparable rates. Fintech platforms that convert foreign currency to MAD at disclosed rates, with fees shown before confirmation, are competitive with the best bureau de change rates and offer the advantage of being accessible from anywhere, without needing to physically visit an exchange office."}}]}]
</script>
Freelancer
•
June 27, 2025
•
8 min read
Visiting Morocco? Here’s how to avoid ATM issues and FX losses
Tunde Aladeloba
TABLE OF CONTENT
SHARE THIS POST
Morocco saw a 20% increase in visitors in 2024, driven by major infrastructure investment, improved air connectivity, and its growing reputation as both a cultural destination and a base for digital nomads. From the medinas of Fes to the Sahara dunes near Merzouga, and the Atlantic coast at Essaouira, Morocco offers memorable experiences.
One thing most travel accounts leave out is the currency situation. Getting local currency (MAD) can be tricky because ATMs sometimes run out of cash, especially on weekends and holidays. Withdrawal limits per transaction are low, so it requires multiple trips and multiple fees. Exchange rates at airports and hotels can be 5% to 8% below the mid-market rate. And informal street exchange offers, while sometimes tempting given the quoted rate, carry documented risks of counterfeit notes and short-changing.
This guide covers how to access cash in Morocco without unnecessary cost or frustration, and how to avoid the exchange rate traps that can quietly reduce what your trip costs relative to what it should.
Morocco is predominantly a cash economy outside major urban centres, such as tourist hotels and restaurants in Casablanca, Rabat, and Marrakech. Taxis, street food vendors, souks, small riads, medina shops, and most transport options expect cash payment in Moroccan dirhams (MAD). Cards are accepted at larger establishments and cab-hailing services. But if you assume card payments will always work, you might set yourself up for awkward situations.
The Moroccan dirham is not traded freely, so you cannot buy dirhams at most exchange services outside Morocco, and you cannot easily convert leftover dirhams back to your home currency once you leave Morocco. This means you must plan your cash management carefully before visiting Morocco and while you’re there.
Bank Al-Maghrib sets a reference exchange rate each day. The rates offered by commercial banks and bureau de change operators are derived from this reference rate, which means there is less variation across formal exchange channels than in fully floating currency markets. The differences that do exist come from the fee or spread each institution applies on top of the reference rate.
Some ATM issues you may face in Morocco
ATMs are available across all major cities and tourist centres, and the infrastructure has improved in recent years. The problems are specific and predictable enough that knowing them in advance removes most of the stress.
Cash availability
ATMs at popular tourist sites, busy souks, and small towns run out of banknotes more frequently than in most Western countries. Banks are closed on weekends and may not reload quickly enough if cash is exhausted. Keeping enough cash on hand to cover a day's expenses, rather than planning to withdraw on demand, is the practical solution.
Withdrawal limits
Most ATMs in Morocco cap single withdrawals at 2,000 to 4,000 MAD, which is approximately $215 to $230. For a traveller trying to cover a week's expenses in a single withdrawal, this means multiple transactions and multiple fees. The fee structure typically involves a charge from the Moroccan bank operating the ATM and a foreign transaction fee from your home bank. Most Moroccan banks charge 22–50 MAD (around $2.50 to $5.50) for ATM withdrawals, while your bank likely charges an additional 1.5%–3% international transaction fee, unless you use a travel-friendly card.
Card acceptance
Visa and Mastercard are both widely accepted at ATMs. American Express is less reliably supported outside major hotel cashpoints. Debit cards from European and US banks generally work without issue at the main commercial bank networks.
Dynamic currency conversion (DCC)
This is the most avoidable of the ATM cost problems. When an ATM asks whether you want to be charged in your home currency rather than in dirhams, always choose dirhams. The DCC option uses the ATM operator's exchange rate rather than your bank's. The catch is that the ATM operator rate is typically 5% to 8% worse than your bank's rate. The ATM presents this as a convenience, but it is actually a way for them to make more money.
Not all ATMs are equal in terms of fees and reliability. The networks worth prioritising:
Société Générale Maroc runs one of the most reliable ATM networks in Morocco, with machines in major cities and tourist centres. International cardholders typically do not face additional surcharges beyond standard foreign card fees.
Attijariwafa Bank is Morocco's largest commercial bank with the widest ATM network. Machines are generally well-maintained and frequently restocked in urban areas.
BMCE Bank (now Bank of Africa) has a strong urban network and reliably accepts Visa and Mastercard. Some branches have ATMs that process larger withdrawals than the average.
Banque Populaire is another widely distributed network, particularly strong in smaller cities and towns.
Avoid ATMs at airports for anything other than immediate cash needs upon arrival. Airport ATMs typically apply worse exchange rates than city centre machines, and the premium for the convenience of accessing cash immediately on arrival is real.
Where to exchange currency in Morocco
Official bureau de change operators are the most reliable option for exchanging EUR, GBP, or USD to MAD outside of ATMs. They are licensed, regulated, and publicly display their rates. The spread above the mid-market rate typically ranges from 0.5% to 2%, significantly better than airport fees, hotel surcharges, or dynamic currency conversion at ATMs. Bureau de change offices are clustered near major tourist areas, near banks, and in town centres. Always check their posted rate before handing over cash and count your notes before leaving.
Bank branches offer exchange services at rates similar to those of bureau de change operators. The disadvantage is queuing time and branch hours. For small amounts, a bureau de change is faster. For larger amounts, a bank branch provides a more auditable transaction with a receipt.
Hotels and riads offer the worst exchange rates among formal channels, typically 5% to 8% below mid-market. Using hotel exchange as anything other than a last resort for a small emergency amount costs meaningfully more than the alternatives.
Airport exchange booths are similarly expensive, with rates comparable to hotel desks. If you arrive needing immediate cash for transport, exchanging MAD 200 to MAD 300 (approximately €18 to €27) at the airport for a taxi into the city and then finding a bureau de change in the city centre minimises the cost of airport exchange rates.
Street exchanges. The informal exchange market exists in Morocco, particularly around medina entrances and popular tourist areas. The quoted rates are sometimes higher than those in formal channels. The risks are documented and real: counterfeit notes, short-counting, and transactions deliberately designed to confuse and manipulate the amount received. The formal bureau de change system is accessible enough and competitive enough that there is no financial case for accepting the risk of informal exchange.
How digital payment solutions and virtual cards reduce FX losses
Most standard debit and credit cards from US and European banks apply a foreign transaction fee of 1.5% to 3% per international transaction. That fee applies to every individual card payment and every ATM withdrawal, which can add up over time.
Cards issued through multi-currency fintech platforms change this. A card connected to a MAD balance, or to a balance that converts at a competitive disclosed rate, removes the per-transaction foreign fee. The conversion happens once, at a known rate, rather than piecemeal on each transaction.
Grey provides a virtual Visa card linked directly to your foreign-currency accounts in USD, EUR, and GBP. When you convert from a foreign currency to MAD within Grey, the rate is shown before confirmation and conversions are charged at 1%. Apple Pay and Google Pay are supported in eligible regions for contactless payments. Multiple cards can be created for different spending purposes, each with its own limit. Withdrawals to a local MAD account cost $2.
Grey charges fees on deposits, conversions, withdrawals, and cross-border card transactions. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%. Exchange rates are variable and include a margin over the mid-market rate. Always review the rate before confirming a transaction. Visithttps://grey.co/blog/fees-and-charges-on-greyfor current rates.
Comparing the best ways to get and send MAD in Morocco
A few habits that consistently reduce currency costs and ATM friction for Morocco visitors:
Withdraw larger amounts less frequently rather than small amounts on demand. Even if the per-transaction fee is fixed, two withdrawals of MAD 2,000 each cost twice the fee of a single withdrawal at the daily limit.
Keep cash in MAD rather than converting back to your home currency at the end of the trip. The Moroccan dirham cannot be reconverted abroad through most channels, and Morocco's own departure exchange rates are no better than arrival rates. Spend what you have or donate the remaining small amount.
Notify your home bank of travel dates before departure. Bank fraud systems that flag unusual geographic activity are the most common reason cards are declined at Moroccan ATMs for travellers whose banks operate aggressive fraud monitoring. A brief call or app notification before travel prevents this entirely.
Use ATMs in public areas during daylight hours rather than late at night in isolated locations. Basic safety practices apply in most countries, including Morocco.
Keep a small cash reserve separate from your main wallet. Pickpocketing is not widespread in Morocco but does occur in busy medina areas. Having MAD 200 to MAD 300 accessible separately from the rest of your cash means losing your wallet does not mean being entirely without funds.
Frequently asked questions
Can I use my credit card for most payments in Morocco?
Cards are accepted at major hotels, upmarket restaurants, larger shops, and some tourist sites, but Morocco's economy outside these settings is cash-based. Taxis, street food, souks, small guesthouses, and most everyday transactions require dirhams in cash. Relying on card payment without carrying adequate cash creates practical problems in Morocco that would not arise in most Western European countries.
How much Moroccan dirham should I bring or withdraw at the start of my trip to Morocco?
A useful starting point for a typical tourist visit is MAD 500 to MAD 800 per day for moderate spending on food, transport, entry fees, and shopping. For a seven-day trip, having MAD 3,500 to MAD 5,600 accessible without relying on multiple ATM visits is comfortable. Withdrawing a larger amount at once from a reliable ATM in a city centre, rather than making daily small withdrawals, reduces total ATM fees.
Is it safe to use ATMs in Morocco?
ATMs operated by major licensed Moroccan banks are generally safe. Skimming devices, which criminals attach to ATM card readers to steal card data, are less common in Morocco than in some other tourist destinations, but do exist. Using ATMs inside bank branches or in well-lit, high-traffic locations reduces risk. Covering the keypad while entering your PIN is standard practice regardless of location.
What is the best exchange rate I can realistically get in Morocco?
The best rate available to tourists through formal channels is typically the bureau de change rate, which is 0.5% to 2% below the mid-market rate shown on Google or XE. Bank branches offer comparable rates. Fintech platforms that convert foreign currency to MAD at disclosed rates, with fees shown before confirmation, are competitive with the best bureau de change rates and offer the advantage of being accessible from anywhere, without needing to physically visit an exchange office.
Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.
Then remote work happened.
Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you need structure. Without the right structure, even the most careful spender can lose track of where their money is going.
The Grey card comes in as a practical budgeting tool for people who live and spend across borders. I’ll explain.
Why budgeting in multiple currencies breaks down so easily
Most people don’t overspend because they’re irresponsible. Rather, they overspend because their money isn’t organised in a way that reflects how they live.
Here’s what usually goes wrong.
You’re spending across platforms, clients, and countries, but everything is tied to one card. Subscriptions, ads, one-off purchases, and travel expenses all blur together. When something goes wrong, such as a spike in ad spend or an unexpected renewal, it’s challenging to pinpoint the cause quickly.
Add foreign currencies to the mix, and it gets worse. The charges don’t always settle immediately, and these small amounts seem harmless until they quietly add up.
What should budgeting look like when you earn and spend globally?
Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:
See exactly what each type of spending is costing you.
Stop or pause spending instantly when needed.
Protect one part of your budget from another.
Make changes without disrupting everything else.
The Grey card is designed around solving these exact needs.
How does the Grey card help with budgeting?
Use multiple cards to separate your spending
One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes.
For example, you can create:
One card for subscriptions and recurring tools
One card for ads and growth experiments
One card for travel or everyday spending
One card per client or project
Each card acts like its own budget lane. You don’t need to guess where the money went; you already know.
This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.
Freeze cards instantly when spending goes off-track
Budgets fail when you can’t act fast enough.
With the Grey card, you can instantly freeze or unfreeze any card in the app. If an ad campaign starts burning cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.
Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.
Set limits that protect your budget
Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.
You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.
For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.
Track spending clearly in one place
When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.
When budgeting time comes around, you’re no longer reconstructing your month from memory. The structure is already there.
Spend confidently across borders
Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.
LDMAG1
A quick note on protection when spending abroad
An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.
When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.
It’s one less thing to worry about while managing money across borders.
What budgeting in foreign currencies is like with the Grey card
When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency it’s coming from and more importantly, when something changes.
Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.
If you’re ready to make your budget work wherever you are, create or update your Grey card and start spending and budgeting in the ways that matter to you.
Working online as an African freelancer opens doors to clients all over the world, and a foreign account makes the whole process a lot easier. Foreign accounts give you the flexibility to receive payments in multiple currencies, move money seamlessly across borders, and access funds whenever you need them. They put you in control of your income, rather than your income being limited by local systems.
These accounts also allow you to plan, save strategically, and operate professionally on a global scale. For anyone building a remote business, having access to foreign banking options is a way to grow your freelance career with confidence and freedom.
Grey is the best choice for African freelancers, offering fast, secure, and multi-currency digital accounts. Payments from anywhere in the world arrive instantly, and fees are transparent and minimal. With full African integration and seamless international banking, freelancers can manage earnings efficiently, hold multiple currencies, and operate professionally online. For freelancers seeking speed, flexibility, and ease of use, Grey stands out as the top solution.
Afriex
Afriex allows Africans to send and receive money globally, supporting multiple currencies with competitive rates. Transfers are generally fast, and fees are lower than those of traditional banks. It’s useful for freelancers receiving payments from international clients, providing a reliable way to manage earnings across borders. While it’s convenient, Afriex doesn’t offer instant multi-currency access or the full range of features some freelancers may need for global business.
Payoneer
Payoneer is widely used by African freelancers for international payments. It supports multiple currencies and allows withdrawals to local banks. Fees for currency conversion and card usage can add up, and transfers may take a few days. It’s reliable for online marketplaces and global clients, but freelancers should be aware of the processing times and cost structure before fully depending on it.
Wise
Wise is known for low fees and transparent, real exchange rates. It’s a solid choice for receiving international payments and transferring funds across borders. Transfers may not be instant, and it doesn’t provide the full suite of multi-currency account features some freelancers prefer. Wise is ideal for cost-effective cross-border payments, but may not meet all the needs of global freelancers.
Flutterwave barter
Flutterwave’s Barter account helps Africans receive international payments and manage multiple currencies. It’s strong for regional and business transactions, offering convenience and easy account setup. Fees apply for card issuance and some transfers. While it works well for freelancers, it may not have the same speed, flexibility, or international reach as other solutions designed specifically for global remote work.
Chipper cash
Chipper cash is ideal for fast, low-fee transfers across African countries. It’s simple, secure, and supports multiple African currencies, making it perfect for freelancers working regionally. However, it has limited options for international currencies and clients outside Africa. While it’s practical for intra-African payments, freelancers seeking fully global, multi-currency access may require additional solutions.
Revolut
Revolut offers multi-currency wallets, competitive exchange rates, and secure banking features. It’s convenient for managing money internationally, though monthly fees and card usage charges may apply. Some features aren’t available in all African countries. Freelancers with tech-savvy clients may find it useful, but it may not always cover the specific needs of African online workers.
Grey provides fast, secure international payments, enabling freelancers to access earnings efficiently without delays or complex banking procedures.
Multi-currency functionality allows seamless management of USD, EUR, GBP, and local African currencies in a single, consolidated account.
Transparent, competitive fees ensure freelancers retain more of their income, avoiding hidden charges or unexpected deductions.
Enterprise-grade security safeguards accounts and transactions, offering peace of mind when handling global payments.
Support for USDC enables freelancers to receive, store, and convert stable digital currency, minimising volatility in international earnings.
LDMAG1
Grey: The ideal foreign account for African remote workers
African freelancers and online workers need foreign accounts to receive international payments, manage multiple currencies, and operate without restrictions. Grey is ideal, offering fast, secure, multi-currency accounts with transparent fees, advanced security, and an intuitive interface built for African users.
If you’ve been looking for a sign to start selling your freelancing services globally, here is the sign. Indian freelancers have the unique opportunity to expand their client base and improve their earning potential by targeting international clients who pay better and in stable currencies like USD, EUR, and GBP.
The thought of managing international payments might be daunting for many Indian freelancers. Understandably so, receiving global payouts with traditional payment options has discouraged many Indian freelancers. From payment delays to account restrictions, cumbersome paperwork, forced conversion at unfair rates, and payment delays, you have a lot to worry about without the right payout options. This article explores the best payout options for Indian freelancers selling services globally to make sure you maximise your earnings.
Managing payouts in India with multi-currency accounts
Using a multi-currency account is a silver bullet that fixes the challenges with traditional banks when managing foreign income. Multi-currency accounts provide you with virtual bank details in major currencies (USD, EUR, GBP, etc.) that clients can pay into as if you had a local bank account in their country. Once funds arrive, you can hold them in those currencies and convert to INR when rates are favourable. With multicurrency accounts, you can avoid slow bank transfers and unfavourable forced conversions, and keep better control over exchange timing and fees. Here are the things you should look out for when managing payouts in India with multi-currency accounts:
Access to USD, EUR, and GBP
Transparent fee structure
Low-fee conversion to INR
Fast transfers to Indian bank accounts
Ability to pay for global tools and subscriptions
There are some top choices:
Grey: Offers US, EUR, and GBP accounts that function like local bank accounts for international clients, with easy conversion and withdrawals to local banks in India. Grey integrates seamlessly with freelancing platforms and online stores where you might be receiving payouts.
Wise: Provides multi-currency accounts, supports withdrawal at mid-market exchange rates, and has a clear fee structure.
Payoneer: A bit pricey compared to Grey and Wise, but widely supported by freelance marketplaces and includes receiving accounts.
Revolut: Best known for their global cards, but also offers multicurrency accounts.
More indigenoushomegrown fintech solutions are emerging to simplify access to international banking for Indians.
Winvesta: Provides multi-currency accounts supporting 30+ currencies with local collection details in the US, UK, and EU. It charges $3 + 0.99% for cross-border payments with no USD forex markup.
Razorpay: This is a leading Indian fintech that offers two primary methods for managing international payouts: the MoneySaver Export Account for platform-based withdrawals and the International Payment Gateway for direct client invoicing.
PayPal is one of the most widely recognised ways to receive international payments. Many international clients are already familiar with it and can easily pay in foreign currency to your PayPal account. You can then withdraw to your Indian bank account in INR.
However, PayPal is expensive. The fees and exchange rates are often higher than those of multi-currency accounts, and conversion to INR on withdrawal eats into your earnings. There’s also the risk of account holds or restrictions if PayPal flags unusual activity.
Freelance marketplace payouts
If you work through platforms such as Upwork, Fiverr, Toptal, or Freelancer.com, the platforms themselves provide payout options:
Most marketplaces let you withdraw earnings via:
Grey
Direct bank transfer to an Indian bank
Payoneer
Wise
These options are embedded in the platform itself and may be the simplest choice if you earn mostly through a single marketplace. Receiving your payout in a stable currency give your better control and helps you maximise your earnings, compared to withdrawing directly to your local account.
Cryptocurrency payouts
Crypto talks can be confusing most of the time. But for those who understand how it works, freelancers are now accepting payments in cryptocurrencies such as Bitcoin, Ethereum, and stablecoins (e.g., USDC, USDT) if the clients are comfortable with it. These can then be converted to INR through exchanges. ****Crypto transactions are typically faster and cheaper. ****However, you must be wary of crypto volatility if you are not opting for stablecoins. You might also need to find how tax and compliance apply in India
Indian freelancers selling services globally have never had more options. While we are generally moving away from traditional banks, fintech solutions now offer better options for managing international payouts. So, if managing payment was going to be a problem, Grey’s got you. Manage USD, GBP, and EUR payments on one platform at low transaction fees and withdraw INR to your local account at competitive exchange rates and without payment delays. Grey cards make online payments on global platforms seamless for freelancers.
Despite being around for a very long time, traditional banks have fallen out of favour with freelancers, and you cannot even blame them. Freelancing has moved beyond working with local clients to a global talent market where people now work for clients thousands of miles away, managing different currencies. Global freelancing has brought global needs, and traditional banking has, so far, not evolved to meet them. Here is why this shift from traditional banks to global accounts is happening.
The truth is, traditional banks are more familiar with managing local transactions in their local currency and less often deal with international payments. Cross-border payments go through the SWIFT network and, sometimes, intermediary banks. Unlike local payments, international transactions are processed over several business days. For freelancers who receive frequent international payments, this traditional system can be inefficient, slow, and frustrating.
Forced currency conversions of traditional banks reduce earnings
One of the biggest pain points for freelancers is the lack of control over currency conversion. Traditional banks usually convert foreign currency to local currency immediately at exchange rates that are less favourable than market rates. The freelancer doesn’t get a say in when or how the conversion happens. This essentially means that every time money comes in, it immediately loses some value. For freelancers who want to keep USD, EUR, or GBP as a hedge against inflation or wait for better exchange rates, this traditional setup just doesn’t cut it.
High charges and hidden fees of traditional banks
International payments through traditional banks usually involve several types of fees charged at different stages of the transaction. There may be incoming wire fees, intermediary bank deductions, and foreign exchange mark-ups applied. It gets even more frustrating that freelancers often cannot even predict how much they will actually receive. A client may send a fixed amount, but the final figure that arrives can be noticeably lower without a clear explanation.
Traditional banks have slow international payment processing
Freelancing income is often unstable. This can make financial planning for many freelancers difficult. Waiting several days for an international payment makes this worse and can affect scheduled payments like rent, subscriptions, and business expenses. Unlike traditional banks, global accounts are designed to settle international payments faster. This helps freelancers access their income earlier and better manage their cash flow.
International clients prefer global accounts
Many foreign clients, especially those based in the US or Europe, prefer to pay into local bank accounts (accounts in their own currency). Asking them to initiate international wire transfers to your local bank can feel inconvenient and, in some cases, unprofessional. Global accounts solve this problem by providing freelancers with banking details in major currencies, making it appear as if clients are making local transactions. This allows freelancers to receive payments as if they were based in the same country as their client, even while working remotely.
Integration with freelance platforms and tools
Freelancers often earn through platforms built with global payments in mind. Global account providers integrate more easily with these systems, ensuring you can withdraw your payout with ease. Payment solutions like Wise, Payoneer, and Grey are commonly supported by global freelancing platforms. On the other hand, traditional banks often struggle with integrating with these platforms.
For freelancers in countries with volatile currencies or rising inflation, holding foreign currency is now more relevant than ever. Before now, holding foreign currency seemed exclusively for wealthy people. But with global accounts, you can easily keep EUR, GBP, and USD. It is a form of financial protection. Traditional banks often restrict this flexibility or impose stringent conditions on foreign currency accounts. Global accounts make it easier for freelancers to hold, manage, and use USD or EUR without unnecessary barriers.
Physical bank visits are inconvenient
Visiting a banking hall can be rather uncomfortable. Traditional banking still relies heavily on in-person visits, physical documents, and long verification processes. This feels out of place for freelancers who work entirely online and from their comfort spaces. Meanwhile, you can access global account services online with remote onboarding and verifications that can be completed in minutes rather than weeks. Avoiding repeated trips to a banking hall is not just convenient; it saves time that can be spent earning.
Freelancers are not abandoning traditional banks because they are unsafe or irrelevant. They are leaving because the evolving global work environment requires financial tools that better meet their needs. Managing cross-border payments requires payment systems that are fast, flexible, affordable, and optimised for cross-border income. This is why Grey offers multi-currency accounts supporting USD, EUR, and GBP payments. This way, freelancers can receive their income at low and transparent fees, competitive rates, and swift payment processing. Grey also simplifies international payments with virtual cards that support direct payment in foreign currencies.
If we give you the short answer, you have to make a pinky promise that you read this article to the end. Trust us, we have more to tell you than just ‘yes, non-residents can open a US bank account online in 2026.’ For the longer answer, there are many other things to consider. Stick with us and let’s go through this together by answering a few questions to give you a clear picture.
Can non-residents open a traditional US bank account online in 2026?
Opening a traditional US bank account, such as a Chase or Wells Fargo account, might be difficult due to their requirements. Here are the key reasons why this is next to impossible:
Requires your physical presence: Major traditional banks often require you visit a US branch to verify your identity and complete the process.
Requires Social Security Number (SSN): While some banks may allow an ITIN (Individual Taxpayer Identification Number) in place of an SSN, many automated online systems strictly require an SSN, which you might not have as a non-resident.
Proof of US address: A physical US address is almost always required to open a traditional bank account in compliance with "Know Your Customer" (KYC) regulations.
Traditional banks are strict on compliance: They adhere to strict regulations (KYC/AML) and find it easier to reject international applications than to verify their legitimacy remotely.
In summary, you cannot open a traditional bank account online as a non-resident living abroad. Even if a bank’s website says “open online,” the system usually blocks or flags non-US residents during the SSN/address checks.
If opening a traditional US bank account can be difficult, who do people bother?
Protects against local inflation: Keeping your earnings in USD protects against the volatility of your local currency.
Easier international payments: A USD account lets you receive USD and make international payments with ease. Whether you are a freelancer with international clients or paying for global subscriptions or tools, a USD account makes it more straightforward.
Reduces losses: When you receive international payments with your local account, the conversion is often done at unfavourable rates. Using a USD account help you time your conversion better and avoid losses.
How can non-residents open a US bank account online in 2026?
While non-US residents cannot open a traditional US bank account, they can still manage USD transactions seamlessly with fintech payment solutions that let you create an account from anywhere, without a physical visit. While these USD accounts might have some limitations, they are reliable and secure for receiving USD payments. They also let you keep USD, make international payments, and withdraw to your local bank account.
Which USD online banking options can non-residents use?
If you want to manage USD with ease, these are some of your best options.
Grey
This offers multicurrency accounts supporting USD, EUR, and GBP, allowing you to manage USD transactions as you would with a traditional USD account. It also seamlessly integrates with freelancing platforms like Upwork and Fiverr to withdraw your earnings. Grey offers you US banking details to receive USD with ease. It is pretty straightforward to create an account, and you can get started with Grey within minutes.
LDMAG1
Wise
Wise provides USD accounts with US routing and account numbers. Wise is known for transparent fees and mid-market exchange rates. It works well for freelancers and remote workers, though some features may vary depending on your country of residence.
Payoneer
Payoneer is widely used on global freelancing marketplaces. It provides USD receiving accounts and allows withdrawals to local banks. While reliable, its fees and exchange rates are generally higher and less transparent than those of newer fintechs.
PayPal
PayPal allows you to receive USD payments, but you cannot truly hold USD long-term in many countries. Withdrawals often force conversion to local currency at unfavourable rates. It works for occasional payments, but not as a long-term USD banking solution.
Why do people open US bank accounts online with Grey?
Grey remains a favourite among frequent international travellers, freelancers with global clients, and everyone managing multiple currencies. Here are the reasons non-residents open a US bank account online in 2026.
Low fees: Grey offers a transparent fee structure with low transaction fees.
Competitive exchange rates: Convert fees at market rates, with no hidden markups.
Swift transactions: Transactions are processed and completed within minutes to a few hours.
Virtual cards: Access multiple virtual cards for your international payments without requiring top-ups. These cards also work with Apple Pay and Google Pay for contactless payment.
Complete your ‘Know Your Customer’ verification by uploading a valid ID, a selfie, and proof of address.
Once verified, request your USD account details.
Share the details with clients, employers, or platforms and start receiving USD payments.
While non-residents cannot open traditional US bank accounts online from abroad, global payment solutions like Grey offer multicurrency accounts that support USD transactions without physically visiting a bank or wading through paperwork. Manage your USD at low cost and withdraw to your local accounts at competitive exchange rates.
In Morocco, earning in US dollars is no longer limited to a few professions. Designers in Casablanca, consultants in Rabat, developers working remotely, and small business owners selling services abroad are now all being paid by US clients. The work is becoming more global, and dollar invoices are now part of everyday reality for many people.
But the experience of receiving that money is not always as smooth as earning it. A $500 payment can take different paths before it reflects locally, and what finally shows up in Moroccan dirhams does not always feel as straightforward as the invoice that was sent. Sometimes it arrives quickly, other times it moves through delays that make you check your account more than once.
That gap between what is sent and what is received is what makes the process worth understanding properly. This article explains the best way to receive US dollar payments in Morocco, what really happens behind each transfer, and how to approach it so you keep more of what you earn.
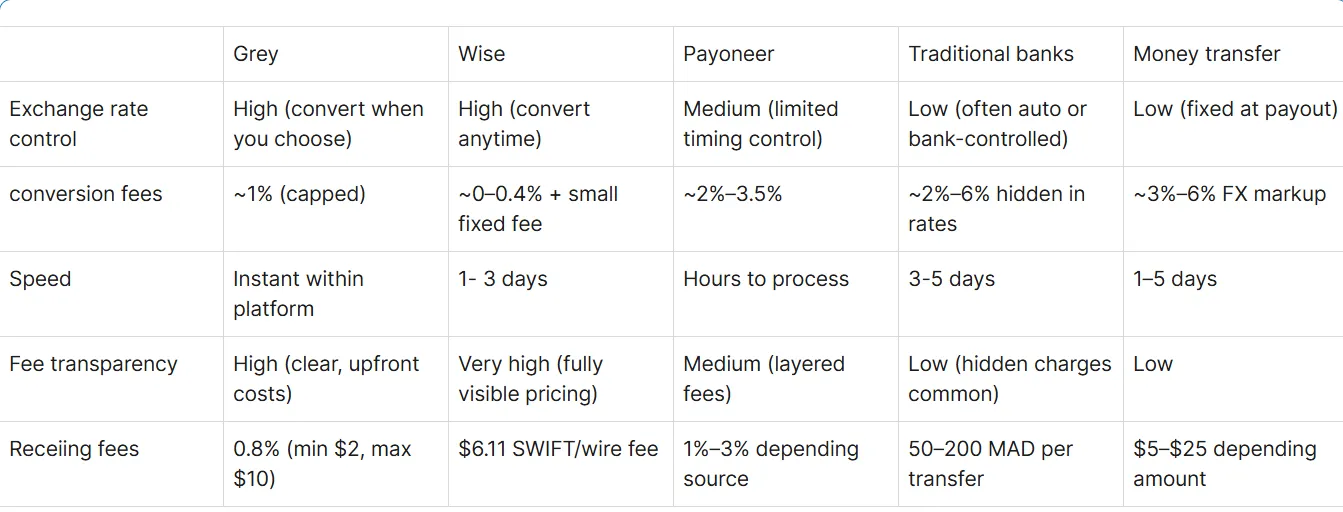
Receiving US dollars in Morocco is now easier through digital platforms and global transfer services, but each option works differently depending on speed, cost, and how much control you want over your money.
Wise
Wise is widely used because it gives you the real mid-market exchange rate when receiving USD in Morocco, which helps you avoid hidden losses. It is especially helpful for freelancers who want clarity on exactly what they are paid. Transfers into your account are usually charged a fixed fee of about $6.11 for wire or SWIFT payments, while ACH transfers are often free. Payments typically arrive within 1 to 5 business days, depending on the sender’s bank and route.
Grey
Grey is designed for users who want more control over how and when they convert their USD earnings. You receive dollars into a virtual account, then decide when to convert into Moroccan Dirhams based on exchange rates. This helps protect your income from poor timing. The receiving fee for ACH is 0.8%, with a minimum of $2 and a maximum of $10. Conversion costs are 1% capped at $6, and withdrawal to a Moroccan bank is a flat fee of $2.
Payoneer
Payoneer is popular among freelancers using global platforms like Fiverr, Upwork, and Amazon services. It allows you to receive USD from international clients and withdraw directly to your Moroccan bank account. However, the cost depends on how you are paid. Credit card payments attract around 3%, while eCheck payments are about 1%. There is also a yearly fee of $29.95 if the account is inactive, and withdrawal and conversion costs typically range between 2% and 3.5%.
Money Transfer Services (Western Union & Remitly)
Money transfer services like Western Union and Remitly are best when you need fast access to cash in Morocco. They are widely available through local agents such as Cash Plus and Wafacash, and you can often receive money within minutes. Bank deposits may take one to five business days, depending on the route. Fees vary based on the amount sent, and exchange rates include a built-in margin, which means you may receive slightly less than market value overall.
Traditional banking (SWIFT transfers)
SWIFT transfers are commonly used for formal international payments, but they are often slower and more expensive compared to digital platforms. Moroccan banks usually charge between 50 and 200 MAD for incoming transfers, while intermediary banks may also deduct additional fees along the way. Exchange rates often include a 2% to 6% margin, which reduces your final amount. Transfers typically take 3 to 5 business days, making this option better for large or occasional payments rather than regular freelance income.
The real cost of using the black market in Morocco
The black market for currency in Morocco often looks attractive on the surface because the exchange rate is higher than official channels. Many people feel they are getting “more value” for their euros or dollars when they convert informally. However, in simple economic terms, it comes with hidden risks that are not always visible at first.
There is no legal protection, no receipt trail, and no guarantee of fairness if something goes wrong. What looks like a better rate can quickly turn into uncertainty and financial exposure. For freelancers, students, and families receiving money from abroad, this can create instability rather than real gain.
The biggest issue is trust. Transactions are often cash-based and unregulated, meaning there is no formal system to resolve disputes. If money is lost, delayed, or miscounted, there is usually no recovery option. It also limits your ability to build a financial record, which is important for visas, loans, or business growth.
Over time, relying on the black market can disconnect you from formal financial systems, making it harder to scale income, prove earnings, or access safer global payment platforms that offer transparency and long-term financial security.
What should you know about fees when receiving USD payments in Morocco?
I know you want all your money, but let’s look at this like this. Imagine you run a small delivery service in Casablanca. Someone asks you to pick up a package, move it across cities, keep it safe, and deliver it on time. You would not do that for free. You would charge for fuel, time, risk, and the system you’ve built to make it reliable.
That is exactly how payment platforms work. Banks and platforms are not just taking money, while maintaining systems that move funds across countries, managing compliance checks, preventing fraud, and ensuring currencies are exchanged safely. These processes cost money, and that cost is shared across users. Without them, international payments would be slower, riskier, and less reliable for everyone involved.
The smarter approach is not avoiding fees completely, but understanding them deeply. When you know how much is lost to conversion, timing, and withdrawal, you start making better decisions. You choose platforms more carefully, you time conversions better, and you plan support to family in a way that does not drain your entire income at once.
Exchange rates work the same way. Platforms may not always give the exact market rate because they include a small margin to cover risk and operations. It is not always exploitation, it is the cost of making global money movement fast, secure, and dependable for everyday use.
How exchange rates and timing shape your real USD income in Morocco
One of the most important but often overlooked parts of receiving USD in Morocco is how exchange rates and timing directly affect what you actually keep.
Exchange fluctuates
On paper, a $500 payment always looks the same. In reality, the value of that $500 can change depending on when it is converted, which platform is used, and how the FX rate is applied at the moment of withdrawal.
Exchange rates are constantly moving due to global market conditions, inflation trends, and currency demand. This means the Moroccan dirham value of your USD earnings is never fully fixed until the moment conversion happens. A small difference of 0.5% to 2% in exchange rates can significantly impact freelancers who regularly receive payments. Over a year, these small variations can add up to the equivalent of an entire project’s income lost without any visible “fee” being charged.
Timing matters
Timing also plays a major role. Converting immediately after receiving payment gives certainty, but it does not always give the best value. Holding USD for a short period can sometimes allow you to benefit from better rates, especially if your platform supports multi-currency wallets. However, holding too long without a strategy can also expose you to market drops, which is why balance matters.
Hidden FX costs
Another key factor is how platforms apply their own FX margins. Even when a service claims “real exchange rates,” there may still be small spreads included to cover operational costs. These are not always labelled as fees, but they function in the same way by reducing your final payout.
For freelancers in Morocco, understanding these dynamics is essential. It shifts the focus from simply “getting paid” to actually “maximising what you keep.” Over time, this awareness leads to better financial decisions, smarter platform use, and more predictable income from international clients.
Why you should choose a secure platform like Grey
Grey gives you a safe, structured way to receive international payments, helping you avoid delays, hidden charges, and the risks that come with informal or unreliable channels.
Reliable global payment access: Grey provides you with real foreign account details, allowing clients to pay you like a local in USD, GBP, or EUR. This reduces failed transfers, avoids confusion, and ensures your payments arrive through trusted, regulated channels every time.
Transparent and controlled fees: With Grey, you see exactly what you are charged before completing any transaction. Fees are clearly stated, with conversion costs around 1% and capped limits. This helps you avoid hidden deductions and better plan your income over time.
Flexibility to hold and convert currencies: You are not forced to convert your money immediately. Grey allows you to hold USD, GBP, or EUR and convert when rates are favourable. This level of control helps you protect your earnings from poor timing and unnecessary losses.
Faster access to your funds: Payments received through Grey are processed quickly, often within 24 hours, depending on the sender. This improves your cash flow and ensures you can access your earnings without long delays common with traditional banking systems.
Built for freelancers and remote workers: Grey is designed with international earners in mind. Whether you are freelancing, consulting, or working remotely, it simplifies cross-border payments, making it easier to manage income, track transactions, and stay financially organised.
Frequently asked questions
Why do different platforms charge different fees for the same payment?
Each platform operates on different infrastructure, partnerships, and risk models. Some prioritise speed, others focus on low cost or convenience. Fees also depend on currency routes and compliance requirements. That is why the same $1,000 transfer can arrive differently depending on the platform used.
Why do people still use the black market despite the risks?
Many people use the black market because the rate looks better at first glance. It feels like you are getting more value for your dollars or euros. But what is often missed is the lack of protection, no transaction record, and the hidden risk of loss if anything goes wrong during exchange.
How can I reduce losses when receiving international payments?
You reduce losses by understanding total cost, not just transfer fees. Compare exchange rates, choose platforms with transparent pricing, avoid unnecessary conversions, and time withdrawals wisely. Over time, small improvements in how you receive money can significantly increase your real take-home income.
Why does understanding exchange rates matter more than just focusing on the amount you are paid?
Because the value of your income changes depending on when and where you convert it. A good-looking payment can lose value quickly through poor timing or weak rates, meaning the same job can result in very different real earnings.
Manage USD payments with Grey
Receiving US dollars in Morocco does not have to be complicated or expensive. Grey offers a simple solution for freelancers, consultants, expats, students, and businesses who receive international payments. With USD accounts, you can receive money directly from US clients, hold your funds securely, and convert when rates are favourable. Transfers are fast, fees are low and transparent, and exchange rates are competitive, helping you keep more of your income. Whether for work or personal use, Grey makes receiving USD in Morocco easier, safer, and more efficient.
Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN, 0.5% for EUR/GBP (minimum €2/£2, maximum €10/£10), and $0.50-$0.65 for KES/UGX/TZS. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction. Visit grey.co/pricing for current rates.