


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/fx-futures-trading#article","headline":"FX futures trading: How currency futures work","description":"FX futures are exchange-traded contracts on currency pairs. Learn how they work, how to trade them, and how they compare to spot FX. Read the full guide today.","inLanguage":"en","url":"https://grey.co/blog/fx-futures-trading","mainEntityOfPage":{"@id":"https://grey.co/blog/fx-futures-trading#webpage"},"datePublished":"2026-09-30T15:56:03.208Z","dateModified":"2026-09-30T15:56:17.595Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/fx-futures-trading#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6abd3102611053508d34e58e_FX%20Futures%20Trading-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6abd3102611053508d34e58e_FX%20Futures%20Trading-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/fx-futures-trading#webpage","url":"https://grey.co/blog/fx-futures-trading","name":"FX Futures Trading: How Currency Futures Work | Grey","description":"FX futures are exchange-traded contracts on currency pairs. Learn how they work, how to trade them, and how they compare to spot FX. Read the full guide today.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/fx-futures-trading#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/fx-futures-trading#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/fx-futures-trading#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"FX futures trading: How currency futures work","item":"https://grey.co/blog/fx-futures-trading"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/fx-futures-trading#faq","mainEntity":[{"@type":"Question","name":"What is the minimum to trade FX futures?","acceptedAnswer":{"@type":"Answer","text":"The minimum to trade FX futures is the initial margin requirement for one contract, plus enough buffer to avoid an immediate margin call if the market moves against you. For EUR/USD futures on the CME, initial margin requirements are typically $2,000 to $3,000 per contract, but this varies with market volatility and can be raised by the exchange at any time. In practice, most experienced futures traders maintain significantly more than the minimum margin in their account to absorb adverse moves without being forced out of a position."}},{"@type":"Question","name":"How are FX futures different from forex spot trading?","acceptedAnswer":{"@type":"Answer","text":"FX futures are standardised contracts traded on regulated exchanges like the CME, with fixed contract sizes, quarterly expiration dates, and prices visible to all participants equally. Spot forex is traded over-the-counter through brokers, with flexible position sizes, no expiration dates, and prices set by the broker. Futures offer greater regulatory oversight and price transparency but require larger minimum positions. Spot forex is more accessible to retail traders, but broker quality and regulatory protection vary by jurisdiction."}},{"@type":"Question","name":"Are FX futures suitable for beginners?","acceptedAnswer":{"@type":"Answer","text":"No. FX futures involve leverage, daily mark-to-market settlement, contract expiration management, and margin call risk. The standardised contract sizes mean a single EUR/USD futures contract controls 125,000 euros, which represents significant notional exposure for a beginning trader. Beginners who want to understand currency markets should start with educational reading rather than live trading, practice on simulated accounts before risking capital, and understand leverage mechanics fully before entering any leveraged position. The FX trading beginner's guide covers foundational concepts for those starting from scratch."}},{"@type":"Question","name":"What is the contract size for EUR/USD futures?","acceptedAnswer":{"@type":"Answer","text":"One EUR/USD futures contract on the CME represents 125,000 euros. At an exchange rate of EUR/USD 1.10, one contract has a notional value of approximately $137,500. The minimum price move (tick) is 0.00005, worth $6.25 per contract. CME also offers E-micro EUR/USD futures contracts at one-tenth the size (12,500 euros per contract), which lowers the capital required per contract and may be more accessible for smaller traders."}},{"@type":"Question","name":"When do FX futures expire?","acceptedAnswer":{"@type":"Answer","text":"CME currency futures expire quarterly: in March, June, September, and December. The specific expiration date is the third Wednesday of the delivery month, though the last trading day is typically the Monday before that Wednesday. Most traders close their positions before expiration to avoid the settlement process. Those who want to maintain exposure beyond the front-month contract “roll” their position by closing the expiring contract and opening the next quarterly contract."}},{"@type":"Question","name":"Is Grey an alternative to FX futures for hedging small businesses?","acceptedAnswer":{"@type":"Answer","text":"For small businesses with straightforward multi-currency needs, Grey addresses the practical problem more simply than futures contracts do. A Grey multi-currency account lets you hold USD, EUR, and GBP balances, receive payments from international clients at low cost, and convert at a transparent rate. This is effective for managing the timing of currency conversion and avoiding forced conversion at poor bank rates, which covers the currency exposure most small businesses actually face. FX futures are appropriate when a business has a specific, large, time-defined currency exposure it needs to hedge precisely, such as a confirmed export contract in a foreign currency with a known settlement date. For most small businesses, that level of complexity and capital commitment isn’t justified. Convert currencies with Grey"}}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/fx-futures-trading#terms","name":"FX futures trading: How currency futures work glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"FX futures trading","description":"FX futures trading is the buying and selling of standardised contracts that commit the holder to exchange a specified amount of one currency for another at a predetermined price on a specific future date.","inDefinedTermSet":{"@id":"https://grey.co/blog/fx-futures-trading#terms"}}]}] </script>

FX futures trading: How currency futures work

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

If you’ve read our FX trading beginner's guide, you already know that the forex market is primarily an over-the-counter market, with no central exchange and trades happening directly between participants. FX futures are different. They are exchange-traded, standardised contracts regulated by a recognised authority, with fixed contract sizes, set expiration dates, and publicly visible prices.

That distinction matters. It shapes everything from how you access the market to who regulates it to how much it costs to trade. This guide explains how FX futures work mechanically, how they compare to spot FX, and when they’re the right tool for a specific financial problem, and when they’re not.

What is FX futures trading?

FX futures trading is the buying and selling of standardised contracts that commit the holder to exchange a specified amount of one currency for another at a predetermined price on a specific future date.

Unlike spot FX, where currencies are bought and sold for immediate delivery (typically two business days), FX futures contracts have a defined expiration date in the future, typically quarterly: March, June, September, and December. You don’t have to hold the contract until expiration: most futures positions are closed before the contract expires by taking the opposite position.

The major FX futures markets are operated by CME Group, which runs the Chicago Mercantile Exchange (CME). The CME is one of the world’s largest derivatives exchanges and lists futures contracts on major currency pairs, including EUR/USD, GBP/USD, USD/JPY, AUD/USD, CAD/USD, CHF/USD, and MXN/USD, among others.

Because FX futures trade on a regulated exchange rather than over-the-counter, all participants see the same prices, all transactions are cleared through a central counterparty (the CME Clearing House), and the Commodity Futures Trading Commission (CFTC) in the US regulates the market. This centralised structure is one of the primary differences from spot FX.

Currency futures explained

Understanding the mechanics of a currency futures contract requires knowing its key specifications. Here is how the major CME EUR/USD futures contract works, using CME Group’s published contract specifications.

Contract size: Each EUR/USD futures contract represents 125,000 euros. This is the standardised unit. You cannot trade a partial contract: if you want exposure to EUR/USD, the minimum is one full contract worth 125,000 euros.

Tick size: The minimum price movement (tick) for EUR/USD futures is 0.00005 dollars per euro, which equals $6.25 per contract (125,000 × 0.00005). This is the smallest profit or loss increment per contract per tick.

Expiration months: EUR/USD futures expire quarterly: March, June, September, and December. The contract expiration date is the third Wednesday of the delivery month. The front-month contract (the one with the nearest expiration date) is typically the most liquid.

Settlement: CME currency futures are physically settled, meaning the actual exchange of currency can occur at expiration if a position is held open. In practice, most traders close their positions before expiration by taking the opposite trade, avoiding physical delivery.

Margin requirements: To trade FX futures, you don’t pay the full value of the contract upfront. You deposit an initial margin, a percentage of the contract’s notional value, as a performance bond. CME publishes initial and maintenance margin requirements. For EUR/USD futures, initial margin requirements vary but are typically between $2,000 and $3,000 per contract, depending on market volatility. This means you’re controlling a contract worth approximately $137,500 (at EUR/USD 1.10) with a margin of a few thousand dollars.

Mark-to-market: Unlike some financial instruments, futures positions are marked to market daily. At the end of each trading session, gains and losses are calculated based on the day’s settlement price and credited or debited from your margin account. If your account falls below the maintenance margin level, you receive a margin call and must deposit additional funds or have your position liquidated.

How to trade FX futures

Trading FX futures requires access to a futures broker and a funded margin account. The process differs from opening a standard retail forex account.

  1. Choose a CFTC-regulated futures broker
    FX futures must be traded through a registered Futures Commission Merchant (FCM). Check CFTC registration at cftc.gov before depositing funds with any broker. Major regulated FCMs include Interactive Brokers, TD Ameritrade Futures, and others. Verify that the broker specifically offers access to CME currency futures.
  2. Open a futures account and complete compliance requirements
    Futures accounts require more documentation than standard brokerage accounts. You’ll complete risk disclosures, provide financial information, and confirm you understand the risks of leveraged derivatives trading.
  3. Deposit initial margin
    Transfer funds to meet the initial margin requirement for the number of contracts you intend to trade. Remember that margin requirements can change based on market volatility: CME can raise them at any time.
  4. Place an order. Select the contract (e.g., EURO FX Futures, symbol 6E), the expiration month, the direction (buy or sell), and the order type (market, limit, or stop). Your broker’s platform will show the current bid and ask price for the contract.
  5. Monitor your position and margin
    Because futures are marked to market daily, your account balance will change each day based on price movement. Monitor your account to ensure it remains above the maintenance margin.
  6. Close or roll before expiration
    To exit a long position, sell the same number of contracts in the same expiration month. To exit a short position, buy. To maintain exposure beyond the current contract’s expiration, “roll” the position by closing the front-month contract and opening the next expiration month.

FX futures vs spot trading

The two primary ways to trade currency markets are FX futures (exchange-traded, standardised, regulated) and spot FX (over-the-counter, flexible, broker-dependent). Here’s how they compare:

Feature FX futures Spot FX (retail forex)
Trading venue Regulated exchange (CME, ICE) Over-the-counter, through brokers
Regulation CFTC (US), FCA (UK), other regulators Varies; some markets lightly regulated
Price transparency Full order book visible; same price for all participants Broker-set spread; prices can vary between brokers
Contract size Standardised (EUR/USD = 125,000 EUR) Flexible; can trade micro lots (1,000 units)
Minimum trade size One contract (typically large notional value) Much smaller; micro lots available
Settlement Physical delivery at expiration (usually closed before) Cash settled; no physical delivery
Leverage Yes; margin-based Yes; margin-based (often higher leverage available)
Expiration Quarterly expiration dates No expiration; positions held indefinitely
Counterparty risk Cleared by exchange (low; exchange guarantees trades) Counterparty is the broker (higher risk with unregulated brokers)
Transaction costs Commission per contract plus bid-ask spread Spread only (plus sometimes swap/overnight fees)
Who uses it Institutional hedgers, professional traders Retail traders, smaller hedgers
Access Requires futures broker account Retail forex broker account

‍

The key practical differences: FX futures offer greater regulatory protection and price transparency, but the standardised contract sizes make them less accessible for small-volume traders. Spot FX offers more flexibility on position size, but with variable broker quality and less regulatory oversight in some jurisdictions.

Hedging with FX futures

One of the primary legitimate uses of FX futures, beyond speculation, is hedging: locking in an exchange rate for a future transaction to protect against adverse currency movement.

Worked example: a UK exporter hedging a USD receivable

A UK manufacturer has agreed to sell £500,000 worth of equipment to a US buyer. The invoice is denominated in USD at today’s GBP/USD rate of 1.27, making the USD invoice amount approximately $635,000. Payment is due in three months.

The risk: if the pound strengthens against the dollar (GBP/USD rises) over those three months, the $635,000 will convert to fewer pounds when received. At GBP/USD 1.35, for example, the same $635,000 would only convert to approximately £470,000, a loss of £30,000 versus today’s rate.

The hedge: the exporter sells GBP/USD futures contracts with an approximate notional value of $635,000. If GBP/USD rises to 1.35, the exporter’s futures position profits, offsetting the loss on the physical receivable. If GBP/USD falls (good news for the exporter), the futures position loses money, but that loss is offset by the better conversion rate on the physical USD received.

The hedge doesn’t make the exporter money. It removes the currency risk, allowing the business to plan based on a known effective exchange rate rather than an unknown future rate. This is what hedging is for.

Who uses FX futures to hedge:

Exporters and importers who invoice in foreign currencies, multinational companies consolidating overseas earnings, and fund managers with foreign currency exposure in their portfolios. For most of these users, the objective is risk reduction, not profit generation.

Risks of FX futures trading

The risks in FX futures are specific and worth naming precisely.

Leverage risk: A $3,000 margin controls a contract worth approximately $137,500. A 1% adverse move in EUR/USD costs approximately $1,375 per contract, nearly 50% of the initial margin. The same move in the favourable direction yields the same gain, but most traders focus on the asymmetry: losses can quickly exceed the initial deposit.

Margin calls: If the market moves against your position and your account balance falls below the maintenance margin level, your broker will issue a margin call: deposit more funds immediately or have your position closed at the current market price, potentially at a significant loss.

Expiration management: Futures contracts expire. If you’re not actively monitoring your position, a contract you intended to hold can expire without you realising it, resulting in automatic closing at the expiration settlement price or, for physically settled contracts, an obligation to deliver or receive currency.

Basis risk for hedgers: FX futures hedge currency risk but introduce basis risk: the risk that the futures price and the spot price don’t move perfectly in tandem. For most major currency pairs, basis risk is small, but it exists and means a futures hedge is rarely a perfect offset.

Liquidity risk in less active contracts: Front-month contracts for major pairs (EUR/USD, GBP/USD, USD/JPY) are highly liquid. Further-out expiration months and minor pair contracts can be less liquid, meaning wider bid-ask spreads and potentially difficulty closing positions at the desired price.

A simpler way to manage real-world currency exposure

FX futures are a sophisticated tool designed primarily for institutional hedgers and experienced traders who need to manage specific, quantifiable currency exposures. For most freelancers, remote workers, expats, and small business owners, the practical currency problem is different: receiving income in one currency, holding it efficiently, and converting at a fair rate when needed.

That doesn’t require a futures account. It requires a multi-currency account with a competitive conversion rate.

Grey lets you hold balances in USD, EUR, and GBP, receive payments from international clients through local payment rails (ACH for USD, SEPA for EUR, Faster Payments for GBP), and convert currencies at mid-market rates with Grey at a conversion fee of 1%, capped at $6. The conversion rate is shown before you confirm; there’s no expiration date to manage, no margin calls, and no leverage amplifying your exposure.

For someone who needs to hold USD earned from US clients and convert it to GBP or local currency at an appropriate time, opening a multi-currency account with Grey is a more practical approach than establishing a futures hedging programme. FX futures are the right tool for managing large, quantifiable, time-specific currency exposures. For everyday multi-currency financial management, a Grey account is more practical.
Download the Grey app today to begin.

Frequently asked questions

What is the minimum to trade FX futures?

The minimum to trade FX futures is the initial margin requirement for one contract, plus enough buffer to avoid an immediate margin call if the market moves against you. For EUR/USD futures on the CME, initial margin requirements are typically $2,000 to $3,000 per contract, but this varies with market volatility and can be raised by the exchange at any time. In practice, most experienced futures traders maintain significantly more than the minimum margin in their account to absorb adverse moves without being forced out of a position.

How are FX futures different from forex spot trading?

FX futures are standardised contracts traded on regulated exchanges like the CME, with fixed contract sizes, quarterly expiration dates, and prices visible to all participants equally. Spot forex is traded over-the-counter through brokers, with flexible position sizes, no expiration dates, and prices set by the broker. Futures offer greater regulatory oversight and price transparency but require larger minimum positions. Spot forex is more accessible to retail traders, but broker quality and regulatory protection vary by jurisdiction.

Are FX futures suitable for beginners?

No. FX futures involve leverage, daily mark-to-market settlement, contract expiration management, and margin call risk. The standardised contract sizes mean a single EUR/USD futures contract controls 125,000 euros, which represents significant notional exposure for a beginning trader. Beginners who want to understand currency markets should start with educational reading rather than live trading, practice on simulated accounts before risking capital, and understand leverage mechanics fully before entering any leveraged position. The FX trading beginner's guide covers foundational concepts for those starting from scratch.

What is the contract size for EUR/USD futures?

One EUR/USD futures contract on the CME represents 125,000 euros. At an exchange rate of EUR/USD 1.10, one contract has a notional value of approximately $137,500. The minimum price move (tick) is 0.00005, worth $6.25 per contract. CME also offers E-micro EUR/USD futures contracts at one-tenth the size (12,500 euros per contract), which lowers the capital required per contract and may be more accessible for smaller traders.

When do FX futures expire?

CME currency futures expire quarterly: in March, June, September, and December. The specific expiration date is the third Wednesday of the delivery month, though the last trading day is typically the Monday before that Wednesday. Most traders close their positions before expiration to avoid the settlement process. Those who want to maintain exposure beyond the front-month contract “roll” their position by closing the expiring contract and opening the next quarterly contract.

Is Grey an alternative to FX futures for hedging small businesses?

For small businesses with straightforward multi-currency needs, Grey addresses the practical problem more simply than futures contracts do. A Grey multi-currency account lets you hold USD, EUR, and GBP balances, receive payments from international clients at low cost, and convert at a transparent rate. This is effective for managing the timing of currency conversion and avoiding forced conversion at poor bank rates, which covers the currency exposure most small businesses actually face. FX futures are appropriate when a business has a specific, large, time-defined currency exposure it needs to hedge precisely, such as a confirmed export contract in a foreign currency with a known settlement date. For most small businesses, that level of complexity and capital commitment isn’t justified.

Convert currencies with Grey

Last updated:

October 13, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to earn yield on USDC: Best options in 2026

•

•

2 min read

USDC is a stablecoin designed to maintain a value close to one US dollar, making it an option for people who want to hold digital dollars without the usual price swings associated with cryptocurrencies like Bitcoin. However, holding USDC in a wallet does not automatically generate interest. To earn a return, you need to invest your holdings in a programme or platform that pays a yield.

USDC itself pays no interest. Yield comes from lending it out through a centralised exchange programme, a crypto lending platform, or a DeFi protocol such as a lending pool or liquidity pair. Rates ranged from about 2 to 8% APY in 2026, depending on the platform, strategy and market conditions.

Each option comes with different levels of risk, access requirements and withdrawal conditions. Before choosing where to earn yield, understand how returns are generated, whether your funds are protected, and what could happen if a platform fails or a smart contract is exploited.

Does USDC pay interest on its own?

No, holding USDC in a crypto wallet does not earn interest by itself. USDC is a stablecoin designed to maintain a value close to one US dollar, but simply owning it does not generate additional income. Whether it sits in a personal wallet or an exchange account, your balance remains unchanged unless you receive additional USDC through another transaction or service.

To earn yield, you need to use a separate financial product built on top of USDC. These products generate returns through activities such as lending your stablecoins to borrowers, supplying liquidity to decentralised finance (DeFi) protocols, or participating in yield programmes offered by cryptocurrency exchanges.

Each option works differently and carries its own risks. A lending platform may pay interest from borrower repayments, while a DeFi protocol may distribute fees or lending revenue to participants. Centralised exchanges may offer promotional rates or rewards under specific conditions.

Before depositing USDC into any yield product, understand how returns are generated, what fees apply, and whether you can withdraw your funds when needed. Yield is never guaranteed.

Also read: How USDC compares with USDT

Centralised exchange and lending platforms

Centralised exchanges and crypto lending platforms allow you to earn yield by depositing your USDC into programmes that generate returns. Exchange earn programmes may lend your USDC to borrowers or use other permitted strategies to generate revenue, sharing a portion of the earnings with you.

Crypto lending platforms work similarly, connecting you with borrowers and paying interest on the funds you supply.
The annual percentage yield (APY) you receive depends on the platform, market demand, lending activity and programme conditions. Rates can change, and promotional offers may have limits or eligibility requirements.

Custody is another important consideration. When you deposit USDC into a centralised platform, the platform typically controls your assets rather than you holding the private keys directly. It may lend, transfer or otherwise use your deposited coins according to its terms.

This exposes you to counterparty risk. If the platform becomes insolvent, freezes withdrawals or suffers a hack, you may struggle to access your funds or lose them entirely. Before depositing your USDC, review the withdrawal terms, fees, security measures and how the platform uses your assets.

DeFi options: lending pools and liquidity pairs

Decentralised finance (DeFi) offers another way to earn yield on USDC without relying on a traditional financial intermediary. Two common options are lending pools and liquidity pairs, each generating returns in different ways.

With a lending pool, you deposit USDC into a protocol where borrowers can access the funds and pay interest. A portion of that interest is distributed to depositors as yield. Your returns depend on borrowing demand, utilisation rates and the protocol’s rules.

With a liquidity pair, you deposit USDC alongside another cryptocurrency into a trading pool. Traders use this pool to swap assets, and liquidity providers may earn a share of trading fees. However, the value of the two deposited assets can change relative to each other, creating impermanent loss.

Both strategies carry risks. Smart contract bugs can expose deposited funds to theft or loss. Impermanent loss can reduce returns compared with simply holding the assets. Depegging occurs when USDC falls below its intended one-dollar value, reducing the value of your holdings even when the yield remains positive.

How the main risks compare

When you earn yield on USDC, your biggest risks depend on where you deposit your funds and how the platform generates returns. Counterparty risk, smart contract risk and depeg risk can all affect how much you earn and whether you recover your initial deposit.

Counterparty risk arises when you trust a centralised exchange or lending platform with your USDC. If the provider fails or freezes withdrawals, you may lose access to your funds. Smart contract risk affects you when a vulnerability in a DeFi protocol allows your deposited funds to be stolen or lost. Depeg risk means your USDC falls below its intended $1 value, reducing the value of your holdings.
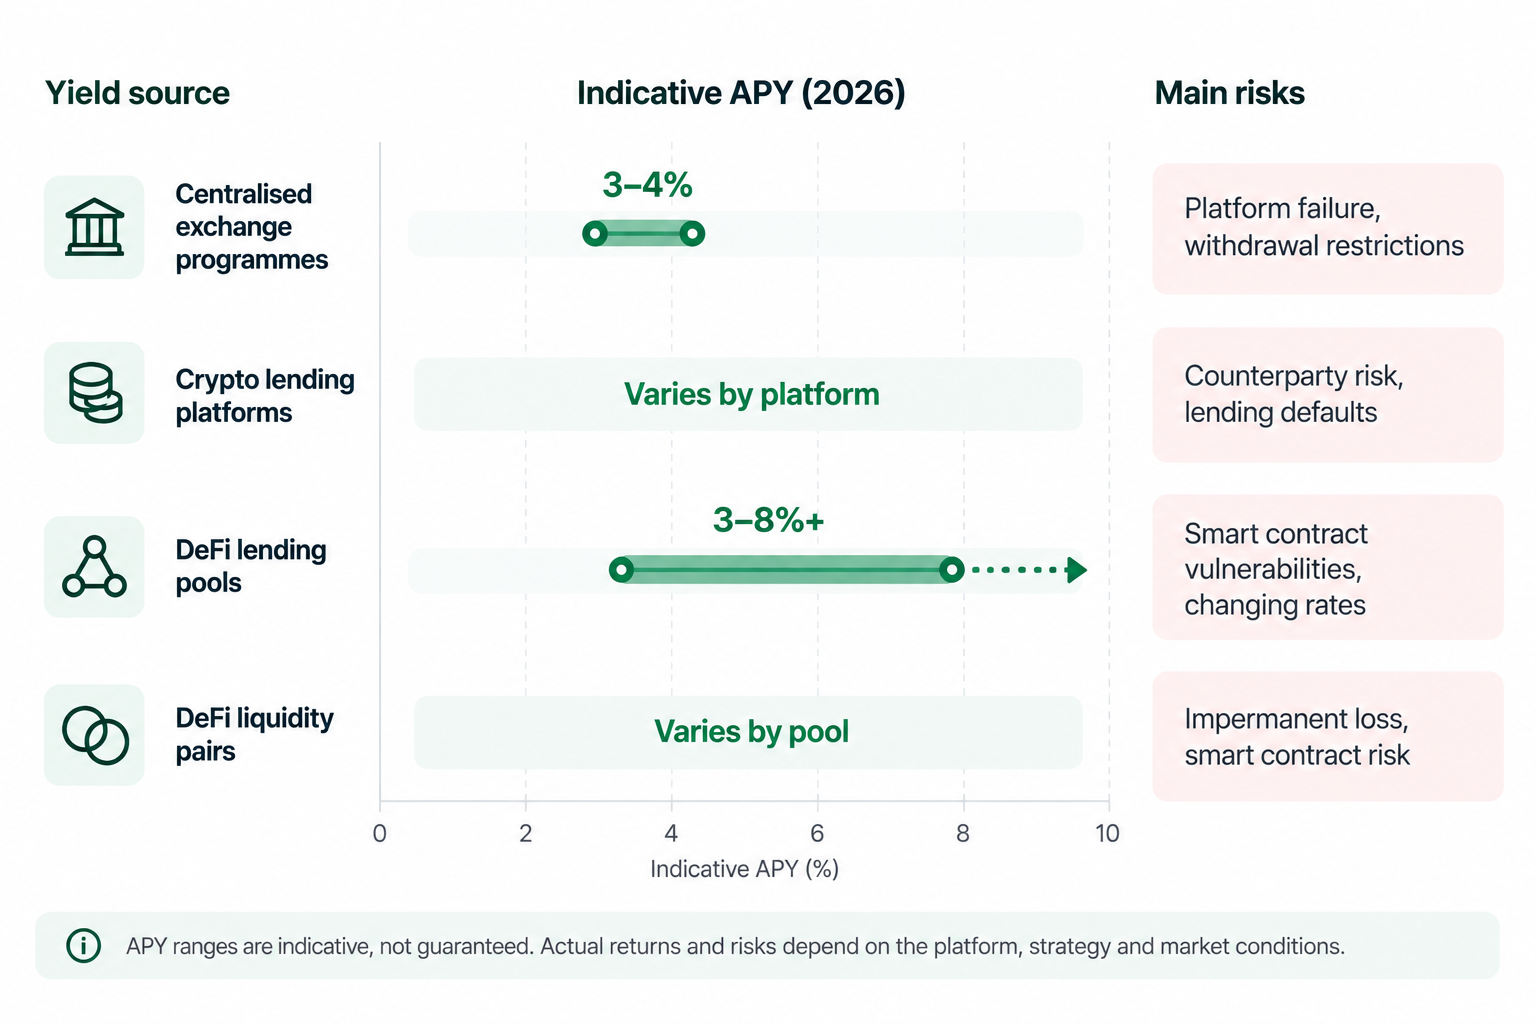
Chart comparing USDC yield options by risk and return.

There is no universal ranking because your exposure depends on the product you choose. However, higher advertised APY usually means higher risk. Before depositing, consider how returns are generated, who controls your funds and what could go wrong.

Your choice of blockchain also matters. Learn how USDC on Solana compares with Ethereum when considering transaction fees, network activity and the platforms available to you.

USDC yield vs a bank savings account

USDC yield can offer a potentially higher return than a regular savings account, but you give up an important protection: USDC does not have government-backed deposit insurance. Your returns depend on the platform and strategy you use, and higher yields often come with greater risk. A bank savings account may offer less, but eligible deposits have protection and more predictable access to your money.

Before choosing USDC for yield, consider whether you can afford the risks, including platform failure, smart contract vulnerabilities and changes in USDC’s value. It is generally better to keep emergency funds in an insured bank account rather than expose money you need urgently to crypto-related risks.

USDC can also make moving money across borders easier. For example, if you need to send money from the US to Nigeria, you can use a platform that supports USDC transfers and local withdrawals. With Grey, you can send, receive and spend USDC, then convert your balance and withdraw funds to a supported local bank account.

The right choice depends on your priorities: bank deposits for protection, USDC for global access and potential yield.

Frequently asked questions about how to earn yield on USDC

1. Is earning yield on USDC safe?

Earning yield on USDC carries risks, including platform failure, smart contract vulnerabilities and loss of funds. Although USDC is designed to maintain a one-dollar value, your investment is not guaranteed. Review the platform’s security, withdrawal terms and yield strategy before depositing funds, and never invest money you cannot afford to lose.

2. What is a typical USDC APY in 2026?

USDC yield varies by platform, market conditions and strategy. In 2026, some centralised reward programmes offer around 3–4% APY, while DeFi lending may offer approximately 3–8% or more. These are indicative ranges, not guaranteed rates. Check current offers, fees and risks before choosing a platform.

3. Do you pay tax on USDC yield?

Yes, USDC yield may be taxable, depending on your country’s tax laws and how you earn it. In the United States, rewards are generally reportable as income. Keep records of payments, dates and amounts, and consult a qualified tax professional to understand your reporting obligations.

4. Can you lose your USDC principal earning yield?

Yes, you can lose some or all of your USDC principal. Platform insolvency, lending defaults, smart contract exploits and liquidity problems can prevent withdrawals or cause losses. USDC can also trade below one dollar. Assess the risks carefully, diversify where appropriate and avoid committing essential savings.

5. What is the difference between USDC yield and USDC staking?

USDC yield usually comes from lending, reward programmes or providing liquidity through a platform or DeFi protocol. Staking typically involves locking cryptocurrency to support a proof-of-stake blockchain. USDC does not use proof-of-stake itself, so products marketed as USDC staking generally involve a different yield-generating mechanism.

6. How do you convert USDC yield into cash you can spend?

First, withdraw your USDC and earn rewards to a supported exchange or financial platform. Convert the balance into your preferred currency, then withdraw it to an eligible bank account or payment method. With Grey, you can send, receive and spend USDC, subject to supported services, currencies and applicable fees.

While USDC yield offers the potential for higher returns, a bank savings account provides greater protection for eligible deposits. For international transactions, Grey gives you a practical way to send, receive and spend USDC, with access to supported currencies for your everyday financial needs.


Gift tax: How much money can you give tax-free?

•

•

2 min read

Giving money to another person may seem straightforward, but large financial gifts can come with tax reporting requirements. In the United States, the Internal Revenue Service (IRS) determines how much you can give each year before you may need to report the gift. Understanding these rules is particularly important when transferring substantial sums, sharing wealth, or planning your finances.

The good news is that exceeding the annual gift tax limit does not automatically mean you owe tax. The IRS provides a lifetime exemption that allows you to give more than the annual limit before gift tax becomes payable. Knowing the difference between the annual exclusion, reporting requirements and lifetime exemption can help you make informed financial decisions.

The IRS annual gift tax exclusion lets you give up to a set amount per recipient each year with no tax owed and no form to file. Gifts above that amount count against your lifetime exemption and require Form 709, though tax is rarely owed until the lifetime exemption itself is used up.

How much can you gift tax-free per year?

For 2026, you can give up to $19,000 per recipient per year without owing federal gift tax or generally needing to file a gift tax return. This annual exclusion applies to qualifying gifts of money or property under US Internal Revenue Service (IRS) rules.

The limit resets every calendar year, beginning January 1. This means gifts made in 2026 are counted separately from gifts made in 2025. You can give money to multiple recipients in the same year, provided each recipient’s total qualifying gifts from you stays within the annual limit.

The exclusion applies per giver and per recipient, rather than as one combined limit for all your gifts. For example, you could give $19,000 each to three people in 2026, totalling $57,000, without exceeding the annual exclusion for any recipient. If two spouses each give the same recipient $19,000, their combined gifts can reach $38,000 under their separate exclusions, subject to applicable IRS rules.

What is the lifetime gift tax exemption?

For 2026, the US lifetime gift and estate tax exemption is $15 million per individual. This is the total amount an individual can transfer through qualifying gifts during their lifetime and leave to beneficiaries at death before federal gift or estate taxes generally apply, subject to applicable rules.

The lifetime exemption works alongside the annual gift tax exclusion. While the annual exclusion allows qualifying gifts of up to $19,000 per recipient in 2026 without using the lifetime exemption, larger gifts generally count toward the $15 million limit. Gifts exceeding the annual exclusion may require you to file IRS Form 709, even when no tax is due.

The important distinction is that the lifetime gift tax exemption and estate tax exemption are shared, not separate allowances. For example, if you make $2 million in taxable gifts during your lifetime, that amount generally reduces the exemption remaining for your estate. Any unused exemption may apply to assets transferred at death, helping determine whether your estate owes federal estate tax.

When do you need to file form 709?

You generally need to file IRS Form 709 if you give more than $19,000 to one person in 2026, unless a specific exception applies. The form reports gifts exceeding the annual exclusion and helps the IRS track your use of the lifetime gift tax exemption.

The filing requirements, deadline and potential tax implications are important to understand before submitting your return.

Who Must File Form 709?

The person giving the gift is generally responsible for filing. You may need to file if your gifts to one recipient exceed the annual exclusion, you transfer certain future interests, or you elect to split gifts with your spouse.

When Is Form 709 Due?

The deadline is generally April 15 of the year following the gift. For gifts made in 2026, the filing deadline is April 15, 2027. An extension may be available, but it does not automatically extend the deadline for paying tax owed.

Does Filing Form 709 Mean You Owe Tax?

No. Filing the form does not automatically mean you owe gift tax. Gifts above the annual exclusion generally reduce your lifetime gift and estate tax exemption. Federal gift tax is typically payable only after your available exemption has been exhausted.

Gift tax vs Estate tax: how they connect

Gift tax and estate tax share one combined lifetime exemption. In 2026, the federal gift and estate tax exemption is $15 million per individual. This means large gifts made during your lifetime and assets transferred after your death generally count toward the same exemption.

If you give a substantial amount of money while alive, the portion exceeding the annual gift tax exclusion generally reduces the exemption remaining for your estate. For example, if you make $2 million in taxable gifts, that amount generally reduces your remaining exemption to $13 million, assuming no other taxable transfers or adjustments.

Alternatively, leaving the money in your estate means its value may be considered when calculating estate tax after your death. If your total taxable estate and applicable prior gifts remain within your available exemption, federal estate tax generally will not be due.

The main difference is when the transfer happens and how the assets are valued. Lifetime gifting can help transfer wealth earlier, but the best approach depends on your financial circumstances, future needs and estate planning goals.

If you're sending money as a gift to family members abroad, it's also worth considering transfer fees and exchange rates. For example, you can send money from the US to Mexico or send money from the US to India using available international transfer services. Just remember that sending money internationally doesn't automatically exempt a gift from US tax reporting requirements.

Frequently asked questions about gift taxes

Does the person receiving a Gift pay tax on it?

Generally, no. Under US federal tax rules, the recipient does not pay income tax on money received as a gift. The person giving the gift is usually responsible for any applicable gift tax reporting and payment. However, income generated by gifted assets may be taxable to the recipient.

Can you gift more than the annual exclusion without paying tax?

Yes. Gifts exceeding the 2026 annual exclusion of $19,000 per recipient may require you to file Form 709. However, the excess generally reduces your lifetime gift and estate tax exemption rather than triggering immediate tax. Gift tax usually becomes payable after the available exemption is exhausted.

Do Gifts to a spouse count toward the annual exclusion?

Generally, gifts to a US-citizen spouse qualify for the unlimited marital deduction and do not count toward the annual exclusion. Gifts to a non-US citizen spouse have a separate annual limit, which is $194,000 for 2026. Special rules may apply depending on the circumstances.

Is money sent to family abroad treated as a Gift for tax purposes?

Yes. Money sent to relatives abroad may qualify as a gift under US tax rules. If the giver is subject to US gift tax, the annual exclusion and reporting requirements may apply regardless of where the recipient lives.

Do you have to report a Gift from a foreign relative?

You may need to. US persons who receive gifts exceeding $100,000 in total from a nonresident alien individual or foreign estate generally must report them on Form 3520. Different thresholds apply to gifts from foreign corporations or partnerships.

What is the penalty for not filing Form 709 when required?

Failure to file Form 709 when required may result in penalties based on the unpaid gift tax, generally 5% per month, up to 25%. If no tax is due, penalties may differ, but the IRS can still assess consequences for noncompliance. Filing requirements should be checked carefully.

Managing money across borders involves more than understanding gift tax. Whether you are supporting family abroad, making international payments or managing everyday expenses, having the right financial tools matters. Grey offers multi-currency accounts and virtual cards that make it easier to manage international finances, pay for online services and handle supported cross-border transactions.

How creators earn from global audiences in 2026

•

•

2 min read

Some years ago, most creators focused on building audiences in their own countries. In 2026, that strategy feels outdated. The most successful creators today earn from audiences scattered across continents. Viewers in Lagos are watching content made in London, subscribers in New York are supporting creators based in Berlin, and brand deals are flowing from Singapore to São Paulo. Everything is global now.

The new creator economy has changed how people build sustainable creative careers. Geography still matters, but in a different way. Where your audience lives now determines how much you earn, which currencies you collect, and how efficiently you can access your money. Understanding these dynamics separates creators who thrive from those who struggle despite growing followings.

Why global audiences matter more than ever in 2026

Global audiences unlock earning potential that local audiences alone can’t match. A creator with 100,000 followers in the UK might earn differently from someone with the same following split between the US, Canada, Australia, and the UAE. The value of the audience matters more than the volume. I’ll explain.

Platforms pay creators based on where viewers live. Ad revenue from viewers in high-GDP countries typically pays more than from viewers in lower-GDP regions. Brand deals follow similar patterns, with companies in certain markets willing to pay significantly more for creator partnerships. Subscription platforms like Patreon or YouTube memberships charge differently by region, affecting how much creators actually receive per subscriber.

In 2026, smart creators analyse where those followers live and how that geography translates into income. A deliberately global audience strategy can double or triple earnings compared to focusing on a single market.

The main ways creators earn from global audiences

In 2026, creators monetise through multiple streams, and the most successful creators diversify rather than rely on a single source.

Ad revenue

This remains foundational for video creators. YouTube, TikTok, and other platforms share ad revenue based on views, but the payouts vary dramatically by viewer location. A thousand views from viewers in the United States typically generate more revenue than the same views from viewers in India or Brazil. Creators building global audiences must quickly learn which regions drive the highest CPMs (cost per mille, or revenue per thousand views).

Brand partnerships and sponsorships

This is also another very viable way to earn. A creator based in South Africa might work with brands headquartered in Germany, the UK, or Singapore. These deals often pay in USD, EUR, or GBP, regardless of the creator’s location, creating both opportunities and sometimes complexities in payment collection.

Affiliate marketing

This works globally but converts differently across regions. Products with international appeal, like software subscriptions, digital courses, and fashion, perform well with diverse audiences. Creators earn commissions when audiences purchase, and those commissions typically flow in the currency of the affiliate platform or merchant.

Subscriptions and memberships

The most common methods are through Patreon, YouTube, Substack, or other creator-owned platforms that generate recurring income. These platforms often handle multi-currency pricing, but creators still need to manage receiving payments in various currencies and converting them efficiently.

Digital products and courses

You can create a course in Nigeria and sell it to students in Canada, Australia, and the UAE simultaneously. Payment processors handle transactions in local currencies, but creators receive payouts in whichever currencies their payment setup supports.

Live gifting and tipping

On platforms like TikTok Live and Twitch, gifting has become a significant revenue stream. Audiences send virtual gifts during live streams, which convert to real money. The value of those gifts and the payout structures vary by platform and region.

How platforms pay creators differently by country

Not all views, clicks, or engagements are worth the same. Platforms calculate creator payouts based on advertiser demand in each region, and that demand fluctuates significantly.

Ad revenue from viewers in the United States, Canada, the UK, Australia, and parts of Western Europe typically pays the highest CPMs. Viewers in these regions see more ads, those ads cost more, and platforms share higher percentages with creators. A creator whose audience skews heavily toward these markets earns more per view than someone with identical content, but whose audience is concentrated in regions with lower advertiser spending.

Platform bonuses and creator funds also vary by location. Some platforms offer incentive programmes only in certain countries, or pay different amounts depending on the creator's location. A creator in Kenya and a creator in the UK producing similar content might qualify for different bonus structures simply based on geography.

This doesn’t mean creators outside high-CPM regions can’t succeed; it means they need larger audiences or stronger monetisation strategies beyond ad revenue to reach similar income levels.

The role of currency and exchange rates in creator earnings

Currency matters more than most creators realise until they start earning internationally. Many brand deals, affiliate programmes, and platform payouts happen in USD, EUR, or GBP. If you live outside those currency zones, you’re constantly converting money and losing a percentage each time unless you’ve set up efficient payment systems.

Exchange rates fluctuate daily. A brand deal worth $5,000 might convert to different amounts in your local currency depending on when you receive payment and how you convert it. Creators earning consistently in foreign currencies face a choice: convert immediately and accept whatever rate applies that day, or hold funds in foreign currency and convert strategically when rates improve.

Traditional banks typically offer poor exchange rates, often 3 - 5% worse than mid-market rates. Over time, this adds up. A creator earning $60,000 annually could lose $1,800–$3,000 in currency conversion fees if they're not paying attention.

LDMAG1

How smart creators receive global payments

The payment infrastructure you choose directly impacts how much money you actually keep. Many creators lose parts of their earnings to unnecessary fees, poor exchange rates, and inefficient transfer methods simply because they haven’t optimised how they collect income.

PayPal is ubiquitous but expensive for international creators. It charges transaction fees, applies unfavourable exchange rates, and withdrawal fees vary by country. A creator receiving $1,000 might see $920-$940 after PayPal’s various fees.

Stripe and similar payment processors work well for selling products or services, but still involve conversion fees and withdrawal costs for non-US creators.

Direct bank transfers via SWIFT are slow and expensive. International wires can take a week, and you spend a lot on combined fees from sending and receiving banks, plus poor exchange rates.

Payoneer is popular among creators working with international platforms. It offers multi-currency receiving accounts and reasonable fees, though conversion costs still apply.

Wise offers transparent exchange rates and multi-currency accounts, making it a strong choice for creators managing income across multiple currencies.

Grey is designed specifically for people earning internationally. You can create USD, EUR, and GBP accounts, allowing brands and platforms to pay directly without the complications of international transfers. You can hold funds in the original currency and convert only when you choose, at transparent rates. This matters when you’re managing income from multiple countries and want control over timing and conversion costs.

How creators can grow and monetise international audiences

Building a global audience starts with understanding platform algorithms that favour certain content types and specific regions. Creators who want international reach produce content with broad appeal and are less reliant on hyper-local references, available in widely spoken languages, or subtitled for accessibility.

Monetisation follows audience development. As your international audience grows, explore revenue streams that work across borders: digital products, memberships, affiliate partnerships with global brands, and sponsorships from companies targeting multiple markets.

Engage directly with your global community. Time zone differences mean some of your audience is always awake. Creators who interact across time zones build stronger international communities, which translates to better retention and higher lifetime value per follower.

What’s next for global creator earnings

The creator economy will continue globalising. Platforms are expanding creator programmes into more countries, payment infrastructure is improving, and brands increasingly view creators as global marketing channels rather than local influencers.

Expect more tools designed specifically for cross-border creator income, better multi-currency accounts, streamlined tax handling for international earnings, and platforms that simplify receiving money from anywhere. Creators who understand these systems early will have significant advantages.

Currency volatility, regulation changes, and platform policy shifts will create ongoing challenges. Still, the fundamental trend is clear: creators who think globally and build systems to manage international income will outperform those who don’t.

The world is now a creator’s marketplace

Geography used to limit creative careers. In 2026, it defines opportunity. Where your audience lives, which currencies you earn, and how efficiently you collect income directly impact your success as a creator.

The creators thriving today aren’t necessarily the most talented; they’re the ones who understand the business infrastructure behind global audiences. They’ve optimised how they receive payments, minimised fees and exchange-rate losses, and built systems that scale as their audiences grow.

If you’re earning from multiple countries, managing several currencies, or frustrated by how much money disappears between brands paying you and money reaching your account, your payment infrastructure needs attention. Grey helps creators receive, hold, and manage international payments in USD, EUR, and GBP, with accounts that work like local accounts for your global income. Open your free account or download the app and keep more of what you earn.

‍

Offshore accounts vs international bank accounts explained

•

•

2 min read

Offshore and international bank accounts are two distinct concepts, but they are often confused because some of their features overlap. If you have been trying to wrap your head around managing your finances across borders, then you have probably come across these terms. This article explores offshore accounts and international bank accounts to help you see their similarities, note the differences, and understand which of the two best meets your financial needs.

What is an offshore bank account?

The easiest way to explain an offshore account is that it is a bank account you open in a country where you don't live. An offshore account is a bank account opened outside your country of residence, usually in a jurisdiction known for financial services, foreign investment, or wealth management. Historically, offshore accounts were associated with tax planning, asset protection, and international investing.

Offshore accounts are often opened in countries such as Switzerland, Singapore, the Cayman Islands, or the Channel Islands. They are typically offered by traditional banks and often require a higher minimum balance, in-person verification, or extensive documentation.

Of course, many people believe offshore bank accounts are illegal and are commonly linked with politicians and business owners looting money or hiding from taxation. This is a misconception, as offshore accounts are completely legal and must be reported to the right financial authorities.

Offshore accounts are commonly used for:

  • Holding large sums of money
  • Long-term wealth preservation
  • International investments and trusts
  • Asset protection in politically or economically unstable regions

Also read: The easiest way to open an offshore bank account online for free

What is an international bank account?

On the other hand, an international bank account is designed to help individuals receive, hold, send, and spend money across multiple countries and currencies. These accounts are often provided by international banks (like HSBC and Standard Chartered), digital banks, or fintech platforms rather than traditional offshore banks. Unlike offshore accounts, international bank accounts are typically accessible online, have low or no minimum balances, and are built for everyday use by freelancers, remote workers, travellers, and globally mobile professionals.

LDMAG1

International accounts usually allow you to:

  • Manage multiple currencies (e.g. GBP, USD, EUR).
  • Receive international payments easily.
  • Convert currencies at transparent rates.
  • Spend internationally with physical or virtual cards.

Also read: 5 red flags when choosing an international payment platform

What are the differences between offshore accounts and international bank accounts?

Here are the key differences between the two:

Location: Offshore means the account is outside your country of residence, typically in jurisdictions with low tax rates and some financial privacy. International accounts don't have that requirement. They could be right in your country and support cross-border transactions.

Perks: Offshore accounts are often used to reduce taxes, protect assets, and maintain some financial privacy. International bank accounts are more about making international transactions, saving in stable currencies, and making currency conversions more convenient.

Access: Offshore accounts are usually more difficult to assess, as some require your physical presence to open an account. It also comes with higher fees and a minimum balance. International bank accounts are easier to open and access through digital platforms, enabling people to open and manage accounts anywhere.

Currency support: Offshore accounts typically impose currency restrictions, whereas most international accounts support USD, EUR, and GBP transactions.

Also read: Global accounts vs traditional exchange houses: which is better?

Managing international payments with Grey

Offshore accounts and international bank accounts serve very different purposes. Offshore accounts focus on where wealth is stored, while international bank accounts focus on how money moves. Understanding this distinction helps you choose the right tool for your financial goals. If you are looking for an international account that supports USD, EUR, and GBP transactions, then Grey is the most reliable platform. It offers low transaction fees, no hidden charges, favourable conversion rates, and swift payment processing. Grey is tailored to help global people make global transactions with ease.

Sign up on Grey or download the app for seamless cross-border payments.

‍

How to receive YouTube earnings in Nigeria

•

•

2 min read

If you’re a Nigerian YouTuber close to monetisation, first congratulations. You’ve earned it, or at least you’re about to. Now it’s important to understand how YouTube will pay you and how to properly set up your payment details, so you don’t lose out on your funds.

In this article, I will share exactly how YouTube pays creators, and what Nigerian creators need to do to maximise earnings.

How YouTube actually pays creators

YouTube doesn’t pay you directly. Instead, they pay through Google AdSense, which is Google’s advertising platform. When you’re accepted into the YouTube Partner Programme, you link your YouTube channel to an AdSense account, and that’s where your earnings accumulate.

AdSense pays in US dollars (USD). There’s a minimum payout threshold of $100, meaning you won’t receive anything until your earnings reach at least $100. Once you cross that threshold, AdSense processes payments monthly, typically between the 21st and 26th, for the previous month’s earnings.

So if you earn $150 in January, AdSense will pay you sometime between 21st and 26th February. Simple enough in theory, but where does that money actually go, and how do you access it in Nigeria?

Also read: How Indian YouTube creators receive their earnings from overseas

What do Nigerian creators need to be eligible?

To receive YouTube earnings in Nigeria, you need a few things in place:

A monetised YouTube channel: This means you’ve been accepted into the YouTube Partner Programme (1,000 subscribers, 4,000 watch hours in the past 12 months, and adherence to YouTube’s policies).

A Google AdSense account: You’ll create this when applying for monetisation. Make sure your AdSense account has your correct legal name and address.

A valid payment method: This is where it gets tricky for Nigerian creators. AdSense needs a way to send you money, and not every method works smoothly in Nigeria. I’ll discuss this in-depth later.

Tax information: AdSense requires you to submit tax details, even if you’re not in the US. Nigerian creators typically complete a W-8BEN form, which confirms that you’re a foreign person not subject to US tax withholding on most AdSense earnings.

Also read: How South Africans can receive YouTube payments from abroad

The problems Nigerian creators run into with receiving YouTube earnings

The first time I set up an AdSense payout, I added a Nigerian bank account and assumed everything would work smoothly. It didn’t.

First problem, delays. My first payment took nearly two weeks to arrive after AdSense marked it as sent. I had no visibility into where the money was or why it was taking so long.

The second problem was the fees and exchange rates. When the money finally arrived, I lost around 5 - 6% due to a combination of receiving fees and a terrible exchange rate set by my bank. On a $200 payout, that’s $10 - $12 gone, money I’d worked hard to earn.

I realised quickly that relying solely on wire transfers to a Nigerian bank wasn’t sustainable. I needed a better system.

Also read: How Ghanaian YouTubers can collect USD earnings

LDMAG1

How to receive YouTube payouts properly

After some research and talking to other Nigerian creators, I eventually figured out what actually works. The key is using a service that provides a US bank account or a more efficient way to receive USD payments than traditional Nigerian banks.

Here’s what I did:

Step 1: I opened an account on a platform that provides virtual USD accounts. Most people recommended Grey, and I obliged. Platforms like this give you US banking details (account number and routing number) that you can add to AdSense as your payout method. When AdSense sends payments, they go to this account instead of directly to a Nigerian bank.

Step 2: I updated my AdSense payment settings. In AdSense, under Payments > Payment methods, I added my new US bank details. AdSense verified the account by making small test deposits, which I confirmed.

Step 3: I waited for my next payout cycle. Once my earnings crossed $100 again, AdSense sent the payment to my US account. It arrived within 3 - 5 days, much faster than wire transfers to Nigerian banks.

Step 4: Instead of being forced to convert USD to naira immediately at whatever rate my bank decided, I held the money in USD and converted it when rates were favourable. I also had the option to spend directly from a USD card or withdraw to my Nigerian bank account.

This setup solved every problem I’d been facing: faster payments, better control over exchange rates, and no rejected transfers.

Also read: Valentine’s Day trips that work for remote couples

Tips I’d give a Nigerian YouTuber

Set up your payment method before you hit $100: Don’t wait until you’ve earned your first payout to sort this out. Get your USD account ready early so there are no delays when you finally qualify for payment.

Don’t rely on traditional wire transfers unless you have no other option: The fees and delays aren’t worth it. Get a free USD account with Grey, Wise to gain better control and faster access to your money.

Keep your AdSense details accurate: Make sure your name, address, and tax information match your official documents. Mismatches can delay payments or cause verification issues.

Track your earnings and fees: Know how much you’re actually receiving after conversion and fees. This helps you plan better and understand the real value of your content.

Focus on creating consistent content: The payment setup is important, but your primary job is still making videos people want to watch. Sort out the money side once, then get back to creating.

Create more, stress less

Once you’ve sorted out a reliable payment method, you can focus on making great videos and growing your audience.

Set up your USD receiving account now, link it to AdSense, and get back to creating. Your content deserves to be rewarded properly, and you deserve to receive that money without unnecessary stress.

Open your free Grey account today, or download the app, and start receiving your YouTube earnings faster, at better rates, and with full control over your money. Because you’ve earned it, you should actually get to keep it.

‍

Receiving foreign income in Morocco without a domiciliary account

•

•

2 min read

Is it possible to receive foreign income in Morocco without a domiciliary account? The simple answer is yes. However, it is not always straightforward, especially with the wrong payment services.

Domiciliary (foreign currency) accounts were once the standard for Moroccans earning in USD, EUR, or GBP, but they are becoming less popular. Opening one often involves extensive paperwork, multiple bank visits, minimum balance requirements, and strict compliance with local regulations. Beyond these,  SWIFT fees, intermediary charges, and poor conversion rates when converting to MAD make them too expensive for the average person.

The good thing is that you don’t need a traditional domiciliary account at banks such as Attijariwafa Bank or Banque Centrale Populaire to manage international payments efficiently. Freelancers, remote workers, and expats earning from abroad can not find alternatives that suit their needs.

This article explains how Moroccans can receive foreign income without a domiciliary account and describes the pros and cons of each option.

Why do many Moroccans avoid domiciliary accounts?

A domiciliary account allows you to receive foreign currencies without immediate conversion to MAD. On paper, this sounds ideal. In practice, these accounts come with significant problems. A domiciliary (or foreign currency) account allows you to receive USD, EUR, or GBP without automatically converting to MAD. However, these accounts have considerable limitations, including:

  • You have to visit the banking hall.
  • It might require cumbersome paperwork.
  • It takes a while to open an account.
  • SWIFT fees and other bank charges can eat into earnings.
  • There is limited flexibility when trying to make online payments and subscriptions.
  • Transactions may take a few days to complete.

How Moroccans receive foreign income without a domiciliary account

There are three main alternatives: online payment platforms, fintech multi-currency accounts, and cash pickup services. Each serves a different purpose, depending on how often you get paid and how much control you want over your money.

LDMAG1

PayPal

PayPal is one of the most widely recognised international payment platforms. Many foreign clients already trust and use PayPal, which makes it easy to request payments without lengthy explanations or setup.

PayPal allows Moroccans to receive payments in foreign currency and withdraw funds to a local bank account or card. Transactions are usually instant, and the platform is easy to use. However, PayPal is designed more for convenience than cost efficiency. Withdrawal requires automatic conversion to MAD, often at exchange rates that include hidden mark-ups. Fees can be substantial, especially for regular income, and users have little control over when or how conversion happens. There are also frequent reports of account restrictions and suspensions that can interrupt your cash flow or lead to losses.

PayPal works best for occasional payments or short-term use, but it becomes expensive and restrictive for consistent freelance or remote income.

Fintech platforms and multi-currency accounts

This is easily a top recommendation for managing international payments in Morocco. Most of these platforms are designed to address the challenges posed by the rigid traditional domiciliary account payment system. They let you complete cross-border transactions like it is local payments and convert to MAD whenever you like.

Also read: Top digital nomad hotspots in Morocco for remote workers

Grey

Grey offers Moroccans USD, EUR, and GBP account details that you can share directly with international clients or employers.  You can hold your income in foreign currency, convert it to MAD when exchange rates are favourable, and withdraw it to your Moroccan bank account.

Grey also supports automated invoicing, integrates with freelance platforms, and provides virtual cards for paying subscriptions, tools, and services directly in foreign currency. This setup gives freelancers and remote workers far more control over exchange timing, fees, and spending, making it well-suited for regular international income.

Also read: How freelancers in Morocco can switch from traditional banks to Grey

Payoneer

Payoneer is widely used by freelancers working with global marketplaces and companies. It offers foreign accounts and allows withdrawals to Moroccan bank accounts. Payoneer is reliable and well-integrated with major freelance platforms, but its fee structure can be cumbersome. Currency conversion and withdrawal fees can be relatively high, and customer support is often slow. It remains a practical option for platform-based freelancers, though it offers less flexibility than newer fintech solutions.

Wise

Wise is known for transparent pricing and mid-market exchange rates. While it offers strong multi-currency functionality globally, features for Moroccan residents are limited, especially regarding local withdrawals and employer payments. Wise is effective for individuals with international banking needs, but may not be the most seamless solution for Moroccan-based freelancers who rely on frequent payouts.

Also read: Freelancing legally in Morocco: licences, taxes and foreign income rules

Cash pickup services

Cash pickup services are another way to receive foreign income without a domiciliary account, but you should treat them more like a fallback than as your main payment solution.

MoneyGram and Western Union allow senders abroad to transfer money for cash pickup in Morocco without a bank account. These services provide fast access to cash and nationwide availability. However, they come with high fees, unfavourable exchange rates, and low transaction limits. They are also not recommended for freelancers and remote workers with regular foreign income, invoicing, and financial  planning.

Managing international payments with Grey

You don’t need a domiciliary account to receive foreign income in Morocco. Freelancers, remote workers, and expats who regularly earn in USD, EUR, or GBP need an alternative that suits their needs. Grey offers you control over exchange rates, lower fees, faster payment processing, and the flexibility required to manage a global income. With the newly improved Grey cards, you now manage your payments globally by creating multiple cards, spend directly from your balance without top ups, and link with Apple Pay and Google Pay. Grey bypasses the paperwork and restrictions of domiciliary accounts, allowing you maximise you income without hassles.

Sign up for a Grey account by downloading the app to manage your foreign income with ease.

‍

Arrow (up)

Back to top
