<script type="application/ld+json">[{"@context": "https://schema.org", "@type": "BlogPosting", "@id": "https://grey.co/blog/cancel-wire-transfer#article", "headline": "How to Cancel a Wire Transfer: What Banks Can and Cannot Do | Grey", "description": "Can you cancel a wire transfer after sending? What banks can and cannot do, and how to act fast if you sent money to the wrong account. Read now.", "inLanguage": "en", "url": "https://grey.co/blog/cancel-wire-transfer", "mainEntityOfPage": {"@id": "https://grey.co/blog/cancel-wire-transfer#webpage"}, "datePublished": "2026-09-24T01:11:48.615Z", "dateModified": "2026-09-24T01:11:55.982Z", "author": {"@type": "Person", "name": "Tunde Aladeloba"}, "publisher": {"@type": "Organization", "@id": "https://grey.co/#organization", "name": "Grey", "url": "https://grey.co"}, "image": "https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6ab478c106dae77fc12d63ca_How%20to%20Cancel%20a%20Wire%20Transfer-compressed.jpg"}, {"@context": "https://schema.org", "@type": "BreadcrumbList", "@id": "https://grey.co/blog/cancel-wire-transfer#breadcrumb", "itemListElement": [{"@type": "ListItem", "position": 1, "name": "Home", "item": "https://grey.co/"}, {"@type": "ListItem", "position": 2, "name": "Blog", "item": "https://grey.co/blog"}, {"@type": "ListItem", "position": 3, "name": "How to cancel a wire transfer: What banks can and cannot do", "item": "https://grey.co/blog/cancel-wire-transfer"}]}, {"@context": "https://schema.org", "@type": "FAQPage", "@id": "https://grey.co/blog/cancel-wire-transfer#faq", "mainEntity": [{"@type": "Question", "name": "How long does a wire transfer recall take?", "acceptedAnswer": {"@type": "Answer", "text": "A wire transfer recall can take several business days, depending on the banks involved, the payment route, and whether the receiving bank cooperates. There is no universal timeline, but international recalls can take longer because multiple institutions may need to review and process the request."}}, {"@type": "Question", "name": "Can a bank reverse a wire transfer?", "acceptedAnswer": {"@type": "Answer", "text": "A bank may be able to stop a wire transfer before it is processed. Once the payment has been sent, however, the bank generally cannot simply reverse it. It may submit a recall request to the receiving bank, but recovery depends on the circumstances and is not guaranteed."}}, {"@type": "Question", "name": "What happens if you send a wire to the wrong account?", "acceptedAnswer": {"@type": "Answer", "text": "Contact your bank immediately and provide the transfer details and reference number. Your bank may be able to stop the payment if it is still pending or submit a recall if it has already been sent. Recovery depends on whether the funds remain available."}}, {"@type": "Question", "name": "Is it possible to cancel a Zelle or ACH transfer?", "acceptedAnswer": {"@type": "Answer", "text": "It depends on the payment. Some Zelle payments cannot be cancelled once they have been sent to an enrolled recipient. ACH payments may sometimes be stopped before processing, but the rules depend on the bank, payment status, and type of ACH transaction."}}, {"@type": "Question", "name": "Who do I contact if my bank will not help with a wire recall?", "acceptedAnswer": {"@type": "Answer", "text": "Start by asking for the bank’s wire transfer or fraud department and request a clear explanation of your options. If the issue remains unresolved, you can ask about the bank’s formal complaint process and the relevant financial regulator or dispute-resolution body in your country."}}]}]</script>

How to cancel a wire transfer: What banks can and cannot do

Tunde Aladeloba

TABLE OF CONTENT

SHARE THIS POST

There is a particular kind of panic that comes after sending a wire transfer and realising something is wrong. Maybe the account number was incorrect, you sent more money than you intended, or the person you were paying suddenly looks suspicious. You check the transaction again, hoping there is a button somewhere that says “cancel.”

Sometimes, there is still time. A wire transfer may be stopped before your bank processes it, which is why contacting the bank immediately matters. But once the money has left your bank, things become more complicated. Your bank may need to request a recall from the receiving bank, and getting the money back is no longer guaranteed.

For someone sending money across countries or between different banks, that uncertainty can be frightening. You may be wondering whether the recipient has received the funds, whether your bank can actually reverse the payment, or what happens if the transfer was fraudulent.

This guide explains when you can cancel a wire transfer, what happens after processing, and what to do if you need your money back.

Can you cancel a Wire transfer after sending?

The first few minutes after sending a wire transfer can make all the difference. You may still be able to stop the payment, but once your bank has processed it, cancelling it becomes much harder.

When you send a wire, the transaction generally moves through two stages. Initiation is when you submit the payment and your bank is still processing the instruction. During this stage, there may be a narrow window to cancel the transfer, although the exact timing varies by bank and payment method.

The second stage is settlement, when the funds move through the banking system to the recipient’s bank. Once the transfer has been processed and settled, you usually cannot simply cancel it. Your bank may instead need to request a recall, which the receiving bank may accept or refuse.

This is different from an ACH payment, so understanding the difference between ACH and wire transfer can help you know what options you have.

How to stop a wire transfer

When a wire transfer needs to be stopped, speed matters more than almost anything else. The sooner your bank knows there is a problem, the more opportunity it may have to act before the payment is processed.

  1. Call your bank immediately. Do not rely on email or a support form when every minute could matter. Tell the bank you need to stop a wire transfer and explain why.
  2. Give the transfer reference number. Have the transaction details ready, including the amount, date, recipient and reference number, so the bank can locate the payment quickly.
  3. Ask what action is possible. If the transfer is still pending, request a cancellation. If it has already been sent, ask the bank to submit a recall request. The process can vary depending on the bank and transfer type.
  4. Follow up in writing. After your call, send a written request through the bank’s approved channel so there is a record of your instruction.
  5. Ask for confirmation. Confirm that your cancellation or recall request has actually been submitted and ask what happens next.

If you regularly send money internationally, the international wire transfer guide can also help you understand how these payments move between banks.

What happens when you request a wire recall

Once a wire transfer has left your bank, getting the money back becomes a different process. Instead of simply cancelling the payment, your bank may need to start a formal wire recall, asking the receiving bank to return the funds.

The request usually moves between the two banks rather than directly between you and the recipient. The receiving bank then checks whether the money is still available in the recipient’s account and whether its procedures allow the funds to be returned. In some cases, the account holder may also need to consent before the money can be released.

That is where the outcome can become uncertain. If the funds are still sitting in the account and the recipient agrees, the recall may succeed. If the money has already been withdrawn, the receiving bank may refuse the request. It is also possible for a bank not to respond to the request.

A recall can take around 7 to 14 business days, although the timeline varies between banks and circumstances. Most importantly, submitting a recall does not guarantee that your money will be returned.

When a wire transfer cannot be recalled

A recall is not always enough to bring your money back. Once the transfer has reached the receiving bank, several things can make recovery difficult or even impossible.

The most obvious problem is that the funds have already been withdrawn from the recipient’s account. Your bank can still submit a recall request, but the receiving bank may have nothing left to return.

The process can also become more complicated if the receiving bank does not participate in the SWIFT recall process. Transfers involving a cryptocurrency exchange may present another challenge because the money can move through a platform rather than remain in a traditional bank account.

The recipient’s location can matter too. If the account is in a country with limited cooperation between financial institutions, your bank may have fewer options for recovering the funds.

This is why acting quickly matters. If you have just sent a payment and need to cancel a wire transfer, contact your bank immediately rather than waiting to see what happens.

How to reduce the risk of sending to the wrong account

A few minutes of checking before you send money can save you from a much bigger problem later. Start by verifying the recipient’s account details by phone, especially when you are making a payment for the first time or sending a large amount.

For larger transfers, use a confirmation call-back procedure so the payment details are confirmed through a trusted contact method rather than simply replying to an email. Then check the IBAN or account number digit by digit before authorising the transfer. One incorrect number can send the payment somewhere you did not intend.

Be especially careful when someone emails you to say their bank details have changed. Confirm the new details independently before making the payment.

These simple checks can also help you avoid some of the top money transfer scams to avoid, particularly those that rely on fake payment instructions.

Frequently asked questions

How long does a wire transfer recall take?

A wire transfer recall can take several business days, depending on the banks involved, the payment route, and whether the receiving bank cooperates. There is no universal timeline, but international recalls can take longer because multiple institutions may need to review and process the request.

Can a bank reverse a wire transfer?

A bank may be able to stop a wire transfer before it is processed. Once the payment has been sent, however, the bank generally cannot simply reverse it. It may submit a recall request to the receiving bank, but recovery depends on the circumstances and is not guaranteed.

What happens if you send a wire to the wrong account?

Contact your bank immediately and provide the transfer details and reference number. Your bank may be able to stop the payment if it is still pending or submit a recall if it has already been sent. Recovery depends on whether the funds remain available.

Is it possible to cancel a Zelle or ACH transfer?

It depends on the payment. Some Zelle payments cannot be cancelled once they have been sent to an enrolled recipient. ACH payments may sometimes be stopped before processing, but the rules depend on the bank, payment status, and type of ACH transaction.

Who do I contact if my bank will not help with a wire recall?

Start by asking for the bank’s wire transfer or fraud department and request a clear explanation of your options. If the issue remains unresolved, you can ask about the bank’s formal complaint process and the relevant financial regulator or dispute-resolution body in your country.

When a wire transfer goes wrong, acting quickly can make a real difference, but prevention is still your strongest protection. Grey gives you another way to manage international money with a multicurrency account, while the Grey virtual card lets you spend from your balances when needed. You can sign up or download the app to get started.

More from Grey

Wire transfer vs ACH: cheapest way to receive USD

A freelancer’s guide to avoiding payment scams online

Last updated:

September 24, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to open a Euro bank account in the UK

2 min read

London remains the heavyweight of global foreign exchange, accounting for 37.8% of global FX turnover. With so much international money moving through the UK, it makes sense that you may need an easier way to manage euros without constantly converting your money back to pounds. Whether you work with European clients, receive payments from abroad, study in Europe, or regularly spend euros, a euro bank account can give you more control over when and how you convert your money.

A euro bank account lets you hold, receive, send, and spend euros while living in the UK, and you do not necessarily need a European address or to travel overseas to open one. FinTech platforms such as Wise and Revolut allow eligible UK residents to open euro balances online, while some traditional banks also offer dedicated euro accounts.

This guide explains how to open a euro bank account in the UK, what documents you need, and the options available to you. You’ll also learn how to get a Euro account with a FinTech and use an IBAN to receive eligible SEPA payments.

UK residents can open a euro account through FinTech platforms like Grey, Wise, or Revolut without travelling to Europe or providing a European address. These accounts give you an IBAN to receive SEPA transfers and a euro balance to hold and spend. Traditional UK banks offer euro accounts but typically charge monthly fees of £5 to £25.

Why open a Euro bank account in the UK?

Managing euros from the UK can become expensive and inconvenient when every payment means converting between pounds and euros. A euro bank account lets you receive, hold, and spend euros directly, making everyday international transactions easier to manage.

For example, you may work with European clients and want to receive payments in euros without converting them immediately. If your business pays European suppliers, you can also keep euros ready for invoices instead of converting pounds each time a payment is due. The same applies when you travel regularly in Europe and want to hold euros before your trip rather than relying on last-minute exchange rates.

Since Brexit, opening a bank account in an EU country can also be more complicated for UK residents, with eligibility and residency requirements varying by country and bank. A UK-based euro account can therefore provide a simpler alternative.

You can also use a SEPA transfer guide to understand how euro payments move across participating European countries.

How to open a Euro account online in the UK

Opening an EU bank account from the UK depends on your residency, the provider you choose, and the features you need.

Here are the main options to compare before you apply.

Provider Monthly fee EUR IBAN SEPA receiving Euro card Best for
Grey £0 Yes Yes Virtual Freelancers and contractors
Wise £0 Yes Yes Physical & virtual Multi-currency banking
Revolut £0–£45 Yes Yes Physical & virtual Travel and everyday spending
Starling Bank £0 Yes Yes Yes Traditional UK banking
Monzo £0–£17 No No No Spending GBP while travelling

You can open a Grey Euro account and hold euros, dollars, and pounds in one place without a European address.

Can non-UK Residents open a Euro account in the UK?

Living outside the UK does not automatically prevent you from opening a euro account through a FinTech platform. Eligibility depends on your country of residence and the provider’s requirements, so check the current eligibility list before applying. Grey, for example, currently supports UK and EU accounts for residents of several countries, including Nigeria.

Once eligible, you can use a Grey EUR account to receive euros through SEPA and send euros to supported UK and EEA accounts, giving you a simpler way to manage euro payments without opening a traditional European bank account.

How to get a Euro account: Step by step with Grey

Opening a euro account online can be straightforward when you use a FinTech platform that supports your country of residence. Grey lets eligible users create a EUR bank account digitally, giving you an IBAN for receiving euro payments through SEPA.

  1. Create your Grey account: Sign up with your name, email, phone number, country of residence, and password.
  2. Complete verification: Verify your email, then complete identity verification with your personal details and valid identification.
  3. Open your EUR account: Log in, select Accounts, choose EUR, and click Get account details.
  4. Complete the prompts: Confirm your name, select your reason for opening the account, and provide your work information.
  5. Get your details: Once created, your EUR account details and IBAN will be available in Grey.

Also read: Step-by-step guide to opening a euro account in the UK

Frequently asked questions

Can I get an IBAN as a UK resident?

Yes. As a UK resident, you can get a euro IBAN through eligible banks and FinTech platforms. The exact IBAN country and account features depend on the provider. Some providers issue European IBANs, allowing you to receive eligible euro payments without maintaining a traditional bank account in an EU country.

What is the best Euro account for UK residents?

There is no single best euro account for every UK resident. Your choice depends on whether you need to receive payments, hold euros, make SEPA transfers, spend while travelling, or access physical cards. Compare fees, IBAN availability, supported currencies, exchange rates, and withdrawal options before opening an account.

Do UK banks offer Euro accounts?

Yes. Some UK banks offer euro accounts to eligible customers, although availability and account requirements vary. These accounts can let you hold euros separately from your pounds. Depending on the bank, you may need an existing current account, meet eligibility requirements, or pay additional fees for international banking services.

Can I receive SEPA transfers into a UK Euro account?

Yes, you can receive SEPA transfers into a UK euro account when the account provides SEPA-compatible euro receiving details. However, the UK is no longer part of the EU's Single Market, so check that your specific provider supports incoming SEPA payments before sharing your IBAN with a sender.

Is it free to open a Euro account in the UK?

It can be free, but not always. Some banks and FinTech platforms offer euro accounts with no monthly account-opening fee, while others charge maintenance or transaction fees. You should also check receiving fees, currency conversion charges, card costs, and international transfer fees before choosing an account.

Also read: How to open a USD account in the UK

How to pay US school fees from Nigeria in 2026

2 min read

Every semester, thousands of Nigerian families face the same problem: a tuition invoice denominated in US dollars, a deadline that does not wait, and a banking system that makes international payments slow, expensive, and stressful.

The traditional route is a SWIFT transfer through a Nigerian bank. That means a branch visit, a queue at the forex desk, Form A paperwork for the CBN, fees that can reach 2% to 5% of the transfer amount, and a wait of 3 to 5 business days with no guarantee the payment will arrive in time. For a $10,000 tuition payment, bank fees alone can cost $200 to $500.

There is a faster and cheaper way to handle this. This guide covers how to pay US university tuition from Nigeria using Grey's Nigeria-to-US transfer, what it costs, how to time it so the payment arrives before the deadline, and how to make sure the university's payment office can match the payment to your student's account.

How US universities accept tuition payments

Before you send money, it helps to understand how the receiving side works. US universities typically accept tuition payments through one or more of these methods:

Direct ACH or wire to the university's bank account. The university's bursar or student accounts office provides a bank name, routing number, and account number. You transfer USD to these details, and the university credits it to the student's account. This is the method Grey supports.

Third-party payment platforms. Some universities use services like Flywire, Western Union Business Solutions, or TransferMate, which handle currency conversion on their end. These can be convenient, but typically charge their own fees and apply their own exchange rates. They handle currency conversion and often provide a payment reference that links directly to the student's account, removing the matching problem. The trade-off is cost: Flywire typically charges a fee or uses an exchange rate with a margin. On a $10,000 payment, the total cost through Flywire can range from $50 to $200, depending on the corridor and the rate at the time. Grey's $6 capped fee is lower, but Flywire's integration with the university's billing system means you do not need to worry about payment matching.

Credit or debit card. Some universities accept card payments through their student portal, though many add a 2% to 3% convenience fee on card transactions. On a $10,000 tuition bill, that is $200 to $300 in convenience fees alone, before you account for the cost of funding the card.

If your university provides direct bank details (routing number and account number), paying via Grey is straightforward and avoids the fees charged by third-party platforms. If the university only accepts payment through a specific platform like Flywire, you will need to use that platform, though you can still use Grey to fund a US bank account and then pay from there.

How to pay US tuition from Nigeria with Grey

1. Get the payment details from the university. Contact the bursar's office or student accounts department. Ask for the bank name, ACH routing number, and account number for tuition payments. Also ask what reference or memo to include so they can match the payment to your student's account. This is usually the student ID number.

2. Open and fund your Grey account. If you do not already have a Grey account, download the app, verify your identity with a government ID and BVN, and transfer naira from your Nigerian bank account into your Grey wallet.

3. Convert and send. Tap Send, select USD, and add the university's bank details as a new recipient. Enter the tuition amount in USD. Grey shows the exchange rate, the conversion fee (1% capped at the equivalent of $6), and the exact dollar amount that will arrive. If Grey's transfer form includes a memo or reference field, add the student ID there. If not, email the university's student accounts office separately with the Grey confirmation receipt, along with the student's name and ID number, so they can match the payment. Confirm the transfer.

4. Keep your confirmation receipt. Grey provides a confirmation with the transfer details, amount, and reference. Save this. If the university's payment office needs proof of payment, this receipt serves that purpose. You can also share it directly from the app.

The payment arrives in the university's US bank account within 1 to 2 business days via ACH.

What it costs to pay tuition via Grey

Tuition payments are typically large, which is where Grey's fee cap makes the biggest difference.

Tuition amount Grey conversion fee Grey payout fee Grey total Typical bank SWIFT cost
$5,000 $6.00 (cap) $0 $6.00 $100-$250
$10,000 $6.00 (cap) $0 $6.00 $200-$500
$20,000 $6.00 (cap) $0 $6.00 $400-$1,000
$30,000 $6.00 (cap) $0 $6.00 $600-$1,500

Grey conversion fee is 1% capped at the naira equivalent of $6. No payout fee on USD transfers to the US. Bank SWIFT costs are estimates based on 2-5% fee range typical of Nigerian bank international transfers; actual fees vary by bank and may include additional charges.

On a $10,000 tuition payment, the difference is stark. Grey charges $6 in total fees. A Nigerian bank might charge $200 to $500 or more. Over four years of university (eight semesters), that saving compounds into thousands of dollars that could go towards the student's living expenses instead.

CBN education allowance: what you need to know

The Central Bank of Nigeria provides a specific forex allowance category for education expenses under Form A. Nigerian banks can process education-related outbound transfers under this allowance, which has historically been one of the approved uses of personal forex allocation.

If you are paying tuition through Grey rather than through your bank's forex desk, the CBN allowance structure still applies to your overall forex usage, but the transfer itself is handled by Grey's licensed banking partners. You do not need to complete Form A when paying through Grey. The key constraint is the platform's own transfer limits, which depend on your verification tier.

For very large tuition payments that exceed a single transfer limit, you may need to split the payment across two or more transfers. Grey processes each transfer independently. Make sure to inform the university's payment office that the total will be paid in multiple deposits and, if possible, include the student ID reference on each one.

When to send to make sure it arrives on time

Tuition deadlines are firm. Missing one can result in late fees, holds on registration, or even loss of enrollment. Here is how to time your payment.

Send at least 3 business days before the deadline. Grey delivers in 1 to 2 business days via ACH, but the university may take an additional day to process and match the payment to the student's account. Sending 3 business days early gives you a buffer.

Avoid sending on Fridays or before US holidays. ACH does not process on weekends or US public holidays. A transfer sent on Friday may not arrive until Tuesday. Check the US holiday calendar before scheduling a payment near a deadline.

Know the semester deadlines. Most US universities follow a similar pattern. Fall semester tuition is typically due in late July or August. Spring semester tuition is due in December or January. Summer session fees are due in April or May. Check your university's specific academic calendar for exact dates.

Check the university's payment processing time. Some universities credit ACH payments the same day they arrive. Others take 1 to 2 business days to match the payment to the student's account. Ask the bursar's office how long their processing takes so you can plan accordingly.

Keep a record of every payment. Save the Grey confirmation receipt and take a screenshot of the transfer details. If the university says the payment has not arrived, you can contact Grey support for the transfer reference so they can locate it.

Other ways to pay US tuition from Nigeria

Flywire / TransferMate / Western Union Business Solutions: Some universities partner with these platforms specifically for international tuition payments. If your university requires or recommends one, use it. If they offer direct bank details as an alternative, Grey is typically cheaper because its fee is capped at $6 regardless of the amount, whereas Flywire's total cost for a $10,000 payment can range from $50 to $200.

Grey virtual card: If the university accepts card payments through their student portal, you can use a Grey Rain card (Visa) to pay. Be aware that many universities charge a 2-3% convenience fee on card payments, which would be in addition to Grey's card funding costs. Bank transfer via ACH is almost always cheaper than paying by card.

Nigerian bank SWIFT transfer: The traditional route. Higher fees (2-5% plus flat charges), slower (3-5 business days), and less transparent on the exchange rate. Still necessary if the university requires a wire transfer rather than ACH, though this is uncommon.

Also read: How to send money from Nigeria to a US bank account in 2026 for the full Nigeria-to-US transfer guide covering all use cases, not just tuition.


Frequently asked questions

Can I pay US university tuition directly from Nigeria?

Yes. If the university provides a US bank account (routing number and account number) for tuition payments, you can send USD directly from Nigeria using Grey. The payment arrives via ACH within 1 to 2 business days. Some universities require payment through specific platforms, such as Flywire; check with the bursar's office.

How much does it cost to pay US tuition from Nigeria with Grey?

Grey charges a 1% conversion fee capped at the naira equivalent of $6. There is no payout fee for USD transfers to the US. A $10,000 tuition payment costs $6 in total Grey fees. By comparison, a Nigerian bank SWIFT transfer on the same amount could cost $200 to $500 or more.

How far in advance should I send tuition from Nigeria?

Send at least 3 business days before the tuition deadline. Grey delivers in 1 to 2 business days, and the university may take an additional day to process and credit the payment. Avoid sending on Fridays or before US public holidays, as ACH does not process on non-business days.

How does the university know which student the payment is for?

If Grey's transfer form includes a memo or reference field, add the student ID there. If not, email the university's student accounts office with the Grey payment confirmation receipt and the student's full name and ID number so they can manually match it. Most universities are accustomed to handling this for international payments.

Can I split a tuition payment across multiple transfers?

Yes. If your tuition amount exceeds a single transfer limit, you can send multiple transfers to the same university bank account. Include the student ID on each transfer if possible, and notify the university's payment office that the total will arrive in parts. Most universities are accustomed to receiving split payments from international students.

Do I need Form A to pay US tuition through Grey?

No. Form A is required when processing education forex through a Nigerian bank's forex desk. When you pay through Grey, the transfer is handled by Grey's licensed banking partners, and you do not need to submit CBN paperwork directly. The CBN's forex allowance structure still applies to your overall forex usage, but the process is handled within the app.

Is it better to use Grey or Flywire to pay US tuition?

If your university requires Flywire, use Flywire. If they accept direct bank transfers as an alternative, Grey is typically cheaper because the 1% conversion fee is capped at the equivalent of $6, regardless of the amount. Flywire's fees and exchange rates vary by corridor and are not always published in advance.

Related reading

How to send money from Nigeria to a US bank account in 2026 is the full Nigeria-to-US transfer guide covering all use cases.

How to send money from Nigeria to any country in 2026 covers outbound Nigeria transfers to 50+ countries.

Cheapest way to send money from Nigeria in 2026 compares fees across Grey, Flutterwave Send, Pesa, and Eversend.

Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion. Grey is a financial technology company, not a bank. Banking services are provided by licensed banking partners. This article is general information, not financial advice.

How to send money from South Africa to Nigeria in 2026

2 min read

South Africa is home to one of the largest Nigerian communities on the African continent. Hundreds of thousands of Nigerians live, work, and study in Johannesburg, Cape Town, Pretoria, and Durban, and a significant proportion of them send money back to family in Nigeria regularly.

Until recently, this has remained an expensive corridor. The World Bank has consistently found that sending money within Africa costs more than sending money from Europe or the US to the same destinations. The South Africa-to-Nigeria corridor is no exception. Comparison data from Monito shows that the cheapest available option on this corridor averaged around 4.1% of the transfer amount over the past month. That is roughly four times what you would pay on a US-to-Nigeria transfer through a competitive app.

The reason is structural. There is no deep, liquid forex market directly between the South African rand and the Nigerian naira. Most transfers are converted through an intermediary currency, usually the US dollar: your rand becomes dollars, and the dollars become naira. Each conversion step adds a margin, and those margins add up.

That said, several apps now serve this corridor with meaningfully lower costs than the traditional banking route. This guide covers how to send money from South Africa to Nigeria in 2026, what each option costs, how long transfers take, and which app makes the most sense depending on how much you send and how often.

What South Africans typically send money to Nigeria for

The reasons for sending money from South Africa to Nigeria are as varied as the community itself, but a few use cases come up more often than others. Understanding your use case matters because it affects how much you send, how often, and whether speed or cost is more important.

  1. Family support and living expenses. This is the most common reason. Many Nigerians in South Africa send a fixed amount monthly to parents, siblings, or extended family for food, utilities, rent, and day-to-day expenses. These tend to be regular transfers of R2,000 to R10,000, where consistency matters more than optimising every transaction.
  2. School fees and education costs. Paying school fees for children, siblings, or relatives attending schools and universities in Nigeria. These tend to be larger, less frequent transfers that align with term dates. For these transactions, the pressure to pay on time is real: if fees are not paid by the deadline, the student's place may be at risk.
  3. Medical expenses. These include urgent transfers to cover hospital bills, surgeries, or medications for family members in Nigeria. These are time-sensitive. Speed of delivery matters more than saving 0.5% on the exchange rate. Grey's minutes-to-same-day delivery is a significant advantage for medical emergencies.
  4. Property and investment. Buying land, building a house, or investing in a business in Nigeria. These involve larger amounts (R20,000 to R100,000+) where the fee cap and exchange rate margin make a meaningful difference to the total cost. For very large amounts, check whether you are within the SDA limit of R1 million.
  5. Ceremonies and celebrations. Contributing to weddings, funerals, naming ceremonies, and community events. These are often one-off transfers with a specific deadline, similar in urgency to school fees.

For regular monthly support, the priority is usually consistency and low cost. For emergencies, it is speed. For large lump sums, it is the exchange rate and fee cap. The sections below help you match each priority to the right app.

Why the South Africa-to-Nigeria corridor is expensive

If you have ever sent money from the UK or US to Nigeria, you know the cost is typically 1% to 2% all-in through a good transfer app. The South Africa corridor is more expensive for three reasons worth understanding, as they affect which app you choose.

No direct ZAR-NGN forex market. The rand and naira do not trade against each other in significant volumes on any international exchange. Your ZAR is converted to USD (or sometimes EUR), and then the USD is converted to NGN. Two conversions mean two margins. Apps that minimise the spread on each leg deliver more naira for the same rand.

South African exchange controls. The South African Reserve Bank (SARB) regulates outbound foreign currency payments. Individuals have a Single Discretionary Allowance of R1 million per calendar year for transfers abroad, without the need for a tax clearance certificate. Above R1 million and up to R10 million, you need a Foreign Investment Allowance, which requires tax clearance from SARS. These regulations add compliance overhead for transfer providers, which can translate into higher fees.

Fewer providers compete on this corridor. The US-to-Nigeria and UK-to-Nigeria corridors have dozens of competing apps, which drives fees down. The South Africa-to-Nigeria corridor has fewer players, which means less competitive pressure on pricing. Monito's comparison engine found only one provider to compare on this route. Moneytransfers.com found seven, but several of them are rate estimates only, without live data.

Which apps support sending money from South Africa to Nigeria

The competitive landscape along this corridor is narrower than that on US or UK routes. Here are the main options available to South African senders in 2026.

Grey supports transfers from South Africa to Nigeria via bank transfer. Grey was cited by moneytransfers.com as the quickest option for ZAR-to-NGN transfers, with delivery in minutes. Grey charges a 1% conversion fee on the transfer amount. The fee cap that applies on major currency pairs (USD, EUR, GBP, NGN) may reduce the cost on larger transfers, but whether the cap applies specifically to ZAR-NGN conversions should be confirmed in the app at the time of transfer, since ZAR is not one of the named Group A currencies. The Nigeria payout fee is NGN 35 flat per transaction.

WorldRemit is the most established name on this corridor and was Monito's recommended provider. WorldRemit supports bank deposit and cash pickup in Nigeria from South Africa. Fees range from $0 to $4.99, depending on the amount and delivery method, with an exchange rate margin on top. Cash pickup is available through partner agent networks in Nigeria, which is useful if your recipient does not have a bank account.

LemFi serves the South Africa-to-Nigeria corridor with low or zero visible transfer fees, earning primarily through the exchange rate spread. LemFi has built a strong reputation among the Nigerian diaspora for competitive parallel-market rates. Unlike the outbound-from-Nigeria direction (where LemFi does not operate), LemFi does work for South African senders sending to Nigeria.

Pesa was identified by moneytransfers.com as the cheapest option on this corridor, at roughly 1% cheaper than the second-best provider. As with all Pesa transfers, there is no visible fee. The cost is embedded in the exchange rate. To know the true cost, compare the naira amount your recipient receives on Pesa versus what they would receive through Grey or WorldRemit at the same moment.

Wise operates in South Africa and supports ZAR as a sending currency to many countries. However, Wise's coverage for direct ZAR-to-NGN transfers should be confirmed at the time of transfer, as Wise has historically had restrictions on the Nigeria corridor. If available, Wise would charge a percentage fee (typically 0.5% to 1.5%) with the mid-market exchange rate.

South African banks can process international transfers to Nigeria via SWIFT, but fees are significantly higher. Standard Bank, FNB, Nedbank, and Absa all offer international payment services, with fees that can reach R300 to R1,000 per transfer plus a wide exchange rate margin. The process typically requires a visit to an in-branch or online banking portal, and delivery takes 3 to 5 business days.

How to send money from South Africa to Nigeria with Grey

The process takes a few minutes from your phone. Here is how to do it step by step.

1. Create and verify your Grey account. Download the Grey app, sign up with your email, and verify your identity. You will need a valid government-issued ID (South African ID card, passport, or driver's licence). Verification typically completes within minutes.

2. Fund your account. Transfer funds from your South African bank account into your Grey wallet. Grey supports multi-currency accounts in USD, EUR, and GBP. Your ZAR will be converted as part of the transfer process.

3. Start your transfer. Tap Send, search for Nigerian Naira (NGN), and select it. Choose bank transfer as the delivery method.

4. Add your recipient's details. Enter your recipient's full name, their Nigerian bank name, and their account number. Grey supports all major Nigerian banks including GTBank, Access Bank, Zenith Bank, First Bank, UBA, and every other commercial bank in Nigeria.

5. Enter the amount and review. Type the amount you want your recipient to receive in NGN, or the amount you want to send. Grey shows the live exchange rate, the conversion fee, the NGN 35 payout fee, and exactly how much naira your recipient will receive. Everything is on one screen before you confirm.

6. Confirm and send. Review the summary, confirm with your PIN or 2FA code, and the transfer is processed. Your recipient's Nigerian bank account is credited within minutes to the same day.

Your recipient does not need a Grey account. The naira arrives as a standard bank deposit in their Nigerian bank account.

What your recipient sees in Nigeria

Your recipient receives a standard domestic bank credit in their Nigerian bank account. The deposit arrives in naira and appears like any other inward transfer. Your recipient does not need to download an app, create an account, or take any action before you send.

The naira amount your recipient receives is the amount shown on your confirmation screen in the Grey app. There are no intermediary deductions between what Grey dispatches and what lands in the account. The NGN 35 payout fee is deducted on your end, not on the recipient's end.

If your recipient banks with a Nigerian bank that sends SMS or push notifications for deposits (most do), they will see the credit notification within minutes of you confirming the transfer. This makes it easy to coordinate: you can tell your recipient the exact amount to expect and they can confirm receipt almost immediately.

Component Amount Notes
Conversion fee 1% of the transfer amount The cap at the naira equivalent of $6 applies to Group A pairs (USD/EUR/GBP/NGN). For ZAR conversions, confirm in the app whether the cap applies, since ZAR is not a named Group A currency.
Nigeria payout fee NGN 35 flat per transfer Charged regardless of amount. Applies to all NGN bank transfers.
Total cost on a R5,000 transfer (uncapped) 1% + NGN 35 If uncapped: ~R50 conversion + NGN 35 payout.
Total cost on a R5,000 transfer (if cap applies) ~R100 cap + NGN 35 If the $6 cap applies at current rates.

The conversion fee cap status for ZAR-NGN specifically requires confirmation in the Grey app before sending. The 1% rate applies regardless. NGN 35 payout fee confirmed from support.grey.co. Data checked September 2026.

Even at the uncapped 1% rate, Grey is competitive on this corridor. The Monito average for the cheapest SA-to-Nigeria option was 4.1% of the transfer amount. A 1% conversion fee plus a negligible payout fee is roughly a quarter of that market average.

For context, South African bank SWIFT transfers to Nigeria typically cost R300 to R1,000 in direct fees (roughly $16 to $55) plus a wider exchange rate margin. On a R10,000 transfer, the bank's total cost can easily exceed 5% of the amount when you factor in both the fee and the rate.

How long does it take?

This is significantly faster than the 3 to 5 business days typical of a South African bank SWIFT transfer. If your recipient needs the money urgently, the speed difference alone justifies using a transfer app over a bank.

Understanding the ZAR to NGN exchange rate

The rand-to-naira exchange rate is one of the most volatile African currency pairs. As of recent data, 1 ZAR buys approximately 80 to 85 NGN, but this fluctuates daily based on oil prices, South African economic data, Nigerian forex policy changes, and global dollar strength.

Because there is no deep direct ZAR-NGN market, the effective rate you receive depends on how the provider routes the conversion. Most providers convert ZAR to USD first, then USD to NGN. The tighter the spread on each leg, the more naira your recipient gets.

Grey shows the effective rate on screen before you confirm. You can compare it against the mid-market ZAR-NGN rate on Google or xe.com at the same moment to gauge the margin. If you are not satisfied with the rate, you can wait and check again later. Currency pairs with this much volatility can move 2% to 3% in a single week, which means timing your transfer well can save more than any fee difference between providers.

If you send regularly, consider converting a larger amount when the rate is favourable and holding the balance in your Grey account until you are ready to send. This lets you lock in a rate without committing to the transfer immediately.

South African regulations for sending money abroad

The South African Reserve Bank (SARB) and SARS regulate all outbound foreign currency payments. As a South African resident, you have two allowances for transferring money abroad:

  • Single Discretionary Allowance (SDA): R1 million per calendar year. No tax clearance certificate required. This is the allowance most individuals use for personal remittances, family support, and gifts. You do not need to declare the purpose in advance, though the transfer must go through an authorised dealer.
  • Foreign Investment Allowance (FIA): Up to R10 million per calendar year. Requires a tax clearance certificate from SARS, which confirms you are a registered taxpayer with no outstanding obligations. Processing the tax clearance can take several weeks, so plan ahead if you need to send amounts above R1 million.

All outbound transfers must go through authorised dealers (licensed banks or approved transfer providers). Grey operates through licensed banking partners within this framework. You do not need to visit a bank branch or obtain separate SARB approval for transfers within the SDA limit.

One practical note: when you set up a new payee for an international transfer in South Africa, some banks and apps require you to provide a reason for the transfer (e.g., family support, education, gift). This is a standard regulatory requirement, not specific to any one provider.

Provider Fee structure Speed Best for
Grey 1% conversion + NGN 35 payout Minutes to same day Fast delivery, transparent fee, multi-currency account
WorldRemit $0-$4.99 + rate margin Minutes to 3 days Cash pickup, established brand, wide delivery options
LemFi Low/zero fee + rate spread Same day Competitive parallel-market rates, diaspora trust
Pesa $0 fee, cost in rate Instant (claimed) Lowest headline cost, zero visible fee
SA bank SWIFT R300-R1,000+ fees + rate margin 3-5 business days Only option if provider apps are unavailable

There is no single cheapest option that wins every time. LemFi and Pesa often offer the most competitive rates because they earn on the spread rather than a visible fee, but you need to check the amount delivered when you send. Grey's advantage is transparency (you see the fee and rate before confirming) and speed (minutes rather than days). WorldRemit's advantage is delivery flexibility (cash pickup in Nigeria for recipients without bank accounts).

For a broader comparison of outbound transfer apps, including those that do not serve the South Africa corridor, see how to send money from Nigeria to any country in 2026.

Four tips for saving on South Africa-to-Nigeria transfers

Compare the delivered amount, not the fee. LemFi and Pesa show no visible fee, but the cost is in the rate. Grey shows a visible 1% fee but may deliver more naira because the rate is tighter. The only number that matters is how many naira your recipient actually receives. Check this on two or three apps before you confirm.

Time your transfer when the rand is strong. The ZAR-NGN rate can move 2% to 3% in a single week. If your transfer is not urgent, check the rate daily and send when the rand strengthens. Grey lets you hold funds in your account without sending, so you can wait for a better rate without any holding cost.

Batch your transfers to reduce cost per rand. If you send R3,000 monthly, you pay the conversion fee twelve times a year. If you can send R9,000 quarterly instead, you pay it four times. On Grey, the NGN 35 payout fee is per transfer, not per rand, so fewer transfers also means fewer flat fees.

Use Grey for large transfers, compare LemFi and Pesa for small ones. On transfers above R5,000, Grey's transparent fee and fast delivery make it the strongest overall option. On smaller, non-urgent transfers, LemFi's parallel-market rates or Pesa's zero-visible-fee model may deliver slightly more naira. The difference is small on low amounts but worth checking if you send frequently.

You can also read the cheapest way to send money from Nigeria in 2026 to see how it works the other way.

Frequently asked questions

How much does it cost to send money from South Africa to Nigeria?

Grey charges a 1% conversion fee plus a NGN 35 flat payout fee per transfer. Whether the fee cap at the naira equivalent of $6 applies to ZAR conversions should be confirmed in the app, since ZAR is not a named Group A currency. Even at the uncapped 1% rate, Grey is significantly cheaper than South African bank SWIFT transfers, which typically cost R300 to R1,000 in fees plus a wider exchange rate margin.

How long does it take to send money from South Africa to Nigeria?

Grey delivers to Nigerian bank accounts in minutes to the same day. Moneytransfers.com cited Grey as the fastest option for ZAR-to-NGN transfers. By comparison, SWIFT transfers from South African banks typically take 3 to 5 business days.

Which Nigerian banks does Grey support?

Grey delivers to all major Nigerian banks, including GTBank, Access Bank, Zenith Bank, First Bank, UBA, and every other commercial bank that accepts domestic deposits. Your recipient does not need a Grey account.

Is it cheaper to use Grey or LemFi for South Africa to Nigeria?

It depends on the amount and the exchange rate at the time. LemFi often offers competitive parallel-market rates with low or zero visible fees, earning through the rate spread. Grey charges a visible 1% fee with a transparent rate. The only way to know which is cheaper on a given day is to compare the total naira your recipient would receive on both apps at the same moment.

Do I need a tax clearance certificate to send money from South Africa to Nigeria?

Not for amounts within the Single Discretionary Allowance of R1 million per calendar year. The SDA allows transfers abroad without a tax clearance certificate. For amounts above R1 million and up to R10 million, you need a Foreign Investment Allowance with tax clearance from SARS.

Can I send money from South Africa to Nigeria using Wise?

Wise operates in South Africa and supports ZAR as a sending currency. However, Wise has historically had restrictions on the Nigeria corridor. Check the Wise app at the time of transfer to confirm whether ZAR-to-NGN is available. If it is, Wise typically charges 0.5% to 1.5% with the mid-market rate.

What exchange rate will I get for ZAR to NGN?

Grey shows the live ZAR-to-NGN rate before you confirm the transfer. The rate includes a margin over the mid-market rate, which is standard across all providers. Because there is no deep, direct ZAR-NGN forex market, conversions typically route through USD (ZAR to USD to NGN), and the rate reflects both legs. You can compare Grey's rate against the mid-market rate on xe.com or Google to gauge the margin.

Related reading

How to send money from Nigeria to any country in 2026 works when the money is going out of Nigeria, this guide is for senders based in Nigeria rather than South Africa.

Cheapest way to send money from Nigeria in 2026 compares fees and how much it costs to send money from Nigeria. 

Best apps to send money internationally from the US in 2026 covers the US outbound market, where the competitive landscape and fee structures are very different.

Exchange rates on Grey are variable and include a margin over the mid-market rate. Always review the rate before confirming a conversion. Grey is a financial technology company, not a bank. Banking services are provided by licensed banking partners. This article is general information, not financial advice.

What is a SEPA transfer? How it works, fees, and timing

2 min read

If you've ever sent euros from one European bank to another, you've used SEPA. You probably didn't realise it, because SEPA payments are designed to feel like a domestic transfer, even when the money crosses borders. That's the whole point.

A SEPA transfer is a euro payment between accounts in the Single Euro Payments Area, which covers the EU and several other European countries. Standard SEPA transfers usually arrive within one business day, while SEPA Instant can arrive in seconds. Fees are typically low or free for euro-to-euro transfers.

But SEPA only works for euros, only within its 36-country zone, and only between accounts that hold IBANs. If you're sending to a country outside that zone, or in a currency other than EUR, you'll need SWIFT instead. In this guide, we'll walk you through how SEPA works, what it costs, how fast it is, and when it's the right choice versus SWIFT.

What is SEPA?

SEPA stands for Single Euro Payments Area. It's a network of 36 countries that agreed to standardise how euro payments move between banks. The idea is simple: sending EUR 500 from a German bank to a French bank should be no more complicated or expensive than sending EUR 500 between two German banks. Before SEPA, cross-border euro transfers within Europe were slow, expensive, and inconsistent. SEPA fixed that. For a broader look at holding euros, see how to send and receive euros in the UK.

The 36 SEPA countries include all EU member states, plus Iceland, Liechtenstein, Norway, Switzerland, Monaco, San Marino, Andorra, Vatican City, and the United Kingdom. Yes, the UK is still part of SEPA despite Brexit. UK banks can send and receive SEPA payments in EUR just as they could before.

SEPA covers three payment schemes:

SEPA Credit Transfer (SCT): A standard bank-to-bank euro payment. This is what most people mean when they say "SEPA transfer." Arrives within one business day.

SEPA Instant Credit Transfer (SCT Inst): A faster version that settles in seconds, 24/7, including weekends and holidays. Not all banks support it yet, but adoption is growing rapidly across Europe.

SEPA Direct Debit (SDD): Allows a payee (like a subscription service or utility company) to pull funds from your account with your authorisation. This is how recurring euro payments, such as gym memberships and energy bills, work across European borders.

How a SEPA transfer works

A SEPA payment works much like a domestic bank transfer. You need the recipient's IBAN (International Bank Account Number) and, in some cases, their BIC/SWIFT code (though BIC is being phased out for SEPA within the EU).

Here's the process: you log in to your bank's app or online banking, select "transfer" or "payment," enter the recipient's IBAN and the amount in EUR, then confirm. Your bank routes the payment through the SEPA clearing system, and the recipient's bank credits their account. For a standard SEPA Credit Transfer, this takes up to one business day.

For SEPA Instant, the process is the same from your side. The difference is on the backend: the payment settles in under 10 seconds, any time of day, any day of the week. The maximum amount for SEPA Instant is currently EUR 100,000 per transaction, though this may increase as the scheme matures.

One thing that catches people off guard: SEPA is euro-only. You can't send GBP, USD, or any other currency through SEPA. If you have a GBP account and want to send EUR, your bank converts GBP to EUR first (at their exchange rate, with their margin), and then sends the euros via SEPA. The SEPA transfer itself is in EUR. The conversion is a separate step with its own cost.

SEPA vs SWIFT: Which should you use?

SEPA and SWIFT solve different problems. SEPA is fast and cheap, but limited to euros within 36 countries. SWIFT is slower and more expensive, but it works globally with any currency. Here's a quick comparison.

Feature SEPA SWIFT
Currency EUR only Any currency
Geographic scope 36 SEPA countries 200+ countries globally
Speed (standard) 1 business day 1 to 5 business days
Speed (instant/expedited) Seconds (SCT Inst, 24/7) Same-day available (premium fee, limited corridors)
Typical fee Free to EUR 5 $15 to $50+
Intermediary banks? No. Direct clearing. Often yes. Each adds time and fees.
Account identifier IBAN SWIFT/BIC code + account number
Best for Euro transfers within Europe Non-euro or non-European transfers

Here's the main thing to know: if you're sending euros to a bank account in a SEPA country, SEPA is almost always the right choice. It's faster, cheaper, and doesn't involve intermediary banks. SWIFT only makes sense for euro transfers if the recipient's bank doesn't support SEPA (rare within the 36 countries) or if you're sending a non-euro currency.

For transfers outside Europe entirely, SWIFT is your only traditional option, though fintech services like Grey often bypass SWIFT by using local payment rails on both sides. See send money internationally with Grey.

SEPA Transfer Fees and Timing

Under EU regulation, banks can't charge more for a SEPA cross-border euro transfer than they charge for a domestic euro transfer. In practice, this means most SEPA transfers within the eurozone are free or cost EUR 0-5.

There are exceptions. Some banks, particularly in Italy and Spain, find ways to add surcharges on cross-border SEPA payments despite the regulation. If your bank charges you for a SEPA transfer that should be free, you may have grounds to challenge the fee under EU Regulation 924/2009.

For UK-based senders, the situation is slightly different. UK banks can still send and receive SEPA payments, but they aren't bound by the EU's fee-parity regulation post-Brexit. Some UK banks charge GBP 5 to 15 for outgoing SEPA payments, plus a GBP-to-EUR conversion margin. Check with your bank before assuming the transfer is free.

Timing depends on the scheme:

Standard SEPA Credit Transfer (SCT): up to 1 business day. Your bank has until the end of the next business day to credit the recipient's account after it receives the payment instruction.

SEPA Instant (SCT Inst): under 10 seconds, 24/7/365. No cut-off times, no weekend delays. The recipient's bank must also support SEPA Instant for this to work.

Cut-off times matter for standard SEPA. Most banks have a daily cut-off (typically 2 pm to 4pm local time) after which the transfer rolls over to the next business day. A standard SEPA transfer initiated at 3 pm on a Friday likely won't arrive until Monday.

Receiving SEPA Payments With Grey

If you're a freelancer, business, or anyone receiving euro payments from clients or employers in Europe, you need an account that can accept SEPA credit transfers. Grey lets you hold euros in a EUR account and receive SEPA payments directly.

When a client sends you EUR via SEPA, the payment is credited to your Grey EUR balance. There's no forced conversion to another currency. You hold the euros until you want to convert them, spend them with a virtual card, or transfer them elsewhere.

This is especially useful for freelancers outside the eurozone (UK, US, Nigeria, India) who invoice European clients in EUR. Instead of receiving a SWIFT wire that takes days and costs $15 to $50, your client sends a SEPA transfer that costs them nothing and arrives within a day. You receive SEPA payments with a Grey account and keep the euros until you're ready to use them.

Getting paid in euros? Open a Grey account to hold EUR and receive SEPA payments from anywhere in Europe, with no forced conversion and no SWIFT fees.

Frequently Asked Questions

What is a SEPA transfer?

A SEPA transfer is a euro-denominated payment between bank accounts in the Single Euro Payments Area. It covers 36 countries, including all EU member states, the UK, Norway, Switzerland, and Iceland. SEPA standardises how euros move across borders so that a cross-border euro transfer works the same as a domestic one.

How long does a SEPA transfer take?

A standard SEPA Credit Transfer takes up to 1 business day. SEPA Instant arrives in under 10 seconds, 24 hours a day, 7 days a week. Cut-off times affect standard SEPA: a transfer initiated after the daily cut-off (typically 2 pm to 4 pm) will process the next business day.

Is SEPA free?

For euro-to-euro transfers within the eurozone, EU regulation requires banks to charge no more than the cost of a domestic transfer, which is usually free or very low (EUR 0-5). UK banks may charge GBP 5-15 for outgoing SEPA payments, plus a conversion margin. Some Italian and Spanish banks add surcharges despite the regulation. Double-check with your bank before sending.

What's the difference between SEPA and SWIFT?

SEPA is a European euro-only payment network covering 36 countries. It's fast (1 day or instant) and cheap (usually free). SWIFT is a global messaging network covering 200+ countries and all currencies. It's slower (1 to 5 business days), more expensive ($15 to $50+), and often involves intermediary banks. Use SEPA for euro transfers within Europe. Use SWIFT for anything outside that scope.

Can I send SEPA transfers from the UK?

Yes. The UK remains part of the SEPA zone despite Brexit. UK banks can send and receive SEPA credit transfers in EUR. However, UK banks aren't bound by the EU fee-parity regulation, so they may charge more than eurozone banks for the same transfer. If you're sending EUR from a GBP account, you'll also pay a conversion margin on top of any transfer fee.

Can I receive SEPA payments outside Europe?

Not directly into a non-European bank account. SEPA only works between banks within the 36 SEPA countries. However, if you have a EUR account with a provider that operates within the SEPA zone (like Grey), you can receive SEPA payments into that account regardless of where you physically are. A freelancer in Nigeria or India with a Grey EUR account can receive SEPA payments from a German client as easily as a freelancer in Paris.

Open a Grey account and start receiving SEPA payments in EUR, wherever you are.

Disclaimer: This article is for informational purposes only. SEPA rules, fees, and timing may vary by bank and country. Verify current terms with your bank or payment provider before sending. Grey is not a bank. Grey is a licensed financial services provider offering multi-currency accounts.

How to receive payments on Etsy as a seller in Sweden

2 min read

Sweden has a long-standing tradition of craftsmanship, from intricate woodworking to contemporary design. Today, many Swedish artisans are looking for global platforms to showcase and sell their unique creations. Etsy provides the perfect solution — an international marketplace that connects creative entrepreneurs with millions of buyers worldwide. However, receiving payments as a Swedish seller can sometimes be challenging.

This guide will walk you through how to receive Etsy payments seamlessly using Grey, ensuring smooth transactions and better financial management.

Why use Grey for Etsy payments?

Grey simplifies the payment process for Swedish Etsy sellers. Here’s why it’s the best choice:

  • Competitive exchange rates: Maximise your earnings when converting to Swedish kronor (SEK).
  • Secure transactions: Grey’s robust security features ensure your funds are protected.
  • Hassle-free withdrawals: Transfer your earnings to your local bank account with ease.

Also read: How to receive payments on Etsy as a seller in Denmark

How to receive payments on Etsy using Grey in Sweden

Grey provides an easy solution for receiving international payments as a Swedish Etsy seller. Follow these steps to get started:

1. Open your Grey app

Log in to your Grey account or create one to access your international USD bank account.

2. Link your Grey account to Etsy

How to receive payments on Etsy as a seller in Sweden
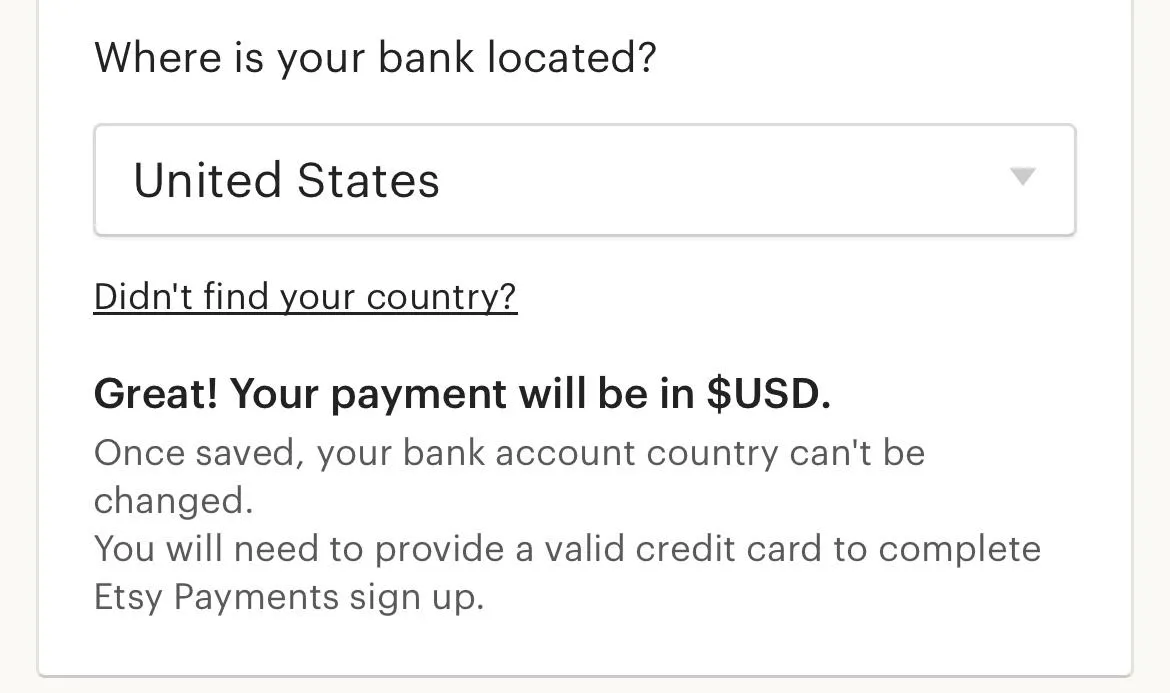
  • Select your bank’s country.
How to receive payments on Etsy as a seller in Sweden
  • Choose whether you’re registering as an individual or a business.
How to receive payments on Etsy as a seller in Sweden
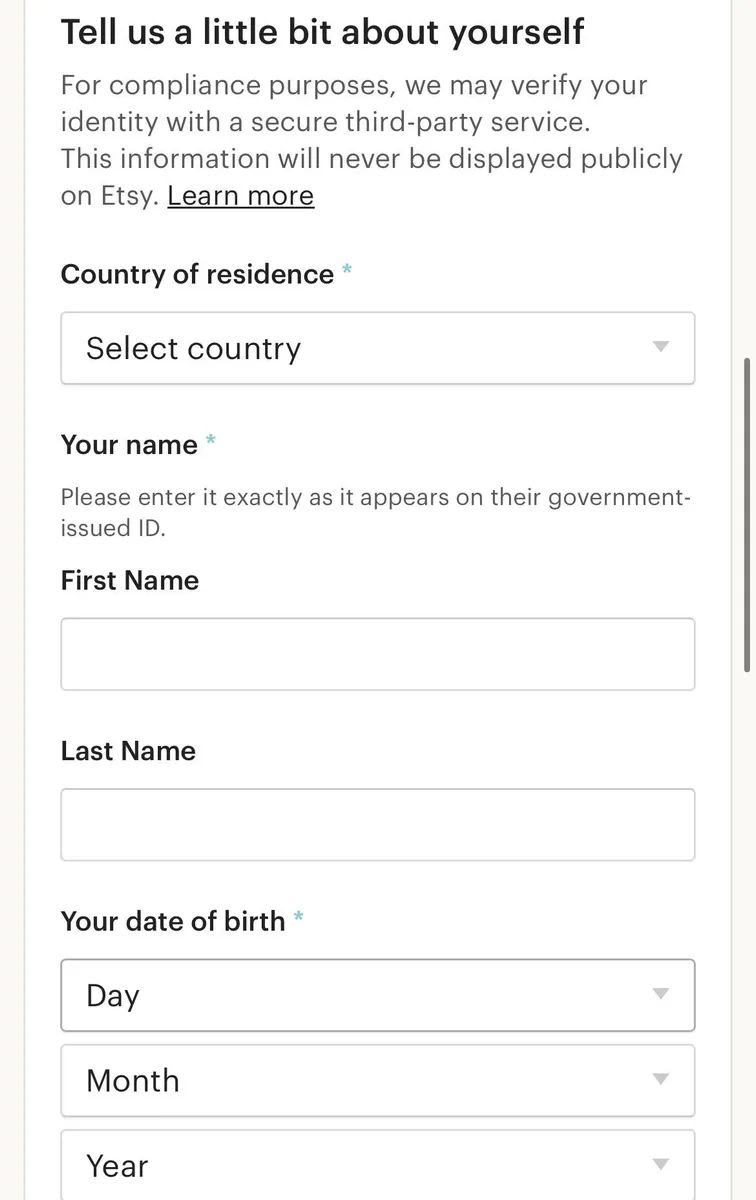
  • Enter your personal information, i.e. name and address.
How to receive payments on Etsy as a seller in Sweden
  • Add your Grey US, EU, or UK bank account details, depending on your preference.
How to receive payments on Etsy as a seller in Sweden
  • Etsy will process payments to your Grey account, making it easy to manage your earnings.

With your Grey account linked, you can receive Etsy payouts directly into your international bank account.It's important to note that you will have to provide a valid ID and depending on the location you pick, may have to fill in a valid address and social security number for your account to be verified.

Also read: How to receive payments on Etsy as a seller in Hungary

Tips for succeeding as a Swedish seller on Etsy

  • Optimise your listings: Use high-quality photos and detailed descriptions to make your products stand out.
  • Offer international shipping: Expand your customer base by providing global shipping options.
  • Respond quickly: Engage with buyers by answering queries promptly and addressing concerns professionally.
  • Leverage social media: Promote your products on apps like Instagram and Pinterest to drive traffic to your Etsy shop.

Also read: How to receive payments on Etsy as a seller in Romania

Simplify Etsy payments with Grey

With Grey, you can stop worrying about receiving Etsy payouts or converting your earnings from Etsy. Manage your finances seamlessly and focus on growing your creative business.

Sign up for a Grey account today and unlock a world of possibilities for your Etsy shop in Sweden.

How to create US and UK bank accounts as a migrant worker in the UK

2 min read

As a migrant worker in the UK, you likely already have a local bank account. But if you work with international clients or send money abroad, you’ve probably had a few challenges — high fees, unfavourable exchange rates, and slow transaction times.

A US bank account can make things easier by allowing you to receive and hold USD without conversion losses. And if you want better financial flexibility, having an additional UK account with a digital bank can help you manage your money more efficiently.

With Grey, you can open US and UK bank accounts easily.

Why do migrant workers in the UK need a US or extra UK bank account?

Even with a UK bank account, opening a US account (or an extra UK account) can be a game-changer. Here’s why:

1. Receiving USD payments without extra fees

If you work for US-based companies or freelance for international clients, you probably receive payments in USD. UK banks often charge high fees for converting USD to GBP. With a US account, you can receive payments directly in dollars without losing money on exchange rates.

2. Holding USD as savings

Slight currency fluctuations can affect your earnings. Holding part of your money in USD instead of GBP gives you more financial stability, especially if you send money abroad regularly.

3. Avoiding expensive international transfers

Sending money across borders? UK banks often have high international transfer fees. With Grey, you can move money seamlessly between your US and UK accounts, saving time and money.

4. Managing finances with an extra UK account

Some workers prefer multiple accounts to separate savings, salary payments, or different income sources. A second UK account can help with budgeting or receiving payments from multiple employers.

Also read: How to manage multiple currencies as an expatriate in Mexico using Grey

Step-by-step guide to opening US and UK bank accounts using Grey

The process is pretty straightforward. Here’s how you can get started:

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

How to create US and UK bank accounts as a migrant worker in the UK
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location.
How to create US and UK bank accounts as a migrant worker in the UK
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
How to create US and UK bank accounts as a migrant worker in the UK
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
How to create US and UK bank accounts as a migrant worker in the UK
  • Once you’re set-up, you’re ready for identity verification — a step required for secure access to financial services.

2. Verify your identity for secure access

Grey requires some basic documents to confirm your identity and keep your funds secure:

  • A valid government-issued ID: A passport or national ID card will do.
  • Proof of address – A recent utility bill or bank statement confirming your residence in the UK.

Verification usually takes a few business days, but accurate and clear uploads speed up the process.

3. Access your US and UK bank accounts

Once your identity is verified, you’re all set to create your foreign accounts:

  • Log in to your Grey account.
  • Go to “Accounts” and select “Create Account.”
  • Choose your preferred currency (USD for a US bank account or GBP for a UK account).
  • Get your virtual bank details instantly.

Your US and UK bank accounts are now ready for use.

Also read: How to manage multiple currencies as an expatriate in Brazil using Grey

Benefits of using Grey as a migrant worker in the UK

  • No hidden fees – Transparent pricing means you keep more of your money.
  • Fast transactions – Receive payments and transfer money without long delays.
  • Global access – Use the Grey app to manage your finances from anywhere, anytime.

Tips for managing finances as a migrant worker

  • Budget wisely: Allocate your income across savings, daily expenses, and remittances to your family.
  • Use secure banking options – Enable two-factor authentication (2FA) for extra security.

Simplify banking across borders with Grey

Managing international payments as a migrant worker in the UK doesn’t have to be complicated. With Grey, you can open a US or extra UK bank account, receive payments seamlessly, and move money across borders.Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

Arrow (up)

Back to top