
<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december#article","headline":"How to pay on Amazon, ASOS, and Shein from Nigeria, Ghana, and Kenya","description":"Shopping on international sites from Africa requires a card that works globally. Here is how to use your Grey virtual Mastercard or Visa to pay on Amazon, ASOS, Shein, and other international stores.","inLanguage":"en","url":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december","mainEntityOfPage":{"@id":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december#webpage"},"datePublished":"2025-12-19T20:16:39.542Z","dateModified":"2026-06-15T14:31:21.256Z","author":{"@type":"Person","@id":"https://grey.co/authors/adeolu-titus-adekunle#person","name":"Adeolu Titus Adekunle","url":"https://grey.co/authors/adeolu-titus-adekunle","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/titusadeoluadekunle/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300cb9b7f8dc5ecd1dfcac_6a300cb84d19e26282106904_best-ways-to-pay-on-amazon-asos-shein-during-december__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300cb9b7f8dc5ecd1dfcac_6a300cb84d19e26282106904_best-ways-to-pay-on-amazon-asos-shein-during-december__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december#webpage","url":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december","name":"Best ways to pay for goods on global e-commerce websites","description":"Shopping on international sites from Africa requires a card that works globally. Here is how to use your Grey virtual Mastercard or Visa to pay on Amazon, ASOS, Shein, and other international stores.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to pay on Amazon, ASOS, and Shein from Nigeria, Ghana, and Kenya","item":"https://grey.co/blog/best-ways-to-pay-on-amazon-asos-shein-during-december"}]}] </script>

How to pay on Amazon, ASOS, and Shein from Nigeria, Ghana, and Kenya

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

In December, online purchases typically increase during the holiday shopping season, driven primarily by gift purchases, festive decorations, and parties. Many people are also in a last-minute rush to tick off some needs from their yearly plan. Many online marketplaces also run sales during this period. Amid this shopping frenzy, someone is wondering how to best pay on Amazon, AOS, and Shein this December. Between payment declines, currency conversion issues, spending limits, and high fees, we understand your frustration.

This article helps you explore your payment options for Amazon, ASOS, and Shein this December. The best ways to pay on Amazon, ASOS, and Shein in December depend on your preference for immediate payment, earning rewards, or using interest-free instalment plans.

Best payment methods for Amazon in December 2025

Amazon offers a wide range of payment options, making it easy to take advantage of holiday promotions.

Credit and debit cards

This is the most straightforward way to pay on Amazon. The payment gateway accepts Visa, Mastercard, American Express, and Discover, with no hidden fees or payment delays.

  • Sign in to Amazon and navigate to "Account & Lists", then go to "Your Account".
  • Select "Your Payments".
  • Tao on "Add a payment method" or "Add a credit or debit card".
  • Enter your card number, name, expiration date, and security code.
  • Follow any further prompts to complete the process.
  • At checkout, you'll see a list of your saved cards. Choose the one you want to use.

Also read: How to receive Amazon payments with Grey

Amazon gift cards

You can use Amazon gift cards for Amazon payments by redeeming the card code and adding it to your account balance. This automatically applies to Amazon purchases and Prime subscriptions. You can also manually apply your gift card balance at checkout for on-Amazon purchases,

  • Go to "Redeem a Gift Card" in ‘Your Account’ and enter the code on your gift card to add its worth to your balance.
  • Your gift card balance automatically applies to your eligible orders.
  • If it doesn’t apply automatically, select "Use a gift card, voucher, or promo code" at checkout to apply it.
  • You can split the payment between your gift card balance and another method (like a card) if the purchase exceeds your balance.

Buy Now, Pay Later (BNPL) options

Depending on your location, you can use Buy Now, Pay Later (BNPL). You can do this through services like Amazon Pay Later and Instalments by Barclays, or by linking to third-party providers such as Afterpay, Affirm, or Klarna. Amazon lets you split monthly payments for select items over 3-36 months, sometimes with 0% APR. Avoid BNPL if you are prone to overspending.

Digital wallets

Amazon supports payments from digital wallets such as Apple Pay and Google Pay when a linked card is used.

Other specialised methods

You can use FSA/HSA cards for health items, and a SNAP EBT card on Amazon for eligible food items by linking it as a payment method.

Also read: Best digital subscriptions to gift this holiday season

Best payment methods for ASOS in December 2025

ASOS is a go-to online fashion marketplace that emphasises flexible payment options, especially during the December holiday season and end-of-year sales. You can get up to 30% off promo codes and choose methods that let you pay later without interest.

Credit and debit cards

ASOS accepts major debit and credit cards, including Visa, Mastercard, American Express, Maestro, Diners Club, and Discover.

  • During checkout, after entering your shipping details, you'll see options to add your payment information.
  • Input your card number, expiry date, security code (CVV), and the name on the card.
  • You can save card details in your ASOS account under "Payment Methods" for future purchases.

Buy Now, Pay Later (BNPL)

ASOS offers several Buy Now, Pay Later (BNPL) options that allow you to split payments or defer them without interest if you pay on time. Here are some of the options:

  • Klarna's Pay lets you make four interest-free payments every two weeks, which is ideal for December expenses, as you don’t have to spend so much at once.
  • Clearpay offers fortnightly instalments.
  • PayPal Pay Later gives 30 days to pay after dispatch, with try-before-you-buy perks.
  • Afterpay (Primary in the US, Australia, and New Zealand) offers a "Pay in 4" structure over 6 weeks.
  • Zilch can be used as a virtual card to spread payments over six weeks or three months.

To use BNPL on ASOS:

  • Add items to your bag, then proceed to ASOS Checkout.
  • Under "Payment Type," click “Change”.
  • Select your preferred BNPL provider (e.g., Klarna or Clearpay).
  • Follow the prompts to log into that service provider's account or sign up if you don’t have na existing account.
  • Complete the order, and your items will ship immediately.

Digital wallets

ASOS accepts digital wallets, specifically Apple Pay, Google Pay, and PayPal. Using these options can simplify the checkout process and is generally very secure.

  • Shop on the ASOS website or app and add items to your cart.
  • Proceed to the checkout page.
  • Under the "Payment Type" section, click ‘Change’.
  • Select your preferred digital wallet provider.
  • You will be prompted to log in or verify the payment (e.g., using a PIN, fingerprint, or facial recognition).
  • Once authorised, the transaction is complete, and your order will be processed.

Ensure that your billing and shipping addresses in your chosen digital wallet's settings are correct, as the order will default to these details. You can find more information about these and other payment options on the ASOS Customer Care page.

LDMAG1

Best payment methods for Shein in December 2025

When you think of low-budget, trendy fashion items, Shein should be at the top of your mind. With frequent flash sales in December, it is a great shopping destination.

Credit and debit cards

Shein primarily accepts debit and credit cards and supports Visa, Mastercard, and other card brands. No fees, but use cards with fraud protection for peace of mind.

  • Enter card details during the final checkout step or save them to your account for faster future purchases.
  • During checkout, choose Credit/Debit Card.
  • Provide your payment card number, expiration date, and the 3-digit CVV/security code.

If you saved your card, you can manage it by going to "Me"> Settings (the gear icon). Select "My Payment Options" to add, edit, or remove card information.

PayPal

Using PayPal on SHEIN remains one of the most popular and secure payment methods because it prevents the seller from seeing your full card details. Venmo is an alternative if you’re shopping from the US.

  • At checkout, select PayPal as your payment method.
  • Authentication: You will be redirected to the secure PayPal site or app to log in and confirm the payment.
  • Completion: Once authorised, you are returned to SHEIN to receive your order confirmation.

PayPal also offers Buy Now, Pay Later. For some items, you can split the cost with PayPal's installment payment plans. Depending on where you shop, you may be eligible for three or four interest-free monthly payments. This option will appear directly on the PayPal checkout screen if you are eligible.

Buy Now, Pay Later (BNPL)

In addition to PayPal, Klarna, Afterpay, and Zip offer interest-free payment plans. This lets you maximise your budget this December without spending too much at once.

Gift cards and prepaid

You can purchase Shein gift cards on the website and preload them for checkout.

  • Add the items you’re buying to your cart.
  • Proceed to the checkout page.
  • In the "Payment Method" section, select the option to add a gift card and enter the 16-digit card number and 4-digit PIN code found in the email you received.
  • Click the "Apply" button. The balance will be deducted from your order total.
  • If the order total exceeds your gift card balance, you will need to select another payment method (credit card, PayPal, etc.) to pay the difference.

Also read: How to plan your 2026 financial goals before January starts

Managing payments on Amazon, ASOS, Shein during December with Grey

While many people scamper through options looking for the best way to pay on Amazon, ASOS, Shein this December, this shouldn’t be you. Grey offers a virtual USD debit card that integrates seamlessly with platforms such as Amazon, ASOS, and Shein. You can fund your account with your local currency and hold USD, EUR, and GBP in the same place. Grey offers the best way to pay on Amazon, ASOS, and Shein during December. Here’s how to get started:

  • Sign up on Grey’s website or download the mobile app and complete your verification.
  • Set up your bank account and fund it,
  • Request for your USD card. This should cost $4, but you need to fund it with at least $1.

Proceed to your Amazon, ASOS, or Shein account and add your card as a payment method. You may also add to your Google Pay or Apple Pay. You can easily avoid payment declines, spending limits, high charges, and currency conversion issues.

Get started by signing up on Grey’s website or downloading the mobile app for seamless online payments this December.

‍

Last updated:

October 9, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Grey Business vs Grey personal banking

•

•

2 min read

“Should I be using Grey Business, or is my personal Grey account enough?”

It’s a common question, especially once your income starts growing.

At the beginning, everything feels simple. You get paid and you withdraw your money easily. But as your work evolves, whether that’s taking on more clients, earning from multiple platforms, or starting a company, the way you manage money needs to evolve too.

Grey offers two account types for this exact reason: Grey Personal and Grey Business. They are not better or worse than each other. They are built for different stages of your earning process.

This guide breaks down the differences, including fees, features, and when to switch, so you can choose the right setup without second-guessing.

‍Also read: Receiving foreign income as a solo founder

What is a Grey personal account?

A Grey personal account is designed for individuals who receive and manage international payments.

If you are a freelancer, remote worker, or creator earning from global clients or platforms, this is the account you are expected to use.

With a personal account, you can open USD, GBP, and EUR balances with real banking details. This allows clients to pay you as if they were making a local transfer in their own country. Instead of receiving an expensive international wire, you receive money through local rails like ACH, SEPA, and FPS.

Once the money arrives, you can hold it in foreign currency, convert it when the rate works for you, or withdraw it to your local bank account. You can also spend directly using your Grey virtual card without needing to manually move funds around.

The focus here is simplicity. You are managing your own income, and the account is designed to make that as flexible as possible.

What fees does Grey Personal charge?

Understanding fees is where most people get confused, so here’s how it actually works.

When you receive money through ACH, SEPA, or FPS, Grey charges a 0.8% fee, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. This means larger payments become proportionally cheaper because of the cap.

Currency conversion depends on the currency pair. Some routes are free, while others range from 0.5% to 1%. For certain major pairs, the fee is capped at $6. The important detail is that Grey shows the rate before you confirm, so there are no hidden charges after the fact.

Withdrawals vary depending on the country, but for major currencies like EUR and GBP, the fee is typically 0.5%, with a minimum and maximum cap. Other corridors may use fixed fees instead.

For less common deposit methods like Fedwire, BACS, or CHAPS, fixed fees apply. These are generally used less often, since local rails like ACH or FPS are cheaper.

Read more: Grey charges explained: what every transaction costs

What is Grey Business?

Grey Business is designed for companies rather than individuals.

If you are running a registered business, working under a company name, or managing revenue that belongs to a business entity, this is the account structure you need.

Unlike a personal account, a Grey Business account is built for your company. This means you can receive payments on behalf of the business, manage funds at a company level, and keep financial records properly organised for accounting and compliance.

The functionality goes beyond receiving payments. Grey Business allows you to manage team access, assign roles, and give multiple people control over finances without sharing a single login.

You can also pay contractors globally, send payments in local currencies, and handle bulk payouts by uploading recipient details. This becomes important as soon as you are working with a team or scaling operations.

The goal of Grey Business is not just to receive money, but to structure how your business handles it.

What fees does Grey Business charge?

Grey Business follows the same core pricing model as personal accounts.

Receiving payments still comes with the 0.8% fee capped at $10. Conversion fees follow the same tiered structure, and withdrawals depend on the payout country.

The difference is not in lower fees, but in what the account enables.

With Grey Business, you are paying for structure, team management, and the ability to operate at scale without mixing personal and company finances.

Grey Personal vs Grey Business: what is the difference?

The main difference comes down to ownership.

A personal account is for money that belongs to you as an individual. A business account is for money that belongs to a company.

Everything else builds from that.

Grey Personal is simpler, quicker to set up, and designed for individuals managing their own income. Grey Business requires verification of a registered company but provides tools to manage payments, teams, and operations effectively.

If you are working alone and getting paid for your own work, a personal account is enough. If you are invoicing as a company, hiring people, or managing shared finances, you need a business account.

‍Also read: Can non-residents open a US bank account online in 2026?

When should you use Grey for personal use?

You should use a personal account if you are earning in your own name.

This includes freelancers, remote employees, and creators earning from platforms like YouTube, TikTok, or Upwork. At this stage, your income is still personal, even if it comes from multiple sources.

A personal account keeps things simple.

When should you use Grey Business?

You should use Grey Business when your income is no longer just yours.

If you have registered a company, invoice under a business name, or manage revenue that belongs to a business entity, a personal account is no longer the right structure.

This is especially important if you are paying contractors, working with a team, or preparing financial records for accounting and tax purposes.

Can you have both Grey for personal use and Grey Business?

Yes, and in many cases, this is the best setup.

If you run a company but also earn income personally, keeping both accounts separate helps avoid confusion. Your business transactions stay within the business account, while your personal income remains separate.

This makes accounting cleaner and reduces the risk of mixing funds.

Grey for personal use vs Grey Business: key differences

Feature Grey Personal Grey Business
Who it’s for Individuals (freelancers, creators, remote workers) Registered companies, startups, agencies
Account ownership Personal use Business entity
Currencies supported USD, GBP, EUR, USDC USD, USDC (business-focused)
Receiving payments Yes (ACH, SEPA, FPS) Yes (for business transactions)
Team access No Yes (multi-user access with roles)
Bulk payouts No Yes (CSV uploads supported)
Virtual cards Yes (for personal use) Yes (multiple cards for teams, tools, ads)
Best use case Getting paid individually Managing company finances and scaling operations
Setup process Fast (ID verification) More detailed (business verification required)

So, which Grey account should you choose?

Most people overthink this decision, but it comes down to one simple question:

Who does the money belong to?

If you’re earning as an individual, whether that’s freelancing, remote work, or content creation, a Grey Personal account is the right fit. It keeps things simple and flexible while giving you full access to international payments.

If you’re operating as a registered business, invoicing clients under a company name, or managing team payments, Grey Business is the structure you need. It helps you separate finances properly and handle growth without creating confusion later.

If you’re in between, which is common, you can start with a personal account and move to business when your setup requires it. Many users also keep both, using one for personal income and the other for company operations.

The goal isn’t to pick the most advanced option. It’s to choose the one that fits how you earn today and won’t slow you down as you grow.

Getting started with Grey

Opening a Grey Personal account takes just a few minutes. You can sign up in under 5 minutes, and once your identity is verified, you can usually start receiving payments the same day.

Opening Grey Business takes a bit longer because it involves business verification. You’ll need to submit your company registration and ownership details, and approval typically takes 1 to 3 business days, depending on the documents provided. This ensures your account is set up correctly from the start.

Frequently asked questions

What is the difference between Grey for persona use and Grey Business?

Grey Personal is for individuals receiving and managing their own income, such as freelancers, creators, and remote workers. Grey Business is for registered companies that need to manage business revenue, pay contractors, and give team members access to finances.

The main difference is ownership. Personal accounts are for your money. Business accounts are for company funds.

Can I use a Grey Personal account for business payments?

You can use a personal account while you are freelancing under your own name. However, once you register a company or start invoicing under a business name, it is better to switch to Grey Business.

Using a personal account for business transactions can create confusion with accounting, taxes, and financial tracking.

Does Grey Business have different fees from Grey Personal?

Grey Business follows the same core pricing structure as personal accounts. Receiving fees are typically 0.8% with a cap, and conversion fees depend on the currency pair.

The main difference is not pricing, but functionality. Grey Business adds tools for team access, bulk payments, and structured financial management.

Can I have both a Grey Personal and Grey Business account?

Yes. Many users have both accounts.

This is useful if you have personal income, such as freelance work or creator earnings, and also run a registered business. Keeping them separate makes accounting cleaner and easier to manage.

When should I switch from Grey Personal to Grey Business?

You should consider switching when your income becomes business revenue instead of personal income.

This usually happens when you register a company, start invoicing clients as a business, hire contractors, or need proper financial records for tax and reporting purposes.

What documents are required to open a Grey Business account?

To open a Grey Business account, you will need to provide company registration documents, ownership details, and verification information about the business.

The process is more detailed than a personal account because it involves verifying a legal entity.

Is Grey Personal enough for freelancers and creators?

Yes. For most freelancers, remote workers, and creators, Grey Personal is more than enough.

It allows you to receive international payments, hold foreign currency, convert when needed, and withdraw locally without needing business-level setup.

Can I receive USD, GBP, and EUR with both accounts?

Yes. Both Grey Personal and Grey Business support multi-currency functionality.

Personal accounts focus on individual income, while business accounts structure those same capabilities for company use.

Which Grey account is better?

Neither is better. They are designed for different use cases.

Grey Personal is better for individuals managing their own income. Grey Business is better for companies managing business finances and scaling operations.

Ready to get started?

Open your Grey Personal account to start receiving international payments as an individual, or set up Grey Business if you’re managing company finances and need a more structured setup.
How to send USD to a Nigerian domiciliary account

•

•

2 min read

Most of the information you’ll find online on sending money to Nigeria will most likely focus on naira delivery. But that’s not what you need if the recipient has a domiciliary account and wants to receive USD without converting to naira.

A Nigerian domiciliary account holds foreign currency, typically US dollars, without forcing an immediate conversion. Sending USD to one keeps that option in the recipient’s hands. It’s a decent choice for freelancers holding dollar savings, importers managing USD expenses, or anyone who wants to preserve dollar value rather than convert at a potentially unfavourable rate.

The mechanics of getting USD from a US bank account into a Nigerian domiciliary account are specific. You need to understand the required details, the fees you’ll encounter, and the mistakes that cause transfers to fail or arrive short before you send. For a broader overview of receiving dollar income in Nigeria, see our guide on how to receive US dollars in Nigeria and the options available for opening a Nigerian dollar account.

What is a domiciliary account?

A domiciliary account, also commonly called a dom account, is a bank account held at a Nigerian commercial bank that stores foreign currency without converting it to naira. The Central Bank of Nigeria (CBN) permits individuals and businesses to hold certain foreign currencies in domiciliary accounts at licensed Nigerian banks.

The key distinction from a standard naira savings account is that funds credited to a domiciliary account remain in the foreign currency in which they were credited. The account holder decides when and whether to convert, and at what rate. This matters because the naira has historically depreciated against major currencies, and holding USD can protect against the value erosion of naira conversions.

Domiciliary accounts are the primary mechanism by which Nigerians receive international SWIFT wire transfers in USD. CBN’s foreign exchange regulations require that inbound USD transfers be credited to a domiciliary account or converted to naira at the official rate. If a sender directs a USD wire to a standard naira account, the bank will convert it on arrival. If the recipient wants the money to remain in USD, the wire must be sent to the domiciliary account number, not the naira account number.

Both the naira and domiciliary accounts exist at the same bank for the same person and may look similar. They are different accounts with different account numbers. Confirm the domiciliary account number explicitly with the recipient before initiating the wire.

How to send USD via SWIFT wire: step by step

A SWIFT wire from a US bank to a Nigerian domiciliary account requires specific information, and if you miss any, it can cause delays, returns, or the transfer landing in the wrong account.

Step one: Collect the recipient’s domiciliary account details.

You need all of the following:

  • Recipient’s full legal name, exactly as registered with the Nigerian bank
  • The domiciliary account number (not the naira account number)
  • The bank name and branch address
  • The bank’s SWIFT code

The SWIFT codes for some major Nigerian banks are as follows: Access Bank: ABNGNGLA, GTBank (Guaranty Trust Bank): GTBINGLA, Zenith Bank: ZEIBNGLA, First Bank of Nigeria: FBNINGLA, United Bank for Africa (UBA): UNAFNGLA, Stanbic IBTC Bank: SBICNGLX, Ecobank Nigeria: ECOCNGLA, Fidelity Bank: FBNKNGLA, FCMB (First City Monument Bank): FCMBNGLA.

Always verify the SWIFT code directly with the recipient’s bank before initiating a high-value transfer, as branch-specific codes sometimes differ from the head office code.

Step two: Initiate the wire transfer at your US bank.

Log in to your online banking or visit a branch. Navigate to international wire transfers. Enter the recipient’s details: full name, domiciliary account number, bank name, branch address, and SWIFT code. Specify USD as the transfer currency. Nigeria is a USD-only wire destination at Bank of America; Bank of America requires international wires to Nigeria to be sent in US dollars due to local regulations, and foreign currency transfers are not available to this destination.

Step three: Select your charge instruction.

Depending on your bank, you may be asked whether to use SHA (shared charges) or OUR (sender pays all). Under SHA, correspondent bank fees are deducted from the transfer amount in transit, meaning the recipient receives less than what you send. Under OUR, you pay all correspondent fees upfront, and the recipient receives the full amount. For transfers where the recipient needs a specific USD amount, OUR is the right choice. For transfers where the fee deductions are acceptable, SHA is the standard default.

Step four: The wire routes through the SWIFT network.

Not all US banks have direct correspondent relationships with Nigerian banks. A US-to-Nigeria wire might involve two or three correspondent bank hops due to limited direct banking relationships. Each correspondent bank in the chain processes and forwards the payment, and under SHA, each one can deduct a fee from the transfer amount before forwarding the remainder.

Step five: The money arrives in the domiciliary account.

SWIFT transfers to Nigeria typically take one to three business days. Large transfers may be held for CBN compliance review, which can extend the timeline. Once that is cleared, the USD is credited to the domiciliary account and remains in dollars until the account holder decides to convert or withdraw.

What a SWIFT wire really costs

The posted fee at your US bank is not the full cost of a SWIFT wire to Nigeria. Three fee layers stack on every transfer.

Layer one: Your US bank’s outgoing wire fee
A 2026 NerdWallet survey reported a median outgoing international wire transfer fee of $45, with major US banks charging $35 to $50 per send. Chase charges $40 online for USD wires. Bank of America charges $35 for online transfers. Wells Fargo charges $25 to $45, depending on account type.

Layer two: Correspondent bank deductions in transit
Correspondent banks that relay the payment along the SWIFT chain can each deduct $10 to $30 in fees from the transferred amount before it reaches its destination. On a US-to-Nigeria wire routed through two correspondent banks, that’s $20 to $60 deducted from the transfer amount. Neither you nor the recipient is notified of these deductions in advance.

Layer three: The Nigerian receiving bank’s incoming wire fee
Nigerian banks charge an inbound wire fee on SWIFT receipts. This is typically deducted from the funds upon arrival before they are credited to the domiciliary account.

Here’s what this looks like on real transfers:

$500 transfer $5,000 transfer
US bank outgoing wire fee $40 $40
Correspondent bank deductions (estimated) $30–$50 $30–$50
Nigerian receiving bank fee $10–$15 $10–$15
Total fees $80–$105 $80–$105
As a percentage of transfer 16–21% 1.6–2.1%
USD received in domiciliary account $395–$420 $4,895–$4,920

‍

Also read: Sending USD from Nigeria to the USA: Step-by-step guide

Cheaper alternatives to a SWIFT wire transfer

For smaller or regular payments, the SWIFT route is difficult to justify. Here are the practical alternatives and when each one makes sense.

Multi-currency accounts (the recommended alternative for most senders)

Platforms like Grey provide USD accounts with US routing numbers and account numbers that senders can use to pay as a standard domestic US transfer, with no SWIFT correspondent chain involved.

The sender pays via ACH from their US bank account to a US account number. The money arrives in the recipient’s Grey USD balance without correspondent bank deductions. The recipient then controls when to convert or hold the USD. Multi-currency fintech accounts route payments through their own infrastructure rather than the SWIFT correspondent chain.

Grey’s deposit fee via ACH is 0.8%, capped at $10. On a $500 transfer, the fee is $4. On a $5,000 transfer, the fee is $10. Currency conversion is charged at 1% capped at $6 when the recipient converts to naira.

Stablecoin route

Some senders use USDC to move dollar value to Nigeria. The sender buys USDC on a US-licensed exchange, transfers to the recipient’s wallet address, and the recipient converts to USD or naira via a licensed Nigerian platform. This route avoids SWIFT entirely and can be faster, but requires both parties to be comfortable with crypto infrastructure and introduces volatility risk if either party converts at an unfavourable moment.

When SWIFT is still the right choice

If the recipient holds a domiciliary account and wants to receive funds in dollars without naira conversion, a bank wire is one of the most practical routes. SWIFT confirmations from US banks carry institutional credibility that other receipts may not in certain legal contexts. Nigerian property lawyers, courts, and some financial institutions require a bank-generated wire confirmation to authenticate a large transfer.

For transfers above $5,000 where the fixed fees are a small percentage, for institutional or legal documentation requirements, and for recipients who specifically need a SWIFT credit advice from a Nigerian bank, the traditional wire remains appropriate.

Sending USD to Nigeria with Grey

Grey provides a USD account with real US banking details, including a routing number and an account number issued by Grey's partner bank. Senders in the US use these details to pay as if they were paying any domestic US account. The payment goes out as a standard ACH transfer, bypasses the SWIFT correspondent chain entirely, and arrives in the recipient’s Grey USD balance within one to two business days.

For the recipient, the USD sits in their Grey account and can be held, converted to naira at a rate shown before confirmation, or used directly for USD-denominated expenses via the Grey virtual card.

The practical comparison on a $500 transfer: SWIFT costs $80 to $105 in stacked fees, leaving the recipient with $395 to $420. Grey costs $4 on the deposit, leaving the recipient with $496. On a monthly transfer of $500, that’s a difference of approximately $900 per year.

For senders who regularly send money to Nigeria with Grey, providing the Grey USD account details to the sender once removes all SWIFT complexity.

For those evaluating their full range of options, see our guide on sending money from the US for a broader comparison of methods and costs on the US-to-Nigeria corridor.

Send USD to Nigeria with Grey

Frequently asked questions on how to send USD from the USA to a Nigerian domiciliary account

Can I send USD to a Nigerian domiciliary account from the US?

Yes. A USD SWIFT wire from any US bank to a Nigerian domiciliary account is the standard method for sending dollars that land in Nigeria and remain there as dollars. You need the recipient’s domiciliary account number (not their naira account number), their bank’s SWIFT code, and the bank’s branch address. Alternatively, if the recipient holds a Grey USD account, you can send via ACH as a domestic US transfer, which avoids the SWIFT fee chain entirely.

How much does a SWIFT wire to a Nigerian domiciliary account cost?

Sending USD to a Nigerian domiciliary account via SWIFT can cost up to $60 to $100 in stacked fees across the three layers: the US bank’s outgoing wire fee ($35 to $50), correspondent bank deductions in transit ($10 to $30 per bank), and the Nigerian receiving bank’s incoming wire fee. These fees apply regardless of the transfer amount, which is why SWIFT wires only make financial sense on larger transfers where the fixed cost is a small percentage of the total.

How long does a SWIFT wire to Nigeria take?

SWIFT transfers to Nigeria typically take one to three business days after the US bank initiates the transfer. Large transfers may be held for CBN compliance review, which can extend the timeline. Transfers initiated late in the US banking day or on Fridays may not begin processing until the following business day. Grey ACH transfers to a US account number typically arrive in one to two business days.

Is there a cheaper way to get USD into Nigeria without using SWIFT?

Yes. A USD account through a multi-currency platform like Grey receives ACH transfers from US senders at a fraction of the cost of SWIFT transfers. Grey’s deposit fee is 0.8%, capped at $10, compared to $60-$100 in SWIFT fees for the same transfer. The tradeoff is that the USD lands in a Grey account rather than a Nigerian bank domiciliary account. For recipients who need SWIFT credit advice from a Nigerian bank for legal or institutional purposes, traditional wire transfers remain necessary. For everyday dollar receipts, the ACH route through Grey is significantly cheaper.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH incur a 0.8% fee (minimum $2, maximum $10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction.

How to convert and send USD to Ugandan Shillings (UGX) online

•

•

2 min read

Managing cross-border payments doesn’t have to be complicated. Whether you’re a freelancer, remote worker, or supporting family in Uganda, converting USD to Ugandan Shilling (UGX) can be quick, secure, and hassle-free with Grey.

This guide shows you how to easily convert and send USD to UGX online, highlighting key benefits, costs, and tips for seamless transactions.

Why use Grey to convert and send USD to UGX?

Grey is a digital banking platform designed for global citizens who want to manage multiple currencies easily. Here’s why Grey is an excellent choice for converting and sending USD to UGX:

  • Competitive exchange rates: Grey offers real-time rates to ensure you get the most value when converting USD to UGX.
  • Low fees: Avoid the high conversion and transfer fees associated with traditional banks.
  • Quick transfers: Funds are processed quickly, ensuring your recipients get the money without delays.
  • User-friendly platform: Grey’s app and website are designed to make international transactions simple and accessible for everyone.

Exchange rates fluctuate for various reasons, so we’ve designed a handy, real time currency converter for you.

Also read: How to convert and send USD with Grey

How to convert and send USD to UGX with Grey

1. Create your Grey account

First, sign up for a free Grey account via the website or app, available on iOS and Android. Registration is straightforward and requires you to:

  • Provide basic personal information.
  • Verify your identity by uploading the required documents.
  • Set up your virtual wallet for multiple currencies, including USD.

2. Add USD to your Grey account

Once your account is active, deposit USD into your Grey wallet. You can do this in several ways:

  • Bank transfer: Link your USD bank account and transfer funds directly.
  • Freelance platforms: Receive payments from platforms like Upwork or Fiverr directly into your Grey USD wallet.
  • Wire transfers: Accept payments from international clients or businesses.

With USD in your account, you can convert it into UGX.

3. Convert USD to Ugandan Shilling with Grey

Follow these steps to convert your USD to UGX:

  1. Log into your account: Open the Grey app or website and sign in.
  2. Navigate to currency exchange: Select the “Convert” option from the dashboard.
  3. Choose currencies: Select USD as the source currency and UGX as the destination currency.
  4. Enter the amount: Specify the amount of USD you want to convert.
  5. Confirm the transaction: Review the exchange rate, fees, and total amount in UGX, then click “Convert.” The converted funds will appear in your UGX wallet instantly.

4. Send UGX to your recipient

Once your USD is converted to UGX, it’s time to transfer the funds to your recipient in Uganda. Here’s how:

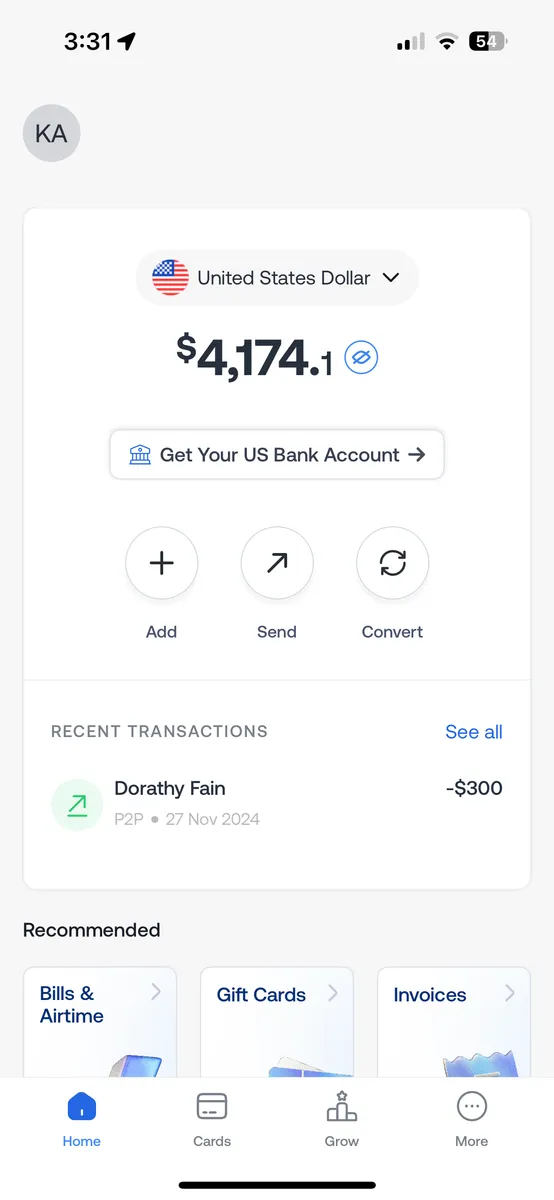
1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

676ec441190ed0b08ba00d26 676ebd9e62b40f1197672db7 send us dollars grey 6

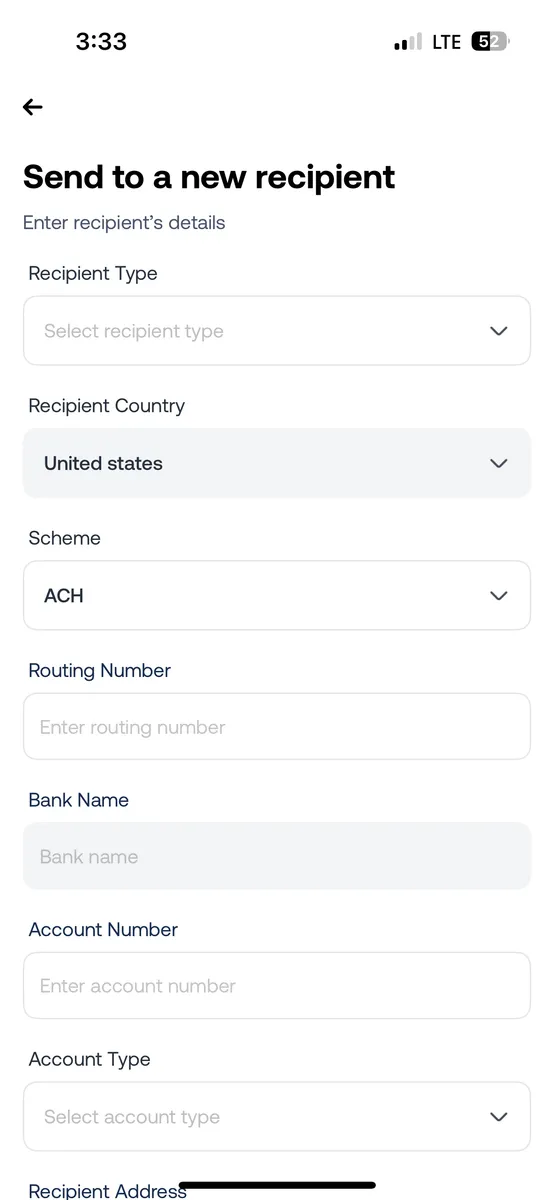
2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

676ec442190ed0b08ba00d42 676ebd4d245072006253a99c send us dollars grey 4

3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

676ec442190ed0b08ba00d3f 676ec3b94c9821344d4d5d63 IMG 0368

4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

676ec442190ed0b08ba00d79 676ec3c426d44aa2a43d7fc8 IMG 0370

5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

676ec442190ed0b08ba00d45 676ec3d1138ab1eb14571c89 IMG 0371

‍

‍You may also like: How to convert and send USD to TZS online

Key tips for converting and sending USD to UGX

  1. Monitor exchange rates: Keep an eye on the exchange rate to convert your funds at the best possible time.
  2. Double-check recipient details: Ensure the accuracy of bank account or mobile wallet information to avoid delays.
  3. Use Grey’s multi-currency wallets: Store USD and UGX in your Grey account to avoid frequent conversions and save on fees.
  4. Track your transactions: Grey offers a transaction history feature to easily track conversions and transfers.

Why Grey is the best option for USD to UGX transfers

Grey stands out as a reliable and cost-effective platform for handling international payments. Here’s why it’s a top choice:

  • Speed: Transfers are processed faster than most traditional banks, so your recipients get their money quickly.
  • Savings: With low fees and competitive exchange rates, you keep more of your hard-earned money.
  • Flexibility: Manage multiple currencies from one account and send funds anytime, anywhere.
  • Security: Grey prioritises secure transactions, giving you peace of mind.

Take control of your cross-border payments with Grey

Converting and sending USD to Ugandan Shilling has never been easier. Whether supporting family, paying vendors, or managing personal finances, Grey’s seamless platform saves you time, money, and effort.

Ready to simplify your financial transactions? Sign up with Grey today and enjoy a hassle-free way to convert and send USD to UGX online.

‍

How to start a dropshipping business in Nigeria

•

•

2 min read

Dropshipping has come a long way in the African market, and that’s because it is a business model that allows entrepreneurs to sell products without holding inventory. The way it works is, whenever a customer orders a product, as the business owner, you’ll buy that item from a third-party supplier, who will ship the product directly to the customer. 

This business model has become increasingly popular because it eliminates the need for upfront inventory costs, storage space, and shipping logistics. 

As a result, it has gained traction in the Nigerian market in recent years as it is a cost-effective way for entrepreneurs to start an online business without needing physical inventory. 

Benefits of dropshipping in Nigeria

There are several benefits of dropshipping in Nigeria; some of them include:

  1. Low Overhead Costs: Dropshipping requires minimal inventory investment so that you can start your business with little or no budget.
  2. Flexibility: Dropshipping allows you to work from anywhere and at any time, as long as you have an internet connection.
  3. Wide Range of Products: With drop shipping, you can offer a wide range of products without worrying about inventory management. Sell whatever you want from multiple suppliers.
  4. Minimal Risk: Dropshipping is less risky than traditional retail because you don’t have to hold inventory.

Seven steps on how to start a dropshipping business in Nigeria

Now that we know what dropshipping is and understand its benefits, how do you start it in Nigeria? 

Step 1: Choose your niche and products

The first step in starting a dropshipping business is to choose a niche and the products you want to sell. A niche is a specific area of focus within a larger market. Choosing a niche you are interested in and knowledgeable about is essential. It will make it easier to identify the best products to sell, and you can create marketing plans that’ll resonate with your target audience.

Once you’ve chosen your niche, research the best products to sell. Look for products that are in demand, have a high-profit margin, and are accessible to source from reliable suppliers. You can use tools like Google Trends, Amazon Bestsellers, and Oberlo to help you find popular products.

Step 2: Research suppliers

There are various online suppliers, depending on what you want to sell. However, your dropshipping business’s success depends on finding reliable suppliers who can provide quality products at competitive prices. 

When researching suppliers, look for those who have a good reputation, offer fast shipping, and have a wide range of products.

There are many dropshipping suppliers that you can use, including AliExpress, SaleHoo, and many more. You can also consider using local suppliers in Nigeria to reduce shipping costs and improve delivery times.

Step 3: Create your online store

Now that you have chosen your niche, products and a reliable supplier, it’s time to create your online store or decide on the platform you’d use for sales. 

You can use e-commerce platforms like Shopify, WooCommerce, or WordPress to set up your store or decide to sell on platforms like Instagram, Snapchat, and WhatsApp. 

However, while creating your online store, choose names or domain names that are easy to remember. Then design your website and add your products. Ensure your website is easy to navigate, visually appealing, and mobile-friendly.

Step 4: Research delivery options

Your dropshipping success or failure depends mainly on delivery, especially in the Nigerian market. So therefore, to run a successful dropshipping business, you must either deal with reputable delivery agents or partner with your hosting platforms, such as Shopify, to set up delivery. 

Step 5: Set up a payment platform

This should be pretty straightforward. However, Shopify provides payment apps and getaways to set up your payment processor. Also, since many of your transactions with supplies will involve foreign currency, you can set up your payments with  Grey.

With Grey, you can send money to any foreign account, including your supplier’s account, without any stress or hidden fees. 

You can also use it to receive payments from your earnings if you’re dropshipping with partners like Amazon FBA.

Step 6: Market your business

Now that your online store is running, it’s time to start marketing your business. There are many ways to promote your dropshipping business, including;

  • Social media marketing: Use platforms like Facebook, Instagram, and Twitter to reach your target audience and promote your products.
  • Content marketing: Create blog posts, videos, and other content that educates your audience about your products and industry.
  • Influencer marketing: Partner with influencers in your niche to promote your products to their followers.
  • Search engine optimization: Optimize your website for search engines to improve your rankings and drive more traffic.

Step 7: Manage your business

As your dropshipping business grows, it’s essential to manage it effectively. This includes tracking inventory, promptly fulfilling orders, and providing excellent customer service.

You’ll also need to continually analyze your business metrics, such as your conversion rate, customer acquisition cost, and lifetime value. This information will help you identify areas where you can improve your business and make data-driven decisions.

In conclusion, dropshipping is a viable business model for entrepreneurs looking to start an online business in Nigeria. 

However, starting a dropshipping business requires research, planning, and execution. When it comes to sending and receiving funds, as that is one the major challenge faced by Nigerians, it is important to sign up for reliable platforms makes it easier to transact globally and that where Grey comes in.

Grey allows you to open a foreign currency account to receive payments from anywhere. Get a free account today to make international payments or convert foreign currencies to Nigeria Naira.

‍

How to convert and send US dollars (USD) with Grey

•

•

2 min read

As a digital nomad your finances should work as flexibly as you do. With Grey, converting and sending USD becomes effortless, no matter where you are. From managing payments with US clients to handling multiple income streams, Grey makes accessing and transferring your funds quick, affordable, and hassle-free.

In this guide, we’ll walk you through effortlessly converting and sending US dollars with Grey, revealing how to maximise savings, cut through complexity, and make global financial management a breeze.

Why Grey is perfect for sending and converting US dollars

Managing your finances can be challenging, especially when working with clients or employers in different currencies. Whether you’re based in Asia, Europe, or anywhere else, having a platform that supports multi-currency accounts and provides transparent exchange rates is essential.

Grey offers several advantages for digital nomads and remote workers:

  • Multi-currency accounts: Grey lets you hold and manage funds in multiple currencies, including USD, EUR, GBP, and more, making it easy to convert and send money.
  • Low fees and competitive rates: Grey provides low conversion fees and competitive exchange rates, ensuring that more of your earnings stay with you.
  • Global accessibility: Whether in Bali, Mexico, or Spain, Grey’s mobile app allows you to manage your finances anywhere with an internet connection.
  • Seamless transfers: Sending USD or any other currency is fast and simple. Grey allows instant transfers to various bank accounts and wallets globally.
  • Easy account integration: You can link your Grey account to platforms like Amazon, freelance job sites, and other payment systems, simplifying the process of receiving and sending payments.

Exchange rates often fluctuate for several reasons, so we’ve created a special currency converter for you.

The benefits of converting and sending USD with Grey

Before diving into the conversion and sending process, let’s take a moment to explore why Grey is a great option for converting USD into local currencies or sending it to other accounts.

  1. Competitive exchange rates

Grey offers competitive exchange rates compared to traditional banks and other payment platforms. While rates vary based on market conditions, Grey provides real-time rates with a transparent view of conversion fees.

  1. Low conversion fees

Grey’s conversion fees are designed to be transparent and affordable.

  1. Efficient cross-border transfers

Fast and secure transfers are key when working internationally. Grey enables you to send USD to international accounts almost instantly. This feature is particularly useful for remote workers who must pay international invoices or send money to family members in other countries.

Grey also allows for quick transfers between different currency accounts, so if you need to convert USD into GBP, EUR, or any other supported currency, you can do so easily.

  1. Global accessibility

Since Grey is a fully digital platform, you can access it from anywhere in the world. This is particularly advantageous for digital nomads who frequently travel or live abroad, as it provides a consistent and reliable way to manage your finances regardless of location.

Step-by-step guide: How to convert and send USD with Grey

Now that you understand the benefits of using Grey, let’s walk through the detailed process of converting USD to another currency and sending it to a recipient, whether for personal or business reasons.

Step 1: Sign up for a Grey account

If you haven’t already, the first step is to create an account with Grey. Visit Grey’s website or download the app from the App Store or Google Play. The sign-up process is straightforward and typically takes just a few minutes.

To start, you’ll need to provide personal details, verify your identity, and set up your account.

Step 2: Deposit USD into your Grey account

Once you’ve created your account, you can deposit USD into your Grey account. You can do this through several methods:

  • Bank transfer: Link your bank account to Grey and deposit funds directly into your USD account.
  • Payment platforms: If you receive payments from platforms like PayPal, Stripe, or other freelance networks, you can transfer your earnings directly to your Grey account.
  • Wire transfer: If you’re working with clients or employers who prefer wire transfers, you can provide them with your Grey account details so they can receive USD payments.

You can begin the conversion process after depositing USD into your Grey account.

Step 3: Convert USD to another currency

To convert USD into another currency, follow these steps:

  1. Open the Grey app: Log into your Grey account and navigate to the currency conversion section.
  2. Select the currencies: Choose USD as the source currency and select the destination currency (e.g., EUR, GBP, ZAR).
  3. Check the exchange rate: Grey will display the current exchange rate for the conversion, along with the conversion fees.
  4. Confirm the conversion: Once you’re satisfied with the rate and fees, confirm the transaction. Your funds will be converted and reflected in your Grey account in the new currency.

Step 4: Send USD or converted funds to a recipient

To send funds to another individual or account, you’ll need to:

1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

__wf_reserved_inherit

2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

__wf_reserved_inherit

3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

__wf_reserved_inherit

4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

__wf_reserved_inherit

5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

__wf_reserved_inherit

Convert and send USD: Key tips for remote workers

  1. Minimise fees: Always review Grey’s exchange rates and conversion fees before confirming any transaction. While Grey offers competitive rates, you may still want to plan your conversions to avoid unnecessary fees, especially if you’re sending large sums.
  2. Use local currency accounts: If you’re working in a country with a stable currency, consider holding a local currency account to avoid frequent conversions and fees.
  3. Monitor exchange rates: Grey updates its exchange rates in real time. If you’re converting large sums, it may be worth monitoring rates for a few days to ensure you get the best deal.
  4. Use Grey’s app for convenience: Grey’s mobile app allows you to convert and send USD or other currencies from anywhere in the world, which is a huge advantage for digital nomads who need to manage their finances on the go. Download Grey now and get started.

Simplify converting and sending USD with Grey

Converting and sending USD with Grey is an efficient and cost-effective way for remote workers and digital nomads to manage their finances. With competitive exchange rates, low fees, and the convenience of a fully digital platform, Grey provides a seamless solution for handling cross-border transactions.

Ready to start using Grey? Sign up today and take control of your global finances.

‍

How the exchange rate fluctuation is affecting Nigerian freelancers

•

•

2 min read

Bisola negotiated a product design contract when the dollar was trading at around ₦1,100. By the time she completed the project and received payment, the rate had shifted to ₦950. Same USD amount, fewer naira in her account. For a freelancer budgeting in naira, that gap is not abstract. It is rent, fuel, and groceries.

This is the reality of earning in foreign currency while spending in naira. Since Nigeria officially floated the naira in June 2023, the exchange rate has become considerably more volatile, more sensitive to external shocks, and harder to plan for than under the previous managed float system. The naira's value is now determined by market forces, which shift week to week.

If you are a freelancer or remote worker earning USD, GBP, or EUR from international clients, exchange rate fluctuations affect your effective income every time you convert. This article breaks down why the naira moves, how that movement hits different types of freelancers, and what you can do to keep more of what you earn.

Why does the naira move so much

Understanding the forces behind the volatility helps you make better decisions about when and how to convert your earnings. Two factors drive most of the movement.

Inadequate dollar supply

Nigeria's economy depends heavily on oil exports for its foreign exchange earnings. When oil revenues drop, whether because of falling global prices, pipeline disruptions, or reduced production quotas, the supply of dollars in the market shrinks. Meanwhile, demand for dollars from businesses and individuals remains constant or increases. When demand outstrips supply, the naira weakens against the dollar. This dynamic has played out repeatedly since the float, with the parallel market rate often diverging significantly from the official rate during periods of acute dollar scarcity.

Inflation

Nigeria's inflation rate has been at record highs since 2023, driven by the removal of fuel subsidies, higher import costs, and currency depreciation, which feed into prices. High inflation reduces the competitiveness of Nigerian exports and increases import demand, which in turn increases the demand for foreign currency and puts further downward pressure on the naira. The result is a feedback loop: the naira weakens, prices rise, and the naira weakens further.

How this plays out for Nigerian freelancers in practice

The impact of exchange rate fluctuations depends on how you have structured your pricing and payment process. Most freelancers fall into one of four categories, and each faces a different kind of exposure.

Freelancers priced in naira with foreign clients

This is the most vulnerable position. If you quote a rate in naira to a foreign client and they pay the naira equivalent at the time of payment, a naira depreciation between when you quoted and when the payment arrives actually increases your naira earnings. But a naira appreciation does the opposite. This unpredictability is why many freelancers are moving away from pricing in naira for international work entirely.

Freelancers are priced in USD, but converting immediately

This is where someone like Bisola falls. If you price in USD, your foreign currency income remains fixed regardless of how the naira moves. However, the naira value of that USD changes depending on when the conversion happens. A freelancer who converts immediately on receipt takes whatever rate is available that day. On a day when the naira has weakened, the conversion is favourable. On a day when the naira is doing better, the freelancer receives less naira than they would have if they had waited.

This is typically what happens with traditional Nigerian bank accounts. If you receive a USD payment into a regular GTBank or Access Bank account, the money gets converted to naira at that day's exchange rate, usually with a 2% to 3% markup applied by the bank, without your control. The account does not support holding USD.

Freelancers holding USD and converting at will

Some freelancers keep their earnings in USD and convert to naira only when the rate looks stable or when they have a specific naira need. The principle is straightforward: do not convert at an arbitrary moment dictated by your bank's processing schedule. This approach requires having a USD account that allows you to hold a balance and choose when to convert. Traditional Nigerian commercial banks do not make this easy; domiciliary account conversions at many banks are done at the bank's rate on the day of conversion, with the account holder unable to choose the timing.

Freelancers are pricing upward to compensate

Some freelancers have responded to exchange rate uncertainty by increasing their USD rates to build in a buffer against unfavourable conversions. This is a rational short-term measure, but it carries risk. If your rates start to exceed market norms for your skill level, you may lose clients to competitors who have found other ways to manage currency exposure. An exchange rate buffer only works if you can sustain it without pricing yourself out.

The difference between a well-timed conversion and a poorly-timed one is not trivial. Between 2024 and 2025, converting $1,000 could mean a difference of ₦150,000 to ₦200,000 depending on the week. For a freelancer converting $2,000 to $5,000 per month, the total annual difference can run into millions of naira.

Also read: Managing irregular income as a freelancer

Managing the effects of exchange rate fluctuations

The goal is not to predict where the naira is headed. It is to structure your earnings and conversion process so that you have control over timing, visibility into rates, and resilience against currency movements.

Diversify your income across currencies

If all your international income is in USD, you are fully exposed to a single exchange rate. A freelancer earning partly in USD from US clients and partly in GBP from UK clients holds two independent, relatively stable currencies. When one rate moves unfavourably, the other may be neutral or positive. This does not eliminate exposure, but it reduces the impact of any single currency swing on your total naira earnings.

Use an account that lets you hold foreign currency

The most practical step a freelancer can take is to separate the moment of receiving payment from the moment of converting to naira. With a foreign currency account, you receive USD, GBP, or EUR directly into a wallet you control. The money sits there until you decide to convert. You are not forced into a conversion at whatever rate your bank offers on the day the payment arrives.

Several platforms offer this for Nigerian freelancers. Grey provides USD, GBP, and EUR accounts with foreign banking details (routing numbers for USD, sort codes for GBP, IBANs for EUR). Wise offers multi-currency accounts with mid-market rate conversions, though its Nigeria withdrawal options are more limited. Payoneer is widely used for platform payouts (Upwork, Fiverr), but it applies a conversion spread that can be higher than that of dedicated multi-currency accounts. Each has trade-offs in fees, supported currencies, and withdrawal speed. The right choice depends on where your clients are and how you spend.

Understand the timing of your conversions

You do not need to become an exchange rate expert. You need to know three things before converting: the rate you are getting, whether there are any markups or fees on top of that rate, and whether you can wait. If your platform shows you the rate before you confirm and lets you hold your balance until a better moment, you have the tools to make a reasonable decision. If your platform converts automatically without showing you the rate, you have no control.

Invoice in a stable foreign currency

Billing international clients in USD, GBP, or EUR removes naira volatility from the pricing equation entirely. Your invoice amount is fixed in a stable currency. The only variable is when you choose to convert it. This is especially important for longer projects where weeks or months pass between quoting and receiving payment. If you quote in naira and the rate moves against you during that period, you absorb the loss. If you quote in USD, the loss (or gain) only materialises at the point of conversion, which you control.

Grey's built-in invoicing feature lets you create and send invoices in USD, GBP, or EUR directly from the app. The client pays, the funds land in your Grey wallet in the invoiced currency, and you convert when you are ready. You can learn more about invoicing on Grey.

Also read: Freelancer's guide to handling currency fluctuations

Choosing a payment platform that gives you control

When currencies are volatile, the platform you use to receive and hold foreign income matters more than usual. The features that make the biggest difference are whether the platform allows you to hold a foreign currency balance without automatic conversion, whether the conversion rate is disclosed before you confirm, whether conversion fees are flat or percentage-based (because on larger amounts a percentage compounds quickly), and whether you can convert at a time you choose.

Here is how three commonly used platforms compare on these criteria for Nigerian freelancers.

Role Entry-Level Pay Senior Pay Key Platforms Barrier to Entry Best For
Software Development $800-$1,300/mo $5,000-$10,000/mo Toptal, Turing, and Andela High (1-2 yrs learning) Nomads with coding experience
Web & Graphic Design $500-$1,000/mo $3,000-$5,000/mo Dribbble, Toptal, 99designs Medium (portfolio needed) Visual thinkers with design tools
Content Writing $0.05-$0.10/word $36K-$60K/yr (agency) Upwork, Fiverr, LinkedIn Low (start writing today) Nomads starting from scratch
Social Media Mgmt $500-$1,000/mo $2,000-$4,000/mo LinkedIn, direct outreach Low-Medium Creative, platform-savvy nomads
Data Science $25-$50/hr $80-$120/hr Kuda, Interswitch, Google High (technical skills) Analytical, quantitative thinkers

Grey provides USD, GBP, and EUR accounts with real foreign banking details. Clients pay via ACH, SEPA, or Faster Payments, depending on the currency. A deposit fee of 0.8% applies (minimum $2/£2/€2, maximum $10/£10/€10). When you are ready to convert, the conversion fee is 1%, capped at $6. Withdrawal to a Nigerian naira bank account costs ₦35 per transaction. Grey virtual cards cost $4 to create with a $1 funding fee and link directly to your balance, so you can spend in USD, GBP, or EUR without converting first. Apple Pay and Google Pay integration is available in supported regions for contactless payments.

Note: Exchange rates on Grey are variable and include a margin over the mid-market rate. Grey does not charge transfer fees; the cost is reflected in the exchange rate. Always review the rate before confirming a conversion.

Frequently asked questions

Should Nigerian freelancers invoice in naira or USD?

Invoicing in USD, GBP, or EUR is generally the better approach for freelancers working with international clients. It removes naira volatility from the equation at the pricing stage, giving you a fixed foreign currency amount to manage. The only decision left is when to convert, which you control if you use an account that allows you to hold foreign currency.

How much does timing a conversion actually save?

The impact depends on the size and frequency of your conversions. Between 2024 and 2025, the naira-to-dollar rate fluctuated enough that converting $1,000 at different points could mean a difference of ₦150,000 to ₦200,000. For freelancers converting $3,000 to $5,000 monthly, choosing to convert during a stable or favourable window rather than at an arbitrary moment can add up to millions of naira annually.

Does the CBN's floating of the naira affect how freelancers receive international payments?

The float itself does not change how international payments arrive. Your USD still lands in your account the same way. What changes is the naira value of those payments at any given point in time. The practical implication is that platforms allowing you to hold foreign currency and convert at a disclosed rate give you more control than those that convert automatically when the money lands.

Can I hold USD in a regular Nigerian bank account?

Standard savings and current accounts at Nigerian banks do not hold USD. They convert incoming foreign currency to naira at the bank's rate on the day of receipt, typically with a 2% to 3% markup. Domiciliary accounts at Nigerian banks do hold foreign currency, but opening one requires a branch visit, paperwork, and sometimes a minimum balance. Fintech platforms like Grey, Wise, and Payoneer offer a faster alternative: you can open a USD account online in minutes and hold your balance until you choose to convert.

What is the cheapest way to convert USD to Naira as a freelancer?

The total cost of conversion depends on two factors: the exchange rate spread (the difference between the provider's rate and the mid-market rate) and any flat or percentage fees applied on top. A platform offering the mid-market rate with a 1% fee may be cheaper than one offering a "free" conversion with a 3% spread baked into the rate. Always compare the effective rate, which is the total naira you receive per dollar after all costs, rather than looking at individual line items.

—

Ready to take control of your conversions? Sign up at grey.co and download the Grey app to open your USD, GBP, or EUR account in minutes.

‍

Arrow (up)

Back to top