<script type="application/ld+json"> [ {"@context":"https://schema.org/","@type":"BlogPosting","@id":"https://grey.co/blog/what-is-an-offshore-account#article","mainEntityOfPage":{"@id":"https://grey.co/blog/what-is-an-offshore-account"},"headline":"What is an offshore bank account? A complete guide","description":"A complete guide to offshore bank accounts: what they are, how they work, whether they're legal, the difference between offshore and foreign accounts, a four-step process to open a multi-currency account online, and how they compare with modern alternatives.","image":["https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a7e2d19e455e9aed8d3d8be_What%20Is%20an%20Offshore%20Bank%20Account%20How%20to%20Open%20One-compressed-p-130x130q80.jpg"],"datePublished":"2026-08-13T09:00:00+01:00","dateModified":"2026-08-17T09:00:00+01:00","inLanguage":"en","articleSection":"Personal Finance","keywords":"offshore bank account, offshore account legal, foreign bank account vs offshore, multi-currency account, FATCA, CRS Common Reporting Standard, FBAR, open offshore account online","author":{"@type":"Person","name":"Adeolu Titus Adekunle","jobTitle":"Content Writer","worksFor":{"@id":"https://grey.co/#organization"}},"publisher":{"@id":"https://grey.co/#organization"},"about":[{"@type":"Thing","name":"Offshore bank accounts"},{"@type":"Thing","name":"Multi-currency accounts"},{"@type":"Thing","name":"International banking compliance"},{"@type":"Thing","name":"Foreign account tax reporting"}]}, {"@context":"https://schema.org/","@type":"BreadcrumbList","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"What is an offshore bank account? A complete guide","item":"https://grey.co/blog/what-is-an-offshore-account"}]}, {"@context":"https://schema.org/","@type":"FAQPage","mainEntity":[{"@type":"Question","name":"Is there a minimum deposit to open an offshore bank account?","acceptedAnswer":{"@type":"Answer","text":"It depends on the provider. Traditional offshore banks, particularly those serving high-net-worth clients, often require minimum deposits of $10,000 or more. Modern multi-currency fintech accounts, including Grey, typically have no minimum deposit, making them more accessible to freelancers, remote workers, and small businesses."}},{"@type":"Question","name":"Is an offshore bank account worth it?","acceptedAnswer":{"@type":"Answer","text":"If you earn, spend, or save in multiple currencies, an offshore or multi-currency account can be useful. It can reduce the need for repeated currency conversions through a domestic bank, which may become expensive over time. For most individuals, a modern multi-currency account can provide the practical benefits of offshore banking with less cost and complexity."}},{"@type":"Question","name":"Can anyone open an offshore bank account?","acceptedAnswer":{"@type":"Answer","text":"Most people can open a modern multi-currency account online if they can complete standard identity verification, usually with a government-issued ID and proof of address. Traditional offshore banks may have stricter requirements, including minimum deposits and restrictions based on nationality or country of residence."}},{"@type":"Question","name":"Is money in an offshore account taxable?","acceptedAnswer":{"@type":"Answer","text":"Yes. Income earned through an offshore or foreign account is generally taxable in your country of tax residence. Depending on your location, you may also need to declare the account even if it does not generate income; for example, US persons may have FBAR reporting requirements. Failing to declare an account when required can lead to significant penalties. This is general information, not tax advice."}},{"@type":"Question","name":"What is the difference between an offshore account and a savings account?","acceptedAnswer":{"@type":"Answer","text":"A savings account describes the purpose of an account: holding money and potentially earning interest. An offshore account describes where the account is held: outside your home country. They are not mutually exclusive. You can have an offshore savings account or an offshore transaction account."}},{"@type":"Question","name":"What is an offshore bank account?","acceptedAnswer":{"@type":"Answer","text":"An offshore bank account is simply a bank account held in a country other than the one you live in or are a citizen of. The term originally referred to accounts in jurisdictions physically separate from major economies, but is now used more broadly for any account held outside your home country. For example, a UK resident opening an account in Ireland, or a US freelancer using a UK-regulated fintech to receive European client payments, are both technically offshore banking."}},{"@type":"Question","name":"Are offshore bank accounts legal?","acceptedAnswer":{"@type":"Answer","text":"Yes, offshore accounts are legal as long as you follow the tax and reporting rules that apply in your country. Simply keeping money in a foreign account is not illegal in itself; what matters is whether you accurately declare that account and any income earned from it to your relevant tax authority. Many countries participate in information-sharing frameworks such as the OECD's Common Reporting Standard (CRS), and US citizens and residents are also subject to FATCA."}}]}, {"@context":"schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/what-is-an-offshore-account#offshore-terms","name":"Offshore and foreign account terms","description":"Key terms used to distinguish offshore banking from foreign accounts, and the international compliance frameworks that apply to them.","hasDefinedTerm":[{"@type":"DefinedTerm","name":"Offshore bank account","description":"A bank account held in a country other than the one you live in or are a citizen of. Historically associated with low-tax or high-secrecy jurisdictions such as the Cayman Islands, Switzerland, and the Channel Islands, though the term is now used more broadly for any account held outside your home country.","inDefinedTermSet":"https://grey.co/blog/what-is-an-offshore-account#offshore-terms"},{"@type":"DefinedTerm","name":"Foreign bank account","description":"A straightforward, neutral term for an account held outside your country of residence. Often used interchangeably with 'offshore bank account' in everyday financial discussion, though the distinction matters more in specific legal, tax, and compliance contexts.","inDefinedTermSet":"https://grey.co/blog/what-is-an-offshore-account#offshore-terms"},{"@type":"DefinedTerm","name":"CRS (Common Reporting Standard)","termCode":"CRS","description":"An OECD international information-sharing framework under which participating countries' foreign banks report information about foreign account holders to the relevant tax authorities.","inDefinedTermSet":"https://grey.co/blog/what-is-an-offshore-account#offshore-terms"},{"@type":"DefinedTerm","name":"FATCA (Foreign Account Tax Compliance Act)","termCode":"FATCA","description":"US legislation requiring foreign financial institutions to report information about US citizens' and residents' foreign accounts to US tax authorities.","inDefinedTermSet":"https://grey.co/blog/what-is-an-offshore-account#offshore-terms"},{"@type":"DefinedTerm","name":"FBAR (Foreign Bank Account Report)","termCode":"FBAR","description":"A report US citizens and residents with foreign accounts above certain thresholds must file with FinCEN, in addition to reporting foreign income on their tax return.","inDefinedTermSet":"https://grey.co/blog/what-is-an-offshore-account#offshore-terms"}]}, {"@context":"https://schema.org/","@type":"HowTo","name":"How to open a multi-currency account online","description":"A four-step process to open a modern multi-currency account as an alternative to a traditional offshore bank account, typically completed the same day with no minimum deposit.","step":[{"@type":"HowToStep","position":1,"name":"Choose a provider based on the currencies you need","text":"Find a multi-currency account provider that gives real foreign account details in USD, EUR, and GBP, such as a routing number, sort code, or IBAN."},{"@type":"HowToStep","position":2,"name":"Complete identity verification online","text":"Most providers require a government-issued ID and proof of address, which you can usually submit via the provider's app or website."},{"@type":"HowToStep","position":3,"name":"Access your account details","text":"Once your account is approved, you can access your local banking details and start receiving and sending money."},{"@type":"HowToStep","position":4,"name":"Fund the account","text":"Add funds by transferring from your existing bank account, or receive your first payment directly once your account details are active."}]} ] </script>

What is an offshore bank account? A complete guide

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

Say the words “offshore bank account”, and most people instinctively think of a shadowy villain in a spy movie, casually wiring millions of dollars to a secret Swiss account. But this image is not quite accurate.

An offshore bank account is simply an account held in a country other than the one you live in. People use them to hold foreign currency, receive international payments, and protect savings against local currency swings. Offshore accounts are legal when declared to your tax authority. A multi-currency account offers most of the same benefits online.

So, it is not about popular culture with secrecy, tax evasion, or complex wealth structures reserved for the very rich. And this guide clarifies this by explaining what an offshore bank account actually is, how it works, whether it is legal, and how modern multi-currency accounts have made many of the practical benefits accessible to anyone.

What is an offshore bank account?

An offshore bank account is simply a bank account held in a country other than the country you live in or are a citizen. The term originally referred to accounts in jurisdictions physically separate from major economies, such as island nations. Today, it is used more broadly for accounts held outside your home country.

That makes offshore banking less mysterious than it often sounds. For example, if you live in the UK and open a bank account in Ireland, that is technically an offshore account. Similarly, if a US freelancer opens a foreign currency account with a UK-regulated fintech to receive payments from European clients, that can also be considered offshore banking.

The idea of offshore accounts as secret bank accounts comes largely from how it has been abused in the past, especially in certain jurisdictions with strict banking secrecy. But with International information-sharing agreements now in play, the secrecy has declined significantly.

Today, offshore accounts are commonly used to hold foreign currencies, manage international income, and access financial services that may not be available in someone's home country.

How do offshore bank accounts work?

An offshore account works much like a regular bank account, although there are some important differences.

  • Holding foreign currency: One of the main reasons people use offshore or foreign accounts is to hold money in another currency without converting it immediately. This can be useful if you earn in a foreign currency or expect to spend money in that currency later.
  • Receiving and sending money internationally: Many offshore accounts provide local banking details for the currency they support. For example, a USD account may provide a US routing number, while a GBP account may provide a UK sort code. Your clients, employers, or family can then send money to you as a local transfer rather than an expensive international wire.
  • Interest and account features: Some offshore accounts pay interest on your balance, although rates vary by provider and currency. Many also offer features such as debit cards, online banking, and international transfers.
  • Access: Traditional offshore bank accounts may require in-person verification, minimum deposits, or ongoing maintenance fees. Modern fintech and multi-currency accounts have made the process much easier, with many allowing you to open an account online after completing identity verification.

Are offshore accounts legal?

Yes, offshore accounts are legal, as long as you follow the tax and reporting rules that apply in your country. Simply keeping money in a foreign account is not illegal in itself. What matters is whether you accurately declare that account and any income earned from it to your relevant tax authority.

Many countries participate in international information-sharing frameworks, including the OECD's Common Reporting Standard (CRS). US citizens and residents are also subject to the Foreign Account Tax Compliance Act (FATCA).

These rules mean foreign banks may be required to report information about foreign account holders to the relevant tax authorities. US citizens and residents with foreign accounts above certain thresholds may also need to file a Foreign Bank Account Report (FBAR) with FinCEN and report foreign income on their tax return.

In other words, the legal issue is usually not having an offshore account. It is failing to declare it when required.

This is general information, not tax or legal advice; consult a qualified tax professional for guidance specific to your situation and jurisdiction.

Who should consider an offshore or multi-currency account?

An account outside your home country can be useful for several groups of people.

  • Expats and people living abroad: If you live in one country but earn money, own assets, or plan to retire in another, an offshore or foreign account can make managing money across both countries easier and reduce unnecessary currency conversions.
  • Freelancers and remote workers with foreign clients: Receiving payments in your client's currency through local banking details can help you avoid international wire fees and repeated currency conversions.
  • Savers dealing with local currency volatility: If your local currency is losing value quickly, holding some savings in a more stable currency such as USD, GBP, or EUR can help protect your purchasing power.
  • Frequent travellers: Holding balances in multiple currencies simplifies spending across countries without repeated conversion at unfavourable rates each time.
  • International business owners: Businesses with customers or suppliers in different countries can use multiple currency accounts to receive and make payments without converting money unnecessarily.

Offshore account vs foreign bank account: what is the difference?

The terms offshore bank account and foreign bank account are often used interchangeably, although there is a slight difference in how they are viewed.

A foreign bank account is simply an account held outside your country of residence. It is a straightforward and neutral description.

An offshore account can mean the same thing, but the term has historical associations with low-tax or high-secrecy jurisdictions such as the Cayman Islands, Switzerland, and the Channel Islands.

In everyday financial discussions, the two terms are often used to describe the same thing. They both refer to a bank account held outside your home country. The distinction becomes more important in specific legal, tax, and compliance situations.

Whether you need an account as an individual or a small business, the use is essentially the same. They allow you to hold, receive, and spend money in another currency or through a financial system different from that of your country.

How to open an offshore or multi-currency account online

Opening a traditional offshore account can be complicated. Many banks require you to visit the bank to open the account, make a large miminum deposit (sometimes over $10,000), and pay the relevant fees (including maintenance fees). You will also need to provide extensive documents for anti-money laundering (AML) checks.

Multicurrency accounts are more modern and opening an account is more straightfoward. Here is how to open a multi-currency account. Note that there might be some slight variations based on your location and the digital platform.

  1. Choose a provider based on the currencies you need: Find a multi-currency account provider that gives real foreign account details in USD, EUR, and GBP, such as a routing number, sort code, or IBAN
  2. Complete identity verification online: Most providers require a government-issued ID and proof of address, which you can usually submit via the provider's app or website.
  3. Access your account details. Once your account is approved, you can access your local banking details and start receiving and sending money.
  4. Fund the account: You can add funds by transferring from your existing bank account or receive your first payment directly once your account details are active.

Opening a multi-currency account with Grey requires these simple steps. And at the end, you can request USD, EUR, and GBP accounts with the relevant details. A Grey account doesn’t require a physical hospital visit, a minimum deposit, or a lengthy account-opening process like traditional offshore banks. For non-residents specifically, see our guide on how non-residents can open international accounts online.

Offshore account vs modern multi-currency account

International offshore accounts and modern multi-currency accounts can solve similar problems, but the experience and costs can be very different.

Feature Traditional offshore account Modern multi-currency account (Grey)
Account opening
Often requires in-person verification Fully online, typically completed same day
Minimum deposit
Often $10,000 or more None
Monthly fees
Common, sometimes significant None
Local banking details
Available, varies by provider Real routing number, sort code, or IBAN provided
Currencies supported Varies, often limited USD, GBP, EUR
Transaction fees
Varies by bank, not usually transparent Disclosed upfront - 0.8% deposit fee, 0.5% to 1% conversion, sometimes capped at $6)
Regulatory oversight
Varies by jurisdiction FinCEN (US) and FINTRAC (Canada)
Best for High-net-worth individuals with complex needs Freelancers, remote workers, expats, and small businesses

For most individuals and small businesses, a modern multi-currency account offers many of the benefits once reserved for traditional offshore accounts, but at lower cost and with less complexity. Our guide on how a multi-currency bank account works explains the mechanics in more detail.

If you earn, spend, or receive payments in different currencies, you don't necessarily need a traditional offshore bank. A multi-currency account can give you local account details, help you receive international payments, and let you hold multiple currencies in one place.

Compare your options and open a multi-currency account with Grey today.

Frequently asked questions about offshore bank account opening

Is there a minimum deposit to open an offshore bank account?

It depends on the provider. Traditional offshore banks, particularly those serving high-net-worth clients, often require minimum deposits of $10,000 or more. Modern multi-currency fintech accounts, including Grey, typically have no minimum deposit, making them more accessible to freelancers, remote workers, and small businesses.

Is an offshore bank account worth it?

If you earn, spend, or save in multiple currencies, an offshore or multi-currency account can be useful. It can reduce the need for repeated currency conversions through a domestic bank, which may become expensive over time. For most individuals, a modern multi-currency account can provide the practical benefits of offshore banking with less cost and complexity.

Can anyone open an offshore bank account?

Most people can open a modern multi-currency account online if they can complete standard identity verification, usually with a government-issued ID and proof of address. Traditional offshore banks may have stricter requirements, including minimum deposits and restrictions based on nationality or country of residence.

Is money in an offshore account taxable?

Yes. Income earned through an offshore or foreign account is generally taxable in your country of tax residence. Depending on your location, you may also need to declare the account even if it does not generate income. For example, US persons may have FBAR reporting requirements. Failing to declare an account when required can lead to significant penalties. This is general information, not tax advice, so speak to a qualified tax professional about your situation.

What is the difference between an offshore account and a savings account?

A savings account describes the purpose of an account: holding money and potentially earning interest. An offshore account describes where the account is held: outside your home country. They are not mutually exclusive. You can have an offshore savings account or an offshore transaction account for

Last updated:

September 3, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Your comprehensive guide to Grey's virtual card: Answers to common questions

2 min read

Thanks to the Black Friday sales, it’s raining discounts soon. The best part is that with a Grey virtual card, you don’t have to miss out on any of these offers, especially from your favorite international stores and brands. You can use your Grey virtual card to make payments on any platform or website that supports a US card, for instance, Apple, Udemy, Crunchyroll, Spotify, and many more.

However, to make your shopping experience easier, we’ll answer some common questions about the Grey card in this post.

1. How can I use it on AliExpress?

First things first, before making any transaction using your virtual card, it’s important to double-check that it’s adequately funded, as having two failed transactions from insufficient funds will lead to your card being flagged or frozen.

Now, to make payments on AliExpress using your Grey card, the process is quite straightforward. All you have to do is go to the payment section in your account and add a new card. You’ll fill out a short form with the following details: the card number, CVV, card name, and date, and be charged $1 by AliExpress for verification reasons.

After successfully adding your Grey card, you can easily select it as your preferred payment method at checkout.

If your virtual card is rejected, it’s usually due to one of the following reasons:

  • Incorrect card details
  • Incorrect card expiry date
  • Security measures from AliExpress, and you can appeal this by submitting the required documents to prove your identity.

2. Can I receive payments and withdraw from my card?

You can’t receive payments with your virtual card but can withdraw from it. However, a minimum of $1 must be left.

To withdraw from your card, all you have to do is reach out to our support team at support@grey.co, stating the amount you want to withdraw, and your request will be reviewed within 24 hours.

3. Can I use it to pay for my Apple subscriptions?

Of course! But because Grey virtual cards are USD cards, they’d only work in a US Apple store. So, you’re going to have to switch to a US store on your phone, which you can easily do on your settings app in five simple steps:

  • Tap your name and go to Media and Purchases.
  • Select view account (you might need to sign in again)
  • Tap Country/Region and select “Change Country and Region.”
  • Select your new country/region (i.e., the United States) and review the terms and conditions.
  • And finally, agree and confirm
  • Once you’ve confirmed this, you’ll be asked to put in your payment information, which would be the details of your Grey card, and that’s it! You no longer have to jump hoops to make Apple payments.

4. Does my Grey card support all types of transactions?

The short answer to this is no. The Grey virtual card doesn’t support the following transactions:

  • Cryptocurrency
  • Adult entertainment and pornography
  • Gambling
  • Sports betting
  • Drug paraphernalia — items used for drug use
  • For security reasons, your card would get blocked if used on any of these restricted websites.

Wrapping up

For only $4, you can easily create your own Grey virtual card, and you don’t have to worry about paying extra charges for card maintenance, transactions, or funding. Also, there are no hidden fees! So take the first step towards a life of easy and convenient payments by opening a Grey account today.

Practical tips to make your salary last longer in 2023

2 min read

Salary week is here again, and for many of us, it’s that time of the month to make poor financial decisions.

And, unfortunately, after 2-3 impulse buys, we’re stuck trying to figure out how to survive till the next credit alert. But you don’t have to live on the edge like this every month. So we’ve put together some practical tips to help you make your salary last till the next payda

1. Automate your savings

You’re probably tired of hearing this, but yes, you should have a savings plan, and ideally, you should save around 20% of your income. To make this process easier so you’re not tempted to spend money on other things, many apps like Piggyvest can help you set up automated savings. This way, you’re able to save consistently and develop good financial habits. Also, if you’re worried about your money losing value to inflation, you can save in EUR, GBP, and USD using a Grey account.

2. Resist peer-pressure

You should never forget, “There’s rice at home.” This can be especially helpful in cases where your friends are planning on eating out for the third weekend in a row. Minimizing the amount of money you spend on outings and overpriced meals every month will help your salary go further.

Also read: A Gen-Z’s Guide to Financial Independence

3. Use public transportation more

The current increase in the price of fuel has more than doubled the amount charged by car-hailing services like Bolt and Uber. However, using public transport more will help you save money as they’re cheaper and even better for the environment. This advice also applies to car owners as this way, they will be able to reduce the amount spent on fuel monthly.

4. Try thrifting

Another great way to stretch your paycheck is by thrifting. This way, you can save money on furniture, electronics, and other household items by buying from thrift or declutter stores online, which can help connect you to people looking to sell their fairly used items. Thrifting is also helpful for people with a unique sense of style, especially when it comes to outfits, as more often than not, you can find one-of-a-kind items that best express your personality.

5. Track your daily expenses

Sometimes, it’s difficult to figure out why or how you run out of money. This is why it’s important to create and stick to a budget. This way, you can easily track what you’re spending money on and identify unnecessary expenses. Grey can help you with your expense management with our expense insights feature that gives you a detailed breakdown of your spending and income.

Wrapping up

We agree that with the cost of living rising steadily, sometimes, the best solution is really a higher salary. However, while you’re still waiting for that to happen, in the meantime, you can try out some of these tips to enjoy the kind of peace having money in your bank account brings.

How to identify and avoid phishing scams: A guide for safe online transactions

2 min read

We’re days away from the second most wonderful time of the year — Black Friday. But as we take advantage of the many discounts to finally clear our carts, we should be careful not to fall victim to phishing websites that can steal your card or bank details to make unauthorized transactions.

This post tells you everything you need to know about phishing and how to recognize and prevent these scams.

What is Phishing?

Phishing scams are one of the most popular forms of cyberattack where a scammer disguises as a credible site, person, or organization to access your device, personal information, or banking details. The stolen information can be used to commit fraudulent activities, including unauthorized purchases.

There are different types of phishing scams, each with different goals. These include:

1. Email Phishing:

These types of emails impersonate banks, loan providers, or e-commerce websites. If you pay attention, you’ll notice that these emails come from unofficial email addresses or the domain name of the organization it claims to be from is misspelled, for instance, msonlineservices@mircosftfonline.com.

Some easy pointers to recognize a phishing mail are:

  • They usually contain spelling or grammatical errors.
  • They ask you to click on links or open suspicious attachments.
  • They use generic greetings like “Good day” or “Dear customer” instead of your first name.
  • They ask for sensitive information like passwords, full name, or card information.
  • They cause unnecessary panic or fear. For instance, emails with subject lines like: “Urgent: Your account has been compromised!”

It’s best to delete these emails and block the senders or install antivirus software to scan your emails and attachments first to ensure no malicious activity.

2. Spear phishing

The targets in spear phishing are targeted towards a specific person, business, or organization, and they are typically more successful because the scammers take time to study said targets. Spear phishing emails or messages are more personalized and are designed to be more convincing. They are also often well-crafted to make it appear more legitimate.

An example of this is an employee getting a mail appearing to come from the company’s CEO asking for a password change or to open an attachment, which eventually leads to a data breach with the company’s information stolen.

Here’s how you can prevent a spear phishing attack:

  • Double-check the sender’s name and email address
  • Check the email’s format to ensure it is similar to previous ones you’ve received
  • When the information being requested over mail is too sensitive, make a phone call to confirm
  • Scan the attachment to make sure it’s free from viruses or harmful codes

3. Whaling:

This is also known as CEO fraud, as it targets and tricks CEOs, CFOs, and COOs into providing sensitive corporate data or authorizing fraudulent transactions. Whaling scams are more complex as the scammers spend months combing through the social media profiles, company websites, and news articles of the targets to create personalized emails and messages that appear legitimate.

Some ways to prevent these types of attacks are:

  • Cybersecurity awareness and training for upper management
  • Installing anti-phishing software to flag emails from outside your organization
  • Use of multi-factor authentication (MFA)
  • Double-check requests for sensitive information or financial transactions

4. Pop-up Phishing:

This type of phishing is also known as clickjacking, and it usually tricks users into installing different types of malware or convinces them to buy fake antivirus software. This is effective because phishers use malicious codes to make these pop-ups appear on legitimate websites.

You can protect yourself from this type of phishing attack in the following ways:

  • Ensure your software and browser are up to date
  • Use a pop-up blocker
  • Don’t click on random pop-ups

Other common ways to protect yourself from phishing attacks include:

  • Never send sensitive information through emails or calls.
  • Use spam filters to get rid of spam and phishing emails.
  • Install security software like Norton 360 and firewalls.
  • Don’t share your information or download files from unsecured websites; secured sites usually start with “https” and have a closed padlock icon next to the URL.

Wrapping up

With over 500k users, we prioritize ensuring your data and funds are completely safe with us; you should also take extra precaution by ignoring links and or any form of communication outside of Grey's official channels. And with the Black Friday sales just around the corner, creating your Grey virtual card offers you access to international store discounts and the peace of mind of secure transactions.

How the exchange rate fluctuation is affecting Nigerian freelancers

2 min read

Bisola negotiated a product design contract when the dollar was trading at around ₦1,100. By the time she completed the project and received payment, the rate had shifted to ₦950. Same USD amount, fewer naira in her account. For a freelancer budgeting in naira, that gap is not abstract. It is rent, fuel, and groceries.

This is the reality of earning in foreign currency while spending in naira. Since Nigeria officially floated the naira in June 2023, the exchange rate has become considerably more volatile, more sensitive to external shocks, and harder to plan for than under the previous managed float system. The naira's value is now determined by market forces, which shift week to week.

If you are a freelancer or remote worker earning USD, GBP, or EUR from international clients, exchange rate fluctuations affect your effective income every time you convert. This article breaks down why the naira moves, how that movement hits different types of freelancers, and what you can do to keep more of what you earn.

Why does the naira move so much

Understanding the forces behind the volatility helps you make better decisions about when and how to convert your earnings. Two factors drive most of the movement.

Inadequate dollar supply

Nigeria's economy depends heavily on oil exports for its foreign exchange earnings. When oil revenues drop, whether because of falling global prices, pipeline disruptions, or reduced production quotas, the supply of dollars in the market shrinks. Meanwhile, demand for dollars from businesses and individuals remains constant or increases. When demand outstrips supply, the naira weakens against the dollar. This dynamic has played out repeatedly since the float, with the parallel market rate often diverging significantly from the official rate during periods of acute dollar scarcity.

Inflation

Nigeria's inflation rate has been at record highs since 2023, driven by the removal of fuel subsidies, higher import costs, and currency depreciation, which feed into prices. High inflation reduces the competitiveness of Nigerian exports and increases import demand, which in turn increases the demand for foreign currency and puts further downward pressure on the naira. The result is a feedback loop: the naira weakens, prices rise, and the naira weakens further.

How this plays out for Nigerian freelancers in practice

The impact of exchange rate fluctuations depends on how you have structured your pricing and payment process. Most freelancers fall into one of four categories, and each faces a different kind of exposure.

Freelancers priced in naira with foreign clients

This is the most vulnerable position. If you quote a rate in naira to a foreign client and they pay the naira equivalent at the time of payment, a naira depreciation between when you quoted and when the payment arrives actually increases your naira earnings. But a naira appreciation does the opposite. This unpredictability is why many freelancers are moving away from pricing in naira for international work entirely.

Freelancers are priced in USD, but converting immediately

This is where someone like Bisola falls. If you price in USD, your foreign currency income remains fixed regardless of how the naira moves. However, the naira value of that USD changes depending on when the conversion happens. A freelancer who converts immediately on receipt takes whatever rate is available that day. On a day when the naira has weakened, the conversion is favourable. On a day when the naira is doing better, the freelancer receives less naira than they would have if they had waited.

This is typically what happens with traditional Nigerian bank accounts. If you receive a USD payment into a regular GTBank or Access Bank account, the money gets converted to naira at that day's exchange rate, usually with a 2% to 3% markup applied by the bank, without your control. The account does not support holding USD.

Freelancers holding USD and converting at will

Some freelancers keep their earnings in USD and convert to naira only when the rate looks stable or when they have a specific naira need. The principle is straightforward: do not convert at an arbitrary moment dictated by your bank's processing schedule. This approach requires having a USD account that allows you to hold a balance and choose when to convert. Traditional Nigerian commercial banks do not make this easy; domiciliary account conversions at many banks are done at the bank's rate on the day of conversion, with the account holder unable to choose the timing.

Freelancers are pricing upward to compensate

Some freelancers have responded to exchange rate uncertainty by increasing their USD rates to build in a buffer against unfavourable conversions. This is a rational short-term measure, but it carries risk. If your rates start to exceed market norms for your skill level, you may lose clients to competitors who have found other ways to manage currency exposure. An exchange rate buffer only works if you can sustain it without pricing yourself out.

The difference between a well-timed conversion and a poorly-timed one is not trivial. Between 2024 and 2025, converting $1,000 could mean a difference of ₦150,000 to ₦200,000 depending on the week. For a freelancer converting $2,000 to $5,000 per month, the total annual difference can run into millions of naira.

Also read: Managing irregular income as a freelancer

Managing the effects of exchange rate fluctuations

The goal is not to predict where the naira is headed. It is to structure your earnings and conversion process so that you have control over timing, visibility into rates, and resilience against currency movements.

Diversify your income across currencies

If all your international income is in USD, you are fully exposed to a single exchange rate. A freelancer earning partly in USD from US clients and partly in GBP from UK clients holds two independent, relatively stable currencies. When one rate moves unfavourably, the other may be neutral or positive. This does not eliminate exposure, but it reduces the impact of any single currency swing on your total naira earnings.

Use an account that lets you hold foreign currency

The most practical step a freelancer can take is to separate the moment of receiving payment from the moment of converting to naira. With a foreign currency account, you receive USD, GBP, or EUR directly into a wallet you control. The money sits there until you decide to convert. You are not forced into a conversion at whatever rate your bank offers on the day the payment arrives.

Several platforms offer this for Nigerian freelancers. Grey provides USD, GBP, and EUR accounts with foreign banking details (routing numbers for USD, sort codes for GBP, IBANs for EUR). Wise offers multi-currency accounts with mid-market rate conversions, though its Nigeria withdrawal options are more limited. Payoneer is widely used for platform payouts (Upwork, Fiverr), but it applies a conversion spread that can be higher than that of dedicated multi-currency accounts. Each has trade-offs in fees, supported currencies, and withdrawal speed. The right choice depends on where your clients are and how you spend.

Understand the timing of your conversions

You do not need to become an exchange rate expert. You need to know three things before converting: the rate you are getting, whether there are any markups or fees on top of that rate, and whether you can wait. If your platform shows you the rate before you confirm and lets you hold your balance until a better moment, you have the tools to make a reasonable decision. If your platform converts automatically without showing you the rate, you have no control.

Invoice in a stable foreign currency

Billing international clients in USD, GBP, or EUR removes naira volatility from the pricing equation entirely. Your invoice amount is fixed in a stable currency. The only variable is when you choose to convert it. This is especially important for longer projects where weeks or months pass between quoting and receiving payment. If you quote in naira and the rate moves against you during that period, you absorb the loss. If you quote in USD, the loss (or gain) only materialises at the point of conversion, which you control.

Grey's built-in invoicing feature lets you create and send invoices in USD, GBP, or EUR directly from the app. The client pays, the funds land in your Grey wallet in the invoiced currency, and you convert when you are ready. You can learn more about invoicing on Grey.

Also read: Freelancer's guide to handling currency fluctuations

Choosing a payment platform that gives you control

When currencies are volatile, the platform you use to receive and hold foreign income matters more than usual. The features that make the biggest difference are whether the platform allows you to hold a foreign currency balance without automatic conversion, whether the conversion rate is disclosed before you confirm, whether conversion fees are flat or percentage-based (because on larger amounts a percentage compounds quickly), and whether you can convert at a time you choose.

Here is how three commonly used platforms compare on these criteria for Nigerian freelancers.

Role Entry-Level Pay Senior Pay Key Platforms Barrier to Entry Best For
Software Development $800-$1,300/mo $5,000-$10,000/mo Toptal, Turing, and Andela High (1-2 yrs learning) Nomads with coding experience
Web & Graphic Design $500-$1,000/mo $3,000-$5,000/mo Dribbble, Toptal, 99designs Medium (portfolio needed) Visual thinkers with design tools
Content Writing $0.05-$0.10/word $36K-$60K/yr (agency) Upwork, Fiverr, LinkedIn Low (start writing today) Nomads starting from scratch
Social Media Mgmt $500-$1,000/mo $2,000-$4,000/mo LinkedIn, direct outreach Low-Medium Creative, platform-savvy nomads
Data Science $25-$50/hr $80-$120/hr Kuda, Interswitch, Google High (technical skills) Analytical, quantitative thinkers

Grey provides USD, GBP, and EUR accounts with real foreign banking details. Clients pay via ACH, SEPA, or Faster Payments, depending on the currency. A deposit fee of 0.8% applies (minimum $2/£2/€2, maximum $10/£10/€10). When you are ready to convert, the conversion fee is 1%, capped at $6. Withdrawal to a Nigerian naira bank account costs ₦35 per transaction. Grey virtual cards cost $4 to create with a $1 funding fee and link directly to your balance, so you can spend in USD, GBP, or EUR without converting first. Apple Pay and Google Pay integration is available in supported regions for contactless payments.

Note: Exchange rates on Grey are variable and include a margin over the mid-market rate. Grey does not charge transfer fees; the cost is reflected in the exchange rate. Always review the rate before confirming a conversion.

Frequently asked questions

Should Nigerian freelancers invoice in naira or USD?

Invoicing in USD, GBP, or EUR is generally the better approach for freelancers working with international clients. It removes naira volatility from the equation at the pricing stage, giving you a fixed foreign currency amount to manage. The only decision left is when to convert, which you control if you use an account that allows you to hold foreign currency.

How much does timing a conversion actually save?

The impact depends on the size and frequency of your conversions. Between 2024 and 2025, the naira-to-dollar rate fluctuated enough that converting $1,000 at different points could mean a difference of ₦150,000 to ₦200,000. For freelancers converting $3,000 to $5,000 monthly, choosing to convert during a stable or favourable window rather than at an arbitrary moment can add up to millions of naira annually.

Does the CBN's floating of the naira affect how freelancers receive international payments?

The float itself does not change how international payments arrive. Your USD still lands in your account the same way. What changes is the naira value of those payments at any given point in time. The practical implication is that platforms allowing you to hold foreign currency and convert at a disclosed rate give you more control than those that convert automatically when the money lands.

Can I hold USD in a regular Nigerian bank account?

Standard savings and current accounts at Nigerian banks do not hold USD. They convert incoming foreign currency to naira at the bank's rate on the day of receipt, typically with a 2% to 3% markup. Domiciliary accounts at Nigerian banks do hold foreign currency, but opening one requires a branch visit, paperwork, and sometimes a minimum balance. Fintech platforms like Grey, Wise, and Payoneer offer a faster alternative: you can open a USD account online in minutes and hold your balance until you choose to convert.

What is the cheapest way to convert USD to Naira as a freelancer?

The total cost of conversion depends on two factors: the exchange rate spread (the difference between the provider's rate and the mid-market rate) and any flat or percentage fees applied on top. A platform offering the mid-market rate with a 1% fee may be cheaper than one offering a "free" conversion with a 3% spread baked into the rate. Always compare the effective rate, which is the total naira you receive per dollar after all costs, rather than looking at individual line items.

Ready to take control of your conversions? Sign up at grey.co and download the Grey app to open your USD, GBP, or EUR account in minutes.

Tips for building a sustainable freelancing career: Insights from Victor Fatanmi

2 min read

At Grey, we believe in empowering freelancers to shape their futures and thrive in the dynamic world of work. In a recent Twitter Chat session, we had the pleasure of hosting Victor Fatanmi, a purpose-driven business leader and co-founder of FourthCanvas and Fullgap.

In this post, we’ll delve into the insights Victor shared on freelancing sustainability, financial planning, work-life balance, and effective networking strategies.

A Little Background on Our Speaker

Victor Fatanmi’s entrepreneurial journey began in 2015 when he co-founded FourthCanvas, a renowned design agency that brings together Africa’s finest brand strategy and design minds.

Drawing inspiration from this experience, he co-founded Fullgap, a tech startup building an operating system for freelancers and individuals seeking to maximize productivity.

With a purpose-driven approach, Victor leads the teams at FourthCanvas and Fullgap to elevate experiences and revolutionize the future of work.

Why We’re Sure Freelancing is a Sustainable Career Path

During the Twitter chat, Victor shed light on the key advantages of freelancing that contribute to its sustainability.

As freelancers, they control their career trajectory, positioning themselves for opportunities and retaining clients. Embracing responsibility becomes a strength that can be applied in any context.

Moreover, freelancers enjoy absolute job security when they invest in their reputation and consistently deliver exceptional work, contrary to the notion of ‘job security’ in a 9-to-5 job.

Additionally, they can balance work and personal life, accommodating essential components such as family, faith, travel, and learning.

How to Maintain A Consistent Flow of Clients and Projects as a Freelancer

To ensure long-term sustainability, Victor shared practical tips for freelancers to maintain a consistent flow of clients and projects.

  1. Regardless of the pay, freelancers should always strive to produce high-quality work and communicate well with clients.
  2. Properly documenting agreements, invoices, and the scope of work enhances their reputation and professionalism.
  3. Leveraging social media platforms to showcase their work, share feedback, and demonstrate continuous improvement can significantly impact their freelance career.
  4. Building a solid portfolio accessible to potential clients, highlighting their expertise and versatility, is an effective way to attract new opportunities.
  5. Engaging in personal projects that excite and showcase their skills, providing value to others in their field, can set them apart.

Overall, proposing solutions and offering valuable insights and advice to potential clients demonstrate their expertise and willingness to contribute to their success.

Strategies For Staying Financially Stable as a Freelancer

While Victor humbly admitted not being a financial expert, he shared practical strategies to ensure financial stability and success as a freelancer.

Freelancers should allocate a portion of their income, around 25%, for savings or low-risk investments to secure their financial future.

Reinvesting in their freelancing career by upgrading their tools and workspace or investing in resources that enhance productivity is wise.

Flexibility is both a boon and a challenge for freelancers, and Victor emphasized the importance of managing it effectively. Embracing the positive impact of flexibility allows freelancers to prioritize personal commitments, be it family, health, or personal development.

At the same time, setting boundaries and practicing discipline are crucial to avoid overworking and maintaining a healthy work-life balance.

5 Tips for Building Strong a Strong Network and Professional Relationships

Victor provided five invaluable tips for freelancers to network effectively and forge strong professional relationships.

  1. Freelancers should support their peers, seniors, and others in their industry, and they will reciprocate in due time.
  2. Demonstrating genuine interest in others’ experiences and accomplishments builds deeper connections.
  3. Freelancers should share their experiences with authenticity and humility, fostering meaningful interactions.
  4. Initiating private conversations with those who respond to their public interactions opens new possibilities.
  5. Exuding confidence in their appearance and communication positively impacts others’ perception of their potential.

Wrapping Up

Our Twitter Chat gave aspiring freelancers valuable insights to navigate the challenges and seize opportunities in their freelance careers.

From embracing responsibility to leveraging social media and networking effectively, freelancers can take concrete steps towards building sustainable and fulfilling careers in the dynamic world of work.

Follow us on Twitter to be on top of all our upcoming Twitter Chat sessions.

Financial tips for freelancers and creators: How to manage Your finances effectively in 2023

2 min read

Being a freelancer or creator empowers you to have complete control over your career. This grants you the freedom to pursue your passions and creativity, set your work hours, and even work from anywhere in the world. However, with great power comes great responsibility, particularly when managing your finances. 

Freelancing can be a rewarding career path, but it can also be challenging. Unlike traditional jobs, you don’t have the luxury of a guaranteed paycheck and often juggle multiple clients or projects simultaneously. These circumstances make it difficult to stay on top of your finances or plan effectively, especially if you’re not used to managing your money.

Here are a few reasons why financial management is so essential for you as a freelancer or creator:

  • Income can be unpredictable and since you can’t rely on a regular cash flow, financial planning can be exhausting when you don’t know where your next pay check is coming from.
  • You’re responsible for paying your taxes, health insurance and other benefits. This can be a huge financial burden, so it’s important to plan ahead.
  • To succeed as a freelancer or creator, you need to invest in your business. This includes allocating funds for things like marketing, equipment, and software to enhance your business.

Now, let’s explore some important tips and strategies you need to know to track your finances and stay on top of your money.

Set Clear Financial Goals 

The first step towards financial stability as a freelancer or creator is setting clear, achievable financial goals. Whether you’re saving for a dream vacation, paying off debt, or investing in a new camera for your content creation, having defined objectives provides you with direction and motivation. Begin by asking yourself what you want to achieve in the short and long term. Your goals should be specific, measurable, and time-bound.

For instance, instead of saying, “I want to earn more money,” set a goal like, “I need to increase my monthly income by 20% within the next six months.”

653104e191b5764e9fac28ad Expense%20Insights%20by%20Grey

Track Your Expenses 

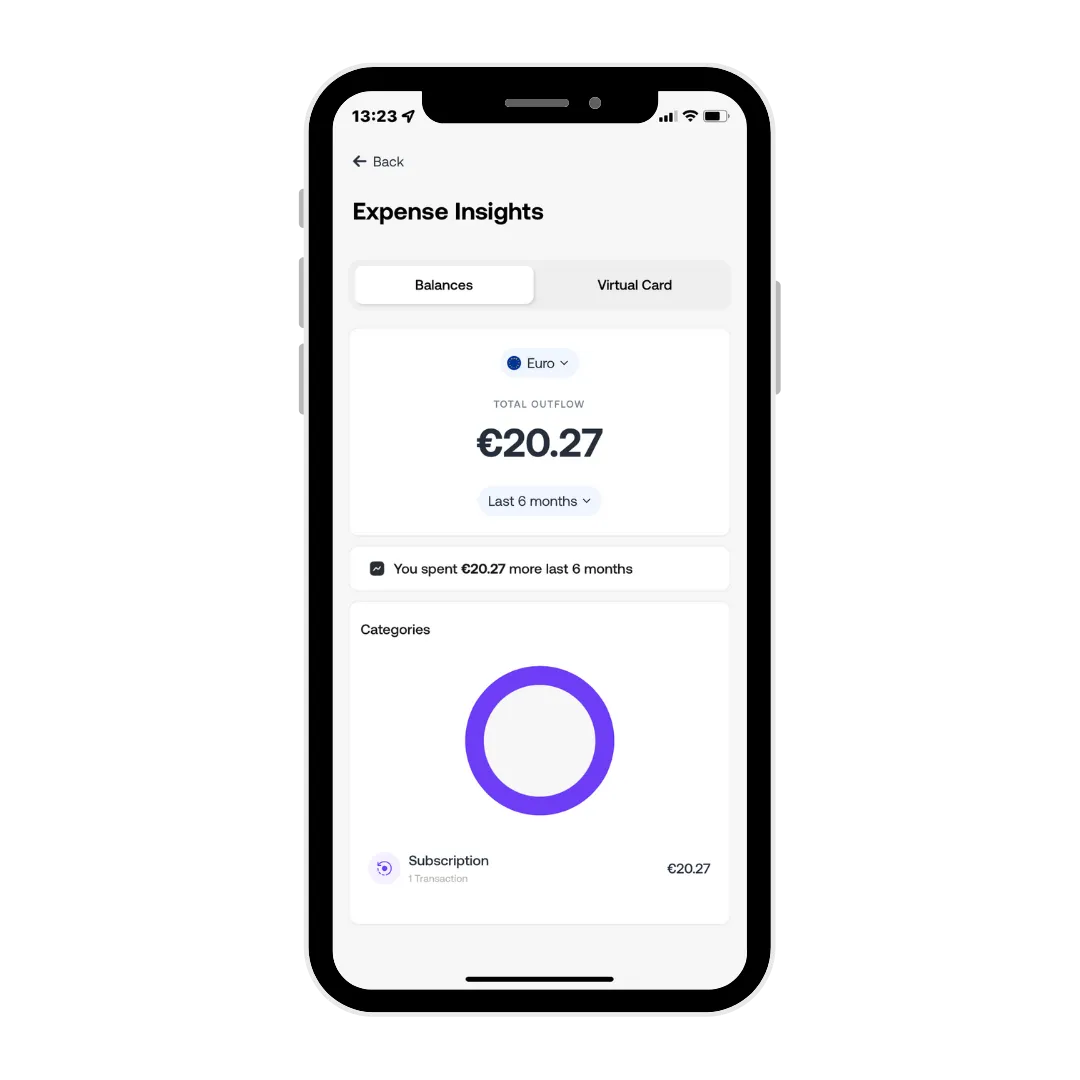
It’s easy to lose track of small expenses, as they add up really quickly if you don’t keep an eye on them. To avoid falling into the trap of overspending, track your expenses diligently. Our ‘Expense insights’ feature on the Grey app can provide a detailed breakdown of your spending habits. Make it a habit to record every cost incurred, no matter how minor it may seem. By doing this, you’ll better understand where your money is going and can make informed decisions.

Invest in Professional Development 

Investing in your skills and knowledge is a wise move for freelancers and content creators. By enhancing your abilities, you not only become competitive in your field, you attract more clients and secure higher-paying gigs. Allocate a portion of your income for education and training in your field or to acquire a new skill. You can enrol in online courses on Udemy or Udacity, attend workshops, or purchase industry-related books; these investments will pay dividends in the long run. 

Diversify Your Income Streams 

Relying solely on one source of income in this current cost-of-living crisis can be a risky proposition. Consider exploring various income avenues, such as affiliate marketing, sponsored content, online courses, digital content or even part-time consulting work. Diversification provides stability during slow periods and ensures you’re not entirely dependent on a single client or revenue source. It also increases your overall income potential.

Logging your finances as a freelancer or content creator can be a headache, but it doesn’t have to be. Simplify your financial operations by using a single platform, like Grey. With Grey, you can seamlessly send invoices to clients, receive payments on time, and pay for online courses—all while conveniently tracking your expenses in one place and focusing on what you do best. Create an account on Grey to stay on top of your money and smash your financial goals!

Arrow (up)

Back to top