The easiest way for Nigerians abroad to send US dollars home

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

Nigerians abroad often need to send money to their loved ones, including ageing parents or younger siblings. Unfortunately, many still struggle with transferring money back home or making payments in Nigeria. This is partly because conventional banks charge exorbitant fees on international transactions and offer unfavourable exchange rates. There could also be delays in completing international transactions during emergencies.

In this article, we will explore how digital payment solutions like Grey help to simplify international transactions for Nigerians abroad who are sending US dollars home.

Also read: Monieworld vs Juicyway vs Cleva vs Grey – which is better?

What to consider before choosing a USD transfer method

Before settling on a platform, here are some factors to keep in the back of your mind.

  • Location

Some international payment platforms are restricted in some countries. You should ensure your choice works smoothly in your country. Also, if you are a frequent traveller, using a widely available cross-border payment option like Grey might be better.

  • Exchange rate transparency

Some platforms offer poor rates or increase exchange rates to make extra profit. Always compare with the mid-market rate using tools like Grey, XE, or Google.

  • Total transfer fees

Look out for both fixed and hidden fees. A provider may offer “no-fee” transfers but disguise charges in poor exchange rates. Always calculate the real total cost.

  • Payout flexibility

Will the recipient get the money in USD or naira? Is it a bank deposit, cash pickup, or a mobile wallet? Choose a platform that offers multiple payout options that suit your recipient.

  • Speed of delivery

Depending on the urgency, opt for platforms that can process transfers within minutes or a few hours. Standard bank transfers can take 1–5 days.

  • Ease of use

A good platform should be easy to sign up for, with a user-friendly interface, clear instructions, and mobile access.

  • Security

Only use regulated platforms that comply with financial laws in your country and Nigeria. This ensures the safety of your funds and personal data.

Best ways to send USD to Nigeria from abroad

Here are some of the most effective options available for Nigerians abroad.

1. Grey

Grey is a reliable cross-border payment platform tailored for Nigerians and other Africans who need to send, receive, and manage multiple currencies. You can send USD directly if the recipient has a USD or Grey account. Grey also supports naira so that you can send directly to a Nigerian bank account at favourable conversion rates.

Why use Grey to send USD home?

  • Instant USD accounts: Sign up, verify your account, and create a virtual USD account in minutes.
  • Favourable exchange rates: Convert between USD and NGN at competitive rates.
  • Send directly to Nigerian accounts: You can fund your USD balance and send it directly to your recipient's Nigerian bank.
  • Fast processing: Transfers are usually completed within minutes.
  • Fully secure: Grey offers robust security features to protect your funds and data
  • Versatile USD card: Grey also offers a virtual USD card to further simplify your online payment experience.

2. Wise

Wise is a financial technology company that provides international money transfers and a multi-currency account. It offers various ways to send money to Nigeria, including direct bank transfers, and allows users to receive payments in Nigerian naira via a Wise account. It offers transparent fees and exchange rates. However, it is not suitable if you need recipients to receive or hold USD as funds arrive in naira.

3. Sendwave

Sendwave supports USD and NGN transfers to Nigeria at low transfer fees and transparent rates. However, Sendwave has limited availability. It can only be used in the USA, UK, Canada, France, Italy, Spain, and Ireland. So, if you live outside these countries, it might not be a great option.

4. Western Union / MoneyGram

Traditional remittance services like Western Union or MoneyGram are helpful for cash pickups in Nigeria. They offer USD cash payouts at over 4,500 designated agent locations nationwide. This option is reliable for unbanked recipients. However, it is usually more expensive and slower than fintech platforms.

Also read: The best international bank accounts for freelancers and remote workers

How to send US dollars home using Grey

You can create an account on Grey and get your US bank details within minutes. Here’s a simple guide to sending US dollars from abroad to Nigeria with Grey:

  1. Create an account: Sign up for free on the Grey website or download the app.
  2. Verify your identity: Submit your KYC documents to activate your USD account.
  3. Receive USD funds: Fund your Grey USD account via wire transfer or other international methods.
  4. Convert to NGN (optional): Use the currency exchange feature to get the best rates. You can convert to naira or send directly in US dollars.
  5. Send to Nigeria: Choose a recipient bank account and complete the transfer in a few clicks.

If the recipient has a Grey account, it even gets easier. You can send money using their Greytag.

Sending money home the easy way

Whether you’re working abroad, studying overseas, or freelancing for global clients, sending money back home should be secure, fast, and stress-free. Platforms like Grey offer an affordable and seamless way for Nigerians abroad to manage USD transactions without high fees or hidden markups.

Get started with Grey today to enjoy easy global money transfers built for Africans abroad.

‍

Last updated:

June 15, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to open a Wells Fargo account from outside the US

•

•

2 min read

If you are a freelancer working with US-based clients, a business owner, or a frequent traveller living outside the US, you might soon discover that a US bank account makes managing your finances much better. It makes it easier to receive USD payments from US clients and make international payments without worrying about conversion and international wire transfer fees.

On one hand, Wells Fargo remains one of the most popular US banks. On the other hand, opening an account outside the US might not be so easy. Non-residents can open a Wells Fargo account, but only in person at a US branch, with a US address, two forms of ID, and an opening deposit. Non-residents can't open an account online. If you cannot travel to the US or do not have a US address, a virtual USD account like Grey is a practical alternative.

In this guide, we’ll walk through the exact requirements for opening a Wells Fargo bank account, the documents you’ll need, and what your alternatives are if you can’t fly to the United States or don’t have a U.S. address.

Can a non-resident open a Wells Fargo account?

Yes, a non-US resident can open a Wells Fargo account, but it is not that straightforward. Wells Fargo requires non-US residents to open an account in person at a US branch. You cannot currently complete the process entirely online from outside the US.

This means you need to travel to the US and bring the required documents. You may also need a US address, depending on the account and branch requirements.

If you cannot travel to the US or do not have a suitable US address, you might not be able to open a  Wells Fargo account. In that case, you can consider a virtual USD account from a fintech provider instead.

What you need to open a Wells Fargo account

The requirements for opening a Wells Fargo account depend on your circumstances, the branch, and the type of account you want to open. Confirm current requirements directly with your chosen branch before travelling. Here is a list of Wells Fargo non-resident account requirements:

  • US address: A physical US address is generally required.
  • Means of identification: A valid passport and possibly a second government-issued ID like a foreign national ID, a visa, or another government-issued document.
  • SSN or ITIN: A Social Security Number is generally requested; if you do not have one, an Individual Taxpayer Identification Number (ITIN) may be accepted, though this varies by branch and account type.
  • Opening deposit: You must make a minimum initial deposit. The specific amount depends on the account type.
  • Physical presence: You have to visit the branch in person. You cannot open the account remotely.

Even if you can travel to the US to open an account, you are unlikely to succeed without a US address. Hotel, short-term rentals, or Airbnb addresses are not allowed. That is why a US address is one of the biggest barriers for non-residents.

See our guide on opening a US account without an SSN.

Step by step: opening the account in a branch

The process for opening a Wells Fargo account may vary slightly from one branch to another. But the process is usually similar.

Step 1: Check the requirements

Contact the Wells Fargo branch you plan to visit and confirm what documents you need. Ensure you have an acceptable US address you can provide. You can consider using a relative’s address, a temporary accommodation with a formal address, or any other option that the specific branch can accept.

Step 2: Gather the required documents

Bring your passport, secondary ID, proof of your US address, and your SSN or ITIN if you have one. Bring more documentation than you think you might need, since requirements can vary by branch and situation.

Step 3: Book an appointment

Many branches might allow you to open an account without booking an appointment. But an appointment can help you avoid unnecessary waiting and confirm that the branch can handle your application.

Step 4: Visit the branch to complete the application

A banker will guide you through the application process, verify your documents, and open the account. This typically takes 30 minutes to an hour. However, it can take longer if they require additional verification.

Step 5: Make your opening deposit

Once your account is open, deposit the required minimum amount to activate it. You can deposit cash or transfer funds from another account.

Step 6: Receive your account details and card

Wells Fargo will provide your account and routing details once the account is opened. They may issue or mail your debit card separately.

If you are visiting the US specifically on a temporary visa, see our related guide on opening a US account as a temporary visitor or on a visit visa.

Where Wells Fargo falls short for non-residents

Wells Fargo can work for some non-residents, but a few limitations are worth considering before you make the trip.

  1. You need to apply in person: Non-residents cannot currently open a Wells Fargo account entirely online. You need to visit a US branch to complete the application.
  2. You may need a US address: A suitable US address can be a major hurdle if you don't have family, friends, or another connection in the country. A hotel or temporary accommodation may not meet the bank's requirements.
  3. The cost involved might be too high: You have to travel to the US. If you are travelling specifically to open a bank account, the cost of flights, accommodation and other expenses might not make it worth the effort, especially if there are easier alternatives.
  4. There is no remote Wells Fargo option: Unlike fintechs and some other traditional banks, Wells Fargo doesn’t offer an online account opening process for non-residents. If your main goal is simply to get US banking details for receiving payments, you should look into fintech platforms that offer USD accounts that can be opened remotely

If you're comparing Wells Fargo with another US bank, our guide to opening a Chase account as a non-US resident can help you understand how the requirements differ.

A no-US-address alternative with Grey

Even if you could afford to travel to the US just to open an account, it still won't be enough without a US address. Consider fintech alternatives like Grey that offer USD accounts without requiring you to set foot in the US or have a US address.

Grey gives you a USD account with an ABA routing number and account number through their banking partner. It works like a traditional bank USD account and lets you receive USD payments and send money via ACH. This means US clients, employers, or platforms can pay you like any US-based recipient.

Opening a USD account with Grey is entirely online and requires identity verification with a valid ID, proof of address, and a photo of you. Once your account is verified, you receive your details, and it's up and running within minutes. You can also open EUR and GBP accounts within the same account, so you can manage these currencies on the same platform.

Read more about opening a USD account remotely without US citizenship.

Grey’s virtual card connects to your multicurrency account without requiring manual top-ups. Essentially, you can spend directly from your USD, EUR, and GBP balances without converting currencies. So, whether you are paying for online subscriptions in USD, shopping on Amazon UK, or visiting the Eurozone, you can spend internationally with a Grey card.

Ready to open a USD account as a non-resident? Open a USD account with Grey, no US trip required.

Frequently asked questions about Wells Fargo accounts for non-residents

Can I open a Wells Fargo account online from abroad?

No. Non-residents generally need to visit a Wells Fargo branch in the US to open an account. If you need an account you can open remotely, a USD account from a fintech provider may be a more practical option.

Do I need an SSN?

Wells Fargo may request an SSN when you open an account. If you don't have one, some branches may accept an Individual Taxpayer Identification Number (ITIN), though this varies. Check with the branch before applying.

Can I open one on a visit visa?

It may be possible, but having a valid visa does not automatically guarantee that you can open an account. You still need to meet the bank's identification, address and other requirements. Contact the branch before travelling.

What is the minimum deposit?

The minimum opening deposit depends on the type of Wells Fargo account you choose. Everyday Checking and Student and Teen Checking require a minimum deposit of $25. Confirm the current minimum deposit requirement for your intended account type at wellsfargo.com or with your chosen branch before your appointment, as these figures may change.

How to avoid scams when sending money to Brazil

•

•

2 min read

Scams targeting international money transfers are a problem worldwide. Fraudsters constantly devise sophisticated tactics to steal funds, and falling victim to these schemes can result in huge financial loss and emotional distress.

Fortunately, secure platforms like Grey offer a safer way to send money internationally, ensuring transparency and protection. This guide will highlight common scams, warning signs, and practical tips to keep your transfers safe.

Common scams targeting money transfers to Brazil

Here are some of the most common scams affecting international money transfers:

1. Romance scams

Fraudsters create fake online profiles and build emotional connections, eventually requesting financial help for fabricated emergencies, travel expenses, or investment opportunities.

2. Investment scams

Scammers pose as brokers or investment managers, promising high returns on real estate, cryptocurrency, or stock market investments in Brazil. Victims then send money only to realise the investment was fake.

3. Business opportunity scams

Victims receive unsolicited offers to participate in lucrative business deals or franchises in Brazil. Scammers often ask for an upfront payment to cover "processing fees" or "government permits."

4. Family emergency scams

Fraudsters impersonate relatives or friends, claiming to be in distress and urgently needing money for medical bills, legal fees, or unexpected expenses.

5. Online shopping scams

Scammers set up fake e-commerce sites or social media storefronts, offering discounted goods. Once payment is made, the items never arrive, and the seller disappears.

Also read: Top tools and resources for digital nomads in Brazil

Red flags to watch out for when sending money to Brazil

Recognising these warning signs can help prevent fraud:

  • Urgency: Scammers pressure you to act quickly, claiming dire consequences if you delay.
  • Unusual payment methods: Requests for payments via unconventional methods should raise suspicion.
  • Poor grammar and communication: Many scam messages have spelling errors and inconsistencies.
  • Refusal to meet or provide identification: Fraudsters avoid video calls, in-person meetings, or fail to provide verifiable documents.
  • Too good to be true promises: Unrealistic investment returns or deeply discounted items are likely scams.
  • Lack of a verifiable online presence: Legitimate businesses and individuals usually have traceable records.

Also read: How to avoid scams when sending money to Algeria

Practical tips for sending money safely to Brazil

1. Verify recipient identity

Always confirm the recipient’s details through a trusted source before making any transfers.

2. Choose secure platforms like Grey

Grey provides secure transactions, ensuring your money reaches the right hands without unnecessary risks.

3. Research investments

Before investing in Brazil, conduct thorough research, verify licenses, and seek professional financial advice.

4. Verify business transactions

Use escrow services or platforms like Grey for added security when dealing with businesses.

5. Confirm emergencies independently

If someone claims to be in trouble, contact them directly through official channels before sending money.

6. Ignore unsolicited requests

Be sceptical of unexpected messages asking for financial assistance or investment opportunities.

7. Understand payment method risks

Avoid payment methods that lack security and traceability. Grey ensures safe, trackable transactions.

8. Keep personal information secure

Never share sensitive banking details or passwords with unknown individuals.

9. Report suspicious activity

If you suspect a scam, report it immediately to local authorities, your bank, or the transfer service you used.

Also read: How freelancers in Brazil can receive payments from the US, UK & EU clients

Choose Grey for your transfers to Brazil

Scammers are always evolving their tactics, but using a trusted platform like Grey significantly reduces the risk. With multi-currency support, secure transactions, and competitive exchange rates, Grey ensures that your money reaches its intended destination safely.

Create your Grey account today or download the app to enjoy inclusive global banking, designed to carry your dreams across borders.

‍

USDC vs. other stablecoins: what's best for global transactions?

•

•

2 min read

Stablecoins are becoming a popular means of international transactions. They offer the benefits of blockchain technology while maintaining price stability. Among them, USD Coin (USDC) has gained significant traction. However, how does it compare to other stablecoins?

This article explores the differences between USDC and other stablecoins to determine what’s best for global transactions.

We will examine USDC’s strengths and weaknesses relative to other major stablecoins such as Tether (USDT), Binance USD (BUSD), and Dai (DAI) to determine the best choice for global transactions. First, let’s understand what stablecoins are.

Understanding stablecoins

A stablecoin is a cryptocurrency with a value pegged to a reference asset. The value of a stablecoin is usually pegged to traditional assets like a commodity (e.g. gold), fiat money (e.g. US dollars, Euro) or another cryptocurrency (e.g. ETH). Backing a stablecoin with a stable asset means the value of the stablecoin is not volatile like other cryptocurrencies.

Using USDC for global transactions

USD Coin (USDC) is a fully backed stablecoin issued by Circle and Coinbase under the Centre Consortium. It is pegged 1:1 to the US dollar (USD) and undergoes regular audits.

USDC is backed by cash and short-term US Treasury bonds. This makes it one of the most transparent stablecoins. It operates on multiple blockchains, including Ethereum, Solana, and Algorand, ensuring fast and flexible transactions.

Pros of USDC for global transactions

Here are the benefits of using USDC for international transactions.

  • Regulatory compliance: USDC adheres to strict financial regulations, making it a trusted option for businesses and institutions.
  • Transparency: Regular third-party audits confirm its full backing, reducing risks of depegging.
  • Fast and efficient: With multi-chain support, USDC enables low-cost, high-speed transfers across borders.
  • Integration with financial institutions: Major banks and fintech companies are adopting USDC, increasing its accessibility for mainstream transactions.

Comparing USDC with other stablecoins

Let’s compare USDC with other popular stablecoins like USDT, DAI and BUSD.

USDT (Tether)

USDT is the most widely used stablecoin. It has higher trading volumes than USDC. It is commonly used for crypto trading and liquidity pools.

Pros:

  • Its higher liquidity makes it preferable for traders and exchanges.
  • It is available on numerous blockchains, ensuring wide usability.

Cons:

  • There are controversies surrounding its reserves and a lack of transparent audits.
  • Regulatory scrutiny raises concerns over its long-term stability.

BUSD (Binance USD)

Paxos and Binance issue BUSD. It is another regulated stablecoin backed 1:1 by US dollars.

Pros:

  • Highly regulated and approved by the New York State Department of Financial Services (NYDFS).
  • Strong integration with Binance’s ecosystem, making it ideal for trading and DeFi applications.

Cons:

DAI

DAI is a decentralised stablecoin issued by MakerDAO. The stablecoin is backed by a mix of cryptocurrencies rather than fiat reserves.

Pros:

  • It is decentralised and resistant to censorship.
  • Users can generate DAI by collateralising crypto assets.

Cons:

  • Collateralisation can make DAI more volatile than fully fiat-backed stablecoins.
  • Less liquidity compared to USDT and USDC.

What’s the best stablecoin for global transactions?

Your choice of stablecoin should depend on your priorities and planned usage. For global transactions, the ideal stablecoin must offer reliability, liquidity, regulatory compliance, and cost efficiency.

USDC is popular for transparency and regulatory compliance. However, USDT has a larger trading volume and liquidity.  DAI, on the other end, edges other stablecoins in decentralisation.

USDC is the best option for businesses and individuals seeking a stable, regulated, and widely accepted stablecoin for global transactions. USDC’s transparency and institutional support make it a more secure choice for large-scale and cross-border payments.

How to send USDC payments using Grey

Transacting with USDC is much easier with reliable global payment platforms like Grey. In case you missed the announcement, Grey now allows users to receive USDC payments and convert to USD.

Here is how to get started.

First, create a Grey account

sign up on Grey to send USDC for global transactions.

Go to the Grey website or download the mobile app. Register for an account and complete the required identity verification process.

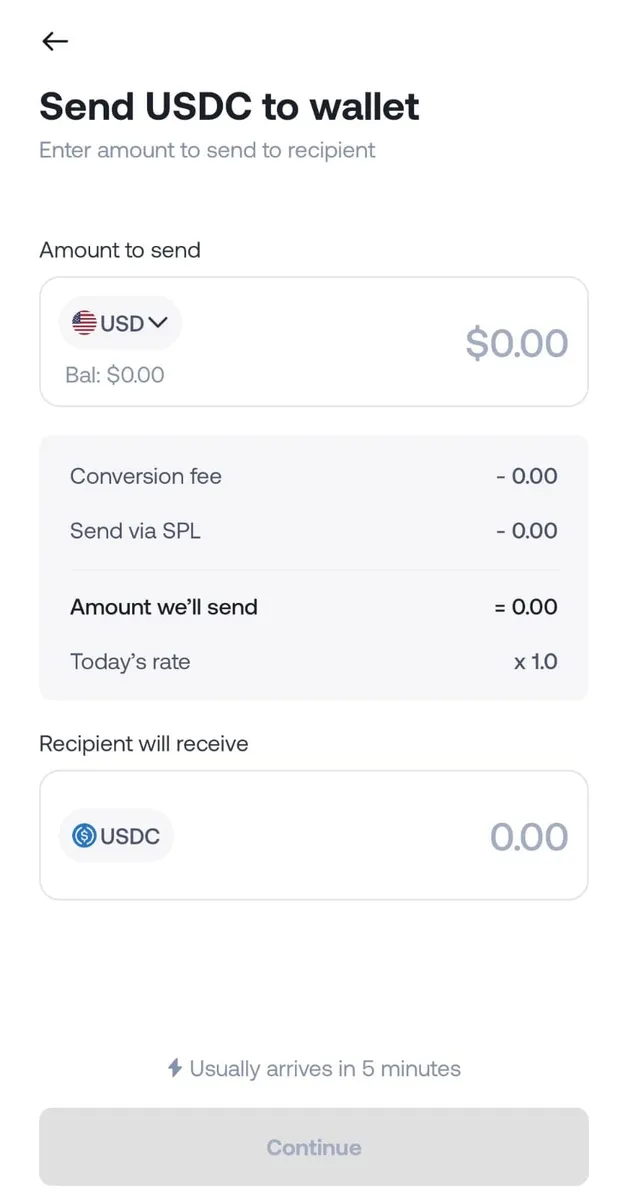
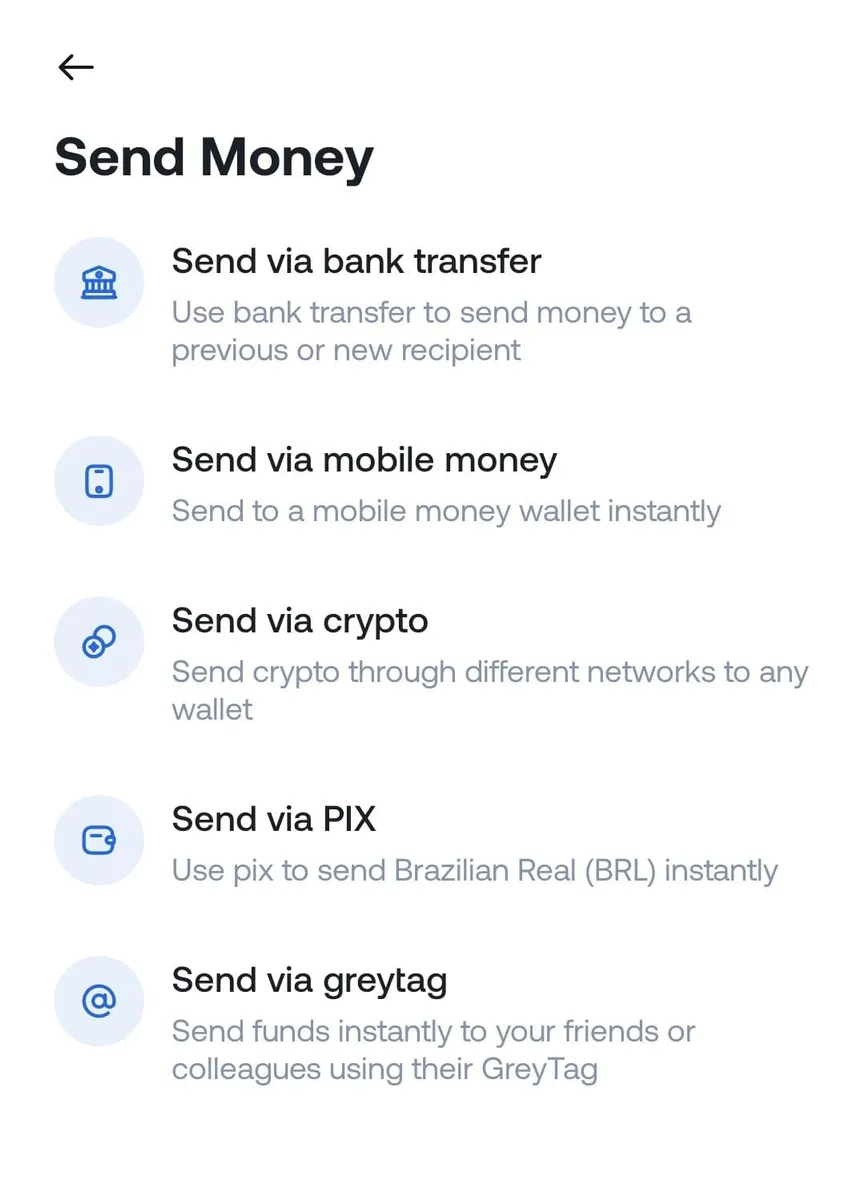
Next, choose “Send via crypto”

Send USDC seamlessly with Grey

Access the “Send money” section and select “Send via crypto” to start your USDC transaction.

Then, complete your USDC transfer

USDC vs. other stablecoins: what's best for global transactions?

‍

Ensure you have USDC in your wallet, input the amount you wish to send, and proceed with the transfer.

Grey will request a two-factor authentication (2FA) code for security purposes before finalising your transaction.

Read also: How to receive and convert foreign currencies to USDC

Fast and secure USDC payments with Grey

Selecting the best stablecoin for global transactions depends on the user’s needs. However, USDC remains one of the most reliable, swift and secure means for global transactions.

Grey simplifies sending and receiving USDC payments, making cross-border transactions quick and secure. Whether you need to pay vendors, accept client payments, or send money internationally, Grey offers a low-cost and efficient solution.

Sign up now and enjoy hassle-free USDC transfers with Grey.

How to save for multiple goals without losing track of your money

•

•

2 min read

Discipline, or in this case, the lack of it, is perhaps the biggest culprit when the topic of saving’s difficulties comes up. Everyone points to it. “If you were more disciplined, you’d have more savings.

Discipline is hard, which is why I usually suggest creating systems to assist you.

For example, when your emergency fund, holiday savings, laptop replacement fund, and next rent payment are all in the same account, every spending decision becomes guesswork. After you check your balance and it looks fine, you just spend. Two months later, you realise the holiday fund has been funding groceries and you’re nowhere near where you need to be.

The problem is the system. Specifically, the absence of one. This article covers how to set financial goals that are specific enough to actually work, how to prioritise when you have several competing at once, and how to structure your savings so every goal has its own lane and its own visible progress.

What are financial goals?

A financial goal is a specific outcome you’re saving toward, with a target amount and a timeline. It is not a vague intention like “save more” or “spend less.” Those are closer to wishes than actual goals. A financial goal sounds like: “Save £1,500 for a trip to Morocco by March,” or “Build a three-month emergency fund of $6,000 by December.”

Being specific is what makes it work. A vague intention gives you nothing to measure and no way to know if you’re behind. A specific goal tells you exactly what to save per month to hit the target, and makes it immediately obvious when you’ve drifted off course.

Financial goals are usually grouped by time horizon.

Short-term goals
These are goals with timelines of up to one year. Perfect examples are a holiday fund, a new laptop, covering an upcoming car service, and building a starter emergency fund. They usually require the most active saving because the deadline is relatively close.

Medium-term goals
These are usually in the one-to-five-year range, for example, a deposit for a flat, a car purchase, a wedding, or a career break fund. These have more time to build but need consistent contributions to stay on track.

Long-term goals
These generally extend beyond five years. Retirement savings, building a property deposit for a major purchase, and funding a child’s education. These are the goals most easily deprioritised because the deadline feels distant, but they’re often the ones that matter most.

Most people are working toward two or three goals from each category simultaneously. That’s not a problem. The problem is trying to manage all of them from the same unmarked pot.

Why does one balance fail when you have several goals?

When all your savings are in a single account, a few predictable things happen.

You lose track of what each pound or dollar is for. The balance looks healthy in aggregate, but you have no idea how much of it belongs to the holiday fund, how much is the emergency fund, and how much is genuinely spare. So you make spending decisions based on the total, which is almost always misleading.

Progress becomes invisible. If you’re trying to save £1,500 for a trip and the money is mixed in with everything else, you can’t see how far you’ve come. The psychological pull of visible progress, watching a number move toward a target, is a real factor in whether people stay consistent.

Goals cannibalise each other. When a short-term need comes up, and the money is all in one place, the easiest thing to do is spend from the pool without realising you’ve just set the holiday back by two months.

This is why separating your money by purpose works. It’s about giving every goal its own space so you can see each one clearly. For more on this, see our piece on why separating your money helps.

How to set and prioritise your savings goals

Start by listing everything you’re saving for, or know you should be saving for, without filtering. Write down every goal, big and small, near and distant.

Once you have the list, add two things to each goal: a target amount and a date.

If the target or the date seems uncertain, make your best estimate and treat it as a working figure. A goal with a rough timeline is more actionable than a goal with no timeline at all. You can revise it later.

Now rank them. There are two useful criteria for prioritisation.

Urgency: How close is the deadline? A goal with a six-month deadline outranks one with a three-year deadline, even if the three-year goal feels more important in the abstract. Near-term goals need more active attention because there’s less time to recover from slow months.

Consequence of missing it: What happens if you underfund this goal? Missing a holiday fund target is recoverable. Missing an emergency fund means you go into debt when something unexpected happens. Missing a rent deposit deadline means you lose the apartment. Try to rank goals with high-consequence outcomes higher, regardless of how appealing they are compared to other goals.

After ranking, you have a practical order of priority. The top two or three goals get the most attention in your monthly allocation. The rest get smaller but consistent contributions, so they’re moving forward rather than stalled.

Review the list and rankings every three to four months because goals change, deadlines shift, and priorities evolve. A quarterly check keeps the system accurate without making it a constant source of admin.

How much to put towards each goal

Once you know your goals and their order of priority, the allocation question is mechanical.

Start with your monthly saving capacity: the amount left after essential expenses that you’re willing to direct toward goals. If this number seems uncertain, work backwards from your income and fixed costs to get a realistic figure rather than an optimistic one.

Then allocate across goals by priority. A simple approach is to give the highest-priority goal the largest share, and work down from there. A useful starting split for someone with three active goals:

  • Goal one (highest priority): 50% of monthly savings
  • Goal two: 30%
  • Goal three: 20%

Adjust the percentages to reflect your specific timeline maths. If goal two has a close deadline and goal one is longer-term, you might temporarily flip the allocation until goal two is funded.

For each goal, run the basic savings goal calculator check: target amount minus what you’ve already saved, divided by the number of months remaining. This gives your required monthly contribution. If your current allocation to that goal doesn’t meet the required contribution, something has to give. Either the timeline extends, the target reduces, or the allocation increases at the expense of another goal.

How to track multiple goals with a Pouch for each

Once you have a priority order and an allocation, the practical question is how to keep everything visible and separated without managing multiple bank accounts or a complex spreadsheet.

You can set aside money for each goal in your Grey account. Each Pouch has a name and a running balance, so you can contribute to each one individually, without the amounts bleeding into one another or your spending balance.

Here’s how that looks for a real example.

Sade is saving for three goals simultaneously: a six-month emergency fund, a trip to Japan, and a new laptop.

Goal Target Monthly contribution Pouch name Months to target
Emergency fund £4,800 £200 Emergency fund 24 months
Japan trip £2,400 £300 Japan 2027 8 months
New laptop £900 £150 Laptop fund 6 months
Total £8,100 £650

Sade has £650 per month set aside. She has three Pouches in her Grey account, each named, each with a target set. On payday each month, she transfers £300 to Japan 2027, £200 to the Emergency fund, and £150 to the Laptop fund. Each balance moves toward its target independently.

The laptop fund hits its target in six months. Amara closes that Pouch and redirects the £150 per month to her emergency fund, accelerating it.

The practical value is clarity. If one is falling behind, it’s immediately obvious. If a goal is reached, the allocation redistributes. Nothing gets lost in a single undifferentiated balance.

To compare savings-goal apps and see how different tools handle multiple goals, this guide covers the main options side by side.

Remember to create a Pouch for each goal and fund it when due.

Frequently asked questions

How do I save for more than one goal at once?

List every goal you’re working toward, assign each one a target amount and a timeline, then rank them by urgency and consequence. Allocate your monthly savings across them in order of priority, with the most urgent goals receiving the largest share. Keep each goal in its own named savings space so you can see progress on each one individually. Review the allocation every three to four months and adjust if any goal is falling behind or has been completed.

How do I decide which goal to prioritise?

Two criteria are most useful: how close the deadline is, and what happens if you miss it. A goal with a deadline in six months and a high consequence if unfunded (an emergency fund, a rental deposit, a time-sensitive purchase) ranks above a goal with a three-year timeline and a recoverable consequence. Once you’ve ranked by urgency and consequence, give the highest-ranked goals the largest share of your monthly saving capacity and work down from there.

How much should I put towards each goal?

For each goal, calculate your required monthly contribution: target amount minus what you’ve already saved, divided by months remaining. Compare that figure to your current allocation for that goal. If your allocation doesn’t meet the required contribution, you have three options: extend the timeline, reduce the target, or increase the allocation by reducing another goal’s share. A simple starting split for three concurrent goals is 50%, 30%, and 20% of total monthly savings, adjusted to reflect which goals have the tightest deadlines.

How many savings goals is too many?

There’s no fixed limit, but more than five or six active goals typically means contributions are spread too thin to make meaningful progress on any of them. If your monthly saving capacity is £400 and you have ten goals, the average contribution per goal is £40, which may not be enough to reach most targets in any reasonable timeframe. A more practical approach is to focus on the top three to four goals actively, with smaller holding contributions to longer-term goals, and add new goals to the active list when existing ones are funded.

How do I track multiple goals without a spreadsheet?

Named savings balances, one per goal, each with a target amount set, handle the tracking automatically. Grey’s Pouches give each goal its own named space within your account with a visible balance. When a contribution is made to a specific Pouch, the balance updates immediately.

How to open a Bank of America account as a non-resident

•

•

2 min read

Opening a US bank account from outside the US can be difficult, especially when the usual requirements are difficult to meet. A non-resident may not have a Social Security number, a US credit history or an established relationship with an American bank, yet still need a US account for work, travel, business or managing money in dollars.

Bank of America is one of the US banks that offers a potential route for non-residents through its Advantage Banking accounts. Unlike some banks that make an SSN or ITIN central to the application, Bank of America may accept other forms of identification from eligible applicants. However, that does not mean the process can be completed entirely from overseas.

A US address and an in-person branch visit can still be part of the process, making the practical requirements just as important as the documents themselves. This guide explains what non-residents should know before applying, including eligibility, identification, address requirements and what to expect at the branch.

Also read: Open a US bank account without an SSN

Can a non-resident open a Bank of America account?

A non-resident may be able to open a Bank of America account, making it one of the more structured options among major US banks for people who live outside the country. However, “possible” does not mean completely remote or guaranteed. Eligibility depends on the applicant’s circumstances and the bank’s requirements.

For non-residents, the process can involve:

  • Visiting a Bank of America branch in person.
  • Providing a US residential address.
  • Presenting acceptable identification, which may include a passport and another form of ID.
  • Meeting the bank’s account-opening requirements for the specific account.

One useful distinction is that an SSN or ITIN may not always be required for eligible non-resident applicants, depending on the circumstances. That can make Bank of America more accessible than banks where a US tax identification number is a central requirement.

The Bank of America offers a more clearly defined path for some non-residents, but it still involves practical hurdles, particularly the US address and potential branch visit. Anyone applying should confirm the current requirements with the branch before travelling.

Also read: How non-US citizens can open a US bank account online

What you need to open a Bank of America account as a non-resident

Bank of America’s Advantage Banking range provides a possible route for eligible non-residents, including some applicants who do not have a US Social Security number. The exact requirements can depend on your circumstances and the account you are applying for, so checking with the branch before travelling is important.

An advantage banking account

The process centres on eligible Advantage Banking accounts rather than a special non-resident account. The bank can assess your application based on your individual circumstances and the documents you provide.

Two forms of identification

Applicants should generally be prepared to provide two forms of ID. A valid passport can serve as primary identification, while the second document depends on what the bank accepts.

A US address

A US residential address is generally part of the application. This can be one of the biggest practical hurdles for someone who lives permanently outside the country.

What about an SSN or ITIN?

An SSN or ITIN may not always be required for eligible non-resident applicants. However, not needing one does not remove the other account-opening requirements. The bank may request additional information depending on your circumstances.

You may also like: How to open virtual bank accounts for freelancers outside the USA

How to apply for a Bank of America account as a non-resident

The process is fairly straightforward on paper, but the branch visit is the part international applicants need to plan around. These four steps give you a clearer idea of what happens from application to approval.

1. Check your eligibility

Before making travel plans, confirm that your circumstances and chosen Advantage Banking account meet Bank of America’s requirements. This can help avoid arriving at a branch only to discover that your application cannot be processed.

2. Prepare your documents

Have the identification, US address information and any other details the bank requests ready. If you are applying without an SSN or ITIN, confirm what the branch will accept before your visit.

3. Visit a branch

Non-residents will generally need to complete the account-opening process at a Bank of America branch in the US. A banker can review your information, verify your identity and process the application.

4. Wait for the account to be opened

If everything is in order, the account may be opened during or shortly after the appointment. Timelines can vary depending on verification and the circumstances of the application, so do not assume approval is guaranteed on the day.

Also read: How to open a USD bank account remotely without US citizenship

Where Bank of America can still be difficult for non-residents

Bank of America may offer a clearer route for some non-residents, but that does not make opening an account from abroad completely straightforward. The biggest issue is still the US address requirement. Someone who lives permanently outside the country may find it difficult to provide the type of residential address the bank expects.

The in-branch requirement can be another hurdle. Instead of completing everything from home, applicants may need to visit a physical Bank of America branch in the United States. For someone based in Africa, Europe or Asia, that can turn what looks like a simple banking application into a trip that requires time, planning and additional expense.

There is also no guarantee that meeting the basic requirements will result in approval. Individual applications can be assessed differently, and a branch may request additional information before opening the account. So while Bank of America can be a more structured option for non-residents, it may not suit someone who needs US banking access entirely online and without a US address.

A US banking option without a US address

A US address can be one of the biggest barriers when trying to access US banking from abroad. For businesses and individuals who mainly need to receive USD payments, opening a traditional US bank account may feel like more work than necessary. An online account with US payment details can offer a simpler alternative.

Grey provides users with a USD account through its partner bank, Lead Bank, including US ACH routing and account details. The account can be opened online, so there is no need to travel to a US branch or provide a US residential address simply to access these USD payment details. This can make receiving eligible payments from US clients or businesses more straightforward.

The account also supports multiple currencies, allowing users to manage funds beyond USD. For everyday spending, Grey’s virtual card provides another layer of flexibility, allowing users to shop online and wherever Visa is accepted. Together, the account and card provide a practical way to receive, hold and spend internationally without setting up a traditional US bank account.

Frequently asked questions

Can a non-resident open a Bank of America account?

Yes, eligible non-residents may be able to open a Bank of America account. The bank provides a more structured route through its Advantage Banking accounts, although requirements still apply. Applicants should expect that an in-person branch visit may be necessary, and approval is not automatic.

Can I open one without an SSN?

In some cases, yes. An SSN or ITIN may not always be required for eligible non-resident applicants, depending on their circumstances and the account involved. However, avoiding the SSN requirement does not remove other requirements, such as acceptable identification and a US residential address.

Do I need a US address?

Generally, yes. A US residential address remains an important part of the application for non-residents, even where an SSN or ITIN is not required. This can make Bank of America difficult for people who live permanently outside the US and do not maintain a US residential address.

Can I open it online from abroad?

Generally, no. Non-residents should expect to complete the account-opening process at a physical Bank of America branch in the United States. The online application process does not provide a dependable way for someone living abroad to open the account entirely remotely.

Should you save in dollars, pounds or euros?

•

•

2 min read

I used to live in Spain while getting paid in dollars, which meant my income was in USD but most of my expenses were in euros. Whenever I wanted to save part of what I earned, I had to decide if it made more sense to keep the money in dollars or convert it to euros.

If you earn internationally, you may have asked yourself the same question. And the answer depends less on which currency is “better” and more on what you’re saving for.

There isn’t one currency that always makes the most sense. It depends on where your money comes from and, just as importantly, where it will eventually go.

A simple rule is to save in the currency you earn or plan to spend. If you’re paid in dollars and your goal is in dollars, keeping that money in USD avoids converting it twice. If you know you’ll eventually spend in another currency, you can plan your savings around that instead.

Let’s look at when saving in USD, GBP or EUR makes sense and how to choose the right currency for different goals.

Does the currency you save in matter?

Yes, especially when your income and expenses involve more than one currency.

Imagine you’re paid $2,000 each month and want to set $300 aside. You could immediately convert that $300 into your local currency, but what happens if you’re saving for something you’ll eventually pay for in dollars?

When the time comes, you may need to convert the money back to USD. That means going through two currency conversions when you could have simply kept part of your original payment in dollars.

Every currency conversion comes with an exchange rate, and providers may include a margin or charge a conversion fee. Exchange rates also change over time, so the amount you get when converting today may be different from what you would get a few months from now.

This is where thinking about the purpose of your savings becomes useful.

Rather than asking which currency is the “best” to save in, ask yourself two questions: What currency do I earn in, and what currency will I need when I spend this money?

The answers can help you decide where to keep it.

When it makes sense to save in dollars, pounds or euros

USD, GBP and EUR are widely used currencies, but that doesn’t mean you need to pick one and keep all your savings there.

The right choice depends on your income, expenses and plans.

Saving in USD

Keeping savings in dollars can make sense if most of your income already arrives in USD.

If part of that money is intended for future expenses in USD, keeping it in dollars means you don’t need to convert it until there’s a reason to.

USD may also make sense for a general buffer if dollars are a regular part of your financial life. The important part is that the currency matches how you expect to use the money.

Saving in GBP

GBP can be a practical choice if you earn or regularly spend in pounds.

Perhaps you work with UK clients and receive part of your income in GBP. Or maybe you’re saving for tuition, rent, a move to the UK or another expense that you know will be charged in pounds.

Keeping that money in GBP means you already have the currency you’ll eventually need.

If you earn in another currency, however, moving everything into pounds just because you think GBP might become stronger introduces another variable. Exchange rates can move in either direction, so your decision is better based on a real future need than trying to predict the market.

Saving in EUR

The same logic applies to euros.

If you receive EUR from clients or employers, you may want to keep part of those earnings in euros rather than immediately converting the full payment.

EUR can also be useful when you have a specific euro-denominated goal. You might be planning a trip around Europe, saving for a move, paying for a course or preparing for another expense that will eventually come out of your pocket in euros.

In that case, gradually setting aside EUR can help you build towards the amount you know you’ll need.

Here’s a simple way to think about it:

If you... Plan to spend in... It may make sense to save in...
Earn in USD from US clients USD USD
Earn in GBP and are building an emergency buffer GBP GBP
Earn in EUR and are planning a European trip EUR EUR
Earn in USD but are moving to the UK GBP GBP for the moving goal
Earn in GBP but are planning a trip priced in EUR EUR EUR for the trip
Earn in several currencies Have goals in different currencies Match each goal to the currency you expect to spend

‍

You don’t necessarily have to make the same choice for every goal. Your emergency money, next holiday and future move can each have different timelines and currency needs.

The real cost of converting too early

It’s tempting to convert foreign income as soon as you receive it, especially if that’s what you’ve always done. But converting before you know what the money is for can sometimes mean paying for an extra conversion later.

Say you receive $1,000 and want to save $200 for something priced in USD. If you keep that $200 in dollars, it’s ready when you need it. But if you convert everything to your local currency, you’ll eventually have to convert part of it back to USD.

That extra conversion can come with fees, and exchange rates may change in the meantime.

Of course, converting the money you need for rent, groceries and other local expenses makes sense. For the rest, think about what you’re saving for before deciding which currency to keep it in.

How to match your savings currency to your goals

Once you start thinking about savings as individual goals rather than one big pot of money, choosing a currency becomes easier.

Say you have three plans: an emergency fund, a trip to Spain and money for an upcoming move to London.

Each one serves a different purpose.

Your emergency fund might stay in the currency you earn or use most often. For your Spain trip, you could gradually set aside EUR because that’s what you’ll spend when you get there. And your moving fund could be kept in GBP because you already know you’ll need pounds for deposits, rent and other expenses.

Instead of trying to decide if USD, GBP or EUR is universally “better”, you’ve matched each currency to a real goal.

You can apply the same approach to smaller plans, like a new laptop priced in USD, a course charged in GBP or a holiday budget in EUR.

If you earn internationally, opening a multi-currency account can make this easier because you don’t have to move everything into one currency as soon as you get paid.

And you can take the idea a step further by separating the money for each goal.

Save in USD, GBP and EUR with Pouch

With Pouch, you can create individual Pouches in USD, GBP and EUR and give each one its own purpose. You might have an Emergency Pouch in USD, a London Pouch in GBP and a Summer Trip Pouch in EUR.

You can also set a target for each Pouch, making it easier to see how close you are to your goal without mixing that money with your everyday balance.

If your first priority is having money available for unexpected expenses, you can also start by learning how to build an emergency fund.

There’s also Round-ups if you want to build towards a goal little by little. When you enable Round-ups, eligible Grey card payments are rounded up and the difference is moved into the Pouch you choose.

Pouch doesn’t pay interest, and the money you put there isn’t invested. It simply gives your savings and plans their own space within Grey, separate from the money sitting in your everyday balance.

If you already receive your income through Grey, you can save in the currency you earn and start building towards your next goal without converting the money first.

The goal is to give the money you’re setting aside a currency that makes sense for how you plan to use it.

Frequently asked questions about saving in dollars, pounds or euros

Is it better to save in dollars or euros?

Neither currency is automatically better for saving. A useful approach is to consider the currency you earn and the currency you expect to spend.

If you earn in USD and are saving for an expense priced in dollars, keeping the money in USD can avoid an unnecessary conversion. If your goal is priced in EUR, saving that portion in euros may make more sense.

Should I save in the same currency I get paid in?

It can make sense, particularly if you expect to use the money in that currency later. Keeping part of your income in its original currency also means you don’t have to convert all of it as soon as you’re paid.

For goals in another currency, you may prefer to set money aside in the currency you expect to spend.

Is it good to keep savings in different currencies?

It can be useful when you earn or spend in multiple currencies. For example, someone earning USD but planning to move to the UK may keep part of their savings in USD and set aside a separate GBP fund for moving expenses.

The decision should reflect your actual plans rather than trying to predict which currency will increase in value.

When should I convert my foreign currency income?

Consider converting the portion you know you’ll need in another currency.

If you’re paid in USD but need local currency for your monthly expenses, converting enough to cover those expenses makes sense. Money intended for a future USD expense may not need to be converted at all.

Can I save in USD, GBP and EUR at the same time?

Yes. With a multi-currency account that supports these currencies, you can keep money in USD, GBP and EUR at the same time.

Grey Pouch also lets you create separate Pouches in each supported currency, so different goals can have their own currency and target.

What is multi-currency saving?

Multi-currency saving means keeping money for different goals in more than one currency rather than converting everything into a single currency.

For example, you might keep an emergency fund in USD, save for UK expenses in GBP and set aside EUR for a European trip. The currencies you choose depend on how you earn and what you’re saving for.

Does Pouch pay interest?

No. Pouch is not an investment or interest-bearing savings product. It is a way to separate money from your main Grey balance and organise it around specific goals in USD, GBP or EUR.

Give each goal its own currency

There’s no need to choose one currency for every part of your savings.

Start with what the money is for. If the goal is to be paid for in dollars, saving in USD may make sense. If you know you’ll need pounds or euros, you can build towards the goal in that currency instead.

With Grey Pouch, you can separate those plans, set targets and keep your USD, GBP and EUR savings organised in one place.

Open a Pouch in the currency you earn and fund it today.

Arrow (up)

Back to top