<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/georgia-digital-nomad-visa#article","headline":"Georgia digital nomad visa: Everything you need to know","description":"Most nationalities can work remotely in Georgia for up to 365 days without a visa. Full guide to the Remoteli programme, costs and requirements. Start now.","inLanguage":"en","url":"https://grey.co/blog/georgia-digital-nomad-visa","mainEntityOfPage":{"@id":"https://grey.co/blog/georgia-digital-nomad-visa#webpage"},"datePublished":"2026-06-30T21:24:02.213Z","dateModified":"2026-07-01T10:48:00+01:00","author":{"@type":"Person","@id":"https://grey.co/authors/adeolu-titus-adekunle#person","name":"Adeolu Titus Adekunle","url":"https://grey.co/authors/adeolu-titus-adekunle","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/titusadeoluadekunle/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/georgia-digital-nomad-visa#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a4433dfbf45799c68e0516e_Georgia%20digital%20nomad%20visa%20Everything%20you%20need%20to%20know-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a4433dfbf45799c68e0516e_Georgia%20digital%20nomad%20visa%20Everything%20you%20need%20to%20know-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/georgia-digital-nomad-visa#webpage","url":"https://grey.co/blog/georgia-digital-nomad-visa","name":"Georgia Digital Nomad Visa: Remoteli and How to Apply | Grey","description":"Most nationalities can work remotely in Georgia for up to 365 days without a visa. Full guide to the Remoteli programme, costs and requirements. Start now.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/georgia-digital-nomad-visa#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/georgia-digital-nomad-visa#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/georgia-digital-nomad-visa#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Georgia digital nomad visa: Everything you need to know","item":"https://grey.co/blog/georgia-digital-nomad-visa"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/georgia-digital-nomad-visa#faq","mainEntity":[{"@type":"Question","name":"Do I need a visa to work remotely in Georgia?","acceptedAnswer":{"@type":"Answer","text":"For citizens of more than 90 countries, including the US, UK, EU member states, Canada, and Australia, no. Georgia's standard visa-free entry allows a stay of up to 365 days, during which remote work for foreign employers or clients is permitted. If your nationality is not on the visa-free list, the D2 Immigration Visa (Freelancer and Entrepreneurial Activity) is the relevant formal route. Always verify your specific nationality's status against Georgia's current official visa-free list before travelling."}},{"@type":"Question","name":"What is the Remoteli programme?","acceptedAnswer":{"@type":"Answer","text":"Remoteli, officially \"Remotely from Georgia,\" was a programme launched in 2020 during the COVID-19 pandemic to give remote workers a formal pathway to enter and reside in Georgia while standard tourism was disrupted. The programme has largely been phased out and is considered close to obsolete, as Georgia's standard one-year visa-free entry for most nationalities now serves the same practical purpose without requiring a separate application. The current formal visa route for those who need one is the D2 Immigration Visa."}},{"@type":"Question","name":"How much does it cost to live in Tbilisi as a digital nomad?","acceptedAnswer":{"@type":"Answer","text":"A comfortable monthly budget in Tbilisi runs $800 to $1,200, covering a one-bedroom apartment in a central area, food, coworking membership, and local transport. This is significantly below most European capitals and even below many other popular nomad destinations in Southeast Asia and Latin America."}},{"@type":"Question","name":"Do I pay tax in Georgia on foreign income?","acceptedAnswer":{"@type":"Answer","text":"In most cases, no, provided you do not trigger Georgian tax residency, which generally requires staying 183 or more days within a 12-month period. Holding a visa or staying visa-free does not automatically make you a tax resident. For those who do register as tax residents and set up as an Individual Entrepreneur with Small Business Status, Georgia offers a flat 1% tax rate on turnover up to approximately $165,000 annually. This is a complex area; consult a tax adviser familiar with Georgian and your home country's tax rules before making decisions."}},{"@type":"Question","name":"Can I open a Georgian bank account as a remote worker?","acceptedAnswer":{"@type":"Answer","text":"Yes. Foreigners in Georgia can easily open local bank accounts, with English-speaking staff and digital-first processes at major banks. Most nomads report being able to open an account in a single 30- to 60-minute visit, though specific document requirements vary by bank. Some banks also offer remote account opening via a power-of-attorney service for an additional fee."}},{"@type":"Question","name":"Can I bring my family to Georgia on a visa-free stay or the D2 visa?","acceptedAnswer":{"@type":"Answer","text":"Family members travelling with the primary applicant generally need to meet the same visa-free or visa requirements as the primary applicant, based on their own nationality. For the D2 visa specifically, confirm with the Georgian consulate whether dependants can be included on the same application or require separate applications, as requirements can vary."}}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/georgia-digital-nomad-visa#terms","name":"Georgia digital nomad visa: Everything you need to know glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"Georgia Remoteli programme","description":"The \"Remotely from Georgia\" programme, often referred to as Remoteli, was launched by the Georgian government in 2020 during the COVID-19 pandemic, when international travel and tourism were heavily disrupted. At the time, it served as a structured pathway for remote workers to enter and reside in Georgia legally while standard tourism was restricted.","inDefinedTermSet":{"@id":"https://grey.co/blog/georgia-digital-nomad-visa#terms"}}]}] </script>

Georgia digital nomad visa: Everything you need to know

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

Georgia has become one of the easiest countries in the world for digital nomads to live and work remotely. Even though Portugal, Thailand, and Bali are more popular, Georgia offers low living costs, reliable internet, a simple immigration process, and less rowdiness. Tbilisi, the capital, has developed into a major remote work hub with coworking spaces, international cafes, growing startup activity, and a large expat and freelancer community.

Georgia allows most nationalities to stay for up to 365 days without a visa, making it one of the easiest countries in the world for remote workers. The "Remotely from Georgia" (Remoteli) programme, launched in 2020, was created to formalise this for digital nomads, but it has largely been superseded by Georgia's standard visa-free regime and is now considered nearly obsolete. For most remote workers, the visa-free stay alone is sufficient.

This guide covers everything you need to know about living in Georgia as a digital nomad, including visa rules, taxes, cost of living, internet quality, banking, healthcare, best cities to live in, and how to manage international payments while working remotely from Georgia.

Can you work remotely in Georgia without a visa?

For the vast majority of digital nomads, yes. Georgia offers one of the most generous visa-free entry policies in the world. Citizens of more than 90 countries, including the United States, the United Kingdom, EU member states, Canada, Australia, and several African nations, can enter Georgia and stay for up to 365 days without applying for a visa in advance.

While Georgia does not currently offer a standalone "digital nomad visa" as Portugal or Spain do, its standard visa-free entry effectively serves the same purpose for most nationalities. This visa-free stay allows digital nomads to live in Georgia for up to 12 months, work remotely for foreign employers or clients, travel freely within the country, and access local services. It, however, doesn’t permit you to work for a Georgian employer or earn a local income from within Georgia.

Georgia recently passed amendments in June 2025 introducing mandatory work permits for foreign nationals starting 1 March 2026. This law targets foreign nationals working in Georgia or for Georgian business registrations. Remote workers earning income entirely from abroad, without entering into Georgian employment or local business registration, are generally expected to fall outside this requirement, though the distinction is still being clarified as implementation proceeds. If your situation involves any local Georgian income or employment, verify the current requirements before relying solely on the visa-free stay.

For a wider comparison of options, see our full list of 50 countries offering digital nomad visas.

What is the Georgia Remoteli programme?

The "Remotely from Georgia" programme, often referred to as Remoteli, was launched by the Georgian government in 2020 during the COVID-19 pandemic, when international travel and tourism were heavily disrupted. At the time, it served as a structured pathway for remote workers to enter and reside in Georgia legally while standard tourism was restricted.

The honest, current picture is that the programme has been largely phased out in practice. The return of Georgia's standard one-year visa-free entry for most nationalities has made the programme unnecessary for most remote workers. The official government information about the programme has not been consistently updated, and some online application portals associated with it have been reported as unreliable or non-functional. Georgia's official e-visa website no longer prominently lists the programme as an active offering.

In practice, this means most digital nomads researching "Georgia digital nomad visa" do not need to apply for anything at all if their passport qualifies for the standard visa-free stay. Travelling to Georgia, finding accommodation, and beginning remote work is sufficient for most nationalities for up to 365 days.

The formal route still matters for nationalities not on Georgia's visa-free list, or for remote workers and freelancers who specifically want a more structured immigration document for purposes such as a longer pathway to residency, tax registration, or nationalities requiring more than the standard tourist entry. For these cases, the relevant formal route is the D2 Immigration Visa for freelance and entrepreneurial activity, which is separate from the original COVID-era Remoteli programme and remains an active, processed visa category.

D2 Immigration Visa: requirements for those who need a formal visa

For remote workers who are not eligible for Georgia's visa-free entry, or who want formal documented status from the outset, the D2 Immigration Visa (Freelancer and Entrepreneurial Activity) is the relevant Georgian visa category. Confirm current requirements directly with the Georgian Ministry of Foreign Affairs or the Georgian consulate in your country before applying, as terms are subject to change.

  • Income or savings: A minimum monthly income equivalent to roughly five times the current national subsistence minimum, which is approximately GEL 1,250 (around $480), or sufficient savings to cover your expenses for the duration of stay
  • Remote work status: Proof of remote employment, freelance contracts, or entrepreneurial activity for clients or a business based outside Georgia
  • Valid passport: Valid for at least three months beyond the intended departure date
  • Health insurance: A policy covering the duration of the stay in Georgia
  • Clean criminal record: A background check from the applicant's home country
  • Accommodation proof: A rental agreement or hotel reservation confirming where the applicant will stay
  • Travel itinerary: Flight booking details confirming entry to Georgia

Acceptable documentation for the income or savings requirement typically includes three to six months of bank statements, employment contracts, freelance agreements, or tax returns. Any documents not already in Georgian or English should be officially translated.

Also read: How to receive USD payments on Etsy as a seller in Georgia

How to apply for the D2 visa: step-by-step

  1. Confirm whether you actually need a visa: Check your nationality against Georgia's current visa-free list before applying for anything. Most nomads from major Western countries, as well as many African and Asian countries, do not need to apply for a visa at all.
  2. Gather your documents: You need your passport, proof of remote income or savings, health insurance certificate, criminal background check, proof of accommodation, and travel itinerary.
  3. Apply through the online visa portal or the relevant Georgian consulate: Applications for the D2 visa are submitted online through the official Georgian government visa portal or, in some cases, through a consulate, depending on your location and circumstances.
  4. Pay the consular fee: The standard consular fee for a long-term immigration visa is approximately $20, though this can vary slightly by consulate.
  5. Wait for processing: Processing typically takes 10 to 30 business days, depending on application volume, documentation completeness, and submission method. Apply well in advance of your intended travel date.
  6. Travel to Georgia and register: Once approved, travel to Georgia within the visa's validity window. If you intend to stay long-term, registering your residential address and exploring residency or tax registration options is the practical next step.

Costs, duration, tax and why Georgia is worth considering

  • Costs: The D2 visa carries a standard consular fee of approximately $20. There is no fee for the standard visa-free stay available to most nationalities.
  • Duration: Both the visa-free stay and the D2 visa permit a stay of up to one year. The permit is generally cancelled if the holder is absent from Georgia for 183 or more days within a 12-month period.
  • Tax position: Holding a Georgian visa, whether visa-free entry or the D2 visa, does not automatically make you a Georgian tax resident. Most digital nomads remain taxed only in their home country unless they meet Georgia's tax residency criteria, which is primarily based on staying in Georgia for 183 or more days within a 12-month period.
  • Cost of living in Tbilisi: Georgia's affordability is one of its strongest draws. A comfortable monthly budget in Tbilisi, covering a one-bedroom apartment in a central neighbourhood, food from local markets and restaurants, coworking membership, and local transport, typically runs $800 to $1,200. Many nomads report living comfortably for closer to $1,000 to $1,500 per month, including occasional travel within the country.
  • Banking: Georgia offers exceptionally accessible banking for foreigners, with English-speaking staff at major banks, modern digital banking platforms, and relatively straightforward account opening. Most digital nomads report being able to open a local account in a single visit that takes 30 to 60 minutes, though requirements vary by bank.

Managing your international income while based in Georgia is more straightforward with a multi-currency account that holds your earnings in their original currency before converting to lari. Open a multi-currency account before you move, and your clients can pay you in USD, GBP, or EUR as a domestic transfer in their own country, with no correspondent bank deductions on the way to you.

Open a Grey account before you move to Georgia. Hold USD, GBP and EUR in one place and spend locally from day one. Pair it with a Grey virtual debit card for everyday spending in Tbilisi and beyond.

Frequently asked questions

Do I need a visa to work remotely in Georgia?

For citizens of more than 90 countries, including the US, UK, EU member states, Canada, and Australia, no. Georgia's standard visa-free entry allows a stay of up to 365 days, during which remote work for foreign employers or clients is permitted. If your nationality is not on the visa-free list, the D2 Immigration Visa (Freelancer and Entrepreneurial Activity) is the relevant formal route. Always verify your specific nationality's status against Georgia's current official visa-free list before travelling.

What is the Remoteli programme?

Remoteli, officially "Remotely from Georgia," was a programme launched in 2020 during the COVID-19 pandemic to give remote workers a formal pathway to enter and reside in Georgia while standard tourism was disrupted. The programme has largely been phased out and is considered close to obsolete, as Georgia's standard one-year visa-free entry for most nationalities now serves the same practical purpose without requiring a separate application. The current formal visa route for those who need one is the D2 Immigration Visa.

How much does it cost to live in Tbilisi as a digital nomad?

A comfortable monthly budget in Tbilisi runs $800 to $1,200, covering a one-bedroom apartment in a central area, food, coworking membership, and local transport. This is significantly below most European capitals and even below many other popular nomad destinations in Southeast Asia and Latin America.

Do I pay tax in Georgia on foreign income?

In most cases, no, provided you do not trigger Georgian tax residency, which generally requires staying 183 or more days within a 12-month period. Holding a visa or staying visa-free does not automatically make you a tax resident. For those who do register as tax residents and set up as an Individual Entrepreneur with Small Business Status, Georgia offers a flat 1% tax rate on turnover up to approximately $165,000 annually. This is a complex area; consult a tax adviser familiar with Georgian and your home country's tax rules before making decisions.

Can I open a Georgian bank account as a remote worker?

Yes. Foreigners in Georgia can easily open local bank accounts, with English-speaking staff and digital-first processes at major banks. Most nomads report being able to open an account in a single 30- to 60-minute visit, though specific document requirements vary by bank. Some banks also offer remote account opening via a power-of-attorney service for an additional fee.

Can I bring my family to Georgia on a visa-free stay or the D2 visa?

Family members travelling with the primary applicant generally need to meet the same visa-free or visa requirements as the primary applicant, based on their own nationality. For the D2 visa specifically, confirm with the Georgian consulate whether dependants can be included on the same application or require separate applications, as requirements can vary.

Last updated:

October 10, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Grey Business vs Grey personal banking

•

•

2 min read

“Should I be using Grey Business, or is my personal Grey account enough?”

It’s a common question, especially once your income starts growing.

At the beginning, everything feels simple. You get paid and you withdraw your money easily. But as your work evolves, whether that’s taking on more clients, earning from multiple platforms, or starting a company, the way you manage money needs to evolve too.

Grey offers two account types for this exact reason: Grey Personal and Grey Business. They are not better or worse than each other. They are built for different stages of your earning process.

This guide breaks down the differences, including fees, features, and when to switch, so you can choose the right setup without second-guessing.

‍Also read: Receiving foreign income as a solo founder

What is a Grey personal account?

A Grey personal account is designed for individuals who receive and manage international payments.

If you are a freelancer, remote worker, or creator earning from global clients or platforms, this is the account you are expected to use.

With a personal account, you can open USD, GBP, and EUR balances with real banking details. This allows clients to pay you as if they were making a local transfer in their own country. Instead of receiving an expensive international wire, you receive money through local rails like ACH, SEPA, and FPS.

Once the money arrives, you can hold it in foreign currency, convert it when the rate works for you, or withdraw it to your local bank account. You can also spend directly using your Grey virtual card without needing to manually move funds around.

The focus here is simplicity. You are managing your own income, and the account is designed to make that as flexible as possible.

What fees does Grey Personal charge?

Understanding fees is where most people get confused, so here’s how it actually works.

When you receive money through ACH, SEPA, or FPS, Grey charges a 0.8% fee, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. This means larger payments become proportionally cheaper because of the cap.

Currency conversion depends on the currency pair. Some routes are free, while others range from 0.5% to 1%. For certain major pairs, the fee is capped at $6. The important detail is that Grey shows the rate before you confirm, so there are no hidden charges after the fact.

Withdrawals vary depending on the country, but for major currencies like EUR and GBP, the fee is typically 0.5%, with a minimum and maximum cap. Other corridors may use fixed fees instead.

For less common deposit methods like Fedwire, BACS, or CHAPS, fixed fees apply. These are generally used less often, since local rails like ACH or FPS are cheaper.

Read more: Grey charges explained: what every transaction costs

What is Grey Business?

Grey Business is designed for companies rather than individuals.

If you are running a registered business, working under a company name, or managing revenue that belongs to a business entity, this is the account structure you need.

Unlike a personal account, a Grey Business account is built for your company. This means you can receive payments on behalf of the business, manage funds at a company level, and keep financial records properly organised for accounting and compliance.

The functionality goes beyond receiving payments. Grey Business allows you to manage team access, assign roles, and give multiple people control over finances without sharing a single login.

You can also pay contractors globally, send payments in local currencies, and handle bulk payouts by uploading recipient details. This becomes important as soon as you are working with a team or scaling operations.

The goal of Grey Business is not just to receive money, but to structure how your business handles it.

What fees does Grey Business charge?

Grey Business follows the same core pricing model as personal accounts.

Receiving payments still comes with the 0.8% fee capped at $10. Conversion fees follow the same tiered structure, and withdrawals depend on the payout country.

The difference is not in lower fees, but in what the account enables.

With Grey Business, you are paying for structure, team management, and the ability to operate at scale without mixing personal and company finances.

Grey Personal vs Grey Business: what is the difference?

The main difference comes down to ownership.

A personal account is for money that belongs to you as an individual. A business account is for money that belongs to a company.

Everything else builds from that.

Grey Personal is simpler, quicker to set up, and designed for individuals managing their own income. Grey Business requires verification of a registered company but provides tools to manage payments, teams, and operations effectively.

If you are working alone and getting paid for your own work, a personal account is enough. If you are invoicing as a company, hiring people, or managing shared finances, you need a business account.

‍Also read: Can non-residents open a US bank account online in 2026?

When should you use Grey for personal use?

You should use a personal account if you are earning in your own name.

This includes freelancers, remote employees, and creators earning from platforms like YouTube, TikTok, or Upwork. At this stage, your income is still personal, even if it comes from multiple sources.

A personal account keeps things simple.

When should you use Grey Business?

You should use Grey Business when your income is no longer just yours.

If you have registered a company, invoice under a business name, or manage revenue that belongs to a business entity, a personal account is no longer the right structure.

This is especially important if you are paying contractors, working with a team, or preparing financial records for accounting and tax purposes.

Can you have both Grey for personal use and Grey Business?

Yes, and in many cases, this is the best setup.

If you run a company but also earn income personally, keeping both accounts separate helps avoid confusion. Your business transactions stay within the business account, while your personal income remains separate.

This makes accounting cleaner and reduces the risk of mixing funds.

Grey for personal use vs Grey Business: key differences

Feature Grey Personal Grey Business
Who it’s for Individuals (freelancers, creators, remote workers) Registered companies, startups, agencies
Account ownership Personal use Business entity
Currencies supported USD, GBP, EUR, USDC USD, USDC (business-focused)
Receiving payments Yes (ACH, SEPA, FPS) Yes (for business transactions)
Team access No Yes (multi-user access with roles)
Bulk payouts No Yes (CSV uploads supported)
Virtual cards Yes (for personal use) Yes (multiple cards for teams, tools, ads)
Best use case Getting paid individually Managing company finances and scaling operations
Setup process Fast (ID verification) More detailed (business verification required)

So, which Grey account should you choose?

Most people overthink this decision, but it comes down to one simple question:

Who does the money belong to?

If you’re earning as an individual, whether that’s freelancing, remote work, or content creation, a Grey Personal account is the right fit. It keeps things simple and flexible while giving you full access to international payments.

If you’re operating as a registered business, invoicing clients under a company name, or managing team payments, Grey Business is the structure you need. It helps you separate finances properly and handle growth without creating confusion later.

If you’re in between, which is common, you can start with a personal account and move to business when your setup requires it. Many users also keep both, using one for personal income and the other for company operations.

The goal isn’t to pick the most advanced option. It’s to choose the one that fits how you earn today and won’t slow you down as you grow.

Getting started with Grey

Opening a Grey Personal account takes just a few minutes. You can sign up in under 5 minutes, and once your identity is verified, you can usually start receiving payments the same day.

Opening Grey Business takes a bit longer because it involves business verification. You’ll need to submit your company registration and ownership details, and approval typically takes 1 to 3 business days, depending on the documents provided. This ensures your account is set up correctly from the start.

Frequently asked questions

What is the difference between Grey for persona use and Grey Business?

Grey Personal is for individuals receiving and managing their own income, such as freelancers, creators, and remote workers. Grey Business is for registered companies that need to manage business revenue, pay contractors, and give team members access to finances.

The main difference is ownership. Personal accounts are for your money. Business accounts are for company funds.

Can I use a Grey Personal account for business payments?

You can use a personal account while you are freelancing under your own name. However, once you register a company or start invoicing under a business name, it is better to switch to Grey Business.

Using a personal account for business transactions can create confusion with accounting, taxes, and financial tracking.

Does Grey Business have different fees from Grey Personal?

Grey Business follows the same core pricing structure as personal accounts. Receiving fees are typically 0.8% with a cap, and conversion fees depend on the currency pair.

The main difference is not pricing, but functionality. Grey Business adds tools for team access, bulk payments, and structured financial management.

Can I have both a Grey Personal and Grey Business account?

Yes. Many users have both accounts.

This is useful if you have personal income, such as freelance work or creator earnings, and also run a registered business. Keeping them separate makes accounting cleaner and easier to manage.

When should I switch from Grey Personal to Grey Business?

You should consider switching when your income becomes business revenue instead of personal income.

This usually happens when you register a company, start invoicing clients as a business, hire contractors, or need proper financial records for tax and reporting purposes.

What documents are required to open a Grey Business account?

To open a Grey Business account, you will need to provide company registration documents, ownership details, and verification information about the business.

The process is more detailed than a personal account because it involves verifying a legal entity.

Is Grey Personal enough for freelancers and creators?

Yes. For most freelancers, remote workers, and creators, Grey Personal is more than enough.

It allows you to receive international payments, hold foreign currency, convert when needed, and withdraw locally without needing business-level setup.

Can I receive USD, GBP, and EUR with both accounts?

Yes. Both Grey Personal and Grey Business support multi-currency functionality.

Personal accounts focus on individual income, while business accounts structure those same capabilities for company use.

Which Grey account is better?

Neither is better. They are designed for different use cases.

Grey Personal is better for individuals managing their own income. Grey Business is better for companies managing business finances and scaling operations.

Ready to get started?

Open your Grey Personal account to start receiving international payments as an individual, or set up Grey Business if you’re managing company finances and need a more structured setup.
Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

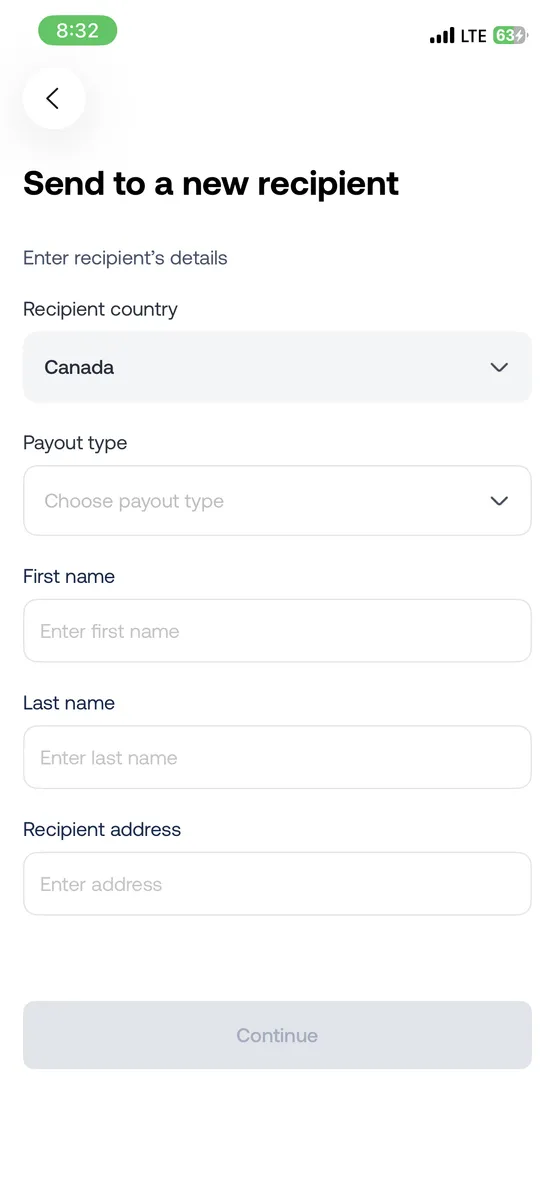
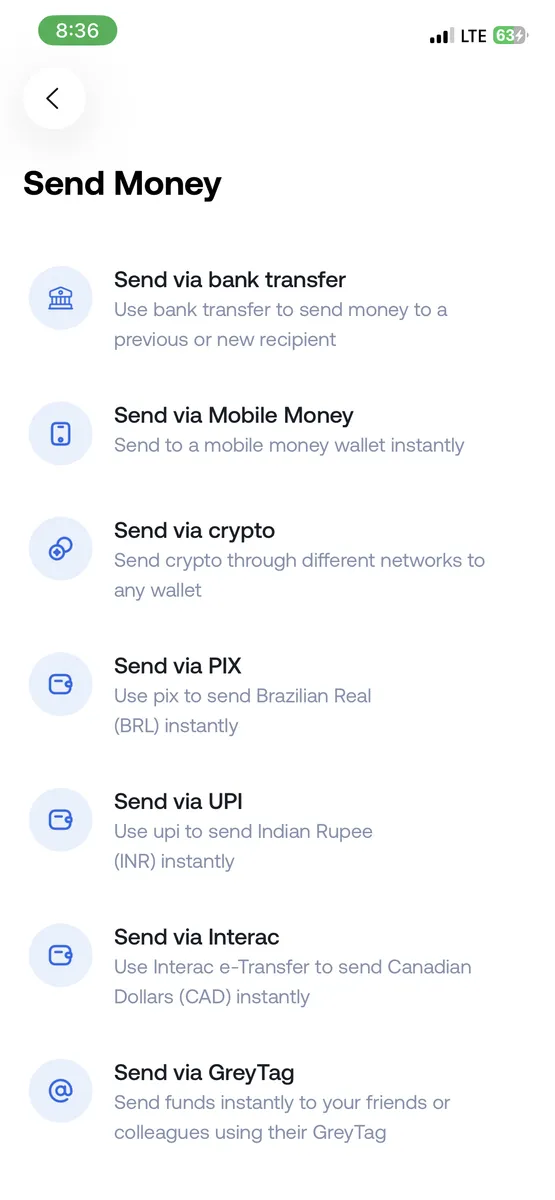
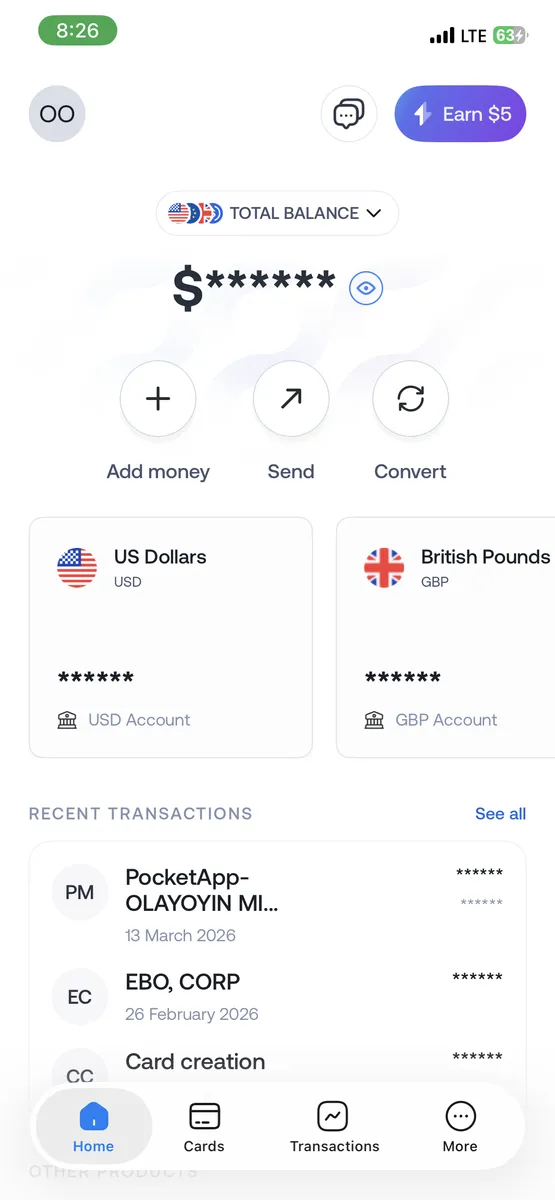
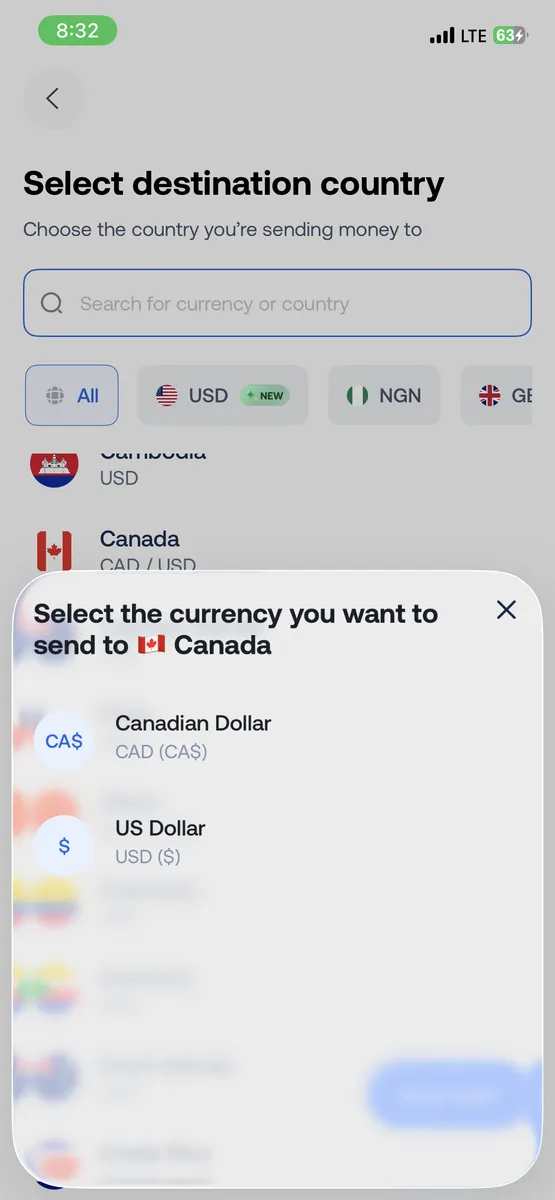
We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

  1. Log in to your Grey account.
    ‍
  2. Click “Send”.
Send Canadian dollars with Grey

‍

2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

How US startups pay remote workers outside the US

•

•

2 min read

Remote work has changed how US startups build their teams. It’s no longer unusual for a founder in the United States to work daily with designers, developers, consultants, and marketers living thousands of miles away. Slack messages replace office conversations, video calls stand in for physical meetings, and shared documents keep projects moving. Talent is no longer limited by geography, and startups are more comfortable hiring skilled professionals regardless of where they live.

But when the work is done, a simple question follows: how do payments actually reach these remote workers outside the US? For many startups, paying global talent has become part of their everyday operations. This article examines how US startups handle payments to remote workers around the world and the practical ways those professionals receive their earnings.

Also read: How freelancers in the US get paid by international clients

Challenges US startups face when sending money abroad

Sending money to remote workers outside the US comes with challenges. Understanding them helps startups pay reliably, build trust, and value global talent.

Transaction fees‍

Wire transfers often come with high fees from intermediary banks and the recipient’s bank. As a US startup, it’s important to anticipate these costs so your remote workers get the full payment they expect. Being aware of fees ahead of time helps you plan better, maintain transparency, and show your team that their work is valued.

Payment delays

‍Sending money to emerging markets can take longer than expected, even with the right platforms. Delays can frustrate your remote team and disrupt workflow. By anticipating timing challenges and keeping your workers informed, you demonstrate reliability and professionalism, ensuring your remote consultants feel respected and confident that their efforts will be rewarded on time.

Platform restrictions

‍Not all payment methods work everywhere. Platforms like PayPal may have limited support in some countries, making it tricky for your team to receive funds. Knowing these restrictions upfront helps you select the right solution, so your remote workers can get paid smoothly, avoiding frustration and maintaining trust in your startup’s global processes.

Security risks

‍Cross-border payments carry risks such as fraud, phishing, and data breaches. Using secure platforms and monitoring transactions carefully protects both your startup and your remote workers. Prioritising security shows professionalism and builds confidence. Your team can focus on delivering great work knowing that their money and personal information are safe, strengthening trust across borders.

Also read: Get paid by clients overseas as a US freelancer

How US startups pay remote workers outside the US

Paying remote workers abroad has become a normal part of US startups. Choosing the right platform ensures fast, reliable payments and builds trust.

Wise

Wise gives US startups a straightforward way to send payments to remote workers in other countries. Businesses can transfer USD directly while the recipient receives funds in their local currency at real exchange rates rather than marked-up bank rates. Transfers are trackable in real time and fees are shown upfront, helping startups plan payroll accurately. Wise also supports multi-currency balances, allowing companies to manage payments in different currencies from one account.

Transaction costs are generally lower than traditional bank wires, and transfers are often completed within one to two business days, making it a practical option for startups paying distributed teams.

Payoneer

Payoneer allows US startups to pay remote workers and contractors across multiple countries through a structured global payments network. Businesses can send funds in major currencies such as USD, EUR, or GBP while recipients withdraw to their local bank accounts or use a prepaid Payoneer card where available.

The platform also integrates with many global marketplaces and invoicing tools, which simplifies contractor payments. Fees and currency conversion rates are visible before sending, helping startups manage payroll budgets.

Western Union

Western Union allows US startups to send funds to remote workers in select countries fast. Payments can be picked up in cash at a local agent or deposited directly to a bank account where supported. While fees can be higher than digital‑first platforms, speed and accessibility make it valuable for urgent needs or recipients without online banking.

With a global agent network and mobile options in many regions, it’s practical when flexibility and immediate access to funds matter most.

Grey (recommended)

Grey helps US startups pay remote workers abroad by sending funds in USD to dedicated foreign currency accounts. Your team members can then convert the money into their local currency when it suits them and withdraw to their local bank accounts. This gives remote workers more control over how and when they manage their earnings while keeping payments straightforward for startups.

Grey follows strict anti-money laundering (AML) standards and is registered with FinCEN in the United States and FINTRAC in Canada, helping ensure payments are handled responsibly within recognised financial compliance frameworks.

Remitly

Remitly is commonly used by US startups when paying remote workers in countries where traditional banking systems may be slower or less accessible. The platform offers two transfer speeds: Express, which delivers funds within minutes but at a higher fee, and Economy, which costs less but can take several days.

Payments can reach bank accounts, mobile wallets, or approved cash pickup locations. For teams spread across different regions, Remitly provides flexibility in how workers receive funds and reliable tracking from the moment the payment is sent.

Sendwave

Sendwave is designed for sending money to workers in regions where mobile money is widely used, particularly across Africa and parts of Asia. Instead of relying on traditional bank transfers, US startups can send funds directly to supported mobile wallets, allowing workers to access their earnings instantly through their phones.

Because of its strong mobile wallet integrations, the platform works well for startups paying contractors in markets where mobile financial services are more common than conventional banking.

What should US startups consider before choosing a payment solution?

Choosing the right payment solution requires thought and planning. US startups need to ensure transfers are smooth and reliable, and that they build trust with their remote team.

Speed

Fast deposits matter for keeping your remote team motivated and satisfied. Delays can frustrate workers and slow project momentum. Look for providers that move funds quickly from US accounts to local accounts abroad, with predictable timing and clear tracking. Understanding typical transfer times allows you to plan payroll cycles efficiently, maintain trust, and show remote workers that their time and efforts are valued.

Security

Protecting payments and sensitive data is essential. Choose a provider with built-in fraud detection, encryption, and 3D secure integration. Secure systems prevent phishing, hacking, and unauthorised access, giving both your startup and remote workers confidence. Strong security safeguards help you avoid costly mistakes, maintain compliance, and demonstrate professionalism, ensuring your global team trusts the platform for every international transfer.

Support quality

Reliable support is crucial for resolving payment issues quickly. Access to 24/7 dedicated customer service ensures that any delays, errors, or account questions are handled efficiently. Responsive support reduces stress for both your startup and remote workers, ensuring smooth operations. Knowing that help is always available allows you to manage international payroll confidently without worrying about interruptions.

High uptime

Choose a payment provider with consistently high uptime to avoid failed transactions, system downtime, or lost revenue. Downtimes can delay payments and erode trust with remote workers. A reliable platform ensures your transfer process runs smoothly around the clock, across time zones, and in line with deadlines. High uptime gives peace of mind, reduces administrative follow-up, and keeps global teams focused on their work.

Regional support

Your payment provider should support local methods in the regions where your remote workers operate. This ensures workers can access funds without complications, whether through local banks, mobile wallets, or cash pickup points. Matching local preferences makes payments convenient and reliable, showing respect for workers’ needs. Regional compatibility also prevents unnecessary delays and demonstrates that your startup values its global team.

Customer preferences

Consider the payment methods your remote workers prefer. Some may favour direct bank transfers, others mobile wallets or platform-specific options. Catering to these preferences increases satisfaction, avoids frustration, and reduces time spent troubleshooting payment issues. Understanding what works best for your team ensures smooth operations, demonstrates attentiveness, and helps build strong, long-term relationships with remote talent across countries.

Fees

Evaluate all costs, including transaction fees, monthly charges, setup costs, and chargeback fees. Hidden or unexpected fees can reduce the amount your remote workers receive and affect budgeting. Comparing fees across platforms helps you choose the most cost-effective solution while maintaining reliability. Transparent costs show professionalism and help build trust with your team, ensuring that payments are fair, predictable, and worry-free.

Send international payments with Grey

Paying remote workers outside the US can be challenging if you don’t carefully consider speed, security, fees, and local support. Choosing the right platform makes all the difference for keeping your team motivated and confident. Grey stands out as a reliable solution that lets you send USD quickly, securely, and transparently. With fast transfers, multi-currency options, and easy withdrawals to local accounts, Grey helps you focus on your work while your team gets paid on time.

Sign up on Grey by creating an account with your email, verifying your identity, and setting up your business profile. You can also download the Grey app to handle international payouts from your phone wherever you work.

‍

Offshore bank accounts: What’s realistic in 2026

•

•

2 min read

For years, offshore bank accounts were seen as tools for billionaires and secretive wealth structures. In 2026, that perception is changing. Freelancers, remote founders, and global professionals earning across borders are exploring offshore options for practical reasons, currency flexibility, asset diversification, and smoother international transactions.

Offshore banking is not new, but the environment around it has evolved. Stricter compliance rules and global transparency standards mean it is no longer about secrecy, but structure and regulation. Unlike standard international accounts, offshore accounts are opened outside your country of residence and may offer broader multi-currency access. For freelancers, this can support better global income management. This article explains what is realistic and relevant in 2026.

Also read: Offshore accounts vs international bank accounts explained

Why offshore accounts make sense for global freelancers

As global work expands and borders matter less, offshore accounts are becoming a practical option for internationally minded freelancers and founders.

1. Investment opportunities

With more freelancers earning from global clients and building wealth independently, access to international investment options matters more. Some offshore accounts open the door to foreign funds and markets beyond your home country. If your income is global, aligning your investments with that reality can feel more strategic.

2. Asset protection

Economic uncertainty, policy shifts and currency swings are becoming more common. Keeping all your money in one country increases exposure to local risks. Holding part of your funds in a stable jurisdiction adds balance and resilience, especially when your income depends on cross-border work.

3. Managing foreign exchange fluctuations

Remote work means more people are paid in foreign currencies. Exchange rates move daily, and automatic conversions can quietly reduce earnings. Offshore accounts often let you hold funds and convert when rates are favourable, giving you more control over how much you actually keep.

4. Holding foreign currencies

Many freelancers now invoice in dollars, euros or pounds. Converting every payment immediately is not always efficient. Offshore structures can help you retain those currencies, making it easier to pay for tools, subscriptions, or travel abroad without incurring repeated conversion costs.

5. Doing business in multiple countries

It’s common to have clients in three or four countries at once. Traditional local accounts are not always built for that. Offshore accounts can simplify receiving and sending payments internationally, helping you operate more smoothly as your business naturally becomes more borderless.

Also read: The easiest way to open an offshore bank account online for free

The realities of offshore banking today

1. Stricter global transparency rules

‍Offshore banking is no longer about secrecy. Thanks to global agreements like the Common Reporting Standard (CRS), banks in many countries automatically share account information with tax authorities. So if you’re hoping to “hide” money abroad, that’s unrealistic in 2026. Offshore accounts are legal, but they’re transparent. The key is compliance, not concealment.

2. Higher compliance and documentation requirements

‍Opening an offshore account today feels a bit like applying for a mortgage. Banks want to know who you are, where your money comes from, your tax residency, and sometimes even your business model. Expect detailed KYC checks, proof of address, source-of-funds documents, and possibly interviews. It’s thorough, but that’s the new normal.

3. Minimum deposit thresholds vary widely

‍Some traditional private banks may require $50,000 or more just to get started. Others, especially digital or fintech-based options, may have little to no minimum balance. The reality in 2026 is that access depends on the institution. It’s less about geography and more about the type of bank you choose.

4. Offshore doesn’t mean tax-free

‍This is the biggest misconception. Where your account is located doesn’t determine whether you pay tax, your country of residence does. If you’re tax-resident somewhere, you usually must declare global income. An offshore account can help with currency diversification or international payments, but it doesn’t cancel your tax obligations. Always think compliance first.

Also read: Top offshore bank accounts US citizens should consider this year

How global workers can prepare for offshore banking

Global workers must adapt to stricter rules, digital banking, and international tax obligations. Preparing early ensures compliance, smoother payments, and career flexibility in 2026’s global landscape.

1. Understand compliance rules

Every country has its own financial and tax regulations. International reporting standards like CRS mean offshore accounts are visible to authorities. Knowing these rules keeps your finances legal, prevents penalties, and avoids costly surprises while working globally.

2. Keep documentation ready

Banks, employers, and regulators now expect thorough records. Identity, proof of income, tax residency, and source-of-funds documents are essential. Staying organised ensures smooth account openings, international transactions, and faster approvals for any global work opportunity.

3. Use digital banking tools

Digital banks and fintech solutions make international payments faster, cheaper, and easier to manage. Learning these tools helps you handle multiple currencies, track transactions securely, and stay efficient while working across borders in 2026’s remote-friendly environment.

4. Plan tax responsibilities

Offshore accounts don’t remove your tax obligations. You must declare worldwide income based on residency rules. Planning avoids fines, audits, and surprises, while allowing you to optimise finances and stay fully compliant with global regulations.

LDMAG1

Managing global payment seamlessly

As work becomes increasingly global, managing payments across borders can be challenging for freelancers, remote workers, and business owners. Offshore accounts offer practical solutions, and Grey stands out as a reliable option. With Grey, you can hold multiple currencies, benefit from competitive conversion rates, and even get a virtual card for online shopping.

Whether you’re receiving payments from clients abroad or making international purchases, Grey simplifies the process. To start, simply sign up on the website or download the app on your mobile device and take control of your global finances.

‍

Grey virtual card vs Chipper, Geegpay, and others: 2026 comparison

•

•

2 min read

Different virtual cards work differently depending on how you spend, where you shop, and which currencies you use. Some excel at simple travel spending, others at multi-currency holding. Some support crypto, others don’t. Understanding the real differences helps you pick which one works for you.

Today, I’m comparing the Grey card with six other well-known virtual card options, just so you know which one works best for you.

1. Wise multi-currency card

If you’ve ever needed a card that is like a multi-currency wallet first and a spending card, Wise probably fits that bill. Wise is widely used as a borderless account with a card that lets you tap into more than 50 currencies and spend internationally at transparent exchange rates.

For many global workers and travellers, such simplicity is appealing. You get the real exchange rate plus a small, clear fee. There are generally no hidden surprises, and you can hold currencies like USD, EUR, or GBP in one place.

Wise also doesn’t support crypto balances, so if you’re someone who keeps part of your funds in digital assets and wants to spend crypto, your Wise card won’t help.

People who want to hold and spend multiple currencies with clear exchange pricing, especially for everyday purchases and travel, will love the Wise card.

Also read: How to shop in the US or Europe with your Grey card

2. Revolut card

Revolut is one of the most talked-about fintech platforms in the world, and its card ecosystem reflects that breadth. You can have both virtual and physical cards, generate disposable virtual cards for added security, and even manage budgeting, investments, and crypto trading all in one app.

It ticks many boxes: multi-currency support, budgeting tools, and virtual card creation. However, the complexity of features can become a hurdle, especially when key perks are tucked behind paid tiers.

Revolut is strong as part of a broader lifestyle finance app, especially for travellers and users who want added perks like travel insurance, purchase protection, and trip disruption coverage, which are included in higher-tier plans such as Premium, Metal, or Ultra. However, these benefits depend on subscription level and eligibility requirements, and coverage is provided through third-party insurers rather than built directly into the card experience.

Its virtual cards can still face issues on international platforms, and the way it converts currencies, including weekend markups, adds a layer of unpredictability for some users.

3. Payoneer card

Payoneer is a name many freelancers, online sellers, and international businesses know quite well. Its card, especially the virtual prepaid card, is excellent for receiving payments from global marketplaces, handling international transfers, and covering business expenses in multiple currencies.

However, many users report sudden card blocks, limited personal support, and slow resolution times, which can be frustrating when you’re trying to pay for everyday subscriptions or online purchases.

In many regions, Payoneer is ideal for business payouts and marketplace earnings; however, it may not be the best option if you require a card for personal multi-currency spending or flexible international use.

Freelancers and businesses requiring comprehensive currency support with global payouts, especially via marketplaces, will appreciate the Payoneer card.

Also read: How to pay online and in stores worldwide with your phone

4. N26 Card

N26 operates as a digital bank primarily across the EU and EEA. Its cards, both physical and virtual, are built around simplicity, with no foreign transaction fees for many currencies and straightforward Mastercard exchange rates.

It works well for everyday spending both within and outside the Eurozone, and virtual cards can be issued quickly as part of the account opening process.

The big limitation, a practical one, is its availability. N26’s services were pulled back from the U.S. and some other markets in recent years, and it remains focused on European customers.

So if you travel frequently within Europe or spend in EUR, N26 cards can be a solid choice. But outside that context, it’s less flexible, especially for global needs.

LDMAG1

5. Crypto-linked cards

Crypto cards deserve their own mention. Cards like the Coinbase Card and Crypto.com Visa Card allow you to spend cryptocurrency by instantly converting it to fiat at the point of sale. These are especially interesting for people who live or earn in digital assets and want to use them without extra conversion steps.

For example, Binance’s card (in regions where it is still supported) offers significant cashback rewards in BNB, and Coinbase lets you spend multiple crypto assets directly, with rewards in crypto.

The downside is that these cards often tie you into a specific exchange ecosystem, may carry higher fees for some transactions, and their rewards are typically token-based — valuable if you’re bullish on crypto, less so if you’re not.

I’ll recommend these cards for crypto holders who want to spend digital assets with conversion at checkout and enjoy token rewards.

6. Traditional bank virtual cards

There’s a whole category of virtual cards issued by traditional or app-based banks, like Monzo (UK), Starling (UK), or wallet-front cards like Curve.

These are solid for everyday use, especially in their home markets, and often integrate well with Apple Pay/Google Pay. However, international currency support varies widely; some have foreign transaction fees, others rely on slower underlying banking rails, and they’re sometimes limited in where they’ll work for recurring payments or certain ad platforms.

For many users, these cards are excellent backups or complementary payment methods. But if your life or work relies on consistent, global spending, their limitations become noticeable.

7. Grey card offers a more flexible virtual global spending experience

By now, it should be clear: not all virtual cards are the same. Some are designed for holding money, others for daily banking, and others still for specific ecosystems.

Grey’s approach sits in a different space from the others above. Your card works across fiat (USD, EUR, GBP, local currency) and stablecoins (USDC), eliminating the need to get an extra crypto card. Your Grey card automatically pulls funds from your available balances in the following order: USD, USDC, and then the next highest available balance.

You can also create multiple cards for different purposes, such as travel, subscriptions, personal, and business. Still, each card will work seamlessly without requiring you to select which balance to spend from. We built the Grey virtual card for people who:

  • Spend in multiple currencies regularly
  • Want predictable outcomes at checkout
  • Value clear messaging and control
  • Need support for both fiat and crypto balances

Instead of requiring top-ups or rigid currency conversion steps, your Grey card automatically draws from your available balances, making spending across fiat and stablecoin currencies effortless.

Many of the other options we’ve discussed above are great in their contexts. However, each has trade-offs that make it difficult to be everything to everyone.

Also read: How to budget in foreign currencies using the Grey card

So, which card is right for you?

There’s no single answer, but here’s a quick way to think about it:

  • If you want clear, no-nonsense multi-currency holding and spending, Wise or N26 are strong choices.
  • If you’re looking for a financial super app with perks, Revolut is a great fit.
  • If you earn or spend in crypto and enjoy token rewards, crypto cards like Coinbase or Crypto.com are worth exploring.
  • If you want a card that automatically draws from different balances, supports multiple cards, and makes international or multi-currency spending predictable globally, we built Grey for your lifestyle.

Different cards shine in various life scenarios. The key is knowing which trade-offs matter to you, and how your day-to-day spending looks.

Choose with clarity, and let your card work for you, not the other way around. Create your Grey visa card and enjoy a smoother, more inclusive, and more predictable global spending experience.

‍

How to shop in the US or Europe with your Grey card

•

•

2 min read

A few months ago, I was eyeing a pair of sneakers on a US website for weeks. Then the store started running sales and I decided to buy them (hashtag #YOLO), but my bank card declined the payment.

Not once, not twice… but four times!.

The same card that worked perfectly in Nigeria where I live, and the same details I’d used for years. I tried to get another card, but by then, sales had ended, and the sneakers were out of stock. It was annoying, but I just had to accept my L.

If you’ve ever tried to shop internationally, on sites like ASOS UK, Amazon US, Zara EU, or even the Apple Store, you may already be familiar with this pain. Sometimes the website rejects your card. Sometimes your bank blocks the transaction. Sometimes the currency conversion takes too long, and the payment times out.

It shouldn’t be this difficult to buy something online in big 2026… yet for many people, it still is.

But if you use a Grey card, you'll eliminate the uncertainty of thoughts like, “Will this payment go through?”, and transform your international shopping into a simple and predictable process.

Why shopping abroad is often frustrating

Shopping from US or European stores usually comes with these hurdles:

1. Many foreign merchants decline local cards

Some US/UK online stores automatically reject certain African-issued cards, even if you have more than enough balance.

2. Stores bill strictly in USD, GBP, or EUR

If your card requires manual currency conversion, it can cause payment delays that may result in declines.

3. Banks block “suspicious” international transactions

This usually happens when the merchant is unfamiliar.

4. Conversion errors and hidden fees

Some cards convert long after the purchase, leading to surprises on your statement.

These problems are common, but they’re also exactly what Grey card is built to avoid.

How your Grey card makes shopping internationally easy

Smart spending across multiple currencies and USDC

Your Grey card doesn’t require you to pick or switch wallets before paying. Instead, it automatically spends from your balances. Your USD account is debited first; if that’s empty, your USDC, and then the highest of your remaining balances.

This means your payment goes through as long as you have funds available in your account, without requiring you to consider currencies at checkout.

Works across major US and European stores

Your Grey card is an international spend card, so you can pay at 150 million merchants worldwide.

Use Apple Pay and Google Pay

For stores that support mobile wallets, you can simply add your Grey Visa card to Apple Pay or Google Pay. This is more secure and makes for much faster checkouts.

Create multiple cards for better organisation

If you shop frequently or mix personal and business purchases, you can:

  • Use one card for personal shopping
  • another for business imports
  • another for gift purchases

It keeps your spending clean and easy to track.

Freeze and unfreeze anytime

You can always freeze your cards to control your spending.

Better protection for online transactions

You receive real-time notifications, card controls, and instant limits - everything you need for peace of mind when buying from foreign sites.

LDMAG1

How to shop in the US or Europe with your Grey card

1. Request your Grey visa card

Create a Grey account and go to the cards section of your Grey app to request a Grey card for $5.

2. Add your card to the store’s checkout

Enter your card details or simply pay through Apple Pay/Google Pay.

3. Make your purchase normally

Shipping, duties, and taxes will be displayed as they are for every other international shopper.

4. Track everything in your Grey app

Every charge, refund, or verification appears instantly, so there are no surprises later.

Tips for smarter international shopping

  • Use a separate card for business or bulk purchases so you can easily track expenses.
  • Keep a bit extra in your wallet for shipping fees and taxes.
  • Use Apple Pay/Google Pay when available. It’s the most seamless way to tap and pay, and also supports contactless payments.

Shopping abroad doesn’t have to be stressful

Your Grey card helps you shop with confidence. There are no random declines or conversion drama. Ahead of your next international purchase, you can create your Grey card and enjoy a smoother, more predictable shopping experience.

‍

Arrow (up)

Back to top