<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/save-money-for-a-trip#article","headline":"How to save for a trip when you get paid in different currencies","description":"Saving for a trip when you earn in different currencies? See how much to set aside and how to avoid conversion fees, then open a Travel Pouch to start.","inLanguage":"en","url":"https://grey.co/blog/save-money-for-a-trip","mainEntityOfPage":{"@id":"https://grey.co/blog/save-money-for-a-trip#webpage"},"datePublished":"2026-08-31T15:09:21.416Z","dateModified":"2026-09-27T02:23:28.917Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/save-money-for-a-trip#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a959908eb9f1b617c638bee_How%20to%20Save%20for%20a%20Trip%20When%20You%20Get%20Paid%20in%20Different%20Currencies-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a959908eb9f1b617c638bee_How%20to%20Save%20for%20a%20Trip%20When%20You%20Get%20Paid%20in%20Different%20Currencies-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/save-money-for-a-trip#webpage","url":"https://grey.co/blog/save-money-for-a-trip","name":"How to Save Money for a Trip and Avoid Fees | Grey","description":"Saving for a trip when you earn in different currencies? See how much to set aside and how to avoid conversion fees, then open a Travel Pouch to start.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/save-money-for-a-trip#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/save-money-for-a-trip#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/save-money-for-a-trip#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to save for a trip when you get paid in different currencies","item":"https://grey.co/blog/save-money-for-a-trip"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/save-money-for-a-trip#faq","mainEntity":[{"@type":"Question","name":"How much should I save for a trip?","acceptedAnswer":{"@type":"Answer","text":"Set your total budget by pricing out flights and accommodation as fixed costs, then estimating daily spending based on your destination. Add 10 to 15% as a buffer. Divide the total by the number of months until you travel to get your monthly savings target. A two-week trip to Southeast Asia on a mid-range budget might require $2,000 to $3,000 total; a similar trip to Western Europe or Japan typically costs $3,500 to $5,000 or more. For multi-currency earners, budget in the currency you'll spend, not the currency you earn, to avoid exchange rate surprises at the end."}},{"@type":"Question","name":"How far in advance should I start saving?","acceptedAnswer":{"@type":"Answer","text":"Six to twelve months is a reasonable window for most trips. The earlier you start, the smaller each monthly contribution needs to be. For multi-currency earners, starting earlier also gives you more flexibility on when to convert: if you're saving in a different currency from your income, a longer saving period means more opportunities to convert at a favourable rate rather than being forced to convert at whatever rate exists the week before departure."}},{"@type":"Question","name":"Should I save in my home currency or the destination currency?","acceptedAnswer":{"@type":"Answer","text":"For multi-currency earners, the best answer is to save in the currency you'll spend, or in the currency you earn that requires the fewest conversions to get there. If you earn in EUR and you're travelling to Europe, save in EUR and skip the conversion entirely. If you earn in USD and you're travelling to Japan, save in USD and convert to JPY shortly before you travel. Every unnecessary currency conversion costs a margin. The fewer conversions between your income and your travel spending, the more you keep."}},{"@type":"Question","name":"How do I avoid losing money to conversion when I earn in multiple currencies?","acceptedAnswer":{"@type":"Answer","text":"Use a multi-currency account to hold earnings in their original currency rather than converting everything to a home currency on receipt. When you do convert, use a provider with a transparent, low margin rather than a traditional bank rate. Grey's conversion fee is 1%, capped at $6, with the rate shown before you confirm. Choose a travel fund denominated in the currency you'll spend so you only convert once, at the right time, rather than converting repeatedly throughout the saving period."}},{"@type":"Question","name":"What is the easiest way to save for a trip automatically when I earn in different currencies?","acceptedAnswer":{"@type":"Answer","text":"If you can, set up a recurring transfer to a dedicated travel fund in the currency your trip requires, timed to run on the same date each month. For multi-currency earners, the key is choosing which currency balances the contribution before you set up the automation, so the transfer happens cleanly without a monthly decision. Grey's Pouches feature lets you create a named travel fund in a specific currency and contribute from your Grey balance, separating your travel savings from everyday spending and preventing accidental dipping."}}]}] </script>

How to save for a trip when you get paid in different currencies

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

Let’s start with a question. If you earn in one currency and spend in another, which currency do you save in, when do you convert, and how do you make sure the money you set aside today is worth what you expect when you arrive?

For example, there’s a freelancer billing clients in USD and euros, another remote worker paid in GBP while living abroad, and an NRI receiving income from multiple countries: for all of these people, the standard advice of “open a savings account and set up a standing order” doesn’t quite fit. The currency question comes first. You can do everything else correctly, save consistently, hit your target number, and still arrive with less purchasing power than you planned because conversion happened at the wrong time, through the wrong provider, or in the wrong direction.

In this guide, I cover how to save money for a trip when your income comes in more than one currency: how to set a realistic target, which currency to save in, why the timing of conversion matters, and the simplest method to automate savings so the money builds without friction every month.

How much should you save for a trip?

Before the currency question, you need a number. While a rough estimate or a figure borrowed from someone on a different budget can be a good starting point, a number based on the actual costs of your specific trip will be more helpful.

A useful working framework has four components: flights, accommodation, daily spending, and a buffer.

Flights and accommodation are fixed costs you can price out before you commit to saving. Try to use real quotes for your travel dates and destination, not averages. Daily spending varies more, but most destinations have reliable benchmark figures: what a meal costs at a local restaurant, what transport between sites runs to, and what attractions charge for entry. For a detailed look at what a specific trip actually costs, see our guide on how much a trip really costs, which breaks down real expenses by category.

Once you have the total, here’s a simple calculation you can use.

Target ÷ months to go = monthly savings target

If you want to spend €3,000 on a three-week trip to Europe and you have 10 months until you leave, you need to set aside €300 per month. If you can only manage €200 per month, you either leave in 15 months or reduce the budget. The formula is the same regardless of how many currencies you earn in.

Add a 10-15% buffer to your estimated total. Prices change, exchange rates move, and unexpected costs appear on almost every trip. A buffer ensures that a surprise doesn’t derail the plan.

Once you have your target and your monthly contribution figure, the next question is which currency to save in.

For help building out the rest of your trip plan, see our guide on how to plan a trip.

Why converting your money too early costs you

For someone paid in different currencies, the temptation is to consolidate everything into one home currency and then save in that. It’s tidier for sure, but it can cost you if you convert at the wrong moment.

When you convert currency, you don’t receive the mid-market rate (the rate you see on Google) instead, you receive a rate that includes the provider’s margin, typically 2 to 4% at a traditional bank. On a €3,000 travel budget converted at a 3% margin, that’s €90 that never reaches your travel fund. If you make that conversion nine months before you travel, you’ve locked in today’s rate and paid the margin, with no ability to benefit from any movement in the exchange rate between now and your departure.

For multi-currency earners, the risk has an additional layer: converting from currency A to your home currency, and then converting again from your home currency to the destination currency. Every hop carries a margin. The fewer the conversions between your income and your travel spending, the more you keep.

The practical approach is to save directly in the currency you will spend, or in a stable currency closely tied to it, and convert only what you need closer to travel. If you earn in USD and you're travelling to Japan, saving in USD and converting to JPY shortly before departure is more efficient than converting USD to your home currency on receipt and then converting again before the trip. If you earn in EUR and you’re travelling to Europe, saving in EUR eliminates the conversion problem entirely. The balance in your travel fund represents exactly what you’ll have to spend.

For people with multi-currency income, this means using a multi-currency account where different currency earnings can sit in their original currency until they’re ready to convert. Spending abroad with the Grey card, directly from your travel currency balance, means the money you saved arrives at your destination as spending power, not as a smaller amount after a last-minute kiosk conversion.

How to save when you are paid in different currencies

For people with income across more than one currency, here is a method that accounts for the specific challenge.

  1. Pick the currency your trip is denominated in. If your destination uses a major currency (EUR, USD, GBP, JPY), saving in that currency from the start removes a conversion step and protects you from exchange-rate movements during the savings period. If your destination uses a less widely held currency, saving in a major currency and converting shortly before travel is more practical.
  2. Decide which income stream funds the trip. If you earn in multiple currencies, allocate the contribution to the stream that's already in the right currency or to the stream where conversion will cost the least. If you bill US clients in USD and you’re saving for a trip to the US, contributions from USD income go directly to the travel fund without any conversion cost.
  3. Set a specific numerical target. Not “roughly €3,000” but exactly €3,000, or whatever your trip budget requires. A specific target lets you track progress clearly and know exactly when you’ve reached the goal.
  4. Automate a fixed contribution each month. Automation is the most effective saving habit available to anyone with irregular or multi-currency income, precisely because it removes the month-by-month decision. Set a recurring transfer or allocation from whichever account or currency balance you’re funding the trip from, on the same date each month, and don’t adjust it unless your income changes significantly.
  5. Direct windfalls straight to the trip fund. Any bonus, unexpected client payment in a currency that would otherwise sit idle, or a tax refund should go directly to the travel fund before it can be absorbed into general spending. Even one or two windfall contributions per year can meaningfully shorten the time to your target.
  6. Review the target if plans or exchange rates change significantly. If flights get more expensive, if your travel dates shift, or if the exchange rate between your earning and spending currencies changes substantially, update your target and contribution to reflect the new reality. A savings plan that reflects the current version of your trip is more useful than one built on early estimates.

The easiest way to save for a trip: automate it

The most reliable saving method is the one that requires the least ongoing willpower. The problem of deciding which currency to contribute, in what amount, and to which account, is enough to delay or derail contributions that a single-currency saver would complete quickly.

Automation removes that friction. Just set it up so the contribution is made on payday, in the right currency, to the right balance, before the money can be spent elsewhere or consumed by general living costs.

Goal-based savings tools, where you name a goal, set a target amount, and track progress toward it, add a practical layer beyond simple automation. When your travel fund is clearly labelled, has a target number attached to it, and is separate from your everyday spending balance, you’re less likely to dip into it for non-trip expenses.

For multi-currency earners, the most useful version of this is a goal-based balance in the currency required for the trip, rather than a generic savings account in the home currency that must be converted before departure. Saving €3,000 in a euro-denominated travel fund that you contribute to directly from euro client income means the balance represents exactly what you have to spend, without a conversion step at the end.

How to create a Travel Pouch in Grey

With Grey, you can create a travel Pouch to set money aside, set a target amount in the currency of your choice, and contribute toward it from your Grey balance. For a multi-currency earner, this means you can create a travel fund in EUR, GBP, or USD, whichever currency your trip requires, labelled with the trip it’s for, and tracking progress visually toward the target.

Here’s how to set one up:

Step one:
Open the Grey app, go to “Grow” and select the option to “Create a Pouch”.

Step two:
Select “Start saving” and choose the currency you want to save in.

Step three:
Give your pouch a name, for example, “Paris summer,” and select what it’s for, in this case, “Travel”. You can also enable round-ups, so extra change from every card spend goes to the pouch.

Step four:
Make your first contribution. Transfer a minimum initial amount of $10, €10, or £10 from your Grey balance in the relevant currency.

Open a Travel Pouch, and set money aside today.

Frequently asked questions on how to save for a trip when you get paid in different currencies

How much should I save for a trip?

Set your total budget by pricing out flights and accommodation as fixed costs, then estimating daily spending based on your destination. Add 10 to 15% as a buffer. Divide the total by the number of months until you travel to get your monthly savings target. A two-week trip to Southeast Asia on a mid-range budget might require $2,000 to $3,000 total; a similar trip to Western Europe or Japan typically costs $3,500 to $5,000 or more. For multi-currency earners, budget in the currency you'll spend, not the currency you earn, to avoid exchange rate surprises at the end.

How far in advance should I start saving?

Six to twelve months is a reasonable window for most trips. The earlier you start, the smaller each monthly contribution needs to be. For multi-currency earners, starting earlier also gives you more flexibility on when to convert: if you're saving in a different currency from your income, a longer saving period means more opportunities to convert at a favourable rate rather than being forced to convert at whatever rate exists the week before departure.

Should I save in my home currency or the destination currency?

For multi-currency earners, the best answer is to save in the currency you'll spend, or in the currency you earn that requires the fewest conversions to get there. If you earn in EUR and you're travelling to Europe, save in EUR and skip the conversion entirely. If you earn in USD and you're travelling to Japan, save in USD and convert to JPY shortly before you travel. Every unnecessary currency conversion costs a margin. The fewer conversions between your income and your travel spending, the more you keep.

How do I avoid losing money to conversion when I earn in multiple currencies?

Use a multi-currency account to hold earnings in their original currency rather than converting everything to a home currency on receipt. When you do convert, use a provider with a transparent, low margin rather than a traditional bank rate. Grey's conversion fee is 1%, capped at $6, with the rate shown before you confirm. Choose a travel fund denominated in the currency you'll spend so you only convert once, at the right time, rather than converting repeatedly throughout the saving period.

What is the easiest way to save for a trip automatically when I earn in different currencies?

If you can, set up a recurring transfer to a dedicated travel fund in the currency your trip requires, timed to run on the same date each month. For multi-currency earners, the key is choosing which currency balances the contribution before you set up the automation, so the transfer happens cleanly without a monthly decision. Grey's Pouches feature lets you create a named travel fund in a specific currency and contribute from your Grey balance, separating your travel savings from everyday spending and preventing accidental dipping.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

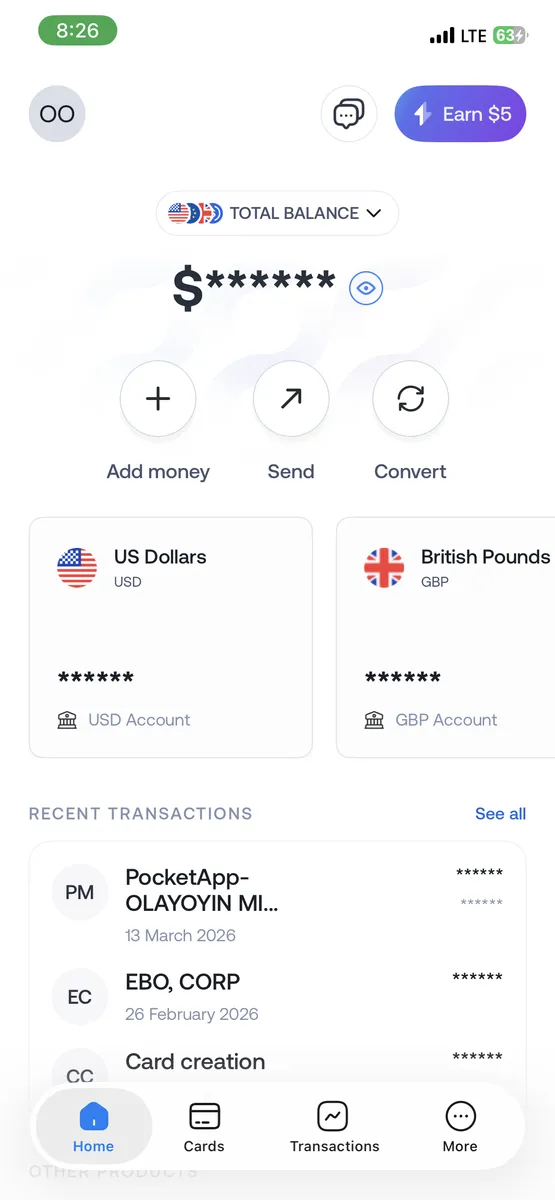
  1. Log in to your Grey account.
    ‍
  2. Click “Send”.
Send Canadian dollars with Grey

‍

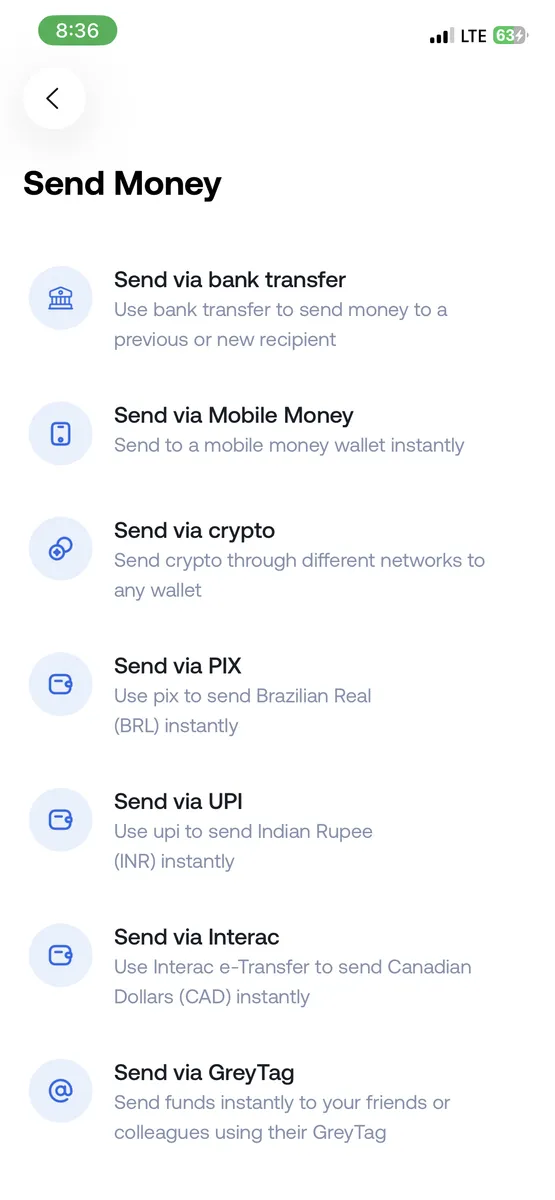
2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

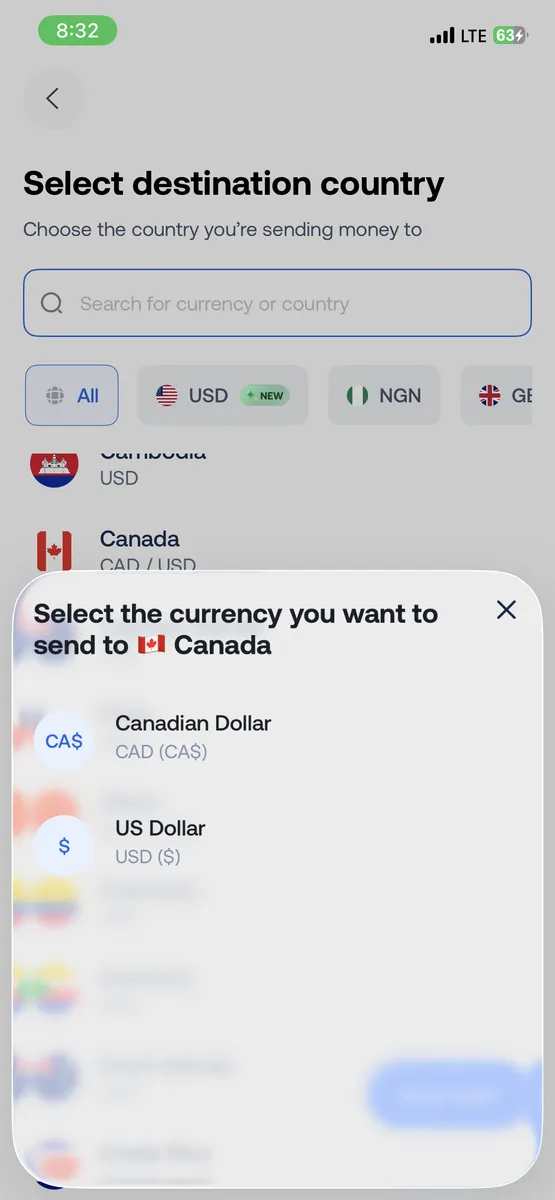
3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

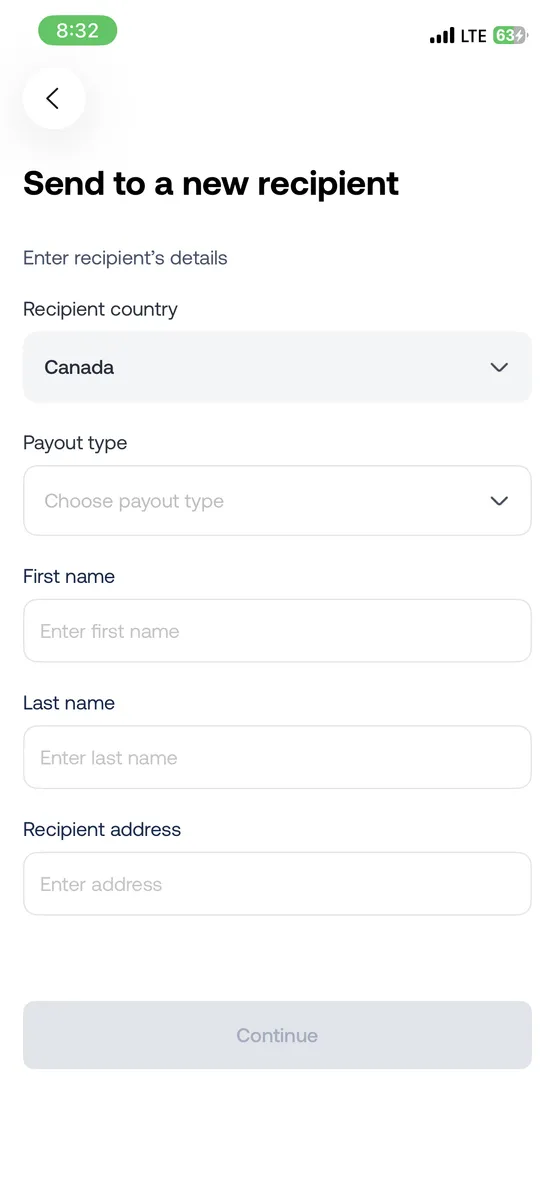
4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

Top activities for tourists in Zanzibar in 2024

•

•

2 min read

Zanzibar is a group of islands, i.e., an archipelago, located off the coast of Tanzania in East Africa. It's a melting pot of languages, cuisines, and cultures and home to some of the most beautiful beaches in the world, making it a popular tourist spot. Beyond its beaches, it’s also a top destination for history enthusiasts, nature lovers, and adventure seekers.

In this post, we’ll curate a list of activities to ensure your trip to Zanzibar is memorable.

But first, when’s the best time to visit Zanzibar?

The best time to visit is during the dry season, from June to October. This is also the peak safari season in Tanzania, which makes Zanzibar a popular post-safari destination choice.

January and March are also great times to visit because the beaches have peak diving conditions, and you can explore the lagoons and coral reefs in clear waters.

Now that you know when to visit, let’s look at some must-do activities in Zanzibar.

Top Activities in Zanzibar

Go on a snorkeling tour.

You can kickstart your trip by taking a snorkeling tour to explore the stunning coral reefs and diverse marine life, such as lionfish, sting rays, sea turtles, and dolphins around the archipelago islands.

snorkelling in Zanzibar

This 5-hour tour is usually conducted at Mnemba island because of the high visibility of its water. You’ll be accompanied by a professional guide providing safety instructions and insights while on the tour.

A trip to Stone Town:

Stone Town is the historic heart of Zanzibar City and a UNESCO World Heritage Site. The Arabs built this town during the slave trade, and it’s renowned for its well-preserved historic architecture. Some of the things you can do in Stone Town include:

  • Visit the slave monument
  • Visit the Old Fort
  • Visit the night market
  • Visit the Forodhani Gardens
  • Visit the Hamamni Persian Baths

A guided tour is the best way to familiarize yourself with Stone Town and its history.

Go on a spice tour:

Zanzibar is often called “Spice Island” due to its nutmeg, pepper, and cinnamon production. During the spice tour, you’ll learn the islands’ relationship with spices and how they are grown, harvested, and prepared to make medicines and food.

spice tour Zanzibar

Kitesurf:

Kitesurfing is a popular activity for tourists in Zanzibar. Paje, a small village on the southeastern coast of Unguja island — the main island of the Zanzibar archipelago — is said to be one of the best places in the world to kitesurf.

kite surfing Zanzibar

This is primarily due to its excellent wind conditions and relatively calm waters, allowing beginners to learn and improve. You can also get a 3-hour kitesurfing lesson for €110.

Nature walk in the Jozani forest:

This is one activity you can’t miss out on while in Zanzibar. The Jozani forest is a protected area in the center-eastern region of Unguja island, and it’s the only home to the endangered Red Colobus Monkey.

Jozani forest Zanzibar

It also hosts a variety of wildlife, such as leopards, lemurs, civet cats, pygmy antelopes, and bush babies.

You can take a guided tour to explore this forest; it usually takes an hour. This would also allow you to learn about the different types of wildlife and their medicinal uses.

Dine at The Rock:

The Rock is a famous picturesque restaurant on a rock formation near the beach.

Aside from its stunning ocean view and intimate setting, this restaurant is famous in Zanzibar for its excellent food, making it a tourist favorite. Most seafood is freshly caught from the reefs near the restaurant.

Relax at the beach:

This list would be incomplete without this. Zanzibar is famous for its white sandy beaches and clear blue waters, making it the perfect place to enjoy a beach holiday.

Beach Zanzibar

You can soak in the scenery, dip in the ocean, or even swim with dolphins.

Wrapping up

Traveling to Zanzibar can be a great way to unwind and learn about different cultures in an immersive way. And as a tourist, the last thing you want to worry about is currency exchange, which is why Grey has you covered.

We’ve made it easy for you to convert your money to Tanzanian shillings (TZS) so you can focus on making memories without the stress of navigating currency exchanges. Get started today by opening a Grey account.

‍

The best summer holiday destinations in the Philippines

•

•

2 min read

Have you ever dreamed of escaping to a place where turquoise waters meet powdery white sand, where lush mountains rise in the distance, and every sunset looks like it was painted just for you? That’s the Philippines, a country made up of more than 7,600 islands, each with its own charm. Every time I visit, I find something new to fall in love with.

Whether you’re craving adventure, a quiet beach retreat, or a deep dive into rich cultural experiences, the Philippines has something for you. And let’s not forget the warm hospitality — Filipinos are known for their friendliness, making visitors feel right at home from the moment they arrive.

If you’re thinking about a summer holiday in the Philippines, here are some of the best places to visit that will make your trip unforgettable.

Best places to visit in the Philippines for summer holidays

From world-famous beaches to hidden gems, here are some of my top must-visit places for an unforgettable summer escape:

1. Boracay – The island of white sand beaches

__wf_reserved_inherit

Boracay is one of those places that feels like a postcard come to life. The powdery white sand is so soft it almost feels unreal, and the sunsets? Absolutely breathtaking. White Beach is where most of the action happens, but depending on what you’re in the mood for, you can pick your vibe:

  • Station 1 – Home to upscale resorts and the widest stretch of fine white sand, ideal for a quieter and more luxurious experience.
  • Station 2 – The heart of Boracay’s action, where shopping, restaurants, and nightlife come to life.
  • Station 3 – A more peaceful area with budget-friendly accommodations and a laid-back vibe.

Beyond White Beach, you will love spending time at Puka Shell Beach for a quieter escape, Bulabog Beach for kitesurfing, and Diniwid Beach for a cosy sunset spot away from the crowds.

Must-do experiences in Boracay:

  • Try parasailing, snorkelling, or paddleboarding in the turquoise waters.
  • Take a sunset paraw (local sailboat) ride — it’s pure magic.
  • If you’re feeling adventurous, go cliff diving at Ariel’s Point.
  • Experience Boracay’s nightlife, where fire dancers and beachside cocktails set the mood.

Also read: How to apply for a digital nomad visa in the Philippines

2. Palawan – A paradise of lagoons and limestone cliffs

__wf_reserved_inherit

If you ask me about my happy place, it’s Palawan. It’s where you find those impossibly blue lagoons, towering limestone cliffs, and hidden beaches straight out of a travel magazine. Every corner of Palawan feels untouched and breathtaking.

Here’s where you should go:

  • El Nido – Stunning lagoons, dramatic cliffs, and secret beaches. Island hopping here is a must.
  • Coron – A diver’s paradise with crystal-clear lakes and World War II shipwrecks.
  • Puerto Princesa – Home to the Puerto Princesa Underground River, one of the New Seven Wonders of Nature.
  • Port Barton – A quieter, more relaxed alternative to El Nido, with incredible island-hopping adventures.

What makes Palawan special?

  • Snorkelling in coral-filled waters and swimming alongside sea turtles.
  • Kayaking through hidden lagoons and mangroves.
  • Exploring remote islands where you’ll feel like the only person in the world.
  • Watching the sunset from a secluded beach, surrounded by nothing but nature.

3. Cebu – A mix of history and adventure

__wf_reserved_inherit

Cebu has it all — history, adventure, and some of the best beaches in the Philippines. One day, you could be exploring Spanish-era churches, and the next, swimming with whale sharks or chasing waterfalls.

Places you can’t miss in Cebu:

  • Cebu City – Visit Magellan’s Cross, the Basilica Minore del Santo Niño, and the Taoist Temple.
  • Oslob – Swim with the gentle giants — whale sharks (don’t worry, it’s safe).
  • Moalboal – Witness the incredible sardine run and dive into a world of colourful corals.
  • Kawasan Falls – Go canyoneering through turquoise waterfalls and jungle trails.
  • Bantayan & Malapascua Islands – Tranquil, beautiful, and perfect for escaping the crowds.

If you love food, don’t leave Cebu without trying lechon (roast pig) and the famous dried mangoes.

You may also like: How to open US and UK bank accounts in the Philippines

4. Siargao – The laid-back island escape

__wf_reserved_inherit

Siargao is my ultimate chill-out spot. It’s known as the surfing capital of the Philippines, but even if you don’t surf, you’ll fall in love with its island vibes. Palm trees line the roads, fresh coconut stalls are everywhere, and life moves at a slow, blissful pace.

Siargao highlights:

  • Cloud 9 – The world-famous surf break, even if you’re just there to watch.
  • Sugba Lagoon – Perfect for paddleboarding and kayaking in emerald-green waters.
  • Magpupungko Rock Pools – Crystal-clear tidal pools that appear during low tide.
  • Island hopping – Naked Island, Daku Island, and Guyam Island are must-visits.
  • Sohoton Cove – Swim with stingless jellyfish in a magical lagoon.

Why Siargao stole my heart:

  • The sunrises and sunsets here are something else.
  • The food scene is incredible — smoothie bowls, fresh seafood, and local delicacies.
  • Riding a motorbike around the island is the best way to explore hidden beaches.
  • The island’s laid-back energy makes it impossible to leave.

5. Bohol – Home to the Chocolate Hills

__wf_reserved_inherit

Bohol is one of those destinations that surprises you. It has one of the most unique landscapes in the world — the Chocolate Hills — but that’s just the beginning.

Must-see places in Bohol:

  • Chocolate Hills – Over 1,200 perfectly rounded hills that turn brown in the dry season.
  • Tarsier Conservation Area – Get up close (but not too close!) to the adorable, wide-eyed tarsiers.
  • Loboc River Cruise – Enjoy a peaceful lunch while floating down a jungle river.
  • Panglao Island – White-sand beaches, world-class diving, and snorkelling with sea turtles.
  • Hinagdanan Cave – An underground lagoon where sunlight creates a magical glow.

Bohol is for you if:

  • You love nature and wildlife.
  • You want a mix of adventure, culture, and relaxation.
  • You enjoy exploring places that feel untouched by mass tourism.

Also read: Top 8 digital nomad cities for remote workers in Southeast Asia

The best way to manage payments while travelling to the Philippines

One thing I’ve learned while travelling is that managing money can be tricky, especially when dealing with currency exchange and international transactions. That’s where Grey makes life easier — you can send, receive, and exchange money in multiple currencies without the crazy fees traditional banks charge. It’s a game-changer when you’re travelling.

Make your summer travel to the Philippines stress-free with Grey

So, if the Philippines is on your summer bucket list (which it absolutely should be!), get ready for the adventure of a lifetime. Pack your bags, explore these incredible destinations, and let Grey handle your international payments seamlessly.

Sign up for a Grey account today, or download the app to get started.

‍

Convert pounds to naira at the best rates online

•

•

2 min read

When converting British pounds (GBP) to Nigerian naira (NGN) through traditional banks, hidden fees, slow transfers, and poor exchange rates are common. This can be annoying because, in truth, every penny matters. With traditional banks and transfer services, you often lose a chunk of your earnings before the money even lands in your account.

Thankfully, there’s a faster, easier, and more cost-effective way. With Grey, you can convert GBP to NGN at competitive rates and without unnecessary delays. In this guide, I’ll show you exactly how to do that and why Grey is the best choice for currency exchange in Nigeria.

Common challenges when converting GBP to NGN

Converting British pounds in Nigeria isn’t always straightforward. Many users face:

  • Unfavourable exchange rates: Banks and transfer providers often mark up rates significantly.
  • Hidden fees: Extra charges can quickly eat into your funds.
  • Slow transfers: Traditional banking systems are notorious for long processing times.
  • Limited flexibility: Some platforms restrict how or when you can access your funds.

Grey eliminates these pain points, making it possible to convert and withdraw funds without hassle.

Also read: The easiest way to open an offshore bank account online for free

How to open a GBP account in Nigeria with Grey

Opening a virtual GBP account used to involve paperwork and international trips. With Grey, the process takes just minutes:

  1. Sign up for a Grey account: Head to Grey.co or download the app to get started.
  2. Verify your identity: Upload a valid ID and complete a quick KYC (Know Your Customer) process.
  3. Access your GBP account: Once verified, you’ll get a virtual UK account with all the details you need.
  4. Receive payments: Share your account number with UK clients, family, or platforms like Payoneer and Amazon.

You can start receiving GBP payments instantly without touching a traditional bank.

Also read: High-paying remote jobs you can land without experience

How to convert GBP to Naira using Grey

Once your funds hit your GBP account on Grey, converting them to naira is seamless:

  1. Log into your Grey account via web or app.
  2. Go to your GBP wallet and tap “Convert”.
  3. Enter the amount you want to exchange.
  4. View the real-time exchange rate and confirm the transaction.
  5. Converted Naira will instantly appear in your NGN wallet, ready to withdraw.

No delays. No guesswork. Just quick, transparent currency exchange.

Why choose Grey for GBP to naira conversions

Here’s why Grey stands out:

  • Best-in-market exchange rates: Get more Naira for every pound you convert.
  • Low, transparent fees: No hidden charges or surprises.
  • Fast processing: Convert and withdraw within minutes.
  • Multi-currency wallets: Hold, convert, and manage funds in GBP, USD, EUR, and NGN.
  • Easy withdrawals: Send money directly to any Nigerian bank account.

Tips to get the best GBP to NGN exchange rates

Want to make your money go even further? Here are a few smart tips:

  • Watch the rates: Grey’s live dashboard helps you monitor real-time rates and convert when they’re in your favour.
  • Convert in larger amounts: Converting bulk amounts can help minimise transaction fees.
  • Use GBP for regular payments: Holding a GBP wallet lets you decide the best time to convert.

Also read: The easiest way to get a virtual dollar account for AdSense earnings

The smarter way to manage GBP payments in Nigeria

With Grey, you can keep more of what you earn and enjoy total control over your international finances.

Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

‍

How to open a US bank account as a temporary visitor or on a visit visa

•

•

2 min read

You’ve landed in the United States for a few months, maybe for a family visit, a business trip, or to explore the country as a digital nomad. Somewhere along the way, you realise how helpful it would be to have a US bank account. Paying for services, receiving payments from abroad, or just avoiding foreign exchange fees, it all becomes easier when you have access to a US account.

But if you’re not a resident or citizen, opening a bank account in the US can feel like hitting a brick wall. The good news? There’s a way around it — you can open a virtual USD account with Grey, no matter where you are in the world.

I’ll show you how to open a US bank account as a temporary visitor or tourist, and how Grey makes the process seamless and borderless.

Can you open a US bank account as a visitor?

Technically, yes — but the process through traditional banks is not easy or visitor-friendly.

Most US banks require the following:

  • A US address
  • A Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN)
  • Two forms of government-issued ID
  • In-person visits to a branch for verification

For most short-term visitors or digital nomads, this creates a barrier. Without US documentation, you’ll likely be turned away. And even if you manage to open an account, maintaining it remotely or accessing your funds from outside the US can be challenging.

That’s why many travellers are turning to international financial platforms like Grey, which offer the same functionality, minus the paperwork and limitations.

Also read: How to open US and UK bank accounts in East Africa

Why you might need a US bank account as a visitor

Opening a US account is a strategic financial move during your stay. With a USD account, you can:

  • Receive payments from US employers, clients, or freelance platforms like Upwork or Fiverr.
  • Shop online from US retailers without worrying about foreign transaction fees.
  • Avoid high exchange rates and withdrawal charges when spending or withdrawing USD.
  • Pay for subscriptions and services like Amazon, Netflix US, or local apps with ease.
  • Manage your finances in USD while keeping your local currency untouched.

If you're a digital nomad or a freelancer travelling through the US, having access to a stable, fully functional USD account makes everyday transactions much simpler.

Also read: How to open US bank accounts in Cameroon

Opening a US bank account as a temporary visitor or on a visit visa with Grey

Grey offers a frictionless way to open and manage a USD account from anywhere, without needing a US address or citizenship. With Grey, you get access to a virtual USD account that works just like a domestic US bank account. You can send, receive, hold, and convert US dollars, all from your phone or laptop. Here’s how to do it:

Sign up

Head to grey.co or download the Grey app to create your account. It takes just a few minutes.

Complete your identity verification (KYC)

Upload a government-issued ID (passport, national ID, or driver’s license), a selfie, and a proof of address document. Grey uses this to verify your identity and ensure your account is secure and compliant with regulations.

Get your virtual USD account

Once verified, you can generate a fully functional USD account. It comes with a US account number and routing number.

Receive payments globally

Share your USD account details with clients, employers, or platforms like Amazon, or Upwork. They can pay you directly, and funds will be credited to your Grey account.

Convert and withdraw funds

Use Grey’s built-in currency converter to switch between USD, GBP, EUR, and your local currency. Withdraw the funds to your local bank at competitive exchange rates.

Also read: Fastest way to receive USD freelance payments in China

Why Grey is ideal for temporary visitors in the US

Traditional banks in the US aren’t built for travellers. From requiring a Social Security Number to in-person visits, the process can be daunting for short-term visitors. Grey, on the other hand, was designed specifically for people who live, work, or travel across borders.

Here’s why it works so well:

  • No US residency required: You don’t need to be a US citizen, green card holder, or even physically present in the US to open an account with Grey.
  • Instant access to a USD account: Grey gives you real US banking details, which you can use for freelance platforms, online shopping, or receiving payments from clients and family.
  • Multi-currency support: Alongside your USD account, you’ll also get access to EUR, GBP, and other currencies. This is perfect for managing international payments while travelling.
  • Competitive rates and low fees: Grey offers better exchange rates and lower fees than traditional banks or money transfer services — especially helpful when converting between currencies.
  • 100% digital onboarding: The entire sign-up process is remote. You don’t need to visit a branch or deal with paperwork.
  • Withdraw to your local account: Once you receive funds in your Grey USD account, you can convert and withdraw them to your local bank account wherever you are.

Also read: How to create US and UK bank accounts as a migrant worker

For anyone visiting the US temporarily, Grey offers a modern, stress-free way to manage money internationally. You get all the benefits of a US-based bank account, without the paperwork, red tape, or restrictions. Create your Grey account today or download the app to enjoy inclusive global banking, designed to carry your dreams across borders.

‍

How to exchange currency safely when visiting Indonesia

•

•

2 min read

Indonesia is a dream destination for travellers. Bali’s serene landscapes, Jakarta’s vibrant nightlife and Yogyakarta’s historical wonders — it doesn’t get better than that. To enjoy all of these things, though, having local currency on hand is important.

Fret not. I’ll teach you how to convert your currency into Indonesian Rupiah (IDR), ensuring you get the best value for your money.

Understanding the Indonesian Rupiah (IDR)

Before you exchange money, it’s important to understand Indonesia’s currency. The Indonesian Rupiah (IDR) comes in various denominations, with common banknotes being 1,000, 5,000, 10,000, 50,000, and 100,000 IDR. Due to the large numbers on the bills, be mindful when handling cash to avoid confusion or overpayment. Exchange rates fluctuate, so it’s a good idea to check the current rate before exchanging money.

Also read: How to open US and UK bank accounts in Indonesia

Best ways to exchange money in Indonesia

There are several options for exchanging currency, but not all are equally safe or cost-effective. Here are the most reliable methods:

1. Banks and authorised money changers

One of the safest ways to convert your money into IDR is through banks or licensed exchange offices. Look for authorised money changers approved by Bank Indonesia, as they follow strict regulations to ensure fair transactions. Reputable options include VIP Money Changer, Dirgahayu Valuta Prima, and Central Kuta Money Exchange.

Tips for safe currency exchange:

  • Always count your money before leaving the counter.
  • Ensure it’s an authorised exchange office — look for official signage and licensing.
  • Avoid exchanging large sums at the airport, where rates are usually less favourable.

2. Withdrawing cash from ATMs

If you prefer convenience, using an ATM is a safe and easy way to withdraw IDR at competitive exchange rates. Major banks like Mandiri, BCA, BNI, and CIMB Niaga have ATMs across the country.

Things to keep in mind:

  • Use ATMs in well-lit, secure areas like malls or banks.
  • Withdraw larger amounts at once to minimise transaction fees.
  • Cover the keypad when entering your PIN to protect against skimming devices.

3. Using multi-currency accounts like Grey

A multi-currency account like Grey is an excellent option for seamless international transactions. With Grey, you can receive, hold, and convert currencies like USD, EUR, and GBP at competitive rates, eliminating the need for physical cash exchanges.

Why choose Grey for currency exchange?

  • Lower fees than traditional banks and exchange bureaus.
  • Instant conversions between multiple currencies.
  • Secure transactions without worrying about counterfeit bills or scams.
  • Ease of use. You can manage your money digitally from anywhere.

Tips to avoid currency exchange scams

Currency exchange scams are common in tourist-heavy areas. Here’s how to stay safe:

  • Avoid unauthorised money changers. If a rate seems too good to be true, it probably is.
  • Double-check your bills. Some scammers use sleight of hand to shortchange tourists.
  • Ask for a receipt. A legitimate money changer will provide one.
  • Be cautious with street exchangers. Stick to banks and reputable exchange offices.

Also read: How to send money to Indonesia

Should you use cash or card?

Cash is still widely used in Indonesia, especially in smaller shops, local markets, and rural areas. However, credit and debit cards (Visa and Mastercard) are accepted in hotels, restaurants, and shopping malls.

Also read: How to get an instant USD debit card in Indonesia

Making transactions seamless with Grey

For a hassle-free way to manage your money while travelling, Grey offers a secure and cost-effective multi-currency solution. Instead of worrying about cash exchange or high bank fees, you can:

  • Convert USD, EUR, and GBP to IDR instantly at competitive rates.
  • Receive and hold multiple currencies in one account.
  • Transfer funds internationally without the high fees of traditional banks.

Travel smart with secure currency exchange

Navigating currency exchange in Indonesia isn’t nearly as stressful as it sounds. You can ensure safe, hassle-free transactions throughout your trip by using authorised money changers, trusted ATMs, or a multi-currency account like Grey.

Planning a visit to Indonesia? Create your Grey account today or download the app to enjoy inclusive global banking, designed to carry your dreams across borders.

‍

Arrow (up)

Back to top