<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/cost-of-living-jakarta#article","headline":"Cost of living in Jakarta: A complete guide for expats and nomads","description":"What does it cost to live in Jakarta? See a real monthly budget for rent, food, and transport for expats and nomads. Plan your move and budget today.","inLanguage":"en","url":"https://grey.co/blog/cost-of-living-jakarta","mainEntityOfPage":{"@id":"https://grey.co/blog/cost-of-living-jakarta#webpage"},"datePublished":"2026-08-10T14:26:08.172Z","dateModified":"2026-10-02T02:20:55.265Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/cost-of-living-jakarta#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a79df68ae5c128ffc212f94_Cost%20of%20living%20in%20Jakarta_%20a%20complete%20guide%20for%20expats%20and%20nomads-compressed.jpg","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a79df68ae5c128ffc212f94_Cost%20of%20living%20in%20Jakarta_%20a%20complete%20guide%20for%20expats%20and%20nomads-compressed.jpg","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/cost-of-living-jakarta#webpage","url":"https://grey.co/blog/cost-of-living-jakarta","name":"Cost of Living in Jakarta: Full 2026 Guide","description":"What does it cost to live in Jakarta? See a real monthly budget for rent, food, and transport for expats and nomads. Plan your move and budget today.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/cost-of-living-jakarta#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/cost-of-living-jakarta#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/cost-of-living-jakarta#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Cost of living in Jakarta: A complete guide for expats and nomads","item":"https://grey.co/blog/cost-of-living-jakarta"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/cost-of-living-jakarta#faq","mainEntity":[{"@type":"Question","name":"How much does a couple need to live comfortably in Jakarta?","acceptedAnswer":{"@type":"Answer","text":"A couple sharing a one-bedroom or two-bedroom apartment in South Jakarta can live comfortably on IDR 30 to IDR 45 million (approximately USD 1,670 to USD 2,500) per month. This covers a well-located apartment, regular dining out at both local and mid-range Western restaurants, utilities, transport, and leisure. Couples with children should budget significantly more, particularly if international school fees apply."}},{"@type":"Question","name":"What are the cheapest areas to live in Jakarta?","acceptedAnswer":{"@type":"Answer","text":"East Jakarta and North Jakarta offer the most affordable rents, with studios and one-bedroom apartments available from IDR 1.5 to IDR 4 million (USD 85 to USD 220) per month. These areas have a more local character and are further from the main expat and coworking hubs of South Jakarta. For a balance of affordability and access, Central Jakarta apartments from IDR 4 to IDR 8 million (USD 220 to USD 445) are worth considering."}},{"@type":"Question","name":"Is Jakarta safe for expats and digital nomads?","acceptedAnswer":{"@type":"Answer","text":"Jakarta is generally safe for expats and nomads in the main residential and commercial areas. Standard urban precautions apply: be aware of your surroundings, avoid displaying expensive items, and use registered transport apps rather than hailing taxis on the street. Petty theft is the primary concern in crowded areas. South Jakarta neighbourhoods like Kemang and Cipete, popular with the expat community, have a strong sense of community and are considered among the safest areas in the city."}},{"@type":"Question","name":"How much does a one-bedroom apartment in Jakarta cost?","acceptedAnswer":{"@type":"Answer","text":"A one-bedroom apartment in the city centre typically costs IDR 8 to IDR 15 million (USD 445 to USD 835) per month. Outside the centre, a one-bedroom apartment costs IDR 4 to IDR 8 million (USD 220 to USD 445) per month. Premium apartments in SCBD or Sudirman with full facilities can exceed IDR 20 million (USD 1,110) for a one-bedroom. Many Jakarta landlords require 12 months’ rent paid upfront at lease signing."}},{"@type":"Question","name":"What is the USD to Indonesian rupiah rate in 2026?","acceptedAnswer":{"@type":"Answer","text":"The mid-market USD to IDR rate averages approximately IDR 18,000 per dollar as of August 2026, with the 30-day range running between IDR 17,900 and IDR 18,164. The rupiah has weakened against the dollar over the past 12 months, which benefits expats and nomads earning in USD. Always check the current mid-market rate on XE.com or a similar source before making large conversions, as the rate offered by banks and bureaux de change includes a margin above the mid-market rate."}},{"@type":"Question","name":"Is Jakarta expensive compared to other Asian cities?","acceptedAnswer":{"@type":"Answer","text":"Jakarta sits comfortably as the cheapest of Asia’s major expat hubs on a like-for-like basis, a clear tier below Singapore and Hong Kong, and roughly on par with Bangkok and Kuala Lumpur once rent is factored in. For nomads earning in USD or EUR, Jakarta offers the purchasing power of a major Asian city at a fraction of the cost of comparable regional hubs. The caveat is that Western-lifestyle choices, imported groceries, frequent international dining, and premium serviced apartments can push costs significantly higher than the headline indices suggest."}}]}] </script>

Cost of living in Jakarta: A complete guide for expats and nomads

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

Jakarta is one of Southeast Asia’s most underrated destinations for expats and digital nomads. The city has world-class infrastructure, a fast-growing remote work scene, reliable connectivity, and a cost of living that stretches a USD or EUR income further than most regional alternatives. For context, Singapore costs three times as much.

If you’re considering living in Jakarta as a remote worker, freelancer, or relocating professional, this guide gives you the real numbers, the actual monthly figures that expats and nomads report in 2026, broken down by category, district, and lifestyle. For those earning internationally and spending locally, Grey for digital nomads is worth exploring before you arrive.

How much does it cost to live in Jakarta?

A comfortable single expat life in Jakarta typically costs USD 1,000 to USD 1,500 per month. Budget-conscious digital nomads can live on USD 600 to USD 900 monthly, particularly if they avoid Western restaurants and expat-grade apartments.

In rupiah terms, a single professional can live well on IDR 30-50 million per month. At the premium end, a luxury-standard life with an SCBD apartment, frequent fine dining, and a car costs IDR 80 million or more (approximately USD 4,400) per month for a single person.

For couples without children, double the mid-range single budget and subtract some shared fixed costs. For families with children in international schools, the budget changes entirely: a typical expat family of four in Jakarta spends USD 7,400 to USD 11,400 per month all-in, with housing and international school fees absorbing around 68% of that total.

Here’s a monthly budget breakdown for a single person at three lifestyle tiers:

Category Budget (IDR / USD) Mid-range (IDR / USD) Comfortable (IDR / USD)
Rent (1-bedroom) IDR 4–5M / USD 220–280 IDR 8–12M / USD 450–670 IDR 15–20M / USD 835–1,110
Food (eating out + groceries) IDR 2–3M / USD 110–170 IDR 4–6M / USD 220–330 IDR 8–12M / USD 445–670
Transport IDR 500K–1M / USD 28–56 IDR 1–2M / USD 56–110 IDR 3–5M / USD 165–280
Utilities (electricity, water, internet) IDR 500K–1M / USD 28–56 IDR 1–1.5M / USD 56–85 IDR 2–3M / USD 110–165
Entertainment and lifestyle IDR 500K–1M / USD 28–56 IDR 2–3M / USD 110–165 IDR 5–8M / USD 280–445
Monthly total (excluding rent) IDR 3.5–6M / USD 194–333 IDR 8–12.5M / USD 445–695 IDR 18–28M / USD 1,000–1,555
Monthly total (including rent) IDR 7.5–11M / USD 417–610 IDR 16–24.5M / USD 890–1,360 IDR 33–48M / USD 1,835–2,665

‍

Figures are estimates, so always verify current rates before making financial decisions.

Rent and housing costs in Jakarta

Rent is the biggest variable in any Jakarta budget, and the rent prices usually vary by district. The same monthly budget that gets you a kos (a furnished room in a shared house, the most budget-friendly option in Jakarta) in an outer district can buy you a comfortable studio in a mid-range apartment building in South Jakarta.

A one-bedroom apartment in the city centre typically costs between IDR 8 million and IDR 15 million (approximately USD 445 to USD 835) per month. Larger apartments with two or three bedrooms in central areas range from IDR 18 million to IDR 35 million (USD 1,000 to USD 1,945) per month. Outside the centre, a one-bedroom may cost IDR 4 million to IDR 8 million (USD 220 to USD 445) per month, while a family house ranges from IDR 12 million to IDR 20 million (USD 670 to USD 1,110).

Here’s how rents break down by district:

District Type Monthly rent
(IDR)
Monthly rent
(USD approx.)
Best for
SCBD / Sudirman 1-bedroom apartment IDR 11–17M USD 610–945 Corporate professionals, walkable lifestyle
SCBD / Sudirman 2-bedroom apartment IDR 20–35M USD 1,110–1,945 Couples, small families
Kemang 1-bedroom apartment IDR 8–14M USD 445–780 Young expats, creative professionals
Kemang House with garden IDR 20–35M USD 1,110–1,945 Families, larger space
Pondok Indah House or large apartment IDR 20–40M USD 1,110–2,220 Families near international schools
Central Jakarta 1-bedroom apartment IDR 4–15M USD 220–835 Budget to mid-range, central access
East / North Jakarta Kos or studio IDR 1.5–4M USD 85–220 Budget nomads, local experience

‍

Jakarta landlords commonly require 12 months’ rent paid upfront, which is the most important practical consideration when budgeting for a move. Your first month’s outlay will be significantly higher than the ongoing monthly cost. Factor this into your arrival budget.

One important note: service charges in Jakarta apartments are typically quoted separately from rent, running IDR 15,000 to IDR 25,000 per square metre per month, and can add IDR 750,000 to IDR 1.5 million to a standard studio’s effective monthly cost.

Food, groceries, and eating out

Food is where Jakarta genuinely impresses. Local food is cheap and widely available, often costing just USD 2 to USD 12 per meal at restaurants and street stalls. A meal at a warung (a local Indonesian street food stall) costs IDR 15,000 to IDR 40,000 (under USD 2.50). Nasi goreng, mie goreng, soto, and bakso are staples available on almost every street corner.

Moving up the price range, a mid-range local restaurant meal with a drink runs IDR 50,000 to IDR 150,000 (USD 3 to USD 8). A meal at a Western-style café or casual international restaurant in South Jakarta runs IDR 150,000 to IDR 350,000 (USD 8 to USD 20). Fine dining at international restaurants in SCBD or Kemang is comparable to mid-range European pricing.

Monthly grocery estimates for a single person:

  • Local market and supermarket basics: IDR 500,000 to IDR 1 million (USD 28 to USD 56)
  • Mid-range supermarket (Ranch Market, Kemchicks, Grand Lucky): IDR 1.5 to IDR 3 million (USD 85 to USD 165)
  • Imported goods and premium supermarkets: IDR 3 to IDR 6 million (USD 165 to USD 335)

The biggest food budget driver in Jakarta is whether you default to Western dining. A month of eating primarily local food, supplemented by occasional Western meals, costs IDR 2 to IDR 4 million (USD 110 to USD 220). A month of primarily Western restaurants in SCBD or Kemang can easily reach IDR 8 to IDR 12 million (USD 445 to USD 670).

Transport, utilities, and other monthly costs

Transport

Jakarta traffic is the city’s most cited downside. Ride-hailing apps like Grab and Gojek make transportation affordable and are the primary mode of getting around for most expats and nomads. A Grab or Gojek car ride of 5 to 10 kilometres costs IDR 30,000 to IDR 70,000 (USD 1.65 to USD 3.90). Monthly ride-hailing spend for regular users runs IDR 1 to IDR 3 million (USD 56 to USD 165).

TransJakarta, the city’s bus rapid transit system, offers a flat fare of IDR 3,500 (under USD 0.20) per journey, making it the cheapest transport option. The MRT Jakarta (Mass Rapid Transit) covers the main Lebak Bulus to Bundaran HI corridor and costs IDR 4,000 to IDR 14,000 per trip, depending on distance.

Some expats and nomads rent a motorbike for IDR 500,000 to IDR 1 million (USD 28 to USD 56) per month for flexible, traffic-beating mobility. Car rental or car ownership adds significantly to the budget and is generally only practical for families or those outside the MRT corridor.

Utilities

Electricity is Jakarta’s most variable utility. Electricity for a unit running two or three air-conditioners continuously costs IDR 2.5 to IDR 4 million per month. A studio with one air-conditioner used moderately typically costs IDR 500,000 to IDR 1.2 million. PLN’s progressive tariffs apply, so heavy users pay proportionally more.

Water bills are typically IDR 100,000 to IDR 300,000 monthly. Internet via home fibre (IndiHome, Biznet, or MyRepublic) runs IDR 250,000 to IDR 600,000 (USD 14 to USD 33) for 20 to 100 Mbps. Mobile data is very cheap: IDR 50,000 to IDR 100,000 per month covers a generous data allowance on providers like Telkomsel or XL Axiata.

Salary vs cost: Can you live comfortably in Jakarta?

The gap between local salaries and expat or nomad income in Jakarta is significant, which is why the city works well for those earning in USD or EUR.

The average monthly salary in Jakarta for local workers varies significantly by industry and seniority. Entry-level formal employment in finance or tech typically starts at IDR 7 to IDR 10 million (USD 390 to USD 556) after tax. Mid-career professionals in corporate roles earn IDR 15 to IDR 30 million (USD 835 to USD 1,670). Senior positions and expatriate packages are substantially higher.

For digital nomads and remote workers earning USD or EUR income, the exchange rate works in their favour. A monthly income of USD 2,000 converts to approximately IDR 36 million, which places a single person comfortably in the mid-to-comfortable lifestyle tier, with money left for savings, travel, and lifestyle spending.

At USD 3,000 per month, a single nomad in Jakarta can afford a well-located apartment in South Jakarta, eat and drink freely, maintain full health insurance, and travel regionally, while saving meaningfully. This level of financial flexibility is difficult to achieve in Singapore, Hong Kong, London, or New York on the same income.

The caveat: Jakarta becomes expensive when expats attempt to replicate a fully Western lifestyle without compromise. Imported groceries by default, Western restaurants by habit, a car and driver stuck in traffic: these choices push the monthly budget into territory where Jakarta’s affordability advantage narrows significantly.

Is Jakarta a good base for digital nomads?

Jakarta has developed meaningfully as a nomad base over the past three years. The city now has a credible coworking infrastructure, fast internet, and a growing international community.

Connectivity: Fibre internet speeds in modern apartments and coworking spaces are reliable. 4G and 5G mobile coverage in central Jakarta is excellent. For video calls and remote work tools, connectivity is not a practical concern in most expat neighbourhoods.

Coworking: CoHive, WeWork, and GoWork have multiple locations across South Jakarta. Day passes run IDR 75,000 to IDR 150,000 (USD 4 to USD 8). Monthly memberships at a fixed desk start at approximately IDR 1.5 to IDR 3 million (USD 85 to USD 165).

Visa: Most nationalities receive a 30-day visa on arrival, extendable once for another 30 days. A social visit visa (B211A) allows stays of up to 60 days and can be extended. Indonesia’s digital nomad visa, introduced in 2023, was designed for remote workers but has had a complicated implementation history. Check current requirements directly with the Indonesian consulate or embassy before planning a long stay. Working without the correct visa carries real risk.

Lifestyle: South Jakarta, in particular, Kemang, Cipete, and Senopati, offers a genuinely international lifestyle: world-class restaurants, independent coffee shops, music venues, and a social scene that makes the city easy to settle into. For a broader context, see our guide on Indonesia for remote workers: tips, connectivity, and community.

Managing money as an expat or nomad in Jakarta with Grey

The practical challenge for expats and nomads in Jakarta is the USD to Indonesian rupiah conversion. The mid-market USD/IDR rate averages approximately IDR 18,000 per dollar over the past 30 days, but the rate your bank or currency exchange offers will be lower. Most traditional banks apply a 2 to 4% margin on the mid-market rate. A bureau de change at a Jakarta airport or mall applies even more.

On USD 3,000 per month converted to IDR at a 3% bank margin, that’s approximately IDR 1.6 million (USD 90) lost every month purely to conversion costs, before spending a single rupiah.

Grey lets you hold USD and convert to rupiah at a transparent rate shown before you confirm, with a conversion fee of 1% capped at $6. On a $3,000 monthly conversion, the fee is $6 at the maximum, compared to $90 at a 3% bank spread. Annually, that’s a difference of over $1,000 staying in your account rather than disappearing to conversion costs.

For digital nomads receiving USD or EUR income from clients abroad, Grey also provides local banking details (USD routing number, EUR IBAN, GBP sort code) so clients can pay via standard domestic transfers. Funds land in your Grey balance without SWIFT wire deductions, you convert what you need to IDR, and the remainder stays in USD or EUR, earning no unnecessary conversion losses.

Grey’s virtual USD card is accepted internationally and can be used at Jakarta’s international merchants and online platforms. It works on most major international services, including AWS, Adobe, and Google Workspace. For a full guide to how nomads across Indonesia manage multi-currency income, see how digital nomads in Indonesia manage USD, EUR, and IDR.

Open a Grey account, hold USD, and spend in rupiah in Jakarta today at grey.co/foreign-accounts.

Frequently asked questions about the cost of living in Jakarta

How much does a couple need to live comfortably in Jakarta?

A couple sharing a one-bedroom or two-bedroom apartment in South Jakarta can live comfortably on IDR 30 to IDR 45 million (approximately USD 1,670 to USD 2,500) per month. This covers a well-located apartment, regular dining out at both local and mid-range Western restaurants, utilities, transport, and leisure. Couples with children should budget significantly more, particularly if international school fees apply.

What are the cheapest areas to live in Jakarta?

East Jakarta and North Jakarta offer the most affordable rents, with studios and one-bedroom apartments available from IDR 1.5 to IDR 4 million (USD 85 to USD 220) per month. These areas have a more local character and are further from the main expat and coworking hubs of South Jakarta. For a balance of affordability and access, Central Jakarta apartments from IDR 4 to IDR 8 million (USD 220 to USD 445) are worth considering.

Is Jakarta safe for expats and digital nomads?

Jakarta is generally safe for expats and nomads in the main residential and commercial areas. Standard urban precautions apply: be aware of your surroundings, avoid displaying expensive items, and use registered transport apps rather than hailing taxis on the street. Petty theft is the primary concern in crowded areas. South Jakarta neighbourhoods like Kemang and Cipete, popular with the expat community, have a strong sense of community and are considered among the safest areas in the city.

How much does a one-bedroom apartment in Jakarta cost?

A one-bedroom apartment in the city centre typically costs IDR 8 to IDR 15 million (USD 445 to USD 835) per month. Outside the centre, a one-bedroom apartment costs IDR 4 to IDR 8 million (USD 220 to USD 445) per month. Premium apartments in SCBD or Sudirman with full facilities can exceed IDR 20 million (USD 1,110) for a one-bedroom. Many Jakarta landlords require 12 months’ rent paid upfront at lease signing.

What is the USD to Indonesian rupiah rate in 2026?

The mid-market USD to IDR rate averages approximately IDR 18,000 per dollar as of August 2026, with the 30-day range running between IDR 17,900 and IDR 18,164. The rupiah has weakened against the dollar over the past 12 months, which benefits expats and nomads earning in USD. Always check the current mid-market rate on XE.com or a similar source before making large conversions, as the rate offered by banks and bureaux de change includes a margin above the mid-market rate.

Is Jakarta expensive compared to other Asian cities?

Jakarta sits comfortably as the cheapest of Asia’s major expat hubs on a like-for-like basis, a clear tier below Singapore and Hong Kong, and roughly on par with Bangkok and Kuala Lumpur once rent is factored in. For nomads earning in USD or EUR, Jakarta offers the purchasing power of a major Asian city at a fraction of the cost of comparable regional hubs. The caveat is that Western-lifestyle choices, imported groceries, frequent international dining, and premium serviced apartments can push costs significantly higher than the headline indices suggest.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How US startups pay remote workers outside the US

•

•

2 min read

Remote work has changed how US startups build their teams. It’s no longer unusual for a founder in the United States to work daily with designers, developers, consultants, and marketers living thousands of miles away. Slack messages replace office conversations, video calls stand in for physical meetings, and shared documents keep projects moving. Talent is no longer limited by geography, and startups are more comfortable hiring skilled professionals regardless of where they live.

But when the work is done, a simple question follows: how do payments actually reach these remote workers outside the US? For many startups, paying global talent has become part of their everyday operations. This article examines how US startups handle payments to remote workers around the world and the practical ways those professionals receive their earnings.

Also read: How freelancers in the US get paid by international clients

Challenges US startups face when sending money abroad

Sending money to remote workers outside the US comes with challenges. Understanding them helps startups pay reliably, build trust, and value global talent.

Transaction fees‍

Wire transfers often come with high fees from intermediary banks and the recipient’s bank. As a US startup, it’s important to anticipate these costs so your remote workers get the full payment they expect. Being aware of fees ahead of time helps you plan better, maintain transparency, and show your team that their work is valued.

Payment delays

‍Sending money to emerging markets can take longer than expected, even with the right platforms. Delays can frustrate your remote team and disrupt workflow. By anticipating timing challenges and keeping your workers informed, you demonstrate reliability and professionalism, ensuring your remote consultants feel respected and confident that their efforts will be rewarded on time.

Platform restrictions

‍Not all payment methods work everywhere. Platforms like PayPal may have limited support in some countries, making it tricky for your team to receive funds. Knowing these restrictions upfront helps you select the right solution, so your remote workers can get paid smoothly, avoiding frustration and maintaining trust in your startup’s global processes.

Security risks

‍Cross-border payments carry risks such as fraud, phishing, and data breaches. Using secure platforms and monitoring transactions carefully protects both your startup and your remote workers. Prioritising security shows professionalism and builds confidence. Your team can focus on delivering great work knowing that their money and personal information are safe, strengthening trust across borders.

Also read: Get paid by clients overseas as a US freelancer

How US startups pay remote workers outside the US

Paying remote workers abroad has become a normal part of US startups. Choosing the right platform ensures fast, reliable payments and builds trust.

Wise

Wise gives US startups a straightforward way to send payments to remote workers in other countries. Businesses can transfer USD directly while the recipient receives funds in their local currency at real exchange rates rather than marked-up bank rates. Transfers are trackable in real time and fees are shown upfront, helping startups plan payroll accurately. Wise also supports multi-currency balances, allowing companies to manage payments in different currencies from one account.

Transaction costs are generally lower than traditional bank wires, and transfers are often completed within one to two business days, making it a practical option for startups paying distributed teams.

Payoneer

Payoneer allows US startups to pay remote workers and contractors across multiple countries through a structured global payments network. Businesses can send funds in major currencies such as USD, EUR, or GBP while recipients withdraw to their local bank accounts or use a prepaid Payoneer card where available.

The platform also integrates with many global marketplaces and invoicing tools, which simplifies contractor payments. Fees and currency conversion rates are visible before sending, helping startups manage payroll budgets.

Western Union

Western Union allows US startups to send funds to remote workers in select countries fast. Payments can be picked up in cash at a local agent or deposited directly to a bank account where supported. While fees can be higher than digital‑first platforms, speed and accessibility make it valuable for urgent needs or recipients without online banking.

With a global agent network and mobile options in many regions, it’s practical when flexibility and immediate access to funds matter most.

Grey (recommended)

Grey helps US startups pay remote workers abroad by sending funds in USD to dedicated foreign currency accounts. Your team members can then convert the money into their local currency when it suits them and withdraw to their local bank accounts. This gives remote workers more control over how and when they manage their earnings while keeping payments straightforward for startups.

Grey follows strict anti-money laundering (AML) standards and is registered with FinCEN in the United States and FINTRAC in Canada, helping ensure payments are handled responsibly within recognised financial compliance frameworks.

Remitly

Remitly is commonly used by US startups when paying remote workers in countries where traditional banking systems may be slower or less accessible. The platform offers two transfer speeds: Express, which delivers funds within minutes but at a higher fee, and Economy, which costs less but can take several days.

Payments can reach bank accounts, mobile wallets, or approved cash pickup locations. For teams spread across different regions, Remitly provides flexibility in how workers receive funds and reliable tracking from the moment the payment is sent.

Sendwave

Sendwave is designed for sending money to workers in regions where mobile money is widely used, particularly across Africa and parts of Asia. Instead of relying on traditional bank transfers, US startups can send funds directly to supported mobile wallets, allowing workers to access their earnings instantly through their phones.

Because of its strong mobile wallet integrations, the platform works well for startups paying contractors in markets where mobile financial services are more common than conventional banking.

What should US startups consider before choosing a payment solution?

Choosing the right payment solution requires thought and planning. US startups need to ensure transfers are smooth and reliable, and that they build trust with their remote team.

Speed

Fast deposits matter for keeping your remote team motivated and satisfied. Delays can frustrate workers and slow project momentum. Look for providers that move funds quickly from US accounts to local accounts abroad, with predictable timing and clear tracking. Understanding typical transfer times allows you to plan payroll cycles efficiently, maintain trust, and show remote workers that their time and efforts are valued.

Security

Protecting payments and sensitive data is essential. Choose a provider with built-in fraud detection, encryption, and 3D secure integration. Secure systems prevent phishing, hacking, and unauthorised access, giving both your startup and remote workers confidence. Strong security safeguards help you avoid costly mistakes, maintain compliance, and demonstrate professionalism, ensuring your global team trusts the platform for every international transfer.

Support quality

Reliable support is crucial for resolving payment issues quickly. Access to 24/7 dedicated customer service ensures that any delays, errors, or account questions are handled efficiently. Responsive support reduces stress for both your startup and remote workers, ensuring smooth operations. Knowing that help is always available allows you to manage international payroll confidently without worrying about interruptions.

High uptime

Choose a payment provider with consistently high uptime to avoid failed transactions, system downtime, or lost revenue. Downtimes can delay payments and erode trust with remote workers. A reliable platform ensures your transfer process runs smoothly around the clock, across time zones, and in line with deadlines. High uptime gives peace of mind, reduces administrative follow-up, and keeps global teams focused on their work.

Regional support

Your payment provider should support local methods in the regions where your remote workers operate. This ensures workers can access funds without complications, whether through local banks, mobile wallets, or cash pickup points. Matching local preferences makes payments convenient and reliable, showing respect for workers’ needs. Regional compatibility also prevents unnecessary delays and demonstrates that your startup values its global team.

Customer preferences

Consider the payment methods your remote workers prefer. Some may favour direct bank transfers, others mobile wallets or platform-specific options. Catering to these preferences increases satisfaction, avoids frustration, and reduces time spent troubleshooting payment issues. Understanding what works best for your team ensures smooth operations, demonstrates attentiveness, and helps build strong, long-term relationships with remote talent across countries.

Fees

Evaluate all costs, including transaction fees, monthly charges, setup costs, and chargeback fees. Hidden or unexpected fees can reduce the amount your remote workers receive and affect budgeting. Comparing fees across platforms helps you choose the most cost-effective solution while maintaining reliability. Transparent costs show professionalism and help build trust with your team, ensuring that payments are fair, predictable, and worry-free.

Send international payments with Grey

Paying remote workers outside the US can be challenging if you don’t carefully consider speed, security, fees, and local support. Choosing the right platform makes all the difference for keeping your team motivated and confident. Grey stands out as a reliable solution that lets you send USD quickly, securely, and transparently. With fast transfers, multi-currency options, and easy withdrawals to local accounts, Grey helps you focus on your work while your team gets paid on time.

Sign up on Grey by creating an account with your email, verifying your identity, and setting up your business profile. You can also download the Grey app to handle international payouts from your phone wherever you work.
‍

Grey Business vs Grey personal banking

•

•

2 min read

“Should I be using Grey Business, or is my personal Grey account enough?”

It’s a common question, especially once your income starts growing.

At the beginning, everything feels simple. You get paid and you withdraw your money easily. But as your work evolves, whether that’s taking on more clients, earning from multiple platforms, or starting a company, the way you manage money needs to evolve too.

Grey offers two account types for this exact reason: Grey Personal and Grey Business. They are not better or worse than each other. They are built for different stages of your earning process.

This guide breaks down the differences, including fees, features, and when to switch, so you can choose the right setup without second-guessing.

‍Also read: Receiving foreign income as a solo founder

What is a Grey personal account?

A Grey personal account is designed for individuals who receive and manage international payments.

If you are a freelancer, remote worker, or creator earning from global clients or platforms, this is the account you are expected to use.

With a personal account, you can open USD, GBP, and EUR balances with real banking details. This allows clients to pay you as if they were making a local transfer in their own country. Instead of receiving an expensive international wire, you receive money through local rails like ACH, SEPA, and FPS.

Once the money arrives, you can hold it in foreign currency, convert it when the rate works for you, or withdraw it to your local bank account. You can also spend directly using your Grey virtual card without needing to manually move funds around.

The focus here is simplicity. You are managing your own income, and the account is designed to make that as flexible as possible.

What fees does Grey Personal charge?

Understanding fees is where most people get confused, so here’s how it actually works.

When you receive money through ACH, SEPA, or FPS, Grey charges a 0.8% fee, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. This means larger payments become proportionally cheaper because of the cap.

Currency conversion depends on the currency pair. Some routes are free, while others range from 0.5% to 1%. For certain major pairs, the fee is capped at $6. The important detail is that Grey shows the rate before you confirm, so there are no hidden charges after the fact.

Withdrawals vary depending on the country, but for major currencies like EUR and GBP, the fee is typically 0.5%, with a minimum and maximum cap. Other corridors may use fixed fees instead.

For less common deposit methods like Fedwire, BACS, or CHAPS, fixed fees apply. These are generally used less often, since local rails like ACH or FPS are cheaper.

Read more: Grey charges explained: what every transaction costs

What is Grey Business?

Grey Business is designed for companies rather than individuals.

If you are running a registered business, working under a company name, or managing revenue that belongs to a business entity, this is the account structure you need.

Unlike a personal account, a Grey Business account is built for your company. This means you can receive payments on behalf of the business, manage funds at a company level, and keep financial records properly organised for accounting and compliance.

The functionality goes beyond receiving payments. Grey Business allows you to manage team access, assign roles, and give multiple people control over finances without sharing a single login.

You can also pay contractors globally, send payments in local currencies, and handle bulk payouts by uploading recipient details. This becomes important as soon as you are working with a team or scaling operations.

The goal of Grey Business is not just to receive money, but to structure how your business handles it.

What fees does Grey Business charge?

Grey Business follows the same core pricing model as personal accounts.

Receiving payments still comes with the 0.8% fee capped at $10. Conversion fees follow the same tiered structure, and withdrawals depend on the payout country.

The difference is not in lower fees, but in what the account enables.

With Grey Business, you are paying for structure, team management, and the ability to operate at scale without mixing personal and company finances.

Grey Personal vs Grey Business: what is the difference?

The main difference comes down to ownership.

A personal account is for money that belongs to you as an individual. A business account is for money that belongs to a company.

Everything else builds from that.

Grey Personal is simpler, quicker to set up, and designed for individuals managing their own income. Grey Business requires verification of a registered company but provides tools to manage payments, teams, and operations effectively.

If you are working alone and getting paid for your own work, a personal account is enough. If you are invoicing as a company, hiring people, or managing shared finances, you need a business account.

‍Also read: Can non-residents open a US bank account online in 2026?

When should you use Grey for personal use?

You should use a personal account if you are earning in your own name.

This includes freelancers, remote employees, and creators earning from platforms like YouTube, TikTok, or Upwork. At this stage, your income is still personal, even if it comes from multiple sources.

A personal account keeps things simple.

When should you use Grey Business?

You should use Grey Business when your income is no longer just yours.

If you have registered a company, invoice under a business name, or manage revenue that belongs to a business entity, a personal account is no longer the right structure.

This is especially important if you are paying contractors, working with a team, or preparing financial records for accounting and tax purposes.

Can you have both Grey for personal use and Grey Business?

Yes, and in many cases, this is the best setup.

If you run a company but also earn income personally, keeping both accounts separate helps avoid confusion. Your business transactions stay within the business account, while your personal income remains separate.

This makes accounting cleaner and reduces the risk of mixing funds.

Grey for personal use vs Grey Business: key differences

Feature Grey Personal Grey Business
Who it’s for Individuals (freelancers, creators, remote workers) Registered companies, startups, agencies
Account ownership Personal use Business entity
Currencies supported USD, GBP, EUR, USDC USD, USDC (business-focused)
Receiving payments Yes (ACH, SEPA, FPS) Yes (for business transactions)
Team access No Yes (multi-user access with roles)
Bulk payouts No Yes (CSV uploads supported)
Virtual cards Yes (for personal use) Yes (multiple cards for teams, tools, ads)
Best use case Getting paid individually Managing company finances and scaling operations
Setup process Fast (ID verification) More detailed (business verification required)

So, which Grey account should you choose?

Most people overthink this decision, but it comes down to one simple question:

Who does the money belong to?

If you’re earning as an individual, whether that’s freelancing, remote work, or content creation, a Grey Personal account is the right fit. It keeps things simple and flexible while giving you full access to international payments.

If you’re operating as a registered business, invoicing clients under a company name, or managing team payments, Grey Business is the structure you need. It helps you separate finances properly and handle growth without creating confusion later.

If you’re in between, which is common, you can start with a personal account and move to business when your setup requires it. Many users also keep both, using one for personal income and the other for company operations.

The goal isn’t to pick the most advanced option. It’s to choose the one that fits how you earn today and won’t slow you down as you grow.

Getting started with Grey

Opening a Grey Personal account takes just a few minutes. You can sign up in under 5 minutes, and once your identity is verified, you can usually start receiving payments the same day.

Opening Grey Business takes a bit longer because it involves business verification. You’ll need to submit your company registration and ownership details, and approval typically takes 1 to 3 business days, depending on the documents provided. This ensures your account is set up correctly from the start.

Frequently asked questions

What is the difference between Grey for persona use and Grey Business?

Grey Personal is for individuals receiving and managing their own income, such as freelancers, creators, and remote workers. Grey Business is for registered companies that need to manage business revenue, pay contractors, and give team members access to finances.

The main difference is ownership. Personal accounts are for your money. Business accounts are for company funds.

Can I use a Grey Personal account for business payments?

You can use a personal account while you are freelancing under your own name. However, once you register a company or start invoicing under a business name, it is better to switch to Grey Business.

Using a personal account for business transactions can create confusion with accounting, taxes, and financial tracking.

Does Grey Business have different fees from Grey Personal?

Grey Business follows the same core pricing structure as personal accounts. Receiving fees are typically 0.8% with a cap, and conversion fees depend on the currency pair.

The main difference is not pricing, but functionality. Grey Business adds tools for team access, bulk payments, and structured financial management.

Can I have both a Grey Personal and Grey Business account?

Yes. Many users have both accounts.

This is useful if you have personal income, such as freelance work or creator earnings, and also run a registered business. Keeping them separate makes accounting cleaner and easier to manage.

When should I switch from Grey Personal to Grey Business?

You should consider switching when your income becomes business revenue instead of personal income.

This usually happens when you register a company, start invoicing clients as a business, hire contractors, or need proper financial records for tax and reporting purposes.

What documents are required to open a Grey Business account?

To open a Grey Business account, you will need to provide company registration documents, ownership details, and verification information about the business.

The process is more detailed than a personal account because it involves verifying a legal entity.

Is Grey Personal enough for freelancers and creators?

Yes. For most freelancers, remote workers, and creators, Grey Personal is more than enough.

It allows you to receive international payments, hold foreign currency, convert when needed, and withdraw locally without needing business-level setup.

Can I receive USD, GBP, and EUR with both accounts?

Yes. Both Grey Personal and Grey Business support multi-currency functionality.

Personal accounts focus on individual income, while business accounts structure those same capabilities for company use.

Which Grey account is better?

Neither is better. They are designed for different use cases.

Grey Personal is better for individuals managing their own income. Grey Business is better for companies managing business finances and scaling operations.

Ready to get started?

Open your Grey Personal account to start receiving international payments as an individual, or set up Grey Business if you’re managing company finances and need a more structured setup.

Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

  1. Log in to your Grey account.
    ‍
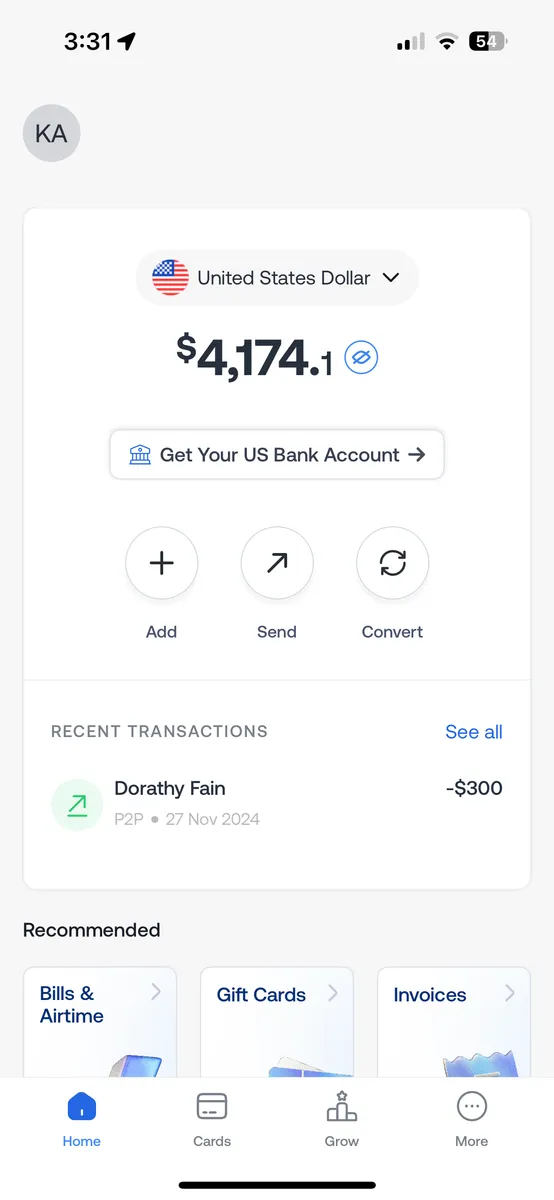
  2. Click “Send”.
Send Canadian dollars with Grey

‍

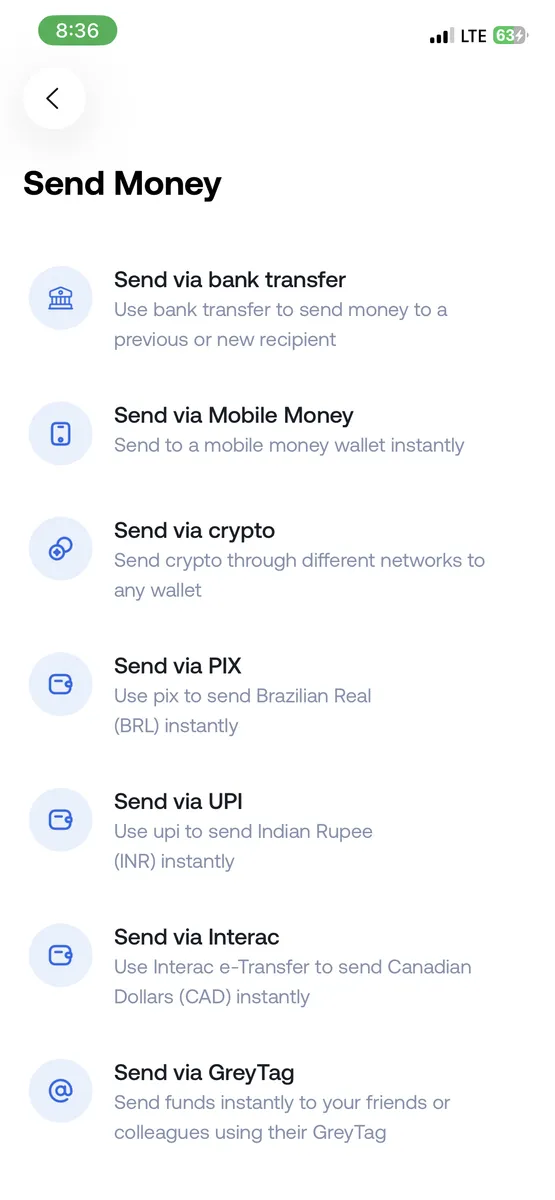
2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

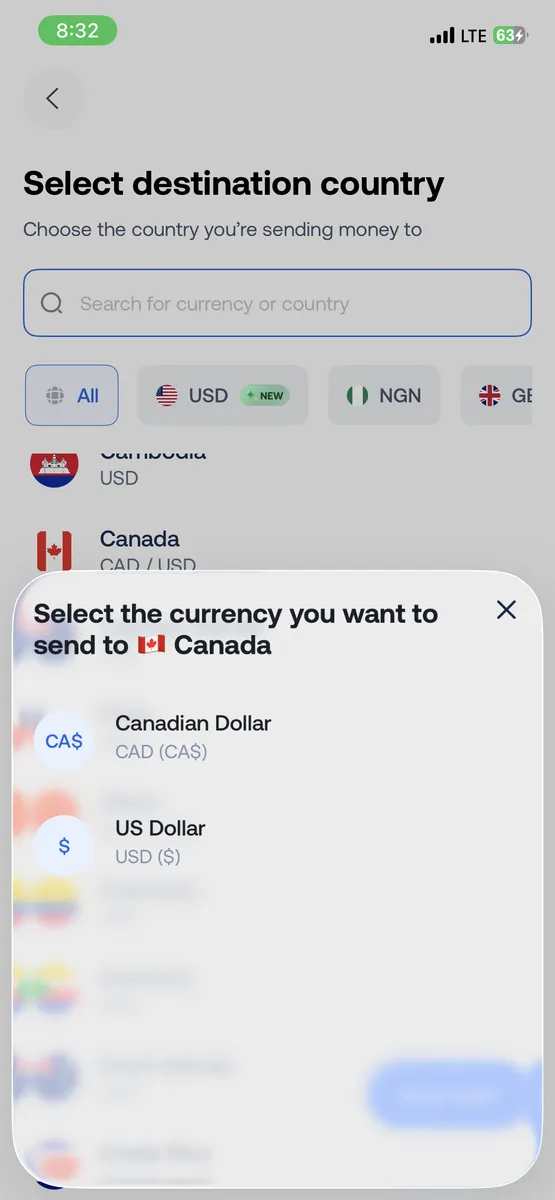
3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

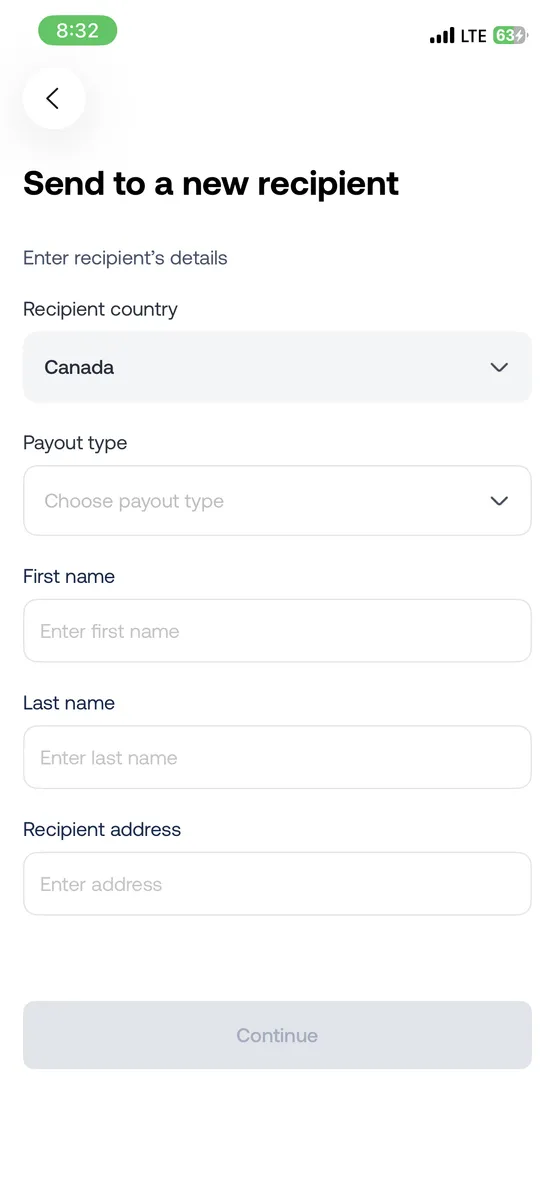
4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

How to send USD to a Nigerian domiciliary account

•

•

2 min read

Most of the information you’ll find online on sending money to Nigeria will most likely focus on naira delivery. But that’s not what you need if the recipient has a domiciliary account and wants to receive USD without converting to naira.

A Nigerian domiciliary account holds foreign currency, typically US dollars, without forcing an immediate conversion. Sending USD to one keeps that option in the recipient’s hands. It’s a decent choice for freelancers holding dollar savings, importers managing USD expenses, or anyone who wants to preserve dollar value rather than convert at a potentially unfavourable rate.

The mechanics of getting USD from a US bank account into a Nigerian domiciliary account are specific. You need to understand the required details, the fees you’ll encounter, and the mistakes that cause transfers to fail or arrive short before you send. For a broader overview of receiving dollar income in Nigeria, see our guide on how to receive US dollars in Nigeria and the options available for opening a Nigerian dollar account.

What is a domiciliary account?

A domiciliary account, also commonly called a dom account, is a bank account held at a Nigerian commercial bank that stores foreign currency without converting it to naira. The Central Bank of Nigeria (CBN) permits individuals and businesses to hold certain foreign currencies in domiciliary accounts at licensed Nigerian banks.

The key distinction from a standard naira savings account is that funds credited to a domiciliary account remain in the foreign currency in which they were credited. The account holder decides when and whether to convert, and at what rate. This matters because the naira has historically depreciated against major currencies, and holding USD can protect against the value erosion of naira conversions.

Domiciliary accounts are the primary mechanism by which Nigerians receive international SWIFT wire transfers in USD. CBN’s foreign exchange regulations require that inbound USD transfers be credited to a domiciliary account or converted to naira at the official rate. If a sender directs a USD wire to a standard naira account, the bank will convert it on arrival. If the recipient wants the money to remain in USD, the wire must be sent to the domiciliary account number, not the naira account number.

Both the naira and domiciliary accounts exist at the same bank for the same person and may look similar. They are different accounts with different account numbers. Confirm the domiciliary account number explicitly with the recipient before initiating the wire.

How to send USD via SWIFT wire: step by step

A SWIFT wire from a US bank to a Nigerian domiciliary account requires specific information, and if you miss any, it can cause delays, returns, or the transfer landing in the wrong account.

Step one: Collect the recipient’s domiciliary account details.

You need all of the following:

  • Recipient’s full legal name, exactly as registered with the Nigerian bank
  • The domiciliary account number (not the naira account number)
  • The bank name and branch address
  • The bank’s SWIFT code

The SWIFT codes for some major Nigerian banks are as follows: Access Bank: ABNGNGLA, GTBank (Guaranty Trust Bank): GTBINGLA, Zenith Bank: ZEIBNGLA, First Bank of Nigeria: FBNINGLA, United Bank for Africa (UBA): UNAFNGLA, Stanbic IBTC Bank: SBICNGLX, Ecobank Nigeria: ECOCNGLA, Fidelity Bank: FBNKNGLA, FCMB (First City Monument Bank): FCMBNGLA.

Always verify the SWIFT code directly with the recipient’s bank before initiating a high-value transfer, as branch-specific codes sometimes differ from the head office code.

Step two: Initiate the wire transfer at your US bank.

Log in to your online banking or visit a branch. Navigate to international wire transfers. Enter the recipient’s details: full name, domiciliary account number, bank name, branch address, and SWIFT code. Specify USD as the transfer currency. Nigeria is a USD-only wire destination at Bank of America; Bank of America requires international wires to Nigeria to be sent in US dollars due to local regulations, and foreign currency transfers are not available to this destination.

Step three: Select your charge instruction.

Depending on your bank, you may be asked whether to use SHA (shared charges) or OUR (sender pays all). Under SHA, correspondent bank fees are deducted from the transfer amount in transit, meaning the recipient receives less than what you send. Under OUR, you pay all correspondent fees upfront, and the recipient receives the full amount. For transfers where the recipient needs a specific USD amount, OUR is the right choice. For transfers where the fee deductions are acceptable, SHA is the standard default.

Step four: The wire routes through the SWIFT network.

Not all US banks have direct correspondent relationships with Nigerian banks. A US-to-Nigeria wire might involve two or three correspondent bank hops due to limited direct banking relationships. Each correspondent bank in the chain processes and forwards the payment, and under SHA, each one can deduct a fee from the transfer amount before forwarding the remainder.

Step five: The money arrives in the domiciliary account.

SWIFT transfers to Nigeria typically take one to three business days. Large transfers may be held for CBN compliance review, which can extend the timeline. Once that is cleared, the USD is credited to the domiciliary account and remains in dollars until the account holder decides to convert or withdraw.

What a SWIFT wire really costs

The posted fee at your US bank is not the full cost of a SWIFT wire to Nigeria. Three fee layers stack on every transfer.

Layer one: Your US bank’s outgoing wire fee
A 2026 NerdWallet survey reported a median outgoing international wire transfer fee of $45, with major US banks charging $35 to $50 per send. Chase charges $40 online for USD wires. Bank of America charges $35 for online transfers. Wells Fargo charges $25 to $45, depending on account type.

Layer two: Correspondent bank deductions in transit
Correspondent banks that relay the payment along the SWIFT chain can each deduct $10 to $30 in fees from the transferred amount before it reaches its destination. On a US-to-Nigeria wire routed through two correspondent banks, that’s $20 to $60 deducted from the transfer amount. Neither you nor the recipient is notified of these deductions in advance.

Layer three: The Nigerian receiving bank’s incoming wire fee
Nigerian banks charge an inbound wire fee on SWIFT receipts. This is typically deducted from the funds upon arrival before they are credited to the domiciliary account.

Here’s what this looks like on real transfers:

$500 transfer $5,000 transfer
US bank outgoing wire fee $40 $40
Correspondent bank deductions (estimated) $30–$50 $30–$50
Nigerian receiving bank fee $10–$15 $10–$15
Total fees $80–$105 $80–$105
As a percentage of transfer 16–21% 1.6–2.1%
USD received in domiciliary account $395–$420 $4,895–$4,920

‍

Also read: Sending USD from Nigeria to the USA: Step-by-step guide

Cheaper alternatives to a SWIFT wire transfer

For smaller or regular payments, the SWIFT route is difficult to justify. Here are the practical alternatives and when each one makes sense.

Multi-currency accounts (the recommended alternative for most senders)

Platforms like Grey provide USD accounts with US routing numbers and account numbers that senders can use to pay as a standard domestic US transfer, with no SWIFT correspondent chain involved.

The sender pays via ACH from their US bank account to a US account number. The money arrives in the recipient’s Grey USD balance without correspondent bank deductions. The recipient then controls when to convert or hold the USD. Multi-currency fintech accounts route payments through their own infrastructure rather than the SWIFT correspondent chain.

Grey’s deposit fee via ACH is 0.8%, capped at $10. On a $500 transfer, the fee is $4. On a $5,000 transfer, the fee is $10. Currency conversion is charged at 1% capped at $6 when the recipient converts to naira.

Stablecoin route

Some senders use USDC to move dollar value to Nigeria. The sender buys USDC on a US-licensed exchange, transfers to the recipient’s wallet address, and the recipient converts to USD or naira via a licensed Nigerian platform. This route avoids SWIFT entirely and can be faster, but requires both parties to be comfortable with crypto infrastructure and introduces volatility risk if either party converts at an unfavourable moment.

When SWIFT is still the right choice

If the recipient holds a domiciliary account and wants to receive funds in dollars without naira conversion, a bank wire is one of the most practical routes. SWIFT confirmations from US banks carry institutional credibility that other receipts may not in certain legal contexts. Nigerian property lawyers, courts, and some financial institutions require a bank-generated wire confirmation to authenticate a large transfer.

For transfers above $5,000 where the fixed fees are a small percentage, for institutional or legal documentation requirements, and for recipients who specifically need a SWIFT credit advice from a Nigerian bank, the traditional wire remains appropriate.

Sending USD to Nigeria with Grey

Grey provides a USD account with real US banking details, including a routing number and an account number issued by Grey's partner bank. Senders in the US use these details to pay as if they were paying any domestic US account. The payment goes out as a standard ACH transfer, bypasses the SWIFT correspondent chain entirely, and arrives in the recipient’s Grey USD balance within one to two business days.

For the recipient, the USD sits in their Grey account and can be held, converted to naira at a rate shown before confirmation, or used directly for USD-denominated expenses via the Grey virtual card.

The practical comparison on a $500 transfer: SWIFT costs $80 to $105 in stacked fees, leaving the recipient with $395 to $420. Grey costs $4 on the deposit, leaving the recipient with $496. On a monthly transfer of $500, that’s a difference of approximately $900 per year.

For senders who regularly send money to Nigeria with Grey, providing the Grey USD account details to the sender once removes all SWIFT complexity.

For those evaluating their full range of options, see our guide on sending money from the US for a broader comparison of methods and costs on the US-to-Nigeria corridor.

Send USD to Nigeria with Grey

Frequently asked questions on how to send USD from the USA to a Nigerian domiciliary account

Can I send USD to a Nigerian domiciliary account from the US?

Yes. A USD SWIFT wire from any US bank to a Nigerian domiciliary account is the standard method for sending dollars that land in Nigeria and remain there as dollars. You need the recipient’s domiciliary account number (not their naira account number), their bank’s SWIFT code, and the bank’s branch address. Alternatively, if the recipient holds a Grey USD account, you can send via ACH as a domestic US transfer, which avoids the SWIFT fee chain entirely.

How much does a SWIFT wire to a Nigerian domiciliary account cost?

Sending USD to a Nigerian domiciliary account via SWIFT can cost up to $60 to $100 in stacked fees across the three layers: the US bank’s outgoing wire fee ($35 to $50), correspondent bank deductions in transit ($10 to $30 per bank), and the Nigerian receiving bank’s incoming wire fee. These fees apply regardless of the transfer amount, which is why SWIFT wires only make financial sense on larger transfers where the fixed cost is a small percentage of the total.

How long does a SWIFT wire to Nigeria take?

SWIFT transfers to Nigeria typically take one to three business days after the US bank initiates the transfer. Large transfers may be held for CBN compliance review, which can extend the timeline. Transfers initiated late in the US banking day or on Fridays may not begin processing until the following business day. Grey ACH transfers to a US account number typically arrive in one to two business days.

Is there a cheaper way to get USD into Nigeria without using SWIFT?

Yes. A USD account through a multi-currency platform like Grey receives ACH transfers from US senders at a fraction of the cost of SWIFT transfers. Grey’s deposit fee is 0.8%, capped at $10, compared to $60-$100 in SWIFT fees for the same transfer. The tradeoff is that the USD lands in a Grey account rather than a Nigerian bank domiciliary account. For recipients who need SWIFT credit advice from a Nigerian bank for legal or institutional purposes, traditional wire transfers remain necessary. For everyday dollar receipts, the ACH route through Grey is significantly cheaper.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH incur a 0.8% fee (minimum $2, maximum $10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction.

How to convert and send USD to Ugandan Shillings (UGX) online

•

•

2 min read

Managing cross-border payments doesn’t have to be complicated. Whether you’re a freelancer, remote worker, or supporting family in Uganda, converting USD to Ugandan Shilling (UGX) can be quick, secure, and hassle-free with Grey.

This guide shows you how to easily convert and send USD to UGX online, highlighting key benefits, costs, and tips for seamless transactions.

Why use Grey to convert and send USD to UGX?

Grey is a digital banking platform designed for global citizens who want to manage multiple currencies easily. Here’s why Grey is an excellent choice for converting and sending USD to UGX:

  • Competitive exchange rates: Grey offers real-time rates to ensure you get the most value when converting USD to UGX.
  • Low fees: Avoid the high conversion and transfer fees associated with traditional banks.
  • Quick transfers: Funds are processed quickly, ensuring your recipients get the money without delays.
  • User-friendly platform: Grey’s app and website are designed to make international transactions simple and accessible for everyone.

Exchange rates fluctuate for various reasons, so we’ve designed a handy, real time currency converter for you.

Also read: How to convert and send USD with Grey

How to convert and send USD to UGX with Grey

1. Create your Grey account

First, sign up for a free Grey account via the website or app, available on iOS and Android. Registration is straightforward and requires you to:

  • Provide basic personal information.
  • Verify your identity by uploading the required documents.
  • Set up your virtual wallet for multiple currencies, including USD.

2. Add USD to your Grey account

Once your account is active, deposit USD into your Grey wallet. You can do this in several ways:

  • Bank transfer: Link your USD bank account and transfer funds directly.
  • Freelance platforms: Receive payments from platforms like Upwork or Fiverr directly into your Grey USD wallet.
  • Wire transfers: Accept payments from international clients or businesses.

With USD in your account, you can convert it into UGX.

3. Convert USD to Ugandan Shilling with Grey

Follow these steps to convert your USD to UGX:

  1. Log into your account: Open the Grey app or website and sign in.
  2. Navigate to currency exchange: Select the “Convert” option from the dashboard.
  3. Choose currencies: Select USD as the source currency and UGX as the destination currency.
  4. Enter the amount: Specify the amount of USD you want to convert.
  5. Confirm the transaction: Review the exchange rate, fees, and total amount in UGX, then click “Convert.” The converted funds will appear in your UGX wallet instantly.

4. Send UGX to your recipient

Once your USD is converted to UGX, it’s time to transfer the funds to your recipient in Uganda. Here’s how:

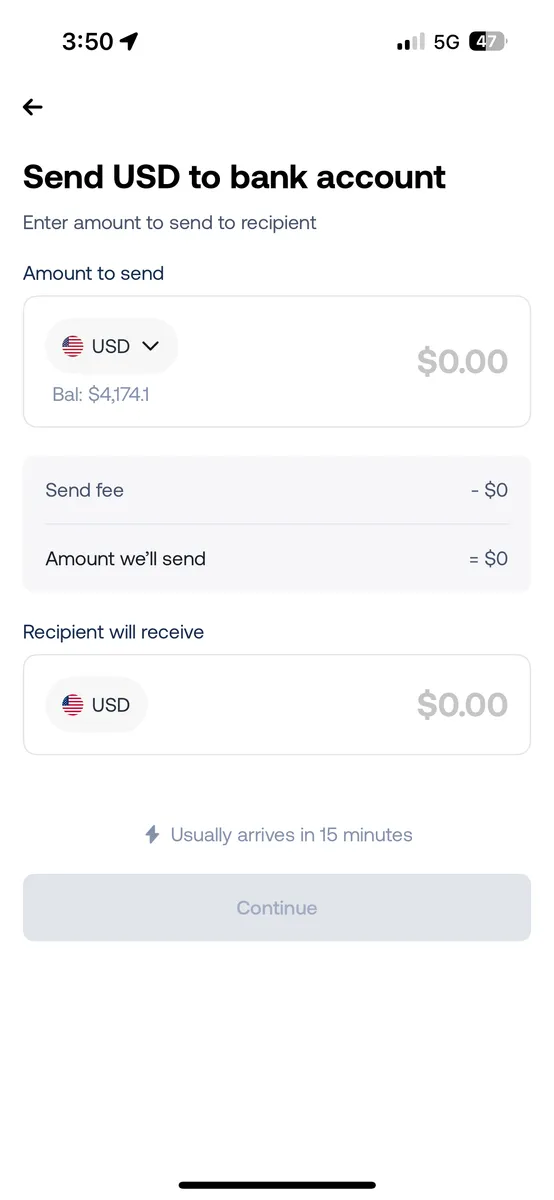
1. Navigate to the Send Money section: Choose the “Send” option in the Grey app.

676ec441190ed0b08ba00d26 676ebd9e62b40f1197672db7 send us dollars grey 6

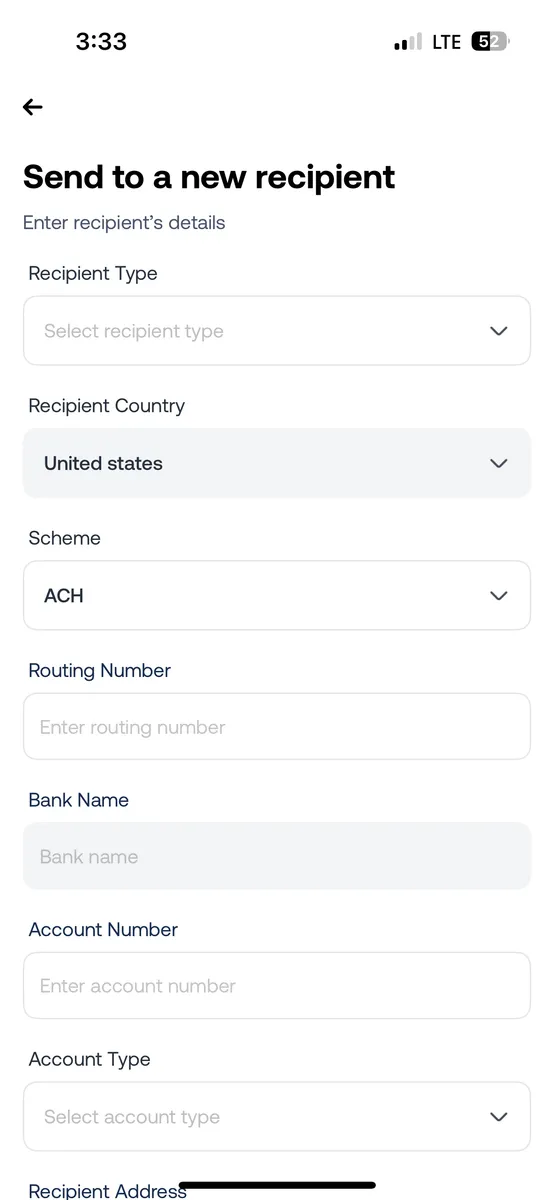
2. Enter the recipient’s details: Add the recipient’s bank account or wallet information. You can also send funds to another Grey user.

676ec442190ed0b08ba00d42 676ebd4d245072006253a99c send us dollars grey 4

3. Choose the amount to send: Enter the amount in USD or your currency (e.g., EUR).

676ec442190ed0b08ba00d3f 676ec3b94c9821344d4d5d63 IMG 0368

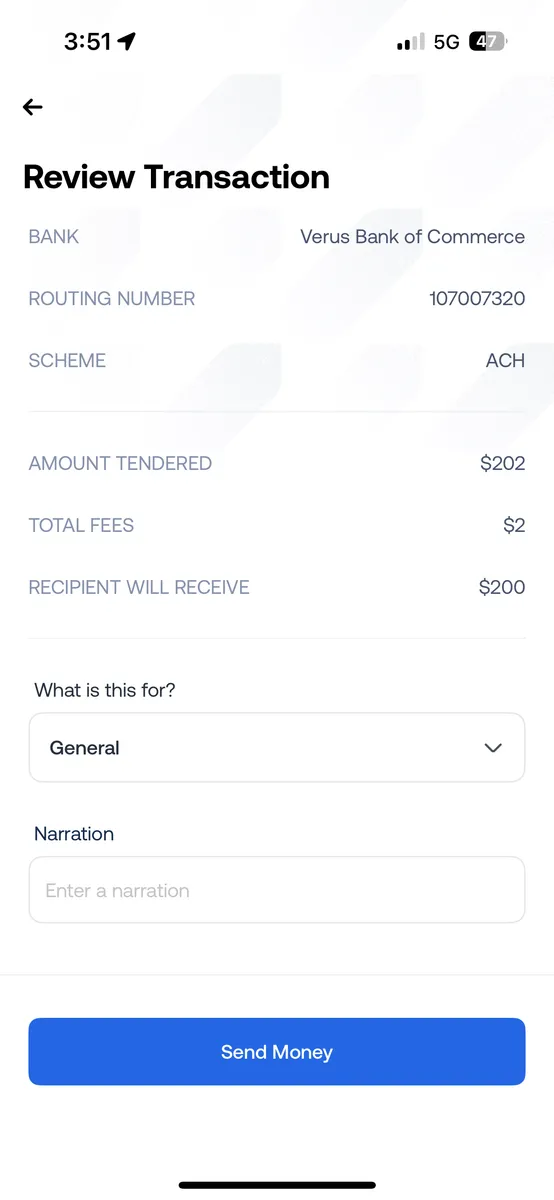
4. Review fees and exchange rates: Grey will estimate the fees and exchange rates so you know exactly how much the recipient will receive.

676ec442190ed0b08ba00d79 676ec3c426d44aa2a43d7fc8 IMG 0370

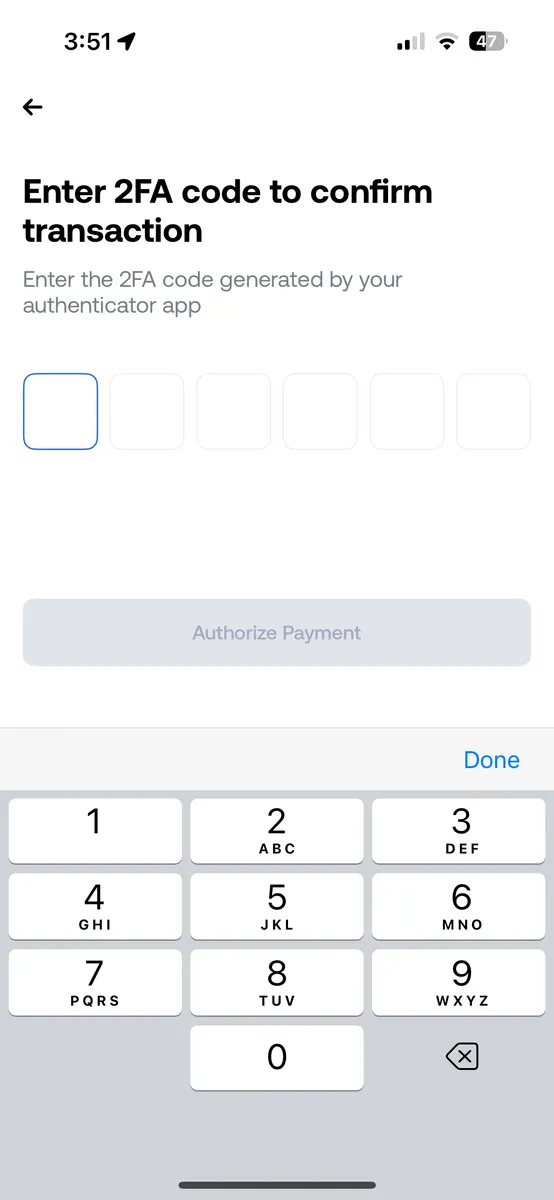
5. Complete the transaction: Confirm the details and authorise the payment. The recipient typically receives the funds in minutes to a few hours, depending on the payment method.

676ec442190ed0b08ba00d45 676ec3d1138ab1eb14571c89 IMG 0371

‍

‍You may also like: How to convert and send USD to TZS online

Key tips for converting and sending USD to UGX

  1. Monitor exchange rates: Keep an eye on the exchange rate to convert your funds at the best possible time.
  2. Double-check recipient details: Ensure the accuracy of bank account or mobile wallet information to avoid delays.
  3. Use Grey’s multi-currency wallets: Store USD and UGX in your Grey account to avoid frequent conversions and save on fees.
  4. Track your transactions: Grey offers a transaction history feature to easily track conversions and transfers.

Why Grey is the best option for USD to UGX transfers

Grey stands out as a reliable and cost-effective platform for handling international payments. Here’s why it’s a top choice:

  • Speed: Transfers are processed faster than most traditional banks, so your recipients get their money quickly.
  • Savings: With low fees and competitive exchange rates, you keep more of your hard-earned money.
  • Flexibility: Manage multiple currencies from one account and send funds anytime, anywhere.
  • Security: Grey prioritises secure transactions, giving you peace of mind.

Take control of your cross-border payments with Grey

Converting and sending USD to Ugandan Shilling has never been easier. Whether supporting family, paying vendors, or managing personal finances, Grey’s seamless platform saves you time, money, and effort.

Ready to simplify your financial transactions? Sign up with Grey today and enjoy a hassle-free way to convert and send USD to UGX online.

‍

How South African freelancers can receive payments from the US, UK & EU clients

•

•

2 min read

South Africa is home to a growing community of freelancers, remote workers, and digital entrepreneurs offering services to clients across the US, UK, and Europe.

However, while working with international clients can be highly rewarding, receiving payments remains a major challenge. High transfer fees, poor exchange rates, and long processing times often reduce earnings and cause unnecessary delays.

With a Grey account, freelancers in South Africa can receive payments in USD, GBP, and EUR, convert at competitive rates, and withdraw directly to their South African bank accounts.

Also read: How freelancers in Morocco can receive payments from US, UK & EU clients

How to open a USD, GBP or EUR account with Grey

1. Sign up for Grey

Creating an account with Grey is simple, requiring only a few personal details. Here’s what you need to do.

How South African freelancers can receive payments from the US, UK & EU clients
  • Choose your country: Select your current country of residence. This helps Grey tailor the setup to your location. In this case, it’s South Africa.
How South African freelancers can receive payments from the US, UK & EU clients
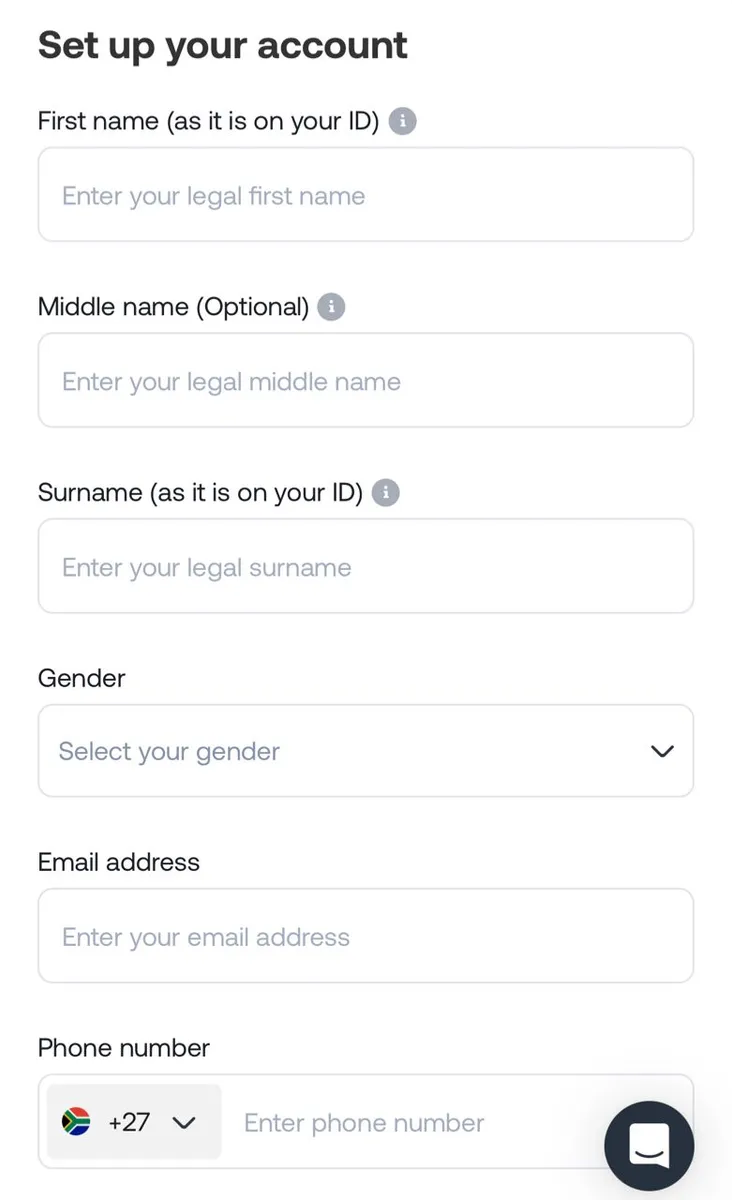
  • Enter your details: You’ll be prompted to provide your full name, email address, and phone number, then create a secure password.
How South African freelancers can receive payments from the US, UK & EU clients
  • Verify your email: Grey will send a one-time password (OTP) to your email address. Simply enter the code on the site to complete this step.
How South African freelancers can receive payments from the US, UK & EU clients
  • Once you’re set up, you’re ready for identity verification.

2. Verify your identity for secure access

Here’s what you’ll need to provide:

  • Government-issued ID: A valid passport or national ID card is required. Make sure it’s clear and up-to-date.
  • Proof of address: A recent utility bill or bank statement will verify your location. Grey uses this document to confirm your residency.
  • Submit your documents for review: Once uploaded, Grey will review your documents, a process that typically takes a few business days. Clear and accurate documentation speeds up approval.

3. Access your global bank accounts

Once your identity is verified, log in to your Grey account.

  • Navigate to the “Accounts” section and select “Create Account.”
  • Choose the currency (USD, GBP or EUR).
  • Your global bank account details, including your account number and routing number, will be generated instantly.

Also read: How to receive payments from Guru in South Africa in 2025

How to receive payments from US, UK & EU clients

Once you’ve created your Grey account, receiving payments is easy. Here’s how:

  • Log in to your Grey account via the app or website to securely access your currency balances.
  • Navigate to "Home" and select your preferred currency account (e.g., USD, EUR, GBP).
  • Share your account details (IBAN, sort code, or account number) with international clients, employers, or payment platforms like PayPal and Upwork.
  • The funds will be deposited into the Grey account.

Also read: How to receive Amazon payments in South Africa

Why Grey is the best online global bank for South African freelancers

Here are major reasons Grey stands out as the best online bank for freelancers in South Africa:

  • No hidden fees – Transparent pricing so you keep more of your earnings.
  • Hold multiple currencies – Manage your finances in USD, GBP, or EUR without forced conversions.
  • Fast international transfers – Receive and send money globally without delays.
  • Global access – Manage your money anytime, anywhere with Grey.
  • Direct withdrawals – Transfer funds seamlessly to your South African bank account.

Simplify banking across borders with Grey

Receiving international payments in South Africa doesn’t have to be complicated. With Grey, you can open a foreign bank account and accept payments seamlessly.

Create your Grey account today or download the app to enjoy inclusive global banking, designed for you to carry your dreams across borders.

‍

Arrow (up)

Back to top