


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#article","headline":"Best countries to work in Southeast Asia","description":"Are you looking for a work adventure in Southeast Asia? Discover the top Southeast Asian countries for work-life balance and career opportunities","inLanguage":"en","url":"https://grey.co/blog/best-countries-to-work-in-southeast-asia","mainEntityOfPage":{"@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#webpage"},"datePublished":"2025-01-31T08:52:34.860Z","dateModified":"2026-06-17T09:31:14.950Z","author":{"@type":"Person","@id":"https://grey.co/authors/toluwani-omotesho#person","name":"Toluwani Omotesho","url":"https://grey.co/authors/toluwani-omotesho"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/679c8ad10877efa8f382203e_Best%20countries%20to%20work%20in%20Southeast%20Asia.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/679c8ad10877efa8f382203e_Best%20countries%20to%20work%20in%20Southeast%20Asia.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#webpage","url":"https://grey.co/blog/best-countries-to-work-in-southeast-asia","name":"Best countries to work in Southeast Asia","description":"Are you looking for a work adventure in Southeast Asia? Discover the top Southeast Asian countries for work-life balance and career opportunities","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Best countries to work in Southeast Asia","item":"https://grey.co/blog/best-countries-to-work-in-southeast-asia"}]},{"@context":"https://schema.org","@type":"ItemList","@id":"https://grey.co/blog/best-countries-to-work-in-southeast-asia#list","name":"Best countries to work in Southeast Asia","numberOfItems":5,"itemListElement":[{"@type":"ListItem","position":1,"name":"Singapore","url":"https://grey.co/blog/how-to-receive-payments-on-etsy-as-a-seller-in-singapore"},{"@type":"ListItem","position":2,"name":"Malaysia"},{"@type":"ListItem","position":3,"name":"Thailand"},{"@type":"ListItem","position":4,"name":"Vietnam","url":"https://grey.co/blog/how-to-open-us-bank-accounts-in-vietnam"},{"@type":"ListItem","position":5,"name":"Indonesia"}]}] </script>

Best countries to work in Southeast Asia

Toluwani Omotesho

TABLE OF CONTENT

SHARE THIS POST

Southeast Asia is increasingly becoming a top destination for people seeking new career opportunities and a better quality of life. With its thriving economy, diverse culture and growing industries, it’s no surprise that many professionals are open to making the move.

Also read: Top 8 digital nomad cities for remote workers in Southeast Asia.

In this blog post, we’ll explore some of the best Southeast Asian countries to work in. But first, let’s discuss a few reasons why this region might be a good fit for you:

  • Cost of living: Southeast Asia is known for its relatively low cost of living. You can comfortably live in many countries for around $1000 per month, covering accommodation, transportation, and food. You can also access quality healthcare at reasonable prices, but we suggest getting health insurance as a safety net.
  • Career opportunities: With the fast-growing economy, several job opportunities exist across different sectors. Singapore and Malaysia are major hubs for finance, tech, and corporate roles, while Vietnam, Thailand, and Indonesia have booming startup and digital marketing sectors. There’s also a strong demand for English teachers, remote workers, and freelancers, making it an attractive destination for migrant professionals and digital nomads looking to grow their careers.
  • Ease of travel: Southeast Asia is known for its affordable transportation and well-connected cities, making it very travel-friendly. It’s also often regarded as a gateway to the rest of Asia as travellers can explore neighbouring cities and countries on a budget.
  • Coworking spaces: Southeast Asia has a great remote worker and digital nomad community, which has resulted in several coworking spaces. With strong internet, modern facilities, and flexible work options, you can easily work from anywhere while connecting with like-minded professionals.

Now that we understand why Southeast Asia might be a dream destination for yo, let’s look into some of the best countries to work in the region:

The top 5 Southeast Asian countries for working

Singapore

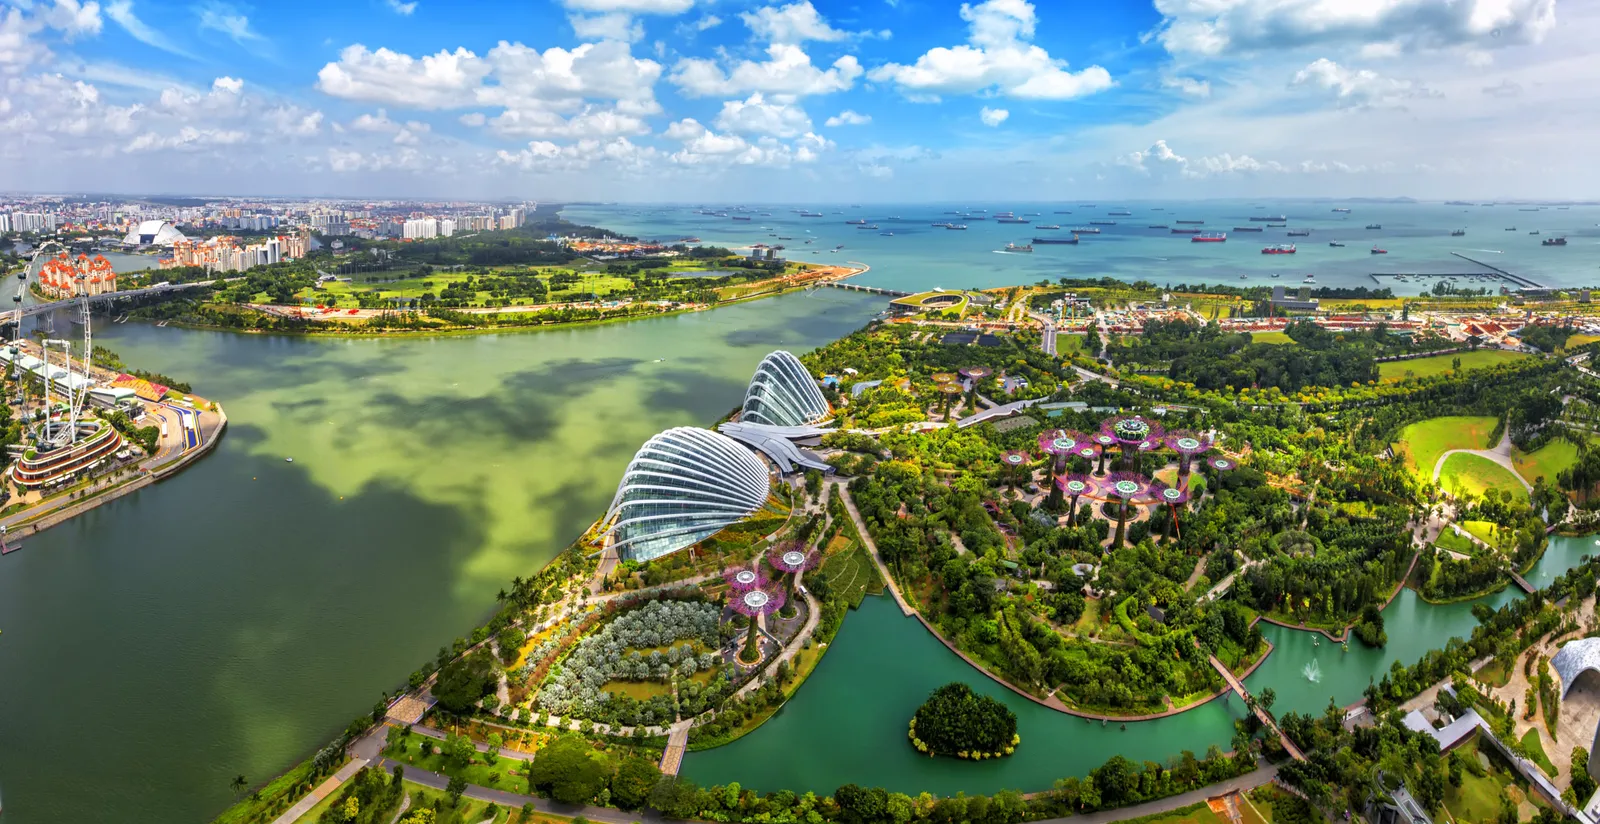
This small island country is one of the most developed in Southeast Asia, renowned for its high quality of life, business-friendly environment, and excellent infrastructure.

With an unemployment rate of 2.1% as of 2022, Singapore attracts professionals from all over the world, offering opportunities for career growth and lucrative salaries. Some industries with good employment opportunities include agritech, healthcare, finance and banking, pharmaceuticals, and aviation.

Southeast Asia country Grey

Singapore’s pro-business policies make it one of the easiest places in the world to start and grow a business. The business registration process is entirely online, takes only a few hours, and costs just $65, making it an attractive destination for entrepreneurs seeking a stable and supportive environment.

Also read: How to open US, UK and Euro bank accounts in Singapore

But beyond career prospects, Singapore offers an excellent quality of life. It has low crime rates with no corruption,  excellent healthcare, and a reputation for being one of the cleanest cities in the world. With English being its official language, migrants find it easier to adapt and feel comfortable.

However, you should know that Singapore’s cost of living is the highest in Southeast Asia, particularly for housing, so it’s crucial that you carefully manage your budget to maintain a comfortable lifestyle.

Malaysia

Malaysia is another popular choice for professionals looking to relocate for work. Its people are known to be friendly and polite, making you feel warm and welcome.

Malaysia southeast asia Grey
Lord Murugan Statue, Batu Caves

While English is widely spoken, Malay is the official language, so learning it can help with networking and socialising.

Malaysia also has a pro-business environment, and its developing economy ensures job opportunities in some of the most in-demand industries, including tourism, finance, healthcare, and information technology.

One of Malaysia’s most significant advantages is its affordability. Compared to Singapore, living costs are lower, making it easier to enjoy a comfortable lifestyle. The country has excellent infrastructure, modern amenities, and an efficient transport system, ensuring convenience for residents.

For remote workers and entrepreneurs, Malaysia has well-equipped coworking spaces and a thriving startup scene, making it an ideal place to live and work.

Also read: How to apply for a digital nomad visa in Malaysia

Thailand

Thailand is a top destination for digital nomads, remote workers, and young professionals. It offers modern infrastructure, career opportunities, and beautiful scenery that ensure a high quality of life.

With a low cost of living, you can enjoy comfortable housing for around $600 monthly, affordable food, and efficient transportation. Bangkok is a major business hub, while cities like Chiang Mai and Phuket attract freelancers, remote workers, and digital nomads with their relaxed atmosphere.

Beyond work, Thailand’s warm climate, stunning beaches, and rich culture make maintaining a healthy work-life balance easy.

Thailand southeast Asia Grey

English is widely spoken in business areas, learning basic Thai can be helpful in day-to-day interactions. The country also has a strong internet infrastructure and coworking spaces, making it ideal for remote workers.

However, the work visa process can be complex, and some jobs are restricted to locals. we put together a guide on how to apply for a Malaysia digital nomad visa.

Vietnam

In the 2024 InterNations Expat Insider report. Vietnam ranked first in Personal Finance and 14th in Working Abroad categories. These rankings show Vietnam’s economic growth and increasing appeal to young professionals and expats.

__wf_reserved_inherit
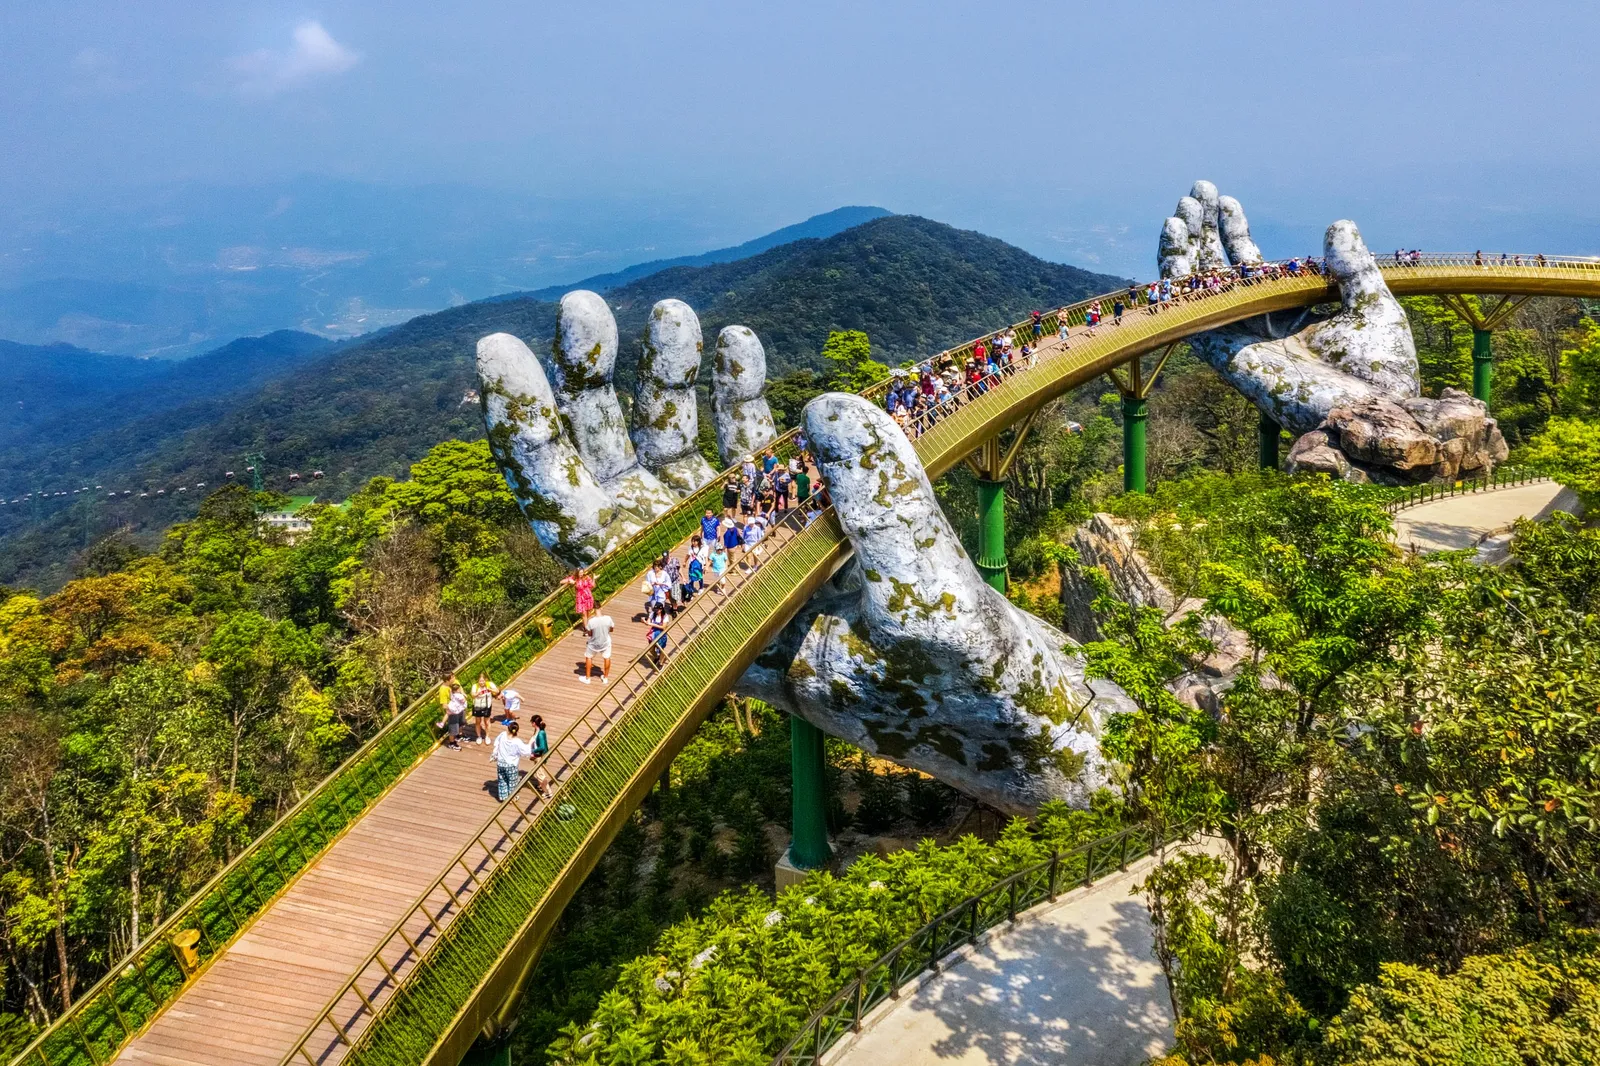
The Golden Bridge

With a rapidly expanding economy and booming sectors like technology, manufacturing, and finance, Vietnam offers promising job opportunities, especially in cities like Ho Chi Minh City and Hanoi. The cost of living is also one of the lowest in the region — 45% lower than in the US — making it easier to save money while enjoying a high quality of life.

To work in Vietnam, you’ll need a work visa (LD visa), valid for two years but tied to an employment contract.

Also read: How to open US bank accounts in Vietnam

Indonesia

Indonesia, famous for its stunning beaches, rich culture, and diverse cuisine, is a hotspot for digital nomads and has the largest economy in Southeast Asia.

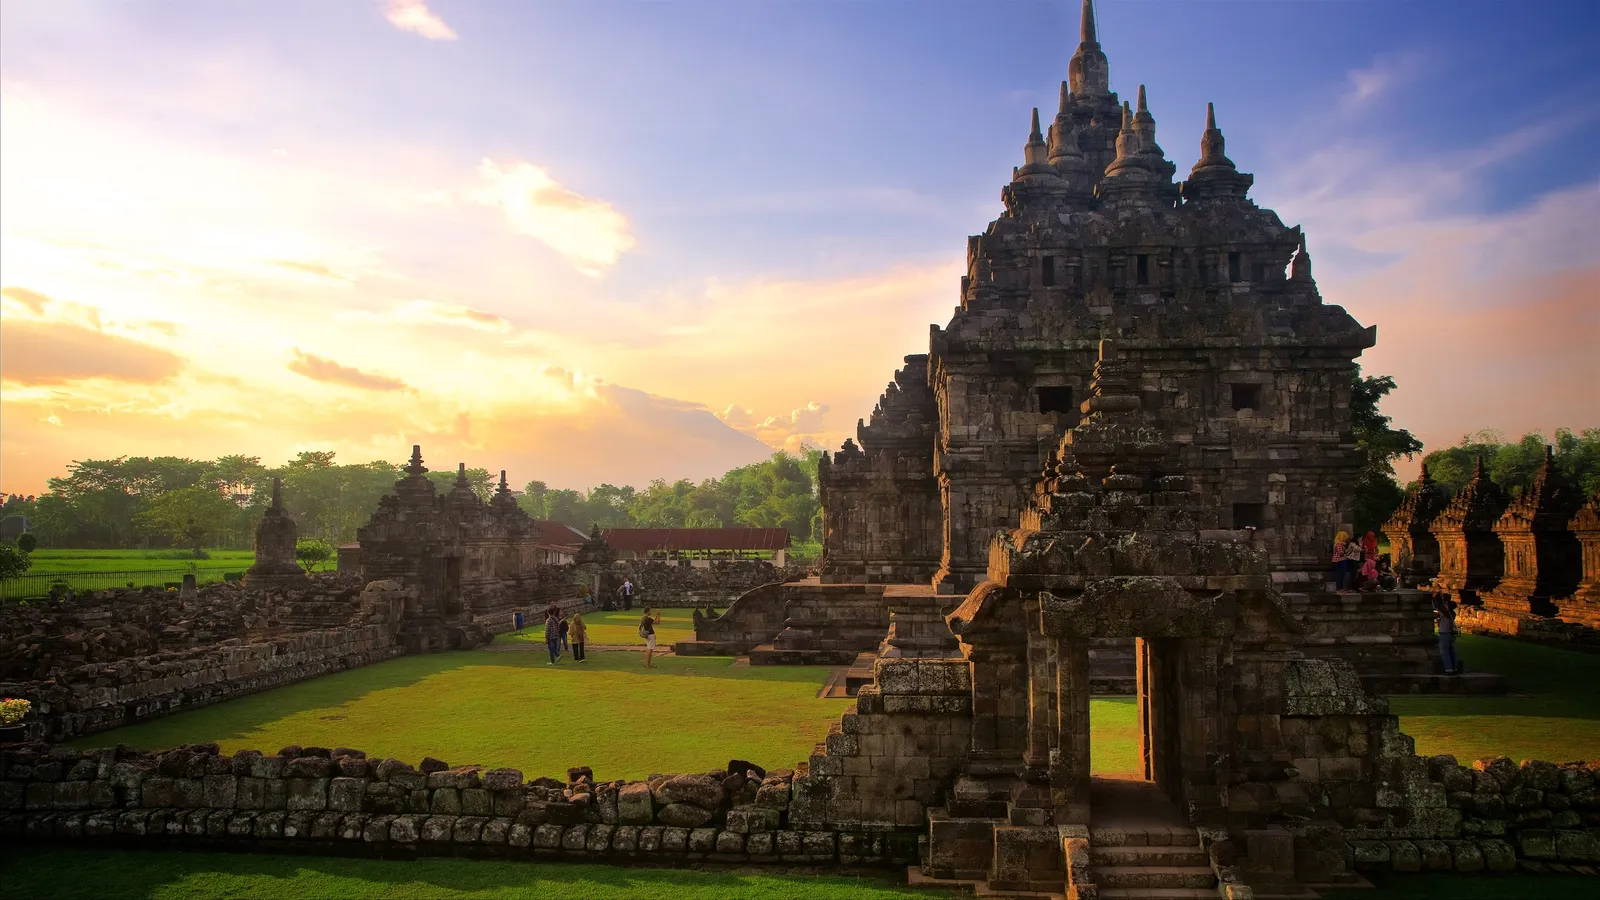
Indonesia Southeast Asia Grey
Prambanan Temple

Whether you’re interested in Bali’s remote work scene or the business hub of Jakarta, the country offers diverse career opportunities across different sectors, including manufacturing, mining, agriculture, and technology.

To work legally in Indonesia, you’ll need a work permit (KITAS), which an employer usually sponsors. The B211A visa is a popular short-term option for remote workers and freelancers, but digital nomads can apply for the Remote Worker Visa (E33G), which is valid for one year with the possibility of an extension.

The country’s work culture is generally more relaxed than Western corporate environments. It emphasises work-life balance, ensuring a good quality of life.

Conclusion

Regardless of the Southeast Asian country you decide to work in, rest assured that with Grey, you can experience life like a local. With our international bank accounts, you can make transactions seamlessly and securely. Open a Grey account today to get started.

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Managing remittances while working from abroad

•

•

2 min read

Working from abroad can be an incredible experience. You can explore new cities, meet new people, and get a fresh perspective on life. In addition, it’s an opportunity to help the people back home and sometimes, build businesses.

In 2024, the World Bank estimated that global remittances to low and middle-income countries reached over $650 billion, with workers abroad making up the bulk of that flow. Challenges like high fees, poor exchange rates, and unpredictable delays often disrupt that flow.

Here’s how you can manage those challenges and keep your remittances smooth, affordable, and stress-free, so you can focus on your work and life abroad without worrying about money transfers.

Also read: How to protect your funds while travelling abroad

Challenges of sending money while abroad

Living and working abroad is exciting, but sometimes, what should be a quick, straightforward transfer often leaves much to be desired.

Here are some of the biggest pain points remote workers and expats face:

  1. High transfer fees: Traditional banks and many remittance services take a sizeable cut, sometimes as much as 5–10% of your transfer. That’s money that could have gone straight to your loved ones.
  2. Poor exchange rates: Even a small difference in the foreign exchange rate can add up to a significant loss on larger transfers. Sometimes, the “bank rate” you’re offered is far worse than the real market rate.
  3. Slow processing times: While you can send an email instantly from anywhere in the world, an international wire transfer can still take several business days to clear. For urgent payments, that delay can be stressful.
  4. Limited payout networks: If your recipient lives in a country with fewer banking or payout options, they may have to travel far or wait longer to collect funds, adding more time and inconvenience.
  5. Hidden costs: Some providers apply receiving charges, intermediary bank fees, or mandatory conversion fees that you only discover after the transfer.

Also read: A freelancer’s guide to avoiding payment scams online

How can you manage remittances effectively?

With the right combination of planning and modern payment tools, you can send money across borders quickly, affordably, and with far fewer headaches. Here are a few tips that can help:

1. Map your routes before you send

Not all transfer paths are created equal. Bank wire, fintech transfer, card payout, and mobile money each have different speeds, fees, and success rates by corridor. Do a quick A/B test with small amounts to see which route lands fastest and cheapest for your destination.

2. Time your transfers with intention

FX moves daily. If you’re paid in a strong currency (e.g., USD/EUR) and sending to a weaker one, batching and converting on favourable days can add up. A nice hack is to set a target rate, and only convert when it’s at or above that line. When in doubt, split transfers, convert some now, hold some to hedge.

3. Avoid double conversions

For example, converting USD to EUR to KES means paying two spreads. Whenever possible, receive the currency you earn and send it in the currency your recipient needs with a single, transparent conversion.

4. Match the payout method to the recipient

Speed, convenience, and cost vary by recipient. A parent may prefer a direct bank credit, while a contractor might want mobile money for instant access. Ask what works for them, then optimise for that rail.

5. Keep a remittance buffer

If your pay fluctuates, hold a small cushion in the sending currency to avoid forced conversions on a bad FX day. Even 2–4 weeks of average transfers can protect you from swings.

6. Prioritise security and compliance

Stick to regulated platforms, complete KYC, and use two-factor authentication. If a service can’t tell you where your money is in the flow, that’s a red flag.

7. Choose a platform built for global workers

You want a fast and easy-to-use platform that works where your recipients live. A good example is Grey.

Also read: How to get paid as a creator on social media from anywhere in the world

With the right tools, you can support your loved ones from anywhere without any issues.

Create your Grey account today or download the app to enjoy inclusive global banking designed to carry your dreams across borders.


‍

Expat bank account before relocating: Full guide

•

•

2 min read

Moving to a new country can be physically and mentally stressful for expats, so setting up a bank account might not be an immediate priority. Most people focus their preparation on visas, housing, and shipping belongings. It is when they arrive that they realise they should have planned for how to manage their finances ahead.

Before relocating, set up banking that works from day one. Host-country banks often need a local address or residency permit you will not have on arrival, so open a multi-currency account you can use immediately, keep your home account open for existing commitments, and send a small test transfer before moving larger sums.

This article guides expats looking to open a bank account before relocation and provides a checklist of what you need to sort out before moving to a new country.

What to sort out before you move

Use this checklist to make sure your banking is squared away before your relocation.

  • Open an account you can use without a local address: Many banks require proof of a local address before opening an account. This can be difficult when you have just arrived and don’t have permanent accommodation yet. You can open a multi-currency account remotely, fund it, and use it to manage your finances while you sort out opening a local bank account.
  • Check which currencies you need: Consider which currency you will be paid in and which you will spend. For example, if you are moving from the US to Europe, you may still receive income in USD while paying for your local expenses in EUR. An account that lets you hold multiple currencies can help you manage both currencies without converting everything immediately.
  • Get a card before you travel: Having a virtual or physical card before you move gives you another way to pay for things when you arrive. It also means you are not relying entirely on your home bank card, which may charge foreign transaction fees or occasionally block transactions it considers unusual.
  • Test by sending a small amount: Before moving your relocation savings or a large amount to the new account, send a small amount first. This way, you can be sure your setup works. Check that it reaches the right account, arrives in the expected currency, and that there were no hidden fees. Once you confirm everything works, you can safely transfer larger amounts.
  • Notify your existing bank about your relocation: If you plan to keep using your current account, let your bank know that you will be moving abroad. Many banks flag transactions initiated from another country as potential fraud if you don’t tell them you are moving to that country.

For more tips on managing your money after relocating, see our guide on managing international payments while living abroad.

Why non-residents get blocked

Opening a local bank account can be difficult when you have just moved because you may not have the documents the bank requires. Here are some reasons you might struggle with opening an account abroad:

  • Proof of local address: Banks may ask for a tenancy agreement, utility bill or other document showing your name and address. If you are staying in a hotel or temporary accommodation, you may not have these documents yet, and won’t be able to open an account.
  • Residency or visa documents: Some banks require proof of your legal residency status before opening an account. Meanwhile, getting the right document might take weeks in some countries.
  • Proof of income or employment: Some banks may ask for an employment contract, payslip or other evidence of income. This can be difficult if you are still job hunting or you haven’t received your first local payslip.
  • No local credit history: In some countries, banks consider your credit history when opening certain account types. And since you are new to the country, you might find it difficult to open such accounts because you don’t financial history in that country.

Requirements for opening a bank account vary by country and bank, but many of the challenges are similar. A multi-currency account available remotely helps bridge the gap by giving you access to different currencies without requiring a local bank account in each country.

Should you keep your home bank account?

You do not necessarily need to close your home bank account when you move abroad. Whether you should keep it depends on your circumstances.

Reasons to keep your home account open

Keeping your existing account can make it easier to:

  • Pay existing direct debits and subscriptions
  • Continue mortgage, insurance or loan payments
  • Support family members at home
  • Access your existing credit cards and other financial products
  • Have a backup account if you return home
  • Receive payments that still come from your home country

Reasons to close it

Closing the account might make sense if:

  • You are paying fees for an account you no longer use
  • You no longer need any services connected to the account
  • Managing accounts in multiple countries creates unnecessary complexity
  • Your new country of residence has reporting or tax rules that make keeping certain accounts less convenient

Before closing your old account, check whether you still have any payments, subscriptions or other financial commitments linked to it.

Consider the tax implications

Moving abroad can also change your tax situation. For example, US citizens and residents who move abroad trigger an FBAR filing requirement if their total foreign account balance is more than $10,000 at any time during the calendar year. Also, once you own certain financial assets abroad, FATCA requires you to file Form 8938 with your regular tax return. can also create additional reporting requirements.

Confirm the tax implications for moving to another country. You can try finding out on your own or involving a tax professional before closing or keeping accounts.

For many people, keeping their existing account open initially is the safer option. You can close it later once you are settled and have confirmed that you no longer need it. Reopening an account from abroad can be much harder than simply keeping an existing one open.

Multi-currency accounts for expats

A multi-currency account can make managing money easier when you move abroad, especially if your income and expenses are in different currencies.

You can keep USD, EUR, and GBP in the same account instead of converting every payment to a single currency. You can then convert your money when you need to and see the exchange rate before you confirm the transaction.

If you move abroad for work but have not opened a local bank account yet, local receiving details in currencies such as USD, EUR, or GBP can give your employer or clients a way to pay you without waiting for your local bank account to be set up.

A virtual card linked to your multi-currency account lets you spend directly in the local currency without the foreign transaction fees that a home-country card typically applies to every purchase abroad.

Using a multicurrency account allows you to hold multiple currencies and convert whenever you like. Seeing the exchange rate and fees upfront also makes it easier to understand the true cost.

See our comparison of the best multi-currency accounts for non-residents.

Setting up before relocation with Grey

One advantage of a multi-currency account is that you can set it up before you leave your home country. This gives you access to your money while you are still sorting out local banking and accommodation.

With Grey, users can get USD, EUR, and GBP accounts with the relevant details. You also get a virtual card linked to your balances, which you can use to spend abroad from your first day.

Getting started on Grey requires verifying your identity with a valid ID, proof of your current address, and a photo. And within minutes, you can access USD, EUR, and GBP accounts that are ready to receive and send money.

Once you open a local bank account after moving, you can continue using Grey alongside it to hold and manage other currencies.

Open a Grey account before you move, and you can manage your finances from your first day abroad.

Frequently asked questions

Can I open an account before moving?

Yes. While a traditional bank in your destination country may require a local address or residency documents, some multi-currency accounts can be opened remotely before you move. This gives you a way to manage your money while you settle in.

Do I need a local address?

For a traditional local bank account in most destination countries, yes, almost universally. This is the single most common barrier new arrivals face, since proving a local address typically requires documentation (a tenancy agreement, utility bill) that you cannot produce until you have already secured housing, which itself sometimes requires a local bank account. A multi-currency account opened before you move avoids this specific barrier entirely, since it does not require a local address in your destination country.

Should I keep my home account open?

For many expats, keeping your home account open at least initially makes sense. It allows you to continue paying bills and other commitments, and provides a backup if your relocation plans change. However, check for account fees and any tax or reporting requirements that may apply after you become a tax resident elsewhere.

What account works from day one?

A multi-currency account that you can open remotely before travelling can give you access to banking services while you are still settling in. Grey offers eligible users USD, EUR and GBP accounts that can be set up online, along with a virtual card for spending.

Best apps for remote workers and global freelancers

•

•

2 min read

The rise of remote work and cross-border freelancing has transformed the way we live, work, and earn. But as freedom grows, so does the need for better tools to stay productive, connected, and financially savvy. The right apps can make all the difference.

I’ve packed the ultimate toolkit with the best apps that every remote worker and freelancer should have and separated them according to their use case.

Also read: Mistakes you are making as a remote worker

1. Communication

Clear, fast communication is key when you’re not sitting across from your teammates or clients.

Slack

Best for: Team chats, quick updates, and async conversations

Why it stands out: Channels keep things organised, and integrations with tools like Google Drive, Notion, and Trello make it easy to centralise your workflow.

Zoom

Best for: Video calls, virtual meetings, workshops

Why it stands out: Still the gold standard for reliable virtual calls. Plus, the ability to record meetings is great for revisiting client briefs or creative sessions.

Also read: A complete guide to budgeting as a remote worker

2. Project management

Freelancing or working remotely means juggling multiple projects. These tools help keep everything from slipping through the cracks.

Trello

Best for: Visual task management

Why it stands out: Kanban boards make it easy to track projects, deadlines, and progress at a glance. It’s ideal for creatives and freelancers.

Notion

Best for: Customisable workspaces

Why it stands out: It is one tool for everything, including documents, calendars, wikis, and task lists. This makes it especially powerful if you love building your own workflows.

ClickUp

Best for: Scalable project management

Why it stands out: It combines task management, docs, goals, and time tracking in one place. It’s great if you’re growing your freelance team.

Also read: Earning in USD? Here’s how to receive your salary as a remote worker

3. Time management

When your time equals money, staying focused is everything.

Toggl Track

Best for: Time tracking and invoicing

Why it stands out: It has simple, user-friendly time tracking with reports and billable hours built in. It’s perfect for freelancers billing by the hour.

Clockify

Best for: Free time tracking and productivity monitoring

Why it stands out: Unlimited projects and team tracking, even on the free plan. Works well for solo freelancers or small remote teams.

4. File sharing & storage

Cloud storage is your best friend when your office is a coffee shop in Lisbon or a co-working space in Nairobi.

Google drive

Best for: File sharing and real-time collaboration

Why it stands out: Generous free storage, integrates with Docs, Sheets, and Slides. Great for client-facing work.

Dropbox

Best for: Secure file storage and backup

Why it stands out: Easy syncing across devices and strong file versioning. Reliable even for large media files.

5. Finance & payments

Managing cross-border payments and currency conversion is a major pain point, especially for freelancers. These tools can help you receive payments efficiently and save on fees.

Grey

Best for: Receiving and converting international payments

Why it stands out: Offers USD, EUR, and GBP accounts you can use to get paid by clients abroad. Real-time conversion to your local currency at competitive rates, with fast local withdrawals. No monthly fees.

It’s perfect for freelancers in Africa, Asia, and Latin America who are working with international clients.

Create your free Grey account to get started.

Payoneer

Best for: Global freelance marketplaces

Why it stands out: It is widely accepted on platforms like Fiverr and Upwork and is good for receiving marketplace payments into local bank accounts.

Wise

Best for: Transparent currency conversion

Why it stands out: Mid-market exchange rates with low, upfront fees. Great for sending money to yourself across borders.

Also read: How to get paid as a remote worker without a PayPal account

6. Invoicing

Don’t let a messy invoice delay your payments.

Wave

Best for: Free invoicing

Why it stands out: Create, send, and track invoices, completely free. Also includes accounting tools if you want more features.

Invoice Ninja

Best for: Freelancers with global clients

Why it stands out: It lets you create invoices in multiple languages and currencies and tracks time and expenses.

7. Security

Working remotely means you’re in charge of your own IT setup. Security is not optional.

1Password

Best for: Password management

Why it stands out: Store and generate strong passwords. Share credentials safely with teams or clients.

NordVPN

Best for: Secure connections while travelling

Why it stands out: Protects your internet activity, especially on public Wi-Fi. Lets you access geo-restricted services too.

Also read: Essential tools every remote worker in Africa needs

Being a remote worker or global freelancer doesn’t mean going it alone. With the right tools, you can simplify your workflow, get paid on time, and stay productive no matter where you are.

Start by choosing a few apps that solve your biggest pain points, then build from there. And if you're looking for the easiest way to manage international earnings, Grey has your back.

Create your Grey account today or download the app to enjoy inclusive global banking designed to carry your dreams across borders.

‍

Can you work remotely while travelling on a tourist visa?

•

•

2 min read

If you’re working remotely while bouncing between countries, there’s one question you’ve probably asked yourself, maybe even a little nervously: “Can I actually work on a tourist visa?”

Let’s examine the rules, what remote workers are doing in practice, and how to navigate the blurred lines of digital nomad life without getting into legal trouble.

What is a tourist visa, and what is it really for?

A tourist visa is typically meant for, well, tourism. That means sightseeing, visiting friends or family, and maybe short courses or conferences — but not working, at least not in the traditional sense.

Most tourist visas specifically prohibit “gainful employment” or “engaging in work.” But here’s where it gets tricky: working remotely for a company or clients outside the country you’re visiting isn’t always clearly addressed.

The truth? Many governments simply haven’t caught up with the remote work boom.

Also read: Visa 101: A comprehensive guide to different types of visas

So... Can you work remotely on a tourist visa?

Technically, in most cases, no. But enforcement and interpretation vary.

Let’s say you’re a Nigerian software developer employed by a UK company and you’re spending two months in Portugal on a tourist visa. You’re not working for a Portuguese client, you’re not taking a local job, and your income doesn’t flow into the country.

From a practical standpoint, you’re not competing in the local labour market, so many remote workers assume this is okay. And in most cases, immigration officials don’t check what you’re doing on your laptop at a co-working space.

But there are still risks.

What are the risks of working on a tourist visa?

Even if you’re not breaking local labour laws, working remotely on a tourist visa might still violate visa conditions. That can lead to:

  • Fines
  • Visa revocation
  • Entry bans
  • Being flagged for future applications

It doesn’t happen often, but it does happen. And it’s more likely if you overstay, draw attention, or try to enter countries with strict border rules multiple times in a short period.

Also read: Top countries for Latin America digital nomad visas

The safer option: digital nomad visas

To keep up with the rise of remote workers, some countries now offer digital nomad visas, which are legal permits that let you live and work without a local employer.

Examples include:

These visas usually require:

  • Proof of remote employment or freelance work
  • Minimum income thresholds
  • Health insurance coverage
  • Application fees

While they take a bit more paperwork, they give you peace of mind and sometimes even perks like tax incentives or longer stays.

What’s the right move for you?

If you’re on a short trip, a tourist visa may be fine, especially if your work is low-profile and your stay is brief. But if you plan to stay in one country for months, or work with local clients, it’s worth looking into proper remote work or digital nomad visas.

The good news is that more countries are embracing the digital nomad lifestyle, and the legal pathways are expanding fast.

Also read: The cheapest digital nomad visas in the world

Remote work allows you to work from anywhere, but before you go anywhere, research and know the visa terms.

Create your Grey account today or download the app to enjoy inclusive global banking designed to carry your dreams across borders.

‍

How to protect your funds while travelling abroad

•

•

2 min read

Travelling abroad can be one of life’s most rewarding experiences. There are new cities, fresh cuisines, and unexpected adventures. The one adventure you definitely don’t want is losing access to your money.

A stolen card, a suspicious transaction, or sudden currency restrictions are typical money troubles that can turn a dream trip into a stressful nightmare. The good news? With a few smart steps, you can enjoy your travels and keep your funds safe no matter where in the world you are.

Here’s your complete guide to protecting your money while travelling internationally.

Also read: Working with international clients: A freelancer’s guide to getting paid

1. Diversify how you carry your money

Relying on a single debit card or one stash of cash is dangerous, especially when travelling. If your card gets blocked or lost, you could be stranded without access to your money.

A better approach:

  • Mix it up: Carry different payment methods. I suggest a primary debit card, a backup credit card, and local currency for small purchases or emergencies.
  • Keep spares safe: Store one backup card somewhere separate from your main wallet, like a hotel safe or a discreet compartment in your luggage.
  • Set up an emergency-only account: Keep a small reserve of funds in a separate account you can access online if your main one is compromised.

By spreading your options, you’re building financial resilience. Even if one payment method fails, you’ve got plans B (and C) ready to go.

2. Use a trusted global banking solution

Nothing kills the vibe faster than your card getting declined because your local bank didn’t like the transaction. Okay, maybe watching a percentage of your hard-earned money vanish as hidden FX fees is a little worse than that.

A truly global banking solution changes everything. Instead of juggling multiple bank accounts, currencies, and time zones, you can run your finances from one secure platform, no matter where you are.

With Grey, for example, you can:

  • Hold multiple currencies (USD, GBP, EUR) in one account, so you’re always ready to receive or spend in your client’s currency.
  • Shop and pay globally with virtual USD cards that protect you from card cloning or fraud.
  • Convert money at competitive rates without the outrageous markups banks sneak in.
  • Withdraw in local currency without worrying about your funds getting trapped in international banking delays.

It’s the difference between hoping your money arrives and knowing it will.

3. Enable security alerts and two-factor authentication

Before you travel, flip on every security feature your bank and fintech app offer. Instant alerts and two-factor authentication give you the split-second advantage. You see a suspicious charge the moment it lands and stop attackers from getting in, even if they have your password.

What to do right now:

  1. Turn on transaction notifications: Enable push notifications and email alerts for all account activity — incoming deposits, withdrawals, attempted logins, and card payments. Set low thresholds (e.g., notify me for any debit over $1) so nothing slips past you.
  2. Choose authenticator apps over SMS: SMS 2FA is better than nothing, but vulnerable to SIM-swap attacks. Use an authenticator app (Authy, Google Authenticator, Microsoft Authenticator) for time-based one-time codes. If your fintech supports hardware keys (YubiKey, Titan), consider those for the highest security.
  3. Secure your 2fa backups: Save backup/recovery codes in a safe place like an encrypted note in a password manager, or an encrypted USB. Don’t email them or keep them on an unlocked cloud folder.
  4. Register a secondary device: Add a tablet or spare phone as a backup 2FA device so you’re not locked out if your main phone is lost or stolen.
  5. Check and prune connected devices: Regularly review active sessions in your banking apps and web services; sign out devices you don’t recognise.

4. Avoid public Wi-Fi for transactions

Free airport Wi-Fi feels like a travel win, perfect for scrolling social media or catching up on Netflix. But when checking your bank balance, paying invoices, or moving money around, that same network could be a hacker’s playground.

Public networks are often unsecured, meaning anyone with the right tools could intercept your data. And if you’re a remote worker or freelancer handling client payments, that’s a risk you simply can’t afford.

If you absolutely must access your accounts online:

  • Stick to mobile data or your own hotspot. Your personal connection is far more secure than public Wi-Fi.
  • Use a VPN (Virtual Private Network). It encrypts your browsing, making it much harder for anyone to snoop on your activity even if you’re connected to public Wi-Fi..

5. Keep your physical cards safe

Nothing can ruin a trip faster than losing access to your money because your card has been lost, stolen, or cloned. It’s still one of the most common and most stressful travel money mishaps.

  • Protect against electronic theft: Use an RFID-blocking wallet or card sleeve to guard against contactless skimming, especially in busy tourist spots or public transport.
  • Never let your card out of sight: If a merchant needs to process a payment, request that they bring the terminal to you. Handing your card over in a back room is an open invitation for fraud.
  • Carry a backup card: Keep a spare debit or credit card in a different bag, pocket, or hotel safe. If your main wallet is lost or stolen, you still have a lifeline.
  • Stay alert with notifications: Enable instant transaction alerts from your bank or payment app so you can spot suspicious activity the moment it happens.

6. Get familiar with the local currency and payment culture

Money works differently around the world. In some places, cash is still the norm, in others, you might get strange looks when offering a banknote instead of tapping your card or phone.

For example, Japan and Morocco still have plenty of cash-only cafés, markets, and small businesses. Sweden, on the other hand, is practically cashless. You could go days without seeing a single coin or note.

By understanding the local payment culture before you arrive, you’ll avoid awkward “sorry, we don’t take cards” moments or getting hit with surprise withdrawal fees.

Here’s what to research in advance:

  • ATM limits and fees: Know how much you can withdraw per day and what your bank or card provider charges.
  • Popular payment methods: Are mobile wallets like Apple Pay, M-Pesa, or Alipay widely accepted?
  • Currency regulations: Some countries limit how much foreign currency you can bring in or take out.
  • Exchange rate hacks: Learn whether you’ll get better rates at ATMs, banks, or currency exchanges.

A little homework here means you’ll land ready to pay your way like a local.

7. Always have an emergency plan

Even the most seasoned remote workers encounter unexpected bumps. The key is being ready before things go wrong.

Here’s how to build a safety net:

  • Save key contacts: Keep the customer service numbers and support emails for your bank, and any payment providers stored in your phone (and written down somewhere safe in case your phone dies).
  • Carry a universal backup currency: A small stash of cash in widely accepted currencies like USD or EUR can be a lifesaver where card systems go down or local ATMs are unreliable.
  • Have a trusted point of contact: Share your travel plans, key account details (securely), and backup payment options with a trusted friend or family member who can step in if you get stuck.
  • Know your digital backups: Keep scanned copies of important documents (passport, IDs, bank cards) in a secure cloud folder to access them anywhere in the world.

Also read: A freelancer’s guide to avoiding payment scams online

Protecting your funds while travelling isn’t about paranoia but preparation. With the right mix of secure banking tools, diverse payment methods, and smart money habits, you can explore the world without stressing over every transaction. Create your Grey account today or download the app to enjoy inclusive global banking designed to carry your dreams across borders.

‍

What no one tells you about earning in dollars while living abroad

•

•

2 min read

Earning in USD while living outside the US seems to be the goal of many entrepreneurs, freelancers and remote workers, especially when you live in a country with a relatively lower living cost. Receiving payments in USD protects against local currency fluctuations and opens you up to a global client base.

While this goal is feasible, it can be cumbersome if you don’t know how to navigate international payments. This article exposes the secrets of international payments that people have been hiding from you. Here are the things no one tells you about earning in dollars while living abroad.

Also read: Working with international clients: A freelancer’s guide to getting paid

1. Currency conversion isn’t always straightforward

If you think all the money the client sends will end up with you after converting to your local currency, you will be making a bad assumption. It might shock you to realise how much money is lost to payment solutions and traditional banks. This means that by the time you convert your hard-earned dollars into local currency, a significant portion of your income has vanished.

Hidden charges such as “processing fees” or “international transfer costs” further eat into your income. For freelancers and small business owners, especially, these costs can quickly add up and erode profit margins. To mitigate against this, Grey is a freelancer-friendly payment option that offers you transparent and affordable charges with competitive exchange rates.

2. Local banking systems may not support seamless USD transactions

Your conventional bank account may not be able to accept USD payments. Many local banks can’t handle international payments, and it will be a good idea to figure that out before you provide your account details to a client. Many other banks offer high transaction charges, unfavourable exchange rates, and frustratingly slow transaction processing. In some settings, your account may even be flagged due to suspicion and might take some time to resolve the dispute.

To be safe, you should receive your payment in a USD account where you can hold funds or spend in USD and convert to your local currency at will. Grey offers multi-currency accounts that enable users to transact in USD, EUR, GBP, USDC, and numerous other local currencies with ease.

3. Exchange rate fluctuations can ruin your financial plan

Earning in USD and spending a relatively volatile local currency means you cannot be certain of your take-home monthly, even if your pay in USD remains the same. If the dollar strengthens, your purchasing power increases. But when it weakens, your income may feel much smaller in the local economy.

These fluctuations can disrupt budgeting, savings plans, and even investment strategies. Many professionals underestimate the stress of planning long-term financial goals when their effective income fluctuates from month to month.

Read our freelancer's guide to handling currency fluctuations to learn more.

4. Tax implications

You may be subject to taxes in both your country of residence and the country where your dollar income originates. Understanding and navigating these tax obligations can be complex. Without clear guidance, it is easy to fall into the trap of double taxation. Some countries have arrangements to avoid this, but others don’t. You must keep detailed records, consult tax professionals where necessary, and ensure compliance with both local and international regulations if you are earning in USD.

5. USD payments don’t always arrive early

Clients abroad may operate in different time zones, banking systems, or legal frameworks, leading to payment delays. Freelancers and contractors often complain about not receiving money on time, sometimes waiting weeks beyond the agreed payment day.

This unpredictability makes it difficult to maintain a consistent cash flow, particularly if you rely solely on international income. Without a reliable payment structure, even the most lucrative contracts can become frustrating.

Earning in USD without hassles

There is a lot you find out when you start earning in USD. While it is a dream, earning in USD is also not always a walk in the park. Between navigating payment delays, exchange fluctuations, and transaction charges, you require a reliable payment solution.

Grey offers multi-currency accounts and supports USD transactions. With Grey’s USD accounts, you can receive USD payments swiftly and convert at competitive rates.

Get started with Grey today to manage your USD payments hassle-free.

‍

Arrow (up)

Back to top