<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens#article","headline":"Indonesia visa requirements for EU citizens","description":"Discover the visa requirements for EU citizens travelling to Indonesia, including essential tips and how to manage international payments with Grey.","inLanguage":"en","url":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens","mainEntityOfPage":{"@id":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens#webpage"},"datePublished":"2025-03-27T17:28:59.281Z","dateModified":"2026-06-15T15:04:03.974Z","author":{"@type":"Person","@id":"https://grey.co/authors/priscila-marotti#person","name":"Priscila Marotti","url":"https://grey.co/authors/priscila-marotti","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/priscila-marotti/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a30146310330dda2a30d508_6a30146226b060918d805e83_indonesia-visa-requirements-for-eu-citizens__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a30146310330dda2a30d508_6a30146226b060918d805e83_indonesia-visa-requirements-for-eu-citizens__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens#webpage","url":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens","name":"Indonesia visa requirements for EU citizens","description":"Discover the visa requirements for EU citizens travelling to Indonesia, including essential tips and how to manage international payments with Grey.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Indonesia visa requirements for EU citizens","item":"https://grey.co/blog/indonesia-visa-requirements-for-eu-citizens"}]}] </script>

Indonesia visa requirements for EU citizens

Priscila Marotti

TABLE OF CONTENT

SHARE THIS POST

From the stunning beaches of Bali to the cultural richness of Yogyakarta, Indonesia is every tourist's dream. But before packing our bags, we need to figure out the visa requirements for EU citizens. If you’re planning a trip to Indonesia, here’s everything you need to know about getting the right visa.

Visa-free entry for short stays

For many EU citizens, visiting Indonesia for a short holiday is incredibly simple. Indonesia offers visa-free entry for up to 30 days for passport holders from most European Union countries. This is perfect for tourists who plan to explore the country briefly without worrying about extra paperwork.

However, there are a few things to keep in mind:

  • The visa-free entry is non-extendable, so if you plan to stay longer than 30 days, you'll need to apply for a visa before arriving.
  • You must enter and exit through designated international airports or seaports that allow visa-free travel.
  • Your passport should be valid for at least six months from the date of arrival.
  • You need a return or onward ticket to prove you won’t overstay.

For official information, you can check the Indonesian Directorate General of Immigration’s website.

Also read: Top travel destinations in Indonesia for summer vacation

Visa on arrival (VOA) for extended stays

If 30 days isn’t enough, you can opt for a Visa on Arrival (VOA), which allows you to stay in Indonesia for up to 60 days. This visa is granted for 30 days initially but can be extended once for another 30 days at an immigration office.

Key details:

  • The VOA costs $35, payable in cash or by card upon arrival.
  • You can apply for an extension before the first 30 days expire.
  • The VOA is available at major international airports and seaports, including Jakarta, Bali, and Surabaya.

For more details and updates on visa fees, visit Indonesia’s immigration website.

Applying for a visa before arrival

For those planning to stay longer or for purposes beyond tourism (such as work or study), you’ll need to apply for a visa before entering Indonesia.

Single-entry tourist visa

If you want to stay beyond 60 days, a single-entry tourist visa allows you to stay for up to 60 days, with the option of extending it for another 30 days. You need to apply at an Indonesian embassy or consulate in your home country before travelling.

Multiple-entry visa

Frequent travellers to Indonesia can apply for a multiple-entry visa, which is valid for one year, allowing stays of up to 60 days per visit. This is ideal for business visitors or those who plan to visit multiple times.

Digital nomad and remote work considerations

Indonesia is a hotspot for digital nomads, especially in Bali. While there is no official digital nomad visa yet, many remote workers enter the country on a business visa (B211A) or a social-cultural visa. These visas allow longer stays but may require sponsorship from an Indonesian company or organisation.

Stay updated on long-term visa options via Indonesia’s official immigration website.

You may also like: How to apply for a digital nomad visa in Indonesia

Important travel tips

Before you embark on your journey to Indonesia, it’s essential to keep a few important travel tips in mind. These can help ensure a smooth trip, avoid unexpected fines, and make your stay more comfortable. Here are some key things to remember:

  • Overstaying penalties: If you exceed your permitted stay, you’ll be fined IDR 1,000,000 (around $65) per day. Long overstays could lead to deportation.
  • Proof of funds: Some visas require you to show sufficient funds for your stay. Carrying a bank statement or proof of income can help.
  • Travel insurance: While not a visa requirement, having travel insurance is highly recommended for medical emergencies and trip cancellations.

Managing finances in Indonesia with Grey

Travelling in Indonesia requires efficient financial management. Grey simplifies international transactions for tourists:

Multi-currency accounts: Hold and manage funds in IDR, USD, EUR, and GBP with Grey.

Competitive exchange rates: Convert currencies at low fees and real-time rates.

Fast international transfers: Send and receive money seamlessly.

Secure mobile banking: Manage your travel expenses through the Grey app.

How to open a Grey account to use in Indonesia

  1. Sign up: Register on the Grey website or download the app.
  2. Verify your identity: Submit a valid passport, proof of address, and a selfie for verification.
  3. Access global bank accounts: Instantly receive USD, EUR, and GBP accounts for seamless transactions.

Grey makes financial management in Indonesia seamless. Create your Grey account today or download the app to enjoy inclusive global banking.

Also read: How to open US and UK bank accounts in Indonesia

Enjoy a smooth Indonesia visa experience

Indonesia is a breathtaking destination, and navigating the visa process as an EU citizen is relatively straightforward. Whether you’re visiting for a short getaway, an extended adventure, or even remote work, planning ahead ensures a hassle-free experience.

Before you book your flight, double-check the latest visa requirements on Indonesia’s official immigration website or consult your nearest Indonesian consulate. Safe travels!

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

What to do if your payment platform delays your payout

•

•

2 min read

Few things are as frustrating as waiting for money you’ve already earned. You’ve delivered the work, the client has paid, and you’re counting on that money to hit your account, only to realise your payment platform is taking forever. Suddenly, your bills, rent, or weekend plans are on hold because of a “processing delay.”

If you’ve ever been in this situation, you know it can feel helpless. However, with the right steps, you can take control, troubleshoot the problem, and ensure you’re not stuck waiting indefinitely.

Let’s break down exactly what to do when your payment platform drags its feet.

Also read: Global accounts vs traditional banks: What remote workers should know

1. First, don’t panic. Check the expected payout window

One of the most common mistakes freelancers make is assuming their money is “late” when on the contrary, the payment platform is following its regular payout cycle. Every platform has its own rhythm, and it’s worth learning it like the back of your hand.

Take PayPal, for instance. Transfers to your bank usually take between one and five business days. Upwork doesn’t pay you right away either. Once a client approves your work, there’s a five-day security hold before the money hits your balance. Fiverr even takes it a step further. Earnings sit in clearance for 14 days after you deliver (seven if you’ve reached top-rated status).

It might be frustrating, but this is how the system works. Before worrying, always double-check the payout windows listed in the platform’s FAQ or support section.

Here’s a smart move: keep a small “payout calendar.” Set reminders for each platform you use so you always know when to expect your earnings. That way, you can plan your expenses around real timelines, instead of stressing over money that may not be late.

Also read: The ultimate guide to using virtual accounts for global payments in 2025

2. Check for account or compliance holds

One of the most common reasons your money may not land sooner is the platform’s compliance rules. These platforms run on strict rules, and the moment something looks unusual, they’re quick to hit pause. Think of it as a safety lock to protect you and them. However, it can feel frustrating when your earnings get stuck in limbo.

Sometimes, the issue is as simple as missing paperwork. If you haven’t completed KYC (Know Your Customer) verification, like uploading your ID, business registration documents, or proof of address, your account might be flagged until you do. Other times, it’s less obvious. A larger-than-usual payment can trigger fraud checks, or something as small as changing your linked bank account or payout method may cause the system to double-check your details before letting funds through.

The first thing to do is log in and check your notifications or inbox. Most platforms are clear about what’s holding your money. They’ll usually prompt you to upload documents, confirm your identity, or re-verify your bank details. Once you’ve cleared these compliance checks, your payouts typically start flowing smoothly again, and you’re less likely to face future delays.

Also read: Why KYC is required to use global accounts (and how to do it easily)

3. Contact your bank

Not every delay is the platform’s fault. Sometimes, the holdup happens once the money has landed in your bank’s system. Banks can flag or pause international transfers for all sorts of reasons: maybe the amount looks out of the ordinary compared to your usual transactions, maybe the sender is from a region they consider “high risk,” or maybe they just need to double-check compliance boxes like anti-money laundering (AML) regulations.

It’s frustrating, but it’s also part of how banks protect themselves and their customers. A quick nudge can often get things moving. Instead of saying something vague like “My money hasn’t arrived,” give them everything they’ll need to trace the transaction quickly. Include your transaction ID or reference number, the exact date, the amount and currency, and the payout method you used.

The more precise you are, the less time they’ll spend searching and the faster you’ll get answers. Adding screenshots of your receipt or payment history is a bonus. It gives them visual proof to work with.

Ask directly if the funds are sitting in a review queue. If they are, confirming a few details with you, like who sent the payment and what it’s for, might be all they need to release it.

By proactively checking in, you can avoid the stress of waiting days for something that could’ve been cleared up in a single phone call or email.

Also read: Receiving dollar payments in Nigeria: Best platforms and what to avoid

4. Build a financial cushion

No one gets excited about putting money aside instead of spending it on a new gadget, a night out, or that trip you’ve been eyeing. But here’s the truth: a financial cushion is your lifeline as a remote worker.

Payouts get delayed. Clients disappear. Platforms take longer than expected to release your funds. If you’re living pay cheque to pay cheque, even a one-week delay can spiral into stress over rent, bills, or groceries. That’s why having an emergency buffer is non-negotiable.

You can start with with5% of each payout, then work up to 10% as things stabilise, then go higher over time, you’ll have enough to cover at least six months of basic expenses. With that safety net in place, you won’t panic the next time a payment drags. Instead, you’ll have breathing room to focus on your work and clients, rather than scrambling to cover essentials.

Also read: How safe is your money with global virtual accounts?

5. Know when to escalate

There’s a difference between being patient and being taken for granted. If the official processing window has long passed, you’ve followed up multiple times, and you’re still stuck with radio silence, it may be time to move beyond polite reminders.

Start with the platform’s formal dispute process. Almost every payment provider has one — even if it’s buried in the help centre. Document every email, chat, or ticket number you’ve raised so far; a clear paper trail often pushes your case forward faster.

If that still doesn’t get things moving, don’t underestimate the power of visibility. Companies that ignore inboxes often sit up quickly when tagged on social media, especially platforms like X (formerly Twitter) or LinkedIn, where their reputation is on show. A professional but straightforward call-out can put your issue at the top of their priority list.

For freelancers or businesses dealing with larger sums, you may also want to explore professional help. Depending on your country, that could mean contacting a local financial regulatory body, consulting with a lawyer, or even leaning on community groups where others share similar experiences.

At the end of the day, delays shouldn’t be normalised. You’ve done the work and deserve to be paid on time.

Also read: Why Brazilian online entrepreneurs need virtual bank accounts

Payment delays can be stressful, especially when you’re counting on that money for rent, bills, or simply keeping your work-life balance in check. The more informed and prepared you are, the less power these hiccups have over your financial stability.

One real game-changer is having a system that puts you in charge, where payments are faster, currency conversion is seamless, and you’re aren’t stuck waiting.

That’s precisely what Grey was built for. With global accounts in USD, EUR, and GBP, instant currency swaps, and tools designed for cross-border payments, Grey helps freelancers and businesses cut through the usual roadblocks and access their money when it matters most.

Create your free Grey account today or download the app for more secure and timely payments.

‍

Best financial apps for remote workers on the move

•

•

2 min read

As a remote worker, freedom is your biggest perk, but with that freedom comes the constant challenge of managing money across borders. Getting paid in one currency, spending in another, and tracking expenses while travelling can feel overwhelming.

Traditional banks weren’t built for your lifestyle, and hidden fees often eat into hard-earned income. That’s why choosing the right financial apps matters. They don’t just help you budget; they protect your earnings, simplify payments, and give you peace of mind wherever you go. For remote workers on the move, smart financial apps are the real travel companions

Read also: Best apps for remote workers and global freelancers

Key considerations in picking a financial app as a remote worker

  • Security: Choose financial apps that prioritise data protection with encryption, fraud monitoring, and two-factor authentication, giving you peace of mind while handling money abroad.
  • Global accessibility: The best apps allow you to operate across borders seamlessly, offering multi-currency accounts, wide coverage, and reliable customer support wherever your work takes you.
  • Transaction fees: Always check the costs of sending and receiving payments. The right app ensures you keep more of your earnings without losing money to hidden charges.
  • Currency exchange rates: If you get paid in multiple currencies, choose apps with competitive rates so you maximise your income.
  • Customer support: Quick and reliable support is essential. Go for platforms that make it easy to resolve issues whenever they arise.

Read also: How to save in USD as a remote worker

The best financial apps for remote workers on the move

  1. Wise: Perfect for managing multiple currencies with low transfer fees. Wise gives remote workers borderless accounts to receive payments globally at real exchange rates. Fast, transparent, and designed for digital nomads, it ensures hidden costs don’t eat up your income.
  2. Payoneer: A favourite for freelancers and businesses alike. Payoneer lets remote workers receive payments from clients worldwide, withdraw to local banks, and even access prepaid cards. It’s a reliable option for managing international earnings while keeping everything simple and professional.
  3. Revolut: Built for global lifestyles, Revolut offers multi-currency wallets, budgeting tools, and instant transfers. Remote workers can easily exchange money at interbank rates, spend abroad without extra fees, and even save or invest directly from the app.
  4. N26: A fully digital bank offering easy expense tracking, no foreign transaction fees, and instant notifications. With N26, remote workers can manage their finances entirely online while enjoying the perks of a modern, borderless banking experience.
  5. PayPal: The classic choice for global freelancers. PayPal makes it easy to send and receive money internationally with trusted security. Though fees can be higher, its wide acceptance makes it a must-have tool for remote workers managing global clients.
  6. Grey: Grey makes it seamless to open international accounts, receive global payments, and exchange currencies instantly. It’s perfect for remote workers who want to remove barriers to earning and enjoying money worldwide.

Read also: Best platforms to find remote jobs for freelancers in 2025

Why Grey is the best solution for remote professionals

  • Seamless global payments: Grey lets you receive payments from international clients without delays, so you never worry about being stranded or waiting endlessly for funds.
  • Competitive exchange rates: Keep more of your hard-earned money with fair and transparent currency conversions designed for global workers.
  • Multi-currency accounts: Open USD, GBP, or EUR accounts easily, making it simple to invoice and get paid like a local wherever your clients are.

Read also: Best platforms to find remote jobs for freelancers in 2025

Seamless banking experience with Grey

Remote workers on the move can now easily manage their finances with reliable mobile banking apps. Grey stands out as one of the best, offering robust security and excellent customer support. Grey also helps streamline finances with its invoicing tool, virtual USD card, and competitive exchange rates.

Sign up with Grey today or download the app to enjoy a seamless mobile banking experience.

Currency conversion traps to avoid when relocating

•

•

2 min read

There are numerous uncertainties associated with relocating to another country. Some of the burning questions can include: Are the people nice? Will I love the food? How do I manage my currency conversions? While we acknowledge that these are valid concerns, the first two questions are tied to personal preferences, so our support there is limited. However, we know some things about managing currency conversions when you relocate.

Relocating to a new country often involves dealing with various financial considerations, and one of the most common pitfalls is currency conversion. Exchange rates fluctuate constantly, and you may find yourself paying more than necessary or missing out on favourable rates. Recognising and avoiding these currency conversion traps is essential for safeguarding your financial well-being during and after your move. This article outlines the most common traps and provides guidance on how to navigate them.

Also read: How to manage international payments while living abroad

1. Ignoring the true exchange rate

Many people accept the advertised rate or what their bank offers without checking the real-time exchange rate. Currency markets are highly dynamic, and rates can vary significantly from one provider to another. Often, the rate displayed at a currency exchange bureau or a financial website appears attractive but does not account for hidden margins or fees.

Tip: Always compare live exchange rates from reputable financial news sources or currency converters before making any significant transactions. Use tools like XE.com or Grey to get an accurate picture of current rates.

2. Using airport or hotel currency exchange desks

Currency exchange kiosks at airports, hotels, or tourist hotspots typically offer poor rates with high commission fees. They often add a markup to the official rate, meaning you receive less foreign currency for your money and end up paying more for goods or services later.

Tip: Avoid currency exchanges at airports unless absolutely necessary. Instead, withdraw cash from ATMs in your destination or use credit/debit cards with favourable rates.

3. Relying on credit or debit cards without understanding fees

Many cards charge foreign transaction fees when used in other countries. These charges can range from 1% to 3% per transaction. While the fees may seem small. This can gradually add up over time, especially if you're making regular payments or purchases in your new country.

Tip: Use a card that offers no foreign transaction fees or charges a competitive rate. Prepaid travel cards or specialised forex cards often provide better exchange rates and lower fees.

4. Falling for dynamic currency conversion

Some shops or ATMs offer to convert the payment amount into your home currency (dynamic currency conversion). While it may seem convenient and they make it appear as though they are doing you a favour, this option often involves poor exchange rates and additional fees, resulting in you paying more than if the transaction were processed in the local currency.

Tip: Always choose to pay in the local currency. This ensures you’re using the official exchange rate and avoiding unnecessary charges.

Also read: Expat banking 101: Opening an account before relocation

5. Not factoring in hidden fees

Many currency exchange providers include fees in the exchange rate margin or charge flat fees that might not be immediately apparent. These ‘hidden’ costs can significantly increase the amount you pay or reduce the amount you receive.

Tip: Check the small print, ask about all fees beforehand, and prefer providers with transparent fee structures. Consider using online currency transfer services that are known for their competitive and transparent pricing, such as Grey.

6. Failing to plan for currency exchange timing

Currency rates can fluctuate daily, sometimes significantly within a matter of hours. Waiting until the last minute or making hurried exchanges can result in unfavourable rates.

Tip: Monitor currency trends and consider scheduling transfers or exchanges when rates are favourable. For larger sums, consult with financial advisors or currency brokers who can offer better timing and rates.

7. Overlooking the impact of cross-border transfers

Sending money internationally through banks or transfer services often incurs high fees, especially if done hastily or through local branches. Besides transfer fees, adverse exchange rates can erode the value of your funds.

Tip: Use specialised international money transfer services like Grey, Wise, or Revolut, which offer real-time rates close to market rates with transparent fees.

You may also like: Moving abroad checklist: 6 Essential considerations for a smooth transition

Safe currency conversion with Grey.

Being aware of currency conversion traps is vital for anyone planning an international move. By doing your homework on exchange rates, fees, and provider transparency, you can avoid unnecessary expenses and make the most of your funds in a new country. Planning ahead and choosing the right financial tools will ensure a financially seamless relocation.

Grey offers foreign accounts to help you manage your finances efficiently, facilitate swift international payments, and provide competitive conversion rates, ensuring seamless financial management as you relocate. Grey’s USD debit card lets you make global payments from anywhere without incurring excessive fees.

Get started on Grey today to avoid currency conversion traps when you relocate.

‍

What it costs to live in 6 nomad hotspots around the world

•

•

2 min read

Many remote workers and aspiring digital nomads believe that being a digital nomad is expensive. However, this isn’t always the case. Many nomad hotspots around the world are popular due to their relatively low living costs. Other factors that characterise a nomad hotspot include a reliable digital infrastructure, vibrant communities, tourist attractions, and cultural diversity. Hence, being a digital nomad requires more than having money and hopping around the globe. It takes strategic planning and budgeting.

The cost of living in these nomad hotspots is influenced by factors such as housing markets, local economies, and seasonal fluctuations. This article examines the cost of living in six nomad hotspots around the world, as well as the factors that influence living expenses.

Also read: Digital nomad jobs with no experience: how to get started in remote work

Factors influencing living costs in nomad hotspots

Various factors contribute to the living costs of nomads in different cities.

  1. Housing demand and tourism: Cities with frequent international visitors and digital nomads often experience a surge in accommodation costs, especially during seasons when the influxes happen.
  2. Local economic conditions: Countries with weak currencies and developing nations tend to be less expensive compared to stronger economies.
  3. Infrastructure and utilities: The quality of internet, electricity, and transportation may vary across hotspots, impacting living costs. Developing regions have cheaper but less reliable utilities.
  4. Lifestyle choices: A digital nomad’s lifestyle choices are another important factor. For instance, feeding would be more affordable if you opt for local dishes compared to someone who prefers fine dining with Western food. Other choices that can influence the living cost are: co-working spaces versus cafes, public transport versus taxis, and shared living versus luxury hotels.
  5. Visa and regulatory environment: Visa fees, extensions, or tax incentives influence long-term costs.
  6. Inflation and global trends: Local and global inflation contribute to many cities' costs.

What it costs to live in 6 nomad hotspots around the world

As the population of digital nomads continues to grow globally, it is expected that more hotspots will emerge over the years. Here are six digital nomads’ favourite destinations and the cost of living in each of them, considering the factors we already discussed.

Chiang Mai, Thailand

__wf_reserved_inherit

Chiang Mai is one of the top destinations in Southeast Asia, thanks to its low-cost, culturally rich environment. There is a wide range of accommodation options to suit your needs and budget. On average, a one-bedroom apartment in the city centre can be rented for approximately $400 TO $700 per month. Local street food offers delicious meals for just $2-$5, while Western-style cafes and restaurants cost around $5-$10 per meal. There are workspaces available, as well as many cafes where you can work from.

Lisbon, Portugal

__wf_reserved_inherit

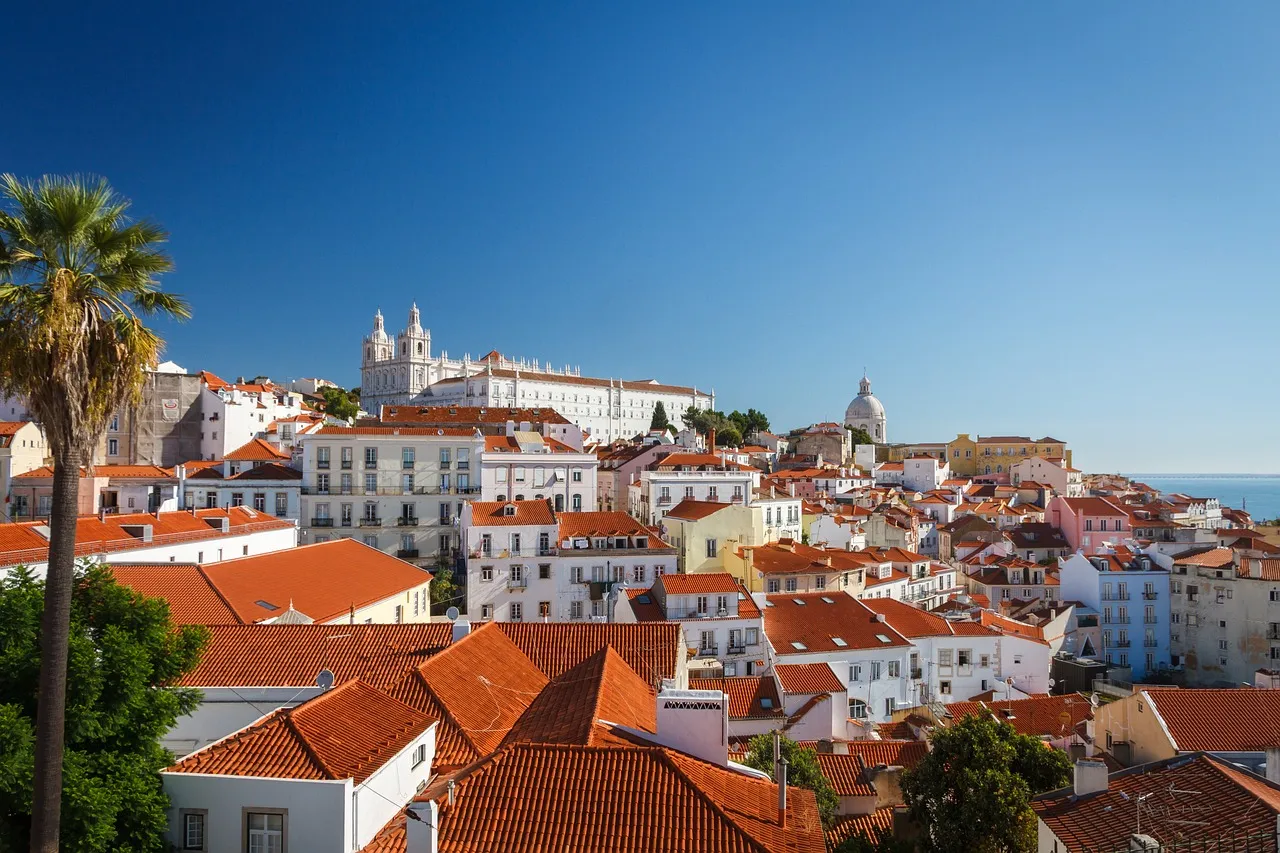
Lisbon is the European hub for digital nomads. It is relatively more expensive than most other locations on this list. However, it offers a modern city life with access to beaches and outdoor activities. Popular activities include exploring the historic streets of Alfama, visiting the Jerónimos Monastery and Belém Tower, and enjoying the trendy LX Factory. Accommodation in Lisbon varies widely. While a one-bedroom apartment in the city centre can average around $1100-$1,500 per month, the prices are lower in smaller towns or suburbs. Food costs are somewhat higher; local meals are about $5-$15, while dining at mid-range restaurants costs approximately $15-$25.

Also read: How to apply for a digital nomad visa in Portugal

Medellín, Colombia

__wf_reserved_inherit

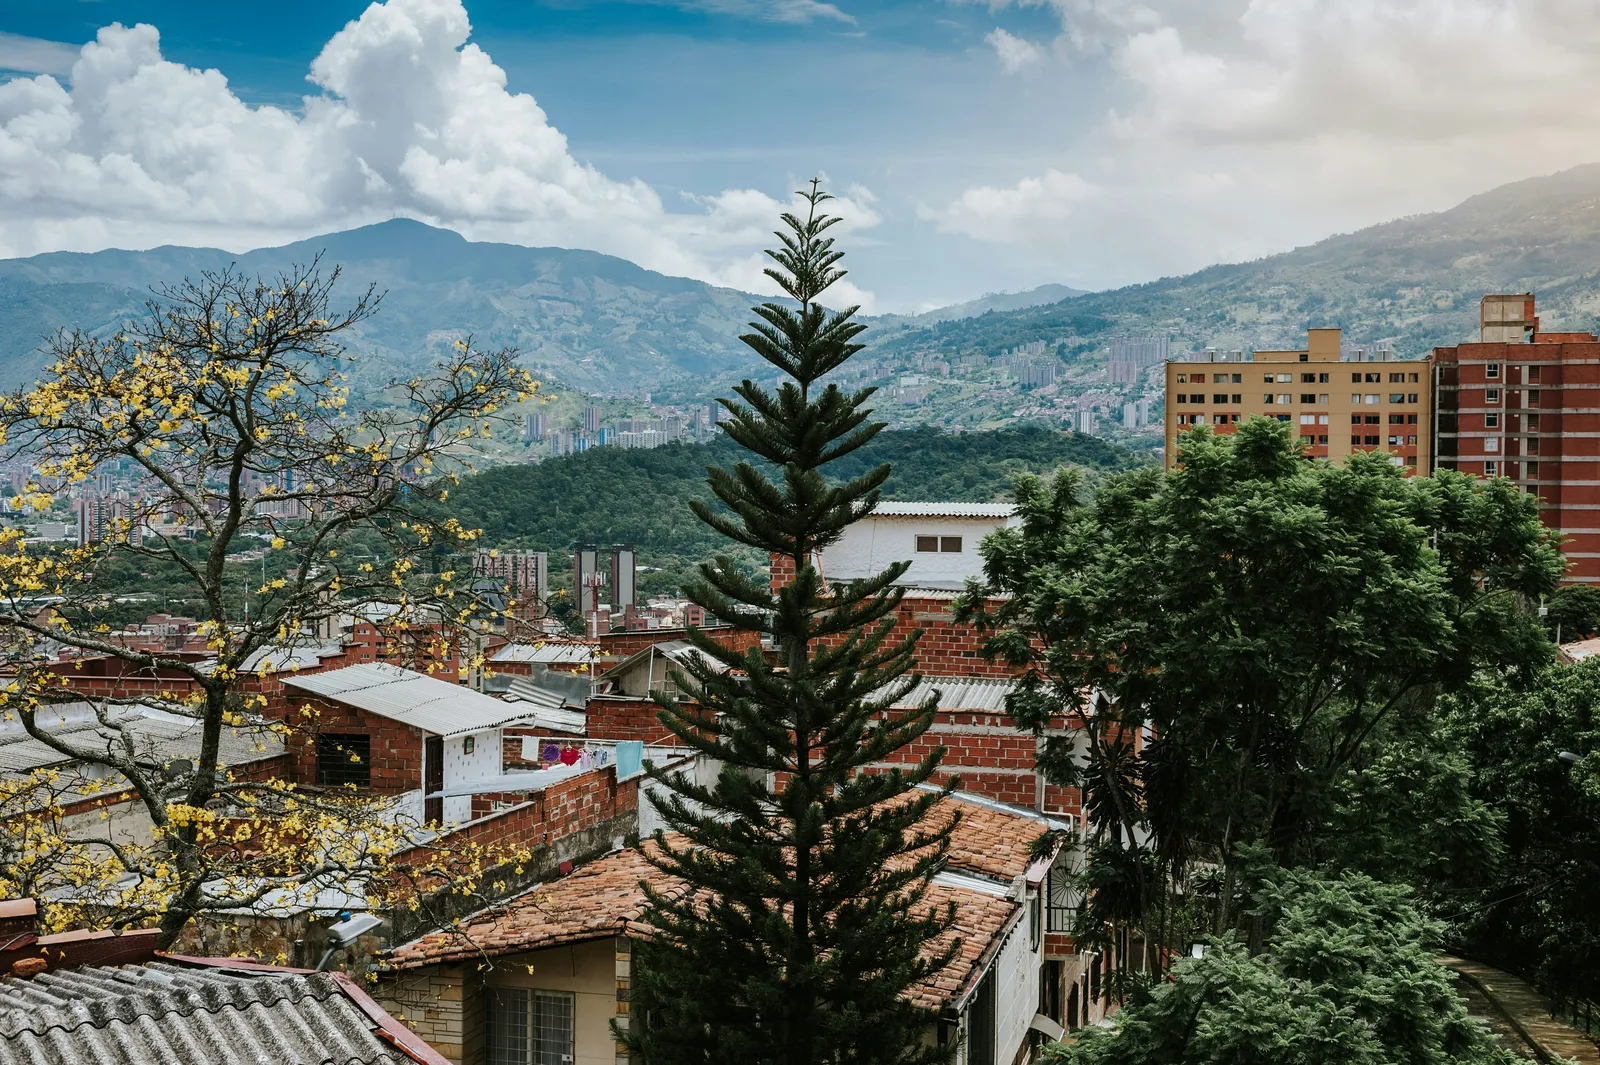
The city boasts of a thriving ecosystem for remote work, featuring reliable internet, numerous coworking spaces, and a vibrant social scene. While the influx of digital nomads has contributed to rising rental costs in some areas, Medellín remains an attractive destination due to its affordability, pleasant climate ("City of Eternal Spring"), and thriving community. The city offers nomads a vibrant nightlife, beautiful parks, and memorable cultural experiences. The overall cost of living in Medellín remains relatively low compared to many Western cities, making it an attractive option for those seeking affordability. Accommodation in the El Poblado district can be rented for about $400-$700 per month for a one-bedroom apartment. Food is affordable; local markets offer meals for around $3-$5, while dining at international or tourist-focused restaurants costs about $10-$20.

Barcelona, Spain

__wf_reserved_inherit

The aerial view of Barcelona is breathtaking, welcoming you into an amazing city. Barcelona offers a variety of coworking spaces, work-friendly cafes, and a strong community of remote workers. Its digital nomad visa also makes it easier for non-EU citizens to live and work in Spain. Barcelona offers a great balance of work and leisure, with its rich culture, beautiful architecture, access to beaches, and proximity to mountains. Accommodation in the city centre can range from $1,500 to $2,000 per month for a one-bedroom apartment. The cost of eating local tapas and meals is about $10-$20, with higher prices for international cuisine.

Ho Chi Minh City, Vietnam

__wf_reserved_inherit

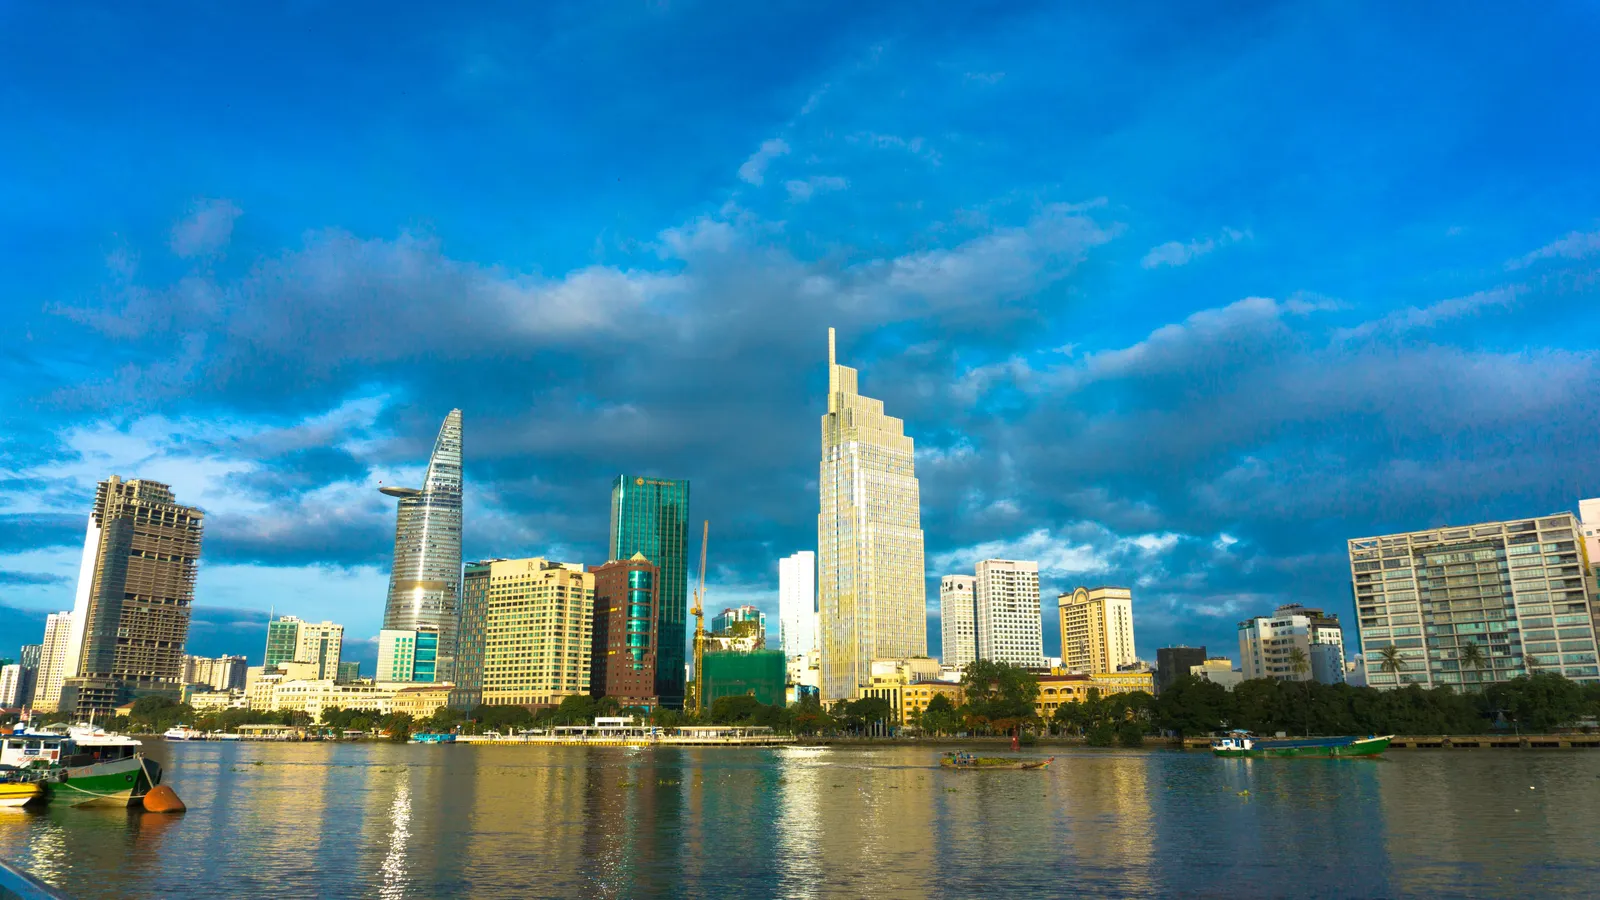
The major selling points of Ho Chi Minh City are low living costs, friendly locals, and reliable internet accessibility. Beyond work, the city offers a wealth of attractions and activities, from exploring historical sites like the War Remnants Museum and the Cu Chi Tunnels to immersing oneself in the bustling atmosphere of Ben Thanh Market. Accommodation can be found for roughly $500-$900 per month in central districts. Food is incredibly inexpensive; street food meals often cost around $2-$5, and Western restaurants charge about $7-$12. Transport, such as motorbike rentals, costs about $60-$100 per month. Utilities are generally between $60 and $90, and internet services are reliable, costing around $20-$35 per month. Living well in HCMC can typically be achieved for around $700-$1,300 per month.

Bali, Indonesia

__wf_reserved_inherit

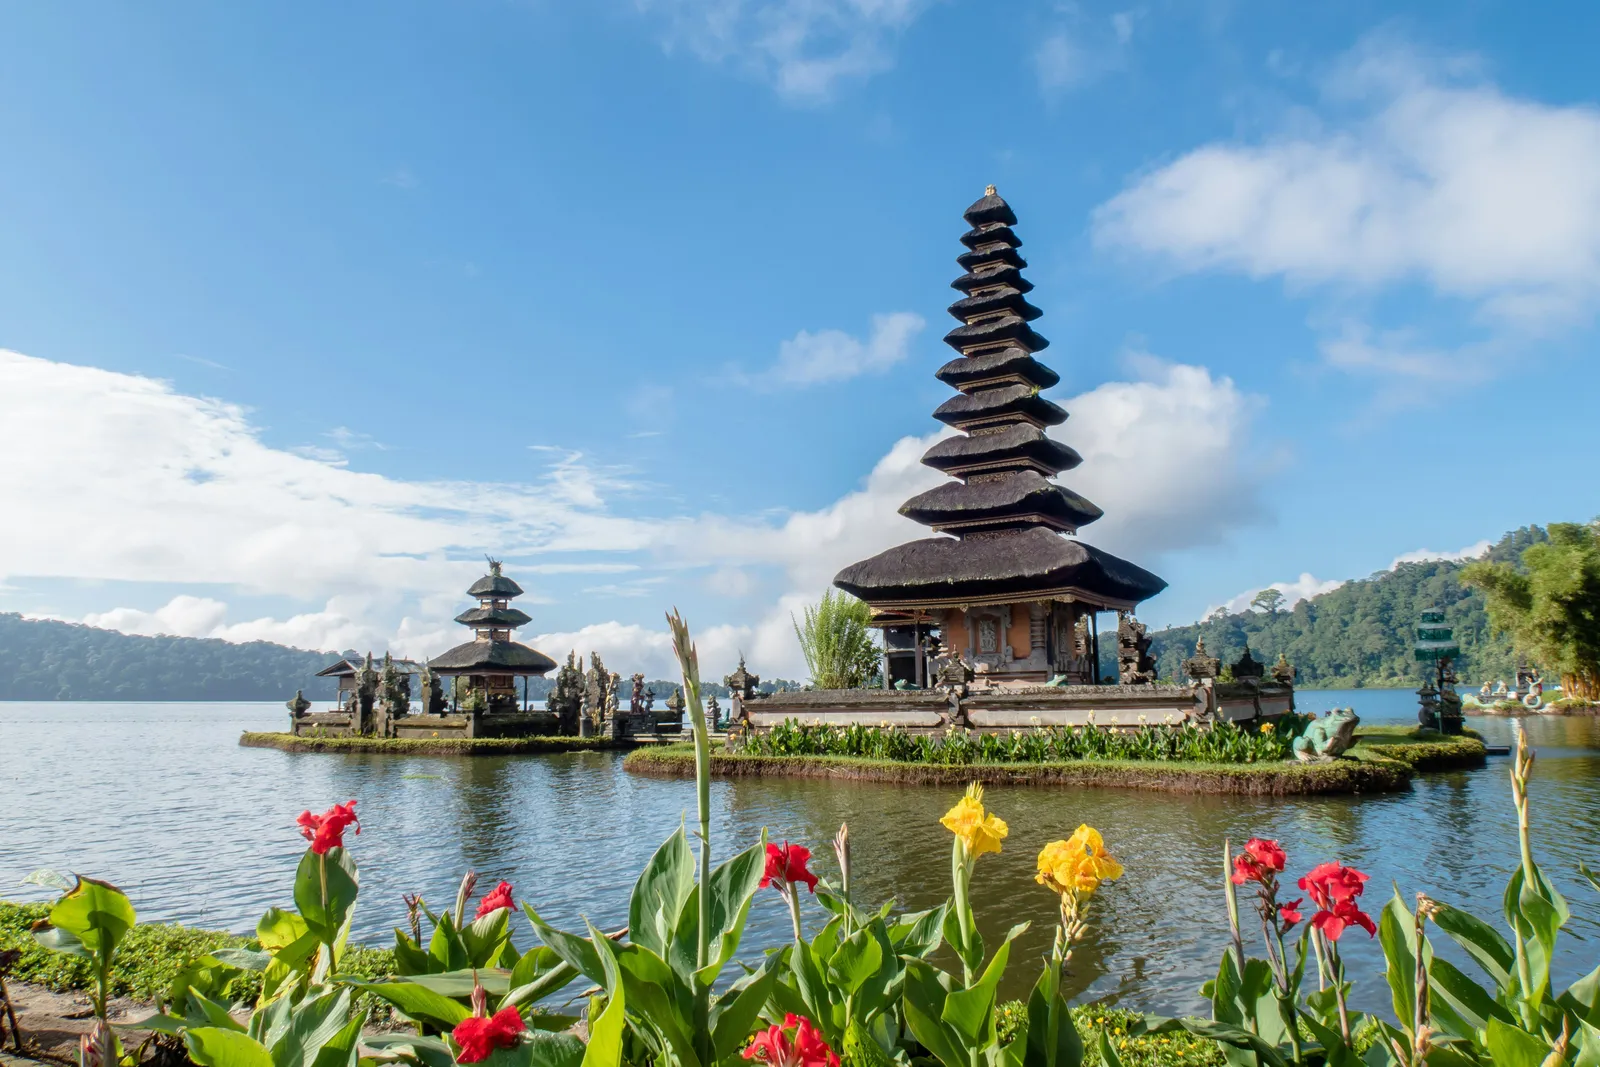
Bali has long been a favourite among digital nomads and tourists, thanks to its beautiful beaches, friendly climate, and affordable cost of living. Bali boasts a large and active digital nomad community, offering opportunities to connect with like-minded individuals through co-working spaces, local events, and online groups. Accommodation costs are quite reasonable; travellers can rent a one-bedroom apartment in popular areas like Canggu or Ubud for approximately $500 to $900 per month. Food is inexpensive, with local meals costing around $3-$5, while dining at restaurants catering to tourists or expats may cost around $5-$15 per meal.

Also read: Top 8 digital nomad cities for remote workers in Southeast Asia

Managing your finances efficiently

The costs of living in these nomad hotspots vary widely and largely depend on your budget, preferences, and lifestyles. Now that you know how much it costs to live in these cities, what is your payment plan? Digital nomads frequently encounter concerns related to currency exchange. Grey makes it easy to get paid, no matter your favourite work location. With a multi-currency account supporting USD, EUR, GBP, and USDC transactions, a virtual USD debit card, swift payment processing, and competitive conversion rates to local currencies, Grey ensures digital nomads travel with no financial restrictions.

Get started on Grey today to manage your finances without hassles and travel without worries.

‍

Expat bank account before relocating: Full guide

•

•

2 min read

Moving to a new country can be physically and mentally stressful for expats, so setting up a bank account might not be an immediate priority. Most people focus their preparation on visas, housing, and shipping belongings. It is when they arrive that they realise they should have planned for how to manage their finances ahead.

Before relocating, set up banking that works from day one. Host-country banks often need a local address or residency permit you will not have on arrival, so open a multi-currency account you can use immediately, keep your home account open for existing commitments, and send a small test transfer before moving larger sums.

This article guides expats looking to open a bank account before relocation and provides a checklist of what you need to sort out before moving to a new country.

What to sort out before you move

Use this checklist to make sure your banking is squared away before your relocation.

  • Open an account you can use without a local address: Many banks require proof of a local address before opening an account. This can be difficult when you have just arrived and don’t have permanent accommodation yet. You can open a multi-currency account remotely, fund it, and use it to manage your finances while you sort out opening a local bank account.
  • Check which currencies you need: Consider which currency you will be paid in and which you will spend. For example, if you are moving from the US to Europe, you may still receive income in USD while paying for your local expenses in EUR. An account that lets you hold multiple currencies can help you manage both currencies without converting everything immediately.
  • Get a card before you travel: Having a virtual or physical card before you move gives you another way to pay for things when you arrive. It also means you are not relying entirely on your home bank card, which may charge foreign transaction fees or occasionally block transactions it considers unusual.
  • Test by sending a small amount: Before moving your relocation savings or a large amount to the new account, send a small amount first. This way, you can be sure your setup works. Check that it reaches the right account, arrives in the expected currency, and that there were no hidden fees. Once you confirm everything works, you can safely transfer larger amounts.
  • Notify your existing bank about your relocation: If you plan to keep using your current account, let your bank know that you will be moving abroad. Many banks flag transactions initiated from another country as potential fraud if you don’t tell them you are moving to that country.

For more tips on managing your money after relocating, see our guide on managing international payments while living abroad.

Why non-residents get blocked

Opening a local bank account can be difficult when you have just moved because you may not have the documents the bank requires. Here are some reasons you might struggle with opening an account abroad:

  • Proof of local address: Banks may ask for a tenancy agreement, utility bill or other document showing your name and address. If you are staying in a hotel or temporary accommodation, you may not have these documents yet, and won’t be able to open an account.
  • Residency or visa documents: Some banks require proof of your legal residency status before opening an account. Meanwhile, getting the right document might take weeks in some countries.
  • Proof of income or employment: Some banks may ask for an employment contract, payslip or other evidence of income. This can be difficult if you are still job hunting or you haven’t received your first local payslip.
  • No local credit history: In some countries, banks consider your credit history when opening certain account types. And since you are new to the country, you might find it difficult to open such accounts because you don’t financial history in that country.

Requirements for opening a bank account vary by country and bank, but many of the challenges are similar. A multi-currency account available remotely helps bridge the gap by giving you access to different currencies without requiring a local bank account in each country.

Should you keep your home bank account?

You do not necessarily need to close your home bank account when you move abroad. Whether you should keep it depends on your circumstances.

Reasons to keep your home account open

Keeping your existing account can make it easier to:

  • Pay existing direct debits and subscriptions
  • Continue mortgage, insurance or loan payments
  • Support family members at home
  • Access your existing credit cards and other financial products
  • Have a backup account if you return home
  • Receive payments that still come from your home country

Reasons to close it

Closing the account might make sense if:

  • You are paying fees for an account you no longer use
  • You no longer need any services connected to the account
  • Managing accounts in multiple countries creates unnecessary complexity
  • Your new country of residence has reporting or tax rules that make keeping certain accounts less convenient

Before closing your old account, check whether you still have any payments, subscriptions or other financial commitments linked to it.

Consider the tax implications

Moving abroad can also change your tax situation. For example, US citizens and residents who move abroad trigger an FBAR filing requirement if their total foreign account balance is more than $10,000 at any time during the calendar year. Also, once you own certain financial assets abroad, FATCA requires you to file Form 8938 with your regular tax return. can also create additional reporting requirements.

Confirm the tax implications for moving to another country. You can try finding out on your own or involving a tax professional before closing or keeping accounts.

For many people, keeping their existing account open initially is the safer option. You can close it later once you are settled and have confirmed that you no longer need it. Reopening an account from abroad can be much harder than simply keeping an existing one open.

Multi-currency accounts for expats

A multi-currency account can make managing money easier when you move abroad, especially if your income and expenses are in different currencies.

You can keep USD, EUR, and GBP in the same account instead of converting every payment to a single currency. You can then convert your money when you need to and see the exchange rate before you confirm the transaction.

If you move abroad for work but have not opened a local bank account yet, local receiving details in currencies such as USD, EUR, or GBP can give your employer or clients a way to pay you without waiting for your local bank account to be set up.

A virtual card linked to your multi-currency account lets you spend directly in the local currency without the foreign transaction fees that a home-country card typically applies to every purchase abroad.

Using a multicurrency account allows you to hold multiple currencies and convert whenever you like. Seeing the exchange rate and fees upfront also makes it easier to understand the true cost.

See our comparison of the best multi-currency accounts for non-residents.

Setting up before relocation with Grey

One advantage of a multi-currency account is that you can set it up before you leave your home country. This gives you access to your money while you are still sorting out local banking and accommodation.

With Grey, users can get USD, EUR, and GBP accounts with the relevant details. You also get a virtual card linked to your balances, which you can use to spend abroad from your first day.

Getting started on Grey requires verifying your identity with a valid ID, proof of your current address, and a photo. And within minutes, you can access USD, EUR, and GBP accounts that are ready to receive and send money.

Once you open a local bank account after moving, you can continue using Grey alongside it to hold and manage other currencies.

Open a Grey account before you move, and you can manage your finances from your first day abroad.

Frequently asked questions

Can I open an account before moving?

Yes. While a traditional bank in your destination country may require a local address or residency documents, some multi-currency accounts can be opened remotely before you move. This gives you a way to manage your money while you settle in.

Do I need a local address?

For a traditional local bank account in most destination countries, yes, almost universally. This is the single most common barrier new arrivals face, since proving a local address typically requires documentation (a tenancy agreement, utility bill) that you cannot produce until you have already secured housing, which itself sometimes requires a local bank account. A multi-currency account opened before you move avoids this specific barrier entirely, since it does not require a local address in your destination country.

Should I keep my home account open?

For many expats, keeping your home account open at least initially makes sense. It allows you to continue paying bills and other commitments, and provides a backup if your relocation plans change. However, check for account fees and any tax or reporting requirements that may apply after you become a tax resident elsewhere.

What account works from day one?

A multi-currency account that you can open remotely before travelling can give you access to banking services while you are still settling in. Grey offers eligible users USD, EUR and GBP accounts that can be set up online, along with a virtual card for spending.

What nobody tells you about your first year living abroad

•

•

2 min read

Living abroad sounds glamorous, new cities to explore, fresh opportunities, and endless adventure. But what nobody tells you about your first year is the mix of highs and unexpected lows. Beyond the Instagram-worthy moments, you’ll navigate language barriers, cultural differences, and cross-border payments. With Grey, you can send and receive money globally without hidden fees or delays, giving you more freedom to focus on work, travel, and building your life overseas. With the right tools, your first year abroad can be exciting, smooth, and rewarding.

Read also: Managing remittances while working from abroad

The benefits of living abroad you can’t ignore

1. Discover new perspectives

Living abroad opens your eyes to new ways of thinking, working, and living. You’ll learn to see the world through a different lens, gaining perspectives that expand your creativity and problem-solving skills, an invaluable advantage both personally and professionally.

2. Build global connections

Stepping outside your country gives you the chance to meet people from all walks of life. These relationships often become lifelong friendships or valuable networks, enriching your journey and sometimes even sparking exciting collaborations across industries and borders.

3. Personal transformation

There’s no growth without challenge, and living abroad tests you in powerful ways. You'll learn languages, adapt to unfamiliar environments and become more confident, resourceful, and independent. These are qualities that shape you into a stronger version of yourself.

Read also: How to protect your funds while travelling abroad

What to expect in your first year living abroad

1. Language barriers

Your first year abroad teaches you that language isn’t only grammar, it’s tone, slang, and even gestures. Ordering food, asking for directions, or making jokes feels exhausting at first. You stumble, repeat, and sometimes give up mid-sentence. But slowly, you catch rhythms, celebrate small wins, and realise language mistakes are part of finding your place.

2. Money transfers

Sending and receiving money is never as smooth as you expected. Exchange rates, transfer delays, and hidden charges turn simple transactions into stress. Your first year abroad forces you to budget tightly, find reliable platforms, and think twice before every transfer. Over time, you learn financial discipline, and the relief of money finally landing safely.

Read also: How virtual cards can simplify your life abroad

3. Loneliness

Even in a buzzing city, the quiet moments hit hardest. You miss familiar voices, inside jokes, and people who understand you without long explanations. Making friends abroad takes effort, patience, and openness. In your first year, loneliness shapes you, it pushes you to step out, join communities, and build connections that slowly start to feel like home.

4. Culture shock

It’s not the big differences that shake you most, but the small ones: how people greet, eat, or manage time. The unspoken rules feel like invisible walls at first. You fumble, misread, and sometimes retreat. But your first year abroad shows you that adaptation is a muscle, one that grows stronger the more you lean into it.

5. Homesickness

That familiar plate of food suddenly feels a world away. You crave your country's food , snacks you can’t find, and the comfort of taste you grew up with. Your first year abroad teaches you that food carries memory, and sometimes you learn to cook just to bring pieces of home back.

6. Navigating paperworks

Visas, permits, healthcare and bank accounts as your first year abroad is full of forms, deadlines, and rules you don’t fully understand. One missing document can delay everything. It feels endless and frustrating, but eventually you master it: keeping copies, asking questions, and building patience. Bureaucracy becomes a hidden teacher, showing you resilience in the most unglamorous ways.

How Grey simplifies payments when living abroad

  • Global accounts: Receive and hold funds in multiple currencies no matter where you are.
  • Fast transfers: Send and receive money across borders quickly without long delays.
  • Low fees: Avoid high conversion rates and hidden charges typical with traditional banks.
  • Secure transactions: Your funds are protected with advanced digital security measures, giving peace of mind

Simplify international payments

Your first year abroad is full of first-time experiences, from culture shocks to building new routines. This article has shown you what to expect, but managing money shouldn’t add to the stress. Grey makes receiving, sending, and converting international payments simple and secure, so financial hurdles don’t hold you back.

Open your Grey account today or download the app and enjoy seamless global transactions

‍

Arrow (up)

Back to top