


How to manage family remittances with multi-currency accounts

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

Having to shuttle between sending GBP for your sibling's studies in the UK, paying for the family vacation to Europe in EUR, and buying household items in USD from a US digital marketplace can be stressful. When you add costly currency conversions, high transaction fees, and slow processing to the mix, it’s clear why you need a seamless platform to manage multiple currencies efficiently.

Multi-currency accounts can streamline family remittances by allowing you to receive, hold, and send money in various currencies within a single platform. They help to reduce money losses from exchange rate fluctuations and transaction fees. Accounts like these also help simplify financial management for family members living abroad, providing a more reliable, affordable, and convenient alternative to traditional banks.

This article explores how to manage family remittances using multi-currency accounts and provides guidance on getting started.

Also read: Using Grey to manage international family expenses

Understanding multi-currency accounts

Multiple currency accounts let you hold and manage various currencies simultaneously on one platform. You can receive funds in different currencies, choose to convert them at favourable exchange rates, or hold them for future use, like paying bills or sending to family members.

Unlike traditional bank accounts, they enable users to store funds in currencies like USD, EUR, GBP, and others, often within the same account. These accounts are offered by traditional banks, fintech platforms, and digital payment providers like Grey.

Why use multi-currency accounts for family remittances?

Managing remittances through traditional banking systems can be costly and inefficient. Here are the benefits of using multi-currency accounts for family remittances:

1. Cost savings on currency conversion

Multi-currency accounts typically offer competitive exchange rates, often close to the mid-market rate, lower fees and transparent charges.

2. Flexibility in holding multiple currencies

With a multi-currency account, you can hold funds in your foreign currencies without going through the stress of converting to local currency every time.

3. Simplified transactions

Multi-currency accounts streamline the process of sending money to multiple family members in different countries. Instead of managing separate accounts or dealing with multiple banks, you can handle all transactions from a single platform.

4. Protection against exchange rate volatility

Exchange rates can fluctuate significantly, impacting the value of remittances. By holding funds in the recipient’s currency or a stable currency like USD, GBP, or EUR, you can time conversions to avoid unfavourable rates.

5. Accessibility and digital convenience

Many fintech platforms offer multi-currency accounts with user-friendly apps, enabling you to manage transfers, track exchange rates, and monitor transactions in real-time from your smartphone.

6. Support for local banking needs

Many multi-currency account providers offer local bank account details in multiple countries. For instance, Grey provides users with local account details for USD, EUR and GBP, enabling recipients to receive funds as if they were local transfers at affordable rates.

Setting up a multi-currency account for remittances

Setting up a multi-currency account is a straightforward process. However, it is essential to carefully consider your options and choose the platform that best suits your needs. Here’s a step-by-step guide to setting up a multi-currency account.

Choose a provider

Research and compare different providers, such as Grey, with other international platforms offering multi-currency accounts.

  • Wise: Known for low fees and mid-market exchange rates, ideal for frequent remittances.
  • Revolut: Offers multi-currency accounts with additional features like budgeting tools and crypto support.
  • Payoneer: Great for freelancers and businesses sending remittances to family members.
  • PayPal: Convenient for smaller transfers, but may have higher fees.
  • Traditional banks: Some banks, such as HSBC and Citibank, offer multi-currency accounts, although fees may be higher.

Compare platforms based on the currencies you need to manage, transfer fees, conversion rates, transfer speed, availability, and ease of use, before making a decision.

Complete the application

Follow the provider’s instructions for opening an account, which may require providing identification and other documents, such as proof of address.

Manage remittances

Once your multi-currency account has been issued, deposit money in the currencies you'll need for sending remittances. If you plan to receive money, share the account details with the desired currency with the sender.

Also read: How Grey makes sending money home easier for migrants

Choosing the right multi-currency account provider

When selecting a provider, consider the following factors:

  • Fees: Look for low or no fees for transfers, conversions, and account maintenance.
  • Supported currencies: Ensure the provider supports the currencies you need.
  • Transfer speed: Check how quickly funds reach recipients, especially for urgent remittances.
  • User experience: Choose a platform with an intuitive app or website.
  • Customer support: Opt for reliable platforms with good support in case of issues.
  • Regulatory compliance: Ensure the provider is licensed and regulated in your country.

Managing family remittances with Grey

While several fintech platforms offer multi-currency accounts, Grey remains a top recommendation for managing remittances. Here’s why you should opt for Grey:

1. Offers multicurrency accounts

Grey offers free multi-currency accounts that support transactions in GBP, EUR, USD, and many other local currencies. This ensures you can fund your account with your local currency and withdraw money to your local account with ease.

2. Swift low-cost transfers with competitive exchange rates

Grey supports instant transfers at low and transparent fees with favourable exchange rates to help you reduce money losses.

3. User-friendly interface

Family members with minimal tech experience can easily navigate the Grey app or website. Setting up an account and managing transactions are straightforward and can be done within minutes.

4. Withdrawal and fund account in local currency

After receiving the remittance, Grey allows you to convert and withdraw funds to your local bank account.

5. Virtual USD debit card

Grey offers a dollar card that works well with global payment platforms, offering more financial flexibility. You can manage daily subscriptions and shop online with ease.

6. USDC support

Grey supports USDC transactions which makes it easier to send money across borders.

How to manage family remittances with Grey

You can set up an account on Grey by following these quick steps

Step 1: Sign up for a free Grey account:

Visit Grey’s website or download the mobile app to create a free account. You’ll be asked to verify your identity using:

  • A government-issued ID
  • A selfie
  • Proof of address (e.g, bank statement, utility bill)

Step 2: Get your international bank details

Once verified, request your USD, GBP, and EUR accounts depending on your needs. Grey will immediately provide you with the corresponding banking details, which you can share to receive remittances.

Step 3: Start receiving remittances

Your relatives abroad can send funds directly from their bank accounts abroad, and you can also send money to a foreign account in the corresponding currency.

Step 4: Convert and withdraw to your local bank account

If you are receiving remittances, once the funds arrive in your Grey account, you can hold them in that currency or convert what you need to your local currency and withdraw them to your local bank at competitive exchange rates.

Managing cross-border family finances doesn’t have to be stressful, expensive, or time-consuming. With a multi-currency account from Grey, you can receive money faster, hold it securely in foreign currencies, and convert whenever needed. You also get a versatile USD debit card to simplify your online needs.

Whether you are managing family remittances for monthly support, school fees, healthcare, or savings, Grey offers you financial flexibility and affordability.

Get started on Grey today to manage your family remittances without breaking a sweat.

‍

Last updated:

June 15, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

FX trading apps: Best mobile platforms for currency traders

•

•

2 min read

Before the advent of mobile phones and the popularity of mobile FX trading platforms, dealers and brokers stood in loud, crowded rooms face-to-face, shouting prices and using hand signals to buy and sell currencies in trading pits. Then were the eras of telephone networks with dedicated phone lines, telex and fax machines, and physical money changers.

But trading occurs around the clock, so traders have to keep track of the market even when going about their daily lives. That's where mobile FX trading apps come in handy. The best FX trading apps balance regulation, tight spreads, intuitive design, and educational resources. Top platforms in 2026 include MetaTrader 5, TradingView, IG, OANDA, and Interactive Brokers, each with its own strengths for different trader profiles. Beginners should prioritise apps with demo accounts, strong regulation, and clear risk warnings rather than the lowest spreads.

FX trading apps let you trade currency pairs from your phone. The market is open 24 hours a day, five days a week, making mobile access more important than in most other asset classes. But the sheer number of apps available, ranging from serious professional platforms to barely regulated gambling-adjacent services, makes choosing carefully essential. This guide focuses on regulated, credible platforms.

See our FX trading beginners’ guide if you are new to the space.

Risk warning: Foreign exchange trading involves significant risk and is not suitable for all investors. You can lose more than your initial deposit. This article is for informational purposes only and does not constitute financial advice. Always verify that any platform you use is regulated in your jurisdiction before depositing funds.

What to look for in a mobile FX trading platform

Not every forex trading app is worth your money. Before opening an account, compare platforms based on the features that actually affect your trading experience and costs.

Regulation

Always choose a regulated broker. Regulation helps protect your funds and ensures the broker follows strict financial standards.

  • UK: Financial Conduct Authority (FCA)
  • US: Commodity Futures Trading Commission (CFTC) and National Futures Association (NFA)
  • Australia: Australian Securities and Investments Commission (ASIC)

If a broker isn't regulated by a recognised authority, it's best to avoid it.

Spreads and commissions

Every trade comes with a cost, usually in the form of spreads, commissions, or both.

Don’t just take the advertised cost at face value. Some brokers advertise commission-free trading but make up for it with wider spreads. Others charge a commission while offering tighter spreads. Compare total trading costs rather than focusing on a single fee.

Leverage

FX platforms offer leverage, which can determine how much you stand to lose or gain in a trade. Leverage allows you to control a larger trading position with a smaller deposit, which also increases how much you risk losing.

In the UK and EU, retail traders are limited to a maximum of 30:1 on major pairs under FCA/ESMA rules. In the US, CFTC limits retail leverage to 50:1 on major pairs. Higher leverage means higher risk. If you're new to forex, lower leverage is usually the safer choice.

Demo account

A demo account lets you practise with virtual money before risking real funds. You can learn how the platform works, test trading strategies, and understand how leverage affects your trades. If a platform does not offer a demo account, treat that as a warning sign.

Mobile UX

Since you'll be trading on your phone, the app should be fast, stable, and easy to navigate.

Look for features such as:

  • Real-time price charts
  • Fast order execution
  • Custom watchlists
  • Price alerts
  • Easy trade management

Deposits and withdrawals

Check how easy it is for you to fund your account and withdraw your money. Look out for fees that may apply. A good trading platform lets you know the deposit methods, withdrawal fees, processing times, and the minimum withdrawal amounts before you sign up.

Check the platform’s reviews, and if they regularly mention delayed withdrawals, consider it a red flag.

The best forex trading apps in 2026

Putting all these features together, here is our list of the best forex trading apps in 2026, their regulation, what they are best for, and their pros and cons.

1. MetaTrader 5

This platform was developed by MetaQuotes.  MT5 is a trading platform, not a broker. You access it through a broker that offers MT5 as its trading interface. The regulation, fees, and spreads depend on which broker you use. So, look for brokers with FCA, ASIC, CySEC, NFA or equivalent.

Best for: Algorithmic traders, multi-asset users and anyone who wants deep customisation on mobile.

Fees: Determined by the connected broker—typically spreads from 0.6–1.5 pips on majors plus possible commission.

Pros

  • Full order types (market, limit, stop, stop-limit) and hedging/netting support on mobile.
  • 80+ built-in indicators, multi-chart layouts and MQL5 Expert Advisors that run on the phone.
  • Works with dozens of regulated brokers, so you can choose pricing and leverage that fit your style.

Cons

  • Interface still feels denser than modern native apps.
  • Charting and execution quality vary with the broker’s servers.
  • Beginners can find the feature set overwhelming at first.

2. TradingView

This is more of a charting and social platform where live trading occurs through integrated, regulated brokers. It does allow order execution through some connected brokers, but most traders use it for analysis and execute trades on a separate platform.

Best for: Technical analysis, idea sharing and traders who want top-tier charts on mobile.

Fees: Free plan available (limited); paid plans start at approximately $14.95 per month. Broker commissions/spreads apply when trading.

Pros

  • Best-in-class mobile charting with full Pine Script support and synced layouts across devices.
  • Large community of shared ideas and scripts.
  • Clean execution when linked to a compatible broker.

Cons

  • Not a broker itself. You still need a regulated trading account.
  • Free version restricts indicators, alerts and multi-chart views.
  • Can feel feature-heavy for pure price-action traders.

3. IG

This platform has Tier-1 licences including FCA (UK), ASIC (Australia), BaFin (Germany) and others.

Best for: Traders who want a polished mobile app plus strong education and research.

Fees: Spreads from around 0.6 pips on EUR/USD (standard account); commission-based DMA account available for tighter pricing.

Pros

  • Award-recognised mobile app with clean order entry, 30+ indicators and reliable push alerts.
  • Excellent regulatory coverage and client-fund protection.
  • Broad multi-asset access beyond forex.

Cons

  • Spreads are competitive but not the absolute tightest for high-volume scalpers.
  • An inactivity fee can apply after prolonged non-use.
  • Advanced customisation is stronger on desktop than mobile.

4. OANDA

OANDA is regulated by the NFA (US), FCA, ASIC and additional licences across eight jurisdictions.

Best for: Beginners and traders who prefer transparent, spread-only pricing.

Fees: Spread-only accounts; EUR/USD typically around 1.2 pips. No minimum deposit on many entities.

Pros

  • Intuitive mobile app with solid charting (30+ indicators, multiple timeframes).
  • Clear pricing with no separate commission layer on standard accounts.
  • Strong educational resources and micro-lot trading.

Cons

  • Spreads are wider than pure ECN/raw-spread brokers.
  • Instrument range is narrower than some multi-asset competitors.
  • Withdrawal fees can apply after the first free withdrawal in a month.

5. Interactive Brokers

They are regulated by multiple Tier-1 regulators, including CFTC/NFA, FCA, MAS, SFC, and others.

Best for: Cost-conscious and professional traders who need global market access.

Fees: Forex commissions from 0.1–0.20 basis points of trade value (minimums apply); spreads as tight as 0.1 pip on major pairs.

Pros

  • Among the lowest all-in trading costs available.
  • Powerful mobile apps (IBKR Mobile and the simpler GlobalTrader) with deep market data.
  • Access to 100+ currencies and extensive forex pairs.

Cons

  • Interface and account setup feel complex for pure beginners.
  • Mobile experience prioritises depth over simplicity.
  • Some advanced tools still work better on a desktop.

6. SaxoRegulation:

Saxo Bank has a Danish FSA (full banking licence), FCA, ASIC and other Tier-1 licences.

Best for: Traders who want bank-level regulation plus high-quality research and multi-asset access.

Fees: Spreads from approximately 0.6–0.9 pips on EUR/USD (Classic account); tighter on higher tiers. Currency conversion is around 0.25%.

Pros

  • Excellent mobile app (SaxoTraderGO) with modern design, biometric login and solid charting.
  • Institutional-grade execution and research tools.
  • Strong regulatory standing as a licensed bank.

Cons

  • Higher account tiers require substantial deposits.
  • Mobile menu can feel dense for pure forex scalpers.
  • Pricing is competitive but not always the absolute lowest for ultra-high-volume traders.

Here is a table piecing these trading apps together.

Platform Regulated by Best for Minimum deposit Spreads
MetaTrader 5 (MT5) Via broker (varies) Advanced traders Via broker Via broker, 0.6-1.5 pips
TradingView No direct trading (via broker links) Charting and analysis N/A N/A
IG FCA (UK), ASIC, others UK traders, comprehensive offering £250 From 0.6 pips
OANDA FCA (UK), NFA (US), others US and UK traders, transparency No minimum From 1.2 pips
Interactive Brokers FCA, SEC, FINRA, others Active traders, professionals No minimum From 0.1 pips
Saxo Bank FCA, others Premium traders £500 0.6–0.9 pips

Best forex apps for beginners

If you are new to FX trading, your priorities should be different from what experienced traders are looking for. You can start from the easiest platform you can lay your hands on before moving to more complex articles.

Start with a broker that offers:

  • A free demo account
  • Clear educational resources
  • Transparent pricing
  • Strong regulation
  • An easy-to-use mobile app

Practice with virtual money until you understand how orders work, what leverage means in practice, and how quickly losses can accumulate. Once you have had a good grasp of how the platform works, you can start committing real money.

Platforms like Trading 212, XTB, and OANDA are designed for accessibility. They combine user-friendly interfaces with educational content and are regulated by the FCA for UK users.

Be cautious with copy trading. Platforms like eToro allow you to automatically copy the trades of other users. This seems appealing, but it does not remove your risk. Copied traders can and do lose money.

Avoid high leverage until you understand it. Even within regulatory limits, using maximum leverage as a beginner dramatically increases the chance of losing your entire deposit on a single trade going the wrong direction.

How to evaluate FX trading app safety

Before depositing any money, take a few minutes to verify that the broker is properly regulated. A legitimate broker should be easy to find on the relevant regulator's website.

Check the regulator

In the UK, search the broker on the Financial Conduct Authority (FCA) Register using its name or Firm Reference Number (FRN).

In the US, use the NFA BASIC database to confirm the broker is registered with the Commodity Futures Trading Commission (CFTC) and is a member of the National Futures Association (NFA).

If you can't find the broker on the appropriate register, don't open an account.

Watch for these red flags

Be cautious if a platform:

  • Isn't listed on a recognised regulatory register
  • Promises guaranteed profits or risk-free returns
  • Pressures you to deposit more money quickly
  • Makes withdrawals slow or unnecessarily difficult
  • Advertises returns that seem far better than those of established, regulated brokers

Understand what regulation protects

Regulation helps protect your money if a broker becomes insolvent, but it doesn't protect you from trading losses.

For example, eligible customers of firms that are authorised by the FCA may be entitled to the Financial Services Compensation Scheme (FSCS) for up to £85,000 if the broker collapses. However, this protection doesn't cover the money you lose on forex trades.

FX trading apps vs currency exchange apps

These are two different product categories, and it is worth being clear about the distinction.

FX trading apps are speculative tools. You buy and sell currency pairs hoping to profit from price movements. You take on risk, you can lose money, and your gains (if any) come from correctly predicting price direction.

Currency exchange apps like Grey are practical financial tools. You hold money in different currencies, convert when you need to, and use the funds for real purposes like paying invoices, receiving client income, or spending abroad. You are not speculating. You are managing money efficiently.

Feature FX trading app Grey
Purpose Speculative trading for profit Holding, converting, and sending currency
Risk High (can lose deposited funds) Low (conversion fee, transparent)
Regulation FCA, NFA, CFTC FinCEN, FINTRAC
Who uses it Traders Freelancers, expats, remote workers
Typical fee Spread + commission per trade 0.8% deposit (capped)+ 0.5% - 1% conversion.

If your goal is to speculate on exchange rates, you'll need a regulated forex broker.

If your goal is to receive USD, EUR, or GBP payments from overseas clients, convert currencies, or send money internationally, a multi-currency account like Grey is a more suitable solution. Open a multi-currency account with Grey to hold, spend, and convert USD, GBP, and EUR from one account.

Convert currencies with Grey without worrying about trading risks and hidden fees.

Frequently asked questions

What is the best FX trading app for beginners?

Trading 212, XTB, and OANDA are consistently among the best for beginners right now. All three are FCA-regulated, offer demo accounts, have clean interfaces, and provide educational resources. Start with a demo account on any of them before trading with real money.

Are FX trading apps safe?

Regulated FX trading apps from FCA, CFTC, or ASIC-authorised brokers are legitimate financial products. The firms themselves are subject to regulatory oversight. However, the trading itself carries substantial risk: the FCA requires most UK FX brokers to publish figures showing what percentage of retail clients lose money, and for most brokers this figure is between 70% and 80%.

Do FX trading apps work in the US?

Yes, although US regulations limit the number of brokers that can serve retail traders. Well-known options include OANDA, FOREX.com, and Interactive Brokers. Always verify that the broker is registered with the NFA before opening an account.

What is the cheapest FX trading app?

For the tightest spreads, Pepperstone's Razor account and Interactive Brokers are frequently cited. Costs vary based on trading volume and account type. The total cost per trade depends on the spread plus any commission, not the spread alone. Compare the all-in cost for the currency pair you plan to trade most often.

Can I lose more than I deposit on an FX trading app?

Retail traders using FCA- or ESMA-regulated brokers benefit from negative balance protection, meaning they cannot lose more than the money in their trading account. This protection may not apply in every country or to professional trading accounts, so always check your broker's terms.

Is Grey an FX trading app?

No. Grey is a multi-currency account designed for receiving, holding, converting, and sending foreign currencies. It doesn't offer leveraged forex trading or investment products. If you want to trade currency pairs, you'll need a regulated forex broker. If you simply need to manage money across currencies, Grey is the more appropriate option.
9 best platforms to earn US dollars in India

•

•

2 min read

You do not need to relocate to earn in dollars. Thousands of Indians are already doing it, working remotely for US companies, freelancing on global platforms, selling digital products, and teaching online. The platforms exist. The demand for Indian talent exists. The only question is how you set yourself up to earn, receive, and keep more of that income.

This guide covers the best platforms to earn US dollars in India, the types of work that pay in USD, and how to withdraw your earnings to your Indian bank account without incurring steep conversion fees or slow bank transfers.

Why earning in USD makes sense for Indians

The Indian rupee has depreciated consistently over the past decade, and inflation continues to pressure salaries and savings. At the same time, global demand for digital services in development, design, writing, marketing, and education continues to grow. Earning in a stable currency like USD gives you a structural advantage.

Beyond currency stability, dollar income gives you stronger purchasing power for international tools, courses, and subscriptions. It gives you better returns when saving or investing. And it gives you more control over when and how you convert, so you can time your conversions around exchange rate movements instead of being forced into bad rates by your bank.

What kind of work pays in USD from India?

Indians are earning dollars in more ways than most people realise. Some of the most common paths include:

  • Freelancing: Writing, web development, video editing, translation, graphic design, and digital marketing on platforms that connect you with international clients.
  • Remote contract jobs: Especially with US-based startups that hire globally for engineering, product, operations, and customer support roles.
  • Online tutoring and teaching: Conversational English, test prep (SAT, GRE, GMAT), and academic subjects through platforms that pay per session or per minute in USD.
  • Content creation: YouTube ad revenue via AdSense, Instagram Reels bonuses, podcast sponsorships, and newsletter monetisation.
  • Selling digital products: Online courses, design templates, printables, stock photography, and music through global marketplaces.
  • Affiliate marketing and dropshipping: Promoting international products and earning commissions in USD.
  • User testing and surveys: Getting paid to review websites, apps, and prototypes for US companies.

Whatever your skill set, there is likely a global market for it, and platforms to help you access it. If you are freelancing for international clients, Grey also lets you invoice clients abroad directly from the app.

Top platforms to earn US dollars in India

Here are 9 platforms Indians use to get paid in USD, with practical details on how each works.

1. Upwork

Upwork is one of the largest freelance marketplaces globally, and Indian professionals regularly secure contracts with US and European clients across fields such as software development, writing, design, data analysis, and virtual assistance. Upwork pays in USD and lets you withdraw via direct bank transfer, PayPal, Payoneer, or wire transfer.

The platform takes a sliding service fee: 20% on the first $500 with each client, dropping to 10% after that, and 5% after $10,000. Long-term contracts are where the real value is. Once you build a relationship with a client and move past the initial fee bracket, Upwork becomes significantly more cost-effective than other platforms.

Best for: Developers, writers, designers, VAs, and marketers with at least some portfolio work to show.

2. Fiverr

Fiverr works differently from Upwork. Instead of bidding on projects, you list fixed-price services ("gigs") and buyers come to you. This suits creatives and service providers who prefer packaging their skills into clear deliverables, such as logo design, video editing, voiceover work, social media management, or website builds.

Fiverr takes a flat 20% commission on every order. Earnings are in USD and can be withdrawn via PayPal, bank transfer, or Fiverr Revenue Card. The key to earning well on Fiverr is niche positioning and strong reviews. Generic gigs get buried.

Best for: Designers, video editors, voiceover artists, and anyone who can package a service into a clear deliverable.

3. Toptal

Toptal is a premium platform that accepts only the top 3% of applicants in software engineering, design, and finance. The vetting process is rigorous (multiple interviews and a test project), but the payoff is access to high-quality, well-paying contracts with major companies. Rates are significantly higher than general freelance platforms, often $60-$150+/hour depending on the role.

Best for: Experienced developers, designers, and finance professionals who can pass the vetting process and want premium rates.

4. Amazon KDP (Kindle Direct Publishing)

If you can write, Amazon KDP lets you self-publish eBooks, paperbacks, and low-content books (journals, planners, workbooks) and earn royalties in USD. Royalties range from 35% to 70%, depending on pricing and distribution. The income is passive once a book is published, and some Indian authors have built meaningful monthly income streams with a catalog of 10-20 books in specific niches.

Best for: Writers, educators, and anyone willing to learn self-publishing. Works well as a side income that compounds over time.

5. YouTube Partner Program

Once your channel hits 1,000 subscribers and 4,000 watch hours (or 10 million Shorts views), you can monetise through Google AdSense. Ad revenue is paid in USD. Indian creators in English-language niches (tech reviews, personal finance, education, productivity) tend to earn higher CPMs than Hindi-language content because advertisers pay more for English-speaking audiences.

Best for: Creators with a niche, consistency, and willingness to build an audience over 6-12 months before meaningful income kicks in.

6. Cambly

Cambly pays you to teach conversational English to learners worldwide. There is no lesson prep required; you simply have conversations. Pay is $0.17/minute ($10.20/hour), paid weekly via PayPal. The sessions are casual and unstructured, which makes it one of the lowest-effort ways to earn USD if you are a fluent English speaker.

Best for: Fluent English speakers looking for flexible, low-commitment side income. Particularly popular with students and professionals with flexible schedules.

7. Teachable and Gumroad

If you have expertise in any subject, you can package it as an online course (Teachable) or as a digital product, such as templates, guides, or design assets (Gumroad). Both platforms serve a global audience and pay in USD. Earning potential scales with your audience and your marketing. Some Indian creators earn $1,000-$5,000+/month from a single well-positioned course.

Best for: Subject matter experts, designers, and educators who can build or already have an audience to sell to.

8. UserTesting and TryMyUI

These platforms pay you to test websites and apps and share your feedback via screen recording. Each test takes 15-20 minutes and pays $4-$10 (UserTesting pays $10 for most tests). Availability depends on your demographic profile matching what companies need, so it works best as supplemental income rather than a primary source of income.

Best for: Anyone with clear English communication skills and a computer with a microphone. Good for side income between other work.

9. Etsy

Even without shipping physical products, you can sell digital downloads on Etsy: printable planners, resume templates, wedding invitations, digital art, and social media templates. Etsy charges a $0.20 listing fee plus a 6.5% transaction fee. Earnings are in USD. The platform has a built-in audience of buyers searching for these products, so you do not need to drive your own traffic.

Best for: Designers and creatives who can produce templates or digital art. Works well as passive income once listings are live.

Also read: Best way to receive euros in India

How to actually receive your USD earnings in India

Landing a client or getting approved on a platform is only half the problem. Withdrawing your earnings to India is where most people lose money.

Traditional Indian banks typically charge 1.5-3% on foreign currency conversion, add wire transfer fees of $15-$30 per transaction, offer exchange rates 2-4% worse than the mid-market rate, take 3-5 business days to process, and require paperwork that slows everything down. PayPal is faster but takes a 3-4% cut when converting USD to INR, in addition to withdrawal fees.

How Grey works for USD earnings in India

Grey gives you a free USD account with US bank details (routing number and account number). You can share these details with clients, connect them to freelance platforms, or use them to receive payments from any US-based source.

Here is how the flow works:

  1. Receive USD: Share your Grey US bank details with your client or platform. Payments arrive as standard ACH transfers.
  2. Hold or convert: Your USD sits in your Grey wallet. No forced conversion. You decide when to move it to INR based on the exchange rate.
  3. Withdraw to India: When you are ready, send to any Indian bank account using the recipient's IFSC code and account number. Grey charges a 1% conversion fee on USD to INR.
  4. Spend in USD: Need to pay for tools, subscriptions, or courses in dollars? Use your Grey virtual USD card to pay directly without converting first.

For a detailed walkthrough with screenshots, see the step-by-step guide to sending money to India. For a full breakdown of costs, check Grey's fees and charges.

Grey vs other ways to receive USD in India

Method Conversion Cost Speed Hold USD?
Grey 1% conversion fee Same day to 1 business day Yes, convert when you choose
Indian bank wire 1.5–3% + wire fee ($15–30) 3–5 business days Requires separate forex account
PayPal 3–4% total (conversion + withdrawal) 1–3 business days Limited, auto-converts
Payoneer Up to 2% + withdrawal fee 2–5 business days Yes, but fees on holding

You can check the current USD-to-INR rate and see the exact amount you would receive using Grey's fee calculator.

Also read: How to receive British pounds in India

Tips to maximise your USD earnings from India

Work directly with clients when possible

Platforms like Upwork and Fiverr take 10-20% in service fees. Once you have built a relationship with a client, consider moving to direct contracts with invoicing. You save the platform fee and get paid faster.

Time your conversions

The USD/INR rate fluctuates daily. If you can hold your dollars in your Grey account and convert when the rate is favourable, you keep more of your earnings. Watch exchange rate trends and convert in batches rather than converting every payment immediately.

Diversify your income sources

Relying on a single platform or client is risky. Combine freelancing with passive income (KDP, digital products) or side income (tutoring, user testing) to stabilise your cash flow.

Track everything

Use a simple Google Sheet or Notion database to track invoices, payment dates, conversion rates, and net INR received. This helps you understand your effective hourly rate across platforms and makes tax filing easier.

Understand the tax implications

Income earned in USD is taxable in India. Freelance income falls under "Income from Business and Profession" and is subject to your applicable income tax slab. You can deduct legitimate business expenses (software, equipment, and internet). If your gross receipts exceed Rs 50 lakh, you may need a tax audit. Consult a CA who understands freelance and foreign income if you regularly earn in USD.

This article is intended for general guidance and does not replace professional tax advice. Readers should consult a chartered accountant for personalised recommendations.

Start earning and receiving USD today. Open a free Grey account and get US bank details you can share with clients and platforms immediately.

Frequently asked questions

How can I earn US dollars from India?

You can earn USD from India through freelancing platforms (Upwork, Fiverr, Toptal), teaching English online (Cambly), selling digital products (Amazon KDP, Gumroad, Etsy), content creation (YouTube), and user testing (UserTesting). Most of these platforms pay in USD and allow you to withdraw to an Indian bank account or a USD account like Grey.

How do I receive USD payments in India?

You can receive USD payments through a Grey USD account, which gives you US bank details (routing number and account number) to share with clients or platforms. When you are ready to withdraw, you can send the funds to any Indian bank account using the recipient's IFSC code and account number. Grey charges a 1% conversion fee.

Is it legal to earn in USD from India?

Yes. Earning foreign currency for services rendered from India is legal under FEMA (Foreign Exchange Management Act) guidelines. You are required to declare the income for tax purposes, and it is taxable under the Indian income tax law based on your slab rate.

Which platform pays the most for freelancers in India?

Toptal pays the highest rates (often $60-$150+/hour) but only accepts the top 3% of applicants. For most freelancers, Upwork offers the best balance of volume and rate, especially once you move past the initial 20% fee bracket with repeat clients.

How do I avoid losing money on USD to INR conversion?

Avoid using traditional bank wires (1.5-3% markup) or PayPal (3-4% total cost). Use a platform like Grey that charges a transparent 1% conversion fee and lets you hold USD until the exchange rate is favourable. Check the exact amount you would receive using the fee calculator before converting.

Can NRIs use Grey to receive USD?

Grey provides USD accounts that NRIs can use to receive payments from US clients or employers. You can hold dollars in the account and send INR to any Indian bank account when you need to transfer money home.

More from Grey:

The best way to receive euros in Algeria

•

•

2 min read

A freelancer has just finished a project for a client in Paris, and a message comes in: payment sent in euros. For a moment, it feels like everything has worked.

By the next morning, a different question takes over. How does that €300 or €500 actually reach Algeria without being reduced from what was originally sent?

That question is not unusual. It reflects a wider reality for many people working remotely in Algeria today, especially those earning from Europe, where getting paid is straightforward, but receiving the money locally is not always as smooth.

This article explains the best ways to receive euros in Algeria, what affects the amount you keep, and how to avoid unnecessary losses during the process.

Challenges of receiving Euros from Algeria

Receiving euros in Algeria is often more complex than it appears. While international payments are possible, individuals and freelancers frequently face structural barriers that affect how quickly, and how much, they actually receive.

Official vs. black market rates

One of the most significant challenges is the gap between official exchange rates and the informal “square” market rate. When euros are processed through official banking channels, they are converted at the government-regulated rate, which can be up to 30% lower in real purchasing power compared to the parallel market. This creates a hidden loss for recipients, especially freelancers and remote workers who depend on foreign income. While the official system is legal and secure, the financial trade-off often feels substantial and discouraging.

Also read: The ultimate digital bank account for freelancers in Algeria

Currency conversion pressure

In many cases, euros sent into Algerian bank accounts are automatically converted into Algerian Dinars (DZD) upon arrival. This means recipients may not have the flexibility to hold or manage their funds in foreign currency. For individuals working with international clients, this reduces financial control and limits the ability to save in a stable currency. It also exposes earnings to local inflation and exchange rate fluctuations, which can affect long-term financial planning and stability.

Bureaucracy and delays

Bank transfers in Algeria are often subject to strict regulatory checks, which can result in long processing times. It is not uncommon for payments to be delayed for weeks or even months while banks request documentation such as invoices, contracts, or proof of income source. Although these measures are designed to prevent fraud and ensure compliance, they can create frustration for recipients who rely on timely payments for living expenses or business operations. The uncertainty can also make cash flow planning difficult.

Limited receiving options

Another key challenge is the limited range of formal channels available for receiving euros. Many international payment platforms either do not operate fully in Algeria or offer restricted services. As a result, individuals often rely on traditional bank transfers, which are slower and less flexible. This lack of diversified payment infrastructure reduces choice and can push users towards informal or less secure alternatives. It also slows down the integration of Algerian freelancers into the global digital economy.

Platforms to receive euros from Algeria

Receiving euros in Algeria is increasingly possible through digital platforms that simplify cross-border payments, reduce friction, and give users more control over how they access and convert funds.

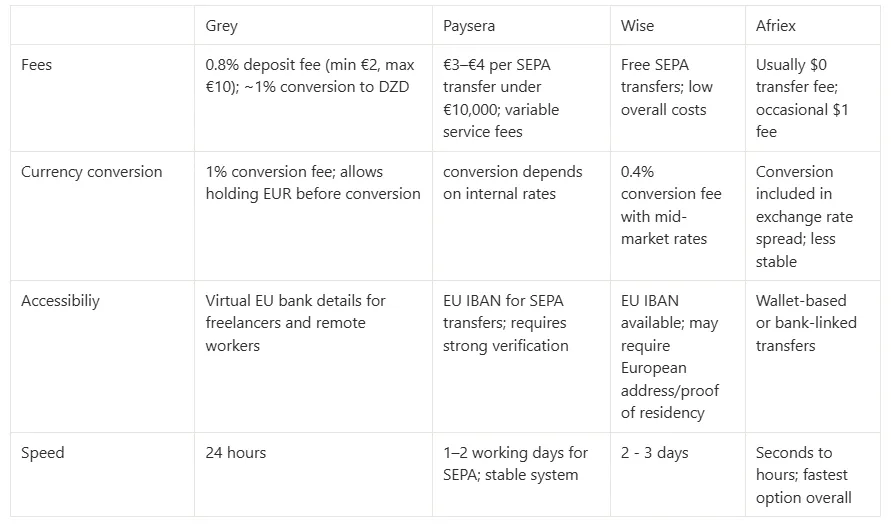
Grey

Grey allows users to receive euros into a digital account with virtual European banking details, making it suitable for freelancers and remote workers. Deposit channels such SEPA, and FPS typically attract a 0.8% fee, with a minimum charge of €2 and a maximum cap of €10, depending on transaction size. When converting euros to Algerian dinars, a 1% conversion fee is applied. This structure makes costs relatively predictable, while still giving users flexibility to hold euros before converting. Processing times are generally fast, supporting quicker access to funds compared to traditional banks.

Paysera

Paysera provides users with a European IBAN, enabling direct receipt of euros via SEPA transfers from clients or businesses across Europe. Incoming payments are generally charged between €3 and €4 for transactions below €10,000, making it cost-effective for moderate inflows. Users can keep funds in euros within the account, avoiding automatic conversion and giving more control over timing. However, additional fees may apply when withdrawing or transferring funds to other currencies. The platform is widely used for its stability, though verification requirements and compliance checks can extend onboarding time.

Wise

Wise supports multi-currency accounts, allowing users to receive, hold, and convert euros at low and transparent costs. SEPA transfers into Wise accounts are usually free, making it attractive for regular euro inflows. Currency conversion to Algerian dinars typically carries a low fee of around 0.4%, applied transparently using mid-market exchange rates. Users benefit from clear pricing without hidden spreads, helping them understand exact costs before transactions. However, full account functionality may require a European address and proof of residency, which can be a limitation for some users in Algeria.

Afriex

Afriex is designed for fast, low-cost international transfers, particularly across Africa and diaspora payment routes. Most transfers are free, though a small fee of around $1 may apply depending on the transaction type or corridor used. The platform focuses on speed, with many transactions processed almost instantly or within a few hours. Conversion rates are generally competitive, with costs embedded in the exchange spread rather than explicit charges. While convenient and accessible, features may vary based on user verification level and regional availability.

Comparing platforms to receiving euros in Algeria

__wf_reserved_inherit

When do you need Euros in Algeria?

There are several practical situations in Algeria where holding or receiving euros becomes important, especially for individuals engaged in global work, financial planning, or cross-border transactions.

International expenses

You need euros when paying for international services such as online subscriptions, foreign tuition fees, software tools, or freelance platforms. Many global companies price their services in EUR or USD, making local currency conversion unavoidable. Holding euros helps reduce repeated conversion costs and gives more control over timing payments when exchange rates are favourable. It also ensures smoother payments without delays or card failures when transacting on global platforms regularly.

Portfolio diversification

Euros are useful for diversifying savings beyond the Algerian dinar, which can be exposed to inflation and currency volatility. By holding part of your income in euros, you spread financial risk across currencies. This approach is especially valuable for freelancers and remote workers who earn internationally and want to protect long-term purchasing power. It also provides financial stability during periods of local currency instability and supports better long-term planning for savings and investments.

Wealth preservation

In uncertain economic conditions, euros can serve as a stable store of value amid local currency fluctuations. Many individuals save in euros to preserve wealth and shield themselves from inflation pressures within the broader African economic environment. It also provides flexibility for travel, investment, or future relocation plans.

Also read: Algeria visa requirements for EU citizens

How to optimise euro payments in Algeria

Optimising euro payments in Algeria requires more than just selecting a platform; it involves building habits that improve consistency and reduce financial leakage over time.

Hold euros before converting

Use platforms that allow you to store euros instead of forcing immediate conversion. This gives you more control over timing and helps you decide when exchange rates are most favourable. Instead of converting at the point of receipt, you can monitor market movements and convert when the rate works better for your income. Over time, this simple flexibility can make a noticeable difference in how much you actually retain from international payments, especially if you are earning consistently in euros.

Consolidate payments

Instead of receiving multiple small payments, try to combine invoices where possible. Each transaction often comes with a fee, and when payments are split, those charges repeat unnecessarily. By consolidating your earnings into fewer, larger payments, you reduce the number of times fees are applied. This improves overall cost efficiency and also makes it easier to track income, manage cash flow, and plan expenses more accurately. It is a small operational change that can significantly improve how much you keep over time.

Compare platforms regularly

Payment platforms are not static. Fees, exchange rates, and processing speeds can change, and new competitors often enter the market with better terms. Regularly reviewing your options ensures you are not locked into outdated or expensive systems. A platform that was cost-effective last year may no longer be the best choice today. By comparing periodically, you stay informed and positioned to move to better options that improve your overall earnings retention and reduce unnecessary losses.

Separate spending and savings

Keep a portion of your income in euros for stability while converting only what you need for local expenses. This approach helps you reduce exposure to currency fluctuations and protects your earnings from sudden naira depreciation. It also encourages better financial discipline by separating operational spending from long-term value storage. Over time, this balance gives you more control, smoother budgeting, and a stronger buffer against inflation risks.

Frequently asked questions

Can I legally receive euros in Algeria through digital platforms?

Yes, you can receive euros in Algeria through regulated digital platforms and international transfer services. However, funds are often subject to local banking rules, documentation checks, and currency controls. While the platforms are legal, the way funds are converted or accessed may still depend on Algerian financial regulations.

Why do I lose money when receiving euros through banks in Algeria?

Losses usually come from currency conversion and exchange rate differences. Banks often apply the official rate, which is lower than the parallel market value. In addition, hidden service fees and automatic conversion to dinars reduce overall value. This gap creates a real difference in purchasing power for recipients.

Is it better to hold euros or convert immediately to dinars?

Holding euros is often more financially strategic, especially during inflation or currency instability. Euros maintain stronger global value compared to local currency fluctuations. However, immediate conversion may be necessary for daily expenses. The best approach depends on your financial goals, urgency of spending, and risk tolerance.

Why are international transfers sometimes delayed in Algeria?

Delays often result from strict compliance checks, anti-money laundering regulations, and documentation requirements. Banks may request invoices, contracts, or proof of income source before releasing funds. While these processes ensure security, they can significantly slow down payments, especially for freelancers who receive frequent international transactions.

Receiving EUR payments from Algeria

Managing international payments from Europe is now easier for freelancers and remote workers in Algeria. Grey provides users with  EUR accounts, complete with European banking details that allow clients to send payments as if they were making a local transfer within the SEPA network. This eliminates unnecessary friction and significantly simplifies cross-border transactions.

You can also manage multiple currencies, including EUR and GBP, all within the same platform, giving you greater control over your earnings. With competitive exchange rates and flexible conversion options, you can decide when and how to convert your funds.

Sign up on Grey and download the app to get your EUR banking details within minutes.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN, 0.5% for EUR/GBP (minimum €2/£2, maximum €10/£10), and $0.50-$0.65 for KES/UGX/TZS. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction. Visit grey.co/pricing for current rates.

How to pay for subscriptions in US dollars from South Africa

•

•

2 min read

We understand the struggles of subscribing to services that charge in US dollars from South Africa. Between the high conversion rate, card declines, location restrictions and delayed confirmations, paying for subscriptions in USD from South Africa can be frustrating. Fortunately, with Grey, you now have a more flexible and affordable way to manage your subscriptions in USD from South Africa.

This article explores the easiest way to pay for subscriptions in US dollars with Grey and how to get started.

Also read: How to receive your Shopify earnings in South Africa

Common challenges with subscription payments

Some of the challenges you might experience when managing subscription payments in USD in South Africa include:

  • Card restrictions: Local cards are often rejected for international or recurring USD payments.
  • High conversion fees: Traditional banks often have unfavourable exchange rates and high charges.
  • Location restrictions: Some platforms restrict payments for subscriptions to US cards registered to a US address. This inevitably restricts people in South Africa.
  • Inconsistent payment success: Payments may fail due to bank restrictions or fraud detection.
  • Unreliable transaction approvals: Many payment methods are not reliable, especially with recurrent subscriptions. Future transactions can still be declined for various reasons, including bank-imposed restrictions or automated fraud detection systems.

Platforms requiring USD payment

Many international streaming services, SaaS tools, hosting platforms, cloud storage, and global learning platforms often charge in US dollars. Whether for work, entertainment or learning, here are some popular platforms in South Africa that require payment in USD.

  • Streaming services: Netflix, Hulu, Disney+
  • Creative and productivity tools: Adobe Creative Cloud, Canva Pro, Microsoft 365
  • E-commerce and marketplaces: Amazon Prime, Shopify, GoDaddy
  • Learning and educational platforms: Coursera, Udemy, MasterClass
  • AI and cloud-based tools: ChatGPT Plus, Google Workspace, Dropbox

Also read: Best ways to receive international wire transfers in South Africa

How Grey helps you pay for USD subscriptions

Grey simplifies USD subscription payments for South Africans by offering flexible and affordable payment methods. Grey helps you pay for USD subscriptions without breaking a sweat by offering:

1. Virtual USD card

Most platforms accept Grey’s virtual USD debit card, bypassing card incompatibility and geo-blocking. It supports recurring payments for uninterrupted access.

2. Affordable fees

Grey offers low charges on transactions and currency conversions with no hidden fees.  ****

3. Seamless platform integration

Grey integrates well with many payment platforms, offering ease in managing subscriptions.

4. USD accounts

Grey allows you to open and manage USD accounts from South Africa with straightforward funding options. With this account, users can pay for subscriptions via bank transfers.

How to pay for subscriptions in US dollars from South Africa

To pay for subscriptions in US dollars from South Africa using Grey, follow these steps:

  • Sign up for Grey: Visit Grey’s website or download the app on your mobile device. Create an account using your details (name, email, phone number).
  • Verify your identity: Complete the Know Your Customer (KYC) process by uploading a valid South African ID (national ID, driver’s license, or passport) and proof of address (e.g., utility bill or bank statement). This ensures compliance with regulations.
  • Request a USD account: Once verified, request a USD account through the Grey app or website. You’ll receive US bank account details (e.g., account number, routing number) that function like a US-based bank account.
  • Create a virtual USD card: Navigate to the “Card” tab in your Grey dashboard. Pay a one-time card creation fee of $4 and add at least $1 to activate the virtual USD card. This card is globally accepted and works for USD-based subscriptions.
  • Fund your account: Deposit money into your Grey USD account via bank transfer, mobile money, or other supported currencies (e.g., ZAR, GBP, EUR). Convert funds to USD within the Grey platform at competitive exchange rates with no hidden fees.
  • Pay for subscriptions: Use your Grey virtual USD card to subscribe to platforms like Netflix, Adobe Creative Cloud, Spotify, or Coursera. Enter the card details at checkout as you would with any debit or credit card. The card works seamlessly for one-time or recurring payments without regional restrictions.

Why you should opt for Grey for your USD subscriptions in South Africa

Grey is your surest bet for managing USD subscriptions in South Africa.

  • Global acceptance: The virtual USD card is accepted by major platforms, avoiding issues with local South African cards that may be declined due to geo-blocking or currency restrictions.
  • Transparent fees: Grey offers competitive exchange rates and no hidden charges, unlike traditional banks that may impose high FX fees.
  • Ease of use: The setup is quick, digital, and manageable from your phone, with a user-friendly interface.
  • Reliability: Ensures uninterrupted subscriptions with no declined payments or delays, ideal for services like streaming, productivity tools, or online courses.

Hassle-free USD subscriptions with Grey

Grey is a reliable digital payment solution that simplifies international transactions and helps users manage USD subscriptions from South Africa. By addressing common payment challenges, Grey ensures reliable access to streaming, productivity, e-commerce, educational, and AI platforms. Users enjoy the flexibility of managing subscriptions via their USD bank account or a versatile virtual USD card.

Sign up on Grey’s website or download the app to start managing subscriptions in USD without breaking a sweat.

‍

How to enjoy Afro Nation on a budget

•

•

2 min read

There’s nothing quite like Afro Nation. The sun, the sand, the sound of Afrobeats blaring across the beach as Africa’s biggest music stars light up the stage. There aren’t enough superlatives to describe the thrill of being surrounded by people from every corner of the world whose sole aim is to enjoy African music. It’s an experience, a proper one.

Experiences like this don’t come cheap. The costs can pile up quickly between ticket prices, flights, accommodation, and “soft life” expenses.

However, you can organise an unforgettable Afro Nation trip on a budget with a little strategy and planning.

Why Afro Nation is worth every cent, even on a budget

Since its debut in Portugal in 2019, Afro Nation has grown from a niche event into one of the most anticipated music festivals worldwide. What started as a dream to unite people through music is now a global movement, pulling crowds from everywhere.

The headliners (even though the line-ups are always insane) aren’t the only reason it has so many attendees. A lot of this is owed to the community, culture, and reconnecting with your roots, all while partying in some of the most beautiful coastal locations in the world.

The experience is what you make it. Budget or not, the vibe remains undefeated.

Also read: How to apply for a digital nomad visa in Portugal

How to score affordable tickets to Afro Nation

The first rule of Afro Nation is to buy your ticket early.

  • Early bird tickets are always the cheapest. Waiting till the line-up drops might feel smart… until you see the price jump.
  • Don’t feel pressured by VIP hype. General Admission gets you into the same party, same performances, and same memories.
  • Keep an eye on official giveaways or community forums; you’d be surprised by how often people resell tickets.

Finding budget-friendly flights

Flights are often the most expensive part of this trip, but they don’t have to be.

  • Use comparison tools like Google Flights, Skyscanner, or Hopper to spot the cheapest options.
  • Be flexible. Flying midweek instead of weekends can save hundreds.
  • Book as early as you can. Last-minute deals are rare for festival season.

Also read: How to receive and convert foreign currencies to USDC in Portugal

Where to stay without going broke

Accommodation during Afro Nation sells out fast.

  • Airbnb with friends is king. Not only does it save money, but it also makes for a more social trip. Split the cost, split the snacks, split the vibes.
  • Consider hostels, modern hostels are clean, safe, and often full of other festival-goers. Instant new friends.
  • Book a spot a bit further from the festival site and commute in. Buses, trains, or group Ubers make it easy and affordable.
  • Lock it in early. Prices skyrocket as the event gets closer.

Eating, drinking, and moving around like a pro

  • Skip tourist traps. Find local markets or restaurants for authentic meals at half the price.
  • Grocery stores are lifesavers. Stock up on snacks, water, and easy breakfasts.
  • Use public transport where possible. It’s cheap and reliable.
  • Split rides with other festival-goers through group chats or apps.

Tips to enjoy Afro Nation on a budget

It’s easy to go from “I’m being responsible” to “How did I just spend €200 on drinks?”

  • Set a daily budget before you arrive.
  • Grey is your secret weapon here. Open a free EUR account, load your funds, and spend directly. There are no hidden conversion fees and no nasty surprises.
  • Watch out for overpriced festival merch. If you really want it, budget for it upfront.
  • Bring essentials: a reusable water bottle, snacks, and a portable charger so you won’t spend money on unnecessary items.
  • Book everything early. Seriously, everything.
  • Travel with friends to split costs.
  • Stick to your spending plan (but leave room for some fun).
  • Prioritise the moments. The music. The people. The memories.

Also read: How Grey differs from a US bank

How Grey helps you stay on budget

Currency fees can eat into your wallet when you’re hopping between currencies.

Here’s how Grey saves the day:

  • Open a EUR, USD or GBP account from home.
  • Pay for tickets, flights, and accommodation without expensive bank fees.
  • Convert between currencies at great rates, not your bank’s shady rates.
  • Withdraw or convert back to your home currency when you’re done, quickly and easily.

With some planning (and a little help from Grey), you can dance, vibe, and live your best life at Afro Nation without the stress of blowing your budget.

Create your Grey account today or download the app to plan your global adventures smartly.

‍

How Grey differs from a EUR bank

•

•

2 min read

Living in this digital age means our worlds are better connected, and so should our finances. Managing international finances requires fast, affordable, and accessible solutions. Traditional EUR banks, such as Deutsche Bank, BNP Paribas, and ING, have long dominated the financial landscape in Europe. However, emerging fintech platforms like Grey are spicing things up to match the demands of this digital age.

Grey is at the forefront of simplifying international transactions by providing users with foreign bank accounts (including EUR accounts) regardless of location. A EUR bank account is typically issued by conventional banking institutions operating in the Eurozone. While the functionality of both banking solutions might overlap, there are vast differences.

This article explores how Grey compares to EUR banks regarding account setup, fees, international transfers, access, features, and regulatory coverage.

Also read: Monieworld vs Juicyway vs Cleva vs Grey – which is better?

How is Grey different from EUR banks?

EUR banks are conventional financial institutions, typically based in the European Union. They are designed to serve residents, businesses, and entities within the region. Grey, on the other hand, is a digital cross-border banking platform that offers multi-currency accounts for users within and outside the EU. Grey users can receive, convert, and spend EUR, USD, and GBP without visiting a bank.

Account opening requirements

EUR banks:

Opening an account with a European bank usually requires proof of residency in the EU, a national ID or passport, and sometimes even a tax ID or local address. Depending on the bank’s regulations, the process can take several days or weeks. Many times, In-person visits or video interviews may be necessary, especially for non-EU residents.

Grey:

Grey simplifies the onboarding process. You only need a government-issued ID and a selfie to verify your identity. The account opening is entirely online and can be completed within minutes without providing proof of EU residency or address. This makes it ideal for anyone who needs to receive and manage euros both within and outside the EU.

Currency support and multi-currency accounts

EUR banks:

Most EUR banks only support euro transactions. While some may support foreign currencies like USD or GBP, high exchange fees and conversion limits might apply. For some others, multi-currency features are limited to big businesses or premium customers.

Grey:

Grey offers multi-currency accounts (EUR, USD, GBP). Users can receive international payments, convert currencies at competitive rates, and withdraw funds to their local bank in various currencies. This allows users to streamline their finances by seamlessly switching between currencies.

Also read: The best international bank accounts for freelancers and remote workers

International money transfers

EUR banks:

Sending money internationally from a EUR bank is often expensive and slow. SWIFT transfers are not always swift, as they can take 2–5 business days. Besides the high fees, some EUR banks charge hidden exchange rate markups or intermediary bank fees. SEPA transfers are faster within the EU but dicey when sending money to Africa or Asia.

Grey:

Grey is optimised for cross-border payments. International transfers from your virtual EUR account to a local account in Nigeria or the Philippines can be completed in minutes, and currency conversions are instant. Grey’s fees are affordable and transparent, as they tell you how much a transaction will cost before initiating it.

Additional fees

EUR banks:

Aside from the regular transfer fees, EUR banks typically charge monthly maintenance fees, card issuance fees, and ATM withdrawal charges. They also profit from foreign exchange markups and may impose penalties for account inactivity or overdrafts.

Grey:

Grey doesn’t charge monthly fees or require minimum balances. Its fees are clearly listed and usually limited to currency conversions and international withdrawals. There are no hidden markups.

Range of services

EUR banks:

Conventional EUR banks offer a broad range of financial products and services. These include credit and debit cards, savings accounts, personal and business loans, mortgages, investment services, insurance, and overdraft facilities. For individuals and businesses needing a more holistic financial experience and access to credit, EUR banks remain the go-to institutions.

Grey:

Grey focuses specifically on international money services. It is not designed to replace a traditional bank for savings, loans, or insurance. Instead, Grey caters the financial needs of individuals who need multi-currency accounts, seamless international payments, and competitive exchange rates.

Regulatory framework and security

EUR banks:

Traditional banks in Europe are regulated by central banks or financial authorities such as the European Central Bank (ECB) or local regulators (e.g. BaFin in Germany, ACPR in France). They offer deposit insurance and are required to meet strict capital requirements.

Grey:

Grey is not a conventional bank but a regulated fintech platform. It partners with licensed financial institutions and complies with KYC/AML regulations in the jurisdictions where it operates. The platform is registered in the United States and subject to the regulatory oversight of the Financial Crimes Enforcement Network (FinCEN) and the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC). It uses industry-standard security protocols to protect your funds and data.

Understanding how Grey differs from a EUR bank

Grey is designed to simplify global transactions for international students trying to pay their fees, freelancers managing payments from international clients, businesspeople transacting globally, and travellers visiting new countries. While EUR banks are better tailored to people resident in the EU zone, Grey offers financial freedom to people who would love to manage multiple currencies on one platform and enjoy transparent fees, swift transactions and competitive exchange rates from anywhere in the world.

Sign up on Grey today to manage your global finances with ease.

‍

Arrow (up)

Back to top

