<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#article","headline":"Receive US payroll payments outside the US","description":"How remote workers receive US payroll payments outside the US at transparent exchange rates.","inLanguage":"en","url":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us","mainEntityOfPage":{"@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#webpage"},"datePublished":"2026-03-31T13:20:44.086Z","dateModified":"2026-06-15T14:19:14.556Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3009e218ef06ba07c2d734_6a3009e1f573870469a3c007_receive-us-payroll-payments-outside-the-us__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3009e218ef06ba07c2d734_6a3009e1f573870469a3c007_receive-us-payroll-payments-outside-the-us__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#webpage","url":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us","name":"Receive US payroll payments outside the US","description":"How remote workers receive US payroll payments outside the US at transparent exchange rates.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Receive US payroll payments outside the US","item":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us"}]},{"@context":"https://schema.org","@type":"FAQPage","@id":"https://grey.co/blog/receive-us-payroll-payments-outside-the-us#faq","mainEntity":[{"@type":"Question","name":"Can I receive US payroll without a US bank account?","acceptedAnswer":{"@type":"Answer","text":"Yes, but it’s inefficient and expensive. Most US payroll systems use ACH direct deposit, which requires US routing and account numbers. Without these, companies must send international wire transfers, which cost them and you significant fees and poor exchange rates. Modern USD account platforms provide US banking details without requiring US residency."}},{"@type":"Question","name":"Do I need to be a US citizen to receive a U.S. salary?","acceptedAnswer":{"@type":"Answer","text":"No. US companies can hire and pay non-US citizens working remotely from outside the US. Employment classification and tax implications vary based on your residency status and where you perform work, but citizenship isn’t required."}},{"@type":"Question","name":"Will the US company withhold taxes from my salary?","acceptedAnswer":{"@type":"Answer","text":"It depends on your classification and tax residency. If you’re a contractor and not a US tax resident, complete Form W-8BEN to prevent 30% withholding. If you’re an employee, tax withholding depends on how the company structures your employment. Consult tax professionals for your specific situation."}},{"@type":"Question","name":"What’s the difference between contractor and employee classification?","acceptedAnswer":{"@type":"Answer","text":"Contractors are self-employed, invoice for services, handle their own taxes, receive no benefits, and have work flexibility. Employees are on the company’s payroll, receive regular salary, may get benefits, and have employment protections. Classification depends on the nature of the working relationship, not just on contract language."}},{"@type":"Question","name":"How long does US payroll take to arrive via ACH?","acceptedAnswer":{"@type":"Answer","text":"ACH transfers typically clear within 1-2 business days of payday. Some modern payroll platforms offer same-day ACH. This is substantially faster than international wire transfers, which take 5-10 business days."}},{"@type":"Question","name":"What is Form W-8BEN, and why is it important?","acceptedAnswer":{"@type":"Answer","text":"Form W-8BEN certifies you’re not a US taxpayer. Without it, US companies must withhold 30% of contractor payments for US taxes. Completing W-8BEN prevents this withholding and confirms you’ll handle taxes in your country of residence."}},{"@type":"Question","name":"How much will I lose to currency conversion?","acceptedAnswer":{"@type":"Answer","text":"Traditional bank wire transfers typically cost 5-7% total in fees and poor exchange rates. USD accounts with transparent conversion rates cost approximately 1–2% total. On a $60,000 annual salary, this difference saves $3,000–3,600 annually."}},{"@type":"Question","name":"Can my employer pay me in my local currency?","acceptedAnswer":{"@type":"Answer","text":"Some employers offer this, but it’s usually worse financially. They convert USD to your currency at unfavourable corporate exchange rates, often with a 4–6% markup. Receiving USD and handling conversion yourself using competitive rates is typically better."}},{"@type":"Question","name":"What if the company says they can’t pay internationally?","acceptedAnswer":{"@type":"Answer","text":"They likely mean their payroll system only supports domestic ACH. Provide USD account details (routing and account number) from a platform like Grey Business. From their perspective, you’re providing standard US banking information that works with existing systems."}}]}] </script>

Receive US payroll payments outside the US

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

How do US employers make domestic US payroll payments?

The general process is to enter a US address, provide a US routing number and account number, and the system will process direct deposit smoothly. Usually, everyone gets paid on schedule.

The dynamics change when someone the employer hires someone from outside the US. Their payroll system requires US banking details that this person doesn’t have. Finance could suggest international wire transfers, which trigger manual processing, about $20 sending fees, week-long delays, and significant deductions from intermediary banks before the money arrives.

In this article, I explain how US payroll systems work, why they create problems for international workers, your actual payment options, and how to receive a US salary efficiently regardless of where you live.

How does US payroll actually work?

Most US companies don’t process payroll manually, instead they use platforms that automate salary calculations, tax withholding, compliance reporting, and payment distribution. These platforms are designed around US domestic assumptions:

  • Employees have US bank accounts with routing and account numbers
  • Employees live in states with specific tax codes
  • Employees fall under US employment law and tax jurisdiction.

The standard payment method is direct deposit through the Automated Clearing House (ACH) network. On payday, the payroll platform initiates ACH transfers from the company’s bank account to each employee’s account. Money moves through the ACH network and typically clears within one to three business days.

ACH is fundamentally domestic. It requires US routing numbers that identify specific US banks and US account numbers that identify specific customers at those banks. International bank accounts don’t participate in the ACH network.

A Nigerian bank account, for example, has an account number and a sort code that follow Nigerian banking standards. An Indian bank account uses IFSC codes and account numbers in the Indian format. These don’t translate into the nine-digit routing numbers and account numbers that US payroll systems expect.

When you don’t have US banking details, several complications arise immediately. The payroll system flags your profile as incomplete or problematic because required fields are empty. Some companies refuse to hire international workers specifically because they find payment too complicated to navigate.

Companies willing to pay internationally face additional challenges. International wire transfers require manual processing outside the normal automated payroll flow. Someone in finance usually must log into the banking platform, enter wire transfer details manually, obtain approval for international payments (often requiring senior authorisation that domestic payroll doesn’t), and initiate the transfer separately from the rest of payroll. Each wire costs the company about $20 in sending fees.

Beyond logistics, there’s the complexity of tax withholding. US payroll systems automatically withhold federal income tax, Social Security, Medicare, and state taxes from employee paychecks. These withholdings apply to US tax residents.

If you’re not a US tax resident or you’re not a US citizen or green card holder, these withholdings shouldn’t apply to you. But payroll systems assume everyone is subject to US tax withholding. Configuring the system to pay someone without US tax withholding requires manual intervention and understanding of tax treaty provisions and IRS regulations.

Then there’s the employment classification question. If you’re working full-time remotely from outside the US, the company needs to determine whether you’re a US employee working abroad temporarily. Are you a foreign employee of a foreign subsidiary? Are you actually an independent contractor despite operational aspects that appear to be employment?

Each classification has different tax implications, different legal obligations, and different payment processes. Many US companies, especially startups and small businesses, aren’t equipped to navigate this. They want to hire talented people regardless of location, but their finance and legal advisors raise compliance concerns that feel insurmountable.

This is why understanding the mechanics matters.

Also read: How consultants structure international client payments

Employment classification: Employee vs contractor

How you’re classified legally determines how payment works, what tax obligations apply, and what documentation both you and the company need.

If you’re classified as an employee, the US company has specific legal obligations. They must provide benefits as required by law if you’re a US-based employee, though obligations differ for foreign employees. They must ensure compliance with employment laws both in the US (for aspects of the employment relationship governed by US law) and potentially in your country of residence.

For non-US residents working remotely outside the US, employment can be complex. Many countries require foreign companies employing local residents to register as employers, withhold local income taxes and social contributions, and comply with local employment standards.

This is why many US companies use Employer of Record services for international employees. The EOR becomes your legal employer in your country, handling local compliance whilst you work operationally for the US company.

Independent contractor classification simplifies payment significantly. As a contractor, you’re self-employed and responsible for your own taxes in your country. The US company has no tax withholding obligations (as long as you’re not a US tax resident). There are no employment law obligations in your country because you’re not an employee.

Payment works the same way as paying any other vendor. You submit invoices, and the company pays them. You don’t receive employee benefits like health insurance or paid time off, but you also have more flexibility in how you structure your work.

Now if you’re properly classified as an employee, the company needs to run you through payroll, which requires addressing all the payment and tax complexities discussed earlier. They may need to establish legal presence in your country by registering an entity or by using an expensive Employer of Record (EOR) service. Payment comes as regular salary on the company’s normal payroll schedule, and you may be subject to local tax withholding depending on how the company structures your employment.

If you’re properly classified as a contractor, you invoice the company for completed work. They pay your invoices the same way they’d pay any vendor. There’s no payroll involvement and no company obligation to withhold taxes. You’re fully responsible for tax compliance in your country. Payment methods are flexible, and the company can use whatever method works best: wire transfer, payment platforms, or modern cross-border payment infrastructure.

The practical reality for most remote international workers is that many who join US startups are technically contractors, even if the company internally calls them “employees.” The company doesn’t want to navigate foreign employment law or establish legal entities in your country, so they structure the relationship as independent contracting, whilst treating you like a team member operationally.

This works as long as you’re comfortable with contractor classification, you handle tax obligations properly in your country, and the company doesn’t exert so much control over your work that you’re actually a misclassified employee. Misclassification creates legal risk that can result in penalties, back taxes, and employment law violations.

Before accepting any position, clarify whether you’re being hired as an employee or contractor. If you’re an employee, understand how the company will handle international employment compliance. If you’re a contractor, understand the invoicing schedule, payment terms, and your tax obligations.

Also read: Global bank accounts vs offshore accounts: what’s the difference

The traditional methods that US companies use to pay international workers and their problems

When companies decide to pay workers outside the US, they typically choose from several established approaches. Each has significant limitations.

International wire transfers via SWIFT are the most common default. The company initiates a wire from their US bank to your bank account in your country. Money passes through the SWIFT network, typically involving one or more intermediary correspondent banks that facilitate cross-border transfers.

The problems are cost and speed. The company pays $30-50 per wire in sending fees. Intermediary banks deduct $20-40 combined for processing the transfer. Your local bank charges a receiving fee of $15-25. Then comes currency conversion. If your account is in local currency, your bank converts the USD at a rate that includes a 3-5% markup over the mid-market rate.

On a $5,000 monthly payment, you can lose up to $250-400 to fees and conversion. The transfer takes three to five business days, sometimes longer, depending on the countries involved and any compliance holds. For the company, this is a manual process. Someone in finance must initiate each wire separately outside the normal payroll system. This doesn’t scale when paying multiple international workers monthly.

Employer of Record (EOR) services like Deel, Remote, and Oyster solve the compliance problem by becoming your legal employer in your country. They handle local tax withholding, benefits administration where required, employment law compliance, and regulatory reporting. The US company pays the EOR, and the EOR pays you in local currency through local banking.

From a compliance perspective, EORs are excellent. They handle complexity that the US company doesn’t want to navigate. You get true employee status with proper local compliance. The relationship is clear and legally sound.

The problems are cost and the employment relationship structure. EOR services charge companies 15–30% above your salary in fees. On a $100,000 salary, the company pays $115,000–130,000 total. Many startups and small companies can’t afford this premium, especially when hiring multiple international workers.

From your perspective, you’re employed by the EOR, not the US company. This can affect equity grants, promotion paths, and a sense of belonging to the team. You’re legally an employee of Deel or Remote, working for the US company through a services agreement. For some people, this matters. For others, it’s irrelevant as long as payment and compliance work smoothly.

Cryptocurrency and stablecoin payments are experimental. Some companies pay contractors in USDC or other stablecoins. Transfers are fast and cheap, but tax reporting is complex in most countries, not all workers are comfortable with crypto, regulatory frameworks are uncertain, and most professional payroll systems don’t support cryptocurrency payments. This remains a niche solution for specific situations, not a mainstream payroll approach.

The pattern across these traditional methods is that they’re either expensive (losing 5–10% to fees), slow (taking a week for payment to clear), administratively burdensome for companies (manual processes outside normal payroll), or legally complex (requiring entity formation or expensive EOR services).

Also read: Alternatives to domiciliary accounts in Nigeria

What you actually need to receive US payroll payments

Strip away complexity and focus on what actually needs to happen for payment to work.

For the company’s payroll system to process your payment smoothly, they need banking details that their system recognises. Most US payroll platforms expect US routing and account numbers. If you can provide those, payment works exactly like paying any other employee. The system validates the routing number, confirms the account number, and queues the ACH transfer for the next payroll run.

For payment to reach you efficiently, you need to receive USD without incurring significant fees or currency conversion costs. Payment should arrive within reasonable timeframes, 1 to 3 business days, not 7. You should be able to convert USD to your local currency at transparent rates when you choose, not when a bank forces immediate conversion.

For tax compliance, if you’re a contractor, you need to provide the company with Form W-8BEN certifying that you’re not a US taxpayer. This prevents them from withholding 30% of your payment for US taxes. If you’re an employee, tax withholding depends on your residency status and the company’s employment structure. This typically requires professional tax advice specific to your situation.

For legal compliance, the company needs to properly classify you as an employee or a contractor. If you’re a contractor, they need a clear contract specifying deliverables, payment terms, and intellectual property ownership. If you’re an employee, they need to address employment law compliance in your country, either through EOR services or by establishing legal presence themselves.

For documentation and record-keeping, you need transaction records for your country's tax filing. The company needs records for their accounting and potential audits.

What solves most of these requirements simultaneously is a USD account with US banking details that you provide to the company’s payroll system. This makes you payable through their normal automated process without requiring special international payment procedures.

The account should provide legitimate US routing and account numbers that payroll systems accept, allow you to hold USD without forced immediate conversion, offer transparent and affordable conversion to your local currency when needed, and generate proper transaction records suitable for tax documentation.

Also read: Best dollar account apps in Nigeria compared

How USD accounts enable US payroll reception outside the US

Modern financial infrastructure has developed solutions specifically designed to address this problem.

Fintech platforms partner with US banks through what’s called banking-as-a-service arrangements. The platforms hold financial services licenses in regulated jurisdictions for example, FINTRAC in Canada, FinCEN in the US and FCA in the UK. These partnerships enable the platform to provide US bank account details to customers worldwide without requiring them to establish direct relationships with US banks.

When you sign up with one of these platforms, you provide identification documents and proof of address from your country. Once your KYC is completed and verified, you receive a US routing number that identifies the platform’s partner bank and a US account number unique to you.

These details function exactly like traditional US bank account details for receiving ACH payments. When your US employer’s HR team asks for banking information, you provide your routing and account number. From their perspective, you’re providing standard domestic banking details. The payroll system validates the routing number, confirms it’s a legitimate US bank, and saves your information alongside other employees.

On payday, the payroll platform initiates an ACH transfer to your routing and account number. Payment enters the US ACH network, the same system used for all domestic payroll. Payment clears in one to two business days, sometimes same-day for instant payroll platforms. Funds are credited to your USD balance held by the fintech platform, segregated in accounts at the partner bank.

You can then hold the USD without converting it, convert to your local currency at transparent rates (typically 1–2% over mid-market rate, significantly better than the 3–5% markup traditional banks apply), withdraw to your local bank account in local currency, or spend directly using a USD debit card if the platform provides one.

This works for both you and your employer because it requires no changes to their payroll process, involves no special international payment procedures, creates no additional fees beyond normal payroll costs, eliminates manual wire transfers each pay period, and produces clean payroll records exactly like any other employee.

For you, it means receiving the full salary amount via ACH with no wire fees or intermediary bank deductions, control over currency conversion timing, transparent exchange rates when you do convert, proper documentation for tax purposes, and fast payment clearing in one to two days instead of seven to ten.

The financial difference is significant. With a traditional international wire transfer on $5,000 monthly salary, wire transfer fees cost $40, intermediary banks deduct $30, your bank charges $20 receiving fee, and currency conversion markup at 3% costs $150. You receive approximately $4,760. You’ve lost $240 or 4.8% of your salary.

When a USD account receives an ACH payment, there are no receiving fees. You hold $5,000 in your USD balance. When you convert at a 1.5% margin, the conversion costs $75. You receive approximately $4,925 in local currency. You’ve lost $75 or 1.5%. The savings are $165 per paycheck.

On a $60,000 annual salary paid bi-weekly over 26 paychecks, this saves approximately $4,290 annually. That’s meaningful money that was simply disappearing into banking infrastructure because payment methods weren’t designed for international work.

The regulatory framework that makes this legitimate and safe involves fintech platforms operating under financial services regulations in their jurisdictions. They must maintain licenses, comply with anti-money laundering requirements, implement know-your-customer procedures, and submit to regulatory oversight. Partner banks are fully licensed US institutions, typically FDIC-insured. Your funds are held in segregated accounts at these banks, separated from the platform’s operational funds.

You remain fully responsible for tax compliance in your country of residence. The USD account is a payment reception infrastructure, not a tax avoidance mechanism. All income must be declared and taxed according to your country’s tax laws.

Also read: How US startups pay remote workers outside the US

Grey: Multi-currency accounts for receiving US payroll

Grey provides USD, EUR, and GBP business accounts designed specifically for professionals receiving international payments, including US payroll and contractor income.

When you open a Grey account, you receive a USD account with US routing and account numbers. These details function exactly like traditional US bank accounts for receiving ACH payments from payroll systems.

The setup process involves signing up, providing identification and proof of address from your country, and completing the verification, which typically takes one to three business days. You then receive your USD account details, including routing number, account number, and bank name.

When providing details to your employer, you enter your Grey USD routing and account number in their payroll system. From the company’s perspective, you’re providing standard US banking details. Their payroll platform validates and accepts the routing number without any indication that this is anything other than a normal US bank account. No special international payment setup is required.

On payday, the company’s payroll system initiates an ACH transfer. Payment clears through the US banking system in one to two business days. Grey charges a 0.8% fee, with a minimum charge of $2 and a maximum charge of $10. For example, a $5,000 deposit will cost $10, while a €500 deposit will cost €4

When you need local currency, you convert only the amount required. Exchange rates are shown before you confirm, typically 1-2% over mid-market rate, which is significantly more affordable than traditional bank markups of 3-5%.

You control conversion timing. If USD to local currency rates are unfavourable, you can wait. If rates improve, you can convert more. This control is impossible with traditional wire transfers, where conversion occurs automatically at the rate that applies when the wire arrives.

Withdrawals to your local bank account process in one to three business days, depending on your country. You transfer converted local currency for local expenses like rent, utilities, and purchases that require local currency.

Beyond USD, because Grey provides EUR and GBP accounts with local banking details, if you work for multiple companies or do freelance work alongside your main employment, you can receive a US salary in your USD account, European client payments in your EUR account, and UK client payments in your GBP account, managing all currencies from one platform.

Grey is regulated by FINTRAC in Canada and FinCEN in the US. Your funds are held in segregated accounts at partner banks, which are FDIC-insured for USD balances. You remain responsible for tax compliance in your country of residence. Grey provides the infrastructure and documentation you need, but doesn’t file taxes on your behalf or provide tax advice.

This infrastructure works particularly well for remote workers receiving a US salary as contractors or employees, professionals working for multiple US companies or clients simultaneously, freelancers supplementing full-time income with contract work, and anyone receiving regular USD income who wants to minimise conversion losses and maintain control over currency management.

Global talent, global payment

Geographic location has become irrelevant for many professional roles. Talented developers, designers, marketers, and other professionals work for US companies from anywhere in the world, contribute to US startups meaningfully, and earn competitive salaries.

Payment infrastructure has finally evolved to match this reality. You don’t need to relocate to the US, form US business entities, or navigate expensive EOR services to receive US payroll efficiently. Modern financial infrastructure solves the payment problem cleanly.

With proper setup, a USD account with US banking details, a clear employment classification as an employee or contractor, and tax compliance handled correctly in your country, receiving a US salary outside the US is straightforward. Your location shouldn’t limit your opportunities. The infrastructure now exists to support genuinely global work with seamless payment.

Open your grey account or download the app to receive your US salary without paying wire fees, incurring poor exchange rates, or experiencing payment delays. Start receiving your paycheck the same way US-based employees do, with full control over your money and transparent costs at every step.

Frequently asked questions

Can I receive US payroll without a US bank account?

Yes, but it’s inefficient and expensive. Most US payroll systems use ACH direct deposit, which requires US routing and account numbers. Without these, companies must send international wire transfers, which cost them and you significant fees and poor exchange rates. Modern USD account platforms provide US banking details without requiring US residency.

Do I need to be a US citizen to receive a U.S. salary?

No. US companies can hire and pay non-US citizens working remotely from outside the US. Employment classification and tax implications vary based on your residency status and where you perform work, but citizenship isn’t required.

Will the US company withhold taxes from my salary?

It depends on your classification and tax residency. If you’re a contractor and not a US tax resident, complete Form W-8BEN to prevent 30% withholding. If you’re an employee, tax withholding depends on how the company structures your employment. Consult tax professionals for your specific situation.

What’s the difference between contractor and employee classification?

Contractors are self-employed, invoice for services, handle their own taxes, receive no benefits, and have work flexibility. Employees are on the company’s payroll, receive regular salary, may get benefits, and have employment protections. Classification depends on the nature of the working relationship, not just on contract language.

How long does US payroll take to arrive via ACH?

ACH transfers typically clear within 1-2 business days of payday. Some modern payroll platforms offer same-day ACH. This is substantially faster than international wire transfers, which take 5-10 business days.

What is Form W-8BEN, and why is it important?

Form W-8BEN certifies you’re not a US taxpayer. Without it, US companies must withhold 30% of contractor payments for US taxes. Completing W-8BEN prevents this withholding and confirms you’ll handle taxes in your country of residence.

How much will I lose to currency conversion?

Traditional bank wire transfers typically cost 5-7% total in fees and poor exchange rates. USD accounts with transparent conversion rates cost approximately 1–2% total. On a $60,000 annual salary, this difference saves $3,000–3,600 annually.

Can my employer pay me in my local currency?

Some employers offer this, but it’s usually worse financially. They convert USD to your currency at unfavourable corporate exchange rates, often with a 4–6% markup. Receiving USD and handling conversion yourself using competitive rates is typically better.

What if the company says they can’t pay internationally?

They likely mean their payroll system only supports domestic ACH. Provide USD account details (routing and account number) from a platform like Grey Business. From their perspective, you’re providing standard US banking information that works with existing systems.

‍

Last updated:

October 13, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Should you use a business or personal bank account as a freelancer?

•

•

2 min read

When I started out as a freelancer, I wasn’t sure if I needed a different bank account for my new “business”, if I could even call it that. I mean, my personal account was right there. Did I really need to do anything more complicated?

Most freelancers are not legally required to use a business bank account unless they are registered as a company. However, keeping freelance income separate from personal spending makes tax reporting significantly easier, reduces errors, and looks more professional to clients. A separate account, whether labelled business or not, is strongly advisable from day one.

In this article, I cover the instances where you may require a business account, what the differences are, and what to look for if you decide to keep your freelance income separate.

Do freelancers need a business bank account?

Whether you are legally required to use a business bank account depends on how your freelance practice is structured.

In the United States, for example, sole proprietors have no legal obligation to maintain a separate business bank account. If you freelance under your own name and haven’t formed a separate legal entity, you and your business are the same entity in the eyes of the law. You can receive client payments into your personal account without violating any rules. If you have formed a Limited Liability Company (LLC), the situation changes. For LLC owners, a separate account is necessary to maintain legal protection.

In the United Kingdom, sole traders face the same position as US sole proprietors: no legal requirement for a business account. HMRC does not mandate one. However, if you operate as a limited company in the UK, your company is a separate legal entity from you as an individual. The company’s money is not your money until you pay yourself a salary or dividend, and mixing the two in a personal account creates both a legal problem and a significant accounting headache.

For freelancers who don’t yet know whether they want to operate as a sole trader or through a limited company, our guide on freelancing vs full-time employment covers how different structures affect your taxes and liability in more detail.

The practical summary: if you’re a sole proprietor or sole trader, you don’t legally need a business account. If you’re a limited company or LLC, you do. Either way, keeping freelance income separate from personal spending is strongly advisable, and the next section explains why.

Business account vs personal account: key differences

If you do open a dedicated account for your freelance income, you’ll face a choice between a traditional business bank account and a personal account used exclusively for freelance purposes.

Feature Traditional business account Personal account (dedicated for freelance)
Monthly fees Often £5–£25/month or higher Usually free
Interest on balance Rarely; some charge for holding funds Often available on personal savings
Overdraft facility Sometimes available; business rates apply Usually available; personal rates apply
Debit card type Business Mastercard or Visa Standard personal debit card
Invoicing tools Some accounts include basic invoicing Usually not included
Accountant access Often available (read-only logins) Rarely offered
IRS / HMRC readiness Transactions clearly categorised as business Requires manual separation
Professional appearance Company or trading name on statements Personal name only
Multi-currency support Limited at traditional banks Limited at traditional banks
Account opening Slower; may require registered company docs Faster; personal ID only

‍

Generally, business accounts at traditional banks cost more, offer fewer consumer protections, and provide features (invoicing tools, accountant access) that most freelancers handle through separate software anyway. The primary advantage of a labelled business account is the psychological and practical clarity that comes from a clean separation between business income and personal spending.

A dedicated personal account used exclusively for freelance income offers most practical benefits at a lower cost, except for company-name branding on statements and the formal accountant access features that some clients or accountants prefer.

Why separating your finances matters even if it is not required

When your freelance income and your personal spending share an account, every bank statement becomes a sorting exercise. Which transactions were business expenses? Which were personal? The takeaway you bought on a Tuesday: was that a client meeting or lunch? The software subscription: was that for client work or personal use? Without separation, these questions require memory, receipts, and time, at exactly the moment when tax season is already stressful.

A separate account means every transaction is cleanly categorised. Income that enters the freelance account is business income. Transfers from the freelance account to your personal account are your pay. Expenses charged to the freelance account are business expenses. The logic is automatic rather than reconstructed retrospectively.

Here’s a simple system that works from day one:

  1. Open a dedicated account for freelance income: This is the account you put on every invoice.
  2. Receive client income into the freelance account: Every payment from every client lands here. If you have international clients paying in different currencies, this account should support multi-currency receipts.
  3. Pay yourself a regular transfer to your personal account: On a fixed date each month, transfer a set amount to your personal account as your salary. This is what you live on. It separates your business cash flow from your personal spending clearly.
  4. Hold tax savings in a third account or Pouch: Set aside a percentage of every payment received for tax. A rough starting point for most freelancers is 20 to 30%, depending on your income level and jurisdiction. Treat this as untouchable until your tax bill arrives.

For guidance on structuring your income before this point, our piece on how to set your freelance rates covers how to price your work to make this system financially viable.

What to look for in a bank account for freelancers

Monthly fees
A freelancer starting out doesn’t need a £15 per month business account. Free accounts exist that provide everything necessary. Monthly fees add up, and a new freelancer spending £180 per year on a bank account that is largely empty in the early months is an unnecessary cost.

Multi-currency support
If any of your clients pay in USD, EUR, GBP, or another currency, you need an account that can receive those payments without forcing an immediate conversion at a poor rate. Most traditional bank accounts convert foreign payments upon receipt at the bank's margin, typically 2 to 4% above the mid-market rate. Multi-currency accounts let you hold income in the currency it arrived in and convert when you choose.

A virtual card for online subscriptions
Many freelancers pay for project management tools, design software, cloud storage, AI subscriptions, and domain hosting. A virtual card linked to your freelance account keeps all of these expenses on one statement, separate from personal card spending, and protects your main account details from exposure on subscription platforms.

Fast account opening with no fixed address requirement
Traditional business accounts often require proof of a registered business address, company documents, and a branch visit. For a freelancer, particularly one who works remotely or lives in multiple places, these requirements are a barrier that digital-first accounts don’t impose.

Invoicing integration or export capability
You don’t necessarily need invoicing built into the account, but your account should be able to export transactions in a format your accounting software can read. Clean data export saves significant time at tax season.

Grey covers all of these for international freelancers. Open a Grey account for your freelance income and receive payments in USD, EUR, and GBP from international clients without losing money on forced conversion.

As the scope of your work expands, you can also open a Grey business account, which gives you both USD and USD accounts, access to bulk payouts, and multiple virtual cards.

Frequently asked questions

Can I use my personal account for freelance work?

Yes, in most cases. Sole proprietors in the US and sole traders in the UK are not legally required to use a separate business account. You can receive client payments into a personal account without breaking any rules. The practical problem is that mixing personal and business transactions in one account makes tax reporting significantly harder and increases the risk of errors. A dedicated account, whether officially labelled business or not, is strongly advisable even if it’s not legally required.

Do I need a business account to invoice clients?

No. You can invoice clients and direct them to pay into any account you hold, including a personal account. Invoices are documents you issue, not something that depends on the type of bank account you hold. What your invoice needs is a valid account number and sort code (or routing number and account number for US payments), your name or trading name, and a unique invoice number. The type of account those details belong to is irrelevant to the invoice’s validity.

What is the best bank account for freelancers?

The best account for a freelancer depends on how they work. For freelancers with only domestic clients in a single currency, a free personal account used exclusively for freelance income covers most practical needs. For freelancers with international clients paying in multiple currencies, a multi-currency account that receives USD, EUR, and GBP without forced conversion is more suitable. Grey provides multi-currency accounts with local banking details (US routing numbers, EUR IBANs, UK sort codes) that let international freelancers receive payments as if they were local vendors in each market.

Can I open a business account without a registered company?

At most traditional banks, a business account requires proof of a registered company: a company registration number, a registered address, and in some cases a minimum trading history. As a sole trader or sole proprietor, you typically cannot open a business account at a traditional bank without a formal business registration. Digital-first accounts and some multi-currency platforms generally have lighter requirements and can be opened by individual freelancers without a registered company.

Is it illegal to use a personal account for business?

For sole traders and sole proprietors, no. There is no law in the UK or US that prohibits receiving business income into a personal account for unincorporated freelancers. Some banks include terms in their personal account agreements that technically restrict business use, but this is a contractual matter rather than a legal one and enforcement is rare. For limited company directors in the UK and LLC members in the US, mixing company and personal funds in a personal account creates legal and tax problems that go beyond a contractual breach.

How do I separate my freelance finances?

The simplest system has three parts: one account that receives all client income and nothing else; one account for personal spending that receives a regular transfer from the freelance account as your salary; and a separate savings balance or account for taxes. Open the freelance account before your first invoice goes out. Put that account number on every invoice from day one. Transfer a set amount to your personal account on a fixed date each month. Set aside a percentage of every payment for tax immediately on receipt. That system, applied consistently, solves the vast majority of freelance financial admin problems.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction.

Open a Grey account and keep your freelance income separate from day one, in any currency your clients pay in.

How to send money to Canada as a freelancer

•

•

2 min read

I recently had a reason to send money to Canada.

A close friend of mine in Canada just had a baby, and like most people living far away from the loved ones, I wanted to show up in the way I could. In my case, that meant sending money as a gift.

I’m a freelancer earning in US dollars, so I assumed it would be a simple process. Convert USD to CAD, send the amount I wanted (in my case, CAD 500), done.

But once I started looking into it, I realised it wasn’t so simple. Between different transfer methods, exchange rates, fees, and how money actually moves within Canada, what I thought would take a few minutes turned into actual research.

So if you’re trying to send money to Canada, here’s what I learned and how to do it without losing more than you should.

Why some transfers to Canada cost more than others

If you earn in USD, GBP, or EUR, sending money to Canada involves two key decisions at once: how you convert your money and how you deliver it.

That’s where costs start to build.

For a CAD 500 transfer, the main variables are:

  • Exchange rate markup (often around 2–4%)
  • Transfer fees (flat or percentage-based)
  • Delivery route (local vs international)

Even small differences matter. A 3% markup on the exchange rate already means about CAD 15 lost before any visible fee is applied.

How money actually gets to Canada

When you send money internationally, it moves through different systems before reaching the recipient.

Traditional transfers rely on global banking networks, which can involve multiple intermediaries. Each step can affect speed and cost.

Canada also has a local system, Interac e-Transfer, which allows funds to move directly between bank accounts, often within minutes.

Transfers that connect to local systems tend to be faster and more efficient. Others rely on longer routes that take more time and may involve additional costs.

Top methods to send CAD to Canada (compared)

There are several ways to send money to Canada, but they don’t all work the same way. The differences come down to pricing, exchange rates, and how the money is delivered.

Here’s how the main options compare.

PayPal

PayPal is often the first option freelancers try, especially if they already use it to receive payments.

It’s widely available and quick to set up, but international transfers follow a different cost structure.

When sending money to Canada, PayPal typically applies:

  • A currency conversion markup (around 3–4%)
  • Additional fees depending on how the payment is funded

Part of the cost is built into the exchange rate, which makes the total less visible upfront.

Typical cost (CAD 500):

Around CAD 15–30

How it compares to alternatives:

Compared to platforms like Wise or Remitly, PayPal tends to have higher overall costs for currency conversion.

It’s familiar and easy to use, but not the most cost-efficient option for sending money to Canada.

Wise and similar transfer platforms

Wise is one of the most widely used alternatives for international transfers, particularly because of its pricing transparency and exchange rates that are closer to the market rate.

Other platforms in this category include Remitly, WorldRemit, and OFX.

These services generally follow the same structure:

  • You fund the transfer in USD, GBP, or EUR
  • The platform converts it to CAD
  • The money is delivered to the recipient in Canada

Typical cost (CAD 500):

Around CAD 3–10 depending on provider and speed

What stands out in this category:

  • Clearer pricing compared to PayPal
  • Lower exchange rate markups
  • Faster delivery than traditional bank transfers

What to keep in mind:

  • Fees can vary depending on payment method
  • Some platforms charge more for faster delivery options

It’s a reliable category for international transfers, especially if you want visibility into costs before sending.

Multi-currency platforms for freelancers

Platforms like Payoneer are designed for freelancers and businesses managing income across different currencies.

They allow you to:

  • Receive payments in USD, GBP, or EUR
  • Hold balances without immediate conversion
  • Convert and send funds when needed

Other platforms in this category include Revolut and Skrill.

Typical cost (CAD 500):

Around CAD 5–15 depending on how funds are converted and sent

What stands out in this category:

  • Useful for managing international income
  • Reduces the need for constant currency conversions
  • Combines multiple financial actions in one platform

What to keep in mind:

  • Exchange rates and fees vary depending on usage
  • Sending to Canada may still rely on international transfer routes

This is well-suited for managing earnings, but not always the most efficient option for sending money to Canada.

Grey (built for sending to Canada)

With Grey, the process is structured around people who already operate across currencies and need to move money internationally.

You can:

The main difference is how the funds are delivered:

  • Interac transfer - usually completed within minutes, CAD 3 fee
  • Bank transfer - typically completed within 1 business day, CAD 2.50 fee

Typical cost (CAD 500):

Around CAD 2.50–3 plus exchange rate

What stands out in this category:

  • Flat, predictable fees
  • Access to local Canadian transfer methods
  • Faster delivery compared to international routes

What to keep in mind:

  • Delivery method affects timing (instant vs next business day)

Grey is a strong option for freelancers who want to control both cost and delivery speed when sending money to Canada.

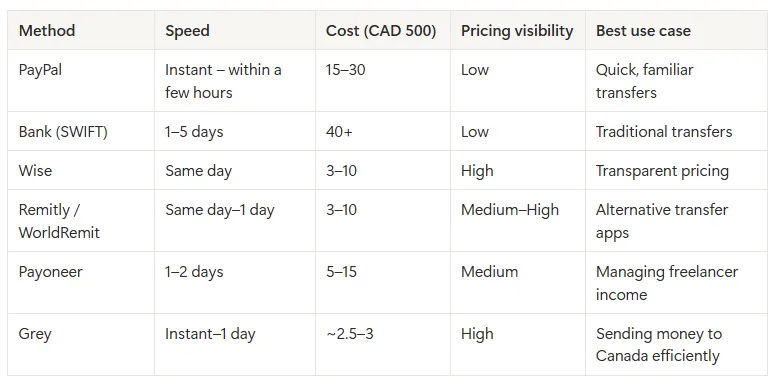
Side-by-side comparison: fees and speed

Table comparing payment methods to send money to Canada

What actually changes the total cost of your transfer

Looking across all methods, three factors consistently determine how much you spend:

  • The exchange rate applied
  • The type of fee (flat vs percentage)
  • The route the money takes into Canada

Reducing unnecessary conversions and avoiding percentage-based fees tends to lower the overall cost.

Why use Grey to send money to Canada?

For freelancers earning in foreign currencies, Grey brings the key elements together in one place.

It allows you to manage multiple currencies, convert when needed, and send money to Canada using delivery methods that prioritise speed or cost depending on your preference.

Grey is also registered with FINTRAC, which means it operates under Canadian financial regulations.

This combination of multi-currency access, clear pricing, and local delivery options makes it particularly relevant for this type of transfer.

How to send money to Canada using Grey

If you’re sending money to Canada through Grey, there are two main ways the funds can be delivered, and each affects speed and cost.

Grey allows you to send CAD to Canada in two ways:

  • Bank transfer: Send directly to any Canadian bank account (personal or business)
  • Interac transfer: Send via Interac, a real-time bank-to-bank system widely used across Canada

The main difference comes down to speed and preference. Interac transfers are typically completed almost instantly, while bank transfers are usually processed within one business day.

What you need before sending

To complete a transfer, you’ll need your recipient’s details. These may vary slightly depending on the method, but generally include:

  • Full name (first and last name)
  • Address
  • Bank details (institution number, transit number, and account number)
  • City and postal code

How the process works

Once your balance is funded, sending money follows a simple flow:

  1. Log in to your account
  2. Select the balance you want to send from (USD, EUR, GBP, or NGN)
  3. Click “Send” and choose your method (bank transfer or Interac)
  4. Add a new recipient or select an existing one
  5. Enter the amount in CAD
  6. Confirm the transfer using your authentication method

After confirmation, the delivery time depends on the method you selected.

This flexibility allows you to prioritise either speed or slightly lower cost depending on the situation.

What I learned trying to send money to Canada

When you break the process down, the differences between transfer methods become easier to evaluate.

For a CAD transfer, most of the variation comes from exchange rates, fee structures, and how the money is delivered in Canada. Once those factors are clear, it becomes easier to choose a method that fits your priorities, whether that is speed, cost, or simplicity.

If you’re already working across currencies and need a reliable way to send money to Canada, opening a free Grey account can help you manage both conversion and transfers in one place.

FAQs about sending money to Canada

What is the best way to send CAD to Canada?

The best option is usually a platform with low exchange rate markup and flat fees, especially one that connects to local Canadian systems like Interac. This helps reduce both conversion costs and transfer fees.

What details do I need to send money to Canada?

To send money to Canada, you’ll usually need the recipient’s full name and either their bank details (institution number, transit number, and account number) or basic contact information if the transfer is sent through local systems like Interac.

How long does it take to send money to Canada?

It depends on the method used:

  • SWIFT transfers: 1–5 business days
  • Online transfer platforms: same day or within 24 hours
  • Interac transfers: often within minutes

Why do I lose money when converting currencies?

Most providers apply a markup to the exchange rate. Even a small difference from the real rate can increase the total cost of your transfer, especially if multiple conversions are involved.

How much does it cost to send CAD 500 to Canada?

Costs vary by provider:

  • PayPal: around CAD 15–30
  • Banks: CAD 40 or more
  • Wise and similar platforms: CAD 3–10
  • Grey:  $2.50 per transfer via bank transfer, and $3 CAD per transfer via Interac.

Is Grey safe to use?

Yes. Grey is registered with FINTRAC, Canada’s financial intelligence agency responsible for monitoring transactions and ensuring compliance with anti-money laundering regulations.

‍

How Nigerian freelancers get international clients

•

•

2 min read

My people have a saying that cooking a delicious pot of soup seems straightforward when you are talking about it. This saying typifies the experience of many talented Nigerians venturing into freelancing. "Oh, you write so well! How about you start writing for international clients and earn a fat USD pay?" People make it seem so easy. But in reality, it requires much more than talent.

No doubt, Nigeria is home to numerous talents, including IT, content marketing, virtual assistance, and graphic design. Even with all this talent, many freelancers struggle to attract international clients who pay well and in foreign currencies. There is no magic bullet for getting international clients. It requires upskilling, strategic positioning, and choosing the right approach to be visible to the right international clients when they are hiring.

Maybe landing an international gig is easier than you think, but you have been using the wrong approach. This article explores the strategic steps that actually work.

Also read: Top financial tips for Nigerian freelancers entering the global market

Position yourself around a specific, marketable skill

The most common positioning mistake Nigerian freelancers make is describing themselves too broadly. "Graphic designer" is a category, not a positioning statement. "Brand identity designer for DTC e-commerce brands" is a positioning statement. The second version tells a specific type of client immediately whether you are relevant to them.

International clients, particularly those hiring remotely for the first time or through platforms, use search and keyword filters to find candidates. A freelancer positioned in a specific niche appears in relevant searches. A generalist competes against everyone.

Choosing a niche doesn't mean you have to do only that work forever. It means you lead with your strongest, most marketable skill and build evidence of results in that specific area before expanding.

No recruiter is looking to fork out money for an average talent who delivers mediocre results. International clients hire for results, and your location will not matter if you can deliver them. Identify the skills in your niche that are most in demand and invest in getting genuinely good at them. Certifications from platforms clients actually recognise (Google, HubSpot, AWS, Meta Blueprint, Coursera) carry more weight than generic online certificates. Personal projects that demonstrate competence in your specific niche, contributed work in public repositories, and case studies with measurable results all build the evidence that converts a profile view into a hire.

LDMAG1

Using global freelance platforms strategically

Most Nigerian freelancers start on platforms like Upwork, Fiverr, and Freelancer. While competition is high, these platforms provide access to clients who are already open to hiring internationally.

Here are a few things to improve your chances as a Nigerian freelancer:

  • Write proposals for the specific job: Clients who post jobs receive many generic responses. A proposal that demonstrates you have read the brief, understood the actual problem, and have relevant experience addressing it converts at a higher rate than one that leads with credentials.
  • The first few reviews matter most. Early on, the goal is not the highest rate. It is a well-reviewed completed project. A strong early track record on Upwork or Fiverr compounds: better reviews produce better visibility, which produces better clients, which produce better rates.
  • You stand a better chance with niche services. Fiverr's search algorithm surfaces gigs based on specificity and relevance. A gig titled "I will write SEO blog posts for SaaS companies" will do better than "I will write blog posts" in searches.

Toptal operates differently from the open marketplaces. It screens applicants through a multi-stage technical and communication assessment before accepting them. The acceptance rate is low, but the client quality and rate ceiling are significantly higher than those of general platforms. For Nigerian developers, designers, and finance professionals who can pass the screening, the application process is worth the effort.

Also read: Top sites to get international remote jobs in Nigeria

Leveraging LinkedIn and reaching out directly

LinkedIn is social media for professionals and decision-makers at international companies: US startup founders, UK marketing agencies, and European media companies. An optimised LinkedIn profile that explains what you do, who you help, and the results you get can attract recruiters and business owners. You can also reach out directly to startups, agencies, and companies that hire remote workers. Sending cold emails or messages takes patience, but it can pay off if you keep trying.

Also read: How to build a global personal brand from Nigeria

Showcasing your work

Evidence is proof of competence. International clients trust evidence since they cannot meet you in person, cannot verify your credentials the way a local employer might

What evidence looks like depends on the discipline:

  • Writers publish articles, either for their own site or as contributed pieces to publications their target clients read.
  • Designers maintain a portfolio on Behance, Dribbble, or a personal site, with case studies that explain the brief, process, and outcome.
  • Developers contribute to open-source projects on GitHub and link to repositories with clean, well-documented code.
  • Marketers document campaign metrics, not just deliverables. "I wrote email campaigns" is a deliverable. "I wrote email campaigns that produced a 32% open rate against a 21% industry average" is a result.

Joining global communities and networks

Remote work thrives on community. Many freelance opportunities are shared informally before they appear on any job board. Remote work Slack groups, Discord servers for specific industries, Twitter or X communities around particular disciplines, and virtual events where international companies participate are all channels where Nigerian freelancers can build relationships that eventually convert to work.

The dynamics in these spaces differ from those on platforms. You are not submitting a proposal. You are contributing to conversations, helping people with questions you are an expert in, and building a reputation within a community of peers and potential clients. When someone in that community has a brief that matches your skills, they think of you before posting it publicly.

Referrals follow the same logic. A past client who had a good experience working with you is a warm introduction to their network that no proposal can replicate. Delivering well and staying in touch with past clients is an underrated client acquisition strategy for freelancers focused entirely on finding new ones.

Set up a payment method that does not cost you clients

A skilled freelancer who is difficult to pay loses clients who would otherwise have hired them. International clients, particularly in the US and UK, default to ACH transfers, Wise, or their own payroll platform. If none of those options delivers easily to you, some clients choose a different freelancer rather than navigate the complexity.

Having a virtual USD account with a real US routing number and account number means US clients can pay you via ACH as a standard domestic transfer, exactly as they pay any other supplier. No SWIFT fees, no correspondent bank deductions, no three-to-five-business-day wait. Sharing these details on your invoice signals to international clients that you have the infrastructure to work with them professionally.

The same applies to UK clients. If you can provide a sort code and account number, they pay via Faster Payments, which is free and settles in seconds from their end. If you can only accept SWIFT wires, they pay £15 to £25 in sender fees, wait 3 to 5 days, and their finance team processes your invoice as an exception rather than a standard payment.

For European clients, a SEPA IBAN allows them to pay in EUR through their normal payment process. Without one, you are asking them to initiate an international wire, which costs them more and takes longer.

Grey provides USD, GBP, and EUR account details from a single account. US clients pay via ACH. UK clients pay via Faster Payments. European clients pay via SEPA. The money lands in your Grey balance in the original currency. You convert to naira when the rate suits you (1% conversion fee, capped at $6) and withdraw to your Nigerian bank for ₦35 per transaction.

You can also link your Grey account to freelancing platforms like Upwork and Fiverr to receive earnings directly.

Note: Exchange rates on Grey are variable and include a margin over the mid-market rate. The rate is always shown before you confirm a conversion. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Conversions are charged at 1%, capped at $6. Withdrawal from a Nigerian bank costs ₦35. For current pricing, visit grey.co/fee-calculator.

Frequently asked questions

Do Nigerian freelancers need to register a business to work with international clients?

Not necessarily. Many Nigerian freelancers work as individuals rather than registered entities and receive payments in their own name without issues. However, some international clients, particularly larger companies, prefer to contract with a registered business for their own compliance reasons. If you plan to work with enterprise clients or at significant monthly volumes, consulting a local accountant about whether formalising your business structure makes sense for your situation is worth the conversation.

How do Nigerian freelancers handle tax on international income?

Income earned from international clients is taxable in Nigeria under the Personal Income Tax Act, regardless of which platform or payment method is used. The Federal Inland Revenue Service requires that foreign-sourced income be declared. Keeping clear records of what each client paid, in what currency, and when simplifies filing. This is general guidance only. Consult a certified tax professional for advice specific to your situation.

What is the biggest mistake Nigerian freelancers make when trying to get international clients?

The most consistent pattern is to apply broadly rather than position specifically. A freelancer who applies to every available job on Upwork with a general profile competes against thousands of others and rarely converts. A freelancer with a specific niche, a clear value proposition, and a portfolio with relevant examples competes against a much smaller pool and wins work at higher rates. Narrowing your positioning can feel counterintuitive when you are trying to increase opportunities, but it consistently delivers better results than staying broad.

Can Nigerian freelancers work directly with US or UK clients without using a marketplace?

Yes, and many experienced Nigerian freelancers eventually move toward direct client relationships as their preferred model. Direct clients pay higher rates because there is no platform taking a percentage, and the relationships tend to be more stable than platform-based work. LinkedIn direct outreach, referrals from existing clients, and a personal website with a clear contact path are the most common routes to direct client relationships. A virtual foreign currency account makes receiving payment from direct clients as simple as sharing your account details on an invoice.

How much can Nigerian freelancers earn from international clients?

It varies widely by skill, experience, and niche. Nigerian developers on Toptal can earn $60 to $120+ per hour. Content writers with SaaS or fintech specialisation typically earn $0.10 to $0.30+ per word from US and UK clients. Virtual assistants with specialised skills (e.g., executive support, project management) earn $15 to $35 per hour. The rate ceiling depends more on positioning and evidence of results than on location. A well-positioned Nigerian freelancer with a strong portfolio commands the same rates as freelancers in other countries.

—

Ready to get paid by international clients? Sign up at grey.co or download the Grey app. Get your USD, GBP, and EUR account details and share them on your next invoice.

‍

Best places remote workers travel to in early 2026

•

•

2 min read

In early 2026, you are likely to see remote workers everywhere. From airport lounges to quiet cafés in unfamiliar cities, people with laptops are moving more freely than ever. Because for many people, work is no longer tied to an office, travel stops being a once-a-year reward, it becomes part of everyday life. You can choose cities that match your pace, your budget, and your curiosity, while still meeting deadlines and staying connected.

For many on-site workers, this freedom still feels like a distant dream. But as a remote worker, you are already living it. You can work from anywhere with strong internet and a comfortable routine. In this guide, you will learn all the top destinations remote workers are travelling to in 2026, and why these places are quickly becoming global hubs for work and life.

Also read: Top skills remote workers need to stay competitive globally

Places remote workers are travelling to in 2026

With work no longer tied to an office, remote workers are exploring cities across the globe. These destinations offer a balance of culture, connectivity, and lifestyle, making both travel and productivity seamless.

Spain

Spain is a favourite because it lets you live well without rushing. Cities like Barcelona, Madrid, and Valencia offer strong internet connections, numerous cafés, and affordable short-term rentals, especially outside peak seasons. You can work mornings, enjoy long lunches, and still explore beaches or historic streets after hours. It feels social, energising, and practical for remote workers who want culture, movement, and balance while travelling.

Mexico

Mexico continues to attract remote workers because it offers a flexible, affordable, and vibrant lifestyle. Places like Mexico City, Playa del Carmen, and Oaxaca offer low daily costs, excellent food, and fast internet. You can live comfortably on a modest budget, meet other nomads easily, and travel between cities without stress. It’s ideal if you want colour, community, and variety without overspending.

Indonesia

Indonesia, especially Bali, feels designed for remote work on the move. Living costs stay low, coworking spaces are everywhere, and short-term rentals are easy to find. Your days can start with focused work and end with beach sunsets or yoga sessions.  Indonesia suits remote workers who want warmth, creativity, and a global community while travelling lightly.

Also read: How to build a personal brand as a successful remote worker

Namibia

Namibia offers vast landscapes and a unique travel experience for digital nomads, with Windhoek, Swakopmund, and Walvis Bay as standout destinations. Earning at least $2,000 per month lets you live comfortably while exploring deserts, wildlife parks, and rugged coastlines. Though internet and co-working options may be less dense than in Europe, the sheer beauty and adventure opportunities make Namibia a memorable remote work destination.

Thailand

Thailand is a classic remote work destination for a reason. Chiang Mai, Bangkok, and Phuket combine affordability with strong infrastructure. Food is cheap, transport is easy, and internet rarely fails. You can stretch your budget while enjoying comfort, safety, and a vibrant lifestyle. For remote workers who want structure without pressure, Thailand offers an easy, enjoyable way to work while exploring Asia.

Kenya

Kenya is becoming increasingly attractive to remote workers seeking something different. Nairobi offers strong internet, growing coworking spaces, and a lively creative scene. Living costs are reasonable, especially for short stays, and weekends can mean safaris or coastal escapes. It’s a place where workdays feel grounded, but life outside your laptop feels expansive and exciting, especially if you enjoy culture and nature.

Portugal

Portugal makes remote work feel calm and intentional. Lisbon, Porto, and Madeira offer reliable internet, walkable cities, and reasonable costs compared to much of Europe. You can settle into a routine quickly, enjoy good food, and still travel easily across the region. It’s perfect for remote workers who want a slower pace, friendly communities, and a sense of ease while moving between cities.

South Africa

South Africa gives remote workers variety in one country. Cape Town stands out with strong internet, affordable short-term living, and incredible scenery. You can work with mountain or ocean views, then unwind outdoors without spending much. While it requires planning, the lifestyle payoff is huge. It suits remote workers who want inspiration, space, and a change of pace while staying productive.

Also read: Best apps for remote workers and global freelancers

Essential items every remote worker should pack before travelling

Before you travel as a remote worker, packing intentionally matters. The right tools keep you productive, comfortable, and stress-free as you move between cities, time zones, and workspaces. Here are essentials you should never leave behind.

  • Light laptop: A lightweight, reliable laptop reduces travel strain and makes it easier to work from cafés, airports, and coworking spaces. Prioritise long battery life, fast performance, and durability so you can stay productive without constantly searching for power outlets.
  • Portable battery pack: A portable battery pack keeps your devices powered during long flights, power outages, or workdays away from your accommodation. It gives you peace of mind, especially in cities where charging points aren’t always accessible or reliable.
  • Noise-cancelling headset: Noise-cancelling headphones help you focus in busy cafés, shared apartments, or airports. They improve call quality, reduce distractions, and create a consistent work environment no matter how noisy your surroundings become.
  • Universal travel adapter: A universal adapter ensures you can plug in anywhere without stress. Different countries use different socket types, and this single tool saves you from hunting for adapters or risking damage to your devices.

Questions to answer before travelling as a remote worker

Before you book flights or pack your bags, asking the right questions helps you avoid stress later. These considerations shape how smoothly you work, live, and earn while travelling as a remote worker.

What is the visa structure like?

Understand whether you need a tourist, digital nomad, or special work visa. Check allowed stay length, renewal options, income requirements, and restrictions on working locally to avoid legal or financial complications.

How long am I staying?

Your length of stay affects housing choices, budgeting, visa rules, and work routines. Short stays suit flexibility, while longer ones require stable accommodation, deeper planning, and realistic expectations around productivity and lifestyle balance.

What is co-working like there?

Research co-working spaces, daily or monthly costs, internet reliability, and the strength of the community. Good coworking environments support focus, networking, and social connection, especially if you work alone most days.

What are healthcare and accommodation costs?

Check access to healthcare, insurance requirements, and typical accommodation prices. Understanding these costs early helps you budget properly and avoid uncomfortable compromises that could affect your health or work performance.

How will I get paid by clients?

Reliable payment access is essential for remote workers. A good solution should convert payments at competitive rates, avoid unnecessary fees, and ensure your income stays predictable no matter where you are in the world. This way, you can focus on your work without worrying about losing money along the way.

LDMAG1

Once you’ve chosen your dream destinations for 2026, the next step is ensuring getting paid is just as seamless. With Grey, you can receive payments in multiple currencies and work easily with clients around the world. This lets you focus on delivering great work and settling into new places, without the stress of payment delays. Sign up or download the Grey app today.

Freelance platforms vs direct clients: which pays better?

•

•

2 min read

For years, as a freelance designer, this question followed me everywhere, from late-night client revisions to quiet moments staring at my bank balance: freelance platforms or direct clients, who really pays better? I tried both. I chased quick wins on platforms, celebrated small payouts, then wondered why I was always busy but rarely ahead. And every time I spoke to another designer, writer, or strategist, they asked the same thing, is this as good as it gets?

This guide is the answer I wish I had earlier. We’ll strip away the hype, talk honestly about money, leverage, and long-term income, and show you which path truly puts more money in your pocket.

Also read: Top platforms to receive freelance payments worldwide

Benefits of using freelance platforms

When you’re just starting out, freelance platforms can feel like a lifesaver. Work is easy to find, clients are already looking, and you can start earning quickly, but is this the smartest way to grow your income?

Easy access to opportunities

Freelance platforms remove the hardest early hurdle, which is finding clients. With a ready-made marketplace, you can pitch immediately without building a huge brand or audience. For freelancers who need income fast, this accessibility creates momentum, confidence, and a quicker path to paid work.

Built-in trust and credibility

Platforms provide reviews, ratings, and escrow systems that reduce client fear. This borrowed trust helps clients hire you faster, even without a strong personal brand. For freelancers, it lowers friction, shortens sales cycles, and makes it easier to close deals with "strangers".

Payment security and structure

Most platforms protect freelancers with milestone payments and dispute systems. This reduces the risk of non-payment and awkward money conversations. You focus more on delivery than chasing invoices, which is especially helpful when you are still learning client management and contracts.

Consistent deal

With enough activity, platforms can provide a steady stream of projects. This consistency helps smooth income gaps and reduces downtime. Even if individual projects pay less, the predictability can offer financial stability during uncertain periods or between larger opportunities.

Also read: Getting paid biweekly vs monthly: Which is better for freelancers?

The advantage of working with direct clients

Working with direct clients can feel like a different world. You generally earn more, have real control over projects, and build relationships that last.

Higher earning potential

Direct clients allow you to price based on value rather than competition. Without platform fees or bidding wars, you can charge more for the same work. Over time, this leads to fewer projects, better margins, and income that reflects your true expertise.

Full ownership

You control pricing, scope, timelines, and communication. There are no platform rules limiting how you work or earn. This autonomy lets you design better processes, protect your energy, and build a freelance business that fits your lifestyle and long-term goals.

Long-term relationships

Direct clients often lead to repeat work, retainers, and referrals. As trust grows, selling becomes easier and projects become smoother. These relationships reduce constant pitching and create compounding income, where one good client can support you for years.

Stronger personal brand

Working directly with clients positions you as a professional partner, not just a service provider. Your reputation grows with every successful project. Over time, your name, not a platform profile, becomes the asset that attracts better clients and opportunities.

This is what freelancers actually earn on platforms

Freelance platforms are often safe. There is always another listing, another client posting a brief, another chance to earn. That steady flow can be comforting, especially when bills are due. But once you spend time there, a pattern appears. Writers are pushed toward $20 per hour, designers hover between $20 and $45, and programmers often sit around $45 to $90. These numbers rarely reflect skill alone. They are shaped by bidding, visibility algorithms, global competition, and the pressure to stay affordable.

What makes it harder is how normal this starts to feel. You stay busy, your calendar is full, yet your income plateaus. Platform fees quietly reduce take-home pay, and raising rates risks losing work. Over time, many freelancers realise they are working more hours, but not earning more money.

What you need to know about getting better pay from direct clients

Working with direct clients offers far more than just higher pay, it changes the entire freelance experience. Unlike platforms, no fees are slicing off your earnings, so what you negotiate is what you take home. These clients also see your work as valuable and strategic rather than a commodity, giving you a higher value perception that naturally justifies better rates. You aren’t competing with dozens of unknown freelancers on price, and your expertise becomes the focus, not how quickly you can bid for a project.

Direct clients also let you invest in your long-term growth. You build your own reputation and client base, which opens doors for referrals, repeat projects, and retainers. With this setup, you gain real negotiation power, controlling rates, scope, and timelines. The result is not just more money, but a sustainable, fulfilling freelance career that rewards both skill and professionalism.

How to position yourself for high-paying direct clients

  • Build a strong portfolio: Showcase your best work, emphasise results, and present it professionally to attract clients who value your expertise.
  • Leverage your network: Reach out to past clients, colleagues, and industry connections; referrals are often the fastest way to secure direct clients.
  • Demonstrate value: Focus on outcomes and problem-solving rather than hourly rates, showing clients why your work is worth paying more.

LDMAG1

Simplify your freelance payments with Grey

When you work with direct clients, you can finally earn what you’re truly worth. By charging for your real value, your freelance income reflects your skill and effort. And because you’re earning more, it’s important to get paid safely and efficiently.

Grey makes it easy to receive payments in multiple currencies, letting you work with clients across countries and get paid in euros, pounds, or dollars. Sign up today or download the Grey app and start getting paid securely.

‍

How Egyptians earn foreign currencies online

•

•

2 min read

Egyptians are increasingly expanding beyond local employment as remote work and digital income opportunities reshape how people earn. Across the country, more professionals, students, and creatives are targeting foreign currency earnings as a way to improve financial stability. With global connectivity improving, it is now common for Egyptians to earn in USD, EUR, or GBP without ever leaving the country. These incomes come from clients in the Gulf, Europe, the United States, and beyond, powered by freelance platforms, remote job boards, and digital marketplaces.

Below are the most practical and widely used ways Egyptians are earning foreign currency online today, along with what it takes to succeed in each path.

Also read: How Egypt is becoming a MENA hub for remote workers

Content creation and monetisation

Content creation has become one of the most visible ways Egyptians earn foreign income. Platforms like YouTube, TikTok and Instagram allow creators to monetise attention through ads, brand partnerships, affiliate marketing, and subscriptions. Egyptian creators span comedy, lifestyle, tech, gaming, and education, proving there is no single path to success. The key is consistency and audience targeting rather than location.

Creators earn mainly in USD through platform monetisation systems and sponsorship deals with international brands. While competition is high, creators who focus on niche topics or global audiences often scale faster. Monetisation also extends beyond ads into memberships, Patreon-style support, and paid collaborations, giving creators multiple income streams rather than relying on a single platform.

Freelancing for international clients

Freelancing remains the most direct and scalable way to earn foreign currency online. Egyptians offer services in software development, graphic design, copywriting, digital marketing, SEO, video editing, data analysis, and customer support. Platforms such as Upwork, Fiverr, and Freelancer connect them to clients worldwide, while LinkedIn and cold outreach help secure higher-paying direct contracts.

Success in freelancing depends on positioning and specialisation. Generalists often struggle, while specialists in high-demand skills like AI development, UI/UX design, and performance marketing command higher rates. Payments are typically received in USD or EUR, giving freelancers access to stronger earning power compared to local currency jobs.

Also read: Opportunities for Egyptian remote workers in the Middle East

Remote jobs with international companies

Remote employment has become one of the most stable ways Egyptians earn foreign income. Instead of project-based work, professionals secure full-time or long-term contracts with foreign companies in tech, finance, customer support, operations, and marketing. These roles provide predictable monthly salaries paid in foreign currency.

Unlike freelancing, remote jobs offer structure, benefits, and long-term stability. Many companies hiring remotely look for English proficiency, technical skills, and time zone flexibility. With the rise of distributed teams, Egyptians can now work for companies in Europe, the US, or the Gulf without relocating.

Online businesses and digital products

Another growing path is building online businesses that sell globally. Egyptians are creating e-commerce stores, SaaS platforms, digital templates, courses, ebooks, and subscription communities. Platforms like Shopify, Amazon, Etsy, and Gumroad make it easier to reach international buyers and collect payments in USD.

Digital products are especially attractive because they scale without physical inventory. A single course, template, or software tool can generate recurring income over time. Many creators also combine content creation with product sales, turning audiences into customers through email lists and social media funnels.

Tutoring, coaching, and consulting

Online tutoring/coaching is another strong income stream. Egyptians teach languages, academic subjects, fitness, business skills, and professional certifications to global students. Platforms like Preply, Italki, and Zoom-based private sessions allow educators to charge hourly rates in foreign currency.

Consulting is the higher-income version of this path. Professionals with experience in marketing, finance, HR, or tech offer advisory services to international startups and small businesses. These services often pay significantly more per hour than traditional jobs in Egypt.

Also read: How to open a UK bank account remotely from Egypt

How to receive money online from Egypt

Payoneer

Payoneer remains one of the most widely used payment platforms among Egyptian freelancers and remote workers. It provides users with virtual receiving accounts in USD, EUR, and GBP, making it easier to receive payments from international clients, freelance marketplaces, and global companies. Funds can then be withdrawn directly into Egyptian bank accounts. Payoneer typically applies combined conversion and withdrawal charges of about 4–4.5%, which can significantly affect larger payouts over time. The platform also charges an annual maintenance fee of $29.95, although this fee is waived for users processing at least $100 in yearly transactions. Its global acceptance remains one of its strongest advantages for freelancers earning internationally.

Grey

Grey is becoming increasingly popular among Egyptians receiving payments from abroad because of its multicurrency flexibility and cleaner fee structure. Users can receive, hold, and manage USD, EUR, or GBP balances within one account before sending to their local accounts when they prefer. This gives users greater control over exchange timing instead of relying on automatic bank conversions. Grey charges a 0.8% deposit fee depending on funding method, while currency conversion costs 1%, capped at $6. Compared to traditional banking routes, this structure makes costs more predictable for freelancers, creators, remote workers, and online business owners receiving regular international payments from clients and global platforms.

Wise

Wise is widely recognised for transparent pricing and exchange rates that closely match the real mid-market rate. Egyptians can receive payments in foreign currencies such as USD and transfer funds directly into local bank accounts with fewer hidden markups than many traditional providers. Wise generally charges around 1.5% plus a small fixed conversion fee depending on the currency route and payout method selected. One of its strongest advantages is clarity, allowing users to see the exact conversion rate and total charges before confirming transactions. This makes Wise particularly attractive to freelancers, consultants, and remote professionals who prioritise predictable international payment costs and fast transfer processing.

PayPal

PayPal remains one of the most globally recognised online payment platforms and is commonly used by freelancers, online sellers, and creators receiving international payments. However, withdrawing funds into Egyptian bank accounts can become expensive due to combined withdrawal and conversion costs. PayPal charges approximately 2% for withdrawals, while USD account conversion fees can add another $1.50, and exchange rate markups can reduce the final amount received. Despite these costs, many people still use PayPal because of its global acceptance and compatibility with international websites, marketplaces, and digital services. It is especially common among beginners entering freelance or online business work for the first time.

How the platforms compare

__wf_reserved_inherit

The cheapest platform is not always the one with the lowest visible fee. Focus on how much finally reaches your Egyptian account after conversion, withdrawal, and hidden FX costs. If you receive payments regularly, even small percentage differences across platforms can save or cost you hundreds of dollars yearly.

Also read: How freelancers in Egypt earn and store foreign currency

How to avoid losing money when receiving payment online in Egypt

Look at what you actually receive

Do not focus on “zero fee” claims when receiving money online in Egypt. Many platforms hide costs inside exchange rates. A service may charge no visible fee but apply a 2%–3% conversion margin, reducing your final USD value more than a small fixed charge. Always compare the actual amount credited to your account from the same payment.

Watch the conversion rate before cashing out

Money received online is often held in USD before conversion into Egyptian pounds. Rates change daily, and timing affects your payout. On a $1,000 payment, even a 1% difference equals $10 lost or gained. If your platform allows holding balances, compare rates before converting instead of accepting automatic conversion.

Use timing to your advantage when converting funds

If your platform allows you to hold funds in USD or other currencies, avoid immediate conversion. Waiting for better rates before withdrawing into Egyptian pounds can improve your final payout. For regular online earners, this simple timing habit reduces long-term losses without needing to predict currency movements.

Frequently asked questions

What is the cheapest way to receive money online in Egypt?

The cheapest option depends on volume and frequency. For larger incoming payments (around $1,000+), platforms that offer low conversion fees and capped charges like Grey can reduce total cost because the effective percentage drops. For smaller or frequent receipts, instant platforms like Wise or PayPal alternatives may feel easier, but exchange rate margins often determine the real cost. Always compare the final USD or EGP amount credited, not just the fee.

How long does it take for international payments to reach Egypt?

Speed depends on the provider and payout method. Fintech platforms like Wise typically settle within minutes to 1 business day. Grey processes payments within 1–2 business days, depending on the route used. Traditional SWIFT bank transfers can take 2–5 business days due to intermediary banks and compliance checks. Cash-based services like Western Union can be instant, but are less common for online earnings.

Can I receive money in USD and convert it later in Egypt?

Yes, but only with certain platforms. Many services convert funds immediately into Egyptian pounds upon receipt, limiting control over timing. Platforms like Grey allow you to hold USD, EUR, or GBP balances before converting. This gives you the flexibility to choose better exchange rates instead of accepting automatic conversion at a weaker rate, improving your final payout.

What documents do I need to receive international payments in Egypt?

For most online payment platforms, basic KYC is required, such as a national ID and proof of address. For higher-value or frequent transactions, providers may request additional information like the source of funds, invoices, or the purpose of payment. This ensures compliance with international AML rules and Egyptian banking regulations governing foreign currency inflows.

Why do two people receiving the same amount get different payouts in Egypt?

Because payment routes differ. One transaction may pass through SWIFT banks with FX spreads and intermediary deductions, while another uses fintech platforms with tighter rates. Timing also matters, exchange rates fluctuate daily. Even when the original amount is identical, the final EGP or USD received can vary based on fees, conversion points, and processing channels.

Also read: Freelance platforms with high payout rates in Egypt

Managing online earnings with Grey

Earning foreign currency is only half the equation. You need to find a way to manage your international earnings without incurring high transfer fees or forced conversions when receiving payments through traditional banks or some digital wallets. Grey is a leading payment platform that helps Egyptians earn globally by offering foreign currency accounts, competitive exchange rates, and easy local withdrawals. You can also get a virtual USD debit card to manage your online payments without stress.

Sign up on Grey or download the app to manage your foreign currency payments and protect your income.

Grey charges fees on deposits, conversions, and withdrawals. Deposits via ACH, SEPA, or FPS incur a 0.8% fee (minimum $2/€2/£2, maximum $10/€10/£10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: ₦35 for NGN, 0.5% for EUR/GBP (minimum €2/£2, maximum €10/£10), and $2 for Egypt. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and the rate before confirming a transaction. Visit grey.co/pricing for current rates.

‍

Arrow (up)

Back to top