Freelancing in Algeria has never been more active. There are developers in Algiers, designers in Oran and digital marketers across the country, all building professional practices with clients in France, Germany, the UK, Canada, and the Gulf. The talent is there, and the demand is real.
Getting paid, however, remains one of the most persistent structural challenges Algerian freelancers face. Algeria has some of the strictest foreign exchange regulations in North Africa. The Banque d’Algérie (Algeria’s Central Bank) tightly controls the flow of foreign currency in and out of the country, making it difficult for people with foreign income to manage their finances efficiently.
Platforms like PayPal and Payoneer are not fully supported in Algeria, making it difficult to receive or withdraw money from abroad. Algerian bank accounts can receive SWIFT wires, but the process is slow and expensive, and it forces an immediate conversion to Algerian dinars (DZD) at the bank’s rate. By the time a European client’s payment arrives in your account, a meaningful portion of it has already disappeared.
This article explains what works for Algerian freelancers receiving international payments in 2026 and how the real options compare in terms of fees and functionality.
Why are international payments harder in Algeria than in most countries?
Before comparing options, the regulatory context is essential. Algeria’s foreign exchange environment is unique in the region and directly shapes which payment platforms are accessible and how they function.
The dinar is non-convertible
The Algerian dinar is a non-convertible currency. It cannot be freely exchanged on international currency markets. This means every international payment arriving in Algeria must be converted to DZD through the official banking system, at the official rate set by the Banque d’Algérie. The parallel market rate has historically been significantly higher than the official rate. Using unofficial exchange channels creates serious legal risk. The 2026 Finance Law significantly tightened enforcement.
The 2026 Finance Law tightened controls further
Algeria’s 2026 Finance Law, which took effect on January 1st, 2026, introduced rigorous new exchange control regulations aimed at dismantling the country’s parallel currency market and strengthening controls on foreign exchange transactions. The law introduced stricter declaration requirements, mandatory bank receipts for currency transactions, and enhanced enforcement mechanisms. For freelancers, this reinforces the importance of receiving income through legitimate, documented channels rather than informal alternatives.
Most international payment platforms don’t fully support Algeria
Platforms like PayPal and Payoneer are not fully supported in Algeria. PayPal operates in a limited capacity, and local withdrawals to Algerian bank accounts are restricted. Payoneer’s local withdrawal functionality for Algeria is limited compared to other African markets. This leaves a meaningful gap between the platforms Algerian freelancers encounter when working with international clients and the platforms that actually enable them to receive and access income in Algeria.
The SWIFT wire problem
For freelancers who do receive payments via SWIFT wire to an Algerian bank, the mechanics are costly. Transactions usually take three to five business days and are automatically converted to DZD. Local Algerian banks charge high fees for international transfers and offer poor exchange rates when converting to dinars. Even when you manage to receive payments, withdrawals can take several days or even weeks to reflect in your account. The client’s bank charges $25 to $50 to send a SWIFT wire, with intermediary banks deducting an additional $10 to $30 along the route. By the time the money arrives, it has been reduced by fees nobody announced and converted at a rate you had no say in.
What works for Algerian freelancers in 2026?
Given the constraints above, the realistic options for Algerian freelancers receiving international income are narrower than in most markets but not as limited as many assume. The key distinction is between platforms that provide foreign currency accounts you control, and platforms that simply route payments through the broken SWIFT chain.
Wise
Wise provides EUR, GBP, and USD accounts with local banking details. The mid-market USD/DZD rate averages approximately DZD 132.40 per dollar over the past 30 days. Wise uses the mid-market rate for all conversions and charges a transparent flat fee, typically 0.42-0.57% of the converted amount. Wise does not support direct DZD withdrawal to Algerian bank accounts. Like Grey, its primary value for Algerian freelancers is as a foreign currency holding account accessible via the Wise card for international spending.
Skrill
Skrill accepts payments from international clients and some freelance platforms, and is easier to use in some regions, including Algeria. Skrill provides a multi-currency digital wallet and a prepaid Mastercard for online spending. Fees are higher than Wise or Grey on conversions, and the platform is better suited to one-off or smaller transactions than to regular professional income at scale. Skrill is regulated by the FCA in the UK.
Grey
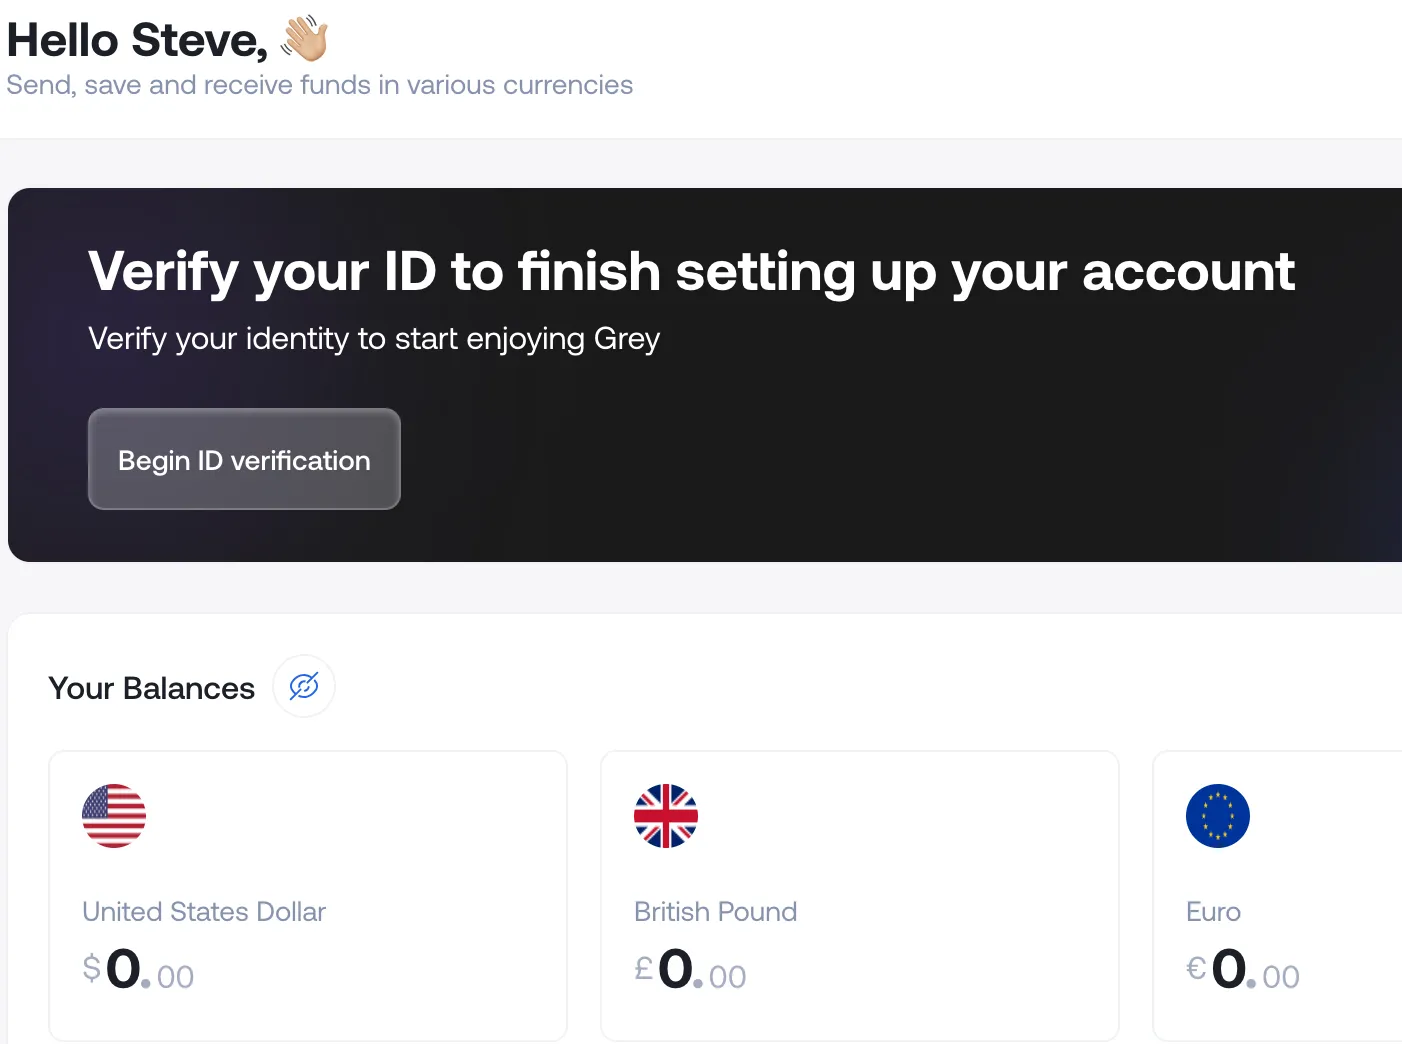
Grey provides Algerian freelancers with EUR and GBP accounts with full local banking details. A EUR account comes with a SEPA IBAN. A GBP account comes with a UK sort code and account number. European clients pay via SEPA or Faster Payments as standard local transfers. The amount arrives in the Grey EUR or GBP balance, with no SWIFT deductions, no correspondent bank fees, and no forced conversion at arrival.
Important clarification: Grey does not currently support USD accounts for users in Algeria.
Deposit fee via SEPA: 0.8%, capped at €10. Conversion fee: 1%, capped at €6. Virtual USD card: $5 one-time creation fee, no monthly fee. Cross-border card transactions (non-USD purchases on a USD card): 2% plus $0.50.
Grey is regulated by FINTRAC and FinCEN. Customer funds are held in segregated accounts at licensed US partner banks.
Direct SWIFT transfer to an Algerian bank
The baseline option. Works without any additional setup. Carries the highest per-transaction cost of any option compared here, forces immediate DZD conversion at the bank’s rate, and offers no foreign currency holding capability. Best for: one-off large payments where no other infrastructure is set up. Worst for: regular monthly invoices where cumulative costs add up significantly.
Comparison table: Digital account options for Algerian freelancers

What Grey provides for Algerian users
Grey offers free GBP and EUR-based accounts for freelancers in Algeria. When a French client pays your invoice via SEPA to your Grey EUR IBAN, the amount arrives in your Grey EUR balance in one to two business days. No SWIFT routing, no correspondent bank deductions, no forced conversion at arrival. You hold the EUR balance and manage it on your terms.
The virtual USD card is the second core benefit. For Algerian freelancers paying for international professional tools, AWS, Google Workspace, Adobe Creative Cloud, ChatGPT Plus, Figma, GitHub, and international advertising platforms, the Grey virtual USD card works without the restrictions that affect Algerian bank cards. Cross-border card transactions on the USD card incur a 2% fee plus a $0.50 fee.
Grey’s fee structure is transparent and capped. Deposit via SEPA: 0.8%, capped at €10. Conversion: 1%, capped at €6. On any payment above €1,250, the combined deposit and conversion fees are capped at €16 regardless of the amount. There is no monthly maintenance fee.
How to get started with Grey in Algeria
- Download the Grey app or visit grey.co
- Sign up with your email address and create a secure password
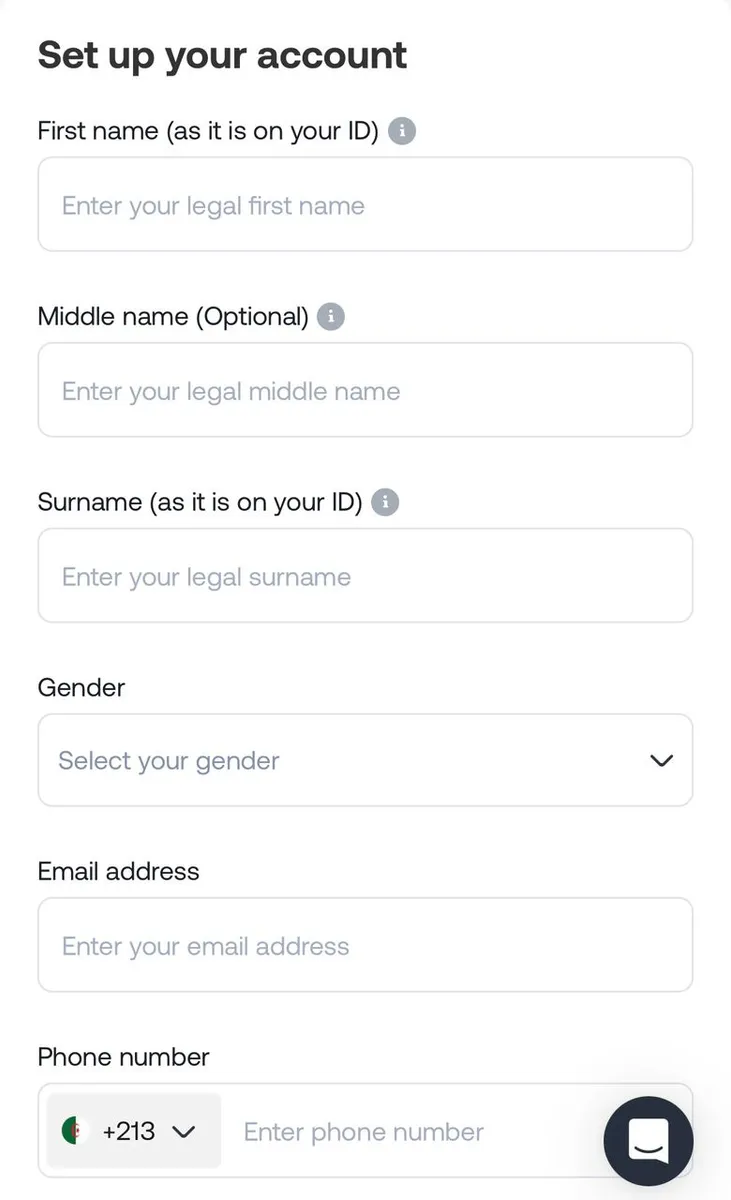
- Complete KYC verification: upload a valid national identity card or passport, proof of address, and a photo
- Verification typically completes within one to three business days after complete documentation is submitted
- Access your EUR account details: your SEPA IBAN is available immediately after verification
- Access your GBP account details: sort code and account number available in the same section
- Update your invoice template with your Grey EUR IBAN for European clients
- Share account details with clients; confirm they can pay via SEPA (EUR) or Faster Payments (GBP)
- Receive payment in one to two business days into your Grey currency balance
- Navigate to the Cards section to set up your virtual USD card for international tool payments
Also read: How freelancers in Algeria can receive payments from the US, UK & EU clients
Algerian freelancers are navigating one of the most restrictive foreign exchange environments in North Africa while trying to build genuinely global careers.
The solution is to use legitimate, regulated infrastructure that works within Algeria’s regulatory reality. An EUR account with a SEPA IBAN eliminates the need for SWIFT wires for European client payments. A virtual USD card solves the problem of international tool payments. Both are available through Grey for Algerian users today.
Open a Grey account today and get started.
Frequently asked questions
Why can’t I use PayPal or Payoneer as an Algerian freelancer?
PayPal and Payoneer are not fully supported in Algeria, making it difficult to receive or withdraw money from abroad.
Does Grey support USD accounts for users in Algeria?
Not currently. Grey provides EUR and GBP accounts for Algerian users but does not currently support USD accounts for this market. Always confirm current product availability at grey.co before applying, as supported features for Algeria are actively developing.
Is it legal for Algerian freelancers to hold income in a foreign account?
Algerian foreign exchange law requires that foreign income from the export of services be repatriated through legitimate banking channels. Algeria’s 2026 Finance Law introduced stricter enforcement of currency controls. Holding income in a regulated foreign account like Grey or Wise and using official conversion channels is the compliant path. Using informal channels or parallel market rates carries serious legal consequences under current Algerian law. Consult a legal or financial professional familiar with Algerian foreign-exchange regulations for advice tailored to your situation.
What is the mid-market EUR/DZD rate and why does it matter?
The mid-market EUR-to-DZD rate is the midpoint between what buyers and sellers are trading at in global currency markets. No provider gives you this rate for free. The difference between mid-market and what your bank or platform credits is their margin. On a €1,000 payment, a 3% bank margin costs DZD 4,664, money that never reaches your account.
What documents do I need for Grey KYC verification in Algeria?
A valid government-issued ID (Algerian national identity card or passport), proof of residential address (a utility bill or official document dated within 90 days), and a photo. The process is entirely digital. No branch visit, no notarised documents, and no minimum balance requirement to open an account.
Grey charges fees on deposits, conversions, and withdrawals. Deposits via SEPA incur a 0.8% fee (minimum €2, maximum €10). Deposits via FPS (GBP) incur a 0.8% fee (minimum £2, maximum £10). Currency conversions are charged at 1%, capped at $6. Withdrawal fees vary by currency: 0.5% for EUR (minimum €2, maximum €10); 0.5% for GBP (minimum £2, maximum £10). Virtual card creation: $5 one-time fee, no monthly fee. Cross-border card transactions (non-USD purchases on a USD card) incur a 2% fee plus $0.50. Exchange rates are variable and include a margin over the mid-market rate. Always review fees and current product availability for Algeria at grey.co/pricing before transacting.