


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency#article","headline":"Living abroad on a student visa: managing rent and bills in foreign currency","description":"Living abroad on a student visa? Learn how to easily manage rent and bills in foreign currency.","inLanguage":"en","url":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency","mainEntityOfPage":{"@id":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency#webpage"},"datePublished":"2025-09-10T08:47:18.476Z","dateModified":"2026-06-15T14:44:13.994Z","author":{"@type":"Person","@id":"https://grey.co/authors/adeolu-titus-adekunle#person","name":"Adeolu Titus Adekunle","url":"https://grey.co/authors/adeolu-titus-adekunle","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/titusadeoluadekunle/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300fbd375175d0e8b022d8_6a300fbc5f75979f410c09b0_living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a300fbd375175d0e8b022d8_6a300fbc5f75979f410c09b0_living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency#webpage","url":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency","name":"Living abroad on a student visa: managing rent and bills in foreign currency","description":"Living abroad on a student visa? Learn how to easily manage rent and bills in foreign currency.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Living abroad on a student visa: managing rent and bills in foreign currency","item":"https://grey.co/blog/living-abroad-on-a-student-visa-managing-rent-and-bills-in-foreign-currency"}]}] </script>

Living abroad on a student visa: managing rent and bills in foreign currency

Adeolu Titus Adekunle

TABLE OF CONTENT

SHARE THIS POST

Studying abroad is exciting. You get to explore new cultures, receive a quality education, and meet new people. But managing your finances as an international student can be tough. Paying rent and bills in a different currency is often stressful. With limited work options, changing exchange rates, and unfamiliar money, you might find yourself struggling to budget.

To navigate these complexities, it’s important to take proactive steps that simplify your financial life. As an international student, you need careful planning and smart strategies. The key steps involve setting up local banking, using cost-effective money transfer services, creating and sticking to a budget, and understanding your tax obligations. This article explores managing rent and bills in foreign currency while on a student visa.

Also read: International student money hacks: Budgeting in multiple currencies

Challenges international students face when managing rent and bills in foreign currency

Navigating international payments can be cumbersome when you are not familiar with your new country’s financial system. Here are some of the common challenges international students may encounter:

  • Exchange rate fluctuations: This is especially worse when your home currency is weaker. Budgeting is tougher because you can create financial plans based on a set exchange rate, but it can fluctuate, meaning you may have to spend more than you originally planned.
  • Bank transfer fees: Traditional banks charge high fees and mark up exchange rates. It is even worse with recurring payments, such as rent.
  • Proof of funds requirements:  Many landlords require several months’ rent in advance, which can be difficult if your funds are still tied up in your home account
  • Budgeting difficulties: It is challenging to budget when you don’t know the cost of your bills. You have to learn everything from scratch – how much the light, water, and phone bills would cost, and how much a month’s groceries are worth. Balancing tuition, daily living, and emergencies in a fluctuating currency environment requires careful financial planning.

Also read: Affordable UK universities with the lowest tuition fees for international students

Managing rent and bills in foreign currency while living abroad on a student visa

Let’s start by listing out what you are likely to spend money on as an international student.

  • Rent
  • Utility bills - light, water, gas, heating
  • Internet and phone bills
  • Transportation
  • Feeding and groceries
  • Miscellaneous fees, including waste disposal, academic resources, local council taxes in some cases.

Recognising these expenses is the first step. Understanding your realities as an international student will help you manage your finances more efficiently. Here are some tips we have for you:

1. Choose an ideal accommodation

It is great to imagine yourself living in a luxurious villa in the heart of town. It is realistic to consider whether you can maintain the rent till you are done with your studies. Housing is often the largest expense for students and can take 30-50% of your budget, but there are ways to manage costs.

  • Shared housing: Sharing a flat or house with others is one of the most effective ways to lower your rent and utility bills.
  • Homestays: Living with a local family can be a more affordable and culturally immersive option, with meals and utilities often included in the monthly fee.
  • Co-living spaces: These designed living spaces offer private bedrooms with shared common areas and often include amenities such as a communal kitchen, laundry facilities, and a gym. While sometimes more costly than traditional shared housing, they can simplify living with an all-inclusive price.
  • University dormitories: On-campus housing can be convenient and often includes all-inclusive packages that cover utilities and sometimes meal plans. While it isn’t always the most affordable option, it offers predictable monthly costs and eliminates commuting expenses.

Also read: Top mistakes international students make with money transfers

2. Find a reliable banking solution

Opening a bank account in your new country is one of the most crucial steps in managing your finances without hassle. A local account makes paying rent and utility bills seamless, and you can start building your credit history. Opening a student account in many local banks offers benefits like low or no monthly fees, no minimum balance requirements, and special perks. You also get a local debit card to avoid high international transaction fees and unfavourable exchange rates that often come with using your home country’s cards.

3. Open a multi-currency account

Digital platforms like Grey, Wise, and Revolut offer multi-currency accounts, allowing you to hold, receive, and spend in different currencies with better exchange rates and lower fees. Your family or sponsors can send money directly in major currencies, which you can convert at favourable rates to pay your rent or bills.

4. Create a realistic budget

Drawing up a practical financial plan is fundamental to managing your rent and bills abroad. Track all expenses by listing all potential expenses, separating them into fixed costs (such as rent, insurance, and visa fees) and variable costs (including groceries, transportation, and entertainment). Apps like Mint or YNAB (You Need a Budget) can help you track your expenses.

5. Plan for exchange rate fluctuations

Fluctuating exchange rates can be a weapon formed against you. Always account for possible fluctuations in your home currency. For example, set aside an extra 5–10% buffer each month to cover unexpected value changes. Monitor real-time exchange rates on Grey and XE, and time your conversions when your home currency is strong. Avoid airport kiosks, hotels, and other unfavourable exchange services.

Also read: How to open a USD or GBP account as an international student in the UK

Grey: Efficient payment solution for international students

Beneath the excitement of moving abroad to pursue higher education is the challenge of financial management. You can focus more on your studies when you have a reliable financial partner to navigate managing your rent and bills in foreign currency. Grey takes the bulk of the burden off you by offering multiple currency accounts, low transaction fees, and competitive exchange rates.

Get started with Grey today for international payments.

‍

Last updated:

October 13, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

UAE Golden Visa: Eligibility and how to apply

•

•

2 min read

The UAE Golden Visa offers long-term residency to investors, entrepreneurs, skilled professionals and individuals with exceptional talent who want to live and build their future in the United Arab Emirates. Depending on the eligibility category, the visa is typically valid for five or ten years and can be renewed.

Unlike standard residency permits, the UAE Golden Visa allows eligible holders to live, work and study in the country without requiring a national sponsor. It also offers greater flexibility for individuals seeking long-term stability, career opportunities and business growth in the UAE.

Eligibility depends on factors such as professional qualifications, salary, investment value, business ownership or recognised achievements. Applicants must meet the specific requirements for their chosen category and provide supporting documents.

The application process generally involves identifying the appropriate eligibility route, gathering the required documents and submitting an application through the relevant UAE government authority or approved channel.

Understanding the eligibility criteria, documentation requirements and application process can help prospective applicants make informed decisions before applying for the UAE Golden Visa.

What is the UAE Golden Visa?

The UAE Golden Visa is a long-term residence permit introduced by the United Arab Emirates to attract investors, entrepreneurs, skilled professionals, scientists and individuals with exceptional talents. It allows eligible foreign nationals to live in the country and pursue career, business or educational opportunities without needing a traditional national sponsor.

The visa is generally issued for five or ten years, depending on the applicant’s eligibility category and the applicable requirements. It is renewable, provided the holder continues to meet the relevant conditions. The validity period offers greater stability for individuals and families planning to establish long-term roots in the UAE.

One of the key benefits of the UAE Golden Visa is self-sponsored residency. Unlike many standard employment-based residence permits, holders do not need an employer or UAE national to sponsor their residency. This provides greater independence when changing jobs, managing businesses or exploring professional opportunities.

For eligible applicants, the UAE Golden Visa offers more than extended residency. It provides flexibility to build a career, invest, study and plan for the future in one of the Middle East’s leading business and lifestyle destinations, subject to applicable laws and visa conditions.

Who Is Eligible for the UAE Golden Visa?

Your eligibility for the UAE Golden Visa depends on your professional achievements, investments, qualifications or exceptional abilities, with specific requirements for each applicant category.

Investors

Investors may qualify through eligible public investments or real estate investments that meet the UAE’s financial and regulatory requirements. Applicants must provide supporting documents to demonstrate that their investments satisfy the applicable criteria.

Entrepreneurs

Entrepreneurs may qualify through business ownership, approved projects or demonstrated entrepreneurial achievements, depending on the relevant eligibility category. Applicants must meet the applicable conditions and provide evidence of their business activities or project qualifications.

Skilled professionals

Skilled professionals may be eligible based on their occupation, educational qualifications, employment status, salary and other requirements. Eligibility depends on the applicant’s professional category and the relevant government regulations.

Students and graduates

Outstanding students and graduates may qualify based on academic performance, examination results and recognised institutional criteria. Specific requirements apply depending on their educational background and the relevant eligibility pathway.

Exceptional talent

Individuals with exceptional abilities in fields such as science, technology, arts, culture and sports may qualify through relevant approvals. Applicants may need to demonstrate recognised achievements, specialised expertise or professional distinction, depending on their field.

Investment routes and thresholds

The UAE Golden Visa offers long-term residency to eligible investors through property ownership and qualifying capital investments. The minimum investment threshold for these routes is generally AED 2 million, subject to the applicable eligibility criteria and documentation requirements.

Property investment

The property investment route requires real estate with a combined value of at least AED 2 million. Multiple properties may be combined to meet the threshold. Certain off-plan and mortgaged properties may qualify, depending on the emirate and applicable conditions.

Capital and public investments

Investors may qualify by investing at least AED 2 million in an eligible UAE investment fund or qualifying business. An approved bank deposit may also meet the requirements, subject to the relevant regulations and supporting documentation.

The 23 Lakh Rumour

Online claims about a UAE Golden Visa costing approximately ₹23 lakh, or AED 100,000, have caused confusion. This amount should not be mistaken for the standard investment threshold for the Golden Visa. Any offer promising residency at a significantly lower cost should be verified through official UAE government channels before payment.

Also read: How UAE freelancers save on currency exchange with Grey

How to apply for the UAE Golden Visa

Step-by-Step application process

1. Check your eligibility and apply

Choose the appropriate Golden Visa category and submit your application or nomination request through the relevant authority. Upload supporting documents, such as your property title deed, investment evidence or salary certificate, as required.

2. Obtain an entry permit if required

If you are applying from outside the UAE, check whether you need an entry permit to complete the residency process. Eligible applicants may use a six-month multiple-entry permit, subject to approval and applicable rules.

3. Complete your medical fitness test

Once in the UAE, complete the required medical fitness examination at an authorised centre. This typically includes a blood test and chest X-ray.

4. Submit your final application

Provide the remaining documents, including your medical fitness results and proof of health insurance, where required. Pay the applicable fees and wait for the authorities to process your application.

5. Complete biometrics and receive your Emirates ID

Attend your biometrics appointment if required. Once your application is approved, your Emirates ID and Golden Residency will be processed.

Where to apply

You can submit your UAE Golden Visa application online through the relevant government portal or get assistance in person at an authorised service centre.

Required documents

Prepare the following documents before applying. Additional requirements depend on your eligibility category.

  • Valid passport: A clear copy of your passport. Six months' validity is commonly recommended.
  • Current visa or status documents: Provide your existing UAE residence visa, visit visa or cancellation documents, as applicable.
  • Medical fitness certificate: Submit the certificate issued by an authorised UAE medical centre when required.
  • Health insurance: Provide valid UAE health insurance or any alternative documentation permitted for your category.
  • Passport photograph: Prepare a recent digital photograph that meets the UAE authorities' specifications, typically with a white background.

Read also: How to open a virtual bank account as a freelancer in the UAE

Money and banking in the UAE

The UAE dirham (AED) is the country’s official currency and is pegged to the US dollar. Understanding money and banking in the UAE helps you manage everyday expenses, receive your salary and plan your finances. Opening a local bank account typically requires identification, residency documents and other information, depending on the bank.

If you manage money across countries, a multi-currency account makes it easier to handle international finances. Grey offers a convenient way to manage multiple currencies, giving you greater flexibility when receiving, holding and moving money across borders.

When you need to send money from the UAE to Nigeria, Grey provides a practical solution for cross-border transfers. Its multicurrency services help simplify international money management, whether you are supporting family, handling personal expenses or managing business payments. With Grey, you can streamline your international finances and make cross-border money transfers more convenient.

Frequently asked questions about the UAE Golden Visa

Who qualifies for the UAE Golden Visa?

Eligible applicants include real estate investors, entrepreneurs, skilled professionals, exceptional talents and outstanding students. Each category has specific financial, academic or professional requirements. Applicants must meet the relevant criteria and provide supporting documents to qualify for long-term UAE residency.

How long is the UAE Golden Visa valid?

The UAE Golden Visa is generally valid for five or ten years, depending on your eligibility category. It can be renewed if you continue to meet the applicable requirements. This long-term residency offers greater stability for professionals, investors and families planning to live in the UAE.

How much do you need to invest?

The minimum investment threshold for qualifying property and capital investment routes is generally AED 2 million. Skilled professionals may qualify through a separate route, subject to salary, qualification and employment requirements, including a monthly salary threshold of AED 30,000 for eligible categories.

Can your family join you?

Yes. Golden Visa holders can sponsor eligible family members, including their spouse and children, subject to applicable requirements. They may also sponsor domestic workers under the relevant rules. This allows families to enjoy greater stability while living together in the UAE.

How do you apply for the UAE Golden Visa?

Applications can be submitted through the relevant government authority, including ICP or GDRFA Dubai, depending on your emirate and category. Prepare your supporting documents, submit the application, complete required medical checks and biometrics, and pay applicable fees.

How can you move money to the UAE?

You can transfer funds to the UAE through international bank transfers or authorised money transfer providers. A local UAE bank account can help manage incoming funds and everyday expenses. Keep supporting documents for larger transfers and comply with applicable banking and anti-money laundering requirements.
Portugal D7 visa: How to apply for the passive income visa

•

•

2 min read

Portugal has become an attractive option for people who want to build a life in Europe without relying on a local job offer. For retirees, property owners and others with regular passive income, the Portugal D7 visa offers a way to apply for residency while continuing to support yourself from income earned outside the country.

The Portugal D7 visa is a residency route for non-EU nationals with a stable passive income, such as pensions, rental income or dividends. You must show income at least equal to the Portuguese minimum wage, plus proof of accommodation.

But having enough income is only one part of the application. You also need to understand the documentation, accommodation requirements, application process and what happens after your visa is approved. If you are considering Portugal as your next home, knowing what the D7 visa requires before you apply can help you avoid delays, prepare the right documents and decide whether this residency route fits your circumstances.

Also read: Portugal transfer limits from US banks: Rules explained

What is the D7 visa?

The Portugal D7 visa is a residency visa for non-EU nationals with stable passive income who want to live in Portugal.

Who Can Apply?

The D7 visa is designed for non-EU nationals who can support themselves through regular passive income. Applicants must demonstrate sufficient financial means and provide accommodation evidence, making it suitable for people planning to relocate rather than simply visit Portugal.

Retirees

Retirees are among the most common D7 applicants because pensions can qualify as passive income. Someone receiving a regular pension from another country may use that income to demonstrate financial stability while moving to Portugal for retirement.

Remote-Income Earners

The D7 can also appeal to people earning a regular income from sources outside Portugal. This may include rental properties, investments or other recurring income streams. However, remote workers whose income comes from active employment or freelancing should check whether another Portuguese visa is more appropriate.

The Passive-Income Requirement

The D7 is based on demonstrating reliable financial resources rather than securing a Portuguese job. Applicants generally need to show recurring income, such as pensions, rental income or dividends, alongside sufficient savings to support their stay and meet the visa requirements.

What are the D7 visa requirements for Portugal?

Understanding the Portugal D7 visa requirements gives you a clearer picture of what to prepare before submitting your application, from proving your finances to securing accommodation and meeting the health and character requirements.

  • Income: Financial stability is central to the D7 application. You need to demonstrate sufficient regular income or financial resources to support your life in Portugal. For 2026, Portugal’s minimum wage is €920 per month, giving a €11,040 annual reference amount for a single applicant.
  • Accommodation: Before applying, arrange a suitable place to live in Portugal. This could be a rental property or a home you own. Your documents should provide evidence of your intended address and show that you have somewhere to live during your stay.
  • Health insurance: Appropriate health insurance is another part of the application. Your policy should cover necessary medical expenses, including urgent treatment and potential repatriation. Once you become a resident, different healthcare requirements may apply depending on your circumstances.
  • Clean record: Your application also needs to demonstrate good character. This usually means providing a criminal record certificate from your country of nationality or the relevant country of residence, with the required authentication. Portuguese authorities will also check your Portuguese criminal record.

For highly qualified professionals moving to Portugal for work, the EU Blue Card route provides another residency option. The route is designed for skilled workers with an eligible employment offer and comes with specific requirements

Also read: Real budgeting tips for nomads living in Lisbon

How to apply for the Portugal D7 visa

If you are applying for the Portugal D7 visa, following the process in the right order helps you prepare your documents, avoid unnecessary delays and know what to expect at each stage.

1. Gather your documents

Start by preparing proof of income or financial resources, accommodation in Portugal, valid health insurance, a criminal record certificate, your passport and any other supporting documents required. You may also need to have certain documents authenticated or translated before submitting your application.

2. Submit your visa application

Next, submit your D7 visa application through the Portuguese consulate or visa application centre responsible for your country of residence. You will provide your documents, complete the application process and attend an appointment or interview if requested.

3. Travel to Portugal

Once your residence visa is approved, you can travel to Portugal within the validity period shown on your visa. This gives you permission to enter Portugal and complete the next stage of your residency application.

4. Apply for your residence permit

After arriving in Portugal, you will attend your appointment with AIMA and submit the documents required for your residence permit. Once your application is approved, you will receive your Portuguese residence card, allowing you to live in Portugal legally.

Residency, taxes and the path to citizenship

Once you have your D7 residence permit, the focus shifts from getting approved to maintaining your residency and planning for the years ahead. That means understanding renewal dates, how much time you need to spend in Portugal, the route to citizenship and how becoming a tax resident could affect your income.

Renewal timeline

Your D7 journey begins with a two-year residence card, followed by a three-year renewal, provided you continue meeting the residency requirements and maintaining your ties to Portugal. You should also plan around the minimum-stay requirement, especially if you work remotely or are registering as self-employed abroad while living in Portugal.

Minimum stay

A D7 residence permit is intended for people who genuinely live in Portugal, so your travel plans matter. You generally need to spend at least six consecutive months or eight non-consecutive months in Portugal each year. If your work takes you abroad frequently, factor these limits into your plans before choosing this residency route.

Citizenship route

After five years of legal residency, D7 holders may become eligible to apply for Portuguese citizenship, subject to the applicable requirements, including an A2-level Portuguese language test. For someone building a long-term life in Portugal, this can turn the D7 from a temporary relocation decision into a potential pathway towards permanent belonging.

How moving to Portugal can affect your tax residency

Getting a D7 residence permit does not automatically mean every tax obligation is the same; your tax residency depends on your circumstances and time spent in Portugal.

Portugal generally considers factors such as spending more than 183 days in the country or having a home there that indicate an intention to maintain it as your habitual residence. Once you become a tax resident, Portuguese IRS rules can apply to your income, including foreign-source income, subject to applicable exemptions, credits and tax treaties.

Proving income and moving money when preparing for life in Portugal

As you prepare your Portugal D7 Visa application, Grey can help you manage the money side of your move. Its multi-currency account lets you hold and manage different currencies, while giving you access to a euro account for receiving, holding and spending euros once you start settling into Portugal.

You will still need to prove that you have stable funds or a regular income to support yourself. Your bank statements and financial documents should clearly show where your money comes from and that you can cover your living costs. Having a euro account can also make everyday payments in Portugal more straightforward.

Whether you are moving money from the UK to Portugal or the US to Portugal, Grey gives you a way to move funds across currencies without having to juggle multiple accounts. You can convert your money to euros when needed and use your euro balance for expenses such as rent, bills and everyday spending.

Frequently asked questions about Portugal D7 visa

What is the D7 visa?

The D7 visa is a Portuguese residence visa for non-EU citizens who have a stable income or sufficient financial resources. It is commonly associated with passive income, including pensions, investments and rental income, and allows eligible applicants to live in Portugal with their families.

How much income do I need?

The minimum income requirement is linked to Portugal’s minimum wage and currently starts at €920 per month for the main applicant. You need additional funds for dependents. You should also be prepared to demonstrate that your income or savings can support your planned life in Portugal.

Can I work on a D7?

Yes. Although your initial D7 application is based on demonstrating sufficient income or financial resources, holding Portuguese residency allows you to work legally in Portugal. This means you can take up employment, become self-employed or develop a business after your residency has been granted.

How long does it take?

The initial D7 visa process can take around 60 days once your application is submitted, although processing times vary by consulate and individual circumstances. After receiving the visa, you travel to Portugal and complete the required steps to obtain your residence permit.

Does it lead to citizenship?

The D7 can provide a route towards Portuguese citizenship. Under the rules applicable to your application, you may become eligible after meeting the required period of legal residence and other conditions, including Portuguese language requirements. Check the current nationality rules before relying on a specific timeline.

How do I move money to Portugal?

You can transfer money internationally into your Portuguese bank account to support your move and everyday expenses. Grey can also help you move money across currencies, including transfers from the UK or US to Portugal, while its multi-currency account gives you access to a euro balance.

EU Blue Card: How to qualify and apply

•

•

2 min read

Moving to Europe for work can feel complicated when you are trying to understand which visa, residence permit and eligibility requirements apply to you. The EU Blue Card offers a route for highly qualified non-EU nationals who have the skills and qualifications European employers need.

To qualify for an EU Blue Card, you generally need a recognised university degree or equivalent professional qualification, a qualifying employment contract or job offer, and a salary that meets the required threshold in the EU country where you plan to work. Requirements can vary between countries, so checking the rules for your destination matters before you apply.

The EU Blue Card combines the right to live and work in a participating EU country with a pathway to greater mobility within the EU. Understanding the eligibility criteria, salary requirements and application process can help you decide whether it is the right route for your move.

Also read: Expat living in Germany: Banking, visas and costs

What is the EU Blue Card?

The EU Blue Card is a work and residence permit for highly qualified non-EU nationals who have a qualifying job offer in a participating European Union country. It is designed to attract skilled professionals from outside the EU by giving them the right to live and work in the country where they are employed, provided they meet the required qualifications, salary and employment conditions.

The “highly qualified” requirement generally means you need higher education qualifications, such as a recognised university degree, or qualifying professional skills recognised under the rules of the country where you apply. You also need a binding job offer or employment contract that meets the required salary threshold. Because these thresholds and application requirements vary by country, your eligibility can depend on where you plan to work.

Most EU countries participate in the EU Blue Card scheme, including Germany, France, the Netherlands, Spain and Italy. Denmark and Ireland do not participate, so you need to consider the specific immigration route available in your chosen destination before applying.

Who qualifies for the EU Blue Card?

You may qualify for the EU Blue Card if you are a highly qualified non-EU national with a qualifying job offer in a participating EU country. You generally need higher professional qualifications, a work contract or binding job offer lasting at least six months, and a salary that meets your destination country’s threshold.

A university degree is the most common way to meet the qualification requirement, typically through a recognised higher education programme of at least three years. However, some countries also recognise relevant professional experience as an alternative, particularly for certain occupations such as IT. Your job must also match the qualifications or professional skills you are using to qualify for the card.

There is no single euro salary figure for the whole EU. Under the current rules, each participating country sets its own threshold, generally between 1 and 1.6 times its average gross annual salary. For example, Germany’s 2026 threshold is €50,700, with a lower €45,934.20 threshold for shortage occupations and certain recent graduates.

The Blue Card in Germany

Germany is the largest issuer of EU Blue Cards in Europe, making it an important destination for highly qualified professionals looking to work in the EU. In 2024, Germany issued 56,252 Blue Cards, representing 72% of all cards issued across the EU.

For 2026, the standard salary threshold in Germany is €50,700 gross per year. A lower threshold of €45,934.20 applies to shortage occupations, provided the Federal Employment Agency approves the employment. Recent graduates can also qualify at the lower threshold, while certain IT specialists may qualify without a university degree if they have the required professional experience.

Germany’s shortage occupations include academic STEM professionals, doctors, veterinarians, dentists, pharmacists, nurses and midwives, teachers and educators, as well as certain managers in manufacturing, logistics, ICT and professional services. This means that when searching for German companies that sponsor work visas, your occupation and the salary offered can directly affect your EU Blue Card eligibility.

How to apply for the EU Blue Card step by step

Once you have confirmed that you qualify, the EU Blue Card application usually follows a straightforward sequence, although the exact process depends on the country where you will work.

  1. Secure a qualifying job: Get a signed employment contract or binding job offer that meets the required salary threshold and runs for at least six months.
  2. Prepare your documents: Gather your valid passport, employment contract, CV, degree certificates, proof of qualifications and health insurance. Your destination country may require foreign documents to be translated, legalised or accompanied by a statement of comparability.
  3. Apply for the required visa: If you need an entry visa, submit your application through the relevant embassy or consulate in your country of residence, including your supporting documents and biometrics.
  4. Enter your destination country: Once your visa is approved, travel to the country where you will work and complete any required address registration or other local formalities.
  5. Apply for your Blue Card: Depending on the country and your circumstances, you may apply before travelling or after arrival. The immigration authority reviews your application and, once approved, issues your biometric EU Blue Card residence permit.

Also read: How to open US, UK and Euro bank accounts in Germany

EU Blue Card benefits and path to permanent residence

The EU Blue Card offers more than permission to work, giving you options for family reunification, mobility across participating EU countries and eventually permanent residence.

Family reunification

Your EU Blue Card can make it easier to bring eligible family members to join you in your destination country. Spouses and dependent children may qualify for residence permits, with specific rights depending on national rules. In many cases, family members can also access employment without needing a separate work permit, helping your household settle more easily.

EU mobility

After legally living in an EU country with an EU Blue Card, you can gain greater mobility within participating EU countries. After 12 months of legal residence in your first member state, you may be able to move to another participating country for highly qualified employment, although you must apply for a new Blue Card under that country’s rules.

Path to permanent residence

The EU Blue Card can also contribute towards long-term residence, although the timeline depends on your circumstances and national rules. Under EU rules, Blue Card holders can generally qualify for EU long-term resident status after five years of continuous legal residence, with periods spent in other participating EU countries potentially counting towards the requirement.

Getting paid in euros and sending money home

Once you start working in Germany, your salary will typically be paid into a German or European bank account in euros. If you regularly move money across borders, opening a euro account can give you a place to receive and hold your earnings before deciding when to convert or transfer them, rather than exchanging everything as soon as you are paid.

Grey can help you manage this money through a multi-currency account where you can receive and hold supported currencies, manage international payments and convert funds when needed. This means your euros can remain available while you decide whether to spend them, convert them or send them elsewhere.

When you are ready to move your money, you can use supported payment routes to send money from Germany or send money to India, depending on the currencies and transfer routes available to you. Whether you are supporting your family, paying expenses abroad or moving your own savings, keeping your money in the currency you receive can give you more control over when you transfer.

Frequently asked questions

What is the EU Blue Card?

The EU Blue Card is a work and residence permit for highly qualified non-EU citizens who want to live and work in participating EU countries. It provides a legal route to employment for professionals who meet the required education, salary and job conditions in their chosen destination.

Who is eligible?

You may qualify as a non-EU professional with a recognised higher education qualification and a qualifying employment contract or binding job offer. In certain cases, particularly for IT professionals, relevant professional experience can replace a traditional degree, depending on the country’s rules.

What salary do I need?

Your salary must meet the threshold set by the country where you will work. Under EU rules, the threshold generally falls between 1.0 and 1.6 times the national average gross annual salary, with lower thresholds potentially applying to shortage occupations and other qualifying groups.

Which countries offer it?

The EU Blue Card is available in 25 EU member states. Denmark and Ireland do not participate in the EU Blue Card scheme, so professionals planning to work there need to explore their separate national work and residence routes instead.

Can my family join me?

Yes. Your eligible family members can generally join you through family reunification procedures, and EU Blue Card rules provide favourable conditions for accompanying family members. Spouses may also have access to employment, although the exact application process and requirements depend on the country where you live.

How do I send money?

Once you are working in Europe, you can send money home through your bank or an international payment platform such as Grey. Grey lets you receive and hold supported currencies in a multi-currency account, manage international payments and choose when to convert your money, giving you greater control over exchange rates and transfers.

Downsides of dual citizenship: What to know

•

•

2 min read

Dual citizenship allows you to be a legal citizen of two countries at the same time. It can give you more freedom to live, work and travel, but it also comes with responsibilities that may affect your finances, legal status and personal choices.

Before applying for a second nationality, it is important to understand the potential downsides of dual citizenship. You may need to file tax returns in both countries, meet military service obligations or follow different laws depending on where you live. You could also face limits on consular assistance while in your other country of citizenship.

In some cases, holding two nationalities can make it difficult to renounce one later. Certain countries also restrict dual citizenship or may withdraw your original nationality when you acquire another. Understanding these rules before making a decision helps you weigh the benefits against the possible risks and avoid unexpected legal or financial complications.

Does dual citizenship mean paying tax twice?

Dual citizenship taxes can be confusing because you may have tax obligations in both countries. Filing two tax returns is common, but paying tax twice on the same income usually is not. Whether you owe taxes in both countries depends on the tax laws of both countries, where you live, where your income comes from, and your citizenship status. Some countries tax residents on worldwide income, while others also tax citizens living abroad.

Tax treaties between countries can help reduce double taxation. These agreements may determine which country has the primary right to tax certain income or allow you to claim relief for taxes paid elsewhere. However, not every country has a tax treaty with every other country, and the rules differ by agreement. A treaty may reduce your tax burden without removing every filing requirement.

If you are a US citizen living abroad, the foreign earned income exclusion may allow you to exclude qualifying foreign-earned income from US federal income tax if you meet specific requirements. It does not automatically eliminate all US tax obligations. Before making decisions, check the rules in both countries and consult a qualified tax professional for guidance on your circumstances.

Which countries do not allow dual citizenship?

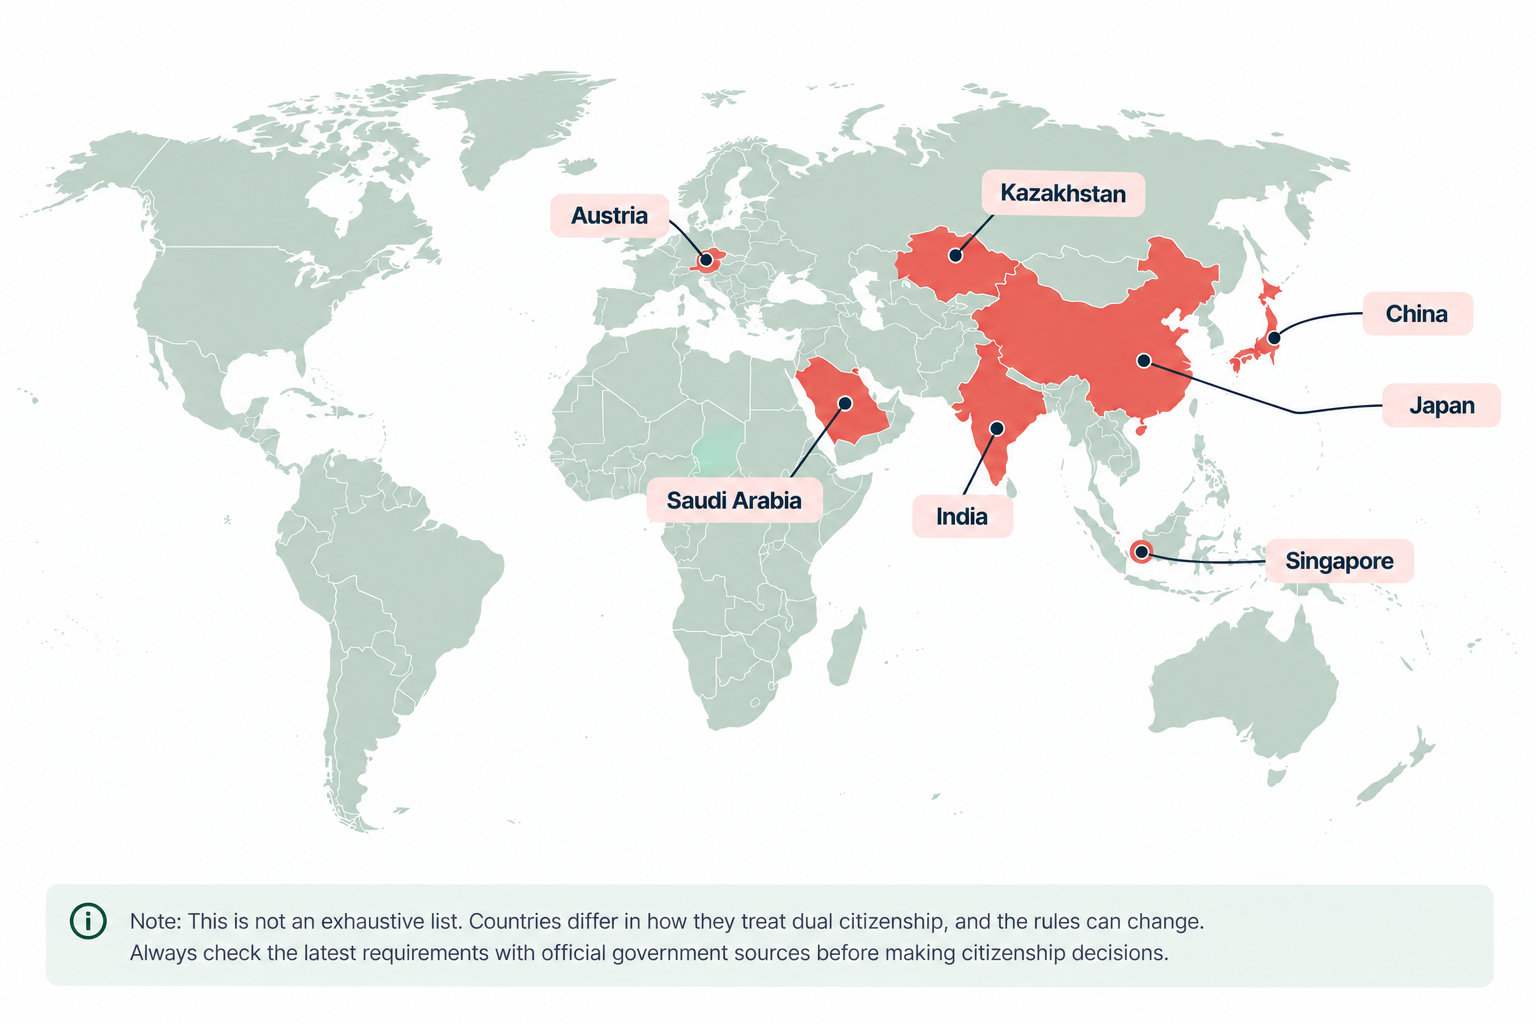
Countries have different rules on dual citizenship, with some prohibiting it altogether or withdrawing nationality when citizens voluntarily acquire another citizenship. Here are some countries that do not allow dual citizenship or impose restrictions on it:

Map marking countries that restrict dual citizenship.

China

China does not recognise dual nationality under its Nationality Law. Chinese citizens who voluntarily settle abroad and acquire foreign nationality may automatically lose Chinese nationality. However, the application of this rule depends on legal circumstances, so verify current requirements before pursuing another citizenship.

India

India does not permit full dual citizenship. Indian citizens who voluntarily acquire another country’s citizenship generally lose Indian citizenship and must surrender their Indian passport. The Overseas Citizen of India (OCI) scheme offers eligible foreign citizens of Indian origin certain benefits, but it is not citizenship.

Japan

Japan generally requires people with multiple nationalities to choose one nationality under its Nationality Act. Those who acquire another nationality voluntarily may lose Japanese nationality. People who hold dual nationality from birth face a nationality-selection requirement, with deadlines and procedures depending on their circumstances.

Singapore

Singapore generally prohibits adult citizens from holding dual citizenship. People who acquire Singapore citizenship may need to renounce their foreign nationality, while Singapore citizens who voluntarily acquire another nationality risk losing Singapore citizenship. Rules for minors differ, so check official requirements before making citizenship decisions.

Saudi Arabia

Saudi Arabia restricts dual nationality. Saudi citizens generally require prior permission to acquire another nationality, and obtaining foreign citizenship without approval may lead to loss of Saudi citizenship under applicable law. The consequences depend on individual circumstances, so confirm current rules with Saudi authorities before applying.

Also read: How to receive international freelance payments in Saudi Arabia

Austria

Austria generally withdraws Austrian citizenship when a citizen voluntarily acquires another nationality, unless they obtain permission to retain Austrian citizenship beforehand. Exceptions may apply in specific circumstances, including certain cases involving citizenship by birth. Always check the legal requirements before pursuing naturalisation in another country.

Kazakhstan

Kazakhstan does not recognise dual citizenship under its nationality laws. Citizens who acquire another nationality are generally required to report it and surrender their Kazakh documents within the applicable period. Failure to comply may result in penalties, so confirm the current reporting and citizenship-loss rules with official authorities.

What consular protection do you lose?

Consular protection is assistance your government provides when you encounter problems abroad, such as arrest, illness, lost travel documents or an emergency. If you hold dual citizenship, you may expect both countries to help you when something goes wrong. However, your ability to receive assistance from one country can be limited when you are inside the other country where you are also a citizen.

For example, if you are a dual citizen of the United States and Nigeria and face arrest while in Nigeria, US officials may be unable to intervene on your behalf. Nigerian authorities may treat you solely as a Nigerian citizen and may not recognise your American nationality. This can limit access to US consular assistance, including visits or representations to local authorities.

These restrictions do not mean you lose all consular protection whenever you travel. Your options depend on the countries involved, their laws and any applicable agreements. Before travelling, check your government’s guidance on dual nationality, local laws and emergency contacts so you understand what support may be available.

Military service and other civic obligations

Dual citizenship can bring legal responsibilities in both countries, even when you live permanently in one. Depending on each country’s laws, you may be required to complete military service, respond to jury duty summons or meet compulsory voting requirements while living abroad.

Military conscription can be particularly important if one of your countries requires eligible citizens to serve in its armed forces. Some countries provide exemptions, deferments or alternative service arrangements, but these depend on factors such as your age, residency and circumstances. Jury duty and voting obligations also vary, and some countries allow citizens overseas to fulfil these duties remotely or qualify for exemptions.

Ignoring a legal obligation may lead to fines, travel restrictions, difficulties renewing documents or other penalties, depending on the country and the specific law. Before acquiring a second nationality, check the civic duties attached to both citizenships. Understanding these requirements can help you avoid unexpected obligations when travelling, relocating or returning to either country.

Also read: D7 visa Portugal: Requirements and how to apply

How hard is it to renounce citizenship?

Renouncing citizenship is not always straightforward. The process depends on the country’s laws, and you may need to apply through an embassy or consulate, attend an appointment, submit original documents and prove that you hold another nationality. Some countries will not allow you to renounce citizenship if doing so would leave you stateless.

Applicant submitting nationality documents at an embassy desk.

Fees and waiting times vary considerably. You may pay an application or administrative fee, cover document certification and translation costs, and wait several months or longer for approval. In some cases, additional checks or incomplete paperwork can delay the process.

Tax obligations can make renunciation more complicated. For example, the United States generally requires certain citizens who renounce their nationality to complete final tax filings, and some may face an expatriation tax if they meet specific criteria. Other countries may impose outstanding tax obligations or departure-related requirements, depending on their laws. Renouncing citizenship does not automatically erase unpaid taxes or other liabilities. Before proceeding, check the official requirements of your country and consider seeking qualified legal or tax advice.

Frequently asked questions

1. Do dual citizens pay tax in both countries?

Yes, dual citizens may have tax obligations in both countries, depending on residency, citizenship and income sources. The United States taxes citizens on worldwide income, even when they live abroad. Tax treaties and foreign tax credits can help reduce double taxation, although filing requirements may still apply.

2. Which countries ban dual citizenship?

Countries such as China, India, Japan and Singapore restrict or generally prohibit dual citizenship under specific circumstances. Saudi Arabia, Austria, Kazakhstan and Indonesia also impose restrictions. However, rules and exceptions vary, so check each country’s current nationality laws before applying for another citizenship.

3. Can you lose your original citizenship automatically?

Yes, some countries may withdraw your original citizenship when you voluntarily acquire another nationality. India generally ends Indian citizenship upon voluntary acquisition of foreign citizenship, while China does not recognise dual nationality and applies specific rules to citizens who settle abroad and acquire foreign citizenship.

4. Can dual citizens be conscripted?

Yes, dual citizens may face military service obligations in either country, depending on its laws. Requirements can depend on age, residency and nationality status. Some countries have exemptions or agreements to prevent double service, so check the rules before travelling or relocating.

5. Which passport should you travel on?

Dual citizens may need to use a particular country’s passport when entering or leaving that country. For example, US citizens generally must use a US passport to enter and leave the United States. Check both countries’ requirements and use the appropriate passport for international travel.

6. Is it hard to give up a second citizenship?

Renouncing citizenship can involve application fees, official documents, interviews and waiting periods. US citizens must generally complete an in-person renunciation appointment and may have tax filing obligations, including potential expatriation tax. Other countries have different procedures, so confirm the requirements before beginning.

Managing money across borders becomes easier when you have the right tools. With Grey, you can send money internationally, including transfers from the US to Canada, while holding and managing multiple currencies. Whether you’re travelling, working remotely or receiving payments from abroad, Grey helps you manage international payments and access your money across borders with greater convenience and flexibility.

Getting paid from Europe and the US while living in India

•

•

2 min read

Earning in euros or dollars while living in India is a common goal for many remote workers, digital nomads, and expats. This often translates to higher earning potential, especially when converted to rupees. Unfortunately, high fees, payment delays, complex paperwork and forced currency conversions often make getting paid from Europe and the US while living in India very challenging.

However, there are various ways to manage international payments seamlessly while working in India. Here is how professionals in India efficiently receive payments from Europe and the US, and keep more of their earnings.

Why getting paid from Europe and the US can be tricky

Most traditional Indian banks are designed for just domestic transactions rather than foreign payments. When payments arrive via international wire, they may pass through multiple intermediary banks and incur extra charges. On top of that, you are forced to convert from EUR or USD to INR immediately the money lands in your accounts, and the rates are often not that great.

Due to processing and the transaction network, it may take a few days for the payment to reach your account. Lack of control over fees, transaction speed, and conversion can be frustrating for many professionals. The uncertainties make financial planning somewhat difficult.

Also read: Why Bengaluru is India’s unofficial capital for remote work and startups

How to get paid from Europe and the US while living in India

Here are the popular options for managing international payments from Europe and the US while living in India

Bank transfers and SWIFT payments

Many European and US companies opt for international bank transfers via SWIFT because it is reliable. This method is widely trusted and works well for both large payments and regular salaries. However, it has drawbacks. Transfers may take several business days, and fees are deducted before the money even gets to your account. You may also need to provide additional documentation to access your earnings, which can be cumbersome.

While SWIFT transfers are acceptable for occasional payments, they are rarely the most cost-effective option for frequent international income.

Using digital payment platforms

Platforms such as PayPal, Payoneer and Skrill are popular because they are easy for foreign clients to use. Payments arrive quickly, and you can withdraw funds to your Indian bank account.

However, convenience comes at a cost. You need to be mindful of platform fees, withdrawal charges, and currency conversion mark-ups that can significantly reduce your earnings. Some users also experience account limitations or compliance reviews that temporarily restrict access to funds. This is why it is best to compare options before choosing a digital payment solution.

  • Payoneer: Ideal if you work through international freelance marketplaces like Upwork or Fiverr. It provides multi-currency accounts and integrates seamlessly with these platforms, making withdrawals straightforward.
  • Razorpay: An India-based payment gateway that allows businesses and some freelancers to accept international card payments in over 130 currencies directly into their Indian bank account.
  • PayPal: Widely used and trusted by global clients. However, while PayPal supports swift transfers, it comes at a higher cost.

Also read: Payment methods Indians often miss: alternatives beyond PayPal and bank transfers

Multi-currency accounts

For many Indians earning from Europe and the US, multi-currency accounts have become the most efficient payment solution. These payment platforms help you open accounts in various currencies such as USD, EUR, and GBP. This way, clients can pay you as if they were making a local transfer within their country.

LDMAG1

You also don’t have to convert your earnings to INR immediately, as a multi-currency account allows you to hold foreign currency and convert when exchange rates are favourable. You can also spend foreign currencies directly to pay for your subscriptions, trips, and online purchases. This level of control protects your income because fees are typically low, transactions are swift, and there are no hidden fees.

  • Grey: Tailored to remote workers in India with international clients. Users can access USD, EUR, and GBP account details for international payments within minutes. Transaction fees are generally low with mid-market exchange rates, and transactions are nearly instant. You can also get a USD debit card for your online payments and automated invoicing to streamline your finances. Grey also integrates seamlessly with global freelancing platforms (like Fiverr and Upwork) and online marketplaces (like Etsy and Amazon), allowing you to access your earnings without delay.
  • Wise: Offers local account details (USD, EUR, GBP) so clients can pay you via a local transfer, avoiding SWIFT fees. Funds are converted at the mid-market exchange rate with low, transparent fees, ensuring you keep more of your earnings.
  • Winvesta: A fintech company providing cross-border payments and multi-currency accounts for Indians. Users can manage payments in USD, EUR, GBP and other foreign currencies.

Also read: How remote workers in India can switch from traditional banks to Grey.

Managing your global income with Grey

Getting paid from Europe and the US while living in India does not have to be stressful. With the right tools, you can maximise your earnings and streamline your finances. Grey provides multi-currency accounts supporting USD, EUR, and GBP. This allows professionals in India to receive payments from Europe and the US easily. You can hold foreign currency, convert at competitive rates, and withdraw to your Indian bank account when it suits you.

Sign up on Grey today or download the app to get started.

‍

What remote workers should plan before relocating

•

•

2 min read

The freedom to work from anywhere as a remote worker is a flex that we don’t talk about enough. Unless you're retiring at 40 with investments to last for a lifetime, remote work is the closest thing to freedom and a premium work-life balance. But as you move around, failing to plan can be a plan to fail.

In this article, we look at the essentials of relocating and the steps you must take before you move. See this as your travel checklist as you pack your bags.

Cross-check the legal status and visa requirements

Moving to a new country to work isn’t always straightforward, and it often requires some paperwork. While many countries don’t expressly permit working remotely on a tourist visa, they don’t enforce compliance. Visa options like digital nomad visas, long-stay visas, and residency permits are often better for remote work. You should understand your visa duration, the rules for visa extensions, work permits, and other local regulations that apply in your destination.

Also read: Visa types every remote worker should know

Review your tax obligations

Often, moving to a different country doesn’t immediately affect your tax obligations. But working abroad can complicate your tax situation over time.  You may be required to pay taxes in your home country, your host country, or both, depending on your residency status, the local tax regulations, and how long you stay. Some countries consider you a tax resident after a certain number of days. Planning ahead helps you avoid double taxation, penalties, or running around at the last-minute to remain compliant. You can consult a tax professional if you are still unclear.

Estimate the living cost and budget appropriately

Relocating can be very expensive,  and you don't want to be shocked by the living costs. Research the average living costs, including rent, food, transportation, groceries, utilities, and fun activities. Check flight prices and book in advance to save money. You can use a spreadsheet for your monthly budget based on your income, and don’t forget to save for rainy days.

Also read: The ultimate guide to budgeting in multiple currencies for digital nomads

Consider internet connectivity and work infrastructure

Don’t choose a destination just based on aesthetics or the abundance of leisure activities. While you should strive for a good off-work lifestyle, you must prioritise a reliable internet and power supply.  Check average internet speeds, mobile data options, and power reliability. Identify coworking spaces or cafés as backups in case your home connection fails.

Relocating may significantly change your working hours. Decide whether you will adapt to your clients’ time zones or adjust your workload. Communicate this change clearly to your clients or employers so they can adjust their expectations accordingly. Clear communication expectations with employers or clients help avoid friction and burnout.

Get health insurance

While no one wishes for it, medical emergencies in an unfamiliar country can be frustrating. It is even worse if you have to pay out of your pocket. Getting travel health insurance before you move might be a smart, protective step to avoid paying too much for health care.

Also read: Getting health insurance and saving in foreign currencies

Set up a reliable payment system

Managing your international payments when you move to another country can be a struggle. It might take some time to open a local bank account, and your old payment system might not be very helpful in your new location. To avoid high transaction fees, exchange rate markups, and delayed payments that can eat into your earnings or affect your cash flow, it is best to plan ahead. Your best bet is to use a digital payment solution that offers multi-currency accounts and supports local withdrawals at the market exchange rate. This ensures you can move around the world, receive your payments, and withdraw locally with ease.

LDMAG1

Managing your finances on the move

Relocating as a remote worker is more than a change of address. It is a shift in how you manage work, your health, and finances. While the prospects can be exciting, it is imperative that you look before you leap. Grey ensures you have a dependable travel partner to help manage your finances anywhere you find yourself. With multi-currency accounts supporting USD, EUR, and GBP, you can easily receive payments from your international clients and withdraw to local accounts at competitive rates. Grey over a transparent fee structure with low charges to ensure you don’t lose a chunk of your money. Grey’s virtual USD debit card lets you make international transactions, giving you more financial freedom.

Get started on Grey’s website or download the mobile app today to manage your finances on the move.

‍

Arrow (up)

Back to top

