



The terms are used all the time interchangeably, but a debit card and a credit card are fundamentally different products.They look identical. They are accepted in the same places. But how they work, what they cost, and what happens if something goes wrong are completely different.
This guide explains the difference clearly, covers virtual versions of both, and helps you understand which card type is right for which situation.
What is a debit card?
A debit card is linked directly to your account balance. When you make a purchase with a debit card, the money is deducted from your account, usually within seconds. You can only spend what you have. If there are no funds in your account, the transaction declines, unless your bank has set up an overdraft.
Most debit cards are issued on Visa or Mastercard networks, which means they are accepted at millions of merchants worldwide. They can be used for in-person purchases, online shopping, and ATM cash withdrawals.
Because you are spending your own money, there is no interest charged on debit card purchases. There is no minimum monthly payment to make. There is no debt to accumulate. The card is a direct window into your own funds.
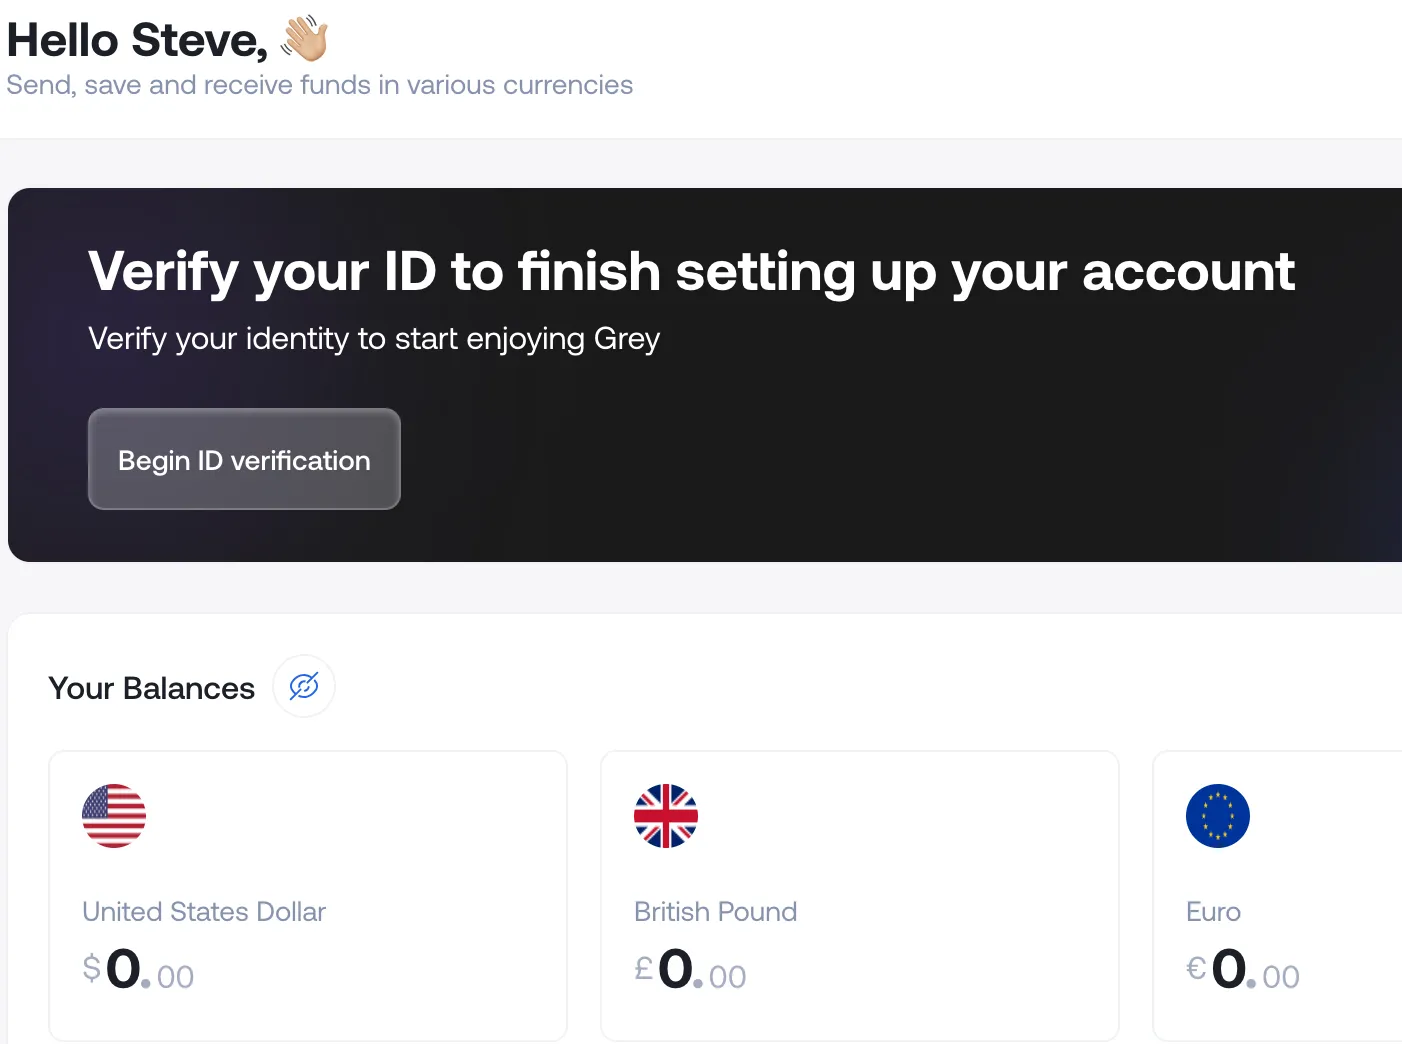
Grey gives you a free virtual debit card the moment you open your account. Spend in multiple currencies, send money home, and manage your finances across borders, all from one place. Get your Grey card
What is a credit card?
A credit card is a borrowing product. When you use a credit card, you are not spending your own money. You are spending money that the card issuer is lending you, up to a credit limit that was agreed when the card was issued. At the end of each billing period, you receive a statement showing what you owe.
If you repay the full balance by the due date, no interest is charged. If you carry any balance over to the next month, interest accrues on the outstanding amount. Credit card interest rates are typically high in the UK. The average credit card interest rate is around 25%, while the average purchase APR is now close to 36%, meaning that carrying a balance for even a short period can become expensive.
Applying for a credit card involves a credit check. The issuer reviews your credit history before deciding whether to approve the application and what limit to offer. A debit card, by contrast, requires only that you have an account with a balance to draw from.
Key differences between a Credit vs Debit Card
| Feature | Debit card | Credit card |
|---|---|---|
| Spending source | Your own account balance | Borrowed funds (credit limit) |
| Interest | None | Yes, if the balance is not repaid in full |
| Credit check required | No (typically) | Yes |
| Spending limit | Your account balance | Set credit limit |
| Debt risk | None | Yes, if not repaid in full each month |
| Purchase protection (UK) | Chargeback (card network) | Section 75 + chargeback |
| Rewards and cashback | Sometimes, varies by provider | Common, varies by card |
| ATM cash withdrawals | Yes, at standard ATM fees | Yes, but interest is charged immediately |
What is a virtual debit card?
A virtual debit card has all the same properties as a physical debit card: it is linked to an account balance, it spends your own money, and it does not charge interest. The only difference is that it has no physical form. Instead of a piece of plastic, you have a card number, expiry date, and CVV stored in an app.
You use a virtual debit card to make online purchases, pay for subscriptions, and transact with merchants that accept card-not-present payments. Because the card exists only digitally, there is nothing to lose or have stolen physically. If you suspect your card details have been compromised, you can delete the virtual card and create a new one immediately, without affecting your underlying account.
Virtual debit cards do not support ATM cash withdrawals. They are designed for online use.
What is a virtual credit card?
A virtual credit card works on the same principle: it is a digital-only version of a credit card, with the same card number, expiry date, and CVV. You use it for online purchases rather than in-person. The key difference from a virtual debit card is that it draws on a credit limit rather than your own funds.
Some people search for 'virtual credit card' when they mean 'virtual debit card'. The two terms are used loosely in everyday language. If you are looking for a card to pay for subscriptions or online purchases without needing to borrow money or undergo a credit check, a virtual debit card is almost certainly what you want.
Grey issues a virtual debit card, not a credit card. There is no credit check, no credit limit, and no interest. You fund the card from your own USD, EUR, or GBP balance and spend from that balance.
When should you use a debit card?
A debit card is the right choice when you want to spend within your means without any risk of accumulating debt or paying interest. It is the straightforward option for:
- Day-to-day online spending and recurring subscriptions
- International platform payments when you hold a balance in that currency
- Situations where you do not qualify for a credit card or prefer not to apply for one
- Anyone managing a tight budget who needs to stay within a fixed amount
- Payments on platforms that may not accept credit cards
For people in Nigeria, India, or other markets with local card spending limits on international platforms, a virtual USD-denominated debit card is often the practical solution. It processes in USD, which avoids both the local currency spending caps and the friction that comes with converting at the point of payment.
When might a credit card be useful?
Credit cards are not inherently bad products. Managed well, they offer protections and benefits that debit cards do not. In the UK, purchases between GBP 100 and GBP 30,000 made on a credit card are covered by Section 75 of the Consumer Credit Act. This means the card issuer shares legal responsibility for the purchase if the merchant fails to deliver or goes into administration. Debit card purchases are protected by chargeback protection through the card network, which is useful but less powerful than Section 75.
Credit cards can also offer cashback, travel rewards, and other perks that effectively reduce the cost of spending, provided you repay the balance in full every month.
The risks are real, though. Carrying a balance even briefly at typical credit card interest rates is expensive. Cash withdrawals on credit cards attract immediate interest charges, often at a higher rate than purchases. For anyone who cannot reliably repay the full balance each month, a debit card is the safer choice.
Grey's virtual debit card: spend your own money, globally
Grey issues a virtual Visa debit card funded from your USD, EUR, or GBP balance. It is a debit card. There is no credit check, no borrowing, and no interest.
Who it is built for
Grey's virtual card exists because a specific problem kept coming up for the borderless generation: naira cards have monthly spending limits on international platforms, and not everyone has access to a USD bank account. Grey's virtual USD card solves that directly. You hold a USD balance in your Grey account, fund the card from that balance, and pay on international platforms in dollars.
The card is particularly used by:
- Nigerians in Nigeria and the UK who pay for USD-denominated services and subscriptions
- NRIs and Indian professionals who want a USD or EUR card for international platform payments
- Freelancers and remote workers receiving income in USD who want to spend from that balance without converting to local currency first
- Anyone in a Grey-supported market who needs a Visa card for online payments
Fee structure
- Card creation: $4 one-time card creation fee, plus a minimum $1 funding amount deducted from your USD balance. You need at least $5 in your USD wallet to create a card.
- Monthly fee: None.
- Interest: None. You spend your own balance.
- FX fee: 2% + $0.50, applied only when a merchant processes in a non-USD currency. Not charged on USD-denominated platforms.
What it does not do
The Grey virtual card does not support ATM withdrawals. It is not a physical card. It is not a credit card and does not offer a credit limit or Section 75 protection. For full UK banking services, you need a separate UK current account in addition to your Grey account.
Debit vs credit card: which is right for you?
| Your situation | Better choice |
|---|---|
| You want to spend without risk of debt or interest | Debit card |
| You do not want a credit check | Debit card |
| You want to pay for international subscriptions in USD without local currency limits | Virtual debit card (e.g. Grey USD card) |
| You want maximum purchase protection on large items (GBP 100+) | Credit card (repaid in full) |
| You want cashback or travel rewards and will repay in full monthly | Credit card |
| You have difficulty repaying a full balance each month | Debit card. Avoid credit card interest. |
Frequently asked questions
Is a virtual card a debit or credit card?
A virtual card can be either. A virtual debit card draws from your account balance and does not charge interest. A virtual credit card draws from a credit limit and charges interest if the balance is not repaid. Many people who search for 'virtual credit card' are looking for a virtual debit card: a digital card for online payments that does not require borrowing. Grey issues a virtual debit card.
Can I use a virtual debit card instead of a credit card?
Yes, for most online payments. Virtual debit cards are accepted anywhere that accepts card-not-present payments, which includes the vast majority of online merchants, subscription platforms, and digital services. The one area where a credit card offers something a debit card cannot is Section 75 protection in the UK on purchases over GBP 100.
Does Grey do a credit check?
No. Grey's virtual card is a debit card. You are spending your own USD, EUR, or GBP balance. There is no borrowing, no credit limit, and no credit check required to create a card.
What is the difference between a virtual card and a prepaid card?
A prepaid card is loaded with a fixed sum of money in advance and cannot be topped up beyond that amount unless the product is designed for reloading. A virtual card is typically part of a full account that you can fund, spend from, and top up as needed. Grey's virtual card is linked to your Grey wallet, which you can fund on an ongoing basis. The distinction matters less in practice than the underlying fee structure and currency support.
Can I use a debit card for online purchases?
Yes. Debit cards are accepted for online purchases wherever Visa or Mastercard payments are accepted. A virtual debit card works identically to a physical one for online transactions, because the merchant never sees or handles a physical card, either way.
Does Grey issue credit cards?
No. Grey issues virtual debit cards only. All Grey cards draw from your account balance in USD, EUR, or GBP. There is no credit product, no credit limit, and no interest charged on card spending.
Debit card security: what to do if something goes wrong
One of the most common concerns about debit cards, whether virtual or physical, is what to do if your details are stolen or a fraudulent transaction appears on your account. Here is a practical guide to what to do and how the protection system works.
Chargeback: the debit card protection mechanism
When you pay with a debit card, and something goes wrong, such as a merchant failing to deliver a product or a fraudulent transaction, you can file a chargeback claim through your card network (Visa or Mastercard). A chargeback is a request to reverse the transaction. Your bank disputes the payment on your behalf with the merchant's bank.
Chargeback is available on all debit cards. It is not a legal right in the same way that Section 75 protection is for credit cards, but it is a card network rule that merchants are bound by. Most legitimate chargeback claims are resolved within 30 to 45 days.
To make a chargeback claim, contact your card provider as soon as you identify the problem. Provide evidence of the issue: order confirmation, delivery failure, or merchant communication. Keep records of everything.
For Grey virtual card transactions
If you identify a transaction on your Grey virtual card that you did not authorise or that a merchant did not deliver as promised, contact Grey's support team through the app. Grey will guide you through the dispute process. For unauthorised transactions, delete the virtual card immediately to prevent further charges and notify Grey support.
Because Grey's card is virtual, the most effective fraud prevention is to delete a compromised card immediately and create a new one. This is faster and more effective than waiting for a physical card to be reissued, which is the process with traditional banks.
Do some debit cards offer rewards?
The assumption that debit cards never offer rewards is not quite accurate in 2026. Several UK debit cards offer cashback or points on spending, though the rewards are generally less generous than those of credit card programs.
- Chase UK: 1% cashback on UK grocery, transport, and fuel spending. No overseas cashback, but zero overseas fees.
- Starling: No cashback program on the standard account.
- Monzo: Monzo's paid plans (Plus and Premium) offer cashback at selected retailers, but the free plan does not.
- Grey: No cashback program on the virtual card. Grey's value is in the multi-currency account, transfer corridors, and fee-free USD spending on USD platforms.
If cashback on everyday UK spending is a priority, Chase is currently the strongest zero-fee option among UK debit cards, with 1% back on specific categories and no overseas fees, making it a practical dual-purpose card.
The difference between debit, credit, prepaid, and charge cards
Debit and credit are the two main categories, but there are two others worth understanding, particularly for anyone managing money across multiple currencies.
Prepaid cards
A prepaid card is loaded with a specific amount of money before use. It is not linked to a bank account or credit line. You can only spend what has been loaded onto it. Once the balance runs out, the card declines. Prepaid cards are useful for budgeting and for people without a bank account, but they are less flexible than a debit card linked to a full account.
Grey's virtual card is sometimes described as a prepaid card, but it is more accurately described as a debit card linked to your Grey USD wallet. Unlike a traditional prepaid card, you can top up your Grey wallet at any time, convert from other currencies, and receive incoming transfers. The card functions as a debit card that draws from a live balance, not a fixed, pre-loaded amount.
Charge cards
A charge card works like a credit card in that you spend now and pay later, but unlike a credit card, the full balance must be repaid at the end of every billing period. There is no option to carry a balance and pay interest. Charge cards are less common in the UK consumer market and are mostly used in corporate contexts. American Express historically issued charge cards alongside credit cards.
Who should consider a virtual debit card as their primary card?
A virtual debit card works well as a primary payment card for certain people and as a supplementary card for others. Here is how to think about it.
A virtual debit card works as a primary card if:
- Most of your spending is online, with subscriptions, platforms, and digital services making up the majority of your card use
- You live in a market where naira or other local currency cards have spending limitations on international platforms
- You receive income in USD, EUR, or GBP and want to spend directly from that balance without converting
- You prefer debit to credit: no debt, no interest, no credit check
A virtual debit card works better as a supplementary card if:
- You regularly make in-person purchases where a physical card is required
- You need ATM access for cash withdrawals
- You want Section 75 purchase protection on large items
- You travel frequently and need a card accepted at card-only payment terminals in different countries
Grey's virtual card is designed to sit alongside a physical debit card, not replace it. For the borderless generation managing money across currencies and platforms, it handles the international digital spending that a standard UK debit card handles poorly or expensively. For in-person everyday UK spending, your UK bank account's physical card remains the right tool.