Moving to a new country can be physically and mentally stressful for expats, so setting up a bank account might not be an immediate priority. Most people focus their preparation on visas, housing, and shipping belongings. It is when they arrive that they realise they should have planned for how to manage their finances ahead.
Before relocating, set up banking that works from day one. Host-country banks often need a local address or residency permit you will not have on arrival, so open a multi-currency account you can use immediately, keep your home account open for existing commitments, and send a small test transfer before moving larger sums.
This article guides expats looking to open a bank account before relocation and provides a checklist of what you need to sort out before moving to a new country.
What to sort out before you move
Use this checklist to make sure your banking is squared away before your relocation.
- Open an account you can use without a local address: Many banks require proof of a local address before opening an account. This can be difficult when you have just arrived and don’t have permanent accommodation yet. You can open a multi-currency account remotely, fund it, and use it to manage your finances while you sort out opening a local bank account.
- Check which currencies you need: Consider which currency you will be paid in and which you will spend. For example, if you are moving from the US to Europe, you may still receive income in USD while paying for your local expenses in EUR. An account that lets you hold multiple currencies can help you manage both currencies without converting everything immediately.
- Get a card before you travel: Having a virtual or physical card before you move gives you another way to pay for things when you arrive. It also means you are not relying entirely on your home bank card, which may charge foreign transaction fees or occasionally block transactions it considers unusual.
- Test by sending a small amount: Before moving your relocation savings or a large amount to the new account, send a small amount first. This way, you can be sure your setup works. Check that it reaches the right account, arrives in the expected currency, and that there were no hidden fees. Once you confirm everything works, you can safely transfer larger amounts.
- Notify your existing bank about your relocation: If you plan to keep using your current account, let your bank know that you will be moving abroad. Many banks flag transactions initiated from another country as potential fraud if you don’t tell them you are moving to that country.
For more tips on managing your money after relocating, see our guide on managing international payments while living abroad.
Why non-residents get blocked
Opening a local bank account can be difficult when you have just moved because you may not have the documents the bank requires. Here are some reasons you might struggle with opening an account abroad:
- Proof of local address: Banks may ask for a tenancy agreement, utility bill or other document showing your name and address. If you are staying in a hotel or temporary accommodation, you may not have these documents yet, and won’t be able to open an account.
- Residency or visa documents: Some banks require proof of your legal residency status before opening an account. Meanwhile, getting the right document might take weeks in some countries.
- Proof of income or employment: Some banks may ask for an employment contract, payslip or other evidence of income. This can be difficult if you are still job hunting or you haven’t received your first local payslip.
- No local credit history: In some countries, banks consider your credit history when opening certain account types. And since you are new to the country, you might find it difficult to open such accounts because you don’t financial history in that country.
Requirements for opening a bank account vary by country and bank, but many of the challenges are similar. A multi-currency account available remotely helps bridge the gap by giving you access to different currencies without requiring a local bank account in each country.
Should you keep your home bank account?
You do not necessarily need to close your home bank account when you move abroad. Whether you should keep it depends on your circumstances.
Reasons to keep your home account open
Keeping your existing account can make it easier to:
- Pay existing direct debits and subscriptions
- Continue mortgage, insurance or loan payments
- Support family members at home
- Access your existing credit cards and other financial products
- Have a backup account if you return home
- Receive payments that still come from your home country
Reasons to close it
Closing the account might make sense if:
- You are paying fees for an account you no longer use
- You no longer need any services connected to the account
- Managing accounts in multiple countries creates unnecessary complexity
- Your new country of residence has reporting or tax rules that make keeping certain accounts less convenient
Before closing your old account, check whether you still have any payments, subscriptions or other financial commitments linked to it.
Consider the tax implications
Moving abroad can also change your tax situation. For example, US citizens and residents who move abroad trigger an FBAR filing requirement if their total foreign account balance is more than $10,000 at any time during the calendar year. Also, once you own certain financial assets abroad, FATCA requires you to file Form 8938 with your regular tax return. can also create additional reporting requirements.
Confirm the tax implications for moving to another country. You can try finding out on your own or involving a tax professional before closing or keeping accounts.
For many people, keeping their existing account open initially is the safer option. You can close it later once you are settled and have confirmed that you no longer need it. Reopening an account from abroad can be much harder than simply keeping an existing one open.
Multi-currency accounts for expats
A multi-currency account can make managing money easier when you move abroad, especially if your income and expenses are in different currencies.
You can keep USD, EUR, and GBP in the same account instead of converting every payment to a single currency. You can then convert your money when you need to and see the exchange rate before you confirm the transaction.
If you move abroad for work but have not opened a local bank account yet, local receiving details in currencies such as USD, EUR, or GBP can give your employer or clients a way to pay you without waiting for your local bank account to be set up.
A virtual card linked to your multi-currency account lets you spend directly in the local currency without the foreign transaction fees that a home-country card typically applies to every purchase abroad.
Using a multicurrency account allows you to hold multiple currencies and convert whenever you like. Seeing the exchange rate and fees upfront also makes it easier to understand the true cost.
See our comparison of the best multi-currency accounts for non-residents.
Setting up before relocation with Grey
One advantage of a multi-currency account is that you can set it up before you leave your home country. This gives you access to your money while you are still sorting out local banking and accommodation.
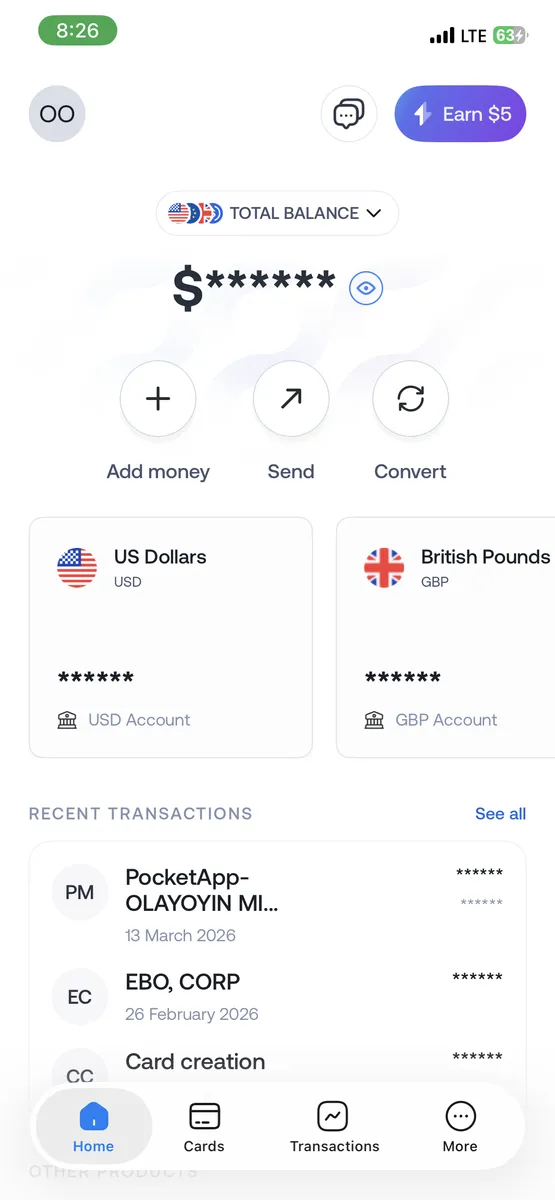
With Grey, users can get USD, EUR, and GBP accounts with the relevant details. You also get a virtual card linked to your balances, which you can use to spend abroad from your first day.
Getting started on Grey requires verifying your identity with a valid ID, proof of your current address, and a photo. And within minutes, you can access USD, EUR, and GBP accounts that are ready to receive and send money.
Once you open a local bank account after moving, you can continue using Grey alongside it to hold and manage other currencies.
Open a Grey account before you move, and you can manage your finances from your first day abroad.
Frequently asked questions
Can I open an account before moving?
Yes. While a traditional bank in your destination country may require a local address or residency documents, some multi-currency accounts can be opened remotely before you move. This gives you a way to manage your money while you settle in.
Do I need a local address?
For a traditional local bank account in most destination countries, yes, almost universally. This is the single most common barrier new arrivals face, since proving a local address typically requires documentation (a tenancy agreement, utility bill) that you cannot produce until you have already secured housing, which itself sometimes requires a local bank account. A multi-currency account opened before you move avoids this specific barrier entirely, since it does not require a local address in your destination country.
Should I keep my home account open?
For many expats, keeping your home account open at least initially makes sense. It allows you to continue paying bills and other commitments, and provides a backup if your relocation plans change. However, check for account fees and any tax or reporting requirements that may apply after you become a tax resident elsewhere.
What account works from day one?
A multi-currency account that you can open remotely before travelling can give you access to banking services while you are still settling in. Grey offers eligible users USD, EUR and GBP accounts that can be set up online, along with a virtual card for spending.