<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada#article","headline":"Do’s and don’ts for international students in Canada","description":"Are you nervous about studying in Canada? Our guide offers essential tips for international students on academics, finances, safety, and more!","inLanguage":"en","url":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada","mainEntityOfPage":{"@id":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada#webpage"},"datePublished":"2024-07-24T08:10:07.057Z","dateModified":"2026-06-15T19:26:49.645Z","author":{"@type":"Person","@id":"https://grey.co/authors/baraka-mafole#person","name":"Baraka Mafole","url":"https://grey.co/authors/baraka-mafole"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301a693b28501995d4b5c2_6a301a68409f3f2f72f8e296_dos-and-donts-for-international-students-in-canada__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301a693b28501995d4b5c2_6a301a68409f3f2f72f8e296_dos-and-donts-for-international-students-in-canada__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada#webpage","url":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada","name":"Do’s and don’ts for international students in Canada","description":"Are you nervous about studying in Canada? Our guide offers essential tips for international students on academics, finances, safety, and more!","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Do’s and don’ts for international students in Canada","item":"https://grey.co/blog/dos-and-donts-for-international-students-in-canada"}]}] </script>

Do’s and don’ts for international students in Canada

Baraka Mafole

TABLE OF CONTENT

SHARE THIS POST

Canada has become a popular destination among international students for their higher learning studies. International students prefer to study in Canada for various reasons, such as global exposure, the credibility of a Canadian degree, and the safety and quality of life.

If you’re among the many people who consider Canada your next study destination, we’ve compiled a list of do’s and don’ts during your stay as an international student.

Do’s for international students in Canada

Do part-time jobs

Canada has laws and regulations which allow international students to work part-time while studying. Canada also allows international students to work up to 20 hrs per week in different job positions during regular school terms in the semester.

Canada has a broad job market that offers many opportunities for international students. Some popular part-time jobs for international students in Canada include barista, teaching assistant, snow removal, and tour guide.

Also read:  Jobs you can get as an international student in the UK

Part-time jobs will assist you as an international student to cover your living expenses.

Be socially active

Being socially active will help you explore new opportunities and connect with people as an international student in Canada. Going out and meeting new people should be on your bucket list, as this will expand your knowledge about the country and help you build lifelong relationships with people.

Some of the best ways to be socially active in Canada include participating in social and educational activities such as parties, football matches and inter-university competitions.

Understanding academic expectations

The Canadian education system differs from other countries; therefore, international students need to familiarise themselves with it. Canada’s education system strongly emphasises academic integrity and participation.

As an international student, you should adhere to the following.

  • Attend classes regularly
  • Engage in class discussions
  • Communicate proactively with Professors and lecturers

Also, plagiarism and academic dishonesty aren’t tolerated; therefore, as an international student, you shouldn’t engage in these practices.

Be friendly and kind to others

If you were to learn only one skill that will benefit you in your academic and professional life, then that skill would be being kind and friendly to others. Being kind will foster trust and help you build meaningful connections with your classmates, professionals, and the community.

Apart from that, being nice attracts reciprocity. When you help others, they will likely support you when you need it.

Open a UK, EU and US bank account with Grey

Don’ts for international students in Canada

Don’t be careless, and stay alert

Vision of Humanity ranks Canada as the 11th safest country due to its low criminal rates compared to other countries. However, this doesn’t guarantee your safety 24/7; therefore, as an international student, you should take some safety measures to protect yourself, such as:

  • Registering with the consulate to safeguard your possessions
  • Reporting to the police in case of crime or emergency

Don’t forget your documents.

Some documents are essential for international students and should be filled out and carefully handled. Don’t leave these documents in your home country; have them in your pocket and bag.

Some of the essential documents international students should have are

  • Student ID card: These are issued by your educational institution.
  • Social insurance number {SIN}: They are required if you plan to work in Canada.
  • Health insurance cards can be obtained from a provincial government or private company.
  • Work permit: this is important if you have a co-op or internship as a part of your program.
  • Travel documents: Keep your passport and study permit valid and updated.

Don’t underestimate the power of budgeting

Managing finances through budgeting is crucial for international students studying in Canada.

Budgeting will enable you to:

  • Understand how your money is spent and how to allocate it wisely.
  • Adjust to the cost of living in Canada
  • Ensure you have funds for emergencies
  • Reduce financial stress and allow you to concentrate on your studies.

Also read: A Gen-Z’s guide to financial independence

Some practical budgeting examples include shopping at discount stores, exploring free or low-cost entertainment activities, and considering shared accommodations to reduce rent costs.

Wrapping up

If you plan to relocate to Canada for academic purposes, these dos and don’ts will help you navigate your new journey there. Don’t forget to open a Grey account, as it will help you pay school fees, make purchases, and receive money from your loved ones.

Open a UK, EU and US bank account with Grey

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

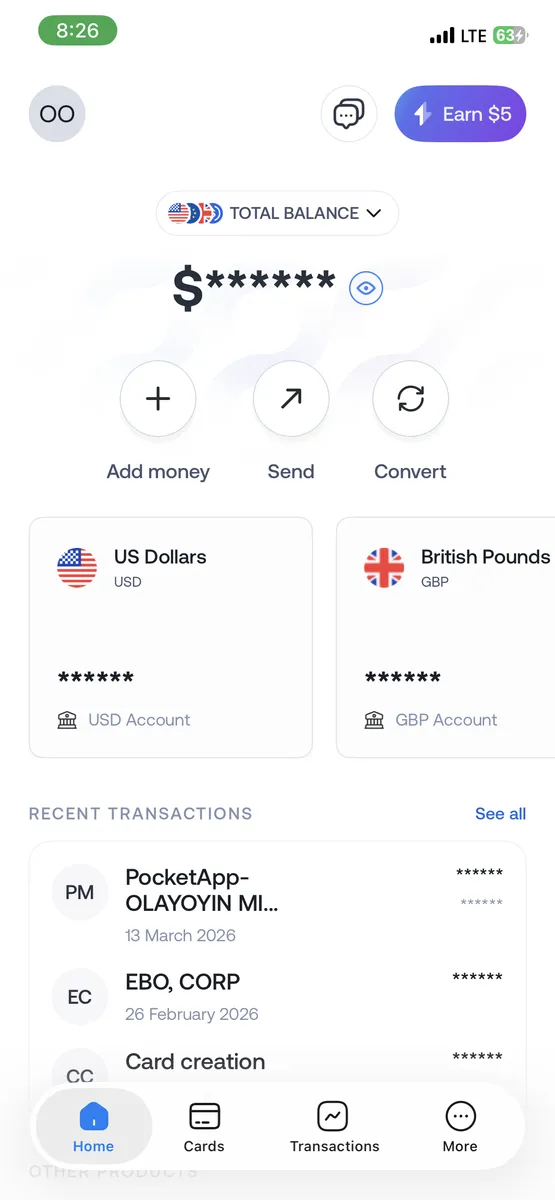
  1. Log in to your Grey account.
    ‍
  2. Click “Send”.
Send Canadian dollars with Grey

‍

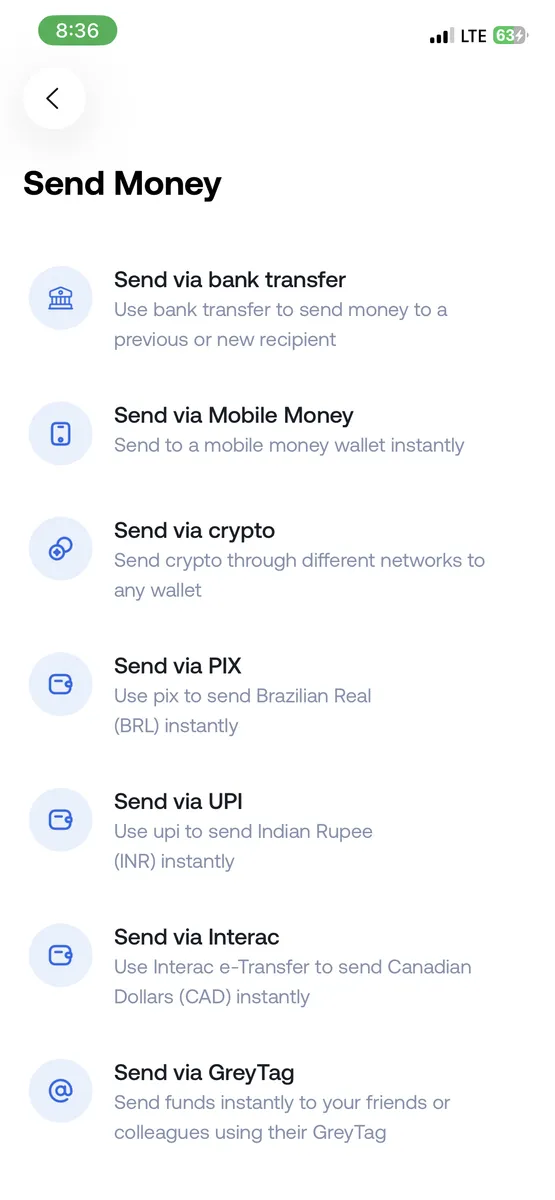
2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

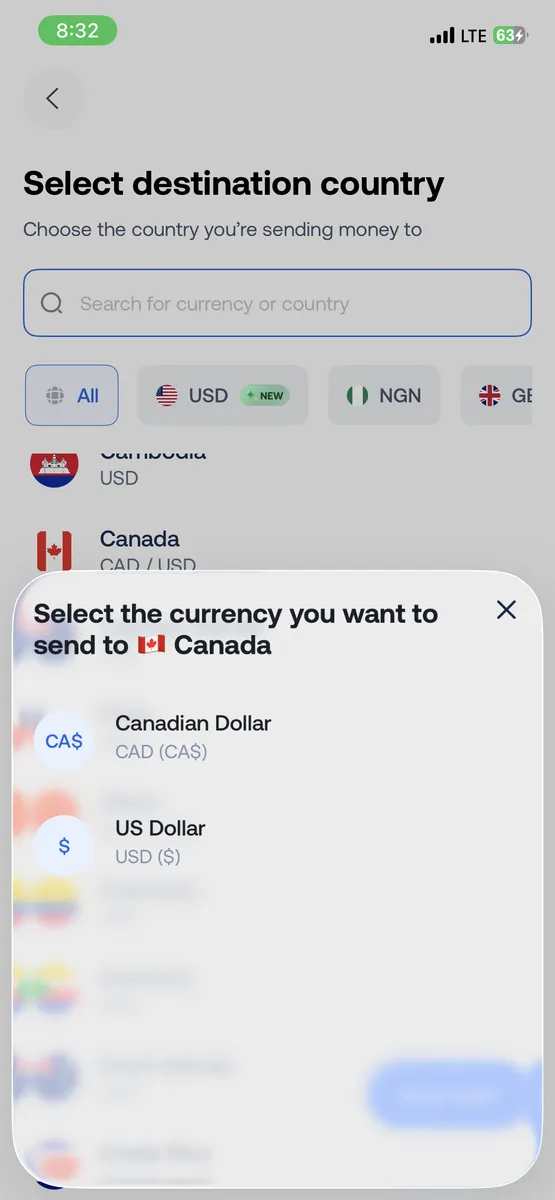
3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

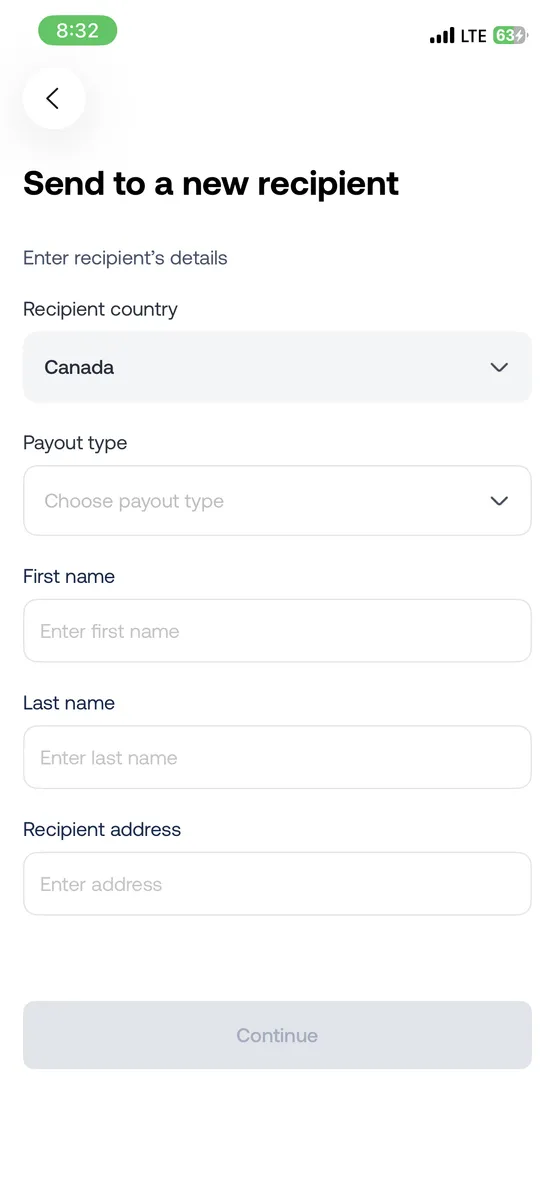
4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

Best ways to make contactless payments while travelling

•

•

2 min read

When you are travelling, small moments move fast.

You land in a new country. You need a taxi. You grab a coffee while figuring out directions. You pay for metro tickets, museum entries, and last-minute train rides. Nobody wants to stand at the counter counting notes or worrying whether their card will be accepted.

Contactless payments have become one of the easiest ways to move through a new place without friction. But not all contactless methods work equally well abroad.

Here are the best ways to make contactless payments while travelling and how to choose the right setup.

1. Use Apple Pay or Google Pay for tap-and-go payments

One of the most reliable ways to make contactless payments while travelling is through Apple Pay or Google Pay.

Instead of pulling out your physical card, you tap your phone or smartwatch on the terminal. Your card details stay encrypted, and merchants never see the full number.

Why it works well abroad:

  • Accepted in most countries that support contactless
  • Faster than chip-and-PIN
  • Adds an extra layer of security
  • Reduces the risk of card skimming

If you lose your phone, you can remotely disable payments. That is much harder to do with cash.

Also read: How to use your Grey card to manage all your subscriptions

2. Use a card built for international spending

Many travellers discover that their domestic debit card works perfectly at home but struggles abroad. Some are blocked automatically. Others add high foreign transaction fees.

The best way to make contactless payments while travelling is to use a card designed for international use.

The Grey virtual card, for example, connects directly to your foreign currency balances and works seamlessly with Apple Pay and Google Pay. That means you can tap your phone in cafés, shops, transport terminals and hotels without manually topping up or switching accounts before every purchase.

Because it is built for cross-border spending, there are fewer unexpected declines compared to local-only cards.

You may also like: How to pay online and in stores worldwide with your phone

3. Avoid relying only on cash

Cash feels safe, but it creates its own problems:

  • You need to exchange money at airports
  • You may get unfavourable rates
  • You risk carrying large amounts
  • You cannot easily track spending

Contactless payments give you a digital trail. You can see every transaction instantly inside your app. This is especially useful when travelling across multiple cities or countries.

4. Enable 3D Secure and payment alerts

Security matters even more when travelling.

Public Wi-Fi, unfamiliar networks and tourist-heavy areas increase exposure to fraud.

Before your trip:

  • Activate transaction notifications
  • Enable 3D Secure authentication
  • Set daily spending limits

The Grey virtual card supports 3D Secure and integrates with Apple Pay and Google Pay, which add biometric verification such as fingerprint or Face ID. That means even if someone gets access to your device, they cannot easily complete a payment.

Also read: How to shop in the US or Europe with your Grey card

5. Use contactless for transport and quick purchases

Many cities now allow direct tap-to-pay access on:

  • Metro systems
  • Buses
  • Airport trains
  • Trams

Instead of buying physical tickets, you can tap your phone at the gate. It saves time and avoids queues.

Contactless is also ideal for:

  • Coffee shops
  • Convenience stores
  • Food markets
  • Ride-hailing services

When you are moving constantly, speed matters.

Why contactless payments are the smartest option for modern travellers

Travelling today is digital.

Boarding passes live in your phone. Hotel confirmations arrive by email. Navigation happens through apps. Payments should match that flow.

The best ways to make contactless payments while travelling combine:

  • Internationally accepted cards
  • Mobile wallet integration
  • Strong security features
  • Clear visibility over transactions

With the Grey virtual card connected to Apple Pay or Google Pay, you can pay quickly, securely and internationally without constantly worrying about currency conversions or blocked transactions.

If you are planning your next trip, setting up the right payment method before you leave can make the entire experience smoother.

Create your Grey virtual card and travel with a payment setup that moves as easily as you do.

‍

5 best travel debit cards UK residents can use abroad 

•

•

2 min read

Using the wrong debit card abroad is one of the most reliable ways to spend more money than you planned. Most standard UK current account debit cards charge a non-sterling transaction fee, typically around 2-3%, every time you pay in a foreign currency. On top of that, ATM withdrawals abroad often carry a separate fee. A fortnight in Europe or a trip to Nigeria adds up fast.

The good news is that the right card costs nothing extra to use abroad. Several UK debit cards now offer zero foreign transaction fees and zero ATM charges. This guide covers the best options, explains the fee structure you need to understand before you travel, and is honest about where different cards suit different travellers, including diaspora users whose travel needs differ from the standard package-holiday crowd.

Want a virtual debit card you can use abroad? Grey gives you a multi-currency account with a virtual debit card, so you can spend, send, and manage money across borders from day one. Get your Grey card

What fees do UK debit cards charge abroad?

Before comparing specific cards, it helps to understand the three fees that make up the total cost of using a debit card internationally.

Non-sterling transaction fee

This is the most common fee and the most significant. When you pay in a foreign currency, your bank has to convert that currency to sterling. Most standard UK bank accounts add a markup of around 2-3% on top of the exchange rate for doing this. On a GBP 500 holiday budget, that is GBP 10 to GBP 15 in fees alone, before you factor in ATM charges.

ATM withdrawal fee

Withdrawing cash from a foreign ATM can trigger a separate fee from your UK bank, on top of whatever the ATM operator charges. Some banks charge a flat fee per withdrawal. Others charge a percentage, typically 1.5-2%, with a minimum amount. The best travel debit cards charge neither.

Exchange rate markup

Even cards that advertise 'no fees' can still cost you money if they apply a markup to the exchange rate itself rather than charging a visible fee. The mid-market rate is the rate you see on a currency converter. Any rate that is worse than that is effectively a hidden charge. Cards that use the Mastercard or Visa exchange rate are typically very close to the mid-market rate, which is why they are considered fee-free in practice.

The best debit cards to use abroad from the UK

All fee and limit information below is based on publicly available data as of June 2026. Verify the current figures on each provider's website before you travel, as providers regularly update their terms.

  1. Starling Bank: the cleanest zero-fee option

Starling is the most straightforward pick for UK travellers who want to spend abroad without thinking about fees. It charges nothing for spending in any foreign currency and nothing for ATM withdrawals anywhere in the world. The card uses the Mastercard exchange rate, which sits very close to the mid-market rate with no additional markup.

  • Foreign transaction fee: None
  • ATM withdrawal fee abroad: None
  • Exchange rate: Mastercard rate, no markup
  • ATM spending limit: GBP 300 per day (maximum 6 withdrawals)
  • Card purchase limit: GBP 10,000 per day
  • Account fee: None
  • Card type: Mastercard debit

Starling regularly tops UK banking service polls for customer satisfaction. The app is clean, the account is easy to open, and there are no tricks in the fee structure. For most UK travellers, this is where the search ends.

One thing to note: the GBP 300 daily ATM limit applies to combined UK and overseas withdrawals. If you need to withdraw significant amounts of local cash, plan accordingly.

If you're travelling to Europe, India, Bangladesh, or Nigeria, you can send money directly to a local bank account in those countries with Grey.

  1. Chase UK: best for ease of access alongside your existing bank

Chase offers zero foreign transaction fees and zero ATM withdrawal fees abroad, with the Mastercard exchange rate and no markup. The major advantage of Chase over Starling is the barrier to entry: you can open a Chase account with only a soft ID check, not a full credit check, and you do not have to switch your existing bank account. Chase sits alongside whatever bank account you already have.

  • Foreign transaction fee: None
  • ATM withdrawal fee abroad: None
  • Exchange rate: Mastercard rate, no markup
  • ATM limit abroad: GBP 500 per day; maximum GBP 1,500 per month when overseas
  • Account fee: None
  • Ongoing perk: 1% cashback on UK grocery, transport, and fuel spending

Chase is particularly useful if you travel infrequently and do not want to go through the process of switching banks. You keep your existing current account for day-to-day UK banking and use Chase only when travelling abroad or when you want the cashback perk.

The monthly ATM cap of GBP 1,500 overseas is lower than Starling's equivalent, which is worth noting if you regularly make larger cash withdrawals when travelling.

  1. First Direct: best all-round package including non-travel perks

First Direct offers the same zero-fee travel proposition as Starling and Chase, with the Mastercard rate and no foreign transaction or ATM fees. Where First Direct stands apart is the overall current account offer: a GBP 200 switching bonus for eligible new customers, a 7% regular savings account rate, and a GBP 250 interest-free overdraft for many customers.

  • Foreign transaction fee: None
  • ATM withdrawal fee abroad: None
  • Exchange rate: Mastercard rate, no markup
  • ATM limit: GBP 500 per day
  • Account fee: None, subject to minimum monthly pay-in or maintaining a minimum balance
  • Switching bonus: GBP 200 for eligible switchers (confirm current terms at firstdirect.com)

First Direct is worth considering as a full bank switch if you want the travel benefits plus the savings rate and overdraft. For people who want the travel card without switching banks, Chase is the simpler option.

  1. Monzo: best for budget tracking alongside zero-fee travel spending

Monzo's free current account comes with a Mastercard debit card that charges no foreign transaction fees. ATM withdrawals in the European Economic Area (EEA) are unlimited and free if Monzo is your main account. Outside the EEA, the first GBP 200 per month is free, and a 3% fee applies thereafter.

  • Foreign transaction fee: None
  • ATM withdrawal fee: Free in EEA (as main account); GBP 200 free per month outside EEA, 3% above limit
  • Exchange rate: Mastercard rate, no markup
  • Purchase limit: GBP 10,000 per day
  • ATM limit: GBP 400 per day
  • Account fee: None (free plan)

Monzo's app is particularly strong for spending visibility: real-time notifications, category breakdowns, and the ability to set pots for specific travel budgets. If you travel mainly within Europe, the unlimited free ATM withdrawals as a main account holder make it one of the strongest free options. For long-haul travel outside the EEA, the GBP 200 monthly ATM cap is a consideration. Wise card is worth considering here, as it lets you hold and convert over 40 currencies and withdraw up to GBP 200 a month fee-free across the globe, making it a practical companion for frequent long-haul travellers.

Full comparison: fee-free debit cards for travel from the UK

Card FX fee ATM fee abroad Exchange rate ATM limit Account fee
Starling None None Mastercard rate GBP 300/day None
Chase UK None None Mastercard rate GBP 500/day; GBP 1,500/month abroad None
First Direct None None Mastercard rate GBP 500/day None (conditions apply)
Monzo None Free in EEA; GBP 200/month outside, 3% above Mastercard rate GBP 400/day None (free plan)
Wise card None (conversion fee from 0.33%) Free to GBP 250/month; 2.69% above Mid-market rate GBP 4,000/month None (GBP 7 one-time physical card fee)
Barclays 2.99% 2.99% (included in non-sterling fee) Visa rate GBP 300/day None (standard account)
Halifax 2.99% 2.99% + GBP 1.50 flat fee (waived in EEA) Mastercard rate GBP 800/day None (standard account)
Lloyds 2.99% 2.99% + GBP 1.50 flat fee (waived in EEA) Mastercard rate GBP 800/day None (standard); GBP 5/month for Club Lloyds, which waives FX fees
HSBC 2.75% 2.75% + 2% (min. GBP 1.75, max. GBP 5) Visa rate GBP 500/day (depends on account type) None (standard); Global Money Account waives all fees
Santander 2.95% 2.95% Mastercard/Visa rate GBP 300/day None (standard)

Cards to avoid for overseas spending

Most standard UK bank account debit cards are expensive to use abroad. The typical arrangement is a 2.99% non-sterling transaction fee, a separate fee of GBP 1 to GBP 1.50 for each ATM withdrawal, and sometimes a flat spending fee of 50p to GBP 1 on top of that.

Lloyds Classic, Halifax Current Account, Bank of Scotland Classic, and TSB Spend and Save all fall into this category for overseas spending. Holding one of these as your main account does not mean you are stuck with high travel fees: opening a Chase account alongside it takes minutes and removes the problem entirely.

Grey: for diaspora users travelling between the UK and their home

Who this section is for: Nigerian professionals, NRIs, and wider diaspora communities in the UK who travel regularly between the UK and their home country, and who already use Grey for money transfers and multi-currency account features.

Grey is not a travel debit card in the conventional sense. Its virtual card charges a 2% plus $0.50 foreign exchange fee on transactions processed in non-USD currencies. That puts it behind Starling, Chase, First Direct, and Monzo for general holiday spending, which processes in any currency for free.

But travel looks different for diaspora users. When a Nigerian professional in the UK flies home to Lagos, they are not looking for a card to tap at a Parisian cafe. They are managing money across two countries simultaneously: salary in sterling, family support in naira, subscriptions in dollars, and potentially a Grey account they already use for transfers.

For that user, Grey's value during travel is not as a spending card. It is the account they already hold that travels with them. If you use Grey to send money to Nigeria, your USD, GBP, and EUR balances are accessible from wherever you are. You can top up your Grey USD card from your USD wallet and pay for USD-denominated services, whether you are in London or Lagos. You can receive international income into your Grey account while abroad.

The practical recommendation for diaspora travellers

  • Open Starling or Chase for local spending while travelling, whether in the UK, Nigeria, India, or anywhere else. Zero fees, immediate ATM access, Mastercard rate.
  • Use Grey for what Grey is built for: your USD, EUR, and GBP balances, international transfers, and paying for USD-denominated platforms from whichever country you are in.
  • These two accounts complement each other. Starling or Chase handles local-currency spend. Grey handles your cross-border financial life.

Grey is not designed for general overseas spending. Its virtual card charges a 2% + $0.50 FX fee on non-USD transactions, which means it serves a different purpose from zero-fee travel cards. Where Grey adds value for travellers is through the multi-currency account and transfer features that travel alongside you.

Do you need to tell your bank before travelling?

For the fee-free digital banks covered in this guide, no notification is typically required. Starling, Chase, and Monzo are designed for international use and rarely block overseas transactions as suspicious. First Direct may occasionally query unusual activity, so it is worth having a UK contact number that works internationally.

For standard bank account debit cards, setting a travel notification in the app before you leave can prevent your card from being blocked for suspected fraud when transactions start appearing from a different country.

Dynamic currency conversion: always decline it

When paying by card abroad, some merchants and ATMs offer to convert the transaction to sterling for you. This is called dynamic currency conversion (DCC). It will almost always be the more expensive option. The rate applied is the merchant's own rate, which is typically worse than the Mastercard or Visa rate your bank would use.

When given the option, always choose to pay in the local currency. Let your card do the conversion. This applies regardless of which card you are using.

Should I use my debit card for hotel check-ins and car rentals abroad?

Hotels and car rental companies often place a temporary hold on your card when you check in or pick up a vehicle. This is a security deposit, not an actual charge, and it is released when you check out or return the car. The amount varies, ranging from GBP 50 to several hundred pounds.

With a debit card, this hold reduces your available balance immediately. If you have GBP 500 in your account and the hotel places a GBP 300 hold, you have GBP 200 available to spend until the hold is released. This can create problems if your account balance is not significantly higher than the hold amount.

With a credit card, the hold is applied to your credit limit rather than your available cash, avoiding the cash flow issue entirely. Some car rental companies specifically require a credit card for this reason. Always check the rental company's policy before you travel. If they require a credit card and you do not have one, some companies will accept a debit card with a larger cash deposit.

For the zero-fee debit cards recommended in this guide, holds work as follows: Starling and Chase place holds in the normal way and release them when notified by the merchant, which can take one to five business days. If a hold is not released promptly, contact the card provider directly.

What to do if your card is blocked or stopped abroad

Even with the best travel debit cards, things occasionally go wrong. A transaction in an unfamiliar country can trigger a fraud alert and temporarily block your card. Here is what to do if it happens.

Check your notifications first

Starling, Chase, and Monzo all send instant push notifications for every transaction. If your card is blocked, you will usually receive a notification explaining why. Some digital banks let you unblock specific transaction types directly in the app, without having to call anyone.

Use the in-app card controls

All four recommended cards have in-app controls that let you freeze and unfreeze your card instantly. If a specific merchant or transaction type is being blocked, you may be able to adjust settings in the app to allow it. Check the card settings before calling the bank.

Have a backup card

The single most important thing you can do before travelling is to carry two cards. Keep them in separate places. If one card is blocked, lost, or stolen, the second card covers you while you sort out the first. Opening a Chase account alongside your existing bank account before you travel costs nothing and takes a few minutes. It means you always have a backup.

Contact the bank's emergency line

First Direct has a 24-hour phone line. Starling and Monzo have in-app chat. Chase has in-app support. If you are abroad and your card is blocked, use the in-app contact method first, as it is usually faster than a phone call. Have your account details ready.

Emergency cash via Western Union or MoneyGram

If you are in a situation where all your cards have failed, and you need cash urgently, someone at home can send you emergency cash via Western Union or MoneyGram for collection at a local agent. This is a last resort, but worth knowing about before you travel.

ATM safety tips when travelling abroad

The best travel debit cards eliminate bank fees on ATM withdrawals, but there are other risks at foreign ATMs beyond what your bank charges.

Use ATMs attached to banks, not standalone machines

Freestanding ATMs in tourist areas, airports, and convenience stores are more frequently targeted by card-skimming devices than those at bank branches. Where possible, use ATMs physically attached to a bank building, ideally in the bank lobby.

Cover the keypad when entering your PIN

Skimming devices can capture your card number electronically, but they still need your PIN to use the card at an ATM. Covering the keypad with your hand when entering your PIN is a basic but effective precaution.

Decline dynamic currency conversion at the ATM

ATMs will often offer to convert the amount to your home currency at the moment of withdrawal. Always decline and choose to withdraw in the local currency. The ATM's conversion rate is almost always worse than the Mastercard or Visa rate your card would apply, and it is a source of significant revenue for ATM operators. This applies even with zero-fee cards: the fee from your bank is zero, but the conversion markup from the ATM operator is not.

Check your account after every ATM withdrawal

Enable real-time notifications on your card so you see every transaction as it happens. If you see a withdrawal you did not make, freeze the card immediately in the app and contact the bank. Early detection significantly improves the chance of recovering funds.

How to manage spending in multiple currencies on the same trip

Some diaspora travellers make stops in more than one country on a single trip. A Nigerian professional in the UK might travel through Dubai before arriving in Lagos, for example. Here is how to manage the card strategy for a multi-currency trip.

The core principle is the same regardless of how many countries you visit: use a zero-fee travel card (Starling or Chase) for all local spending in local currency, and use Grey for any USD-denominated services you access while travelling. This approach keeps costs at zero for local spending and avoids FX fees on USD platform spending.

For countries where cash is preferred for day-to-day transactions, draw local currency from an ATM using Starling or Chase on arrival. Both cards give you the Mastercard rate with no ATM fee, which is the best available rate short of having a bank account in that country.

If you receive income from a client while travelling, Grey's USD or EUR account details work from anywhere. You can share your Grey account number and routing details with a client in any country and receive the payment directly into your Grey wallet. You do not need to be physically in the UK to use your Grey account.

Travel cards for UK residents sending money home

For diaspora travellers, a trip home often involves more than tourist spending. You may need to support family, pay for services locally, and manage money across two banking systems simultaneously. The card strategy needs to account for all of this.

The most efficient setup for a UK-based Nigerian professional travelling to Nigeria:

  • Starling or Chase: for local spending in Naira at Nigerian merchants and ATMs. Zero foreign transaction fees, Mastercard rate.
  • Grey: for sending naira directly to Nigerian family bank accounts before or during the trip. Grey's NGN transfer corridor lets you send from your GBP or USD balance to any Nigerian bank account at a transparent rate, without carrying large amounts of cash.
  • Grey USD card: for paying USD-denominated platforms and services you continue to use while in Nigeria, such as cloud tools, subscriptions, and professional platforms.

This three-layer approach covers local spending, family support, and international platform payments without paying unnecessary fees on any of them.

Frequently asked questions about travel cards

Which UK debit card has no foreign transaction fees?

Starling, Chase, First Direct, and Monzo all charge zero foreign transaction fees on their free current account debit cards. All use the Mastercard exchange rate with no additional markup.

Does Starling charge fees abroad?

No. Starling charges no foreign transaction fees and no ATM withdrawal fees anywhere in the world. It uses the Mastercard exchange rate with no markup. The daily ATM limit is GBP 300 (up to 6 withdrawals).

Can I use Grey as a travel card?

Grey is not designed as a general travel spending card. It charges a 2% plus $0.50 FX fee on non-USD transactions, which makes it more expensive than the zero-fee options above for everyday spending abroad.

Where Grey stands out is in sending money home. For diaspora users and businesses that work across borders, Grey lets you send money directly to bank accounts and mobile wallets around the world, at fees that start from $1 and without the markups that traditional banks charge. Use Starling or Chase for local spending, and use Grey to send money home, pay international contractors, or manage balances across currencies.

Send money with Grey

What is a non-sterling transaction fee?

A non-sterling transaction fee is a charge applied by your bank when you pay in a foreign currency. Your bank converts the foreign amount to sterling and then charges a percentage, typically 2-3%, for doing so. The best travel debit cards do not charge this fee. Standard high street bank debit cards usually do.

Is Chase Bank good for travelling abroad?

Yes. Chase UK charges zero foreign transaction fees and zero ATM withdrawal fees abroad. It uses the Mastercard exchange rate with no markup. The main limit to be aware of is the GBP 1,500 monthly cap on overseas ATM withdrawals. For most travellers, this is not a binding constraint.

Should I let an ATM convert the currency for me?

No. When an ATM offers to convert the amount to sterling and show you the total in GBP, it is applying its own exchange rate, which is typically worse than the rate your card would use. Always select the local currency option and let your debit card handle the conversion.

Can I use a UK debit card in Nigeria?

Yes. All four recommended cards (Starling, Chase, First Direct, Monzo) are Mastercard debit cards and are accepted at Mastercard-enabled ATMs and point-of-sale terminals in Nigeria. ATM availability varies by city and area. In major cities like Lagos and Abuja, Mastercard acceptance is generally good at bank ATMs. In more rural areas, carry local cash as a backup.

Does Monzo work in Nigeria?

Yes. Monzo's Mastercard debit card works at Mastercard ATMs in Nigeria. The first GBP 200 per month in ATM withdrawals are free outside the EEA if Monzo is your main account, with a 3% fee thereafter. For spending at point-of-sale terminals, there are no foreign transaction fees.

Is it better to use a card or cash in Nigeria?

In Lagos and Abuja, cards are increasingly accepted at hotels, restaurants, and larger shops. For markets, transport, and smaller vendors, cash is usually required. The practical approach is to withdraw a reasonable amount of naira from an ATM on arrival using Starling or Chase (zero fees) and use your card where it is accepted. Avoid airport exchange bureaux, which offer poor rates.

What is the best card to use in India?

Starling and Chase both offer no foreign transaction fees and no ATM charges (within their respective limits). UPI (Unified Payments Interface) is widely used in India for local payments, but requires an Indian bank account. For UK visitors, a zero-fee Mastercard debit card for ATM withdrawals and card payments at hotels and larger merchants is the practical approach for local spending. You can also send money to a local bank in India with Grey.

Can I use contactless payments abroad?

Yes. Starling, Chase, First Direct, and Monzo all support contactless payments via Mastercard at contactless terminals. Apple Pay and Google Pay are also supported by all four cards. Contactless limits vary by country and are set by local payment network rules, not your UK bank.

What if I lose my card abroad?

Freeze the card immediately in the app. For Starling, Chase, and Monzo, this takes seconds. Then contact the bank through their in-app chat or phone line to report the card lost and request a replacement. While waiting for a replacement, your second card (or Apple Pay / Google Pay on your phone if already set up) can continue to work. This is another reason to have two cards before you travel.

15 best travel insurance providers in the UK

•

•

2 min read

Travel insurance often feels like an unnecessary expense right up until something goes wrong. A delayed flight, lost baggage, unexpected illness, or cancelled holiday can quickly turn a well-planned trip into a costly experience. That is why choosing the right policy is just as important as booking your flights and accommodation, especially if you travel regularly or visit destinations where medical treatment can be expensive.

The best travel insurance in the UK covers medical expenses abroad, trip cancellation, baggage loss, and personal liability. Prices range from under £10 for a single trip to around £100 for annual multi-trip cover. The right policy depends on how often you travel, your destination, and whether you need extras like adventure sports or gadget cover. Understanding these differences is essential because the cheapest policy is not always the one that offers the protection you actually need.

With dozens of insurers competing for travellers' attention, comparing policies can quickly become overwhelming. Some providers specialise in affordable single-trip cover, while others offer comprehensive annual plans packed with benefits. To make your decision easier, we have reviewed 15 of the best travel insurance providers in the UK, highlighting their strengths, coverage levels, and suitability for different types of travellers.

Also read: Travel insurance for digital nomads

What does travel insurance in the UK cover?

  • Standard travel insurance cover: Most UK travel insurance policies include protection for the most common travel risks. This typically covers emergency medical expenses if you become ill or injured abroad, as well as medical evacuation where necessary. Policies also usually include trip cancellation or curtailment cover if you need to cancel or cut short your trip due to unforeseen circumstances. Other common benefits include protection for baggage and personal belongings, personal liability if you accidentally cause injury or damage, and missed departure cover if delays prevent you from reaching your transport on time.
  • Optional extras and specialist cover: Many insurers allow travellers to customise their policy with additional protection. Common extras include gadget cover for phones, laptops, and tablets, winter sports cover for skiing and snowboarding holidays, and cruise cover for cruise-specific disruptions. Travellers planning more active holidays may also need adventure activities cover, which can provide protection for activities such as scuba diving, hiking, mountain biking, or other higher-risk pursuits not included in standard policies.

15 best travel insurance providers in the UK

  • Direct Line offers comprehensive cover, strong customer service, and flexible policy options. Policies typically range from £15–£120, making it a solid choice for travellers seeking dependable all-round protection.
  • Aviva combines generous medical cover with optional upgrades and prices that generally range from £12–£130. It is particularly well suited to families and frequent travellers.
  • AXA is known for extensive emergency medical and cancellation cover. With policies typically costing £10–£140, it appeals to travellers who prioritise international medical protection.
  • Staysure specialises in cover for older travellers and people with pre-existing medical conditions. Pricing generally starts from £20 and can exceed £200 depending on age and medical requirements.
  • Post Office Travel Insurance offers straightforward cover and competitive pricing, with policies typically ranging from £9–£110, making it popular among budget-conscious holidaymakers.
  • Sainsbury's Bank provides flexible levels of cover and Nectar member benefits. Policies generally cost between £10–£120, offering good value for occasional travellers.
  • LV stands out for strong customer service and comprehensive benefits. Prices typically range from £12–£130, making it a dependable option for a wide range of travellers.
  • Admiral offers single-trip, annual, and family policies with useful optional extras. Pricing generally falls between £10–£125, making it attractive for families and regular travellers.
  • Marks & Spencer provides premium travel insurance with higher cancellation limits and enhanced benefits. Policies generally range from £15–£140.
  • Coverwise focuses on affordability, with policies typically costing £7–£90, making it one of the strongest low-cost providers in the market.
  • InsureandGo offers flexible cover for different ages and medical circumstances. Pricing generally ranges from £9–£150, depending on destination and cover level.
  • Columbus Direct delivers strong medical and cancellation benefits, with policies usually costing £10–£130. It remains popular with families and frequent travellers.
  • Battleface is designed for digital nomads, long-term travellers, and those visiting unconventional destinations. Pricing varies significantly depending on destination and trip length.
  • World Nomads specialises in adventure travel and covers activities often excluded elsewhere. Policies generally range from £30–£250+, depending on destination and activities selected.
  • Saga focuses on travellers aged 50 and above. Policies typically start from £25 and can exceed £220, reflecting its comprehensive cover and specialist support.

Also read: Smart money tips for first-time international travellers

Single-trip vs annual travel insurance: which is better?

Choosing between single-trip and annual travel insurance comes down to how often you travel. If you only take one holiday a year or are planning a single extended trip, single-trip insurance is usually the most cost-effective option because you only pay for the specific journey you are taking. It also tends to offer greater flexibility for travellers taking one longer holiday. Annual travel insurance, by contrast, covers multiple trips within a 12-month period and is often cheaper overall if you travel more than twice a year.

If you only travel occasionally, single-trip cover is often sufficient. If weekend breaks, business travel, or multiple holidays are part of your year, annual cover usually provides better value and convenience.

Also read: How to find lasting travel insurance for long-term remote work

What to check before buying UK travel insurance

  • Check the excess amount carefullyA low premium can sometimes hide a high excess, meaning you'll pay more out of pocket when making a claim. Always compare the excess alongside the policy price before deciding.
  • Review the medical cover limitAs a rule, look for at least £2 million in medical cover for Europe and £5 million or more for destinations such as the United States, where healthcare costs can be extremely high.
  • Declare all pre-existing medical conditionsFailing to disclose a condition could invalidate a claim. Even if a condition seems minor or well managed, check whether your insurer requires it to be declared.
  • Confirm your destination is coveredSome policies exclude specific countries or regions. You should also check the latest FCDO travel advice, as travelling against official guidance can affect your insurance coverage.
  • Check baggage and gadget limitsIf you're travelling with expensive phones, laptops, cameras, or tablets, make sure the policy covers their full replacement value, not just a limited amount per item.

How to get the best price for travel insurance

One of the easiest ways to reduce the cost of travel insurance is to compare multiple providers before buying. Rather than choosing the cheapest option immediately, focus on finding the best balance between price and protection.

Timing can also make a difference. Buying travel insurance soon after booking your trip ensures you are covered for cancellation from the outset and may help you secure lower premiums. If you travel more than twice a year, annual travel insurance is often significantly cheaper than purchasing separate policies for every trip. Frequent travellers can save both money and time by choosing annual cover.

Before purchasing a policy, check whether you already have travel insurance through a packaged bank account or premium credit card. Some providers include travel cover as a customer benefit. It is also worth paying by credit card where possible, as purchases over the qualifying amount may benefit from Section 75 protection, providing an additional layer of consumer protection.

Frequently asked questions

What is the best travel insurance in the UK?

The best travel insurance depends on your destination, age, medical history, and travel frequency. Providers such as Direct Line, Aviva, AXA, and Staysure consistently rank highly for customer service and cover levels. Rather than focusing solely on price, compare medical cover, cancellation protection, baggage limits, and optional extras to find the most suitable policy.

Is annual travel insurance worth it?

Annual travel insurance is usually worth it if you travel more than twice a year. Instead of purchasing separate policies for every trip, one annual policy covers multiple journeys over a 12-month period. It is often cheaper overall, more convenient to manage, and particularly useful for frequent holidaymakers, business travellers, and people who regularly take short breaks.

Does UK travel insurance cover Europe after Brexit?

Yes. UK travel insurance still covers trips to Europe after Brexit, although cover varies between providers. Travellers should not rely solely on the GHIC card, as it does not cover everything. Travel insurance can provide protection for cancellations, baggage loss, personal liability, and emergency medical expenses that may not be covered elsewhere.

What is not covered by travel insurance?

Most travel insurance policies exclude known events, undeclared medical conditions, reckless behaviour, and claims arising from travelling against official government advice. Standard policies may also exclude adventure sports, expensive gadgets, or cruise-related issues unless additional cover is purchased. Always review exclusions carefully before travelling to avoid unexpected claim rejections.

How much should travel insurance cost in the UK?

Travel insurance costs vary depending on age, destination, trip length, and medical history. Single-trip policies can cost less than £10 for European holidays, while annual cover often ranges from £30 to £100 or more. Premiums increase for older travellers, long-haul destinations, and those requiring cover for pre-existing medical conditions.

Can I get travel insurance with a pre-existing medical condition?

Yes. Many insurers, including specialist providers such as Staysure and Saga, offer cover for pre-existing medical conditions. You will usually need to declare all relevant conditions during the application process. While premiums may be higher, declaring your condition is essential because failing to do so could invalidate future claims.

When is the best time to buy travel insurance?

The best time to buy travel insurance is immediately after booking your trip. Doing so provides cancellation cover from the date the policy begins, protecting your financial investment if illness, injury, or another covered event forces you to cancel before departure. Waiting until just before travel can leave you unnecessarily exposed.

Can travel insurance cover cancelled flights and travel delays?

Yes, many travel insurance policies provide compensation for flight cancellations, significant delays, missed departures, and additional accommodation costs caused by covered disruptions. However, the level of protection varies between insurers. Checking the policy limits and delay thresholds before purchasing can help ensure you have adequate cover for your travel plans.

Also read: Grey for travellers and tourists

The right travel insurance can protect you from unexpected medical bills, cancellations, delays, and lost baggage, giving you greater confidence whenever you travel. Once your cover is in place, don't forget your travel money. Get your travel insurance sorted, then open a Grey account to spend abroad without foreign transaction fees on every trip, helping you manage your money more efficiently wherever you go.

How to budget in foreign currencies using the Grey card

•

•

2 min read

Budgeting used to be simple. You earned money, spent money, and tracked what was left. At that time, you had only one account with one currency, which required just one mental model.

Then remote work happened.

Now you might earn in EUR, pay for tools in USD, and travel in between. Discipline isn’t enough for budgeting anymore; you need structure. Without the right structure, even the most careful spender can lose track of where their money is going.

The Grey card comes in as a practical budgeting tool for people who live and spend across borders. I’ll explain.

Why budgeting in multiple currencies breaks down so easily

Most people don’t overspend because they’re irresponsible. Rather, they overspend because their money isn’t organised in a way that reflects how they live.

Here’s what usually goes wrong.

You’re spending across platforms, clients, and countries, but everything is tied to one card. Subscriptions, ads, one-off purchases, and travel expenses all blur together. When something goes wrong, such as a spike in ad spend or an unexpected renewal, it’s challenging to pinpoint the cause quickly.

Add foreign currencies to the mix, and it gets worse. The charges don’t always settle immediately, and these small amounts seem harmless until they quietly add up.

At that point, your budget is broken.

Also read: How to use your Grey card to manage all your subscriptions

What should budgeting look like when you earn and spend globally?

Clarity, separation, and control are the most crucial factors when budgeting across multiple currencies. You should be able to:

  • See exactly what each type of spending is costing you.
  • Stop or pause spending instantly when needed.
  • Protect one part of your budget from another.
  • Make changes without disrupting everything else.

The Grey card is designed around solving these exact needs.

How does the Grey card help with budgeting?

Use multiple cards to separate your spending

One of the most effective budgeting habits is separation. Instead of using a single card for everything, you can create multiple cards with clear purposes.

For example, you can create:

  • One card for subscriptions and recurring tools
  • One card for ads and growth experiments
  • One card for travel or everyday spending
  • One card per client or project

Each card acts like its own budget lane. You don’t need to guess where the money went; you already know.

This is especially useful if you freelance, manage ads, or run multiple income streams. When spending is separated, budgeting becomes more straightforward.

Also read: How to pay for ads easily with your Grey card

Freeze cards instantly when spending goes off-track

Budgets fail when you can’t act fast enough.

With the Grey card, you can instantly freeze or unfreeze any card in the app. If an ad campaign starts burning cash, freeze the card. If a subscription you forgot about renews unexpectedly, freeze the card. If you’re travelling and want to lock down non-essential spending, freeze the card.

Freezing a card doesn’t affect your other cards or balances. It simply stops that specific spending lane, which is precisely how budgeting should work.

Set limits that protect your budget

Budgets can fail when they’re too rigid. Grey’s spending limits work more like guardrails.

You can set daily or monthly limits per card, receive alerts when you’re approaching your limit, and still stay flexible. The goal isn’t to punish spending. I mean, who wants that? It’s to keep you aware before things drift too far.

For shared cards or subscriptions, limits are especially useful. You know exactly how much can be spent, and nothing sneaks past unnoticed.

Track spending clearly in one place

When you’re budgeting across currencies, visibility matters more than perfection. Every Grey card transaction appears clearly in your app, linked to the card you used. That means you’re not just seeing how much you spent, but why you spent it.

When budgeting time comes around, you’re no longer reconstructing your month from memory. The structure is already there.

Spend confidently across borders

Trust helps with budgeting too. When you’re shopping internationally, paying for ads, or travelling, declined payments and unexpected charges can throw everything off. The Grey Card works across global merchants and even supports Apple Pay and Google Pay, so everyday spending feels normal, even when you’re far from home.

LDMAG1

A quick note on protection when spending abroad

An often-overlooked aspect of budgeting is preparing for contingencies in case things go wrong.

When you pay with your Grey card, you have access to Visa benefits, including purchase protection, extended warranties, and price protection, depending on the transaction and your activation status. It’s not something you think about daily, but it adds a layer of reassurance when you’re buying electronics, booking travel, or shopping internationally.

It’s one less thing to worry about while managing money across borders.

Also read: How to claim your Visa card benefits

What budgeting in foreign currencies is like with the Grey card

When your card and your accounts are aligned, budgeting stops being guesswork. You know what you’re spending, which currency it’s coming from and more importantly, when something changes.

Instead of constantly reacting to your balance, you’re now making decisions with clarity. And that’s what good budgeting should be like, whether you’re at home, travelling, or working remotely.

If you’re ready to make your budget work wherever you are, create or update your Grey card and start spending and budgeting in the ways that matter to you.

‍

How tax-free shopping works for international travellers

•

•

2 min read

If you've ever shopped abroad and wondered why you pay more than the people who live there, put the blame on taxes you shouldn’t be paying because you are a foreigner. Sometimes, you are asked if you want a tax-free receipt, which is a legal way to help you reclaim the Value Added Tax (VAT) or sales tax on goods you take out of the country. As a foreigner, tax-free shopping while travelling can help you spend less if you understand how the system works. This article explains how tax-free shopping works for international travellers and how you can cut down on your shopping expenses.

What is tax-free shopping for international travellers?

Tax-free shopping is also called a VAT refund or a tourist refund. It's a provision that allows international travellers to reclaim the local sales tax (VAT) they paid on goods they take home. In most countries, this can save you 5–25% on major purchases, such as fashion items and electronics.

VAT is usually included in the displayed prices in most countries. Tax-free shopping removes tax on certain items after you’ve purchased them, depending on the country. Usually, you must be a short-term visitor (staying less than six months) to qualify for tax-free shopping. You would also be required to prove you're not a resident of the country you're shopping in. For example, a non-EU passport is all you need in Europe. Tax-free shopping only applies to personal items not intended for resale in your country. The item must also be leaving the country with you.

Also read: How virtual cards can simplify your life abroad

How do you shop tax-free as an international traveller?

Here is how you can benefit from tax-free shopping as an international traveller:

1. Visit participating stores

Not all stores offer tax refunds for tourists. Look for stores with stickers that say “Tax Free”, “VAT Refund”, or “Global Blue”/“Premier Tax Free” on their window or at checkout. Many big department stores and designer boutiques offer tax-free shopping. Many times, these stores have a minimum amount you can spend per visit.

2. Request for a tax refund form at the till

Show your passport (some stores will permit a clear photo on your phone). The shop will issue a tax refund form or an electronic receipt. In some systems, you pay the full price, including tax, while others deduct the tax at checkout. Keep the items unused and with their tags, as customs may require them.

LDMAG1

3. Validate at customs validation

Before you check in your bags (or after security in some airports), go to the customs desk. Show them your form, passport, and the goods. They stamp or electronically validate it to confirm you're exporting the items. This step is important because you won’t get a refund without the custom validation.

4. Get your money back

Once stamped, go to the refund counter (often run by Global Blue or Planet). You can usually choose cash (in local currency or sometimes USD/EUR), credit to your card, or bank transfer. Many now offer instant refunds on their app. There might be a service fee of around 10–20%. You may not be receiving the full tax refund.

Also read: A complete guide to budgeting as a remote worker

Managing your international shopping with Grey

Every traveller will take the slightest opportunity to maximise their budget. Tax-free shopping is an effective way to reduce your expenses while travelling. If you're wondering whether there is an easier way to pay for your international travel and shopping, Grey makes it simple with multi-currency accounts that support USD, EUR, and GBP. With low transaction costs, versatile virtual cards, and competitive exchange rates, you save more on your international spending. Grey now allows you to manage multiple cards for different purposes, helping you track your international spending more effectively. You can also spend directly from your balance without waiting to top up your card, reducing delays. You can also receive your tax refund seamlessly by providing your account details to the service provider.

Sign up on Grey today by installing the Grey app to manage your international shopping with ease.

‍

Arrow (up)

Back to top