


<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#article","headline":"Top digital nomad cities for long-term rentals in Latin America","description":"Discover long-term rentals in Latin America with key tips for digital nomads. Explore vibrant cities like São Paulo, Mendoza, and Montevideo, and gain insights on rental prices and essential documentation for an affordable and culturally rich experience.","inLanguage":"en","url":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america","mainEntityOfPage":{"@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#webpage"},"datePublished":"2024-10-25T14:06:16.170Z","dateModified":"2026-06-15T19:23:51.978Z","author":{"@type":"Person","@id":"https://grey.co/authors/priscila-marotti#person","name":"Priscila Marotti","url":"https://grey.co/authors/priscila-marotti","jobTitle":"Content Writer","sameAs":["https://www.linkedin.com/in/priscila-marotti/"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301a0fd807c78c444d7215_6a301a0eb24e8fcf46a20595_top-digital-nomad-cities-for-long-term-rentals-in-latin-america__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a301a0fd807c78c444d7215_6a301a0eb24e8fcf46a20595_top-digital-nomad-cities-for-long-term-rentals-in-latin-america__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#webpage","url":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america","name":"Top digital nomad cities for long-term rentals in Latin America","description":"Discover long-term rentals in Latin America with key tips for digital nomads. Explore vibrant cities like São Paulo, Mendoza, and Montevideo, and gain insights on rental prices and essential documentation for an affordable and culturally rich experience.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Top digital nomad cities for long-term rentals in Latin America","item":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america"}]},{"@context":"https://schema.org","@type":"ItemList","@id":"https://grey.co/blog/top-digital-nomad-cities-for-long-term-rentals-in-latin-america#list","name":"Top digital nomad cities for long-term rentals in Latin America","numberOfItems":4,"itemListElement":[{"@type":"ListItem","position":1,"name":"São Paulo, Brazil"},{"@type":"ListItem","position":2,"name":"Montevideo, Uruguay"},{"@type":"ListItem","position":3,"name":"Mexico City, Mexico"},{"@type":"ListItem","position":4,"name":"Santiago, Chile"}]}] </script>

Top digital nomad cities for long-term rentals in Latin America

Priscila Marotti

TABLE OF CONTENT

SHARE THIS POST

Latin America is becoming a top destination for remote workers seeking affordable rentals and exciting new experiences. The region’s vibrant cities, stunning natural landscapes, and lower living costs offer nomads a perfect blend of comfort, adventure, and culture. However, finding the ideal long-term rental in Latin America requires knowledge of local markets, legal requirements, and available resources.

This guide explores some of the top cities for digital nomads looking for long-term rentals, providing key insights into documentation, rental prices, and tips for making the most out of your stay.

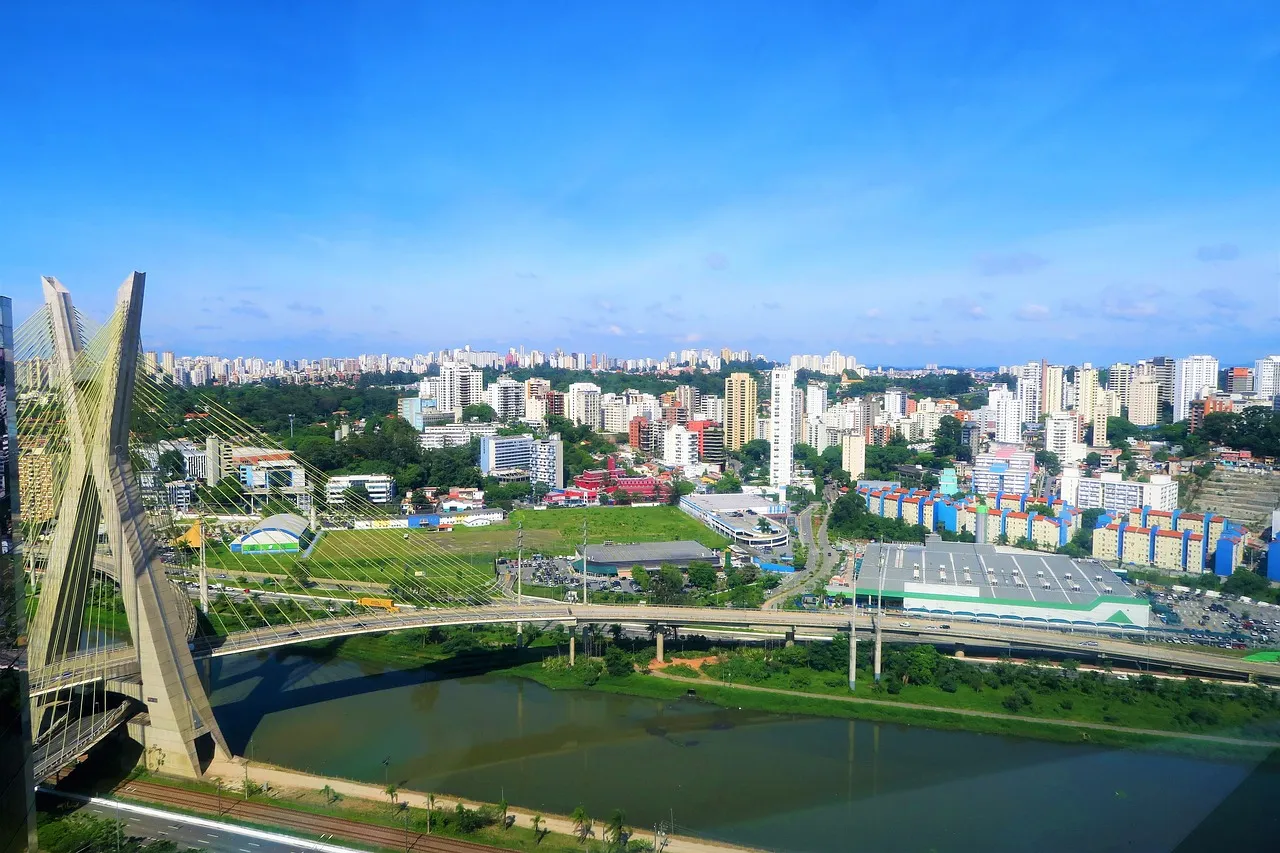
São Paulo, Brazil: A bustling economic hub

__wf_reserved_inherit

São Paulo, Brazil’s largest city and its financial powerhouse, has long attracted expats, students, and professionals. With over 12 million inhabitants, it offers many rental options, from luxury apartments in upscale areas to more budget-friendly options in growing neighbourhoods.

The fast-paced environment, reliable internet, and co-working spaces make São Paulo an appealing base for digital nomads. The city’s transportation infrastructure allows easy access to business districts, while its diverse food scene, cultural attractions, and nightlife provide plenty to explore.

Rental prices in São Paulo:

  • Luxury neighbourhoods like Jardins and Vila Madalena: Expect monthly rents between $600 to $1500.
  • More affordable areas: Neighbourhoods such as Mooca or Tatuapé offer rents from $400 to $600.

Documents for renting in São Paulo:

  1. Valid passport: Proof of identity is essential.
  2. CRNM (foreign resident ID): Required if you stay for an extended period.
  3. Proof of income: Often necessary to demonstrate financial stability, whether from a Brazilian employer or an overseas job.
  4. Guarantor or security deposit: Most landlords will ask for a guarantor (someone who can co-sign the lease) or a security deposit, typically 1-3 months’ rent.

Pro tips:

  • Rent directly from landlords to avoid agent fees.
  • Consider flat-sharing, as São Paulo has a vibrant community of expats looking for roommates.

São Paulo is a large, dynamic city with plenty of variety in the rental market, so doing thorough research and negotiating prices is recommended.

Find out more about long-term rentals in Brazil.

Mendoza: The wine capital of Argentina

__wf_reserved_inherit

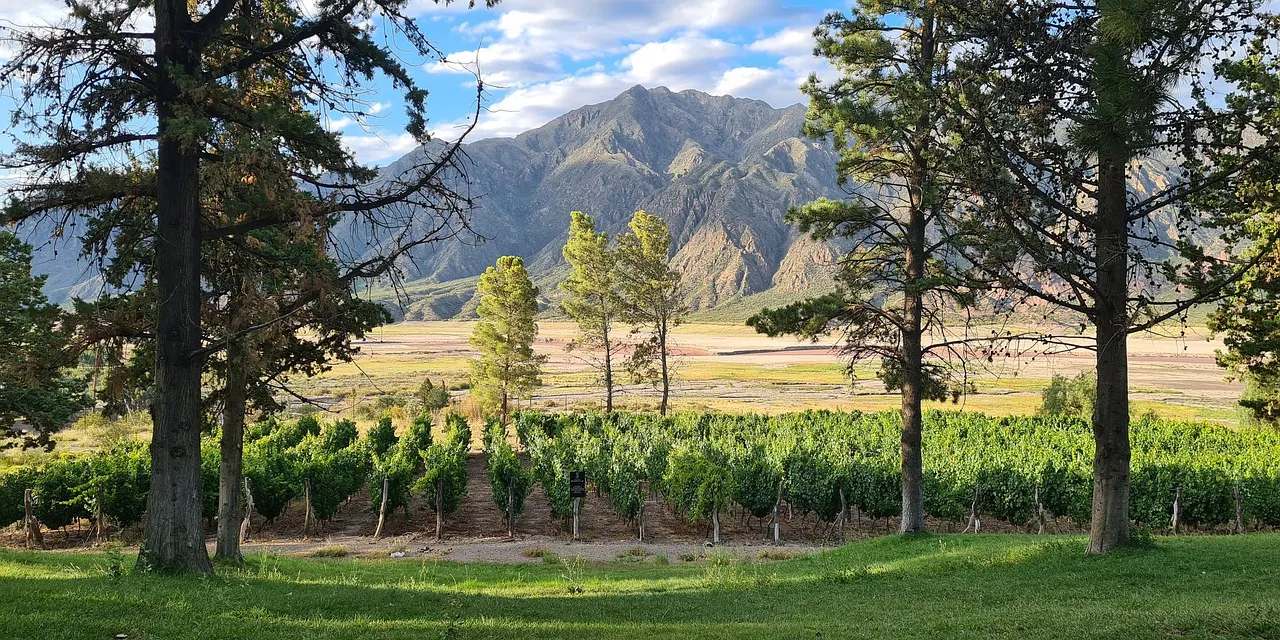
Located at the base of the Andes Mountains, Mendoza is renowned for its stunning landscapes and exceptional vineyards. This vibrant city is Argentina’s leading wine-producing region, offering a unique blend of urban life and outdoor adventure. With its sunny climate and picturesque views, Mendoza attracts both tourists and digital nomads seeking a laid-back yet culturally rich environment.

Rental prices in Mendoza:

  • In central neighborhoods like Ciudad and Godoy Cruz, one-bedroom apartments typically cost $400 to $700 monthly.
  • More budget-friendly options are available in areas like Maipú and Luján de Cuyo, where rents may start around $300.

Documents for renting in Mendoza:

  • Identification: A valid passport or Argentine ID (DNI) is required to sign a lease.
  • Proof of income: Landlords often ask for proof of income, especially for long-term leases.
  • Guarantor (fiador): If you lack a local guarantor, be prepared to offer a larger security deposit.

Pro tips:

  • Use local websites or real estate agents for rental listings to avoid scams and ensure reliability.
  • Explore neighbourhoods outside tourist hotspots to discover charming local areas and better rental prices.

Renting in Mendoza offers the best of both worlds: a rich cultural experience paired with outdoor activities like hiking, wine tours, and horseback riding. With its welcoming community and stunning scenery, Mendoza is an excellent choice for those seeking a peaceful lifestyle while enjoying urban conveniences.

Explore more about Argentina’s rental options.

Also read: Moving abroad checklist: 6 Essential considerations for a smooth transition

Montevideo, Uruguay: Coastal charm and high quality of life

__wf_reserved_inherit

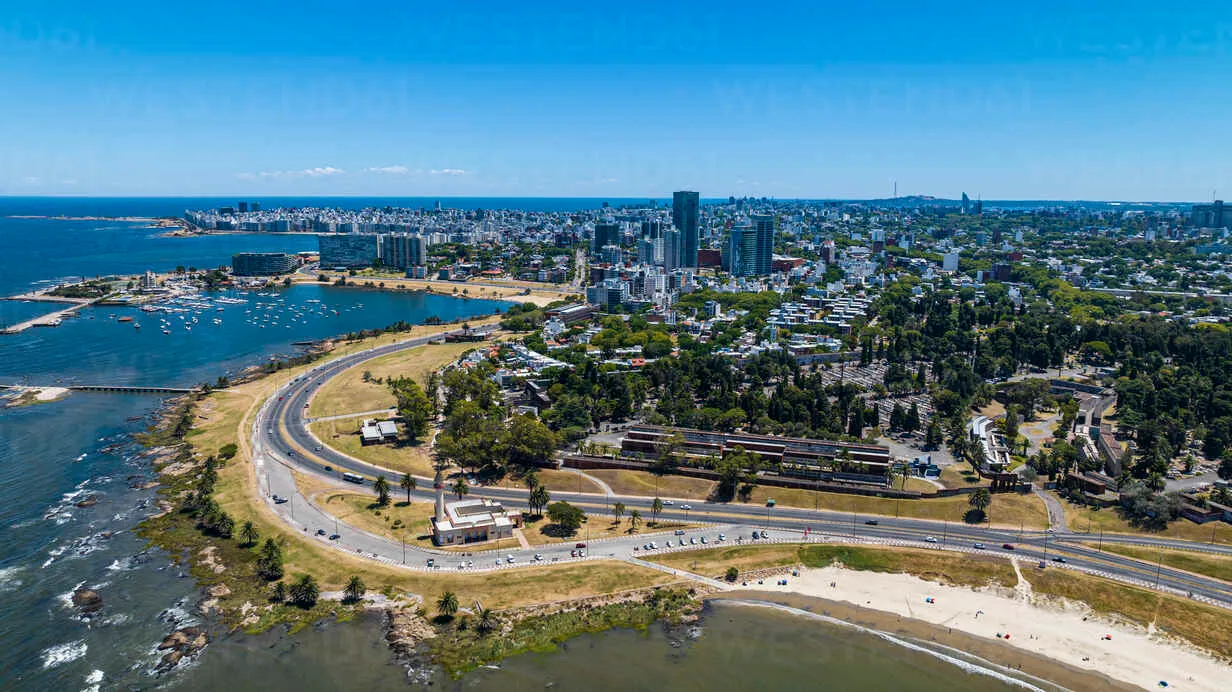
Montevideo is Uruguay’s capital and largest city, known for its laid-back coastal lifestyle, safety, and high quality of life. It’s a particularly good choice for digital nomads who prefer a slower pace but still want access to modern amenities. The city boasts reliable internet, a thriving arts scene, and excellent public healthcare options.

Rental prices in Montevideo:

  • In popular areas like Pocitos or Punta Carretas, rents are typically between $750 and $1000 monthly.

Documents for renting in Montevideo:

  1. Passport: You’ll need this for identification.
  2. Proof of income: This is required to demonstrate that you can afford the rent.
  3. Guarantor or security deposit: If you don’t have a guarantor, expect to pay 1-2 months’ rent as a deposit.

Pro tips:

  • Landlords in Montevideo are often willing to negotiate, especially if you’re renting for an extended period.
  • Consider renting in neighborhoods slightly outside the city center, such as Malvín Norte and Parque Rodó. These areas offer more affordable rental options while providing convenient access to amenities and public transport, ensuring you won’t miss Montevideo’s vibrant lifestyle.

Montevideo offers a blend of coastal charm and urban conveniences, making it ideal for digital nomads looking to settle in a stable, welcoming city.

Learn more about Montevideo rentals.

Mexico City, Mexico: A dynamic cultural metropolis

__wf_reserved_inherit

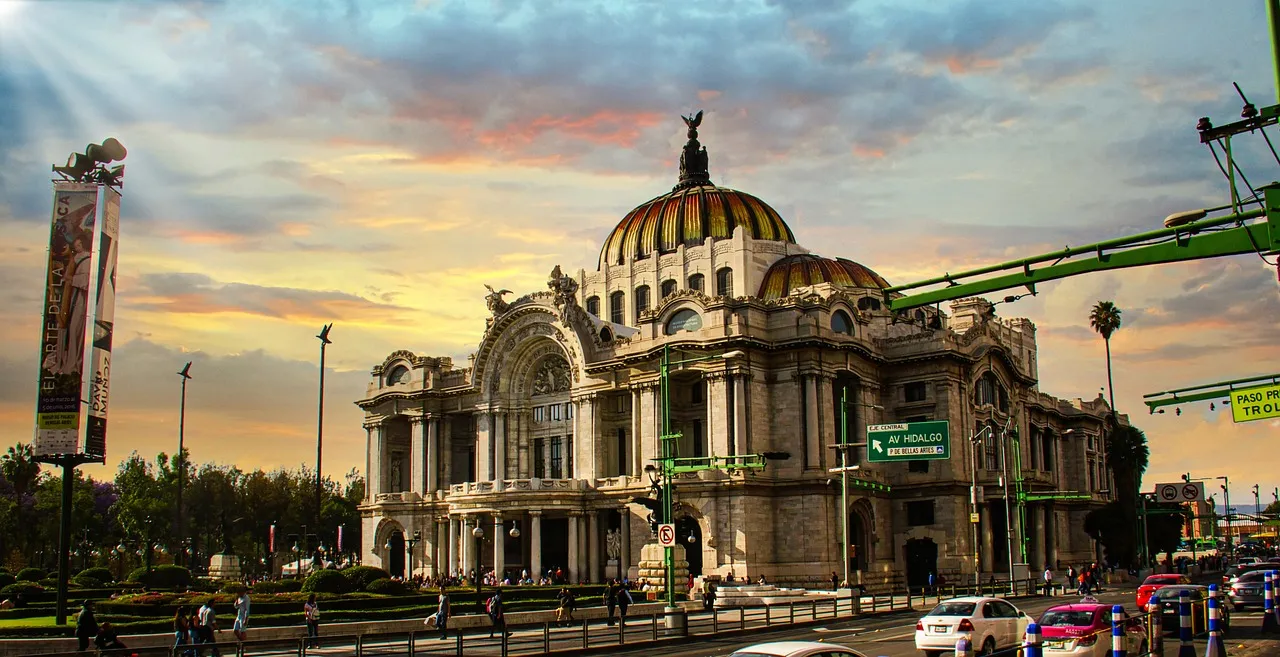
Mexico City, the country’s expansive capital, is a dream destination for digital nomads due to its diverse cultural offerings, modern infrastructure, and affordable cost of living. The city boasts vibrant neighbourhoods, excellent street food, and a rich history that spans centuries. Digital nomads particularly appreciate its wide selection of co-working spaces and strong internet connectivity.

Rental prices in Mexico City:

  • Rents range from $500 to $1200 per month in trendy areas like Roma and Condesa, while they can be significantly cheaper in less touristy places.

Documents for renting in Mexico City:

  1. Passport or Mexican ID: Required for long-term leases.
  2. Guarantor (fiador): Often requested, though a higher deposit may substitute if you don’t have one.
  3. Proof of income: Landlords may request recent bank statements or proof of income, especially for long-term rentals.

Pro tips:

  • Consider looking for rentals outside tourist-heavy neighborhoods, such as Coyoacán, for more budget-friendly options.
  • Walking through neighborhoods and spotting “Se Renta” signs can sometimes lead to better deals than online listings.

Mexico City offers an unparalleled mix of urban excitement, history, and modern comforts, making it a prime choice for remote workers seeking both inspiration and practicality.

Find Mexico City rental properties.

Santiago, Chile: Modernity and stability in the Andes

__wf_reserved_inherit

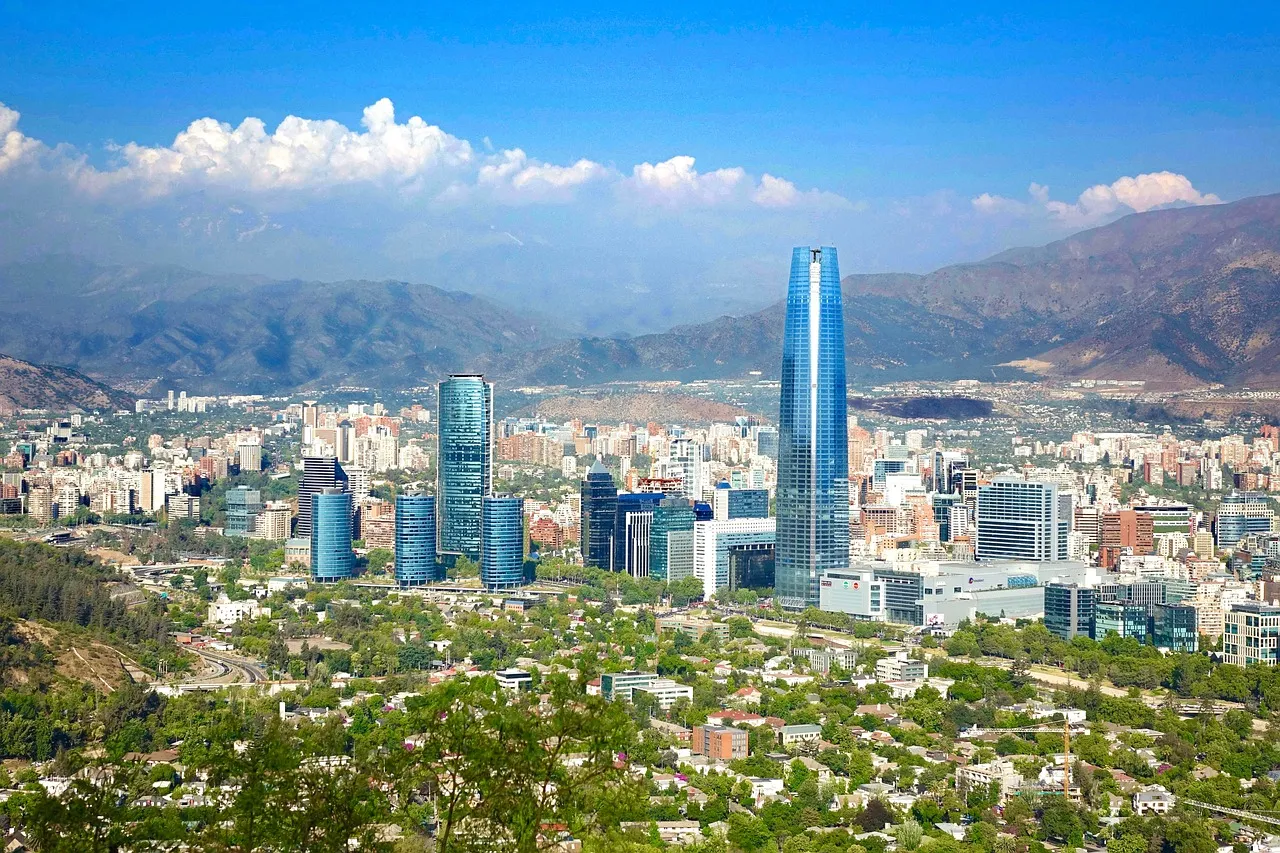
Santiago is one of the most modern cities in South America, featuring excellent infrastructure, reliable public transportation, and a strong economy. It’s a perfect destination for digital nomads who value stability, access to co-working spaces, and stunning mountain views. The city is known for its excellent internet and safety, particularly in neighbourhoods favoured by expats.

Rental prices in Santiago:

  • Central neighbourhoods like Providencia or Las Condes range from $600 to $1200 monthly.

Documents for renting in Santiago:

  1. RUT (Chilean ID): If you stay long-term, you will need this.
  2. Proof of income: To qualify, your salary should typically be 50% higher than the monthly rent.
  3. Guarantor or deposit: A guarantor or 2-3 months’ rent as a deposit is often required.

Pro tips:

  • Many digital nomads find better deals in neighborhoods just outside the city center, which are still well-connected by public transport.
  • Look into shared apartments to reduce rental costs while meeting fellow expats or locals.

Santiago’s mix of modern amenities and proximity to breathtaking nature make it a unique choice for digital nomads looking for adventure and comfort.

Explore more about living costs in Santiago.

5 crucial tips for saving on long-term rentals in Latin America

  1. Do your research: Local real estate websites, forums, and rental agents can provide valuable insights into the rental market.
  2. Consider flat-sharing: This can significantly reduce costs and also introduce you to a local community of expats or digital nomads.
  3. Negotiate: Many landlords are open to negotiation, particularly for long-term rentals, so don’t hesitate to ask for a discount.
  4. Monitor local markets: Keep track of rent fluctuations, as prices can vary depending on the season or local economic factors.
  5. Plan for additional costs: When budgeting, always factor in utilities, building maintenance fees, and other potential costs.

Long-term rentals in Latin America are an attractive option for digital nomads seeking to balance affordability with a rich cultural experience. Whether you’re drawn to the energy of São Paulo, the coastal tranquility of Montevideo, or the mountain backdrop of Santiago, understanding the local rental markets and knowing what to expect regarding documentation and costs will help ensure a smooth transition.

No matter where you go, simplify your finances as a digital nomad. Create your free Grey account today to easily send and receive money, exchange currencies, and manage your finances from anywhere.

‍

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

How to Pay for ChatGPT Plus in Nigeria

•

•

2 min read

ChatGPT Plus costs $20 a month. The first problem for most Nigerians is that OpenAI does not accept naira-denominated debit cards, which means your standard Nigerian bank card will be declined at checkout every time.

The solution is a virtual dollar card. With a Grey account, you can create one in minutes and complete the ChatGPT Plus subscription on the same day. This guide covers the full process: what you are paying for, how much it costs in naira, how to set up your Grey card, and exactly how to complete the subscription on desktop and mobile.

What is ChatGPT Plus?

ChatGPT is the AI assistant developed by OpenAI and launched in November 2022. The free version gives you access to a limited version of OpenAI’s models with lower message caps and slower responses during busy periods.

ChatGPT Plus is OpenAI’s paid subscription tier at $20 per month. It gives you significantly more capability across every dimension of the product.

ChatGPT Plus vs Free: what you actually get

Feature Free Plus
GPT-5.5 Instant (standard model) Limited access Expanded access
GPT-5.5 Thinking (reasoning model) Not available Expanded access
Message limits Limited Expanded
Response speed Limited by demand Fast
Voice conversations Yes (basic) Expanded
Voice with video No Yes
Image generation Limited Yes (including with Thinking)
File uploads and data analysis Limited Yes
Deep research and agent mode Limited Expanded
Custom GPT creation No Yes
Tasks and scheduled actions No Yes
Apps connecting to internal tools No Yes
Early access to new features No Yes
Context window (Instant model) 27K tokens (about 12 pages) 54K tokens (about 40 pages)
Price Free $20 per month

Is there a higher-tier plan?

Yes. Above Plus, OpenAI offers ChatGPT Pro at $100 per month (billed in GBP on the UK pricing page; USD equivalent applies for Nigerian users). Pro gives you five to twenty times more usage than Plus, access to GPT-5.5 Pro (the most powerful version), unlimited image generation, maximum deep research and agent mode, and a research preview of new features before they reach Plus.

For most Nigerian users, Plus at $20 per month covers everything. Pro is designed for power users who hit Plus usage limits regularly.

OpenAI does not currently offer annual billing for ChatGPT Plus or Pro. All plans are billed monthly.

How much does ChatGPT Plus cost in naira?

OpenAI charges $20 per month, billed in USD. The naira equivalent shifts with the exchange rate. At typical market rates, $20 works out to roughly N25,000 to N30,000 per month. Verify the current rate in the Grey app before subscribing, since this changes daily.

Because the charge is in USD and your Grey card operates in USD, there is no currency conversion on the ChatGPT transaction itself. You only pay the Grey FX swap fee once, when you convert naira to USD to fund your account.

Why do Nigerian naira cards not work for ChatGPT subscription?

OpenAI processes all payments in USD through Stripe, its payments processor. Stripe requires a card with a valid USD billing relationship. Nigerian naira debit cards issued by local banks are naira-denominated and do not meet this requirement, so they are declined at the payment step regardless of your card balance.

This is not a Grey-specific issue. Any naira card, whether issued by GTBank, Access, Zenith, UBA, First Bank, or any other Nigerian bank, will be declined. The only cards that work are dollar-denominated Visa or Mastercard cards, either physical (from a domiciliary account) or virtual (such as Grey’s virtual dollar card).

OpenAI also does not accept PayPal on the web checkout, gift cards, or prepaid cards without a matching billing address. Apple Pay and Google Pay work on mobile apps only, and only if your Apple or Google account is linked to a valid dollar payment method.

What you need before you subscribe

  • A Grey account (download the Grey app from the App Store or Google Play and complete signup)
  • A Grey virtual dollar card
  • A ChatGPT account, which is free to create at chatgpt.com

Step 1: Create a Grey account

If you already have a Grey account, skip to Step 2.

  1. Download the Grey app from the App Store (iOS) or Google Play (Android).
  2. Open the app and tap Sign Up.
  3. Enter your email address and create a password.
  4. Complete identity verification. Grey requires a valid government-issued ID to comply with financial regulations.
  5. Your account is active once verification is approved.

Step 2: Get a Grey virtual dollar card

If you already have a Grey virtual card, skip to Step 3.

  1. Open the Grey app and tap the Cards section on the dashboard.
  2. Select Create Virtual Card.
  3. Review the card creation fee. A $5 one-time creation fee will be charged. You need a minimum of $5 USD in your account before creating the card.
  4. Confirm, and your card is created immediately. Your card number, expiry date, and CVV appear in the Cards section of the app.

Your Grey virtual dollar card is a Visa card which pulls directly from your USD balance. It’s accepted anywhere Visa is supported internationally, including on ChatGPT and on every major USD-billed subscription platform.

Step 3: Fund your Grey USD balance

You need at least $20 in your USD balance to pay for ChatGPT Plus. The recommended method is to swap naira to USD inside the Grey app.

  1. Open the Grey app and tap “Convert”.
  2. Select NGN to USD and enter the amount. A 1% currency conversion fee (capped at $6) will apply.
  3. Review the rate and confirm. Your USD balance updates immediately.

You can also fund your USD balance via ACH transfer from a US bank account if you have one. The ACH receiving fee is 0.5% (minimum $2, maximum $10). For most Nigerian users, the in-app naira-to-USD swap is the most straightforward route.

Step 4: Subscribe to ChatGPT plus

On a desktop browser (recommended)

  • Go to chatgpt.com and log into your account.
  • Click your profile icon in the bottom-left corner.
  • Select Upgrade Plan.
  • Choose the Plus plan at $20 per month.
  • On the payment screen, enter your Grey virtual card number, expiry date, and CVV. Use the name on your Grey account and any valid billing address.
  • Click Subscribe. Your subscription activates immediately, and $20 is charged to your Grey card balance.

On Android

  • Open the ChatGPT app and go to Settings.
  • Select Upgrade to Plus.
  • Payment is processed through Google Play. Add your Grey virtual card as a payment method on Google Play before proceeding if you have not already done so.

On iOS

  • Open the ChatGPT app and tap the menu at the top.
  • Select Get Plus.
  • Payment goes through Apple’s in-app purchase system. Add your Grey card to your Apple ID payment methods first. You can do this in iPhone Settings under your Apple ID, then Payment and Shipping.

Payment methods: what works and what does not

Method Works? Notes
Grey virtual dollar card (Visa) Yes Recommended. Works on web, Android, and iOS.
Physical dollar card (domiciliary) Yes Works, but requires sourcing USD separately through your bank.
Nigerian naira debit card No OpenAI does not accept naira-denominated cards on any platform.
PayPal Not on web Works on iOS or Android only if PayPal is linked to your Apple or Google account.
Gift cards No OpenAI does not accept gift cards for ChatGPT subscriptions.
Annual billing No OpenAI currently offers monthly billing only for Plus and Pro.

How to manage your ChatGPT subscription

To view your subscription details, invoices, or cancel your plan, log into chatgpt.com, click your profile icon, select Settings, then Account.

To cancel, go to Manage My Subscription and select Cancel Plan. Cancelling stops the next renewal charge. Your Plus access continues until the end of the billing period you have already paid for.

If you subscribed through the iOS app, manage and cancel through iPhone Settings, then your Apple ID, then Subscriptions. The same applies to Android subscriptions managed through Google Play.

What happens at renewal?

ChatGPT Plus renews automatically every month on the same date you first subscribed. OpenAI charges your Grey card for $20 on that date.

If your Grey USD balance is below $20 at renewal time, the charge will fail, and your account will be downgraded to the free plan. You will need to top up your balance and resubscribe. To avoid this, set a reminder to check your Grey balance a few days before each renewal date, or keep a small buffer in your USD balance above the $20 threshold.

OpenAI sends a receipt by email for each billing cycle. If you see an unexpected charge, you can request a refund through OpenAI’s support. Refunds are typically processed within five to ten business days after approval.

Troubleshooting common issues

Payment declined at checkout

  • Check that your Grey USD balance has at least $20 available.
  • Confirm that the card number, expiry date, and CVV are entered correctly from the Grey app.
  • Make sure the billing name matches the name on your Grey account.
  • If using a billing address, use a consistent format. Grey’s registered address works.
  • If the issue persists, contact Grey support through the app.

Subscribed but account still shows “free plan”

  • Log out of ChatGPT on all devices and log back in using the exact email address you used to subscribe.
  • If you subscribed through Apple and used Hide My Email, find the private relay address in your Apple ID settings and use that to sign in.
  • On iOS or Android, go to Settings and tap Restore Purchases to sync your subscription.
  • If none of these work, contact OpenAI support with your receipt or the last four digits of the card charged.

Grey card not accepted on Google Play or Apple

  • On Google Play: go to pay.google.com, add your Grey card as a new payment method, then return to the ChatGPT app to subscribe.
  • On Apple: go to iPhone Settings, tap your name, then Payment and Shipping, and add your Grey card. Once added, it will be available for in-app purchases.

Other USD subscriptions you can pay with your Grey card

Once your Grey virtual dollar card is set up, it works across every major USD-billed subscription platform. You do not need to create a new card for each service.

Service What you can pay for
Adobe Creative Cloud Photoshop, Illustrator, Premiere Pro, Acrobat, the full Creative Cloud suite
Notion AI Notion Plus and AI add-on plans
Canva Pro Canva Pro monthly and annual plans
Spotify Premium Spotify individual and family plans billed in USD
Netflix Netflix plans billed in USD
AWS Amazon Web Services usage and reserved instance billing
Shopify Shopify Basic, Grow, and Advanced plans
Figma Figma Starter and Professional plans
GitHub Copilot GitHub Copilot Individual and Business plans
Midjourney Midjourney AI image generation plans

The smart way to manage dollar subscriptions from Nigeria

A Grey multi-currency account lets you hold a USD balance and spend it directly with a virtual dollar card across all of the above. One account, one card, no currency conversion at the point of payment on any USD-billed service. You convert naira to USD once, at Grey’s 1% rate, and spend from that balance across every subscription you run.

If you also send money internationally, Grey pays out to bank accounts and mobile money in Nigeria, India, Ghana, Kenya, the Philippines, and over 50 other destinations. You can manage everything from one app.

Open a Grey account, create your virtual dollar card, and have ChatGPT Plus running today at grey.co.

Frequently asked questions

Does ChatGPT Plus renew automatically?

Yes. OpenAI charges your card $20 on the same date each month. Make sure your Grey USD balance has at least $20 before each renewal date to avoid the payment failing and your account reverting to free.

Is there a transaction fee when ChatGPT charges my Grey card?

No fee on the card transaction itself. ChatGPT charges in USD, and your Grey card operates in USD, so no currency conversion happens at the point of payment.

What if my card balance is too low at renewal?

OpenAI will attempt the charge. If it fails, your account is downgraded to the free plan. Top up your Grey USD balance and re-subscribe. OpenAI does not automatically retry failed payments, so you need to go back into the subscription flow to reactivate.

Can I use one Grey card for multiple subscriptions?

Yes. Your Grey virtual card is a standard Visa card. Use it for ChatGPT Plus, Adobe, Notion, Canva, AWS, Shopify, and any other USD-billed service simultaneously. There is no limit on the number of services you can subscribe to from one card.

Does the 2% cross-border card fee apply to ChatGPT?

No. The 2% plus $0.50 cross-border card fee applies only when a merchant processes a transaction in a currency other than USD. ChatGPT Plus is billed in USD, so you pay no cross-border fee on this subscription. The same applies to any other service that charges in USD.

Can I get a refund if I cancel ChatGPT Plus?

OpenAI does not automatically refund unused time if you cancel mid-cycle. If you believe you were incorrectly charged, you can submit a refund request through OpenAI’s support pages. Refunds typically take five to ten business days to process after approval.’

Is there a ChatGPT Go plan below Plus?

Yes. OpenAI introduced ChatGPT Go at $7 per month (GBP equivalent on the UK pricing page). Go gives you more access than Free, including more messages and uploads, longer memory, and the ability to create and share custom GPTs. It does not include GPT-5.5 Thinking, deep research tools, or tasks. Go is a middle-ground option if $20 per month is too much. You can pay for it with your Grey card using the same process described in this guide.

Is ChatGPT data private on Plus?

OpenAI may use conversations to improve model performance and safety on all individual plans including Plus. You can opt out of having your data used for training at any time through Settings in your ChatGPT account. Business and Enterprise plans do not use data for training by default.

This article is for general information purposes only. Subscription pricing, plan features, and accepted payment methods are set by OpenAI and may change at any time. Always verify current pricing and terms at chatgpt.com before subscribing. Grey’s fees are accurate as of June 2026; verify current rates in the Grey app before transacting.

Spain digital nomad visa 2026: Complete application guide

•

•

2 min read

Spain’s digital nomad visa enables freelancers, entrepreneurs, and remote employees to legally base themselves in Spain while continuing to work for foreign employers or clients. Applicants must earn at least 200% of Spain’s minimum wage, approximately €2,646 per month, and must hold valid private health insurance throughout their stay. The programme reflects Spain’s broader strategy to position itself as a hub for international talent and digital innovation.

Spain's digital nomad visa was designed to attract global talent and strengthen Spain’s innovation ecosystem, and has has quickly become one of Europe’s most appealing residency pathways for remote professionals seeking sunshine, culture, and connectivity.

For remote workers, the appeal goes beyond legal residency. Spain offers a high quality of life, strong infrastructure, affordable living in many regions, and easy access to the wider Schengen area. This guide will walk you through the Spain digital nomad visa requirements, application process, costs, eligibility criteria, and key tips to help you successfully relocate and build a remote lifestyle in Spain.

Also read: A list of 50+ countries offering digital nomad visas

What is the Spain digital nomad visa?

The Spain Digital Nomad Visa, introduced under the Ley de Startups in January 2023, is a residence permit designed for non-EU/EEA remote workers and self-employed professionals who want to live in Spain while continuing to work for companies or clients based outside the country. The key idea behind the Spain Digital Nomad Visa is to allow global talent to legally reside in Spain without entering the local job market, making it ideal for freelancers, entrepreneurs, and remote employees.

The visa initially grants permission to live and work in Spain for one year, offering enough time to settle, explore the lifestyle, and establish a base in the country. Unlike many short-term permits, it is renewable and can be extended for up to five years in total, provided the applicant continues to meet the eligibility requirements, such as income level and valid health insurance.

Beyond its duration, one of the most attractive features of the Spain Digital Nomad Visa is that it can lead to longer-term residency. This makes it not just a temporary stay option, but a potential pathway for remote workers looking to build a more permanent life in Spain while enjoying its culture, climate, and quality of life.

Spain digital nomad visa requirements

  • Minimum income requirement: Applicants must demonstrate a net monthly income of at least 200% of Spain’s minimum wage (SMI), which is approximately €2,849 per month. This ensures you have sufficient financial stability to support yourself while living in Spain without relying on local employment.
  • Foreign work status: You must work primarily for employers or clients based outside Spain. The visa is designed for remote workers whose income is generated abroad. However, freelancers are allowed limited local work, provided income from Spanish clients does not exceed 20% of total earnings.
  • Professional experience: Applicants must show at least three years of professional experience in their current field. This can be proven through work history, contracts, qualifications, or professional references that demonstrate consistent expertise in remote or specialised work.
  • Health insurance: You must have comprehensive private health insurance authorised to operate in Spain. The policy must provide full coverage within the country and include a minimum medical coverage of €30,000, including emergency care and hospital treatment.
  • Criminal record requirement: Applicants must provide a clean criminal record certificate from their country of residence for the past five years, confirming good conduct and eligibility for long-term stay in Spain under immigration rules.

Also read: How to apply for a digital nomad visa in Spain

Spain digital nomad required documents

  • Valid passport: You must hold a valid passport with sufficient validity beyond your intended stay in Spain. It should also have at least two blank pages for visa stamps and entry/exit records. The passport must be in good condition, as damaged or incomplete documents may lead to delays or rejection during processing.
  • Proof of income: Applicants must provide evidence of stable earnings through payslips, bank statements, tax returns, client contracts, or an employer letter confirming remote work arrangements. This documentation must demonstrate consistent income that meets Spain’s minimum requirement for digital nomad applicants and proves financial independence while living in the country.
  • Health insurance certificate: You are required to have private health insurance valid in Spain. The policy must cover medical expenses, emergencies, and hospitalisation during your stay. It should provide sufficient coverage to meet immigration standards and remain valid for the full duration of your visa period without interruption.
  • Criminal background check: A clean criminal record certificate is required, typically covering the past five years. This document must be apostilled and officially translated where necessary. It confirms good conduct and ensures eligibility for long-term residence under Spain’s immigration rules for non-EU remote workers.
  • Accommodation proof: Applicants must submit a completed visa application form, passport-sized photographs, and proof of accommodation in Spain, such as a rental agreement or property booking. In addition, professional qualifications or credentials may be required to demonstrate expertise in your field and support your application approval.

Also read: The best digital nomad jobs to earn from anywhere in Spain

How to apply: step-by-step

Route A: Apply from your home country (1-year visa)

  1. Book an appointment at your nearest Spanish embassy or consulate using the Spain Ministry of Foreign Affairs website to secure a submission date.
  2. Attend the appointment in person with all required documents, including your passport, completed application form, proof of income, insurance, and payment of the visa fee.
  3. Wait for processing, which typically takes 10 to 45 days. If approved, your passport will receive a visa sticker allowing entry into Spain.

Route B: Apply from within Spain (3-year residence permit)

  1. Enter Spain legally, usually on a standard Schengen tourist entry, ensuring you comply with permitted stay rules.
  2. Prepare and submit your application through Spain’s official online immigration platform under the Large Companies Unit (UGE), uploading all required documents digitally.
  3. Await approval of your residence permit, which can grant up to three years of legal stay, allowing you to live and work remotely in Spain.

Costs, duration, and renewal for Spain digital nomad visa

The Spain Digital Nomad Visa includes specific income and administrative costs that applicants must meet before approval. The minimum income requirement is €2,849 per month (approximately €34,188 per year) for a single applicant. Additional dependents increase the threshold, with around €1,069 required for a spouse and €357 per child. Application-related fees are relatively modest, with consular or residence permit charges ranging between €80 and €90. You will also need to pay for your NIE (foreigner number) and TIE (residence card), which together cost approximately €25.

In terms of duration, the length of stay depends on where you apply. If you apply from outside Spain through a consulate, you are initially granted a 1-year visa, which is later converted into a 3-year residence permit upon arrival in Spain. If you apply from within Spain after entering legally, you are typically granted a 3-year residence permit directly, offering longer initial stability for remote workers.

For taxation and renewal, digital nomads staying more than 183 days per year may become tax residents. However, eligible applicants can benefit from the “Beckham Law” regime, which allows qualifying remote workers to pay a flat 24% tax rate on Spanish income up to €600,000 annually instead of standard progressive rates. The visa can be renewed if the requirements continue to be met.

__wf_reserved_inherit

Frequently asked questions

Is the Spain Digital Nomad Visa worth it for remote workers?

Yes, it is highly valuable for remote workers seeking a legal base in Europe. It offers access to Spain’s lifestyle, strong infrastructure, and Schengen travel freedom. Beyond convenience, it provides long-term stability, potential residency, and tax advantages like the Beckham Law, making it one of Europe’s most attractive digital nomad programmes for global professionals.

Can freelancers easily qualify for the Spain Digital Nomad Visa?

Freelancers can qualify, but they must meet stricter requirements than employees. You need proof of consistent foreign clients, contracts, and income stability above €2,849 monthly. Additionally, only up to 20% of income can come from Spanish clients. Strong documentation, tax records, and professional history significantly improve approval chances for self-employed applicants.

What happens if my income drops after approval?

If your income falls below the required threshold after approval, it may affect renewal eligibility. Spanish authorities expect continuous compliance with financial requirements. While temporary fluctuations may not immediately cancel your visa, consistent underperformance can lead to refusal of renewal or residency extension, making stable income essential for long-term stay security.

Does the Spain Digital Nomad Visa lead to permanent residency?

Yes, it can lead to long-term residency in Spain if you maintain legal status and renew consistently. After five years of continuous residence, you may become eligible for permanent residency. This makes the visa not just a temporary solution but a structured pathway toward settling long-term in Spain.

Can I switch jobs while holding the visa?

Yes, you can change employers or clients as long as you continue working remotely for non-Spanish companies and meet income requirements. However, any new employment arrangement must remain compliant with visa rules. It is important to ensure documentation is updated so your legal status in Spain remains valid and uninterrupted.

Living as a nomad in Spain becomes easier with a multicurrency account, holding EUR, GBP and USD in one place. Grey is ideal for you as you get excellent exchange rates, converting at the best time and avoiding unnecessary losses on currency swaps. It keeps your money flexible while you focus on work, travel and settling into life abroad. Sign up to get started and stay financially ready from day one in Spain.

Receive US payroll payments outside the US

•

•

2 min read

How do US employers make domestic US payroll payments?

The general process is to enter a US address, provide a US routing number and account number, and the system will process direct deposit smoothly. Usually, everyone gets paid on schedule.

The dynamics change when someone the employer hires someone from outside the US. Their payroll system requires US banking details that this person doesn’t have. Finance could suggest international wire transfers, which trigger manual processing, about $20 sending fees, week-long delays, and significant deductions from intermediary banks before the money arrives.

In this article, I explain how US payroll systems work, why they create problems for international workers, your actual payment options, and how to receive a US salary efficiently regardless of where you live.

How does US payroll actually work?

Most US companies don’t process payroll manually, instead they use platforms that automate salary calculations, tax withholding, compliance reporting, and payment distribution. These platforms are designed around US domestic assumptions:

  • Employees have US bank accounts with routing and account numbers
  • Employees live in states with specific tax codes
  • Employees fall under US employment law and tax jurisdiction.

The standard payment method is direct deposit through the Automated Clearing House (ACH) network. On payday, the payroll platform initiates ACH transfers from the company’s bank account to each employee’s account. Money moves through the ACH network and typically clears within one to three business days.

ACH is fundamentally domestic. It requires US routing numbers that identify specific US banks and US account numbers that identify specific customers at those banks. International bank accounts don’t participate in the ACH network.

A Nigerian bank account, for example, has an account number and a sort code that follow Nigerian banking standards. An Indian bank account uses IFSC codes and account numbers in the Indian format. These don’t translate into the nine-digit routing numbers and account numbers that US payroll systems expect.

When you don’t have US banking details, several complications arise immediately. The payroll system flags your profile as incomplete or problematic because required fields are empty. Some companies refuse to hire international workers specifically because they find payment too complicated to navigate.

Companies willing to pay internationally face additional challenges. International wire transfers require manual processing outside the normal automated payroll flow. Someone in finance usually must log into the banking platform, enter wire transfer details manually, obtain approval for international payments (often requiring senior authorisation that domestic payroll doesn’t), and initiate the transfer separately from the rest of payroll. Each wire costs the company about $20 in sending fees.

Beyond logistics, there’s the complexity of tax withholding. US payroll systems automatically withhold federal income tax, Social Security, Medicare, and state taxes from employee paychecks. These withholdings apply to US tax residents.

If you’re not a US tax resident or you’re not a US citizen or green card holder, these withholdings shouldn’t apply to you. But payroll systems assume everyone is subject to US tax withholding. Configuring the system to pay someone without US tax withholding requires manual intervention and understanding of tax treaty provisions and IRS regulations.

Then there’s the employment classification question. If you’re working full-time remotely from outside the US, the company needs to determine whether you’re a US employee working abroad temporarily. Are you a foreign employee of a foreign subsidiary? Are you actually an independent contractor despite operational aspects that appear to be employment?

Each classification has different tax implications, different legal obligations, and different payment processes. Many US companies, especially startups and small businesses, aren’t equipped to navigate this. They want to hire talented people regardless of location, but their finance and legal advisors raise compliance concerns that feel insurmountable.

This is why understanding the mechanics matters.

Also read: How consultants structure international client payments

Employment classification: Employee vs contractor

How you’re classified legally determines how payment works, what tax obligations apply, and what documentation both you and the company need.

If you’re classified as an employee, the US company has specific legal obligations. They must provide benefits as required by law if you’re a US-based employee, though obligations differ for foreign employees. They must ensure compliance with employment laws both in the US (for aspects of the employment relationship governed by US law) and potentially in your country of residence.

For non-US residents working remotely outside the US, employment can be complex. Many countries require foreign companies employing local residents to register as employers, withhold local income taxes and social contributions, and comply with local employment standards.

This is why many US companies use Employer of Record services for international employees. The EOR becomes your legal employer in your country, handling local compliance whilst you work operationally for the US company.

Independent contractor classification simplifies payment significantly. As a contractor, you’re self-employed and responsible for your own taxes in your country. The US company has no tax withholding obligations (as long as you’re not a US tax resident). There are no employment law obligations in your country because you’re not an employee.

Payment works the same way as paying any other vendor. You submit invoices, and the company pays them. You don’t receive employee benefits like health insurance or paid time off, but you also have more flexibility in how you structure your work.

Now if you’re properly classified as an employee, the company needs to run you through payroll, which requires addressing all the payment and tax complexities discussed earlier. They may need to establish legal presence in your country by registering an entity or by using an expensive Employer of Record (EOR) service. Payment comes as regular salary on the company’s normal payroll schedule, and you may be subject to local tax withholding depending on how the company structures your employment.

If you’re properly classified as a contractor, you invoice the company for completed work. They pay your invoices the same way they’d pay any vendor. There’s no payroll involvement and no company obligation to withhold taxes. You’re fully responsible for tax compliance in your country. Payment methods are flexible, and the company can use whatever method works best: wire transfer, payment platforms, or modern cross-border payment infrastructure.

The practical reality for most remote international workers is that many who join US startups are technically contractors, even if the company internally calls them “employees.” The company doesn’t want to navigate foreign employment law or establish legal entities in your country, so they structure the relationship as independent contracting, whilst treating you like a team member operationally.

This works as long as you’re comfortable with contractor classification, you handle tax obligations properly in your country, and the company doesn’t exert so much control over your work that you’re actually a misclassified employee. Misclassification creates legal risk that can result in penalties, back taxes, and employment law violations.

Before accepting any position, clarify whether you’re being hired as an employee or contractor. If you’re an employee, understand how the company will handle international employment compliance. If you’re a contractor, understand the invoicing schedule, payment terms, and your tax obligations.

Also read: Global bank accounts vs offshore accounts: what’s the difference

The traditional methods that US companies use to pay international workers and their problems

When companies decide to pay workers outside the US, they typically choose from several established approaches. Each has significant limitations.

International wire transfers via SWIFT are the most common default. The company initiates a wire from their US bank to your bank account in your country. Money passes through the SWIFT network, typically involving one or more intermediary correspondent banks that facilitate cross-border transfers.

The problems are cost and speed. The company pays $30-50 per wire in sending fees. Intermediary banks deduct $20-40 combined for processing the transfer. Your local bank charges a receiving fee of $15-25. Then comes currency conversion. If your account is in local currency, your bank converts the USD at a rate that includes a 3-5% markup over the mid-market rate.

On a $5,000 monthly payment, you can lose up to $250-400 to fees and conversion. The transfer takes three to five business days, sometimes longer, depending on the countries involved and any compliance holds. For the company, this is a manual process. Someone in finance must initiate each wire separately outside the normal payroll system. This doesn’t scale when paying multiple international workers monthly.

Employer of Record (EOR) services like Deel, Remote, and Oyster solve the compliance problem by becoming your legal employer in your country. They handle local tax withholding, benefits administration where required, employment law compliance, and regulatory reporting. The US company pays the EOR, and the EOR pays you in local currency through local banking.

From a compliance perspective, EORs are excellent. They handle complexity that the US company doesn’t want to navigate. You get true employee status with proper local compliance. The relationship is clear and legally sound.

The problems are cost and the employment relationship structure. EOR services charge companies 15–30% above your salary in fees. On a $100,000 salary, the company pays $115,000–130,000 total. Many startups and small companies can’t afford this premium, especially when hiring multiple international workers.

From your perspective, you’re employed by the EOR, not the US company. This can affect equity grants, promotion paths, and a sense of belonging to the team. You’re legally an employee of Deel or Remote, working for the US company through a services agreement. For some people, this matters. For others, it’s irrelevant as long as payment and compliance work smoothly.

Cryptocurrency and stablecoin payments are experimental. Some companies pay contractors in USDC or other stablecoins. Transfers are fast and cheap, but tax reporting is complex in most countries, not all workers are comfortable with crypto, regulatory frameworks are uncertain, and most professional payroll systems don’t support cryptocurrency payments. This remains a niche solution for specific situations, not a mainstream payroll approach.

The pattern across these traditional methods is that they’re either expensive (losing 5–10% to fees), slow (taking a week for payment to clear), administratively burdensome for companies (manual processes outside normal payroll), or legally complex (requiring entity formation or expensive EOR services).

Also read: Alternatives to domiciliary accounts in Nigeria

What you actually need to receive US payroll payments

Strip away complexity and focus on what actually needs to happen for payment to work.

For the company’s payroll system to process your payment smoothly, they need banking details that their system recognises. Most US payroll platforms expect US routing and account numbers. If you can provide those, payment works exactly like paying any other employee. The system validates the routing number, confirms the account number, and queues the ACH transfer for the next payroll run.

For payment to reach you efficiently, you need to receive USD without incurring significant fees or currency conversion costs. Payment should arrive within reasonable timeframes, 1 to 3 business days, not 7. You should be able to convert USD to your local currency at transparent rates when you choose, not when a bank forces immediate conversion.

For tax compliance, if you’re a contractor, you need to provide the company with Form W-8BEN certifying that you’re not a US taxpayer. This prevents them from withholding 30% of your payment for US taxes. If you’re an employee, tax withholding depends on your residency status and the company’s employment structure. This typically requires professional tax advice specific to your situation.

For legal compliance, the company needs to properly classify you as an employee or a contractor. If you’re a contractor, they need a clear contract specifying deliverables, payment terms, and intellectual property ownership. If you’re an employee, they need to address employment law compliance in your country, either through EOR services or by establishing legal presence themselves.

For documentation and record-keeping, you need transaction records for your country's tax filing. The company needs records for their accounting and potential audits.

What solves most of these requirements simultaneously is a USD account with US banking details that you provide to the company’s payroll system. This makes you payable through their normal automated process without requiring special international payment procedures.

The account should provide legitimate US routing and account numbers that payroll systems accept, allow you to hold USD without forced immediate conversion, offer transparent and affordable conversion to your local currency when needed, and generate proper transaction records suitable for tax documentation.

Also read: Best dollar account apps in Nigeria compared

How USD accounts enable US payroll reception outside the US

Modern financial infrastructure has developed solutions specifically designed to address this problem.

Fintech platforms partner with US banks through what’s called banking-as-a-service arrangements. The platforms hold financial services licenses in regulated jurisdictions for example, FINTRAC in Canada, FinCEN in the US and FCA in the UK. These partnerships enable the platform to provide US bank account details to customers worldwide without requiring them to establish direct relationships with US banks.

When you sign up with one of these platforms, you provide identification documents and proof of address from your country. Once your KYC is completed and verified, you receive a US routing number that identifies the platform’s partner bank and a US account number unique to you.

These details function exactly like traditional US bank account details for receiving ACH payments. When your US employer’s HR team asks for banking information, you provide your routing and account number. From their perspective, you’re providing standard domestic banking details. The payroll system validates the routing number, confirms it’s a legitimate US bank, and saves your information alongside other employees.

On payday, the payroll platform initiates an ACH transfer to your routing and account number. Payment enters the US ACH network, the same system used for all domestic payroll. Payment clears in one to two business days, sometimes same-day for instant payroll platforms. Funds are credited to your USD balance held by the fintech platform, segregated in accounts at the partner bank.

You can then hold the USD without converting it, convert to your local currency at transparent rates (typically 1–2% over mid-market rate, significantly better than the 3–5% markup traditional banks apply), withdraw to your local bank account in local currency, or spend directly using a USD debit card if the platform provides one.

This works for both you and your employer because it requires no changes to their payroll process, involves no special international payment procedures, creates no additional fees beyond normal payroll costs, eliminates manual wire transfers each pay period, and produces clean payroll records exactly like any other employee.

For you, it means receiving the full salary amount via ACH with no wire fees or intermediary bank deductions, control over currency conversion timing, transparent exchange rates when you do convert, proper documentation for tax purposes, and fast payment clearing in one to two days instead of seven to ten.

The financial difference is significant. With a traditional international wire transfer on $5,000 monthly salary, wire transfer fees cost $40, intermediary banks deduct $30, your bank charges $20 receiving fee, and currency conversion markup at 3% costs $150. You receive approximately $4,760. You’ve lost $240 or 4.8% of your salary.

When a USD account receives an ACH payment, there are no receiving fees. You hold $5,000 in your USD balance. When you convert at a 1.5% margin, the conversion costs $75. You receive approximately $4,925 in local currency. You’ve lost $75 or 1.5%. The savings are $165 per paycheck.

On a $60,000 annual salary paid bi-weekly over 26 paychecks, this saves approximately $4,290 annually. That’s meaningful money that was simply disappearing into banking infrastructure because payment methods weren’t designed for international work.

The regulatory framework that makes this legitimate and safe involves fintech platforms operating under financial services regulations in their jurisdictions. They must maintain licenses, comply with anti-money laundering requirements, implement know-your-customer procedures, and submit to regulatory oversight. Partner banks are fully licensed US institutions, typically FDIC-insured. Your funds are held in segregated accounts at these banks, separated from the platform’s operational funds.

You remain fully responsible for tax compliance in your country of residence. The USD account is a payment reception infrastructure, not a tax avoidance mechanism. All income must be declared and taxed according to your country’s tax laws.

Also read: How US startups pay remote workers outside the US

Grey: Multi-currency accounts for receiving US payroll

Grey provides USD, EUR, and GBP business accounts designed specifically for professionals receiving international payments, including US payroll and contractor income.

When you open a Grey account, you receive a USD account with US routing and account numbers. These details function exactly like traditional US bank accounts for receiving ACH payments from payroll systems.

The setup process involves signing up, providing identification and proof of address from your country, and completing the verification, which typically takes one to three business days. You then receive your USD account details, including routing number, account number, and bank name.

When providing details to your employer, you enter your Grey USD routing and account number in their payroll system. From the company’s perspective, you’re providing standard US banking details. Their payroll platform validates and accepts the routing number without any indication that this is anything other than a normal US bank account. No special international payment setup is required.

On payday, the company’s payroll system initiates an ACH transfer. Payment clears through the US banking system in one to two business days. Grey charges a 0.8% fee, with a minimum charge of $2 and a maximum charge of $10. For example, a $5,000 deposit will cost $10, while a €500 deposit will cost €4

When you need local currency, you convert only the amount required. Exchange rates are shown before you confirm, typically 1-2% over mid-market rate, which is significantly more affordable than traditional bank markups of 3-5%.

You control conversion timing. If USD to local currency rates are unfavourable, you can wait. If rates improve, you can convert more. This control is impossible with traditional wire transfers, where conversion occurs automatically at the rate that applies when the wire arrives.

Withdrawals to your local bank account process in one to three business days, depending on your country. You transfer converted local currency for local expenses like rent, utilities, and purchases that require local currency.

Beyond USD, because Grey provides EUR and GBP accounts with local banking details, if you work for multiple companies or do freelance work alongside your main employment, you can receive a US salary in your USD account, European client payments in your EUR account, and UK client payments in your GBP account, managing all currencies from one platform.

Grey is regulated by FINTRAC in Canada and FinCEN in the US. Your funds are held in segregated accounts at partner banks, which are FDIC-insured for USD balances. You remain responsible for tax compliance in your country of residence. Grey provides the infrastructure and documentation you need, but doesn’t file taxes on your behalf or provide tax advice.

This infrastructure works particularly well for remote workers receiving a US salary as contractors or employees, professionals working for multiple US companies or clients simultaneously, freelancers supplementing full-time income with contract work, and anyone receiving regular USD income who wants to minimise conversion losses and maintain control over currency management.

Global talent, global payment

Geographic location has become irrelevant for many professional roles. Talented developers, designers, marketers, and other professionals work for US companies from anywhere in the world, contribute to US startups meaningfully, and earn competitive salaries.

Payment infrastructure has finally evolved to match this reality. You don’t need to relocate to the US, form US business entities, or navigate expensive EOR services to receive US payroll efficiently. Modern financial infrastructure solves the payment problem cleanly.

With proper setup, a USD account with US banking details, a clear employment classification as an employee or contractor, and tax compliance handled correctly in your country, receiving a US salary outside the US is straightforward. Your location shouldn’t limit your opportunities. The infrastructure now exists to support genuinely global work with seamless payment.

Open your grey account or download the app to receive your US salary without paying wire fees, incurring poor exchange rates, or experiencing payment delays. Start receiving your paycheck the same way US-based employees do, with full control over your money and transparent costs at every step.

Frequently asked questions

Can I receive US payroll without a US bank account?

Yes, but it’s inefficient and expensive. Most US payroll systems use ACH direct deposit, which requires US routing and account numbers. Without these, companies must send international wire transfers, which cost them and you significant fees and poor exchange rates. Modern USD account platforms provide US banking details without requiring US residency.

Do I need to be a US citizen to receive a U.S. salary?

No. US companies can hire and pay non-US citizens working remotely from outside the US. Employment classification and tax implications vary based on your residency status and where you perform work, but citizenship isn’t required.

Will the US company withhold taxes from my salary?

It depends on your classification and tax residency. If you’re a contractor and not a US tax resident, complete Form W-8BEN to prevent 30% withholding. If you’re an employee, tax withholding depends on how the company structures your employment. Consult tax professionals for your specific situation.

What’s the difference between contractor and employee classification?

Contractors are self-employed, invoice for services, handle their own taxes, receive no benefits, and have work flexibility. Employees are on the company’s payroll, receive regular salary, may get benefits, and have employment protections. Classification depends on the nature of the working relationship, not just on contract language.

How long does US payroll take to arrive via ACH?

ACH transfers typically clear within 1-2 business days of payday. Some modern payroll platforms offer same-day ACH. This is substantially faster than international wire transfers, which take 5-10 business days.

What is Form W-8BEN, and why is it important?

Form W-8BEN certifies you’re not a US taxpayer. Without it, US companies must withhold 30% of contractor payments for US taxes. Completing W-8BEN prevents this withholding and confirms you’ll handle taxes in your country of residence.

How much will I lose to currency conversion?

Traditional bank wire transfers typically cost 5-7% total in fees and poor exchange rates. USD accounts with transparent conversion rates cost approximately 1–2% total. On a $60,000 annual salary, this difference saves $3,000–3,600 annually.

Can my employer pay me in my local currency?

Some employers offer this, but it’s usually worse financially. They convert USD to your currency at unfavourable corporate exchange rates, often with a 4–6% markup. Receiving USD and handling conversion yourself using competitive rates is typically better.

What if the company says they can’t pay internationally?

They likely mean their payroll system only supports domestic ACH. Provide USD account details (routing and account number) from a platform like Grey Business. From their perspective, you’re providing standard US banking information that works with existing systems.

‍

Grey Business vs Grey personal banking

•

•

2 min read

“Should I be using Grey Business, or is my personal Grey account enough?”

It’s a common question, especially once your income starts growing.

At the beginning, everything feels simple. You get paid and you withdraw your money easily. But as your work evolves, whether that’s taking on more clients, earning from multiple platforms, or starting a company, the way you manage money needs to evolve too.

Grey offers two account types for this exact reason: Grey Personal and Grey Business. They are not better or worse than each other. They are built for different stages of your earning process.

This guide breaks down the differences, including fees, features, and when to switch, so you can choose the right setup without second-guessing.

‍Also read: Receiving foreign income as a solo founder

What is a Grey personal account?

A Grey personal account is designed for individuals who receive and manage international payments.

If you are a freelancer, remote worker, or creator earning from global clients or platforms, this is the account you are expected to use.

With a personal account, you can open USD, GBP, and EUR balances with real banking details. This allows clients to pay you as if they were making a local transfer in their own country. Instead of receiving an expensive international wire, you receive money through local rails like ACH, SEPA, and FPS.

Once the money arrives, you can hold it in foreign currency, convert it when the rate works for you, or withdraw it to your local bank account. You can also spend directly using your Grey virtual card without needing to manually move funds around.

The focus here is simplicity. You are managing your own income, and the account is designed to make that as flexible as possible.

What fees does Grey Personal charge?

Understanding fees is where most people get confused, so here’s how it actually works.

When you receive money through ACH, SEPA, or FPS, Grey charges a 0.8% fee, with a minimum of $2, €2, or £2 and a maximum of $10, €10, or £10. This means larger payments become proportionally cheaper because of the cap.

Currency conversion depends on the currency pair. Some routes are free, while others range from 0.5% to 1%. For certain major pairs, the fee is capped at $6. The important detail is that Grey shows the rate before you confirm, so there are no hidden charges after the fact.

Withdrawals vary depending on the country, but for major currencies like EUR and GBP, the fee is typically 0.5%, with a minimum and maximum cap. Other corridors may use fixed fees instead.

For less common deposit methods like Fedwire, BACS, or CHAPS, fixed fees apply. These are generally used less often, since local rails like ACH or FPS are cheaper.

Read more: Grey charges explained: what every transaction costs

What is Grey Business?

Grey Business is designed for companies rather than individuals.

If you are running a registered business, working under a company name, or managing revenue that belongs to a business entity, this is the account structure you need.

Unlike a personal account, a Grey Business account is built for your company. This means you can receive payments on behalf of the business, manage funds at a company level, and keep financial records properly organised for accounting and compliance.

The functionality goes beyond receiving payments. Grey Business allows you to manage team access, assign roles, and give multiple people control over finances without sharing a single login.

You can also pay contractors globally, send payments in local currencies, and handle bulk payouts by uploading recipient details. This becomes important as soon as you are working with a team or scaling operations.

The goal of Grey Business is not just to receive money, but to structure how your business handles it.

What fees does Grey Business charge?

Grey Business follows the same core pricing model as personal accounts.

Receiving payments still comes with the 0.8% fee capped at $10. Conversion fees follow the same tiered structure, and withdrawals depend on the payout country.

The difference is not in lower fees, but in what the account enables.

With Grey Business, you are paying for structure, team management, and the ability to operate at scale without mixing personal and company finances.

Grey Personal vs Grey Business: what is the difference?

The main difference comes down to ownership.

A personal account is for money that belongs to you as an individual. A business account is for money that belongs to a company.

Everything else builds from that.

Grey Personal is simpler, quicker to set up, and designed for individuals managing their own income. Grey Business requires verification of a registered company but provides tools to manage payments, teams, and operations effectively.

If you are working alone and getting paid for your own work, a personal account is enough. If you are invoicing as a company, hiring people, or managing shared finances, you need a business account.

‍Also read: Can non-residents open a US bank account online in 2026?

When should you use Grey for personal use?

You should use a personal account if you are earning in your own name.

This includes freelancers, remote employees, and creators earning from platforms like YouTube, TikTok, or Upwork. At this stage, your income is still personal, even if it comes from multiple sources.

A personal account keeps things simple.

When should you use Grey Business?

You should use Grey Business when your income is no longer just yours.

If you have registered a company, invoice under a business name, or manage revenue that belongs to a business entity, a personal account is no longer the right structure.

This is especially important if you are paying contractors, working with a team, or preparing financial records for accounting and tax purposes.

Can you have both Grey for personal use and Grey Business?

Yes, and in many cases, this is the best setup.

If you run a company but also earn income personally, keeping both accounts separate helps avoid confusion. Your business transactions stay within the business account, while your personal income remains separate.

This makes accounting cleaner and reduces the risk of mixing funds.

Grey for personal use vs Grey Business: key differences

Feature Grey Personal Grey Business
Who it’s for Individuals (freelancers, creators, remote workers) Registered companies, startups, agencies
Account ownership Personal use Business entity
Currencies supported USD, GBP, EUR, USDC USD, USDC (business-focused)
Receiving payments Yes (ACH, SEPA, FPS) Yes (for business transactions)
Team access No Yes (multi-user access with roles)
Bulk payouts No Yes (CSV uploads supported)
Virtual cards Yes (for personal use) Yes (multiple cards for teams, tools, ads)
Best use case Getting paid individually Managing company finances and scaling operations
Setup process Fast (ID verification) More detailed (business verification required)

So, which Grey account should you choose?

Most people overthink this decision, but it comes down to one simple question:

Who does the money belong to?

If you’re earning as an individual, whether that’s freelancing, remote work, or content creation, a Grey Personal account is the right fit. It keeps things simple and flexible while giving you full access to international payments.

If you’re operating as a registered business, invoicing clients under a company name, or managing team payments, Grey Business is the structure you need. It helps you separate finances properly and handle growth without creating confusion later.

If you’re in between, which is common, you can start with a personal account and move to business when your setup requires it. Many users also keep both, using one for personal income and the other for company operations.

The goal isn’t to pick the most advanced option. It’s to choose the one that fits how you earn today and won’t slow you down as you grow.

Getting started with Grey

Opening a Grey Personal account takes just a few minutes. You can sign up in under 5 minutes, and once your identity is verified, you can usually start receiving payments the same day.

Opening Grey Business takes a bit longer because it involves business verification. You’ll need to submit your company registration and ownership details, and approval typically takes 1 to 3 business days, depending on the documents provided. This ensures your account is set up correctly from the start.

Frequently asked questions

What is the difference between Grey for persona use and Grey Business?

Grey Personal is for individuals receiving and managing their own income, such as freelancers, creators, and remote workers. Grey Business is for registered companies that need to manage business revenue, pay contractors, and give team members access to finances.

The main difference is ownership. Personal accounts are for your money. Business accounts are for company funds.

Can I use a Grey Personal account for business payments?

You can use a personal account while you are freelancing under your own name. However, once you register a company or start invoicing under a business name, it is better to switch to Grey Business.

Using a personal account for business transactions can create confusion with accounting, taxes, and financial tracking.

Does Grey Business have different fees from Grey Personal?

Grey Business follows the same core pricing structure as personal accounts. Receiving fees are typically 0.8% with a cap, and conversion fees depend on the currency pair.

The main difference is not pricing, but functionality. Grey Business adds tools for team access, bulk payments, and structured financial management.

Can I have both a Grey Personal and Grey Business account?

Yes. Many users have both accounts.

This is useful if you have personal income, such as freelance work or creator earnings, and also run a registered business. Keeping them separate makes accounting cleaner and easier to manage.

When should I switch from Grey Personal to Grey Business?

You should consider switching when your income becomes business revenue instead of personal income.

This usually happens when you register a company, start invoicing clients as a business, hire contractors, or need proper financial records for tax and reporting purposes.

What documents are required to open a Grey Business account?

To open a Grey Business account, you will need to provide company registration documents, ownership details, and verification information about the business.

The process is more detailed than a personal account because it involves verifying a legal entity.

Is Grey Personal enough for freelancers and creators?

Yes. For most freelancers, remote workers, and creators, Grey Personal is more than enough.

It allows you to receive international payments, hold foreign currency, convert when needed, and withdraw locally without needing business-level setup.

Can I receive USD, GBP, and EUR with both accounts?

Yes. Both Grey Personal and Grey Business support multi-currency functionality.

Personal accounts focus on individual income, while business accounts structure those same capabilities for company use.

Which Grey account is better?

Neither is better. They are designed for different use cases.

Grey Personal is better for individuals managing their own income. Grey Business is better for companies managing business finances and scaling operations.

Ready to get started?

Open your Grey Personal account to start receiving international payments as an individual, or set up Grey Business if you’re managing company finances and need a more structured setup.

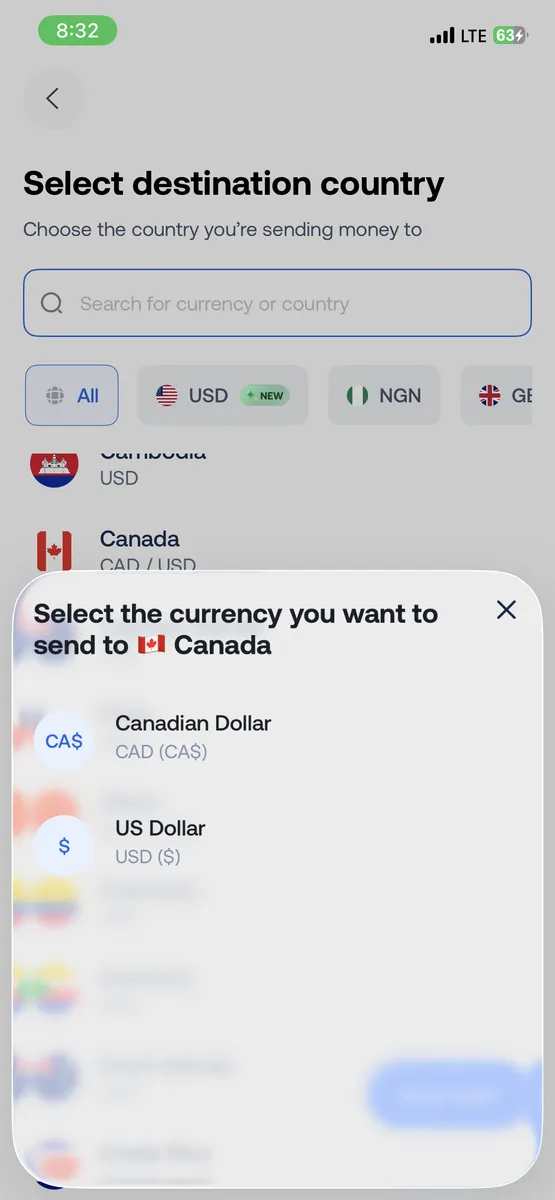
Send Canadian dollars with Grey

•

•

2 min read

Everything we do at Grey is aimed at making it easier for you to make global payments.

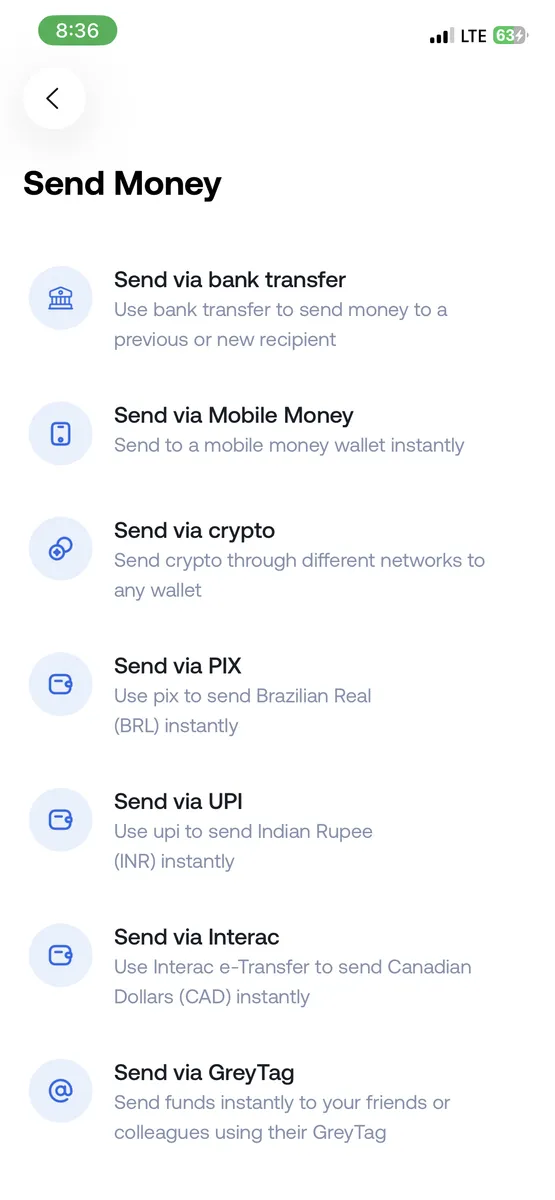
We’re excited to announce that Grey now supports Canadian dollars (CAD) payments, which means you can send money to Canada directly from your Grey account via Interac e-Transfer.

You can pay freelancers, send money to family, or make cross-border payments to Canadian businesses right from your phone.

What exactly does this mean for you?

Send money to Canada easily‍

Because we’ve integrated with Interac e-Transfer, you can send money directly to any Canadian bank account. You’ll only pay a flat $3 fee, regardless of how much you’re sending.

Expand your global operations with less friction

‍CAD joins our growing list of supported currencies, giving you more flexibility when operating across borders.

No additional setup required

‍It’s the same Grey account you already have. Sending CAD works exactly like sending any other currency through Grey. There’s no confusion about exchange rates and no need for the recipients to sign up for anything.

How does sending CAD work with Grey?

We’ve kept things simple. Here’s how to send Canadian Dollars using Grey:

  1. Log in to your Grey account.
    ‍
  2. Click “Send”.
Send Canadian dollars with Grey

‍

2. On the “Send Money” tab, select “Send via Interac”.

Send Canadian dollars with Grey

‍

3. Select Canada as the destination and choose CAD as the currency.

Send Canadian dollars with Grey

4. Enter the recipient’s details and confirm the transfer.

Send Canadian dollars with Grey

Enjoy global payments with Grey

At Grey, our mission is to make globalisation work for everyone. Supporting payments in Canadian Dollars takes us closer towards achieving that goal.

We want more freelancers, businesses, and remote workers to operate internationally without friction.

More currencies, more countries, and more ways to manage money across borders, that’s where we’re headed.

Open a free Grey account today, or download the app to get started.

‍

How US startups pay remote workers outside the US

•

•

2 min read

Remote work has changed how US startups build their teams. It’s no longer unusual for a founder in the United States to work daily with designers, developers, consultants, and marketers living thousands of miles away. Slack messages replace office conversations, video calls stand in for physical meetings, and shared documents keep projects moving. Talent is no longer limited by geography, and startups are more comfortable hiring skilled professionals regardless of where they live.

But when the work is done, a simple question follows: how do payments actually reach these remote workers outside the US? For many startups, paying global talent has become part of their everyday operations. This article examines how US startups handle payments to remote workers around the world and the practical ways those professionals receive their earnings.

Also read: How freelancers in the US get paid by international clients

Challenges US startups face when sending money abroad

Sending money to remote workers outside the US comes with challenges. Understanding them helps startups pay reliably, build trust, and value global talent.

Transaction fees‍

Wire transfers often come with high fees from intermediary banks and the recipient’s bank. As a US startup, it’s important to anticipate these costs so your remote workers get the full payment they expect. Being aware of fees ahead of time helps you plan better, maintain transparency, and show your team that their work is valued.

Payment delays

‍Sending money to emerging markets can take longer than expected, even with the right platforms. Delays can frustrate your remote team and disrupt workflow. By anticipating timing challenges and keeping your workers informed, you demonstrate reliability and professionalism, ensuring your remote consultants feel respected and confident that their efforts will be rewarded on time.

Platform restrictions

‍Not all payment methods work everywhere. Platforms like PayPal may have limited support in some countries, making it tricky for your team to receive funds. Knowing these restrictions upfront helps you select the right solution, so your remote workers can get paid smoothly, avoiding frustration and maintaining trust in your startup’s global processes.

Security risks

‍Cross-border payments carry risks such as fraud, phishing, and data breaches. Using secure platforms and monitoring transactions carefully protects both your startup and your remote workers. Prioritising security shows professionalism and builds confidence. Your team can focus on delivering great work knowing that their money and personal information are safe, strengthening trust across borders.

Also read: Get paid by clients overseas as a US freelancer

How US startups pay remote workers outside the US

Paying remote workers abroad has become a normal part of US startups. Choosing the right platform ensures fast, reliable payments and builds trust.

Wise

Wise gives US startups a straightforward way to send payments to remote workers in other countries. Businesses can transfer USD directly while the recipient receives funds in their local currency at real exchange rates rather than marked-up bank rates. Transfers are trackable in real time and fees are shown upfront, helping startups plan payroll accurately. Wise also supports multi-currency balances, allowing companies to manage payments in different currencies from one account.

Transaction costs are generally lower than traditional bank wires, and transfers are often completed within one to two business days, making it a practical option for startups paying distributed teams.

Payoneer

Payoneer allows US startups to pay remote workers and contractors across multiple countries through a structured global payments network. Businesses can send funds in major currencies such as USD, EUR, or GBP while recipients withdraw to their local bank accounts or use a prepaid Payoneer card where available.

The platform also integrates with many global marketplaces and invoicing tools, which simplifies contractor payments. Fees and currency conversion rates are visible before sending, helping startups manage payroll budgets.

Western Union

Western Union allows US startups to send funds to remote workers in select countries fast. Payments can be picked up in cash at a local agent or deposited directly to a bank account where supported. While fees can be higher than digital‑first platforms, speed and accessibility make it valuable for urgent needs or recipients without online banking.

With a global agent network and mobile options in many regions, it’s practical when flexibility and immediate access to funds matter most.

Grey (recommended)

Grey helps US startups pay remote workers abroad by sending funds in USD to dedicated foreign currency accounts. Your team members can then convert the money into their local currency when it suits them and withdraw to their local bank accounts. This gives remote workers more control over how and when they manage their earnings while keeping payments straightforward for startups.

Grey follows strict anti-money laundering (AML) standards and is registered with FinCEN in the United States and FINTRAC in Canada, helping ensure payments are handled responsibly within recognised financial compliance frameworks.

Remitly

Remitly is commonly used by US startups when paying remote workers in countries where traditional banking systems may be slower or less accessible. The platform offers two transfer speeds: Express, which delivers funds within minutes but at a higher fee, and Economy, which costs less but can take several days.

Payments can reach bank accounts, mobile wallets, or approved cash pickup locations. For teams spread across different regions, Remitly provides flexibility in how workers receive funds and reliable tracking from the moment the payment is sent.

Sendwave

Sendwave is designed for sending money to workers in regions where mobile money is widely used, particularly across Africa and parts of Asia. Instead of relying on traditional bank transfers, US startups can send funds directly to supported mobile wallets, allowing workers to access their earnings instantly through their phones.

Because of its strong mobile wallet integrations, the platform works well for startups paying contractors in markets where mobile financial services are more common than conventional banking.

What should US startups consider before choosing a payment solution?

Choosing the right payment solution requires thought and planning. US startups need to ensure transfers are smooth and reliable, and that they build trust with their remote team.

Speed

Fast deposits matter for keeping your remote team motivated and satisfied. Delays can frustrate workers and slow project momentum. Look for providers that move funds quickly from US accounts to local accounts abroad, with predictable timing and clear tracking. Understanding typical transfer times allows you to plan payroll cycles efficiently, maintain trust, and show remote workers that their time and efforts are valued.

Security

Protecting payments and sensitive data is essential. Choose a provider with built-in fraud detection, encryption, and 3D secure integration. Secure systems prevent phishing, hacking, and unauthorised access, giving both your startup and remote workers confidence. Strong security safeguards help you avoid costly mistakes, maintain compliance, and demonstrate professionalism, ensuring your global team trusts the platform for every international transfer.

Support quality

Reliable support is crucial for resolving payment issues quickly. Access to 24/7 dedicated customer service ensures that any delays, errors, or account questions are handled efficiently. Responsive support reduces stress for both your startup and remote workers, ensuring smooth operations. Knowing that help is always available allows you to manage international payroll confidently without worrying about interruptions.

High uptime

Choose a payment provider with consistently high uptime to avoid failed transactions, system downtime, or lost revenue. Downtimes can delay payments and erode trust with remote workers. A reliable platform ensures your transfer process runs smoothly around the clock, across time zones, and in line with deadlines. High uptime gives peace of mind, reduces administrative follow-up, and keeps global teams focused on their work.

Regional support

Your payment provider should support local methods in the regions where your remote workers operate. This ensures workers can access funds without complications, whether through local banks, mobile wallets, or cash pickup points. Matching local preferences makes payments convenient and reliable, showing respect for workers’ needs. Regional compatibility also prevents unnecessary delays and demonstrates that your startup values its global team.

Customer preferences

Consider the payment methods your remote workers prefer. Some may favour direct bank transfers, others mobile wallets or platform-specific options. Catering to these preferences increases satisfaction, avoids frustration, and reduces time spent troubleshooting payment issues. Understanding what works best for your team ensures smooth operations, demonstrates attentiveness, and helps build strong, long-term relationships with remote talent across countries.

Fees

Evaluate all costs, including transaction fees, monthly charges, setup costs, and chargeback fees. Hidden or unexpected fees can reduce the amount your remote workers receive and affect budgeting. Comparing fees across platforms helps you choose the most cost-effective solution while maintaining reliability. Transparent costs show professionalism and help build trust with your team, ensuring that payments are fair, predictable, and worry-free.

Send international payments with Grey

Paying remote workers outside the US can be challenging if you don’t carefully consider speed, security, fees, and local support. Choosing the right platform makes all the difference for keeping your team motivated and confident. Grey stands out as a reliable solution that lets you send USD quickly, securely, and transparently. With fast transfers, multi-currency options, and easy withdrawals to local accounts, Grey helps you focus on your work while your team gets paid on time.

Sign up on Grey by creating an account with your email, verifying your identity, and setting up your business profile. You can also download the Grey app to handle international payouts from your phone wherever you work.

‍

Arrow (up)

Back to top