<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/domiciliary-accounts#article","headline":"How to open and use a domiciliary account","description":"Want to open a domiciliary account? Learn the types, benefits, drawbacks, and step-by-step process to get started!","inLanguage":"en","url":"https://grey.co/blog/domiciliary-accounts","mainEntityOfPage":{"@id":"https://grey.co/blog/domiciliary-accounts#webpage"},"datePublished":"2022-11-30T17:29:53.551Z","dateModified":"2022-11-30T17:29:53.551Z","author":{"@type":"Person","@id":"https://grey.co/authors/winner#person","name":"Winner Ajibola","url":"https://grey.co/authors/winner"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/domiciliary-accounts#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/638cea2772cd3a672a16977e_blogpost_what-is-a-dom-account-1024x536.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/638cea2772cd3a672a16977e_blogpost_what-is-a-dom-account-1024x536.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/domiciliary-accounts#webpage","url":"https://grey.co/blog/domiciliary-accounts","name":"How to open and use a domiciliary account","description":"Want to open a domiciliary account? Learn the types, benefits, drawbacks, and step-by-step process to get started!","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/domiciliary-accounts#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/domiciliary-accounts#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/domiciliary-accounts#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to open and use a domiciliary account","item":"https://grey.co/blog/domiciliary-accounts"}]},{"@context":"https://schema.org","@type":"DefinedTermSet","@id":"https://grey.co/blog/domiciliary-accounts#terms","name":"How to open and use a domiciliary account glossary","hasDefinedTerm":[{"@type":"DefinedTerm","name":"Domiciliary Account","description":"A domiciliary account is an account that allows you to receive, send, and transfer foreign payments from your local country. You can receive any type of foreign payment on your dom account. However, sticking to widely accepted currencies like USD, EUR, and GBP is advisable because you can only receive funds based on your bank’s available currencies.","inDefinedTermSet":{"@id":"https://grey.co/blog/domiciliary-accounts#terms"}}]}] </script>

How to open and use a domiciliary account

Winner Ajibola

TABLE OF CONTENT

SHARE THIS POST

Have you been trying to receive foreign currencies like USD? As a business owner, do you need to make frequent transactions in foreign currencies? Getting domiciliary or foreign accounts will make your transactions a lot more seamless.

A domiciliary account is probably one of the top recommendations you’d already be familiar with. Popularly referred to as a ‘Dom account,’ domiciliary accounts are a common way to receive USD, EUR, and GBP payments in your local country. 

In this post, we’ll explore the types of dom accounts available, what you need to open one and share answers to some frequently asked questions about these accounts.

What is a Domiciliary Account?

A domiciliary account is an account that allows you to receive, send, and transfer foreign payments from your local country. You can receive any type of foreign payment on your dom account. However, sticking to widely accepted currencies like USD, EUR, and GBP is advisable because you can only receive funds based on your bank’s available currencies. 

One limitation of this account type is that you must open accounts based on the currencies you want to receive. This means that to receive Dollar payments, you have to create a USD dom account. And for Pounds, you have to create a GBP domiciliary account.

Unfortunately, you cannot transfer from your local currency to your dom account. You can only receive a currency based on the account you’ve created.

Types of Domiciliary Accounts

Before heading over to the bank to open yours, there are two types of domiciliary accounts you’d have to choose from. 

1. Current Dom Account: This is like a typical current account. It’s mostly suitable for business people who need to carry out many transactions. For example, you can issue checks to third parties on this account. The downside is that it attracts more usage fees compared to the other type of domiciliary accounts.

2. Savings Dom Account: With this account, you can save in foreign currencies and withdraw with a bank teller whenever you want. This is more convenient for individuals who carry out little transactions. 

Both accounts are eligible to receive interests. However, the rates are not fixed. To withdraw funds from any dom account, you need to visit the nearest bank branch and fill out a bank teller. Once you receive the withdrawn sum in cash, you can change that sum to your local currency at any bureau de change office. 

How to Open a Domiciliary Account

The process for opening a dom account in Nigeria, Kenya or Tanzania is pretty much the same. Any individual or business can open a domiciliary account as long as they have the requirements listed below;

  • A completed account opening form given by the bank
  • Recent passport photographs
  • Proof of address such as a utility bill
  • Referee letters
  • A minimum opening balance (varies from bank to bank)
  • A government-issued ID

Please note that the documents required primarily depend on the bank you’re applying to. The entire process is free, so once the checklist you need is confirmed, visit the nearest branch and apply in person. 

Benefits of a Dom Account

Some of the advantages of opening a domiciliary account is that you can;

  1. Open foreign accounts and receive payments in foreign currencies
  2. You can receive interests on your domiciliary savings account

Drawbacks of a Dom Account

While domiciliary accounts are a great option for carrying out foreign transactions, they have several limitations. Some of the disadvantages of a domiciliary account is that;

  1. You cannot process withdrawals from anywhere or directly fund your account with your local currency
  2. Dom accounts have high withdrawal commissions 
  3. Opening an account requires referees and guarantors which can be inconvenient
  4.  You have to physically visit a branch to open an account

A Better Alternative for Receiving Foreign Payments

You need a domiciliary account alternative that allows you to transfer and receive foreign payments conveniently. With a Grey virtual foreign account, you can

  • Create accounts in multiple currencies from the comfort of your home
  • Get instant access to your foreign accounts
  • Enjoy zero to low fees on transfers and international payments
  • Seamless withdrawals to your local accounts
  • Get lower withdrawal costs and great conversion rates
  • Save time by avoiding endless bank queues

And so much more. Ready to explore? Create a foreign account for free and start receiving foreign payments today

Last updated:

October 2, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Passive income ideas for freelancers: 7 ways to earn while you sleep

•

•

2 min read

Imagine waking up to a payment notification without sending an invoice, joining a client meeting or spending hours at your desk. That's the power of passive income. While freelancing offers flexibility and independence, it also comes with one challenge: when you stop working, your income often stops too. Creating passive income helps you break that cycle by turning your skills into assets that continue earning even after the work is done.

Some of the best passive income ideas for freelancers include selling digital products, creating online courses, affiliate marketing, writing a paid newsletter, selling stock photography or assets, renting out unused equipment, and dividend investing. Most freelancers can launch their first passive income stream within 30 to 60 days using skills they already have.

Regardless of your niche, a writer, designer, developer, marketer or creator, this guide explores seven practical ways to build new income streams, earn more from the expertise you already have and create a business that works even when you take time off.

Also read: How freelancers increase earnings year over year

What counts as passive income for freelancers?

Passive income is money you continue to earn after the initial work has been completed. Unlike client projects, where you're paid for your time, passive income comes from assets you've already created or investments you've already made. For freelancers, this could mean selling digital products, earning affiliate commissions, publishing an online course or collecting dividends from investments. The goal isn't to stop working altogether, but to build income streams that don't rely on constant client work.

That said, passive income is rarely "set and forget". Most successful income streams require upfront effort to create and occasional maintenance to keep them profitable. You may need to update a course, refresh a digital product, promote your newsletter or optimise your affiliate content. While it won't generate money overnight, the long-term payoff can be significant. Instead of trading hours for income every day, you're building assets that continue working for you, giving you greater financial stability, flexibility and freedom over time.

7 passive income ideas every freelancer should consider

Whether you're a writer, designer, developer or marketer, these passive income ideas can help you earn beyond client work and build long-term financial stability.

1. Sell digital products

Create ebooks, Notion templates, design assets, spreadsheets or printable resources that solve a specific problem. Once published, they can generate recurring sales with only occasional updates and marketing.

  • Potential earnings: $100–$5,000+ per month
  • Time investment: 2–6 weeks to create

2. Create an online course

Package your expertise into a structured course on platforms like Udemy, Teachable or Skillshare. As your audience grows, your course can continue generating revenue for years.

  • Potential earnings: $500–$10,000+ per month
  • Time investment: 4–8 weeks to develop

3. Start affiliate marketing

Recommend software, tools or services you genuinely use and earn a commission whenever someone purchases through your referral links.

  • Potential earnings: $50–$5,000+ per month
  • Time investment: 3–6 months to build traffic

4. Launch a paid newsletter

Share exclusive insights, tutorials or industry updates through a subscription-based newsletter. Consistent, valuable content helps build a loyal paying audience.

  • Potential earnings: $200–$3,000+ per month
  • Time investment: Weekly publishing and promotion

5. Sell stock content

Upload stock photos, videos, illustrations, music or digital assets to marketplaces and earn royalties every time your work is downloaded.

  • Potential earnings: $50–$2,000+ per month
  • Time investment: Ongoing content creation

6. Rent out equipment

If you own cameras, drones, lighting kits or podcast equipment, renting them to other creators can generate extra income with minimal effort.

  • Potential earnings: $100–$1,500+ per month
  • Time investment: Minimal maintenance and scheduling

7. Invest in dividend stocks

Build a portfolio of dividend-paying companies that provide regular payouts while your investments continue to grow over time.

  • Potential earnings: Depends on portfolio size
  • Time investment: Initial research with occasional reviews

Also read: Best ways freelancers get paid internationally

How to build your first passive income stream as a freelancer

Follow this practical framework to turn your existing skills into a passive income stream that can grow alongside your freelance business.

1. Identify the skills people already pay you for

Start with the services you already offer. If clients repeatedly pay you for the same expertise, there's likely an opportunity to package that knowledge into a product, course or resource that can generate income beyond one-to-one work.

2. Choose the right passive income model

Match your skills to a passive income stream. Writers can sell ebooks or newsletters, designers can create templates, photographers can sell stock images, while consultants may find online courses or digital guides more profitable.

3. Validate your idea before building

Don't spend weeks creating something nobody wants. Ask your audience, review frequently asked client questions, research search demand and analyse competitors to confirm there's genuine interest before investing your time.

4. Build a simple first version

Focus on creating a minimum viable product instead of chasing perfection. Launch your first template, course or digital product quickly, then improve it using customer feedback and real-world results.

5. Launch and promote consistently

Publish your product, announce it to your audience and promote it through content, email marketing, SEO and social media. Even the best products need consistent visibility to generate ongoing sales.

6. Measure, improve and scale

Track sales, customer feedback and conversion rates to understand what's working. Update your product regularly, improve the customer experience and expand into new passive income streams as your audience grows.

Also read: Freelancer vs Employee Tax: What You Owe Compared

How much can freelancers realistically earn from passive income?

Your earning potential depends on the passive income stream you choose, the time you invest and how consistently you market and improve it.

Passive income stream After 1 month After 6 months After 12 months
Digital products $0–$200 $300–$2,000 $1,000–$5,000+
Online courses $0–$100 $500–$3,000 $2,000–$10,000+
Affiliate marketing $0–$50 $200–$1,500 $1,000–$5,000+
Paid newsletter $0–$100 $200–$1,000 $1,000–$3,000+
Stock content $0–$50 $100–$800 $500–$2,000+
Equipment rental $100–$500 $300–$1,000 $500–$1,500+
Dividend investing Depends on investment size Gradual growth Long-term recurring income

These figures are realistic estimates rather than guaranteed earnings. Digital products, online courses and affiliate marketing often take several months to gain momentum, while equipment rental can generate income almost immediately if there's local demand. The most successful freelancers don't rely on a single source, rather they combine multiple income streams to create predictable, long-term earnings.

Managing passive income across multiple currencies

If your passive income comes from global platforms, receiving payments efficiently is just as important as earning them. Here's how to manage international payouts.

Stripe payouts

If you sell digital products, online courses or subscription services through Stripe, you'll often receive payments in foreign currencies. Depending on where you're based, receiving these funds directly into a local bank account can involve higher fees, slower settlements and unfavourable exchange rates.

Gumroad earnings

Gumroad makes it easy to sell ebooks, templates, design assets and other digital products to customers worldwide. As your sales grow internationally, you'll need a reliable way to receive foreign currency payments without losing a significant portion of your earnings to conversion charges.

Affiliate marketing payments

Many affiliate programmes, including those from software companies and online marketplaces, pay commissions in USD or GBP. Managing multiple payment platforms and converting funds into your local currency can quickly become expensive if you're relying solely on traditional banks.

Grey

Grey gives freelancers foreign currency accounts in USD, GBP and EUR, allowing you to receive international payouts like a local. You can hold multiple currencies, convert them at competitive exchange rates and transfer funds to your local bank account whenever you need them, making it easier to keep more of what you earn.

Frequently asked questions

Can I build passive income with little or no money?

Yes. Many passive income ideas require more time than money to get started. Creating digital products, launching a paid newsletter, starting affiliate marketing or publishing an online course usually costs very little upfront. If you already have marketable skills and an internet connection, you can begin building your first income stream today.

Is passive income really "set and forget"?

Not entirely. Most passive income streams require significant upfront work and occasional maintenance. You may need to update a course, refresh a digital product, publish new newsletter content or optimise affiliate articles. While the income becomes less dependent on your time, successful passive income still requires regular attention.

Will I have to pay tax on passive income?

In most countries, yes. Income earned from digital products, affiliate marketing, investments or other passive sources is generally taxable. The rules vary depending on where you live and the type of income you earn, so it's always advisable to understand your local tax obligations or speak with a qualified tax adviser.

Which passive income idea is best for freelancers?

The best option depends on your skills and audience. Writers often succeed with ebooks and newsletters, designers can sell templates, photographers benefit from stock content, while consultants and educators frequently earn the most from online courses. Start with something that builds on work you're already doing.

Can I build passive income while working with clients?

Absolutely. In fact, many freelancers use their client work to create passive income opportunities. Common questions, repeatable processes and successful project templates can all be turned into products or courses that generate additional income without replacing your freelance business.

What's the easiest way to receive passive income from overseas?

If you're earning through platforms like Stripe, Gumroad or affiliate programmes, receiving payments in foreign currencies can be challenging. Grey makes it easier by providing foreign currency accounts in USD, GBP and EUR, allowing you to receive international payouts, convert your money at competitive rates and transfer funds when needed.

Building passive income won't make you rich overnight, but it can reduce your dependence on client work and create more financial freedom over time. Start with one income stream, stay consistent and let it grow. Open a Grey account or download the app today to receive international payouts, manage multiple currencies and keep more of what you earn.
Cost of living in London for international students

•

•

2 min read

There are only a handful of moments quite as exciting as a confirmation mail from the university you applied to.

It’s that single moment when months of applications, essays, and anxious email refreshing finally pay off. It’s even more surreal when the university is in London, one of the world’s most popular and cosmopolitan cities.

However, once the excitement subsides, the important question of how much it will cost to live in London inevitably arises.

That’s why I’ve put together this guide. It’s a complete breakdown of what it really costs to live as an international student in London. We’ll cover everything from accommodation to entertainment, and I’ll show you how Grey helps you to make your pounds stretch further (especially if you’re receiving money from home).

So, let’s unpack the numbers, shall we?

Accommodation

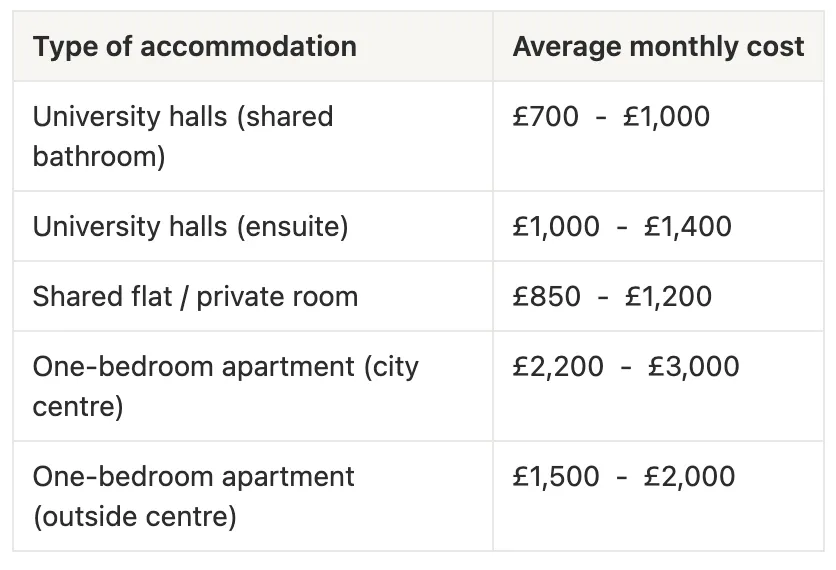
Rent is almost always the biggest part of a student’s budget. It varies depending on where you live. Central areas like Bloomsbury, Shoreditch, and South Kensington are pricier because they’re near top universities (UCL, LSE, Imperial). If you’re okay with a longer commute, you’ll find cheaper options in areas like Stratford, Lewisham, or Wembley.

Cost of living in London for international students

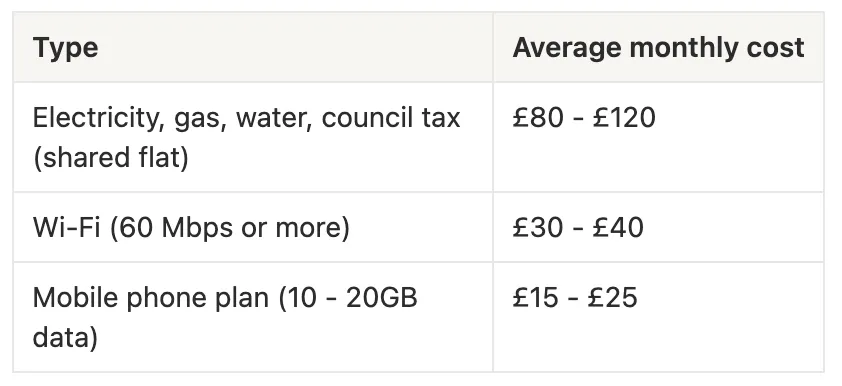
Many students save by sharing flats. Websites like SpareRoom or UniAcco help you find affordable, student-friendly housing. Remember that bills (electricity, Wi-Fi, water) often aren’t included in private rentals, so you’ll need to add another £150 - £250 monthly.

LDMAG1

Food and groceries

How much you spend on groceries depends entirely on your lifestyle. Cooking at home can save a lot, especially if you shop smart. Supermarkets like Aldi, Lidl, Tesco, and Asda are student favourites, while M&S and Waitrose are pricier but great for the occasional treat.

Cost of living in London for international students

If you cook most of your meals, you’ll likely spend around £150 - £250 per month on groceries. Eating out regularly or relying on takeaways can double that. You can also get student discounts in nearby restaurants and cafes. Also, meal prepping on weekends helps cut weekday costs and saves you from impulsive buying.

Also read: Cost of living in Alexandria

Transportation

Public transport in London is excellent but pricey, so plan ahead as much as you can. Most students rely on the Tube, buses, and trains, with discounted Oyster cards or Student Travelcards to keep costs down. I recommend using Trainpal or Trainline to book trains ahead, especially when you’ll be travelling outside London.

Cost of living in London for international students

If your classes are close to home, cycling can save a ton. Santander Cycles (Boris Bikes) cost just £20/month for unlimited 60-minute rides. Walking is also underrated in central London; you’ll be surprised how much you can explore on foot. It’s important to note that mobile maps, such as Google or Apple Maps, are helpful. The London commute can be very confusing, so it’s a great way to stay informed about your location. Ensure your device is charged, type in the address, and you’re all set.

Utilities and internet

If you live in university housing, utilities are usually included. However, if you’re renting privately, you may need to pay separately for essentials such as electricity, gas, and Wi-Fi. You can also find private accommodation with all bills included, but these are usually in the form of flatshares.

Cost of living in London for international students

Students are exempt from paying Council Tax if they’re enrolled full-time, so make sure to get a letter from your university confirming your status.

Study materials and personal expenses

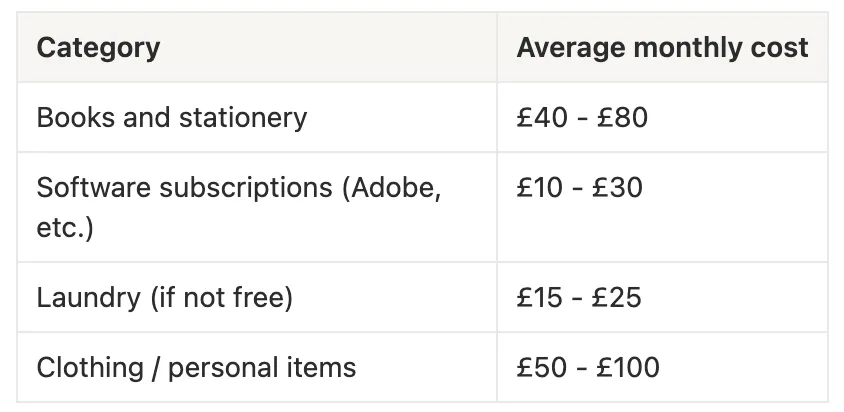
Books, printing, and supplies might not seem like much, but the costs can quickly add up. Most universities have libraries stocked with required textbooks; however, some courses may require specific editions or software (you can use the Grey virtual card for this).

Cost of living in London for international students

Most students also budget for occasional entertainment, streaming services, and social activities. It’s London. You’ll want to see a play, visit museums, or just enjoy a pint with friends now and then.

Also read: Cost of living in London vs New York: A full comparison

Entertainment and leisure

London is full of free and low-cost experiences. Museums like the Tate Modern, British Museum, and V&A are all free, and many theatres have discounted student tickets. Still, it’s nice to have a small leisure budget. A modest £150 - £250 per month for entertainment covers the occasional night out, gym membership, or city exploration.

Cost of living in London for international students

Total estimated monthly cost of living for international students

‍

Cost of living in London for international students

Total estimated monthly cost: £1,500 - £2,500

Your exact budget depends on where you live and how you spend, but a realistic figure for most international students in London falls between £18,000 and £25,000 per year.

Also read: Cost of living in London

Managing money in London with Grey

While studying your course in school, you’ll also need to learn how to manage your money outside of it. Many international students face the challenge of finding a reliable way to receive funds from outside the country or send some money back home occasionally.

Grey completely solves that. With a multicurrency account, you can receive money from home in USD, GBP, or EUR, convert at competitive rates, and spend directly in pounds, all without worrying about hidden fees or bad exchange rates.

So, if your parents send you funds monthly or even if you freelance part-time, Grey helps you manage your finances like a local.

Open a Grey account today or download the app and take one more thing off your student to-do list.

‍

Disclaimer: This article is based on researched data and is intended to give you a general overview of the cost of living in London. The figures provided are estimates gathered at the time of writing and may vary depending on location, lifestyle, and market changes.

‍

How South African YouTubers receive YouTube payments in 2026

•

•

2 min read

YouTube is now considered one of the most popular search engines in the world, and South African creators are taking full advantage of it, with over 25 million South Africans actively using the platform. This shows that there’s a huge market for you as a creator. And you can, of course, make money from it.

How?

First, you create videos that people watch worldwide; next, your account gets monetised, and then the money accumulates in your AdSense account. After that, you can withdraw and then start spending.

Except... I’ve spoken to many creators who waited weeks for transfers, lost significant portions of their earnings due to unfavourable exchange rates, or had payments rejected because their bank didn’t accept international wire transfers. None of those stories need to be yours. Below, I’ll explain how YouTube pays, the pain points most South Africans face, and most importantly, practical, step-by-step options to receive your money quickly and with minimal fees.

Also read: Send US dollars to South Africa from anywhere

Why do USD earnings matter for South African creators?

As a South African creator, your payments from YouTube are made in US dollars. Earning in USD gives your income more global value. Great yeah? Well, most local bank accounts in South Africa can’t receive USD directly. For those that do, when your earnings are converted into South African Rand (ZAR), they often take a significant cut due to high transfer fees and unfavourable exchange rates.

Sometimes, currency fluctuations can make this worse. Your income’s real value may drop the moment it’s converted. By holding part of your earnings in USD, you can protect yourself from these swings and preserve the value of what you’ve earned.

Earning in a stable foreign currency helps you stay in control by keeping more of your money, allowing you to decide when to convert it, and ultimately, getting paid on your own terms.

How does YouTube pay?

Before you can cash out your earnings, it’s important to understand how YouTube’s payment system works.

1. Join the YouTube Partner Program (YPP)

You can only start earning from ads once you’re part of the YouTube Partner Program (YPP). To qualify, your channel needs to meet one of YouTube’s monetisation thresholds within the past 12 months:

  • Option 1: 1,000 subscribers and 4,000 valid public watch hours, or
  • Option 2: 1,000 subscribers and 10 million valid public Shorts views

Once your channel is approved, you’ll be able to monetise through ads, channel memberships, Super Chats, Super Stickers, and YouTube Premium revenue. Essentially, every view or engagement can start earning you money, as long as it happens on monetised content.

2. Set up a Google AdSense account

YouTube doesn’t send money directly to your bank. All payments are processed through Google AdSense, so setting it up is a crucial step.

Here’s what you’ll need to do:

  1. Create or link an AdSense account to your YouTube channel.
  2. Submit your tax information. This ensures compliance with YouTube’s global payment policies.
  3. Choose your preferred payout method, such as direct bank transfer or wire transfer.

Your AdSense dashboard is where you’ll monitor your estimated earnings, payment history, and any deductions for taxes or invalid activity.

3. Reach the payment threshold

YouTube doesn’t pay out every time you make a few dollars; it works on a minimum payment threshold system. You’ll need to earn at least $100 in your AdSense account before Google processes a payout.

If your earnings for the month fall short, the amount will simply roll over to the next month until you reach the threshold. Once you cross that mark and your account is verified, YouTube will automatically schedule your payment in the next payment cycle.

For most creators, payments will be sent around the 21st of each month, covering your total earnings up to the end of the previous month. So, if you hit $100 in March, you’ll typically get paid in April.

4. Understand the payment timeline

So, let's talk more about the payment cycle. The payment system runs on a monthly cycle, but payments aren’t instant. There’s a short delay while your earnings are verified and processed.

Here’s how it works:

  • Earnings are finalised between the 3rd and 10th of the following month. During this time, YouTube reviews your ad revenue to confirm everything’s valid.
  • Payments are processed between the 21st and 26th, once your balance reaches the $100 threshold.
  • You’ll only receive your payout if there are no payment holds, such as missing tax information or pending account verification.

So, for example, if you earned $200 in April, those funds will appear in your AdSense account in early May, but you’ll actually receive the money later in May. Once Google processes that month’s payouts.

It’s a simple system. Once you understand the rhythm, you just need a bit of patience between creating the content and seeing the cash hit your account.

Also read: How to pay for subscriptions in US dollars from South Africa

How to receive USD from YouTube in South Africa with Grey

Grey allows South African YouTubers to open a USD account effortlessly, all without leaving the country.

1. Create your Grey account

Visit the Grey website or download the app. Sign up and complete your KYC verification.

2. Access your USD account details

After approval, you’ll get your account information, including a US routing number, account number, and SWIFT code.

3. Connect your Grey USD account to AdSense

Log in to AdSense, select “Add payment method,” and enter your Grey account details.

4. Receive payments in USD

YouTube will deposit your earnings directly into your Grey account in USD, eliminating the need for automatic currency conversion.

5. Convert whenever you want

Use Grey’s in-app exchange to convert USD to ZAR at competitive rates or hold your USD in your account if you prefer.

Also read: How to send and receive British pounds in South Africa

What other ways can South African YouTubers boost earnings?

Once you’ve set up a reliable payment method, you can turn your channel into a sustainable income source. The most successful creators don’t rely on just one revenue stream; they layer multiple income sources to protect against dips in views or ad rates.

Here’s how you can do the same:

Channel memberships

Offer loyal fans exclusive perks like members-only videos, live Q&As, or custom emojis in exchange for a monthly subscription. This builds community and gives you a predictable monthly income.

Super chat & super stickers

These features allow viewers to pay to have their messages highlighted or to send animated stickers during live chats, providing a fun way for fans to support you in real-time.

Affiliate marketing

By adding affiliate links in your video descriptions, you can earn a commission every time someone buys a product you recommend. This works well if you review gear, software, or services your audience already needs.

Brand sponsorships

You can partner with companies to feature their products or services in your content. Sponsored deals often pay far more than ad revenue, especially if you have a niche audience that brands want to reach.

Also read: How to get paid as a creator on social media from anywhere in the world

At the end of the day, the more diverse your income streams, the more stable your creator career will be. If ad rates drop or one revenue source slows down, your other income channels keep you afloat.

Why Grey is the best option for South African creators

Now to the solution. Grey is built to accommodate how modern creators work, earn, and spend across borders. If you’re a South African YouTuber, influencer, or freelancer receiving international payments, Grey removes the friction that usually comes with getting paid from abroad.

Free USD account setup

Grey lets you open a USD account, providing you with the same payment details (routing and account numbers) that US-based creators typically use.

Low, transparent FX rates

Grey offers competitive exchange rates that are visible upfront, so you know exactly how much you’ll receive before confirming a transfer.

Multi-currency accounts to grow your income

With Grey, you can also hold EUR, GBP and USD, which is perfect if you land brand deals in Europe or work with clients in the UK.

Fast, reliable payouts

You no longer need to wait weeks for your money to clear. Grey processes transfers quickly, so you can move your earnings to your local bank account without delay, helping you maintain a steady cash flow.

Built with creators in mind

Every feature is designed to make life easier for people who get paid globally, so you can focus on making content instead of chasing payments. This makes it easier to keep more of your hard-earned YouTube income and avoid the usual international payment frustrations.

Being a YouTuber in South Africa is a great way to share your voice with the world and earn a living from it. By setting up a USD account with Grey, you can receive your YouTube earnings quickly, securely, and without incurring losses due to unfavourable exchange rates.

Create your free Grey account today or download the app to make your creator journey easier, smarter, and borderless.

‍

Cost of living in Mumbai

•

•

2 min read

The more you know, the more you realise that you don’t know. This saying is attributed to the great Aristotle. He may not have been talking about Mumbai, but he just as easily could have been.

The city has that effect on people. Just when you think you’ve figured it out, you learn something new. Mumbai is a city that overwhelms your senses but finds a way to make you fall in love with it anyway. It’s India’s financial capital, a melting pot of dreams, and of course, the home of Bollywood.

If you’re considering moving there, understanding the cost of living is the first step to finding your place in the city that never really slows down.

Let’s break it all down. We’ll do housing, groceries, transport, utilities and every essential thing you need to know about how much it costs to live in the city of flamingoes.

Rent

Rent in prices in Mumbai aren’t exactly straightforward. There’s a lot of contrast depending on what part of the city you stay. So it’s heavily dependent on the lifestyle, neighbourhood, and how much of Mumbai you want to properly immerse yourself in.

If you plan on staying in the south, you’ll most likely be close to the sea, which can push up the rent. If you move further out to places like Thane, Navi Mumbai, or even Andheri, things start to look friendlier on the wallet. The commute might stretch a little, but with Mumbai’s expanding metro network, that trade-off’s becoming easier every year.

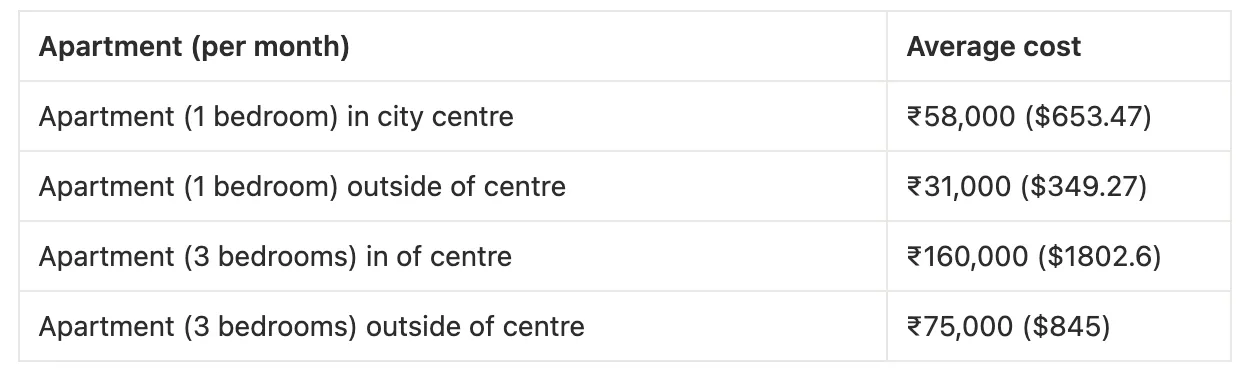
Here’s a quick look at what renting in Mumbai actually costs on average:

__wf_reserved_inherit

What if you prefer to buy an apartment in Mumbai?

If you’re thinking long-term and planning to buy rather than rent, brace yourself. Mumbai’s property market is as intense as the city itself. So think long and hard and decide if it’s a commitment you want to make.

The city’s real estate scene is famously competitive. In South Mumbai, there are neighbourhoods where proximity to the sea and skyline views can easily double the cost per square metre. Folks who buy property here usually do it for comfort and prestige.

If you have a tighter budget, areas like Navi Mumbai, Thane, and Chembur are redefining urban living have significantly lower property prices. These neighbourhoods attract young professionals and families looking for value without losing touch with the city’s pulse.

Still, property ownership in Mumbai is no small feat, regardless of where you chose. Mumbai remains one of India’s most expensive and fast-moving real estate markets.

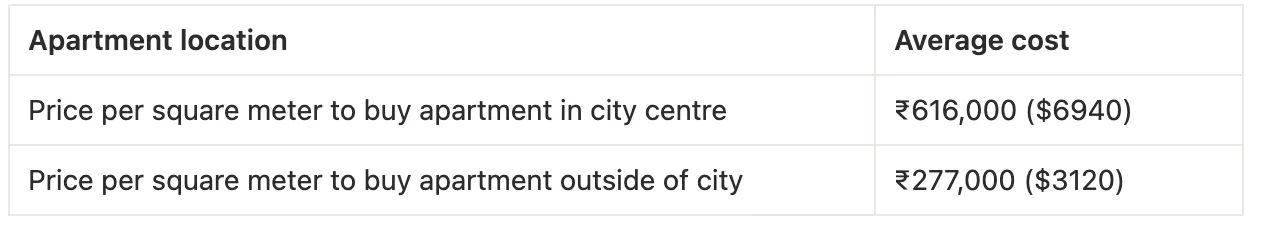
Here’s a breakdown of the average cost of buying an apartment in Mumbai:

__wf_reserved_inherit

Also read: Cost of living in New Delhi

Restaurants

I know you’re probably trying to save money, but you can’t move to a new country without properly immersing yourself in it. And what better way is there to immerse yourself in the culture of a people than through their food?

Mumbai has options for every kind of budget and craving.

A full meal at a small local eatery can cost as little as ₹150 - ₹500, making it easy to eat well without overspending. Mid-range restaurants, the kind you’ll find in Bandra, Powai, or Lower Parel, usually charge around ₹1,500 - ₹2,500 for two people, while fine dining establishments in South Mumbai can easily cross ₹5,000 - ₹8,000 for a three-course meal.

Fast food and café culture are also big parts of daily life Mumbai. A McDonald’s combo meal costs around ₹400, a cappuccino averages ₹230, and a bottle of water costs roughly ₹17, give or take. Meanwhile, imported drinks or craft cocktails at upscale bars can range from ₹350 - ₹900 depending on the location and brand.

What’s especially interesting about Mumbai’s dining scene is how it blends affordability and aspiration. On one street, you can find a family-run thali joint serving unlimited curries for the price of a metro ticket, and right next door, a sleek restaurant serving modern Indian tasting menus that could rival Paris or New York. Just pick what works for you and have a good time.

Here’s a breakdown of the average cost of eating out in Mumbai:

__wf_reserved_inherit

Also read: Cost of living in Bengaluru (Bangalore)

Markets

The smell of spices spilling from open sacks, and the sight of produce piled high in street markets, are things that are synonymous with Mumbai. The city’s markets mirror its people. They’re diverse, adaptable, and endlessly resourceful.

For most residents, groceries make up about 10% - 15% of their monthly expenses, depending on lifestyle and household size. I know for sure that mine would be less than 10%. I eat out a lot as I rather unfortunately, can’t cook.Local staples such as rice, lentils, vegetables, and bread remain relatively affordable, with prices that fluctuate slightly based on season and supply. Buying directly from open-air markets or smaller vendors often stretches your rupee further than shopping exclusively at premium stores. Imported goods can cost two to three times their local equivalents, which is why many Mumbaikars (a person residing or born in the Indian city of Mumbai), ****mix local essentials with the occasional indulgence.

One important thing to note: beef is largely unavailable in Mumbai due to local religious and legal restrictions. Cows are considered sacred in Hinduism. Most households substitute with chicken, fish, or mutton, and the city’s coastal location ensures seafood remains a staple in many diets, especially along the western suburbs.

For the average single professional, monthly grocery bills typically range between ₹5,000 - ₹10,000, while families might spend upwards of ₹20,000 - ₹30,000 depending on preferences and eating habits. Despite global inflation and rising urban costs, Mumbai’s mix of traditional markets and modern retail options keeps grocery shopping flexible.

Here’s what everyday market prices in Mumbai look like on average:

__wf_reserved_inherit

Also read: Cost of living in Bali: what remote workers and expats should expect

Transportation

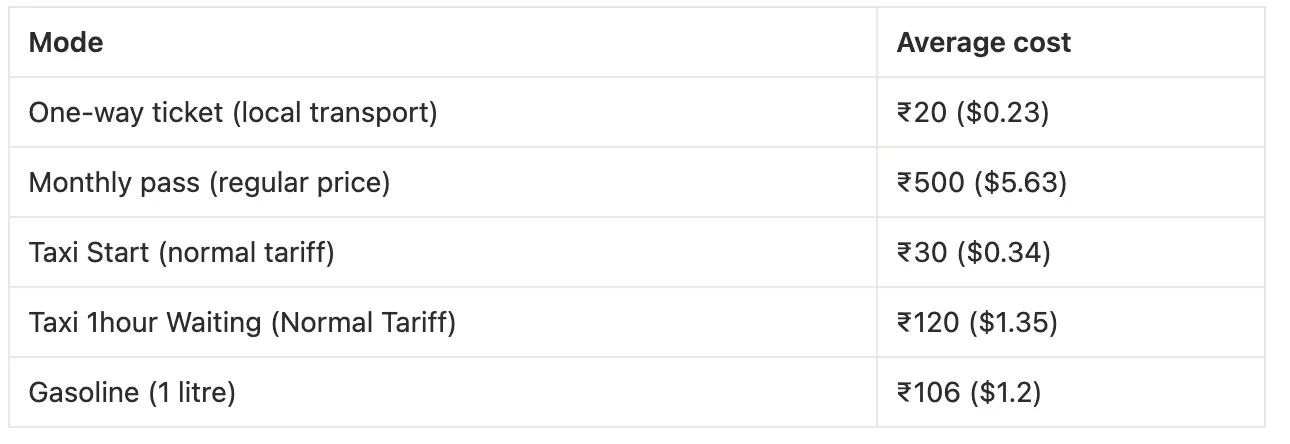
Getting around Mumbai is both a logistical exercise and a lesson in patience. But it’s also part of what gives the city its pulse. The local train network is often called the city’s lifeline, and for good reason too. It moves over 7.5 million passengers daily across its Western, Central, and Harbour lines. It’s the fastest and most affordable way to get around, with tickets costing as little as ₹20 for short distances. You don’t want to be on the train during rush hours though. They are usually packed.

For shorter journeys, auto-rickshaws, locally called “tuk-tuk”, and black-and-yellow taxis are everywhere. A quick rickshaw ride across the suburbs might cost between ₹30 and ₹150, depending on distance and traffic, while taxis are a slightly pricier but more comfortable alternative. The city’s Uber and Ola network is extensive too, though surge pricing during heavy rains or traffic jams can double the fare.

Public transport users typically spend around ₹2,000 - ₹3,000 per month, depending on routes and frequency. Those relying on taxis or private cars could easily see transport costs rise to ₹8,000 - ₹15,000 monthly, especially with petrol prices hovering around ₹106 per litre and parking charges creeping upward in business districts like Lower Parel or Bandra.

You could also get your own car. Between fuel, maintenance, and parking, monthly costs can exceed ₹12,000 - ₹20,000, depending on usage. So most residents prefer a hybrid approach, combining public transport with occasional cabs or two-wheelers to strike a balance.

__wf_reserved_inherit

Utilities

Once you’ve found your place in Mumbai, your next concern will likely be managing monthly utilities. This will vary widely based on your lifestyle.

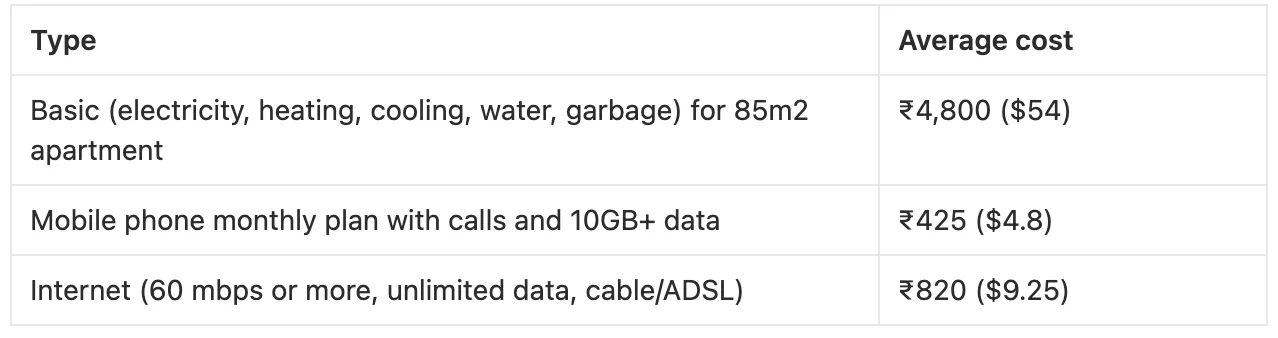
For most residents, electricity is the biggest recurring expense. Mumbai is generally hot and humid, so air conditioning is almost non-negotiable during the summer months. A small apartment using fans and minimal AC might see monthly electricity bills between ₹2,000 - ₹3,500, while larger households running multiple air conditioners could pay anywhere from ₹5,000 - ₹10,000 or more. The average unit rate for electricity in the city ranges from ₹7 - ₹12 per kWh, depending on consumption slabs and provider (BEST, Adani, or Tata Power).

Water and waste management are generally more affordable but vary depending on your housing society. Monthly water charges typically range between ₹300 and ₹800, and some buildings include it in maintenance fees. Waste disposal and building maintenance can add another ₹1,000 - ₹3,000, particularly in gated communities or high-rise apartments.

Internet connectivity in Mumbai is among the most reliable in India. With high-speed fibre connections from providers like JioFiber, Airtel Xstream, and ACT you can get speeds between 100 Mbps to 1 Gbps. Most monthly plans start at about ₹700 - ₹1,500. Freelancers and remote workers often opt for mid-range packages that balance speed and stability, typically around ₹1,000 per month.

For mobile data, plans from Airtel, Jio, and VI start at around ₹300 - ₹500 per month for unlimited calls and up to 2GB of daily data, making it easy to stay connected without breaking the bank.

Altogether, a single professional living in a one-bedroom apartment might spend roughly ₹4,500-₹7,000 per month on utilities, while families in larger apartments can expect anywhere between ₹8,000 - ₹15,000, depending on usage and comfort level.

__wf_reserved_inherit

Sports and leisure

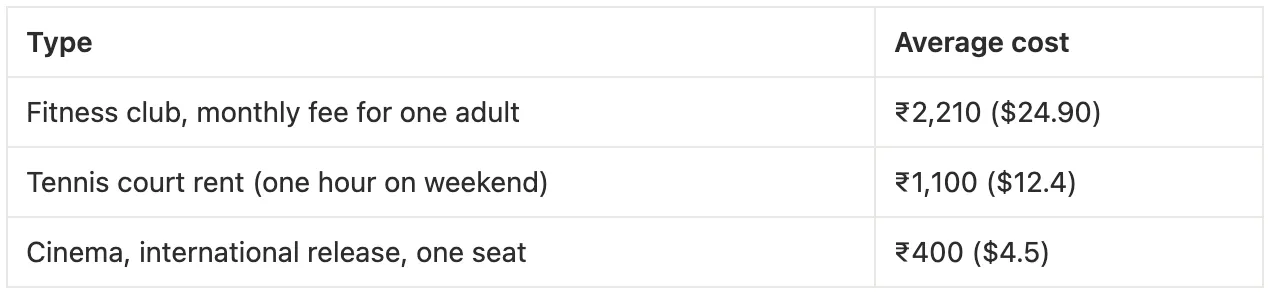
If staying active is a priority, you’ll find a wide range of fitness options across the city. Basic gym memberships in local neighbourhoods start around ₹1,200 - ₹2,500 per month, while premium chains like Gold’s Gym, Cult.Fit or Fitness First charge between ₹3,000 - ₹6,000 monthly.

Outdoor enthusiasts often take advantage of Mumbai’s coastline and public spaces. Early morning jogs along places like Marine Drive or Carter Road are pretty common. Cycling is also very popular. These activities are mostly free, apart from park entry fees (around ₹50 - ₹100).

For those with a competitive streak, sports club memberships can range dramatically from ₹10,000 annually for smaller community clubs to over ₹1 - 2 lakh per year for prestigious venues like the Bombay Gymkhana or CCI (Cricket Club of India). Renting a tennis or badminton court for an hour typically costs ₹600 - ₹1,200, depending on the location and time.

A standard cinema ticket for an international release ranges from ₹250 - ₹600, although luxury theatres like PVR ICON or INOX Insignia charge up to ₹900 for recliner seats.

In short, there’s something for every kind of lifestyle. You can live simply and spend next to nothing, or indulge and experience the best of urban leisure. The choice, as always in Mumbai, depends on how much you want to spend.

__wf_reserved_inherit

Also read: Cost of living in Jakarta: a complete guide for travellers and digital nomads

Childcare

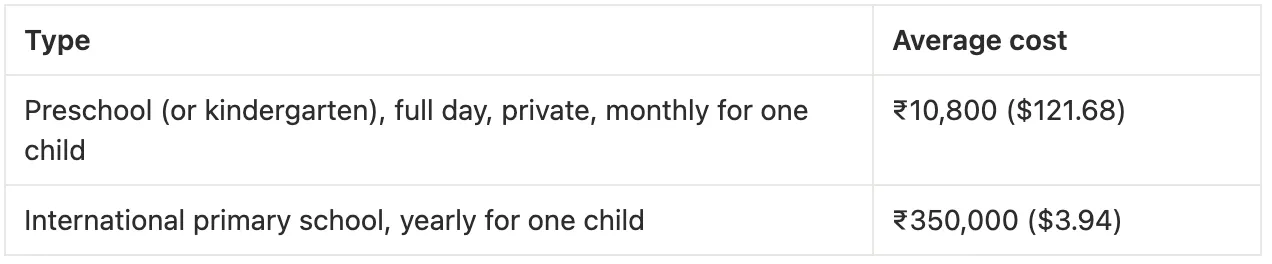
For families, education is one of Mumbai’s biggest expenses. While local preschools are relatively affordable, international schools are significantly more expensive due to global curricula and facilities. Still, many expat and professional families consider the investment worthwhile for quality and continuity.

__wf_reserved_inherit

Clothing and shoes

If you’re shopping on the high street, international brands like Zara, H&M, Levi’s, and Uniqlo have a strong presence in malls like Phoenix Palladium and Oberoi Mall. A pair of jeans typically costs around ₹2,500 - ₹4,000, casual shirts or blouses range from ₹1,200 - ₹2,500, and summer dresses or chinos fall within the ₹2,000 - ₹3,500 bracket.

For mid-range or local brands, men’s t-shirts and women’s kurtas often cost ₹800 - ₹1,500, while workwear or ethnic outfits average ₹2,000 - ₹3,000. Many locals also shop at Linking Road (Bandra) or Hill Road, where you can bargain for trendy pieces, sandals, and accessories, usually for under ₹1,000.

When it comes to footwear, expect to spend around ₹2,000 - ₹3,500 for a good pair of sneakers, while local brands or markets sell stylish alternatives for ₹800 - ₹1,200. During the monsoon months, rubber sandals or waterproof shoes are a must-have and usually cost between ₹500 - ₹1,000.

The city’s fashion culture encourages you to stay cool, stylish, and comfortable.

__wf_reserved_inherit

LDMAG1

Living smart in Mumbai with Grey

To live a proper life in Mumbai, you need to plan, budget and work towards it. It’s a city that rewards ambition. It encourages you to push yourself, to work, to thrive. But there’s only so much you can do without the right tools. Managing your money, especially as someone who gets paid in foreign currency is important. And in Grey, you have the perfect solution.

With Grey, you can create a multicurrency account to receive, convert, and spend money across borders seamlessly. Grey helps you manage it all from one platform with real exchange rates and no hidden fees. So you don’t need to worry about payments. You can pay for everything you need in this new city, right from your app.

Sign up or download the Grey app today and make managing money in Mumbai easier.

Disclaimer: This article is based on researched data and is intended to give readers a general overview of the cost of living in Mumbai. The figures provided are estimates gathered at the time of writing and may vary depending on location, lifestyle, and market changes.

‍

A simple guide to online shopping from abroad for Indonesians

•

•

2 min read

Global marketplaces like Shopee and Tokopedia have created a reliable platform for international shopping. While you might be unable to visit the US to buy that designer bag or the cute handcrafted gift from Kenya, you can still access international stores from the comfort of your home.

Shopping from digital stores has become increasingly popular among Indonesians looking for better prices, wider product choices and brands not available locally. Unfortunately, buying from overseas can be confusing without accurate information. This guide breaks down everything you need to know about online shopping from abroad, so you can shop safely, affordably and confidently.

Also read: Grey vs. local banks: The best currency exchange choice in Indonesia

Why Indonesians shop from abroad

Many Indonesians opt for online international stores for reasons such as:

  • Access to global brands and exclusive products: Many reputable brands and product collections are not readily available in local markets.
  • Better pricing than local mark-ups: Buying directly from international sellers can be cheaper than buying certain products locally. Many local sellers hike their selling prices unfairly to increase their profit margins.
  • Availability of electronics, fashion, and niche products: Many niche products, fashion items, and electronics are available on online stores and may not be sold locally. These stores also offer a wide variety of items to help you take control of your shopping.
  • Seasonal sales, discount codes and loyalty programmes: Black Friday, Cyber Monday, last-minute deals, holiday sales and other promotions provide an opportunity for you to buy items at cheaper rates. Some online stores also offer discount codes, coupons and loyalty programmes to help you save some money while you shop.
  • More reliable authenticity for certain products (e.g., tech, skincare): In a world where dupes look more original than the originals, shopping from reputable international online stores offers a better guarantee of authentic products.

Popular platforms Indonesians use for international purchases

Indonesians generally favour regionally popular shopping platforms

  • Shopee: This is perhaps the most popular online market in Indonesia for international purchases. It provides a marketplace for brands, sellers, and consumers to conduct transactions safely and easily online. The platform has an extensive catalogue, a user-friendly mobile experience, and a robust logistics network.
  • Lazada: Lazada is a major international e-commerce marketplace and one of the largest online shopping destinations in Southeast Asia, headquartered in Singapore and owned by the Alibaba Group. It operates a platform for various brands and sellers, offering a wide range of consumer goods.
  • TikTok Shop/ShopTokopedia: TikTok is evolving into a global marketplace for not just engaging content but also e-commerce. This platform has experienced rapid expansion and strong traction since its integration into Tokopedia to comply with local laws.
  • Etsy: Etsy is gaining some popularity in Indonesia. Buyers in Indonesia can purchase items from Etsy sellers worldwide. The platform automatically handles currency exchange, so transactions are seamless. Buyers can also easily find a wide range of products, especially handcrafted items, souvenirs, and gifts.

Also read: Using USDC for international transfers in Indonesia

Considerations before online shopping from abroad

Shopping on online international stores has many perks, but it isn't always straightforward. Before you dash into an online digital marketplace and start shopping, there are certain factors to consider to ensure a favourable experience.

1. Total cost estimation

Don’t assume the price you see on the product will be the total cost you’ll incur. Other factors might add to the cost at the payment gateway ro before receiving your order. These include:

  • Product price: The base cost of the item you are ordering
  • International shipping fees: the cost of transporting your order to Indonesia. It usually varies based on the item's value, weight, size, destination, and dispatch speed.
  • Customs duties and import taxes: charges levied by the government on goods entering its borders
  • Currency conversion costs: If you are paying in IDR, expect some cost on currency conversion.
  • Payment platform charges: The payment platform might also charge a fee for the transaction.
  • Service charge: Some online stores charge a token for purchasing items from their platform,

2. Customs and import rules

Your international purchases are subject to import duties, Value Added Tax (VAT), and potentially other sales taxes. Specific rules depend on the value of the goods (Cost, Insurance, and Freight, or CIF) and the type of product. If the total CIF value per shipment is less than 3 USD, they are exempt from import duties, but VAT (11%) will still apply. The US$3 threshold does not apply to certain products, especially fashion items, which have specific regulations. You should understand how these regulations apply to you before shopping online.

3. Shipping options and considerations

Sometimes, the shopping platform has an existing partnership with a shipping company for order delivery. You may opt for a shipping option based on speed, cost, and reliability.

  • Express services: DHL, FedEx, or UPS with 3-7 day delivery are ideal for valuables but pricier.
  • Economy options: USPS Priority Mail or China Post take 2-4 weeks, are cheaper but less trackable.

Shipping costs usually vary and depend on the parcel's volumetric weight and value.

4. Payment methods for Indonesians

A reliable, secure, and convenient payment option is key to a hitch-free experience when shopping online internationally. Here are some payment options:

  • Credit/debit cards: Visa and Mastercard cards are widely accepted, with local payment gateways like GPN integrating seamlessly. However, markup on exchange rates can be high.
  • Digital wallets: GoPay, OVO, DANA, or ShopeePay are available for quick transactions/
  • Bank transfers and fintechs: Both traditional bank transfers and emerging fintech payment options, such as Grey, are also used for online shopping in Indonesia.

LDMAG1

Tips to stay safe while shopping internationally

Not all sellers are legit. You should have a high index of suspicion when shopping online.

  • Only buy from verified sellers with strong ratings.
  • Avoid deals that seem too good to be true.
  • Use secure payment methods with buyer protection.
  • Keep all receipts for customs clearance.
  • Track your parcel and contact support immediately if delayed.

Also read: How freelancers in Indonesia can receive payments from the US, UK & EU clients

Managing online purchases with Grey

Online shopping from abroad provides access to global products, competitive prices and higher-quality goods. Despite its perks, Indonesians should consider customs rules, secure payment options, overall cost and reliable shipping methods before going ahead. With the right planning, you can shop internationally with confidence and ease. That plan starts with having a reliable payment solution for your online purchases. And this is where Grey comes in. Grey makes online shopping from abroad simpler for Indonesians:

  • Multi-currency accounts in USD, GBP and EUR
  • Virtual dollar cards that work on most global websites
  • Better exchange rates than traditional banks
  • Transparent, low fees
  • Withdrawal into a local bank account

Open a Grey account today for seamless international online purchases.

‍

Paying abroad from the UK: a simple guide for first-time traveller

•

•

2 min read

Travelling out of your country can be an exciting experience, but it can also be distressing without the right information. You get to experience life differently from what you are used to in your home country. One common concern for people leaving the UK for the first time is how to manage international payments. Between unfavourable exchange rates, card restrictions, and high transaction fees, many UK travellers end up spending more than they should simply because they don’t know the best way to pay. Here’s a simple guide to help you understand your options, avoid hidden fees, and pay confidently while travelling abroad.

Also read: Summer vacation ideas for families in the UK

Understanding your payment options

There are various payment options, each with its pros and cons. Your choice of payment options should depend on destination, trip length, and spending habits. Regardless, opt for options that offer exchange rates close to the mid-market rates and low or no foreign transaction fees. Here are your options

  • Cash: It is readily accepted in markets and convenience stores in most countries. You can also use it to pay for your train tickets or bus passes. There are no additional charges for using cash, and you won't get stranded if your card fails or a machine isn’t available. On the other hand, you risk loss or theft if you aren’t careful enough. It is better to carry small amounts at a time. Also, obtaining cash, especially if you are converting at an airport, hotel or using international ATMs, can be expensive. It is also challenging to pay in cash for online transactions.
  • Regular UK debit card payments: Your regular UK debit card works in many countries, but charges may be steep.
  • Travel debit card: An international travel debit card is usually better for avoiding high fees and conversion charges. Card payments are convenient for both physical and online payments. Digital banks like Starling Bank, Monzo, and Chase offer current accounts with debit cards that have no foreign transaction fees and good exchange rates.
  • Travel credit cards: Specialist credit cards, such as the Halifax Clarity or Barclaycard Rewards Visa, are fee-free for spending abroad. Section 75 consumer protection on purchases between £100 and £30,000 is still applicable. So, if you pay for a service or a single item within this rate and the quality isn’t excellent, you can file for a refund. You, however, need a good credit score to get one. You also have to pay off the credit quickly to prevent the interest from piling up.
  • Prepaid travel cards: You load these cards with a specific amount of currency before you travel. This way, you are locking in the exchange rate at that moment. It is great for budgeting and is not usually linked to your primary bank account. This adds extra security and protects against sudden unfavourable exchange rate changes. It is advisable to consider the associated fees before proceeding. This usually includes an application fee and charges on top-ups and withdrawals. Also, the exchange rates aren't always the absolute best available.
  • Digital payment solutions: Digital payment solutions are revolutionising how we manage international payments by removing barriers to affordable cross-border transactions. Transactions are cheaper, exchange rates are better, and payment processing is swifter. With payment solutions like Grey, you get a multicurrency account supporting USD, GBP, EUR, and even USDC, and you can withdraw funds to a local bank account in many countries at competitive exchange rates. You can also get a virtual USD debit card that can be added to Google or Apple Pay, further simplifying payments abroad.

Also read: How Grey differs from a UK bank

LDMAG1

Pre-travel checklist

Before you jet off, a little preparation will help you avoid unexpected costs and stay secure.

  • Inform your bank: Most modern digital banks don’t require you to inform them of your travel plans. However, with traditional high-street banks, it's a good idea to let them know so they don't block your card if they discover transactions from another country.
  • Check fees: Scrutinise the fees charged by your existing UK bank for foreign transactions and ATM withdrawals. Many charge a non-sterling transaction fee of around 3%, plus a flat fee per withdrawal.
  • Carry some cash: While cards are widely accepted, using cash may be better suited for tips, small vendors, street markets, or areas with unreliable internet. You will get better exchange rates if you get money in advance from a bureau de change, rather than at airports or hotels.
  • Have a backup: Have at least one alternative payment option. Keep cards in separate, secure places in case one is lost or stolen.
  • Know your numbers: Keep a physical or digital note of your bank's emergency contact details so you can quickly report a lost or stolen card and block it.

Also read: How UK residents can send and receive US dollars easily

Travelling with Grey

Paying abroad doesn’t have to be complicated or costly. With a bit of preparation and the right tools, you can enjoy your trip without worrying about hidden fees or bad rates. If you’re travelling soon, consider opening a Grey account to get access to multi-currency features that work globally. It’s one of the simplest ways for UK travellers to manage payments abroad safely, affordably, and conveniently. Get a Grey USD debit card to give you more financial flexibility.

Sign up on Grey today for seamless payments abroad.

‍

Arrow (up)

Back to top