<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/start-dropshipping-business-nigeria#article","headline":"How to start a dropshipping business in Nigeria","description":"Want to start a dropshipping business in Nigeria? Follow our easy seven-step guide to launch with minimal risk and investment!","inLanguage":"en","url":"https://grey.co/blog/start-dropshipping-business-nigeria","mainEntityOfPage":{"@id":"https://grey.co/blog/start-dropshipping-business-nigeria#webpage"},"datePublished":"2023-03-21T07:32:10.136Z","dateModified":"2026-05-30T23:20:46.324Z","author":{"@type":"Person","@id":"https://grey.co/authors/ngozi#person","name":"Ngozi Enelamah","url":"https://grey.co/authors/ngozi"},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/start-dropshipping-business-nigeria#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/64195be79b63110de14d25e3_greyblogpost-growfreelan.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/64195be79b63110de14d25e3_greyblogpost-growfreelan.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/start-dropshipping-business-nigeria#webpage","url":"https://grey.co/blog/start-dropshipping-business-nigeria","name":"How to start a dropshipping business in Nigeria","description":"Want to start a dropshipping business in Nigeria? Follow our easy seven-step guide to launch with minimal risk and investment!","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/start-dropshipping-business-nigeria#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/start-dropshipping-business-nigeria#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/start-dropshipping-business-nigeria#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"How to start a dropshipping business in Nigeria","item":"https://grey.co/blog/start-dropshipping-business-nigeria"}]}] </script>

How to start a dropshipping business in Nigeria

Ngozi Enelamah

TABLE OF CONTENT

SHARE THIS POST

Dropshipping has come a long way in the African market, and that’s because it is a business model that allows entrepreneurs to sell products without holding inventory. The way it works is, whenever a customer orders a product, as the business owner, you’ll buy that item from a third-party supplier, who will ship the product directly to the customer. 

This business model has become increasingly popular because it eliminates the need for upfront inventory costs, storage space, and shipping logistics. 

As a result, it has gained traction in the Nigerian market in recent years as it is a cost-effective way for entrepreneurs to start an online business without needing physical inventory. 

Benefits of dropshipping in Nigeria

There are several benefits of dropshipping in Nigeria; some of them include:

  1. Low Overhead Costs: Dropshipping requires minimal inventory investment so that you can start your business with little or no budget.
  2. Flexibility: Dropshipping allows you to work from anywhere and at any time, as long as you have an internet connection.
  3. Wide Range of Products: With drop shipping, you can offer a wide range of products without worrying about inventory management. Sell whatever you want from multiple suppliers.
  4. Minimal Risk: Dropshipping is less risky than traditional retail because you don’t have to hold inventory.

Seven steps on how to start a dropshipping business in Nigeria

Now that we know what dropshipping is and understand its benefits, how do you start it in Nigeria? 

Step 1: Choose your niche and products

The first step in starting a dropshipping business is to choose a niche and the products you want to sell. A niche is a specific area of focus within a larger market. Choosing a niche you are interested in and knowledgeable about is essential. It will make it easier to identify the best products to sell, and you can create marketing plans that’ll resonate with your target audience.

Once you’ve chosen your niche, research the best products to sell. Look for products that are in demand, have a high-profit margin, and are accessible to source from reliable suppliers. You can use tools like Google Trends, Amazon Bestsellers, and Oberlo to help you find popular products.

Step 2: Research suppliers

There are various online suppliers, depending on what you want to sell. However, your dropshipping business’s success depends on finding reliable suppliers who can provide quality products at competitive prices. 

When researching suppliers, look for those who have a good reputation, offer fast shipping, and have a wide range of products.

There are many dropshipping suppliers that you can use, including AliExpress, SaleHoo, and many more. You can also consider using local suppliers in Nigeria to reduce shipping costs and improve delivery times.

Step 3: Create your online store

Now that you have chosen your niche, products and a reliable supplier, it’s time to create your online store or decide on the platform you’d use for sales. 

You can use e-commerce platforms like Shopify, WooCommerce, or WordPress to set up your store or decide to sell on platforms like Instagram, Snapchat, and WhatsApp. 

However, while creating your online store, choose names or domain names that are easy to remember. Then design your website and add your products. Ensure your website is easy to navigate, visually appealing, and mobile-friendly.

Step 4: Research delivery options

Your dropshipping success or failure depends mainly on delivery, especially in the Nigerian market. So therefore, to run a successful dropshipping business, you must either deal with reputable delivery agents or partner with your hosting platforms, such as Shopify, to set up delivery. 

Step 5: Set up a payment platform

This should be pretty straightforward. However, Shopify provides payment apps and getaways to set up your payment processor. Also, since many of your transactions with supplies will involve foreign currency, you can set up your payments with  Grey.

With Grey, you can send money to any foreign account, including your supplier’s account, without any stress or hidden fees. 

You can also use it to receive payments from your earnings if you’re dropshipping with partners like Amazon FBA.

Step 6: Market your business

Now that your online store is running, it’s time to start marketing your business. There are many ways to promote your dropshipping business, including;

  • Social media marketing: Use platforms like Facebook, Instagram, and Twitter to reach your target audience and promote your products.
  • Content marketing: Create blog posts, videos, and other content that educates your audience about your products and industry.
  • Influencer marketing: Partner with influencers in your niche to promote your products to their followers.
  • Search engine optimization: Optimize your website for search engines to improve your rankings and drive more traffic.

Step 7: Manage your business

As your dropshipping business grows, it’s essential to manage it effectively. This includes tracking inventory, promptly fulfilling orders, and providing excellent customer service.

You’ll also need to continually analyze your business metrics, such as your conversion rate, customer acquisition cost, and lifetime value. This information will help you identify areas where you can improve your business and make data-driven decisions.

In conclusion, dropshipping is a viable business model for entrepreneurs looking to start an online business in Nigeria. 

However, starting a dropshipping business requires research, planning, and execution. When it comes to sending and receiving funds, as that is one the major challenge faced by Nigerians, it is important to sign up for reliable platforms makes it easier to transact globally and that where Grey comes in.

Grey allows you to open a foreign currency account to receive payments from anywhere. Get a free account today to make international payments or convert foreign currencies to Nigeria Naira.

‍

Last updated:

October 13, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

What is a W-2 form? How to read yours

•

•

2 min read

Tax season can be confusing, especially when you are trying to figure out how much you earned and how much tax you paid. Your W-2 form helps you understand both. What is a W-2? It is a US tax form your employer sends you each year. It shows your total earnings and the taxes taken out of your pay. You need it to file your income tax return.

Your employer generally sends your W-2 by January 31 for the previous year. The form has different boxes showing your wages, taxes, and other details about your pay.

If you work as an employee, you will usually receive a W-2. Independent contractors generally receive a 1099 instead. Knowing what a W-2 means and how to read yours can help you file your taxes correctly. Let’s look at what the boxes on your form mean.

What is a W-2 form?

A W-2 form shows how much you earned from your job during the year and how much tax your employer took out of your pay. You need it to file your US income tax return and report your earnings correctly.

Your employer prepares and sends you the form. If you worked for multiple employers during the year, each one should give you a separate W-2. Check your name, wages, and tax details when it arrives to make sure everything is correct.

The deadline for employers to send W-2 forms is generally January 31 each year. The form covers the previous tax year, so your W-2 received in January 2027 will usually report your 2026 earnings.

A W-2 reports what you earned and the taxes withheld. A W-4, on the other hand, helps your employer determine how much federal income tax to withhold from your paycheck. Understanding the difference between the two forms can help you manage your tax paperwork and avoid confusion when filing your return.

How to read your W-2 box by box

Your W-2 form contains several boxes that show your earnings and the taxes taken from your paycheck. Knowing what each box means helps you check your details before filing your tax return.

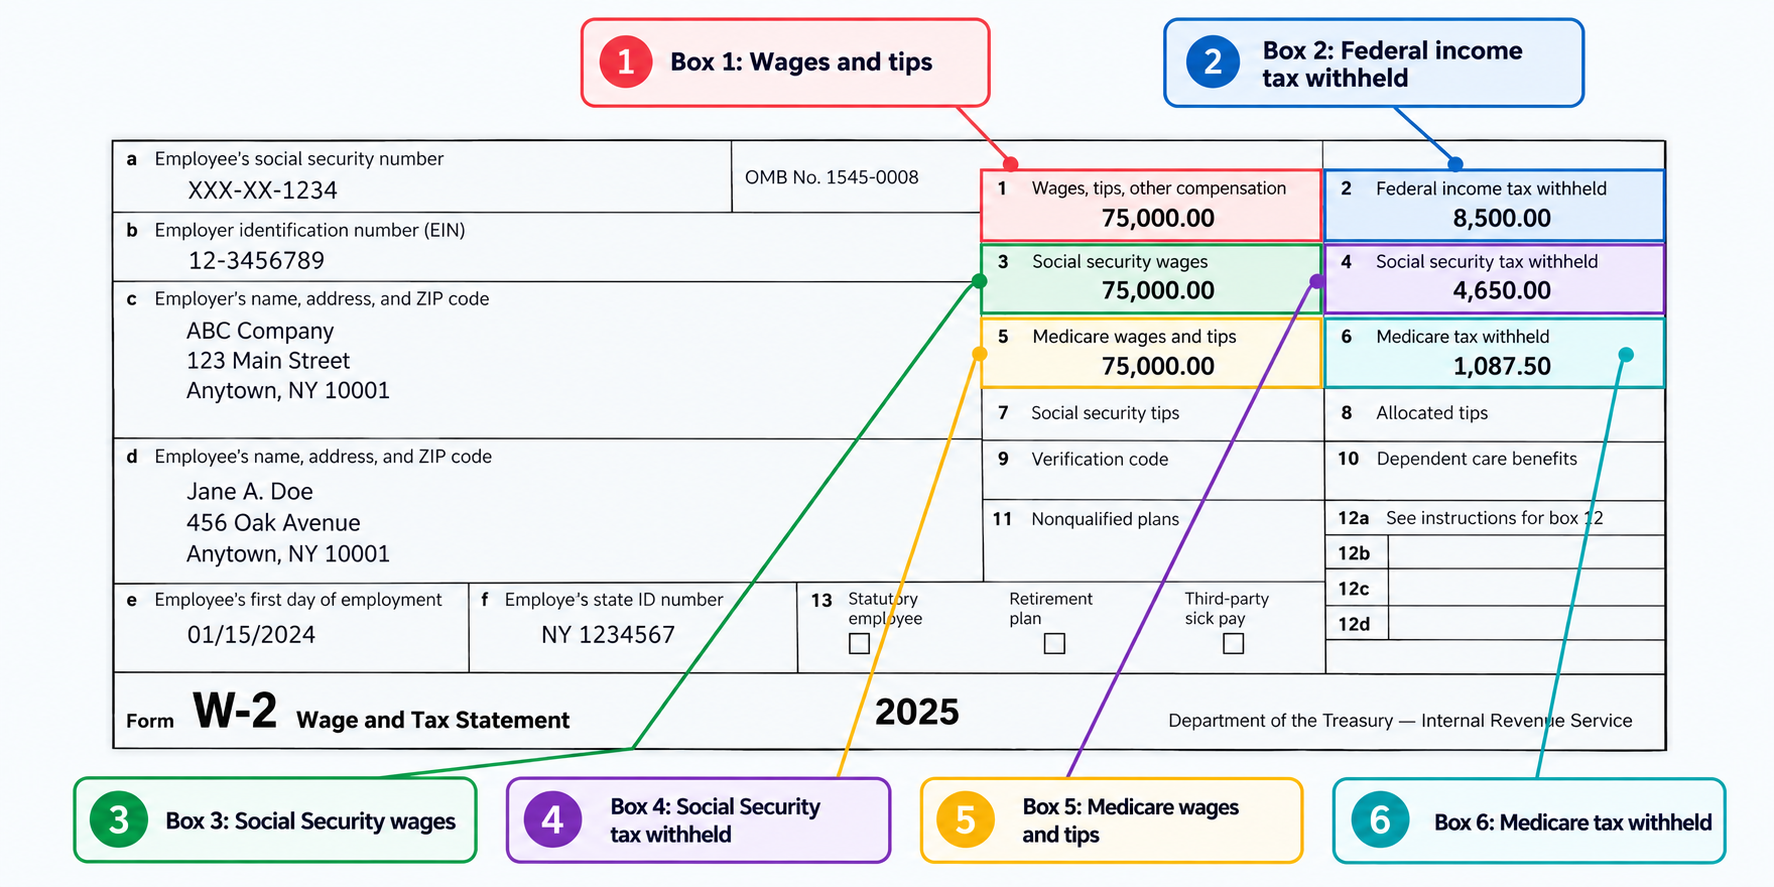
An annotated W-2 form with callouts on the wages, withholding, Social Security and Medicare boxes.
  • Box 1: Wages and tips. Shows the income subject to federal income tax.
  • Box 2: Federal income tax withheld. Shows how much federal income tax your employer took from your pay.
  • Box 3: Social Security wages. Shows the earnings subject to Social Security tax.
  • Box 4: Social Security tax withheld. Shows the Social Security tax deducted from your paycheck.
  • Box 5: Medicare wages and tips. Shows the earnings used to calculate Medicare tax.
  • Box 6: Medicare tax withheld. Shows the Medicare tax withheld from your pay.

These boxes help you understand your reported income and tax payments. Compare the figures with your pay records, and contact your employer if you notice any errors. Correct information helps you file your tax return accurately.

W-2 vs. 1099: What is the difference?

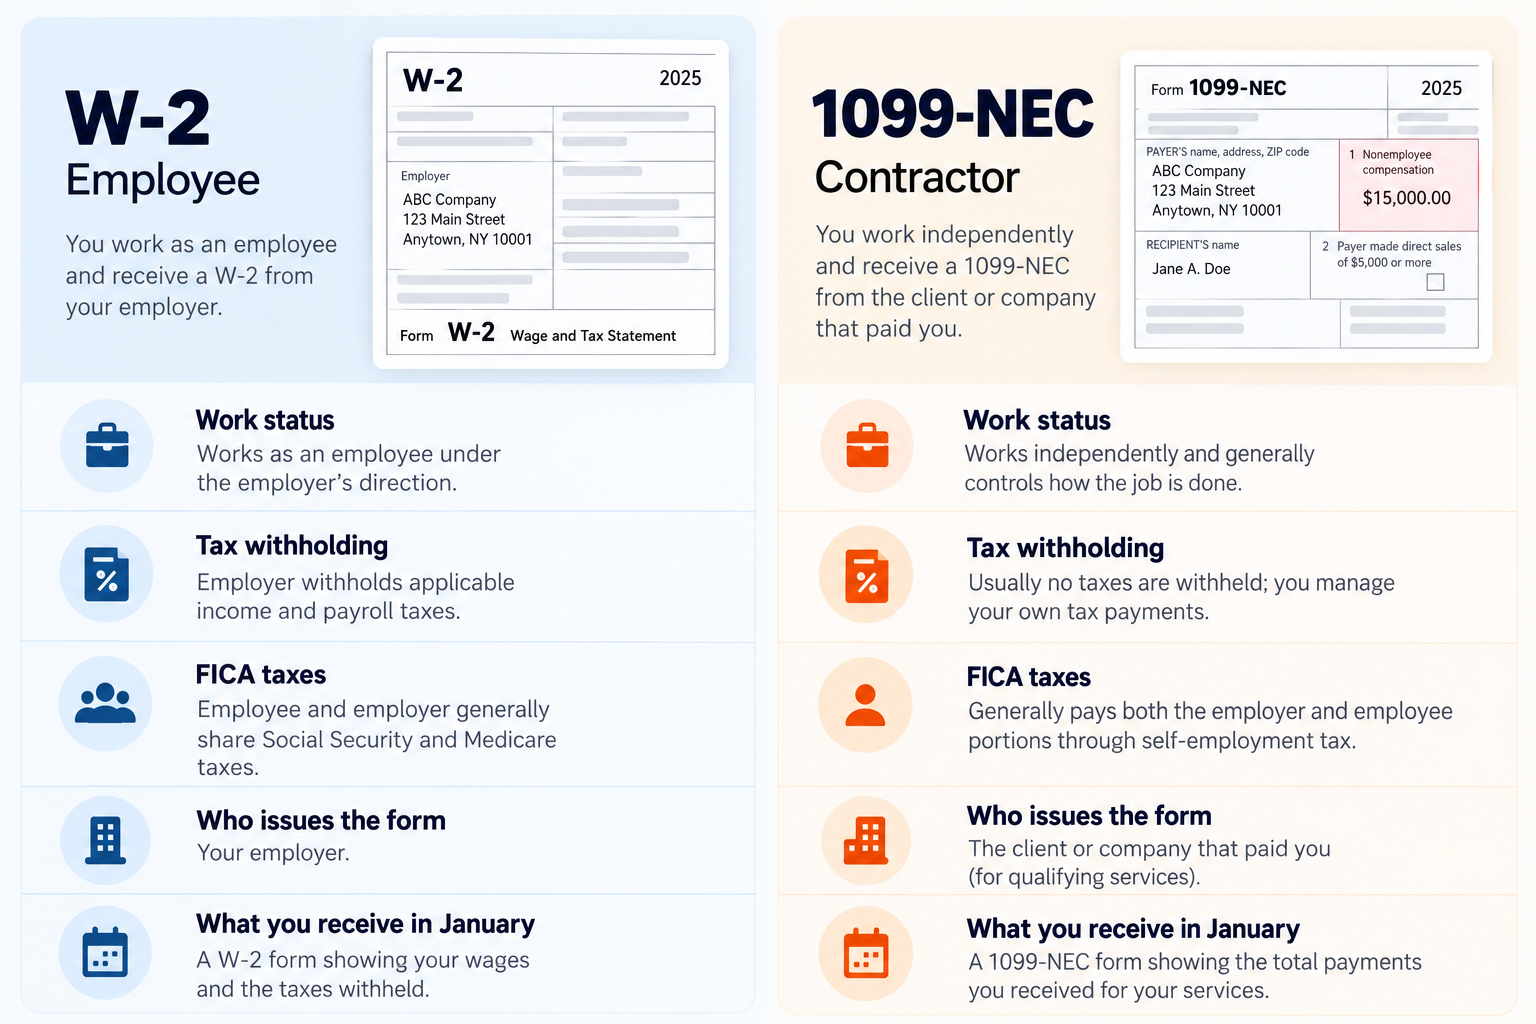
The main difference between a W-2 and a 1099-NEC is your work status and how you pay taxes. A W-2 is for employees, while a 1099-NEC is generally used to report payments to independent contractors. Understanding the difference between 1099 and W-2 can help you know which form applies to your work.

Comparison graphic showing the differences between a W-2 employee and a 1099 contractor.

Your classification affects how you handle taxes and other work responsibilities. If you are unsure whether you are an employee or an independent contractor, look at the nature of your working relationship, not just the form you receive.

What to do if your W-2 is wrong or missing

If your W-2 has the wrong income, tax details, or Social Security number, or you have not received it, do not ignore the problem. You need the correct information to file your tax return.

Contact your employer first: Explain what is wrong or ask when your missing W-2 will arrive. If your original form has an error, your employer can issue a corrected form called Form W-2c. Check the updated details before filing your taxes.

Contact the IRS if the problem continues: If your W-2 is still missing or has not been corrected by the end of February, call the IRS at 800-829-1040 for help. The IRS can contact your employer and explain your next steps.

What if the deadline is near: If you cannot get your W-2 in time to file, the IRS may direct you to use Form 4852, which serves as a substitute. Use your pay records to estimate your wages and taxes accurately. If you already filed using incorrect figures, you may need to submit an amended tax return.

Getting paid across borders

Getting paid by a US employer or client should not be difficult just because you live in another country. You still need a reliable way to receive your money, manage it in dollars, and use it where you live. This is where getting paid across borders becomes important, especially for freelancers, remote workers, and businesses working with international clients.

Grey helps you receive international payments through a foreign currency account. With a Grey USD account, you can share your account details with eligible US employers or clients to get paid from the US without relying on a traditional US bank account. You can then keep your money in dollars or convert it to your local currency when you need it.

To get started, you can open a USD account with Grey, complete identity verification, and check the available receiving options and fees for your location. This makes it easier to manage your international earnings from one place.

Frequently asked questions about the W-2 form

What is a W-2 form?

A W-2 form is an official US tax document that shows how much you earned from your employer during the year and how much tax was withheld from your pay. You use it to report your earnings and taxes when filing your annual income tax return.

When should I get my W-2?

Employers generally must send your W-2 by January 31 each year for the previous tax year. You may receive it by mail or through your employer’s online payroll portal. If it has not arrived by early February, contact your employer to confirm when it will be available.

How do I read a W-2?

Box 1 shows wages subject to federal income tax, while Box 2 shows federal income tax withheld. Boxes 3 and 4 cover Social Security wages and tax, while Boxes 5 and 6 show Medicare wages and tax withheld.

What is the difference between a W-2 and a 1099?

W-2 employees generally have income and payroll taxes withheld by their employers. 1099 contractors usually receive payments without tax withholding and must manage their own tax payments, including self-employment taxes when applicable.

What if my W-2 is wrong?

Contact your employer’s payroll department as soon as possible and explain the error. Ask them to issue a corrected form called Form W-2c. Check the corrected details carefully and use accurate information when filing your tax return.

What if I do not receive my W-2?

Contact your employer first to request your missing form. If it has not arrived by the end of February, call the IRS at 800-829-1040 for assistance. Keep your pay stubs handy to help estimate your earnings and taxes if needed.

USDC vs USDT: 11 major differences

•

•

2 min read

The rise of stablecoins has made it possible to hold and transfer digital dollars without relying on traditional bank transfers for every transaction. Two of the most widely used options are USDT (Tether) and USDC (USD Coin). Although both aim to maintain a value of $1 per token, they differ in several important ways that can affect how you use them.

Understanding USDT vs USDC starts with knowing who issues each stablecoin. Tether issues USDT, while Circle issues USDC. Both use reserves to support their dollar pegs, but their reserve disclosures, reporting practices, regulatory approaches, blockchain availability, and adoption differ.

USDT generally has a larger circulating supply and broad trading support, making it popular across crypto markets. USDC is known for its regular reserve attestations and emphasis on transparency and regulatory compliance.

These differences matter if you want to trade crypto, transfer money internationally, or hold digital dollars. This guide compares 11 major differences to help you understand how each stablecoin works and which may suit your needs.

What is the main difference between USDT and USDC?

The main differences between USDT and USDC are their issuer, reserve transparency, and adoption across crypto markets. USDT is issued by Tether, while USDC is issued by Circle. Both aim to maintain a value of $1 per token, but they differ in how they disclose their reserves, approach regulatory compliance, and support trading and transfers across blockchain networks.

USDT is widely used for crypto trading because of its large circulating supply and broad exchange support. USDC emphasises reserve transparency, with backing primarily in cash and short-term US Treasury securities.

Neither stablecoin is risk-free. Their value can temporarily move away from $1, and their availability, transaction costs, and protections depend on the platform and blockchain you use.

Feature USDT (Tether) USDC (USD Coin)
Issuer
Tether Circle
Dollar peg
Aims for $1 Aims for $1
Reserve composition Primarily US Treasury bills and other assets, including repurchase agreements and money market funds Cash and eligible cash-equivalent assets, including short-term US Treasuries and overnight Treasury-backed repurchase agreements
Reserve reporting
Independent quarterly attestations Monthly third-party reserve attestations
Market adoption
Generally broader global trading use Strong adoption among institutions and regulated financial services
Blockchain support
Multiple networks, including Tron and Ethereum Multiple networks, including Ethereum and Solana

‍

Circle publishes monthly third-party reserve assurances, while Tether also publishes independent reserve attestations. These are attestations, not full independent audits of all reserve holdings.

Which one should you choose?

  • USDT: May suit you if you prioritise exchange liquidity and broad trading-pair support.
  • USDC: May suit you if you prioritise published reserve disclosures and its institutional payment ecosystem.

How the reserves compare

When comparing USDT vs USDC, one of the biggest differences is how each stablecoin backs its dollar peg. USDC, issued by Circle, is backed by cash and short-term US Treasury securities held in its reserve structure. USDT, issued by Tether, once held significant amounts of commercial paper but has since shifted its reserves toward US Treasury bills and other assets.

Both issuers publish independent attestations to provide information about their reserves and liabilities. However, an attestation reflects the position at a specific point in time. It does not guarantee continuous backing, immediate access to every reserve asset, or protection against legal and liquidity problems during a sudden market sell-off.

Why does this matter to you? If you hold stablecoins to preserve dollar value or plan to convert them into cash, reserve quality and redemption access are important considerations. Before cashing out, learn how USDC to USD conversion works so you understand the process and what to consider when turning your stablecoins into dollars.

Transparency, audits, and regulation

When comparing USDT vs USDC, transparency and regulation can help you understand how each stablecoin manages its reserves and reports financial information. However, it is important to distinguish between an attestation and a full audit.

An attestation checks whether reported assets and liabilities match at a specific point in time. A full audit examines financial records, transactions, internal controls, and other relevant information over a defined period. Both provide useful information, but neither automatically guarantees that a stablecoin will maintain its dollar peg under every market condition.

Circle, the issuer of USDC, operates within applicable US regulatory frameworks, including state money transmission requirements. Tether is registered with FinCEN as a Money Services Business (MSB). However, MSB registration is not the same as federal approval or insurance of a stablecoin's reserves.

If you use stablecoins for international payments, consider their transparency, regulatory status, and availability across your preferred platforms. Understanding how USDC compares with other stablecoins for global transactions can help you weigh these factors before choosing a suitable option.

Network support and transaction costs

When comparing USDT vs USDC, the blockchain you choose can make a big difference in how much you pay to send money. Both stablecoins operate across multiple networks, but their availability varies. USDT is widely used on Tron and Ethereum, while USDC is available on Ethereum, Solana, Base, and other supported blockchains.

Transaction fees depend mainly on the network, its congestion, and the type of transaction, rather than the stablecoin itself. For example, sending USDC on Ethereum can cost several dollars during busy periods, while transferring USDC on Solana typically costs a fraction of a cent. Base can also offer low-cost transfers. Tron is a popular option for USDT transfers, often with different fees depending on your wallet and available network resources.

Network Typical fee level What it means for you
Ethereum Can be several dollars or more Costs can rise when the network is busy.
Solana Usually a fraction of a cent for a basic transfer A low-cost option for sending USDC.
Base Generally low Can make USDC transfers cheaper than Ethereum mainnet.
Tron Varies with account resources and wallet fees Commonly used for USDT transfers.

‍

Ethereum fees fluctuate with demand, while Solana's standard transaction fees are generally very low.

What should you choose? If you are sending USDC, compare Solana, Base, and Ethereum before confirming your transaction. Check the estimated fee displayed in your wallet or exchange, and make sure the recipient supports the same network. Also account for any withdrawal or service fees charged by your platform, as these are separate from blockchain fees.

Also read: USDC on Solana compared with Ethereum

Converting USDT and USDC into money in your bank account

To turn stablecoins into money you can spend through a bank account, you need a platform that converts cryptocurrency into traditional currency. One option is to use a crypto exchange such as Coinbase or Kraken, where supported. You can deposit USDT or USDC, sell your tokens for USD or another available currency, and withdraw the funds to a linked bank account.

Another option is to use an off-ramp service. Circle Mint, for example, supports eligible institutional customers converting USDC into USD. Access depends on your location and account eligibility.

Once your funds are converted, a multi-currency account can help you manage your dollars and international payments. [Grey](https://app.grey.co/auth/register?) supports sending and receiving USDC and offers multi-currency financial services for eligible users. Depending on your account and location, this can help you manage USD alongside cross-border transactions without converting everything immediately into your local currency. Before transferring funds, check supported networks, conversion rates, fees, and withdrawal options to understand the full cost of moving your money.

Frequently asked questions

1. Is USDC safer than USDT?

USDC may appeal to users who prioritize reserve transparency and regular reporting, while USDT benefits from broad market adoption and liquidity. However, neither stablecoin is risk-free. Both depend on their issuers, reserve management, redemption arrangements, and market conditions. Compare their disclosures and consider your intended use before choosing either option.

2. Which stablecoin is more widely accepted?

USDT generally has broader adoption across global cryptocurrency exchanges and trading pairs, particularly in markets where stablecoins support everyday crypto trading. USDC is also widely supported and has strong adoption among institutions and payment platforms. Acceptance varies by exchange, wallet, blockchain network, and country, so check compatibility before transferring funds.

3. Can you swap USDT for USDC?

Yes, you can swap USDT for USDC through supported cryptocurrency exchanges and decentralized trading platforms. You typically deposit USDT, select USDC as the asset you want to receive, and confirm the transaction. Check the exchange rate, trading fees, network costs, and withdrawal options before completing your swap.

4. Do USDT and USDC ever lose the dollar peg?

Yes, both USDT and USDC can temporarily trade above or below $1. These deviations may occur during market volatility, liquidity shortages, or concerns about an issuer's reserves. Although both aim to maintain their dollar pegs, neither guarantees a constant market price. Check current market prices before buying or selling.

5. Which has lower transfer fees?

Neither USDT nor USDC always has lower transfer fees. Costs depend mainly on the blockchain network, network congestion, and any exchange or wallet charges. For example, transfers on Solana or Base can be inexpensive, while Ethereum fees may rise during busy periods. Compare the estimated total cost before sending.

6. How do you turn a stablecoin into cash?

You can convert USDT or USDC into cash by selling it through a supported cryptocurrency exchange and withdrawing the proceeds to your bank account. Alternatively, eligible services may offer stablecoin conversion and payment options. Check your country's availability, supported networks, exchange rates, withdrawal fees, and identity verification requirements before proceeding.

How to earn yield on USDC: Best options in 2026

•

•

2 min read

USDC is a stablecoin designed to maintain a value close to one US dollar, making it an option for people who want to hold digital dollars without the usual price swings associated with cryptocurrencies like Bitcoin. However, holding USDC in a wallet does not automatically generate interest. To earn a return, you need to invest your holdings in a programme or platform that pays a yield.

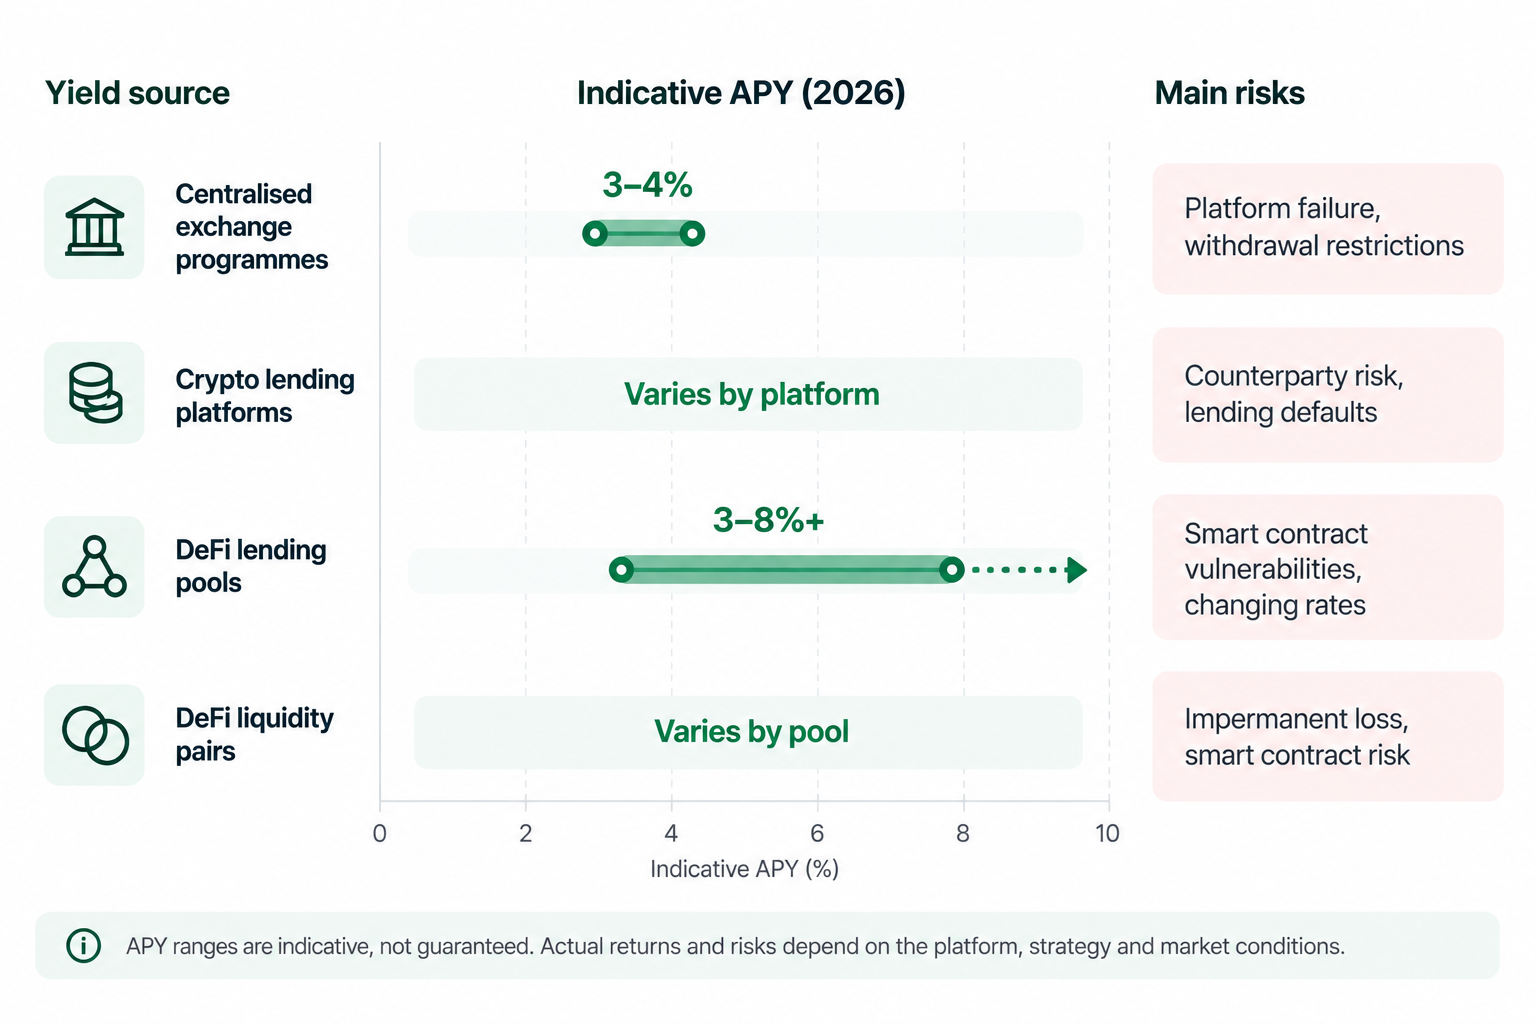
USDC itself pays no interest. Yield comes from lending it out through a centralised exchange programme, a crypto lending platform, or a DeFi protocol such as a lending pool or liquidity pair. Rates ranged from about 2 to 8% APY in 2026, depending on the platform, strategy and market conditions.

Each option comes with different levels of risk, access requirements and withdrawal conditions. Before choosing where to earn yield, understand how returns are generated, whether your funds are protected, and what could happen if a platform fails or a smart contract is exploited.

Does USDC pay interest on its own?

No, holding USDC in a crypto wallet does not earn interest by itself. USDC is a stablecoin designed to maintain a value close to one US dollar, but simply owning it does not generate additional income. Whether it sits in a personal wallet or an exchange account, your balance remains unchanged unless you receive additional USDC through another transaction or service.

To earn yield, you need to use a separate financial product built on top of USDC. These products generate returns through activities such as lending your stablecoins to borrowers, supplying liquidity to decentralised finance (DeFi) protocols, or participating in yield programmes offered by cryptocurrency exchanges.

Each option works differently and carries its own risks. A lending platform may pay interest from borrower repayments, while a DeFi protocol may distribute fees or lending revenue to participants. Centralised exchanges may offer promotional rates or rewards under specific conditions.

Before depositing USDC into any yield product, understand how returns are generated, what fees apply, and whether you can withdraw your funds when needed. Yield is never guaranteed.

Also read: How USDC compares with USDT

Centralised exchange and lending platforms

Centralised exchanges and crypto lending platforms allow you to earn yield by depositing your USDC into programmes that generate returns. Exchange earn programmes may lend your USDC to borrowers or use other permitted strategies to generate revenue, sharing a portion of the earnings with you.

Crypto lending platforms work similarly, connecting you with borrowers and paying interest on the funds you supply.
The annual percentage yield (APY) you receive depends on the platform, market demand, lending activity and programme conditions. Rates can change, and promotional offers may have limits or eligibility requirements.

Custody is another important consideration. When you deposit USDC into a centralised platform, the platform typically controls your assets rather than you holding the private keys directly. It may lend, transfer or otherwise use your deposited coins according to its terms.

This exposes you to counterparty risk. If the platform becomes insolvent, freezes withdrawals or suffers a hack, you may struggle to access your funds or lose them entirely. Before depositing your USDC, review the withdrawal terms, fees, security measures and how the platform uses your assets.

DeFi options: lending pools and liquidity pairs

Decentralised finance (DeFi) offers another way to earn yield on USDC without relying on a traditional financial intermediary. Two common options are lending pools and liquidity pairs, each generating returns in different ways.

With a lending pool, you deposit USDC into a protocol where borrowers can access the funds and pay interest. A portion of that interest is distributed to depositors as yield. Your returns depend on borrowing demand, utilisation rates and the protocol’s rules.

With a liquidity pair, you deposit USDC alongside another cryptocurrency into a trading pool. Traders use this pool to swap assets, and liquidity providers may earn a share of trading fees. However, the value of the two deposited assets can change relative to each other, creating impermanent loss.

Both strategies carry risks. Smart contract bugs can expose deposited funds to theft or loss. Impermanent loss can reduce returns compared with simply holding the assets. Depegging occurs when USDC falls below its intended one-dollar value, reducing the value of your holdings even when the yield remains positive.

How the main risks compare

When you earn yield on USDC, your biggest risks depend on where you deposit your funds and how the platform generates returns. Counterparty risk, smart contract risk and depeg risk can all affect how much you earn and whether you recover your initial deposit.

Counterparty risk arises when you trust a centralised exchange or lending platform with your USDC. If the provider fails or freezes withdrawals, you may lose access to your funds. Smart contract risk affects you when a vulnerability in a DeFi protocol allows your deposited funds to be stolen or lost. Depeg risk means your USDC falls below its intended $1 value, reducing the value of your holdings.

Chart comparing USDC yield options by risk and return.

There is no universal ranking because your exposure depends on the product you choose. However, higher advertised APY usually means higher risk. Before depositing, consider how returns are generated, who controls your funds and what could go wrong.

Your choice of blockchain also matters. Learn how USDC on Solana compares with Ethereum when considering transaction fees, network activity and the platforms available to you.

USDC yield vs a bank savings account

USDC yield can offer a potentially higher return than a regular savings account, but you give up an important protection: USDC does not have government-backed deposit insurance. Your returns depend on the platform and strategy you use, and higher yields often come with greater risk. A bank savings account may offer less, but eligible deposits have protection and more predictable access to your money.

Before choosing USDC for yield, consider whether you can afford the risks, including platform failure, smart contract vulnerabilities and changes in USDC’s value. It is generally better to keep emergency funds in an insured bank account rather than expose money you need urgently to crypto-related risks.

USDC can also make moving money across borders easier. For example, if you need to send money from the US to Nigeria, you can use a platform that supports USDC transfers and local withdrawals. With Grey, you can send, receive and spend USDC, then convert your balance and withdraw funds to a supported local bank account.

The right choice depends on your priorities: bank deposits for protection, USDC for global access and potential yield.

Frequently asked questions about how to earn yield on USDC

1. Is earning yield on USDC safe?

Earning yield on USDC carries risks, including platform failure, smart contract vulnerabilities and loss of funds. Although USDC is designed to maintain a one-dollar value, your investment is not guaranteed. Review the platform’s security, withdrawal terms and yield strategy before depositing funds, and never invest money you cannot afford to lose.

2. What is a typical USDC APY in 2026?

USDC yield varies by platform, market conditions and strategy. In 2026, some centralised reward programmes offer around 3–4% APY, while DeFi lending may offer approximately 3–8% or more. These are indicative ranges, not guaranteed rates. Check current offers, fees and risks before choosing a platform.

3. Do you pay tax on USDC yield?

Yes, USDC yield may be taxable, depending on your country’s tax laws and how you earn it. In the United States, rewards are generally reportable as income. Keep records of payments, dates and amounts, and consult a qualified tax professional to understand your reporting obligations.

4. Can you lose your USDC principal earning yield?

Yes, you can lose some or all of your USDC principal. Platform insolvency, lending defaults, smart contract exploits and liquidity problems can prevent withdrawals or cause losses. USDC can also trade below one dollar. Assess the risks carefully, diversify where appropriate and avoid committing essential savings.

5. What is the difference between USDC yield and USDC staking?

USDC yield usually comes from lending, reward programmes or providing liquidity through a platform or DeFi protocol. Staking typically involves locking cryptocurrency to support a proof-of-stake blockchain. USDC does not use proof-of-stake itself, so products marketed as USDC staking generally involve a different yield-generating mechanism.

6. How do you convert USDC yield into cash you can spend?

First, withdraw your USDC and earn rewards to a supported exchange or financial platform. Convert the balance into your preferred currency, then withdraw it to an eligible bank account or payment method. With Grey, you can send, receive and spend USDC, subject to supported services, currencies and applicable fees.

While USDC yield offers the potential for higher returns, a bank savings account provides greater protection for eligible deposits. For international transactions, Grey gives you a practical way to send, receive and spend USDC, with access to supported currencies for your everyday financial needs.

Gift tax: How much money can you give tax-free?

•

•

2 min read

Giving money to another person may seem straightforward, but large financial gifts can come with tax reporting requirements. In the United States, the Internal Revenue Service (IRS) determines how much you can give each year before you may need to report the gift. Understanding these rules is particularly important when transferring substantial sums, sharing wealth, or planning your finances.

The good news is that exceeding the annual gift tax limit does not automatically mean you owe tax. The IRS provides a lifetime exemption that allows you to give more than the annual limit before gift tax becomes payable. Knowing the difference between the annual exclusion, reporting requirements and lifetime exemption can help you make informed financial decisions.

The IRS annual gift tax exclusion lets you give up to a set amount per recipient each year with no tax owed and no form to file. Gifts above that amount count against your lifetime exemption and require Form 709, though tax is rarely owed until the lifetime exemption itself is used up.

How much can you gift tax-free per year?

For 2026, you can give up to $19,000 per recipient per year without owing federal gift tax or generally needing to file a gift tax return. This annual exclusion applies to qualifying gifts of money or property under US Internal Revenue Service (IRS) rules.

The limit resets every calendar year, beginning January 1. This means gifts made in 2026 are counted separately from gifts made in 2025. You can give money to multiple recipients in the same year, provided each recipient’s total qualifying gifts from you stays within the annual limit.

The exclusion applies per giver and per recipient, rather than as one combined limit for all your gifts. For example, you could give $19,000 each to three people in 2026, totalling $57,000, without exceeding the annual exclusion for any recipient. If two spouses each give the same recipient $19,000, their combined gifts can reach $38,000 under their separate exclusions, subject to applicable IRS rules.

What is the lifetime gift tax exemption?

For 2026, the US lifetime gift and estate tax exemption is $15 million per individual. This is the total amount an individual can transfer through qualifying gifts during their lifetime and leave to beneficiaries at death before federal gift or estate taxes generally apply, subject to applicable rules.

The lifetime exemption works alongside the annual gift tax exclusion. While the annual exclusion allows qualifying gifts of up to $19,000 per recipient in 2026 without using the lifetime exemption, larger gifts generally count toward the $15 million limit. Gifts exceeding the annual exclusion may require you to file IRS Form 709, even when no tax is due.

The important distinction is that the lifetime gift tax exemption and estate tax exemption are shared, not separate allowances. For example, if you make $2 million in taxable gifts during your lifetime, that amount generally reduces the exemption remaining for your estate. Any unused exemption may apply to assets transferred at death, helping determine whether your estate owes federal estate tax.

When do you need to file form 709?

You generally need to file IRS Form 709 if you give more than $19,000 to one person in 2026, unless a specific exception applies. The form reports gifts exceeding the annual exclusion and helps the IRS track your use of the lifetime gift tax exemption.

The filing requirements, deadline and potential tax implications are important to understand before submitting your return.

Who Must File Form 709?

The person giving the gift is generally responsible for filing. You may need to file if your gifts to one recipient exceed the annual exclusion, you transfer certain future interests, or you elect to split gifts with your spouse.

When Is Form 709 Due?

The deadline is generally April 15 of the year following the gift. For gifts made in 2026, the filing deadline is April 15, 2027. An extension may be available, but it does not automatically extend the deadline for paying tax owed.

Does Filing Form 709 Mean You Owe Tax?

No. Filing the form does not automatically mean you owe gift tax. Gifts above the annual exclusion generally reduce your lifetime gift and estate tax exemption. Federal gift tax is typically payable only after your available exemption has been exhausted.

Gift tax vs Estate tax: how they connect

Gift tax and estate tax share one combined lifetime exemption. In 2026, the federal gift and estate tax exemption is $15 million per individual. This means large gifts made during your lifetime and assets transferred after your death generally count toward the same exemption.

If you give a substantial amount of money while alive, the portion exceeding the annual gift tax exclusion generally reduces the exemption remaining for your estate. For example, if you make $2 million in taxable gifts, that amount generally reduces your remaining exemption to $13 million, assuming no other taxable transfers or adjustments.

Alternatively, leaving the money in your estate means its value may be considered when calculating estate tax after your death. If your total taxable estate and applicable prior gifts remain within your available exemption, federal estate tax generally will not be due.

The main difference is when the transfer happens and how the assets are valued. Lifetime gifting can help transfer wealth earlier, but the best approach depends on your financial circumstances, future needs and estate planning goals.

If you're sending money as a gift to family members abroad, it's also worth considering transfer fees and exchange rates. For example, you can send money from the US to Mexico or send money from the US to India using available international transfer services. Just remember that sending money internationally doesn't automatically exempt a gift from US tax reporting requirements.

Frequently asked questions about gift taxes

Does the person receiving a Gift pay tax on it?

Generally, no. Under US federal tax rules, the recipient does not pay income tax on money received as a gift. The person giving the gift is usually responsible for any applicable gift tax reporting and payment. However, income generated by gifted assets may be taxable to the recipient.

Can you gift more than the annual exclusion without paying tax?

Yes. Gifts exceeding the 2026 annual exclusion of $19,000 per recipient may require you to file Form 709. However, the excess generally reduces your lifetime gift and estate tax exemption rather than triggering immediate tax. Gift tax usually becomes payable after the available exemption is exhausted.

Do Gifts to a spouse count toward the annual exclusion?

Generally, gifts to a US-citizen spouse qualify for the unlimited marital deduction and do not count toward the annual exclusion. Gifts to a non-US citizen spouse have a separate annual limit, which is $194,000 for 2026. Special rules may apply depending on the circumstances.

Is money sent to family abroad treated as a Gift for tax purposes?

Yes. Money sent to relatives abroad may qualify as a gift under US tax rules. If the giver is subject to US gift tax, the annual exclusion and reporting requirements may apply regardless of where the recipient lives.

Do you have to report a Gift from a foreign relative?

You may need to. US persons who receive gifts exceeding $100,000 in total from a nonresident alien individual or foreign estate generally must report them on Form 3520. Different thresholds apply to gifts from foreign corporations or partnerships.

What is the penalty for not filing Form 709 when required?

Failure to file Form 709 when required may result in penalties based on the unpaid gift tax, generally 5% per month, up to 25%. If no tax is due, penalties may differ, but the IRS can still assess consequences for noncompliance. Filing requirements should be checked carefully.

Managing money across borders involves more than understanding gift tax. Whether you are supporting family abroad, making international payments or managing everyday expenses, having the right financial tools matters. Grey offers multi-currency accounts and virtual cards that make it easier to manage international finances, pay for online services and handle supported cross-border transactions.

USDC on Solana vs Ethereum: Which should you use?

•

•

2 min read

Solana or Ethereum? Both can move the same dollar-backed stablecoin, but the difference becomes clear when speed and transaction fees matter.

Solana can settle a USDC transfer in a few seconds, usually for a fraction of a cent. Ethereum, on the other hand, can take several minutes, with fees that increase when the network is busy. For a straightforward payment, Solana can be the more practical option when keeping costs low matters.

Both versions of USDC are issued by Circle and designed to maintain a 1:1 value with the US dollar. The real choice is therefore not between two different stablecoins, but between two networks. The better option depends on where the money is going, which network the recipient supports, and whether speed, low fees or access to Ethereum’s wider ecosystem matters most.

What is the difference between USDC on Solana and Ethereum?

The main difference between USDC on Solana and Ethereum is the blockchain network used to settle your transaction, even though both versions are issued by Circle, designed to maintain a 1:1 value with the US dollar and redeemable through the same issuer. When you choose between them, you are therefore choosing a different settlement layer, with Solana generally offering faster and cheaper transfers while Ethereum can become more expensive when the network is busy.

The distinction becomes more important when you come across native and bridged USDC. Native USDC is issued directly by Circle on the blockchain where you hold it, so USDC issued natively on Solana is Circle-issued USDC on Solana, while native USDC on Ethereum is issued directly on Ethereum. This means you should not assume that every token labelled “USDC” has the same issuance structure.

Bridged USDC represents USDC that has been moved between blockchains using a bridge, rather than being directly issued by Circle on the destination network. Before sending your USDC, check the network supported by the recipient and whether you are dealing with native or bridged USDC, because sending through an unsupported network can make it difficult or impossible to recover your funds.

How fees and settlement times compare

When you compare Ethereum and Solana for USDC transfers, the biggest differences you'll notice are the network fee and how quickly your transaction settles. Ethereum fees change with supply and demand, so when more people compete for limited block space, the base fee rises and you may pay an additional tip to have your transaction prioritised. Solana generally offers lower and more predictable fees, which can make it more practical for frequent transfers.

On Ethereum Layer 1, you may pay around 0.01–0.20, with settlement taking roughly 12 seconds to several minutes depending on network conditions and the level of finality you require. Solana typically settles transactions within seconds at a fraction of a cent.

Ethereum Layer 2 networks can reduce the cost further by processing transactions away from the main chain and later posting transaction data to Ethereum. This gives you faster execution and lower fees, although the final settlement process works differently from a direct Layer 1 transaction. Network conditions change, so check current fees before sending.

Also read: USDC to USD: How to convert your stablecoin to cash

What happens if you send USDC to the wrong network?

Sending USDC to the wrong network can put your funds at risk, and whether you can recover them depends on where the money was sent and who controls the receiving wallet. If the destination supports the network you used, recovery may be possible, but if it does not, you may need help from the exchange or wallet provider, with no guarantee that the funds can be recovered.

Before sending, check that the network selected on your platform matches the network supported by the recipient. Do not rely on the wallet address alone, because the same address format can sometimes work across different networks. If you use a USD bridge to move USDC between blockchains, confirm the destination network and the type of USDC being received before approving the transaction.

For a large transfer, send a small test amount first, then check the network name, token and destination address before sending the remaining balance. Once a blockchain transaction is confirmed, it generally cannot be reversed.

Also read: How to convert and use USDC in Nigeria

How to choose a network for your transfer

Choosing a network for your USDC transfer comes down to three things: how much you are sending, where the money is going and how quickly you need it to arrive. Start with the destination, because the cheapest or fastest network is not useful if the recipient’s wallet or exchange does not support it. Check the supported networks before you enter the amount or confirm the transaction.

Next, consider the amount you are sending. For a small transfer, a network with very low transaction fees can help you avoid losing a noticeable percentage of your money to fees. For a larger transfer, the fee may matter less, but you should still confirm that the network supports the exact USDC you are sending.

Finally, consider urgency. If you need the money to arrive within seconds or minutes, a faster network may make more sense. If timing is flexible, you can compare fees and choose the cheaper option. Whatever you choose, confirm the network on both sides before sending.

Open a multi-currency account to send and receive USDC

Turning USDC into local currency usually involves one more step after receiving your payment: moving the funds from your crypto wallet or exchange into a bank account where you can spend them. A multi-currency account can fit between these steps, giving you a place to receive and hold funds before converting them into the currency you need.

With Grey, you can open a multi-currency account and use it to manage your international payments in one place. Once you receive USDC, you can move the funds through the available conversion and withdrawal options rather than immediately sending everything to a local bank account. This can give you more control over when you convert and where your money goes.

The process is straightforward: receive your USDC, convert or off-ramp it through a supported route, then withdraw the resulting currency to your local bank account. The exact steps depend on the currencies and payment routes available to you, so check the supported options before starting your transfer.

Frequently asked questions

Is USDC on Solana the same as USDC on Ethereum?

USDC on Solana and USDC on Ethereum are both issued by Circle and designed to maintain a 1:1 value with the US dollar, but they operate on different blockchains. The main differences are transaction speed, network fees and where you can send or receive each version of USDC.

Which network has lower USDC fees?

Solana generally has lower USDC transaction fees than Ethereum, with transfers typically costing a fraction of a cent. Ethereum fees can increase when the network is busy because users compete for limited block space. Before sending, check the current network fee and make sure the recipient supports your chosen network.

Can I send USDC from Solana to an Ethereum wallet?

You cannot send native USDC on Solana directly to an Ethereum-only address and expect it to arrive correctly. To move USDC between networks, you need a supported bridge or exchange that handles the transfer. Always confirm both the sending and receiving networks before approving the transaction.

What happens if I pick the wrong network?

Choosing the wrong network can make your USDC difficult or impossible to recover, depending on the receiving wallet or exchange. Before sending, check the network supported by the recipient and make sure it matches the network selected in your wallet. For larger amounts, consider sending a small test transaction first.

Is USDC on Solana safe?

USDC on Solana can be safe when you use the official, native version of USDC and send it through a supported wallet or exchange. Your biggest risks usually come from choosing the wrong network, using an unsupported token or sending funds to an incorrect address. Always verify the token and destination.

How do I convert USDC to my local currency?

To convert USDC into your local currency, you typically send it to a supported exchange or financial platform, sell or convert the USDC, then withdraw the resulting funds to your bank account. A multi-currency account can also give you a place to receive and manage funds before converting them.

How to save money in USD in Nigeria: Best ways and apps

•

•

2 min read

If you saved NGN 1,000,000 in a Nigerian bank account five years ago, that money has lost more than half its purchasing power in dollar terms. The naira has depreciated from roughly NGN 410/USD to over NGN 1,500/USD since 2021. Saving in naira means watching your wealth shrink. Saving in dollars means preserving it.

Nigerians can save in USD through domiciliary accounts at commercial banks, fintech apps like Grey, PiggyVest, and Bamboo, or by holding dollar-denominated stablecoins. Each method has different costs, access requirements, and risk profiles. The best option depends on how much you're saving, how quickly you need access, and how comfortable you are with digital platforms.

This guide compares every method available in Nigeria for saving in dollars, with the real costs, risks, and trade-offs for each. For a broader look at saving in foreign currencies from anywhere, see how to save in foreign currency.

Why save in USD from Nigeria?

The case for saving in dollars is straightforward: the naira has lost value against the dollar consistently for over a decade. This isn't a temporary dip. It's a structural trend driven by Nigeria's dependence on oil exports, foreign exchange shortages, and monetary policy decisions.

Saving in naira means your money buys less every year, even when the number in your account stays the same or grows. A Nigerian who saved NGN 5 million in 2020 had roughly $13,000 at the time. That same NGN 5 million is now worth under $3,500. The account balance didn't change. The purchasing power collapsed.

Saving in USD preserves your purchasing power relative to the global economy. Your dollar savings buy the same amount of imported goods, school fees, medical treatment, and international services regardless of what happens to the naira.

That said, saving in USD isn't without risk. If the naira strengthens (it has happened in short bursts, usually after CBN interventions), your dollar savings lose value in naira terms temporarily. Converting naira to dollars also carries a cost: the exchange rate spread, which runs 1 to 5% depending on the method. The decision to save in dollars should be a long-term one, not a short-term speculation on the naira.

Don't convert your rent money or next month's food budget to dollars. Keep 3 to 6 months of living expenses in naira for immediate needs. Save in dollars with what you can afford to hold for at least 6 to 12 months.

Method 1: Domiciliary accounts

A domiciliary account ("dom account") is a foreign currency account at a Nigerian commercial bank. You hold USD, GBP, or EUR in the account and can deposit or withdraw in those currencies. GTBank, Access Bank, Zenith Bank, First Bank, and UBA all offer them. For a step-by-step guide, see how to open a domiciliary account.

Requirements: BVN, NIN, a valid ID (international passport or national ID card), a utility bill not older than 3 months, two reference letters (some banks still require these; others have dropped the requirement), and a minimum opening deposit (typically $100 to $500, depending on the bank). The process requires a branch visit, and the documentation verification can take 3 to 7 business days.

Pros: Regulated by CBN, funds are NDIC-insured (up to NGN 500,000 equivalent per depositor per bank), physical branch access for withdrawals, and you can receive international wire transfers directly into the account via SWIFT.

Cons: The biggest issue is sourcing dollars. Nigerian banks don't sell USD to individuals at the official rate. You need to deposit dollars you already have, whether from exports, remittances, freelance income, or the parallel market. Interest is typically 0% on most domiciliary accounts. Withdrawals can be restricted during FX shortages, with some banks limiting cash withdrawals to $5,000 per month. Monthly maintenance fees of $1 to $5 are common, and some banks charge for incoming wire transfers.

Who should use this: Anyone with large dollar savings ($10,000+) who wants maximum regulatory protection and doesn't need frequent access. The NDIC insurance and CBN regulation make this the safest option on paper.

Method 2: Fintech apps

Several Nigerian fintech apps let you save in dollars or dollar-equivalent instruments from your phone. They're faster to set up than dom accounts, don't require a branch visit, and typically have lower minimum deposits. The trade-off is different (and sometimes less clear) regulatory protection.

PiggyVest: One of Nigeria's most popular savings apps. Offers USD savings with up to 7% annual interest through their dollar savings feature. You buy dollars within the app at the prevailing rate.

Pros: User-friendly interface, competitive interest rates, automated savings features.

Cons: $20 fee to transfer USD out to a domiciliary account, USD isn't always available for purchase (demand often exceeds supply), and the platform is not a bank, so deposit insurance works differently. Best for people who want to save small amounts regularly and don't mind limited withdrawal windows.

Bamboo: Primarily an investment app for US stocks and ETFs, but its fixed-income dollar product lets you save idle USD at up to 8% interest for 90-day lock-in periods.

Pros: Dollar-denominated, SEC-regulated (for the stocks side), accessible from Nigeria.

Cons: the 90-day lock-in means no access during that period, and the platform is more investment-oriented than a pure savings product. Best for people who want to park $500+ for 3 months and earn yield while they wait.

Rise: Another investment platform with dollar savings features. Offers fixed-income and real estate dollar funds alongside stock investments.

Pros: Diversified dollar savings options, regulated, and accessible.

Cons: Returns vary by fund, minimum investments apply, and liquidation times depend on the fund type. Real estate funds can take days to liquidate. Best for people who want dollar exposure beyond simple savings.

Cowrywise: Offers naira and dollar mutual fund investments. Dollar savings come through dollar-denominated fixed-income funds managed by licensed fund managers.

Pros: Automated savings, SEC-regulated fund managers, and accessible.

Cons: Dollar availability can be limited during high-demand periods, returns aren't guaranteed (they're based on fund performance, not a fixed interest rate), and withdrawals may take 24 to 72 hours.

Who should use fintech apps: anyone saving $50 to $5,000 monthly who wants easy access, doesn't want a branch visit, and is comfortable with digital platforms. Compare the interest rates, lock-in periods, and withdrawal policies before committing.

Method 3: Stablecoins (USDT, USDC)

Stablecoins are cryptocurrencies pegged 1:1 to the US dollar. Buying USDT (Tether) or USDC (Circle) is effectively buying digital dollars. You purchase them on exchanges like Binance, Bybit, or Luno using naira via P2P trading.

Pros: Instant access at any hour, no bank involved, 24/7 liquidity (you can convert back to naira at 2am on a Sunday), and the ability to earn yield through DeFi protocols (though this adds substantial risk). Converting back to naira via P2P is straightforward and settles within minutes.

Cons: Not regulated by CBN, which means no deposit insurance. The exchange rate spread on P2P purchases runs 1 to 3% above the mid-market rate, eating into your savings immediately. Platform insolvency is a real risk (FTX collapsed owing billions to depositors). You need basic crypto knowledge to manage wallets, avoid scams, and understand the difference between custodial and non-custodial storage. P2P trading also carries counterparty risk: the counterparty could fail to deliver.

Who should use stablecoins: People comfortable with crypto who want maximum flexibility and don't mind managing their own security. Keep holdings on reputable exchanges (Binance, Bybit) or in a hardware wallet for larger amounts. This isn't a savings account. It's holding a digital asset pegged to the dollar.

Method 4: Grey USD account

Grey lets Nigerian residents open a USD account that holds real dollars with US routing and account details. You can receive USD from international clients, freelance platforms, or transfers, hold the dollars, and convert to naira when you choose.

What makes it different: Grey isn't a savings app that lets you buy dollars at a markup. It's an account that receives and holds USD directly. If you earn in dollars (freelancing, remote work, exports), the money lands in your Grey account as USD. You decide when to convert to naira, based on the rate you see in the app. No forced conversion, no lock-in period, no minimum balance.

You can also spend directly from your USD balance using a Grey virtual card for online purchases, subscriptions, and international payments. This means you don't need to convert to naira just to pay for a Netflix subscription or buy something from an international merchant.

To organise money for a specific goal (a trip, tuition, an emergency fund), set it aside in a Grey Pouch so it's visually separate from your spending balance.

Pros: Real USD account details (ACH routing number and account number), no minimum deposit, no lock-in period, instant setup, virtual card for spending.

Cons: No interest earned on balances; 1% conversion fee (capped at $6) when you swap to naira.

Who should use Grey: Anyone earning in dollars who wants to hold those dollars and convert on their own terms. Especially freelancers, remote workers, and small business owners receiving payments from US clients.

Cost comparison: Converting NGN 500,000 to USD

Here's what it costs to convert NGN 500,000 (roughly $330 at parallel market rates) into dollars through each method:

Domiciliary account: You bring cash dollars to the bank. The cost is whatever you paid to source those dollars, typically the parallel market rate, which includes a 1 to 3% premium over the official rate. No conversion fee from the bank, but you're paying the spread on acquisition.

PiggyVest: You buy dollars within the app at their rate, which includes a spread. The effective cost is typically 1 to 3% above the parallel market rate. On $330, that's $3 to $10 in spread.

Stablecoins (P2P): Binance P2P rates for USDT include a 1 to 3% spread over the mid-market rate. On $330, that's $3 to $10 in spread, plus any trading fees (typically 0%).

Grey: If you're receiving dollars from clients, the cost is zero on receiving. When you convert from naira to dollars within Grey, the 1% swap fee (capped at $6) applies. On $330, that's $3.30.

The real cost isn't the platform fee. It's the exchange rate you get when sourcing dollars. Compare the effective rate (how many naira per dollar) across methods before converting a large amount.

Which method should you use?

If you earn in dollars (freelancing, remote work, exports): Grey. Your income arrives in USD and stays in USD until you choose to convert. No intermediary, no markup on receiving.

If you want to convert naira to dollars for long-term savings: PiggyVest or a domiciliary account. PiggyVest is easier to set up and pays interest; dom accounts offer more regulatory protection. If the amount is large ($10,000+), the dom account's NDIC insurance matters.

If you want dollar-denominated investments: Bamboo or Rise. These go beyond simple savings into fixed-income and equity products that earn returns.

If you're comfortable with crypto: Stablecoins (USDT/USDC) offer the most flexibility and 24/7 access, but with no deposit insurance and additional platform risk. Keep no more than you can afford to lose on any single exchange.

If you want both savings and spending: Grey. Hold dollars, spend with a virtual card, convert to naira when you need to. One account covers receiving, saving, and spending.

Frequently asked questions about saving in USD in Nigeria

Is it legal to save in dollars in Nigeria?

Yes. Nigerian residents can legally hold and operate domiciliary accounts in USD, GBP, or EUR at commercial banks. The CBN permits individuals to hold foreign currency for legitimate purposes, including savings, investment, and business transactions. Fintech apps operate under different regulatory frameworks depending on the specific licence. Stablecoins exist in a regulatory grey area but are not prohibited for individual holding.

How much interest can I earn on dollar savings in Nigeria?

Domiciliary accounts at banks: typically 0% (banks don't pay interest on foreign currency deposits). PiggyVest: up to 7% annually. Bamboo: up to 8% on 90-day fixed-income lock-in. Stablecoin DeFi yields vary widely (2 to 15%) but carry proportionally higher risk. Grey doesn't pay interest on USD balances but lets you hold and convert on your terms with no lock-in.

What is the safest way to save in dollars in Nigeria?

A domiciliary account at a CBN-regulated bank offers the most regulatory protection, with NDIC insurance covering up to NGN 500,000 equivalent per depositor per bank. Fintech apps offer convenience but may not carry the same level of deposit insurance. Stablecoins offer no deposit protection. For amounts under $5,000, a regulated fintech app is a reasonable balance of convenience and safety. For larger amounts, consider splitting across a dom account and a fintech platform.

Can I open a domiciliary account without a salary account at the same bank?

Yes. You don't need a salary account at the same bank to open a dom account. You need your BVN, NIN, valid ID, proof of address, and the minimum opening deposit ($100 to $500, depending on the bank). Some banks ask for reference letters. The process requires a branch visit at most banks, though some now offer partial online applications.

Ready to save in dollars? Open a Grey USD account and hold real dollars with US account details.

Disclaimer: This article is for informational purposes only. All costs and details are estimates based on mid-2026 data. Verify current information before making decisions. Grey isn't a bank. We're a licensed financial services provider offering multi-currency accounts.

Arrow (up)

Back to top