
<script type="application/ld+json" data-schema-version="grey-blog-v4"> [{"@context":"https://schema.org","@type":"BlogPosting","@id":"https://grey.co/blog/is-grey-legit-and-safe-to-use#article","headline":"Is Grey legit and safe to use? Honest review for 2026","description":"Grey is registered with FinCEN and FINTRAC. It has served hundreds of thousands of users across Nigeria, Kenya, Ghana, and 30+ countries. Here is an honest breakdown of what Grey does well and what to know before signing up.","inLanguage":"en","url":"https://grey.co/blog/is-grey-legit-and-safe-to-use","mainEntityOfPage":{"@id":"https://grey.co/blog/is-grey-legit-and-safe-to-use#webpage"},"datePublished":"2026-03-31T13:17:37.310Z","dateModified":"2026-06-15T14:19:20.114Z","author":{"@type":"Person","@id":"https://grey.co/authors/olayoyin-olorunmota#person","name":"Olayoyin Olorunmota","url":"https://grey.co/authors/olayoyin-olorunmota","jobTitle":"Content Writer","sameAs":["http://www.linkedin.com/in/olayoyinolorunmota","http://x.com/yoyin_michael"]},"publisher":{"@type":"Organization","@id":"https://grey.co/#organization","name":"Grey","url":"https://grey.co","logo":{"@type":"ImageObject","url":"https://cdn.prod.website-files.com/6360022338a81bd6fdbb1145/6564ae1077a67e39d3c491a6_Grey%20Logo%20Lockup%20Black.svg"}},"image":{"@type":"ImageObject","@id":"https://grey.co/blog/is-grey-legit-and-safe-to-use#primaryimage","url":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3009e72871718d8f162313_6a3009e72871718d8f16224e_is-grey-legit-and-safe-to-use__header-image.webp","contentUrl":"https://cdn.prod.website-files.com/636a85d290ee58e70c17e1c0/6a3009e72871718d8f162313_6a3009e72871718d8f16224e_is-grey-legit-and-safe-to-use__header-image.webp","width":1200,"height":675}},{"@context":"https://schema.org","@type":"WebPage","@id":"https://grey.co/blog/is-grey-legit-and-safe-to-use#webpage","url":"https://grey.co/blog/is-grey-legit-and-safe-to-use","name":"Is Grey legit and safe to use?","description":"Grey is registered with FinCEN and FINTRAC. It has served hundreds of thousands of users across Nigeria, Kenya, Ghana, and 30+ countries. Here is an honest breakdown of what Grey does well and what to know before signing up.","inLanguage":"en","primaryImageOfPage":{"@id":"https://grey.co/blog/is-grey-legit-and-safe-to-use#primaryimage"},"breadcrumb":{"@id":"https://grey.co/blog/is-grey-legit-and-safe-to-use#breadcrumb"}},{"@context":"https://schema.org","@type":"BreadcrumbList","@id":"https://grey.co/blog/is-grey-legit-and-safe-to-use#breadcrumb","itemListElement":[{"@type":"ListItem","position":1,"name":"Home","item":"https://grey.co/"},{"@type":"ListItem","position":2,"name":"Blog","item":"https://grey.co/blog"},{"@type":"ListItem","position":3,"name":"Is Grey legit and safe to use? Honest review for 2026","item":"https://grey.co/blog/is-grey-legit-and-safe-to-use"}]}] </script>

Is Grey legit and safe to use? Honest review for 2026

Olayoyin Olorunmota

TABLE OF CONTENT

SHARE THIS POST

We built Grey to make it easier for people and businesses to receive, manage, and spend money across borders.

With Grey, you can hold foreign currencies, convert between them, spend with a linked card, and send money internationally, all from one platform.

But when it comes to financial services, the important question of trust always comes up.

If you’re considering using Grey to receive payments, hold foreign currency, or manage international transactions, it’s completely normal to ask questions.

Here’s a clear breakdown of how Grey works and the systems we put in place to keep your money and data secure.

Is Grey safe?

Grey is a fintech platform that provides multi-currency accounts and payment infrastructure. We’re not a bank, and it’s important to be clear about that upfront. You can hold USD, EUR, and GBP, convert between currencies, spend using cards, and withdraw funds to your local bank account.

As a financial service provider, we operate within compliance frameworks designed to protect users and ensure accountability. These include:

  • KYC (Know Your Customer) requirements
  • AML (Anti-Money Laundering) regulations
  • Ongoing transaction monitoring and compliance checks

These frameworks are standard across the financial industry and are essential for preventing fraud and illegal activity.

We also work with regulated partner institutions to provide our services.

Website and app security

We designed Grey primarily for online and in-app use, so we built security into every layer of the experience.

To open an account, you must complete a verification process and set secure login credentials. Once active, your account is protected with:

Behind the scenes, we run security checks and monitoring systems to detect and prevent suspicious activity.

On your end, you can:

  • Monitor transactions in real time
  • Freeze or unfreeze cards instantly
  • Manage multiple cards for different use cases
  • Track balances across currencies

These features give you transparency and control over your finances.

Is it safe to send money with Grey?

Yes, Grey is safe for sending money internationally.

To make a transfer, you need to verify your account first. This ensures that all transactions are tied to verified identities, reducing the risk of fraud.

Your payments are processed through secure financial networks, and you can track the transactions within the app.

If you need help with anything, you can reach out to support@grey.co for assistance with transactions or account-related issues.

Is it safe to leave money in your Grey account?

When you hold funds in your Grey account, they aren’t mixed with our operational finances. Instead, we hold them with regulated partner institutions in segregated accounts.

This means:

  • Your money always remains separate from company funds
  • Your funds are available when you need them
  • You can convert, spend, or withdraw at any time

Unlike traditional banks, Grey does not use customer funds for lending. Our focus is on enabling access, movement, and control of money, not leveraging deposits.

Also read: Why creators move away from Payoneer and PayPal

Why does verification matter?

Why do you need to submit identity documents, proof of address, and sometimes additional information about income sources or business activities?

The answer is regulation. Financial services are legally required to verify the identity of their customers. This is KYC (Know Your Customer) compliance, designed to prevent money laundering, fraud, and other financial crimes. Every legitimate bank, fintech platform, or payment processor must do this.

When we ask for your ID, proof of address, or business documentation for Grey Business, we’re complying with the law and keeping you safe.

Also read: How to budget in foreign currencies using the Grey card

Where does Grey Business fit in?

We designed Grey Business for SMEs, agencies, startups, and growing teams that need proper business-level financial infrastructure for international operations.

This way, there’s a clearer separation between personal and business finances, which is important for accounting, tax compliance, and professional credibility.

For businesses, compliance and structure matter even more than for individuals. You’re managing company funds, potentially with partners, investors, or regulatory obligations. With this reality in mind, Grey Business offers USD and USDC accounts, bulk pay outs in multiple currencies and access to multiple virtual USD cards.

Also read: Meet Grey Business: the growth engine for global finances

LDMAG1

When Grey might not be the right fit for you

If you need traditional banking services like loans, mortgages, or overdrafts, we don’t provide those. Our focus is on multi-currency accounts and payments, not full-service banking.

If you operate entirely in one currency and never deal with international payments, Grey probably isn’t necessary.

If you’re uncomfortable with digital-only financial services and prefer in-person banking, Grey won’t suit you. You can mange everything through the app and our 24/7 online support.

So, is Grey legit and safe?

Is it legit? Yes. Is it safe? Yes

The question shouldn’t be whether Grey is safe in some absolute sense, it’s whether it’s the right tool for your needs. If you’re managing foreign currency, receiving international payments, or running a business with cross-border operations, Grey is perfect.

Trust takes time to build, and that’s fair. Start small if you’re cautious. Use Grey for one payment, see how it works, and decide from there.

Open your free Grey account or explore Grey Business if you’re ready to manage international payments with proper infrastructure behind them.

‍

Last updated:

October 14, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

Ways remote workers protect income across countries

•

•

2 min read

If it has ever crossed your mind that someone might be spending your income behind your back, then you are not alone. One minute, you get paid, and the next minute, the funds have dried up, and you are looking forward to the next payday. On second thought, there might actually be someone else spending your money. Unfavourable exchange rates, local currency devaluation, high platform charges, and unplanned taxes can affect your income. Here are the most effective ways remote workers protect their income while working across countries.

They separate their income from their spending

Separating your earnings from your spending helps you manage money better. Remote workers would rather take a regular salary, which is a fraction of their income. They receive payments into an account and periodically move the money they need (maybe monthly) to a separate account where they spend it.

They avoid forced conversions

One of the biggest mistakes remote workers make is converting foreign income into local currency immediately, especially with traditional banks. This exposes you to poor exchange rates and removes the flexibility to decide when you want to convert your income. The OG remote workers know to keep income in the currency it is paid in, then convert only when they need to spend locally or when rates are favourable.

Using multi-currency accounts allows them to receive USD, EUR or GBP, hold balances securely and manage conversions strategically. This simple separation alone can preserve a significant portion of income over time.

They avoid dynamic currency conversion

If you use an international ATM with your local card and choose to be debited in your home currency, that is one of your income drains. Dynamic currency conversion automatically converts payments at unfavourable rates. Remote workers would choose to pay or withdraw in the local currency of the transaction, not their home currency, to avoid hidden mark-ups.

They invoice in stable currencies

Remote workers charge in stable currencies like USD, EUR, and GBP. This improves their earning potential and ensures their money is protected from local economic factors and currency fluctuations. Quoting in these currencies also ensures the income value remains predictable. Even if their home currency weakens, their income in stable currencies acts as a hedge against inflation or sudden devaluation.

They plan for taxes across borders

Unplanned taxes are a recipe for financial disaster. Unexpected tax liabilities can wipe out months of earnings. Remote workers who protect their income understand their tax residency, keep accurate records and set aside money regularly for tax obligations.

They track invoices, payment dates and conversions carefully. Even when working in multiple countries, having organised records prevents penalties and reduces stress.

Also read: How to plan your taxes across multiple income sources

They use contracts and clear payment terms

Working without a clear contract can affect your income. Defining payment terms, timelines, currencies, late fees, and dispute processes beforehand helps remote workers manage expectations and financial disruptions. This reduces delayed payments and gives them leverage if issues arise.

They also avoid working extensively without upfront deposits or milestones, especially with new clients.

Also read: Negotiating cross-border freelance contracts: Tips and templates

They have financial discipline

The money you make from remote work can be seasonal. Sometimes, you’re doing great; other times, you are grasping at straws. Remote workers understand their earnings can be irregular, so they maintain emergency funds to cover three to six months of expenses. They’d usually keep part of their money in stable foreign currencies to protect against local economic changes. Financial discipline involves solid financial planning, strict budgeting, expense tracking, compulsory savings, and emergency funds.

Also read: Managing irregular income as a freelancer

Protecting your foreign income with Grey

Protecting your income as a remote worker boils down to smart planning and the right payment solution. Grey is tailored to help remote workers maximise their earnings with their multi-currency accounts. Users can hold their earnings in USD, GBP, and EUR or convert to local currencies at competitive exchange rates.

Sign up on Grey today and download the mobile app to protect your foreign income.
‍

How global workers plan income, location, and lifestyle together

•

•

2 min read

Often, the logistical considerations for global workers can be more exhausting than the job itself. You have to plan your finances, research your destination, and schedule trips while ensuring an optimal work-life balance. It is likely to become so chaotic that you may consider a traditional work structure instead. If you hope to enjoy your global work life, then integrating your financial plan, location, and lifestyle is your surest bet. This article explores how you can piece these work elements together to ensure optimal work performance.

Also read: How global work culture is changing the way we live and earn

Planning your income as a global worker

Your income determines a lot. When people consider becoming a global worker, they think of Dubai first, even though their income should make them think of Mumbai. Experienced digital nomads ensure they have their finances locked in before setting out. If you are an I will figure it out’ kind of person, you might end up stranded in an unfamiliar country because you like the aesthetics. These are some measures for global workers:

  • Detailed research: Before moving, research the cost of living (rent, utilities, food, transport, and leisure) using tools like Numbeo or Expatistan.
  • Track expenses: Use apps like YNAB or simple spreadsheets to monitor spending and adjust accordingly over time.
  • Set a Budget: Follow it strictly. The popular 50/30/20 budget (50% needs, 30% wants, 20% savings) is often recommended.
  • Manage taxes: Understand tax residencies, avoid double taxation, and keep meticulous records. When in doubt, hire a tax expert.
  • Savings and emergency funds: Global workers aim to save 3 to 6 months of their living expenses as a backup in case their income becomes unstable. Set up automatic transfers to a savings account.
  • Contracts: Ensure work contracts clearly define payment methods, payment terms, and currency (use stable currencies like USD, EUR, or GBP).
  • Use multicurrency accounts: These allow them to receive payments globally at low cost and withdraw to local currency at competitive rates

You may also like: Global accounts vs traditional banks: What remote workers should know

Choosing a destination as a global worker

Once your finances are sorted, you can start thinking of locations your income can support. Global workers prioritise destinations with solid Wi-Fi, affordable living, and digital nomad visas that let you stay longer. Evaluate safety, healthcare, and work-life balance. Also, don't forget time zones. For example, if your clients are in the US, avoid places like New Zealand where calls mean midnight meetings.

Being a digital nomad doesn’t mean you are constantly moving around without a plan. Rather than moving impulsively, global workers plan their relocations around times when they have less work. This reduces stress and maximises performance.

Managing lifestyle as a global worker

Managing lifestyle as a global worker requires a strategy that balances your job responsibilities and your personal well-being. Global workers should be clear on what type of life they’d like to experience. It is easy to get carried away with exciting adventures and relax. But there is a job that sponsors this lifestyle, and this should always be at the back of your mind.

Establish work-life boundaries by separating work areas from living areas. Have a clear work structure that defines your working hours and accommodates varying time zones if you’re working with a global team. Regular exercise and sleep are essential for managing stress and improving well-being.

Also read: Financial habits that make global work sustainable

Balancing income, location, and lifestyle as a global worker

Now, let’s piece these elements together.

We have already established that your finances strongly influence your location and lifestyle. It is therefore important to adapt your lifestyle and location choices to fit within your budget while leaving enough for a rainy day. Don’t be afraid to start small and gradually grow.

Mastery in global work is balancing location and lifestyle on your finances while maximising productivity. Grey helps you achieve this balance by streamlining your finances to improve planning. With multicurrency accounts, you can manage USD, EUR, and GBP transactions in one place and withdraw in local currencies at competitive rates. You also avoid losing a chunk of your income to high transaction fees and unfair exchange rates. Grey’s virtual USD debit card gives you more flexibility to make payments as you travel globally.

Sign up on Grey and download the app to manage your finances across borders.

‍

How to convert an eSIM back to a physical SIM

•

•

2 min read

A phone upgrade is usually a straightforward process, until the SIM becomes part of the equation. Let's say the new device supports an eSIM, the number transfers successfully, and everything seems ready to go, then comes a trip abroad, a change of network or an older mobile phone that only accepts a physical SIM card.

At that point, the question is simple: what happens to the eSIM?

Unlike changing a setting on the phone, moving from an eSIM back to a physical SIM is handled by the mobile carrier. The network provider needs to deactivate the existing eSIM and issue a replacement physical SIM linked to the same mobile number. The exact process can vary, but most carriers allow the request through an app, over the phone or at a physical store.

The switch itself is usually straightforward once the replacement SIM arrives. After activation, the physical SIM takes over the number and the old eSIM profile can be removed from the device.

Also read: How to activate an eSIM: Step-by-step guide

Can you convert an eSIM back to a physical SIM?

Yes, you can switch from an eSIM to a physical SIM through your mobile carrier. However, your phone cannot make this conversion on its own. You'll need to contact your carrier to request a physical SIM card and transfer your number to it.

An eSIM is a digital SIM profile stored securely within the phone, while a physical SIM is a separate chip that needs to be issued and activated by the mobile network. Your carrier controls the connection between your mobile number, account and SIM credentials, so the switch has to happen on the network provider’s side.

The process is usually treated as a SIM swap or SIM replacement. Your carrier deactivates the existing eSIM and issues a physical SIM linked to the same number and account. Depending on the provider, the request may be available through its app, customer service team or a physical store.

Once the replacement SIM is activated, the old eSIM can be removed from your device.

How to request a physical SIM from your carrier

Requesting a physical SIM from your mobile carrier usually involves choosing a replacement method, completing an identity check, receiving the SIM and activating it on your existing number.

  1. Request a physical SIM through the carrier app
  2. Open your carrier’s app and look for options such as “Replace SIM”, “SIM swap” or “Get a physical SIM”. Follow the instructions and provide any information requested to verify your account.
  3. Call your carrier’s customer service team
  4. Contact your network provider and explain that you want to switch from an eSIM to a physical SIM while keeping your existing number. The representative will explain the available replacement options and the delivery process.
  5. Visit a carrier store
  6. A nearby carrier shop can process the SIM replacement in person. Bring your phone and a valid form of identification, as the staff may need to confirm that you are the account holder.
  7. Complete the identity checks
  8. Expect security checks before the physical SIM is issued or activated. Depending on the carrier, these may include account details, passwords, identification documents or other verification questions.
  9. Activate the replacement SIM
  10. Once the physical SIM arrives or is issued, follow your carrier’s activation instructions. Your number can then move from the eSIM to the physical SIM.

How to delete the eSIM profile once the physical SIM works

Before removing your eSIM, make sure the replacement physical SIM is fully activated and working. Test it by making a call, sending a text message and checking that mobile data works. Deleting the eSIM too early could leave your phone without cellular service if the physical SIM has not yet been activated.

On iPhone

The wording can vary slightly depending on your iOS version and region:

  1. Open Settings.
  2. Tap Cellular or Mobile Service.
  3. Select the eSIM or cellular plan you want to remove.
  4. Tap "Delete eSIM" or "Remove Cellular Plan".
  5. Confirm the removal when prompted.

On Android

Android settings differ between manufacturers, so the menu names may not be identical on every device:

  1. Open Settings.
  2. Tap Connections or Network & Internet.
  3. Select SIM manager, SIMs or a similar option.
  4. Choose the eSIM profile you want to remove.
  5. Tap Remove, Delete SIM or the equivalent option, then confirm.

Afterwards, check that your physical SIM remains selected for calls, texts and mobile data. If anything stops working, contact your carrier before making further changes.

Also read: eSIM vs Google Fit: Which is better for international travel?

When is a physical SIM the better choice?

Choosing between an eSIM vs a physical SIM often comes down to how, where and why a phone is being used. An eSIM is convenient for digital setup and travel, but a physical SIM still has practical advantages that can make it the better option in certain situations.

Selling or handing down a handset is one example. A physical SIM can simply be removed before the phone changes hands, leaving the new owner to insert their own SIM. This makes the separation between your mobile number and the device straightforward, particularly when the phone is being resold.

Travel is another consideration. Some dual-SIM phones make it easy to combine a physical SIM with an eSIM, allowing a local travel SIM to work alongside a primary number. This can be useful when moving between countries while keeping the main line active.

In some regions, eSIM support remains limited across carriers, plans and devices. A physical SIM can therefore provide greater flexibility when travelling or changing networks. For anyone comparing eSIM vs physical SIM, checking carrier and country compatibility before switching can prevent unexpected connectivity problems.

What it costs and how long it takes

The quickest way to replace your eSIM with a physical SIM is usually a store visit, but ordering online can be more convenient. Here is what you can generally expect from major US carriers:

  • Verizon: A store visit can mean instant activation, usually at $0 at corporate locations, although independent retailers may charge $10–$25. Online orders typically arrive within 3–5 business days, with no standard hardware fee.
  • AT&T: Visiting a corporate store can provide same-day activation, often for $0, although a $5 fee may apply. Online orders generally take 3–5 business days and carry a $5 replacement fee.
  • T-Mobile: In-store replacement can be activated immediately, but costs can reach $60, including the $25 SIM fee and potential $35 assisted-support fee. Ordering online usually takes 2–5 business days and costs $25, without the assisted-support charge.
  • Mint Mobile: There are no dedicated Mint stores, so replacement is handled online. Delivery generally takes 2–5 business days, with replacement costs typically ranging from 0–10.

While ordering your replacement SIM, you may also need to make a payment. Grey can make that easier, with a multi-currency account and virtual card for international payments. If you're travelling, you can also buy an eSIM through Grey and manage your connectivity and spending from the same platform.

Frequently asked questions about converting an eSIM back to a physical SIM

1. Will I lose my number?

No, your phone number remains exactly the same. Your carrier simply transfers your existing mobile account and number from the eSIM to the new physical SIM. Once the replacement card is activated, you can continue making calls, sending messages and using mobile data as before.

2. How much does a replacement cost?

Replacement fees vary by carrier, location and how you request the SIM. In many cases, you may pay between $0 and $25. Some major networks provide replacement cards free at corporate stores, while budget or prepaid providers may charge a separate SIM replacement fee.

3. Can I keep both active?

No, you generally cannot keep both SIM profiles active on the same number. Your carrier links the number to the newly activated SIM during the replacement process, which deactivates the previous eSIM. Your phone may support two SIMs, but they cannot share one number simultaneously.

4. How long does it take?

An in-store SIM replacement can often be completed within 10 to 15 minutes once your identity and account details have been verified. Ordering a physical SIM online usually takes longer, with standard delivery commonly taking around 3 to 5 business days, depending on your carrier.

5. Should I delete the eSIM early?

No. Keep your eSIM active until the replacement physical SIM has arrived, been activated and successfully connects to the network. Deleting the eSIM too early can leave your phone without mobile service, particularly when the new SIM has not yet been activated.

6. Do all carriers issue physical SIMs?

Many carriers still offer physical SIM cards, but availability depends on the network and your device. Before requesting one, check that your handset has a physical SIM tray. Some newer phones, including certain regional models, are designed as eSIM-only devices and cannot accept a physical card.

How to use Google Pay worldwide with your Grey virtual card

•

•

2 min read

I’ve always loved feeling independent, the kind of person who can move through the world without needing to stop and sort out a dozen little hassles. Maybe that’s why tapping my phone to pay has become one of my favourite tiny freedoms.

If you’re anything like me, you know those moments well. Rushing through an airport with no hands to spare. Grabbing breakfast from a food stall because you’re curious about how the locals eat. Signing up for an online tool at midnight because the timing just felt right.

That’s exactly why learning how to use Google Pay worldwide with your Grey virtual card makes such a difference. Once your card sits snugly inside Google Pay, every payment becomes smoother. No digging through bags, topping up a card before paying, and no declines. Just a quick tap and the quiet satisfaction of knowing you’ve sorted it.

And now that the Grey virtual card has officially landed, this is the perfect time to explore everything it can do to keep your days light, easy, and wonderfully yours.

Why the Grey virtual card works so effortlessly with Google Pay

If you’re looking for a simple, reliable way to use Google Pay worldwide, the Grey virtual card makes the process smoother than ever. With our upgraded virtual card experience now live, Google Pay becomes more than a convenient feature. It becomes the easiest way to spend your foreign currency and crypto balances across countries, platforms, and everyday transactions.

Here’s why using Google Pay with your Grey virtual card is such a seamless match:

One card, multiple balances

Your Grey virtual card connects directly to any balance you choose, including USD, GBP, EUR, or crypto like USDC, USDT, or BTC. No manual top-ups. No switching between wallets. Just direct, instant spending power everywhere Google Pay is accepted.

A smoother global experience

Many people switching to the Grey virtual card do so after dealing with cards that fail on international platforms. This upgraded virtual card was designed to remove that frustration. You get fewer random declines, clearer communication, and fast support whenever you need it, making global payments feel more predictable.

Contactless convenience, everywhere

When you combine Google Pay’s tap-to-pay simplicity with Grey’s global card functionality, you get fast, contactless payments across countries, currencies, and online merchants. Whether you’re shopping locally or paying for international services, everything works with a tap.

Stronger security

The Grey virtual card supports 3D Secure (3DS), giving you added protection during online and in-store transactions. It’s a safer way to shop, travel, and pay globally.

Who benefits most from using Google Pay with the Grey virtual card?

If you’ve been searching for a reliable virtual card that works with Google Pay worldwide, this duo is designed exactly for the way modern global citizens live, earn, and spend.

Digital nomads and travellers

Once your Grey virtual card is added to Google Pay, you can tap your way through airports, metros, cafés, supermarkets, and co-working spaces, anywhere contactless payments are accepted.

Crypto enthusiasts

If you hold or earn in crypto, Google Pay becomes your gateway to everyday fiat spending. Link your Grey virtual card to your crypto balances and pay like a local in any country.

Freelancers and remote workers

Whether you earn in USD, work with clients in Europe, or pay for tools hosted abroad, Google Pay + Grey card gives you a consistent and flexible way to manage global payments without failed transactions or confusing restrictions.

Small business owners

Running ads on Meta, TikTok, or X? Paying for global subscriptions and software? Your Grey virtual card helps every payment go through smoothly, without hidden fees or last-minute surprises.

How to create your Grey virtual card and add it to Google Pay

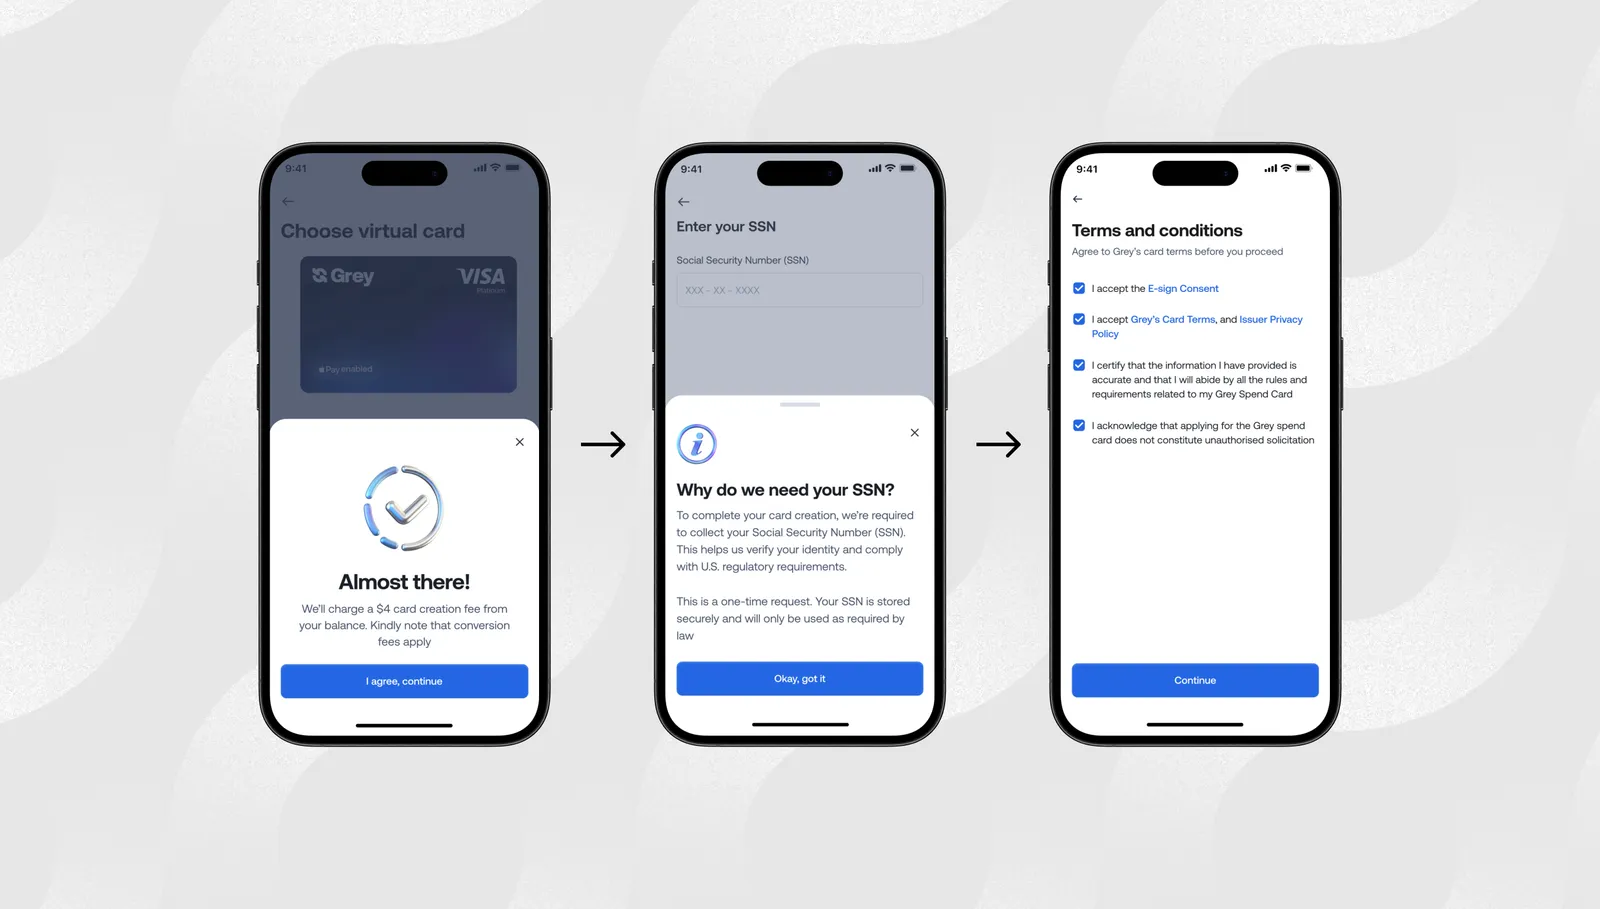
If you’re learning how to use Google Pay with your Grey virtual card, the setup takes just a few seconds:

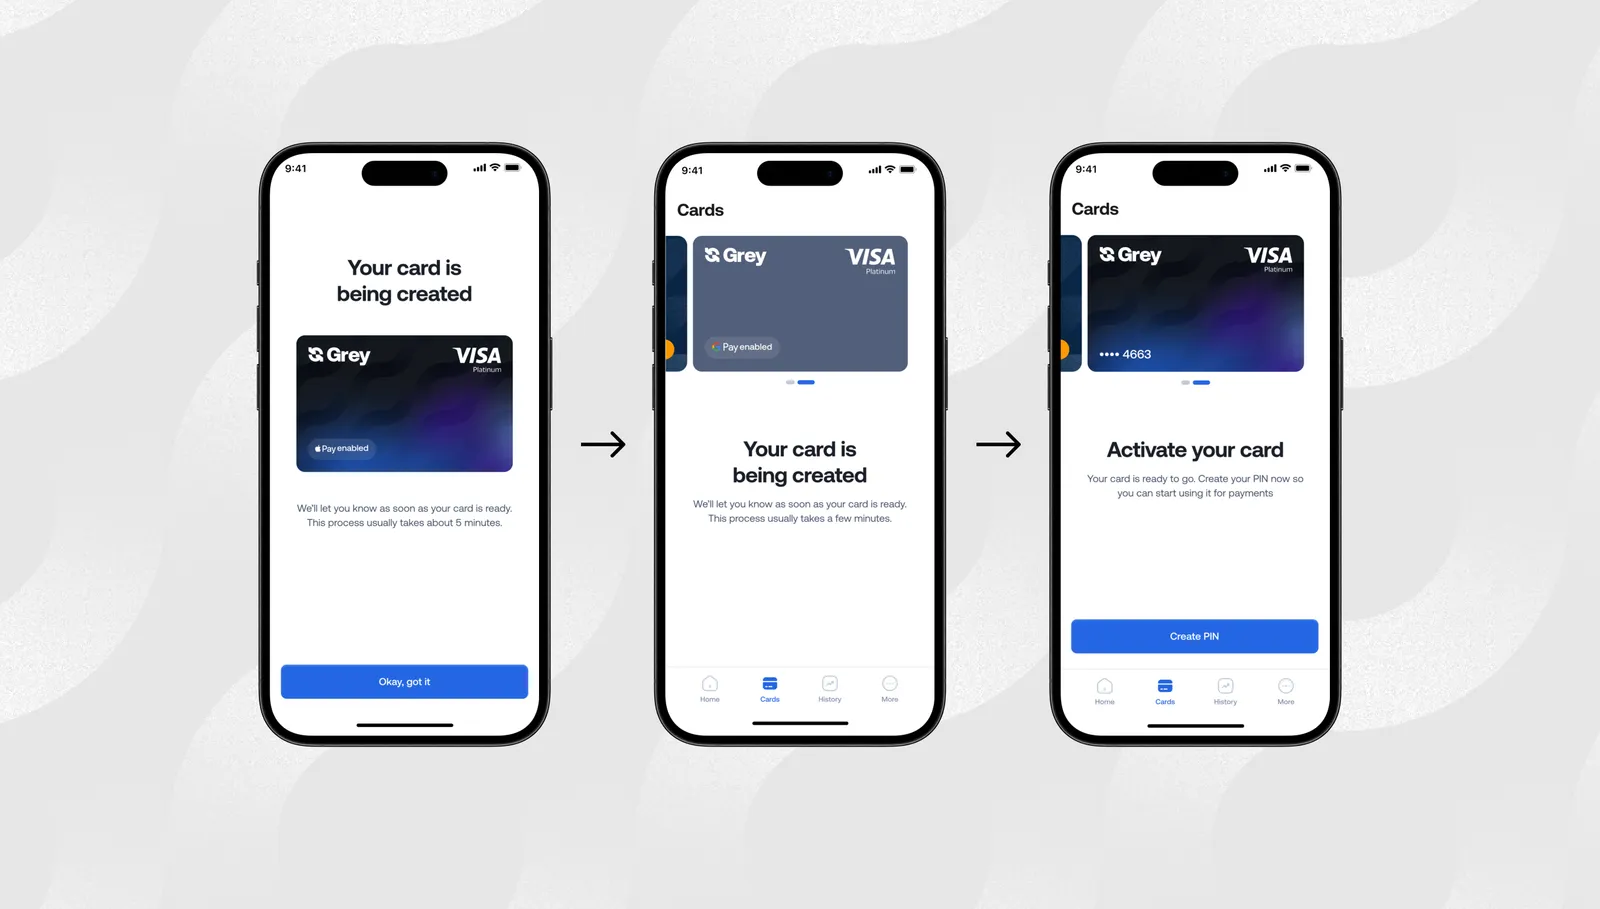
Tap to create your Grey card in the app.

__wf_reserved_inherit

Follow the verification steps.

__wf_reserved_inherit

It usually takes a few hours for the card to be created.

__wf_reserved_inherit

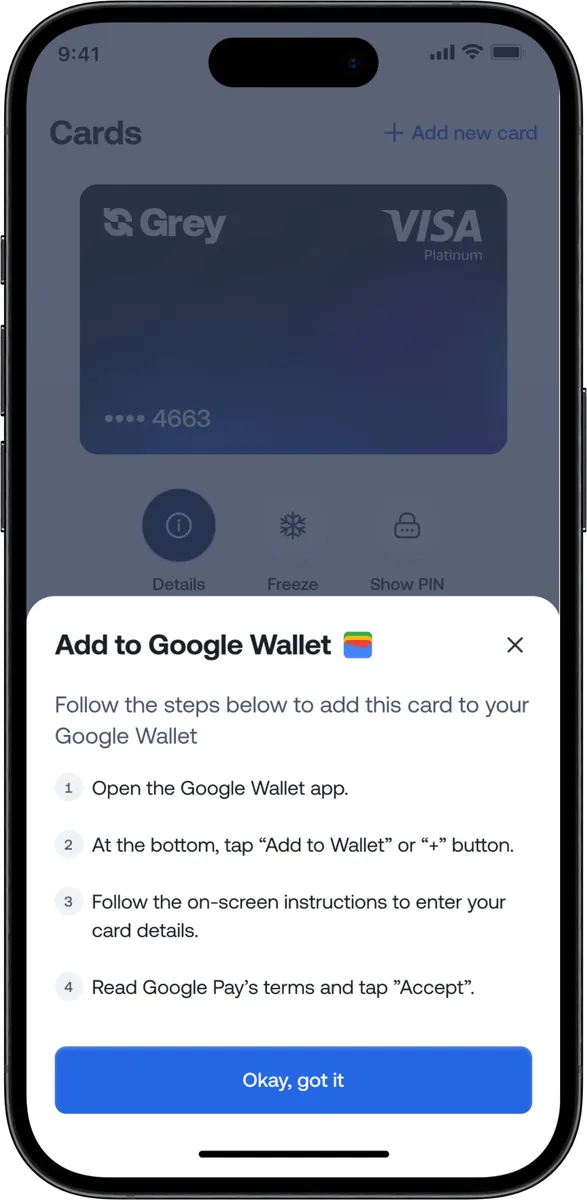
Once your Grey virtual card is ready, you can follow the steps to add it to Google Pay.

__wf_reserved_inherit

Once added, you can use Google Pay for contactless payments, online checkouts, in-app purchases, public transport, and global merchants that support Google Pay.

Where you can use Google Pay with your Grey virtual card worldwide

Google Pay works in dozens of countries and millions of merchant locations. With the Grey virtual card connected, you can:

  • Book international flights
  • Pay for Airbnb and travel bookings
  • Buy coffee and groceries in cities like Barcelona, Nairobi, Accra, Mexico City, or Bali
  • Subscribe to Amazon, Spotify, Canva, YouTube Premium, and more
  • Pay for ad platforms like Meta, TikTok, Google Ads, and X

Your Grey Visa card selects the right balance automatically, while Google Pay makes each payment instant and contactless.

Why this upgrade matters now

For years, users dealt with failed payments, poor international compatibility, and unclear card restrictions. The new Grey virtual card was built to fix these problems and make global payments through Google Pay easier than ever.

This upgrade helps you:

  • Spend globally with fewer limitations
  • Enjoy reliable virtual card functionality
  • Avoid unexpected card blocks or errors
  • Use foreign currency and crypto balances effortlessly
  • Make international purchases with more confidence

It’s all part of our goal to make international spending feel as easy as local shopping.

If you live or work globally, you deserve a payment setup that travels with you. Google Pay paired with the Grey virtual card removes friction from your everyday life so you can focus on what actually matters.

Ready to tap and go anywhere in the world?

Open your Grey app, get your Grey virtual card, and start using Google Pay wherever life takes you.

‍

How to pay for ads easily with your Grey card

•

•

2 min read

Last month, my friend called me in a panic. He’d just launched a big Meta Ads campaign. He’d spent days tweaking it, and right in the middle of a strong performance spike, the worst thing happened. His payment failed.

Meta paused the entire campaign, and he lost momentum, leads, and a potential client renewal. All because his bank randomly declined an international payment at 2 am.

If you’ve ever run ads before, you know this story almost too well.

There are a few things a paid ads manager dislikes more than payments disrupting their ads. Even for creators, freelancers, and small businesses who depend on continuous campaigns, this is annoying and expensive.

This is exactly where the Grey card becomes a practical lifesaver, and I’ll explain here.

Why paying for ads can be difficult sometimes

People don’t always talk about it, but most ad buyers run into the same problems:

1. International cards get declined

Many local bank cards struggle with platforms like Google Ads or Facebook because they’re billed in USD or EUR, depending on your country.

2. Currency headaches

If you earn in your local currency, say naira, but pay for ads in dollars, fees and conversion delays can throw off your budget.

3. Too many campaigns, one payment method

Freelancers running multiple client campaigns often use a single card, which can become a budgeting nightmare.

4. Ad platforms are strict

If your payment fails, the platform pauses your campaign immediately. You lose reach, data, and momentum.

The Grey Visa card was made to solve these exact pain points.

How your Grey helps you run ads without stress

Spend directly from your available balances

Your Grey card automatically pulls funds from your available accounts in the order USD → USDC → the next highest currency, eliminating the need for manual top-ups or wallet selection.

For example, if an ad platform charges $50, the payment is automatically deducted from the available balance, ensuring campaigns run uninterrupted.

Supports Apple Pay and Google Pay

For people who prefer not typing their card details into every ad account, this is a blessing. Just tap, approve, and your campaign goes live.

Create multiple cards to stay organised

You can create separate cards for:

  • Google Ads
  • Meta Ads
  • TikTok
  • LinkedIn
  • Client-specific campaigns

Multiple cards now still work seamlessly from the same unified wallet structure, so you don’t have to worry about linking different currencies or crypto separately.

This makes reconciliation significantly easier and provides peace of mind if one card needs to be frozen or replaced.

Instant freeze/unfreeze and spending limits

If you want to pause a campaign, you can freeze the card without accessing the ad platform. To control costs, you can simply set a monthly limit.

LDMAG1

How to start paying for ads with your Grey card

1. Get your Grey card

You can sign up on Grey, go to the cards section and create your card. This will cost $5.

2. Add it to your ad account

Link it to Google Ads, Meta, TikTok, LinkedIn or wherever you run campaigns.

3. Set a spending limit

This helps with client budgets, personal campaigns, or one-off experiments.

4. Track your payments in the Grey app

Every charge, every retry, every refund is neatly organised right on the app.

Tips to run ads more smoothly with Grey

  • Use separate cards for each client or campaign category.
  • Freeze cards to instantly pause campaigns when needed.
  • Add your card to Apple Pay or Google Pay for fast approvals.

Your ads deserve stability

Running ads is stressful enough. You shouldn’t also have to worry about whether your card will work when Meta tries to charge you at dawn.

If you’re ready for smoother campaigns, fewer declines, and easier budgeting, you can create your Grey Visa card and set up your first ad payment in minutes.

‍

How freelancers receive Upwork payments without losing to fees

•

•

2 min read

Upwork is one of the world’s leading freelance platforms, connecting professionals with clients across countries and industries. From designers and writers to developers and consultants, freelancers use Upwork to find steady work, build lasting client relationships, and earn in strong currencies. The platform is easy to register on, simple to navigate, and trusted by businesses seeking reliable talent, making it a top choice for freelancers at every stage.

If you’re already on Upwork, you’ve likely noticed that fees can quietly reduce your earnings. This blog shows simple ways to receive your payments without losing money to unnecessary fees along the way.

Also read: Upwork vs. Fiverr: which freelancing platform is the best?

Why freelancers use Upwork to get clients

Upwork has become a go-to platform for freelancers worldwide, making it easier to find clients, get paid securely, and build a professional reputation without the usual hassles.

Global clients

Imagine landing clients from New York, London, or Tokyo without leaving your home. Upwork opens doors to global businesses, giving freelancers exposure they couldn’t easily access otherwise. This means more opportunities, diverse projects, and higher-paying gigs. Freelancers can work across time zones, explore different industries, and grow an international client base, all from a single platform.

Security

Freelancers often worry about getting paid on time. Upwork removes that stress by holding client funds in escrow before work begins. Once the project is completed and approved, the money is released. This system protects both sides, ensuring clients get quality work while freelancers receive guaranteed payments, creating trust and a safer environment for online collaboration worldwide.

Easy project access

Finding projects can be overwhelming, but Upwork simplifies the process. Freelancers can browse opportunities tailored to their skills, submit proposals, and start working without endless outreach. By reducing the need for cold pitching, Upwork allows professionals to focus on work they excel at, turning the platform into a curated marketplace where opportunity meets preparation.

Inbuilt invoicing

Managing invoices and payments can slow freelancers down, but Upwork handles this automatically. Every completed project generates invoices, tracks payments, and ensures timely delivery to your account. Freelancers don’t have to worry about chasing clients or missing deadlines, allowing them to stay organised, professional, and focused entirely on delivering high-quality work to their global clients.

Also read: Freelance trends shaping income in 2026

Reputation badge

Your Upwork profile tells a story of experience, reliability, and skill. Ratings, reviews, and badges make it easy for clients to trust you. Over time, freelancers with strong reputations attract higher-paying projects, repeat clients, and long-term contracts. This built-in credibility transforms your profile into a marketing tool, helping your freelance career grow steadily and consistently across international markets.

Best methods to receive Upwork payment from clients

Getting paid on Upwork should be simple, but choosing the right method can make a big difference. Here’s a breakdown of the best ways to receive your money and make the most of your earnings.

Direct to local bank (Outside U.S.)

Upwork lets you send your earnings directly to your local bank if you live outside the U.S. For just $0.99 per transfer, your dollars are converted to local currency and deposited straight into your account. Many freelancers prefer this because it’s straightforward, avoids extra steps, and ensures your Upwork payments land safely where you can use them immediately.

Instant pay (U.S. only)

If you’re in the U.S., Upwork’s Instant Pay is perfect for when you need funds quickly. By connecting your debit card, you can transfer earnings for $2 per transaction, and the money appears instantly. This is ideal for freelancers who want to access their Upwork payments immediately without waiting for standard processing times, keeping cash flow smooth and predictable.

PayPal

Upwork integrates seamlessly with PayPal, making it a popular option for freelancers worldwide. Your payments move quickly from Upwork into your PayPal wallet, giving you flexibility to hold, spend, or transfer the money to your bank. For many, this method is convenient and familiar, especially if you already use PayPal for online purchases or other freelance work outside of Upwork.

Payoneer

Freelancers using Upwork can link Payoneer to receive payments in multiple currencies. This is especially useful if you have clients in different countries and want to manage your earnings in one place. Once received, you can withdraw to your local bank or card, making Payoneer a flexible and reliable way to handle your Upwork funds across borders.

Grey

Grey works directly with your Upwork account to make receiving payments seamless. Your earnings arrive in USD, and you can convert them to your local currency at competitive rates. With fast transfers and multi-currency support, Grey ensures your Upwork income reaches you safely and efficiently, giving freelancers full control over their money every step of the way.

Also read: Freelance platforms vs direct clients: which pays better?

How to receive Upwork payments with Grey

Grey gives you US, UK, and EU bank accounts, so you can receive payments from Upwork without losing fees. Here’s how to get started:

  • Set up Grey: Create and verify your account on the Grey app or website. Once done, you’ll have access to multicurrency accounts ready to receive international payments.
  • Get your bank details: In the Grey app, select the currency account you want to use, like USD. You’ll see your account number and ACH routing number, this is what Upwork needs to send your funds.
  • Link to Upwork: On Upwork, go to Settings > Get Paid > Add Method. This is where your Grey account becomes your payment bridge.
  • Select payment method: Choose “Direct to U.S. Bank” (or the relevant currency for GBP/EUR). This tells Upwork exactly where to send your earnings.
  • Enter details: Copy the account number and routing information from Grey into Upwork. Double-check each number to avoid delays.
  • Verify your name: Ensure the name on your Grey account matches your Upwork profile. A mismatch can cause holds or delays in receiving your money.

LDMAG1

Freelancers on Upwork want to receive their funds without losing a dime, because nothing beats getting paid in full when clients settle up. Grey makes this possible, giving you multi-currency accounts, zero hidden charges, and a simple way to transfer your earnings to your local currency. Ready to take full control of your Upwork payments? Sign up on Grey today

‍

Arrow (up)

Back to top