How UK residents can send and receive US dollars easily

Priscila Marotti

TABLE OF CONTENT

SHARE THIS POST

You land a freelance gig with a US client or find the perfect deal on an American site. The only catch? You need to pay or get paid in USD, and your bank is already making things harder than they should be. Between unclear fees, slow transfers, and exchange rates that never seem to work in your favour, it feels like you're losing money before it even moves.

That’s where Grey steps in. It helps you skip the usual banking fuss with a USD account made for UK residents. Whether you're sending or receiving dollars, you can do it quickly, securely, and without the hidden costs.

Why sending and receiving USD in the UK can be challenging

Despite London’s status as a global financial centre, everyday banking for US dollars can be surprisingly cumbersome for UK residents due to:

  • Limited access to dedicated USD accounts

Most UK banks don’t offer personal US dollar accounts, so USD payments are usually converted to pounds automatically at poor exchange rates, leaving you with less money and no control over when to exchange.

  • High fees and slow transfers

Cross-border USD transfers via UK banks often involve several intermediary banks, causing delays of 3 to 5 business days or more. Additionally, traditional banks charge high fees and add significant markups on exchange rates, making these transfers expensive.

  • Regulatory and compliance complexities

Since Brexit, the UK has been updating its financial regulations independently from the EU, leading to ongoing changes in payment services and currency handling. While this fosters innovation, UK residents need to stay aware of compliance rules, especially for large or frequent USD transactions.

  • Tax and reporting considerations

Receiving USD payments, particularly for freelancers and businesses, requires careful record-keeping for UK tax compliance. Currency gains or losses from exchange rate fluctuations must be reported accurately to HMRC.

  • Time zone differences and banking hours

The UK’s time zone difference with the US can add to transfer delays, as banks operate within local business hours. This can slow down payment processing and affect cash flow timing.

These issues create unnecessary barriers and uncertainty for freelancers, small business owners, and expats in the UK.

Also read: How to create US and UK bank accounts as a migrant worker in the UK

How Grey helps UK residents to send and receive US dollars

Grey offers a modern, digital-first solution tailored for UK residents who need to send and receive US dollars efficiently.

Open a virtual USD account with US bank details

Grey lets you open a USD account from the UK. This means you can:

  • Receive payments from US-based platforms like Upwork, PayPal, Fiverr, and Stripe directly into your Grey account without delays or forced conversions.
  • Accept transfers from US clients, companies, or friends quickly and with low fees.
  • Hold your funds in USD and choose when to convert to GBP, helping you protect your income from currency fluctuations.

Send US dollars with low fees and transparent rates

Convert your GBP to USD at competitive, transparent rates with no hidden charges. Make international payments quickly and securely, avoiding the slow and costly processes common with UK banks.

How to manage US dollars in the UK using Grey

Getting started is straightforward:

  1. Sign up for a Grey account
  2. Register online or via the app, verify your identity with UK documents such as a passport or driving licence, and open your virtual USD account.
  3. Add funds to your Grey USD account
  4. Top up your account by transferring GBP from your UK bank and convert to USD when you choose to optimise exchange rates.
  5. Receive and send USD easily
  6. Share your Grey USD account details with clients or contacts in the US to receive payments instantly. Send USD internationally at low cost and track all transactions in real time.

You may also like: How to send and receive euros in the UK

Practical tips for UK residents using Grey

  • Monitor exchange rates: Hold your USD in Grey until rates are favourable before converting to GBP.
  • Use multi-currency management: Grey allows you to hold GBP and USD balances, helping you manage currency risk and avoid unnecessary conversions.
  • Avoid multiple transfers: Send USD directly to reduce fees and delays.
  • Stay compliant: Keep records of your international payments and consult a UK tax advisor if needed, especially if you are self-employed or running a business.

Why Grey is the best choice for UK residents managing US dollars

Grey offers a seamless, affordable, and secure way to send and receive US dollars from the UK. Its USD accounts with US bank details, fast transfers, transparent pricing, and a user-friendly platform make it ideal for freelancers, small businesses, expats, and anyone transacting internationally.

Open your Grey account today and experience hassle-free international payments designed for the British market.

Last updated:

June 15, 2026

Open a free Grey account to get startedJoin 1 million digital nomads
IF YOU ENJOYED THIS, CHECK THESE OUT

BBVA Mexico SWIFT code: How to find and use it

•

•

2 min read

Trying to send money to a BBVA account in Mexico without the SWIFT code is like trying to mail a package without an address. A SWIFT code is a short combination of letters and numbers that informs the international banking system exactly where your money needs to go.

The SWIFT code for BBVA Mexico (BBVA Bancomer) is BCMRMXMM, used to route international transfers to a BBVA account in Mexico. You need it, along with the recipient's account number or CLABE, to send money from abroad. Always confirm the code with the recipient or BBVA before sending.

BBVA Mexico SWIFT/BIC code: BCMRMXMM

If you are sending money internationally to a BBVA Mexico account, whether to pay a supplier, support family, or settle a personal transaction, you need this code to route the transfer correctly. This guide explains what the code means, how to find it yourself, and what else you need to complete a successful transfer.

What is the BBVA Mexico SWIFT code?

BBVA Mexico is Mexico’s largest financial institution, established in 1932 with its headquarters in Mexico City.  It is the most profitable overseas subsidiary of BBVA Spain, its parent institution.

BBVA Mexico's SWIFT/BIC code is BCMRMXMM
You may also see it written as BCMRMXMMXXX, where the XXX identifies the head office. Both formats can be accepted for international transfers.

A SWIFT code is also called a Bank Identifier Code (BIC). It refers to an 8 to 11-character code that identifies a bank when sending money internationally. It tells the sending bank where to send the transfer. It may also specify the branch and location to route the transfer to.

BBVA Mexico was formerly known as BBVA Bancomer until 2019, when the bank rebranded. However, the SWIFT code BCMRMXMM remained unchanged after the rebranding. Only the bank’s name changed from BBVA Bancomer to BBVA Mexico, S.A. So, if you see older documentation referencing "BBVA Bancomer," the SWIFT code shown there is still valid.

BBVA Mexico's code (BCMRMXMM) is different from BBVA Spain’s code (BBVAESMMXXX). These are separate entities, even though BBVA Spain is the parent institution. If you're sending money to a Mexican BBVA account, use the Mexico-specific code. If you use BBVA Spain’s code instead, your money will be routed to the wrong account and may not be recoverable.

How to find the SWIFT code yourself

If you're unsure which SWIFT code to use, you can check:

  • Through online or mobile banking: If you or the recipient has access to BBVA Mexico's online banking or mobile app, the SWIFT/BIC code is usually listed under account details or international transfer information.
  • On a bank statement: Some BBVA Mexico statements include the SWIFT code with your account information.
  • On BBVA's official website: Check BBVA Mexico's website to confirm the current SWIFT codes for international transfers.
  • Directly from the recipient: If you're sending money to someone with a BBVA Mexico account, ask them to confirm their banking details before making the transfer. Some branches may have an extended SWIFT code.

SWIFT code vs CLABE: what is the difference?

If you're sending money to a BBVA Mexico account, you may need both the SWIFT code and CLABE, but they serve different purposes.

  • The SWIFT code (BCMRMXMM) identifies the bank in Mexico that receives the payment and how to route the transfer from the sending bank to BBVA Mexico. Think of it as the bank's international address that tells the international banking network where to send the money.
  • The CLABE (Clave Bancaria Estandarizada) is an 18-digit standardised interbank code unique to Mexico. It is required for all electronic transfers within the Mexican banking system. It identifies the specific account within BBVA Mexico where the funds should be paid. Think of it as identifying the specific mailbox at the address the SWIFT code points you to.

For an international wire transfer to a BBVA Mexico account, you generally need both the SWIFT code to route the transfer to the correct bank and the CLABE to ensure the funds land in the correct account.

How to use it to send or receive money

Once you have the recipient's details, sending the money is straightforward.

Step 1: Confirm all the recipient's details

You need the recipient's full legal name, their CLABE (18 digits), the SWIFT code (BCMRMXMM, or the specific branch code if provided), and the bank's name and address.

Step 2: Initiate the transfer through your bank

Log in to your bank's online platform or visit a branch. Select international wire transfer and enter the recipient's details exactly as provided, including the SWIFT code and CLABE.

Step 3: Enter the details

Enter the recipient's information exactly as provided. Double-check the SWIFT code and CLABE before continuing.

Step 4: Confirm the transfer currency

Depending on your bank and the recipient's account, you may be able to send USD or MXN. Confirm which currency the recipient expects before sending.

Step 5: Review fees before confirming

Your sending bank will typically charge an outgoing wire fee, commonly $25 to $50 for international wires from US banks. Correspondent banks in the routing chain may deduct additional fees before the funds reach BBVA Mexico.

Step 6: Track the transfer

Save the transfer reference your bank provides so you can track the payment if there is a delay. Many banks now support SWIFT GPI tracking, which shows where the transfer is in the routing chain and its estimated arrival time.

International wire transfers to Mexico typically take 1 to 5 business days, depending on the sending bank, the currency, and whether the transfer passes through one or more correspondent banks.

If you regularly send to Mexico, opening a multi-currency account can simplify the process rather than using international wires each time. You can hold money in your preferred currency before converting it for a transfer to Mexico.

A cheaper way to send money to Mexico

Traditional SWIFT transfers can come with several fees. Your bank may charge an outgoing wire fee, correspondent banks may deduct undisclosed fees along the way, and the exchange rate may include an additional 1-5% markup. These costs can reduce the amount your recipient receives.

Sending money from the US to Mexico with Grey offers a transparent alternative. You can see the exchange rate and transfer fee before confirming, so you know how much your recipient will receive in Mexican pesos. This is particularly useful for regular transfers, whether supporting family, paying a Mexican contractor, or handling personal finances across the two countries.

If you're planning a trip and sending money, our guide on the best time to visit Mexico covers weather, seasons, and money tips.

Send money to Mexico with Grey and avoid international wire fees, correspondent bank charges, and hidden exchange-rate markups.

Frequently asked questions about BBVA Mexico’s SWIFT code

What is BBVA Mexico's SWIFT code?

BBVA Mexico's SWIFT/BIC code is BCMRMXMM, sometimes shown as BCMRMXMMXXX. This code identifies BBVA Mexico's head office for international wire transfers. Some branches may have extended codes (such as BCMRMXMMPYM), so it's always best to confirm with the recipient before sending.

Is BBVA the same as Bancomer?

Yes, in the sense that BBVA Mexico was formerly branded as BBVA Bancomer before a 2019 rebrand. It is the same institution with the same SWIFT code (BCMRMXMM) as before the name change. If you have older documentation or contacts referencing "Bancomer," the bank details remain accurate; only the name has updated.

Do I need the CLABE too?

Yes. The SWIFT code alone routes your transfer to BBVA Mexico as an institution, but it does not identify a specific account. The 18-digit CLABE (Clave Bancaria Estandarizada) identifies the exact account the funds should be credited to. Both are required for a complete and accurate international transfer to a Mexican bank account.

How long does a transfer take?

International wire transfers to BBVA Mexico typically take one to five business days, depending on your sending bank, the currency used, and whether the transfer passes through one or more correspondent banks in transit. Transfers sent through platforms using local payment networks rather than the full SWIFT correspondent chain can settle faster.

What are the fees?

Standard SWIFT wires from US banks typically incur an outgoing fee of $25 to $50, plus potential correspondent bank deductions of $15 to $30 in transit, and a currency conversion margin if the transfer is converted to Mexican pesos, generally 1% to 5% above the mid-market rate. These costs are not always fully disclosed before you send.

Is there a cheaper alternative to a SWIFT wire?

Yes. Platforms like Grey process international transfers with fees and exchange rates disclosed before you confirm. They often route payments through local payment networks rather than the traditional SWIFT correspondent-bank chain. This avoids the additional costs of a standard bank wire. This is often a cheaper alternative to a SWIFT wire, especially for regular transfers to Mexico.
What is the currency of Switzerland? Franc symbol and code

•

•

2 min read

If you have always thought the currency used in Switzerland is the euro, it is unlikely you are the only wrong person in the room. Switzerland's currency is the Swiss franc (currency code CHF), issued by the Swiss National Bank and divided into 100 centimes. Switzerland and Liechtenstein both use it. Despite being surrounded by the eurozone, Switzerland has kept the franc, which is widely seen as a stable, safe-haven currency.

So, if you are planning a trip or business dealings involving the country, it is good that you didn't assume Switzerland uses the euro because of its central European location. This guide explains what the Swiss franc actually is, why Switzerland has kept its own currency, and what to know before spending or sending money there.

What is the currency of Switzerland?

Switzerland's official currency is the Swiss franc, issued and managed by the Swiss National Bank (SNB), Switzerland's independent central bank

Switzerland is not a member of the European Union and has deliberately chosen to remain outside the eurozone. The country has maintained its independent currency and monetary policy despite being geographically surrounded by eurozone countries (France, Germany, Italy, and Austria).

This is closely tied to Switzerland’s political and economic independence. It has maintained long-standing neutrality and is not a member of the EU. The people and policymakers made this choice.

The Swiss franc symbol and code

The ISO 4217 currency code for the Swiss franc is CHF. The code combines “CH”, from the Latin name for Switzerland, Confoederatio Helvetica, with “F” for franc. It is Latin for the Swiss Confederation. This is why the code uses "CH" rather than an abbreviation of "Switzerland" in English.

You may also see the franc written as Fr. or SFr. in Switzerland, depending on the region and language. Switzerland has four official languages: German, French, Italian, and Romansh.

  • German regions (Standarddeutsch): Use Fr. or CHF. The currency is called Franken, and the smaller unit (cents) is called Rappen (Rp.).
  • French regions (Romandie): Use Fr. or CHF. The currency is called franc, and the cents are called centime (ct.).
  • Italian regions (Svizzera italiana): Use Fr. or CHF. The currency is called franco, and the cents are called centesimo (ct.).
  • Romansh regions (Rumantschia): Use Fr. or CHF. The currency is called franc, and the cents are called rap (rp.).

The Swiss franc is subdivided into 100 centimes (in French-speaking areas) or Rappen (in German-speaking areas), similar to how a dollar is divided into cents.

Depending on the local language, the placement of the code changes on official documents:

  • German and English: The code or symbol usually goes before the amount (e.g., CHF 100 or Fr. 100).
  • French and Italian: The code or symbol usually goes after the amount, separated by a space (e.g., 100 CHF or 100 fr.

How prices are typically written:

  • CHF 100 - the standard international format)
  • Fr. 100 or 100 - (common within Switzerland)
  • SFr. 100 - (an older but still recognised format)
Denomination Type
10 francs Banknote
20 francs Banknote
50 francs Banknote
100 francs Banknote
200 francs Banknote
1000 francs Banknote (one of the highest-value circulating banknotes in the world)
5 francs Coin
2 francs Coin
1 franc Coin
50 centimes/rappen Coin

Notably, the 1000-franc note is one of the highest-denomination banknotes in active circulation globally.

Which countries use the Swiss franc?

Switzerland is not the only country using the Swiss franc. Liechtenstein, a small country between Switzerland and Austria, also officially uses the Swiss franc as its currency. These countries have a formal currency union agreement and have close economic and monetary ties.

A smaller and less widely known place where CHF is also used is Campione d'Italia. It is a small Italian municipality near Lugano, entirely surrounded by Swiss territory. Because of its isolation from the rest of Italy, it has been more practical to work with the Swiss economy. As a result, the Swiss franc circulates widely there alongside the euro.

You may also find Swiss francs accepted informally in some border areas near Switzerland, but the euro or local currency is normally used there.

Since German is one of Switzerland's official languages alongside French, Italian, and Romansh, see our guide to countries that speak German,

Franc to US dollar and euro

The Swiss franc is known as a safe-haven currency. This means investors worldwide often buy it during economic or political uncertainty because Switzerland is seen as relatively stable with low inflation rates and a remarkable banking system.

Its value against currencies such as the US dollar and euro changes regularly based on interest rates, economic conditions and investor confidence. If you need to know how much one US dollar is worth in Swiss francs, check a live exchange rate before travelling or sending money. Exchange rates can change throughout the day.

Getting and spending francs as a traveller

Switzerland is one of the more expensive countries to visit, so it is worth planning your spending before travelling.

You can generally pay with your card across Switzerland, including at restaurants, shops, hotels, and even many smaller establishments. Contactless payment is very common and widely expected.

You can use cash for smaller transactions at local markets and in some rural areas. Although CHF 1,000 exists, it's best to stick to smaller denominations. However, Switzerland remains one of Europe's more card-friendly countries.

ATMs are widely available and generally accept Visa and Mastercard. As with most international travel, your home bank may apply a foreign transaction fee, and the ATM operator may add its own fee on top.

Switzerland is expensive. A simple meal at a casual restaurant can cost significantly more than the equivalent in most neighbouring European countries. Set a realistic daily budget before you travel to avoid unpleasant surprises and find ways to maximise your funds.

One way to reduce costs is to minimise additional fees on every transaction. Spending abroad with a Grey card linked to a foreign currency balance avoids the layered foreign transaction fees many home bank cards charge.

Read our guide on avoiding foreign transaction fees before your trip.

If you need to send money from the US to Switzerland, or vice versa, whether for business or personal reasons, sending money internationally with Grey shows the exchange rate and fee before you confirm.

Planning a trip to Switzerland? Spend abroad with a Grey card using your foreign currency balance and avoid unnecessary conversion costs.

Frequently asked questions about the currency of Switzerland

Does Switzerland use the euro?

No. Switzerland uses the Swiss franc and is not part of the eurozone. Some businesses in tourist areas may accept euros, but paying in Swiss francs is usually more straightforward.

What is the symbol for the Swiss franc?

There is no single symbol used everywhere. You will commonly see CHF, Fr., or SFr. when prices are shown in Swiss francs.

Which countries use the franc?

Switzerland and Liechtenstein officially use the Swiss franc. It is also widely used in Campione d'Italia, an Italian town surrounded by Switzerland.

How much is 1 dollar in francs?

The dollar-to-franc exchange rate changes continuously with market conditions. So, check a live currency converter or financial data source before travelling or transferring money.

Is Switzerland expensive?

Yes, Switzerland is one of the most expensive countries in the world. It is generally more expensive than many other European countries, particularly for accommodation, food and transport. Set a higher daily budget when planning a trip.

Can I use my card in Switzerland?

Yes. Visa and Mastercard are widely accepted, including at most hotels, restaurants and shops. Contactless payments are also common. Keeping some cash is still useful for smaller purchases.

What is CHAPS? UK same-day payments

•

•

2 min read

You might not come across CHAPS in everyday banking, but when you need to move a large amount of money quickly, it can become an important option. It’s particularly common when buying a property, making a large business payment, or completing another high-value transaction.

CHAPS is a UK payment system for sending large sums on the same working day with no upper limit. People often use it for high-value payments, such as buying a house. Banks usually charge a fee and have a same-day cut-off time. Unlike Faster Payments, CHAPS has no transaction cap.

If you have been told to make a "CHAPS payment" by your solicitor, bank, or estate agent, particularly when completing a property purchase, this guide explains exactly what CHAPS is, how it works, and when it makes sense to use it rather than the alternatives.

What does CHAPS stand for?

CHAPS stands for the Clearing House Automated Payment System. It is a UK sterling payment system operated in partnership between the Bank of England and the banking industry.

CHAPS is for large-volume, time-sensitive payments that must be completed on the same working day. Unlike some other UK payment systems, CHAPS transfers are settled individually and in real time, rather than in batches. This difference makes them faster and better suited to large, urgent transactions.

CHAPS has operated since 1984 and remains the standard payment method for the largest and most time-sensitive payments in the UK, including property purchases.

How a CHAPS transfer works

A CHAPS transfer moves money from one UK bank account to another on the same working day, as long as you send it before your bank's cut-off time.

Here are some details on how a CHAPS transfer works.

  • Same-day settlement: CHAPS payments are processed one by one in real time throughout the working day. This differs from other payment systems, where transactions are batched and processed in bulk. Once processed, CHAPS transfers are final and cannot be recalled. This is one reason CHAPS is trusted for high-value, legally significant transactions like property completions.
  • No upper limit: Unlike Faster Payments, CHAPS has no maximum transaction value. This makes it suited for very large payments.
  • Cut-off times: Each bank has its own cut-off time for same-day CHAPS processing, typically in the early to mid-afternoon (commonly around 2 pm to 3.30 pm, though this varies by bank). Payments submitted after the cut-off are processed the next working day.
  • Details needed: To send a CHAPS payment, you need the recipient's account number and sort code, their full name, the amount, and typically a reference. Your bank processes the payment through the CHAPS system on your behalf; you do not interact with CHAPS directly.

When to use CHAPS

CHAPS is best suited when the payment needs to arrive the same day, and this certainty is more important than the transaction cost. Here are some scenarios you should consider CHAPS:

  • Property purchases: CHAPS is commonly used in the UK for property purchases because the funds need to arrive on the agreed completion date.
  • Large, time-critical business payments: It can be useful for large invoices, business acquisitions, or other payments where a delay could lead to additional charges or contract issues.
  • Payments above the Faster Payments limit. If the amount you need to send exceeds your bank's Faster Payments limit (commonly £250,000 to £1 million, depending on the bank), CHAPS is often the only same-day option available.
  • When completion matters: Because CHAPS payments are settled individually and are generally irrevocable once processed, they provide greater certainty for high-value transactions.

CHAPS vs Faster Payments vs BACS

Feature CHAPS Faster Payments BACS
Speed Same working day
before the cut-off
Usually within seconds to hours Usually 3 working days
Maximum amount No upper limit Usually £250,000 to £1 million, depending on the bank No formal cap, but not designed for very large payments
Typical cost £20 to £35 per transaction Usually free Usually free
Best for Property purchases and large, urgent payments Everyday personal and business transfers Payroll, direct debits and recurring payments
How payments are processed Individual, real-time, irrevocable Almost instant,
processed in batches
Processed in batches over three days
Availability Business hours
subject to cut-off
Generally 24/7 Business days only

For most everyday payments, Faster Payments is the better option because it is usually free, fast and available 24/7. CHAPS is mainly useful when you need to send a large amount that exceeds your bank's Faster Payments limit or when same-day settlement is essential, such as for a property purchase.

Costs and alternatives for sending abroad

Most UK banks charge £20 to £35 per outgoing CHAPS payment, although some banks with premium account tiers may offer free CHAPS transfer. Receiving a CHAPS payment is typically free to receive.

The higher fee compared to Faster Payments and BACS is due to the transfer speed, individual payment processing, and the certainty that the transaction will be completed on the same day.

CHAPS works only for domestic transactions within the UK. It is important to understand that CHAPS operates exclusively within the UK sterling payment system. It cannot be used to send money internationally. If you need to move money abroad, whether in GBP or another currency, you need a different payment system entirely. People typically use an international wire transfer via SWIFT or an international payment platform.

International wire transfers entail initiating a SWIFT payment through a traditional bank. The sender is charged about $15-$40 (or the GBP equivalent). This payment passes through one or more banks, which deduct correspondent fees before the funds reach the recipient’s bank. The receiving banks convert the money to their local currency at an exchange rate with 1-4% hidden margins.

Using a cross-border payment service gives you access to a foreign currency account. This means international transactions are processed like domestic payments. This avoids the fees associated with international wire transfers, and the recipient receives the funds in the original currency. This means they can convert whenever they like.

Sending money internationally with Grey shows the exchange rate and fee before you confirm. So, you are not worried about hidden fees and high exchange-rate margins that a standard international bank wire often entails. Whether you are sending money from the UK for business, family support, or property purchases abroad, most payments are completed within minutes or a couple of days.

For anyone managing money across multiple currencies, holding and sending multiple currencies from one account avoids the need to convert repeatedly through your main bank at an undisclosed rate.

Send money abroad from the UK with Grey with transparent fees and exchange rates shown before you confirm.

Frequently asked questions about CHAPS

What is a CHAPS payment?

A CHAPS payment is a UK same-day sterling transfer processed through the Clearing House Automated Payment System, operated in partnership between the Bank of England and UK banks. It is designed for high-value, time-critical payments, most commonly used for residential property completions, with no upper limit on the amount that can be sent.

How long does CHAPS take?

A CHAPS payment settles on the same working day, provided it is submitted before your bank's specific cut-off time, typically in the early to mid-afternoon. Payments submitted after the cut-off are processed on the next working day. Once settled, CHAPS payments are final and cannot be recalled.

Is there a limit?

No, CHAPS has no maximum transaction value, which distinguishes it from Faster Payments (typically capped between £250,000 and £1 million depending on the bank). This makes CHAPS the standard choice for very large payments, including most property completions and significant business transactions.

How much does CHAPS cost?

Most UK banks charge between £20 and £35 for an outgoing CHAPS payment, though some premium account tiers waive this fee. Receiving a CHAPS payment is typically free. The fee reflects the same-day, individually settled nature of the transaction compared to free alternatives like Faster Payments.

CHAPS vs Faster Payments: which should I use?

For most everyday transfers, particularly below £250,000, Faster Payments is faster in practice (often settling within minutes), free, and available around the clock. CHAPS becomes the appropriate choice specifically when the amount exceeds your Faster Payments limit, or when an absolute guaranteed same-day settlement is a legal or contractual requirement, as is standard for UK property completions.

Can I use CHAPS to send money abroad?

No. CHAPS is a UK domestic sterling payment system and cannot be used for international transfers. To send money abroad, whether in GBP or another currency, you need a separate international payment method, such as a SWIFT wire transfer through your bank, or a specialist international transfer provider like Grey, which shows the exchange rate and fee before you confirm.

Zelle limits: How much you can send per day

•

•

2 min read

Zelle, Venmo, Cash App, and PayPal are leading peer-to-peer payment platforms that let you send and receive money using a phone number, email, or username. But unlike most other P2P services that have digital wallets, Zelle integrates with your bank app for bank-to-bank transfers.

One other clear distinction between Zelle and other platforms is the transfer limit. Zelle send limits are set by your bank, not by Zelle, so they vary widely. Many large banks allow a few thousand dollars per day and a higher monthly cap, while some smaller banks set lower limits. There is no receiving limit, and you usually can't request higher limits.

If you tried to send a larger payment through Zelle and hit an unexpected limit, the explanation lies with your bank, not Zelle. This guide explains how Zelle limits work, what typical ranges look like across major banks, and your options for sending larger amounts or transferring money internationally.

What is the Zelle limit?

Zelle does not have one standard sending limit for everyone. Zelle limits are set individually by each participating bank or credit union. Your Zelle limit depends entirely on the bank your Zelle is connected to. So two people using Zelle can have significantly different limits just because they use different banks.

Your bank sets the Zelle limit, which is capped at a specific daily or monthly amount based on its risk management policies, your account history, and sometimes your account tier.

There is also generally no receiving limit. Most banks allow you to receive money through Zelle without a specific cap, although very large payments may be reviewed for fraud or compliance reasons.

Daily and monthly limits

Zelle limits typically apply on both a daily and rolling monthly (often described as 30-day) basis, and the specific figures vary meaningfully between institutions.

The typical daily limits across major US banks generally range from $500 to $10,000. However, some banks may set higher or lower rates. Some accounts, particularly newer accounts or those without extensive transaction history, may start with lower limits that can increase over time as the bank builds confidence in how the user transacts.

Some banks tie their Zelle limit to a fixed number of transactions. For example, Bank of America allows $500 over 10 transactions for new Zelle users. Business accounts often have higher Zelle limits than personal accounts.

Daily limits usually reset at midnight, though the exact time may vary by bank. Some banks also use a rolling 30-day limit instead of a calendar-month limit. This means your available limit depends on your total sent in the previous 30 days, not the calendar month.

Always verify your current limits in your banking app or by contacting your bank, as each bank sets and can change these limits at any time.

Zelle limits by bank

The table below gives a general idea of the limits you may see at some major US banks for personal accounts. Business accounts usually have higher limits. These figures can vary by the account tier and are subject to change. Always confirm your current limit in your bank’s app or by contacting your bank’s support.

Bank Typical daily limit Typical monthly limit
Bank of America $500 to $3,500/10 transactions Up to $20,000/60 transactions
Chase $500 to $15,000 Unstipulated
Wells Fargo Up to $3,500 Up to $20,000
Citibank $500 - $5,000 $2,500 - $20,000
PNC Bank Varies Varies
Credit unions (general) Depends, Often lower, $500 to $2,500 Often lower, $2,000 to $10,000

Credit unions like Truity have a weekly transaction limit (Up to $3000)

Verify with your specific bank before relying on these figures. Zelle limits change over time and can also vary within the same bank based on your account type, tenure, and transaction history. The most reliable way to confirm your current limit is directly within your bank's Zelle interface, in your banking app, or by contacting customer service.

Can you increase your Zelle limit?

You may be able to increase your Zelle limit, depending on your bank’s specifications.

Your bank may increase your limit automatically after you use your account regularly and build a transaction history. Some banks also allow customers to request a higher limit through customer service or their banking app.

However, some account types have fixed limits that cannot be increased. Moving to a different account tier may increase your limit, but it depends on the bank.

You cannot ask Zelle to increase your limit because Zelle doesn't set individual sending limits. Any increase has to come from your bank or credit union.

Sending larger amounts of money abroad

If you need to send more than your Zelle limit, you may need to wait for your limit to reset or split the payment across multiple days. This can be uncomfortable, especially when you need to complete the payment immediately. You might need to find an alternative payment option for a large domestic transfer.

Zelle doesn’t support international transfers. Zelle only works between eligible US bank accounts, so you cannot use it to send money to an international bank account. If you need to send money internationally, you'll need an alternative.

For larger domestic transfers within the US, you can use a same-day ACH or FedNow transfer through your bank. Your bank's ACH and FedNow limits are often higher than Zelle limits. You can also initiate a wire transfer for very large or time-critical amounts if you think the transfer fee is worth it.

For international transfers, you need a cross-border payment service to send money outside the US or to a non-US bank account. Traditional international wire transfers can be expensive because the sending bank, intermediary banks, and receiving bank may each charge fees. The receiving bank may also apply a markup when converting the money into the recipient’s currency. These transfers can also take up to five business days to arrive.

Sending money abroad from the US can be cheaper with cross-border payment solutions like Grey, which offers USD, EUR, and GBP accounts. The cost of sending money internationally with Grey depends on the currency. However, Grey displays the exchange rate and fees before you confirm the transaction. USD, EUR, and GBP transfers using local rails cost 0.5% (minimum: 2 USD/GBP/EUR). The general maximum limit for international money withdrawals and sending is $10,000 equivalent per day and $30,000 equivalent per month.

If you spend internationally, shop from global markets, or pay for subscriptions in foreign currencies, a Grey card linked to your foreign currency balance lets you pay directly in the currency you hold, helping you avoid repeated foreign transaction fees.

Need to send money abroad? Send money abroad with Grey, with access to USD, EUR, and GBP accounts and higher transfer limits.

Frequently asked questions about Zelle limits

What is the Zelle daily limit?

There is no single Zelle daily limit that applies universally; each participating bank sets its own limit, generally ranging from $500 to $10,000 depending on the institution, account type, and account history. Check your current limit directly within your bank's Zelle interface, since it varies significantly by bank.

Does Zelle have a receiving limit?

Most banks do not impose a specific limit on how much you can receive via Zelle, unlike sending, which is capped daily and monthly. However, unusually large incoming amounts may occasionally trigger a review for compliance or fraud prevention purposes, even without a formal receiving cap.

Can I increase my limit?

Sometimes. Some banks automatically raise limits over time as you build a longer, consistent transaction history on the account. Others let you request an increase directly, though approval depends on the bank's policies and isn't guaranteed. Some entry-level account types have hard limits that cannot be increased regardless of request.

Why do limits differ by bank?

Zelle does not set user-level sending limits; each participating bank sets its own limits based on its risk management policies, fraud-prevention approach, and account-tier structure. This is why the same person can experience very different limits simply by having accounts at different banks.

Can I use Zelle internationally?

No. Zelle is a US domestic payment service that only works between enrolled US bank accounts. It cannot be used to send money to international bank accounts or to recipients outside the United States, regardless of the amount. For international transfers, you need a dedicated cross-border payment service.

How do I send more than the limit?

Options include waiting for your daily limit to reset (typically at midnight) and splitting the payment across multiple days, using a same-day ACH transfer through your bank if the amount fits within your bank's ACH limits, or using a wire transfer for very large or time-critical domestic amounts. For international transfers, Zelle isn't an option regardless of the amount; you'll need a dedicated international transfer service like Grey instead.

7 places to find high paying remote jobs in Kenya

•

•

2 min read

Not long ago, landing a well-paying job often came with battling Nairobi traffic, navigating endless office corridors, or waiting months for interview calls that never came. But times have changed. Today, a growing number of Kenyan professionals are closing deals with British startups, designing for European brands, or writing for global media from their living rooms in Kisumu, Nakuru, or Mombasa.

Whether you’re a software developer, designer, marketer, writer, or virtual assistant, there’s a global gig with your name on it.

In this guide, we’ll explain the best platforms to find remote jobs in Kenya — and how to get paid like a global professional.

1. Upwork – Build a strong freelance profile and land global gigs

Best for: Freelancers with experience and a professional portfolio.

Type of work: Writing, design, tech, admin, and more.

Why it stands out:

Upwork is one of the most well-established freelance platforms globally. Kenyan professionals can create detailed profiles, showcase past projects, and apply for jobs posted by clients worldwide. The platform also offers long-term contract opportunities and supports hourly or fixed-price arrangements.

Pro tip: Take time to polish your profile and earn a few early reviews; it helps you land better-paying gigs.

Also read: High-paying remote jobs you can land without experience

2. Remote OK – Find remote tech and digital roles with ease

Best for: Tech professionals and digital creatives.

Type of work: Programming, marketing, product management.

Why it stands out:

Remote OK curates remote job listings from multiple sources, with a focus on digital roles. Many listings are full-time positions with international companies, making it ideal if you’re looking for career growth rather than one-off gigs.

Pro tip: Filter listings by time zone or region to find jobs that suit your schedule.

3. FlexJobs – Access premium, vetted remote job listings

Best for: Serious remote job seekers looking for vetted listings.

Type of work: Customer service, project management, writing, education.

Why it stands out:

FlexJobs is a subscription-based platform, but it’s well worth the cost for its thoroughly vetted listings. The platform avoids scams and focuses on high-quality remote opportunities, including part-time and freelance options.

Pro tip: Opt in for the trial period first to explore available options in your niche.

4. LinkedIn – Use your network to discover remote opportunities

Best for: Networking and full-time remote roles.

Type of work: Across all industries.

Why it stands out:

LinkedIn isn’t just for networking; it’s also a great source for remote job listings. Use the search filter to find “remote” or “work-from-home” opportunities and follow companies hiring globally. Many employers now list remote roles explicitly in their job postings.

Pro tip: Turn on the “Open to work” feature and update your profile with remote-specific keywords.

5. Toptal – Join a global network of elite freelancers

Best for: Highly experienced professionals in tech and finance.

Type of work: Software development, finance, product design.

Why it stands out:

Toptal connects top freelancers with top-tier clients. While it’s not for beginners — their vetting process is intense — it offers access to high-paying, long-term projects. If you’ve got a strong background in tech or business, this is a solid platform to consider.

Pro tip: Prepare thoroughly for the application process; Toptal only accepts a small percentage of applicants.

6. We Work Remotely – Discover top-tier remote jobs across industries

Best for: Skilled professionals looking for global companies.

Type of work: Development, customer support, design, sales.

Why it stands out:

This platform focuses exclusively on remote work and attracts companies like GitHub, Shopify, and Basecamp. It’s great for tech-savvy Kenyans looking to land jobs with companies that embrace remote work culture.

Pro tip: Check the site regularly. Listings go fast!

You may also like: The best digital nomad jobs to earn from anywhere in Kenya

7. Fiverr – Sell your skills through microservices and creative gigs

Best for: Creative professionals and microservices.

Type of work: Graphic design, writing, video editing, translation.

Why it stands out:

Fiverr allows you to set up “gigs” offering services starting from $5 (hence the name). It’s perfect for creatives and those looking to turn a specific skill into a source of income. Fiverr is especially useful if you want to build multiple income streams.

Pro tip: Use SEO-friendly gig descriptions and eye-catching visuals to attract buyers.

Bonus: Use Facebook and WhatsApp local communities for quick wins

Best for: Quick gigs and community support.

Why it stands out:

While not a traditional job platform, there are several local groups dedicated to freelance and remote job opportunities in Kenya. These communities often share job leads, advice, and reviews about clients and platforms.

Pro tip: Always verify opportunities and avoid groups that regularly post vague or unverified jobs.

Get paid like a global professional

One of the biggest challenges Kenyan freelancers face is how to get paid. Job boards and platforms often pay in GBP or EUR — but local banks may charge high fees or offer poor exchange rates.

With Grey, you can access global banking designed for freelancers, remote workers and digital nomads.

  • Open free EUR or GBP accounts
  • Receive payments directly from platforms like Upwork, Fiverr, or clients abroad.
  • Convert your earnings to Kenyan Shillings at competitive rates.
  • Withdraw to your local bank or Mobile Money account with ease.
  • Get a globally accepted virtual dollar Mastercard to pay for tools and subscriptions anywhere.

Your remote career starts now

Remote work has created a level playing field for talented professionals across the globe. With the right skills, platforms, and tools like Grey, Kenyan freelancers can tap into international markets and earn like global pros.

Open a free Grey account and get paid for your remote work, wherever you are in Kenya.

‍

The best countries in Europe to land a remote job

•

•

2 min read

When I first started working remotely, I had one big dream: to take my laptop and build a life somewhere inspiring, connected, and filled with new experiences.

Like many freelancers and remote workers, I realised that Europe had a lot to offer: strong internet, progressive work cultures, and the opportunity to tap into global markets. But the question was: what’s the best country to get a remote job in Europe?

I now have the answers. Read on.

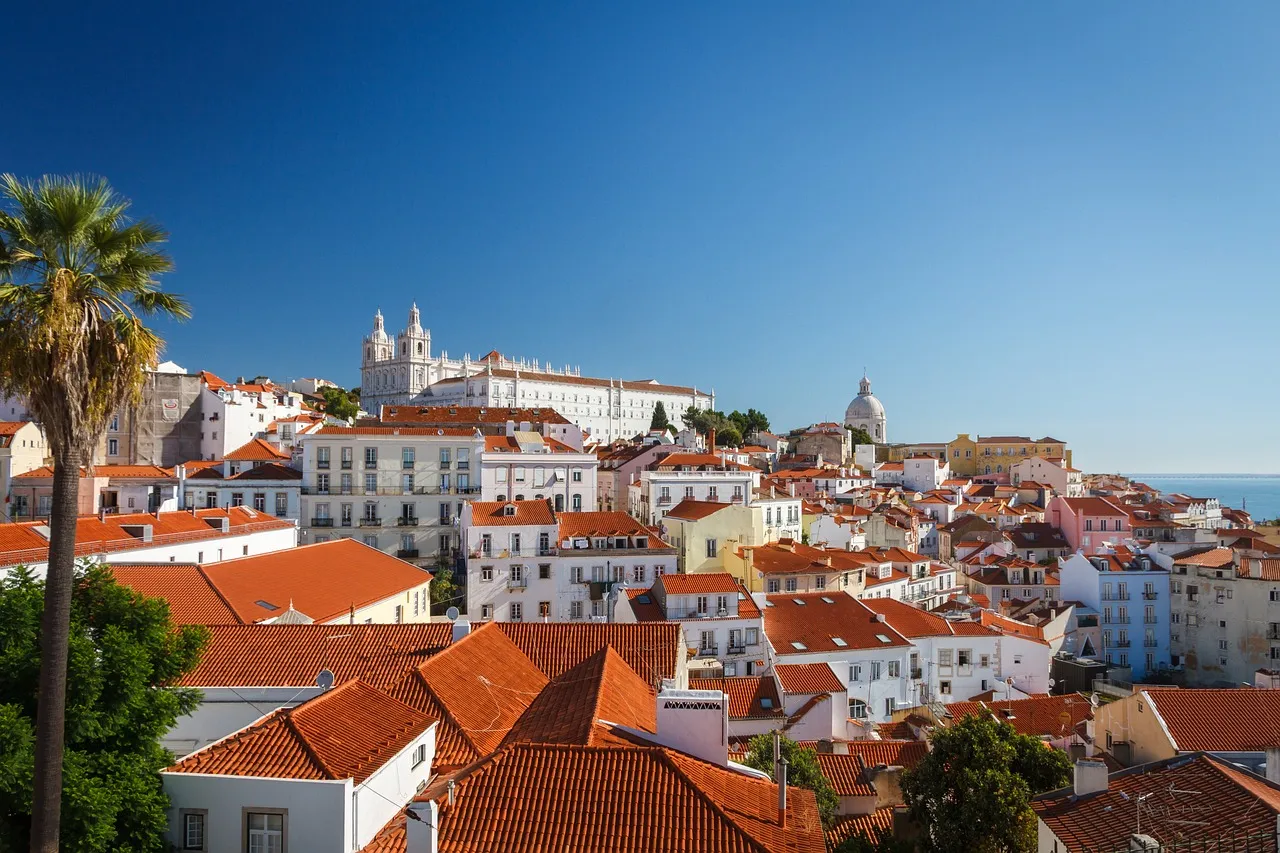
Portugal: My peaceful productivity haven

__wf_reserved_inherit

Portugal was the first European country I lived and worked as digital nomad — and honestly, it set the bar so high. Lisbon had everything I needed: fast Wi-Fi, a buzzing remote work community, affordable living (especially compared to London or Paris), and cafés that felt more like co-working spaces.

Local tip: In Lisbon, check out “Outsite” or “Second Home” for flexible co-working. For a slower pace, head to Ericeira, a coastal town with a great surf scene and chill cafes.

Why I’d go back: Friendly locals, reliable infrastructure, and an inspiring mix of city buzz and seaside calm. For many, Portugal is the best country to get a remote job in Europe thanks to its visa schemes and cost of living.

Germany: Professionalism with a creative edge

__wf_reserved_inherit

Next up is Berlin — a city that felt alive with innovation. For tech freelancers, Germany offers access to serious clients and a strong professional network. It wasn’t as laid-back as Portugal, but if you’re looking for growth and structure, Germany is a great option.

Local tip: Berlin’s “Factory Berlin” is a hotspot for entrepreneurs and creatives. Don’t miss cafes like Sankt Oberholz in Mitte, known as Berlin’s remote work HQ.

Why I’d recommend Germany for remote work: There is a high demand for skilled talent, efficient systems, and easy access to the rest of Europe. Germany is often listed as the best country for tech professionals to get a remote job in Europe.

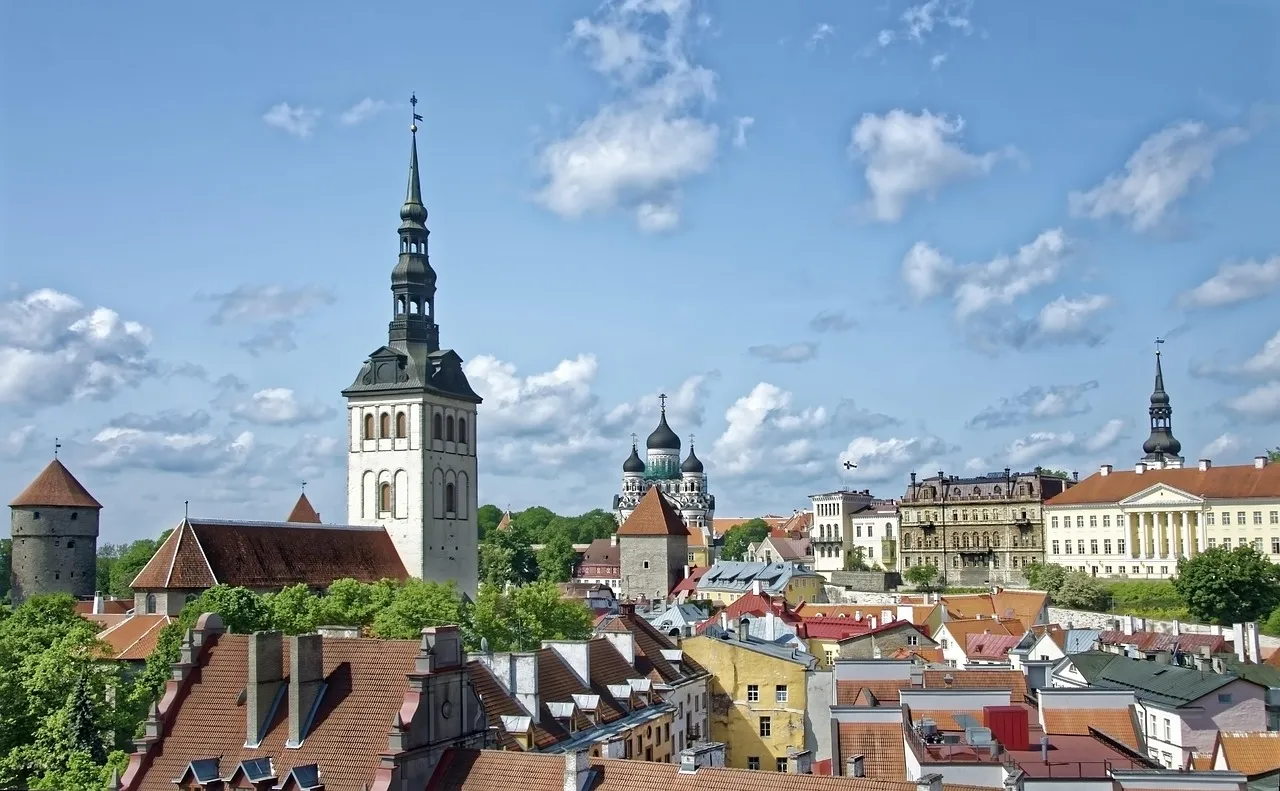
Estonia: The most digital country I’ve ever seen

__wf_reserved_inherit

I never moved to Estonia, but discovering their e-residency programme and digital nomad visa showed me how flexible remote work in Europe could be. With options to register a business online or live and work legally in the country, Estonia makes it easy for freelancers and remote workers to tap into the European market without the usual red tape.

Local tip: Tallinn’s Telliskivi Creative City is full of co-working spaces, indie boutiques, and community vibes. For quiet work time, “Spring Hub” offers top-tier facilities.

Why it’s unique: Total freedom. You can be based anywhere and still benefit from EU business access.

The Netherlands: Where creativity meets structure

__wf_reserved_inherit

Amsterdam charmed me with its creativity and culture, but it’s also one of the best places in Europe to find remote work in design, marketing, and tech.

Local tip: Settle in at “B. Amsterdam” and experience its huge co-working campus with everything from gyms to rooftop cafe. Explore De Pijp for great brunch spots with Wi-Fi.

What stood out: International vibe, high English fluency, and access to global companies. The Netherlands remains a top contender for the best country to get a remote job in Europe for digital creatives.

Spain: Sun, speed, and a startup spirit

__wf_reserved_inherit

I spent a few weeks working from Barcelona, and it honestly felt like I was cheating at life with its great food, amazing weather, and a growing community of creatives and remote workers.

Local tip: Grab a desk at “Aticco” in Barcelona’s Eixample neighbourhood or head south to Valencia, an underrated hub with lower living costs and great workspaces.

What I loved: The pace of life, the energy of the startup scene, and how affordable things were outside the big cities. If lifestyle matters most to you, Spain could easily be the best country to get a remote job in Europe.

Also read: How to apply for a digital nomad visa in Spain

Croatia: Where creativity meets the coast

__wf_reserved_inherit

Croatia immediately caught my attention when I was looking for a more affordable European destination with a high quality of life. The country’s stunning coastline along the Adriatic Sea and rich cultural heritage made it an ideal choice for a remote worker like me. Plus, Croatia offers a digital nomad visa, which is perfect for freelancers wanting to spend an extended period in this beautiful country.

Aside from the breathtaking views,  Croatia is becoming a hotspot for freelancers, thanks to its affordable cost of living, reliable internet, and vibrant local communities. Cities like Zagreb and Split were exactly what I needed while I lived there; they’re full of energy and creativity, making them perfect places for anyone looking to spark inspiration.

Local tip: I loved working by the sea when I found myself in Split. There are amazing spots to work by the water, and I highly recommend Re.Split Coworking for a modern, remote-friendly workspace.

You may be interested: A simple guide to digital nomad visas in the Mediterranean

How I made it work (and how you can too)

Landing remote gigs in Europe is totally doable if you approach it with a plan. Here’s what helped me:

  • Keeping my LinkedIn and portfolio sharp
  • Applying on remote-friendly platforms like We Work Remotely and EuropeRemotely
  • Joining Slack groups and Discord channels with other freelancers
  • Reaching out directly to companies offering remote roles in Europe
  • Joining The Grey Area, a community built by Grey for digital nomads, freelancers, and remote workers who want to connect, network, and grow.

And here’s something I wish I had known sooner...

Manage your global income with ease — here’s how

One of the biggest challenges I faced wasn’t finding work; it was getting paid without losing money to fees or delays. That’s when I found Grey — a digital banking platform built for freelancers like us.

With Grey, I was able to:

  • Create virtual USD, EUR, and GBP accounts
  • Receive payments from international clients
  • Convert currency at great rates
  • Withdraw to my local account — no stress, no surprises

If you’re a remote worker and want to simplify your financial life, Grey is hands down the best solution I’ve used.

Ready to find your best fit?

So, what’s the best country in Europe to get a remote job? The truth is, it depends on your priorities. For sun and ease of life? Portugal or Spain. For structure and growth? Germany or the Netherlands. For total flexibility? Estonia.

Wherever you choose, having the right tools makes all the difference. With a platform like Grey by your side, you can focus less on logistics and more on what you do best. Open your free Grey account today and experience a better way to bank — built for where you are, and where you’re going.

‍

Arrow (up)

Back to top